• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Debt

The Federal Reserve Rate Cut That Did Nothing for Credit Card Holders

February 5, 2026 by Brandon Marcus Leave a Comment

The Federal Reserve Rate Cut That Did Nothing for Credit Card Holders
Image source: shutterstock.com

The Federal Reserve made headlines with its long‑awaited rate cut, and for a brief, shining moment, millions of credit card holders dared to hope. Maybe—just maybe—their sky‑high APRs would finally ease up. Perhaps carrying a balance wouldn’t feel like dragging a boulder uphill. And maybe this was the break everyone had been waiting for.

And then… nothing happened. Credit card interest rates barely blinked, balances didn’t get cheaper, and consumers were left wondering why the Fed’s big move felt like a firework that fizzled before it left the ground. If you’ve been staring at your statement wondering why your APR still looks like a bad joke, you’re not imagining it. There’s a very real reason the Fed’s rate cut didn’t help—and understanding it can save you money in ways the Fed never will.

Why Credit Card APRs Don’t Drop Just Because the Fed Says So

When the Federal Reserve cuts rates, it affects a lot of things—mortgages, auto loans, personal loans, and even savings account yields. But credit cards live in their own universe, one where interest rates are tied to the prime rate and to whatever margin your card issuer decides to tack on.

Yes, your APR is technically variable, but that doesn’t mean it moves in lockstep with the Fed. Even when the prime rate drops, issuers can keep their margins high, which means your APR barely budges. And because credit card rates are already at historic highs, many issuers simply choose not to pass along the full benefit of a rate cut. It’s not illegal, it’s not hidden—it’s just how the system works.

The Credit Card Industry Has Zero Incentive to Lower Your Rate

Credit card companies make money from interest, and right now, they’re making a lot of it. With average APRs sitting well above 20%, issuers have little motivation to reduce rates unless they absolutely have to. A Fed rate cut gives them the option to lower rates, but not the requirement. And because consumer demand for credit remains strong, issuers know they can maintain high APRs without losing customers.

Even when the prime rate shifts, the margin they add on top can stay exactly the same. This is why your APR might drop by a fraction of a percent—just enough to technically reflect the Fed’s move—but not enough to make any meaningful difference on your monthly bill. It’s a system designed to benefit lenders first and borrowers last.
The Federal Reserve Rate Cut That Did Nothing for Credit Card Holders
Image source: shutterstock.com

Variable APRs Move Slowly—And Sometimes Not at All

Many credit cards come with variable APRs, which means they’re supposed to adjust when benchmark rates change. But “adjust” doesn’t mean “drop dramatically.” In reality, variable APRs often move in tiny increments, and issuers can delay adjustments depending on their internal policies.

Some cards only update APRs quarterly, while others adjust monthly. And even when they do adjust, the change is usually small—think tenths of a percentage point, not whole numbers. For someone carrying a balance, that tiny shift barely makes a dent. So while the Fed’s rate cut may technically ripple through the system, it’s more like a gentle ripple in a bathtub than a wave strong enough to lower your debt burden.

Record‑High Consumer Debt Keeps APRs Elevated

Another reason credit card rates remain stubbornly high is the sheer amount of consumer debt in circulation. Americans are carrying record levels of credit card balances, and delinquency rates have been rising. When lenders see increased risk, they raise margins to protect themselves. Even if the Fed lowers rates, issuers may keep APRs high to offset the risk of borrowers falling behind.

This means your interest rate is influenced not just by economic policy, but by the behavior of millions of other cardholders. It’s a collective effect that keeps APRs elevated even when the broader financial environment becomes more favorable.

Why Your Minimum Payment Didn’t Shrink Either

Even if your APR technically dropped a little, your minimum payment probably didn’t. That’s because minimum payments are calculated using formulas that prioritize fees, interest, and a small percentage of your principal. A tiny APR reduction doesn’t change the math enough to lower your minimum.

And if your balance has grown due to everyday spending, inflation, or unexpected expenses, your minimum payment may actually increase despite the Fed’s rate cut. It’s a frustrating reality, but it’s also a reminder that relying on minimum payments is one of the most expensive ways to manage credit card debt.

What You Can Do When the Fed Won’t Save You

The good news is that you’re not powerless. Even if the Fed’s rate cut didn’t help, there are strategies that can. One of the most effective is calling your credit card issuer and asking for a lower APR. Many companies will reduce your rate if you have a strong payment history or if you mention that you’re considering transferring your balance elsewhere.

Speaking of balance transfers, 0% APR offers can be a game‑changer if you qualify and can pay off the balance before the promotional period ends. You can also explore debt‑consolidation loans, which often have lower rates than credit cards, especially after a Fed rate cut. And if you’re feeling overwhelmed, nonprofit credit counseling agencies can help you create a plan that reduces interest and simplifies payments.

Rate Cuts Don’t Fix Credit Card Debt—You Do

The Federal Reserve can influence a lot of things, but it can’t force credit card companies to lower your APR in a meaningful way. That power still lies with you. Whether it’s negotiating your rate, switching to a better card, consolidating your debt, or adjusting your spending habits, the most effective changes come from your own actions. The Fed may set the stage, but you’re the one who gets to rewrite the script. And the more you understand how credit card interest really works, the easier it becomes to take control of your financial story.

What’s the most surprising thing you’ve learned about credit card interest rates lately? Give us your thoughts in the comments.

You May Also Like…

Retail Store Credit Cards Now Charging 30% APR on Average

Why Credit Card APRs Only Dropped 0.35% Even After Three Fed Rate Cuts in 2025

7 Ways Credit Card Debt Builds Faster Than Expected

The Quiet Credit Score Rule Change That’s Raising Borrowing Costs for Older Americans

10 Reasons Your Credit Card Fraud Claim Was Denied—and What You Can Do About It

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: credit cards Tagged With: APR, banking, consumer debt, credit cards, credit credit card problems, Debt, Fed rate cut, federal reserve, financial literacy, interest rates, money tips, Personal Finance

The Single Late Payment That Raises APR to 29.99% Permanently at Discover

February 3, 2026 by Brandon Marcus Leave a Comment

The Single Late Payment That Raises APR to 29.99% Permanently at Discover
Image source: shutterstock.com

It happens in a blink. One forgotten due date, one autopay glitch, one chaotic week where life just steamrolls your calendar—and suddenly your credit card balance becomes a financial monster. If you have a Discover card, that single late payment can trigger a penalty APR of 29.99%, a number so high it practically deserves its own warning label.

The scariest part? Many people think it’s permanent. While that’s not technically true, the impact can feel permanent in your wallet if you don’t know how the system works.

The Moment Everything Changes: How One Late Payment Can Flip Your APR Switch

Discover, like most major credit card issuers, includes something called a penalty APR in its cardmember agreements. If your payment is late—typically 60 days past due—Discover can raise your interest rate to as high as 29.99%. No, that’s not a typo. This is nearly double the standard APR many people start with, and it applies to existing balances, not just future purchases.

Many cardholders believe that once the penalty APR hits, they’re stuck with it forever. Technically, Discover does allow for the penalty APR to be reviewed and potentially reduced after six consecutive on-time payments, but that’s not automatic, guaranteed, or fast. For many people, life doesn’t suddenly get calmer just because interest rates went nuclear, and missed payments can snowball.

Why 29.99% Is Financially Dangerous (and Not Just “High Interest”)

29.99% isn’t just “a little expensive.” It’s mathematically punishing. At that rate, interest compounds aggressively, meaning your balance grows faster than most people can realistically pay it down—especially if you’re only making minimum payments. It’s like trying to walk up a downward-moving escalator while carrying groceries and emotional baggage.

What makes this worse is psychological. When balances stop shrinking despite payments, people often get discouraged, avoid checking statements, and fall into financial avoidance mode. That’s how debt becomes sticky. The penalty APR isn’t just a financial hit—it’s a behavioral trap that makes recovery harder because progress feels invisible.

The Myth of “Permanent” vs. the Reality of Long-Term Damage

Discover’s penalty APR is not technically permanent. According to cardmember agreements, issuers may reduce it after consistent on-time payments (typically six months). But just because something isn’t permanent on paper doesn’t mean it isn’t long-lasting in real life. Many people never get the rate reduced because they miss another payment, carry high balances, or don’t even realize they need to request a review.

Even if the APR does eventually drop, the financial damage lingers. You’ve already paid extra interest. Your credit report may reflect late payments. So while the word “permanent” may not be legally accurate, the consequences absolutely can be long-term if you’re not proactive.

How to Protect Yourself From Ever Triggering a Penalty APR

The best strategy is boring, but powerful. Automation beats discipline every time. Set up autopay for at least the minimum payment. Put due date alerts on your phone. Sync your credit card due dates with your calendar. Use one financial app to track all bills in one place. These systems protect you from bad weeks, bad months, and bad mental health days.

If you’re already behind, act fast. Call Discover immediately. Sometimes, late fees can be negotiated and potentially waived, and while penalty APRs are harder to reverse, early communication helps.

The Single Late Payment That Raises APR to 29.99% Permanently at Discover
Image source: shutterstock.com

Why Credit Card Companies Use Penalty APRs in the First Place

Penalty APRs aren’t accidental. Credit card companies use them to manage risk and maximize revenue. From a business perspective, a late payment signals higher default risk. The response? Increase the interest rate to compensate for that risk and profit from it. It’s not personal—it’s math, data, and financial modeling.

But understanding this gives you power. When you realize that the system is designed to profit from mistakes, you stop blaming yourself and start building defenses. Systems beat willpower. Structure beats motivation. Financial safety isn’t about perfection—it’s about designing your life so one mistake doesn’t trigger a financial avalanche.

The Real Lesson Behind Discover’s 29.99% Penalty APR

One missed payment shouldn’t feel like financial doom—but with penalty APRs, it often does. The real lesson is that credit cards are powerful tools, but unforgiving ones. They reward consistency and punish chaos. They amplify habits, good or bad.

If you treat credit like a convenience tool instead of a long-term loan, automate your payments, and stay proactive, you’ll probably never see 29.99% on your statement. But if you rely on memory, stress, or luck to manage your bills, the system eventually catches you slipping. And when it does, it charges interest.

The One Mistake That Can Turn a Good Credit Card Into a Financial Nightmare

It only takes one late payment to turn a useful financial tool into a debt accelerator. Discover’s 29.99% penalty APR is a perfect example of how fast things can flip. One missed due date can reshape your entire financial trajectory for months—or longer. The difference between safety and struggle isn’t income level, intelligence, or even discipline. It’s systems, structure, and awareness.

What do you think? Should penalty APRs even exist, or are they just another way banks profit from everyday mistakes? Give us all of your thoughts in the comments.

You May Also Like…

Why Credit Card APRs Only Dropped 0.35% Even After Three Fed Rate Cuts in 2025

Credit Card Interest Rates Average 23.79% in January 2026 Despite Fed Rate Cuts

7 Ways Credit Card Debt Builds Faster Than Expected

The Truth About “0% APR” Balance Transfer Cards and Their Hidden Fees

10 Reasons Your Credit Card Fraud Claim Was Denied—and What You Can Do About It

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: credit cards Tagged With: APR, Consumer Protection, credit cards, credit score, Debt, Discover Card, financial literacy, interest rates, Late payment, Penalty APR, Personal Finance

Your Attorney Isn’t the Only One Who Needs Your Will Details: 5 Conversations That Prevent Family Disputes

January 30, 2026 by Brandon Marcus Leave a Comment

Your Attorney Isn’t the Only One Who Needs Your Will Details: 5 Conversations That Prevent Family Disputes
Image source: shutterstock.com

When it comes to wills, most people think of attorneys, paperwork, and maybe a quiet sigh of relief once everything is signed. But here’s the catch: drafting a will is only half the battle. The other half—arguably the more important part—happens around the dinner table, in the living room, or over a cup of coffee with the people who matter most.

Without clear communication, even the most meticulously crafted will can spark confusion, hurt feelings, and yes, family disputes. Sharing your plans doesn’t just protect your estate—it safeguards relationships and prevents misunderstandings that can linger long after you’re gone.

1. Who Gets What—And Why It’s Not Just About the Money

One of the trickiest conversations is also the one everyone dreads: talking about who will inherit what. While it might seem simple to divvy up assets, the reality is that unspoken expectations often cause friction. A handwritten note giving Aunt Susie the silverware might feel harmless, but if no one knows why, it can ignite resentment.

Explaining the reasoning behind your decisions—whether it’s sentimental value, long-term financial planning, or rewarding caregiving—can diffuse potential misunderstandings before they escalate. Experts suggest framing your conversation with empathy: acknowledge that you understand people might be surprised or disappointed, but clarify your rationale with honesty. This isn’t about debating or justifying endlessly; it’s about transparency.

2. Guardianship Decisions for Children: Tough but Necessary

For parents, naming guardians for minor children is a responsibility that can’t be avoided. Yet many delay this conversation because it’s uncomfortable. Who will raise your children if you’re no longer there? Which values and routines are non-negotiable? These are not questions to leave to chance or a court decision.

Choosing a guardian is important, emotionally heavy work. Talking openly with a potential choice ensures everyone understands expectations, from daily routines to long-term educational plans. Even if your kids are young, letting them know your plan in an age-appropriate way can provide reassurance.

3. Healthcare and End-of-Life Wishes: More Than Just a Living Will

Your will handles property and finances, but healthcare directives deal with life itself. Without explicit conversations about medical preferences, family members may face agonizing decisions during emergencies. Do you want life support if recovery is unlikely? Are there specific treatments you refuse? Sharing your healthcare wishes in clear, calm discussions—along with a formal living will or advance directive—helps family members respect your choices while avoiding guilt or conflict.

Research shows that families who discuss end-of-life plans are less likely to experience long-term stress and discord. Consider involving a medical professional to answer questions and provide clarity. And don’t treat this as a one-time conversation; preferences evolve, so revisit and update your instructions regularly.

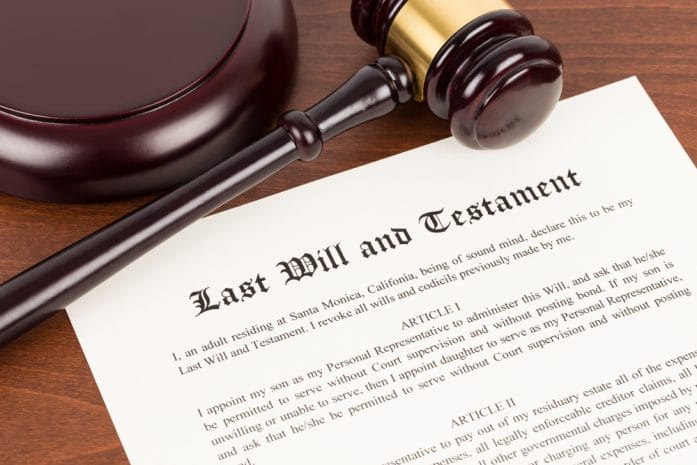
Your Attorney Isn’t the Only One Who Needs Your Will Details: 5 Conversations That Prevent Family Disputes
Image source: shutterstock.com

4. Debts, Liabilities, and Digital Assets: The Modern Oversight

When most people think of wills, they picture houses, jewelry, or bank accounts—but modern life includes digital assets and debts that often get overlooked. From online accounts and social media profiles to cryptocurrency wallets, failing to communicate access details can create legal headaches for your heirs. Similarly, family members need clarity on debts or co-signed loans to prevent financial strain or unexpected conflicts.

Experts recommend compiling a comprehensive “estate binder” that includes login credentials, insurance policies, loan documents, and contact information for financial advisors. Sharing this binder with trusted family members or executors ensures no one is left guessing.

5. The Executor Conversation: Choosing the Right Person for the Job

Picking an executor isn’t just a legal checkbox—it’s a conversation that sets the tone for how your estate will be managed. The executor handles bills, distributes assets, and ensures your wishes are fulfilled, but the role can be emotionally and logistically demanding. Openly discussing your choice with the person you’ve named allows them to accept or decline and prepares them for the responsibilities involved. Share your expectations clearly: Will they need to hire attorneys? Keep detailed records? Mediate between family members?

Executors who understand the full scope of their duties are far less likely to feel overwhelmed, which in turn reduces the risk of family conflict. And don’t forget to choose a backup executor—life is unpredictable, and having a secondary plan demonstrates foresight.

Talking Is Caring: How Conversations Shape Your Legacy

A will is a vital document, but it’s the conversations surrounding it that truly protect your family. By addressing inheritance decisions, guardianship, healthcare, debts, digital assets, and executor responsibilities, you minimize confusion and emotional stress. Open dialogue doesn’t eliminate surprises entirely, but it fosters trust, clarity, and mutual respect.

Sharing your intentions ensures your loved ones are emotionally prepared to honor your wishes without resentment or confusion. Ultimately, these discussions are acts of care, providing guidance that endures long after you’re gone. The document on the desk is only effective when the people who matter understand it.

What conversations have you had with your family about your will or estate planning? Could a simple chat today prevent conflict tomorrow? Share your thoughts below.

You May Also Like…

The Estate Planning Shortcut That Saves Time but Costs Families More in the Long Run

Why Some People Leave Everything to Strangers—and Not Their Kids

The Inheritance Mistakes That Turn Siblings Into Legal Enemies After a Parent Dies

5 Inheritance Tricks That Make Your Heirs Love You Forever

How a Solid Estate Plan Can Protect Your Finances

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Estate Planning Tagged With: death in the family, deathbed, Debt, digital assets, end-of-life, Estate plan, Estate planning, executor, families, Family, family conversations, family discussions, family issues, healthcare, liabilities, will and testament

8 Personal Finance Beliefs That No Longer Apply

January 25, 2026 by Brandon Marcus Leave a Comment

8 Personal Finance Beliefs That No Longer Apply
Image source: shutterstock.com

Money advice has a habit of hanging around long after it stops being useful. Some tips were brilliant in a different economy, with different technology, and wildly different expectations about work, debt, and retirement. Yet they keep getting passed down at dinner tables and in comment sections like sacred truths.

The result is a lot of people doing “the right thing” and still feeling behind, stressed, or confused. It’s time to clear the air, bust a few myths, and talk about what no longer deserves a spot in your financial playbook.

1. You Must Stay Loyal To One Employer For Financial Security

This belief came from an era when pensions were common and job-hopping raised eyebrows. Today, long-term loyalty often results in slower wage growth compared to changing roles strategically. Many workers now see their biggest salary increases when they switch companies rather than waiting for annual raises.

Benefits like retirement accounts and health insurance are no longer exclusive to one-employer careers. In fact, skills-based hiring and remote work have expanded opportunities across industries. Financial security now comes from adaptability, not staying put out of fear.

2. Buying A Home Is Always Better Than Renting

Homeownership has been marketed as the ultimate financial milestone for decades. While owning can build equity, it also comes with maintenance costs, property taxes, insurance, and reduced flexibility. Renting can be the smarter financial move depending on location, job stability, and housing market conditions. In high-cost areas, renting and investing the difference may outperform buying for many years.

Mobility has real economic value in a changing job market. The smarter question now is not “Should I buy?” but “Does buying make sense for my life right now?”

3. Carrying Any Debt Means You’re Bad With Money

This belief turns a nuanced topic into a moral judgment. Not all debt is created equal, and some forms can support long-term financial growth. Student loans, business loans, and mortgages can increase earning potential or asset ownership.

The real issue is whether debt is manageable, affordable, and aligned with your goals. Avoiding all debt at any cost can sometimes slow progress or limit opportunity. Smart money management focuses on strategy, not shame.

4. Credit Cards Should Be Avoided Completely

Credit cards earned their bad reputation through high interest rates and misuse. However, used responsibly, they offer fraud protection, rewards, and a way to build credit history. Paying balances in full each month avoids interest entirely while still capturing benefits.

Many essential financial activities, from renting a car to booking travel, are easier with a credit card. A strong credit profile can lower borrowing costs across your lifetime. The problem isn’t credit cards themselves—it’s carrying balances without a plan.

5. Budgeting Means Saying No To Everything You Enjoy

Old-school budgeting often felt like a financial punishment. Modern budgeting is more about awareness than restriction. Knowing where your money goes allows you to spend intentionally on what actually matters to you.

A good budget includes room for enjoyment, hobbies, and rest. Deprivation-based plans tend to fail because they ignore human behavior. Sustainable finances are built on balance, not constant self-denial.

6. You Need A Lot Of Money To Start Investing

This belief kept many people out of the market for years. Today, investing is more accessible than ever, with low-cost funds and platforms that allow small, regular contributions.

Compound growth rewards time more than large starting amounts. Waiting until you feel “ready” often means missing valuable years of growth. Even modest investments can build momentum and confidence. The most important step is starting, not starting big.

8 Personal Finance Beliefs That No Longer Apply
Image source: shutterstock.com

7. Talking About Money Is Rude Or Taboo

Silence around money has cost people real opportunities to learn. When finances aren’t discussed openly, misinformation fills the gap. Talking about salaries, debt, and financial mistakes can lead to better decisions and fairer outcomes. Transparency helps normalize learning curves and reduces shame.

Many people discover they are not alone once conversations begin. Financial literacy improves faster in the open than in isolation.

8. Retirement Is A Single Age With A Single Plan

Retirement used to look like a hard stop at a specific age. Now it’s often a gradual transition that varies widely by person. Some people aim for part-time work, passion projects, or flexible schedules rather than complete withdrawal. Life expectancy, healthcare costs, and personal goals all influence what retirement looks like. Planning now involves building options, not just hitting a number. Financial freedom has become more personalized—and more realistic—than ever before.

Updating The Rules Of Money

Outdated financial beliefs don’t just waste time; they can quietly limit your choices. Letting go of rules that no longer apply creates space for smarter, more flexible decisions. Personal finance works best when it reflects real life, not outdated expectations. If one of these beliefs shaped your past money choices, you’re in good company.

Feel free to add your experiences or lessons learned in the comments section below—your perspective might be exactly what someone else needs to read today.

You May Also Like…

10 Personal Finance Lessons People Learn the Hard Way

8 Budget Fixes That Instantly Turn Finances Around

7 Personal Money Questions Advisors Can’t Believe Are Real

4 Bold Predictions About The Future of Personal Finance Technology

10 Things You Should Never Ignore in Your Personal Finances

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Finance Tagged With: buying a home, buying a house, credit cards, credit score, Debt, eliminating debt, finance, finances, financial anxiety, Financial Security, general finance, home ownership, investing, Investment, Money, money beliefs, money habits, money issues, paying off debt, Personal Finance, spending

Why Do So Many People Feel Financially Stuck

January 25, 2026 by Brandon Marcus Leave a Comment

Why Do So Many People Feel Financially Stuck
Image source: shutterstock.com

Money stress has a special talent for showing up uninvited. One minute life feels manageable, and the next minute the bank balance looks like it’s playing a cruel joke. Bills stack up, goals feel far away, and even doing “everything right” somehow doesn’t seem to move the needle.

This feeling of being financially stuck isn’t rare or shameful—it’s widespread, deeply human, and rooted in forces much bigger than individual choices. To understand why it’s so common, we need to zoom out, slow down, and look at what’s really going on beneath the surface.

1. Rising Costs And Shrinking Breathing Room

For many households, the biggest culprit is simple math that no longer works. The cost of housing, groceries, healthcare, transportation, and childcare has climbed steadily over the past decades, often outpacing wage growth. Even people with steady jobs can feel like their paycheck evaporates the moment it lands. This creates a constant sense of pressure, where there’s little room to save, invest, or recover from surprises.

When every dollar already has a job, there’s no cushion for setbacks or opportunities. Over time, that tightness doesn’t just strain budgets—it drains motivation and confidence. Feeling financially stuck often starts with the exhausting reality of running faster just to stay in the same place.

2. Debt That Lingers Longer Than Expected

Debt is another heavy anchor, especially when it’s taken on early and follows people for years. Student loans, credit cards, medical bills, and auto loans can quietly shape financial lives long after the original purchase or emergency is forgotten. Interest turns small balances into stubborn obstacles that refuse to shrink. Many people make payments faithfully and still feel like they’re not making progress, which can be deeply discouraging.

Debt also limits choices, from where someone can live to which jobs they can take. The emotional weight matters too, as ongoing debt can fuel stress, guilt, and a sense of failure. That combination makes it harder to plan long-term or feel optimistic about money.

3. Income That Feels Unstable Or Inadequate

Even when expenses are controlled, income can be unpredictable or insufficient. Gig work, contract jobs, tipped positions, and variable schedules make it hard to count on a consistent monthly amount. Without reliable income, planning becomes a guessing game instead of a strategy. Raises and promotions also tend to come slowly, while costs rarely wait. For many workers, productivity has increased without a matching increase in pay, creating a gap between effort and reward.

This disconnect can make people feel powerless, as if no amount of hard work changes the outcome. Financial progress depends on income growth, and when that growth stalls, so does the sense of momentum.

4. Financial Education Gaps And Confusing Systems

Most people were never formally taught how money works beyond the basics. Budgeting, investing, taxes, credit, and insurance are often learned through trial and error. Financial systems are complex, filled with jargon, and sometimes designed in ways that benefit institutions more than individuals. This lack of clarity can lead to hesitation or avoidance, especially when mistakes feel costly.

Without clear guidance, people may miss opportunities or fall into habits that quietly hold them back. Over time, confusion turns into self-blame, even though the system itself is hard to navigate. Feeling stuck often has less to do with intelligence and more to do with missing information and support.

5. Social Pressure And Invisible Comparisons

Modern life comes with a nonstop highlight reel of other people’s spending and success. Social media, advertising, and cultural expectations can quietly redefine what feels “normal.” Vacations, new cars, home upgrades, and constant experiences start to look like basic milestones instead of luxuries.

Trying to keep up, even subconsciously, can push people into spending choices that strain their finances. At the same time, many struggles stay hidden, creating the illusion that everyone else has it figured out. That gap between perception and reality fuels frustration and embarrassment. Feeling financially stuck often worsens when people think they’re alone in it, even though they’re very much not.

6. Emotional Fatigue And Decision Overload

Money decisions are rarely just logical; they’re emotional. Constantly worrying about finances drains mental energy and focus. When every choice feels high-stakes, from grocery shopping to opening an email from a lender, exhaustion sets in. This fatigue can lead to avoidance, procrastination, or short-term fixes that don’t solve long-term problems.

Stress also makes it harder to learn new skills or think creatively about solutions. Over time, the emotional toll of money pressure can become as limiting as the financial reality itself. Feeling stuck is often the result of burnout, not laziness or lack of effort.

Why Do So Many People Feel Financially Stuck
Image source: shutterstock.com

Naming The Stuck Feeling Is The First Step

Feeling financially stuck isn’t a personal failure; it’s a signal. It reflects rising costs, lingering debt, uneven income, complex systems, and the emotional weight of navigating all of it at once. When people understand that these pressures are shared and structural, shame loosens its grip. Awareness creates space for better conversations, smarter choices, and more realistic expectations. Progress rarely comes from one dramatic move, but from small shifts paired with patience.

If this topic resonates with you, the comments section below is open for your experiences, insights, and reflections. Honest conversations are how financial stress starts losing its power.

You May Also Like…

8 Unsettling Financial Patterns That Keep Families Stuck for Generations

9 Financial Habits That Look Responsible but Feel Stressful

8 Grocery Shopping Habits That Make You Spend More Without Realizing It

6 Bad Money Habits Families Show During The Holidays

9 Budgeting Fears That Keep You Stuck

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: Cost of living, Debt, debt payoff, eliminating debt, finance, finances, financial education, financially stuck, general finance, Income, income stream, Life, Lifestyle, Money, money habits, money issues, money problems, rising costs

10 Budget Mistakes That Create Long-Term Pressure

January 24, 2026 by Brandon Marcus Leave a Comment

These Are 10 Budget Mistakes That Create Long-Term Pressure
Image source: shutterstock.com

Ever feel like your money disappears faster than ice cream on a hot day? You’re not alone. Most of us start budgeting with enthusiasm, then hit roadblocks that turn simple planning into stress-inducing chaos. Some of these pitfalls are obvious—buying expensive coffee every morning, impulsively splurging online—but others quietly accumulate, creating tension that sticks around for years.

The tricky part is that these mistakes don’t scream “problem!” right away. They sneak in slowly, reshaping your finances in ways you might not notice until you’re elbow-deep in bills or wondering where all your savings went. Understanding these traps is like spotting the cracks in your foundation before the entire house wobbles.

1. Ignoring Irregular Expenses

One of the most underestimated financial blunders is ignoring irregular expenses. These are costs that don’t appear on your monthly statement like clockwork, such as car maintenance, medical bills, or annual subscriptions. Failing to account for them can leave you scrambling when they pop up, forcing you to borrow or dip into your emergency fund. Creating a realistic budget means anticipating the unexpected and smoothing out the bumps over the year.

Even small amounts set aside consistently add up, reducing stress when irregular expenses inevitably arrive. Treating your budget like a static, unchanging plan is a recipe for constant catch-up, and that kind of pressure is exactly what long-term financial strain looks like.

2. Underestimating Debt Payments

Debt is a pressure cooker. Ignoring interest rates or underestimating minimum payments might feel harmless in the moment, but interest compounds faster than most people realize. Student loans, credit cards, and personal loans all have a habit of quietly inflating your monthly obligations if you’re not proactive. Not factoring these correctly into your budget can create a domino effect, where payments eat into savings and essentials.

The smart approach is to track every debt, understand the interest, and prioritize repayment strategically. This isn’t about living without enjoyment—it’s about preventing a small fire from growing into a full-blown financial inferno.

3. Skipping an Emergency Fund

Many budgeters dive into financial planning and completely skip one critical element: an emergency fund. Life throws curveballs—broken appliances, unexpected travel, or sudden medical expenses—and without a cushion, your budget crumbles instantly. Relying on credit cards or payday loans in emergencies only makes pressure compound over time.

A good rule of thumb is having three to six months’ worth of essential expenses saved. Think of it as the invisible shield that absorbs life’s blows. Even if your income fluctuates, a small emergency stash can transform panic into manageable inconvenience.

4. Neglecting Small Recurring Charges

Subscriptions are tiny, tempting, and oh-so-easy to forget. That yoga app, streaming service, or magazine subscription may seem insignificant individually, but they quietly drain your budget month after month. Ignoring these charges can derail your financial planning without any dramatic event to signal trouble.

Tracking every recurring expense—even the ones under ten dollars—gives you clarity and control. Cancel what you don’t use and adjust your budget to reflect the ones you genuinely value. This level of awareness prevents months of subtle budget erosion from turning into a serious problem later.

5. Overestimating Income

Optimism about your income can sabotage your budget faster than overspending ever could. Many people assume every paycheck will be perfect and consistent, then encounter unexpected tax changes, reduced hours, or delayed payments. Budgeting as if you earn more than you actually do creates stress when reality doesn’t match expectations.

Being conservative with your projected income forces your budget to reflect what you truly have to work with. It also creates a cushion for months that are less than ideal, preventing a pattern of shortfalls and anxiety.

6. Ignoring Inflation and Cost Increases

Budgets often feel set in stone, but inflation is the silent creep that eats your purchasing power over time. Ignoring rising costs on groceries, utilities, rent, or transportation may seem harmless in the short term, but it slowly transforms a balanced budget into a strained one. Regularly reviewing your spending and adjusting for inflation keeps your financial plan realistic. The goal isn’t panic—it’s preparation. Even a small monthly adjustment can prevent the slow, frustrating squeeze that turns a reasonable budget into a pressure-filled nightmare.

7. Not Tracking Spending

It sounds basic, but not tracking where your money goes is a massive mistake. You can create a detailed budget, but if you don’t monitor actual spending, you have no idea whether your plan is effective. Overspending in one category might require painful cutbacks elsewhere, building tension and anxiety over time.

Tracking expenses, whether through apps or manual logs, provides a reality check. It shows patterns, highlights problem areas, and creates accountability. Knowledge is power, and in this case, it’s the difference between financial calm and chronic stress.

These Are 10 Budget Mistakes That Create Long-Term Pressure
Image source: shutterstock.com

8. Living Beyond Your Means

Trying to maintain a lifestyle that exceeds your income is a guaranteed source of long-term pressure. It’s not just about the occasional treat or luxury—it’s about consistent overspending to keep up appearances. Credit cards and loans make this tempting, but they only postpone the inevitable strain. Long-term stress comes from the constant cycle of repayment, interest accrual, and guilt. Living within your means is empowering: it reduces anxiety, frees up funds for genuine priorities, and makes financial goals achievable rather than mythical.

9. Setting Unrealistic Goals

Ambition is great, but setting unattainable financial goals is a subtle form of self-sabotage. Trying to save half your paycheck in a month or pay off a huge debt without a plan leads to disappointment, frustration, and pressure that builds quietly.

Realistic, incremental targets create momentum rather than panic. Break goals into manageable steps, celebrate small wins, and adjust as circumstances evolve. Sustainable progress keeps stress in check while still pushing you forward.

10. Failing To Reevaluate Regularly

A budget isn’t a one-and-done project—it’s a living, evolving plan. Life changes, priorities shift, and unexpected expenses crop up. Failing to reassess your budget periodically can transform a healthy system into a pressure cooker. Review your finances monthly, adjust for changes, and be honest about what’s working and what isn’t. Flexibility prevents long-term pressure by addressing problems before they spiral. Think of it as giving your finances a tune-up, ensuring smooth operation for years to come.

Avoid Long-Term Pressure By Learning From Mistakes

Budgeting isn’t about perfection—it’s about creating a structure that reduces stress and gives you control over your financial life. The mistakes above are common because they’re easy to overlook, but they have long-term consequences if ignored. Recognizing them, planning for them, and actively correcting them can turn financial tension into clarity and freedom.

Your experience matters—what budget mistakes have crept up on you, and how have you handled them? Drop your thoughts, insights, or financial stories in the comments section below and let’s keep this conversation going.

You May Also Like…

Why Are Utility Bills Becoming a Bigger Budget Problem

Why Does Budgeting Feel More Emotional Than Logical

Legacy Design: 5 Ways to Pass on Wealth Without Passing on Pressure

8 Tips for Talking With Your Partner About Health, Finances & Legacy

Why Do So Many People Believe Budgeting Apps Solve Everything


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Budgeting Tagged With: Budget, budget mistakes, budget tips, budgeting, Debt, debt payments, emergency funds, Income, income streams, Inflation, living beyond your means, Money, money issues, money mistakes, overspending, recurring charges, spending, spending mistakes, splurging, tracking spending

6 Financial Missteps People Make In Their 20s

January 23, 2026 by Brandon Marcus Leave a Comment

These Are 6 Financial Missteps People Make In Their 20s
Image source: shutterstock.com

Your 20s are loud, busy, and full of moments that feel like they matter right now. Rent is due, friends are planning trips, careers are wobbling into place, and money often feels like it’s either slipping through your fingers or sitting just out of reach. One minute you feel wildly independent, and the next you’re staring at a bank app wondering how adulthood got so expensive so quickly.

This decade is where habits form, mistakes happen, and lessons stick—sometimes after a little financial whiplash. Let’s discuss the most common money missteps people make in their 20s, why they happen, and how to spot them before they quietly drain your future.

1. Ignoring Budgeting Because It Feels Restrictive

Many people in their 20s avoid budgeting because it sounds boring, rigid, or like a punishment for enjoying life. There’s a widespread belief that budgeting means saying no to everything enjoyable, when in reality it’s about knowing where your money goes.

Without a basic plan, spending decisions are made emotionally, which often leads to overspending on convenience, social pressure, or impulse buys. Small, frequent expenses—coffee runs, food delivery, random subscriptions—can quietly consume hundreds of dollars each month.

Budgeting doesn’t mean eliminating fun; it means giving your money a job so you don’t wonder where it disappeared. Learning this skill early makes every future financial decision easier and far less stressful.

2. Treating Credit Cards Like Extra Income

Credit cards can feel like magic during your 20s, especially when limits are higher than your checking account balance. It’s easy to swipe now and assume future-you will sort it out later.

The problem is that balances add up faster than expected, and interest charges turn modest purchases into long-term expenses. Many young adults carry balances without fully understanding how interest compounds over time.

This habit can trap people in cycles of minimum payments that barely make a dent. Used responsibly, credit cards can build credit and offer protections, but treating them like free money is a costly misunderstanding.

These Are 6 Financial Missteps People Make In Their 20s
Image source: shutterstock.com

3. Not Saving Anything Because Retirement Feels Forever Away

Retirement seems abstract when you’re more focused on rent, relationships, and career survival. Many people postpone saving because they believe they’ll earn more later and catch up then. What gets missed is the power of time, which matters more than the amount saved.

Even small contributions in your 20s can grow significantly thanks to compound interest. Waiting a decade often means needing to save much more to reach the same outcome. Saving early isn’t about sacrificing your present—it’s about giving yourself options later. Building the habit now matters far more than the size of the account.

4. Overspending to Match a Lifestyle That Isn’t Yours

Social media and peer pressure create powerful illusions about what adulthood should look like. Nice apartments, constant travel, designer clothes, and endless nights out can make overspending feel normal.

Many people in their 20s quietly stretch their finances to keep up with friends or online expectations. The reality is that everyone’s financial situation is different, even if it looks identical on the surface.

Spending beyond your means often leads to debt, stress, and resentment. True financial confidence comes from aligning your spending with your own priorities, not someone else’s highlight reel.

5. Skipping Emergency Savings Because Nothing Has Gone Wrong Yet

When life is relatively stable, emergency savings can feel unnecessary. It’s easy to assume you’ll handle problems if they come up. Unfortunately, unexpected expenses rarely give advance notice, especially in your 20s. Job changes, medical bills, car repairs, or sudden moves can derail finances overnight.

Without a cushion, people often turn to credit cards or loans, making a tough situation worse. An emergency fund isn’t pessimistic; it’s practical. Even a small buffer can provide peace of mind and prevent short-term problems from becoming long-term financial damage.

6. Avoiding Financial Education Because It Feels Overwhelming

Money topics can feel intimidating, especially when they involve unfamiliar terms or long-term consequences. Many people avoid learning about investing, taxes, or credit because they don’t know where to start.

This avoidance often leads to missed opportunities and preventable mistakes. Financial literacy isn’t about becoming an expert overnight; it’s about building understanding one step at a time.

Your 20s are the ideal decade to ask questions, make low-stakes mistakes, and learn without massive consequences. The more informed you are, the less power fear and confusion have over your decisions.

Small Choices Now, Powerful Results Later

Financial missteps in your 20s are common, understandable, and rarely permanent. What matters most is noticing them early and adjusting course before they become patterns that follow you for decades.

Every thoughtful decision you make now—no matter how small—adds momentum to your future stability and freedom. Money doesn’t need to control your life, but it does respond to attention and intention.

If you’ve learned lessons the hard way or picked up smart habits early, the comments section below is the perfect place to add your perspective and experiences.

You May Also Like…

10 Common Budgeting Mistakes That Create Constant Money Stress

Legacy Blueprint: 5 Estate Mistakes Lawyers Still See Constantly

5 Investment Mistakes Young People Make

Holiday Trap: 6 Gift-Spending Mistakes That Could Wreck Your Budget

Forget Your 20s—Here’s Why People Over 50 Are Actually the Happiest

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Finance Tagged With: Budget, budgeting, budgeting mistakes, credit cards, credit score, Debt, eliminating debt, finance, finances, financial choices, financial decisions, financial missteps, financial mistakes, general finance, overspending, payoff debt, spending, youth, youthful mistakes

Why Do So Many People Say Money Stress Is Constant

January 22, 2026 by Brandon Marcus Leave a Comment

Why Do So Many People Say Money Stress Is Constant
Image source: shutterstock.com

Money stress doesn’t knock politely and wait for an invitation. It crashes the mental party, grabs a chair, and refuses to leave. One minute you’re enjoying a quiet coffee, and the next your brain is running numbers you didn’t ask for.

Bills, savings, emergencies, future plans, and that one expense you forgot about all start talking at once. It’s loud, distracting, and weirdly exhausting, even when nothing is technically “wrong.” So why do so many people describe money stress as constant instead of occasional?

The Feeling Of Never Quite Catching Up

A huge reason money stress feels nonstop is the sense that you’re always a step behind. Paychecks arrive, then disappear into rent, groceries, utilities, and other basics before you can blink. Even people who budget carefully often feel like progress moves at a crawl. When necessities take priority, goals like saving or investing get pushed further down the list.

That gap between what people earn and what life costs creates a steady background hum of worry. Over time, that hum starts to feel normal, which is unsettling in its own way. The stress isn’t always about crisis; it’s about endurance.

Why Modern Life Makes Money Feel Louder

Money concerns didn’t suddenly appear in recent decades, but modern life amplifies them. Prices for housing, healthcare, childcare, and education have climbed faster than many wages. Meanwhile, people are constantly exposed to images of other lifestyles through social media and advertising.

That exposure can quietly reset expectations about what “normal” looks like. When your reality doesn’t match those images, stress fills the gap. Add in subscription services, automatic payments, and financial apps pinging your phone, and money becomes a daily presence. It’s hard to relax when reminders are built into your pocket.

Why Do So Many People Say Money Stress Is Constant
Image source: shutterstock.com

Debt Turns Time Into A Bill

Debt is one of the most powerful reasons money stress sticks around. Unlike a one-time expense, debt stretches into the future and follows people for years. Each payment is a reminder of past choices, emergencies, or structural realities like student loans. Interest adds pressure by making balances feel stubbornly resistant to progress.

Even manageable debt can weigh heavily because it limits flexibility and options. Many people don’t just worry about paying today’s bills; they worry about how long those bills will exist. That long horizon makes stress feel permanent instead of temporary.

Uncertainty Keeps The Nervous System On Alert

Another reason money stress feels constant is uncertainty. Jobs change, industries shift, and unexpected expenses show up without warning. Even people with stable incomes know that one medical bill or major repair could disrupt everything.

The human brain is wired to scan for threats, and financial uncertainty fits that category perfectly. When the future feels unpredictable, the body stays slightly tense, even during calm moments. This low-level vigilance can be draining over time. It’s not panic; it’s preparedness that never fully switches off.

Talking About Money Is Still Awkward

Money stress is also intensified by how rarely people talk honestly about it. Many cultures treat money as private or even taboo, which leaves people feeling isolated. Without open conversations, it’s easy to assume everyone else has it figured out.

That assumption fuels shame and self-blame, even when struggles are common. Silence makes stress heavier because it removes perspective. When people don’t hear others admit similar worries, they internalize the pressure. The result is a quiet, persistent tension that feels personal but is actually widespread.

Why The Stress Feels Constant

Money stress is rarely about one bill or one bad month. It’s about systems, expectations, uncertainty, and the mental load of planning for a future that never feels fully secure. When costs rise, debt lingers, and conversations stay quiet, stress becomes a steady companion instead of a passing visitor. Understanding why it feels constant can help people feel less alone in it.

If this topic resonates with you, feel free to leave your thoughts or personal experiences in the comments section below. Your perspective might help someone else feel seen.

You May Also Like…

What Does Financial Stress Do To Your Body?

9 Financial Habits That Look Responsible but Feel Stressful

7 Common Money Habits That Increase Stress Instead of Reducing It

Why Does Money Anxiety Increase With Age Instead of Decrease

Why Do People Feel Guilty Spending Money Even on Necessitiesd

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Finance Tagged With: anxiety, bills, conversations about money, Debt, eliminating debt, Emotional Spending, emotions, financial anxiety, financial stress, impulse spending, Life, Lifestyle, modern life, Money, money issues, money stress, monthly bills, Pay Off Debt, stress

10 Personal Finance Lessons People Learn the Hard Way

January 22, 2026 by Brandon Marcus Leave a Comment

These Are 10 Personal Finance Lessons People Learn the Hard Way
Image source: shutterstock.com

Money lessons rarely arrive politely. They crash into life during overdraft alerts, awkward conversations, or that sinking feeling after opening a credit card statement. Most of us don’t learn personal finance from calm instruction; we learn it from experience, stress, and a few “well, that didn’t work” moments.

The upside is that these lessons stick. They change habits, sharpen judgment, and turn past mistakes into future wisdom. Here are ten personal finance lessons people commonly learn the hard way, usually after their wallet has already taken a hit.

1. Spending More Than You Earn Always Catches Up

Living beyond your income feels manageable at first, especially when credit fills the gaps. Bills get paid, life looks normal, and the problem seems distant. Over time, though, the math becomes unavoidable. Interest compounds, balances grow, and flexibility disappears.

Many people only grasp this lesson after losing sleep over money or juggling due dates. Once learned, it often leads to tracking expenses, setting limits, and respecting the simple truth that income sets the ceiling.

2. An Emergency Fund Is Not Optional

Emergencies are rude, unpredictable, and expensive. Cars break down, jobs vanish, and medical bills appear without warning. Without savings, even small surprises can spiral into debt.

People usually learn this after relying on credit cards for emergencies and struggling to recover. A basic emergency fund provides breathing room and better choices. It turns crises into inconveniences instead of financial disasters.

3. Credit Cards Are Tools, Not Extra Income

Credit cards make spending feel painless, which is exactly the danger. Swiping now and worrying later often leads to balances that linger for years. Interest rates quietly punish unpaid balances month after month.

Many people realize this only after paying far more in interest than the original purchase cost. Used carefully, credit cards can build credit and offer protections. Used carelessly, they become very expensive loans.

4. Lifestyle Inflation Can Sabotage Raises

Earning more money feels like progress, and it is. The trap appears when spending rises just as fast. Bigger paychecks often bring bigger apartments, nicer cars, and more subscriptions.

At some point, people notice they feel just as broke as before, despite earning more. This lesson usually arrives with frustration and confusion. Keeping lifestyle inflation in check allows raises to actually improve financial security.

5. Ignoring Retirement Early Is Costly

Retirement feels far away, especially in your twenties and thirties. It’s easy to delay saving while focusing on current needs. Years later, people realize how powerful time and compound growth could have been. Catching up requires much larger contributions and sacrifices.

This lesson hits hardest when projections reveal uncomfortable gaps. Starting early, even with small amounts, dramatically reduces future stress.

6. Insurance Matters More Than It Seems

Insurance feels boring until the moment it’s desperately needed. Skipping coverage can save money short term, but the risk is enormous. Accidents, illnesses, and disasters can erase years of savings instantly.

Many people learn this lesson after paying out of pocket for something insurance would have covered. Proper coverage protects not just money, but stability and peace of mind. It’s about risk management, not optimism.

7. Not All Debt Is Created Equal

Debt often gets treated as a single category, but its impact varies widely. High-interest consumer debt drains finances quickly, while lower-interest debt can sometimes be strategic.

People often learn this after struggling to escape credit card balances while managing other obligations. Understanding interest rates and repayment terms changes priorities. It encourages attacking the most expensive debt first. This clarity can speed up financial recovery dramatically.

8. Small Purchases Add Up Faster Than Expected

Daily habits quietly shape financial outcomes. Coffee runs, delivery fees, and impulse buys seem harmless in isolation. Over months, they can consume hundreds or thousands of dollars.

Many people only notice after reviewing statements and feeling shocked by the totals. This lesson isn’t about deprivation. It’s about awareness and choosing what truly adds value.

9. Money Stress Affects Relationships

Financial problems rarely stay contained to spreadsheets. They spill into conversations, decisions, and emotional well-being. Couples and families often clash over spending, saving, and priorities.

People usually recognize this lesson after tension builds or trust erodes. Open communication and shared goals reduce conflict. Managing money together requires honesty, compromise, and patience.

These Are 10 Personal Finance Lessons People Learn the Hard Way
Image source: shutterstock.com

10. No One Cares More About Your Money Than You Do

Advice comes from everywhere, but responsibility rests with the individual. Employers, banks, and even well-meaning friends have their own interests.

Many people learn this after blindly following guidance that didn’t fit their situation. Taking ownership means learning basics, asking questions, and paying attention. Confidence grows with knowledge. Ultimately, financial control starts with personal accountability.

Turning Hard Lessons Into Lasting Wins

Personal finance mistakes can sting, but they also teach clarity and resilience. Each hard-earned lesson strengthens future decisions and builds confidence over time. Money management isn’t about perfection; it’s about progress and awareness.

Everyone’s journey includes missteps, and those stories matter. Feel free to give your thoughts or add your own experiences in the comments section below.

You May Also Like…

Risk Proaction: 5 Steps to Stress-Test Your Finances for Worst-Case Scenarios

5 Lessons Young People Should Know About Investing

7 Old-School Life Lessons Only Today’s 50-Somethings Still Remember

5 Valuable Lessons Learned From Market Crashes Historically

7 Personality Clues That Predict Divorce Before It Happens

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Finance Tagged With: Debt, debt payoff, eliminating debt, emergency fund, emergency funds, finance, finance lessons, financial goals, financial lessons, lessons, Life, Lifestyle, Lifestyle Inflation, Money, money anxiety, money issues, money plans, money stress, overspending, Personal Finance, purchases, Retirement, retirement accounts, retirement plan, retirement planning, retirement savings, small purchases, Smart Spending, spending

10 Money Decisions That Feel Urgent Later in Life

January 20, 2026 by Brandon Marcus Leave a Comment

These Are 10 Money Decisions That Feel Urgent Later in Life
Image source: shutterstock.com

Money has a way of turning into a silent, persistent pressure cooker. One day, you’re breezing through your twenties thinking, “I’ll deal with that later,” and the next, you’re staring at a spreadsheet and wondering why no one warned you about the little things that spiral into life-altering dilemmas.

We all make financial decisions that feel trivial at the moment, but they suddenly scream for attention decades down the line. Some of them hit like a surprise plot twist in your favorite show—except this time, it’s your bank account. Let’s dive into ten decisions you might be putting off, but that could demand urgent attention later.

1. Not Starting Retirement Savings Early

Delaying retirement savings is the classic “I’ll start tomorrow” trap. Compound interest is like a quiet superhero; it’s powerful, but only if you give it time to work. Even small contributions in your twenties can balloon into life-changing sums by your sixties, while waiting too long means you’re playing catch-up with every paycheck.

Many people underestimate how much they need for retirement, assuming Social Security or pensions will cover the gap. By the time you realize you should’ve started, the pressure to save aggressively can feel suffocating. Starting now, even modestly, gives your future self a serious advantage.

2. Ignoring Emergency Funds

Life is unpredictable, and bills don’t care about your plans. Skipping an emergency fund can turn a minor car repair, medical bill, or job loss into a full-blown crisis. Financial advisors usually recommend three to six months’ worth of living expenses, but even a small cushion is better than none. Without it, you might find yourself relying on high-interest credit cards or loans, which can snowball faster than you expect. Building a safety net gradually doesn’t hurt your present, but it pays off immensely later. Once emergencies arise, the peace of mind from having a buffer is priceless.

3. Letting Debt Go Unmanaged

Debt has a sneaky way of multiplying if ignored. Student loans, credit cards, and personal loans accumulate interest that often outpaces inflation, meaning your balance grows even as you pay. Many people put off tackling debt thinking it’s “manageable,” until it becomes a heavy anchor on everything else in life. Addressing it early allows for strategic repayment plans, potential refinancing, or consolidation, which all reduce stress down the road. Unmanaged debt can limit your choices, from buying a home to investing in your future. Facing it head-on today saves headaches, sleepless nights, and financial strain tomorrow.

4. Skipping Health Insurance Planning

Health expenses are unpredictable, but skipping or underestimating insurance is a major pitfall. Medical bills can spiral into six figures unexpectedly, particularly in later adulthood when preventive care and chronic conditions become more common. Some young adults feel invincible and avoid paying for coverage, only to discover that a serious illness or accident can wipe out savings in months. Adequate health insurance acts as a protective shield, not just for emergencies but for everyday medical maintenance. Planning now avoids the scramble and financial jeopardy that often feels urgent in midlife.

These Are 10 Money Decisions That Feel Urgent Later in Life
Image source: shutterstock.com

5. Neglecting Long-Term Care Considerations

Long-term care isn’t just for the very elderly—it’s a planning step that many overlook. Assisted living, home modifications, or in-home help can be costly, and these expenses tend to rise faster than inflation. Without preparation, families often face emotional and financial stress simultaneously. Options like long-term care insurance or dedicated savings accounts give more control and flexibility later. It might feel remote in your thirties or forties, but thinking ahead keeps your independence intact. Ignoring it can turn what could have been a smooth transition into a financial and logistical scramble.

6. Underestimating Lifestyle Inflation

Lifestyle inflation happens quietly as income rises: bigger rent, fancier cars, more frequent vacations. While rewarding yourself is natural, unchecked spending increases your baseline expenses faster than your wealth grows. Suddenly, saving or investing feels impossible because the “new normal” consumes every extra dollar. Being mindful of lifestyle inflation allows you to balance enjoyment with growth, ensuring your future self isn’t stressed over missed opportunities. Small choices today—like saving raises instead of spending them all—can compound into financial freedom later.

7. Postponing Estate Planning

No one likes thinking about death, but delaying estate planning is a costly oversight. Wills, trusts, and beneficiary designations protect loved ones and prevent legal chaos. Without a plan, assets can be tied up in court, creating delays and expenses for heirs. Estate planning also includes powers of attorney and healthcare directives, which matter far sooner than most expect. Tackling this early ensures clarity and reduces emotional strain during difficult times. Your future self—and your family—will thank you for thinking ahead.

8. Ignoring Tax-Advantaged Accounts

401(k)s, IRAs, HSAs—these aren’t just buzzwords. Tax-advantaged accounts can significantly boost wealth over decades, but ignoring them leaves money on the table. Many people focus on today’s spending and forget the exponential benefits of tax savings and compounding. Starting contributions early maximizes these accounts’ power and gives more flexibility for major life goals. Failing to use them is like leaving a bonus paycheck unclaimed every year. When you realize the opportunity cost decades later, it can feel like a wake-up call you wish you had earlier.

9. Avoiding Financial Education

Understanding basic finance isn’t glamorous, but skipping it creates a lifetime of stress. Knowing how interest works, how to invest, and how to read financial statements arms you with control and confidence. Many people make avoidable mistakes simply from ignorance—like high fees, bad investments, or missed deductions. Lifelong learning about money turns uncertainty into strategy. The earlier you start, the fewer surprises and regrets you’ll face. Knowledge compounds just like money; the sooner you invest in it, the bigger the payoff.

10. Delaying Conversations About Money With Loved Ones

Family money conversations are awkward, but postponing them can lead to misunderstandings, resentment, or missed opportunities. From inheritance plans to joint expenses or household budgeting, clear communication reduces stress. Many people wait for emergencies to bring up finances, which adds pressure and emotional strain. Early discussions establish expectations, foster cooperation, and prevent financial surprises. Talking openly might feel uncomfortable now, but it saves a lifetime of tension later.

Reflect And Engage

Money is more than numbers—it’s freedom, stress, opportunity, and sometimes, a sneaky source of regret if we ignore it. The choices we make today ripple through the decades, shaping our options, comfort, and peace of mind.

Which of these ten decisions resonates with your life most? Have you already faced some of these challenges or learned lessons the hard way? Drop your thoughts or personal stories in the comments.

You May Also Like…

Could Giving Money to Friends Be the Worst Investment Choice

Why Do People Feel Guilty Spending Money Even on Necessitiesd

9 Money Assumptions That No Longer Work in Today’s Economy

How Can Student Loans Quietly Shape Life Decisions for Decades

What Are The Worst Choices You Can Make As A New Investor?

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Finance Tagged With: 401(k), Debt, debt payoff, eliminating debt, emergency funds, Estate planning, financial choices, financial decisions, health insurance, healthcare costs, Life, Lifestyle, Lifestyle Inflation, Money, money choices, money decisions, money issues, Retirement, retirement account, retirement savings

  • « Previous Page
  • 1
  • 2
  • 3
  • 4
  • 5
  • 6
  • …
  • 22
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework