• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for taxes

8 State-Level Tax Changes Retirees Need to Watch Before the End of May

May 24, 2026 by Brandon Marcus Leave a Comment

8 State-Level Tax Changes Retirees Need to Watch Before the End of May
Retirees need to be well aware of these upcoming tax changes – Shutterstock

Retirement finances can shift quickly when state tax rules change, and timing often makes a major difference. Many retirees rely on stable income sources, yet state governments continue adjusting tax policies that affect property bills, pension income, and exemptions. These updates often roll out quietly, but they can significantly impact monthly budgets and long-term savings plans. Waiting too long to react can reduce benefits or trigger higher costs in the following tax year.

State lawmakers across the country continue adjusting tax structures in response to housing costs, inflation, and budget gaps. Retirees often feel these shifts first because they rely heavily on fixed incomes and tax relief programs. Some states expand exemptions, while others tighten eligibility or change filing deadlines. Each change carries real financial consequences that can affect daily living expenses.

1. Florida Property Tax Relief Adjustments Affect Senior Budgets

Florida continues adjusting homestead exemption rules that directly affect retired homeowners. Local counties sometimes revise assessment practices that increase taxable property values. Retirees who rely on fixed incomes often feel pressure when even small increases hit annual tax bills. Some proposed relief programs aim to offset rising housing costs, but eligibility rules shift frequently.

Retirees in Florida should track county-level announcements closely before tax deadlines arrive. Delays in filing exemption paperwork can reduce potential savings for the entire year. Many seniors benefit from reviewing assessment notices early and challenging inaccuracies when needed. Small adjustments in property valuation can lead to meaningful annual savings or unexpected costs.

2. California Retirement Income Tax Bracket Shifts Change Planning Strategies

California continues to adjust income tax brackets that affect pension withdrawals and retirement account distributions. Higher-income retirees often feel these changes first, especially those with multiple income streams. Even modest bracket shifts can push retirees into higher tax categories. This creates pressure to revisit withdrawal timing from IRAs and 401(k) accounts.

State-level updates also affect deductions and credits tied to senior taxpayers. Some retirees may need to adjust estimated payments before deadlines approach. California’s tax structure rewards careful planning, especially for those balancing pensions and investment income. Staying alert to bracket changes helps retirees avoid unnecessary tax spikes.

3. New York Property Tax Rebate Deadlines Tighten for Seniors

New York continues offering property tax relief programs, but deadlines for rebates often arrive faster than expected. Retirees who miss filing windows risk losing valuable credits tied to school district and municipal taxes. These rebates can reduce overall housing costs, especially in high-tax counties. Timing plays a critical role in securing full benefits.

State administrators continue pushing digital filing systems, which require careful attention to submission rules. Seniors who delay paperwork often lose eligibility for that tax cycle. Local tax assessors also update valuation data that affects rebate amounts. Retirees should review mail notices closely to avoid missing key deadlines.

4. Texas Homestead Exemption Updates Impact Property Owners

Texas continues expanding homestead exemption discussions, but local implementation varies by county. Retirees benefit from exemptions that reduce taxable home value, especially in fast-growing metro areas. Some counties revise exemption caps, which changes how much savings retirees receive annually. These updates often occur before fiscal year transitions.

Homeowners should confirm exemption status every year rather than assuming automatic renewal. Filing errors or outdated records can eliminate savings without warning. Property tax bills in Texas can rise quickly when exemptions do not apply correctly. Retirees gain the most protection when they verify county tax records early in the season.

5. Illinois Retirement Income Exemption Changes Alter Take-Home Pay

Illinois offers retirement income exemptions that reduce taxes on certain pensions and retirement distributions. Recent adjustments tighten eligibility thresholds for higher-income retirees. These changes can shift expected take-home income for many households. Some retirees may need to adjust spending plans to match new net income levels.

State tax officials continue refining exemption rules to balance budget demands. Retirees who rely heavily on pension income should review updated guidelines carefully. Even small changes in exemption limits can affect annual tax filings. Planning ahead helps reduce surprises during tax season.
8 State-Level Tax Changes Retirees Need to Watch Before the End of May
Retirees would love settling down in Illinois, but they can’t forget about upcoming tax changes – Shutterstock

6. Pennsylvania Inheritance Tax Rules Create Planning Urgency

Pennsylvania maintains one of the more complex inheritance tax systems, and recent updates increase attention on estate planning. Retirees who pass assets to family members may trigger unexpected tax obligations. Different asset types receive different tax rates, which can complicate planning decisions. Families often underestimate the timing required to settle these obligations.

State-level enforcement continues tightening reporting requirements for estates. Retirees benefit from reviewing beneficiary designations and estate documents before deadlines arrive. Clear planning reduces confusion and prevents unnecessary tax penalties. Early preparation helps families protect more of their inherited wealth.

7. New Jersey Senior Freeze Program Updates Affect Eligibility

New Jersey’s Senior Freeze program helps eligible retirees stabilize property tax costs, but income thresholds continue shifting. Some retirees lose eligibility when income rises slightly above limits. The program reimburses property tax increases, making it a valuable tool for long-term homeowners. Recent updates require careful income tracking.

Filing requirements also grow more detailed, with stricter documentation rules. Retirees must submit proof of residency and income annually to maintain benefits. Missing even one filing window can reset eligibility status. Careful recordkeeping helps retirees maintain consistent tax relief.

8. Washington Capital Gains Tax Rules Influence Retirement Investments

Washington State applies capital gains taxes that can affect retirees selling stocks or investment properties. Recent adjustments expand reporting requirements for certain asset sales. Retirees who rely on investment income often need to reassess timing strategies. Even moderate gains can trigger tax obligations under state rules.

Financial advisors in the region often recommend spreading asset sales across multiple tax years. This approach helps reduce exposure to higher tax brackets. Retirees should track both federal and state implications before selling investments. Planning ahead prevents unexpected reductions in retirement income.

Retirees Watching State Tax Shifts Should Remember This

State tax changes continue shaping retirement budgets across the country, and timing matters more than ever. Retirees who track exemptions, income thresholds, and filing deadlines often protect more of their savings. Each state applies rules differently, which creates both risks and opportunities depending on location. Small oversights can lead to higher tax bills or missed credits that reduce yearly income. Staying proactive with state updates helps retirees maintain financial stability throughout the year.

What state tax change has had the biggest impact on retirement planning in your experience?

You May Also Like…

Why More Americans Are Delaying Retirement as Medicare Premiums Approach $200 Per Month

The 5 Most Expensive Retirement Mistakes Americans Over 60 Are Making During This Inflation Spike

5 Financial Rules That Can Reduce Retirement Income Faster Than Expected

How Seniors Jeopardize Their Social Security Right After Retirement

10 Retirement States That No Longer Cater to Retirees

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Retirement Tagged With: Income tax, Planning, property tax, retirees, Retirement, Senior Benefits, state tax changes, taxes

The Hidden Problem With a Bigger Social Security COLA That Financial Advisors Say Many Retirees Miss

May 22, 2026 by Brandon Marcus Leave a Comment

The Hidden Problem With a Bigger Social Security COLA That Financial Advisors Say Many Retirees Miss
A Larger Social Security COLA sounds good, but it could pose problems – Shutterstock

A bigger Social Security COLA often feels like a financial win for retirees, especially when grocery bills and utility costs keep climbing. That annual adjustment is designed to help benefits keep pace with inflation, and on paper, it sounds like extra breathing room. But financial advisors warn that the increase can quietly trigger ripple effects that shrink the real benefit.

Many retirees focus on the higher monthly check without noticing the downstream costs that follow. Those hidden trade-offs can turn a “raise” into a budgeting surprise that hits later in the year.

Why a Bigger COLA Can Push Retirees Into a Higher Tax Bracket

A larger COLA increase can push more retirees into taxable income territory, even when their lifestyle stays the same. Social Security benefits can become partially taxable when combined income crosses certain thresholds set by federal tax rules. That means a higher monthly benefit can unintentionally increase the portion of benefits subject to income tax. Many retirees do not adjust their tax withholding after a COLA bump, which creates a surprise bill during tax season. Financial advisors often see this issue pop up when retirees assume the adjustment only helps and never hurts.

This tax impact can feel especially frustrating because it does not come with extra cash flow flexibility. Retirees may discover that the government effectively “reclaims” part of the COLA through taxes, reducing the net gain. Some households even move from a zero-tax situation to a partial tax situation due to small income shifts. Advisors recommend reviewing total income projections after each COLA announcement to avoid surprises. A proactive tax plan often prevents that sudden feeling of losing part of the raise before it ever reaches the bank.

Medicare Premiums Often Rise Right Along With COLA Gains

Medicare Part B premiums frequently rise in the same period as COLA adjustments, and that timing creates a frustrating offset. Since premiums typically come directly out of Social Security checks, retirees may see a smaller net increase than expected. This effect becomes more noticeable when inflation pushes both COLA and healthcare costs upward at the same time. Many retirees assume their benefit increase equals extra spending money, but Medicare deductions can quickly shrink that gain. Financial advisors often call this the “silent offset” because it happens automatically without much visibility.

Higher-income retirees can also face additional Medicare surcharges known as IRMAA, which stand for Income-Related Monthly Adjustment Amounts. A slightly higher COLA can tip someone into a higher IRMAA bracket, raising premiums for both Medicare Part B and Part D. That increase can erase a meaningful portion of the COLA before it ever reaches everyday expenses. Retirees often do not anticipate how sensitive Medicare thresholds can be to small income changes. Planning ahead for these thresholds can help avoid unexpected jumps in healthcare costs after a COLA increase.

Inflation Doesn’t Always Match the COLA Formula in Real Life

The COLA calculation uses a specific inflation index that does not always reflect the real costs retirees face daily. For example, healthcare, housing, and food inflation often rise faster than the official measure used for Social Security adjustments. That mismatch means retirees may receive a “raise” that still fails to keep up with actual spending patterns. Financial advisors often point out that COLA acts more like a partial adjustment rather than a full inflation match. This gap becomes more noticeable during periods of uneven inflation across different sectors.

Retirees also tend to spend differently than working households, which makes the inflation formula even less precise for their needs. Essentials like prescriptions and rent take up a larger share of their budgets, and those categories often rise faster than average inflation. Even with a higher COLA, purchasing power can still decline if personal expenses rise faster than the adjustment rate. Advisors encourage retirees to track spending categories individually rather than relying on headline inflation numbers. That approach helps reveal whether the COLA actually supports real financial stability or simply looks good on paper.

The Budget Illusion That Can Lead to Overspending After COLA Increases

A bigger COLA can create a psychological boost that leads retirees to increase spending too quickly. That extra monthly amount can feel like “found money,” even though it is meant to offset higher costs. Financial advisors often see retirees adjust their lifestyle upward before fully accounting for taxes, Medicare changes, or inflation gaps. This reaction can slowly erode savings or increase reliance on withdrawals from retirement accounts. The result often looks like stable income on paper but shrinking financial flexibility in practice.

This illusion becomes especially risky for retirees on fixed incomes who already operate with tight margins. A small increase in discretionary spending across multiple categories can add up faster than expected over a year. Advisors frequently recommend treating COLA increases as protection against inflation rather than a spending opportunity. That mindset helps preserve long-term financial stability and reduces the risk of shortfalls later. Careful budgeting after each COLA announcement can make the difference between comfort and unexpected strain.

The Hidden Problem With a Bigger Social Security COLA That Financial Advisors Say Many Retirees Miss
Budgeting is vital for all retirees, even with a bigger Social Security COLA – Shutterstock

What Retirees Often Miss About the Bigger COLA Picture

A larger COLA often brings short-term relief, but it rarely tells the full financial story for retirees. Taxes, Medicare premiums, and inflation mismatches all work together to reduce the real impact of that increase. Financial advisors emphasize that COLA should be viewed as one piece of a much larger retirement puzzle. Retirees who zoom out and evaluate total income, healthcare costs, and tax exposure tend to make better financial decisions. That broader perspective helps prevent overconfidence in what looks like a simple benefit increase.

What do you think matters more in retirement planning: maximizing income increases or minimizing hidden costs?

You May Also Like…

North Carolina Retirees Are Filing for Social Security Earlier as Insolvency Fears Grow

Florida Seniors Could See a 3.9% Social Security COLA in 2027 — But Energy Bills Are Rising Even Faster

Why More Americans Are Delaying Retirement as Medicare Premiums Approach $200 Per Month

6 Retirement Planning Errors That Could Cost You Thousands Under New Tax Rules

6 Insurance Changes That Can Increase Costs in Retirement

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: social security Tagged With: COLA, Inflation, Medicare, Personal Finance, Planning, retirees, retirement income, Social Security, taxes

9 Everyday Money Mistakes That Quietly Lead to IRS Penalties

May 18, 2026 by Brandon Marcus Leave a Comment

9 Everyday Money Mistakes That Quietly Lead to IRS Penalties
The official IRS website – Shutterstock

Tax penalties rarely arrive out of nowhere. They often grow from small, everyday financial habits that seem harmless at first glance. A missed form here or a rushed filing there can quietly snowball into fees, interest, and stress.

The IRS does not ignore small errors when they repeat or involve missing payments. Staying ahead of these mistakes helps protect both money and peace of mind.

1. Missing Tax Deadlines Sets Off Immediate Penalties

Missing the federal tax deadline triggers automatic penalties that begin the very next day. The IRS charges a failure-to-file penalty that increases the longer the delay continues. Interest also builds on any unpaid balance, creating a compounding financial burden. Even short delays can cost significantly more than expected. Filing on time eliminates one of the fastest ways to lose money unnecessarily.

2. Underpaying Estimated Taxes Creates a Growing IRS Bill

Self-employed workers and freelancers must pay estimated taxes throughout the year. Underpaying those quarterly amounts leads to penalties even if the annual return gets filed correctly. The IRS calculates penalties based on how much gets underpaid and how long the shortfall lasts. Many taxpayers underestimate income fluctuations and accidentally fall short. Staying consistent with estimated payments helps prevent surprise fees.

3. Mixing Personal and Business Expenses Confuses Tax Records

Blending personal spending with business expenses creates confusion during tax season. The IRS expects clear separation between business costs and personal purchases. Mixed records often lead to disallowed deductions and higher taxable income. Small business owners face extra risk when they rely on one bank account for everything. Clean financial separation strengthens accuracy and reduces audit concerns.

4. Ignoring 1099 Income Leads to Underreported Earnings

The IRS receives copies of all 1099 forms directly from employers and clients. Failing to report that income creates a mismatch that often triggers penalties or audits. Gig workers and freelancers sometimes overlook smaller payments from side projects. Every dollar reported on a 1099 must appear on a tax return. Accurate reporting prevents automatic enforcement actions from the IRS system.

5. Claiming Incorrect Deductions Raises Audit Risk

Taxpayers sometimes claim deductions they cannot fully support with documentation. The IRS requires proof for business expenses, charitable donations, and certain credits. Inflated or incorrect deductions increase the chance of an audit and penalties. Even honest mistakes can lead to costly adjustments later. Careful recordkeeping ensures deductions hold up under review.

9 Everyday Money Mistakes That Quietly Lead to IRS Penalties
A collection of money and forms and a clipboard that reads “Tax Deductions” – Shutterstock

6. Failing to Report Side Hustle Income Triggers Red Flags

Side gigs generate income that still falls under federal tax rules. The IRS tracks digital payment platforms and third-party processors closely. Missing even small amounts of side income can create discrepancies. These discrepancies often result in penalty notices or delayed refunds. Reporting all earnings keeps tax filings aligned with federal records.

7. Poor Recordkeeping Makes Tax Season Riskier

Receipts, invoices, and financial statements support every tax claim made on a return. Losing or failing to organize these documents weakens a taxpayer’s position during an audit. The IRS can reject deductions that lack proper proof. Digital tools and apps help track expenses throughout the year. Organized records reduce stress and improve filing accuracy.

8. Choosing the Wrong Filing Status Increases Tax Liability

Filing status affects tax rates, deductions, and eligibility for credits. Selecting the wrong category can raise taxes or reduce refunds. Common mistakes include incorrectly filing as single, head of household, or married filing separately. The IRS reviews filing status carefully when returns show inconsistencies. Choosing the correct status ensures fair and accurate taxation.

9. Ignoring IRS Notices Makes Penalties Grow Faster

IRS notices often start with simple correction requests or payment reminders. Ignoring these letters allows penalties and interest to accumulate quickly. The agency escalates enforcement when taxpayers fail to respond. Even minor issues can turn into larger financial problems over time. Responding early often prevents serious consequences.

The Real Cost of Small Tax Mistakes Add Up Fast

Small tax mistakes rarely stay small when the IRS gets involved. Each error, from missed deadlines to incorrect deductions, adds financial pressure that compounds over time. Many taxpayers discover that prevention costs far less than correction after penalties appear. Staying organized, reporting all income, and filing on time builds a strong defense against unnecessary fees. Tax rules may feel complicated, but consistent habits keep most problems away.

What tax mistake has caused the biggest surprise in your life, and how did it get resolved? We want to hear your tales of the IRS below in our comments.

You May Also Like…

The IRS’s “Math Error” Notice Could Cost You More Than You Think

IRS Audit Rates Are Increasing for Middle-Income Earners—Here’s Why

6 Mistakes People Make When Appealing an IRS Identity Check

7 “Trigger Words” the IRS Uses to Flag Returns Faster

The IRS Is Sending More “Math Error” Notices—Here’s What They Really Mean

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: 1099 income, deductions, Estimated taxes, financial mistakes, IRS penalties, IRS rules, side hustle taxes, tax audit, tax filing, tax mistakes, taxes

The IRS Is Cracking Down on Side Hustle Income Again in 2026

May 18, 2026 by Brandon Marcus Leave a Comment

The IRS Is Cracking Down on Side Hustle Income Again in 2026
A man on his bike, working for DoorDash – Shutterstock

The side hustle economy keeps booming across the United States, but the IRS now watches every dollar more closely than ever before. Gig apps, online marketplaces, and payment platforms continue to fuel extra income streams for millions of Americans, and tax rules struggle to keep up with that rapid growth. In 2026, the IRS steps up enforcement efforts that target unreported or underreported side hustle earnings with sharper reporting systems and tighter compliance checks. Freelancers, part-time sellers, rideshare drivers, and digital creators all feel the impact of these changes in real time.

Financial transparency no longer feels optional, especially when platforms automatically share income data with federal systems. This shift forces everyday earners to pay closer attention to how money moves through their accounts. Side income still offers opportunity, but the rules now demand far more precision and documentation than before.

Why the IRS Is Zeroing In on Side Hustle Income in 2026

The IRS focuses heavily on side hustle income because millions of Americans now rely on gig work as either supplemental or primary income. Platforms like Etsy, Uber, DoorDash, and PayPal automatically track transactions, which makes underreporting easier for the IRS to detect. Technology upgrades inside federal systems now allow faster matching of reported income versus actual payments received. Tax gaps widen when people forget or misunderstand reporting requirements, especially with multiple income streams. The IRS responds by tightening enforcement to close those gaps and boost overall compliance.

This crackdown does not target small earners unfairly, but it does require more accuracy from everyone participating in the gig economy. The agency now uses advanced data matching tools that flag inconsistencies within seconds instead of months. Digital payment networks feed structured reports directly into IRS databases, which reduces blind spots significantly. Side hustle growth created a massive shift in the tax landscape, and enforcement now catches up with that reality. Anyone earning outside a traditional paycheck now faces higher scrutiny and clearer expectations.

What Counts as Taxable Side Hustle Income Today

Taxable side hustle income includes far more than people often realize, and that confusion creates serious risk during tax season. Any money earned from freelance work, online sales, gig driving, or digital services qualifies as taxable income under IRS rules. Even casual selling through apps or marketplaces counts when profits exceed minimal thresholds. Cash payments, digital transfers, and platform deposits all fall under reporting requirements when tied to services or goods. The IRS treats side income the same as traditional wages when it comes to taxable responsibility.

Many people still assume small earnings fall outside reporting rules, but that assumption leads to penalties over time. Hobby income may seem informal, yet consistent profit-making activity pushes it into taxable territory quickly. Expenses tied to side hustles may reduce taxable income, but proper recordkeeping becomes essential. The IRS expects clear documentation that shows both income and legitimate business costs. Without records, deductions disappear, and tax liability increases faster than expected.

New Reporting Rules That Catch More Freelancers Off Guard

New reporting rules continue to expand across digital payment platforms, and those changes affect freelancers at every income level. The IRS pushes stricter 1099-K reporting standards that require third-party payment processors to report more transactions than ever before. Even smaller payments now trigger reporting when cumulative activity reaches lower thresholds. This change increases visibility for freelancers who rely on apps for client payments. Financial platforms now act as direct reporting intermediaries between users and the IRS.

These updates often surprise part-time earners who never considered themselves business operators. A few hundred dollars per month from multiple clients can now generate official tax documents automatically. Freelancers who rely on Venmo, PayPal, Cash App, or similar tools now receive far more detailed reporting statements. The IRS uses this data to cross-check self-reported income with platform submissions. Mismatches trigger notices quickly, which leaves little room for oversight or error.

The IRS Is Cracking Down on Side Hustle Income Again in 2026
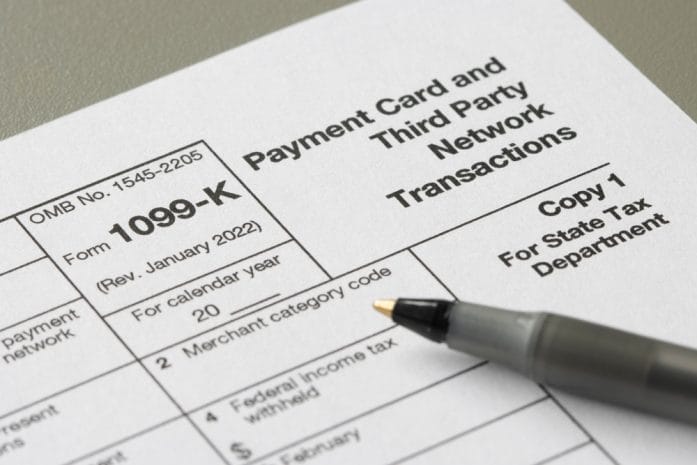
A blank 1099-K form – Shutterstock

Smart Ways to Stay Ahead of IRS Scrutiny Without Panic

Strong organization helps side hustlers stay ahead of IRS expectations without feeling overwhelmed during tax season. Clear tracking systems for income and expenses create an immediate safety net when filing returns. Many earners use spreadsheets or accounting apps to separate personal and business transactions effectively. Consistent recordkeeping reduces stress and prevents last-minute scrambling when tax documents arrive. Organized finances also help identify deductions that reduce overall taxable income.

Professional guidance can also help clarify confusing rules without adding unnecessary stress. Tax professionals often spot deductions and reporting strategies that casual filers miss entirely. Estimated tax payments help prevent large surprises when filing deadlines arrive. Separate business accounts create cleaner financial records and reduce the risk of mixing personal spending with taxable income. Careful planning gives side hustlers more control and fewer surprises when IRS notices appear.

What This Crackdown Means for Everyday Earners Moving Forward

The 2026 IRS crackdown signals a long-term shift toward full visibility in the gig economy rather than a short-term enforcement wave. Side hustles remain a powerful income tool, but they now operate inside a much stricter reporting environment. Digital payment tracking continues to eliminate gaps that once allowed informal earnings to go unnoticed. Workers who adapt quickly gain more stability and fewer tax-season surprises. Those who ignore the changes risk penalties, interest charges, and unnecessary stress.

What changes stand out most in your own side hustle experience, and how do you plan to adjust going forward?

You May Also Like…

The IRS’s “Math Error” Notice Could Cost You More Than You Think

IRS Audit Rates Are Increasing for Middle-Income Earners—Here’s Why

The IRS’s New 1099-K Threshold Could Catch Side Hustlers Off Guard

7 Side Hustles Compatible with a Slower Pace

Side Hustles That Look Legit—Until They Break Tax Laws

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: 1099-K, 2026 taxes, freelance income, gig economy, IRS, IRS audit, PayPal reporting, self-employment tax, side hustle, small business income, tax season, taxes, Venmo taxes

Why More Americans Are Getting Tax Notices Over Payment App Transactions

May 18, 2026 by Brandon Marcus Leave a Comment

Why More Americans Are Getting Tax Notices Over Payment App Transactions
The PayPal app on a smartphone – Shutterstock

A growing number of Americans now open their mailboxes to find IRS notices tied to money sent through apps like Venmo, Cash App, and PayPal. What once felt like casual digital convenience now sits under a much brighter spotlight from federal tax enforcement. The shift doesn’t just affect side hustlers or small business owners—it reaches everyday users who never expected tax paperwork from splitting dinner or selling used furniture online.

The IRS continues tightening reporting rules as digital payments surge across the country, and that change now reshapes how people think about “personal” transactions. Many taxpayers now discover that activity they assumed stayed invisible no longer flies under the radar.

Why Payment Apps Now Trigger IRS Scrutiny

Payment apps exploded in popularity as Americans embraced fast, cashless transactions for everything from rent splits to weekend gig work. The IRS responded by increasing oversight because these platforms now move billions of dollars every year without traditional banking structures. Federal officials aim to capture income that previously went unreported, especially earnings from side hustles and informal work. This shift creates a new reality where digital convenience directly connects to tax responsibility. Many users now realize that labeling money as “friends and family” does not automatically remove tax obligations if it reflects income.

The IRS does not randomly target users but instead relies on data matching from payment processors. Platforms now issue tax documents when users cross certain reporting thresholds, which automatically flags activity for review. That process means even small sellers on online marketplaces can trigger notice letters if their activity appears consistent and income-like. Gig workers, resellers, and freelancers face the highest exposure because their income often flows through these apps. This enforcement trend signals a broader push toward full visibility in the digital economy.

How 1099-K Forms Changed the Game for Everyday Users

The 1099-K form plays a major role in the rise of tax notices tied to payment apps. This form reports payment activity that meets federal thresholds and sends that information directly to both the IRS and the user. In recent years, lawmakers pushed to lower reporting thresholds, which expanded the number of Americans who receive these forms. Even small-scale sellers now find themselves included in reporting systems that once focused only on high-volume businesses. That change dramatically widened the net for tax reporting compliance.

Many users misunderstand how the IRS interprets 1099-K data, which creates confusion during tax season. The form does not automatically mean someone owes taxes on every dollar shown, but it does signal income that requires explanation. The IRS compares these reports with filed tax returns to identify mismatches or missing income. When discrepancies appear, the agency issues notices asking taxpayers to clarify or amend filings. This system pushes more responsibility onto individuals to track and document every digital transaction carefully.

Common Mistakes That Lead Straight to IRS Notices

One of the biggest mistakes involves mixing personal payments with business income in the same app account. Users often forget that selling old items, receiving freelance payments, or collecting gig income counts as taxable activity. That blending creates confusion when the IRS reviews transaction histories tied to a 1099-K form. Even small inconsistencies between reported income and app activity can trigger automated notices. These errors often start with casual use of payment apps that later turn into income channels.

Another common issue involves poor recordkeeping across multiple platforms. Many users rely on memory instead of tracking spreadsheets or financial tools, which leads to missing documentation during tax filing. The IRS expects taxpayers to substantiate income and deductions with clear records, not estimates. When users cannot explain transaction patterns, the agency assumes underreporting and sends follow-up letters. Strong recordkeeping habits reduce the risk of unnecessary audits or penalties.

Why More Americans Are Getting Tax Notices Over Payment App Transactions
A magnifying glass on the IRS website – Shutterstock

What the IRS Looks for When Reviewing Payment App Activity

The IRS focuses on patterns rather than single transactions when reviewing payment app data. Regular deposits labeled as goods or services raise more attention than occasional peer-to-peer transfers. Consistency signals business activity, which pushes the agency to verify whether the taxpayer reported income correctly. Large spikes in activity compared to prior years also trigger automated review systems. These checks help the IRS identify unreported earnings across the gig economy.

The agency also compares reported income across multiple data sources to identify gaps. Banks, payment processors, and employer filings all feed into IRS systems for cross-referencing. When numbers do not align, the IRS sends notices requesting clarification or correction. Taxpayers who respond quickly and provide documentation often resolve issues without penalties. Delays or incomplete responses, however, increase the likelihood of further scrutiny.

The New Reality of Digital Payments and Tax Responsibility

Digital payment apps now function as financial ecosystems rather than simple money-transfer tools. That evolution brings convenience, but it also brings stronger tax accountability across nearly every transaction type. Americans who rely on these platforms for side income now face expectations that match traditional business reporting standards. The IRS continues refining its systems to capture more digital earnings, which means compliance becomes less optional and more automatic. This shift marks a permanent change in how everyday financial activity interacts with federal tax rules.

Payment apps reshaped how Americans send and receive money, but they also reshaped how the IRS tracks income across the country. What steps should users take today to avoid surprises from tomorrow’s tax rules?

You May Also Like…

The IRS’s “Math Error” Notice Could Cost You More Than You Think

IRS Audit Rates Are Increasing for Middle-Income Earners—Here’s Why

7 “Trigger Words” the IRS Uses to Flag Returns Faster

Digital Payment Apps Could Soon Become Mandatory for Federal Benefits

What Happens If You Cash Out a 529 Plan in 2026?

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: tax tips Tagged With: 1099-K, Cash App, digital payments, freelance income, gig economy, IRS, payment apps, PayPal, Small business, tax notices, tax reporting, taxes, Venmo

New Rule Requires Venmo and PayPal Users to Verify Tax Info—or Risk Losing Access

May 16, 2026 by Brandon Marcus Leave a Comment

New Rule Requires Venmo and PayPal Users to Verify Tax Info—or Risk Losing Access
Someone using Venmo in front of the PayPal logo – Shutterstock

Digital payments keep reshaping how money moves across the United States, but a new layer of scrutiny now changes the game for millions of users. Venmo and PayPal users face growing pressure to verify tax information as financial regulators push for tighter reporting standards. Platforms that once felt casual and frictionless now sit under the same compliance spotlight as traditional banks. Small transactions between friends, side hustle payouts, and freelance income all now fall into a more structured financial reporting system. That shift signals a major turning point in how everyday money transfers get tracked and reported.

The push for tax verification connects directly to broader federal efforts aimed at closing reporting gaps in digital income. Payment platforms must now confirm taxpayer details for users who cross certain earning thresholds or trigger reporting requirements. Without verified information, accounts can face restrictions, payment holds, or even temporary loss of access to sending and receiving funds. Many users only notice the change when a transaction suddenly fails or a notification requests updated tax documentation.

Why Venmo and PayPal Now Demand Tax Verification

Venmo and PayPal now operate under stricter financial reporting rules that align more closely with IRS expectations. These platforms must collect accurate taxpayer information such as Social Security numbers or Employer Identification Numbers for qualifying accounts. The shift connects to expanded reporting requirements that target income earned through digital payment apps, especially in gig work and freelance transactions. Even casual sellers and side hustlers may now trigger verification requests if their transaction volume or total payments exceed reporting thresholds. This change aims to improve tax transparency and reduce underreported income across digital ecosystems.

The IRS continues to increase oversight of third-party payment processors as online income grows across the country. Platforms now flag accounts that show consistent incoming payments labeled as goods and services instead of personal transfers. Users who ignore verification prompts may experience delayed deposits or limited access to key features like instant transfers. Financial systems now prioritize compliance early in the user journey rather than after issues arise. This approach creates a tighter connection between everyday digital spending and official tax reporting systems.

What Happens If Users Ignore Verification Requests

Account restrictions often begin with simple limitations on sending or receiving money until users submit tax information. Venmo and PayPal typically send repeated alerts before escalating restrictions, but delays can still interrupt cash flow. Freelancers who rely on quick payments for services may feel the impact within hours of a flagged transaction. The platforms may also freeze certain features, including card withdrawals or business transaction capabilities. These safeguards protect compliance but can surprise users who never previously treated these apps as financial institutions.

Long-term noncompliance creates more serious consequences, including potential account suspension or mandatory identity verification checks. Payment processors now coordinate more closely with tax authorities to ensure reported income matches user records. Users who repeatedly ignore requests risk losing access to transaction history needed for tax filing. Business accounts face even stricter enforcement due to higher transaction volumes and commercial activity classification. These rules push users toward treating digital wallets with the same seriousness as bank accounts.

New Rule Requires Venmo and PayPal Users to Verify Tax Info—or Risk Losing Access
A magnifying glass looking at Venmo online – Shutterstock

Who Feels the Biggest Impact From These Rules

Gig workers and freelancers experience the strongest impact because they rely heavily on platforms like Venmo and PayPal for income. Delivery drivers, tutors, designers, and consultants often receive frequent payments that quickly reach reporting thresholds. Casual sellers on marketplaces also face increased scrutiny when payments shift from occasional to consistent activity. Even hobby sellers who occasionally move items online may see unexpected verification prompts. The system now blurs the line between casual use and business activity.

Younger users and part-time workers also encounter confusion when personal transactions trigger compliance checks. A friend sending payment for shared expenses might look different from business income if the transaction descriptions or patterns shift. Many users underestimate how quickly small payments add up over a calendar year. Tax reporting systems now analyze cumulative activity instead of single transactions alone. This shift forces users to track digital payments more carefully than ever before.

How Users Can Stay Ahead of Compliance Changes

Users can avoid disruptions by verifying tax information early instead of waiting for platform prompts. Updating Social Security numbers, business details, and legal names helps payment apps maintain uninterrupted service. Tracking incoming payments throughout the year also helps users understand when reporting thresholds might apply. Many financial advisors recommend separating personal and business transactions to reduce confusion during tax season. These habits reduce the risk of unexpected account restrictions.

Staying organized also helps users prepare for tax filings without scrambling for missing records. Digital payment histories now play a major role in determining taxable income for many independent earners. Platforms increasingly send annual summaries that align with IRS reporting forms like 1099-K documentation. Users who proactively review these summaries can catch discrepancies early and avoid penalties. Financial awareness now matters as much as convenience in the modern payment landscape.

What This Means for Everyday Digital Money

Digital wallets no longer function as informal money-sharing tools without oversight or structure. Venmo and PayPal now sit firmly inside a regulated financial ecosystem that tracks income and verifies identity. This shift reflects a broader national move toward transparency in digital financial activity. Users who adapt early avoid disruptions and maintain smoother access to funds. The future of digital payments now ties convenience directly to compliance.

Payment apps continue evolving into full financial platforms that mirror traditional banking expectations. That evolution brings stronger protections but also more responsibility for users who rely on them daily. Tax verification rules signal only the beginning of more structured oversight in the digital economy. Users who stay informed and organized will navigate these changes with fewer surprises. The landscape now rewards proactive financial management over casual usage habits.

How do you feel about these changes in Venmo and PayPal rules, and do they make digital payments feel more secure or more complicated?

You May Also Like…

The Venmo Privacy Setting That Can Trigger Unwanted Tax Reporting

IRS Warning: That Venmo Payment for Your Garage Sale Just Triggered a Surprise Tax Bill

7 “Trigger Words” the IRS Uses to Flag Returns Faster

9 Digital Payment Habits That Banks Are Quietly Flagging in 2026

5 Digital Banking Changes That May Be Adding New Fees Without Notice

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Technology Tagged With: 1099-K, account verification, digital payments, fintech, gig economy, IRS reporting, money transfer apps, online payments, PayPal, tax compliance, taxes, Venmo

Millions Of Americans Are Missing Out On The SALT Deduction

May 16, 2026 by Brandon Marcus Leave a Comment

Millions Of Americans Are Missing Out On The SALT Deduction
A piggy bank next to a SALT deduction placard – Shutterstock

The SALT deduction, which stands for state and local taxes, continues to play a significant role in how Americans calculate their federal tax bills. Many households in high-tax states rely on this deduction to soften the blow of property taxes, income taxes, and sales taxes. Federal tax law allows taxpayers to deduct certain state and local taxes from their taxable income, which can lower the amount owed to the IRS. However, not everyone realizes how this deduction works or how much money it can potentially save. That gap in awareness leads many households to leave real money on the table every single year.

High-income and middle-class families in expensive regions feel the impact most strongly when they overlook SALT deductions. States with higher living costs often come with higher property taxes and state income taxes, which makes the deduction even more relevant. Without it, taxpayers face a heavier federal tax burden that compounds already steep local costs. Many filers assume tax software automatically optimizes everything, but mistakes and limitations still happen. The result creates a quiet but widespread financial blind spot across the country.

The $40,000 Cap That Changed Everything

The federal government recently upgraded to a $40,000 cap on SALT deductions, and that single rule reshaped tax outcomes for millions of households. Before the cap, taxpayers in high-tax states often deducted far more in combined state and local taxes. Now, many filers hit that ceiling quickly, especially homeowners with significant property tax bills. This change hit married couples and families in high-cost regions particularly hard because their tax liability often exceeds the cap. The cap effectively limits how much relief taxpayers can receive, no matter how high their local taxes climb.

This restriction creates frustration because it disconnects local tax burdens from federal tax relief. A homeowner in New Jersey or California can pay far more than $40,000 in state and local taxes yet only deduct a fraction of that amount. The mismatch leads many people to feel penalized for living in areas with higher costs of public services and housing. Taxpayers often miss the full impact until they review their itemized deductions closely during tax season. Once they see the numbers, the limitation becomes impossible to ignore.

Smart Moves Taxpayers Use to Work Around SALT Limits

Taxpayers across the country look for legal ways to reduce the impact of the SALT cap by adjusting how they manage deductions and expenses. Some homeowners choose to bunch property tax payments into a single tax year when possible, which can help maximize itemized deductions in that year. Others evaluate whether itemizing still makes sense compared to taking the standard deduction, which increased significantly in recent years. Financial planners often encourage clients to compare both options carefully before filing. These small adjustments can lead to meaningful savings depending on income level and local tax rates.

Charitable giving also plays a role in overall tax strategy because it can increase total itemized deductions. Many households in high-tax states combine donation planning with tax timing strategies to improve overall efficiency. Some taxpayers also review mortgage interest deductions, which still apply under certain conditions and can push total deductions higher. Professional tax advisors often highlight the importance of year-round planning instead of last-minute filing decisions. These strategies do not eliminate the SALT cap, but they help soften its impact in practical ways.

Millions Of Americans Are Missing Out On The SALT Deduction
A notebook with “State & Local Income Tax” written in it – Shutterstock

Why the SALT Cap Still Shapes Tax Bills Across America

The SALT deduction cap continues to influence financial decisions, especially for homeowners in expensive housing markets and high-tax states. Families often discover that their expected federal tax savings shrink significantly once the cap enters the equation. This shift forces many households to rethink budgeting, housing choices, and long-term financial planning. Even with other deductions available, the SALT cap remains one of the most impactful limitations in the federal tax code. Its effects ripple through property markets, household budgets, and even relocation decisions.

Tax policy debates continue to revisit the SALT deduction because of its uneven impact across income levels and geographic regions. Some taxpayers benefit less from federal tax relief simply because their local tax structure pushes them against the cap. That reality keeps SALT at the center of ongoing discussions about fairness and tax equity. For now, millions of Americans continue to feel its effects each filing season, whether they notice it or not. Awareness remains the first step toward minimizing the financial impact and making smarter tax decisions.

What changes would make the SALT deduction feel fairer for everyday taxpayers dealing with high local taxes?

You May Also Like…

7 Little-Known Deductions That Could Vanish After the One Big Beautiful Bill

Why Large Itemized Deductions Can Trigger a 2026 Refund Review

How The SALT Deduction Caps Squeezed Many Middle-Income Taxpayers

Florida Has 0% Income Tax — But Seniors Still Spend Thousands a Year on Essentials

Unreported Income: How the IRS Finds Out (and What It Costs You)

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: tax tips Tagged With: federal taxes, IRS, itemized deductions, middle class taxes, property tax, SALT deduction, state taxes, tax policy, tax reform, tax savings, taxes, US economy

What Happens If You Cash Out a 529 Plan in 2026?

May 15, 2026 by Brandon Marcus Leave a Comment

What Happens If You Cash Out a 529 Plan in 2026?
A notebook with the words “529 plan” written on it – Shutterstock

College costs continue to climb faster than a summer gas bill, so millions of Americans stash money inside 529 plans to protect their future budgets. Those accounts offer juicy tax advantages, flexible investment choices, and powerful long-term growth, but cashing one out without a strategy can create a financial mess in a hurry. Families often assume they can pull money whenever they want without consequences, then discover the IRS waited patiently around the corner with a calculator and a penalty form.

New rule changes in recent years added flexibility to 529 plans, yet plenty of confusion still surrounds withdrawals, rollovers, and non-education spending. Anyone who plans to tap a 529 account in 2026 needs a clear roadmap before touching a single dollar.

The IRS Still Wants Its Slice of the Pie

A qualified withdrawal for tuition, books, housing, and approved education expenses usually slides through without federal taxes, which explains why 529 plans remain wildly popular with parents and grandparents. Trouble starts when account holders cash out funds for vacations, credit card debt, luxury purchases, or random expenses that carry zero educational connection. The IRS taxes the earnings portion of a non-qualified withdrawal as ordinary income, and the government also slaps a 10% penalty on those earnings in most situations. Someone who contributed $40,000 and grew the account to $55,000 would owe taxes and penalties only on the $15,000 gain instead of the original contribution amount. That detail softens the blow slightly, although the final bill can still sting harder than a surprise root canal.

Many families forget that states often jump into the action too, especially when residents claimed state tax deductions during earlier contribution years. Several states demand repayment of those tax breaks after a non-qualified withdrawal, which can pile extra costs onto an already painful federal hit. Financial advisors frequently warn clients about this double-whammy because state clawbacks catch people off guard every single year. Timing matters as well because a large withdrawal can push taxable income higher and create ripple effects across tax credits or financial aid calculations. A quick cash-out decision during a stressful moment can easily turn a helpful savings account into an expensive headache.

New 529 Flexibility Changes the Game in 2026

Recent federal rule updates gave 529 plans a much-needed glow-up by expanding the ways families can use leftover money. Starting in 2024, eligible beneficiaries gained the ability to roll unused 529 funds into a Roth IRA under specific conditions, and that option continues in 2026 with lifetime rollover limits attached. Families who feared overfunding a college account suddenly gained a backup plan that rewards long-term saving instead of punishing cautious parents. The rollover still requires careful attention because the account must meet age requirements and annual Roth contribution limits still apply. Smart savers now view 529 plans less like a rigid education vault and more like a flexible financial tool with several escape routes.

That flexibility does not create a free-for-all, however, because strict guidelines still control how these transfers work. The beneficiary must own earned income during the rollover year, and account holders cannot simply dump massive balances into a Roth IRA overnight. Congress designed these rules to encourage education savings rather than create a giant tax shelter for wealthy investors. Financial planners increasingly recommend reviewing older 529 accounts now because some families may benefit more from a gradual rollover strategy than a straight cash withdrawal. A thoughtful plan can preserve tax advantages, avoid penalties, and keep long-term retirement goals moving in the right direction.

Scholarships and Other Exceptions Can Save Money

Several exceptions allow families to dodge the dreaded 10% penalty even after a non-qualified withdrawal, which surprises people who assume the IRS never shows mercy. Scholarship recipients can withdraw an amount equal to the scholarship without paying the additional penalty, although ordinary income taxes on earnings still apply. Military academy attendance, disability, and certain death-related circumstances can also trigger penalty exceptions under federal rules. These carveouts create breathing room for families whose original education plans shifted unexpectedly after years of careful saving. A student who lands a full-ride scholarship should celebrate first and panic about the 529 balance much later.

Families often overlook another important strategy that avoids penalties entirely by changing the beneficiary to another eligible relative. A younger sibling, cousin, spouse, or even future grandchild can use those funds later without resetting the entire account. That flexibility helps multigenerational families keep educational money working instead of surrendering chunks of growth to taxes and penalties. Parents who rushed into cashing out leftover balances during previous years sometimes regretted the move once younger children approached college age. Patience often pays better returns than panic when a large 529 balance remains after graduation season ends.

What Happens If You Cash Out a 529 Plan in 2026?
A bunch of coins and small graduation cap, symbolzing a scholarship – Shutterstock

Cashing Out at the Wrong Time Can Wreck a Budget

A giant 529 withdrawal can create unexpected tax complications that spill far beyond the account itself. Higher taxable income may reduce eligibility for valuable credits, increase Medicare premium costs later, or create bigger tax bills than families anticipated during retirement planning. Investment markets add another layer of risk because cashing out during a downturn can lock in losses after years of disciplined contributions. Savvy account holders usually coordinate withdrawals with tuition schedules, market conditions, and yearly tax planning instead of making emotional decisions. Financial professionals constantly stress that timing matters almost as much as the withdrawal reason itself.

Families also need to track receipts carefully because the IRS expects documentation that matches qualified education expenses with withdrawal dates. Sloppy recordkeeping creates unnecessary stress during tax season and raises the risk of audits or reporting mistakes. Many experts recommend keeping digital copies of tuition bills, housing invoices, and textbook purchases for several years after withdrawals occur. A few extra minutes of organization can save hundreds or thousands of dollars later when questions arise about account activity. Strong planning, careful timing, and detailed records transform a 529 plan from a confusing financial puzzle into a powerful money-saving tool.

The Smartest Move Starts Before the Withdrawal

529 plans still rank among the strongest education savings tools available in America, but cashing one out carelessly can torch valuable tax advantages in record time. Families who study the rules, review recent law changes, and coordinate withdrawals with broader financial goals usually keep far more money in their pockets. The rise of Roth IRA rollover options gives savers more flexibility than previous generations ever enjoyed, which makes thoughtful planning even more important in 2026. Every withdrawal decision carries tax consequences, timing concerns, and long-term financial effects that deserve serious attention before anyone hits the transfer button. A little preparation today can prevent a painful tax surprise tomorrow and keep years of hard-earned savings working exactly as intended.

What would happen to a leftover 529 balance in your household, and would a Roth IRA rollover change the way your family saves for college?

You May Also Like…

The Sandwich Generation Crunch: Saving for College While Supporting Parents

Missed Notices, Lost Credits: How Student Loans Are Trapping Borrowers Again

New FAFSA Rules in Could Change When — and How — Families Save for College

Student Loans Forgiven Are Now Taxable In 2026 — Set Money Aside for Tax Bills

9 Financial Plans That Collapse the Moment Real Life Gets Involved

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: 529 plans, College Savings, education savings, family finances, investing, IRS rules, money management, Personal Finance, Planning, savings accounts, taxes, tuition costs

5 Financial Transactions That Now Trigger the IRS’s New 1% Remittance Tax

May 15, 2026 by Brandon Marcus Leave a Comment

5 Financial Transactions That Now Trigger the IRS’s New 1% Remittance Tax
The letters “IRS” on top of a pile of cash – Shutterstock

Sending money overseas suddenly got more expensive, and plenty of Americans have no idea the change even happened. The IRS’s new 1% remittance tax now applies to certain international money transfers, adding another fee to transactions that millions of families already depend on every month. For households sending support to relatives abroad, even a small percentage can snowball into a serious annual expense.

The tax especially affects cash-based transfers, prepaid cards, money orders, and other financial tools commonly used outside traditional banking systems. Before sending another dollar overseas, Americans need to know exactly which transactions now trigger the extra charge and why the costs may climb faster than expected.

1. Cash Transfers Sent Through Money Transfer Services

Americans who regularly send money overseas through services like Western Union or MoneyGram now face a new financial wrinkle that could quietly chip away at every transaction. The IRS’s new 1% remittance tax targets certain international cash transfers, especially those funded through cash, money orders, or similar payment methods. That means a $1,000 transfer could suddenly cost an extra $10 before regular service fees even enter the picture. While that amount may sound small at first glance, families who send money monthly could lose hundreds of dollars every year. Financial experts already warn that frequent remittance users may need to rethink how they move money internationally.

The tax mainly affects people who use traditional walk-in transfer locations rather than digital banking tools tied directly to verified accounts. A worker sending emergency money to relatives abroad after a hurricane or medical crisis may suddenly face extra costs during an already stressful moment. Critics argue the rule unfairly hits lower-income households that rely heavily on cash-based financial services. Banks and fintech companies have started promoting account-to-account transfers as a way to legally avoid the added charge. Americans who still prefer cash transactions should carefully check receipts because the tax may appear as a separate line item rather than getting bundled into regular fees.

2. International Transfers Funded With Money Orders

Money orders once carried a reputation as one of the safest low-tech ways to send funds overseas, especially for people without traditional bank accounts. Now they sit directly in the IRS spotlight because the new remittance tax applies to many transfers funded this way. A customer purchasing a $500 money order to send abroad could face both the money order fee and the additional 1% tax. That combination can make older payment methods far more expensive than many consumers expect. Some neighborhood financial centers have already posted warning signs explaining the added charges to confused customers.

The rule especially affects older Americans and immigrant households that still trust paper-based payment methods over mobile apps or online banking platforms. Many people grew comfortable using money orders after years of avoiding fraud risks tied to digital systems. Unfortunately, the IRS rule does not care whether the sender chooses paper for security, convenience, or habit. Financial advisors now encourage consumers to compare costs between money orders and direct bank transfers before sending large sums abroad. Even a few percentage points in savings can matter when someone regularly supports family members in another country.

3. Certain Prepaid Debit Card Transfers

Prepaid debit cards exploded in popularity over the last decade because they offered flexibility without requiring a traditional checking account. Millions of Americans use reloadable cards to pay bills, shop online, and send money internationally. Under the new IRS remittance tax framework, some international transfers funded through prepaid cards now trigger the extra 1% charge. The key factor usually depends on how the card gets funded and whether the transaction qualifies as a remittance under federal guidelines. Consumers who assumed prepaid cards offered a loophole may discover an unpleasant surprise at checkout.

This change creates particular headaches for gig workers and younger consumers who use prepaid cards as their primary financial tool. Someone driving for delivery apps or working freelance jobs may keep most earnings on a reloadable debit card instead of a bank account. Sending money overseas from that card could now cost more than expected, especially when paired with existing transfer fees and exchange-rate markups. Financial analysts expect more people to migrate toward digital bank accounts that connect directly to ACH systems. The IRS has not hidden the fact that it wants greater transaction visibility, and prepaid products often operate in murkier territory than traditional banking services.

4. Cross-Border Cash Payments Made Through Retail Kiosks

Retail payment kiosks inside grocery stores, convenience shops, and check-cashing centers became wildly popular because they offered quick international transfers without much paperwork. Customers could walk in with cash, complete a short form, and send money abroad within minutes. The new IRS remittance tax now applies to many of those cash-funded kiosk transactions. A customer sending $2,000 through one of these services may now pay an extra $20 on top of standard transfer costs. That sudden increase has already sparked frustration in communities where kiosk services dominate the local financial landscape.

These kiosks often serve workers who do not maintain traditional bank accounts or who need immediate transfer options outside normal banking hours. Construction workers, restaurant employees, and seasonal laborers frequently rely on late-night cash transfers to support relatives overseas. The IRS argues the tax creates greater consistency across remittance channels while helping fund federal programs. Critics counter that the policy effectively punishes working-class households that lack easy access to cheaper digital alternatives. Consumers should now compare several transfer methods before sending large amounts because the cost difference between providers can vary dramatically.

5 Financial Transactions That Now Trigger the IRS’s New 1% Remittance Tax
A digital money transfer – Shutterstock

5. Some Cryptocurrency-to-Cash International Transfers

Cryptocurrency enthusiasts once believed digital assets would completely bypass old-school banking regulations and government oversight. That belief now looks shakier as the IRS tightens rules surrounding international money movement. Certain crypto-to-cash transfers that convert digital currency into cash for recipients abroad may trigger the new 1% remittance tax. The exact rules depend on how the transaction gets processed and whether regulated intermediaries participate in the transfer. Crypto investors who assumed blockchain technology automatically shielded them from remittance-related fees may need a serious reality check.

This area remains especially confusing because cryptocurrency regulations continue evolving at breakneck speed across the United States. One transfer platform may classify a transaction differently than another, creating inconsistent costs for consumers. Financial compliance experts strongly recommend reviewing exchange policies before sending large crypto-funded transfers overseas. A person converting Bitcoin into cash for a relative abroad could face taxes, exchange fees, and volatility losses all at once. The IRS clearly wants digital assets to operate inside the same regulatory framework as traditional financial systems, and this remittance tax signals that tighter oversight has already arrived.

The Bigger Money Lesson Hiding Behind This Tax

The new IRS remittance tax may only add 1% to certain transactions, but its ripple effects could hit millions of Americans who regularly send money overseas. Families already juggling inflation, rising rent, and higher grocery bills now face another layer of financial pressure every time they move money internationally. The smartest consumers will compare transfer methods carefully, read fee disclosures closely, and explore lower-cost digital banking options before making future transfers. Small percentage-based fees often feel harmless until they pile up month after month across an entire year. In personal finance, tiny leaks can sink a budget faster than most people realize.

Which of these new remittance tax rules surprised you the most, and do you think the government should tax international money transfers at all?

You May Also Like…

Tennessee Residents Still Pay Federal Taxes on Investment Income Despite State Changes

Wyoming Property Tax Relief Deadline: Missing the May Filing Window Can Cost Homeowners Thousands

5 Reasons Your 401(k) Could Trigger a Tax Surprise Next Year

7 Inheritance Protection Moves: How Families Shield Assets From Creditors Under 2026 Rules

Rebuilding Credit and Confidence: Financial Recovery Tips for Post-Divorce Life

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: tax tips Tagged With: banking, financial transactions, international transfers, IRS, money transfers, Newsbreak, Personal Finance, remittance payments, remittance tax, saving advice, tax law, taxes

Overlooked Tax Credits That Could Save You Thousands This Year

May 15, 2026 by Brandon Marcus Leave a Comment

Overlooked Tax Credits That Could Save You Thousands This Year
A calculator with the words “tax credits” written on top of it – Shutterstock

Tax season usually sparks two emotions: dread and confusion. Most Americans scramble to find receipts, pray for a decent refund, and hope they didn’t accidentally anger the IRS with a typo. Meanwhile, billions of dollars in tax credits sit untouched every year because people simply don’t realize they qualify. That’s the frustrating part. Many of these credits reward completely normal life choices like going to school, upgrading a home appliance, saving for retirement, or caring for children.

Tax credits matter because they reduce taxes dollar for dollar, which makes them far more powerful than deductions. A $2,000 tax credit can literally erase $2,000 from a tax bill. Some credits even deliver refundable money back into a bank account. Yet countless taxpayers skip them because tax software moves too fast, forms look intimidating, or people assume they earn too much to qualify.

The Saver’s Credit Rewards People for Preparing Ahead

Retirement savings rarely feel exciting in the moment because the payoff sits decades away. The IRS decided to sweeten the deal with the Saver’s Credit, which many taxpayers completely overlook every year. This credit rewards low- and moderate-income workers who contribute to retirement accounts like a 401(k) or IRA. Depending on income and filing status, the credit can reach up to $1,000 for individuals or $2,000 for married couples filing jointly. Someone who contributed steadily during the year could score a meaningful tax break without changing anything at filing time.

The income limits catch many people off guard because they assume retirement incentives only benefit high earners. In reality, the Saver’s Credit specifically targets workers earning more modest incomes. For 2026, eligibility thresholds continue to cover millions of Americans, especially younger workers and part-time employees. Even gig workers and freelancers can qualify if they contribute to a retirement account. Financial planners often call this one of the most underused credits in the entire tax code because people focus on deductions and forget about direct credits.

Energy-Efficient Home Credits Continue Paying Off

Homeowners who upgraded windows, insulation, heat pumps, or HVAC systems over the last year could qualify for surprisingly generous tax credits. Federal clean energy incentives expanded significantly in recent years, yet many taxpayers still assume they only apply to expensive solar panel projects. Smaller home improvements now unlock valuable credits too. Energy-efficient exterior doors, qualifying water heaters, and upgraded electrical panels may all count toward savings. Some homeowners can claim credits worth hundreds or even thousands of dollars depending on the project.

The paperwork scares people away, but contractors often provide certification information that simplifies the process. Homeowners should keep receipts, product details, and installation records organized before filing taxes. The Energy Efficient Home Improvement Credit generally covers 30% of eligible costs, though annual limits apply to certain upgrades. Solar energy systems and battery storage projects can trigger even larger credits under separate clean energy programs. Rising utility bills make these upgrades attractive already, but the tax savings add another layer of financial relief.

Parents Often Miss Valuable Childcare Tax Breaks

Childcare costs now rival mortgage payments in many parts of America, which makes every tax break count. The Child and Dependent Care Credit helps families offset daycare, babysitting, preschool, and even summer day camp expenses in some situations. Many parents mistakenly confuse this credit with the Child Tax Credit and fail to claim both. Eligible families can receive a percentage of qualifying care expenses depending on income. That percentage may not erase the pain of childcare bills, but it can soften the blow significantly.

Working parents frequently miss this credit because they fail to save proper records throughout the year. Care providers must usually supply a taxpayer identification number for filing purposes. Families who use flexible spending accounts through employers should also pay close attention because coordination rules apply. Divorced parents sometimes stumble into confusion over who gets to claim the child-related benefits. Tax professionals regularly warn families to double-check eligibility because mistakes here happen constantly.

Education Credits Can Rescue Adults Returning to School

College students grab plenty of attention during tax season, but adults returning to school often leave money on the table. The Lifetime Learning Credit helps cover tuition, fees, and educational expenses for undergraduate courses, graduate programs, and professional development classes. Unlike some education tax breaks, this credit does not require full-time enrollment. Someone taking a single career-boosting class may still qualify. The maximum credit reaches $2,000 per return, which can dramatically reduce education costs.

Americans pursuing certifications, trade programs, or career changes frequently overlook this opportunity. Nurses completing continuing education requirements, tech workers learning new skills, and professionals earning specialized licenses may all qualify. Income phaseouts apply, but many middle-income households still remain eligible. The credit also carries flexibility because students can claim it for multiple years without the stricter limitations attached to other education incentives. Rising tuition costs make every available tax break more valuable than ever.

The Earned Income Tax Credit Still Goes Unclaimed

The Earned Income Tax Credit ranks among the largest anti-poverty programs in the country, yet millions of eligible Americans never claim it. Some taxpayers mistakenly believe the credit only applies to parents with children. Others assume they earn too much or too little to qualify. In reality, eligibility stretches across various income levels and family situations. Workers without children can sometimes qualify too, although families with children typically receive larger credits.

Refund amounts can become substantial very quickly. Families with multiple qualifying children may receive several thousand dollars back depending on earnings and filing status. The IRS estimates that billions in Earned Income Tax Credit money goes unclaimed every year because people misunderstand the rules. Gig workers, part-time employees, and workers with fluctuating income should pay especially close attention. Even someone who earned little during the year may still qualify for a meaningful refund through this program.

Overlooked Tax Credits That Could Save You Thousands This Year
A woman using tax software – Shutterstock

Small Details Can Lead to Big Refund Surprises

Tax credits reward behavior the government wants to encourage, but the system hides many of those incentives behind complicated rules and forgettable forms. That complexity causes countless Americans to miss refunds that could cover groceries, rent, debt payments, or emergency savings. A taxpayer who combines retirement contributions, education credits, and childcare benefits could potentially save thousands in a single filing season. That kind of money changes budgets fast. Smart taxpayers treat filing season like a financial treasure hunt instead of a rushed chore.

Tax software helps, but software only works well when users enter complete information. Missing receipts, skipped questions, or incorrect assumptions can leave valuable credits untouched. Financial experts often recommend reviewing last year’s return line by line before filing again because forgotten credits frequently repeat themselves. Americans who experienced major life changes this year should pay especially close attention to eligibility rules. A new child, career change, home upgrade, or retirement contribution could unlock savings that never appeared before.

Which overlooked tax credit surprised you the most, and have you ever discovered a refund opportunity at the last minute during tax season?

You May Also Like…

The New Remittance Transfer Tax Begins January 1—Here’s How It Works

The IRS Is Sending More “Math Error” Notices—Here’s What They Really Mean

Maryland Seniors: Filing Errors on Local Tax Credits Are Causing Residents to Lose Key Savings

Why Some Senior Tax Credits Disappear Once You File Jointly

Tennessee Residents Still Pay Federal Taxes on Investment Income Despite State Changes

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: tax tips Tagged With: Child Tax Credit, education credits, energy tax credits, IRS, Money Saving tips, Personal Finance, Planning, retirement savings, saving money, tax credits, Tax Deductions, tax refunds, taxes

  • « Previous Page
  • 1
  • …
  • 4
  • 5
  • 6
  • 7
  • 8
  • …
  • 22
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • 10 Tactics for Building an Emergency Fund from Scratch by Vanessa Bermudez
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald

Copyright © 2026 · News Pro Theme on Genesis Framework