• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Brandon Marcus

Retirement Redflag: 6 Withdrawal Moves That Could Drain Your Nest Egg Fast

December 10, 2025 by Brandon Marcus Leave a Comment

Here Are 6 Retirement Withdrawal Moves That Could Drain Your Nest Egg Fast
Image Source: Shutterstock.com

Retirement planning feels like climbing a mountain—years of slow, steady progress, all leading to the breathtaking moment you finally reach the summit. But one wrong step on the descent, especially when it comes to withdrawing your savings, can send you tumbling faster than you’d expect.

Many retirees assume that saving is the hard part and spending is the easy part, but the opposite is often true. Withdrawal mistakes can quietly sabotage decades of discipline, shrinking your nest egg in ways that feel almost invisible until it’s too late.

Before you take that first celebratory distribution, it’s worth understanding the sneaky withdrawal habits that can turn a comfortable retirement into a stressful scramble.

1. Taking Too Much, Too Soon

Withdrawing aggressively in the early years of retirement feels tempting, especially when you finally have the time to travel, relax, and enjoy life. But draining your accounts before they’ve had time to grow through your early retirement years can wreak havoc on long-term stability. Many retirees underestimate how quickly compounding can work in their favor if they keep withdrawals modest. What feels like harmless spending now can become a cascade of financial pressure later. The safest move is pacing yourself so your future self can still thrive twenty years down the line.

2. Ignoring Market Conditions While Withdrawing

Pulling money out during market downturns can compound losses faster than most retirees realize. When you withdraw in a down market, you’re selling more shares than you would during a stable or rising period, making it harder for your portfolio to recover. Many people assume withdrawals should stay consistent year after year, but flexibility is key to protecting your balance. Taking smaller withdrawals during downturns and larger ones during upswings can dramatically extend your nest egg’s lifespan. A little withdrawal strategy often outperforms blind consistency.

3. Forgetting About Required Minimum Distributions

Required Minimum Distributions, or RMDs, may sound like financial fine print, but ignoring them can cost you heavily. If you forget to take your RMDs, the penalties can be some of the harshest in the entire tax code. Many retirees mistakenly assume RMDs don’t matter until their late seventies, but planning for them early can save you headaches later. Taking strategic withdrawals before RMD age can reduce tax burdens and keep your retirement plan on track. A smart approach ensures your money works for you instead of triggering unnecessary fees.

4. Relying Entirely On One Account Type

Using a single retirement account as your primary withdrawal source may feel simple, but it’s rarely smart. Different accounts come with different tax consequences, and tapping just one can quickly push you into higher tax brackets. Retirees often overlook the power of mixing withdrawals from taxable, tax-deferred, and Roth accounts to maximize efficiency. With a little coordination, you can smooth out your tax bill and stretch your savings further. A diversified withdrawal plan is like a well-balanced meal—it keeps everything functioning smoothly.

Here Are 6 Retirement Withdrawal Moves That Could Drain Your Nest Egg Fast
Image Source: Shutterstock.com

5. Treating Your Retirement Like a Checking Account

Some retirees fall into the habit of pulling money whenever they want rather than following a structured withdrawal plan. This casual approach often leads to overspending and emotional decision-making, both of which can sink your financial stability. A retirement portfolio isn’t built for spontaneous, unplanned withdrawals—it needs rhythm, consistency, and strategy. Without those guardrails, retirees often discover too late that the money they assumed would last forever has quietly dwindled. Following a consistent plan helps keep both your budget and your confidence intact.

6. Forgetting How Inflation Eats Away At Your Money

Inflation may seem like a distant concept when your retirement portfolio feels large and healthy, but it can erode purchasing power faster than expected. Retirees who don’t adjust for inflation often withdraw too little at first and then too much later to compensate. This uneven pattern can destabilize even the most well-crafted financial plans. Understanding inflation-friendly investments and keeping withdrawals aligned with rising prices is crucial for long-term stability. Ignoring inflation doesn’t just reduce comfort—it can actively sabotage your financial future.

Protect Your Future By Planning Today

Retirement withdrawals aren’t just about pulling money from an account—they’re about maintaining a lifestyle that lasts as long as you do. With the right strategies, your nest egg can support you through years of adventure, rest, and personal fulfillment. Avoiding these withdrawal red flags helps ensure your savings stay strong instead of slowly slipping away.

If you’ve faced any surprising challenges with retirement withdrawals or learned lessons worth sharing, leave your thoughts or stories in the comments below.

You May Also Like…

Calculate Your True Retirement Number Using Our Exclusive Online Tool

How to Transition From Full-Time Work to ‘Semi-Retirement’ Smoothly

8 Home Upgrades Seniors Are Choosing Over Moving Into Facilities

5 Mistakes Young People Make About Their Financial Futures

7 Financial Surprises of Caring for Elderly Parents


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Retirement Tagged With: elderly workers, financial future, Money, money issues, nest egg, retire, retirees, Retirement, retirement plan, retirement planning, retirement red flags, saving money, senior citizens, seniors

5 Mistakes Young People Make About Their Financial Futures

December 9, 2025 by Brandon Marcus Leave a Comment

Here Are The Mistakes Young People Make About Their Financial Futures
Image Source: Shutterstock.com

The moment you start earning your own money, the world seems wide open—full of possibilities, adventures, upgrades, and “I’ll figure it out later” energy. It’s exciting, empowering, and a little dangerous in that sneaky, invisible way financial mistakes tend to be. Most young people feel like they have all the time in the world to get their money right, and that’s exactly what makes the early years so risky.

The habits you build now have long shadows, and the misconceptions you carry can quietly shape your financial future for decades. But the good news? Once you spot these mistakes, you can stop making them—and start building something strong, smart, and sustainable.

1. Believing Retirement Is A Problem For Future-You

So many young people assume retirement is some faraway milestone reserved for older adults who suddenly develop a love for yard tools and early dinners. The truth is that retirement planning hits hardest when you start early, because time—not income—is the real power player. When you put off contributing to retirement accounts, you’re not just delaying savings; you’re losing out on years of compound growth that could multiply your money effortlessly.

Even small contributions now can become huge cushions later, but you only get that advantage if you begin early. Future-you will thank you for thinking ahead instead of hoping everything magically works out.

2. Thinking Debt Doesn’t Matter As Long As You Keep Up With Payments

At first, having a credit card or a few small loans feels manageable—almost invisible—as long as you’re making your minimum payments. But high-interest debt is like a slow leak in your financial boat: you don’t always notice the damage until you’re sinking. Young people often underestimate how quickly interest snowballs, quietly eating away at money that could have gone toward savings, goals, or experiences that actually matter. The earlier you tackle debt, the easier it is to stay ahead of it, and the more flexibility you’ll have later in life. Treating debt lightly now can lock you into obligations you never expected.

3. Assuming A Higher Income Guarantees Financial Freedom

It’s easy to believe that once you land the right job or earn a higher salary, everything will finally fall into place. But lifestyle creep—the tendency to spend more as you earn more—creeps up faster than most people expect. Without good habits, a bigger income simply becomes a bigger opportunity to overspend, overextend, and under-save. Financial freedom comes from control, awareness, and choices, not just a big paycheck. If you learn to manage what you have well now, you’ll be unstoppable when you eventually level up.

4. Underestimating Emergency Expenses And Assuming “It Won’t Happen To Me”

Young people often have a sense of invincibility that pairs poorly with unpredictable expenses. Car repairs, medical bills, job changes, and surprise costs don’t ask permission before happening—they just show up. Without an emergency fund, even small mishaps can trigger financial spirals that take months or years to recover from.

Saving for emergencies isn’t pessimism; it’s financial armor that protects your future goals. If you build even a small safety net now, you’ll move through life with confidence instead of crossing your fingers and hoping for the best.

Here Are The Mistakes Young People Make About Their Financial Futures
Image Source: Shutterstock.com

5. Believing You Don’t Need A Budget If You “Feel Responsible Enough”

Many young people think budgeting is unnecessary, too restrictive, or only for people who struggle with money. But in reality, budgeting is the opposite: it’s the thing that gives you freedom to make better choices without guilt or confusion. Relying on your gut or memory can trick you into thinking you’re spending less than you are, and by the time you realize the truth, the damage is already done. A budget doesn’t limit you—it guides you, supports you, and helps you stay aligned with your actual goals instead of your impulses. When you know exactly where your money is going, you take control instead of drifting.

Your Future Starts Earlier Than You Think

Your financial future doesn’t begin “one day” when you feel older, wiser, or more prepared—it’s already happening right now. The choices you make today will shape your opportunities, freedom, and peace of mind in the years ahead. By recognizing these common mistakes, you can start making smarter decisions long before they become major setbacks. Your future self will appreciate every smart move you make today.

Have you spotted any of these mistakes in your own life? Give us all of your thoughts, experiences, or hard-earned lessons in the comments for others to learn from.

You May Also Like…

13 Things Young People Won’t Stop Doing That Elderly People Don’t Understand

What Is “Cash Stuffing” — And Why Everyone’s Doing It Again

7 Bold Assertions to Make About Your Financial Future Today

9 Important Questions to Ask Before Trading Options or Futures

Could Too Much Cash in the Bank Actually Hurt Your Financial Future


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Finance Tagged With: Budget, budgeting, Debt, emergency expenses, emergency funds, financial choices, financial freedom, financial future, financial mistakes, Income, mistakes, Money, money choices, money issues, money matters, Retirement, teens, young adults, young people

Alert Phase: 5 Tax Tricks You’ll Regret Ignoring Before Year-End

December 9, 2025 by Brandon Marcus Leave a Comment

Here Are The Tax Tricks You’ll Regret Ignoring Before Year-End
Image Source: Shutterstock.com

The final stretch of the year always hits with a strange mix of holiday excitement and mild financial panic. Suddenly, you’re juggling gift lists, travel plans, and the nagging realization that tax season is right around the corner waving a clipboard in your face. This is the moment when smart decisions make a massive difference, and tiny mistakes can cost you big if you’re not paying attention.

There are a few clever moves you can still make—right now—that can save you serious money and keep your future self from yelling at you in April. Before the year officially closes, it’s time to shift into alert mode and check off these five tax tricks you’ll absolutely regret skipping.

1. Max Out Your Retirement Accounts Before The Clock Runs Out

Most people think retirement contributions are something to “get around to later,” but later tends to vanish once holiday chaos kicks in. Contributing to eligible retirement accounts before year-end can lower your taxable income in ways that feel like cheating (but aren’t). Even a small bump in your contribution can shave hundreds off your tax bill without changing your lifestyle.

This one step basically lets you pay your future self while paying the government less, which feels like a win-win every time. If you want next tax season to sting a whole lot less, this trick belongs at the top of your to-do list.

2. Harvest Your Losses Before They Expire On You

Tax-loss harvesting sounds like something only Wall Street people talk about, but it’s actually a simple move anyone with investments can use. If you have stocks or funds that dipped this year, selling them at a loss can offset gains elsewhere and reduce your taxable income. It’s like turning financial lemons into tax lemonade, except the lemonade reduces what you owe the IRS.

The trick is making these moves before December 31, because once the new year starts, those losses won’t apply the same way. If you skip this, you might end up paying taxes you didn’t need to, and nobody wants that kind of regret.

3. Make Strategic Charitable Donations While They Still Count

A well-timed charitable donation does more than warm your heart—it can seriously shrink your tax liability. Whether it’s cash, clothing, household goods, or even appreciated assets, those contributions add up quickly when used correctly. The difference between donating on December 31 and donating on January 1 is a full year of deduction opportunities. That’s why last-minute giving sprees aren’t just generous—they’re financially brilliant. If you’re planning to help others anyway, doing it before the year ends makes both emotional and fiscal sense.

Here Are The Tax Tricks You’ll Regret Ignoring Before Year-End
Image Source: Shutterstock.com

4. Check Your Withholding Before It Backfires

Many people don’t realize they’ve been under-withholding all year until it’s too late and their refund disappears—or worse, they end up owing. A quick check now can reveal whether you need to adjust your last few paychecks or prepare for a different outcome in the spring. If you’ve switched jobs, gotten a raise, or taken on freelance work, updating your withholding can save you from a painful surprise. Even small adjustments can keep your tax situation balanced and predictable. Ignoring this is a fast track to unexpectedly writing a large check to Uncle Sam.

5. Use Your Flexible Spending Account Before The Money Evaporates

Flexible Spending Accounts are incredible—until you forget the “use it or lose it” part. Most FSAs require you to spend the funds by the end of the year, or you risk watching that hard-earned money disappear into the financial abyss. This is the moment to grab receipts, schedule medical appointments, or finally buy that pair of glasses you’ve been putting off. It’s shocking how many people lose out simply because they didn’t do a quick year-end sweep of their reimbursable expenses. Don’t let your own money vanish because you forgot to submit a few forms.

Don’t Let Year-End Creep Up On You

The final weeks of the year always come at full speed, and tax prep isn’t usually the thing anyone wants to think about. But knocking out these simple, strategic moves can save you real money and eliminate the stress bomb waiting for you at tax time. Every tip here is practical, doable, and designed to give you maximum benefit before the year resets. Your finances deserve a strong finish, and you deserve a smoother, less painful tax season.

Have you used any of these tricks before, or learned a tax lesson the hard way? Write about your stories, thoughts, or advice in the comments for others to learn.

You May Also Like…

6 Advanced Techniques to Lower Your Capital Gains Taxes Legally

Can Your Taxes Be Cut In Half By You Simply Incorporating Your Name?

8 Insider Tricks Advisors Say the Wealthy Use to Pay Less Tax

9 Financial Dangers of Ignoring Property Taxes

Are There Tax-Saving Strategies My Current Advisor Completely Missed?


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Personal Finance

7 Fine-Print Exclusions in Your Homeowner’s Policy That Could Cost You Everything

December 9, 2025 by Brandon Marcus Leave a Comment

Here Are The Fine-Print Exclusions In Your Homeowner's Policy That Could Cost You Everything
Image Source: Shutterstock.com

Your home might feel like the safest place in the world—cozy, familiar, protected by a homeowner’s policy you assume has your back. But hidden inside those long, eye-glazing paragraphs of fine print are exclusions that could turn a bad day into a financial nightmare. Most homeowners never discover these surprises until they file a claim and hear the dreaded phrase: “Unfortunately, this isn’t covered.”

The truth is, insurance policies are full of tiny loopholes, tricky phrasing, and “gotcha” moments that can leave you paying out of pocket for disasters you didn’t even know existed. Before fate decides to test your policy, let’s pull back the curtain on the sneakiest exclusions that could cost you everything.

1. Earth Movement Exclusion

Earth movement sounds dramatic, but it includes more than just major earthquakes. Everything from sinkholes to shifting soil can be considered “earth movement,” and most standard policies exclude all of it. That means your foundation cracks, driveway collapse, or patio tilting could easily be labeled as uncovered events.

Even heavy rain causing the soil beneath your home to shift can fall into this category, leaving you with a repair bill that could make your wallet cry. If your home sits on unstable ground—or near construction—you’ll want to know exactly what your policy defines as earth movement.

2. Water Backup And Sump Overflow

Water damage is one of the most common home insurance claims, but ironically, one of its most expensive sources isn’t usually covered. When a sewer backs up, a sump pump fails, or a drain overflows, most plans treat it as a separate risk needing its own added coverage. Without that endorsement, you could be stuck replacing carpets, drywall, electronics, and furniture on your own dime.

The worst part? It often happens suddenly, giving you no time to react or prevent the damage. A small monthly add-on can save you thousands, but many homeowners never know they need it.

Here Are The Fine-Print Exclusions In Your Homeowner's Policy That Could Cost You Everything
Image Source: Shutterstock.com

3. Mold And Rot Limitations

Mold seems harmless until it takes over your walls, floors, and lungs—and then suddenly it’s a very expensive and very unwelcome guest. Most homeowner’s policies severely limit mold coverage or exclude it altogether, especially if the insurer decides the issue was caused by “ongoing moisture.” Rot, mildew, and fungus often fall into the same excluded category, meaning any long-term water problem can become your financial responsibility. Insurance companies treat mold as a preventable issue, even though many homeowners discover it only after it’s spread. If you live in a humid climate or have an older home, this exclusion can be a scary one.

4. Neglect And Maintenance Issues

Insurance companies love to frame anything unpleasant as a “maintenance issue,” which conveniently shifts the responsibility back onto you. Roof leaks caused by age. Not covered. A pipe that corrodes over time? Also not covered. If an adjuster believes the damage resulted from neglect—anything from failing to clean your gutters to not servicing your HVAC—they can deny your claim entirely. This exclusion is especially slippery because it often comes down to interpretation, and the interpretation rarely leans in your favor. Staying ahead on maintenance isn’t just smart—it’s essential for protecting your coverage.

5. Intentional Damage by Residents

This exclusion sounds obvious until you realize how broad it can be. If someone living in your home intentionally causes damage—anything from punching a hole in the wall to smashing windows during an argument—insurance doesn’t have to pay. That also includes damage caused by teenagers, roommates, or even guests who stay long enough to count as residents. The definition of “intentional” can also get blurry, which can lead to claim disputes you didn’t expect. In short, if someone under your roof does something reckless, your insurer may wipe their hands clean.

6. Certain Pet-Related Liabilities

Your beloved dog might be your best friend, but to your insurance company, he might be considered a liability on four legs. Many policies exclude certain breeds from coverage, especially for bites, scratches, or property damage. Even if your pet has never shown aggression, the exclusion still stands and can leave you responsible for lawsuits or medical bills. Some insurers even restrict non-traditional pets like reptiles or exotic animals, treating them as automatic risks.

7. Acts Of War, Civil Unrest, And Certain Vandalism Scenarios

These exclusions sound like plot points from an action movie, but they exist in almost every homeowner’s policy. If your property is damaged during a riot, protest, or civil disturbance, coverage can get complicated very quickly. Many policies exclude any damage connected to “war” or government actions, even if the terms are broadly interpreted. Some insurers even exclude vandalism if the home is vacant for a certain period, meaning a long vacation could unintentionally void your protection. These exclusions seem remote—until they aren’t.

Read The Fine Print Before It Reads You

The fine print matters, and the exclusions hidden inside it can determine whether a disaster becomes a minor inconvenience or a financial catastrophe. By understanding what your policy doesn’t cover, you can take steps to protect what matters most and avoid painful surprises during stressful moments.

Have you ever discovered a surprising exclusion in your policy, or faced an unexpected insurance denial? Give us all of your stories, questions, or frustrations.

You May Also Like…

7 Ways You’re Accidentally Destroying Your Home’s Value

Beyond the White Picket Fence: Is Homeownership Still the Goal?

10 Amazing Opportunities in Global Real Estate Markets Now

8 Creative Alternatives to Buying a Traditional Home

8 Hidden Money Leaks Around the House You Can Fix Today


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Real Estate Tagged With: fine print, fine-print exclusions, home issues, home neglect, homeowner, homeowner's policy, homeowners, homeownership, house damage, maintenance issues, mold, pets, property problems, Real estate

4 Indispensable Tools for Backtesting Investment Theories Swiftly

December 9, 2025 by Brandon Marcus Leave a Comment

There Are Several Indispensable Tools for Backtesting Investment Theories Swiftly
Image Source: Shutterstock.com

Every investor has a moment when a brilliant idea pops into their head and they’re suddenly convinced they’ve cracked the market’s secret code.

But ideas are cheap, and markets are not, so the real question becomes: Does this theory actually hold up when you run it through real historical data? That’s where backtesting comes in, transforming hunches into measurable results and separating sharp strategy from wishful thinking.

The best part is that backtesting doesn’t have to be a tedious, all-day chore bogged down by confusing code or endless spreadsheets. With the right tools, you can stress-test almost any investment hypothesis quickly, confidently, and with a surprising amount of fun.

1. Quantconnect: Institutional Power Without The Intimidation

QuantConnect takes algorithmic investing from mysterious to magnetic by giving you access to a massive library of historical data and the same testing environment used by professional quants. The interface feels sleek without being overwhelming, allowing curious investors to explore strategies with real-world conditions in mind. It supports multiple asset classes, meaning your theories about stocks, crypto, futures, or forex all get equal treatment under its analytical spotlight.

Even better, the platform allows you to experiment with coding ideas easily, and the atmosphere feels more like an innovation lab than a math exam. Whether you’re a hobbyist or a budding quant, QuantConnect delivers the speed and precision that make backtesting addictive in the best way.

2. Tradingview Strategy Tester: Simple, Visual, And Seriously Effective

TradingView’s Strategy Tester is a dream for anyone who prefers charts over code and clarity over complexity. Backtesting becomes incredibly intuitive here because everything is visualized in real time. This lets you watch your strategy play out candle by candle. You can adjust parameters instantly and see immediately how those tweaks would have changed performance across different market cycles. The built-in scripting language, Pine Script, is surprisingly accessible, making it easy to translate your ideas into testable logic even if you’re not a coder. It’s the perfect middle ground between power and simplicity, offering fast results that help you refine theories without drowning in data.

3. MetaTrader Backtester: A Classic Workhorse with Serious Depth

MetaTrader’s backtesting engine has earned its reputation as a reliable platform for traders who want precise simulations of market behavior. It lets you test everything from automated trading robots to nuanced manual strategies with impressive accuracy. Because the platform is so widely used, you get access to a huge community, endless tutorials, and countless strategy templates to experiment with.

The depth of customization is remarkable, allowing you to fine-tune execution conditions and explore how your theory behaves in fast-moving markets. For anyone who wants a combination of trusted stability and deep flexibility, MetaTrader’s backtester remains a top-tier contender.

There Are Several Indispensable Tools for Backtesting Investment Theories Swiftly
Image Source: Shutterstock.com

4. Portfolio Visualizer: Big-Picture Analysis For Long-Term Thinkers

Portfolio Visualizer stands out because it takes a more long-range, portfolio-based approach to backtesting. You can simulate entire strategies over decades. You can evaluate asset allocation and rebalance schedules, and risk-adjusted returns with surprising detail and speed. The interface is polished and beginner-friendly, but the analytical output feels advanced, making it ideal for investors who want to understand the story behind the numbers.

It’s especially useful for anyone testing theories around diversification, factor investing, or retirement planning. In a world full of tools for rapid, tactical testing, Portfolio Visualizer is a refreshing option for strategic thinkers with long-term vision.

Turn Ideas Into Data-Driven Confidence

Every great investment theory needs to prove itself under the weight of real historical evidence. These tools make that process faster, smoother, and infinitely more enjoyable. Whether you’re exploring short-term trading strategies or long-term portfolio concepts, backtesting gives you the clarity that separates solid insight from risky speculation. When you can see how an idea would have behaved, you gain confidence that spreadsheets alone can’t provide.

Have you tried any of these tools, or do you have a favorite backtesting platform of your own? Share your thoughts, stories, or strategy wins in the comments for others to learn.

You May Also Like…

8 Bold Strategies for Investing During Periods of High Inflation

8 Essential Items Boomers Should Invest In If They’ll Be Living Alone

7 Risky Investment Trends Only Experts Understand Fully

7 Genius Kitchen Tools That Instantly Make Cooking Easier

4 Quick Methods to Verify Advisor Backgrounds Using Public Tools


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Investing Tagged With: backtesting investments, bad investing advice, invest, investing, investing advice, Investing Tips, investment theories, investment tools, Investor

9 Georgia Counties Where Property Taxes Are Set to Rise the Fastest

December 9, 2025 by Brandon Marcus 2 Comments

Here Are The Georgia Counties Where Property Taxes Are Set to Rise the Fastest
Image Source: Shutterstock.com

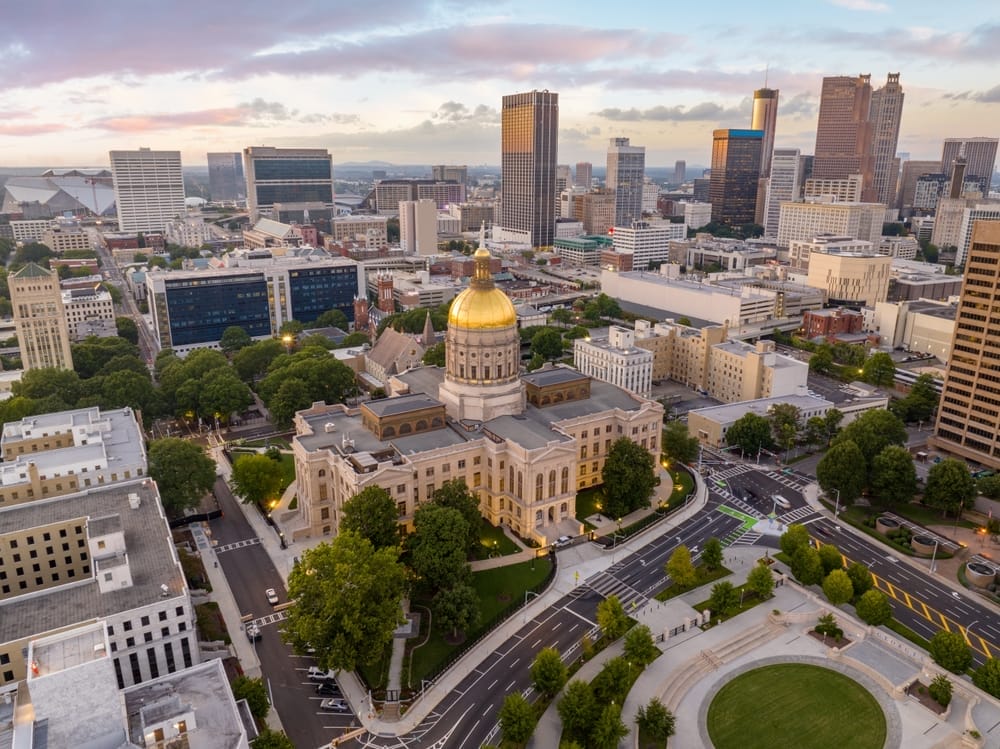
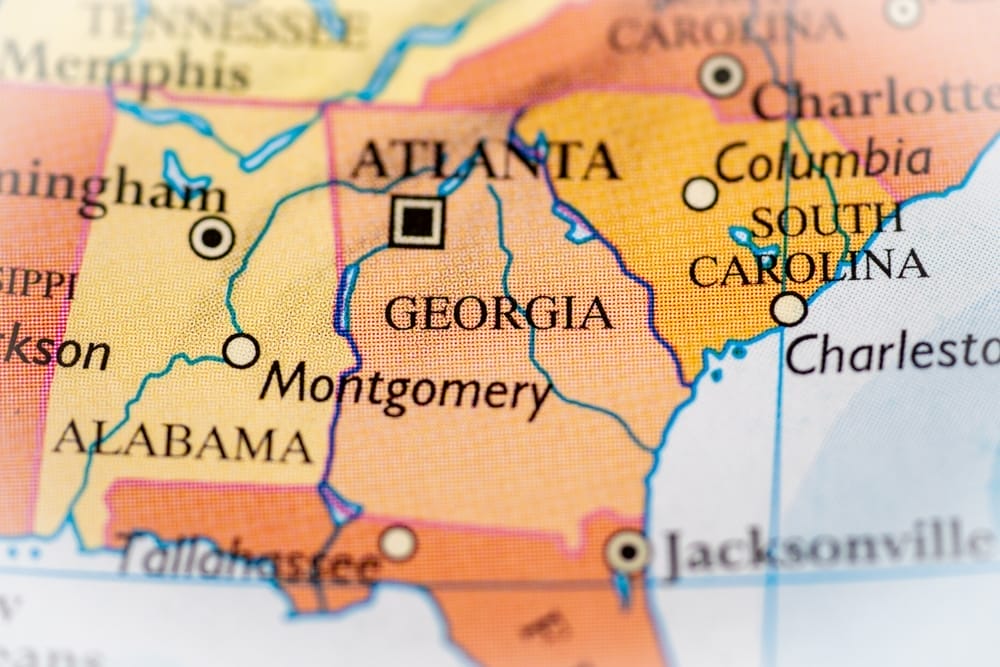
Let’s dive right in — if you own property in Georgia (or you’re house-hunting), buckle up. Home values are shooting up across parts of the state, and that means for many homeowners, the property tax bill that lands in your mailbox this year could hit a lot harder than last year. Between rapidly rising assessments, shifting millage rates, and local governments scrambling to keep up with growth (or budget shortfalls), there are several counties where taxes are on track to climb faster than you might expect.

Here are nine Georgia counties to watch if you care about what your home will cost you — and what you might start paying soon.

1. DeKalb County

DeKalb County is practically waving a red flag when it comes to rising tax burdens in 2025. The county’s governing authority has approved a tentative millage rate of 12.427 mills — that’s 2.690 mills over the computed “rollback” rate, representing a 27.6 percent increase from what the rollback formula would dictate. Even though the combined rate for all levies has been held flat at 20.81 mills since 2015, the reassessment of property values means many homeowners are still looking at significantly larger tax bills.

For those living in parts of metro Atlanta where housing demand has exploded — and with schools, public services, and infrastructure under pressure — the jump in tax obligations feels like the price tag for growth. If your property was reassessed upward even a little, that 27% swing could hit harder than it looks on paper.

2. Cobb County

Cobb County remains one of Georgia’s fastest-growing suburban hubs, and with growth comes rising home values — and rising taxes. According to the 2025 residential property value report, the market value of single-family homes rose about 3.1 percent compared to 2024. That’s not the kind of jump that knocks you off your feet overnight — but consistent annual increases add up over time, especially when many homeowners already operate on tight margins or fixed incomes.

The ripple effect? Expect next year’s tax digest (and likely your bill) to reflect the new valuations. As properties change hands or get upgraded, it’s a reminder that suburban expansion often comes with a hidden cost.

3. Fulton County

In the heart of metro Atlanta, Fulton County continues to see some of the steepest home-value gains statewide — and that typically translates directly into steeper taxes. A recent report showed residential property values increased by 5.9 percent overall, with even bigger upswing among higher-valued homes. It’s not just luxury mansions driving the spike either; mid-range properties saw solid upward movement, pushing more “average” homeowners into new tax brackets.

The truth is, when demand is high and inventory is tight, tax assessments follow market prices — and that upward pressure tends to stick. For many long-time residents, this can feel like being priced out of your own neighborhood without ever moving.

Here Are The Georgia Counties Where Property Taxes Are Set to Rise the Fastest
Image Source: Shutterstock.com

4. Gwinnett County

Though not always in the headlines, Gwinnett County in recent years has seen rapid population growth and mounting development. As demand pushes property values upward, tax bills are likely to follow. In recent statewide property-tax data, Gwinnett had among the highest effective tax burdens for homeowners. This county is part of the broader metro-Atlanta growth wave — new homes, families moving in, and expanding services. With schools, roads, and infrastructure needing funding, officials often lean on property tax increases to keep pace. If you own in Gwinnett and haven’t looked at your latest assessment closely — now might be a good time.

5. Chatham County

Way out on the coast, things are heating up in Chatham County too. As home to the city of Savannah and its surrounding suburbs, Chatham is seeing rising demand for housing — which tends to push up property valuations. According to the latest county-by-county data, Chatham’s effective property tax rate and median tax bills are among the higher ones in Georgia. For coastal homeowners, rising property taxes can clash with other cost pressures like insurance, maintenance, and flood-related expenses. If you own a home in this region, prepare for what could be a steeper climb than many inland counties are facing.

6. Fayette County

Fayette County is often overlooked in discussions about tax spikes, but it’s a place where property value increases and tax burdens have quietly climbed. According to recent data, many mid-sized Georgia counties like Fayette are seeing rising effective tax rates and increased tax bills, even as statewide attention focuses on the major metros. For long-term homeowners, that can mean incremental increases over successive years — enough to shift what was once a manageable payment into a financial burden. Communities that had affordable charm a few years back may now feel the squeeze as valuations edge upward and local government costs rise.

7. Henry County

Henry County, which sits on the growing periphery of metro Atlanta, is another spot where homeowners should keep a close eye. As development expands outward and more people move in, property values tend to follow — and with that, tax bills often climb too. Tax data show that Henry County’s effective property tax burden is already above the statewide median. For families moving into what once felt like affordable suburbs, this means the dream of lower-cost living might be under threat from rising assessments and incremental tax pressure. New growth brings new amenities — but also new expenses.

8. Coweta County

Few counties outside the big metro centers get much attention, but Coweta County is quietly part of the broader shift. As people look for more space and affordability outside major urban zones, places like Coweta become magnets — which can trigger property value hikes. According to recent property-tax data sets, Coweta shows a relatively high effective rate, suggesting that as home values rise, tax bills are likely to follow. This dynamic often sneaks up on homeowners: the neighborhood feels peaceful, the home feels like your refuge, but the tax bill creeping up in your mailbox tells a different story. If you call Coweta home — or are thinking about buying there — it’s worth budgeting for steeper taxes down the line.

9. Butts County

Last but not least, Butts County stands out among Georgia’s smaller and more rural counties, yet it shows signs of rising tax burden that many might not expect. According to county-by-county effective property tax data, Butts is among the counties where rates — relative to property values — are trending upward. As urban sprawl pushes outward, even rural zones can feel the ripple effect of increased demand, leading to reassessments and higher bills. For homeowners who moved here for peace, space, or affordability, that tax increase can sting: what once felt affordable might suddenly feel like a stretch.

What This Means For Georgia Homeowners

If you own — or are thinking of buying — a home in Georgia, these counties show that the property-tax landscape is shifting quickly. Rising home values, population growth, and local budget pressures are colliding to make increases more common than exceptions. It’s a reminder that homeownership isn’t just about your mortgage and that property taxes can sneak up and add real impact to your bottom line.

Have you seen a jump in your latest tax bill? Are you feeling the squeeze — or moving because of it? We want to hear your story. Drop your experience, tips, or frustrations in the comments below.

You May Also Like…

6 Advanced Techniques to Lower Your Capital Gains Taxes Legally

Can Your Taxes Be Cut In Half By You Simply Incorporating Your Name?

5 Reasons Why Homeowners Should Increase Their Property’s ROI

9 Financial Dangers of Ignoring Property Taxes

7 Lesser-Known Costs of Selling Inherited Property


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: tax tips Tagged With: Butts County, Chatham County, Cobb County, Coweta County, DeKalb County, Fayette County, Fulton County, Georgia, Gwinnett County, Henry County, property tax, property taxes, tax rules, taxes

6 Credit Mistakes That Redditors Confess Cost Them Thousands

December 8, 2025 by Brandon Marcus Leave a Comment

There Are Countless Credit Mistakes That Redditors Confess Cost Them Thousands
Image Source: Shutterstock.com

The wild world of Reddit has no shortage of cautionary tales, but few are as brutally honest—or financially painful—as people confessing the credit mistakes that burned them the most. These are not the polished, sanitized stories you’d hear in a financial workshop. These are the raw, funny, chaotic, facepalm-worthy confessions from people who learned credit lessons the hard way and want everyone else to avoid repeating them. And honestly? Some of these mistakes are so common that you might find yourself nervously laughing, nodding along, or quietly rethinking your last late payment.

So let’s dig into the kinds of credit blunders Redditors openly admit cost them thousands—sometimes tens of thousands—and uncover the lessons hidden inside their financial misadventures.

1. Maxing Out Cards “Just This Once”

Reddit is filled with stories of users who swore they’d pay off a big purchase quickly—only to watch the balance snowball out of control. Many believed a temporary max-out wouldn’t hurt their score, but the utilization spike hit harder than expected. When that balance sat there longer than planned, interest charges kicked in with the subtlety of a wrecking ball. Worse, several people admitted they kept spending on the already maxed-out card because they felt the damage was “already done.” What they learned is simple: a credit card at 95% utilization can tank your score faster than almost anything else.

2. Forgetting One Tiny Bill That Turned Into a Credit Nightmare

Redditors love to share stories of a single medical bill, phone bill, or store card they accidentally forgot about—and how that $38 oversight became a $400 collections entry. Many didn’t even know anything was overdue until they checked their reports or were denied a loan. The shock in their posts is palpable, mostly because the mistake felt trivial at the time. What stings even more is how long that mark can stay on a credit report, quietly sabotaging financial opportunities. The takeaway echoes through countless threads: it’s always the small bills that cause the biggest headaches.

3. Closing Old Accounts To “Simplify Finances”

At first glance, closing unused credit cards feels responsible and organized, and plenty of Redditors admit they did it thinking it would boost their credit score. Instead, they wiped out years of credit history in a single click. That shorter history caused their scores to dip dramatically, leaving them confused and frustrated. Some users even realized too late that those old cards were anchoring their utilization ratio in a good place. Their regret is unanimous: closing an old account often hurts much more than it helps.

4. Paying Only the Minimum For Far Too Long

There is no shortage of Reddit threads where users reveal the horrifying moment they calculated how much interest they had paid after years of minimum payments. Many had no idea the balance would barely budge, even as thousands disappeared into interest. Some describe feeling trapped, others admit they ignored the statements because they were too stressful to look at. By the time they faced the numbers, the damage was already done and painfully expensive. It’s a lesson repeated across countless comments: minimum payments keep you afloat, but they never move you forward.

5. Co-Signing Out Of Love, Trust, Or Pure Naivety

Some of the most dramatic credit horror stories on Reddit involve co-signing gone wrong. Whether it was for a partner, a friend, or a family member, these tales often end with missed payments and ruined credit. Many co-signers didn’t even realize they were legally responsible for the entire debt—and sometimes didn’t find out about the missed payments until their score had cratered. The emotional fallout is often just as messy as the financial one, creating whole threads of regret-filled advice. If Reddit has a collective motto on co-signing, it’s this: “Don’t do it unless you’re ready to make the payments yourself.”

6. Applying For Too Many Cards In A Short Time

Redditors frequently confess to impulsively applying for multiple cards to chase rewards, freebies, or sign-up bonuses. What they didn’t expect was how quickly those hard inquiries would stack up and drag down their scores. Many admit they didn’t even realize inquiries stayed on credit reports for years. Others say lenders viewed the applications as “financial desperation,” leading to denied loans or higher interest rates. The confession threads always end with the same advice: space out applications unless you want your credit score to look panicked.

There Are Countless Credit Mistakes That Redditors Confess Cost Them Thousands
Image Source: Shutterstock.com

Learn From The Scars, Not Just The Stories

Redditors may joke, meme, and laugh about their financial disasters, but the lessons underneath their stories are worth taking seriously. Credit mistakes don’t usually happen because people are reckless—they happen because life is messy, stress is real, and small financial choices can snowball in ways no one expects. By understanding where others went wrong, you give yourself the chance to go right.

Have you ever made a credit mistake that cost you more than you expected? Give us all of your stories, lessons, or confessions in the comments section.

You May Also Like…

6 Times When Using Credit Beats Paying With Cash

8 Times “0% Interest” Credit Cards Turn Into Financial Traps

Why Paying Only the Minimum on Your Credit Cards Is a Financial Death Trap

Why Closing an Old, Unused Credit Card Can Wreck Your Credit Score

10 Reasons Your Credit Card Fraud Claim Was Denied—and What You Can Do About It


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: credit score Tagged With: applying for credit cards, bills, co-sign, co-signing, credit, credit card, credit cards, credit limit, credit mistakes, credit problems, credit repair, credit report, credit score, finance, finances, issues with credit, maxing our credit cards, Reddit

Are Payday Loans Still A Big Problem?

December 8, 2025 by Brandon Marcus Leave a Comment

Payday Loans Are Still A Big Problem
Image Source: Shutterstock.com

The second you hear the phrase payday loan, your brain probably lights up with memories of neon signs, desperate decisions, and financial advice articles screaming “DON’T DO IT.”

Payday loans have a reputation that could make even the boldest risk-taker flinch, yet millions of people continue turning to them every year. It’s the kind of financial trap that feels outdated—like floppy disks or dial-up internet—but somehow refuses to disappear. And despite reforms, regulations, and endless warnings, these short-term, high-interest loans are still woven into the financial survival strategies of many Americans.

The real question isn’t whether payday loans exist—it’s why they’re still thriving in a world full of budgeting apps, credit-builder programs, and financial education resources.

Why Payday Loans Became So Popular

People don’t wake up and decide a payday loan sounds fun. These loans exploded because they offered something traditional banks didn’t: instant cash with zero judgment. For someone facing an emergency, a shut-off notice, or a sudden bill, payday lenders felt like the only ones willing to help. The convenience, speed, and no-questions-asked nature of these loans made them tempting, even when the risks were obvious. Over time, their popularity grew not because they were good, but because many people felt they had no better option.

How The Debt Cycle Traps Borrowers

The biggest issue with payday loans isn’t that they’re expensive—it’s how quickly they snowball. Borrowers often can’t repay the full amount on their next paycheck, which forces them to roll the loan over with even more fees. This cycle can turn a small loan into a financial black hole that keeps growing with each extension. Many borrowers end up paying far more in fees than the original loan amount. The tragic part is that the system is designed this way, making repeat customers the backbone of the industry.

The Role Of Regulation In Slowing The Industry Down

Regulation has stepped in many times, hoping to rein in predatory lending without completely eliminating emergency financial options. Some states have capped interest rates, while others have imposed stricter repayment rules or outlawed payday lending altogether. These measures helped reduce the most extreme abuses, but they didn’t eliminate the problem. Lenders often find loopholes or rebrand themselves under new categories like installment loans or cash advances. Even with tougher rules, the core issue—people lacking affordable short-term credit—continues to fuel demand.

Why Payday Loans Haven’t Disappeared

Despite years of warnings, payday loans are still around for one simple reason: financial desperation hasn’t gone anywhere. Many households live paycheck to paycheck, and when an emergency hits, options are limited. Traditional banks don’t offer tiny short-term loans because they aren’t profitable. Credit cards require approvals many consumers can’t get. So payday loans fill a gap—an extremely costly gap, but a gap nonetheless—and until that need is addressed, they’re unlikely to fade away.

Payday Loans Are Still A Big Problem
Image Source: Shutterstock.com

The Digital Transformation That Complicates Everything

Just when regulators thought they had payday loans somewhat contained, the industry went digital. Online payday lenders exploded, offering nationwide access, instant approvals, and ways to bypass state regulations. With the entire process happening behind a screen, transparency became murkier and oversight became harder. Digital borrowers can take out multiple loans without realizing how deep they’ve gone. The shift online made payday lending faster, easier, and in some cases even more dangerous.

The Human Impact Behind The Statistics

Every payday loan customer has a story filled with stress, fear, or desperation. For many, it starts with something small that spirals—like a car repair, a medical bill, or an unexpectedly short paycheck. The shame surrounding payday loans often keeps borrowers silent, creating a private struggle that feels isolating and unfixable. These loans don’t just drain bank accounts; they drain confidence, security, and peace of mind. When you zoom out from the dollar signs, what emerges is a deeply human problem tied to systemic financial inequalities.

Are Alternatives Actually Helping?

In recent years, alternatives have begun popping up—credit unions offering micro-loans, employers providing wage advances, and apps that help users avoid overdraft charges. Some banks have finally started introducing small-dollar loan programs with reasonable terms. These options are promising but not yet widespread, and many consumers still don’t know they exist. Financial literacy programs also help, but education alone can’t fix income instability. Until alternatives become accessible, familiar, and widely trusted, payday loans will continue filling the void.

The Future Of Payday Lending

The future of payday loans depends heavily on policy, technology, and the economy. If incomes rise, emergency savings become normal, and alternative lending grows, payday loans could lose their foothold. But if wages stay stagnant and financial emergencies remain common, people will keep seeking fast cash, no matter the cost. New fintech companies may offer safer solutions, but they must compete with the convenience and simplicity payday lenders mastered long ago. The next decade will reveal whether payday loans shrink into irrelevance—or simply evolve into something harder to regulate.

Why The Problem Still Matters Today

Many people assume payday loans are a relic of the early 2000s, something we’ve collectively moved past. But millions of Americans still rely on them, which means the problem is far from solved. Payday lenders thrive where financial vulnerability thrives, and that vulnerability remains widespread. Understanding how these loans work, why they persist, and who they hurt is crucial for building better solutions. The payday loan problem isn’t about borrowing—it’s about the conditions that make such borrowing necessary.

 Share Your Thoughts Below

Payday loans may not dominate headlines like they used to, but they continue to shape the financial lives of those living on the edge. They’re a symptom of deeper problems—income instability, a lack of short-term credit options, and the ongoing struggle many people face in managing unexpected expenses. Reform has helped, but it hasn’t erased the core issue.

What’s your experience with payday loans? Share your thoughts, personal stories, or questions in the comments below.

You May Also Like…

5 Hidden Costs of Relying on Payday Loans

Why Do People Ignore the Risks of Cosigning Loans

These 3 Loans Are Worse Than Pay Day Loans

6 Hidden Dangers of Taking Out Student Loans Too Young

Why Do Families Rely on Payday Loans in Emergencies


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: dangerous loans, financial dangers, financial matters, lending money, Life, Lifestyle, Loan, loaning money, loans, Money, money issues, payday loans

8 Hidden Risks People Overlook When Financing a Car at High APR

December 8, 2025 by Brandon Marcus Leave a Comment

There Are Hidden Risks People Overlook When Financing a Car at High APR
Image Source: Shutterstock.com

Buying a car can feel like a thrilling power move—new wheels, fresh start, big energy. But once that excitement fades and the paperwork settles, many drivers discover a financial plot twist they never saw coming. High-APR financing looks simple on the surface, yet it hides a handful of sneaky dangers that can quietly drain your wallet long after the dealership coffee turns cold.

Most people focus on the monthly payment and ignore the traps tucked into the long-term math. Before signing on the dotted line, let’s break down the risks most drivers don’t even realize they’re stepping into—and why your APR might matter more than your car’s horsepower.

1. Total Cost Skyrockets Faster Than Expected

Financing a car at a high APR might seem manageable at first because the monthly payments look reasonable. What many people forget is that those interest charges compound with ruthless consistency. Over several years, you may pay thousands more than the car is actually worth. By the time the loan ends, some drivers realize they could have bought a nicer vehicle for the same total amount. This creeping cost increase is one of the biggest hidden dangers of high-interest financing.

2. You Become Trapped In Negative Equity

Negative equity happens when you owe more on your car loan than your car is worth. High APRs accelerate this issue because your payments attack the interest before making a dent in the principal. As your car depreciates, the gap between its value and your loan balance grows wider. This trap can become a nightmare if you need to sell or trade the vehicle early. Because of negative equity, many drivers feel stuck in a loan they no longer want or can no longer afford.

3. Refinancing Options Shrink Dramatically

People often assume they can refinance down the road and escape their high APR, but lenders don’t always make that easy. If your loan is already upside-down, many banks simply won’t touch it. Even if refinancing is possible, you may face terms that aren’t much better than what you already have. High APRs can essentially lock you into a long-term struggle with hefty interest payments. The belief that refinancing is a guaranteed safety net is one of the most common—and painful—misconceptions.

4. Repairs Hit Harder Because Savings Disappear

A high-APR loan gnaws away at your financial breathing room, leaving less space in your budget for surprise repairs. Cars don’t wait for perfect timing to break down, and repairs can show up before your paycheck does. When savings are thin because your interest charges eat everything first, even minor issues feel like a crisis. This forces many drivers to turn to credit cards or additional loans, deepening the spiral. Over time, the stress of constant financial juggling becomes just as exhausting as the debt itself.

There Are Hidden Risks People Overlook When Financing a Car at High APR
Image Source: Shutterstock.com

5. Insurance Requirements Stay Expensive Longer

When you finance a car, your lender usually requires full-coverage insurance. With a high APR, your loan term might be longer, meaning you’re stuck paying higher insurance premiums for years. Drivers who expected to downgrade coverage once the loan balance dropped often find themselves paying more than they planned. This hidden long-term cost adds up and makes the total financial burden heavier than expected. The extended commitment to pricey insurance only intensifies the sting of an already expensive loan.

6. Trade-In Flexibility Practically Disappears

High-APR loans limit your freedom to upgrade or switch cars. When your balance grows slower than your vehicle depreciates, you lose the ability to trade in early without bringing cash to the table. Dealerships may roll your negative equity into the next loan, which traps you in an even higher mountain of debt. This domino effect creates a cycle where every new car becomes more financially draining than the last. Before long, what started as a simple purchase becomes an ongoing chain reaction of costly commitments.

7. Financial Stress Slowly Becomes a Daily Companion

Money stress doesn’t announce itself all at once—it creeps in. High-interest car payments can quietly turn into a monthly source of dread as other expenses pile up around them. When too much income goes toward interest, everyday costs feel heavier and unexpected expenses become overwhelming. This strain can spill into relationships, work performance, and overall well-being. The emotional toll might not appear on a loan agreement, but it’s one of the biggest hidden risks of all.

8. Your Credit Score Can Take a Hit Without Warning

People assume that simply making payments keeps their credit safe, but high APR loans can still cause damage indirectly. When a huge chunk of your budget goes toward an expensive car payment, you’re more likely to fall behind on other bills. Even small slip-ups can lead to missed payments or high credit utilization, which hurts your score. A weakened credit profile then makes future loans—car, mortgage, or otherwise—more expensive. Over time, the high APR that started with just one car can ripple across your entire financial life.

Protect Your Wallet Before the Keys Even Touch Your Hand

Financing a car at a high APR may feel convenient in the moment, but the long-term risks are far bigger than most people realize. From rising total costs to shrinking flexibility and mounting stress, the dangers hide in plain sight until they’re too big to ignore. Understanding these risks helps you make smarter decisions—not just for your next car, but for your overall financial health.

Have you ever dealt with a high-interest auto loan or financial surprises at the dealership? Give us your stories, thoughts, or advice in the comments below.

You May Also Like…

The Rental Car Insurance Mistake That Can Cost You a Fortune

The Truth About APR Balance Transfer Cards and Their Hidden Fees

7 Wild Facts About Electric Cars That’ll Shock You

Why Do Families Spend More On Cars Than Homes Over a Lifetime

Why Do Wealthy People Lease Cars Instead of Buying Them Outright


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Car Tagged With: APR, automobiles, automotive care, buying a car, car, car insurance, car issues, car repairs, cars, credit score, equity, finances, financial issues, financial stress, financing a car, Money, money issues, overspending, refinancing, Smart Spending, spending, trade-in car

Am I the Only One Who Thinks Estate Planning Is Deeply Terrifying?

December 8, 2025 by Brandon Marcus Leave a Comment

Am I the Only One Who Thinks Estate Planning Is Deeply Terrifying?
Image Source: Shutterstock.com

Estate planning has this eerie ability to make even the most responsible adult suddenly want to crawl under a blanket and pretend the future isn’t happening. The moment someone mentions wills, executors, or power of attorney, your brain fires off alarms you didn’t even know you had. It’s like the ultimate grown-up test: plan for events you don’t want to imagine, make decisions you don’t want to make, and somehow act calm about it all. And yet, everyone insists it’s important—as if organizing your own eventual absence should feel as casual as organizing a sock drawer.

If you’ve ever felt personally victimized by the phrase “end-of-life documents,” trust me, you are not the only one.

The Emotional Weight Hits You Like A Plot Twist

Estate planning forces you to confront scenarios that feel wildly hypothetical yet uncomfortably real at the same time. Even if you’re usually logical, the idea of putting future-you on paper can spark internal chaos. It’s the odd mix of responsibility and existential dread that makes every sentence of a will feel heavier than it looks. Most people expect it to feel practical, but it actually feels like writing instructions for a movie you won’t be around to watch. No wonder so many of us suddenly remember “urgent laundry” whenever someone suggests starting the process.

The Legal Language Feels Designed To Intimidate

You sit down to read a simple explanation of estate documents and suddenly you’re knee-deep in terminology that sounds like it came from a medieval courtroom. Words like “intestate,” “fiduciary duty,” and “revocable trust” seem specifically engineered to make newcomers doubt they graduated high school. It’s like learning a new language, except the stakes are way higher than ordering lunch in another country. Even when lawyers explain things clearly, the paperwork somehow still reads like a secret code. It’s enough to make otherwise confident adults whisper, “Am I supposed to understand any of this?”

Choosing Decision-Makers Feels Like A Relationship Minefield

Assigning someone as your executor or power of attorney feels like awarding a crown you’re terrified someone might misuse. You start overthinking everything—who’s responsible enough, who’s organized enough, who won’t panic under pressure, and who won’t turn this into a family drama. Suddenly, every relative becomes a character in your imaginary courtroom saga and you’re the casting director. Even if everyone gets along now, estate planning introduces new layers of “What if?” into the dynamic. Making these choices isn’t just logistical—it’s emotional roulette.

Am I the Only One Who Thinks Estate Planning Is Deeply Terrifying?
Image Source: Shutterstock.com

Trying To Predict The Future Is Weirdly Exhausting

Estate planning requires you to imagine life years or decades ahead, which is impressive considering most of us can barely plan dinner. You’re asked to anticipate needs, circumstances, and financial realities that may or may not ever happen. That kind of guessing game feels more intense than fantasy football and definitely less fun. The mental gymnastics can make your head spin as you try to plan responsibly without knowing what your life will even look like. It’s no wonder so many people procrastinate until the universe forces them to stop avoiding it.

Talking About Money And Mortality At The Same Time Is A Lot

Most people can handle financial discussions, and most can eventually handle mortality discussions, but put them together and it’s a whole new emotional category. Estate planning conversations with family members often involve awkward pauses, uncomfortable laughs, and deep breaths that signal everyone wants to be anywhere else. There’s something uniquely jarring about discussing inheritances, assets, and final wishes in one sitting. Even with the most supportive families, the tension can sneak in like an uninvited guest. It’s a cocktail of practicality and vulnerability that’s hard to sip slowly.

The Fear Of Messing Up Is Surprisingly Intense

Estate planning feels high-stakes because it is, and that pressure can make the simplest decisions feel enormous. You worry about forgetting something important or accidentally creating chaos for the people you care about. Even when professionals reassure you, there’s a tiny voice inside whispering, “But what if I misunderstood a step?” It’s the ultimate perfectionist nightmare: a process where mistakes aren’t discovered until you’re no longer around to fix them. That’s enough to make anyone double-check every line like they’re defusing a bomb.

The Sheer Amount Of Paperwork Feels Endless

Just when you think you’ve completed everything, another document appears like a boss level you weren’t warned about. Estate planning doesn’t stop at a will—there are directives, beneficiary updates, property designations, and more. Each form has its own rules, signatures, and conditions, and keeping track can feel like juggling flaming batons. It doesn’t matter how organized you usually are; this process will test your patience, your filing skills, and your ability to stay calm. Even digital versions somehow manage to feel like a mountain.

It Forces You To Think About The People You Love Differently

Estate planning pushes you to imagine your loved ones’ lives without you in ways that feel both tender and crushing. You start thinking about what they’ll need, what would make things easier, and how to support them even in your absence. That level of emotional depth can feel overwhelming, especially when paired with practical decision-making. It reminds you how interwoven your life is with others and how much thought goes into caring for them long-term. It’s beautiful, but it’s heavy in a way that stays with you.

Starting Feels Impossible, But Finishing Feels Like Superhero Energy

Most of the fear sits in the beginning—the moment you decide to stop running from the process and finally start. It feels like standing at the edge of a high dive, hesitating even though you know the landing will be fine. But once you get through it, something weirdly magical happens: you feel powerful. You feel responsible, prepared, and a little more grown-up than you expected. For something so terrifying at the start, estate planning ends up leaving you with peace of mind that’s worth every anxiety-filled minute.

It’s Terrifying Because It Actually Matters

Estate planning is scary in the same way important life decisions are scary—they touch the parts of our lives we care most deeply about. The people we love, the future of what we’ve built, and the desire to protect others all collide in one emotionally loaded project. That’s why the fear feels so real: it’s tied to meaning, legacy, and love. But it’s also why facing it feels rewarding, because it turns uncertainty into reassurance. And beneath the fear, there’s something empowering about taking control of the things most people avoid.

Maybe It’s Terrifying, But You’re Definitely Not Alone

Estate planning might feel like an emotional roller coaster wrapped in legal terminology, but the fear it brings is completely human. Anyone who’s ever tried to start the process has felt the same blend of dread, confusion, and reluctant responsibility. The important part is knowing that you don’t have to navigate it alone and that understanding your fears is the first step toward overcoming them.

So tell us—have you felt the same panic, hesitation, or dark humor while diving into estate planning? Share your thoughts, stories, or “tell me why this is so stressful” moments in the comments.

You May Also Like…

Why a Payable-on-Death (POD) Account Is Better Than a Will for Your Cash

7 Excuses Millennials Use to Delay Estate Planning (and Why It’s Risky)

Is Estate Planning The Only Way To Preserve Your Legacy?

7 Things That Must Be in Your Will to Prevent Vicious Family Fights

5 Subtle Estate-Tax Traps the Government Quietly Introduced

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Estate Planning Tagged With: death, death in the family, emotional weight, emotions, end-of-life, Estate plan, Estate planning, Family, family issues, mortality, power of attorney, Will, will and testament

  • « Previous Page
  • 1
  • …
  • 116
  • 117
  • 118
  • 119
  • 120
  • 121
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • 10 Tactics for Building an Emergency Fund from Scratch by Vanessa Bermudez
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald

Copyright © 2026 · News Pro Theme on Genesis Framework