• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Brandon Marcus

Running Out of Money in Retirement? 9 Planning Errors Advisors See Every Day

February 24, 2026 by Brandon Marcus Leave a Comment

Running Out of Money in Retirement? 9 Planning Errors Advisors See Every Day
Image Source: Pexels.com

Retirement does not forgive sloppy planning. You can work for forty years, save diligently, and still watch your balance shrink faster than you ever imagined if you make a handful of common missteps.

Financial advisors see the same errors again and again, and none of them require exotic investments or dramatic market crashes to do real damage. They grow from ordinary decisions, repeated over time, without a clear strategy behind them. If you want your money to last as long as you do, you need to know where people stumble and how to step around those traps with intention.

1. Treating Retirement Like a Finish Line Instead of a 30-Year Journey

Too many people view retirement as the moment they stop working, not as a new phase that could last three decades or more. The Social Security Administration reports that a 65-year-old today has a strong chance of living into their mid-80s or beyond, and many couples will see one spouse live past 90. That timeline demands a plan built for endurance, not a quick victory lap.

When someone pulls money from a portfolio without considering longevity risk, they create a slow leak that compounds over time. Advisors often recommend sustainable withdrawal strategies, such as the well-known 4 percent rule, which emerged from historical market data. Even that guideline requires flexibility because market returns and inflation never follow a script. You need a plan that adapts to changing conditions rather than one that assumes the first few years set the tone forever.

Build projections that stretch well into your 90s. Stress-test your plan with conservative return assumptions. And remind yourself that retirement marks the start of a long financial marathon, not the ribbon at the end of a sprint.

2. Claiming Social Security Without a Strategy

Social Security remains one of the most valuable retirement income sources, yet people often claim benefits at the first opportunity without understanding the trade-offs. You can start collecting as early as 62, but that choice permanently reduces your monthly benefit. If you wait until full retirement age, which ranges from 66 to 67 depending on your birth year, you receive 100 percent of your earned benefit. If you delay until 70, your benefit increases.

Advisors frequently see retirees leave tens of thousands of dollars on the table because they treat Social Security like a quick cash infusion instead of a long-term income stream. For married couples, claiming decisions also affect survivor benefits, which can shape financial stability for decades.

Before you file, run the numbers. Consider your health, family longevity, income needs, and tax situation. Social Security offers inflation-adjusted income for life, and that feature makes it incredibly powerful when you use it thoughtfully.

3. Underestimating Healthcare Costs

Healthcare can swallow a retirement budget faster than almost any other expense. Fidelity’s annual estimates consistently show that a 65-year-old couple may need hundreds of thousands of dollars to cover healthcare costs in retirement, even with Medicare. Medicare covers many services, but it does not eliminate premiums, deductibles, copayments, and services such as long-term care.

Advisors often meet clients who assume Medicare equals free healthcare. That assumption leads to underfunded health savings and painful trade-offs later. Long-term care poses a particular risk because nursing home stays or extended in-home care can cost tens of thousands of dollars per year.

You can prepare by maximizing contributions to a Health Savings Account if you qualify, exploring long-term care insurance options, and building a specific line item for medical costs into your retirement budget. Treat healthcare like a major category, not an afterthought.

4. Ignoring Inflation Because It Feels Manageable Today

Inflation rarely announces itself with fireworks, yet it quietly erodes purchasing power year after year. Even modest inflation of 2 to 3 percent can cut the value of your dollar dramatically over 20 or 30 years. Advisors regularly encounter retirees who hold too much in cash because it feels safe, only to watch their spending power shrink as prices climb.

A retirement portfolio needs growth assets, such as diversified stock investments, to outpace inflation over time. You can reduce volatility with bonds and other fixed-income investments, but eliminating growth entirely often backfires. History shows that equities have provided higher long-term returns than cash, though they fluctuate along the way.

Balance matters. Review your asset allocation regularly, and resist the urge to retreat fully into cash after market dips. Inflation never sleeps, so your portfolio cannot either.

5. Taking on Too Much or Too Little Investment Risk

Risk works like seasoning in a recipe. Too much overwhelms the dish; too little leaves it bland and ineffective. Some retirees keep aggressive portfolios packed with stocks because they chased strong returns during their working years. A severe downturn early in retirement can devastate a portfolio when withdrawals compound losses, a concept known as sequence-of-returns risk.

On the other hand, some people flee to ultra-conservative investments the moment they retire. That decision can protect against short-term swings but often undermines long-term sustainability. Advisors help clients calibrate risk by aligning investments with income needs, time horizon, and personal tolerance for volatility.

You should know how much income you need from your portfolio versus guaranteed sources like Social Security or a pension. That clarity allows you to structure investments with purpose instead of fear.

Running Out of Money in Retirement? 9 Planning Errors Advisors See Every Day
Image Source: Pexels.com

6. Failing to Create a Real Retirement Budget

Many people estimate retirement expenses based on rough guesses rather than detailed numbers. They assume spending will drop significantly once work ends, yet travel, hobbies, and healthcare often fill the gap. Advisors frequently ask new retirees to track spending for several months, and the results surprise almost everyone.

A written budget forces you to confront fixed expenses, discretionary spending, and irregular costs such as home repairs. Without that clarity, you may withdraw too much too soon or underestimate how quickly small indulgences add up.

Start with your current expenses, adjust for changes you expect in retirement, and review the plan annually. A realistic budget does not restrict your life; it gives you control.

7. Carrying Debt Into Retirement

Debt changes the math in retirement because you lose the steady paycheck that once supported those monthly payments. Credit card balances with double-digit interest rates can sabotage even a well-funded portfolio. Mortgage payments, car loans, and personal loans also reduce flexibility.

Advisors encourage clients to enter retirement with minimal high-interest debt whenever possible. Paying off a mortgage before retirement can lower required monthly income and reduce stress. However, each situation differs, and you should weigh interest rates, tax considerations, and investment returns before making large payoff decisions.

8. Overlooking Taxes in Withdrawal Planning

Retirement does not eliminate taxes; it simply shifts how you pay them. Traditional 401(k) and IRA withdrawals count as ordinary income. Required Minimum Distributions begin at age 73 under current law, and they can push retirees into higher tax brackets if they fail to plan ahead.

Advisors often recommend tax diversification, which means holding assets in taxable accounts, tax-deferred accounts, and tax-free accounts such as Roth IRAs. Strategic withdrawals from each bucket can help manage tax brackets over time. You can also explore Roth conversions during lower-income years, though you should evaluate the tax impact carefully. Taxes influence how long your money lasts, so treat them as a central part of your strategy.

9. Skipping Professional Advice or a Second Opinion

Some people avoid financial advisors because they fear high fees or believe they can manage everything alone. Others rely on outdated advice from decades ago. While many individuals handle their own finances successfully, complex retirement decisions often benefit from expert insight.

A fiduciary financial advisor must act in your best interest, and that standard offers an added layer of accountability. Even a one-time comprehensive review can reveal blind spots in withdrawal strategies, tax planning, insurance coverage, or estate documents. You do not need to surrender control to seek guidance. You can use an advisor as a sounding board and strategic partner, especially during major transitions.

Your Real Goal: Confidence That Your Money Will Last

Running out of money in retirement ranks among the most common financial fears, and it makes sense. You cannot simply pick up extra shifts at 85 to fix a planning mistake from your 60s. Yet most retirement disasters grow from preventable errors, not from catastrophic events.

So here is the real question: which of these planning errors might quietly sit in your own strategy right now, and what will you do this month to fix it? Talk about it in our comments section below.

You May Also Like…

Social Security, 401(k)s, and Market Swings: Why Retirement Feels Riskier Than Ever

Hidden 401(k) Fees Are Still Shrinking Retirement Balances

7 Medical Costs That Can Wreck Retirement Even With Solid Savings

The Retirement Income Assumption That Breaks Down First During Inflation Cycles

Why Financial Stress Feels Worse After Retirement Instead of Better

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Retirement Tagged With: 401(k), budgeting in retirement, Estate planning, financial advisors, financial independence, healthcare costs, inflation risk, investment strategy, retirement mistakes, retirement planning, Social Security, tax planning

Apple and Google “Legacy” Warning: 5 Settings You Must Change Today to Avoid a Post-Mortem Tech Nightmare

February 24, 2026 by Brandon Marcus Leave a Comment

Apple and Google "Legacy" Warning: 5 Settings You Must Change Today to Avoid a Post-Mortem Tech Nightmare
Image Source: Unsplash.com

Your entire life sits behind a password. Photos, messages, financial records, location history, health data, purchase receipts, voice notes, and that email account you opened in college and never closed. Apple and Google don’t just store your data. They store your identity. And if something happens to you tomorrow, that identity can turn into a locked vault that your family cannot open.

Both Apple and Google built tools that let you decide what happens to your data after you die. Most people never touch those settings. That creates confusion, legal headaches, and in some cases, permanent data loss. If you want to avoid a post-mortem tech nightmare, you need to change five settings today.

1. Apple’s Legacy Contact: The One Setting Too Many People Ignore

If you use an iPhone, iPad, or Mac, your Apple ID controls everything tied to iCloud. That includes your photos, notes, device backups, messages, and even purchases. Apple created a feature called Legacy Contact to solve the access problem after death, yet many people never activate it.

When you add a Legacy Contact, you choose someone who can access specific data in your Apple account after you pass away. You generate a special access key and share it with that person. After your death, they submit that key and a death certificate to Apple. Apple then grants them access to your data for a limited period.

Without this setting, your family might need a court order just to retrieve photos. Even then, Apple does not guarantee access to everything. Privacy laws and company policies limit what Apple can release.

2. Google’s Inactive Account Manager: Your Digital Executor in Disguise

Your Google account probably runs your email, cloud storage, calendar, YouTube subscriptions, and maybe even your phone. If you use Gmail, Google Photos, or Google Drive, your digital footprint grows fast. Google built a feature called Inactive Account Manager that lets you decide what happens if your account goes unused for a set period.

You choose how long Google waits before it considers your account inactive, usually between three and eighteen months. After that, Google contacts you through your listed recovery methods. If you still do not respond, Google notifies the trusted contacts you selected. You can allow them to download specific data, such as photos or emails.

You can also instruct Google to delete your account permanently after that process. That choice matters. Some people want preservation. Others want a clean digital exit.

3. Two-Factor Authentication: Protection That Can Backfire

Two-factor authentication keeps hackers out. It adds a second step, often a code sent to your phone or generated by an app. Apple and Google both encourage it, and you absolutely should use it. Apple uses two-factor authentication for Apple ID, and Google supports several 2FA methods for Google Accounts.

But here is the problem: if you do not document your recovery options, two-factor authentication can lock out your family permanently.

Review your trusted phone numbers and recovery email addresses right now. Make sure they stay current. If you changed numbers recently and forgot to update your account, you created a future disaster. Check your account recovery contacts in both Apple ID settings and your Google Account security page.

Also, consider where you store backup codes. Google lets you generate one-time backup codes. Save them in a secure password manager or physical safe. If no one can access your phone and no one can receive your recovery codes, your digital life freezes in place.

Apple and Google "Legacy" Warning: 5 Settings You Must Change Today to Avoid a Post-Mortem Tech Nightmare
Image Source: Unsplash.com

4. Password Managers: Stop Being the Only Person With the Keys

If you handle every password in your head or in a secret note app, you create a single point of failure. Apple offers iCloud Keychain inside your Apple ecosystem. Google offers its own password manager through Chrome and Android. Many people also use third-party managers.

These tools encrypt and store your login credentials. They make daily life easier and safer. But you must think about inheritance. If you use Apple’s built-in password system tied to your Apple ID, your Legacy Contact can eventually access data after approval. If you use Google’s password manager, access depends on your Inactive Account Manager settings.

You should also evaluate whether you want a separate password manager that supports emergency access features. Some services allow you to designate a trusted contact who can request access, with a waiting period that gives you time to deny the request if you are alive.

5. Data Cleanup: Decide What Deserves to Survive You

You do not need to preserve every digital breadcrumb. Apple and Google store years of data by default. Google Maps may hold location history. Google Photos may store thousands of images. iCloud may contain backups from devices you no longer own.

Review what you actually want someone to access. Log into your Google Account and examine your activity controls. Decide whether you want location history and web activity saved long-term. Check your iCloud storage and delete what no longer serves you.

This step does two things. It reduces your digital footprint, and it simplifies what your trusted contacts must sort through later. You shape your legacy by choosing what remains.

Your Digital Afterlife Deserves a Plan

You plan for insurance, wills, and medical directives. Your tech life deserves the same respect. Apple and Google gave you the tools. They did not activate them for you.

We live online now. Photos, conversations, and memories sit on servers instead of in shoeboxes. If you care about the people who will handle your affairs someday, give them clarity instead of chaos.

Have you adjusted your Apple or Google settings yet, or does this feel like something you keep meaning to do but never quite start? Let’s discuss it in the comments below.

You May Also Like…

Market Frame: 4 Visual Techniques Advisors Use to Explain Risk Better

Tech-Threat: 5 Ways AI Is Changing What Your Financial Advisor Should Be Doing for You

7 Tech Products Gen Z Can’t Live Without — That Are Actually Downgrades

9 Powerful Techniques to Master Your Money Emotions Wisely

Lease Management Made Easy: Best Software Solutions

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Technology Tagged With: Apple ID, digital estate planning, Gmail Security, Google Account, iCloud Data, Inactive Account Manager, iPhone Settings, Legacy Contact, online privacy, password management, Tech Safety, two-factor authentication

Is Your State a Skimmer Hub? The 9 Places Where Credit Card Fraud Is Skyrocketing

February 24, 2026 by Brandon Marcus Leave a Comment

Is Your State a Skimmer Hub? The 9 Places Where Credit Card Fraud Is Skyrocketing
Image Source: Pexels.com

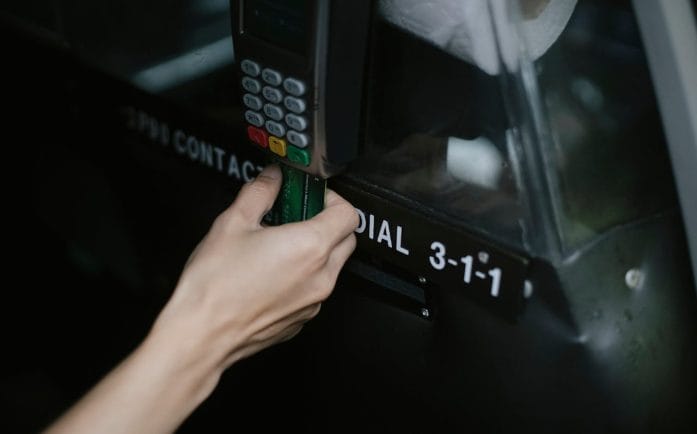
Think about this scenario: you’re fueling up, grabbing lunch, or swiping at a checkout—and somewhere in the machinery, someone isn’t playing by the rules.

Credit card fraud isn’t just something that happens to other people. It’s exploding in certain parts of the country, and understanding where it’s happening most can be the difference between catching a great deal and getting hit with a nasty financial surprise. Let’s cut through the fear-mongering and get to the facts, plus exact strategies to keep your money where it belongs.

1. Florida: Sunshine and Skimmers

Florida isn’t just a top travel destination; it also tops the list for credit card fraud reports per capita in the U.S. This has been a growing trend shaped by heavy tourism, transient customers less likely to scrutinize their statements, and endless high-traffic transactions that make perfect cover for card thieves.

Gas stations along major interstates and standalone ATMs in tourist zones often turn into magnets for skimming devices because of that constant footfall. If you find yourself in Florida, think beyond the beach umbrella: choose payment methods like tap-to-pay where possible, and ALWAYS check your statements within days of any travel. On the road, watch for unfamiliar ATMs and skip the ones tucked out of sight.

2. Georgia: The New Fraud Frontier

Georgia has rapidly risen up the charts to become one of the most common places for credit card fraud. Atlanta’s busy airport, sprawling suburbs, and high commuter traffic create a near-endless corridor of opportunity for skimming rings to plant devices unnoticed.

In addition to gas pumps, convenience store POS units and hotel lobby ATMs are frequently hit because they move so much volume in a single day it’s easier for thieves to stay under the radar. One of the few bright spots? If your card supports contactless payments through your phone or smart watch, using that option can sidestep swipe-based skimmers entirely. If you must dip your chip or swipe, glance at the reader and back away if anything seems out of place.

3. Nevada: Tourist Traps Aren’t Just Casinos

Las Vegas and Reno don’t just lure visitors for entertainment—they also attract fraudsters hunting for card data. Nevada’s blend of tourism, heavy cash flow, and high-turnover transactions makes it a perfect playground for skimming operations.

Whether you’re grabbing gas to hit the next attraction or using an ATM after dinner, criminals know that large crowds can camouflage illegal card readers. Casinos and hospitality businesses invest heavily in security, but smaller ATMs and gas station terminals often lag behind. As with other hotspots, the smartest move here is caution: prefer payments that don’t require swiping or inserting your card, and take a moment to inspect devices before touching them.

4. California: Population Power Meets Criminal Innovation

When it comes to sheer numbers of skimming events, California tops many lists. Far too many incidents have taken place in the Golden State, largely because of massive population density and a vast network of ATMs and independent gas stations.

Whether you’re in Los Angeles, the Bay Area, or smaller inland towns, the sheer volume of financial transactions gives thieves more victims with less effort. Even with advanced EMV chip technology widely deployed, the human element still matters; as more criminals switch to internal skimmers that latch inside card slots, spotting them becomes harder. Routine vigilance—like wiggling a card reader before using it or preferring chip or contactless transactions—is essential here.

5. Texas: Big State, Growing Problem

Texas often makes this list not because it has the highest per-capita rate, but because of its size and sheer number of cases reported annually. Large metropolitan areas like Houston, Dallas and Austin see a lot of card usage, and that volume gives fraudsters plenty of opportunities.

Law enforcement is cracking down in parts of the state with tougher sentencing and focused fraud units, and that’s helping to deter some shady players. However, people should stay alert everywhere from freeway gas stations to mall kiosks. If a payment terminal seems loose or sticker seals are damaged, walk inside and pay at the register. This isn’t paranoia—it’s paying attention to the details that protect you.

6. New York: Big City Risks, Big Data Losses

New York doesn’t just draw headlines for its skyline; it draws fraud activity too. Heavy travel, millions of daily transactions, and abundant independent ATMs and retail terminals make the state a high-risk zone for skimming devices.

Federal and local task forces have recently upped enforcement in cities like New York City itself to crack down on organized skimming rings, especially ones targeting lower-income communities and benefit cards that often lack modern security features. In such environments, choosing EMV chip or contactless payments isn’t just smart, it’s one of the most effective defenses you have.

Is Your State a Skimmer Hub? The 9 Places Where Credit Card Fraud Is Skyrocketing
Image Source: Pexels.com

7. Pennsylvania: A Quiet but Dangerous Player

Pennsylvania doesn’t always top the news for fraud, but its mix of urban centers like Philadelphia and Pittsburgh coupled with endless smaller towns makes it fertile ground for skimming.

Criminals know that in quieter areas, people might be less wary. Payment terminals at gas stations and smaller merchants often lack the most advanced tamper-proof protections, and that makes them inviting targets. Staying informed about local alerts—many police departments will publicize skimming devices found in their precincts—can give you an edge before you swipe. Naming unfamiliar ATMs and choosing terminals within sight of staff cuts your risk dramatically.

8 & 9. Maryland and Virginia: Beltway Busts

Down on the East Coast, Maryland and Virginia round out a cluster of states where card skimming has frequently been spotted. Their proximity to major travel corridors, commuter traffic, and dense populations means payment terminals get hammered every day. In these states, fraud isn’t always about big numbers in one city—it’s about opportunity everywhere you look.

If you’re filling up on I-95 or stopping at a rest area kiosk, assume that thieves are trying to get ahead of you. When possible, switch to contactless payments, check terminals for tampering just like you check your locks at night, and set up instant fraud alerts with your bank so if anything unusual happens, you know immediately.

Getting Ahead of the Skimmers

Credit card fraud isn’t going away. In fact, the FBI estimates card skimming alone costs consumers and banks more than $1 billion annually, and criminals keep refining their tools and tactics. While EMV chips, tokenization, and digital wallets have cut down some types of fraud, physical skimmers and the digital scams that follow still thrive because there’s always personal data to grab. Skimmers often attach to ATMs, gas pumps, and point-of-sale devices and harvest card info and PINs before you even notice a thing.

Do you think your state could be next, or have you spotted high-risk areas where you live? Share your thoughts in the comments.

You May Also Like…

8 Job-Scam Red Flags Everyone Needs to Know in 2025

8 Beauty Scams That Fooled Everyone — And Still Do

The “Love Bombing” Tactic Scammers Use to Gain Financial Control in a New Relationship

7 Reasons Credit Card Limits Drop After Paydowns — Even When You Never Miss a Payment

23% of Americans With Credit Card Debt Don’t Believe They’ll Ever Pay It Off

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Crime Tagged With: card skimmers, consumer advice, credit card fraud, credit theft statistics, Financial Security, fraud prevention, identity theft, skimming hotspots, U.S. fraud trends

10 Documents That Should Be Locked Away in a Safety Deposit Box

February 24, 2026 by Brandon Marcus Leave a Comment

These Are 10 Documents That Should Be Locked Away in a Safety Deposit Box
Image Source: Pexels.com

You can replace a couch. You can rebuild a wardrobe. You cannot casually replace the documents that prove who you are, what you own, and who should inherit it all. Some papers carry the weight of your entire financial life, and they deserve more than a junk drawer or a random folder on a closet shelf.

A safety deposit box at a bank offers something your house simply cannot promise: controlled access, security monitoring, and protection from fire or theft beyond what a standard filing cabinet can handle. While you should never stash everything in there—especially items you might need immediately—certain documents absolutely belong behind that heavy steel door.

1. Your Will: The Blueprint for Everything You Leave Behind

If you created a will, you invested time and likely money to make sure your assets go where you want them to go. Leaving that document in a desk drawer defeats the purpose. You want the original signed copy stored somewhere secure and protected from fire, flood, and prying hands.

An executor cannot probate a will without the original in many states, so safeguarding it matters. A safety deposit box works well, but you should confirm that your executor can access it after your death. Some banks seal boxes upon notification of death, which can create delays if no one else has authorized access.

2. Trust Documents: The Rulebook for Your Assets

If you established a living trust, you probably did so to avoid probate and keep your affairs private. The original trust document outlines how you want your assets managed during your lifetime and distributed afterward. That document carries legal authority, so it needs protection.

While you may keep a copy at home for reference, the original signed version should sit in a secure location. A safety deposit box shields it from accidental loss or damage. You should also ensure your successor trustee knows exactly where to find it.

3. Property Deeds: Proof That You Own What You Own

Your home likely represents your largest asset, and the deed proves ownership. If you own additional real estate, those deeds carry serious weight as well. Although local governments record deeds, keeping your original copies provides peace of mind and simplifies future transactions.

You might not need to access a deed often, but when you do, you will want it intact and legible. Fire or water damage can destroy paper in minutes. A safety deposit box provides a stable, secure environment. If you plan to refinance, sell, or transfer property, having clean documentation makes the process smoother. Think of deeds as the backbone of your asset portfolio.

4. Vehicle Titles: Small Paper, Big Value

Car titles look unimpressive, yet they prove legal ownership of a vehicle. Without the title, selling or transferring a car becomes complicated. Replacing a lost title involves fees, paperwork, and time that no one enjoys.

You rarely need a title unless you sell the vehicle or use it as collateral. That infrequency makes it a strong candidate for a safety deposit box. It stays safe, out of reach from accidental spills or misplacement.

If you own multiple vehicles, boats, or recreational vehicles, gather all titles together and store them in one organized folder inside the box. Future you will feel grateful.

5. Birth Certificates and Adoption Papers: Identity at Its Core

A birth certificate anchors your identity. It supports passport applications, Social Security claims, and countless other official processes. Adoption papers carry equal importance, especially for legal and inheritance matters.

While you may need a certified copy occasionally, the original deserves extra protection. Identity theft remains a real concern, and losing these documents can create significant headaches. A safety deposit box adds an extra layer of defense.

Keep at least one certified copy accessible at home for routine needs, but place originals in the box. That balance gives you convenience without sacrificing security.

These Are 10 Documents That Should Be Locked Away in a Safety Deposit Box
Image Source: Unsplash.com

6. Marriage Licenses and Divorce Decrees: Relationship Records That Matter

Marriage licenses and divorce decrees do more than commemorate life events. They affect taxes, property rights, Social Security benefits, and estate plans. If you ever need to prove marital status, you will rely on these documents.

Storing them in a safety deposit box protects them from damage and loss. Legal institutions often require certified copies, but having your official documents readily available in a secure location helps prevent unnecessary stress.

If your marital status changed recently, review your estate plan and make sure these documents align with your current wishes. Paperwork should always reflect your present reality.

7. Social Security Cards and Citizenship Documents: Guard the Essentials

Social Security cards and citizenship certificates rank among the most sensitive documents you own. Identity thieves actively seek this information because it opens doors to credit fraud and financial crime.

You should not carry your Social Security card in your wallet. Instead, store it securely and retrieve it only when necessary. A safety deposit box offers a controlled environment that reduces risk. Citizenship or naturalization certificates also require careful handling. Replacing them involves time, expense, and paperwork. Secure storage prevents that ordeal from becoming your problem.

8. Insurance Policies: The Paper Trail of Protection

Homeowners, life, and long-term care insurance policies spell out the coverage you rely on when things go wrong. While many insurers provide digital access, you should keep copies of the full policy documents.

Storing the originals in a safety deposit box ensures they remain intact even if your home suffers damage. You might also consider keeping a summary sheet at home that lists policy numbers and contact information for quick reference. If disaster strikes, you will want to move quickly. Organized documentation makes that possible.

9. Business Agreements and Partnership Contracts: Protect Your Professional Life

If you own a business or hold a partnership stake, your agreements define your rights and responsibilities. Operating agreements, shareholder contracts, and buy-sell agreements carry serious legal weight.

Losing these documents can complicate disputes or transitions. A safety deposit box provides an ideal location for the originals. You can keep working copies in your office for day-to-day reference. Entrepreneurs often focus on growth and innovation, but protecting foundational documents matters just as much. Treat them like the assets they are.

10. Powers of Attorney and Health Care Directives: Authority in Critical Moments

A financial power of attorney allows someone you trust to handle your financial affairs if you cannot. A health care directive outlines your medical preferences and appoints someone to make decisions on your behalf.

These documents step into action during emergencies. You should inform the designated individuals about their roles and provide copies as needed. At the same time, store the signed originals in a safety deposit box to protect them. Clear planning prevents chaos. When people understand your wishes and can access the paperwork, they can act with confidence.

Lock It Up, But Think It Through

A safety deposit box works best when you use it thoughtfully. You should not place your only copy of documents that loved ones might need immediately after your death without arranging access. Add a trusted co-renter if appropriate, and review your bank’s policies on box access.

Avoid storing items you might need urgently, such as a passport if you travel frequently. Balance convenience with security. Create a simple inventory list of everything inside the box and keep that list at home so you always know what sits behind that steel door.

Which of these documents already sit safely locked away, and which ones still hide in a drawer somewhere waiting for attention? This is a discussion we need to have in our comments section.

You May Also Like…

The Tax Document Most Homeowners Fail to Update That Triggers Surprise Liens

Estate Overhaul: 10 Document Updates to Make Before New Tax Rules Kick In

Estate Shift: 4 Overlooked Documents That Could Trigger Major Tax Headaches

11 Essential Components of a Bulletproof Estate Plan Document

The Estate Planning Shortcut That Saves Time but Costs Families More in the Long Run

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Lifestyle Tagged With: Estate planning, home safety, identity protection, important paperwork, legal documents, life organization, money management, Personal Finance, Planning, safety deposit box, wills and trusts

Bank Alert: 7 Reasons “Courtesy Credits” Get Taken Back Without Warning

February 24, 2026 by Brandon Marcus Leave a Comment

Bank Alert: 7 Reasons “Courtesy Credits” Get Taken Back Without Warning
Image Source: Unsplash.com

You see a credit pop up in your account and feel a quick rush of relief. The bank refunded a fee. A disputed charge disappeared. Someone fixed a mistake. Then, days or weeks later, that same amount vanishes. No fireworks. No dramatic alert. Just a quiet reversal that leaves your balance lower than you expected.

Courtesy credits sound generous, and sometimes they are. But banks issue them with conditions, and they do not hesitate to take them back when those conditions change. If you rely on that money as if it’s permanent, you can end up scrambling. Let’s talk about why this happens and what you can actually do about it.

1. When a Dispute Doesn’t Go Your Way

Banks often issue a temporary credit when you dispute a debit card charge. Federal rules under Regulation E require banks to investigate errors, and they typically give you provisional credit within 10 business days if they need more time. That credit helps you avoid financial strain while the bank investigates.

But that credit does not mean you won the dispute. If the investigation finds that the charge was valid, the bank will reverse the provisional amount. The merchant might provide proof of authorization, delivery confirmation, or a signed receipt. Once the bank decides the charge stands, it removes the credit.

You can protect yourself here by following through on the dispute process. Provide documents quickly. Respond to bank emails. Keep screenshots and receipts. If you ignore requests for information, you increase the odds that the bank rules against you and pulls that courtesy credit back out of your account.

2. The Deposit That Didn’t Really Clear

Banks sometimes give you access to funds before a check fully clears. You might see a “courtesy” or “provisional” credit that lets you spend part or all of a deposit right away. That early access feels convenient, especially when you need the money urgently.

However, if the check bounces, the bank reverses the credit. The Federal Reserve’s funds availability rules allow banks to make funds available before final settlement, but that availability does not guarantee that the check is good. If the paying bank rejects it for insufficient funds, a closed account, or fraud, your bank removes the money from your balance.

You should treat any recent check deposit as conditional until you confirm it cleared. Avoid spending the full amount immediately, especially if you don’t know the check writer well. If someone pressures you to deposit a check and send money back quickly, that situation almost always signals a scam.

3. Fee Refunds With Strings Attached

Sometimes a bank waives an overdraft fee or monthly maintenance fee as a one-time courtesy. You call, explain the situation, and a representative credits your account. That goodwill gesture often depends on your account staying in good standing.

If you rack up more overdrafts right away or fail to bring your balance positive within a required time frame, the bank can reverse the courtesy refund. Many banks disclose in their account agreements that fee reversals fall under discretionary policies. They reserve the right to adjust your account if new activity changes the picture.

You can avoid this headache by reading your account terms and asking direct questions when you request a refund. Ask whether the credit depends on future behavior. Then adjust your habits. Set up low-balance alerts. Link a savings account for overdraft protection. Take the second chance seriously.

4. Fraud Claims That Change Midstream

When you report suspected fraud, banks move quickly to limit damage. They often issue a provisional credit while they investigate unauthorized transactions. That action protects you from losing access to your own money during the review.

But banks also analyze patterns, device information, transaction history, and merchant data. If they determine that you authorized the transaction or shared your credentials, they can deny the claim and reverse the credit. Some cases fall into gray areas, such as recurring subscription charges you forgot about or transactions made by someone you allowed to use your card.

You strengthen your position by reporting fraud immediately and changing your passwords right away. Avoid sharing debit card details, even with friends or family. Monitor your account frequently so you catch suspicious activity within the required reporting window. Timing matters in fraud claims, and delays can cost you that provisional credit.

Bank Alert: 7 Reasons “Courtesy Credits” Get Taken Back Without Warning
Image Source: Pexels.com

5. Merchant Chargebacks and Double Credits

Sometimes the confusion starts with the merchant, not the bank. You might receive a refund from a retailer and also see a temporary credit from your bank after filing a dispute. If both credits hit your account, you might assume you came out ahead.

Banks reconcile these situations carefully. If the merchant processes a refund and your bank already credited you for the same transaction, the bank will reverse its courtesy credit. You only get one refund for one transaction. The system corrects duplicates once the investigation closes.

Keep track of communications with both the merchant and the bank. If a merchant promises a refund, you may not need to file a dispute at all. Filing too quickly can complicate the process. Patience sometimes saves you from seeing that credit disappear later.

6. Account Reviews and Policy Violations

Banks conduct routine account reviews. They look for patterns that suggest misuse, policy violations, or high risk. If they spot frequent disputes, repeated overdrafts, or suspicious deposit activity, they can reassess prior credits.

In some cases, a bank might determine that a courtesy credit violated internal policy or resulted from incomplete information. When that happens, they adjust the account. The reversal might not come with much explanation beyond a standard notice in your transaction history.

You can lower your risk by keeping your account activity clean and consistent. Avoid frequent returned deposits. Limit disputes to legitimate errors. Maintain clear records. If you notice a reversal that seems wrong, contact the bank promptly and ask for a detailed explanation in writing.

7. Time Limits Expire Quietly

Provisional credits do not sit in limbo forever. Regulation E allows banks up to 45 days to complete most investigations, and even longer in certain cases. During that period, the credit remains temporary.

If the bank reaches a decision near the end of that window, it can reverse the credit with little fanfare. You might not receive a phone call. Instead, you’ll see a transaction labeled “reversal” or “chargeback adjustment.” That timing can feel abrupt, especially if you assumed weeks of silence meant approval.

Mark important dates when you file a dispute. Count forward 10 business days and then 45 calendar days. If you approach those deadlines without hearing back, call the bank and ask about the status. Staying proactive keeps you from getting blindsided.

The Fine Print Always Wins

Account agreements stretch for pages, and most people scroll past them. Those documents spell out the rules around provisional credits, fee reversals, and error investigations. Banks rely on those disclosures when they reverse a courtesy credit.

You do not need to memorize every clause, but you should understand key sections about funds availability, disputes, overdrafts, and fraud claims. Many banks publish simplified summaries online. Spending 20 minutes reviewing those policies can save you from confusion later.

If something feels unclear, ask for clarification. Document the date and the representative’s name. Clear communication builds a paper trail, and that paper trail helps you if you ever escalate a complaint to a regulator or file a formal dispute.

Don’t Treat Temporary Money Like It’s Permanent

Courtesy credits serve a purpose. They cushion mistakes, buy time during investigations, and show goodwill. But they do not equal guaranteed funds until the bank finalizes the underlying issue.

The smartest move involves caution. Leave disputed amounts untouched until the case closes. Build a small emergency cushion so a sudden reversal does not wreck your budget. Turn on transaction alerts and review your account weekly. These habits create breathing room.

Have you ever had a courtesy credit reversed, and did the bank explain it clearly or leave you piecing it together on your own? We want to hear about it in our comments.

You May Also Like…

Banks Are Still Charging Daily Overdraft Fees After Accounts Go Negative

Why Free Online Checking Continues to Beat Traditional Banks

Major Banks Continue Generating Billions From Overdraft Fees

Big Banks Are Still Collecting Billions in Overdraft and NSF Fees

5 Outrageous Fees Hidden in Everyday Banking Services

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Banking Tagged With: bank fees, banking, chargebacks, checking accounts, consumer advice, courtesy credit, deposits, financial literacy, fraud prevention, money management, overdraft, Personal Finance

Utility Billing Cycle Changes Causing Double Charges

February 23, 2026 by Brandon Marcus Leave a Comment

Utility Billing Cycle Changes Causing Double Charges
Image Source: Unsplash.com

A single date change can rattle an entire household budget. When a utility company shifts its billing cycle, many households open a statement that looks inflated, confusing, and sometimes downright alarming.

The total often appears far higher than usual, and panic sets in before anyone even scans the fine print. Utility billing cycle changes can cause what looks like double charges, but the real story often sits in the details, and those details deserve close attention.

Why Billing Cycles Change in the First Place

Utility companies do not change billing cycles on a whim. Providers sometimes adjust billing schedules to streamline operations, align meter-reading routes, or upgrade internal systems. When a company rolls out new billing software or reorganizes service territories, it often shifts customer billing dates to match those new structures.

These changes can also occur after a customer moves service to a new address, switches rate plans, or enrolls in budget billing programs. In some cases, regulators approve adjustments that affect billing cycles, especially when utilities update rate structures or modernize their metering infrastructure. None of this automatically means a mistake occurred, but it does mean the next bill might cover more days than usual.

That extended billing period often triggers the appearance of a double charge. Instead of billing for 30 days, the utility might bill for 45 or even 60 days to transition from the old cycle to the new one. The total rises because the billing period grew longer, not because the company charged twice for the same electricity or water. Still, without clear communication, that spike can feel like a punch to the budget.

When One Bill Covers Two Time Periods

A billing cycle change often results in what industry professionals call a “prorated” bill. That term simply means the company calculated charges based on the actual number of days in the billing period. If the cycle shifts forward by two weeks, the next statement might include six weeks of usage instead of four.

That longer window can easily look like a duplicate charge. The total doubles compared to a typical month, and the brain jumps to the worst-case scenario. In reality, the bill likely reflects real usage over a longer stretch of time. Electricity, gas, and water meters continue to record consumption every day, so a longer billing period naturally generates a higher total.

Utilities typically show the start and end dates for the billing period on the statement. Those dates tell the real story. If the previous bill covered January 1 through January 30 and the new bill covers January 31 through March 15, the math adds up. That statement reflects 44 days of service, not two separate charges for the same month. Scrutinizing those dates clears up confusion faster than any call to customer service.

Red Flags That Signal a Real Problem

Not every high bill stems from a harmless billing cycle change. Errors can occur, and customers should never ignore a number that feels wildly off. A true double charge usually appears as two identical line items for the same service period or two withdrawals from a bank account for the same invoice.

Online account portals make this easier to track. Many utilities allow customers to view payment history, pending charges, and past statements in one place. If the system shows two payments processed for the same bill number, that signals a potential issue. Bank and credit card statements can also confirm whether a duplicate payment cleared.

Another warning sign involves mismatched meter readings. Each bill typically lists the previous and current meter reading. If those numbers jump far beyond normal usage without explanation, something may have gone wrong with the reading or data entry. In that situation, contacting the utility promptly can prevent late fees and additional stress.

Utility Billing Cycle Changes Causing Double Charges
Image Source: Unsplash.com

How to Respond Without Losing Your Cool

The worst move involves ignoring the bill out of frustration. Late fees, service interruptions, and credit reporting consequences can follow quickly if payment deadlines pass. Instead, take a methodical approach.

First, review the billing period dates and compare them to the previous statement. Calculate the number of days covered in each bill. If the latest statement includes significantly more days, the higher total likely reflects a transition period rather than a duplicate charge.

Second, check whether the utility sent prior notice about a billing cycle change. Many companies send emails, letters, or bill inserts explaining upcoming adjustments. Those notices often outline what to expect and warn about a potentially larger transitional bill.

Third, contact customer service if confusion persists. Utility companies typically offer payment plans for unusually large bills, especially when a billing cycle shift creates a temporary spike. Many providers also allow customers to spread the cost over several months through installment arrangements or budget billing programs.

Keeping detailed records strengthens any dispute. Save copies of statements, screenshots of account histories, and confirmation numbers from phone calls or online chats. Organized documentation can speed up resolution if the situation escalates.

Protecting Your Budget From Future Surprises

A billing cycle change highlights a bigger truth about household finances: flexibility matters. Setting aside a small monthly cushion in a dedicated utilities fund can soften the blow of an unexpectedly large bill. Even a modest buffer can prevent panic when a statement jumps higher than usual.

Enrolling in budget billing programs offers another layer of stability. Many utilities calculate an average monthly payment based on past usage and spread costs evenly throughout the year. While the total annual cost remains the same, the predictable payment can simplify planning.

Monitoring usage through smart meters and online dashboards also helps. Many utilities now provide near real-time data, allowing households to track daily or weekly consumption. That visibility makes it easier to spot unusual spikes and adjust habits before the next statement arrives.

Finally, always read notices from utility providers, even when they look routine. Billing inserts and email updates often contain critical information about rate changes, cycle adjustments, or new fees. Staying informed prevents confusion and strengthens confidence when a bill looks unfamiliar.

Information Beats Panic Every Time

A billing cycle change can inflate a single statement and create the impression of double charges, but the explanation usually lies in the dates and the number of days billed. Utilities adjust schedules for operational reasons, and those transitions often produce one larger-than-normal bill rather than an actual duplicate charge. Careful review of billing periods, meter readings, and payment history separates harmless timing shifts from true errors.

Taking a calm, organized approach protects both finances and peace of mind. Reviewing statements closely, keeping records, and reaching out to customer service when necessary ensures that no one pays more than required. A larger bill may feel alarming at first glance, but clear information often replaces that anxiety with understanding.

Has a recent utility bill caught attention in a way that felt confusing or overwhelming, and what steps helped clarify the situation? We want you to share with everyone below.

You May Also Like…

Why Monthly Bills Are Rising Even for Households That Haven’t Changed Spending

Why Are Utility Bills Becoming a Bigger Budget Problem

Could Your Retirement Be at Risk From Rising Utility Costs

9 Everyday Costs Rising Faster Than Seniors’ Income

Why Do So Many People Believe Budgeting Apps Solve Everything

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Lifestyle Tagged With: billing cycle change, billing errors, Consumer Protection, customer service, double charges, electricity rates, energy bills, household budgeting, payment due dates, Personal Finance, utility bills, water bills

How The SALT Deduction Caps Squeezed Many Middle-Income Taxpayers

February 23, 2026 by Brandon Marcus Leave a Comment

How The SALT Deduction Caps Squeezed Many Middle-Income Taxpayers
Image Source: Pexels.com

A single number — $10,000 — redrew the financial map for millions of households. When Congress passed the Tax Cuts and Jobs Act in late 2017, lawmakers lowered tax rates, nearly doubled the standard deduction, and promised broad relief. Yet one provision quietly shifted the ground under middle-income families in states with higher property and income taxes. The new cap on the state and local tax deduction, widely known as SALT, limited the total deduction for state income taxes, property taxes, and certain local taxes to $10,000 per household per year.

That cap landed with force in places where housing costs and state tax bills already ran high, and it changed the math for families who once relied on itemizing their deductions to soften the blow. And although it is now changing, the damage has already been done.

The $10,000 Line That Changed the Equation

Before 2018, taxpayers who itemized could deduct the full amount of eligible state and local taxes paid, subject to some limitations like the alternative minimum tax. Many middle-income households in states such as New York, California, and New Jersey regularly deducted well above $10,000, especially if they owned homes with substantial property tax bills. The 2017 law imposed a firm ceiling of $10,000.

That detail stunned many households because it did not scale with income, home value, or regional cost of living. A family paying $14,000 in property taxes and $8,000 in state income taxes could deduct only $10,000 total, leaving $12,000 without any federal tax relief. That lost deduction increased taxable income and, in turn, increased federal tax liability. While lower federal tax rates and a larger standard deduction offset some of that impact, families in high-tax areas often discovered that the cap erased much of the benefit.

Middle-Income Households Felt the Pinch

High earners certainly lost deductions under the cap, but middle-income households often experienced the squeeze more sharply because they lacked the flexibility and planning options that wealthier taxpayers use. In suburban counties with high property values, a teacher married to a mid-level manager could face annual property taxes well above $10,000 without owning a mansion. Add state income taxes, and the total climbs quickly past the cap.

In states with progressive income tax systems, families earning between $150,000 and $300,000 frequently saw the largest proportional increase in federal taxable income due to the cap. Those households rarely qualify as ultra-wealthy, yet they shoulder significant local tax burdens because local governments fund schools and services heavily through property taxes. When the federal government limited the deduction, it effectively required those families to pay federal tax on income already taxed at the state and local level.

Real Estate, Relocation, and Ripple Effects

The SALT cap did not operate in a vacuum. Housing markets and migration patterns responded to the new reality. In some high-tax suburbs, prospective buyers began calculating not only mortgage payments and property taxes but also how much of those taxes they could actually deduct. A property tax bill that once softened under a full deduction suddenly felt heavier.

Some analysts linked the cap to modest declines in home price growth in certain high-tax areas after 2018, though many factors influence real estate markets, including interest rates and local economic conditions. Still, the psychology changed. A $15,000 property tax bill no longer carried the same federal offset, so buyers adjusted their willingness to pay.

At the same time, lower-tax states such as Florida and Texas attracted attention from households looking to reduce overall tax burdens. These states do not impose a state income tax, which means residents avoid one component of the SALT cap entirely. Migration trends accelerated during the pandemic for many reasons, including remote work, but tax policy joined the conversation more prominently than it had in years.

How The SALT Deduction Caps Squeezed Many Middle-Income Taxpayers
Image Source: Pexels.com

The Political Tug-of-War Continues

The SALT cap never escaped controversy. Lawmakers from high-tax states have pushed for repeal or modification since 2018, arguing that the cap penalizes their constituents unfairly. Others counter that the pre-2018 unlimited deduction disproportionately benefited higher-income taxpayers and that the cap helps fund lower federal rates and other provisions.

Due to new law, the SALT deduction cap is now set to quadruple to $40,000 through the tax-year 2029. However, after that year, the deduction cap will drop back down to $10,000. Between now and then, a lot can change, and there is no guarantee that Congress won’t act again to alter that $40,000 qualifier or the timeline.

Anyone who lives in a high-tax state should keep a close eye on legislative developments over the next year. And more changes to the cap could alter housing decisions, retirement timing, and even career moves.

The Bottom Line for Households Feeling the Pressure

The SALT deduction cap reshaped federal tax bills in a way that many middle-income households did not anticipate. It limited a deduction that once scaled naturally with local tax burdens and replaced it with a flat ceiling that ignores regional cost differences.

The $10,000 figure may look simple, but it carries complicated consequences that ripple through housing, migration, and personal finance decisions. The $10,000 cap is changing, and that could benefit many, but the story of the SALT cap isn’t done yet.

What are your stories with the SALT deduction cap, and how have they affected your life? Let’s hear about it in the comments below.

You May Also Like…

What Changing SALT Caps Mean for Your Inheritance Now

5 Reasons To Talk To Your Kids About Taxes

Income Threshold: 4 Hidden Taxes That Hit Once You Cross Certain Limits

8 Cities Millennials Are Flocking To — And Why

Social Security 2026 COLA: Why Your 2.8% Raise Disappeared After Medicare Deductions

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: tax tips Tagged With: federal income tax, high-tax states, IRS rules, itemized deductions, middle-income taxpayers, Personal Finance, property taxes, SALT deduction, state and local tax deduction, Tax Cuts and Jobs Act, tax planning, tax strategy

Why Some Charitable Donations No Longer Lower Tax Bills

February 23, 2026 by Brandon Marcus Leave a Comment

Why Some Charitable Donations No Longer Lower Tax Bills
Image Source: Unsplash.com

A generous donation once came with a predictable bonus: a lower tax bill. That assumption no longer holds true for millions of households, and the shift has reshaped how giving fits into financial planning. Many people still write checks or click “donate” with the belief that April will reward their generosity.

In reality, tax law changes, income thresholds, and stricter rules around eligible organizations now block that benefit in many situations. Anyone who gives regularly needs to understand what changed and how those changes affect the bottom line.

The Standard Deduction Changed the Game

The most significant reason charitable donations no longer reduce tax bills for many households comes down to one number: the standard deduction. The Tax Cuts and Jobs Act of 2017 nearly doubled the standard deduction beginning in 2018. The figures continue to adjust annually for inflation.

This shift surprised many households because they continued their usual giving patterns without realizing that the math no longer worked in their favor. A couple who once itemized mortgage interest, state taxes, and charitable contributions may now find that the total falls below the standard deduction. In that case, itemizing offers no advantage, and the charitable contribution delivers no tax savings.

Itemizing Requires Clearing a Higher Bar

To deduct charitable contributions, taxpayers must itemize on Schedule A. That requirement sounds simple, but it demands that total itemized deductions exceed the standard deduction. Those itemized deductions include mortgage interest, state and local taxes (capped at $10,000 under current law), medical expenses above certain income thresholds, and charitable gifts.

The $10,000 cap on state and local tax deductions, often called the SALT cap, makes itemizing harder for many middle- and upper-income households. Even those who live in high-tax states may struggle to reach the standard deduction threshold when the SALT cap limits how much they can claim. If mortgage interest has declined because of refinancing or a paid-off home, the hurdle grows even higher.

Charitable donations must compete with those other deductions for space. If the total does not exceed the standard deduction, the tax code effectively ignores the charitable gift. That reality explains why many people feel confused at tax time when their donation receipts fail to move the needle.

Not Every Donation Qualifies

Even taxpayers who itemize cannot deduct every contribution. The Internal Revenue Service only allows deductions for gifts made to qualified organizations. That includes most 501(c)(3) nonprofits, religious organizations, and certain governmental entities. Political campaigns, social clubs, and some foreign charities do not qualify.

Donors must also follow documentation rules. Cash donations require bank records or written communication from the charity. Noncash donations, such as clothing or household goods, must remain in good condition or better. For high-value noncash contributions, additional forms and appraisals may apply.

If someone gives to a friend’s online fundraiser that lacks a qualified nonprofit sponsor, that gift does not count as a deductible charitable contribution. If someone drops cash into a jar without documentation, that money cannot support a deduction. These details matter, and the IRS enforces them.

Income Limits Can Shrink the Benefit

Even when a donation qualifies and the taxpayer itemizes, income limits may reduce the deductible amount. In general, cash contributions to public charities can reach up to 60 percent of adjusted gross income. Contributions of appreciated assets, such as stocks, often face a 30 percent limit of adjusted gross income. Excess amounts can carry forward for up to five years, but that carryforward requires planning and recordkeeping.

High-income households sometimes assume they can deduct the full value of a large gift in one year. In reality, income limits may restrict the deduction, especially for substantial contributions. If income fluctuates from year to year, the timing of a donation can change how much of the gift produces a tax benefit.

These limits rarely affect modest annual donations, but they matter for major gifts, estate planning strategies, and large transfers of appreciated property. Anyone contemplating a significant contribution should review those thresholds before finalizing the gift.

Why Some Charitable Donations No Longer Lower Tax Bills
Image Source: Pexels.com

The Temporary Pandemic Break Is Gone

During the height of the COVID-19 pandemic, Congress allowed a temporary above-the-line deduction for charitable contributions for taxpayers who did not itemize. But that temporary rule expired. For tax years after 2021, the tax code returned to its traditional structure: no itemizing, no deduction for charitable contributions. Many taxpayers grew accustomed to seeing at least some small tax benefit from donations during those pandemic years. When that line disappeared from returns, confusion followed.

Anyone who last reviewed tax strategy during that temporary window may now operate under outdated assumptions. The current rules offer no comparable above-the-line deduction for charitable gifts.

Smart Giving Still Makes Financial Sense

A charitable donation should never rely solely on tax savings, but smart planning can still maximize the financial impact. Taxpayers who want to restore the deduction effect sometimes use a strategy called “bunching.” Instead of giving the same amount every year, they combine two or more years of donations into one tax year to push itemized deductions above the standard deduction. In the off years, they claim the standard deduction.

Donor-advised funds can help with that strategy. A donor can contribute a larger lump sum in one year, claim the deduction in that year, and then recommend grants to charities over time. This approach allows steady support for nonprofits while concentrating deductions in a single year.

Donating appreciated assets, such as long-held stocks, can also improve tax efficiency. By transferring shares directly to a qualified charity, a donor avoids paying capital gains tax on the appreciation and may deduct the fair market value, subject to income limits. This strategy often delivers more tax value than selling the asset and donating the cash proceeds.

Qualified charitable distributions from individual retirement accounts offer another option for those age 70½ or older. A direct transfer from an IRA to a qualified charity can count toward required minimum distributions and exclude the amount from taxable income. That move does not require itemizing and can lower adjusted gross income, which may affect other tax calculations.

Giving With Eyes Wide Open

Charitable giving still matters, and nonprofits rely on consistent support. The tax code, however, no longer guarantees a reward for every donation. Larger standard deductions, stricter caps on other itemized deductions, qualification rules, and expired temporary provisions all contribute to the change.

Anyone who gives regularly should review total deductions, income levels, and long-term goals before assuming a tax benefit will follow. A tax professional can model scenarios and suggest timing strategies that align generosity with financial efficiency. Financial software can also estimate whether itemizing makes sense in a given year.

The most powerful approach combines purpose with planning. Donations should reflect values and priorities, but donors should also understand the current rules that govern deductions. When generosity meets informed strategy, both the cause and the household budget can thrive.

The Real Reward of Giving

Tax law has shifted, and charitable deductions have narrowed, but generosity has not lost its impact. A donation may no longer shrink a tax bill in many cases, yet it can still strengthen communities, fund research, and provide relief where it matters most. Financial clarity empowers smarter decisions, and smarter decisions can stretch each dollar further.

Before making the next contribution, review whether itemizing makes sense this year and consider whether bunching, appreciated assets, or qualified charitable distributions could improve the outcome. Giving works best when intention and strategy move in the same direction.

How has the change in tax rules affected personal giving strategies, and has it altered the way donations are planned each year? We want to hear your stories in our comments section.

You May Also Like…

Charity Strategy: 9 Giving Moves That Bring Tax Benefits Many People Ignore

6 Life-Changing Organizations You’ve Probably Never Donated To (But Should)

8 Surprising Reasons People Secretly Hate Donating to Charity

5 Ways to Use Qualified Charitable Distributions at 70½ to Cut Your RMD Tax Bill

8 Times Charities Used Donations in Shocking Ways

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: tax tips Tagged With: Charitable Donations, donor-advised funds, Estate planning, IRS rules, itemized deductions, nonprofit organizations, Personal Finance, philanthropy, standard deduction, Tax Deductions, tax planning, taxes

Florida Condo Fees Continue Surging — Seniors Face Massive Assessments

February 23, 2026 by Brandon Marcus Leave a Comment

Florida Condo Fees Continue Surging — Seniors Face Massive Assessments
Image Source: Unsplash.com

Florida condo living once promised a predictable budget and a breezy retirement. That promise now looks fragile across large stretches of the state, where monthly dues keep climbing and special assessments land with five-figure force. For many seniors on fixed incomes, the math simply does not work anymore.

Across Florida, condominium associations have raised fees to cover skyrocketing property insurance premiums, inflation-driven maintenance costs, and sweeping new safety requirements.

Safety Comes With a Bill

Florida lawmakers passed major condo safety reforms in 2022 and refined them in 2023, requiring milestone inspections for older buildings and mandating structural integrity reserve studies. Associations must now fully fund reserves for critical structural components, including roofs, load-bearing walls, plumbing, and electrical systems. Boards no longer enjoy the easy option of waiving reserves with a simple membership vote.

That shift forces associations to confront decades of deferred maintenance. Many buildings kept fees artificially low for years, and some boards postponed expensive repairs to avoid angering residents. The new law demands transparency and action. If engineers identify serious structural problems, associations must address them. If reserves fall short, boards must raise monthly dues or levy special assessments.

For seniors who purchased condos decades ago, the shock feels profound. A retiree who once paid a few hundred dollars a month may now face dues that double or triple, plus a special assessment that runs into the tens of thousands. These costs do not reflect luxury upgrades or cosmetic changes; they fund basic structural safety. That distinction matters, but it does not soften the financial blow.

Insurance Premiums Add Fuel to the Fire

Condo associations in Florida face another brutal reality: property insurance costs continue to surge. Florida’s insurance market has endured years of turmoil driven by hurricane losses, litigation, and carrier insolvencies. When insurers pull out of the state or tighten underwriting standards, associations scramble to secure coverage at much higher premiums.

Associations often pass those higher premiums straight to owners through increased dues. A building that once paid manageable rates may now confront premiums that multiply year over year. Even associations that maintain clean loss histories cannot escape statewide market pressures.

Seniors who budgeted carefully for retirement rarely anticipate this kind of volatility. Social Security benefits and pension payments do not spike to match insurance premiums. Fixed incomes do not stretch easily. When associations stack insurance hikes on top of new reserve funding requirements, the combined effect strains even disciplined retirees.

Special Assessments: The Five-Figure Surprise

Monthly fee increases hurt, but special assessments often cause the most panic. Associations impose special assessments when they need immediate cash for large repairs or to shore up underfunded reserves.

Seniors who lack savings or liquid assets face difficult choices. Some tap retirement accounts and trigger tax consequences. Others take out loans or reverse mortgages. Some list their units for sale, only to discover that buyers hesitate when looming assessments or expensive repairs appear in the association’s financial disclosures.

Florida lawmakers have attempted to offer limited relief by adjusting deadlines for reserve funding in certain circumstances, particularly for smaller or less complex buildings. However, the core safety requirements remain in place. Engineers must inspect qualifying buildings, and associations must fund reserves for structural components. Owners cannot vote these obligations away.

Anyone considering the sale of a condo should review the association’s financial statements, reserve study, and any pending assessments before listing. A realistic understanding of the building’s financial health prevents last-minute surprises that derail a transaction.

Fixed Incomes Meet Unpredictable Costs

Retirement planning relies on stability. Many seniors purchased Florida condos precisely because they wanted fewer maintenance headaches and more predictable expenses than a single-family home might demand. Condo life promised simplicity: pay the monthly fee, and the association handles the roof, landscaping, and exterior maintenance.

That promise now feels complicated. Inflation drives up the cost of materials and labor. Insurance premiums rise sharply. Reserve funding requirements tighten. Boards face little room to maneuver, and residents absorb the results.

Seniors who feel overwhelmed should start with information rather than panic. Attend association meetings. Request copies of the reserve study and milestone inspection reports. Ask the board about long-term financial planning and whether the association explores competitive insurance bids or phased repair schedules. Knowledge reduces fear and helps owners make rational decisions.

Florida Condo Fees Continue Surging — Seniors Face Massive Assessments
Image Source: Pexels.com

Buyers Beware: Due Diligence Matters More Than Ever

The Florida condo market has not collapsed, but buyers now scrutinize buildings with a sharper eye. Lenders often require detailed documentation about reserves and inspections before approving mortgages. Cash buyers also demand transparency.

Anyone shopping for a Florida condo should dig deeply into the association’s finances. Review recent budgets and reserve balances. Examine the structural integrity reserve study and confirm whether the association fully funds required reserves. Look for pending litigation or major repair projects that could trigger new assessments.

Location still matters, and well-maintained buildings in strong markets continue to attract interest. However, buyers who chase the lowest monthly fee without examining reserves may inherit future headaches. A slightly higher fee in a well-funded building often signals better long-term stability.

Sellers should prepare for tougher questions. Full disclosure and organized documentation build trust. A proactive board that communicates clearly about repairs and finances can help stabilize property values, even in a challenging environment.

Policy, Politics, and the Path Forward

State leaders continue to debate how to balance safety, affordability, and market stability. Some lawmakers have proposed adjustments to reserve deadlines or financing options to ease the burden on owners, particularly seniors. At the same time, no serious policymaker wants to weaken structural safety standards.

The tension remains obvious. Safety demands funding. Funding demands higher fees. Higher fees pressure retirees and working families alike. Florida’s large senior population makes the stakes even higher.

Community associations and advocacy groups encourage owners to stay engaged in the legislative process. Tracking proposed bills and contacting local representatives can shape future refinements to the law. Change often moves slowly, but organized voices carry weight in Tallahassee.

A New Era for Florida Condo Living

Florida condo ownership now requires sharper attention, stronger reserves, and more realistic budgeting than ever before. Seniors face genuine stress as fees rise and assessments hit mailboxes, yet the underlying goal of safer buildings carries undeniable importance.

Owners who educate themselves, attend meetings, and seek professional advice stand in a stronger position than those who ignore the issue. Buyers who perform careful due diligence can still find solid opportunities in well-managed communities. Boards that communicate clearly and plan responsibly can rebuild trust and stabilize their associations.

What steps should Florida take next to protect both building safety and the financial well-being of seniors who call these condos home? If you have ideas, we want to hear them in the comments below.

You May Also Like…

Florida Escrow Payments Continue Rising as Insurance Costs Climb

State Farm Files for 10% Rate Reduction in Florida After Years of Increases

6 Hidden Costs of Homeownership That Blindside First-Time Buyers

Can’t Qualify for That Condo: 7 Things You Should Know About a Spot FHA Loan

The Hidden Cost of Rent Control in California

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Real Estate Tagged With: condo fees, condo safety law, fixed income retirees, Florida condos, Florida seniors, HOA costs, housing affordability, property insurance Florida, real estate news, reserve requirements, special assessments, Surfside collapse

The Little-Known Deduction Couples Over 65 Often Miss

February 23, 2026 by Brandon Marcus Leave a Comment

The Little-Known Deduction Couples Over 65 Often Miss
Image Source: Unsplash.com

Retirement changes the tax game in ways that surprise even the most organized couples. Many people assume that once the paychecks stop and Social Security begins, taxes fade into the background. That assumption costs real money every single year.

One of the most overlooked opportunities for couples over 65 sits right inside the federal tax code, waiting quietly behind paperwork and receipts. The medical expense deduction rarely gets the spotlight, yet it can create meaningful savings for older couples who know how to use it.

When Health Costs Turn Into Tax Relief

Healthcare does not get cheaper with age, and the IRS recognizes that reality. The medical expense deduction allows taxpayers to deduct qualified unreimbursed medical expenses that exceed 7.5% of adjusted gross income. That threshold applies to everyone, including couples over 65. Once total eligible expenses cross that 7.5% line, every additional qualified dollar becomes deductible if the couple itemizes.

This deduction covers far more than doctor visits and hospital bills. It includes Medicare Part B and Part D premiums, Medicare Advantage plan premiums, and long-term care insurance premiums up to age-based limits set by the IRS. It also includes out-of-pocket costs for prescriptions, dental treatment, vision care, hearing aids, medical equipment, and even mileage driven for medical appointments at the IRS medical mileage rate.

Couples over 65 often rack up thousands of dollars in these expenses without realizing they might qualify for a deduction. Many assume that Medicare handles most of the bill, yet premiums, copays, and supplemental coverage add up quickly. When those expenses cross that 7.5% threshold, the tax savings can become substantial.

Why So Many Couples Miss It

The medical expense deduction requires itemizing instead of taking the standard deduction. That single requirement stops many couples in their tracks. The standard deduction for taxpayers 65 and older increases beyond the base amount, which makes it even more attractive and easier to choose. Couples look at the larger standard deduction and assume itemizing will not benefit them.

However, retirement often shifts the math. Mortgage interest may shrink or disappear, and state tax deductions might decrease, but medical expenses often climb. In years with major procedures, new hearing aids, dental implants, or increased long-term care costs, itemized deductions can suddenly exceed the standard deduction.

Some couples also misunderstand what qualifies. They overlook transportation costs for medical care. They forget to include insurance premiums deducted from Social Security benefits. They fail to track small but steady expenses like monthly prescription copays. Those seemingly minor amounts accumulate into meaningful totals over twelve months.

The Social Security Connection Most People Ignore

Social Security benefits complicate the picture in ways that confuse even financially savvy retirees. Depending on total income, up to 85% of Social Security benefits can count as taxable income. When adjusted gross income climbs because of required minimum distributions from retirement accounts, capital gains, or part-time work, taxable Social Security income can rise as well.

Here is where strategy matters. Higher adjusted gross income raises the 7.5% medical deduction threshold. That reality means income planning and medical deduction planning must work together. Couples who carefully manage withdrawals from traditional IRAs and 401(k)s can sometimes keep adjusted gross income lower, which lowers the medical expense threshold and increases the portion of expenses that qualify for deduction.

This coordination does not require aggressive tactics. It simply requires awareness. Timing withdrawals, spreading income across years, and understanding how retirement income sources interact can make a noticeable difference. A tax professional or financial planner who understands retirement distribution strategies can help align those pieces.

Long-Term Care Premiums: The Overlooked Heavyweight

Long-term care insurance premiums deserve special attention. The IRS allows deductions for qualified long-term care premiums, but it caps the deductible amount based on age. For individuals over 70, the maximum deductible premium increases significantly compared to younger taxpayers. For couples where both spouses carry policies, the combined deductible amount can become substantial.

These premiums often run into thousands of dollars per year. When combined with Medicare premiums and other medical expenses, they frequently push total medical costs above the 7.5% threshold. Yet many couples forget to include them or assume they do not qualify.

The IRS sets clear limits each year for age-based premium deductions, so couples should review the current limits before filing. Keeping annual statements from insurance providers simplifies the process. A single overlooked form can mean leaving a sizable deduction on the table.

Assisted Living and Home Care Costs Can Qualify

The rules surrounding assisted living and in-home care surprise many retirees. If a person requires assistance with activities of daily living such as bathing, dressing, or eating, and a licensed healthcare provider certifies that need, many of those costs can qualify as medical expenses. In some cases, a significant portion of assisted living facility fees qualifies as deductible medical expenses, not just direct nursing services.

Home health aides, nursing services at home, and certain modifications to a home for medical reasons can also qualify. Installing ramps, widening doorways, or modifying bathrooms for accessibility may count as medical expenses to the extent they do not increase the home’s value. That nuance matters, and documentation becomes critical.

Families often focus on covering the immediate costs of care without considering the tax implications. When annual care expenses reach tens of thousands of dollars, the deduction can become one of the most powerful tools available.

The Little-Known Deduction Couples Over 65 Often Miss
Image Source: Unsplash.com

Organization Beats Guesswork Every Time

Claiming the medical expense deduction requires detailed recordkeeping. Couples must track receipts, insurance statements, mileage logs, and premium notices. Waiting until tax season to reconstruct a year’s worth of expenses almost guarantees missed deductions.

A simple system can solve that problem. A dedicated folder, digital spreadsheet, or budgeting app can track expenses monthly. Recording mileage to medical appointments as they occur prevents undercounting. Saving annual Social Security benefit statements ensures accurate reporting of Medicare premium deductions.

Couples should also compare the total of itemized deductions to the standard deduction before filing. Tax software often performs that comparison automatically, but reviewing the numbers personally encourages smarter planning for the following year. If itemizing produces a higher deduction in one year because of major medical expenses, it may not do so every year. Each tax year stands alone.

Timing Can Make or Break the Benefit

Strategic timing can amplify the value of this deduction. If significant medical procedures or elective treatments can occur in the same calendar year, bunching those expenses may push total costs above the 7.5% threshold. Spreading them across two years might prevent reaching the threshold in either year.

This approach does not mean delaying necessary care. Health decisions should always come first. However, when flexibility exists, timing can influence tax results. The same concept applies to paying medical bills before year-end if possible, since the deduction applies to expenses paid during the tax year, not simply incurred.

Couples who anticipate high medical costs should review their projected adjusted gross income early in the year. That foresight allows better decisions about retirement account withdrawals and expense timing.

The Real Win: Awareness and Action

The medical expense deduction does not grab headlines, and it does not offer flashy credits or dramatic loopholes. It simply rewards careful attention to costs that many retirees already face. For couples over 65, those costs often exceed expectations, and the tax code offers a way to soften the impact.

The key lies in awareness, documentation, and coordination with overall retirement income planning. Ignoring the deduction means accepting a higher tax bill than necessary. Embracing it means taking control of a complex system and making it work more efficiently.

Retirement already demands thoughtful financial management. Taxes remain part of that picture, even without a traditional paycheck. Couples who review their medical expenses annually, understand the 7.5% threshold, and evaluate whether itemizing makes sense position themselves to keep more of their money.

The Deduction That Rewards Paying Attention

Smart tax planning in retirement does not require exotic strategies or complicated maneuvers. It requires curiosity, consistency, and a willingness to look beyond the standard deduction. The medical expense deduction stands as one of the most overlooked yet potentially valuable opportunities for couples over 65.

Those who track their expenses, understand eligibility rules, and coordinate income decisions can transform unavoidable healthcare costs into meaningful tax savings. That shift turns frustration over rising medical bills into a measure of financial control.

What medical expenses might already sit in a folder or bank statement, quietly waiting to reduce next year’s tax bill? If you have some tax tips to share, you should do so below.

You May Also Like…

Can You Trust AI With Your Taxes and Investments? 8 Risks No One Explains

5 Reasons To Talk To Your Kids About Taxes

5 Years Without Filing: 8 Hidden Consequences That Make People Avoid the IRS

IRS 1099-K Rules in 2026: Who Must Report Payments This Year

What Happens When Small Business Owners Skip Taxes

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: tax tips Tagged With: IRS deductions, itemized deductions, medical expense deduction, Medicare costs, over 65 deductions, retirement income strategy, retirement taxes, senior financial planning, senior tax tips, Social Security and taxes, tax planning for retirees

  • « Previous Page
  • 1
  • …
  • 114
  • 115
  • 116
  • 117
  • 118
  • …
  • 157
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba
  • How Can I Get Rid of Wells Fargo PMI on My Home Loan? by Tamila McDonald
  • Is It Safe to Throw Away Bank Statements? by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework