• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Money

9 Expenses That Feel Manageable Until One Changes

January 25, 2026 by Brandon Marcus Leave a Comment

These Are 9 Expenses That Feel Manageable Until One Changes
Image source: shutterstock.com

You’re cruising along, bills paid, coffee in hand, feeling like you’ve finally cracked the code of adulthood. The numbers line up, the math works, and nothing feels out of control. Then one small shift happens—a rate bumps up, a habit evolves, or life throws in a new variable—and suddenly that “totally fine” expense demands a second look.

These aren’t dramatic financial disasters; they’re the subtle changes that turn comfort into tension. Let’s talk about the everyday costs that behave nicely until one thing changes and reminds you who’s really in charge.

1. Rent Or Mortgage Payments

Housing costs often feel stable because they’re predictable month to month. You sign a lease or lock in a mortgage and build your budget around that number. The problem appears when a lease renewal brings a higher rate or property taxes push a mortgage payment upward. Even a modest increase can ripple through the rest of your finances because housing already takes a large slice of income.

Add in rising insurance premiums or unexpected maintenance, and that once-manageable payment suddenly demands sacrifices elsewhere. Housing doesn’t need to double to cause stress; it just needs to inch upward at the wrong time.

2. Car Ownership Costs

A car payment alone can seem perfectly reasonable, especially when the vehicle feels reliable. Then gas prices rise, insurance renews at a higher rate, or repairs start appearing more often. Maintenance costs tend to cluster, which makes a dependable car feel suspiciously expensive all at once.

A longer commute or a job change can quietly increase fuel and wear costs. Registration fees and taxes add another layer that’s easy to forget until they’re due. Cars are manageable until usage or upkeep changes, and then they demand attention fast.

3. Childcare Expenses

Childcare is often budgeted carefully because it’s expected and essential. It works until a schedule change requires more hours or a provider raises rates. As children grow, their needs change, sometimes requiring different care arrangements that cost more.

Summer programs, after-school care, and holiday coverage add layers that weren’t always there. Even small increases add up quickly because childcare is already a major expense. Families often find that one shift in routine can reshape the entire monthly budget.

4. Health Insurance And Medical Costs

Monthly premiums can feel manageable when they’re predictable and benefits are familiar. Trouble starts when a job change alters coverage or deductibles reset for the year. A single unexpected medical issue can turn a quiet line item into a dominant expense. Prescription changes or specialist visits add costs that weren’t part of the original plan. Even routine care can become expensive when coverage rules change. Healthcare costs rarely explode all at once; they grow louder with each adjustment.

5. Utilities And Energy Bills

Utilities often fade into the background because they’re relatively steady. Seasonal shifts, however, can dramatically change heating or cooling costs. Energy rate increases can arrive quietly and stay for good. A larger household, remote work, or aging appliances can push usage higher without much notice.

Weather extremes make those changes impossible to ignore. Utilities are manageable until consumption or pricing changes, and then they demand respect.

6. Groceries And Household Supplies

Food budgets feel flexible because shopping habits feel familiar. Prices rise gradually, making it hard to pinpoint when things got more expensive. Dietary changes, growing families, or hosting more often can nudge spending upward.

Convenience items and prepared foods quietly cost more over time. Even switching stores or brands can impact totals. Groceries rarely shock you in one trip; they wear you down over dozens of receipts.
These Are 9 Expenses That Feel Manageable Until One Changes
Image source: shutterstock.com

7. Subscriptions And Memberships

Subscriptions are famous for feeling harmless. A few dollars here and there don’t seem worth worrying about. Then prices increase, free trials end, or services add tiers you didn’t plan on.

The number of subscriptions can grow while their value stays the same. Annual renewals can hit all at once, creating a sudden cash crunch. Subscriptions are manageable until they multiply or change terms without asking.

8. Student Loan Payments

Student loans often come with structured repayment plans that feel predictable. That sense of control shifts when interest accrues faster or repayment pauses end. Income changes can make once-comfortable payments feel heavy. Consolidation or refinancing can alter timelines and totals in unexpected ways.

Even small interest rate differences matter over long periods. Student loans behave until one variable changes, and then they remind you they’re in it for the long haul.

9. Pet Care And Veterinary Costs

Pets usually fit neatly into a budget with food and routine care. The challenge appears when health issues arise or pets age. Veterinary costs can escalate quickly and aren’t always optional. Specialized food, medications, and emergency visits add layers of expense. Even grooming and boarding costs can increase with changing needs. Pet expenses feel manageable until one unexpected visit rewrites the budget.

When Small Changes Make A Big Difference

Most budgets don’t collapse because of reckless spending. They wobble when familiar expenses quietly change their rules. Recognizing which costs are sensitive to change helps you prepare before stress sets in. Awareness creates flexibility, and flexibility keeps finances feeling human.

If any of these expenses have caught you off guard, your experience could resonate with others reading along. Drop your thoughts or stories in the comments section below and keep the conversation going.

You May Also Like…

Why Do Fixed Expenses Feel Anything But Fixed

The Texas Mortgage Shock: Why Your Monthly Payment Just Jumped $400 Without Warning

Why Does Spending Turn A Dream Vacation Into A Nightmare?

Debt Alert: 6 Ways Holiday Spending Could Trigger a January Credit Score Crisis

Why Do Unexpected Expenses Always Seem to Hit at the Worst Time

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Smart Spending Tagged With: buying a card, car ownership, childcare, childcare costs, energy bills, expenses, fixed expenses, groceries, grocery prices, Money, money habits, mortgage, mortgage payments, overspending, Paying Rent, Rent, Smart Spending, spending, utilities, utility bills

5 Money Habits That Keep You Stuck In Place

January 25, 2026 by Brandon Marcus Leave a Comment

These Are 5 Money Habits That Keep You Stuck In Place
Image source: shutterstock.com

Money—it’s supposed to make life easier, right? Yet somehow, it often feels like we’re running on a treadmill, moving our feet frantically but never getting anywhere. You might be paying your bills on time, saving a little, and thinking you’re doing everything “right,” but subtle habits can quietly anchor you to the same financial spot year after year.

These aren’t catastrophic mistakes that ruin your life overnight—they’re the small, persistent behaviors that quietly drain your momentum.

1. Ignoring The Power Of Budgeting

Budgeting has a bad reputation, as if it’s all about restriction and misery, but that couldn’t be further from the truth. Ignoring a budget is like trying to navigate a city without a map—you’ll eventually get somewhere, but it might be the wrong somewhere, and it will cost you extra time, stress, and money. People often assume that tracking spending is tedious, but the act of actually knowing where your money goes is empowering.

Even a simple system that categorizes bills, essentials, and discretionary spending can reveal patterns that you never noticed before. Skipping this step can lead to recurring “mystery” expenses that drain your bank account silently. Budgeting isn’t a punishment; it’s a way to take control and give yourself room to grow financially without feeling trapped.

2. Living Paycheck To Paycheck

It’s easy to fall into the paycheck-to-paycheck trap, especially when life seems to demand more than your income provides. Relying entirely on the timing of your next paycheck creates constant stress and makes it nearly impossible to invest in bigger financial goals. People often prioritize immediate gratification, thinking, “I’ll start saving next month,” while the months slip by unnoticed.

Without a safety net, even a small unexpected expense—a car repair, a medical bill, or a sudden trip—can set you back weeks or months. Building an emergency fund, even if it’s modest at first, can break this cycle and create a sense of security. Once the anxiety of “what if?” fades, you can start thinking about opportunities instead of obstacles.

3. Avoiding Investments Out Of Fear

There’s a common myth that investing is only for the wealthy or that it’s too risky to bother with at all. Avoiding investments altogether keeps your money stagnant, working for no one but the institutions holding it. Inflation silently erodes cash over time, so hoarding money under your mattress or in a low-interest account is basically giving it away. People often wait for “the perfect time” to invest, but markets reward consistent action over timing perfection. Even small, steady investments in retirement accounts or index funds can grow exponentially thanks to compound interest. The key is learning enough to act confidently, rather than letting fear dictate your financial future.

4. Overspending On Things That Don’t Matter

It’s easy to justify little purchases—those daily lattes, online impulse buys, or trendy gadgets—because they feel small individually. But small, frequent expenses add up quickly and can silently sabotage your long-term goals. When money goes out the door for things that don’t provide real value, you’re trading your future for fleeting satisfaction.

Overspending often feeds emotional urges, stress relief, or social comparison rather than real needs, keeping you trapped in a cycle of temporary happiness followed by financial frustration. Tracking where your money disappears each month can reveal habits you didn’t even realize existed. Redirecting just a fraction of these expenses into meaningful investments or savings can snowball into serious financial progress.

These Are 5 Money Habits That Keep You Stuck In Place
Image source: shutterstock.com

5. Neglecting Financial Education

Money literacy isn’t innate; it’s a skill you develop, and neglecting it can stunt your financial growth more than any single purchase or debt. People often assume they “know enough” or that learning about personal finance is boring or complicated. This mindset keeps you dependent on others’ advice or reactive decision-making, rather than proactive strategy. Understanding interest rates, debt management, investing options, and even basic tax implications can transform how you handle money. Education doesn’t need to be overwhelming—a few reliable resources or even a weekly deep dive into one topic can make a huge difference. The more you know, the more confident you become, and the more opportunities you can seize instead of letting life’s financial currents carry you along.

Take Charge And Grow

Breaking free from these habits isn’t about dramatic, overnight change—it’s about consistent awareness and small, intentional steps. Start by picking one habit that resonates most with your situation and commit to making a tiny adjustment. Over time, these changes compound and open doors you didn’t even know were there. Your financial life doesn’t have to feel like a loop you can’t escape.

If any of these habits hit close to home, or if you’ve already tackled one successfully, drop your thoughts and experiences in the comments below. Let’s get a conversation going about what works, what doesn’t, and how to move forward with confidence.

You May Also Like…

9 Financial Habits That Look Responsible but Feel Stressful

8 Grocery Shopping Habits That Make You Spend More Without Realizing It

8 Financial Habits That Quietly Drain Your Checking Account

6 Bad Money Habits Families Show During The Holidays

Behavior Habit: 5 Daily Money Moves That Build Long-Term Wealth

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Finance Tagged With: bad money habits, daily habits, finance, finances, general finance, investments, living paycheck to paycheck, Money, money habits, money issues, overspending, paycheck to paycheck, Smart Spending, spending, stuck in place

7 Financial Choices That Seem Safe Until They Aren’t

January 24, 2026 by Brandon Marcus Leave a Comment

7 Financial Choices That Seem Safe Until They Aren’t
Image source: shutterstock.com

Money mistakes aren’t always the dramatic kind that make headlines. Sometimes, they lurk in plain sight, dressed in the reassuring clothes of “safe decisions.” You think you’re doing everything right—saving diligently, investing carefully, avoiding debt—but a few seemingly innocent choices can actually sabotage your finances without you noticing.

Imagine getting a little shock years down the line because a decision you trusted turns out to have hidden pitfalls. That’s the territory we’re entering today. Let’s pull back the curtain on seven financial moves that might feel harmless or even smart, but are actually ticking time bombs for your wallet.

1. Keeping Cash Under Your Mattress Or In A Checking Account

It sounds crazy, but some people genuinely feel safer holding on to physical cash or keeping all their money in a standard checking account. The problem is, inflation is quietly eroding the purchasing power of that cash every single year. What looked like $10,000 last year might not buy nearly as much today, and that gap widens over time.

Checking accounts also usually pay near-zero interest, meaning your money isn’t working for you at all. There’s no compounding growth, no opportunity to harness investments, and your funds are essentially stagnating. Sure, it’s “safe” from the stock market’s ups and downs, but that safety is deceptive because it doesn’t protect against the invisible thief of inflation. Meanwhile, investing even a portion wisely could have you building real long-term wealth instead of just watching numbers sit still.

2. Relying Only On Employer Retirement Plans

Many people lean heavily on their 401(k) or pension plan and assume that’s enough. Employer plans are great, but they aren’t one-size-fits-all, and they often lack the flexibility needed for changing circumstances. Contribution limits, investment options, and fees can all quietly chip away at your growth potential. Some employees even overestimate how much they’ll need at retirement because they assume their employer will fully cover future inflation or healthcare costs.

If you ignore outside opportunities like IRAs, Roth accounts, or other investment vehicles, you could be leaving significant money on the table. Diversifying your retirement strategy can provide a much safer cushion against market fluctuations and unexpected life events. In short, assuming your employer’s plan is a silver bullet is a surprisingly risky choice.

3. Paying Only The Minimum On Credit Cards

The minimum payment trick seems like a stress-free solution. You only pay what’s required, your account stays current, and you avoid late fees. Sounds safe, right? The reality is far less comforting. High-interest rates compound quickly, and what seems like a manageable balance can balloon into a long-term debt trap. Years can pass, and you might still owe more than you initially borrowed, even while faithfully making those minimum payments.

This slow-motion financial drain is one of the sneakiest forms of “safe” behavior because it looks responsible on the surface. Paying a bit more than the minimum each month can save you tens of thousands in interest over time, creating freedom and peace of mind.

7 Financial Choices That Seem Safe Until They Aren’t
Image source: shutterstock.com

4. Buying “Too Safe” Investments

Certificates of deposit, government bonds, and ultra-conservative mutual funds are often praised as safe bets. While low-risk assets protect your principal, they can also fail to keep up with inflation. Your money might technically be safe, but if it doesn’t grow, your future purchasing power shrinks. Investors sometimes focus so much on avoiding risk that they miss opportunities for modest growth that outpaces inflation.

This is especially important for younger investors who have decades to recover from market dips. The key is balance: a mix of secure and growth-oriented investments can provide both safety and real progress toward financial goals.

5. Co-Signing Loans For Friends Or Family

Helping someone out financially feels noble, but co-signing a loan is one of those decisions that can backfire spectacularly. If the primary borrower misses a payment or defaults, you are legally responsible for the debt. This can impact your credit score, limit your ability to get loans, and even lead to collections actions against you. It’s tempting to trust loved ones, but emotions don’t cancel out financial responsibility.

Understanding the potential consequences fully before putting your signature on the dotted line is critical. Sometimes saying no is actually the safest and kindest choice—for both parties.

6. Ignoring Insurance Or Having The Wrong Coverage

Insurance is boring until you need it. Many people skip coverage thinking it’s an unnecessary expense, or they pick the cheapest plan and assume it’s adequate. The truth is, underinsurance or no insurance can devastate your finances in an instant. Medical emergencies, natural disasters, or liability claims can wipe out savings faster than you can react.

Comprehensive coverage might cost a little more upfront but can save you from catastrophic losses down the line. Regularly reviewing and updating your policies ensures your safety net is both current and sufficient.

7. Overestimating Passive Income Streams

The promise of passive income is seductive—earn money while you sleep, they say—but it’s rarely as simple as it sounds. Rental properties, online businesses, or dividend stocks all require ongoing attention and carry risks that aren’t immediately obvious. Market shifts, tenant vacancies, or regulatory changes can quickly erode the expected income.

People often treat passive income as guaranteed when in reality it’s more like semi-passive; it demands effort, monitoring, and sometimes unexpected financial input. Overreliance on assumed income streams can leave you exposed when reality doesn’t match expectations.

What Decisions Will You Make?

Financial decisions that seem safe can sometimes be the riskiest ones of all. Awareness, research, and a willingness to adapt are your best tools for avoiding long-term pitfalls.

What financial choices have you made that turned out differently than you expected? Or have you spotted “safe” moves that really weren’t?

You May Also Like…

10 Personal Finance Lessons People Learn the Hard Way

What Are The Worst Choices You Can Make As A New Investor?

8 Poor Choices People Make When They Make Too Much Money

How a Solid Estate Plan Can Protect Your Finances

Tired Of Being Single? Avoid These 5 Career Choices


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Finance Tagged With: cash, finance, financial choices, financial decisions, Insurance, insurance premiums, investing, investments, Money, money issues, overspending, Passive income, passive income stream, Retirement, retirement accounts, retirement planning, safe financial choices, safe investments, safe spending, spending

10 Budget Mistakes That Create Long-Term Pressure

January 24, 2026 by Brandon Marcus Leave a Comment

These Are 10 Budget Mistakes That Create Long-Term Pressure
Image source: shutterstock.com

Ever feel like your money disappears faster than ice cream on a hot day? You’re not alone. Most of us start budgeting with enthusiasm, then hit roadblocks that turn simple planning into stress-inducing chaos. Some of these pitfalls are obvious—buying expensive coffee every morning, impulsively splurging online—but others quietly accumulate, creating tension that sticks around for years.

The tricky part is that these mistakes don’t scream “problem!” right away. They sneak in slowly, reshaping your finances in ways you might not notice until you’re elbow-deep in bills or wondering where all your savings went. Understanding these traps is like spotting the cracks in your foundation before the entire house wobbles.

1. Ignoring Irregular Expenses

One of the most underestimated financial blunders is ignoring irregular expenses. These are costs that don’t appear on your monthly statement like clockwork, such as car maintenance, medical bills, or annual subscriptions. Failing to account for them can leave you scrambling when they pop up, forcing you to borrow or dip into your emergency fund. Creating a realistic budget means anticipating the unexpected and smoothing out the bumps over the year.

Even small amounts set aside consistently add up, reducing stress when irregular expenses inevitably arrive. Treating your budget like a static, unchanging plan is a recipe for constant catch-up, and that kind of pressure is exactly what long-term financial strain looks like.

2. Underestimating Debt Payments

Debt is a pressure cooker. Ignoring interest rates or underestimating minimum payments might feel harmless in the moment, but interest compounds faster than most people realize. Student loans, credit cards, and personal loans all have a habit of quietly inflating your monthly obligations if you’re not proactive. Not factoring these correctly into your budget can create a domino effect, where payments eat into savings and essentials.

The smart approach is to track every debt, understand the interest, and prioritize repayment strategically. This isn’t about living without enjoyment—it’s about preventing a small fire from growing into a full-blown financial inferno.

3. Skipping an Emergency Fund

Many budgeters dive into financial planning and completely skip one critical element: an emergency fund. Life throws curveballs—broken appliances, unexpected travel, or sudden medical expenses—and without a cushion, your budget crumbles instantly. Relying on credit cards or payday loans in emergencies only makes pressure compound over time.

A good rule of thumb is having three to six months’ worth of essential expenses saved. Think of it as the invisible shield that absorbs life’s blows. Even if your income fluctuates, a small emergency stash can transform panic into manageable inconvenience.

4. Neglecting Small Recurring Charges

Subscriptions are tiny, tempting, and oh-so-easy to forget. That yoga app, streaming service, or magazine subscription may seem insignificant individually, but they quietly drain your budget month after month. Ignoring these charges can derail your financial planning without any dramatic event to signal trouble.

Tracking every recurring expense—even the ones under ten dollars—gives you clarity and control. Cancel what you don’t use and adjust your budget to reflect the ones you genuinely value. This level of awareness prevents months of subtle budget erosion from turning into a serious problem later.

5. Overestimating Income

Optimism about your income can sabotage your budget faster than overspending ever could. Many people assume every paycheck will be perfect and consistent, then encounter unexpected tax changes, reduced hours, or delayed payments. Budgeting as if you earn more than you actually do creates stress when reality doesn’t match expectations.

Being conservative with your projected income forces your budget to reflect what you truly have to work with. It also creates a cushion for months that are less than ideal, preventing a pattern of shortfalls and anxiety.

6. Ignoring Inflation and Cost Increases

Budgets often feel set in stone, but inflation is the silent creep that eats your purchasing power over time. Ignoring rising costs on groceries, utilities, rent, or transportation may seem harmless in the short term, but it slowly transforms a balanced budget into a strained one. Regularly reviewing your spending and adjusting for inflation keeps your financial plan realistic. The goal isn’t panic—it’s preparation. Even a small monthly adjustment can prevent the slow, frustrating squeeze that turns a reasonable budget into a pressure-filled nightmare.

7. Not Tracking Spending

It sounds basic, but not tracking where your money goes is a massive mistake. You can create a detailed budget, but if you don’t monitor actual spending, you have no idea whether your plan is effective. Overspending in one category might require painful cutbacks elsewhere, building tension and anxiety over time.

Tracking expenses, whether through apps or manual logs, provides a reality check. It shows patterns, highlights problem areas, and creates accountability. Knowledge is power, and in this case, it’s the difference between financial calm and chronic stress.

These Are 10 Budget Mistakes That Create Long-Term Pressure
Image source: shutterstock.com

8. Living Beyond Your Means

Trying to maintain a lifestyle that exceeds your income is a guaranteed source of long-term pressure. It’s not just about the occasional treat or luxury—it’s about consistent overspending to keep up appearances. Credit cards and loans make this tempting, but they only postpone the inevitable strain. Long-term stress comes from the constant cycle of repayment, interest accrual, and guilt. Living within your means is empowering: it reduces anxiety, frees up funds for genuine priorities, and makes financial goals achievable rather than mythical.

9. Setting Unrealistic Goals

Ambition is great, but setting unattainable financial goals is a subtle form of self-sabotage. Trying to save half your paycheck in a month or pay off a huge debt without a plan leads to disappointment, frustration, and pressure that builds quietly.

Realistic, incremental targets create momentum rather than panic. Break goals into manageable steps, celebrate small wins, and adjust as circumstances evolve. Sustainable progress keeps stress in check while still pushing you forward.

10. Failing To Reevaluate Regularly

A budget isn’t a one-and-done project—it’s a living, evolving plan. Life changes, priorities shift, and unexpected expenses crop up. Failing to reassess your budget periodically can transform a healthy system into a pressure cooker. Review your finances monthly, adjust for changes, and be honest about what’s working and what isn’t. Flexibility prevents long-term pressure by addressing problems before they spiral. Think of it as giving your finances a tune-up, ensuring smooth operation for years to come.

Avoid Long-Term Pressure By Learning From Mistakes

Budgeting isn’t about perfection—it’s about creating a structure that reduces stress and gives you control over your financial life. The mistakes above are common because they’re easy to overlook, but they have long-term consequences if ignored. Recognizing them, planning for them, and actively correcting them can turn financial tension into clarity and freedom.

Your experience matters—what budget mistakes have crept up on you, and how have you handled them? Drop your thoughts, insights, or financial stories in the comments section below and let’s keep this conversation going.

You May Also Like…

Why Are Utility Bills Becoming a Bigger Budget Problem

Why Does Budgeting Feel More Emotional Than Logical

Legacy Design: 5 Ways to Pass on Wealth Without Passing on Pressure

8 Tips for Talking With Your Partner About Health, Finances & Legacy

Why Do So Many People Believe Budgeting Apps Solve Everything


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Budgeting Tagged With: Budget, budget mistakes, budget tips, budgeting, Debt, debt payments, emergency funds, Income, income streams, Inflation, living beyond your means, Money, money issues, money mistakes, overspending, recurring charges, spending, spending mistakes, splurging, tracking spending

6 Healthy Budget Tips To Keep Your Financially Healthy Until Payday

January 24, 2026 by Brandon Marcus Leave a Comment

These Are 6 Healthy Budget Tips To Keep Your Financially Healthy Until Payday
Image source: shutterstock.com

Ever feel like your paycheck evaporates the moment it hits your account? One minute you’re feeling like a financial superhero, and the next you’re staring at your bank app wondering where it all went. Managing money doesn’t have to feel like juggling flaming torches while walking a tightrope, though. With a few smart strategies, some foresight, and a little self-discipline, you can glide through the days leading up to payday without stressing about every purchase.

The trick isn’t about depriving yourself—it’s about controlling the chaos, making informed choices, and maybe even sneaking in a little fun along the way. If you’ve ever wished your money would just cooperate, these six healthy budget tips will help you take the reins and keep your financial health intact.

1. Track Every Dollar Like A Detective

If you don’t know where your money is going, it’s impossible to make smart choices. Start by tracking every single dollar, whether it’s a latte, a streaming subscription, or the mysterious $7 that always disappears from your account. There are apps that do this automatically, but even a notebook works if you prefer old-school methods. The key is consistency—logging your spending daily paints a clear picture of patterns you might not notice otherwise. You might realize you’re spending half your budget on tiny treats that don’t even bring real joy.

Once you know exactly where your money goes, you can pinpoint places to cut back and adjust without feeling deprived. Think of it as shining a flashlight in a dark room—you’ll finally see all the corners where money tends to vanish.

2. Prioritize Needs Over Wants Without Feeling Restricted

It’s tempting to grab that impulse buy because it looks fun or convenient, but distinguishing between needs and wants can make a huge difference. Needs cover essentials like rent, groceries, bills, and basic transportation, while wants are extras that don’t serve your immediate survival. When payday is still days away, focus your cash on covering needs first, then decide if any wants truly fit within your budget.

This doesn’t mean saying goodbye to treats forever—it just means timing them smartly. By keeping wants optional, you gain a sense of control and avoid that creeping guilt of overspending. Planning in advance also allows for small indulgences without blowing your entire budget.

3. Create A Mini Emergency Stash

Even a tiny emergency fund can be a lifesaver when the unexpected hits. It doesn’t have to be huge; even $50 set aside each month creates a cushion for surprises like a car repair or an unplanned dinner out. Having this buffer prevents you from resorting to credit cards or high-interest loans, which can trap you in a cycle of stress. Keep this money separate from your main account so you don’t accidentally dip into it for everyday expenses. Watching your emergency stash grow is also oddly satisfying—it’s a small win that reinforces good financial habits. Over time, it builds confidence, making payday feel less like a lifeline and more like routine maintenance for your finances.

4. Meal Plan And Cut Unnecessary Food Costs

Food spending is one of the easiest areas to lose track of, but a little planning goes a long way. Make a meal plan for the week and stick to a shopping list to prevent those impulsive purchases at the store. Cooking at home not only saves money but can also be healthier, giving you energy to tackle the week ahead. Batch cooking and freezing meals means fewer last-minute takeout temptations, which tend to be expensive and less nutritious.

Even small steps, like brewing your own coffee instead of buying it daily, add up quickly. The combination of planning and intentional purchases allows you to stretch your paycheck while still enjoying good food.

These Are 6 Healthy Budget Tips To Keep Your Financially Healthy Until Payday
Image source: shutterstock.com

5. Set Spending Limits And Stick To Them

Without limits, spending can quickly spiral out of control. Decide how much you’re comfortable spending in different categories—groceries, entertainment, transportation, and extras—and be strict with yourself. One trick is using envelopes or separate accounts for each category to prevent overspending. Digital alerts can also help keep you accountable, notifying you when you’re getting close to your limit. Treat limits as a challenge rather than a restriction, turning budgeting into a game you can win. By respecting your boundaries, you maintain stability and reduce financial anxiety, which is surprisingly freeing.

6. Automate Savings To Avoid Temptation

Saving isn’t just for the future—it’s a daily defense against financial stress. Automating even small amounts ensures money goes into savings before you have the chance to spend it. Think of it as paying yourself first rather than hoping you’ll have leftovers at the end of the month.

Automatic savings grow without you thinking about it, providing security and peace of mind. Even $5 or $10 a week builds momentum, and as your confidence grows, you can gradually increase contributions. By setting up a system that works for you, you take control without having to constantly monitor every cent.

Keep The Financial Conversation Going

Managing your money until payday doesn’t have to be stressful or boring. With strategies like tracking spending, prioritizing essentials, building small emergency funds, planning meals, setting limits, and automating savings, you can maintain financial health and even enjoy the process. These methods turn reactive habits into proactive choices, giving you more control and less anxiety.

Have you tried any of these tips before, or do you have unique methods that help you stretch your budget? Tell us your experiences or insights in the comments below.

You May Also Like…

Why Are Utility Bills Becoming a Bigger Budget Problem

10 Common Budgeting Mistakes That Create Constant Money Stress

10 Budget Adjustments People Make Without Talking About Them

New Year, New Credit Score: Tips to Improve Your Financial Health

7 Ways Financial Stress Physically Damages Your Health

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: budget tips Tagged With: Budget, budget tips, budgeting, Budgeting Tips, emergency funds, financial choices, financial decisions, Financial Health, financial needs, Money, money choices, money issues, overspending, paycheck to paycheck, payday, Smart Spending, spending, spending limits, tracking every dollar, tracking spending

Why Does Spending Feel Riskier Than It Used To

January 24, 2026 by Brandon Marcus Leave a Comment

Why Does Spending Feel Riskier Than It Used To
Image source: shutterstock.com

Remember the last time you bought something without a second thought? That impulsive click on an online cart or grabbing a snack on your way home now comes with a twinge of hesitation. Suddenly, every purchase feels like a decision worthy of an intense boardroom meeting. It’s not your imagination—spending really does feel riskier than it used to. The reasons are part psychological, part economic, and entirely fascinating.

From rising costs to the influence of digital shopping, the landscape of spending has shifted in ways that make even the simplest purchase feel loaded with uncertainty. But what exactly is behind this newfound financial anxiety?

Inflation And Economic Shifts Have Changed Our Perspective

One of the biggest culprits behind this feeling is inflation. Prices creep up, sometimes subtly, other times glaringly, and our brains notice more than we realize. A cup of coffee that cost $2 five years ago now rings in at $4, and suddenly the act of paying feels like a gamble. It’s not just about dollars and cents; it’s about the psychology of value. When our money buys less, every decision carries more weight. Even small purchases start to feel like they could tip the balance of a weekly budget.

Economic uncertainty compounds the effect. Job markets fluctuate, investments rise and fall, and global events impact local costs in unpredictable ways. Our brains are wired to seek stability, and when our financial environment feels shaky, even routine spending can trigger a heightened sense of risk.

Digital Spending And Instant Awareness Amplify Anxiety

Online shopping has transformed how we interact with money, but not always in comforting ways. When your bank balance is just a tap away on your phone, each purchase feels immediate and irreversible. This constant visibility can make spending feel riskier because you’re reminded of the cost before, during, and after the transaction.

Even contactless payments amplify this effect. Swipe, tap, or scan, and the transaction is instant—but so is the mental accounting. Without the tangible sensation of handing over cash, our brains struggle to register spending in a satisfying, completed way.

Why Does Spending Feel Riskier Than It Used To
Image source: shutterstock.com

Psychological Factors Heighten Our Sense Of Risk

Spending anxiety isn’t just about dollars—it’s about human psychology. Loss aversion, the idea that losing feels worse than gaining feels good, plays a huge role. When you spend money, you’re essentially giving up something tangible for something intangible, and our brains register that as a mini-loss. Combine this with uncertainty about future expenses, and suddenly, every decision feels like high-stakes poker.

FOMO, or fear of missing out, can also backfire. We want the latest gadget or trendy product, but in an environment of rising prices and unpredictable finances, the thrill of ownership is often overshadowed by a lingering dread of overspending.

Reflect On Your Spending Experiences

Feeling cautious about spending is completely normal in today’s financial landscape. The combination of inflation, digital payment habits, and deep-seated psychological biases has made each purchase feel more loaded than ever before. Understanding why spending feels risky can help you approach purchases with awareness rather than guilt or anxiety. Take note of the moments when you hesitate and consider what’s driving the feeling—is it a real financial concern or just a psychological quirk?

We’d love to hear your thoughts or experiences with spending in today’s world—what makes you pause before reaching for your wallet?

You May Also Like…

Why Does Spending Turn A Dream Vacation Into A Nightmare?

Why Do People Feel Guilty Spending Money Even on Necessities

8 Grocery Shopping Habits That Make You Spend More Without Realizing It

Why Does Interest Rate Talk Suddenly Affect Everyday Spending

Holiday Trap: 6 Gift-Spending Mistakes That Could Wreck Your Budget

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Spending Habits Tagged With: digital spending, economic challenges, economic problems, Inflation, Money, money habits, money issues, overspending, risky spending, Smart Spending, spend, spending, Spending Habits

Why Are So Many People Rethinking How They Budget

January 23, 2026 by Brandon Marcus Leave a Comment

Why Are So Many People Rethinking How They Budget
Image source: shutterstock.com

Money—it’s thrilling, terrifying, and somehow always at the center of our life choices. But recently, something curious is happening: people are no longer just sitting down with a spreadsheet or an app and dutifully categorizing every coffee and grocery purchase.

Instead, there’s a movement, subtle but undeniable, where individuals are rethinking not only how they spend but why they spend at all. It’s not about cutting every indulgence or living austerely; it’s about taking control in ways that make sense for today’s world, a world that feels less predictable than ever.

If you’ve noticed friends experimenting with new budgeting methods or reconsidering their financial priorities, you’re not imagining it. And the reasons behind this shift are as fascinating as they are practical.

Economic Uncertainty Is Changing Spending Habits

One major reason people are reevaluating their budgets is economic uncertainty. Inflation, fluctuating interest rates, and job market shifts have made yesterday’s strategies feel outdated.

People used to be able to predict monthly expenses with a degree of confidence, but now, expenses that were once minor can suddenly balloon, throwing a traditional budget out of balance. Many are turning to more flexible budgeting approaches that allow them to respond to unexpected costs without panic.

These methods often emphasize adaptability over rigidity, making it easier to balance financial goals with reality. Interestingly, this trend isn’t just about survival; it’s about regaining a sense of control. In an unpredictable economy, knowing where your money is going and having the freedom to adjust can be surprisingly empowering.

Digital Tools Are Making Budgeting Smarter And Simpler

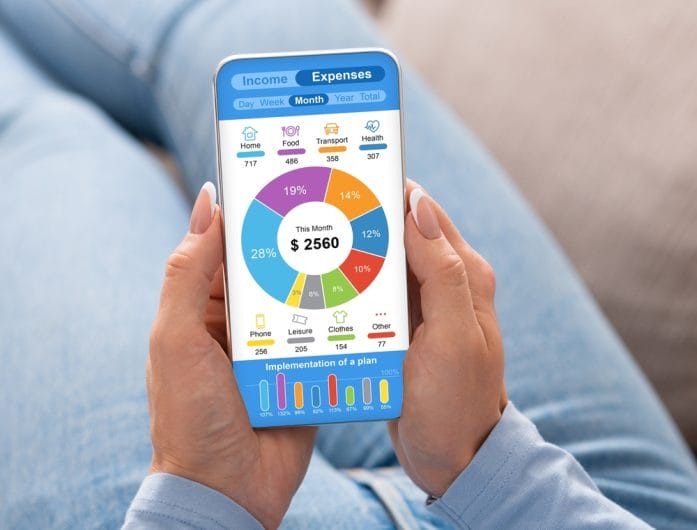
Technology is transforming budgeting in ways most of us could barely imagine a decade ago. Apps now categorize spending automatically, track bills, and even forecast cash flow based on past patterns. Artificial intelligence and machine learning have started helping people identify patterns in their finances, from recurring charges they might have missed to spending habits they weren’t aware of.

This digital assistance makes the process feel less like a chore and more like having a personal finance coach in your pocket. Users can set goals, monitor progress in real-time, and make tweaks instantly rather than waiting until the end of the month.

It’s no wonder more people are exploring these tools—they offer insight and control, packaged in a surprisingly user-friendly interface. Ultimately, technology is not replacing personal responsibility; it’s making that responsibility far easier to manage.

Why Are So Many People Rethinking How They Budget
Image source: shutterstock.com

Mindset Shifts Are Reshaping Financial Priorities

Budgeting today is less about deprivation and more about intentional living. People are increasingly questioning traditional advice like “save first, spend later” or “track every penny,” asking instead what spending choices actually bring value to their lives.

Many are adopting value-based budgeting, where money is allocated according to priorities rather than rigid categories. This could mean spending more on wellness, hobbies, or travel while cutting back on things that feel less meaningful.

Psychology is playing a huge role in this shift, too: people are learning that budgeting works best when it aligns with personal goals and emotional satisfaction. By integrating mental health, lifestyle goals, and financial planning, budgets are becoming tools for fulfillment rather than simply accounting exercises.

Social Influence And Financial Transparency Are Shaping Choices

Another fascinating factor behind the budgeting rethink is the rise of social influence. Platforms where users openly discuss their financial habits—whether successes, failures, or clever hacks—have created a new culture of accountability and inspiration.

People are seeing alternatives to traditional budgeting methods and realizing that there’s no single “right” approach. This transparency helps remove shame from financial mistakes while encouraging experimentation. For instance, someone might learn about envelope budgeting from a friend, try it, and tweak it to fit their unique lifestyle.

Peer examples provide both validation and motivation, which can be far more impactful than generic advice. As a result, budgeting is becoming a shared journey, where lessons learned collectively help everyone refine their strategies.

The Rise Of Irregular Income Is Forcing Creative Approaches

Freelancers, gig workers, and side hustlers are redefining budgeting because their income isn’t predictable. Traditional monthly budgeting doesn’t fit a world where paychecks fluctuate wildly. Instead, people are adopting flexible systems that separate fixed needs from variable wants, ensuring essentials are covered regardless of income swings.

Methods like zero-based budgeting, percentage allocation, or even building substantial emergency funds have become essential for this demographic. These approaches teach not just discipline but also creativity in managing money. Learning to budget around irregular income isn’t just practical—it’s an exercise in resilience and strategic planning that anyone can benefit from.

Financial Education Is More Accessible Than Ever

Finally, access to financial education has exploded, leading many to rethink old habits. Podcasts, online courses, YouTube channels, and community forums make expert advice and real-life examples widely available.

People are no longer limited to advice from family, friends, or traditional financial advisors—they can explore diverse perspectives that challenge assumptions and spark innovation. This democratization of knowledge allows individuals to make informed choices tailored to their circumstances.

Better education encourages experimentation, and when mistakes happen, they’re treated as learning opportunities rather than failures. With this influx of information, the act of budgeting transforms from a mundane task to an engaging process of discovery and improvement.

Rethinking Budgets As A Personal Journey

Rethinking how we budget isn’t just about dollars and cents—it’s about values, priorities, and empowerment. More people are realizing that budgeting can be a flexible, adaptive, and even enjoyable tool to shape life the way they want.

Whether prompted by economic uncertainty, technological innovation, changing mindsets, social influence, irregular income, or accessible financial education, the trend is clear: people want budgets that reflect their lives, not constrain them.

What’s your experience with budgeting? Have you tried a method that changed the way you see your money, or discovered a tip that transformed your approach? Tell your story!

You May Also Like…

Why Are Utility Bills Becoming a Bigger Budget Problem

Why Does Budgeting Feel More Emotional Than Logical

10 Common Budgeting Mistakes That Create Constant Money Stress

Why Do So Many People Believe Budgeting Apps Solve Everything

9 Budget Categories That Blow Up After One Emergency

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Budgeting Tagged With: Budget, budget apps, budget tips, budgeting, budgeting problems, Budgeting Tips, digital tools, economic uncertainty, financial choices, financial priorities, Mindset, mindshift, Money, money issues, money problems, overspending, Smart Spending, spending, Spending Habits

8 Money Habits That Increase Anxiety Without Helping

January 23, 2026 by Brandon Marcus Leave a Comment

These Are 8 Money Habits That Increase Anxiety Without Helping
Image source: shutterstock.com

Some people think money anxiety is just about not having enough. The truth is, the way you handle money can be just as anxiety-inducing as an empty bank account. Imagine staring at your finances, trying to “stay on top of everything,” only to feel your chest tighten, palms sweat, and brain spiral into “what if?” mode.

It turns out, a lot of our financial stress isn’t caused by dollars and cents—it’s caused by habits that make us feel busy, responsible, or cautious, but do very little to actually improve our situation. Let’s break down eight of these surprisingly counterproductive behaviors.

Obsessively Checking Your Bank Account Multiple Times A Day

It seems harmless, even responsible, right? Checking your balance frequently might make you feel like you’re in control, but it can quickly turn into a vicious cycle. Each glance at your bank app can trigger anxiety spikes, especially if you see pending charges or bills you forgot about.

Research shows that repetitive checking can heighten stress and worsen decision-making because your brain becomes overloaded with micro-worries. Instead of clarity, you get tension, racing thoughts, and sometimes even impulsive spending out of frustration.

Your account balance is a snapshot, not a full story, and obsessing over it rarely helps you plan or save. Creating a schedule for reviewing finances—like once a week—can maintain awareness without turning your day into a mini panic fest.

Comparing Yourself To Others Constantly

Scrolling through social media or talking to friends about money can trigger the comparison trap. “They bought a new car, I’m still paying off last year’s credit card,” is a familiar thought pattern for many.

Comparison doesn’t motivate; it triggers anxiety and self-doubt. Financial situations are deeply personal, shaped by debt, income, savings, and life priorities. Comparing yourself to someone else’s highlight reel is like judging your marathon performance against someone who’s already halfway to the finish line.

It can make you feel inadequate, overworked, and stressed about things that don’t actually matter. Focusing on your own goals, however small, provides measurable progress and relief from constant mental pressure.

Ignoring Budgets Because They Feel Restrictive

Many people avoid creating budgets because they fear it will feel like jail for their money. Ironically, not budgeting can create more anxiety than following one. Without a clear plan, every purchase triggers a moment of guilt or panic.

You’re left guessing whether you can afford things, constantly second-guessing yourself, and carrying the mental load of financial uncertainty. A budget is not a cage—it’s a map.

By defining limits and priorities, you can make confident spending decisions without that nagging “did I overspend?” stress. Over time, seeing your money allocated intentionally can actually be liberating, reducing financial tension.

Making Impulse Purchases As Emotional Therapy

Shopping to feel better is a classic stress-relief trick, but it backfires financially and emotionally. Every time you buy a mood boost, your short-term pleasure is overshadowed by long-term worry.

Credit card balances rise, bills loom, and guilt accumulates faster than the receipts in your wallet. Emotional spending also teaches your brain that money equals comfort, making anxiety worse when you don’t spend.

The smarter approach? Identify your triggers—boredom, stress, loneliness—and find low-cost ways to satisfy them. A walk, a phone call, or even a quick meditation can calm anxiety without jeopardizing your bank account.

Hoarding Receipts And Financial Papers Without Organization

Some people keep stacks of receipts, invoices, and statements because they think it might help later. The truth is, disorganized piles just fuel stress.

When you need information, finding it feels like searching for treasure in a hurricane. Hoarding can also create a sense of looming doom, like something bad will happen if you throw anything away.

Organization doesn’t have to be extreme; a simple filing system, labeled folders, or even a digital scanning habit can cut anxiety dramatically. Knowing where everything is provides mental space, so your brain isn’t constantly running “what if” simulations about lost documents.

These Are 8 Money Habits That Increase Anxiety Without Helping
Image source: shutterstock.com

Overthinking Every Financial Decision

Spending hours deliberating over every minor purchase—$5 coffee or $6?—can be exhausting. Overanalyzing doesn’t guarantee better choices; it breeds indecision and anxiety.

While thoughtful planning is important for big-ticket items, micromanaging tiny transactions is overkill. Constant rumination also hijacks your attention, reducing your mental bandwidth for more meaningful financial planning.

Letting go of the need for perfection in small matters builds confidence and reduces stress. Trusting your judgment on everyday expenses frees mental energy for decisions that actually matter.

Avoiding Professional Advice Out Of Fear Or Pride

Many people think they can figure out finances alone, believing that asking for help is a weakness. Avoiding professional guidance can heighten anxiety, because unresolved questions linger and stress compounds.

Financial advisors, accountants, or even reputable educational resources can provide clarity, reduce errors, and give peace of mind. The trick isn’t blind reliance—it’s informed decision-making.

Getting help often reduces stress immediately, creating a foundation for smarter, calmer financial habits. Pride may feel good temporarily, but clarity feels better in the long term.

Obsessing Over News Headlines And Market Fluctuations

Watching the stock market or economic news obsessively might feel like staying informed, but it’s more likely to spike anxiety than improve your portfolio. Markets fluctuate constantly, and day-to-day news is rarely actionable for long-term financial health.

Consuming too much financial media can create a sense of impending doom, even when your personal finances are stable. Instead, consider limiting exposure to periodic reviews instead of continuous monitoring. Controlled, intentional information intake keeps your mind focused and reduces panic-driven decision-making.

Rethink, Relax, And Reset Your Money Habits

Money stress doesn’t come solely from lack of funds; it often comes from behaviors that keep your mind spinning. By identifying habits that raise anxiety without real benefits—like overchecking balances, comparing yourself to others, or overanalyzing every decision—you can take steps toward calmer, smarter financial management. Experiment with pacing, organization, and professional guidance to reclaim peace of mind.

Now it’s your turn: what money habits have you noticed increasing your stress, and which strategies have helped you breathe easier? Feel free to comment with your experiences, tips, or aha moments. Your insight could be exactly what someone else needs to feel less overwhelmed.

You May Also Like…

7 Common Money Habits That Increase Stress Instead of Reducing It

8 Financial Habits That Quietly Drain Your Checking Account

How To Regularly Save Money At The Grocery Store

8 Toxic Money Habits That Are Silently Poisoning Your Relationship

Why Does Money Anxiety Increase With Age Instead of Decrease

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Finance Tagged With: anxiety, bank account, banking, Budget, budget tips, budgeting, Budgeting Tips, comparison, finance, finances, financial anxiety, financial stress, impulse purchase, impulse spending, Money, money habits, money issues, news headline, overspending, overthinking, professional advice, saving money, Smart Spending, spending

Why Do So Many People Say Money Stress Is Constant

January 22, 2026 by Brandon Marcus Leave a Comment

Why Do So Many People Say Money Stress Is Constant
Image source: shutterstock.com

Money stress doesn’t knock politely and wait for an invitation. It crashes the mental party, grabs a chair, and refuses to leave. One minute you’re enjoying a quiet coffee, and the next your brain is running numbers you didn’t ask for.

Bills, savings, emergencies, future plans, and that one expense you forgot about all start talking at once. It’s loud, distracting, and weirdly exhausting, even when nothing is technically “wrong.” So why do so many people describe money stress as constant instead of occasional?

The Feeling Of Never Quite Catching Up

A huge reason money stress feels nonstop is the sense that you’re always a step behind. Paychecks arrive, then disappear into rent, groceries, utilities, and other basics before you can blink. Even people who budget carefully often feel like progress moves at a crawl. When necessities take priority, goals like saving or investing get pushed further down the list.

That gap between what people earn and what life costs creates a steady background hum of worry. Over time, that hum starts to feel normal, which is unsettling in its own way. The stress isn’t always about crisis; it’s about endurance.

Why Modern Life Makes Money Feel Louder

Money concerns didn’t suddenly appear in recent decades, but modern life amplifies them. Prices for housing, healthcare, childcare, and education have climbed faster than many wages. Meanwhile, people are constantly exposed to images of other lifestyles through social media and advertising.

That exposure can quietly reset expectations about what “normal” looks like. When your reality doesn’t match those images, stress fills the gap. Add in subscription services, automatic payments, and financial apps pinging your phone, and money becomes a daily presence. It’s hard to relax when reminders are built into your pocket.

Why Do So Many People Say Money Stress Is Constant
Image source: shutterstock.com

Debt Turns Time Into A Bill

Debt is one of the most powerful reasons money stress sticks around. Unlike a one-time expense, debt stretches into the future and follows people for years. Each payment is a reminder of past choices, emergencies, or structural realities like student loans. Interest adds pressure by making balances feel stubbornly resistant to progress.

Even manageable debt can weigh heavily because it limits flexibility and options. Many people don’t just worry about paying today’s bills; they worry about how long those bills will exist. That long horizon makes stress feel permanent instead of temporary.

Uncertainty Keeps The Nervous System On Alert

Another reason money stress feels constant is uncertainty. Jobs change, industries shift, and unexpected expenses show up without warning. Even people with stable incomes know that one medical bill or major repair could disrupt everything.

The human brain is wired to scan for threats, and financial uncertainty fits that category perfectly. When the future feels unpredictable, the body stays slightly tense, even during calm moments. This low-level vigilance can be draining over time. It’s not panic; it’s preparedness that never fully switches off.

Talking About Money Is Still Awkward

Money stress is also intensified by how rarely people talk honestly about it. Many cultures treat money as private or even taboo, which leaves people feeling isolated. Without open conversations, it’s easy to assume everyone else has it figured out.

That assumption fuels shame and self-blame, even when struggles are common. Silence makes stress heavier because it removes perspective. When people don’t hear others admit similar worries, they internalize the pressure. The result is a quiet, persistent tension that feels personal but is actually widespread.

Why The Stress Feels Constant

Money stress is rarely about one bill or one bad month. It’s about systems, expectations, uncertainty, and the mental load of planning for a future that never feels fully secure. When costs rise, debt lingers, and conversations stay quiet, stress becomes a steady companion instead of a passing visitor. Understanding why it feels constant can help people feel less alone in it.

If this topic resonates with you, feel free to leave your thoughts or personal experiences in the comments section below. Your perspective might help someone else feel seen.

You May Also Like…

What Does Financial Stress Do To Your Body?

9 Financial Habits That Look Responsible but Feel Stressful

7 Common Money Habits That Increase Stress Instead of Reducing It

Why Does Money Anxiety Increase With Age Instead of Decrease

Why Do People Feel Guilty Spending Money Even on Necessitiesd

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Finance Tagged With: anxiety, bills, conversations about money, Debt, eliminating debt, Emotional Spending, emotions, financial anxiety, financial stress, impulse spending, Life, Lifestyle, modern life, Money, money issues, money stress, monthly bills, Pay Off Debt, stress

10 Personal Finance Lessons People Learn the Hard Way

January 22, 2026 by Brandon Marcus Leave a Comment

These Are 10 Personal Finance Lessons People Learn the Hard Way
Image source: shutterstock.com

Money lessons rarely arrive politely. They crash into life during overdraft alerts, awkward conversations, or that sinking feeling after opening a credit card statement. Most of us don’t learn personal finance from calm instruction; we learn it from experience, stress, and a few “well, that didn’t work” moments.

The upside is that these lessons stick. They change habits, sharpen judgment, and turn past mistakes into future wisdom. Here are ten personal finance lessons people commonly learn the hard way, usually after their wallet has already taken a hit.

1. Spending More Than You Earn Always Catches Up

Living beyond your income feels manageable at first, especially when credit fills the gaps. Bills get paid, life looks normal, and the problem seems distant. Over time, though, the math becomes unavoidable. Interest compounds, balances grow, and flexibility disappears.

Many people only grasp this lesson after losing sleep over money or juggling due dates. Once learned, it often leads to tracking expenses, setting limits, and respecting the simple truth that income sets the ceiling.

2. An Emergency Fund Is Not Optional

Emergencies are rude, unpredictable, and expensive. Cars break down, jobs vanish, and medical bills appear without warning. Without savings, even small surprises can spiral into debt.

People usually learn this after relying on credit cards for emergencies and struggling to recover. A basic emergency fund provides breathing room and better choices. It turns crises into inconveniences instead of financial disasters.

3. Credit Cards Are Tools, Not Extra Income

Credit cards make spending feel painless, which is exactly the danger. Swiping now and worrying later often leads to balances that linger for years. Interest rates quietly punish unpaid balances month after month.

Many people realize this only after paying far more in interest than the original purchase cost. Used carefully, credit cards can build credit and offer protections. Used carelessly, they become very expensive loans.

4. Lifestyle Inflation Can Sabotage Raises

Earning more money feels like progress, and it is. The trap appears when spending rises just as fast. Bigger paychecks often bring bigger apartments, nicer cars, and more subscriptions.

At some point, people notice they feel just as broke as before, despite earning more. This lesson usually arrives with frustration and confusion. Keeping lifestyle inflation in check allows raises to actually improve financial security.

5. Ignoring Retirement Early Is Costly

Retirement feels far away, especially in your twenties and thirties. It’s easy to delay saving while focusing on current needs. Years later, people realize how powerful time and compound growth could have been. Catching up requires much larger contributions and sacrifices.

This lesson hits hardest when projections reveal uncomfortable gaps. Starting early, even with small amounts, dramatically reduces future stress.

6. Insurance Matters More Than It Seems

Insurance feels boring until the moment it’s desperately needed. Skipping coverage can save money short term, but the risk is enormous. Accidents, illnesses, and disasters can erase years of savings instantly.

Many people learn this lesson after paying out of pocket for something insurance would have covered. Proper coverage protects not just money, but stability and peace of mind. It’s about risk management, not optimism.

7. Not All Debt Is Created Equal

Debt often gets treated as a single category, but its impact varies widely. High-interest consumer debt drains finances quickly, while lower-interest debt can sometimes be strategic.

People often learn this after struggling to escape credit card balances while managing other obligations. Understanding interest rates and repayment terms changes priorities. It encourages attacking the most expensive debt first. This clarity can speed up financial recovery dramatically.

8. Small Purchases Add Up Faster Than Expected

Daily habits quietly shape financial outcomes. Coffee runs, delivery fees, and impulse buys seem harmless in isolation. Over months, they can consume hundreds or thousands of dollars.

Many people only notice after reviewing statements and feeling shocked by the totals. This lesson isn’t about deprivation. It’s about awareness and choosing what truly adds value.

9. Money Stress Affects Relationships

Financial problems rarely stay contained to spreadsheets. They spill into conversations, decisions, and emotional well-being. Couples and families often clash over spending, saving, and priorities.

People usually recognize this lesson after tension builds or trust erodes. Open communication and shared goals reduce conflict. Managing money together requires honesty, compromise, and patience.

These Are 10 Personal Finance Lessons People Learn the Hard Way
Image source: shutterstock.com

10. No One Cares More About Your Money Than You Do

Advice comes from everywhere, but responsibility rests with the individual. Employers, banks, and even well-meaning friends have their own interests.

Many people learn this after blindly following guidance that didn’t fit their situation. Taking ownership means learning basics, asking questions, and paying attention. Confidence grows with knowledge. Ultimately, financial control starts with personal accountability.

Turning Hard Lessons Into Lasting Wins

Personal finance mistakes can sting, but they also teach clarity and resilience. Each hard-earned lesson strengthens future decisions and builds confidence over time. Money management isn’t about perfection; it’s about progress and awareness.

Everyone’s journey includes missteps, and those stories matter. Feel free to give your thoughts or add your own experiences in the comments section below.

You May Also Like…

Risk Proaction: 5 Steps to Stress-Test Your Finances for Worst-Case Scenarios

5 Lessons Young People Should Know About Investing

7 Old-School Life Lessons Only Today’s 50-Somethings Still Remember

5 Valuable Lessons Learned From Market Crashes Historically

7 Personality Clues That Predict Divorce Before It Happens

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Finance Tagged With: Debt, debt payoff, eliminating debt, emergency fund, emergency funds, finance, finance lessons, financial goals, financial lessons, lessons, Life, Lifestyle, Lifestyle Inflation, Money, money anxiety, money issues, money plans, money stress, overspending, Personal Finance, purchases, Retirement, retirement accounts, retirement plan, retirement planning, retirement savings, small purchases, Smart Spending, spending

  • « Previous Page
  • 1
  • 2
  • 3
  • 4
  • 5
  • …
  • 11
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework