• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Money

A Lower Monthly Payment Can Make Debt More Expensive — Here’s the Math

September 26, 2026 by Brandon Marcus Leave a Comment

A Lower Monthly Payment Can Make Debt More Expensive — Here’s the Math
A lower monthly payment can reduce monthly budget pressure, but extending a loan term can increase the total interest paid over the life of the debt – Shutterstock

A lower monthly payment can make a loan easier to fit into a budget, but it can also stretch the debt across more months and increase the interest bill. The payment that looks friendlier on a lender’s screen may cost much more by the time the balance reaches zero.

That matters because monthly payment size tells only part of the story. A loan can require less cash each month while charging interest for a much longer stretch of time. The CFPB specifically warns that longer loan terms can lower monthly payments while increasing total interest costs.

The monthly payment hides part of the price

Consider a simple $20,000 loan with a 4.75% interest rate. The CFPB uses this example to show how dramatically the repayment term can change the final cost.

With a three-year term, the payment works out to about $597 per month, with roughly $1,498 in total interest. Stretch that same loan to six years, and the payment falls to about $320, but total interest rises to roughly $3,024. The borrower gets an easier monthly bill, but pays more than twice as much interest.

The math works because interest continues accumulating while the balance remains outstanding. Early in an amortizing loan, a larger share of each payment generally goes toward interest. As the principal falls, more of each payment goes toward reducing the balance. That makes loan length more than a scheduling choice. It changes how long the lender gets to charge for the money.

A Cheaper Payment Can Come from Adding More Time

This issue appears in more places than car financing. Someone refinancing a loan might see a lower payment after extending the repayment period, even if the interest rate itself barely changes. A mortgage refinance can work the same way if a borrower replaces a shorter remaining term with a longer one. The CFPB advises borrowers to determine whether a lower mortgage payment comes from a lower rate, a longer term, or both.

Student loans offer another example. A private refinance can lower a monthly payment by extending the repayment period, but that longer schedule may increase the total cost of the loan. A borrower therefore needs to compare the new APR, repayment term, monthly payment, and total amount repaid instead of treating the smaller payment as proof of a cheaper loan.

That becomes especially useful when comparing two offers that advertise similar rates. The term can quietly change the math underneath those rates. A few extra years of interest can outweigh the relief created by the smaller monthly bill.

The Calculator Needs More than One Number

Before accepting a lower payment, write down four figures: the amount financed, the APR, the loan term, and the total amount of payments. The monthly payment still matters, but it should sit beside the other numbers rather than replacing them.

For example, suppose one loan requires $450 a month for four years and another requires $340 a month for six years. The second offer saves $110 every month, which can look attractive in a tight budget. But the borrower makes 24 additional payments, and those extra months give interest more time to accumulate. The actual cost depends on the rate, fees, and loan structure, so the total repayment figure provides the clearest comparison.

This approach also prevents a common mistake: comparing payments attached to different amounts borrowed. A loan with a smaller payment may simply finance less money. Another offer may include fees or other financed costs that change the amount being repaid.

The CFPB recommends comparing the amount borrowed, APR, loan length, and monthly payment when evaluating auto loans. That same habit can help consumers evaluate other installment loans too.

Sometimes Stretching the Loan Can Still Make Sense

A longer term does not automatically make a loan a bad choice. A household dealing with a temporary cash squeeze may value a lower required payment because missing payments can create its own financial problems. The decision becomes more complicated when the lower payment encourages someone to borrow more than the budget can comfortably handle.

There can also be legitimate reasons to refinance or restructure debt. A borrower might qualify for a meaningfully lower interest rate, need short-term payment relief, or want to replace several debts with a single installment payment. Those benefits need to be weighed against fees, the new term, and the total amount repaid. Personal installment loans, for example, can carry different rates, fees, and repayment periods depending on the lender and borrower.

The mistake comes from treating the monthly payment as the entire price tag. It is really a slice of the price spread across time.

Put the Loan on A Total-Cost Diet

The most useful question before signing a loan may not be, “Can this payment fit?” It may be, “What will this loan cost from the first payment to the last?”

A lower payment can provide breathing room, and sometimes that breathing room has real value. But stretching repayment also stretches the period during which interest can accumulate. A shorter term may demand more from the monthly budget while reducing the amount paid to the lender overall.

The best comparison does not ignore the monthly payment. It puts that payment in its proper place alongside the APR, term, fees, amount financed, and total repayment. Once those figures sit next to each other, the “cheaper” loan can look very different from the one with the smallest number on the monthly bill.

Would you choose a lower monthly payment if it meant paying more interest overall? Share your thoughts in the comments.

You May Also Like…

7 Money Red Flags That Leave You Legally Liable for a Partner’s Debt Once You Merge Accounts

The Debt Husbands Forget to Mention—Until the Joint Mortgage Credit Pull Kills Your Rate

“Pennies on the Dollar” Tax Debt Promises Should Set Off This Red Flag

Which Debt Should Go First? The Highest Rate Isn’t Always the Whole Answer

You Got a $10,000 Bonus: Debt, Emergency Fund or Roth IRA?

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Personal Finance Tagged With: borrowing, consumer finance, Debt, Interest, loans, Money, monthly payments, Personal Finance

States Where Credit Card Borrowing Is Growing, And Why

September 5, 2026 by Brandon Marcus Leave a Comment

States Where Credit Card Borrowing Is Growing, And Why
Credit card balances are growing faster in several states, with Arkansas, Colorado and Nevada leading LendingTree’s Q1 2026 year-over-year increases. Rising everyday costs, housing expenses and household cash-flow pressures can all influence how heavily consumers rely on credit cards – Shutterstock

Credit card borrowing is picking up in several states, but the story looks very different depending on where people live. Arkansas, Colorado, Nevada, Hawaii, and Connecticut all posted notable increases in average credit card balances between the first quarters of 2025 and 2026, according to LendingTree data.

That does not automatically mean households in those states have suddenly gone on a shopping spree. Credit cards can cover everything from a restaurant bill to an emergency car repair, and rising balances can reflect higher prices, tighter household budgets, greater access to credit, or some combination of all three. The more interesting question is what sits underneath those growing balances, because a credit card can act like a financial pressure gauge long before a household feels ready to admit that something has gone wrong.

The National Credit Card Tab Is Still Moving Up

The broader picture helps put the state numbers in perspective, because U.S. credit card balances reached about $1.263 trillion in the second quarter of 2026, according to the Federal Reserve Bank of New York. That marked a $54 billion increase from a year earlier, although the pace of growth has moderated compared with the huge jumps seen earlier this decade.

The Federal Reserve’s 2025 household survey also offers an important warning about what higher balances can mean, because people facing financial hardship recorded much larger balance increases than people who said they lived comfortably. In other words, a growing balance does not automatically signal financial disaster, but it deserves a closer look when household expenses keep outrunning income. Credit cards make that gap particularly tempting to bridge because the purchase happens immediately while the financial pain arrives later. And later has a nasty habit of showing up with interest.

Arkansas Is Leading the Pack

Arkansas recorded the fastest increase in average credit card debt among the states in LendingTree’s Q1 2026 comparison, with the average balance rising 9.8% from the same quarter a year earlier. The average balance climbed from $5,194 to $5,704, which also shows why percentage increases can look dramatic even when balances remain below those in several higher-cost states.

Arkansas also starts from a relatively modest household-debt base compared with many coastal states, so changes in everyday expenses can put noticeable pressure on budgets. Higher grocery, transportation, housing, and utility costs can push some households toward cards when cash flow gets tight, particularly when savings cannot absorb an unexpected bill. That does not prove that inflation caused Arkansas’s credit card increase, but it provides a plausible backdrop for the trend. The practical warning involves the reason for the balance, not just the size of it: a card used for a planned purchase looks very different from one that repeatedly covers basic bills.

Colorado’s High Costs Meet Rising Card Balances

Colorado posted the second-fastest increase in LendingTree’s Q1 comparison, with average credit card debt climbing 8.4% year over year to $9,319. That places Colorado among the states with both high average balances and some of the fastest recent growth, an uncomfortable combination for households already dealing with expensive housing and other everyday costs.

The state’s economic picture adds some useful context, because Colorado reported average private-sector hourly earnings above the national figure in May 2026 while job growth remained sluggish. The University of Denver also highlighted the squeeze created when expenses rise faster than wages, noting that some households increasingly rely on revolving credit to fill the gap. A household can earn a respectable income and still feel squeezed when housing, transportation, insurance and other recurring bills consume more of the paycheck. That makes Colorado a good reminder that credit card stress does not belong exclusively to households with low incomes.

Nevada’s Balances Are Climbing Too

Nevada recorded an 8.1% increase in average credit card debt between Q1 2025 and Q1 2026, reaching $8,404. That increase placed the state just behind Colorado and Arkansas among the fastest-growing balances in LendingTree’s comparison.

Housing costs offer one possible piece of the puzzle, because Nevada lawmakers and analysts continue to point to constrained housing supply, elevated inflation and higher borrowing costs as major affordability challenges. Southern Nevada’s housing market has started to stabilize, but prices remain substantial enough to keep housing expenses prominent in household budgets. When a large chunk of a paycheck disappears into rent or a mortgage, smaller expenses can become surprisingly difficult to absorb. A credit card can then turn a short-term cash-flow problem into a longer-term balance that costs considerably more to carry.

Hawaii’s High Prices Can Make Cards Harder to Put Away

Hawaii’s average credit card balance also rose 5.4% year over year to $9,334 in LendingTree’s Q1 2026 data. That placed Hawaii among the states with the highest average balances while also putting it firmly among states where borrowing increased.

The state’s own economic data show why household budgets deserve attention, because Honolulu prices rose 5.1% year over year in May 2026, with housing, food, and transportation all posting increases. Hawaii’s economy continued to grow, but state analysts also expected slower job growth and continued inflationary pressure. High prices do not force anyone to use a credit card, but they can make routine expenses consume more cash than expected. When that happens month after month, a card balance can quietly shift from convenience to financing.

Connecticut Shows Why High Debt Deserves a Closer Look

Connecticut’s average credit card balance increased 5.2% year over year to $9,645, giving the state one of the highest average balances in the country as well as meaningful recent growth. LendingTree’s figures put Connecticut second only to New Jersey for average card debt among states in Q1 2026.

Connecticut’s numbers also show why a high balance should not automatically trigger panic, because higher incomes and higher spending can produce larger balances without creating the same financial strain for every household. At the same time, the Connecticut comptroller reported that serious credit card delinquencies remained elevated at the end of 2025 and linked rising balances to affordability pressures. That combination deserves attention because a large balance becomes more dangerous when a household can no longer comfortably pay the statement each month. The real dividing line is therefore not simply “How much debt exists?” but “Why is the balance growing, and can the household keep paying it down?”

A Growing Balance Is a Signal, Not a Verdict

The states with rising credit card balances do not share one neat explanation, and that is actually the most useful takeaway. Arkansas, Colorado, Nevada, Hawaii, and Connecticut have different economies, housing markets, and household incomes, yet consumers in each state increased their average card balances over the latest year studied.

For anyone watching a household budget, the important clues sit closer to home than a state ranking. A balance that rises because of one large, planned purchase may look very different six months later from a balance that grows because groceries, utilities, and car repairs keep landing on the same card.

Which states do you think are feeling the biggest pressure from rising credit card costs, and have you noticed borrowing habits changing where you live?

You May Also Like…

10 States Where New Credit Card Borrowing Is Changing Fastest

Federal Agencies Withdraw 2022 Guidance on Special Credit Programs — What Borrowers Should Know

Retail Store Credit Cards Now Charging 30% APR on Average

8 Times “0% Interest” Credit Cards Turn Into Financial Traps

Should You Pay Off a 0% Credit Card Before the Promotional Rate Ends?

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: credit cards Tagged With: consumer debt, credit card borrowing, Credit card debt, Debt Management, financial trends, household debt, Money, Personal Finance

Relationship Inequality: 10 Real Reasons She Can’t Pay 50% of The Bills

April 3, 2026 by Brandon Marcus Leave a Comment

Relationship Inequality: 10 Real Reasons She Can't Pay 50% of The Bills
Image Source: Pexels.com

Money conversations in relationships can feel like navigating a minefield blindfolded. One minute, everything seems fine, and the next, a simple question about splitting the rent sparks tension, awkward silence, or worse, a full-blown argument. The idea of a 50/50 split sounds fair in theory, but in reality, it can clash with income differences, career paths, and the messy, unpredictable ways life actually works. Expecting perfect equality in bills isn’t just unrealistic—it’s often downright unfair.

Understanding why she might not pay exactly half the bills requires stepping back and looking at the bigger picture. It isn’t about blame or laziness—it’s about economics, choices, and life circumstances. This article dives into ten real, evidence-based reasons she can’t—or won’t—split costs evenly, while offering practical ideas for balancing finances without killing romance or sanity. If couples want money to be a tool instead of a weapon, they have to get strategic, honest, and maybe a little creative.

1. Income Imbalance Isn’t Just a Buzzword

The most obvious factor is income, but it’s more nuanced than “he earns more, she pays less.” According to the U.S. Bureau of Labor Statistics, women, on average, earn roughly 82 cents for every dollar a man makes. That gap widens for women of color, single mothers, and women in industries traditionally dominated by men. Expecting a woman to pay the same share of bills as a higher-earning partner ignores these structural disparities.

Even when both partners work full time, salaries often don’t match up. If one partner earns 70% more than the other, a straight 50/50 split actually creates financial strain for the lower-earning partner. In practical terms, this can mean choosing between paying rent and groceries or saving for emergencies. Couples who want fairness might consider proportional contributions—splitting bills based on income rather than fixed percentages—so everyone’s budget breathes a little.

2. Student Loans and Debt Can Steal Disposable Income

It’s easy to forget that monthly bills aren’t the only money drain. Student loan debt alone can swallow hundreds or even thousands of dollars per month. That debt can make the idea of splitting rent 50/50 seem impossible.

Other forms of debt—credit cards, medical bills, personal loans—can compound the problem. Even if she earns a decent salary, a significant chunk may be earmarked for debt repayment. Couples facing this situation benefit from transparency: share the full financial picture, including debts, and negotiate a fair contribution that doesn’t put either partner in the red. Debt repayment plans can be integrated into household budgeting without resentment building in the background.

3. Unpaid Labor at Home Counts for Something

Money isn’t the only form of work in a household. Research consistently shows that women often shoulder the majority of unpaid domestic labor, from cleaning and cooking to childcare and scheduling. According to a Pew Research Center study, even dual-income households divide chores unevenly, leaving women spending more hours on unpaid work weekly.

If she’s managing the home in ways that save time and money, that contribution has real value. Paying half the bills isn’t the only way to demonstrate fairness. Couples might consider swapping labor for cash contributions, or at least acknowledging the invisible work that balances the household. It can feel radical to think of chores as currency, but it works if everyone agrees and keeps things fair.

4. Career Paths Affect Cash Flow

Not all jobs pay equally, even with the same hours worked. Industries like tech, finance, and engineering tend to pay more than teaching, social work, or creative professions. If her career path is in a lower-paying field, expecting her to split bills 50/50 ignores economic reality.

Freelance and gig work can complicate this further. Irregular income makes it hard to commit to a consistent share of rent or utilities. Budgeting tools, apps, or agreements to adjust contributions month to month can smooth these bumps. Open discussions about income expectations and lifestyle choices prevent tension and resentment from sneaking in unnoticed.

5. Geographic Cost of Living Differences

Even if both partners earn similar salaries, location matters. Urban areas often carry higher rents, utilities, and commuting costs. If she moved from a more expensive city or neighborhood, the reality of a 50/50 split might be financially crushing.

Cost-of-living adjustments can make splitting bills more realistic. Couples can calculate contributions as percentages of income instead of flat numbers or use a tiered approach where bigger earners cover a larger share of specific expenses. It’s less glamorous than a straight split, but it preserves fairness while keeping the lights on and the fridge stocked.

6. Emergency Savings Take Priority

Financial experts stress the importance of emergency savings, ideally covering three to six months of expenses. If she’s building this safety net, she may temporarily contribute less to joint bills. It’s not avoidance; it’s financial foresight.

Couples can accommodate this by creating separate and joint funds. By setting aside money for emergencies, she maintains financial stability without jeopardizing shared responsibilities. Open conversations about priorities reduce judgment and make both partners feel supported, not pressured.

Relationship Inequality: 10 Real Reasons She Can't Pay 50% of The Bills
Image Source: Pexels.com

7. Career Breaks or Family Planning

Taking time off for maternity leave, caregiving, or other family responsibilities directly impacts income. Women disproportionately shoulder these interruptions. Even short breaks from work can disrupt cash flow and the ability to contribute evenly to household bills.

Planning ahead with a clear budget that accounts for these pauses can prevent friction. Some couples find success by front-loading savings before expected breaks or adjusting contributions dynamically. Life is unpredictable, and flexibility keeps the partnership strong even when the paycheck fluctuates.

8. Financial Trauma or Anxiety Can Affect Participation

Money stress affects mental health. Past financial struggles, bankruptcy, or growing up in a household where money was a constant source of anxiety can make her hesitant to commit to large bills. This isn’t laziness—it’s a learned survival mechanism.

Couples can support one another by building trust, creating a plan, and breaking bills into manageable chunks. Open dialogue about money habits, fears, and triggers strengthens relationships, while judgment only escalates tension. Financial counseling or joint planning sessions can turn anxiety into empowerment.

9. Lifestyle Differences Influence Contributions

Personal choices matter too. She might prioritize travel, hobbies, or fitness differently than her partner. These priorities often shape discretionary income, meaning she might be able to contribute less toward bills without compromising her overall financial health.

The solution isn’t imposing strict rules; it’s negotiating together. Couples can choose which expenses are shared, which are split proportionally, and which remain personal. Respecting lifestyle choices while ensuring core responsibilities are met prevents resentment from creeping in unnoticed.

10. Negotiated Fairness Beats Equal Splits Every Time

Ultimately, equality isn’t about identical numbers—it’s about fairness. Every relationship has unique financial dynamics. Some couples thrive on proportional contributions, some trade chores for cash, and some set flexible monthly budgets. The key is communication, honesty, and ongoing evaluation.

Rather than obsessing over a perfect 50/50 split, couples should focus on equitable agreements that respect income, responsibilities, and priorities. When both partners feel valued, supported, and heard, money becomes a tool, not a battlefield. Planning, negotiation, and mutual respect keep partnerships strong long-term.

Balancing the Scales Without Losing Your Mind

Money isn’t just numbers; it’s power, choice, and emotional weight. Expecting her to pay exactly half of every bill ignores real-world factors like income, debt, unpaid labor, career paths, and life circumstances. Couples who want harmony need to define fairness on their terms—whether that means proportional splits, chore-based compensation, or flexible monthly agreements. Acknowledging complexity instead of demanding equality makes money less stressful and relationships healthier.

How do you and your partner handle financial fairness? Are there strategies, creative splits, or budgeting hacks that make it work without tension? Share your ideas, experiences, or clever solutions in the comments section below.

You May Also Like…

Breaking Free at 50: 12 Relationship Rules That Are Officially Outdated

The “Love Bombing” Tactic Scammers Use to Gain Financial Control in a New Relationship

8 Toxic Money Habits That Are Silently Poisoning Your Relationship

10 Things Therapists Know About Your Relationship With Money

9 Ways People Test You in Relationships Without Saying a Word

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: relationships Tagged With: bills, budgeting, Communication, couple goals, dating, equality, finances, financial stress, gender roles, modern love, Money, partnership, relationships

The Inheritance Mistakes That Turn Siblings Into Legal Enemies After a Parent Dies

January 27, 2026 by Brandon Marcus Leave a Comment

The Inheritance Mistakes That Turn Siblings Into Legal Enemies After a Parent Dies
Image source: shutterstock.com

Inheritance is supposed to be a time of family connection, warm memories, and maybe a little extra cash to finally take that dream vacation or pay off lingering debts. But in real life, it often transforms into a battlefield where siblings who used to share inside jokes and childhood secrets suddenly start reading legal documents with the intensity of a courtroom drama.

One seemingly innocent mistake in how a parent structures their estate can ignite a firestorm of lawsuits, resentment, and permanent family rifts. And no, it doesn’t have to involve enormous fortunes or scandalous secrets—it often starts with something as simple as vague wording, unequal distribution, or leaving heirs in suspense.

Vague Wording In Wills That Creates Confusion

The most common way inheritance disputes erupt is through vague and unclear wording in a will. A parent may intend to leave their prized collection of antiques to one child and the family cabin to another, but if the language is ambiguous, it can spiral into an argument over ownership, intent, and even sentimental value.

For example, describing a collection as “valued at market rate” without defining the term can lead to wildly different appraisals and accusations of favoritism. Siblings can interpret the same will in dramatically different ways, and once emotions run high, it becomes far more than a matter of legal interpretation—it becomes a personal feud. Courts often have to weigh the deceased’s intent against conflicting claims, which is stressful, costly, and damaging to family bonds.

Unequal Distribution That Sparks Resentment

Vague wording in a will may lead to uneven distribution of assets, which can ignite tension. Because of this, parents might give more to one child, and siblings who receive less may feel betrayed or undervalued.

This is especially tricky with family businesses, shared properties, or sentimental heirlooms where monetary value doesn’t capture emotional weight. What seems like a thoughtful plan can backfire if it’s not communicated clearly and openly, creating resentment that lingers long after the estate is settled and can often turn into legal battles.

The Inheritance Mistakes That Turn Siblings Into Legal Enemies After a Parent Dies
Image source: shutterstock.com

Failure To Update Legal Documents Over Time

Beyond vague wording, an outdated will could also impact the rest of the family. Parents may draft their will decades earlier and forget to revise it after major life events—divorce, remarriage, birth of grandchildren, or selling significant assets. Old wills can conflict with new intentions, leaving heirs confused and ready to challenge decisions in court.

Imagine a parent who bought a vacation home years ago and listed it in the will, but later sold it without updating the documents. Regularly reviewing and updating estate planning documents isn’t just good practice—it’s essential to prevent misinterpretation, frustration, and unnecessary family strife.

Ignoring Communication With Heirs Before Death

Another surprisingly overlooked step in inheritance planning is simply talking to your heirs. Open discussions about expectations, intentions, and the reasoning behind asset distribution can prevent misunderstandings and accusations later. Silence often breeds assumption and imagination, and once a parent passes, everyone suddenly becomes a lawyer, detective, or detective-lawyer hybrid, dissecting every word of a will for hidden meaning.

While it’s never easy to talk about death and money, clear communication can transform inheritance from a potential war zone into a thoughtful transition of wealth and legacy.

When Emotions Overrule Logic

It’s important to remember that even when every document is perfect and all vague wording is removed, emotions can still fuel disputes. Grief, jealousy, and perceived slights often overshadow rational thinking. Siblings may dredge up old resentments, compare contributions, or question fairness, sometimes escalating minor disagreements into full legal battles.

Estate planning can address many potential conflicts, but it can’t eliminate the human tendency to feel wronged. Recognizing that emotions will play a role and preparing for them—through communication, transparency, and careful documentation—helps reduce the chances that grief turns into litigation.

Your Estate Planning Thoughts Matter

Inheritance doesn’t have to be a source of lifelong family tension. With careful planning, clear language, equal treatment—or at least transparent reasoning—and professional guidance, you can avoid turning siblings into legal enemies. Families that navigate inheritance well often do so by addressing both the financial and emotional dimensions of passing on wealth.

Do you have experiences with inheritance disputes, unexpected generosity, or lessons learned from family legal battles? Your thoughts, reflections, or stories about navigating these tricky waters are welcome in the comments—let’s start a conversation about turning potential feuds into understanding.

You May Also Like…

5 Inheritance Tricks That Make Your Heirs Love You Forever

Legacy Trap: How Your Kids Might Inherit More Tax Than Wealth Without Realizing It

Family Homes Done Right: Kid-Friendly Interior Design on a Budget

6 Blended-Family Will Mistakes That Can Tear Families Apart

6 Unspoken Rules of Inheritance Nobody Teaches You Earlier

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Estate Planning Tagged With: avoiding inheritance disputes, death, delay your inheritance, Estate plan, Estate planning, Family, family communication, family death, family disputes, family money, inheritance mistakes, inheriting money, legal advice, legal documents, Money, money issues, parenting, parenting advice

Why Your Emergency Fund Isn’t Protecting You the Way It Did Five Years Ago

January 27, 2026 by Brandon Marcus Leave a Comment

This Is Why Your Emergency Fund Isn’t Protecting You the Way It Did Five Years Ago
Image source: shutterstock.com

Remember when tucking away a few months’ worth of expenses in a savings account felt like financial armor? That shield, once considered indestructible, now seems a little thinner around the edges. If your emergency fund hasn’t been adjusted in years, you might be in for a surprise: what once covered rent, groceries, and a few random emergencies may no longer stretch far enough to keep you truly safe.

The world changes fast, and your emergency plan can’t stay frozen in time. Between rising inflation, housing costs, and everyday expenses creeping higher, that old nest egg might only cover half of what it used to.

Inflation Is Quietly Eating Your Safety Net

Inflation is like that guest at a party who slowly eats all the snacks while you’re distracted. Over the past five years, the cost of groceries has skyrocketed by nearly 30%, while utilities and transportation have steadily climbed, often outpacing the interest your savings account earns.

If your emergency fund hasn’t grown at the same pace as your expenses, its real purchasing power has quietly eroded. This means you might think you’re financially protected, but when the real-world bills come knocking, you’ll notice the difference immediately. It’s not that your money disappeared—it’s that it doesn’t buy as much as it used to.

Interest Rates And Savings Accounts Are No Longer Your Allies

Five years ago, parking money in a high-yield savings account could earn you a respectable return. Those days are largely behind us. Interest rates have fluctuated dramatically, leaving many emergency funds stagnating while costs continue to rise. Meanwhile, prices on essential goods keep climbing, silently chipping away at your financial cushion.

This mismatch between what you earn on savings and what you spend on necessities can turn a seemingly comfortable fund into something worryingly thin. If you’re relying on the same account strategy you used in 2018, it’s time for a serious checkup. Your fund isn’t broken—it’s just outdated.

The Cost Of Housing Has Shifted Dramatically

Renters and homeowners alike have felt the squeeze. In cities across the country, the housing affordability crisis has caused costs to soar, while wages haven’t always kept pace.

For many, the cost of maintaining a home or apartment now takes up a larger slice of the monthly budget than it did five years ago. This shift doesn’t just affect renters—homeowners feel it too, thanks to rising property taxes, insurance, and utility costs. The reality is simple: your old emergency fund was calculated for a different world, and the world has changed.

Healthcare Costs Are A Silent Drain

Medical expenses often lurk in the background until an emergency hits. Over the last few years, healthcare costs, insurance premiums, and prescription prices have climbed steadily, while even minor medical events that once cost a few hundred dollars can now run into the thousands.

If your emergency fund hasn’t been adjusted for these increases, it may not provide enough coverage when a health situation arises. And with healthcare expenses unpredictable and sometimes unavoidable, this silent drain can turn a well-meaning fund into an inadequate safety net. Ignoring these rising costs is a recipe for financial stress the moment life throws a curveball.

This Is Why Your Emergency Fund Isn’t Protecting You the Way It Did Five Years Ago
Image source: shutterstock.com

Unexpected Expenses Are Growing In Scale

Emergencies themselves haven’t gotten smaller. Natural disasters, car repairs, home maintenance, and sudden job changes all tend to cost more than they did half a decade ago.

When people calculate their emergency savings based on old expense numbers, they underestimate the magnitude of today’s unpredictable costs. Life has a way of being more expensive than we imagine, and the gap between your fund and reality can be shockingly wide.

Rethinking Your Emergency Fund For Today’s Reality

The good news is that updating your emergency fund isn’t just necessary—it’s doable. Start by recalculating your essential monthly expenses, including rent, utilities, groceries, insurance, and potential healthcare costs. Factor in any new financial obligations that have popped up since your last review. Then, consider a buffer for unexpected events that could derail your budget, like car repairs, urgent home fixes, or temporary unemployment.

Adjusting your fund to match current realities ensures it can genuinely act as a protective cushion rather than a false sense of security.

Practical Tips To Keep Your Fund Effective

Keeping an emergency fund truly effective goes beyond just numbers. Consider diversifying where you keep your money: a combination of high-yield savings accounts, money market accounts, or short-term, low-risk investments can help your fund maintain its value against inflation.

Regularly reviewing and updating the total amount ensures your fund keeps pace with rising costs and lifestyle changes. Automating contributions can take the pressure off while maintaining steady growth. And don’t underestimate the psychological benefit of knowing your emergency fund is truly ready for today’s world—it can provide a sense of control and calm when financial surprises hit.

Make Your Emergency Fund Work As It Should

Your emergency fund is only as strong as the environment it exists in, and the world around it has changed significantly in the last five years. By accounting for rising costs, inflation, and unexpected emergencies, you can rebuild your financial confidence and avoid the stress of discovering your protection is thinner than you thought.

We’d love to hear about how you’ve adjusted—or plan to adjust—your emergency fund in today’s landscape, or any experiences that taught you the importance of keeping it current. Leave your thoughts and stories in the comments below.

You May Also Like…

Why Are Emergency Funds Harder to Rebuild Than People Expect

9 Budget Categories That Blow Up After One Emergency

Why So Many Retirees Are Being Forced to Spend Savings Faster Than Planned This Year

Savings Strategy: 9 Micro moves That Add Tens of Thousands Over Time

Savings Leap: 9 Mid-Life Moves That Boost Long-Term Retirement Odds

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: saving money Tagged With: bank account, Cost of living, emergency expenses, emergency funds, emergency spending, finance, finances, general finance, healthcare, healthcare costs, Housing Costs, interest rates, medical expenses, Money, money issues, Personal Finance, saving accounts, saving money, savings, unexpected expenses

The Quiet Credit Score Rule Change That’s Raising Borrowing Costs for Older Americans

January 26, 2026 by Brandon Marcus Leave a Comment

The Quiet Credit Score Rule Change That’s Raising Borrowing Costs for Older Americans
Image source: shutterstock.com

The bill arrives and nothing looks unusual—until the interest rate does. It’s higher than expected, higher than last time, and higher than what a lifetime of on-time payments seems to deserve.

For many older Americans, this moment has become oddly common. No missed payments. No maxed-out cards. Just a creeping sense that the rules changed while no one was watching. They did, and the ripple effects are landing squarely on borrowers who thought experience counted for something.

What Actually Changed Behind The Scenes

This isn’t about a single new law or a dramatic announcement blasted across financial headlines. The shift comes from the slow adoption of newer credit scoring models and updated mortgage pricing frameworks that weigh behavior differently than before. Lenders are increasingly leaning on models that emphasize recent activity, patterns over time, and active credit usage rather than long histories alone.

At the same time, mortgage pricing has been adjusted through updated risk grids that tie interest rates and fees more tightly to credit score bands and other factors. These adjustments were designed to better reflect risk, but they don’t always play nicely with the financial profiles of retirees or near-retirees. Someone with a pristine but quiet credit file can now be priced as if they’re less predictable.

Why Older Borrowers Feel It More Than Anyone Else

Older Americans are more likely to have paid off their mortgages, closed long-unused credit cards, or stopped borrowing altogether. From a life perspective, that’s a win. From a modern credit-scoring perspective, it can look like dormancy. Newer models tend to reward consistent, recent activity because it offers fresh data. A credit file that hasn’t changed much in years may be considered thinner, even if it’s flawless.

There’s also the issue of credit mix. Retirees often streamline their accounts, leaving fewer open tradelines. That can subtly lower scores under models that like variety and motion. Add in the fact that fixed incomes can limit the appetite for new credit, and you have a group doing everything “right” for real life while drifting out of alignment with algorithmic expectations.

The Mortgage Pricing Piece Nobody Talks About At Dinner

Credit scores don’t just decide approval anymore; they increasingly shape the exact price of a loan. Updated loan-level price adjustments, especially in the mortgage world, slice credit scores into narrower bands. Moving from one band to another—even by a few points—can mean a higher rate or added upfront costs. For older borrowers hovering near a cutoff, the margin for error has shrunk.

This matters because the newer scoring emphasis on recent behavior can introduce small score dips that feel arbitrary. Paying off a loan, for example, can temporarily lower a score by reducing active credit. Closing an old card to simplify finances can do the same. These moves make sense for someone planning retirement, but they can push a score just enough to trigger less favorable pricing.

It’s Not Age Discrimination, But It Feels Personal

To be clear, lenders aren’t allowed to price loans based on age, and this shift isn’t an intentional swipe at older Americans. It’s an unintended consequence of modernization. Credit models are built to predict future risk, and their designers focus on patterns that statistically correlate with repayment. Recent data tends to be more predictive than distant history, so the models tilt that way.

The emotional sting comes from the mismatch between lived responsibility and digital scoring. Many older borrowers did exactly what financial advice recommended for decades: pay things off, avoid debt, keep life simple. Now they’re told—quietly, indirectly—that a little more activity would make them look safer.

The Quiet Credit Score Rule Change That’s Raising Borrowing Costs for Older Americans
Image source: shutterstock.com

How Older Americans Can Adapt Without Playing Games

No one should take on debt just to please a scoring model, but small, thoughtful adjustments can help. Keeping one or two long-standing credit cards open and lightly used can maintain activity without risk. A small recurring charge paid in full each month often does the trick. Monitoring credit reports for accuracy matters more than ever, especially as older accounts fall off over time.

It also helps to shop around. Different lenders adopt new models at different speeds, and pricing can vary widely. Asking which credit score version a lender uses isn’t rude; it’s informed. Finally, timing matters. Applying for credit before closing accounts or paying off a major loan can preserve a stronger score snapshot. These steps don’t change the system, but they can soften its edges.

A System Catching Up, And Leaving Some Behind

This quiet credit score shift wasn’t designed to punish experience, but it does reveal how financial systems can drift away from real lives. Older Americans aren’t suddenly riskier borrowers; the measuring tape just changed. Understanding that difference is empowering, even if it’s frustrating.

If you’ve noticed higher borrowing costs, surprising rate quotes, or confusing credit score changes later in life, your perspective matters. Drop your thoughts or personal experiences in the comments below—this conversation is just getting started.

You May Also Like…

Why Major Banks Are Quietly Lowering Credit Limits for Customers With & Holiday Debt

Debt Alert: 6 Ways Holiday Spending Could Trigger a January Credit Score Crisis

6 Warning Signs That Your Credit Card Is A Problem

7 Ways Credit Card Debt Builds Faster Than Expected

10 Uncommon Tactics for Boosting Your Credit Score Rapidly

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: credit score Tagged With: Americans, borrowing money, building credit, credit, credit repair, credit report, credit score, Money, money issues, repairing credit

The IRS Reporting Threshold Change That Just Created a Tax Risk for Millions in 2026

January 26, 2026 by Brandon Marcus Leave a Comment

The IRS Reporting Threshold Change That Just Created a Tax Risk for Millions in 2026
Image source: shutterstock.com

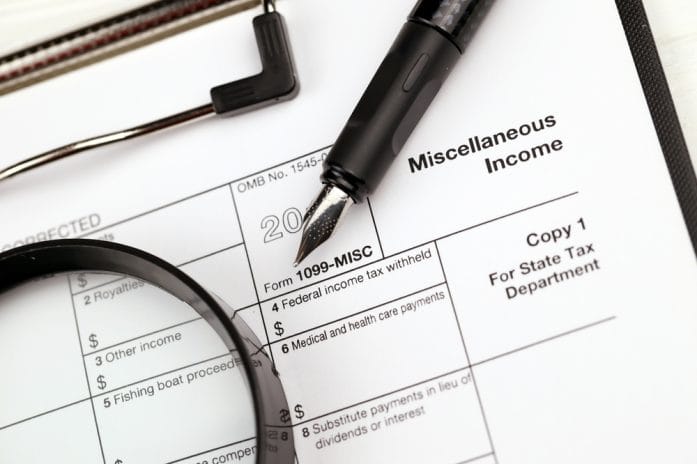
If you’ve ever sold a vintage jacket on an app, picked up extra cash doing freelance work, or split dinner with friends via Venmo, you might have heard rumblings about a tax reporting change that could have snared millions of everyday Americans into unexpected IRS reporting paperwork in 2026.

The chatter about a strict new $600 rule had everyone from Etsy flippers to neighborhood babysitters biting their nails — but then Congress stepped in with a twist that changed the story entirely. And just like a tax-season plot twist, the IRS reporting threshold that once seemed so imminent has now shifted — in a big way.

The $600 Rule That Almost Was

For years, the IRS had been working toward lowering the reporting threshold for Form 1099-K, the tax document that payment processors like PayPal and Venmo send to both you and the IRS to report income received through their platforms. Under the American Rescue Plan Act of 2021, that threshold was slated to plummet to just $600, with no minimum transaction count attached — meaning that even a handful of casual transactions could have triggered a 1099-K form in 2026.

Tax professionals and everyday sellers alike were alarmed. Selling a couch, doing some freelance work, or even collecting contributions for a group gift suddenly looked like it could generate IRS paperwork. Millions of people stood on the brink of receiving tax forms for what they considered ordinary financial behavior — and that’s a recipe for confusion.

Enter The One Big Beautiful Bill Act

Then came a curveball: the One Big Beautiful Bill Act of 2025 — a massive tax and spending law signed July 4, 2025. Among its many provisions, it rewrote how 1099 reporting thresholds work. Instead of embracing the $600 threshold, Congress essentially hit rewind.

Under the new law, the 1099-K reporting threshold no longer drops to $600. Instead, it reverts to the old school standard that was in place before all this turmoil: you’ll receive a Form 1099-K only if you have more than $20,000 in gross payments and more than 200 transactions on a single payment platform in a calendar year.

That’s the rule that originally existed before the American Rescue Plan Act stirred the pot — and this reinstatement is retroactive for reporting years going back to 2022.

Why This Is Huge (But Not In The Way You Think)

Let’s be candid: for most folks, that old-school requirement of $20,000 and 200 transactions was already pretty high. Casual sellers, hobbyists, and part-time gigsters were rarely hitting both of those marks on a single platform in a year. So repeating that threshold makes a huge difference for day-to-day people.

Suddenly, that tiny Etsy shop selling handmade postcards — or that spinach quiche you flipped after thrift-shopping — probably won’t generate a 1099-K heading to your mailbox. But this doesn’t mean the IRS thinks the money isn’t taxable. It just means you won’t automatically get a tax form from PayPal or another processor for smaller totals.

It’s worth repeating: even if you don’t get a 1099-K, all income is still taxable. That’s tax law 101 — the presence (or absence) of a form doesn’t dictate your obligation to report income on your return.

The IRS Reporting Threshold Change That Just Created a Tax Risk for Millions in 2026
Image source: shutterstock.com

The New 1099 Thresholds For Businesses And Freelancers

But wait — the tax fun doesn’t stop with Form 1099-K. The same law made other changes to reporting forms that matter to small businesses and freelancers. Specifically, the reporting threshold for Form 1099-MISC and Form 1099-NEC — used to report payments to contractors, landlords, and miscellaneous income — has been increased. Starting in 2026, businesses generally won’t need to issue these forms unless the total payments reach at least $2,000 in a year, and this threshold will be adjusted for inflation in future years.

This is a big deal for small outfits and side hustlers. Under the old $600 rule, a small business that paid a freelancer $800 could have had to send out a 1099-NEC. Now? Not until payments hit that higher $2,000 mark. That’s less paperwork, fewer forms flying around, and fewer opportunities for innocent mistakes to turn into IRS penalties.


What Do You Think?

This change in tax reporting thresholds for 2026 is one of those rare moments when tax law manages to ease confusion rather than amplify it. Between reinstating the $20,000/$200 1099-K standard and raising the bar on other 1099 forms, the law reshapes how everyday earners interact with IRS reporting. We’ve covered the facts, the history, and the implications — now we want to hear from you.

Tell us what this change means to you, how it might affect your side hustle or business, or even the tax tales you’ve lived through — drop your thoughts or experiences in the comments below!

You May Also Like…

IRS Warning: That Venmo Payment for Your Garage Sale Just Triggered a Surprise Tax Bill

What Your First Budget Of The Year Should Include

8 Tax Moves That Save You When You Can’t Pay the IRS on Time

5 Reasons To Talk To Your Kids About Taxes

6 Advanced Techniques to Lower Your Capital Gains Taxes Legally

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: tax tips Tagged With: 2026, 2026 laws, 2026 taxes, family finances, family money, finance, finances, general finance, Internal Revenue Service, IRS, IRS reporting, Money, money issues, tax planning, tax risk, tax risks, tax tips, taxes

8 Personal Finance Beliefs That No Longer Apply

January 25, 2026 by Brandon Marcus Leave a Comment

8 Personal Finance Beliefs That No Longer Apply
Image source: shutterstock.com

Money advice has a habit of hanging around long after it stops being useful. Some tips were brilliant in a different economy, with different technology, and wildly different expectations about work, debt, and retirement. Yet they keep getting passed down at dinner tables and in comment sections like sacred truths.

The result is a lot of people doing “the right thing” and still feeling behind, stressed, or confused. It’s time to clear the air, bust a few myths, and talk about what no longer deserves a spot in your financial playbook.

1. You Must Stay Loyal To One Employer For Financial Security

This belief came from an era when pensions were common and job-hopping raised eyebrows. Today, long-term loyalty often results in slower wage growth compared to changing roles strategically. Many workers now see their biggest salary increases when they switch companies rather than waiting for annual raises.

Benefits like retirement accounts and health insurance are no longer exclusive to one-employer careers. In fact, skills-based hiring and remote work have expanded opportunities across industries. Financial security now comes from adaptability, not staying put out of fear.

2. Buying A Home Is Always Better Than Renting

Homeownership has been marketed as the ultimate financial milestone for decades. While owning can build equity, it also comes with maintenance costs, property taxes, insurance, and reduced flexibility. Renting can be the smarter financial move depending on location, job stability, and housing market conditions. In high-cost areas, renting and investing the difference may outperform buying for many years.

Mobility has real economic value in a changing job market. The smarter question now is not “Should I buy?” but “Does buying make sense for my life right now?”

3. Carrying Any Debt Means You’re Bad With Money

This belief turns a nuanced topic into a moral judgment. Not all debt is created equal, and some forms can support long-term financial growth. Student loans, business loans, and mortgages can increase earning potential or asset ownership.

The real issue is whether debt is manageable, affordable, and aligned with your goals. Avoiding all debt at any cost can sometimes slow progress or limit opportunity. Smart money management focuses on strategy, not shame.

4. Credit Cards Should Be Avoided Completely

Credit cards earned their bad reputation through high interest rates and misuse. However, used responsibly, they offer fraud protection, rewards, and a way to build credit history. Paying balances in full each month avoids interest entirely while still capturing benefits.

Many essential financial activities, from renting a car to booking travel, are easier with a credit card. A strong credit profile can lower borrowing costs across your lifetime. The problem isn’t credit cards themselves—it’s carrying balances without a plan.

5. Budgeting Means Saying No To Everything You Enjoy

Old-school budgeting often felt like a financial punishment. Modern budgeting is more about awareness than restriction. Knowing where your money goes allows you to spend intentionally on what actually matters to you.

A good budget includes room for enjoyment, hobbies, and rest. Deprivation-based plans tend to fail because they ignore human behavior. Sustainable finances are built on balance, not constant self-denial.

6. You Need A Lot Of Money To Start Investing

This belief kept many people out of the market for years. Today, investing is more accessible than ever, with low-cost funds and platforms that allow small, regular contributions.

Compound growth rewards time more than large starting amounts. Waiting until you feel “ready” often means missing valuable years of growth. Even modest investments can build momentum and confidence. The most important step is starting, not starting big.

8 Personal Finance Beliefs That No Longer Apply
Image source: shutterstock.com

7. Talking About Money Is Rude Or Taboo

Silence around money has cost people real opportunities to learn. When finances aren’t discussed openly, misinformation fills the gap. Talking about salaries, debt, and financial mistakes can lead to better decisions and fairer outcomes. Transparency helps normalize learning curves and reduces shame.

Many people discover they are not alone once conversations begin. Financial literacy improves faster in the open than in isolation.

8. Retirement Is A Single Age With A Single Plan

Retirement used to look like a hard stop at a specific age. Now it’s often a gradual transition that varies widely by person. Some people aim for part-time work, passion projects, or flexible schedules rather than complete withdrawal. Life expectancy, healthcare costs, and personal goals all influence what retirement looks like. Planning now involves building options, not just hitting a number. Financial freedom has become more personalized—and more realistic—than ever before.

Updating The Rules Of Money

Outdated financial beliefs don’t just waste time; they can quietly limit your choices. Letting go of rules that no longer apply creates space for smarter, more flexible decisions. Personal finance works best when it reflects real life, not outdated expectations. If one of these beliefs shaped your past money choices, you’re in good company.

Feel free to add your experiences or lessons learned in the comments section below—your perspective might be exactly what someone else needs to read today.

You May Also Like…

10 Personal Finance Lessons People Learn the Hard Way

8 Budget Fixes That Instantly Turn Finances Around

7 Personal Money Questions Advisors Can’t Believe Are Real

4 Bold Predictions About The Future of Personal Finance Technology

10 Things You Should Never Ignore in Your Personal Finances

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Finance Tagged With: buying a home, buying a house, credit cards, credit score, Debt, eliminating debt, finance, finances, financial anxiety, Financial Security, general finance, home ownership, investing, Investment, Money, money beliefs, money habits, money issues, paying off debt, Personal Finance, spending

Why Does Financial Confidence Feel Fragile?

January 25, 2026 by Brandon Marcus Leave a Comment

Why Does Financial Confidence Feel Fragile?
Image source: shutterstock.com

The moment you feel financially on top of the world can vanish faster than a paycheck on rent day. One minute, you’re proud of your budgeting skills and long-term plans; the next, a surprise expense or alarming headline sends your confidence tumbling. That emotional whiplash around money isn’t a personal flaw or a sign you’re “bad with finances.” It’s a deeply human response to a system that mixes math, emotion, uncertainty, and identity into one messy package.

Financial confidence feels empowering, but it also feels oddly delicate, like a houseplant that needs just the right light, water, and reassurance to stay alive. To understand why it wobbles so easily, we need to look beyond bank balances and into how people actually experience money.

Money Is Emotional, Not Just Mathematical

Money is often presented as a numbers game, but human brains do not treat it that way. Every financial decision carries emotional weight because money is tied to safety, freedom, and self-worth. Even people with solid savings can feel anxious if they grew up with financial instability or witnessed money-related stress at home. Research in behavioral economics shows that people experience losses more intensely than gains, which means a single setback can overshadow many past successes.

This emotional imbalance makes confidence fragile, because it’s constantly negotiating between logic and feeling. When fear or shame enters the picture, spreadsheets rarely stand a chance. Financial confidence suffers not from a lack of intelligence, but from an overload of emotion layered onto every dollar decision.

Uncertainty Is Baked Into Modern Life

Financial confidence thrives on predictability, and modern life offers very little of it. Jobs change, industries evolve, and economic conditions can shift with unsettling speed. Even careful planners cannot fully control interest rates, inflation, or unexpected health costs. This uncertainty creates a background hum of anxiety that never fully switches off.

When the future feels unclear, confidence becomes conditional rather than stable. People start thinking, “I feel okay now, but what if something goes wrong?” That lingering question erodes confidence, even when things are objectively fine. The fragility isn’t irrational; it’s a response to living in a system where stability often feels temporary.

Why Does Financial Confidence Feel Fragile?
Image source: shutterstock.com

Comparison Is A Confidence Thief

Financial confidence rarely exists in isolation, especially in a world saturated with curated success stories. Social media, casual conversations, and even well-meaning advice can turn money into a competitive sport. People tend to compare their behind-the-scenes reality to someone else’s highlight reel. That comparison can make perfectly reasonable financial situations feel inadequate.

Studies consistently show that relative income affects happiness more than absolute income, which explains why confidence fluctuates depending on who we’re comparing ourselves to. When someone else appears to be doing better, confidence shrinks, regardless of personal progress. The constant measuring stick makes confidence dependent on external validation rather than internal stability.

Financial Language Is Often Confusing And Intimidating

Confidence struggles when the subject matter feels inaccessible, and finance is notorious for jargon. Terms like diversification, amortization, and liquidity can sound intimidating, even when the concepts themselves are manageable. When people don’t fully understand the language, they may doubt their ability to make good decisions. This doubt doesn’t reflect actual competence; it reflects a communication gap.

Financial systems often reward those who already feel confident enough to ask questions or seek guidance. For everyone else, confusion quietly chips away at confidence over time. Feeling unsure about the rules of the game makes it hard to trust your own moves.

Past Experiences Leave Long Shadows

Financial confidence carries a memory, and that memory can be stubborn. A past mistake, like falling into debt or making a poor investment, can linger emotionally long after the situation is resolved. The brain treats these experiences as warnings, replaying them to prevent future harm. While this protective instinct can be useful, it can also become overactive.

People may hesitate to take reasonable risks or doubt positive progress because they remember how quickly things once went wrong. Trauma around money doesn’t require dramatic events; even subtle, repeated stress can shape long-term confidence. Healing financial confidence often means addressing the past, not just improving current numbers.

Control Feels Limited, Even When It Isn’t

Confidence grows when people feel in control, yet money often feels like it operates by its own rules. Bills arrive whether we’re ready or not, markets fluctuate without warning, and emergencies ignore planning calendars. Even when individuals make smart choices, outcomes can still disappoint. This disconnect between effort and result weakens confidence over time. Humans are wired to associate control with competence, so when control feels limited, self-trust takes a hit.

Financial confidence becomes fragile because it’s tethered to outcomes that aren’t fully controllable. Recognizing this gap is essential to understanding why confidence rises and falls so unpredictably.

Learning To Steady The Feeling

Financial confidence feels fragile because it lives at the intersection of emotion, uncertainty, memory, and social pressure. It isn’t a permanent state you unlock once and keep forever; it’s a feeling that requires care and context. Understanding why it wobbles can reduce self-blame and open the door to healthier money relationships. Confidence doesn’t mean never feeling anxious or unsure; it means trusting yourself to respond when those feelings show up.

If you’ve noticed your own confidence rise and fall over time, your experience is far from unusual. The conversation around money gets richer when real stories enter the room, so feel free to add your perspective or experiences in the comments below.

You May Also Like…

Behavior Backfire: 5 Overconfidence Traps That Hurt Even Smart Investors

How to Wisely Invest in Lawn Maintenance and Upkeep

How Can Overconfidence in the Market Cost Millions

Tax Foresight: 6 Planning Moves That Could Save You Money Soon

Why Does Money Anxiety Increase With Age Instead of Decrease

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: anxiety, Emotional Spending, financial anxiety, financial confidence, financial language, financial stress, financial uncertainty, Life, Lifestyle, Money, money habits, money mindset, overspending, Smart Spending, spending, stress

Why Do So Many People Feel Financially Stuck

January 25, 2026 by Brandon Marcus Leave a Comment

Why Do So Many People Feel Financially Stuck
Image source: shutterstock.com

Money stress has a special talent for showing up uninvited. One minute life feels manageable, and the next minute the bank balance looks like it’s playing a cruel joke. Bills stack up, goals feel far away, and even doing “everything right” somehow doesn’t seem to move the needle.

This feeling of being financially stuck isn’t rare or shameful—it’s widespread, deeply human, and rooted in forces much bigger than individual choices. To understand why it’s so common, we need to zoom out, slow down, and look at what’s really going on beneath the surface.

1. Rising Costs And Shrinking Breathing Room

For many households, the biggest culprit is simple math that no longer works. The cost of housing, groceries, healthcare, transportation, and childcare has climbed steadily over the past decades, often outpacing wage growth. Even people with steady jobs can feel like their paycheck evaporates the moment it lands. This creates a constant sense of pressure, where there’s little room to save, invest, or recover from surprises.

When every dollar already has a job, there’s no cushion for setbacks or opportunities. Over time, that tightness doesn’t just strain budgets—it drains motivation and confidence. Feeling financially stuck often starts with the exhausting reality of running faster just to stay in the same place.

2. Debt That Lingers Longer Than Expected

Debt is another heavy anchor, especially when it’s taken on early and follows people for years. Student loans, credit cards, medical bills, and auto loans can quietly shape financial lives long after the original purchase or emergency is forgotten. Interest turns small balances into stubborn obstacles that refuse to shrink. Many people make payments faithfully and still feel like they’re not making progress, which can be deeply discouraging.

Debt also limits choices, from where someone can live to which jobs they can take. The emotional weight matters too, as ongoing debt can fuel stress, guilt, and a sense of failure. That combination makes it harder to plan long-term or feel optimistic about money.

3. Income That Feels Unstable Or Inadequate

Even when expenses are controlled, income can be unpredictable or insufficient. Gig work, contract jobs, tipped positions, and variable schedules make it hard to count on a consistent monthly amount. Without reliable income, planning becomes a guessing game instead of a strategy. Raises and promotions also tend to come slowly, while costs rarely wait. For many workers, productivity has increased without a matching increase in pay, creating a gap between effort and reward.

This disconnect can make people feel powerless, as if no amount of hard work changes the outcome. Financial progress depends on income growth, and when that growth stalls, so does the sense of momentum.

4. Financial Education Gaps And Confusing Systems

Most people were never formally taught how money works beyond the basics. Budgeting, investing, taxes, credit, and insurance are often learned through trial and error. Financial systems are complex, filled with jargon, and sometimes designed in ways that benefit institutions more than individuals. This lack of clarity can lead to hesitation or avoidance, especially when mistakes feel costly.

Without clear guidance, people may miss opportunities or fall into habits that quietly hold them back. Over time, confusion turns into self-blame, even though the system itself is hard to navigate. Feeling stuck often has less to do with intelligence and more to do with missing information and support.

5. Social Pressure And Invisible Comparisons

Modern life comes with a nonstop highlight reel of other people’s spending and success. Social media, advertising, and cultural expectations can quietly redefine what feels “normal.” Vacations, new cars, home upgrades, and constant experiences start to look like basic milestones instead of luxuries.

Trying to keep up, even subconsciously, can push people into spending choices that strain their finances. At the same time, many struggles stay hidden, creating the illusion that everyone else has it figured out. That gap between perception and reality fuels frustration and embarrassment. Feeling financially stuck often worsens when people think they’re alone in it, even though they’re very much not.

6. Emotional Fatigue And Decision Overload

Money decisions are rarely just logical; they’re emotional. Constantly worrying about finances drains mental energy and focus. When every choice feels high-stakes, from grocery shopping to opening an email from a lender, exhaustion sets in. This fatigue can lead to avoidance, procrastination, or short-term fixes that don’t solve long-term problems.

Stress also makes it harder to learn new skills or think creatively about solutions. Over time, the emotional toll of money pressure can become as limiting as the financial reality itself. Feeling stuck is often the result of burnout, not laziness or lack of effort.

Why Do So Many People Feel Financially Stuck
Image source: shutterstock.com

Naming The Stuck Feeling Is The First Step

Feeling financially stuck isn’t a personal failure; it’s a signal. It reflects rising costs, lingering debt, uneven income, complex systems, and the emotional weight of navigating all of it at once. When people understand that these pressures are shared and structural, shame loosens its grip. Awareness creates space for better conversations, smarter choices, and more realistic expectations. Progress rarely comes from one dramatic move, but from small shifts paired with patience.

If this topic resonates with you, the comments section below is open for your experiences, insights, and reflections. Honest conversations are how financial stress starts losing its power.

You May Also Like…

8 Unsettling Financial Patterns That Keep Families Stuck for Generations

9 Financial Habits That Look Responsible but Feel Stressful

8 Grocery Shopping Habits That Make You Spend More Without Realizing It

6 Bad Money Habits Families Show During The Holidays

9 Budgeting Fears That Keep You Stuck

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: Cost of living, Debt, debt payoff, eliminating debt, finance, finances, financial education, financially stuck, general finance, Income, income stream, Life, Lifestyle, Money, money habits, money issues, money problems, rising costs

  • « Previous Page
  • 1
  • 2
  • 3
  • 4
  • …
  • 11
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework