• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Brandon Marcus

5 Warning Signs Someone Is Using Your Social Security Number

March 27, 2026 by Brandon Marcus Leave a Comment

5 Warning Signs Someone Is Using Your Social Security Number
Image Source: Shutterstock.com

When it comes to identity theft, damage builds quietly, often hiding in plain sight while accounts shift, numbers change, and red flags stack up. One small clue can signal something much bigger, and ignoring that clue can turn a manageable issue into a full-blown financial nightmare. The reality feels uncomfortable, but awareness changes everything, especially when it comes to something as powerful as a Social Security number.

Most people assume they would notice identity theft immediately, but that assumption creates the perfect blind spot. Fraud rarely starts with dramatic moves; it creeps in with subtle changes that seem easy to brush off or explain away. That makes early warning signs incredibly valuable, because catching them quickly can save thousands of dollars, protect credit scores, and prevent months of cleanup. Knowing what to look for does not require expert-level knowledge, just a willingness to pay attention and act fast when something feels off.

1. Your Credit Report Starts Telling a Story You Don’t Recognize

A credit report should read like a familiar biography, filled with accounts, balances, and history that match real financial decisions. When unfamiliar accounts or inquiries suddenly appear, that story shifts into something confusing and concerning. New credit cards, loans, or even hard inquiries from lenders can signal that someone else uses personal information to apply for credit. These entries often show up before any bills or collection notices arrive, which makes regular credit checks one of the strongest early defenses.

Identity thieves rely on speed, opening accounts quickly and moving on before detection catches up. That means even one unfamiliar inquiry deserves attention, especially if it comes from a lender that has never appeared before. Checking credit reports from all three major bureaus adds another layer of protection, since not every account appears everywhere right away. A free annual report offers a baseline, but more frequent checks can reveal issues much earlier.

Taking action immediately matters more than trying to confirm every detail first. Filing a fraud alert or freezing credit can stop further damage while sorting out what happened. Credit monitoring services can also provide real-time alerts, which adds another safety net for anyone who wants constant visibility. Staying proactive here keeps control firmly in the right hands.

2. Bills and Statements Suddenly Go Missing In The Mail

Mail rarely disappears without a reason, especially when it comes to financial statements, tax documents, or official notices. When expected bills stop arriving, something may interfere behind the scenes. Identity thieves sometimes change mailing addresses on accounts to redirect sensitive information, which allows them to operate without interruption. That small change can delay discovery long enough to rack up serious damage.

Missing mail does not always scream fraud right away, but it should raise questions. Checking with service providers or financial institutions can confirm whether address changes occurred without permission. Online account access also helps verify recent activity, which can reveal whether someone has tampered with account details.

Switching to electronic statements can reduce the risk of intercepted mail while adding convenience. At the same time, keeping an eye on physical mail still matters, especially for government-related correspondence. Acting quickly when something goes missing prevents identity theft from gaining momentum.

5 Warning Signs Someone Is Using Your Social Security Number
Image Source: Pexels.com

3. Debt Collectors Call About Accounts That Don’t Exist

Few things feel more jarring than a call about a debt that has no connection to reality. When collectors start asking for payment on accounts that never existed, that often points directly to identity theft. These accounts may include credit cards, personal loans, or even medical bills opened under a stolen Social Security number.

Ignoring these calls can make the situation worse, since unpaid debts can move into collections and damage credit scores. Instead, requesting detailed information about the account helps clarify what happened. Debt collectors must provide verification, which can reveal the origin of the fraudulent account.

Disputing these debts quickly becomes critical, especially through credit bureaus and the original creditor. Filing an identity theft report with the Federal Trade Commission creates a formal record, which helps during disputes. Keeping organized records of every conversation and document can speed up the resolution process and protect against further complications.

4. Your Tax Return Gets Rejected Out of Nowhere

Tax season usually follows a predictable rhythm, but identity theft can throw that rhythm off instantly. When a tax return gets rejected because someone already filed using the same Social Security number, that signals a serious issue. Tax-related identity theft allows criminals to claim refunds before the real filer even submits their return.

This type of fraud often goes unnoticed until filing time, which makes it particularly frustrating. The rejection message usually includes a code that indicates duplicate filing, which provides a clear starting point for resolving the issue. Contacting the IRS and completing an identity theft affidavit sets the recovery process in motion. Filing taxes as early as possible each year can reduce the risk of this type of fraud. An Identity Protection PIN from the IRS adds another layer of security by requiring a unique code for filing. Staying ahead of tax deadlines can make a huge difference in preventing someone else from stepping in first.

5. Government Benefits Show Activity You Never Approved

Government benefits like Social Security or unemployment assistance should never show unexpected changes or claims. When benefits suddenly appear, increase, or shift without authorization, that often signals misuse of a Social Security number. Fraudsters sometimes file for benefits using stolen identities, collecting funds while the rightful owner remains unaware.

Checking benefit statements regularly can reveal these discrepancies early. Online portals for government programs often provide detailed activity logs, which can highlight unauthorized changes. Reporting suspicious activity immediately helps stop payments and prevents further misuse. Securing online accounts with strong passwords and multi-factor authentication adds a critical layer of protection. Monitoring government correspondence also helps catch unusual activity quickly. Staying alert in this area can prevent long-term complications that take months to resolve.

Stay Protected And Always in Control

Spotting identity theft early changes everything, and these warning signs offer a powerful advantage when used wisely. Each red flag, whether it shows up on a credit report or arrives as a confusing phone call, deserves attention and action. Waiting rarely improves the situation, but quick responses can limit damage and restore control faster than expected.

Building strong habits around monitoring financial activity, checking reports, and protecting personal information creates a solid defense against identity theft. Small steps, taken consistently, can block even determined fraud attempts. The goal does not involve living in fear, but staying informed and ready to act when something feels off.

What stands out the most among these warning signs, and what steps feel realistic to take right away? Share all of your thoughts, strategies, or even close calls in the comments, because real experiences can help others stay one step ahead.

You May Also Like…

8 Silent Costs of Ignoring Identity Theft

6 Free Credit Monitoring Tools That Expose You to Identity Theft

8 Email Habits That Make You a Target for Identity Theft After 40

Check Your Credit Report NOW—5 Signs of Identity Theft

6 Free Credit Monitoring Tools That Expose You to Identity Theft

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: scams Tagged With: credit monitoring, credit score, cybersecurity, data breach, financial safety, fraud alerts, fraud prevention, identity protection, identity theft, Personal Finance, scams, Social Security number

Banks Are Reversing Certain Deposits — Why Some Customers Are Losing Access to Funds

March 27, 2026 by Brandon Marcus 3 Comments

Banks Are Reversing Certain Deposits — Why Some Customers Are Losing Access to Funds
Image Source: Unsplash.com

A deposit should mean one thing: the money is yours. It lands in the account, the balance goes up, and everything moves forward. That expectation feels solid, almost automatic, like flipping a switch and watching the light turn on. So when that same deposit suddenly disappears or gets reversed, it doesn’t just cause confusion—it sparks frustration, stress, and a whole lot of questions. People expect consistency from their banks, not surprise plot twists that hit their balance overnight.

Something important sits beneath those reversals, and it goes far beyond random glitches or rare mistakes. Financial institutions follow strict systems designed to protect against fraud, errors, and risk, but those systems don’t always feel friendly when they freeze or pull back funds. The reality is simple but not always obvious: a deposit showing up in an account doesn’t always mean the money has fully cleared.

When “Available” Doesn’t Mean “Yours”

Banks move fast when it comes to showing deposits, but the actual verification process often takes longer than most people realize. When someone deposits a check or receives a transfer, the bank may make a portion—or even all—of that money available right away. That quick access helps people pay bills, cover expenses, or move money around without waiting days. However, behind the scenes, the bank still needs to confirm that the funds actually exist and that the transaction holds up under scrutiny. That delay creates a temporary window where money looks usable but hasn’t officially cleared the system.

That window matters more than ever, especially as digital banking speeds everything up on the surface. If a check bounces, a transfer fails, or a sending account lacks funds, the receiving bank can reverse the deposit entirely. At that point, the money disappears just as quickly as it arrived, and the account holder ends up stuck dealing with the aftermath. Some people feel blindsided because the funds showed as available, which creates a sense of certainty that doesn’t match reality. Banks don’t always make that distinction obvious, and that gap in understanding causes most of the frustration when reversals happen.

The situation becomes even more complicated when someone spends money tied to a deposit that later gets reversed. That can trigger overdraft fees, declined payments, or a negative balance that snowballs quickly. Banks don’t usually absorb those losses because they treat the reversal as a correction, not a mistake. That means the account holder carries the consequences, even if the original deposit looked legitimate. Understanding that “available” funds still sit in a kind of financial limbo helps explain why these reversals feel so abrupt and disruptive.

The Rise of Fraud and Why Banks Are Hitting the Brakes

Banks don’t reverse deposits for fun—they do it because fraud has become faster, smarter, and more widespread. Scammers have figured out how to exploit the gap between deposit availability and final verification, using fake checks, stolen accounts, or manipulated transfers to create the illusion of real money. They rely on speed, knowing that if someone withdraws or sends funds before the bank catches the issue, the damage sticks. Financial institutions have responded by tightening controls, increasing scrutiny, and acting more aggressively when something looks off.

That shift means more deposits get flagged, delayed, or reversed, even in situations that might seem harmless at first glance. A check from an unfamiliar source, a sudden large transfer, or unusual account activity can all trigger a review. Banks use automated systems to scan for patterns that match known fraud tactics, and those systems don’t always distinguish between a scam and a legitimate transaction right away. When something raises a red flag, the bank steps in quickly, sometimes freezing or reversing funds before the situation fully unfolds.

This heightened vigilance protects the overall system, but it also creates friction for everyday account holders. People who receive legitimate payments may still face delays or reversals simply because the transaction doesn’t fit a typical pattern. That reality forces a new kind of awareness around how money moves, especially when dealing with large sums or unfamiliar sources. Staying cautious about who sends money and how it arrives becomes more important than ever, because the bank’s priority focuses on minimizing risk first and sorting out details later.

Banks Are Reversing Certain Deposits — Why Some Customers Are Losing Access to Funds
Image Source: Shutterstock.com

Common Situations That Trigger Deposit Reversals

Not every reversal comes from fraud, even though that gets most of the attention. Everyday banking situations can also lead to deposits getting pulled back, often without much warning. One of the most common triggers involves checks that bounce due to insufficient funds or closed accounts. Even if the check looked perfectly valid at the time of deposit, the bank can reverse it once the issuing bank rejects the payment. That reversal can happen days after the initial deposit, which makes it feel sudden and unexpected.

Another frequent issue involves ACH transfers, especially when someone disputes a transaction or cancels a payment. Unlike instant transfers, ACH payments can take time to finalize, and they come with built-in reversal rights under certain conditions. If the sender claims an error or unauthorized activity, the bank may reverse the transaction while investigating. That process protects consumers but can leave the recipient temporarily—or permanently—without the funds they thought they had secured.

Errors also play a role, even in highly automated systems. A duplicate deposit, a misrouted transfer, or a processing mistake can all lead to corrections that look like reversals. Banks move quickly to fix those issues, which sometimes means pulling funds back without much notice. While those cases don’t involve wrongdoing, they still create confusion and inconvenience for anyone affected. Recognizing these scenarios helps explain why reversals don’t always signal a problem with the account holder, even though they still require careful attention.

How to Protect Your Money (and Your Sanity)

Avoiding deposit reversals entirely isn’t always possible, but smart habits can reduce the risk and soften the impact when they do happen. Waiting for full clearance before spending large or unfamiliar deposits stands out as one of the most effective strategies. That patience may feel inconvenient, but it prevents a situation where money disappears after it has already been used. Checking with the bank about hold times and clearance policies can also provide clarity, especially when dealing with checks or transfers from new sources.

Verifying the source of any deposit matters just as much as timing. If a payment comes from someone unfamiliar or feels unexpected, taking a moment to confirm its legitimacy can prevent bigger problems later. Scammers often rely on urgency, pushing people to act quickly before questions arise. Slowing things down, asking for details, and avoiding immediate transfers or withdrawals can break that pattern and reduce exposure to fraud. That approach keeps control in the hands of the account holder rather than the scammer.

Keeping a financial cushion in the account also helps absorb the shock of a reversal. Even a small buffer can prevent overdraft fees and declined payments if funds suddenly disappear. Monitoring account activity regularly adds another layer of protection, allowing quick responses to any changes or issues. These habits don’t just reduce risk—they create a sense of control in a system that sometimes feels unpredictable. When banks act fast, having a plan in place makes a noticeable difference.

Stay Sharp, Stay Informed, Stay in Control

Deposit reversals don’t come out of nowhere, even though they can feel that way in the moment. Banks operate within a framework that prioritizes verification, security, and risk management, and that framework doesn’t always line up with everyday expectations. Understanding the difference between available funds and cleared funds changes the way deposits get handled, especially when larger amounts or unfamiliar sources come into play. That awareness turns confusion into strategy, giving people a clearer path through situations that might otherwise feel chaotic.

What’s the most surprising thing you’ve seen happen with a bank deposit, or what strategies have helped you avoid issues like this? Drop your thoughts, experiences, or tips in the comments.

You May Also Like…

Biometric Banking and the Rise of Fraud Concerns in 2026

5 Budgeting Apps That Integrate With Biometric Banking

4 Steps to Take if You Hold More Than $250K in One Bank

Bank Alert: 7 Reasons “Courtesy Credits” Get Taken Back Without Warning

What Happens if Adult Children Control Your Online Banking Credentials

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Banking Tagged With: ACH transfers, bank policies, banking, banking news, check deposits, consumer awareness, deposits, financial safety, Financial Tips, fraud prevention, money management, Personal Finance

Social Security Checks Are Getting Smaller for Some Retirees — And It’s Not a Benefit Cut

March 26, 2026 by Brandon Marcus 1 Comment

Social Security Checks Are Getting Smaller for Some Retirees — And It’s Not a Benefit Cut
Image Source: Shutterstock.com

Imagine opening your mailbox, flipping open your latest Social Security statement, and discovering that your check looks a little leaner than last month. Panic sets in for many retirees, but before assuming the worst, it’s crucial to understand what’s really happening. Social Security checks can shrink for some retirees, even though no one in Washington pressed the “benefit cut” button. This phenomenon isn’t about punishment—it’s about math, taxes, and the sneaky ways living costs adjust under federal rules. For anyone counting on Social Security as a primary income source, this shift can feel unsettling, but knowing the why can ease a lot of worry.

At first glance, the idea of a smaller check seems like bad news. After all, Social Security is designed to provide steady, predictable income. But when retirees notice their deposits decreasing, it often has nothing to do with the Social Security Administration slashing benefits. The reality is more nuanced.

The Inflation Twist: COLA Isn’t Always Enough

Cost-of-living adjustments, or COLA, sound like a built-in financial cushion. Every year, Social Security recipients are supposed to get a bump that accounts for inflation. In theory, this is great news: your income should rise just enough to match higher prices at the grocery store or gas pump. Reality, however, has a few quirks. Inflation doesn’t hit every part of life equally. Retirees often spend a larger portion of their income on healthcare, which has historically risen faster than general inflation. So even if the COLA adds a few dollars to a check, it may not fully cover increased medical expenses or other cost surges.

The other wrinkle is the timing. Social Security benefits are adjusted annually, while prices climb continuously. During months when inflation spikes sharply, it can feel like your check is lagging behind real-world costs. Even when the system technically provides a raise, your spending needs may outpace it. This discrepancy isn’t a sign of a policy failure; it’s a reality of how benefits are calculated versus how prices actually move. Savvy retirees can mitigate the pinch by reviewing monthly expenses, prioritizing higher-cost essentials, and seeking supplemental income opportunities when necessary. Budgeting tools and automatic expense trackers can help spot where every dollar is going and where small adjustments could have a meaningful impact.

Medicare Premiums: The Silent Deduction

Few retirees anticipate just how much Medicare can quietly chip away at their Social Security checks. Part B and D premiums are deducted directly from payments, and these premiums can rise year to year depending on healthcare costs and legislative adjustments. While the premium increases are technically predictable, they can still feel like a shock when a recipient notices that their “new” check seems smaller than last year’s. What makes this deduction tricky is that it’s automatic and often overlooked when calculating expected income.

Income-based adjustments can complicate matters further. Higher earners may pay more for Medicare premiums through a mechanism called IRMAA (Income-Related Monthly Adjustment Amount). If someone’s income crosses certain thresholds, their premiums can jump significantly, reducing net benefits. Planning ahead is essential: retirees can review Medicare statements, understand the calculation behind their deductions, and consider tax strategies or supplemental insurance options that might lower total costs. Taking a proactive approach can help prevent surprises and make the monthly budget feel far more manageable.

Taxes: Uncle Sam’s Slice of Your Check

Social Security is not entirely tax-free, and this is where many retirees feel a bite that looks like a mysterious reduction in their benefits. Depending on income from other sources, up to 85% of Social Security benefits can become taxable at the federal level. That includes earnings from pensions, investments, or part-time work. The result? Even though the Social Security Administration hasn’t cut a single dollar, the IRS collects its share before the check hits the bank.

State taxes can also affect retirees, depending on where they live. Some states tax Social Security income fully, partially, or not at all, which adds an additional layer of complexity. The key takeaway is that understanding how taxes interact with Social Security is crucial to anticipating the actual take-home amount. Smart financial planning, including strategic withdrawals from other income sources or tax-advantaged accounts, can maximize the cash that actually lands in a retiree’s hands. This is another area where consulting a financial planner or using tax software to simulate outcomes can save headaches and preserve more of what you’ve earned.

Budgeting and Lifestyle Tweaks That Can Make a Big Difference

Smaller Social Security checks don’t have to translate into smaller lifestyles. Retirees can find creative ways to stretch income without sacrificing enjoyment. One method is reviewing discretionary spending with a fine-tooth comb: entertainment subscriptions, dining habits, and travel choices can all be optimized without feeling deprived. Even small changes, like shopping with a list or timing grocery runs to catch sales, can yield noticeable savings over time.

Another strategy involves exploring supplemental income options. Part-time work, freelancing, or even renting out extra space in a home can boost monthly cash flow. Pairing this with careful investment management and debt reduction strategies helps ensure that Social Security remains a stable foundation rather than the sole lifeline. Financial advisors often recommend a combination of careful planning and proactive lifestyle adjustments to preserve financial comfort while keeping retirement stress levels low. The goal is simple: make the most of every dollar while still enjoying the flexibility and freedom that retirement should offer.

Social Security Checks Are Getting Smaller for Some Retirees — And It’s Not a Benefit Cut
Image Source: Shutterstock.com

The Check May Shrink, But Planning Can Stretch It

Smaller Social Security checks aren’t inherently bad news. They often reflect taxes, Medicare premiums, and cost-of-living quirks rather than a government cut. Understanding these dynamics equips retirees to plan strategically, stretch income, and adjust spending without panic. Looking at the full picture—taxes, healthcare costs, inflation, and potential income streams—turns a moment of worry into a chance to make financial choices that work smarter. Retirement is about comfort, independence, and making sure every check supports the lifestyle you want. A well-informed approach ensures that even if a check looks smaller, the lifestyle it supports doesn’t have to shrink at all.

Have strategies that help stretch Social Security or creative ways to offset shrinking checks? Share your tips, stories, or insights in the comments below—let’s build a smarter, more vibrant retirement conversation together.

You May Also Like…

8 Mistakes That Can Trigger a Social Security Overpayment Notice

Waiting on Social Security? Why Thousands of Retirees Are Stuck in Payment Limbo Right Now

8 Hidden Fees That Can Eat Away at Your Retirement Savings

Is it Too Late at 45? How to Use the Mega Backdoor Roth to Dump Tens of Thousands into Retirement in One Year

Payment Delay Alert: Why Your January Social Security Deposit May Not Hit Your Account Today

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: social security Tagged With: budgeting, COLA, Cost of living, federal benefits, finances, Inflation, Planning, Retirement, seniors, Social Security, taxes

7 Expenses That Are Rising Faster Than Most People Expected

March 26, 2026 by Brandon Marcus Leave a Comment

7 Expenses That Are Rising Faster Than Most People Expected
Image Source: Pexels.com

The price of everyday life didn’t just creep up—it jumped, sprinted, and in some cases, practically launched into orbit. Some expenses grabbed headlines, sure, but others quietly picked up speed until they started draining wallets faster than expected. This isn’t just about big purchases or luxury splurges either. These increases hit right in the middle of daily routines, where habits meet reality and budgets start to feel tight.

Staying ahead of rising costs takes more than shrugging and hoping things level out. It requires attention, a bit of strategy, and a willingness to rethink what used to feel normal. Some of these price jumps come from global shifts, others from industry changes, and a few from simple supply and demand doing what it does best.

1. Grocery Bills That Refuse to Chill Out

Grocery prices no longer feel like a weekly inconvenience—they now feel like a full-on budgeting event. Fresh produce, dairy, and meat continue to climb in price, and even basic pantry staples no longer offer the same comfort they once did. Supply chain disruptions, higher transportation costs, and climate-related issues have all pushed prices upward in ways that don’t reverse overnight. Walking through a grocery store now requires more decision-making than ever before, especially when familiar items suddenly cost significantly more.

Smart shoppers now treat grocery trips like strategy sessions rather than casual errands. Planning meals ahead of time, comparing unit prices, and leaning into store brands can make a noticeable difference over the course of a month. Bulk buying works well for non-perishable items, but only when done with intention instead of impulse. Seasonal produce often comes with better prices and better quality, making it an easy win. Keeping an eye on flyers and digital coupons adds another layer of savings without much effort.

2. Housing Costs That Keep Climbing Higher

Housing doesn’t just take a chunk out of income—it often takes the biggest slice. Rent continues to rise in many areas, and homeownership comes with its own set of escalating costs, including property taxes, maintenance, and mortgage rates. Even those who locked in lower mortgage rates years ago now face higher insurance premiums and repair costs. The idea of “stable housing costs” feels less realistic than it once did, especially in fast-growing regions.

Adapting to rising housing expenses requires a mix of creativity and long-term thinking. Some households explore downsizing or relocating to more affordable areas, while others focus on maximizing their current space rather than upgrading. Renting out unused space or taking on a roommate can offset costs in a meaningful way. Keeping up with maintenance prevents small issues from turning into expensive problems later. Housing may remain expensive, but smart decisions can soften the impact.

7 Expenses That Are Rising Faster Than Most People Expected
Image Source: Pexels.com

3. Insurance Premiums That Quietly Surge

Insurance rarely grabs attention until renewal time rolls around—and that’s when the surprise hits. Auto insurance, home insurance, and even renters insurance have all seen noticeable increases. Repair costs, natural disasters, and higher claim payouts have forced insurers to adjust pricing across the board. That means even those with clean records and no claims still feel the pinch when premiums go up.

Staying proactive makes a big difference here. Shopping around for quotes every year often uncovers better deals, especially since loyalty doesn’t always lead to lower rates. Bundling policies can unlock discounts, and raising deductibles can reduce monthly premiums when handled carefully. Keeping a strong credit score and maintaining a claims-free history also help keep costs manageable. Insurance may feel like a fixed expense, but it still offers room for strategy.

4. Utility Bills That Spike Without Warning

Utility bills used to follow predictable patterns, but recent shifts have made them far less reliable. Electricity, heating, and water costs have all increased due to higher energy prices and infrastructure demands. Seasonal changes now bring sharper spikes, and extreme weather events push usage—and costs—even higher. Opening a bill no longer feels routine when the number at the bottom fluctuates so dramatically.

Reducing utility costs starts with awareness and small changes that add up quickly. Energy-efficient appliances and LED lighting lower consumption without sacrificing comfort. Smart thermostats allow for better control, especially during peak seasons. Sealing drafts and improving insulation keeps heating and cooling costs from spiraling. Even simple habits like unplugging unused electronics or running full loads of laundry can make a noticeable difference over time.

5. Dining Out That Costs More Than Just Convenience

Eating out used to feel like a small treat, but it now carries a much bigger price tag. Restaurants face higher food costs, increased wages, and rising overhead, and those costs show up directly on menus. Portions sometimes shrink while prices increase, creating a double hit for anyone who enjoys dining out regularly. Even quick-service options no longer offer the same affordability they once did.

Cutting back doesn’t mean giving up the experience entirely. Choosing lunch over dinner often brings lower prices for the same quality. Sharing dishes or skipping extras like drinks and desserts keeps bills manageable without sacrificing enjoyment. Takeout can sometimes cost less than dining in, especially when service fees and tips factor in. Cooking at home more often and treating dining out as a planned event rather than a habit can restore balance.

6. Travel Expenses That Stretch Every Budget

Travel has bounced back in a big way, and prices have followed right behind. Flights, hotels, and rental cars have all become more expensive due to high demand and limited availability. Even smaller costs like baggage fees and resort charges add up quickly. The idea of a spontaneous getaway now requires more planning and flexibility than ever before.

Savvy travelers adapt by shifting how and when they book. Traveling during off-peak seasons often brings significant savings, along with fewer crowds. Booking flights midweek instead of weekends can reduce costs, and using fare comparison tools helps track deals. Loyalty programs and credit card rewards offer real value when used strategically. Planning ahead doesn’t just save money—it also opens up better options.

7. Healthcare Costs That Continue to Climb

Healthcare remains one of the most unpredictable and steadily rising expenses. Insurance premiums, prescription medications, and out-of-pocket costs all contribute to the upward trend. Even routine visits can feel expensive without proper coverage, and unexpected medical needs can disrupt even the most carefully planned budget. The complexity of healthcare pricing adds another layer of frustration.

Taking control of healthcare expenses requires a proactive approach. Preventative care often costs less than treatment later, making regular checkups a smart investment. Comparing prescription prices across pharmacies can uncover surprising differences. Health savings accounts provide a tax-advantaged way to prepare for future expenses. Asking questions about billing and exploring payment plans can also ease financial pressure when larger costs arise.

Staying Ahead of the Cost Curve

Rising expenses don’t follow a single pattern, and they rarely slow down all at once. Each category brings its own challenges, and together they create a financial landscape that demands attention and adaptability. Ignoring the changes only makes them harder to manage, while small, consistent adjustments can create a sense of control. Awareness turns frustration into action, and action builds resilience over time.

Which of these rising expenses has hit you the hardest, and what strategies have made the biggest difference in keeping things under control? Share thoughts, ideas, or even creative money-saving wins in the comments.

You May Also Like…

Alaska’s Eye-Popping Healthcare Costs — Planning for Higher Medical Expenses

2.4% Inflation Rate and Its Quiet Impact on Everyday Costs

7 Steps to Run a Financial Autopsy on Your 2025 Spending

9 Expenses That Used to Be Optional but Aren’t Anymore

Savings Fallout: 4 Hidden Expenses That Quietly Drain Retirement Budgets

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Smart Spending Tagged With: Budgeting Tips, Cost of living, groceries, healthcare expenses, Housing Costs, Inflation, insurance rates, Personal Finance, Planning, rising expenses, travel costs, utilities

The “One Dollar Over” Rule — How a Small Income Increase Can Cost You Thousands

March 26, 2026 by Brandon Marcus Leave a Comment

The “One Dollar Over” Rule — How a Small Income Increase Can Cost You Thousands
Image Source: Unsplash.com

A single extra dollar can flip the script on an entire financial year. That sounds dramatic, but it lands squarely in reality once income thresholds enter the picture. Governments design benefits, tax credits, and subsidies with hard cutoffs or gradual phase-outs, and those rules don’t care how hard someone worked for that extra income. Cross the wrong line, and suddenly a raise starts to look like a penalty instead of a reward. The math doesn’t lie, and it doesn’t always feel fair.

Picture a situation where a raise should spark celebration, but instead triggers a quiet financial headache that stretches across months. That small bump in income nudges earnings past a critical threshold, and a cascade begins: benefits shrink, credits disappear, and tax obligations climb higher than expected. What looked like progress starts to feel like a step sideways—or even backward.

The Threshold Trap That Changes Everything

Income thresholds sit at the heart of many tax systems and benefit programs, and they carry far more weight than they appear to at first glance. Governments often create programs with eligibility cutoffs, meaning a specific income level determines whether someone qualifies for financial help or not. These thresholds don’t always phase out gently, and in some cases, they drop off sharply, creating what economists call a “cliff effect.” That means earning just a little more money can result in losing access to valuable benefits entirely, rather than gradually.

This effect shows up in real-world programs like childcare subsidies, housing assistance, student aid, and tax credits. A person who earns just below a threshold might receive thousands in support, while someone who earns slightly above it may receive nothing at all. That creates a strange imbalance where two people with nearly identical incomes end up in completely different financial positions. The system rewards staying under the line in some cases, which feels counterintuitive in a world that celebrates earning more. The structure doesn’t punish ambition directly, but it can certainly make financial progress feel complicated and frustrating.

The psychological impact adds another layer to this issue, because people expect raises to improve their situation across the board. Instead, they sometimes face reduced net income after losing benefits, which feels like a betrayal of effort. That disconnect between expectation and reality leads to confusion and poor financial decisions. Without a clear understanding of thresholds, many people accept raises or extra work without realizing the full consequences. Knowledge becomes the key advantage here, because awareness allows for smarter planning and better timing of income changes.

Why More Money Doesn’t Always Mean More Money

The idea that higher income automatically leads to better financial outcomes sounds logical, but thresholds disrupt that assumption in surprising ways. Taxes alone rarely cause the problem, because most tax systems use progressive brackets that only tax additional income at higher rates rather than the entire income. The real issue emerges when benefits and credits disappear alongside higher earnings, creating a combined effect that feels like a steep financial drop.

Imagine someone earning just under the limit for a childcare subsidy worth several thousand dollars per year. A modest raise pushes income slightly over that limit, and suddenly that subsidy disappears. The raise might add a few hundred dollars annually, but the lost benefit removes far more than that. The result leaves the person worse off despite technically earning more, which creates a frustrating and often overlooked financial paradox. That scenario plays out more often than many people realize, especially in systems with rigid eligibility rules.

Timing also plays a major role in how this plays out, because annual income calculations often determine eligibility. A bonus, overtime, or freelance income can unexpectedly push earnings past a threshold even if base salary stays the same. That means even temporary income increases can trigger long-term financial consequences. Strategic planning becomes essential, because understanding when and how income counts can help avoid crossing a costly line at the wrong moment. A little foresight can protect thousands of dollars that might otherwise disappear without warning.

The Fine Print That Nobody Talks About

Many financial guides focus heavily on taxes, but they often skip over the fine print tied to benefits and credits. That gap leaves people unprepared for the real-world impact of crossing income thresholds. Government programs frequently include complex rules that determine eligibility, phase-outs, and reporting requirements, and those details don’t always appear front and center. Instead, they sit buried in policy documents that most people never read.

This lack of visibility creates a major problem, because people make financial decisions without complete information. A raise, a second job, or a side hustle might seem like a clear win, but the hidden rules can shift the outcome dramatically. Financial advisors often emphasize gross income, but net outcomes matter far more in these situations. Without considering the full picture, people risk making choices that unintentionally reduce their overall financial position.

Clarity changes everything here, and simple awareness can prevent costly mistakes. Taking time to review eligibility rules for key benefits can reveal where thresholds sit and how they operate. Many programs offer gradual phase-outs instead of hard cutoffs, but others still rely on strict limits that create sudden losses. Understanding which type applies makes a huge difference in planning. Knowledge doesn’t eliminate the problem, but it turns a hidden trap into a manageable challenge.

Smart Moves to Stay Ahead of the Line

Avoiding the negative effects of the “one dollar over” rule doesn’t require extreme measures, but it does demand a thoughtful approach. One of the most effective strategies involves timing income carefully, especially when bonuses or additional earnings come into play. Deferring income to a different tax year, when possible, can help keep total earnings below a critical threshold. That approach works particularly well for freelancers or those with flexible compensation structures.

Another powerful tactic involves using deductions and tax-advantaged accounts to reduce taxable income. Contributions to retirement accounts, health savings accounts, or similar programs can lower reported income and help maintain eligibility for benefits. This strategy doesn’t just protect access to programs; it also builds long-term financial security, which creates a double advantage. Small adjustments in how income gets reported can make a significant difference in overall financial outcomes.

Communication also plays a crucial role, especially when employers offer flexible compensation options. Some workplaces allow employees to adjust how and when they receive bonuses or other forms of income, which opens the door for strategic planning. Understanding these options and using them effectively can prevent unintended consequences. Financial planning doesn’t need to feel overwhelming, but it does require attention to detail and a willingness to look beyond surface-level numbers.

The “One Dollar Over” Rule — How a Small Income Increase Can Cost You Thousands
Image Source: Pexels.com

Winning Comes From Knowing the Rules

The “one dollar over” rule doesn’t exist as an official policy, but its impact shows up in real financial outcomes every single year. Income thresholds, benefit cutoffs, and eligibility rules shape financial realities in ways that don’t always align with expectations. That doesn’t make the system broken, but it does make it complex enough to require attention and strategy. The difference between losing money and keeping it often comes down to awareness and planning.

What strategies have worked when dealing with income thresholds, or what surprises have popped up along the way? Drop thoughts, experiences, or even lessons learned in the comments and keep the conversation going.

You May Also Like…

Why a $100K Salary Feels Like $40K in 2026

Arizona’s Rising Cost of Living — What $100K Buys in Phoenix Today

Zelle and Instant Payments Are Facing New Scrutiny—Here’s What Users Are Seeing

Why Monthly Bills Are Rising Even for Households That Haven’t Changed Spending

Why Does Spending Turn A Dream Vacation Into A Nightmare?

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Personal Finance Tagged With: Budgeting Tips, financial literacy, government benefits, income strategy, income thresholds, money mistakes, Personal Finance, Planning, tax brackets, tax credits, taxes, Wealth Building

5 Phone Calls You Should Never Return — Even If They Sound Urgent

March 26, 2026 by Brandon Marcus Leave a Comment

5 Phone Calls You Should Never Return — Even If They Sound Urgent
Image Source: Pexels.com

The phone rings, and suddenly everything feels urgent. A missed call flashes on the screen with a warning tone in the voicemail or a number that looks oddly official, and the instinct kicks in to fix whatever problem might be brewing. That sense of urgency feels powerful, almost impossible to ignore, and it pushes people to act fast instead of thinking things through. Scammers count on that exact reaction, because speed and panic make people easier to manipulate. One quick callback can open the door to losing money, personal information, or even control of important accounts. That single moment of curiosity or concern can turn into a costly mistake that lingers far longer than the call itself.

Plenty of calls deserve attention, but some absolutely do not deserve a return call under any circumstances. The tricky part comes from how convincing these calls sound, because they often mimic real institutions, real emergencies, or real opportunities that feel too important to ignore. Modern scam tactics rely on technology that masks phone numbers, imitates voices, and creates believable scenarios that fool even careful people.

1. The “One-Ring” Trap That Hooks You Fast

A missed call that rings once and disappears might seem harmless, but it often signals a well-known scam designed to get a callback. Scammers use automated systems to dial thousands of numbers and hang up almost immediately, leaving behind a tempting mystery. That curiosity pushes people to return the call, especially when the number looks unfamiliar or international. Once someone calls back, the scam kicks into gear through premium-rate numbers that charge high fees per minute. These charges can pile up quickly without any clear warning, leaving a shocking phone bill behind. The scam works because it feels so simple and innocent, and that simplicity masks the financial damage it can cause. A quick callback turns into a costly mistake that feels completely avoidable in hindsight.

The best move here involves ignoring the urge to investigate and resisting the temptation to call back unknown numbers entirely. If a call truly matters, the caller will leave a detailed message with clear identification and a legitimate reason to respond. Searching the number online can also reveal whether others have reported it as suspicious or linked it to scams.

Phone carriers and apps now offer spam detection features, and enabling those tools adds another layer of protection. Staying cautious about unfamiliar international numbers also helps, especially when no clear connection exists to that location. A missed call might spark curiosity, but curiosity should never outweigh caution when money sits on the line.

2. The Fake “Government Emergency” That Demands Immediate Action

Some calls come packed with urgency, claiming that a government agency needs immediate attention or that a serious issue requires instant action. These calls often mention unpaid taxes, legal trouble, or benefits that face suspension, and they rely heavily on fear to push people into reacting quickly. The caller may sound authoritative, using official-sounding language and even spoofed phone numbers that appear legitimate at first glance. That combination of urgency and authority creates a powerful sense of pressure that makes people act without verifying the situation. Scammers know that fear short-circuits logic, and they lean into that emotional response to keep control of the conversation. A callback gives them exactly what they want: engagement and a chance to escalate the scam.

Real government agencies do not operate this way, and they do not demand immediate payment or personal information over the phone without prior official communication. Anyone receiving a message like this should avoid calling back directly and instead look up the agency’s official contact information independently. Calling a verified number ensures that any conversation happens with a legitimate representative instead of a scammer. Staying calm and refusing to rush into action makes a huge difference, because urgency often signals manipulation rather than reality. Keeping personal information private and never sharing sensitive details over unsolicited calls also blocks many common scam tactics. A moment of patience can prevent a situation from spiraling into something far more serious.

3. The “Bank Alert” That Isn’t From Your Bank

Few things grab attention faster than a message about suspicious activity on a bank account, and scammers take full advantage of that reaction. A voicemail or missed call might claim that unauthorized transactions occurred, urging a quick callback to secure the account. The message often sounds polished and professional, sometimes even including partial account details to appear more convincing. That sense of urgency pushes people to act immediately, especially when money feels at risk. Once the callback happens, scammers guide the conversation toward gathering login credentials, PINs, or verification codes. That information gives them direct access to accounts, turning a fake alert into a real financial problem.

Handling these situations requires a deliberate shift in approach, because calling back the number provided creates unnecessary risk. Instead, checking the account directly through an official app or website provides accurate information without involving a third party. Contacting the bank using a verified number printed on a card or official statement ensures a safe connection. Financial institutions already encourage this habit, and following it protects against many common scams. Staying skeptical about unsolicited alerts also helps, especially when the message pressures immediate action. A real bank prioritizes security and clarity, while a scammer prioritizes speed and confusion.

4. The “Prize or Package” Call That Sounds Too Good to Miss

Excitement can feel just as powerful as fear, and scammers know exactly how to tap into that energy. A missed call or voicemail might claim that a prize awaits or that a package requires confirmation before delivery. These calls often create a sense of urgency by suggesting that the opportunity will disappear without quick action. That pressure pushes people to call back, hoping to claim something valuable or resolve a delivery issue. Once the connection happens, scammers may ask for personal details, payment for fees, or verification information that leads to identity theft. The initial excitement quickly fades when the consequences start to unfold.

Staying grounded and questioning the legitimacy of unexpected offers helps prevent falling into this trap. Legitimate companies do not require payment or sensitive information just to claim a prize or receive a package. Checking tracking numbers directly through official shipping websites provides accurate updates without relying on unknown callers. Ignoring unsolicited prize notifications also removes the temptation to engage with potential scams.

5. The “Tech Support Panic” Call That Creates Chaos

Technology issues can feel overwhelming, and scammers exploit that confusion with fake tech support calls. A voicemail or missed call might claim that a device has been compromised or that immediate action is needed to prevent damage. The message often includes alarming language that suggests viruses, hacking attempts, or data breaches. That sense of panic pushes people to call back quickly, hoping to fix the problem before it gets worse. Once connected, scammers may request remote access to devices or ask for payment to resolve the issue. That access gives them control over personal files, accounts, and sensitive information, turning a fake problem into a real one.

Avoiding these scams requires a clear understanding of how legitimate tech companies operate. Reputable companies do not initiate unsolicited calls about device issues, and they do not request remote access without a verified support request. Running antivirus software and keeping systems updated provides real protection without relying on unknown callers. Seeking help directly through official support channels ensures that any assistance comes from trusted sources.

5 Phone Calls You Should Never Return — Even If They Sound Urgent
Image Source: Unsplash.com

Let Suspicion Win Every Time

Every one of these calls shares a common thread: urgency designed to override good judgment. That urgency might come from fear, excitement, or confusion, but it always pushes for quick action without verification. Slowing down and questioning the situation creates a powerful defense against scams that rely on emotional reactions. Ignoring suspicious calls and refusing to return unknown numbers removes the opportunity for scammers to gain a foothold. Technology continues to evolve, and scammers adapt quickly, but a cautious mindset remains one of the strongest protections available. Taking control of how and when to respond keeps personal information and finances secure.

What strategies work best for handling suspicious calls, and which types of messages raise the biggest red flags? Share your thoughts, experiences, or tips in the comments and keep the conversation going.

You May Also Like…

7 New Scam Tactics That Look Real — And Are Still Fooling Americans

Is Quality Furniture Officially a Scam? Why Filling a New Home in 2026 is Destroying Senior Nest Eggs

8 Subtle Illusions Used by Scammers in Investment Offers

6 Elder Scams That Began Over the Phone Earlier This Year

10 Quiet Retirement Scams Targeting Women Who Just Got Divorced

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: scams Tagged With: consumer safety, cybersecurity, fraud prevention, identity theft, personal finance safety, phishing, phone safety, phone scams, robocalls, scam awareness, scam calls, tech tips

The IRS Is Sending More “Math Error” Notices — Why You Could Owe Without Realizing It

March 26, 2026 by Brandon Marcus Leave a Comment

The IRS Is Sending More “Math Error” Notices — Why You Could Owe Without Realizing It
Image Source: Shutterstock.com

A letter from the IRS doesn’t need flashing red lights to feel urgent, and lately, more of those letters arrive stamped with a deceptively simple phrase: “math error.” That label sounds harmless, almost like a quick fix, but it often carries a financial sting that catches people off guard. The number of these notices has climbed in recent years, and they don’t just target complicated returns or high earners. They hit everyday tax filers who thought they checked every box correctly and walked away confident.

These notices don’t wait for a full audit, and that’s exactly what makes them so disruptive. The IRS uses automated systems to flag discrepancies, adjust returns, and send out corrections before anyone has time to react. One small mismatch can turn into a reduced refund or even a balance due, and the clock starts ticking the moment that notice lands.

When “Math Error” Doesn’t Mean What You Think It Means

The phrase “math error” sounds like someone added numbers wrong, but the IRS uses it far more broadly than that. The agency applies this label to a wide range of issues, including missing information, mismatched Social Security numbers, and incorrect claims for credits like the Earned Income Tax Credit or Child Tax Credit. That means a notice could arrive even when every calculation on the return adds up perfectly. The system flags inconsistencies between what someone reported and what the IRS has on file, often pulling data from employers, financial institutions, and prior filings.

This automated approach speeds things up, but it also removes the human layer that might otherwise catch context. For example, a slight typo in a dependent’s Social Security number can trigger a rejection of a credit, which then leads to a reduced refund or a sudden balance due. The IRS doesn’t ask for clarification before making the change, and it sends the notice after the adjustment already happens. That creates a jarring moment where expectations collide with reality, especially when someone counted on a refund for bills or savings.

The rules behind these notices come from the IRS’s authority to correct certain “obvious” errors without launching a full audit. That sounds efficient, but it leaves little room for nuance. Many people don’t realize that they have only a limited window, usually 60 days, to respond if they disagree with the change. Ignoring the notice can lock in the adjustment and open the door to penalties and interest. Taking it seriously right away gives the best chance to fix the issue before it snowballs.

Why These Notices Are Showing Up More Often

The rise in math error notices doesn’t come out of nowhere, and a few key factors drive the trend. The IRS has leaned more heavily on automation, especially as it processes large volumes of returns quickly. Technology allows the agency to cross-check data at scale, which increases the chances of catching discrepancies, even minor ones. At the same time, tax laws have shifted in recent years, especially around credits and stimulus-related provisions, and those changes have added layers of complexity to otherwise simple returns.

More complexity creates more room for error, and not all of those errors come from carelessness. Some stem from confusion about eligibility rules, especially for credits tied to income thresholds, filing status, or dependent qualifications. A slight misunderstanding can lead to a claim that doesn’t match IRS records, and the system flags it immediately. The IRS then adjusts the return without waiting for clarification, which leads to a notice that feels sudden and unexpected.

Another factor comes from timing. Employers and financial institutions submit forms like W-2s and 1099s directly to the IRS, and any mismatch between those records and what appears on a return triggers a red flag. Even something as simple as entering the wrong income figure by a small amount can set off the system. The combination of real-time data matching and automated corrections means fewer discrepancies slip through unnoticed, but it also means more notices land in mailboxes.

Smaller Refunds or Surprise Bills

A math error notice doesn’t just point out a problem; it changes the outcome of a tax return. The IRS can reduce a refund, delay it, or convert it into a balance due, depending on the situation. That shift can disrupt plans in a big way, especially when someone expects a certain amount and suddenly sees a different number. The notice explains the adjustment, but it doesn’t always feel clear at first glance, which adds to the confusion.

When the IRS reduces or eliminates a credit, the financial impact can feel immediate. Credits like the Earned Income Tax Credit or Child Tax Credit can significantly boost a refund, so losing them changes the bottom line quickly. If the adjustment creates a balance due, interest and penalties can start accruing if the amount isn’t paid on time. That turns a simple correction into a growing obligation that demands attention.

The emotional impact matters too, even if it doesn’t show up on a balance sheet. A notice from the IRS can create stress and uncertainty, especially when it arrives without warning. The key lies in shifting from reaction to action, because these notices often come with clear next steps. Reading the notice carefully, comparing it to the original return, and gathering any supporting documents can bring clarity and control back into the situation.

The IRS Is Sending More “Math Error” Notices — Why You Could Owe Without Realizing It
Image Source: Shutterstock.com

What To Do If That Letter Shows Up

Opening the notice and setting it aside might feel tempting, but that approach can make things worse. The IRS includes a specific explanation of what changed and why, and understanding that explanation should come first. Comparing the notice to the original return helps identify whether the IRS made a valid correction or missed something important. That step alone can reveal simple issues like a typo or a missing form.

If the correction looks accurate, paying the balance or accepting the reduced refund resolves the issue quickly. If something doesn’t add up, responding within the allowed timeframe becomes critical. The IRS usually provides instructions for disputing the change, and that process often involves sending documentation that supports the original filing. Acting within the deadline preserves the right to challenge the adjustment and prevents it from becoming final.

Getting help can make a big difference, especially when the notice involves credits or eligibility rules. A tax professional can review the situation, spot errors, and guide the response. Keeping organized records, including W-2s, 1099s, and receipts, strengthens any case and speeds up the resolution. Taking these steps turns a stressful moment into a manageable task, and it prevents the issue from escalating.

Don’t Let a “Math Error” Catch You Off Guard

A math error notice might sound minor, but it carries real financial weight and demands quick attention. The IRS uses that label to cover a wide range of issues, and the rise in these notices reflects a system that moves faster and checks more data than ever before. Taking the time to understand how these notices work can prevent confusion and protect against unexpected bills or reduced refunds. Staying organized, double-checking details, and responding quickly to any notice can turn a frustrating situation into a manageable one.

What steps feel most helpful when it comes to avoiding surprises at tax time, and what strategies have worked best for keeping everything accurate and stress-free? Share all of your thoughts, tips, or experiences in the comments and keep the conversation going.

You May Also Like…

Refunds Are Being Delayed Over New IRS Identity Flags — Why More Returns Are Getting Pulled

7 Common Deductions That Are Getting More Scrutiny From the IRS

IRS Changes for Seniors: What’s Actually New on the 1040‑SR for 2026

6 Advanced Techniques to Lower Your Capital Gains Taxes Legally

9 Financial Dangers of Ignoring Property Taxes

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: tax tips Tagged With: audit risk, credits, IRS, IRS letters, math error notice, Personal Finance, tax debt, tax filing mistakes, tax refund, tax season, tax tips, taxes

6 Income Thresholds That Can Trigger Higher Medicare Premiums

March 25, 2026 by Brandon Marcus Leave a Comment

6 Income Thresholds That Can Trigger Higher Medicare Premiums
Image Source: Shutterstock.com

Medicare sounds simple at first glance: sign up, get coverage, pay your premium, and move on. But your income can suddenly start working against you. Not just a little, but enough to make your monthly premium feel like a full-blown bill shock. The reality is that Medicare has income-related adjustments that can hit some participants hard, and knowing exactly where those thresholds lie is crucial to staying ahead. If your earnings are just a tad higher than the federal limits, you could end up paying hundreds more every month.

Before panic sets in, it’s worth understanding how these income thresholds actually work. The government looks at your tax filings from two years prior to determine whether you’ll pay more than the standard Medicare premiums. This isn’t just about bragging rights on income statements; it directly impacts what comes out of your pocket for Part B and Part D. And these thresholds aren’t random. They’re designed to scale premiums so higher earners contribute more, but if your finances aren’t planned carefully, the “gradual” part can feel like a slap in the face.

1. When $103,000 Becomes a Price Tag

For single filers, $103,000 is the first line in the sand. Cross it, and Part B premiums start climbing thanks to IRMAA, the Income-Related Monthly Adjustment Amount. Couples filing jointly hit the same adjustment at $206,000. This first jump isn’t catastrophic, but it’s enough to get your attention—especially if you weren’t expecting it.

The smart move is to anticipate these bumps before they hit. Reviewing taxable investments, retirement withdrawals, and the timing of Social Security benefits can make a real difference. Adjusting these factors a year or two ahead can save hundreds over time. Staying aware of income levels, especially as retirement plans unfold, is far better than reacting to a surprise invoice.

2. $129,000 and the Next Step Up

Once single filers cross $129,000—or $258,000 for joint filers—the adjustments get more noticeable. This is where Medicare premiums start to feel like a real line item rather than a background cost. Part D premiums also rise at this point, doubling the impact.

Proactive planning becomes essential. Strategic Roth conversions, spacing out withdrawals, and revisiting taxable accounts can help keep income below the line. Working with a tax professional who understands retirement planning can turn these thresholds from landmines into manageable markers. Predictability is the goal, and smart planning keeps premiums from spiraling.

3. $161,000: The Middle Ground Premium Spike

At $161,000 for singles and $322,000 for couples, the adjustment becomes tangible. This isn’t a minor uptick—it’s a meaningful monthly expense that can throw off retirement budgets if ignored. Both Part B and Part D premiums rise again, and the bite becomes harder to ignore.

This is the moment to reassess investments that generate taxable gains, explore charitable deductions, or rethink bonus or freelance income. Even small adjustments can keep you under a threshold. With careful planning, the sting of these premiums can be softened, keeping more money in your accounts while maintaining full coverage.

4. $193,000 and the High-Income Territory

This threshold for single filers—and $386,000 for couples—is where Medicare adjustments start feeling like a major financial factor. Premiums jump sharply, reflecting the policy that higher earners pay more for their coverage. At this level, the difference between careful planning and reactive scrambling becomes painfully clear.

Managing income here requires a multi-layered approach. Timing retirement account distributions, tax-loss harvesting, and adjusting asset allocation can all help. Couples can also benefit from smart income-splitting strategies. Staying aware of income levels throughout the year transforms a potentially painful premium hike into a manageable adjustment.

6 Income Thresholds That Can Trigger Higher Medicare Premiums
Image Source: Shutterstock.com

5. $500,000+: Premiums Hit the Stratosphere

Once income passes $500,000 for singles—or $750,000 for couples—IRMAA hits its top tier. Medicare doesn’t just nudge premiums here; it pushes them into a dramatically higher bracket. At this point, you’re looking at some of the highest monthly premiums Medicare offers.

This is where advanced planning becomes essential. Carefully timed Roth conversions, philanthropic giving, and reviewing all taxable income sources can help reduce spikes. High earners benefit from working with advisors who specialize in retirement tax strategy. Even at this level, smart planning can reduce the sting.

6. The Top Tier: No Higher Bracket, Just Higher Stakes

Beyond these levels, there isn’t another IRMAA bracket—this is the ceiling. But that doesn’t mean the stakes disappear. Once you’re in the top tier, even small changes in income can affect how long you stay there. This is the zone where timing, deductions, and strategic planning matter more than ever.

Coordinating tax planning, charitable contributions, and income timing pays off. Even small missteps can trigger large premium increases, making ongoing attention essential. Understanding how these thresholds work turns a seemingly intimidating system into a manageable plan.

Mastering Medicare Premiums Without Breaking a Sweat

These six income thresholds show that Medicare premiums aren’t fixed—they flex with your financial life. By understanding where these thresholds lie and planning carefully, it’s possible to reduce or even avoid surprise premium increases. Adjusting income timing, using tax-advantaged accounts, and leveraging charitable deductions all play a role. Awareness plus proactive planning equals more predictable healthcare costs. It’s not about restricting income; it’s about managing it strategically so Medicare stays manageable and retirement funds stay healthy.

Have thoughts on creative strategies for handling Medicare premiums? Tried any clever planning tricks or adjustments that worked? Share your ideas or stories in the comments—other readers will appreciate the insight.

You May Also Like…

From Medicare to Medicaid: Why Billing Glitches Are Causing Unexpected Medical Bills Nationwide

More Retirees Are Seeing Higher Medicare Costs—And It’s Tied to Income From Years Ago

The 2026 Medicare Premium Shock: Why Your Part B Bill Just Jumped by 9.7%

The COLA Theft: Why Half of Your Social Security Raise Just Vanished into Medicare This Morning

7 Financial Medicare Mistakes to Avoid

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Personal Finance Tagged With: health insurance, healthcare costs, income planning, IRMAA, Medicare, Medicare Part B, Medicare Part D, Planning, premiums, Retirement, senior finance, senior savings, Social Security

Retirement Healthcare Costs Are Climbing Again — What the Average Couple Now Needs

March 25, 2026 by Brandon Marcus Leave a Comment

Retirement Healthcare Costs Are Climbing Again — What the Average Couple Now Needs
Image Source: Unsplash.com

You might think retirement means cocktails, sunshine, and guilt‑free naps. But there’s another number lurking in the background that’s as important as any beach house or bucket list trip: healthcare costs. And right now those numbers are creeping upward again, faster than many people would like to admit. Since medical costs for older Americans have consistently outpaced general inflation for decades, retirement healthcare isn’t just a small line item—it’s one of the biggest chunks of a nest egg most couples will face.

So let’s get real: if a couple dreams of a comfortable retirement without financial stress, they need to know how much healthcare will cost, what Medicare actually covers (spoiler: not everything), and how to craft a strategy that doesn’t leave them eating instant oatmeal for the rest of their lives.

The Shocking Numbers Behind Healthcare in Retirement

The raw numbers might make you raise your eyebrows—or even snort your coffee. According to the latest estimates, a 65‑year‑old couple retiring today can expect to spend around hundreds of thousands on healthcare costs over the course of their retirement. That’s not insurance premiums alone, but the total tab for medical care, copays, deductibles, prescriptions, and other out‑of‑pocket expenses.

Think about that for a moment. That number exists before factoring in major care needs or long‑term services like assisted living, which Medicare barely touches. Even if you’re healthy and optimistic, medical costs tend to rise as people age, and health inflation has historically outstripped general inflation. That means your $1,000 doctor’s bill today could easily be $1,500 in a few short years.

Medicare helps, of course, but it’s not a golden ticket. It covers hospitalization, doctor visits, and basic prescription coverage—but it doesn’t kick in until age 65, and it leaves plenty of gaps in coverage. Dental care, vision, hearing aids, long‑term care, and many routine services simply aren’t part of the package. That’s where retirees often feel like they’re constantly filling holes in a leaky bucket

Then there’s the unpredictable stuff: a health scare, an unexpected surgery, chronic conditions that require medication year after year. Those costs add up quickly and sometimes without warning. Planning for the big stuff and the small stuff is smart—because ignoring it won’t make the bills go away.

Understanding Medicare (and What It Really Covers)

Let’s demystify Medicare because most people assume it’s “free healthcare for seniors,” and that’s just not accurate. The program consists of multiple parts, each with its own costs and caveats. Original Medicare Part A handles hospital stays, and Part B covers doctor visits and outpatient services—but both require premiums. There’s also Part D for prescription drugs, with its own premium and cost‑sharing obligations.

Then there’s the whole world of supplemental coverage. Medicare Advantage plans bundle Parts A, B, and usually D together, often with lower premiums but tighter provider networks. Medigap plans—also called Medicare Supplement Insurance—can help pick up what Original Medicare leaves behind, such as copayments, coinsurance, and deductibles. But these policies come with their own monthly premiums.

So when planners say Medicare “covers most expenses,” they really mean it covers some major categories, while you’re left juggling the rest. And those premiums and gaps can make the total cost of healthcare over retirement surprisingly large. That’s why many financial professionals suggest factoring Medicare premiums, supplemental policies, out‑of‑pocket costs, and expected health needs into your long‑term budget early—because guessing wrong could mean dipping deep into your savings to cover surprise bills.

Don’t Forget Long‑Term Care

If healthcare costs are the elephant in the room, long‑term care is the entire herd. Medicare provides only limited coverage for skilled nursing or rehab after a hospital stay, but it does not cover ongoing custodial care—like help with bathing, dressing, or daily supervision. And that’s exactly what many retirees end up needing.

Consider this: a private room in a skilled nursing facility can easily exceed $115,000 per year, while assisted living costs often hover around $70,000 or more. If you or your spouse needs in‑home care, even a few hours a day can add up to tens of thousands of dollars annually. These aren’t fringe expenses—they’re very real possibilities for a large portion of retirees.

Because Medicare leaves this major gap, planning ahead matters. Long‑term care insurance can help cover a portion of these costs, but policies are most affordable when purchased at younger ages—usually in your 50s or early 60s. For some couples, building a dedicated care fund or considering hybrid life‑insurance policies with long‑term care riders can soften the financial blow. Ignoring this huge category because it’s uncomfortable to think about today could turn into a retirement nightmare tomorrow.

Retirement Healthcare Costs Are Climbing Again — What the Average Couple Now Needs
Image Source: Unsplash.com

Smart Moves to Lower Retirement Healthcare Burdens

Okay, now for the good news: there are ways to get ahead of these costs instead of watching them swallow your retirement savings. First up, consider using tax‑advantaged accounts like Health Savings Accounts while you’re still working. These triple‑tax‑advantaged vehicles let you stash money pre‑tax, grow it tax‑free, and withdraw it tax‑free for qualified medical expenses—including Medicare premiums and other out‑of‑pocket costs later in life.

Another strategy involves actively reviewing your Medicare options each year during open enrollment. Plans change, premiums change, and what worked last year might not be the best fit next year. Doing a yearly check‑in and comparing Medigap, Medicare Advantage, and Part D options could save you hundreds or even thousands annually. It’s a little work now for a lot less stress later.

Living a healthier lifestyle today can also pay off later. Regular exercise, balanced nutrition, and preventive care not only improve quality of life—they can reduce the frequency and severity of expensive health events down the line. While you can’t control everything, taking charge of what you can influence often pays dividends in both enjoyment and cost savings.

What the Numbers Should Make You Do

If you and your partner want to retire without healthcare costs gnawing away at your budget, you can’t ignore the numbers. Set realistic expectations, build a healthcare savings plan, and remember that Medicare is a foundation—not a full safety net. Expect to spend hundreds of thousands of dollars on medical care in retirement, and plan accordingly. Even if that sounds like a lot, treating it like a key part of your retirement plan—not an afterthought—will drastically improve your financial confidence in your later years.

What strategies have worked for you? Are you saving with an HSA, eyeing long‑term care insurance, or thinking about lifestyle moves to stretch your retirement dollars? Drop your thoughts, ideas, or stories of savvy planning (or happy mistakes!) in the comments below.

You May Also Like…

8 Hidden Fees That Can Eat Away at Your Retirement Savings

More Retirees Are Seeing Higher Medicare Costs—And It’s Tied to Income From Years Ago

Is it Too Late at 45? How to Use the Mega Backdoor Roth to Dump Tens of Thousands into Retirement in One Year

The Retirement Honeymoon Phase — Planning for Years 1 and 2

Utah’s $7,522 Healthcare Annual Cost And What It Means for Residents

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Retirement Tagged With: aging expenses, health savings accounts, healthcare inflation, Long-term care, Medicare Advantage, Medicare costs, Medigap, Planning, retirement budgeting, retirement healthcare, retirement planning, senior health

7 Financial Transactions That Could Be Reported Without You Realizing It

March 25, 2026 by Brandon Marcus Leave a Comment

7 Financial Transactions That Could Be Reported Without You Realizing It
Image Source: Pexels.com

We all know that money moves faster than gossip, and some of your financial transactions might already be under the microscope without you even knowing. Every swipe, transfer, and deposit has the potential to catch the attention of regulators, banks, or the IRS. Most people think only massive transfers ring alarm bells, but the reality is far more nuanced. Financial institutions must file certain reports to comply with laws, and those reports can include transactions that seem mundane.

Awareness isn’t just about avoiding trouble—it’s about making smarter choices and staying in control. From large cash deposits to frequent wire transfers, some routine financial activities might be reported automatically. Even digital payments can trigger reports under specific thresholds or patterns. The key is knowing what falls under the radar, why it matters, and what proactive steps can help keep everything above board.

1. Big Cash Deposits: When Your Wallet Makes Headlines

Dropping thousands of dollars in cash at your bank might feel like a private victory, but the government has a keen eye on this type of movement. Any cash deposit over $10,000 triggers a Currency Transaction Report (CTR), which goes straight to the Financial Crimes Enforcement Network (FinCEN). Banks have to report this to comply with anti-money laundering laws. Even structured deposits just under the $10,000 mark, if repeated, can catch attention through Suspicious Activity Reports (SARs). The IRS uses these reports to monitor unusual cash inflows, making it essential to understand limits.

It’s not just about large sums. A series of smaller deposits might look innocent but can appear as an attempt to avoid reporting, a practice known as structuring. Banks monitor accounts for these patterns and may file a SAR if they detect suspicious behavior. To avoid unnecessary headaches, maintain records of large transactions and be transparent with your bank if you expect frequent big deposits. Planning ahead and communicating with your financial institution helps keep transactions smooth, compliant, and stress-free. This knowledge empowers smarter financial decisions, avoiding unintended attention.

2. Wire Transfers: The Digital Fingerprints

Sending money electronically seems quick and effortless, but wire transfers leave detailed trails. Financial institutions must report certain domestic and international wire transfers. These records include sender and recipient information, creating a paper trail that regulators can follow if needed. International transfers can also trigger additional reporting requirements under the Bank Secrecy Act, making transparency critical for cross-border transactions.

Even small transfers can attract scrutiny if patterns suggest unusual activity. Repeated high-volume transfers or payments to unfamiliar accounts may prompt banks to file a Suspicious Activity Report. To stay ahead, use reliable services, double-check recipient details, and maintain documentation of the transaction’s purpose. Being organized ensures that your transfers remain smooth, compliant, and stress-free. It’s a small step that saves major headaches down the line while protecting both personal finances and reputations.

3. Cryptocurrency Moves: Digital Currency, Real-World Rules

Buying, selling, or transferring cryptocurrency may feel anonymous, but regulators increasingly track these transactions. The IRS considers cryptocurrency property for tax purposes, requiring reporting of gains and losses. Exchanges must report users’ transactions above specific thresholds, and wallets used for business purposes can attract reporting requirements. Even transferring digital coins between your own wallets may need documentation to avoid misunderstandings later.

Crypto doesn’t escape scrutiny just because it exists online. Large purchases, frequent trades, or transfers to exchanges without verified identities could trigger alerts. Keeping records of all transactions, including timestamps, amounts, and counterparties, is essential. Using reputable exchanges with strong reporting practices also helps stay compliant. Understanding crypto’s reporting obligations transforms digital currency from a confusing gray area into a manageable, strategic part of your financial life.

4. Gift Cards and Prepaid Cards: Tiny Packages, Big Attention

It’s easy to treat gift cards and prepaid debit cards as harmless tokens, but large purchases of these can trigger reporting. Banks may monitor purchases of prepaid cards, especially when done in bulk. These transactions sometimes appear similar to cash deposits, raising questions about the source of funds. In certain cases, regulators require reporting to ensure these instruments aren’t used for money laundering or tax evasion.

Avoid surprises by limiting large or repeated purchases of prepaid cards and keeping receipts for all transactions. Documenting the purpose—gifts, business expenses, or personal use—adds transparency. It’s a small habit that keeps financial activity clean and organized while ensuring compliance. Recognizing that even seemingly innocent purchases can be reported reinforces smart money management.

5. Foreign Accounts: Reporting Overseas Holdings

Having a bank account or investment abroad isn’t inherently suspicious, but the U.S. government takes notice. The Foreign Bank Account Report (FBAR) requires reporting accounts exceeding $10,000 in aggregate value. Failure to report can lead to steep penalties, even if the funds are fully legal. The IRS also expects individuals to report foreign investments for income tax purposes.

It’s easy to underestimate the reporting requirements when dealing with overseas accounts. Frequent transfers to and from foreign institutions or earnings from international investments require careful documentation. Using trusted financial advisors and maintaining detailed records ensures compliance while keeping international finances organized. Awareness of these rules avoids unnecessary complications and preserves financial security across borders.

7 Financial Transactions That Could Be Reported Without You Realizing It
Image Source: Pexels.com

6. Large Purchases with Financing: More Than a Swipe

Buying expensive items on credit or financing agreements doesn’t automatically sound like a reportable transaction, but it can be. Banks and lenders might report high-dollar loans or unusual payment patterns to regulatory bodies if they suspect fraud of any kind. Even multiple smaller financed purchases that collectively seem significant might attract attention. Financial institutions use these reports to assess risk and detect unusual patterns that could indicate fraud or money laundering.

To navigate large financed purchases, you should keep thorough records of transactions and their purposes. Inform your lender if you plan high-volume purchases or need unusual financing. Planning ahead can prevent unnecessary reports or investigations while ensuring smooth approval and tracking. Smart financial management often means balancing large acquisitions with careful documentation.

7. Cashing Checks and Money Orders: Paper Trails Everywhere

Checks and money orders seem old-school, but they carry a strong paper trail. Depositing large checks or money orders can sometimes trigger reports similar to cash deposits. Banks must report suspicious patterns or significant amounts exceeding $10,000, following federal regulations. Even money orders bought in batches can raise flags if patterns suggest an attempt to bypass reporting rules.

Document the source and purpose of large checks or money orders. Keeping receipts, noting sender information, and maintaining transaction records provides transparency. Proper documentation ensures smooth banking experiences and avoids misinterpretations by regulators. Awareness of how even traditional payment methods are monitored reinforces responsible financial habits.

Managing Transactions Wisely

Financial reporting isn’t about catching mistakes—it’s about accountability and safety. Large cash deposits, wire transfers, crypto trades, gift card bulk purchases, foreign accounts, financed purchases, and checks all carry reporting obligations that can trigger attention. By understanding these reporting thresholds and maintaining organized records, financial transactions become manageable and stress-free. Proactive communication with banks and advisors minimizes surprises and empowers confident decision-making. Staying informed transforms what might feel like scrutiny into a system that works for you rather than against you.

Which transactions have surprised you the most? Have you encountered any unexpected reporting situations or found clever ways to stay organized and compliant? Share your thoughts, stories, or strategies in the comments.

You May Also Like…

The $50k Dating Trap: 3 “First Date” Red Flags That Scream Financial Disaster

10 New Financial Regulations Your Bank Isn’t Telling You About

Are You Unknowingly Triggering Tax Penalties With December Transactions?

More Retirees Are Seeing Higher Medicare Costs—And It’s Tied to Income From Years Ago

Customers Beware: Banks Are Tightening Fraud Rules and Freezing Accounts Faster Than Ever

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
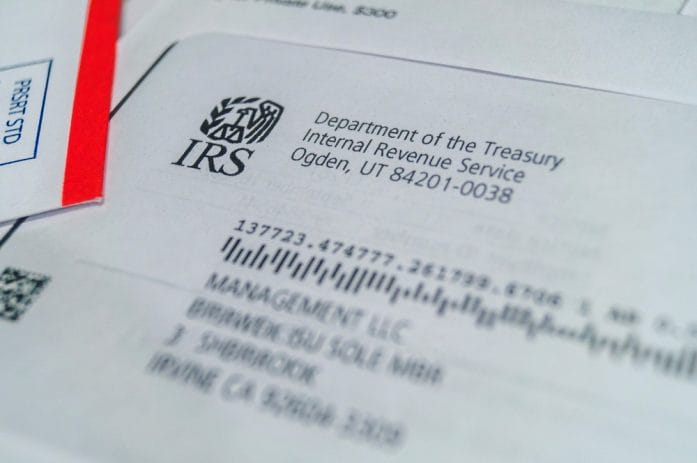
Filed Under: Personal Finance Tagged With: banking, budgeting, credit cards, digital payments, finance, finance tips, financial reporting, IRS, legal compliance, money management, regulations, savings, taxes

  • « Previous Page
  • 1
  • …
  • 99
  • 100
  • 101
  • 102
  • 103
  • …
  • 157
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba
  • How Can I Get Rid of Wells Fargo PMI on My Home Loan? by Tamila McDonald
  • Is It Safe to Throw Away Bank Statements? by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework