• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Brandon Marcus

Payment Delay Alert: Why Your January Social Security Deposit May Not Hit Your Account Today

January 14, 2026 by Brandon Marcus 8 Comments

Here's Why Your January Social Security Deposit May Not Hit Your Account Today
Image Source: Shutterstock.com

The morning coffee is poured, the phone is unlocked, and there it is—the banking app—staring back with a balance that hasn’t budged. For millions of Social Security recipients, that moment can spark a mix of confusion, concern, and a dozen rapid-fire questions. January is supposed to feel like a clean slate, yet nothing rattles the calm quite like a missing deposit.

Before panic sets in or customer service numbers get dialed at lightning speed, it helps to understand what’s really going on behind the scenes. This isn’t a mystery novel twist or a financial cliffhanger—it’s a story with rules, timing quirks, and a few very human explanations.

How Social Security Payment Timing Really Works

Social Security payments don’t all land on the same day, and that alone explains a huge chunk of January confusion. The Social Security Administration uses a staggered schedule that depends on your birthday and the type of benefit you receive. Retirement and disability benefits typically arrive on a Wednesday, and which Wednesday depends on whether your birthday falls early, mid, or late in the month. Supplemental Security Income usually follows a different rhythm entirely, often arriving on the first of the month unless that date collides with a weekend or holiday.

January magnifies these differences because it opens with a federal holiday and a brand-new calendar. When expectations don’t match the actual schedule, it can feel like a delay even when everything is technically right on time.

January’s Calendar Quirks Can Shift Deposit Dates

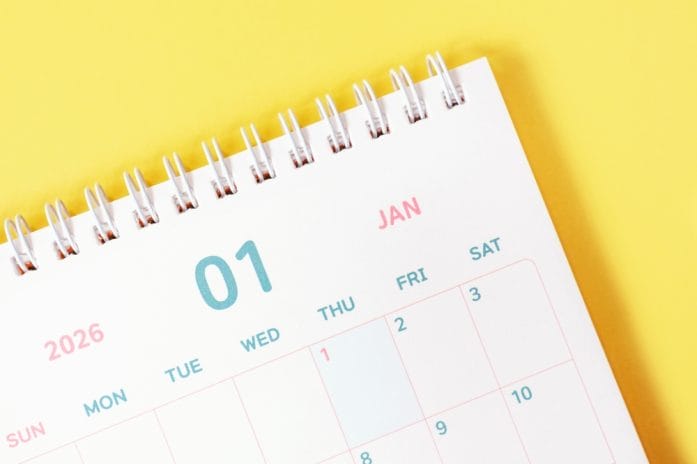
January loves to play calendar tricks, and your Social Security payment sometimes feels the impact. New Year’s Day is a federal holiday, and banks close their doors, even if digital banking stays open. When a scheduled payment date lands on a weekend or holiday, the deposit doesn’t vanish—it simply moves. Sometimes it arrives earlier, sometimes the next business day, depending on the benefit type and banking processes.

That shift can make it seem like today was supposed to be the day, even when the official payment date quietly changed. Understanding that January’s layout isn’t business-as-usual can ease a lot of unnecessary worry.
Here's Why Your January Social Security Deposit May Not Hit Your Account Today
Image Source: Shutterstock.com

Banks And Processing Times Add Another Layer

Even when Social Security releases payments exactly as scheduled, banks still have a role to play. Financial institutions process deposits on their own timelines, and those timelines aren’t always identical. One bank might post funds the moment they’re received, while another may take several hours or even an extra business day. High-volume periods, such as the start of a new year, can slow things slightly as systems update and reconcile accounts. Online banking apps don’t always refresh instantly, which can add to the illusion of a missing payment. In many cases, patience of a single day is all it takes for the deposit to finally appear.

Cost-Of-Living Adjustments Can Cause Brief Confusion

January is also when cost-of-living adjustments take effect, and that change can add a layer of complexity. Updated benefit amounts require system-wide updates, recalculations, and verification checks. While these adjustments are designed to help recipients keep up with rising expenses, they can temporarily slow the flow of information between agencies and banks. Some people notice a different deposit amount and assume something went wrong, while others expect the increase and think a delay has occurred. The reality is that recalibration takes time, and January is when all of it happens at once. The payment is still coming, even if it arrives with a few extra steps behind the curtain.

When A Delay Is Normal And When It’s Not

Most January payment concerns fall squarely into the “normal” category, even if they don’t feel that way in the moment. A deposit that’s one business day late is rarely a sign of trouble, especially around holidays. However, a delay stretching beyond several days deserves attention. Incorrect banking information, a recently changed account, or a flagged issue can hold things up longer than expected. Keeping personal details up to date with Social Security is one of the simplest ways to avoid extended delays. Knowing the difference between a routine timing issue and a genuine problem helps you respond calmly and effectively.

Smart Steps To Take If Your Payment Hasn’t Arrived

The first and most powerful step is checking your official payment schedule to confirm the expected date. Next, take a look at your bank’s processing policies, especially around holidays and weekends. It’s also wise to monitor your account for pending deposits that may not be fully posted yet. If a few business days pass with no sign of your payment, reaching out to Social Security or your bank can provide clarity. Keeping notes of conversations and confirmation numbers can save time if follow-up is needed. Acting methodically beats reacting emotionally every time.

Stay Informed And Stay Calm

January payment delays can feel unsettling, but they’re often the result of timing, calendars, and behind-the-scenes processes rather than true problems. Understanding how Social Security schedules payments and how banks handle deposits puts the power back in your hands. If you’ve experienced a January delay before, or if today’s missing deposit sparked a few nerves, your perspective could help others feel less alone.

Drop your thoughts or personal experiences in the comments section below and join the conversation. Sometimes reassurance is just one story away.

You May Also Like…

Pension Shock: 9 Myths About Social Security That Could Derail Your Retirement

Could Your Social Security Plans Collapse If The Economy Shifts Again This Winter?

Did You Know Social Security Has a Hidden Bonus for Widowers?

11 Social Security Surprises That Hit You After Losing a Spouse

Is There Any Way to Get More Social Security Than You Qualify For?


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: social security Tagged With: America, bank account, bank processing, banking, Banks, elderly, government policy, January, Money, money issues, senior citizen, seniors, Social Security, social security changes, Social Security deposit, social security payment, United States

10 Financial Wake-Up Calls People Experience After Age 55

January 13, 2026 by Brandon Marcus Leave a Comment

These Are 10 Financial Wake-Up Calls People Experience After Age 55
Image Source: Shutterstock.com

Turning 55 can feel like stepping onto a financial rollercoaster you didn’t exactly buy a ticket for. One minute, you’re comfortably cruising through your career, and the next, a cascade of bills, taxes, and retirement worries hits like a surprise drop. Life doesn’t hand out a manual at this age, but it does offer a series of wake-up calls that can either jolt you into action or leave you scrambling.

From unexpected medical expenses to realizing your retirement savings aren’t quite what you thought, these financial alarms are loud, unavoidable, and—if you pay attention—highly motivating.

1. Retirement Savings Suddenly Look Smaller Than You Remembered

It’s a jolt when you finally sit down and do the math. All those years of socking away money in 401(k)s, IRAs, and other accounts suddenly don’t stretch as far as you imagined. Inflation has quietly chipped away at your purchasing power, and market dips may have erased gains you thought were untouchable. Many people realize they need to either work longer, invest smarter, or tighten spending.

This isn’t a panic button moment; it’s a wake-up call to take control. Reviewing your savings strategies and adjusting contributions—even at this stage—can make a huge difference. The key is to confront the numbers head-on instead of hiding from them.

2. Health Costs Start to Take a Bigger Bite

Health insurance premiums, prescription costs, and specialist visits tend to rise sharply after 55. Even people who’ve been careful with their budgets can be caught off guard by the sheer scale of medical expenses. Preventive care and early screenings become non-negotiable, but they add up. Without a solid plan, a few unexpected procedures can throw off months of financial stability. Long-term care insurance or a robust health savings account (HSA) can help, but realizing these costs is a serious wake-up call for planning. Suddenly, the question shifts from “Can I afford a vacation?” to “Can I handle an emergency hospital stay?”

3. Social Security Decisions Feel Overwhelming

At some point after 55, Social Security creeps into conversations and planning. The decisions—when to start taking benefits, how it will impact taxes, and how it interacts with retirement savings—can be more complicated than expected. Many people underestimate the long-term effects of claiming early or delaying benefits. It’s a critical moment to study options and potentially speak with a financial advisor. Understanding how Social Security works now can prevent regrets later. For many, the realization hits: timing really is everything, and small decisions now can create a huge impact in retirement.

4. Debt Suddenly Feels Heavier

Debt that seemed manageable in your 40s or early 50s can feel like a mountain as you approach retirement. Mortgage balances, credit card debt, and lingering personal loans suddenly become stress points. The closer you get to retirement, the more urgent it is to minimize these obligations. Interest payments that once seemed tolerable can consume a large portion of your budget. Many people feel a mix of guilt and motivation as they face the reality of carrying debt into the next chapter of life. Aggressive debt reduction plans or refinancing can offer a sense of relief and control.

5. Housing Plans Become Pressing

Whether you’re thinking about downsizing, relocating, or aging in place, housing becomes a financial and emotional focus after 55. The cost of maintenance, property taxes, and potential renovations can take a bigger chunk out of your budget than expected. Many realize their dream retirement home might require more saving—or compromise—than they imagined. This wake-up call forces a reckoning: your living situation affects not just comfort but financial stability. Planning early allows you to explore options like reverse mortgages or equity strategies without panic. Home is more than walls; it’s a financial cornerstone.

6. Taxes Get More Complicated

As income streams diversify through investments, side businesses, or retirement distributions, taxes become less predictable. People over 55 often discover that they may owe more than expected, especially with withdrawals from retirement accounts. Capital gains, RMDs (required minimum distributions), and changes in tax law can create surprises. Ignoring taxes until April is a risky strategy now. Smart planning—deductible contributions, tax-efficient withdrawals, or professional guidance—becomes critical. It’s a wake-up call to stop procrastinating and understand the intricacies of your financial footprint.

7. Long-Term Care Planning Isn’t Optional

The reality of needing long-term care—whether at home or in a facility—becomes real after 55. The costs are staggering, often exceeding savings for many. Without planning, a sudden health crisis can wipe out decades of careful financial preparation. Long-term care insurance or creating a dedicated fund can mitigate this risk, but most people realize too late that they should have started sooner. It’s one of the clearest wake-up calls: your health and independence may depend on proactive financial moves. Preparing for the unexpected transforms fear into strategy.

These Are 10 Financial Wake-Up Calls People Experience After Age 55
Image Source: Shutterstock.com

8. Lifestyle Inflation Becomes More Noticeable

At 55, you may have reached peak earnings, but lifestyle inflation can be stealthy. Vacations, hobbies, and daily comforts that once felt reasonable now compete with retirement savings. It’s a wake-up call to examine discretionary spending with a sharper eye. Many people realize they’ve adjusted their spending upward alongside income, leaving less room for true financial security. Conscious budgeting and thoughtful choices can help preserve the life you want without derailing your future. It’s a subtle but significant alarm that money habits matter at every age.

9. Inheritance And Estate Planning Become Real

Suddenly, questions about wills, trusts, and estate planning feel urgent. Even if you’ve never thought about these details, turning 55 often triggers a deep awareness of legacy. Without proper planning, assets may not pass on according to your wishes, and loved ones could face unnecessary stress or tax burdens. It’s a wake-up call to organize documents, designate beneficiaries, and consider estate strategies. Addressing these issues proactively is empowering. It ensures that your financial journey includes not just personal security but also care for the people you love.

10. The Urgency Of Financial Education Hits Hard

Many people realize that their knowledge of investments, taxes, and retirement planning was patchy at best. Suddenly, you’re faced with decisions that have real consequences for decades ahead. This wake-up call is about empowerment: learning how money works now can drastically improve outcomes. Seminars, books, advisors, and courses are no longer optional—they’re essential. The earlier you embrace financial literacy, the more options you preserve. After 55, understanding the rules of money isn’t just smart—it’s critical to freedom and peace of mind.

Your Thoughts And Experiences

Financial wake-up calls after 55 can feel intimidating, but they’re also a chance to take control and make intentional choices. Each challenge—whether it’s retirement planning, health costs, or estate preparation—is an opportunity to reassess, adjust, and act strategically.

Have you encountered one of these wake-up calls? How did it change the way you approach money? Your reflections and experiences can provide insight for others navigating this exciting but complex stage of life.

Drop your thoughts in the comments below and let’s spark a conversation about smart financial moves after 55.

You May Also Like…

8 Home Upgrades Seniors Are Choosing Over Moving Into Facilities

Funding Gap: 8 Ways Rising College Costs Are Changing Mid-Life Financial Planning

Why Does Retirement Feel More Expensive Than People Planned For

How a Solid Estate Plan Can Protect Your Finances

12 Capital-Gains Surprises When You Sell the Family Home After 55


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Finance Tagged With: bad financial habits, Debt, debt payoff, finance, finances, financial choices, financial decisions, financial wake-up calls, general finance, health costs, healthcare, healthcare costs, housing, paying off debt, Planning, retire, retiree, retirees, Retirement, retirement savings, Social Security, taxes

How To Regularly Save Money At The Grocery Store

January 13, 2026 by Brandon Marcus Leave a Comment

How To Regularly Save Money At The Grocery Store
Image Source: Shutterstock.com

Stepping into a grocery store can feel like entering a labyrinth designed to make your wallet sweat. Bright lights, perfectly arranged produce, and irresistible smells of fresh bread create a sensory experience that tempts even the most disciplined shopper. Yet, amid the chaos of aisles stacked high with endless options, there’s a treasure map for saving money—if you know where to look. The thrill of discovering smart strategies that keep your budget intact can be almost addictive.

It’s like becoming a savvy treasure hunter in your own neighborhood, hunting for deals, maximizing value, and walking out with a cart full of goodies without the post-shopping guilt. Let’s dive into practical, tried-and-true ways to make every grocery trip a victory for both your taste buds and your bank account.

Plan Your Meals With Purpose

The first secret to grocery savings is a game-changing tactic: meal planning. Knowing exactly what you’re going to cook for the week not only saves time but also prevents those impulse purchases that quietly drain your budget. Start by taking stock of what’s already in your pantry and fridge, then build meals around those ingredients. Make a list of recipes that share ingredients to reduce waste and stretch your dollars further. By sticking to a plan, you can strategically purchase only what you need, avoiding the temptation of “bonus” items that often end up in your cart and then forgotten in the back of the fridge.

Meal planning also gives you the power to buy in bulk for items that last, like grains, beans, or frozen veggies, which can save significant amounts over time. It transforms grocery shopping from a chaotic scavenger hunt into a calculated, money-saving mission.

Master The Art Of Coupons And Digital Deals

Coupons aren’t just for Sunday paper inserts—they’re a secret weapon for the modern shopper. From digital apps to store loyalty programs, there are countless ways to snag discounts on your favorite products. The key is to be strategic: stack coupons with in-store sales for maximum savings. Many apps allow you to scan barcodes or link your loyalty card to automatically apply discounts at checkout, which is like having a personal assistant dedicated to stretching your budget. Keep an eye out for manufacturer coupons for items you already buy regularly; these can add up surprisingly fast. Timing your shopping trips around major promotions or double-coupon days is another trick that can make a huge difference over a month. With a little planning, you’ll find that couponing can be as satisfying as finding hidden treasure in the aisles.

Stick To A Shopping List And Avoid Impulse Buys

A shopping list is your armor against the seductive pull of the snack aisle. Write it, check it, and commit to it. Research shows that shoppers who stray from their list spend significantly more money, often on items they don’t need or even want. Keep your list organized by sections of the store to avoid wandering aimlessly, which increases the risk of spontaneous purchases. If you see a tempting item not on your list, pause and ask yourself whether it’s a necessity or just a fleeting craving. Bringing a small notebook or using a phone app to track prices of items over time can also help you identify when a purchase is truly a good deal. Discipline here doesn’t mean joyless shopping—it means making deliberate choices that let you enjoy what you bring home without regret.

Buy Seasonal And Local Produce

Fresh fruits and vegetables often take a big bite out of your grocery budget, but buying seasonal and local produce can dramatically reduce costs. Items that are in season are abundant and often cheaper, and they usually taste better too. Farmers’ markets, local co-ops, or even small roadside stands can be fantastic sources of affordable, high-quality produce. When you know what’s in season, you can plan meals around it, saving money while eating fresher and more flavorful food.

Freezing or preserving seasonal items for later is another excellent strategy—think frozen berries, canned tomatoes, or pickled vegetables. Eating with the seasons isn’t just a healthful choice, it’s a savvy financial move that can keep your grocery bills in check year-round.

How To Regularly Save Money At The Grocery Store
Image Source: Shutterstock.com

Take Advantage Of Store Brands And Bulk Options

Store brands have come a long way from the days of bland, cheap substitutes. Many grocery chains now offer private-label products that match or even exceed the quality of name brands, often at a fraction of the price. Try comparing ingredients and taste to see which items you can swap without compromise. For staples like rice, pasta, and canned goods, buying in bulk can save you a substantial amount over time, especially if you have the storage space. Just make sure you’re buying items you will actually use—bulk purchases only save money if they don’t go bad.

Combining bulk buys with your meal plan can make weekly prep a breeze while keeping costs low. Store brands and bulk buying together create a dynamic duo that stretches every dollar further.

Shop Smart Around Sales And Promotions

Sales and promotions are like hidden bonuses if you approach them strategically. Instead of being drawn in by flashy signs, focus on items you regularly use and check if they are genuinely discounted. Learn to calculate unit prices to compare deals accurately, because bigger packages aren’t always better bargains. End-of-aisle displays often feature promotions, but only buy if it aligns with your planned meals or pantry needs.

Keep a notebook or app handy to track prices over time, which will help you recognize real deals versus marketing tricks. Being a savvy shopper means combining patience, observation, and planning, and it can turn the thrill of a sale into genuine savings that add up fast.

Join The Conversation And Inspire Others

Saving money at the grocery store isn’t about deprivation—it’s about empowerment, creativity, and making intentional choices that benefit both your wallet and your lifestyle. Whether it’s planning meals, using digital deals, sticking to a list, or taking advantage of seasonal produce, every small effort adds up.

Have you tried any of these strategies or discovered your own money-saving hacks? Tell us how you approach grocery shopping and what tips have worked best for you in the comments below.

You May Also Like…

8 Grocery Shopping Habits That Make You Spend More Without Realizing It

Why Do Grocery Prices Feel Higher No Matter Where You Shop Now

The 6 Best Ways To Save At The Grocery Store In 2026

Can Your Grocery Store Loyalty Card Be Used to Track You?

7 Tactics Grocery Stores Use to Keep You From Thinking About Price


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Smart Shopping Tagged With: coupons, digital deals, grocery bill, grocery costs, grocery prices, Grocery savings, grocery shopping, grocery store, grocery store prices, impulse spending, meal planning, overspending, Shopping, shopping list, Smart Spending, spending

Why Do People Feel Guilty Spending Money Even on Necessitiesd

January 13, 2026 by Brandon Marcus Leave a Comment

Why Do People Feel Guilty Spending Money Even on Necessitiesd
Image Source: Shutterstock.com

Spending money should feel like a simple transaction: you hand over cash or tap your card, and in return, you get the things you need. Yet, for millions of people, even buying the essentials—groceries, hygiene products, or a warm meal—can trigger a wave of guilt that feels disproportionate and relentless. Why does something as mundane as paying for toothpaste or gas bring on a mix of anxiety, regret, and self-reproach? It turns out, the answer is far more interesting than just “being cheap” or “poor money management.”

Deep down, our brains, our upbringing, and society itself conspire to make spending money feel like a moral test, and sometimes, we fail it even when there’s nothing to fail.

The Psychology Behind Spending Guilt

Humans are wired to attach emotions to almost every decision we make, and money is no exception. Spending guilt is a psychological reaction that stems from a combination of self-perception, societal pressure, and survival instincts. Evolutionarily, our ancestors had to be careful with resources—food, tools, and shelter were precious, so conserving them was crucial for survival. That caution is now hardwired into our brains, and even though we live in a world of abundance, our instincts often still scream, “Don’t waste!”

Modern life may have replaced spears with debit cards, but the emotional circuitry hasn’t caught up. When we spend money—even on necessary items—our brain interprets it as risk, triggering guilt signals that feel like moral feedback.

Childhood Lessons And Family Influences

Much of our guilt over spending stems from early experiences and the money messages we absorbed as kids. If you grew up in a household where every penny was scrutinized or saving was preached as a virtue above all else, you may carry that internalized voice into adulthood. Phrases like “Money doesn’t grow on trees” or “Think before you spend” are simple enough, but over time they cultivate a subconscious sense that spending is inherently bad. Even if you’ve reached financial stability as an adult, those early lessons can make grocery shopping feel like a test of discipline. It’s fascinating how the echoes of childhood still ripple into our wallet habits decades later.

Why Do People Feel Guilty Spending Money Even on Necessitiesd
Image Source: Shutterstock.com

Social Comparison And Modern Pressure

Another culprit behind spending guilt is our tendency to compare ourselves to others. Social media amplifies this endlessly—everyone’s brunch looks perfect, every purchase seems smart, and suddenly your practical necessities feel extravagant. Even necessities can feel luxurious if you perceive them as indulgent compared to what you think “everyone else” spends. This social pressure isn’t just online; it’s in friendships, workplaces, and family dynamics. If a colleague casually mentions budgeting while you buy groceries, your brain can interpret it as judgment. The guilt arises not from the act itself but from imagined social critique, which makes simple spending surprisingly stressful.

The Role Of Personal Values And Identity

People also feel guilty spending money when purchases clash with their personal values or self-image. If you pride yourself on frugality or minimalism, a sudden expense—even a necessary one—can feel like a betrayal of your identity. This guilt is particularly pronounced when spending intersects with moral or ethical concerns, like buying products from companies with questionable practices or paying for conveniences that feel indulgent.

In these moments, your brain doesn’t just see a dollar leaving your account; it sees a small failure of character. Spending guilt, then, becomes less about finances and more about staying true to the image of yourself you’ve cultivated over time.

Coping Strategies And Mindful Spending

The good news is that awareness can reduce the sting of spending guilt. Mindful spending—pausing to acknowledge the necessity and value of each purchase—can transform guilt into confidence. Tracking spending and budgeting are helpful, but so is reframing the narrative: buying groceries isn’t a moral failing, it’s fuel for your body. Some people find it useful to separate money into categories: necessities, savings, and treats. When expenses are labeled clearly, even essential spending feels justified. The key is to recognize that money is a tool, not a measure of your worth. By realigning how you think about transactions, guilt can shrink, leaving you free to actually enjoy what your money buys.

When Guilt Signals Something Bigger

Occasionally, the guilt you feel isn’t just about spending—it’s a signal of deeper anxiety or unresolved financial stress. Chronic financial guilt can be a symptom of underlying issues like compulsive saving, fear of scarcity, or even mental health challenges like anxiety and depression. Recognizing this is important because persistent guilt over necessities isn’t normal or harmless. Talking to a financial therapist, practicing self-compassion, or setting structured budgets can help turn this destructive guilt into constructive awareness. Understanding why you feel guilty is the first step to reclaiming the simple joy of buying what you need without judgment.

Thoughts On Spending Without Regret

Spending money, even on necessities, is complex. It touches on psychology, childhood lessons, social pressures, personal values, and deeper anxieties. The next time you feel that familiar twinge of guilt at the checkout counter, pause and consider where it’s really coming from. Is it instinct, upbringing, social comparison, or something more? Recognizing the roots of your guilt can empower you to approach your finances with clarity, confidence, and even a bit of joy.

What experiences or insights have you had about spending guilt? Leave your thoughts in the comments below—we’d love to hear how you navigate this surprisingly common feeling.

You May Also Like…

Why Does Interest Rate Talk Suddenly Affect Everyday Spending

Holiday Debt: 9 Warning Signs Your Spending Is Already Off Track

Holiday Trap: 6 Gift-Spending Mistakes That Could Wreck Your Budget

Ways Adult Kids Quietly Drain Your Finances Without Guilt

12 Ways to Beat Back the Guilt of Spending on Yourself Finally


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Smart Spending Tagged With: emotional guilt, everyday items, families, Family, family influence, guilty, identity, Mindful Spending, necessities, overspending, personal value, pressure, Smart Spending, social comparison, spending, spending guilt, spending money

8 Budget Line Items That Keep Growing Without Notice

January 13, 2026 by Brandon Marcus Leave a Comment

Here Are 8 Budget Line Items That Keep Growing Without Notice
Image Source: Shutterstock.com

Money has a sneaky way of slipping through your fingers. One month, your budget looks manageable, and the next, you’re staring at numbers that make your jaw drop. Some expenses aren’t obvious—they don’t scream “I’m draining your bank account!” but quietly expand in ways that would make a magician jealous.

If you’ve ever wondered why your paycheck disappears faster than coffee on a Monday morning, you might be surprised at which line items are silently multiplying.

1. Subscription Services That Multiply Like Rabbits

Subscriptions start innocently—a streaming service here, a monthly app there—and suddenly, your bank account reads like a subscription buffet. Each one might seem harmless alone, but add them up, and they can devour hundreds of dollars a month. Many people forget about old trials that auto-renew or secondary services they barely use. What’s worse, some subscriptions increase prices yearly, quietly inflating without any alert.

Reviewing them regularly isn’t just smart; it’s practically a survival tactic for your finances. Take a close look at your statements and cancel the ones you genuinely don’t need—you might be shocked at how much you reclaim.

2. Utilities That Inch Up Silently

Electricity, water, gas—these bills rarely feel dramatic until they aren’t what you expect. Seasonal changes, rate hikes, and inefficient appliances can quietly push costs higher. Leaving lights on, overusing heating or cooling, or even letting phantom electronics draw power overnight can add to the stealthy climb. Tracking your usage and switching to energy-efficient solutions may feel tedious, but it saves more than just money; it saves stress.

Watching your utility bills like a hawk reveals patterns you can control instead of letting them control you. Small tweaks now prevent a shocking total later.

3. Grocery Costs That Spiral Out Of Control

Groceries are the classic example of creeping inflation that slips under the radar. Price increases, new food trends, and impulse buys can turn a reasonable shopping trip into a wallet workout. Shopping without a list, buying on convenience, or ignoring bulk opportunities leads to more than you planned. Even small daily snacks or specialty coffees can accumulate into a shocking sum over a month. Meal planning, comparing prices, and sticking to essentials can curb the rise. Once you see the numbers in black and white, it’s amazing how much control you regain.

4. Dining Out That Feels Small But Isn’t

Dinner out with friends or takeout after a long day often feels like a treat, not a threat. Yet these expenses stack faster than most realize. Ordering consistently, adding drinks, or tipping generously can turn “just once in a while” into a recurring drain. The allure of convenience masks the cumulative effect on your budget. Tracking dining expenses for a month often reveals jaw-dropping totals. Cooking at home even a few times per week can dramatically reduce your monthly outflow without cramping your lifestyle. And hey, experimenting in your own kitchen can be a delicious adventure.

Here Are 8 Budget Line Items That Keep Growing Without Notice
Image Source: Shutterstock.com

5. Transportation Costs That Balloon

Car payments, fuel, insurance, maintenance, and parking—transportation isn’t just a one-line expense. Fuel prices fluctuate, insurance premiums rise, and unexpected repairs sneak up at the worst times. Even public transportation costs add up, especially when factoring in occasional rideshare trips or taxis. Neglecting to maintain vehicles can lead to expensive emergencies, silently adding hundreds to your monthly tab. Comparing insurance, planning routes, and maintaining your vehicle are underrated strategies for stopping this creeping growth. Awareness is the first step toward taming these travel-related giants.

6. Impulse Purchases That Add Up Slowly

It’s not always the big buys that hurt—it’s the tiny impulse purchases that slowly nibble away at your finances. A gadget here, a trendy accessory there, a spontaneous online purchase at midnight—these “small” purchases can snowball. When added over weeks, they often total more than planned. People often underestimate the emotional triggers behind these splurges, which makes them harder to control. Setting limits, pausing before purchases, or even tracking all spending can curb this invisible inflation. Watching these micro-expenses gives you a sense of power over your wallet that’s surprisingly satisfying.

7. Healthcare Expenses That Aren’t Obvious

Insurance premiums, co-pays, prescriptions, and unexpected medical visits can quietly inflate your budget. Preventative care, routine check-ups, and regular prescriptions often feel minor, but the cumulative cost can be substantial. Lifestyle factors, aging, or changing coverage plans contribute to rising expenses. People rarely anticipate the “hidden” costs like over-the-counter medications or specialty treatments. Planning ahead with a health savings account or budgeting for medical needs reduces anxiety and keeps surprises in check. Staying proactive turns these creeping costs from budget-breaking to manageable.

8. Home Maintenance That Sneaks Up

Owning a home is a joy, but it comes with ongoing, often unexpected maintenance costs. Roof repairs, plumbing issues, painting, seasonal upkeep—all can surprise you when least expected. Ignoring minor problems often escalates them into expensive emergencies. Even simple upgrades like new appliances or energy-efficient renovations can temporarily spike expenses. Regular maintenance schedules and setting aside a home emergency fund keeps your home running smoothly without shocking your budget. Consider it the investment that protects both your house and your sanity.

Keep An Eye On Your Budget Growth

Budgets are living things—they change, evolve, and sometimes quietly expand without warning. By paying attention to subscriptions, utilities, groceries, dining, transportation, impulse purchases, healthcare, and home maintenance, you regain control over where your money goes. Catching these creeping expenses early transforms your financial life from reactive to proactive.

Which of these line items has caught you by surprise lately? Let us know your stories or strategies in the comments section below—we’d love to hear how you keep your budget in check.

You May Also Like…

10 Costs That Make Retirement Budgets Feel Unstable

9 Budget Categories That Blow Up After One Emergency

Why Do So Many People Believe Budgeting Apps Solve Everything

9 Everyday Expenses People Forget to Include in Their Budget

Are Budgeting Apps Designed to Push You Into Debt?

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Budgeting Tagged With: Budget, budget items, budget tips, budgeting, Budgeting Tips, Emotional Spending, grocery budget, grocery costs, grocery prices, grocery store, impulsing spending, subscriptions, transportation costs, utilities, utility bills

Why Does Shopping for Basics Feel Emotionally Draining Now

January 13, 2026 by Brandon Marcus Leave a Comment

Why Does Shopping for Basics Feel Emotionally Draining Now
Image Source: Shutterstock.com

Walking into a store to grab a simple pack of socks or a carton of milk used to feel straightforward. You knew what you needed, you got it, and you left. But now? Even grabbing the most mundane items can feel like stepping into a mental obstacle course. Suddenly, the fluorescent lighting, endless shelves, and decision overload seem to conspire against you, and what should take ten minutes stretches into a full-blown emotional workout.

Why has shopping for basics become such a draining experience, and is it just in your head, or is there something bigger going on? Let’s unpack the surprisingly complex world of everyday shopping stress.

The Overwhelming Tide Of Choices

One of the biggest culprits is choice overload. Today’s supermarkets, pharmacies, and online stores offer an absurd number of options for products that used to come in two or three varieties. Think toothpaste: whitening, enamel protection, sensitive, kids, natural, fluoride-free, vegan, eco-friendly—the list goes on. While variety sounds like a luxury, it actually triggers decision fatigue, which is a real psychological phenomenon.

Your brain has a limited reservoir of mental energy for making decisions, and when even the simplest choice becomes a marathon, it’s exhausting. That little thing like choosing between two brands of bread suddenly feels monumental. Each decision drains just a little more mental bandwidth, leaving shoppers feeling mentally frazzled by the time they reach the checkout.

Inflation And Anxiety Collide

Another factor is the creeping anxiety over money. Prices for basics have been creeping up steadily, and the rise of inflation is impossible to ignore. When you’re juggling a budget and trying to make your paycheck stretch, every decision carries extra weight. You might find yourself staring at a bag of rice and calculating, in your head, whether it’s the best value per ounce. This financial tension subtly amplifies the emotional toll of shopping, making what used to be a neutral experience feel loaded with stress. It’s not just the money itself—it’s the mental gymnastics of trying to feel responsible while still getting what you need.

Digital Shopping Doesn’t Make It Easier

Online shopping promised convenience, but in many ways, it has intensified the problem. Endless scrolling, hundreds of reviews, and the pressure to choose the “best” product can make even buying toilet paper a mentally exhausting chore. Notifications ping, ads pop up, and suddenly the act of selecting an essential item has spiraled into a full research project. Algorithms suggest items you didn’t even know existed, leaving you to wonder if the product you actually need is even the right choice. While the digital shift saves physical effort, it often multiplies cognitive load, keeping your mind in overdrive long after the virtual cart is filled.

The Emotional Weight Of Everyday Decisions

Shopping isn’t just about logistics; it’s emotional. Humans have a natural aversion to regret, and even small choices can trigger stress when you fear making the “wrong” one. Add in social comparison—seeing other people’s carts, Instagram grocery hauls, or product reviews—and suddenly picking a basic cereal becomes tied to your self-perception. There’s a subtle emotional labor in wanting to do “right” by yourself, your family, or even the planet, and every item feels like a little moral puzzle. These emotional pressures, often invisible but very real, turn mundane errands into unexpected psychological marathons.

Why Does Shopping for Basics Feel Emotionally Draining Now
Image Source: Shutterstock.com

The Role Of Sensory Overload

If you’ve felt physically tense in stores lately, you’re not imagining it. Bright lights, loud announcements, lingering scents, and crowded aisles all contribute to sensory overload. Even minor sensory irritations can accumulate into emotional strain, especially when combined with the mental load of decisions and budget concerns. Grocery stores and big-box retailers aren’t designed to soothe; they’re designed to stimulate—and that constant stimulation is exhausting. For introverts or anyone sensitive to noise and chaos, the emotional drain isn’t just figurative—it’s real, measurable stress.

When Convenience Becomes Stressful

Ironically, the conveniences meant to make shopping easier can also make it harder. Pre-packaged meals, subscription boxes, or online grocery services save time but often introduce their own stressors: Will the produce arrive fresh? Did I order the right quantity? Will the delivery window fit my schedule? Even the act of planning ahead, once a simple task, now demands attention to logistics, timing, and accuracy. Convenience doesn’t automatically reduce stress—it just shifts it, often in ways that sneak up on you.

The Psychological Impact Of Repetition

Finally, there’s the sheer monotony of routine shopping. Buying basics feels repetitive, yet every iteration comes with new challenges: price changes, inventory shifts, and seasonal product rotations. Our brains are wired to seek novelty, and repetitive tasks with high stakes—like budgeting, comparing, and evaluating quality—can feel draining. What should be automatic becomes mentally taxing when the repetition is paired with continuous choice and subtle pressure. It’s like running on a treadmill that keeps speeding up without warning.

How Shopping Shapes Our Emotions

In the end, shopping for basics is no longer just a transactional task—it’s a surprisingly intricate emotional experience. Choice overload, inflation, online complexity, sensory bombardment, moral considerations, and repetitive tasks all collide to make simple errands unexpectedly draining. Understanding why it feels this way is the first step in reclaiming some sanity from your grocery trips or essential shopping sprees.

How do you navigate the emotional weight of buying basics? Have you noticed the stress piling up during simple errands? Your experiences could help others realize they’re not alone—feel free to drop your thoughts or stories in the comments section below.

You May Also Like…

8 Grocery Shopping Habits That Make You Spend More Without Realizing It

7 Simple Techniques to Conquer Impulsive Shopping Forevermore

9 Sneaky Costs of Online Shopping Sprees

6 Silent Money Drains in Everyday Shopping

12 Financial Hacks to Beat Emotional Spending and Save Big!


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Spending Habits Tagged With: anxiety, digital shopping, Emotional Spending, impulse spending, Inflation, overspending, shop, Shopping, shopping choice, shopping online, smart shopping, Smart Spending, spending

9 Expenses That Used to Be Optional but Aren’t Anymore

January 12, 2026 by Brandon Marcus Leave a Comment

Here Are 9 Expenses That Used to Be Optional but Aren’t Anymore
Image Source: Shutterstock.com

The world didn’t just change overnight—it upgraded, auto-renewed, and charged your card while you weren’t looking. What once felt like a lifestyle choice has quietly transformed into a requirement for keeping a job, raising a family, or simply existing without daily frustration. Somewhere between dial-up tones and paper maps, modern life added a stack of “must-haves” that now feel as essential as electricity.

These expenses didn’t arrive with warning labels, but here we are, budgeting around them anyway. Let’s talk about the nine costs that graduated from “nice to have” to “you can’t realistically opt out.”

1. Mobile Data And Internet Access

Once upon a time, the internet lived in a single room and made loud noises while connecting. Now it’s the backbone of work, school, healthcare, banking, entertainment, and social life. Mobile data and home internet aren’t luxuries when job applications, homework portals, and appointment scheduling all happen online. Even basic communication often assumes instant access to email, messaging apps, and video calls.

Many employers quietly expect workers to be reachable, connected, and capable of hopping onto digital platforms at any moment. Trying to function without reliable internet today doesn’t make you frugal—it makes you invisible.

2. Smartphones

Smartphones used to be flashy gadgets for early adopters and tech enthusiasts. Today, they’re the remote controls for everyday life. From boarding passes and two-factor authentication to payment apps and emergency alerts, entire systems assume you have one. Schools send updates through apps, workplaces rely on messaging platforms, and even restaurants expect you to scan a code. Without a smartphone, simple tasks take longer, cost more, or become impossible. It’s not about brand loyalty or upgrades—it’s about participation.

3. Subscription Software And Apps

Buying software once and owning it forever now sounds like a fairy tale. Essential tools for work, creativity, taxes, fitness, and productivity increasingly live behind monthly or annual paywalls. Students and professionals alike are expected to use specific platforms just to keep up. Even things like note-taking, document signing, and cloud storage often require ongoing fees. These subscriptions may look small individually, but together they form a quiet, permanent drain on monthly budgets. Cancel too many, and daily life suddenly becomes much harder.

4. Health Insurance And Out-Of-Pocket Healthcare Costs

Healthcare has always cost money, but the degree of personal financial responsibility has shifted dramatically. Insurance premiums, deductibles, copays, and surprise bills have turned basic medical care into a budgeting challenge. Preventive care, mental health services, and prescription medications are no longer optional if you want to function well. Skipping care can quickly lead to bigger, more expensive problems down the road. For many people, healthcare expenses are now as non-negotiable as rent.

5. Reliable Transportation

Transportation used to mean getting from point A to point B when needed. Now, reliability is everything. Many jobs require flexible schedules, long commutes, or multiple daily stops that public transit can’t always support. Ride-share costs add up fast, and unreliable transportation can threaten employment itself. Even remote workers often need dependable transportation for childcare, errands, or medical appointments. Whether it’s car payments, maintenance, insurance, or transit passes, getting around is no longer optional—it’s foundational.

6. Childcare And After-School Programs

There was a time when childcare was considered a short-term or optional expense. Today, it’s a necessity for most working families. Dual-income households aren’t a luxury anymore—they’re often the only way to stay afloat. Safe, reliable childcare and after-school programs allow parents to work consistent hours without constant stress. These services also support children’s development, learning, and social skills. For many families, childcare costs rival housing expenses, yet opting out simply isn’t realistic.

7. Home Security And Digital Protection

Locks on doors used to be enough. Now, physical and digital security go hand in hand. Home security systems, smart cameras, identity theft protection, and antivirus software have become standard defenses. Online banking, remote work, and digital records make personal data more vulnerable than ever. Recovering from fraud or a breach can cost far more than preventive measures. Peace of mind, it turns out, comes with a monthly fee.

Here Are 9 Expenses That Used to Be Optional but Aren’t Anymore
Image Source: Shutterstock.com

8. Professional Development And Continuing Education

Education no longer ends with a diploma. Industries evolve quickly, and staying employable often requires constant learning. Certifications, online courses, workshops, and licensing fees are now part of many careers. Employers may expect skills updates without fully covering the cost. Falling behind can mean fewer opportunities or lower pay. Investing in yourself isn’t just aspirational anymore—it’s a survival strategy.

9. Convenience Services And Time-Saving Tools

Time has become one of the most expensive resources of all. Grocery delivery, meal kits, cleaning services, and digital assistants once felt indulgent. Now they’re coping mechanisms for overloaded schedules and burnout. When work, family, and obligations collide, convenience fills the gaps. These services help people stay functional when time and energy run low. Paying for time, it turns out, is often the only way to get any back.

Living In A World Of Non-Optional Options

Modern life has quietly rewritten the definition of “essential.” Expenses that once felt elective are now woven into how we work, connect, and care for ourselves and others. Recognizing these shifts doesn’t make budgeting easier, but it does make it more honest.

Everyone’s list looks a little different depending on lifestyle and priorities. Drop your thoughts or personal experiences in the comments below and let the conversation continue.

You May Also Like…

Why Do Unexpected Expenses Always Seem to Hit at the Worst Time

Are App-Linked Budget Tools Selling Your Income Data?

3 Reasons You Can’t Afford to Lose Your Smartphone

5 Tips to Save Money on Your Smartphone Bill

What Happens When Retirement Plans Ignore Healthcare Costs


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Spending Habits Tagged With: childcare, Cost of living, costs, cutting expenses, digital safety, Digital Security, everyday costs, expense mindset, expense tracking, expenses, health insurance, healthcare, home security, insurance costs, internet access, mobile data, smartphone apps, smartphones, subscriptions, transportation

Why Are Prescription Costs Catching So Many People Off Guard

January 12, 2026 by Brandon Marcus Leave a Comment

Why Are Prescription Costs Catching So Many People Off Guard
Image Source: Shutterstock.com

The pharmacy counter used to be a quick stop between errands. Now it can feel like the dramatic climax of a movie you didn’t buy tickets for. You hand over a prescription, tap your foot, scroll your phone, and then—bam—the total flashes on the screen like a plot twist nobody warned you about. Eyes widen. Brows furrow. Wallets quietly panic.

Across kitchen tables, group chats, and waiting rooms, people are asking the same stunned question: how did everyday medications turn into budget-blowing surprises? The answer is layered, complicated, and honestly kind of wild.

The Price Tag Shock At The Pharmacy Counter

One of the biggest reasons prescription costs feel so jarring is that the final price often appears out of nowhere. Most people walk into a pharmacy assuming their insurance has everything neatly handled, only to discover that “covered” does not always mean “affordable.” Copays, deductibles, and coinsurance can stack together in ways that feel more like a puzzle than a plan. Even longtime medication users can be caught off guard when a refill suddenly costs double what it did last month. Formularies change, coverage tiers shift, and pharmacies update prices more often than most people realize.

Because these changes happen quietly, the shock hits right at the register, when there’s little time to process or plan. That moment of surprise is what makes prescription costs feel personal, immediate, and stressful.

Insurance Isn’t As Predictable As It Sounds

Insurance is often described as a safety net, but it can feel more like a trampoline with unpredictable bounce. Plans differ wildly in what they cover, how much they cover, and when coverage actually kicks in. A medication that was affordable under one employer’s plan might become painfully expensive after a job change, even if nothing else changes in your life. High-deductible plans have become more common, meaning patients may pay full price for prescriptions until they hit a spending threshold that feels very far away. Prior authorizations can delay access and sometimes push people toward more expensive alternatives. All of this creates a sense that insurance rules are written in pencil, not ink. When the ground keeps shifting, it’s no wonder people feel blindsided.

Drug Pricing Is A Maze With Too Many Turns

Behind every prescription price is a complex system that most patients never see. Drug manufacturers set list prices, but those numbers are only the beginning of the story. Pharmacy benefit managers, wholesalers, pharmacies, and insurers all play roles that influence what someone ultimately pays. Rebates and negotiations happen behind closed doors, which can lead to higher list prices even when discounts exist somewhere in the system. Generic options help, but they are not always available or dramatically cheaper. New medications often enter the market with premium pricing, especially if they treat chronic or hard-to-manage conditions.

From the outside, it looks chaotic, and from the inside, it’s even more complicated. That complexity makes it hard for patients to predict costs or understand why two people taking the same drug might pay very different amounts.

Chronic Conditions Turn Surprise Into Ongoing Stress

For people managing long-term health conditions, prescription costs are not a one-time shock. They are a recurring line item that can quietly reshape a household budget. Monthly refills mean monthly reminders that prices can rise without warning. Skipping doses or stretching medication becomes a tempting but risky strategy when costs climb. The emotional toll adds another layer, as people weigh their health against financial pressure. Parents managing medications for children or caregivers supporting aging relatives feel this stress even more intensely.

Over time, the surprise turns into vigilance, with patients bracing themselves every time they approach the counter. That constant uncertainty is exhausting, and it explains why prescription pricing has become such a hot-button issue.

Why Are Prescription Costs Catching So Many People Off Guard
Image Source: Shutterstock.com

Why It Feels Worse Now Than It Used To

Prescription costs have existed for decades, so why does it feel more shocking now? Part of the answer lies in visibility. People talk more openly about money and healthcare experiences than they did years ago, so stories travel fast. Social media amplifies individual moments of sticker shock into shared outrage. At the same time, wages have not always kept pace with healthcare expenses, making price jumps harder to absorb.

More medications are used to manage conditions over longer lifespans, increasing total spending even when individual prices hold steady. Add in economic uncertainty, and every unexpected expense feels heavier. The surprise isn’t just about the number on the receipt; it’s about timing, context, and the feeling that control has slipped away.

Let’s Talk About The Real Cost Of Staying Healthy

Prescription costs catch people off guard because they combine surprise, complexity, and deeply personal stakes. They show up at moments when people are focused on feeling better, not decoding billing systems. Understanding why these costs feel so unpredictable is the first step toward navigating them with more confidence. Conversations matter, especially when they bring hidden frustrations into the open.

If you’ve had a moment at the pharmacy counter that left you stunned, or if you’ve found creative ways to manage medication expenses, add your thoughts or stories in the comments section below.

You May Also Like…

7 Clever Ways Grandparents Save on Family Vacations

Expense Spike: 8 Healthcare Costs That Hit Harder in Later Life

The Prescription Scandal No One Wants to Talk About

Navigating the Sandwich Generation: Caring for Kids, Aging Parents & Yourself

8 Tips for Talking With Your Partner About Health, Finances & Legacy


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Health & Wellness Tagged With: chronic conditions, drug pricing, drugs, generic drugs, health, health and wellness, health insurance, healthcare, healthcare costs, Insurance, medical expenses, medicine, over-the-counter drugs, prescription, prescription drugs, prescriptions, Smart Spending, spending

7 Common Money Habits That Increase Stress Instead of Reducing It

January 12, 2026 by Brandon Marcus Leave a Comment

These Are 7 Common Money Habits That Increase Stress Instead of Reducing It
Image Source: Shutterstock.com

Money advice is everywhere, shouted from podcasts, splashed across social feeds, and whispered by well-meaning relatives at family dinners. Yet for all that guidance, many people still feel a tight knot in their stomach every time they open a banking app. The twist is that some habits praised as “responsible” are actually fueling anxiety instead of calming it. These behaviors often look smart on the surface, but underneath, they quietly crank up pressure, guilt, and overwhelm.

If your finances feel more exhausting than empowering, you’re not broken. You might just be practicing a few stress-boosting money habits without realizing it.

1. Treating A Budget Like A Punishment

A budget is supposed to be a tool, not a disciplinary hearing, yet many people approach it like a scolding authority figure. Every coffee, snack, or small indulgence becomes evidence in a case against yourself. This mindset turns budgeting into a constant emotional battle rather than a helpful roadmap. When a budget feels restrictive and joyless, it often leads to rebellion spending, followed by guilt and self-criticism.

Stress grows because the budget is framed as something to survive rather than something that supports your life. A healthier approach allows room for enjoyment, flexibility, and adjustments as life changes.

2. Obsessively Checking Accounts And Balances

Keeping an eye on your money is wise, but refreshing your banking app ten times a day is a fast track to anxiety. Each glance becomes a mini emotional roller coaster, especially if balances fluctuate or expenses hit unexpectedly. This habit keeps your nervous system on high alert, as if a financial emergency is always seconds away. Instead of feeling informed, you feel monitored by your own numbers. Constant checking can also distort reality, making normal spending feel dangerous. Trust grows when you set intentional check-in times rather than living inside your balance screen.

3. Saving Every Extra Dollar Without Purpose

Saving money is often treated like an unquestionable virtue, but saving without clarity can be surprisingly stressful. When every spare dollar disappears into an unnamed savings account, it can feel like money is vanishing instead of working for you. This creates a vague sense of deprivation without a satisfying payoff. Goals give savings emotional meaning, whether it’s security, freedom, or future experiences. Without that meaning, saving feels endless and heavy. Stress eases when you know exactly what your money is preparing you for.

4. Avoiding Money Conversations Completely

Silence around money can feel safer than awkward conversations, but avoidance tends to magnify fear. When finances are never discussed, misunderstandings grow, assumptions take over, and anxiety fills in the blanks. This is especially true in relationships where unspoken expectations quietly build pressure. Avoidance can also prevent problem-solving, allowing small issues to snowball into major stressors.

Talking about money doesn’t have to be confrontational or uncomfortable. Honest, calm conversations often replace dread with relief and clarity.

5. Comparing Your Finances To Everyone Else’s

Financial comparison is a stress factory disguised as motivation. Social media highlights vacations, new cars, and dream homes without showing debt, trade-offs, or family support behind the scenes. Measuring your progress against someone else’s highlight reel can make even solid finances feel inadequate. This habit breeds impatience and dissatisfaction, pushing people to make choices that don’t align with their reality. Comparison also ignores personal values, priorities, and timelines. Peace grows when success is defined on your own terms, not someone else’s feed.

6. Using Credit As Emotional Relief

Swiping a card can feel like instant relief after a hard day, a rough week, or an emotional blow. That temporary comfort, however, often carries a delayed stress bill. Purchases made to soothe feelings can quickly turn into regret when statements arrive. The cycle repeats as stress leads to spending, which then creates more stress. Credit itself isn’t the villain, but using it as emotional support can quietly erode financial confidence. Awareness and alternative coping strategies can break this exhausting loop.

These Are 7 Common Money Habits That Increase Stress Instead of Reducing It
Image Source: Shutterstock.com

7. Believing You Should Already Know Everything About Money

Many adults secretly believe they missed a class where everyone else learned how money works. This belief creates shame, hesitation, and fear of asking questions. When you think you should already understand investing, taxes, or debt, learning feels intimidating instead of empowering. Stress thrives in that silence, convincing you to avoid decisions altogether. The truth is that money skills are learned, not inherited through some mysterious adulthood rite. Giving yourself permission to learn at your own pace can dramatically reduce financial tension.

Turning Stress Into Financial Confidence

Money stress often isn’t about numbers alone; it’s about habits, beliefs, and emotional patterns woven into daily life. When these common behaviors go unchecked, they can quietly drain energy and confidence. The encouraging part is that awareness opens the door to change, and even small shifts can bring noticeable relief. By reframing how you budget, save, spend, and think about money, finances can start to feel supportive instead of suffocating. Everyone’s journey with money is different, shaped by experiences, values, and goals.

Feel free to tell us what habits have caused you the most stress or what changes have made the biggest difference for you in the comments below.

You May Also Like…

6 Bad Money Habits Families Show During The Holidays

Behaviour Check: 8 Money Habits That Sabotage Boomers’ Financial Futures

The Impact Of Mortgage Choices On Your Financial Health

Risk Proaction: 5 Steps to Stress-Test Your Finances for Worst-Case Scenarios

9 Money Assumptions That No Longer Work in Today’s Economy


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: bank account, Budget, budgeting, checking account, comparing finances, conversations about money, financial choices, financial decisions, Life, Lifestyle, Money, money choices, money habits, overspending, saving money, savings account, smart saving

Why Does Financial Anxiety Show Up Even When Bills Are Paid

January 12, 2026 by Brandon Marcus Leave a Comment

Why Does Financial Anxiety Show Up Even When Bills Are Paid
Image Source: Shutterstock.com

Your rent is covered, the lights are on, the credit card balance is behaving, and yet your chest still tightens when you open your banking app. Your stomach does a tiny flip when someone mentions inflation. You catch yourself running numbers in your head while brushing your teeth, even though the math already works. This isn’t a personal failure or a secret sign that you’re “bad with money.” It’s a deeply human reaction rooted in psychology, memory, culture, and the way our brains interpret safety.

Financial anxiety can feel ridiculous when everything looks fine on paper, which somehow makes it even louder. Let’s pull back the curtain and talk about why this stress shows up anyway, and why it makes perfect sense.

Your Brain Is Wired To Fear Uncertainty

The human brain loves predictability and absolutely panics at open-ended questions. Money, even when stable today, represents tomorrow, next month, and ten years from now, which is more than enough to set off mental alarms. Paying bills handles the present, but anxiety lives in the future, where outcomes feel blurry and uncontrollable. Evolution didn’t design our minds for long-term spreadsheets; it designed them to spot potential threats and react fast.

A single news headline, offhand comment, or unexpected expense can activate that threat system instantly. Once it’s on, logic struggles to compete with emotion, even if your checking account is calm. That’s why reassurance from numbers alone often feels thin when your brain is asking bigger, scarier questions about stability and survival.

Past Money Experiences Leave Emotional Residue

Financial anxiety doesn’t reset just because your circumstances improved. If you’ve lived through job loss, debt, family stress, or periods of scarcity, your nervous system remembers that instability vividly. Those memories sit quietly until something reminds them it could happen again. You might not consciously think about those moments, yet your body reacts as if it’s preparing for a repeat performance. Even people who grew up watching adults argue about money can internalize tension without realizing it. Paying bills now doesn’t erase the emotional imprint of earlier experiences. Instead, anxiety becomes a protective reflex, trying to prevent a return to those uncomfortable chapters.

Control Feels Different From Safety

Having enough money and feeling secure are not the same experience. Control is about knowing what’s happening right now, while safety is about trusting that you can handle whatever comes next. Many people manage their finances responsibly yet still feel unsafe because their sense of control feels fragile. One surprise expense can make everything seem wobbly, even if the savings account exists for that exact reason.

Anxiety often shows up when people believe one wrong move could unravel everything. This belief doesn’t mean it’s true; it means the margin for emotional comfort feels narrow. When safety hasn’t been fully internalized, control becomes exhausting to maintain.

Social Comparison Fuels Invisible Pressure

Money anxiety loves a comparison trap, especially in a world where financial success is constantly displayed. Social media highlights vacations, renovations, side hustles, and milestone purchases without context. Even if you’re doing well, someone else always appears to be doing better, faster, or with less effort. This creates a subtle feeling of falling behind, even when your own goals are being met.

Cultural messages about success, productivity, and wealth quietly raise the bar higher than necessary. Anxiety grows in the gap between what you have and what you think you should have by now. The result is stress that feels personal but is actually socially engineered.

Why Calm Does Not Automatically Arrive

Many people expect financial peace to arrive the moment bills are paid consistently, but calm doesn’t work like a light switch. Emotional regulation takes practice, not just progress. Your nervous system needs repeated evidence that stability lasts, not just a single month of success. Anxiety lingers because it’s trying to protect you, even if it’s overdoing the job.

Learning to trust your own resilience is often harder than learning to budget. Without that trust, peace keeps getting postponed to some imaginary future milestone. Calm arrives slowly, built through experience, reassurance, and self-compassion rather than perfect numbers.

Why Does Financial Anxiety Show Up Even When Bills Are Paid
Image Source: Shutterstock.com

Making Peace With Money Feelings

Financial anxiety isn’t a contradiction; it’s a signal asking for understanding rather than judgment. Paying bills proves responsibility, but emotional security asks for patience and gentleness with yourself. When anxiety shows up, it doesn’t mean something is wrong; it means your brain is trying to keep you safe using outdated information. Awareness is the first step toward changing that relationship. Over time, recognizing patterns and reframing fear can soften its grip.

If any part of this felt familiar, the comments section below is a great place to add your voice and reflect on what money stress has looked like in your own life.

You May Also Like…

11 Anxiety Triggers Caused By Living Paycheck-to-Paycheck Still

7 Reasons You’re More Prone to Anxiety in Your 40s (And How to Fix It)

10 Common Budgeting Mistakes That Create Constant Money Stress

Risk Exposure: 9 Stress Tests Every Soon-to-Retire Investor Should Run

10 Things That Instantly Reduce Anxiety and Overthinking


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Finance Tagged With: anxiety, bills, comparison, finance, finances, financial anxiety, financial chocies, financial stress, general finance, Money, money issues, paying bills, prepaying bills, social anxiety, spending, stress, utility bills

  • « Previous Page
  • 1
  • …
  • 135
  • 136
  • 137
  • 138
  • 139
  • …
  • 157
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework