• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Technology

Can A New Smartphone Ruin Your Budget?

October 3, 2026 by Brandon Marcus Leave a Comment

Can A New Smartphone Ruin Your Budget?
A smartphone’s advertised monthly payment can tell only part of the story. Wireless service, insurance, accessories, financing terms, and trade-in conditions can all change the true cost of an upgrade – Shutterstock

A new smartphone can quietly become a budget problem long after the excitement of opening the box disappears. The phone itself may cost hundreds or even more than $1,000, but the real strain can come from the payment plan, wireless service, accessories, insurance, and other recurring charges attached to it.

That makes the purchase less like buying a gadget and more like adding another bill to the household. A manageable monthly payment can also make an expensive purchase feel smaller than it really is. The Federal Trade Commission warns consumers to look beyond payment amounts and examine the full cost of installment purchases, including fees and what happens if payments become difficult.

The Monthly Payment Can Hide the Real Price

Suppose a phone costs $1,000 and a retailer or carrier spreads the purchase across several dozen payments. A payment around $40 may not sound dramatic by itself. Add a wireless plan, device insurance, taxes, a case, screen protection, and perhaps a few accessories, and the monthly commitment starts looking very different.

That distinction matters because budgets rarely track purchases one at a time. They track everything that leaves the checking account. A $40 phone payment may compete with a streaming subscription, a higher utility bill, a credit card payment, or money that previously went into savings. The phone does not need to create a huge financial disaster to cause trouble. It only needs to consume money that the budget already had assigned somewhere else.

Installment financing also deserves a closer look. Some plans carry no interest, while other payment arrangements can include interest or fees. The CFPB advises consumers to review loan documents for fees and other charges rather than assuming the advertised payment tells the whole story.

The Phone May Not Be the Biggest Expense

The purchase price gets most of the attention, but the wireless plan can keep costing money long after the phone stops feeling new. Someone might upgrade because the device offers a better camera or more storage, then discover that the new arrangement also changes the monthly service bill.

That creates a sneaky budgeting problem. A shopper may compare two phones based on their device payments while ignoring differences in service requirements. Some promotions also depend on specific plans, trade-in conditions, or a commitment to keep the account active for a certain period. Those terms can change the financial picture.

The same issue appears with insurance and protection plans. Paying for coverage may make sense for some consumers, especially when replacing a damaged phone would strain their finances. But that recurring charge belongs in the budget too. A $15 monthly add-on becomes $180 over a year before any claim, deductible, or other condition enters the picture.

Trade-Ins Can Make a Costly Upgrade Look Smaller

Trade-in promotions can dramatically reduce the amount a shopper sees on the financing screen. That does not automatically make the upgrade inexpensive.

The value of a trade-in depends on the device, its condition, the promotion, and the terms attached to the offer. A phone that qualifies for a promotional credit may not produce that credit immediately as cash in the shopper’s pocket. Instead, the carrier or retailer may apply credits over time.

That distinction matters if someone plans to switch carriers, pay off the phone early, or upgrade again before the promotional period ends. The advertised trade-in value can look fantastic while the actual commitment remains substantial. Before accepting the offer, consumers should check how the credit works, how long it lasts, and what happens if the account changes.

A trade-in also has an opportunity cost. Selling an old phone independently might produce a different amount than accepting a carrier promotion. Neither option automatically wins. The useful comparison involves the total value received and the obligations attached to each choice.

A Phone Can Collide With Other Debt

The budget gets particularly delicate when the new phone arrives alongside existing debt. A consumer might comfortably handle a phone payment in a month with no surprises. That same payment can feel very different after a medical bill, car repair, insurance increase, or credit card balance appears.

Financing can also encourage a psychological shortcut: focusing on whether the monthly payment fits instead of asking whether the entire purchase fits. The FTC uses a similar warning for other financed purchases, noting that low payments can obscure a higher total cost.

Credit cards create another potential problem. Charging the entire phone and carrying the balance can turn a technology purchase into an interest-bearing debt. The FTC notes that carrying a credit card balance generally makes the purchase more expensive because interest applies to the unpaid amount.

A phone upgrade should not force a household to carry ordinary expenses on a credit card. If that happens, the purchase has effectively reached beyond the phone budget.

The Best Test Takes Five Minutes

Before buying, write down the phone’s full price and every recurring cost connected to it. Include the device payment, wireless service change, insurance, taxes, accessories, and any financing or service fees. Then compare that total with the amount currently available for discretionary spending each month.

Next, run one uncomfortable scenario. What happens if the budget loses $100 of breathing room for three months? Maybe a bill rises, work hours fall, or an unexpected repair arrives. If the phone payment leaves no flexibility, the purchase may carry more risk than the checkout screen suggests.

Also read the actual terms behind promotional financing. The CFPB notes that installment products can involve different fees, repayment structures, and credit-reporting practices.

There is nothing wrong with financing a phone when the arrangement fits the household’s finances. The problem starts when the payment works only under perfect conditions.

A Better Upgrade Starts With the Budget

A smartphone does not need to be cheap to be affordable. It needs to fit without forcing other financial priorities off the table.

That may mean keeping the current phone another year, choosing a less expensive model, buying outright, or waiting until enough cash has accumulated. It may also mean taking the expensive model but skipping extras that add recurring costs. The right choice depends on the household’s income, existing obligations, savings, credit terms, and how much value the new device actually provides.

The most useful number is therefore not the phone’s monthly payment. It is the amount of money the entire decision removes from the budget and for how long. Once that number becomes visible, the shiny new phone becomes much easier to evaluate like any other purchase.

Would you rather pay more upfront for a phone or accept a smaller monthly payment over several years? Share your approach in the comments.

You May Also Like…

FCC Wants Tougher Robocall Rules to Keep Bad Actors Out of U.S. Phone Networks

Phone and Internet Discounts Seniors May Still Qualify For After ACP Ended

10 Financial Traps Hidden in Cell Phone Contracts

15 Pieces of Technology Gen Z Can’t Live Without That Are Actually Regressive

5 Phone Scam Warning Signs Too Many Americans Ignore

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Technology Tagged With: budgeting, consumer spending, Debt, mobile phones, monthly payments, Personal Finance, smartphones, technology

Searching Google to Pay a Bill Could Lead to the Wrong Website

September 22, 2026 by Brandon Marcus Leave a Comment

Searching Google to Pay a Bill Could Lead to the Wrong Website
A paid search result can appear above a company’s regular listing, so checking the website address before entering payment information can help consumers avoid third-party fees and fraudulent lookalike sites – Shutterstock

Searching Google for a bill-payment website can feel like one of the safest things possible. Type the company name, find the familiar-looking result, click, pay, and move on with the day.

That routine can go sideways, though, because the first result may not belong to the company you searched for. The Federal Trade Commission recently warned that dishonest businesses can use paid search advertisements to steer people toward third-party payment websites. In some cases, those sites can add fees or create the impression that they represent the company whose name appeared in the search.

The problem does not require a dramatic fake website covered in spelling errors. Sometimes the danger starts with a perfectly ordinary search.

The First Result Is Not Necessarily the Company

Search engines place paid advertisements above many unpaid results. Those ads can look remarkably similar to ordinary search listings, especially when someone searches for a familiar business followed by words such as “pay bill” or “make payment.”

The FTC recently described a case involving Doxo, a third-party bill-payment platform. The agency alleged that Doxo used search advertising that could make consumers think they had reached an official payment channel for companies and agencies, including Labcorp, AT&T, and state toll authorities. The FTC said Doxo often had no relationship with the companies consumers believed they were paying, and alleged that the service added fees to some payments. Doxo agreed to pay $2.1 million to settle the FTC’s allegations without admitting wrongdoing.

That distinction is important because a third-party payment service and a criminal phishing site are not automatically the same thing. A consumer can still land somewhere other than the intended company’s payment system and face unexpected costs or confusion about where the money goes.

The FBI has separately warned about criminals buying search advertisements that imitate legitimate businesses. Those ads can lead to convincing fake websites designed to collect passwords, financial information, or other sensitive data.

A Familiar Logo Does Not Settle the Question

A company logo can create instant confidence. So can familiar colors, a recognizable business name, and a payment page that looks polished.

None of those details proves who operates the website. The FTC’s recent bill-payment warning recommends checking the destination instead of assuming the search result tells the whole story. Look for the small “Ad” or “Sponsored” label beside a result. Then check the website address carefully before entering an account number, password, card number, or bank information. The FBI also recommends checking URLs for small differences, including misspellings that can make a fraudulent address resemble a legitimate one.

A strange-looking domain does not automatically mean fraud, either. Some legitimate businesses use different payment processors or separate domains for billing. That is why the safest check involves the company itself.

If a paper bill provides the company’s website, type that address into the browser rather than searching for it. If the company sends customers to a separate payment provider, its official website should identify that relationship.

The Bill Itself Can Give You a Safer Route

The piece of mail or email that creates the bill may also contain the information needed to avoid the search-result problem.

Check the bill for the company’s official website, customer-service number, or instructions for online payments. A phone number printed on a statement gives you a more direct route than grabbing the first number that appears in a search.

That distinction matters with utilities, too. The FTC advises consumers with questions about utility accounts to contact the company through the number on the bill or the company’s known website. It specifically warns that search results can lead consumers to paid advertisements from businesses that impersonate utilities or charge additional fees for bill payments.

There is another useful habit here: separate the search for information from the search for a payment button. Someone might reasonably search Google to find a company’s customer-service page. That does not mean the first payment-related result deserves the same trust as a website the company itself identifies as official.

Slow Down Before the Payment Screen

The most useful moment to stop is before entering payment information. Look at the web address. Check whether the page identifies the actual company receiving the payment. Read the payment terms before submitting anything, particularly if the page mentions processing, delivery, convenience, or service fees.

A payment page that suddenly asks for information that seems unrelated to the bill deserves another look. So does a page that pressures you to use an unusual payment method. The Consumer Financial Protection Bureau lists demands for gift cards, cryptocurrency, wire transfers, payment apps, or other hard-to-recover payment methods among common fraud warning signs.

A normal payment deadline can create plenty of pressure without anyone adding more. If a page makes the situation feel unusually urgent, closing the tab and verifying the site through the company’s known contact information can prevent an expensive mistake.

Already Paid Through the Wrong Site? Act Quickly

Finding out that a payment went through an unfamiliar website does not necessarily mean the money disappeared. The next steps depend on what happened, who received the payment, and how the transaction occurred.

Start by checking the payment confirmation and your bank or card account. Save the receipt, website address, emails, and transaction details. If you suspect fraud, contact the financial institution or payment provider through a trusted phone number or website and ask what options exist for the transaction.

If you entered a password on a suspicious site, change that password through the legitimate company’s website. Do not use a link from the suspicious page or any follow-up message to make the change.

The CFPB recommends contacting financial institutions and government agencies through trusted websites and phone numbers when reporting suspected fraud. Consumers can also report scams to the FTC, and suspected internet crime can be reported to the FBI’s Internet Crime Complaint Center.

A Two-Second Check Can Change the Whole Payment

Google can still be a useful starting point for finding information. The mistake comes from treating the first result as proof that the destination belongs to the company being searched.

For recurring bills, there is an even easier solution. Once the legitimate website has been verified, bookmark it or save the address in a password manager. The next payment can begin with that known destination instead of another search.

That small change removes one layer of uncertainty from an otherwise routine chore. A bill may still arrive with an annoying due date, but at least the payment does not have to begin with a guessing game.

Have you ever clicked a search result expecting an official bill-payment page and discovered that another company was behind it?

You May Also Like…

New York Attorney General Warns of Gold Bar Scam That Has Cost Victims More Than $100 Million

New IRS Matching Technology Is Catching Income Discrepancies That Used to Slip Through

Making your Company Website More User-Friendly

Scan a QR Code to Pay? Check These 3 Things Before Entering Your Card Number

See a Charge From a Company You Don’t Recognize? Don’t Assume It’s Just a Subscription You Forgot

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Technology Tagged With: bill payment, Consumer Protection, FTC', Google Search, identity theft, Online Safety, online scams, phishing

How to Keep Your Home Secure on a Budget

August 23, 2026 by Erin H. Leave a Comment

Keeping your home secure doesn’t have to mean spending thousands of dollars on an elaborate security system. In many cases, a few affordable upgrades, better habits, and regular maintenance can make a meaningful difference. The key is to focus your budget on the areas burglars and household hazards are most likely to exploit.

Start With Your Doors

Exterior doors are one of the first places to concentrate your security efforts. A strong door is only as effective as the hardware securing it, so inspect your locks and replace worn or low-quality options. Installing durable deadlocks on outside doors and making sure window locks are actually engaged can substantially lower the chances of an opportunistic break-in.

Don’t overlook the condition of the door itself. Check for loose hinges, damaged frames, or gaps that could make forced entry easier. If your door has glass panels, consider whether they provide easy access to the lock. Reinforcing vulnerable areas can often cost far less than installing a comprehensive alarm system.

Make locking up part of your daily routine. Even the best security hardware cannot help if doors and windows are left unsecured.

Make Windows Work for You

Windows can create two problems at once: they can be potential entry points and major sources of energy loss. Because windows are a weak point in a home’s thermal envelope, they can account for as much as 40% of the heat a house loses. Improving them can therefore support both security and household efficiency.

Begin with the basics. Make sure every accessible window has a functioning lock, and replace broken latches promptly. Basement and ground-floor windows deserve particular attention because they are easier to reach from outside.

For additional protection, inexpensive window security film can make glass harder to shatter and penetrate. Curtains or blinds can also prevent people outside from seeing valuable belongings inside your home. During the evening, use lighting strategically so your windows do not reveal an unattended property.

Use Lighting as a Low-Cost Deterrent

Good outdoor lighting can provide significant security value without a major investment. Motion-activated lights are particularly useful around entrances, driveways, garages, side passages, and other areas that are hidden from the street.

You do not necessarily need to illuminate the entire property. Instead, identify places where someone could approach the house without being easily noticed. A reasonably priced motion sensor light in one of these locations may be more useful than several decorative fixtures.

Inside the home, timers can create the appearance that someone is present when you are away. Set a few lights to turn on and off at different times rather than leaving one light running continuously.

Don’t Advertise Your Valuables

Security also involves controlling what potential thieves can see. Keep expensive electronics, jewelry, tools, and other desirable possessions away from windows. If you purchase a high-value item, avoid leaving its packaging beside the curb where it can announce what is now inside your home.

For longer trips, ask a trusted neighbor to collect mail and packages. An overflowing mailbox or pile of deliveries can quickly signal that nobody is home. Similarly, keep your lawn maintained and arrange for snow removal when you are away during winter.

Protect Your Home From Electrical Fires

Home security is about more than preventing burglary. Fire protection should also be part of a sensible budget, especially because inexpensive preventive measures can reduce potentially devastating losses.

The National Fire Protection Association reports that roughly 15% of home electrical-structure fires begin in kitchens or cooking spaces, making these areas particularly important to monitor. Keep appliances away from water, avoid overloading outlets, and replace damaged cords rather than continuing to use them.

Another concern is outdated electrical equipment. ZipDo estimates that 40% of American households contain at least one aging electrical device that can elevate fire danger. Replace old or malfunctioning appliances when practical, and pay attention to warning signs such as overheating, unusual odors, sparks, or repeatedly tripped breakers.

Smoke alarms are among the most affordable safety investments available. Install them on every level and near sleeping areas, test them regularly, and replace batteries as recommended. A small fire extinguisher rated for kitchen use is another inexpensive addition to your household safety plan.

Keep Pests From Eating Into Your Budget

Pests can cause a surprisingly large amount of structural damage. Termites are particularly destructive because their activity can remain hidden until significant damage has occurred. In the United States, termite damage exceeds the combined property losses caused by fires and floods, with annual costs to homeowners topping $5 billion.

Preventive maintenance is usually cheaper than major repairs. Look for signs such as discarded wings, mud tubes, hollow-sounding wood, or small piles of insect debris. Keep wood, cardboard, and other cellulose-rich materials away from your home’s foundation, and address moisture problems promptly.

Regularly inspect areas that are dark, damp, or difficult to access, including crawl spaces, basements, and around plumbing. If you suspect an infestation, getting professional advice early may help prevent a minor issue from becoming a major structural expense.

Add Smart Security Where It Counts

Technology can improve home security without requiring a full smart-home overhaul. A basic video doorbell or security camera can provide visibility around key entry points, while inexpensive sensors can alert you when doors or windows are opened.

The trick is to avoid paying for features you do not need. Start with the most vulnerable locations and expand only if necessary. Some homeowners may get more practical value from one well-positioned camera and strong door hardware than from a large collection of connected devices.

Also secure your digital equipment. Use strong, unique passwords for security cameras, routers, and smart-home accounts, and enable two-factor authentication when available. A sophisticated physical security setup can still create problems if its online accounts are poorly protected.

Build a Security Routine

Finally, remember that consistency matters more than expensive equipment. Before going to bed or leaving home, take a quick tour: lock exterior doors and accessible windows, check that appliances are switched off, confirm that outdoor lights are functioning, and make sure valuables are not visible.

Walk around your property occasionally and look at it from an outsider’s perspective. Are there dark corners? Overgrown shrubs near windows? An unlocked gate? A ladder sitting outside? Fixing these small weaknesses can cost little or nothing.

The most effective budget-friendly security strategy is layered. Combine strong locks, sensible lighting, secured windows, fire precautions, pest prevention, and a few carefully chosen technology upgrades. By addressing vulnerabilities before they become expensive problems, you can make your home safer without putting unnecessary strain on your wallet.

Filed Under: Home Improvement, Technology

What to Know About Payment-App Records to Save Before Disputing a Transfer

August 3, 2026 by Brandon Marcus Leave a Comment

What to Know About Payment-App Records to Save Before Disputing a Transfer
A smartphone displaying a payment confirmation screen. Fraud prevention, documentation, and smart digital money habits need to be top of mind for anyone using payment apps – Shutterstock

A payment-app transfer can feel almost too easy. A few taps, a confirmation screen, and money moves from one account to another, but that convenience can create a headache when something goes wrong. Saving the right records before disputing a transfer can help people organize the details and explain what happened clearly.

Payment apps handle money quickly, but problems can become messy just as fast. A missing payment, suspected scam, or unauthorized transaction often leaves people searching through notifications and emails like a detective hunting for clues. A little preparation can make that search much easier.

Save the Details Before a Payment Problem Appears

Payment-app records can tell the story of a transaction from start to finish. Save details such as the date, amount, recipient information, transaction ID, and any messages connected to the payment. These small pieces of information create a timeline that helps explain the situation.

Screenshots can also help preserve important details before an app changes a screen or removes older information. Keep confirmation pages, chat conversations, emails, and alerts related to the transfer in one secure place. A digital folder labeled with the payment date can turn a stressful search into a simple review.

The Consumer Financial Protection Bureau recommends taking steps to protect against fraud and keeping information that can help when reporting problems. Records do not guarantee a refund or recovery, because consumer protections vary by transaction type. Still, organized information gives a clearer picture of what happened when someone contacts a payment provider or files a complaint.

Build a Simple Timeline Instead of a Mystery File

A good payment dispute starts with a clear timeline. Write down what happened, including when the transfer started, who received the money, what communication occurred, and when the problem appeared. A timeline keeps important facts together instead of scattered across dozens of notifications.

Imagine someone sends money after receiving a message from a person pretending to represent a company. The payment goes through, then the sender realizes the message was a scam. Saved messages, payment confirmations, and account details can help show the sequence of events.

Avoid editing or deleting conversations connected to the transaction. Even a short message that seemed unimportant at the time may provide useful context later. A clean timeline helps remove confusion and keeps the focus on the facts.

Know What Information to Share During a Dispute

Payment providers need specific details to review a problem. Share the transaction amount, date, account information related to the payment, and a description of why the transfer needs review. Clear explanations work better than a long message filled with guesses or frustration.

Keep copies of everything sent during the dispute process. Save confirmation emails, case numbers, and any responses from the payment company. These records create a trail that helps track the issue from the first report through later conversations.

The Consumer Financial Protection Bureau also provides a complaint process for people who cannot resolve certain issues directly with a company. A complaint should include accurate details and supporting documents that explain the situation. Consumer protections differ depending on the type of transaction, so no process promises a guaranteed recovery.

Avoid Common Mistakes That Can Slow Down Help

One common mistake involves waiting too long before gathering information. Notifications disappear, memories become fuzzy, and important details can slip away after a stressful payment problem. Quick action helps preserve the facts while they remain fresh.

Another mistake involves sending incomplete information. A dispute that says only “the payment went wrong” leaves too many questions unanswered. Adding dates, amounts, names, messages, and transaction records creates a much stronger explanation.

People also should avoid sharing sensitive account details publicly while asking for help online. Payment records can contain personal information that belongs in private conversations with the company or official complaint channels. Careful record keeping should protect money without creating another security problem.

Turn Payment Records Into a Helpful Money Safety Habit

Saving payment-app records does not need to become a giant paperwork project. A few minutes spent storing confirmations and important messages can create a valuable safety net. Think of it like keeping a receipt for a major purchase, except the receipt lives inside a digital wallet.

The best time to organize payment records comes before a problem appears. Create a simple habit of checking transaction details and keeping important confirmations. That small routine can make future disputes less confusing and more manageable.

What steps do you take to keep track of your payment-app transactions and protect yourself from problems?

You May Also Like…

Social Security Now Requires Electronic Benefit Payments for Most Recipients

Working, Overpayments, and 2 Other Reasons Social Security Benefits Can Change

Deepfakes and Fake AI Breakthroughs: The Investment Scams the SEC Is Now Targeting

9 Warning Signs a Social Media Investment Group Is Really a Scam

7 Private Student Loan Complaint Records Families Should Keep Until the Balance Is Cleared

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Technology Tagged With: Consumer Protection, financial records, fraud prevention, money transfers, payment apps

5 Financial Data Permissions Consumers Should Review Before Linking a Budgeting App

July 14, 2026 by Brandon Marcus Leave a Comment

5 Financial Data Permissions Consumers Should Review Before Linking a Budgeting App
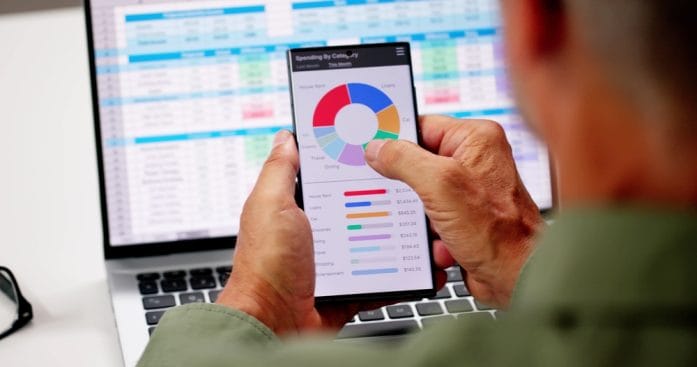
A smartphone displaying a budgeting app highlights the importance of reviewing financial data permissions before connecting accounts – Shutterstock

Connecting a budgeting app to your bank account takes less than a minute. Understanding exactly what you’re giving that app permission to see can take much longer—and many people never look beyond the “Allow” button.

“Too many Americans are stuck in financial products with lousy rates and service,” said former CFPB Director Rohit Chopra back in 2024. And the same continues to be true today. A few minutes spent checking what an app can access can prevent surprises later and help people make smarter choices about their personal financial information.

1. Check Exactly Which Accounts the App Can Reach Before Connecting

The first permission to review involves the accounts a budgeting app can access after a connection gets approved. A money management tool might request information from checking accounts, savings accounts, credit cards, loans, or investment accounts, depending on its features. Before approving anything, consumers should confirm that the app only reaches accounts that actually help with the budgeting goal. Giving an app access to every financial account simply because the button says “connect all” can create unnecessary exposure.

A practical example shows why this matters: someone who wants help tracking grocery spending probably does not need an app connected to a retirement account or an old credit card they rarely use. Consumers should look for clear explanations about the purpose of each connection request instead of clicking through quickly. The Consumer Financial Protection Bureau finalized a personal financial data rights rule designed to give families more control and choice over financial data sharing while encouraging competition among financial service providers. The rule also focuses on privacy protections and consumer access to financial information.

2. Review What Type of Financial Data the App Collects and Uses

Data categories deserve a close look because not every budgeting app needs the same information to work properly. Some apps only need transaction details, while others may request account balances, income information, or recurring payment history. Consumers should check whether the app collects more information than necessary for the features they want. A simple spending tracker should not require a digital treasure map of someone’s entire financial life.

Not every budgeting app requests the same level of access. Some only receive read-only transaction data, while others may ask for permissions that allow bill payments, transfers, or payment initiation.

Small details often reveal a company’s approach to privacy, so the privacy policy deserves more than a quick scroll. Look for explanations about how the app uses transaction records, whether it creates financial profiles, and whether it keeps information after an account closes. A person who only wants help managing monthly expenses may feel uncomfortable if an app uses financial patterns for additional purposes. Reviewing those details helps consumers choose tools that match their comfort level instead of accepting every request automatically.

3. Look at Permission Duration and How Access Ends

Many people check permissions during signup but forget about them months later when their financial habits change. Consumers should review whether an app keeps access continuously or requires occasional approval again. A budgeting tool that helped during a busy season may no longer need access after someone changes their money routine. Removing unused connections can reduce unnecessary data sharing and keep digital accounts cleaner.

Closing an app account does not always mean every connection disappears instantly, so consumers should follow the company’s instructions for removing access. Banks and financial institutions often provide account management tools where customers can review connected services and revoke permissions. A quick digital cleanup once or twice a year can prevent forgotten apps from holding onto access long after they stop providing value. Think of it like cleaning out a kitchen drawer full of gadgets, except the clutter involves financial information instead of old utensils.

4. Understand Third-Party Sharing and Security Practices

A budgeting app may rely on outside companies to help connect accounts, process information, or provide certain features. Consumers should check whether their financial data travels beyond the main app and which partners receive access. The name of a familiar budgeting app does not automatically explain every company involved behind the scenes. Clear information about third-party relationships helps consumers make better decisions before connecting accounts.

Security details also deserve attention because financial information requires careful handling. Consumers should look for features such as strong account protections, secure login options, and clear explanations of how companies protect stored information. No app can promise perfect safety, but responsible companies explain their practices instead of hiding behind vague language. Asking questions before linking accounts can prevent frustration later if a privacy concern appears.

It’s also advisable to look for budgeting apps that support multi-factor authentication, biometric login, or passkeys and clearly explain how financial information is encrypted both during transmission and while stored.

5. Confirm Data Deletion Options Before Sharing Information

Data deletion choices represent another important permission that many people overlook during signup. Consumers should check whether an app lets them request deletion of personal information when they leave the service. Keeping old financial data around can create unnecessary concerns, especially when a person no longer uses the tool. A good budgeting app should make it clear how customers can manage their information over time.

Before connecting an account, consumers should save details about the company’s privacy settings and account removal process. Taking screenshots of permission pages or saving important instructions can help if questions appear later. Digital financial tools work best when people stay involved instead of treating account connections like a one-time decision.

Many newer budgeting apps connect through secure APIs rather than older “screen scraping” methods that required users to share online banking credentials. Secure API connections generally allow consumers to control exactly what data is shared while reducing the need to provide banking passwords directly.

Most importantly… Deleting the app from your phone doesn’t necessarily revoke financial access. Consumers should confirm they’ve disconnected bank accounts, revoked data-sharing permissions, and requested deletion of stored information when they stop using the service.

Before Connecting an Account, Check Whether the App Can Access:

  • Transaction history
  • Account balances
  • Investment accounts
  • Loan information
  • Account and routing numbers
  • Payment initiation
  • Identity information
  • Income data

Consumers should only approve permissions that are necessary for the features they actually intend to use.

A Smarter Way to Connect Money Tools Without Losing Control

Reviewing financial data permissions does not mean avoiding budgeting apps altogether because these tools can help people organize spending and build better habits. The goal involves making informed choices about what information an app receives and why it needs that information. Consumers who check account access, data use, sharing practices, and deletion options create a stronger layer of protection around their finances. The best financial tools combine useful features with respect for personal privacy. A little caution before tapping “allow” can save plenty of headaches later.

What steps do you take before connecting a budgeting app to your bank accounts, and which privacy settings matter most to you?

You May Also Like…

The “Loud Budgeting” Trend and Transparent Money Conversations

New York Renters Say Their Budget Stretch Isn’t Coming From Rent Alone Anymore

The New Banking Frustration of 2026: More Customers Say Fraud Alerts Are Blocking Legitimate Purchases

Why Some Banks Are Suddenly Freezing Large Zelle Transfers

Don’t Wait Until 2033: The Ugly Medicare Trust Fund Truths Missing From Your Budget

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Technology Tagged With: budgeting apps, CFPB, data permissions, digital banking, financial privacy, money management, Personal Finance

8 Jobs That AI Will Never Be Able to Take Over

May 29, 2026 by Brandon Marcus Leave a Comment

8 Jobs That AI Will Never Be Able to Take Over
Some jobs, such as teachers, should be safe in the age of AI – but are they? – Shutterstock

Artificial intelligence keeps reshaping industries at lightning speed, but not every job fits neatly into an algorithm. Some careers rely on physical presence, emotional intelligence, or split-second human judgment that machines still struggle to replicate.

While automation continues to grow, certain roles stay firmly anchored in human capability. These jobs also offer long-term stability in an uncertain labor market. The list below highlights careers that continue to thrive even as AI expands.

1. Electricians and Skilled Trades Workers

Electricians work in unpredictable environments where every building presents unique wiring challenges. They troubleshoot real-world problems that change from job to job, and no two houses ever tell the same story. AI can suggest solutions, but it cannot safely climb into an attic or crawl through a tight basement space.

These professionals also interpret building codes, physical layouts, and unexpected hazards in real time. One wrong assumption can lead to serious safety risks, so human judgment drives every decision. Skilled trades continue to grow in demand because infrastructure always needs hands-on expertise.

2. Nurses and Hands-On Healthcare Workers

Nurses provide direct patient care that requires emotional awareness, quick thinking, and physical interaction. They monitor subtle changes in condition that often come from observation rather than data alone. AI can support diagnostics, but it cannot comfort a patient during a difficult night.

Hospital environments shift rapidly, and nurses constantly adjust priorities based on urgency and human need. They also communicate with families in emotionally charged situations that require empathy and clarity. Healthcare will always depend on people who combine skill with compassion.

3. Teachers in Early Education and Special Needs

Teachers shape how students learn, grow, and build confidence in real time. They adjust lesson plans based on mood, behavior, and classroom dynamics that change daily. AI tools can assist with learning materials, but they cannot manage a room full of unpredictable human personalities.

Early education especially depends on emotional connection and trust between teacher and student. Special needs education requires constant adaptation and deep personal engagement. Strong teachers influence lifelong development in ways no software can replicate.

4. Firefighters and Emergency Responders

Firefighters face unpredictable danger where every second matters and conditions shift rapidly. They assess structural risks, weather conditions, and human behavior under extreme pressure. AI cannot physically enter a burning building or make split-second rescue decisions.

Emergency responders also coordinate teamwork in chaotic environments where communication must stay clear and immediate. They rely on experience, instincts, and training to save lives in real time. These roles demand courage and presence that technology cannot replace.

8 Jobs That AI Will Never Be Able to Take Over
Sadly, we will always need firefighters, but can AI make an impact on that profession? – Shutterstock

5. Mental Health Professionals and Therapists

Therapists guide people through emotional challenges that require trust, empathy, and deep human connection. They notice tone, body language, and emotional shifts that go far beyond data points. AI chat tools may simulate conversation, but they cannot build genuine therapeutic relationships.

Sessions often involve unpredictable emotional breakthroughs that require careful human response. Mental health professionals also adjust strategies based on lived experience and subtle feedback. Healing conversations rely on presence, not programming.

6. Chefs and Culinary Creators

Chefs transform ingredients into experiences that rely on taste, texture, and creativity. They adjust recipes on the fly based on ingredient quality, customer preferences, and sensory feedback. AI can suggest recipes, but it cannot smell, taste, or plate food with artistic instinct.

Restaurant kitchens also operate under intense pressure where timing and coordination matter. Chefs lead teams, manage chaos, and maintain consistency under stress. Culinary work thrives on human creativity that technology struggles to match.

7. Social Workers and Community Advocates

Social workers handle complex human situations involving families, housing, safety, and emotional distress. They assess real-life circumstances that require compassion and careful judgment. AI can process data, but it cannot walk into a home and build trust with vulnerable individuals.

These professionals also navigate systems like courts, schools, and healthcare providers. Every case involves unique emotional and logistical challenges that demand flexibility. Social work depends on human connection at its core.

8. Artists, Performers, and Creative Professionals

Artists create meaning through expression, emotion, and cultural perspective. They produce work shaped by personal experience, imagination, and social context. AI can generate images or music, but it cannot live a human story.

Performers also connect with audiences through energy, presence, and spontaneity. Every performance changes based on crowd reaction and emotional flow. Creative fields thrive on originality that comes from lived experience.

Why Human Careers Still Hold the Future

Human-centered jobs continue to resist automation because they rely on qualities AI cannot fully replicate. Emotional intelligence, physical presence, and moral judgment drive decisions in unpredictable environments. Many of these roles also involve responsibility for human safety, learning, or well-being. That responsibility requires accountability that machines cannot shoulder. As technology grows, these careers will likely become even more valuable, not less.

What job do you think will stay fully human no matter how advanced AI becomes?

You May Also Like…

Why Banks Are Watching Large Transfers More Closely Than Ever

4 Bold Predictions About The Future of Personal Finance Technology

15 Pieces of Technology Gen Z Can’t Live Without That Are Actually Regressive

11 Careers With Big Money But Zero Appeal

Hidden Hazards: Exploring the Dark Side of Popular Careers

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Technology Tagged With: AI jobs, Career Advice, Education, future of work, healthcare careers, job security, skilled trades, technology trends

How AI Is Changing Personal Finance Faster Than Most Consumers Realize

May 29, 2026 by Brandon Marcus Leave a Comment

How AI Is Changing Personal Finance Faster Than Most Consumers Realize
AI is everywhere, including in many of the personal finance tools that we use daily – Shutterstock

Artificial intelligence now sits inside everyday money tools and reshapes financial decisions at a speed that surprises most users. Budgeting apps, investment platforms, and lending systems all rely on machine learning models that process behavior in real time. These systems no longer wait for monthly reports or human input to adjust financial guidance. Instead, they react instantly to spending patterns, income changes, and even subtle habits like subscription activity. That speed creates a financial environment where decisions form before users even notice the shift.

This change does not stay hidden in the background anymore, because AI actively shapes what people see on their screens. Personalized insights, automated savings rules, and predictive alerts now guide millions of users each day. Financial platforms compete by offering smarter recommendations that feel tailored and intuitive. That competition pushes AI deeper into personal finance tools at a rapid pace.

AI Is Quietly Rewriting Budgeting Apps

Budgeting apps now act less like simple trackers and more like active financial assistants that learn from user behavior. AI systems categorize transactions instantly and adjust spending insights based on evolving habits. These platforms highlight risks such as rising food costs or sudden subscription spikes before users manually review statements. That real-time feedback loop encourages faster financial decisions and reduces reliance on end-of-month reviews. Many apps now predict future cash flow based on historical spending patterns and income timing.

These tools also push users toward better habits through subtle behavioral nudges that feel natural rather than forced. AI models detect when users overspend in certain categories and automatically suggest corrective actions. Some platforms even adjust savings goals dynamically when income fluctuates or expenses increase. That flexibility creates a more responsive financial system that adapts to real life rather than fixed budgets. Consumers often notice improved financial stability without realizing how many automated decisions drive those results.

Smarter Investing Tools That React in Real Time

Investment platforms now use AI to analyze market movements faster than any human trader can react. Algorithms scan global news, earnings reports, and trading patterns to identify opportunities within seconds. These systems then adjust portfolio recommendations based on risk tolerance and market volatility. That constant recalibration creates a dynamic investing environment that evolves throughout the day. Many retail investors now rely on AI-driven insights without needing deep financial expertise.

Robo-advisors also use machine learning to rebalance portfolios automatically and reduce emotional decision-making. These platforms remove hesitation during market dips by following pre-set risk models powered by AI analysis. Some systems even simulate long-term financial outcomes to guide investment choices with more precision. That predictive capability helps users avoid panic-driven decisions that often hurt returns. The combination of speed and automation transforms investing into a more structured and data-driven experience.

How AI Is Changing Personal Finance Faster Than Most Consumers Realize
From budgeting to investing, AI is changing the way smartphone apps work – Shutterstock

AI Credit Scores and Lending Decisions Move Faster Than Humans

Credit scoring no longer depends only on traditional reports because AI expands the range of data points lenders analyze. Machine learning models evaluate spending behavior, payment timing, and financial consistency in real time. That expanded analysis allows lenders to make faster approval decisions with more personalized risk assessments. Borrowers often receive credit offers within seconds instead of waiting days for manual review. This speed changes how people access loans, credit cards, and financing options.

Lending platforms also use AI to adjust interest rates based on continuous risk evaluation. That system rewards consistent financial behavior while tightening terms for higher-risk activity. Some fintech companies now update credit insights daily instead of monthly, which increases transparency for consumers. That frequent updating helps users track how financial decisions influence their credit health. The result creates a more dynamic credit system that reacts to behavior almost immediately.

What This Shift Means for Everyday Money Decisions

AI-driven finance tools now shape nearly every aspect of personal money management, from budgeting to borrowing. These systems reduce friction by automating decisions that once required manual effort or financial expertise. Users gain convenience, but they also rely more heavily on algorithms that influence outcomes behind the scenes. That reliance makes transparency and awareness more important than ever for financial confidence. People who track how these tools operate often make more informed decisions about their money habits.

What do you think about AI taking a bigger role in personal finance decisions? It’s an important topic, so now is the time to talk about it in our comments.

You May Also Like…

Cost Effective Strategies in Nursing Education and Trainings

Why Banks Are Watching Large Transfers More Closely Than Ever

Could Everyday Technology Be Quietly Stealing Wealth

8 Personal Finance Beliefs That No Longer Apply

10 Personal Finance Lessons People Learn the Hard Way

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Technology Tagged With: AI, budgeting apps, credit scores, fintech, investing, money management, Personal Finance

New Rule Requires Venmo and PayPal Users to Verify Tax Info—or Risk Losing Access

May 16, 2026 by Brandon Marcus Leave a Comment

New Rule Requires Venmo and PayPal Users to Verify Tax Info—or Risk Losing Access
Someone using Venmo in front of the PayPal logo – Shutterstock

Digital payments keep reshaping how money moves across the United States, but a new layer of scrutiny now changes the game for millions of users. Venmo and PayPal users face growing pressure to verify tax information as financial regulators push for tighter reporting standards. Platforms that once felt casual and frictionless now sit under the same compliance spotlight as traditional banks. Small transactions between friends, side hustle payouts, and freelance income all now fall into a more structured financial reporting system. That shift signals a major turning point in how everyday money transfers get tracked and reported.

The push for tax verification connects directly to broader federal efforts aimed at closing reporting gaps in digital income. Payment platforms must now confirm taxpayer details for users who cross certain earning thresholds or trigger reporting requirements. Without verified information, accounts can face restrictions, payment holds, or even temporary loss of access to sending and receiving funds. Many users only notice the change when a transaction suddenly fails or a notification requests updated tax documentation.

Why Venmo and PayPal Now Demand Tax Verification

Venmo and PayPal now operate under stricter financial reporting rules that align more closely with IRS expectations. These platforms must collect accurate taxpayer information such as Social Security numbers or Employer Identification Numbers for qualifying accounts. The shift connects to expanded reporting requirements that target income earned through digital payment apps, especially in gig work and freelance transactions. Even casual sellers and side hustlers may now trigger verification requests if their transaction volume or total payments exceed reporting thresholds. This change aims to improve tax transparency and reduce underreported income across digital ecosystems.

The IRS continues to increase oversight of third-party payment processors as online income grows across the country. Platforms now flag accounts that show consistent incoming payments labeled as goods and services instead of personal transfers. Users who ignore verification prompts may experience delayed deposits or limited access to key features like instant transfers. Financial systems now prioritize compliance early in the user journey rather than after issues arise. This approach creates a tighter connection between everyday digital spending and official tax reporting systems.

What Happens If Users Ignore Verification Requests

Account restrictions often begin with simple limitations on sending or receiving money until users submit tax information. Venmo and PayPal typically send repeated alerts before escalating restrictions, but delays can still interrupt cash flow. Freelancers who rely on quick payments for services may feel the impact within hours of a flagged transaction. The platforms may also freeze certain features, including card withdrawals or business transaction capabilities. These safeguards protect compliance but can surprise users who never previously treated these apps as financial institutions.

Long-term noncompliance creates more serious consequences, including potential account suspension or mandatory identity verification checks. Payment processors now coordinate more closely with tax authorities to ensure reported income matches user records. Users who repeatedly ignore requests risk losing access to transaction history needed for tax filing. Business accounts face even stricter enforcement due to higher transaction volumes and commercial activity classification. These rules push users toward treating digital wallets with the same seriousness as bank accounts.

New Rule Requires Venmo and PayPal Users to Verify Tax Info—or Risk Losing Access
A magnifying glass looking at Venmo online – Shutterstock

Who Feels the Biggest Impact From These Rules

Gig workers and freelancers experience the strongest impact because they rely heavily on platforms like Venmo and PayPal for income. Delivery drivers, tutors, designers, and consultants often receive frequent payments that quickly reach reporting thresholds. Casual sellers on marketplaces also face increased scrutiny when payments shift from occasional to consistent activity. Even hobby sellers who occasionally move items online may see unexpected verification prompts. The system now blurs the line between casual use and business activity.

Younger users and part-time workers also encounter confusion when personal transactions trigger compliance checks. A friend sending payment for shared expenses might look different from business income if the transaction descriptions or patterns shift. Many users underestimate how quickly small payments add up over a calendar year. Tax reporting systems now analyze cumulative activity instead of single transactions alone. This shift forces users to track digital payments more carefully than ever before.

How Users Can Stay Ahead of Compliance Changes

Users can avoid disruptions by verifying tax information early instead of waiting for platform prompts. Updating Social Security numbers, business details, and legal names helps payment apps maintain uninterrupted service. Tracking incoming payments throughout the year also helps users understand when reporting thresholds might apply. Many financial advisors recommend separating personal and business transactions to reduce confusion during tax season. These habits reduce the risk of unexpected account restrictions.

Staying organized also helps users prepare for tax filings without scrambling for missing records. Digital payment histories now play a major role in determining taxable income for many independent earners. Platforms increasingly send annual summaries that align with IRS reporting forms like 1099-K documentation. Users who proactively review these summaries can catch discrepancies early and avoid penalties. Financial awareness now matters as much as convenience in the modern payment landscape.

What This Means for Everyday Digital Money

Digital wallets no longer function as informal money-sharing tools without oversight or structure. Venmo and PayPal now sit firmly inside a regulated financial ecosystem that tracks income and verifies identity. This shift reflects a broader national move toward transparency in digital financial activity. Users who adapt early avoid disruptions and maintain smoother access to funds. The future of digital payments now ties convenience directly to compliance.

Payment apps continue evolving into full financial platforms that mirror traditional banking expectations. That evolution brings stronger protections but also more responsibility for users who rely on them daily. Tax verification rules signal only the beginning of more structured oversight in the digital economy. Users who stay informed and organized will navigate these changes with fewer surprises. The landscape now rewards proactive financial management over casual usage habits.

How do you feel about these changes in Venmo and PayPal rules, and do they make digital payments feel more secure or more complicated?

You May Also Like…

The Venmo Privacy Setting That Can Trigger Unwanted Tax Reporting

IRS Warning: That Venmo Payment for Your Garage Sale Just Triggered a Surprise Tax Bill

7 “Trigger Words” the IRS Uses to Flag Returns Faster

9 Digital Payment Habits That Banks Are Quietly Flagging in 2026

5 Digital Banking Changes That May Be Adding New Fees Without Notice

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Technology Tagged With: 1099-K, account verification, digital payments, fintech, gig economy, IRS reporting, money transfer apps, online payments, PayPal, tax compliance, taxes, Venmo

API Banking Lock: Why Budget Apps May Lose Access Under New Security Standards

May 6, 2026 by Brandon Marcus Leave a Comment

API Banking Lock: Why Budget Apps May Lose Access Under New Security Standards
Image Source: Shutterstock.com

Budgeting apps have become the digital sidekick many people rely on to track spending, crush debt, and stay financially sharp. But a major shift in banking security standards could shake up that relationship in a big way.

New API restrictions aim to tighten data access, which sounds great for safety, but creates real friction for the apps people trust daily. Some tools may lose access entirely, while others scramble to adapt behind the scenes. The result could feel like your favorite money app suddenly forgot who you are—and why it exists.

The Security Shake-Up That’s Changing Everything in Fintech

Banks no longer tolerate loose data-sharing practices, and regulators now demand stronger protections across the board. Financial institutions push toward secure APIs instead of older screen-scraping methods that quietly collected your login details. That shift closes dangerous loopholes, but it also cuts off many apps that relied on those older connections to function smoothly. Developers now face stricter approval processes, technical requirements, and compliance hurdles that slow everything down. The days of instant plug-and-play budgeting tools may fade as security takes center stage.

This transformation doesn’t come out of nowhere, and it reflects years of rising cyber threats and data breaches. Banks want to control exactly how third parties access customer data, which gives them more oversight and accountability. That means apps must request permission through official channels, and banks can deny or limit access whenever they choose. Consumers gain more protection, but they also lose some of the seamless experience they once enjoyed. That trade-off sits right at the heart of this API banking lock.

Why Budget Apps Depend on Access More Than You Think

Budgeting apps don’t magically know your spending habits, and they rely heavily on direct bank connections to deliver real-time insights. Every time an app categorizes your grocery bill or alerts you about overspending, it pulls that data from your linked accounts. Without that steady stream of information, the app turns into little more than a manual spreadsheet with a fancy interface. Users expect automation, and losing that automation feels like a major downgrade. That’s why API access isn’t just helpful—it’s absolutely essential.

Many popular apps depend on intermediaries like Plaid or Yodlee to bridge the gap between banks and users. These services aggregate financial data and translate it into something apps can use quickly and efficiently. When banks tighten API permissions, those middlemen feel the squeeze first, and the ripple effect hits every app that depends on them. Some apps may negotiate new agreements, while others struggle to meet the updated standards. Users may notice broken connections, delayed updates, or missing transactions almost overnight.

What Happens When Apps Lose Access to Your Bank Data

Losing access doesn’t always mean a complete shutdown, but it definitely changes how an app behaves. You might open your budgeting tool and see outdated balances, missing transactions, or error messages that refuse to go away. That kind of disruption can derail financial planning, especially for people who rely on daily tracking. Manual entry becomes the fallback option, which adds time and effort that most users won’t stick with long-term. Convenience disappears, and engagement often drops right along with it.

Some apps will pivot and rebuild their systems to comply with the new API standards, but that process takes time and resources. Smaller developers may not survive the transition, which could shrink the number of available budgeting tools on the market. Larger platforms will likely adapt faster, but even they may limit features or charge more to offset compliance costs. Users could face subscription hikes or reduced functionality as companies adjust. The landscape of personal finance apps may look very different within a year.

API Banking Lock: Why Budget Apps May Lose Access Under New Security Standards
Image Source: Unsplash.com

The Upside: Stronger Protection for Your Financial Data

This shift isn’t all bad news, and stronger security delivers real benefits that shouldn’t get ignored. API-based access eliminates the need to share your banking username and password with third-party apps, which reduces a major security risk. Banks can monitor and revoke access instantly if something looks suspicious, giving users more control over their data. That level of oversight helps prevent fraud and limits the damage from potential breaches. In a world full of digital threats, that kind of protection matters more than ever.

Users also gain more transparency about who accesses their financial information and why. Instead of vague permissions, APIs often require clear consent for specific types of data sharing. That clarity builds trust, even if it comes with a few extra steps during setup. People who value privacy will appreciate the tighter controls and reduced exposure. Security may feel inconvenient at times, but it plays a crucial role in keeping your money safe.

Keeping Your Budgeting Tools Working Smoothly

Staying ahead of these changes doesn’t require a tech degree, but it does require a little awareness and action. Start by checking whether your current budgeting app supports secure API connections with your bank. Many companies already updated their systems, and they often provide guides to reconnect accounts under the new standards. Keeping your app updated ensures you benefit from the latest compatibility fixes and security improvements. Ignoring updates could leave you stuck with broken features.

It also helps to diversify how you track your finances instead of relying on a single app for everything. Some users combine budgeting apps with direct bank tools or spreadsheets to maintain visibility if one system fails. Exploring alternatives now can save frustration later if your favorite app loses access. Reading app announcements and user forums can also provide early warnings about potential disruptions. A little preparation goes a long way in keeping your financial routine intact.

The Bigger Picture for the Future of Money Apps

This API banking lock signals a broader evolution in how financial technology operates and grows. The industry moves toward a more structured, regulated environment that prioritizes safety over speed. Innovation won’t stop, but it will look different as developers work within stricter boundaries. New apps will emerge with built-in compliance, while older ones either adapt or disappear. That shift may ultimately create a more stable and trustworthy ecosystem.

Consumers will play a key role in shaping that future through their choices and expectations. Apps that balance security with usability will win loyalty, while clunky or restrictive tools will fade away. Financial institutions will also compete to offer better API integrations, which could improve the overall experience over time. The transition period may feel messy, but it sets the stage for smarter and safer money management tools. Change always brings friction, but it also opens the door to something better.

Budget Apps and Today’s Banking Barriers

Budgeting apps stand at a crossroads as new API standards redefine how they connect to your financial life. Security improvements bring undeniable benefits, but they also disrupt the convenience users have come to expect. Some apps will rise to the challenge, while others may quietly disappear from your home screen. Staying informed and proactive can help you avoid unpleasant surprises and keep your finances on track. The key lies in adapting alongside the technology instead of getting left behind.

What changes would make you stick with—or ditch—your favorite budgeting app?

You May Also Like…

The “Loud Budgeting” Trend and Transparent Money Conversations

Life on Pause? How to Stay Mobile on a Budget When Your License Is Suspended

5 Budgeting Apps That Integrate With Biometric Banking

5 Financial Apps That Baby Boomers Refuse To Use But Need

8 Times Financial Tracking Apps Sold Your Purchase History

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Technology Tagged With: API banking, budgeting apps, cybersecurity, data privacy, financial apps, fintech regulation, fintech security, money management, open banking, personal finance tips, Plaid, Yodlee

Apple and Google “Legacy” Warning: 5 Settings You Must Change Today to Avoid a Post-Mortem Tech Nightmare

February 24, 2026 by Brandon Marcus Leave a Comment

Apple and Google "Legacy" Warning: 5 Settings You Must Change Today to Avoid a Post-Mortem Tech Nightmare
Image Source: Unsplash.com

Your entire life sits behind a password. Photos, messages, financial records, location history, health data, purchase receipts, voice notes, and that email account you opened in college and never closed. Apple and Google don’t just store your data. They store your identity. And if something happens to you tomorrow, that identity can turn into a locked vault that your family cannot open.

Both Apple and Google built tools that let you decide what happens to your data after you die. Most people never touch those settings. That creates confusion, legal headaches, and in some cases, permanent data loss. If you want to avoid a post-mortem tech nightmare, you need to change five settings today.

1. Apple’s Legacy Contact: The One Setting Too Many People Ignore

If you use an iPhone, iPad, or Mac, your Apple ID controls everything tied to iCloud. That includes your photos, notes, device backups, messages, and even purchases. Apple created a feature called Legacy Contact to solve the access problem after death, yet many people never activate it.

When you add a Legacy Contact, you choose someone who can access specific data in your Apple account after you pass away. You generate a special access key and share it with that person. After your death, they submit that key and a death certificate to Apple. Apple then grants them access to your data for a limited period.

Without this setting, your family might need a court order just to retrieve photos. Even then, Apple does not guarantee access to everything. Privacy laws and company policies limit what Apple can release.

2. Google’s Inactive Account Manager: Your Digital Executor in Disguise

Your Google account probably runs your email, cloud storage, calendar, YouTube subscriptions, and maybe even your phone. If you use Gmail, Google Photos, or Google Drive, your digital footprint grows fast. Google built a feature called Inactive Account Manager that lets you decide what happens if your account goes unused for a set period.

You choose how long Google waits before it considers your account inactive, usually between three and eighteen months. After that, Google contacts you through your listed recovery methods. If you still do not respond, Google notifies the trusted contacts you selected. You can allow them to download specific data, such as photos or emails.

You can also instruct Google to delete your account permanently after that process. That choice matters. Some people want preservation. Others want a clean digital exit.

3. Two-Factor Authentication: Protection That Can Backfire

Two-factor authentication keeps hackers out. It adds a second step, often a code sent to your phone or generated by an app. Apple and Google both encourage it, and you absolutely should use it. Apple uses two-factor authentication for Apple ID, and Google supports several 2FA methods for Google Accounts.

But here is the problem: if you do not document your recovery options, two-factor authentication can lock out your family permanently.

Review your trusted phone numbers and recovery email addresses right now. Make sure they stay current. If you changed numbers recently and forgot to update your account, you created a future disaster. Check your account recovery contacts in both Apple ID settings and your Google Account security page.

Also, consider where you store backup codes. Google lets you generate one-time backup codes. Save them in a secure password manager or physical safe. If no one can access your phone and no one can receive your recovery codes, your digital life freezes in place.

Apple and Google "Legacy" Warning: 5 Settings You Must Change Today to Avoid a Post-Mortem Tech Nightmare
Image Source: Unsplash.com

4. Password Managers: Stop Being the Only Person With the Keys

If you handle every password in your head or in a secret note app, you create a single point of failure. Apple offers iCloud Keychain inside your Apple ecosystem. Google offers its own password manager through Chrome and Android. Many people also use third-party managers.

These tools encrypt and store your login credentials. They make daily life easier and safer. But you must think about inheritance. If you use Apple’s built-in password system tied to your Apple ID, your Legacy Contact can eventually access data after approval. If you use Google’s password manager, access depends on your Inactive Account Manager settings.

You should also evaluate whether you want a separate password manager that supports emergency access features. Some services allow you to designate a trusted contact who can request access, with a waiting period that gives you time to deny the request if you are alive.

5. Data Cleanup: Decide What Deserves to Survive You

You do not need to preserve every digital breadcrumb. Apple and Google store years of data by default. Google Maps may hold location history. Google Photos may store thousands of images. iCloud may contain backups from devices you no longer own.

Review what you actually want someone to access. Log into your Google Account and examine your activity controls. Decide whether you want location history and web activity saved long-term. Check your iCloud storage and delete what no longer serves you.

This step does two things. It reduces your digital footprint, and it simplifies what your trusted contacts must sort through later. You shape your legacy by choosing what remains.

Your Digital Afterlife Deserves a Plan

You plan for insurance, wills, and medical directives. Your tech life deserves the same respect. Apple and Google gave you the tools. They did not activate them for you.

We live online now. Photos, conversations, and memories sit on servers instead of in shoeboxes. If you care about the people who will handle your affairs someday, give them clarity instead of chaos.

Have you adjusted your Apple or Google settings yet, or does this feel like something you keep meaning to do but never quite start? Let’s discuss it in the comments below.

You May Also Like…

Market Frame: 4 Visual Techniques Advisors Use to Explain Risk Better

Tech-Threat: 5 Ways AI Is Changing What Your Financial Advisor Should Be Doing for You

7 Tech Products Gen Z Can’t Live Without — That Are Actually Downgrades

9 Powerful Techniques to Master Your Money Emotions Wisely

Lease Management Made Easy: Best Software Solutions

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Technology Tagged With: Apple ID, digital estate planning, Gmail Security, Google Account, iCloud Data, Inactive Account Manager, iPhone Settings, Legacy Contact, online privacy, password management, Tech Safety, two-factor authentication

  • 1
  • 2
  • 3
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework