• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Brandon Marcus

The Tariff Truth No One Wants to Say Out Loud: You Pay the Price, Not the Companies

February 28, 2026 by Brandon Marcus Leave a Comment

The Tariff Truth No One Wants to Say Out Loud: You Pay the Price, Not the Companies
Image Source: Unsplash.com

A tariff does not punish a foreign company. A tariff raises your bill. That statement makes people uncomfortable because it clashes with the political sales pitch. Leaders across the spectrum frame tariffs as a way to make other countries or overseas corporations “pay their fair share.” The image feels satisfying. A tough policy, a firm handshake, a promise that someone else will foot the bill. Yet the mechanics of tariffs tell a different story, and the numbers back it up.

Tariffs act as taxes on imported goods. Governments collect them at the border when companies bring products into the country. Businesses then face a simple choice: absorb the cost and shrink profits, or pass the cost along through higher prices. In competitive markets with tight margins, companies almost always pass along at least part of that cost. That means shoppers feel the impact at the checkout line, not some distant executive in another country.

The Border Tax That Doesn’t Stay at the Border

A tariff works like this: a government sets a percentage tax on a specific imported product, such as steel, electronics, clothing, or machinery. When an importer brings that product into the country, the government charges the tariff based on the product’s value. The importer writes the check. That part fuels the popular narrative that “foreigners pay.”

But the importer rarely stops the cost there. Retailers buy from importers. Manufacturers buy imported components. Those businesses calculate their new costs and adjust prices accordingly. When costs rise, companies that want to stay profitable raise prices or cut expenses elsewhere, often through smaller product sizes or reduced services.

Research from respected institutions has shown that tariffs imposed in recent years led to higher prices for many imported goods and even for some domestic goods that rely on imported inputs. The cost did not remain trapped at the port. It traveled through supply chains and settled into everyday products.

Tariffs on steel and aluminum, for example, increased costs for domestic manufacturers that use those materials to produce cars, appliances, and construction materials. Those manufacturers did not enjoy a magical shield from higher input costs. They faced them head-on and passed them forward. That dynamic explains why tariffs often ripple through the broader economy instead of staying neatly confined to one industry.

Why Companies Rarely “Eat the Cost”

Some argue that giant corporations can afford to absorb tariffs without raising prices. That idea sounds appealing, especially in an era of public frustration with corporate profits. However, markets reward efficiency and punish shrinking margins. Publicly traded companies answer to shareholders. Privately held firms answer to lenders and owners who expect returns.

When a tariff raises the cost of a product by 10 or 25 percent, that jump rarely fits within existing profit margins. Retailers often operate on thin margins, sometimes just a few percentage points. A sudden cost increase can wipe out profit entirely. Businesses respond by adjusting prices, seeking alternative suppliers, or redesigning products. None of those options magically erase the cost.

Even when companies attempt to hold prices steady, they often shrink product sizes, reduce features, or delay investments. That strategy still affects buyers. A smaller cereal box at the same price reflects a hidden price increase. A delayed factory expansion can slow hiring and wage growth. Tariffs create pressure points that businesses cannot simply wish away.

The Political Appeal of a Simple Story

Tariffs carry strong political appeal because they offer a clear villain and a simple solution. Leaders can stand in front of factories and promise to protect domestic jobs. They can claim that foreign competitors engage in unfair practices and that tariffs level the playing field. That narrative resonates with communities that have lost manufacturing jobs or seen industries decline.

Trade policy, however, involves trade-offs. Economists across many administrations, both Republican and Democrat, have long argued that broad tariffs often raise consumer prices and invite retaliation. When one country imposes tariffs, others often respond with their own. That cycle can hurt exporters such as farmers and manufacturers who rely on foreign markets.

The Congressional Budget Office has analyzed trade policies and found that tariffs can reduce overall economic output when trading partners retaliate. Farmers experienced this firsthand when other countries imposed tariffs on agricultural products in response to U.S. tariffs. Governments then stepped in with aid packages to offset losses, which taxpayers ultimately funded.

None of this means that trade policy lacks complexity or that every tariff lacks purpose. Governments sometimes use targeted tariffs to address national security concerns or specific unfair trade practices. Yet broad claims that tariffs make foreign companies pay without domestic consequences simply do not match economic reality.

The Hidden Impact on Everyday Budgets

Tariffs do not announce themselves on receipts. They blend into higher prices for washing machines, electronics, clothing, and groceries. A 20 percent tariff on an imported component can nudge up the price of a finished product in ways that feel gradual but persistent.

Studies examining tariffs on washing machines in recent years found that prices rose not only for imported machines but also for domestically produced ones. Domestic manufacturers raised prices as well because the competitive pressure from cheaper imports weakened. That pattern illustrates a key point: tariffs can lift prices across the board, not just for foreign brands.

Anyone tracking monthly expenses should pay attention to trade headlines. Policy decisions in distant capitals can influence grocery bills and back-to-school shopping costs. That connection deserves far more attention than it usually receives in campaign speeches.

The Tariff Truth No One Wants to Say Out Loud: You Pay the Price, Not the Companies
Image Source: Unsplash.com

How to Think Clearly About Tariffs

Trade policy deserves serious debate, not bumper-sticker slogans. Anyone trying to make sense of tariffs should start by asking a few grounded questions. Who pays the tariff at the border? How do companies typically respond to higher input costs? What evidence exists from previous rounds of tariffs?

Consumers can also take practical steps. Comparing prices across brands, watching for product size changes, and paying attention to country-of-origin labels can provide clues about how tariffs affect specific items. Supporting transparent discussions about trade policy at the local and national level can also push leaders to explain costs honestly rather than relying on applause lines.

The Price Tag No One Prints on the Sign

Tariffs promise strength. They deliver complexity. When leaders claim that foreign companies will absorb the cost, the claim ignores how markets function. Importers pay tariffs first, businesses adjust next, and households often settle the final bill. Research from respected institutions and real-world price data confirm that pattern again and again.

That does not mean every tariff fails or that trade should flow without rules. It means voters deserve clarity. Honest conversations about trade policy should include both potential benefits and the likely price increases that follow. Ignoring that reality leaves families unprepared for the financial impact.

The next time a speech celebrates a new round of tariffs as a win that makes someone else pay, consider the path that cost will travel from the port to the store shelf. When prices climb quietly and steadily, will the applause still feel worth it?

How are you and your family dealing with tariffs? Tell us your thoughts and strategy in the comments section.

You May Also Like…

What Would Happen to Your Plan in a Trade-Tariff Spiral

5 Reasons People Pause Financial Plans During Tariff-Driven Volatility

Why Your Emergency Fund Isn’t Protecting You the Way It Did Five Years Ago

Family Homes Done Right: Kid-Friendly Interior Design on a Budget

6 Blended-Family Will Mistakes That Can Tear Families Apart

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Lifestyle Tagged With: consumer prices, Cost of living, economics, global trade, government policy, import taxes, Inflation, manufacturing, retail prices, supply chains, tariffs, trade policy

IRS Changes for Seniors: What’s Actually New on the 1040‑SR for 2026

February 28, 2026 by Brandon Marcus Leave a Comment

IRS Changes for Seniors: What’s Actually New on the 1040‑SR for 2026
Image Source: Unsplash.com

The IRS has not added new lines to Form 1040‑SR, but seniors do have something genuinely new to work with this year: a significantly larger deduction created by recent legislation.

The form itself remains a senior‑friendly version of the standard 1040, with larger print and a clear standard‑deduction chart, but the tax rules behind it have shifted in ways that matter for older filers. Understanding those changes can help retirees keep more of their income and avoid missing deductions they qualify for.

A Bigger Deduction for Seniors Under the New Law

The most important update for the 2026 filing season is the enhanced deduction for seniors, created by the One Big Beautiful Bill Act. This deduction applies to anyone who is 65 or older by the end of the tax year, and it stacks on top of the existing additional standard deduction seniors already receive.

For tax years 2025 through 2028, eligible taxpayers can claim an extra $6,000 deduction per person, or $12,000 for married couples filing jointly when both spouses are 65 or older. This deduction is available whether someone takes the standard deduction or itemizes, and it phases out at higher income levels.

Form 1040‑SR highlights the standard deduction amounts more clearly than the regular 1040, which helps seniors confirm they’re receiving the correct total. But the new senior deduction itself is not a form change—it’s a tax‑law change that applies regardless of which version of the form someone uses.

What Form 1040‑SR Still Does Well

Form 1040‑SR continues to offer the same advantages it has since its introduction. The layout is easier to read, the standard deduction chart is printed directly on the form, and the income sections are organized with retirees in mind. Social Security benefits, pensions, annuities, and IRA distributions appear in familiar places, reducing the chance of misreporting income.

These features matter because accuracy affects more than the final tax bill. Reporting retirement income correctly determines how much of a person’s Social Security becomes taxable. Up to 85 percent of benefits can be taxed when income crosses certain thresholds, so clarity on the form helps seniors avoid mistakes that could trigger IRS notices later.

Deductions and Credits Seniors Often Overlook

Even though the form itself hasn’t added new lines, several deductions and credits remain especially important for older taxpayers. Medical expenses continue to be deductible when they exceed 7.5 percent of adjusted gross income, and Medicare premiums count toward that total. In years with major dental work, surgeries, or long‑term care costs, itemizing can produce a larger deduction than the standard option.

Charitable contributions still require itemizing to be deductible now that the temporary pandemic‑era above‑the‑line deduction has expired. Seniors who give regularly to religious or charitable organizations should compare both filing methods each year rather than assuming the standard deduction always wins.

Credits also deserve attention. The Credit for the Elderly or Disabled still exists, though income limits restrict eligibility. The Saver’s Credit can apply to older workers who continue contributing to retirement accounts, especially those with part‑time income. Form 1040‑SR does not change how these credits work, but its clearer layout makes it easier to follow the references to the schedules where they are claimed.

IRS Changes for Seniors: What’s Actually New on the 1040‑SR for 2026
Image Source: Unsplash.com

Turning the New Rules Into Real Savings

The biggest opportunity for seniors this year comes from combining the enhanced senior deduction with careful tracking of medical expenses, charitable giving, and retirement‑account withdrawals. Seniors who assume the standard deduction is always best may miss out in years with unusually high medical costs. Others may benefit from reducing adjusted gross income through IRA contributions or self‑employed health‑insurance deductions, which can lower the taxable portion of Social Security.

Form 1040‑SR makes these comparisons easier, but the strategy still depends on reviewing records throughout the year. Organized receipts, donation letters, and medical statements help seniors decide whether itemizing or taking the standard deduction produces the better result.

Filing With Confidence

Form 1040‑SR remains a senior‑friendly version of the standard tax return, but the real change this year comes from the law, not the form. The new $6,000 senior deduction can meaningfully reduce taxable income, and the form’s clear layout helps ensure that older taxpayers don’t overlook the benefits they already qualify for.

A thoughtful review of income, deductions, and credits—combined with the updated rules—can make this tax season more rewarding and less stressful.

How do you want to approach your filing strategy this year to make sure the new senior deduction works to your advantage? Any and all seniors with advice should share it below in our comments.

You May Also Like…

7 Sun Belt Retirement Towns Seeing Significant Price Corrections

Why Retirees Are Running Out of Money Faster Than Expected

Why Fixed Income Doesn’t Feel Fixed Anymore for Retirees in 2026

The Medicare Part B Increase That’s Reducing Social Security Checks By About $185/Month in 2026

Why More Seniors Are Getting Surprise Social Security Overpayment Notices


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: tax tips Tagged With: 1040-SR, federal income tax, IRS, Medicare premiums, older taxpayers, retirement income, retirement planning, senior taxes, Social Security, tax credits, Tax Deductions, tax savings

Thinking of Cosigning? Here’s How You Could End Up Owing the Entire Loan Yourself

February 28, 2026 by Brandon Marcus Leave a Comment

Thinking of Cosigning? Here’s How You Could End Up Owing the Entire Loan Yourself
Image Source: Pexels.com

Sign one piece of paper, and suddenly a loan that never bought a single thing for you can land squarely on your shoulders. Cosigning sounds generous and supportive, even noble. Lenders frame it as a simple favor, and family members or close friends often describe it as a temporary bridge to independence. Yet the legal reality cuts through the emotion with sharp clarity: a cosigner promises to repay the entire debt if the primary borrower fails to do so.

That promise carries real weight. Courts enforce it. Credit bureaus track it. Collection agencies pursue it. Anyone considering cosigning needs to understand exactly what that signature commits them to, because once ink hits paper, backing out becomes nearly impossible.

When “Helping Out” Turns Into Full Legal Responsibility

Cosigning does not mean offering moral support. It creates a binding legal obligation. When someone cosigns a loan, the lender treats that person as equally responsible for repayment. If the primary borrower misses payments, defaults, or files for bankruptcy, the lender can demand payment from the cosigner without first exhausting every effort against the borrower.

Lenders do not need to chase the borrower for months before turning to the cosigner. In many cases, they can pursue both parties at the same time. That arrangement appears in auto loans, personal loans, private student loans, and even some rental agreements. The contract spells out joint and several liability, which means each signer bears full responsibility for the total balance, not just half or some agreed-upon portion.

That legal structure explains why lenders often encourage cosigners in the first place. A cosigner reduces risk. If the borrower lacks credit history or carries a low credit score, a financially stable cosigner increases the lender’s chance of getting repaid. From the lender’s perspective, two legally responsible people beat one every time.

Your Credit Score Stands on the Line Too

Cosigning does more than create a legal obligation. It ties your credit profile directly to the loan’s performance. Credit bureaus such as Equifax, Experian, and TransUnion track the loan under both names. Every on-time payment can help, but every missed payment can hurt.

If the borrower pays late, the lender can report that delinquency on the cosigner’s credit report as well. A single 30-day late payment can drop a strong credit score by dozens of points. Multiple missed payments can cause even more serious damage. When the account goes into default, collection accounts and charge-offs can follow, and those marks stay on a credit report for years.

That damage does not disappear just because the cosigner never touched the loan proceeds. Mortgage lenders, auto lenders, and credit card issuers review the full credit report, including any cosigned accounts. A struggling borrower can quietly undermine the cosigner’s future plans, from buying a home to qualifying for a business loan.

Debt-to-Income Ratios Don’t Care Who Spends the Money

Lenders evaluate more than credit scores. They also calculate debt-to-income ratios, which measure monthly debt payments against gross monthly income. A cosigned loan increases the cosigner’s monthly debt obligations in the eyes of other lenders, even if the borrower makes every payment on time.

Imagine applying for a mortgage while carrying a cosigned auto loan on your credit report. Even if the borrower handles the payments responsibly, the mortgage lender may still count that auto loan payment as part of your obligations. That higher debt-to-income ratio can shrink the mortgage amount you qualify for or even lead to a denial.

Some lenders allow exceptions if the cosigner can prove that the primary borrower has made consistent payments from their own account for a certain period, often 12 months or more. However, policies vary widely. No universal rule forces lenders to ignore a cosigned loan simply because someone else makes the payments. That uncertainty adds another layer of risk that many people overlook.

Default Doesn’t Just Mean Missed Payments

Many people imagine worst-case scenarios as total abandonment of the loan. Reality often looks more complicated. A borrower might fall behind during a job loss, a medical crisis, or another financial setback. Those missed payments trigger late fees and interest accrual. If the loan includes variable interest, the cost can climb even faster.

Once the account enters default, the lender can accelerate the loan. Acceleration means the lender demands the entire remaining balance at once, not just the overdue amount. That demand applies to the cosigner as well. If the cosigner cannot pay the full balance immediately, the lender can send the account to collections or pursue legal action.

In some cases, lenders file lawsuits and seek judgments. A court judgment can lead to wage garnishment or bank account levies, depending on state law. Cosigners rarely anticipate that level of consequence when they agree to help a relative secure a car or a student loan. Yet the contract permits those outcomes.

Student Loans: A Special Case With Real Consequences

Private student loans frequently require cosigners because young borrowers often lack sufficient credit history. Federal student loans usually do not require cosigners, but private lenders often insist on one. Companies such as Sallie Mae and other private lenders evaluate both borrower and cosigner credit profiles before approving a loan.

Private student loans do not offer the same flexible repayment options and protections that federal loans provide. If the borrower struggles after graduation, the cosigner can face immediate pressure. Some private lenders offer cosigner release programs after a certain number of on-time payments, but those programs require strict qualifications. The borrower must apply, meet credit and income standards independently, and receive lender approval.

Cosigners should never assume that release will happen automatically. Until the lender formally approves a release in writing, the cosigner remains legally responsible. That reality can stretch for years, especially with long-term student loans.

Emotional Pressure Often Clouds Financial Judgment

Family bonds and close friendships create powerful emotional incentives. A parent wants to help a child attend college. A grandparent wants to support a first car purchase. A close friend pleads for assistance during a tough stretch. In those moments, declining a request can feel harsh or disloyal.

However, financial agreements do not bend around emotions. They follow the terms of the contract. Agreeing to cosign without a full review of the loan terms can lead to resentment, strained relationships, and lasting financial damage. Open conversations about expectations, repayment plans, and worst-case scenarios matter deeply before any signature appears on a document.

Practical steps can reduce risk. Request access to the loan account so you can monitor payments. Set up alerts for due dates and missed payments. Encourage the borrower to create automatic payments to avoid accidental lateness. Consider drafting a separate written agreement that outlines expectations between both parties, even though that agreement does not override the lender’s contract.

Thinking of Cosigning? Here’s How You Could End Up Owing the Entire Loan Yourself
Image Source: Pexels.com

Smart Questions to Ask Before Signing Anything

Before agreeing to cosign, pause and ask direct questions. What happens if the borrower misses one payment? Does the lender notify the cosigner immediately? Does the loan include a cosigner release option, and under what conditions? What fees and interest rates apply?

Review the entire loan agreement carefully. Look for clauses about acceleration, default, and collection costs. Confirm whether the loan includes variable interest rates that could increase over time. Understand the total repayment amount over the life of the loan, not just the monthly payment.

Also, evaluate your own financial stability. Could you cover the full monthly payment comfortably if the borrower stopped paying tomorrow? Could you handle the entire remaining balance if the lender accelerated the loan? If those answers create anxiety, that reaction deserves attention. Financial generosity should never jeopardize your own security.

The Signature That Changes Everything

A cosigner’s signature carries the same legal weight as the borrower’s. Courts do not treat it as symbolic. Credit bureaus do not treat it as secondary. Lenders do not treat it as optional. That signature transforms someone else’s debt into your potential obligation in full.

Generosity holds value. Supporting loved ones matters. Yet smart support requires clear eyes and careful planning. Anyone considering cosigning should approach the decision like any other major financial commitment: with thorough research, honest conversations, and a realistic assessment of risk.

So before agreeing to back someone else’s loan, take a deep breath and ask a hard question: if the borrower walked away from the debt tomorrow, would you feel ready and willing to take it over completely?

This topic is very important for many people with close family and friends, so let’s discuss it more in our comments below.

You May Also Like…

Why Do People Ignore the Risks of Cosigning Loans

5 Sneaky Financial Costs of Cosigning a Loan

5 Reasons You Should Never Co-Sign a Loan (Not Even for Family)

Family Homes Done Right: Kid-Friendly Interior Design on a Budget

Are Payday Loans Still A Big Problem?

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Finance Tagged With: auto loans, cosigning, credit protection, credit score, debt responsibility, family finances, financial risk, loan agreements, loans, money advic, Personal Finance, student loans

The Harsh Truth About Delaying Social Security: You Might Never See the Money

February 28, 2026 by Brandon Marcus Leave a Comment

The Harsh Truth About Delaying Social Security: You Might Never See the Money
Image Source: Unsplash.com

Retirement planning loves a magic number. For Social Security, that number often lands at age 70, the point when monthly benefits max out thanks to delayed retirement credits. Financial pundits repeat the advice so often that it sounds like gospel: wait as long as possible and lock in the biggest check.

That advice leaves out one uncomfortable reality. Not everyone who delays will live long enough to enjoy the bigger payout. In fact, some will walk away with far less lifetime income than they would have collected by claiming earlier. The strategy that promises security can backfire, and it can backfire quietly.

The Allure of a Bigger Check at 70

Social Security rewards patience, and the math looks compelling at first glance. After full retirement age, benefits grow by about 8 percent per year until age 70. That increase stacks on top of cost-of-living adjustments, so the difference between claiming at 62 and 70 can reach 70 percent or more, depending on full retirement age.

Full retirement age now ranges from 66 to 67 for most workers born in 1960 or later. Claim at 62, and the Social Security Administration permanently reduces the monthly benefit. Wait until 70, and the system permanently increases it. Bigger monthly checks create a powerful psychological pull because they look like a guaranteed raise for life.

But bigger monthly checks do not automatically mean more money over a lifetime. The key question never centers on the size of the payment. It centers on how long someone will collect it.

Longevity Is the Real Gamble

Delaying Social Security turns into a bet on longevity, whether anyone frames it that way or not. The Social Security break-even age often falls in the late 70s or early 80s, depending on individual circumstances. That means someone who delays until 70 must live well into their 80s to clearly come out ahead compared to claiming at 62.

Life expectancy in the United States hovers in the mid-to-late 70s overall, although it varies by gender, health, income, and lifestyle. Many people live far longer than average, and many do not. Health conditions, family history, and personal habits all shape the odds, yet retirement advice often ignores those factors and pushes a one-size-fits-all strategy.

A person with chronic health issues or a shorter family life expectancy may sacrifice years of payments by waiting. Eight years of forgone checks between 62 and 70 add up to tens of thousands of dollars. If death arrives sooner than expected, those skipped payments vanish forever. Social Security does not send a refund.

The Opportunity Cost Nobody Talks About

Money claimed at 62 does not have to sit idle. Early benefits can reduce withdrawals from retirement accounts, preserve investment balances, or even get invested for growth. When someone delays Social Security, they often draw more heavily from 401(k)s or IRAs during those waiting years. That decision carries its own risks.

Market downturns early in retirement can hurt portfolios badly, especially when withdrawals continue. Financial planners call this sequence-of-returns risk, and it can shrink long-term wealth. Taking Social Security earlier can ease that pressure and protect investments during volatile years.

Taxes also enter the equation. Larger withdrawals from retirement accounts can push income higher and increase taxes on Social Security later. Medicare premiums can rise with higher income as well. A strategy that focuses only on maximizing the monthly benefit can trigger ripple effects across the entire financial plan.

Spouses, Survivors, and the Bigger Picture

Social Security does not operate in a vacuum, especially for married couples. Spousal and survivor benefits complicate the decision in meaningful ways. When the higher-earning spouse delays, the surviving spouse may receive a larger survivor benefit later, which can provide valuable protection.

For couples with a significant earnings gap, delaying the higher earner’s benefit can make sense as insurance against longevity risk. The surviving spouse keeps the larger of the two benefits, so boosting that top number matters. On the other hand, if both spouses face health concerns, claiming earlier might protect total lifetime income.

Divorced individuals may qualify for benefits based on an ex-spouse’s record if the marriage lasted at least 10 years. Widows and widowers also have flexible claiming options. Each situation demands a careful look at the rules set by the Social Security Administration rather than a blanket recommendation to wait.

The Harsh Truth About Delaying Social Security: You Might Never See the Money
Image Source: Unsplash.com

The Myth of “Free Money” for Waiting

Some financial commentary frames delayed retirement credits as free money from the government. That framing oversimplifies reality. Social Security calculates benefits using lifetime earnings and designed actuarial adjustments so that, on average, people receive similar lifetime payouts regardless of when they claim.

The system spreads payments differently depending on claiming age. Early claimants receive smaller checks over more years. Late claimants receive larger checks over fewer years. The average life expectancy drives those calculations, but individuals do not live on averages.

Inflation adjustments apply no matter when someone claims. Cost-of-living adjustments increase benefits each year based on inflation data. Waiting does not unlock special inflation protection beyond what early claimants receive. Delaying increases the base benefit, but it does not create a magical bonus pool.

Health, Work, and Reality on the Ground

Life does not follow spreadsheets. Some people lose jobs in their early 60s and struggle to find comparable work. Others face caregiving responsibilities or physical limitations that make full-time employment unrealistic. Delaying Social Security often assumes steady income and good health through the late 60s.

Claiming before full retirement age while still working can reduce benefits temporarily if earnings exceed certain limits. The Social Security Administration withholds part of the benefit above those thresholds, but it adjusts payments later to account for withheld amounts. Still, many people misunderstand these rules and avoid claiming out of fear.

Health insurance plays a role as well. Medicare eligibility begins at 65. Those who retire before that age must secure coverage elsewhere, often at high cost. Social Security decisions intertwine with healthcare planning, and the pressure to bridge those years can influence claiming strategies.

Smart Strategies Instead of Blind Delays

No universal age fits everyone. A thoughtful approach weighs health, family history, marital status, savings, taxes, and work plans. Running detailed projections through the Social Security Administration’s online tools can reveal break-even ages under different scenarios. Financial planners often use specialized software to model lifetime income under multiple claiming strategies.

For someone in excellent health with strong family longevity and sufficient savings, delaying to 70 can provide valuable insurance against living into the 90s. For someone with limited savings or health concerns, claiming earlier can improve quality of life and reduce financial stress. The right choice aligns with personal realities, not with headlines.

Building flexibility into retirement planning helps as well. Part-time work, phased retirement, or consulting income can reduce the need to tap Social Security immediately while avoiding heavy withdrawals from investment accounts. Diversifying income sources provides more control than relying on one optimal claiming age.

The Real Question to Ask Before Waiting

Delaying Social Security can increase monthly income, but it can also increase risk. The risk does not come from the government canceling benefits. It comes from time itself. Years without payments represent real money left on the table, and no one can predict exactly how many years lie ahead.

Retirement planning should focus on total lifetime income, personal health, and peace of mind. A larger check at 70 looks impressive on paper, yet it does not guarantee a better outcome. Every decision about Social Security carries trade-offs, and smart planning acknowledges them instead of chasing a single number.

So before circling age 70 on the calendar as the automatic goal, ask a harder question: does waiting truly fit your life, your health, and your financial reality, or does it simply sound like the safest choice because everyone repeats it? Let’s talk about it in our comments below.

You May Also Like…​

Why More Seniors Are Getting Surprise Social Security Overpayment Notices

The Hidden Tax Rules Shrinking Social Security Checks — What Seniors Need to Know

Social Security 2026 COLA: Why Your 2.8% Raise Disappeared After Medicare Deductions

7 Sun Belt Retirement Towns Seeing Significant Price Corrections

7 Medical Costs That Can Wreck Retirement Even With Solid Savings

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: social security Tagged With: Claiming Benefits, Delayed Retirement Credits, Full Retirement Age, longevity risk, Medicare, Personal Finance, Planning, retirement planning, Retirement Strategy, Social Security, spousal benefits, Wealth management

The Truck Warning: Why 355,000 Ford Pickups Just Hit the Urgent Recall List

February 28, 2026 by Brandon Marcus Leave a Comment

The “Do Not Drive” Warning: Why 355,000 Ford Pickups Just Hit the Urgent Recall List
Image Source: Unsplash.com

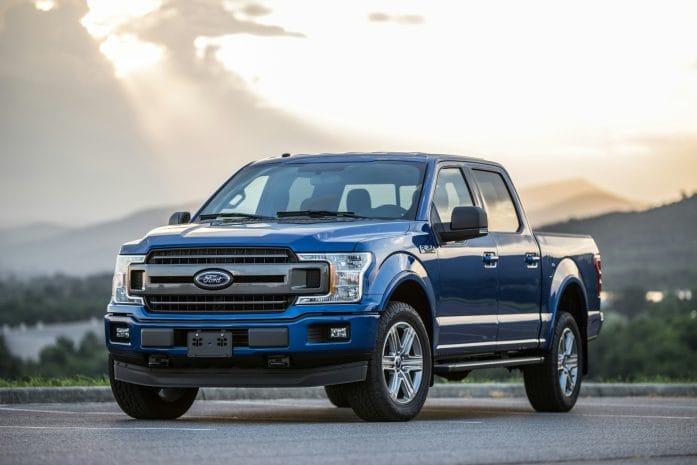
A major corporate warning does not show up unless something demands immediate attention. When that warning lands on more than 355,000 pickup trucks across the United States, it signals a problem that no driver should ignore.

This time, the spotlight falls on certain heavy-duty trucks from Ford Motor Company. Federal safety regulators flagged a defect serious enough to tell owners to bring their vehicles in ASAP. That kind of language carries weight.

A Failure Risk That Demands Immediate Action

The recall centers on certain Ford Super Duty and F-150 pickup trucks equipped with certain instrument panels. According to filings with the National Highway Traffic Safety Administration, a failure inside the panels prevents drivers from seeing critical information such as the speedometer and warning lights. That means, of course, that drivers are at much higher risk of a crash.

Ford determined that the truck’s instrument panel could fail internally. When that failure happens, drivers might not notice warning messages on the dashboard or even chimes that signal a malfunction. Regulators and Ford both treat that possibility with urgency. A truck that weighs thousands of pounds needs to be reliable. When that confidence disappears, every mile on the road carries more risk than it should.

Why 355,000 Trucks Ended Up on the List

The recall affects hundreds of thousands of trucks from specific model years. These trucks often serve as workhorses. Contractors rely on them to haul equipment. Farmers count on them for daily operations. Families use them to tow campers and trailers across long stretches of highway.

Automakers investigate patterns through warranty claims, field reports, and internal testing. Once engineers identify a safety-related defect, federal law requires a recall. In this case, Ford chose to issue an advisory for certain trucks that show symptoms, and it instructed owners to contact dealers immediately if they notice warning light changes or concerns.

That level of caution underscores how seriously Ford and regulators view the issue. A heavy-duty pickup that isn’t reliable does not simply create inconvenience. It can create life-threatening danger.

What This Really Means for Owners

If a truck falls under the recall, owners should try to avoid driving it until a dealer completes the repair. Ford dealers will inspect affected trucks and replace the equipment at no cost. Anyone who owns a Ford truck from the affected years should check the vehicle identification number, often called the VIN. Owners can enter that VIN on Ford’s recall website or on the NHTSA recall lookup tool to confirm whether their specific truck falls under the recall.

Scheduling a service appointment quickly reduces risk and restores peace of mind. With the stakes so high and so much on the line, second-guessing shouldn’t be an option for drivers.

The “Do Not Drive” Warning: Why 355,000 Ford Pickups Just Hit the Urgent Recall List
Image Source: Unsplash.com

Smart Steps Every Truck Owner Should Take Now

Anyone who owns a Super Duty or F-150 truck should not wait for a letter to land in the mailbox. Taking a few proactive steps can make a big difference. First, check the VIN online through Ford or NHTSA to confirm recall status. That process takes only a few minutes and provides clear answers.

Second, pay attention to dashboard warnings. Modern trucks communicate problems through messages and alerts. Ignoring those signals can turn a manageable repair into a dangerous situation.

Third, schedule service promptly if the truck appears on the recall list. Dealers receive instructions and replacement parts to address the defect. Acting quickly prevents inconvenience later and reduces potential risk on the road.

What This Recall Says About the Industry

Large recalls often spark frustration, but they also show how safety oversight works. Automakers monitor performance data constantly. Federal regulators track complaints and investigate patterns. When evidence points to a safety defect, the recall process moves forward. No manufacturer enjoys issuing a recall, especially one that affects more than 355,000 vehicles. However, identifying a defect and offering free repairs protects drivers and reinforces accountability.

Truck buyers expect durability and strength from heavy-duty models. That expectation extends to every system under the hood. When a flaw emerges, swift corrective action matters far more than silence.

Park It, Fix It, Then Get Back to Work

This recall carries a simple message: take it seriously and take action. Owners of affected Ford pickups should verify their VIN, watch for warning signs, and schedule repairs without delay. Dealers stand ready to replace the faulty component.

A warning does not appear often in the automotive world. When it does, it deserves immediate respect. For anyone who depends on a truck for work, travel, or daily life, safety should always outrank convenience.

Will this recall change how truck owners approach maintenance and safety checks going forward? Let’s hear about it from all truck drivers in our comments below.

You May Also Like…

Are Pickup Truck Owners Just Trying to Compensate for Something?

7 Myths About Memory You Should Forget Immediately

Missed Insurance Payment? Your Auto Lender May Raise Your Costs Overnight

5 Steps to Take After a Truck Accident

How to Choose the Right Automotive Insurance Company

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Auto & Tech Tagged With: auto industry news, automotive defects, car maintenance, Ford recall, Ford trucks, NHTSA, pickup truck recall, recall alert, safety warning, truck news, truck owners, vehicle safety

Why Smart Drivers Are Refinancing Their Auto Loans Before Rates Shift Again

February 27, 2026 by Brandon Marcus Leave a Comment

Why Smart Drivers Are Refinancing Their Auto Loans Before Rates Shift Again
Image Source: Pexels.com

The cost of borrowing never sits still for long. Interest rates move, markets react, and monthly payments either shrink or swell depending on timing. Right now, financially savvy drivers refuse to sit back and hope for the best. They review their auto loans with a critical eye, weigh their options carefully, and refinance before the next rate shift catches them off guard.

That sense of urgency does not come from panic. It comes from preparation. The same drivers who comparison-shop for vehicles and negotiate purchase prices understand that the financing deserves just as much attention. An auto loan can quietly shape a budget for five, six, or even seven years. A smarter rate can free up breathing room every single month.

Rates Don’t Wait for Anyone

Interest rates rarely move in a straight line. The Federal Reserve adjusts its benchmark rate in response to inflation, employment trends, and overall economic stability. Lenders respond by adjusting the rates they offer on loans, including auto financing. Even small shifts in benchmark rates ripple through the lending market and change what borrowers qualify for.

Drivers who locked in financing during a period of higher rates often find themselves paying more than necessary once rates ease. On the other hand, when rates trend upward, anyone sitting on a variable-rate loan or considering refinancing may lose a valuable opportunity. Timing matters, but preparation matters more. Smart borrowers monitor economic signals without obsessing over headlines. They review their credit profile, compare lender offers, and calculate potential savings before they act. That proactive approach creates options instead of stress.

Refinancing Isn’t Just About a Lower Payment

A lower monthly payment grabs attention quickly, but refinancing delivers more than short-term relief. When a borrower secures a lower interest rate, more of each payment goes toward the principal balance instead of interest. That shift can shorten the life of the loan or reduce the total interest paid over time.

For example, consider a driver with a $25,000 balance on a five-year loan at 8 percent interest. If that borrower qualifies for 6 percent instead, the difference over the remaining term can add up to hundreds or even thousands of dollars in interest savings, depending on the exact balance and term. Those savings do not rely on gimmicks or tricks. They come straight from math.

Refinancing also allows drivers to adjust the structure of the loan. Some borrowers shorten the term to pay off the vehicle faster and reduce overall interest costs. Others extend the term to ease monthly cash flow during tight seasons. The key lies in choosing a structure that supports long-term financial goals instead of chasing a quick fix.

Credit Scores Open Doors

Credit plays a starring role in refinancing decisions. Lenders base interest rates largely on credit scores and overall credit history. Drivers who financed a vehicle with fair or average credit may qualify for better rates after a year or two of consistent, on-time payments and improved credit habits.

Raising a credit score even modestly can unlock noticeably better offers. Paying down credit card balances, avoiding late payments, and checking credit reports for errors can strengthen a profile before submitting a refinancing application. Many financial institutions and credit bureaus allow consumers to review reports for accuracy at no cost, which makes this step both practical and essential.

Smart drivers treat refinancing as a reward for responsible behavior. They recognize that consistent payments build credibility with lenders. When that credibility translates into a lower interest rate, the financial system finally works in their favor.

The Fine Print Deserves Attention

Refinancing can save money, but it demands careful evaluation. Some loans include prepayment penalties, which charge a fee for paying off the loan early. Although many modern auto loans do not carry these penalties, borrowers should always confirm the details in their original agreement.

Fees also matter. Some lenders charge application fees, title transfer fees, or administrative costs. A slightly lower interest rate may not deliver meaningful savings if fees eat away at the benefit. Smart borrowers calculate the total cost of refinancing, not just the headline rate.

Loan term adjustments also require thought. Extending a loan from three years to five years might reduce the monthly payment, but it can increase total interest paid over time. Drivers who want true savings often pair a lower rate with a reasonable term length that keeps overall costs down.

Why Smart Drivers Are Refinancing Their Auto Loans Before Rates Shift Again
Image Source: Pexels.com

Fixed Rates Offer Stability in Uncertain Times

Most auto loans carry fixed interest rates, which lock in the same rate for the entire term. That stability provides predictability, especially during periods of economic uncertainty. When market rates climb, borrowers with fixed rates avoid sudden payment increases.

Some refinancing options may include variable rates, although they remain less common for auto loans. A variable rate can start lower but rise later if broader rates increase. Borrowers who value stability typically gravitate toward fixed-rate options, particularly when rates sit near historic averages.

Drivers who refinance before anticipated rate increases can secure favorable terms while they remain available. Watching economic trends and acting decisively can prevent regret later. Nobody controls the market, but everyone can control their response to it.

When Refinancing Makes the Most Sense

Refinancing does not suit every situation. Drivers with very low interest rates may not find better offers, especially if market rates trend higher than when they originally financed. Similarly, vehicles that have depreciated significantly may not qualify for favorable refinancing terms, since lenders consider the vehicle’s current value.

However, refinancing often makes sense when credit has improved, when rates have declined since the original loan, or when monthly cash flow needs adjustment. Drivers who plan to keep their vehicles for several more years stand to gain the most from lower interest costs.

Timing also depends on loan age. Many lenders prefer vehicles under a certain age or mileage threshold. Checking eligibility requirements before applying can prevent unnecessary credit inquiries.

Financial Agility Beats Financial Complacency

Complacency costs money. A car loan may feel routine after the paperwork settles and the first few payments clear. Yet markets change, credit profiles improve, and opportunities emerge. Smart drivers revisit their financing periodically instead of assuming the original deal remains the best possible arrangement. They treat auto loans as dynamic financial tools rather than fixed burdens. That mindset encourages flexibility and positions them to act quickly when rates shift.

Refinancing requires effort, but it rarely demands overwhelming complexity. A few hours of research, some straightforward calculations, and a willingness to compare offers can reshape years of payments. That kind of return on effort deserves attention.

The Road Ahead Rewards Those Who Act

Interest rates will continue to move, because economic forces never stand still. Drivers who understand that reality take control of what they can influence. They monitor rates, strengthen credit, compare lenders, and refinance strategically instead of reactively.

A well-timed refinance can lower monthly payments, reduce total interest, or create breathing room in a tight budget. More importantly, it reinforces a habit of financial awareness that extends far beyond a single vehicle loan.

The next rate shift will arrive sooner or later. The real question centers on readiness. Will the next move in the market catch drivers off guard, or will preparation turn it into an opportunity? If you have plans or ideas about your auto loan, talk about them in our comments.

You May Also Like…

How Paying Off a Loan the Right Way Can Still Lower Your Score — and Why

Missed Insurance Payment? Your Auto Lender May Raise Your Costs Overnight

Every Affirm Purchase Adds a Loan to Your Credit Report — Here’s What That Means

7 Hidden Signs You Should Refinance Your Mortgage Right Now

15 Warning Signs You Should Refinance Your Mortgage

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Auto & Tech Tagged With: auto loan refinancing, car loan rates, car payments, Credit Score Tips, Debt Management, federal reserve, fixed vs variable rates, interest rates, loan terms, money saving strategies, Personal Finance, vehicle ownership

The Medical Bill “Convenience Fees” Creating an Unnecessary Financial Burden for The Middle Class

February 27, 2026 by Brandon Marcus Leave a Comment

The Medical Bill “Convenience Fees” Creating an Unnecessary Financial Burden for The Middle Class
Image Source: Pexels.com

Healthcare in the United States already costs more than other high-income nation on earth. According to data from the Centers for Medicare & Medicaid Services, national health spending reached $4.5 trillion in 2022, averaging well over $13,000 per person. That number alone should command attention.

Yet another cost hides in plain sight, tucked between line items and payment portals: the medical bill “convenience fee.” It sounds harmless, even polite. In reality, it adds yet another layer of financial strain on families who already stretch every dollar to stay afloat.

The Polite-Sounding Charge That Isn’t So Polite

Hospitals, clinics, and physician groups increasingly charge extra fees when patients pay bills with a credit or debit card. They label these charges “convenience fees” or “processing fees,” and they often justify them as necessary to offset card transaction costs. Credit card companies typically charge merchants between 1.5% and 3.5% per transaction, depending on the card network and agreement. Instead of absorbing those costs as part of doing business, some healthcare providers pass them directly to patients.

That shift might seem minor in isolation. A two or three percent fee on a $75 copay may not raise eyebrows. But medical bills rarely stop at $75. A $2,000 outpatient procedure can suddenly carry an extra $60 fee. A $6,000 hospital charge can tack on nearly $180 simply for using a card to manage the payment. Middle-class families who rely on credit cards to juggle cash flow feel those extra dollars immediately.

Some states regulate or restrict surcharges on credit card payments, but the rules vary widely. Some card networks allow surcharges under certain conditions, provided merchants follow disclosure requirements and cap the fee at the actual processing cost. Patients often see these details buried in fine print, posted on a billing page, or mentioned only after they enter payment information. Transparency exists in theory, but clarity often falls short in practice.

When “Convenience” Becomes a Budget Problem

The middle class occupies a financial gray zone. Many families earn too much to qualify for Medicaid or generous hospital charity programs, yet they lack the disposable income to shrug off surprise costs. A significant portion of adults report difficulty paying unexpected medical bills, even among those with employer-sponsored insurance. Insurance coverage does not erase deductibles, coinsurance, or out-of-network charges. It certainly does not eliminate convenience fees.

Consider how families manage cash flow. Many use credit cards strategically to spread out payments, earn rewards, or avoid overdraft fees. When a hospital adds a surcharge for card use, that strategy suddenly carries a penalty. Paying by check or bank transfer may avoid the fee, but not everyone keeps a checkbook handy or feels comfortable linking a bank account online. Some patients must choose between paying the fee or delaying payment altogether.

The Medical Bill “Convenience Fees” Creating an Unnecessary Financial Burden for The Middle Class
Image Source: Pexels.com

A System That Shifts Costs Downward

Healthcare providers argue that rising administrative costs, staffing shortages, and tight reimbursement rates leave little room to absorb card processing fees. Hospitals operate within a complex payment structure shaped by private insurers, Medicare, and Medicaid. The American Hospital Association frequently highlights financial pressures facing hospitals, especially rural and community facilities.

Yet shifting costs to patients carries real consequences. When providers treat transaction fees as a separate, add-on expense, they fragment the true cost of care into smaller, less visible pieces. Patients face a maze of bills from hospitals, anesthesiologists, laboratories, and imaging centers. Adding a payment surcharge to that mix deepens frustration and erodes trust.

Middle-class households often absorb these costs quietly. They cut discretionary spending, dip into savings, or carry balances on high-interest credit cards. Interest compounds quickly, especially when card rates hover in the high teens or above. A modest convenience fee today can snowball into a much larger expense over time if it pushes a balance higher.

What Patients Can Actually Do About It

Complaining about convenience fees may feel satisfying, but practical action matters more. Patients can start by reviewing billing statements carefully and checking payment portals before entering card details. Many providers offer free electronic bank transfers. Choosing that option can eliminate the extra fee entirely.

Patients can also call billing departments and ask about alternative payment arrangements. Many hospitals offer interest-free payment plans, particularly for large balances. Negotiating a structured plan directly with the provider can avoid both card fees and high credit card interest. Some billing departments even waive small fees upon request, especially when patients point out financial hardship.

For those who qualify, hospital financial assistance programs can reduce or eliminate portions of the bill itself. Nonprofit hospitals must offer financial assistance under federal rules tied to their tax-exempt status. The application process may require documentation, but the potential savings often justify the effort.

Above all, patients benefit from asking questions early and often. A quick phone call before making a payment can uncover cheaper options. Silence almost always favors the billing system, not the household budget.

The Price of Paying Shouldn’t Be Another Bill

Healthcare already demands careful budgeting, detailed record-keeping, and emotional stamina. Adding a “convenience” charge for the simple act of paying a bill crosses a line that many middle-class families feel acutely. These fees may follow industry rules, but they rarely align with common sense.

Healthcare spending continues to climb, and families continue to shoulder a significant share of that burden. If something as small as a processing fee can spark frustration, what does that say about the broader structure of medical billing in this country?

Should essential care really come with a surcharge for swiping a card, or does it deserve a more thoughtful approach? What do you think about this important healthcare situation? Talk about it in our comments below.

You May Also Like…

Why Medical Billing Disputes Can Raise Final Charges Instead of Lowering Them

Why Do Medical Bills Feel So Hard to Plan Around

How Can Medical Bills Wipe Out Savings Faster Than a Market Crash

8 Shocking Costs of Ignoring Small Medical Bills

Why More Boomers Are Declaring Bankruptcy—And It’s Not Medical Bills

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Lifestyle Tagged With: billing transparency, Consumer Protection, convenience fees, credit card fees, healthcare costs, healthcare reform, hospital billing, medical bills, medical debt, middle-class finances, patient rights, Personal Finance

The End of the 3% Mortgage: Why “Assumable Loans” Are A Smart Way to Buy a House in 2026

February 27, 2026 by Brandon Marcus Leave a Comment

The End of the 3% Mortgage: Why “Assumable Loans” Are A Smart Way to Buy a House in 2026
Image Source: Pexels.com

The 3% mortgage is not coming back. That era burned bright and fast, fueled by emergency rate cuts and historic economic chaos, and it left behind a generation of homeowners clinging tightly to loans they will never refinance away.

In 2026, buyers face a completely different landscape, one shaped by higher interest rates, stubborn affordability challenges, and fierce competition for anything that looks remotely like a deal. Traditional 30-year fixed rates no longer hover near 3%. They sit much higher than pandemic lows, and that reality forces buyers to rethink everything they thought they knew about financing a home.

One strategy now stands out from the noise: assumable loans. For many buyers, especially those priced out by today’s rates, assuming someone else’s lower-rate mortgage may offer the only realistic way to secure a payment that makes sense.

The 3% Mortgage Era Is Over, and the Market Knows It

Between 2020 and early 2022, buyers locked in 30-year mortgage rates that dipped below 3%, according to data from Freddie Mac. That window closed quickly once inflation surged and the Federal Reserve began raising its benchmark rate aggressively in 2022. Mortgage rates climbed above 6% and, at times, even higher, reshaping monthly payments in a dramatic way.

A buyer who could afford a $500,000 home at 3% suddenly faced a much steeper payment at 6% or 7%. The math stopped working for many households. At the same time, millions of homeowners who locked in ultra-low rates chose to stay put rather than trade a 3% mortgage for a 6% one. That “rate lock-in” effect shrank housing inventory and intensified competition for the homes that did hit the market.

In 2026, the market still feels the ripple effects. Rates fluctuate, but they remain well above pandemic lows. Buyers now hunt for creative financing options because the traditional route no longer delivers the same affordability.

What an Assumable Loan Actually Means

An assumable loan allows a buyer to take over a seller’s existing mortgage, including its interest rate, repayment schedule, and remaining balance. Instead of applying for a brand-new mortgage at current market rates, the buyer steps into the seller’s shoes and continues making payments under the original terms.

Not every mortgage qualifies. However, many government-backed loans remain assumable, including those insured by the Federal Housing Administration and guaranteed by the U.S. Department of Veterans Affairs. Some loans backed by the U.S. Department of Agriculture also allow assumptions under specific conditions.

That detail changes everything. If a homeowner secured an FHA or VA loan in 2021 at 2.75% and decides to sell in 2026, a qualified buyer may assume that low rate instead of borrowing at today’s higher rates. The lender still evaluates the buyer’s creditworthiness and financial stability, so approval does not happen automatically. Still, the possibility opens a door that otherwise remains shut.

Why Assumable Loans Suddenly Look Like Gold

In a high-rate environment, interest rate differences of even one or two percentage points can mean hundreds of dollars per month. A gap of three or four percentage points can change a family’s entire budget. Assuming a 3% mortgage when new loans hover around 6% or higher can slash monthly payments dramatically over the life of the loan.

Those savings create leverage. Buyers can qualify more easily because the lower rate reduces the debt-to-income ratio. They can preserve cash flow for repairs, upgrades, or emergencies. They can also avoid paying certain closing costs tied to originating a new mortgage, though assumption fees and other expenses still apply.

Sellers benefit too. A home with a 2.8% assumable mortgage stands out in a crowded listing feed. That low rate becomes a powerful marketing tool. In a market where affordability squeezes buyers from every direction, a transferable mortgage can attract serious attention and potentially justify a stronger sale price.

The End of the 3% Mortgage: Why “Assumable Loans” Are A Smart Way to Buy a House in 2026
Image Source: Pexels.com

Assumable Does Not Mean Easy

Assumable loans offer opportunity, but they also demand strategy and preparation. They are not easy to find, and the biggest hurdle often involves the equity gap. When a buyer assumes a mortgage, the buyer must pay the seller the difference between the home’s purchase price and the remaining loan balance.

Approval also takes time. The lender servicing the original loan must review the buyer’s income, credit, and financial history. Processing can stretch longer than a typical mortgage approval because many lenders have not built streamlined systems for handling assumptions at scale. Buyers must stay patient and organized throughout the process.

Another important detail involves VA loans. If a non-veteran assumes a VA loan, the original veteran’s entitlement may remain tied up in that property unless the buyer qualifies as an eligible veteran who can substitute entitlement. That factor can affect a seller’s future borrowing power, so both parties must understand the implications before moving forward.

How to Hunt for an Assumable Loan in 2026

Finding an assumable loan requires intention. Standard listing platforms rarely highlight assumption status in bold, flashing letters. Buyers must ask directly. Real estate agents can search for properties with FHA, VA, or USDA financing and then confirm assumption eligibility with the loan servicer.

Sellers should check their original mortgage documents or contact their loan servicer to verify whether their loan qualifies and what conditions apply. Transparency upfront can save weeks of confusion later.

Buyers can also include language in their offers that signals willingness to pursue an assumption. That approach shows creativity and flexibility, especially when competing against other offers. In some cases, buyers may negotiate a slightly higher purchase price in exchange for securing a much lower interest rate, and the long-term math can still work in their favor.

The 3% Dream Lives On—But Only for the Strategic

The 3% mortgage era may have ended, but its legacy continues through assumable loans. Buyers who understand how these loans work can unlock opportunities that others overlook. Sellers who recognize the value of their low-rate mortgage can position their homes more competitively in a tight market.

Success in 2026 demands more than scrolling listings and hoping for rate cuts. It requires asking sharper questions, reviewing loan documents carefully, and working with professionals who understand the assumption process. The housing market no longer rewards passive participation. It favors those who adapt quickly and think creatively.

Will assumable loans become the defining strategy of this high-rate era, or will the market shift again before most buyers catch on? Talk about all housing matters in our comments.

You May Also Like…

What Retirees in Income-Based Housing Should Know Before Inheriting

What Happens When Parents Rely on Kids for Housing

Forget Traditional Home Ownership: 12 Alternative Housing Options That Can Give You Real Financial Freedom

Escrow Shock: Why Some Mortgage Payments Suddenly Jumped $300 or More

Insurance Now Accounts for 9% of Typical Monthly Mortgage Payment

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: assumable loans, buying a house, FHA loans, first-time homebuyers, home buying tips, housing market 2026, interest rates, mortgage rates, mortgage strategy, property investment, real estate trends, VA loans

The 2026 Medicare Premium Shock: Why Your Part B Bill Just Jumped by 9.7%

February 27, 2026 by Brandon Marcus Leave a Comment

The 2026 Medicare Premium Shock: Why Your Part B Bill Just Jumped by 9.7%
Image Source: Pexels.com

A 9.7% jump in a bill that already strains fixed incomes does not qualify as a small adjustment. It qualifies as a wake-up call for millions who need Medicare for their daily lives.

The 2026 increase in Medicare Part B premiums forces millions of Americans to take a harder look at their healthcare budgets, their Social Security checks, and the uncomfortable math of retirement. This change does not sit quietly in the background. It lands right in the middle of monthly cash flow, and it demands attention.

What Exactly Is Changing in 2026?

Medicare Part B covers doctor visits, outpatient care, preventive services, durable medical equipment, and many of the routine healthcare needs that keep older Americans stable and independent. Unlike Part A, which most people receive without a premium because they paid Medicare taxes during their working years, Part B requires a monthly premium. In 2026, that standard premium will rise by 9.7%, marking one of the more noticeable increases in recent years.

The Centers for Medicare & Medicaid Services sets these premiums each year based on projected healthcare spending and other financial factors within the Medicare program. When healthcare costs climb, Part B premiums usually follow. Medicare law requires beneficiaries to cover roughly 25% of Part B costs through premiums, with the federal government covering the rest. When spending projections rise, that 25% share rises too.

Higher-income beneficiaries will continue to pay more through Income-Related Monthly Adjustment Amounts, commonly called IRMAA. Those surcharges sit on top of the standard premium and can push monthly costs significantly higher for retirees with larger incomes. That structure has not changed, but the higher base premium means IRMAA brackets now start from a bigger number.

The Real Reasons Behind the 9.7% Increase

Healthcare inflation drives much of this story. Hospitals, physician groups, outpatient centers, and pharmaceutical companies all face higher labor costs, supply expenses, and administrative demands. Those higher costs ripple outward into Medicare’s projections. When Medicare anticipates higher spending for outpatient services, it adjusts Part B premiums accordingly.

New and expensive treatments also play a role. Advanced biologic drugs, specialty medications, and cutting-edge outpatient therapies come with high price tags. Medicare Part B covers certain physician-administered drugs, and when those costs rise, the program’s overall spending rises as well. Lawmakers and policymakers continue to debate drug pricing reform, but until structural changes lower those costs, beneficiaries feel the impact.

Policy decisions can also influence premiums. When lawmakers expand coverage, adjust payment formulas, or add benefits, Medicare must fund those changes. Even when those updates improve care or access, they can raise short-term costs. The 2026 increase reflects a mix of healthcare inflation, projected service use, and ongoing shifts in how providers deliver care.

The 2026 Medicare Premium Shock: Why Your Part B Bill Just Jumped by 9.7%
Image Source: Pexels.com

How This Hits Social Security Checks

Most people enrolled in Medicare Part B have their premiums deducted directly from their Social Security payments. That arrangement simplifies billing, but it also makes every increase feel immediate. When Part B premiums climb by 9.7%, that deduction grows before the remaining benefit reaches a bank account.

The Social Security Administration coordinates with Medicare to manage those deductions. If a cost-of-living adjustment for Social Security benefits does not outpace the premium increase, retirees can feel as though they stand still or even slide backward. Even when Social Security announces a COLA, healthcare costs often eat up a large share of that raise.

The “hold harmless” provision protects many beneficiaries from seeing their Social Security checks shrink from one year to the next due to Part B premium increases. However, that rule does not protect everyone. Higher-income beneficiaries subject to IRMAA, new enrollees, and those who do not receive Social Security benefits can still feel the full impact of the increase without that buffer.

What You Can Do Right Now to Protect Your Budget

No one can wave away a 9.7% increase, but proactive planning can soften the blow. Start with a detailed review of monthly expenses. Identify fixed costs, variable spending, and areas where adjustments can create breathing room. Healthcare premiums often rise gradually over time, so building flexibility into a budget now can prevent future stress.

Consider working with a fee-only financial planner who understands retirement income strategies. A thoughtful withdrawal plan from retirement accounts can help manage taxable income and potentially reduce exposure in future years. Tax-efficient strategies such as spreading out large distributions or coordinating Roth conversions over multiple years can keep income below surcharge thresholds.

Explore programs that offer assistance. Individuals with limited income and assets may qualify for Medicare Savings Programs or Extra Help for prescription drug costs. State Health Insurance Assistance Programs provide free counseling to help beneficiaries understand options and make informed decisions.

Medicare’s Long-Term Pressure

The 2026 increase does not stand alone. Medicare faces long-term financial pressure as the population ages and healthcare costs continue to rise. More than 65 million people rely on Medicare today, and that number will grow as more baby boomers reach eligibility.

Policymakers continue to debate reforms that address drug pricing, payment models, and program financing. Some proposals aim to cap out-of-pocket costs or expand benefits, while others focus on sustainability and cost control. Each policy choice carries trade-offs, and premium levels often reflect those broader decisions.

For retirees, the lesson remains clear: healthcare costs will likely keep rising over time. Planning for those increases must become a core part of retirement strategy rather than an afterthought. Ignoring the trend invites unnecessary stress later.

A 9.7% Reminder That Planning Matters More Than Ever

A nearly 10% increase in Medicare Part B premiums sends a clear message about the cost of healthcare in retirement. This change may feel frustrating, but it also offers an opportunity to reassess budgets, tax strategies, and long-term plans. Careful review of income levels, plan options, and spending habits can turn a surprise increase into a manageable adjustment.

Healthcare will always command a significant share of retirement dollars. Those who stay informed, revisit their choices each year, and adjust strategies as needed will navigate these shifts with more confidence and less disruption.

How will this 9.7% jump influence the way retirement planning unfolds in the years ahead? How is it changing your life? Let’s talk about it in our comments.

You May Also Like…

Social Security 2026 COLA: Why Your 2.8% Raise Disappeared After Medicare Deductions

The Medicare Part B Increase That’s Reducing Social Security Checks By About $185/Month in 2026

The Sunshine State Squeeze: Why Florida Retirees are Seeing Smaller Social Security Checks This Week

The COLA Theft: Why Half of Your Social Security Raise Just Vanished into Medicare This Morning

Medicare Now Covers Mental Health Sessions Without Cost-Sharing—Are You Using It Yet?

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: 2026 Medicare premiums, budgeting, government policy, health insurance, healthcare costs, Inflation, IRMAA, Medicare, Medicare Part B, retirement planning, senior finances, Social Security

How Much Cash You Really Need to Survive a 48-Hour Digital Blackout

February 27, 2026 by Brandon Marcus Leave a Comment

How Much Cash You Really Need to Survive a 48-Hour Digital Blackout
Image Source: Unsplash.com

A digital blackout doesn’t need to last a week to cause chaos. Forty-eight hours without working card machines, banking apps, ATMs, or payment processors can bring daily life to a grinding halt. Gas pumps stall. Grocery stores switch to cash-only. Online banking turns into a blank screen. The question stops being abstract and turns urgent: how much actual cash would it take to get through two days without tapping, swiping, or clicking?

The answer depends on lifestyle and location, but it never equals zero. A 48-hour digital disruption demands real, physical currency in hand, and it demands more than most people keep in their wallets. Smart preparation does not mean hoarding thousands of dollars. It means knowing what daily life truly costs and planning for that reality.

The Real-World Cost of Two Offline Days

Start with basic survival categories: food, water, fuel, medication, and unexpected extras. In most U.S. cities, groceries for two days for one adult cost between $25 to $60, depending on eating habits and whether someone cooks at home. Add a second person and that total easily doubles. Families with children need more, especially if schools close and meals shift entirely to home.

Fuel adds another layer.  During a blackout, gas stations may operate on generators and accept cash only. Waiting until the tank dips near empty creates unnecessary stress. Keeping enough cash to cover at least one full tank protects mobility.

Medications and small essentials matter more than people expect. Pharmacies sometimes switch to cash during system outages, and a last-minute refill can cost $10 to $50 for common prescriptions with insurance pricing. Over-the-counter basics like batteries, bottled water, or baby supplies add another $20 to $50 quickly.

Add these numbers together and the realistic minimum for one adult often lands around $150 to $250 for 48 hours. A couple may need $300 to $400. A family of four may need $400 to $600, especially if they rely on formula, specific dietary foods, or longer commutes.

Why Cards Become Useless Faster Than You Think

Modern payment systems rely on electricity, internet connectivity, and banking networks that communicate constantly. When any link in that chain fails, the transaction fails. Even if a store wants to accept cards, it cannot process payments without network access. Some businesses run offline systems temporarily, but most avoid that risk because fraud and declined transactions create losses.

ATMs also rely on network verification. Without connection to banking systems, machines shut down or limit withdrawals. During widespread outages, lines form quickly at any working machine. Waiting until a crisis begins almost guarantees inconvenience.

Cash never depends on servers or satellites. It requires no battery, no signal, and no password. During short-term outages caused by cyber incidents, technical failures, or severe storms, physical currency keeps daily life moving. That simple reliability makes it powerful.

Building the Right Cash Buffer Without Going Overboard

No one needs to stash thousands of dollars under a mattress for a 48-hour blackout. Instead, focus on calculated coverage. A practical goal for a single adult in an urban area falls around $300 in small bills. Families should consider $500 or slightly more, depending on size and needs.

Small bills matter. During outages, businesses may struggle to make change. Keeping a mix of $5s, $10s, and $20s speeds up transactions and reduces frustration. Avoid storing only large denominations.

Storage also matters. A fireproof home safe offers better protection than a random drawer. Some people divide emergency cash into two locations in case one area becomes inaccessible. Avoid carrying the entire amount daily; that increases theft risk.

Treat this cash like an emergency tool, not spending money. Replenish it immediately after use. Think of it as a financial flashlight: invisible until needed, essential when darkness hits.

Where People Underestimate Their Spending

Most budgeting apps show average spending, but outages change behavior. Without food delivery services or online shopping, people shift toward in-person purchases. That shift often increases impulse spending.

Coffee shops that accept only cash suddenly seem irresistible. Convenience stores become the fallback for forgotten items. Prices at small neighborhood markets often exceed big-box prices. In a short crisis, convenience beats comparison shopping.

Transportation costs also rise when public transit systems face payment glitches. Ride-sharing services may stall if apps fail. Taxis often accept cash, but fares add up quickly. Someone who normally spends $10 a day commuting could easily spend $40 or more during disruptions.

Hands fanning out a stack of $100 bills
Image Source: Unsplash.com

The Hidden Value of Preparedness Beyond Money

Cash solves immediate transaction problems, but preparation extends beyond paper bills. Keeping a small stock of nonperishable food, bottled water, flashlights, and backup phone chargers reduces the need to spend at all.

FEMA recommends maintaining basic emergency supplies that can sustain a household for several days during disasters. While a 48-hour blackout does not equal a full-scale disaster, that guidance reinforces the logic of self-sufficiency. When supplies already sit at home, cash stretches further.

Communication plans also matter. If digital networks fail, meeting points and printed contact numbers become essential. A simple printed sheet with key phone numbers avoids panic when contact lists disappear behind locked screens.

Urban vs. Rural: Why Location Changes the Number

City dwellers often rely heavily on digital payments. Parking garages, public transit systems, and quick-service restaurants rarely keep robust offline systems. That reliance increases the importance of cash.

Rural areas face different challenges. Longer driving distances increase fuel needs. Smaller stores may already operate primarily on cash, which can ease transaction stress but limit inventory. A rural household might prioritize extra fuel cash, while an urban resident might prioritize food and transportation alternatives.

Climate also matters. A winter blackout in a cold region demands backup heating solutions, which may require fuel purchases. A summer outage in a hot region may push people toward hotels with generator power, and that can cost $100 to $200 per night in many areas. Including one night of emergency lodging in a cash plan may make sense for households with medical needs or extreme weather risks.

Cash Is Boring Until It Isn’t

Digital payments feel seamless and efficient, and they deserve credit for convenience. Yet convenience can vanish overnight when systems fail. A modest stash of cash transforms inconvenience into minor disruption.

Preparation does not signal fear. It signals awareness. Forty-eight hours pass quickly when plans exist. Without preparation, those same hours feel long and chaotic. Emergency cash should not drain savings or create anxiety. It should sit quietly, ready for use if needed. Once set aside, it fades into the background of daily life until it proves its value.

Two Days, One Smart Plan

The key here lies in clarity. Calculate actual needs, add a cushion, store small bills securely, and refresh the stash after any use. Pair cash with basic supplies to reduce reliance on emergency spending.

If payment systems went dark tonight, would the cash on hand feel sufficient or suddenly very small? Let’s talk about emergency and financial planning in the comments.

You May Also Like…

7 Decisions Grandparents Must Put in Writing Before a Medical Emergency

The $1,000 Crisis: Why Most Families Can’t Handle a Simple Emergency Anymore

Why Your Emergency Fund Isn’t Protecting You the Way It Did Five Years Ago

9 Budget Categories That Blow Up After One Emergency

The Verizon $20 Trap: Why That “Outage Refund” Text Message Could Wipe Out Your Bank Account

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Finance Tagged With: blackout tips, cash on hand, debit card outage, digital blackout, disaster readiness, emergency budgeting, emergency cash fund, emergency preparedness, personal finance basics, Planning, power outage survival, short-term crisis planning

  • « Previous Page
  • 1
  • …
  • 112
  • 113
  • 114
  • 115
  • 116
  • …
  • 157
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba
  • How Can I Get Rid of Wells Fargo PMI on My Home Loan? by Tamila McDonald
  • Is It Safe to Throw Away Bank Statements? by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework