• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Brandon Marcus

Tech-Threat: 5 Ways AI Is Changing What Your Financial Advisor Should Be Doing for You

December 15, 2025 by Brandon Marcus Leave a Comment

Here Are The Ways AI Is Changing What Your Financial Advisor Should Be Doing for You
Image Source: Shutterstock.com

Money advice used to feel mysterious, guarded, and sometimes intimidating, like it was locked behind mahogany desks and expensive jargon. Now artificial intelligence has kicked the door wide open, changing not just how financial advice is delivered but what you should reasonably expect from the person managing your money.

AI tools can analyze markets in seconds, spot patterns humans miss, and automate tasks that once took entire teams to complete. That doesn’t mean financial advisors are becoming obsolete, but it does mean the bar has been raised—dramatically. If your advisor isn’t evolving alongside this technology, you may be paying human prices for work a machine already does better.

1. Real-Time Data Analysis Should Replace Guesswork

AI can process massive amounts of financial data in real time, meaning market trends no longer need to be interpreted days or weeks later. Your financial advisor should now be using AI-driven insights to explain what’s happening as it happens, not after the opportunity has passed. This shifts their role from speculator to interpreter, helping you understand what the data actually means for your personal goals. If advice still feels vague or delayed, that’s a red flag in an AI-powered world. Modern advising should feel timely, informed, and grounded in live information rather than educated hunches.

2. Personalized Financial Strategies Must Go Deeper

AI makes hyper-personalization possible, analyzing spending habits, risk tolerance, timelines, and even behavioral patterns. That means generic advice and cookie-cutter portfolios no longer cut it. Your advisor should be using AI-enhanced tools to tailor strategies that reflect how you actually live and make decisions. This allows conversations to move beyond “average investor” assumptions and into truly customized planning. When personalization is done right, your financial plan should feel like it was designed specifically for your life, not pulled from a template.
Here Are The Ways AI Is Changing What Your Financial Advisor Should Be Doing for You
Image Source: Shutterstock.com

3. Routine Tasks Should Be Automated, Not Billed

Rebalancing portfolios, tracking performance, and running projections can now be done instantly by AI systems. Your financial advisor shouldn’t be spending your time or money on tasks that technology can complete faster and more accurately. Instead, automation should free them up to focus on higher-value work like strategic planning and complex decision-making. If meetings still revolve around reports you could generate yourself, something is off. The human role should now center on insight, not administration.

4. Behavioral Coaching Becomes The Human Advantage

AI excels at numbers, but it can’t talk you off the ledge during a market panic or challenge emotional money habits with empathy. This is where your financial advisor should truly shine, using emotional intelligence to complement technological precision. Advisors should help you navigate fear, overconfidence, and impulsive decisions that no algorithm can fully prevent. With AI handling the math, humans should handle the mindset. The best advisors now act as behavioral coaches as much as financial strategists.

5. Transparency And Education Are No Longer Optional

AI-powered platforms make information easier to access, compare, and verify than ever before. Your financial advisor should be proactively explaining decisions, assumptions, and strategies rather than expecting blind trust. Education becomes a core service, not an add-on, because informed clients can now fact-check instantly. Advisors who resist transparency risk losing credibility in an era where data is democratized. Trust today is built through clarity, not authority.

The Advisor-Client Relationship Is Being Rewritten

AI isn’t replacing financial advisors, but it is redefining what good advice looks like. The role is shifting away from number crunching and toward interpretation, personalization, and emotional guidance. Clients now have the power to expect smarter tools, deeper insight, and more meaningful conversations. When technology raises the baseline, excellence becomes the differentiator.

How do you feel about AI’s role in financial advice, and what do you expect from your advisor going forward? Share your thoughts, stories, or experiences in the comments section below.

You May Also Like…

7 Obsolete Job Skills That Defined the ’80s Workforce

Is Your Retirement Timeline Still Safe If The Market Drops Again Before New Year’s Eve?

7 Tech Products Gen Z Can’t Live Without — That Are Actually Downgrades

8 Trendy Tech Products Everyone in Silicon Valley Is Obsessed With

4 Bold Predictions About The Future of Personal Finance Technology

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Financial Advisor Tagged With: AI, artificial intelligence, big tech, finance, finances, financial advisor, financial advisors, general finance, portfolio, technology

Is Your Retirement Timeline Still Safe If The Market Drops Again Before New Year’s Eve?

December 14, 2025 by Brandon Marcus Leave a Comment

Is Your Retirement Timeline Still Safe If The Market Drops Again Before New Year’s Eve?
Image Source: Shutterstock.com

The clock is ticking toward the end of the year, and suddenly, your retirement plan feels a little more like a roller coaster than a steady climb. Stocks are jittery, headlines are dramatic, and every market dip makes you question whether your carefully plotted timeline is still realistic. For anyone relying on investments to fund their golden years, this is the kind of stress that can sneak up faster than holiday shopping lines.

But before panic sets in, it’s worth taking a step back and examining what a market drop really means for your retirement—and what you can actually do about it. Let’s discuss why short-term swings don’t always spell disaster and how you can keep your financial goals on track.

Market Fluctuations Are More Normal Than You Think

Volatility is the stock market’s middle name. Daily swings, sudden drops, and unexpected rallies happen more often than most investors realize. Even when news cycles make it feel like the sky is falling, history shows that markets tend to recover over time. If your retirement horizon is years or decades away, a brief dip isn’t the same as a permanent setback. Understanding that ups and downs are standard can reduce stress and prevent impulsive decisions that might hurt your long-term plan.

Your Timeline Is A Buffer, Not A Deadline

One of the biggest mistakes people make is thinking their retirement date is carved in stone. In reality, your timeline is flexible, and market drops are part of the financial landscape. Many advisors recommend keeping a buffer—both in years and in savings—to weather periods of low returns. If the market drops before New Year’s Eve, it may slow your growth temporarily, but it rarely derails a carefully structured plan. Adjusting your strategy without abandoning your timeline is often enough to keep your retirement goals intact.

Diversification Can Act As A Safety Net

Relying on a single type of investment is risky, especially when the market dips unexpectedly. Diversification—spreading money across stocks, bonds, and other assets—reduces the impact of sudden declines. Balanced portfolios often smooth out volatility, making market drops less painful. Even if one sector tanks, others can help stabilize your overall growth. This principle is why long-term investors rarely need to hit the panic button during temporary downturns.

Emotional Reactions Can Be Costly

Watching numbers plummet on a screen can trigger fear faster than almost anything else. Emotional investing—selling at the bottom or chasing hot trends—often causes more damage than the market itself. Successful retirement planning requires discipline and perspective, not reactionary moves. Understanding that temporary dips are a normal part of investing helps prevent knee-jerk decisions. Keeping calm and reviewing your plan strategically is almost always more beneficial than acting out of panic.

Emergency Funds And Income Streams Are Your Friends

Having an emergency fund isn’t just for unexpected car repairs or medical bills. It can also be a lifeline if the market takes a nosedive and your investments temporarily underperform. Knowing that you have liquid assets to cover immediate needs removes the pressure to sell investments at the worst possible time. Additionally, other income streams, such as pensions or part-time work, create stability regardless of market fluctuations. These safety nets allow you to let your portfolio recover while still maintaining your lifestyle.

Is Your Retirement Timeline Still Safe If The Market Drops Again Before New Year’s Eve?
Image Source: Shutterstock.com

Reviewing Your Asset Allocation Matters

Your retirement investments shouldn’t be “set it and forget it.” Over time, shifts in the market can cause your portfolio to drift away from your target allocation. Regular reviews help you ensure that your risk level aligns with your timeline and comfort zone. If a market drop causes your stocks to underperform, rebalancing can restore balance and reduce future risk. Staying proactive instead of reactive is key to maintaining both growth and peace of mind.

Long-Term Growth Often Outpaces Short-Term Worries

Even the most dramatic end-of-year drops tend to be smoothed out over time. Historically, markets have recovered from downturns and reached new highs, rewarding patient investors. If your retirement is a decade or more away, today’s dip is a small blip in the larger trajectory. Focusing on consistent contributions and staying invested often beats attempting to time the market. The real advantage comes from compounding returns and letting time do the heavy lifting.

Professional Guidance Can Reduce Anxiety

Working with a financial advisor isn’t just about making money—it’s about managing stress and creating a roadmap. Advisors can provide perspective, suggest adjustments, and help you stick to your plan during turbulent times. Knowing that someone is monitoring your strategy and making informed recommendations gives peace of mind that numbers alone can’t provide. Even brief consultations can help you understand whether a drop is significant or just noise. Professional insight ensures that fear doesn’t drive your financial decisions.

Stay Calm, Stay On Track

Short-term market drops before New Year’s Eve may feel alarming, but they don’t automatically derail your retirement plan. Understanding volatility, keeping your timeline flexible, maintaining diversified investments, and leaning on safety nets can keep your goals intact. Emotional reactions are rarely helpful, and focusing on long-term growth usually wins over panic.

Have you ever faced a market drop that shook your confidence? Share your experiences, strategies, or lessons learned in the comments section below.

You May Also Like…

Retirement Redflag: 6 Withdrawal Moves That Could Drain Your Nest Egg Fast

Calculate Your True Retirement Number Using Our Exclusive Online Tool

New Year, New Credit Score: Tips to Improve Your Financial Health

Why Do Families Pretend They Can Afford the Holidays

Why Must I Pay a Percentage of My Assets Even When Markets Fall Hard?


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Retirement Tagged With: Asset Allocation, beginning investors, diversify, emergency funds, Emotional Spending, Holiday Savings, holiday spending, Holidays, income streams, investing, investments, investors, market fluctuations, multiple income streams, reitire, retire, retiree, retirees, Retirement, retirement savings, retirement timeline, saving money, stock market

Charity Strategy: 9 Giving Moves That Bring Tax Benefits Many People Ignore

December 14, 2025 by Brandon Marcus Leave a Comment

There Are Giving Moves That Bring Tax Benefits Many People Ignore
Image Source: Shutterstock.com

Giving to charity isn’t just about making the world a better place—it can also be a surprisingly smart move for your wallet. Many people donate generously without realizing that the way they give could unlock tax benefits that often go unnoticed. With a little strategy, your generosity can be amplified: helping others while potentially saving yourself money.

Understanding the nuances of charitable giving doesn’t require a finance degree—just some savvy planning and a willingness to think creatively. Let’s dig into nine giving moves that can transform both your impact and your tax situation.

1. Donate Appreciated Stock Instead Of Cash

Instead of writing a check, consider giving stocks or other appreciated assets to charity. If you’ve held the stock for over a year, you can deduct its full market value and avoid paying capital gains taxes. This means your contribution could be worth more than if you sold the stock first and donated the cash. Many people overlook this option simply because it feels more complicated than it is. With a quick conversation with your broker or financial advisor, this move can be surprisingly straightforward and highly rewarding.

2. Bundle Smaller Gifts Into One Year

Instead of giving smaller amounts over several years, you can “bunch” donations into a single tax year. By concentrating your charitable contributions, you may exceed the standard deduction threshold, allowing you to itemize and maximize your tax benefits. This strategy works especially well for families or individuals who alternate between standard and itemized deductions each year. Planning ahead and timing your donations can increase both the financial and emotional payoff. Many people give steadily but miss out on the tax advantage of bundling, making this an easy win.

3. Use Donor-Advised Funds

Donor-advised funds, or DAFs, are like a personal giving account that lets you donate now and distribute later. Contributions to a DAF are immediately tax-deductible, even if the actual charitable grants happen years down the line. This flexibility allows you to manage your giving strategically while potentially benefiting from tax advantages in high-income years. It’s also a simple way to involve family members in philanthropy. Savvy donors often forget this tool exists, even though it’s one of the most effective ways to multiply impact.

4. Give Through Your IRA

If you’re over 70½, making charitable donations directly from your IRA can be a tax-smart move. Known as a Qualified Charitable Distribution (QCD), these gifts count toward your required minimum distribution without being taxed as income. This can reduce your taxable income while supporting causes you care about. Many retirees are unaware that this option exists, leaving potential savings on the table. A quick check with your IRA custodian can clarify the rules and make this move painless and beneficial.

5. Donate Items Instead Of Money

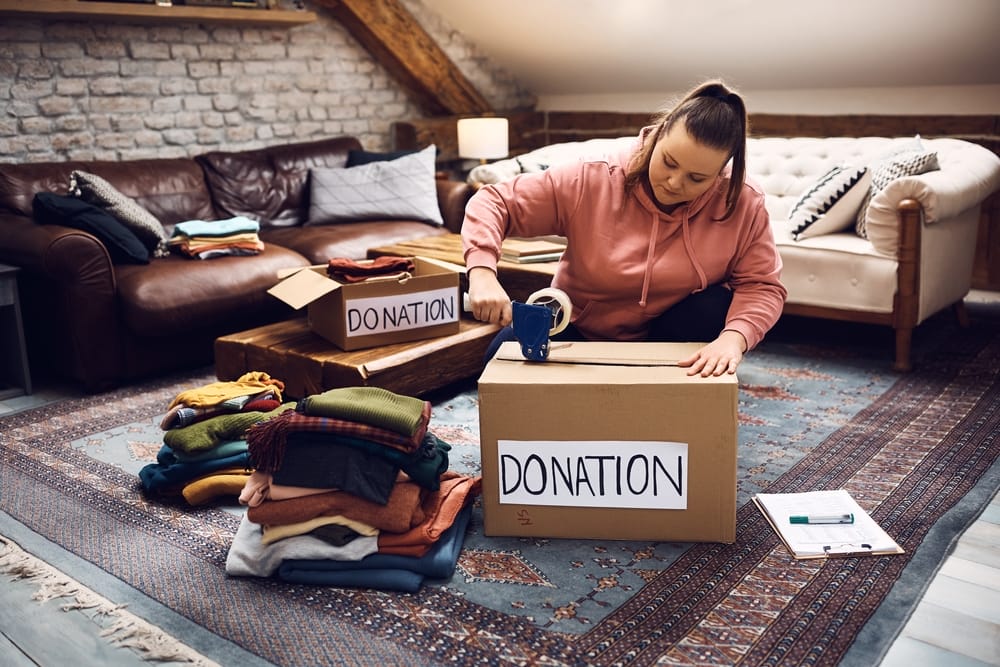
Giving clothing, household items, or even vehicles can provide significant tax deductions if properly documented. Many people undervalue or forget the tax implications of donating tangible goods.

By keeping accurate records and obtaining receipts, you can claim deductions based on fair market value. It’s a win-win: your items help someone in need and may reduce your tax bill. The key is organization—without proper documentation, the deduction may not be allowed, so tracking is essential.

There Are Giving Moves That Bring Tax Benefits Many People Ignore
Image Source: Shutterstock.com

6. Pay Tuition Or Medical Expenses For Someone Through A Charity

Certain charitable organizations allow you to cover educational or medical costs for individuals directly through the charity. These contributions may qualify for tax deductions while making a big impact in someone’s life. Many people don’t realize that donations to these programs can be deductible just like traditional cash gifts. The effect is twofold: you provide immediate support and potentially lower your tax liability. Researching qualified organizations that offer these programs can unlock a creative giving strategy.

7. Donate From Your Business

Business owners have a unique opportunity to make charitable giving work for both philanthropy and taxes. Contributions from a business can often be deducted as business expenses, lowering taxable income. This works whether you’re a sole proprietor, partner, or run a corporation, though the rules differ slightly. By integrating charitable giving into your business strategy, you can amplify both your social impact and your financial efficiency. Entrepreneurs sometimes overlook this, treating personal and business giving separately, when combining them could be highly advantageous.

8. Give Appreciated Real Estate

Just like stocks, real estate can be donated to charity in ways that maximize deductions and minimize capital gains taxes. If you’ve held a property for years and its value has appreciated, donating it instead of selling can yield significant tax benefits. It also frees you from ongoing maintenance or management responsibilities. Charities often welcome such gifts because they can sell the property to fund their programs. Many donors assume real estate donations are complicated, but with proper guidance, it can be surprisingly straightforward and impactful.

9. Take Advantage Of State-Level Tax Credits

Federal deductions are well-known, but state-level incentives are frequently ignored. Some states offer tax credits for donations to specific local charities or programs, effectively reducing your state tax bill directly. These credits can sometimes be as valuable—or more valuable—than federal deductions. The challenge is knowing which programs qualify, so research is essential. By exploring state-level incentives, you can unlock extra value from your generosity that many donors overlook entirely.

Maximize Your Giving While Saving

Charitable giving doesn’t have to be purely altruistic—it can be strategically smart as well. From donating stocks and real estate to taking advantage of donor-advised funds and state tax credits, there are many opportunities to combine impact with financial savvy. The key is awareness and planning, ensuring your generosity goes further both for the causes you care about and for your own tax benefits.

Have you used any of these strategies, or do you have a favorite creative way to give? Make sure that you share your experiences, tips, or stories in the comments section below.

You May Also Like…

7 Unexpected Things Smart People Leave to Charity Instead of Family

8 Surprising Reasons People Secretly Hate Donating to Charity

10 Times the Rich Used Charities to Hide Their Wealth

5 Tax Benefits That Disappear if You Downsize Too Late

Can Your Taxes Be Cut In Half By You Simply Incorporating Your Name?


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: charitable giving Tagged With: charitable contributions, Charitable donation, Charitable Donations, charitable giving, Charitable Giving Strategies, charitable tax break, charities, charity, charity donations, donated stocks, donating, donations, Stock, stock market, stocks, tax benefits, tax breaks, taxes

Debt Alert: 6 Ways Holiday Spending Could Trigger a January Credit Score Crisis

December 14, 2025 by Brandon Marcus Leave a Comment

Here Are The Ways Holiday Spending Could Trigger a January Credit Score Crisis
Image Source: Shutterstock.com

The holidays are supposed to be magical—a time for twinkling lights, festive music, and, of course, gift-giving. But after the last present is unwrapped and the New Year’s confetti settles, reality often hits like a snowball to the face. Credit card statements arrive, debt balances loom, and suddenly, that cozy holiday cheer feels a lot more like financial panic. Even responsible spenders can fall into traps that quietly tank their credit score before January is over.

The problem is that holiday spending isn’t just about overspending—it’s about how small decisions compound in ways most people never anticipate.

1. Maxing Out Credit Cards Without A Repayment Plan

It’s tempting to swipe without thinking when stores are decked out in lights and promotions are everywhere. Unfortunately, maxing out your credit cards over the holidays can dramatically affect your credit utilization ratio, one of the most important factors in your score. High balances relative to your credit limit send a signal to lenders that you might be overextended. Even if you pay the balance off quickly, the timing of reporting can mean your January statement still shows a maxed-out card. Without a clear repayment plan, what felt like a festive splurge can quickly turn into a credit score nightmare.

2. Racking Up Multiple Store Credit Cards

Those “instant approval” offers at checkout might seem harmless—or even smart if they come with a discount. The reality is that opening multiple store credit cards in a short period can ding your credit score in multiple ways. Each application triggers a hard inquiry, which can shave points off your score temporarily. The added new accounts also reduce the average age of your credit history, another factor lenders evaluate. While one or two cards might be manageable, a stack of plastic can make January feel more stressful than celebratory.

3. Missing Minimum Payments During Holiday Chaos

Holiday schedules are hectic, and bills can slip through the cracks. Missing a minimum payment—even by a few days—can have a surprisingly large impact on your credit score. Late payments are reported to credit bureaus and can linger on your report for years. The stress of managing gifts, parties, and travel often means people forget to prioritize monthly bills. Staying organized and setting reminders is critical; otherwise, that cheerful December spending spree can echo as a January credit disaster.

4. Overreliance On Buy Now, Pay Later Options

Buy Now, Pay Later (BNPL) services are everywhere, making it tempting to spread out payments over weeks or months. But while the idea feels harmless, these services can quietly affect your creditworthiness. Missing a payment or delaying your repayment can trigger late fees and potential credit reporting consequences. Even when you pay on time, juggling multiple BNPL plans can lead to a confusing financial picture that increases stress and risk. It’s easy to underestimate the impact until the first statement arrives in January—then panic sets in.

5. Ignoring Existing Debt When Holiday Shopping

It’s easy to get caught up in gift lists and holiday deals, but ignoring pre-existing debt can be dangerous. Adding new balances on top of old ones increases your total debt load and raises your credit utilization across all cards. Lenders see this as a higher risk, and your credit score can drop as a result. Even if your spending seems reasonable, failing to account for ongoing obligations can create a compounding effect. Keeping track of both old and new debt is essential to avoid a post-holiday financial hangover.

6. Not Monitoring Credit Reports Until It’s Too Late

After the holiday rush, many people don’t check their credit reports until something goes wrong. The problem is that errors, overlooked balances, or unexpected charges can silently damage your score if you’re not paying attention. Monitoring your credit allows you to catch issues early, dispute errors, and plan repayment strategies before they spiral. Waiting until January to see your credit score can be a rude awakening. Staying proactive during and after the holidays is key to preventing a financial headache you could have avoided.

Here Are The Ways Holiday Spending Could Trigger a January Credit Score Crisis
Image Source: Shutterstock.com

Stay Ahead Of The Holiday Hangover

The holidays are meant to be joyful, but without careful planning, they can also trigger a credit score crisis that lasts well into the new year. From maxed-out cards to missed payments and Buy Now, Pay Later traps, even well-intentioned spending can have long-term consequences.

Awareness is the first step—recognizing how decisions made in December can affect January and beyond allows you to act before the damage is done. By planning, tracking, and staying organized, it’s possible to enjoy the season without financial regrets.

Have you ever experienced a post-holiday credit surprise? Share your stories, tips, or cautionary tales in the comments section below—we want to hear your experiences.

You May Also Like…

6 Credit Mistakes That Redditors Confess Cost Them Thousands

8 “Harmless” Daily Habits That Are Secretly Wrecking Your Credit Score

The Medical Bill Mistake That Can Cripple Your Credit for a Decade

Accelerate Your Debt Repayment Using Our Powerful Snowball Method.

6 Sneaky Financial Risks Hiding in Holiday Spending


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Debt Management Tagged With: average joe debt, avoiding debt, avoiding overspending, buy now pay later, credit, Credit card debt, credit cards, credit repair, credit report, credit score, Debt, debt advice, debt alerts, debt collections, Debt Collectors, debt consolidation, Debt Management, gift-giving, Holiday, holiday spending, Holidays, repayment plans, Smart Spending, spending

5 Sneaky Signs That Debt Is Adding Up

December 14, 2025 by Brandon Marcus Leave a Comment

Here Are 5 Sneaky Signs That Debt Is Adding Up
Image Source: Shutterstock.com

Debt is one of those things that can sneak up on you without warning, almost like a financial ninja in the night. One day, you’re sipping your latte and paying your bills on time, and the next, you’re juggling multiple due dates and wondering where all your money went. It doesn’t always show itself with obvious red flags like missed payments or overdraft fees. Often, it starts small, with tiny habits and unnoticed patterns that quietly multiply over time. Recognizing these sneaky signs early is the key to staying in control before debt turns into a full-blown money crisis.

1. You Constantly Transfer Balances Or Borrow To Pay Bills

One of the clearest signs debt is creeping up is when you start using one debt to pay another. Credit card balance transfers, short-term loans, or borrowing from friends might seem like temporary fixes, but they often hide a bigger problem. It creates a cycle where you’re not actually reducing your debt—you’re just moving it around. The more you do this, the harder it becomes to see the full picture of your financial health. If you find yourself constantly hopping from one payment solution to another, it’s a red flag that debt is quietly stacking up.

2. Your Minimum Payments Are Becoming The Norm

Paying only the minimum on credit cards or loans might feel manageable, but it’s a classic sign that debt is starting to dominate your finances. Minimum payments are designed to keep you in the game for the long haul, not to help you get ahead. When you start defaulting to minimums month after month, interest accumulates, and balances can balloon without you noticing. Over time, this habit drains your financial flexibility and leaves less room for essentials or savings. If you’re seeing your payments linger at the minimum line more than your budget allows, it’s time to pay attention.

3. You Avoid Checking Your Accounts

Ignoring account statements, bank apps, or credit card notifications may feel like a stress-free strategy, but it’s one of the most dangerous signs that debt is piling up. Avoidance doesn’t make debt disappear—it makes it grow silently, often faster than you realize. Missing updates on balances, due dates, or interest charges can lead to late fees, penalties, and more stress. The anxiety of knowing you’ve ignored your finances can spiral into a vicious cycle of avoidance and accumulating debt. Regularly checking your accounts, even when it’s uncomfortable, is essential to staying on top of things.

4. Everyday Purchases Require Credit

If you find yourself reaching for a credit card for things you used to pay with cash, it might be a sneaky indicator that debt is increasing. Small, routine purchases—like groceries, gas, or coffee—add up quickly when you rely on credit instead of money you actually have. This behavior often reflects a gap between income and expenses, which can spiral into bigger financial problems if left unchecked. While it may not feel urgent now, repeated reliance on borrowing for everyday spending is a clear warning. Tracking where your money goes and catching these habits early can prevent small purchases from turning into a mountain of debt.

Here Are 5 Sneaky Signs That Debt Is Adding Up
Image Source: Shutterstock.com

5. You Feel Constant Stress About Money

Debt doesn’t just affect your finances—it affects your mental and emotional state, too. If you’re constantly worrying about bills, budgeting, or what to pay first, it’s a strong sign that debt may be quietly accumulating. Chronic financial stress can influence decisions, leading to impulsive spending or avoiding the problem entirely. It’s often subtle at first, like a background noise you barely notice, until it starts dictating daily decisions and your overall mood. Paying attention to how you feel about money can give you an early warning that debt is creeping higher, even if balances look manageable on paper.

Catch Debt Early Before It Takes Over

Debt doesn’t always announce itself with alarms or flashing lights. Sometimes it sneaks in through small habits, quiet patterns, and unnoticed behaviors that slowly tighten their grip. Recognizing signs like relying on credit for everyday purchases, avoiding statements, and feeling constant financial stress can save you from bigger trouble down the line. Awareness is the first step to regaining control and planning a path out of debt.

Have you noticed any of these sneaky signs in your own finances? Share your experiences, insights, or tips in the comments section below.

You May Also Like…

How to Teach Kids About Debt

Accelerate Your Debt Repayment Using Our Powerful Snowball Method.

5 Debt Strategies Redditors Recommend When You’re Drowning But Financial Advisors Say Are Stupid

What Really Happens If You Ignore a Debt Collector’s Voicemail

7 Things You Should Never Say to a Debt Collector on the Phone


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Debt Management Tagged With: avoiding debt, borrowing money, Debt, debt advice, debt avalanche, debt collection, debt collections, Debt Collectors, debt consolidation, Debt Management, debt payoff, eliminating debt, Money, money issues, Saving, saving money, savings account, sneaking debt

Market Calm: 4 Quiet Moves Wealthy Clients Are Making Before the Holidays

December 14, 2025 by Brandon Marcus Leave a Comment

Here Are The Quiet Moves Wealthy Clients Are Making Before the Holidays
Image Source: Shutterstock.com

As the holiday season approaches, the markets have a way of feeling like a slow-moving storm—predictable enough to prepare for, but unpredictable enough to keep you on your toes. For most investors, it’s a time of cautious optimism, holiday cheer, and a few lingering worries about portfolio performance. But the wealthiest clients aren’t just sitting back with eggnog in hand. They’re making quiet, deliberate moves that fly under the radar while the rest of the market focuses on festive distractions.

These strategies aren’t flashy, but they’re clever, effective, and reveal how high-net-worth investors think differently about money, timing, and opportunity.

1. Rebalancing Portfolios With Surgical Precision

Wealthy investors rarely let their portfolios drift aimlessly. Before the holidays, many take a step back to review their holdings and rebalance with surgical precision. They aren’t just selling the underperformers or buying the winners—they’re adjusting allocations to align with long-term goals while capitalizing on seasonal market patterns. By rebalancing now, they reduce risk, capture gains, and prepare their investments for the first quarter of the next year. Unlike casual investors who check their accounts sporadically, these clients approach rebalancing as a strategic ritual that maintains control and calm in a market that can otherwise feel chaotic.

2. Tax-Efficient Moves To Lock In Gains

High-net-worth investors are always mindful of taxes, especially when the year is coming to a close. Quietly, many are harvesting gains or losses in a way that minimizes their tax exposure while positioning themselves for future growth. This isn’t about panic selling—it’s about intelligent timing and understanding which moves make sense in a broader financial picture. The holidays are often a time to assess what’s worked and what hasn’t, and to act in ways that protect wealth while preparing for new opportunities. By planning these moves discreetly, they avoid the noise of market hype and maintain flexibility heading into the new year.

Here Are The Quiet Moves Wealthy Clients Are Making Before the Holidays
Image Source: Shutterstock.com

3. Strategic Cash Positioning For Early-Year Opportunities

Wealthy clients understand that liquidity is power. As the holiday season winds down, many are quietly increasing their cash positions, not out of fear, but to ensure they have dry powder for strategic investments early in the next year. This allows them to take advantage of market dips, special offerings, or private deals that less-prepared investors might miss. It’s a calm, patient approach: they don’t chase trends but position themselves to move decisively when opportunities appear. By being proactive now, they transform uncertainty into leverage, keeping their portfolios both flexible and resilient.

4. Review And Fine-Tune Long-Term Plans

While the public is distracted by year-end parties, wealthy clients are reviewing their broader financial plans. They’re looking at estate strategies, philanthropic commitments, retirement allocations, and other long-term goals that require careful attention. The holidays provide a natural pause—a time to check progress without the constant day-to-day noise of market movements. This review often leads to small, quiet adjustments that compound into significant advantages over time. It’s a methodical, deliberate approach that reinforces the principle that wealth management is not just about reacting to the market—it’s about designing it thoughtfully.

Learn From Quiet Strategies

While the average investor might focus on seasonal trends, flashy predictions, or panic-driven decisions, wealthy clients are quietly shaping their financial future with calm, deliberate actions. Rebalancing portfolios, making tax-efficient moves, positioning cash strategically, and reviewing long-term plans are subtle yet powerful practices that can make a dramatic difference. Observing these behaviors offers a masterclass in thoughtful, patient wealth management, especially during a time of year when emotions often run high.

Have you tried implementing any of these strategies in your own investing or financial planning? Share your experiences, tips, or holiday-season investing stories in the comments section below.

You May Also Like…

Why Young People Should Invest In The Stock Market

Why Must I Pay a Percentage of My Assets Even When Markets Fall Hard?

5 Valuable Lessons Learned From Market Crashes Historically

How Much Money Is Enough to Be Considered Truly Wealthy Nowadays?

7 Money Lessons Baby Boomers Taught That Still Build Wealth


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: cash positioning, gains, holiday spending, Holidays, investing, investments, investors, Life, Lifestyle, overspending, portfolios, Smart Spending, spending, spending strategies, Wealth, wealthy clients, wealthy investors

Year-End Push: 10 Checklist Items That Could Save Thousands If You Act Fast

December 13, 2025 by Brandon Marcus Leave a Comment

Here Are The Items That Could Save Thousands If You Act Fast
Image Source: Shutterstock.com

The end of the year is a wild sprint. Between holiday shopping, tax planning, and trying to wrap up lingering projects, it’s easy to forget that a few smart financial moves could save you thousands before the calendar flips. The clock is ticking, but the right actions now can make a huge difference in your bank account—and your stress levels.

Think of it as a strategic game: every box you check on this list is a power-up that keeps more money in your pocket. Let’s dive into ten urgent, high-impact items that can pay off big if you move quickly.

1. Maximize Your Retirement Contributions

Retirement accounts like 401(k)s and IRAs often have annual contribution limits, and year-end is the perfect time to make sure you’ve maxed them out. Contributing the full amount can reduce your taxable income while boosting your long-term savings—a double win. If you haven’t been diligent all year, even a last-minute deposit can have a meaningful impact on your tax bill. Many employers allow catch-up contributions or last-minute deposits in December, so it’s worth checking. Taking action now sets you up for financial freedom decades down the line.

Here Are The Items That Could Save Thousands If You Act Fast
Image Source: Shutterstock.com

2. Harvest Investment Losses

If your portfolio includes underperforming stocks or funds, you may be able to offset gains by selling them—a strategy called tax-loss harvesting. This can reduce your taxable income, potentially saving you thousands on your tax bill. Don’t worry; you can reinvest in similar assets without losing your market position, as long as you avoid wash sale rules. Reviewing your investments before year-end ensures you’re not leaving money on the table. Even small losses strategically harvested can compound into significant savings over time.

3. Review Flexible Spending Accounts

If you have a flexible spending account (FSA), now is the time to use any remaining balance. FSAs often have a “use it or lose it” policy, meaning money not spent by the end of the year disappears. Stock up on medical supplies, schedule appointments, or pay for eligible services before the deadline. These accounts are pre-tax dollars, so spending them is essentially getting a discount on healthcare costs. Checking your FSA now ensures you’re not accidentally forfeiting free money.

4. Make Charitable Donations

Charitable giving is not just good for the soul—it can also be good for your taxes. Donations made before December 31 can be deducted from your taxable income, potentially lowering your year-end tax liability. Keep records and receipts, and consider donating appreciated assets like stocks, which can also help you avoid capital gains taxes. Donating strategically allows you to support causes you care about while maximizing financial benefits. Planning your contributions now ensures your giving counts for the current tax year.

5. Reevaluate Your Withholding

Many people overpay taxes throughout the year without realizing it, leaving their money sitting with the IRS instead of in their pockets. Reviewing your withholding now allows you to adjust your paycheck before year-end, giving you more cash flow immediately. It’s a small change with immediate impact, especially if your income has shifted or you’ve had life changes like marriage or a new child. Accurate withholding ensures you’re not giving an interest-free loan to the government. Even minor tweaks can save hundreds or thousands, depending on your income level.

6. Pay Down High-Interest Debt

High-interest debt is a silent killer of personal finances, and December is a great time to knock it down before interest compounds further. Every dollar you pay off now reduces future interest charges, freeing up money in the coming year. Consider targeting credit cards or personal loans with the highest rates first for maximum impact. Reducing debt also improves your financial flexibility and credit score. Acting now gives your future self a lighter financial load and more breathing room in your budget.

7. Reassess Your Insurance Coverage

Year-end is a natural checkpoint for reviewing your insurance policies, from health to auto to homeowners. Are your coverage limits still appropriate? Have you accumulated assets that need protection or removed items that don’t? Adjusting your policies can reduce premiums and ensure you’re not overpaying—or underprotected. A quick review now could prevent costly surprises later. Staying proactive on insurance protects both your finances and peace of mind.

8. Take Advantage Of Employer Benefits

Many employer benefits reset at year-end, including wellness programs, tuition reimbursement, or dependent care accounts. If you have unused funds or eligible benefits, it’s smart to take action before they vanish. Scheduling a last-minute dental procedure, enrolling in a course, or submitting claims can make a meaningful difference. These benefits are essentially free money that supports health, education, or family needs. Checking in now ensures you’re fully leveraging everything your employer provides.

9. Plan For Next Year’s Major Expenses

Even though the new year is days away, planning for major expenses like vacations, home repairs, or big purchases can save money in the long run. Knowing what’s coming lets you adjust spending, open dedicated savings accounts, and take advantage of seasonal deals. Pre-planning also reduces financial stress and prevents last-minute debt. Setting aside funds now puts you ahead of the game instead of scrambling in January. It’s a simple strategy that builds momentum and keeps your finances on track.

10. Evaluate Tax Credits And Deductions

Tax credits and deductions are among the most overlooked opportunities for year-end savings. Childcare credits, energy-efficient home improvements, and education credits can all impact your bottom line. Reviewing eligibility before December 31 ensures you don’t miss out on valuable reductions. Even smaller credits, when combined, can add up to substantial savings. A quick consultation with a tax professional or thorough self-review can make the difference between paying extra and keeping more of your hard-earned money.

Take Action Now And Reap The Rewards

The last month of the year is hectic, but it’s also a golden opportunity to make smart financial moves that pay off big. From contributions and deductions to debt reduction and benefit maximization, these ten checklist items are your fast-track to saving thousands. The key is urgency—waiting until January can mean missed deadlines, lost opportunities, and unnecessary stress.

Which of these tips will you tackle first? Share your thoughts, strategies, or year-end wins in the comments section below; your story could inspire someone else to act fast and save big.

You May Also Like…

Is It Too Late to Start Saving Aggressively for a Comfortable Retirement?

Did You Know Turning Off Your Wi-Fi Router at Night Can Save You Money?

Are There Tax-Saving Strategies My Current Advisor Completely Missed?

Could Ignoring Inflation Erase Decades of Savings

7 Stock Market Myths That Cost Beginner Investors Their Life Savings


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Finance Tagged With: 401(k), automate savings, bad investing advice, Charitable Donations, charity, Debt, everyday items, flexible spending accounts, high-interest debt, investing, Investment, investment losses, retire, Retirement, retirement contributions, Roth IRA, Saving, saving money, savings, spending accounts

Behavior Risk: 4 Psychological Traps Mid-lifers Fall Into When Markets Turn Choppy

December 13, 2025 by Brandon Marcus Leave a Comment

Here Are Psychological Traps Mid-lifers Fall Into When Markets Turn Choppy
Image Source: Shutterstock.com

Markets are unpredictable.

One moment, everything feels like a smooth ride toward retirement bliss; the next, your portfolio looks like a rollercoaster with no brakes. For mid-lifers, who are juggling mortgages, college funds, and plans for the next chapter of life, market turbulence can trigger reactions that aren’t always rational.

What many investors don’t realize is that our brains have quirks—psychological traps—that can make us act in ways that hurt long-term financial goals. Understanding these behaviors can mean the difference between steady growth and emotional whiplash.

1. Overconfidence In Times Of Stability

It’s easy to feel invincible when markets are steadily climbing. Mid-lifers often assume that past success guarantees future gains, which can lead to excessive risk-taking. Overconfidence can manifest as ignoring diversification, investing too heavily in a single stock, or chasing returns without considering downside. The danger is that when the market inevitably stumbles, the shock can be brutal, both financially and emotionally. Recognizing overconfidence as a trap allows investors to reassess risk realistically and maintain balance.

2. Loss Aversion That Freezes Decision Making

Humans are wired to hate losses more than we enjoy gains, and this tendency intensifies as retirement looms closer. Mid-lifers often cling to underperforming investments, refusing to sell because the idea of locking in a loss feels unbearable. This psychological trap can result in stagnant portfolios, missed opportunities, or even compounding losses over time. Fear-driven inaction is just as damaging as impulsive decisions, because markets reward disciplined movement, not paralysis. Understanding loss aversion helps investors make decisions based on strategy, not fear.

3. Herd Mentality That Fuels Panic Selling

Market downturns often feel like a stampede, and mid-lifers are not immune to the herd instinct. When peers or news outlets scream about crashes, it’s tempting to sell everything in a panic, even if fundamentals remain sound. This trap is dangerous because it’s rarely the market itself that’s the problem—it’s the emotional reaction to it. Selling at the bottom locks in losses and often prevents participation in eventual recoveries. Recognizing when you’re following the herd allows for calmer, more calculated responses instead of knee-jerk reactions.

4. Confirmation Bias That Distorts Reality

We all like to hear what confirms our beliefs, and mid-lifers are especially prone to this when markets become volatile. Investors might only read articles that support their bullish or bearish stance while ignoring contradicting data that could encourage better decisions. This selective attention can reinforce bad habits, like holding on to risky assets or avoiding opportunities because they challenge preconceptions. Over time, confirmation bias clouds judgment and prevents rational portfolio adjustments. Being aware of this trap encourages a more balanced perspective, weighing both risk and reward without emotional distortion.

Here Are Psychological Traps Mid-lifers Fall Into When Markets Turn Choppy
Image Source: Shutterstock.com

Recognize The Traps, Protect Your Portfolio

Financial markets aren’t just about numbers—they’re about human behavior. Mid-lifers often face unique pressures, balancing retirement goals with current obligations, and psychological traps can magnify mistakes during market turbulence. Awareness is the first step: recognizing overconfidence, loss aversion, herd mentality, and confirmation bias can make a huge difference in long-term financial outcomes.

By understanding the ways our brains misfire, investors can respond more strategically, keep panic in check, and maintain confidence through choppy waters.

Have you experienced any of these psychological traps? Write about your thoughts, stories, or tips in the comments section below.

You May Also Like…

8 Hidden Risks People Overlook When Financing a Car at High APR

8 Financial Risks Hidden in Pet Ownership

4 Psychological Hurdles Preventing Your Financial Independence Now

10 Reasons The Lower Middle Class Are Afraid to Invest

7 Clear Paths to Financial Freedom With Minimal Risk Exposure


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Investing Tagged With: beginning investing, confirmation bias, financial advisor risk, financial risk, herd mentality, invest, investing, investors, loss aversion, markets, Money, money issues, psychological traps, stock market

Risk Reboot: 5 Portfolio Tweaks If You Believe a Rate Hike Surprise Is Coming

December 13, 2025 by Brandon Marcus Leave a Comment

Here Are 5 Portfolio Tweaks If You Believe a Rate Hike Surprise Is Coming
Image Source: Shutterstock.com

Markets have a way of throwing curveballs just when you think you’ve got a handle on them, and an unexpected rate hike is about as sudden and disruptive as it gets. Investors who ignore the possibility of higher rates can wake up to portfolio losses that feel more like a slap than a gentle nudge. On the flip side, a nimble strategy can transform fear into opportunity, turning a surprise rate increase into a chance to reposition, hedge, and thrive.

If you’re mentally bracing for central bank action, it’s time to consider tweaks that protect your gains and exploit the new landscape. From bonds to equities and alternative assets, small adjustments now could save headaches later—and maybe even unlock unexpected growth.

1. Adjust Your Bond Duration

Interest rate hikes are the arch-nemesis of long-duration bonds, which tend to fall in value when yields rise. Shortening the duration of your fixed-income holdings can reduce sensitivity to rate shocks and stabilize your portfolio.

Think of it as trading in a long, wobbly bridge for a series of shorter, sturdier spans. Inflation-protected securities, floating-rate notes, and shorter-term bonds can also help cushion the impact of sudden hikes. By strategically managing duration, you’re not avoiding bonds altogether—you’re just making them more resilient to surprises.

2. Tilt Towards Financial Sector Equities

Financial institutions, particularly banks and insurers, often thrive in rising rate environments because higher rates improve interest margins. A rate hike surprise could boost earnings expectations for this sector faster than for more rate-sensitive industries like utilities or real estate. Investors might consider rebalancing a small portion of their equity allocation toward these beneficiaries to capture upside potential. Timing matters, of course, and overexposure could backfire if the hike triggers broader market volatility. Even a modest tilt can provide both defensive ballast and opportunistic growth during turbulent rate shifts.

3. Reevaluate Your Dividend Strategy

High-dividend stocks are popular for income-focused investors, but they’re also among the most sensitive to interest rate changes. When rates climb unexpectedly, some investors may flee dividend-paying equities in favor of safer fixed-income alternatives. Reassessing your holdings can help avoid surprise losses while still maintaining income objectives. Consider companies with strong earnings growth and a sustainable dividend track record rather than chasing yield alone. The goal is to maintain steady income without compromising resilience against rate-driven volatility.

Here Are 5 Portfolio Tweaks If You Believe a Rate Hike Surprise Is Coming
Image Source: Shutterstock.com

4. Increase Exposure To Inflation Hedges

Unexpected rate hikes often coincide with inflationary pressure or expectations, and inflation can erode portfolio value if left unchecked. Allocating part of your portfolio to real assets such as commodities, real estate, or inflation-linked securities can provide a buffer. Gold, energy commodities, and Treasury Inflation-Protected Securities (TIPS) have historically helped preserve wealth during rate spikes. Diversifying in this way doesn’t eliminate risk, but it adds a layer of protection against both rising rates and rising prices. Investors who embrace inflation hedges position themselves to survive turbulence and potentially capitalize on dislocations.

5. Keep Liquidity On Standby

In periods of rate uncertainty, liquidity can become your secret weapon. Having cash or cash-equivalents ready allows you to seize opportunities when volatility spikes and markets overreact. Short-term instruments like money market funds, ultra-short-term bonds, or high-yield savings accounts can provide flexibility without locking you into poor yields. Liquidity also grants psychological freedom—knowing you can act fast reduces the temptation to panic-sell under pressure. Essentially, cash isn’t just a safe harbor; it’s a tool that lets you maneuver when the market throws an unexpected curveball.

Stay Nimble And Reflect

Adjusting your portfolio in anticipation of a surprise rate hike isn’t about predicting the future—it’s about positioning for resilience and opportunity. By shortening bond duration, tilting toward financials, reassessing dividends, embracing inflation hedges, and keeping liquidity ready, you’re creating a strategy that’s adaptable and thoughtful. Markets may surprise, but preparation softens the blow and opens doors for upside potential. Investors who reflect on their allocations regularly and remain proactive are far better equipped to navigate turbulence than those who react after the fact.

Have you ever repositioned your portfolio for a rate hike or felt the sting of an unexpected rate move? Give us all of your strategies, experiences, and lessons in the comments.

You May Also Like…

10 Shocking Facts About Index Funds Versus Actively Managed Portfolios

6 Honest Discussions About The Role of Gold in Modern Portfolios

5 Smart Strategies for Managing Your Portfolio Without Them

Beat the Hike: Take This One Step Before Your Mortgage Payment Jumps

Could Ignoring Rising Interest Rates Destroy Your Budget


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: bonds, bull market, dividend, Inflation, interest rate, interest rate hikes, interest rates, Life, Lifestyle, portfolio, portfolio analysis, portfolio management, portfolio mistakes, portfolio risk, portfolio strategy, rate hikes

Should You Make A Roth Conversion Now Or Wait For January’s Tax Environment To Settle?

December 13, 2025 by Brandon Marcus Leave a Comment

Should You Make A Roth Conversion Now Or Wait For January’s Tax Environment To Settle?
Image Source: Shutterstock.com

Timing is everything when it comes to Roth conversions, and right now, the financial world feels like a rollercoaster with the lights off. Tax rules, market fluctuations, and political chatter are swirling together in a way that can make anyone’s head spin. Should you convert your traditional IRA to a Roth now to lock in current rates, or is it wiser to wait until January when the dust settles? The answer isn’t black and white—it’s more like a carefully layered financial lasagna, with different slices depending on your goals, risk tolerance, and tax strategy.

Understanding the nuances now can save you thousands later and help you sleep better at night knowing you made an informed move.

Why Roth Conversions Can Be A Smart Move

Roth conversions are appealing because they allow your money to grow tax-free from the moment it lands in your Roth account. Unlike traditional IRAs, where withdrawals are taxed as ordinary income, Roth IRAs let you plan for a future without surprises from Uncle Sam. Converting now could make sense if you expect your tax rate to rise in the coming years, because you’ll pay taxes at today’s rates instead of potentially higher ones later. It also gives younger investors or those with smaller conversions the ability to strategically manage their tax bill over several years. Finally, a Roth conversion can be a smart estate-planning tool, allowing you to pass on tax-free growth to heirs.

The Case For Waiting Until January

On the other hand, waiting until January has its perks, especially if your current tax situation is uncertain. Lawmakers often tweak tax rules at the start of a new year, and waiting could clarify what rates or deductions you’ll actually face. Market fluctuations can also play a role; a volatile market may make it more beneficial to delay a conversion until asset values stabilize. Additionally, spreading out conversions over multiple years can prevent bumping yourself into a higher tax bracket this year. Finally, delaying allows you to gather all necessary financial information and make a thoughtful, stress-free decision rather than rushing into it.

How Market Volatility Affects Roth Conversion Decisions

The stock market is unpredictable, and that unpredictability directly impacts the timing of a Roth conversion. Converting during a market dip can be advantageous because you’re paying taxes on a lower account value, leaving more room for future growth tax-free. Conversely, if the market surges right after your conversion, you might have paid taxes on less value than the Roth ultimately grows to—but the upside is that the growth is tax-free. Regular investors may prefer to wait until there’s some clarity in the market to avoid making a big conversion during a sharp swing. Ultimately, understanding your portfolio’s risk tolerance and expected returns is critical before pulling the trigger on a conversion.

Tax Brackets And Timing: A Delicate Balance

Tax brackets are a central piece of the Roth conversion puzzle. Paying taxes at a lower rate now could save you thousands compared to waiting for potentially higher rates next year. However, converting too much in one year can push you into a higher bracket, eroding the benefits. Strategic partial conversions over multiple years allow you to stay in a lower bracket while still benefiting from Roth growth. Calculating exactly how much to convert requires careful planning and an eye on your projected income for the current and upcoming years.

Personal Circumstances Matter More Than Headlines

It’s easy to get caught up in financial news and the latest chatter about tax reforms, but personal circumstances often matter more than national headlines. Your income, retirement timeline, and other deductions all play a role in determining whether converting now or waiting makes sense. Health considerations or plans to access funds in the near future can also impact your decision. If your job situation or financial needs are changing, flexibility becomes more important than theoretical tax gains. In short, your unique financial landscape should guide your timing more than external noise.

Should You Make A Roth Conversion Now Or Wait For January’s Tax Environment To Settle?
Image Source: Shutterstock.com

Partial Conversions Can Reduce Stress

If you’re unsure whether to convert all at once, partial conversions are an elegant compromise. They allow you to take advantage of current tax rates without the shock of a massive tax bill. Partial conversions also provide a buffer against market volatility by spreading the risk over time. This approach can keep you in lower tax brackets while steadily moving funds into a Roth account. Many financial planners recommend this method as a balanced strategy, especially when future tax policies remain uncertain.

Planning For The Long Term Matters Most

Roth conversions are ultimately a long-term strategy, and thinking beyond this year’s taxes can pay dividends. Tax-free growth over decades can outweigh the immediate sting of a conversion tax bill, especially if you anticipate higher spending or tax rates in retirement. Planning with a multi-year perspective allows you to optimize not just your taxes, but your overall retirement income strategy. It also gives you room to adjust if your personal circumstances or the economy shift. A thoughtful, long-term approach turns a short-term headache into a strategic advantage for your financial future.

Make An Informed Choice That Works For You

Deciding whether to convert now or wait for January isn’t about rushing to follow the latest headlines; it’s about understanding your personal finances and the interplay of tax laws, market conditions, and retirement goals. Roth conversions can be powerful tools, but timing them correctly requires planning, patience, and an eye on both immediate and future impacts. Whether you decide to act now or wait, the key is to make an informed, strategic choice that aligns with your financial reality.

Have you wrestled with the decision to convert or wait? Share your experiences, strategies, or thoughts in the comments section below.

You May Also Like…

10 Crucial Differences Between Roth and Traditional IRA Accounts

Is a 529-to-Roth Rollover Worth It for Grandkids Under the New Rules?

11 Roth Conversion “Cliffs” in 2025 That Accidentally Hike Your Medicare IRMAA

Are You Prepared For The Tax-Law Changes Arriving Sooner Than Most Americans Expect?

Can Your Taxes Be Cut In Half By You Simply Incorporating Your Name?


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: 2026 tax law, 529-to-Roth rollover, business tax, financial changes, financial choices, financial moves, Roth, Roth 401k, Roth conversion, Roth conversions, Roth IRA, roth ira conversion, Roth IRA conversion ladder, Tax, tax brackets, taxes

  • « Previous Page
  • 1
  • …
  • 113
  • 114
  • 115
  • 116
  • 117
  • …
  • 121
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • 10 Tactics for Building an Emergency Fund from Scratch by Vanessa Bermudez
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald

Copyright © 2026 · News Pro Theme on Genesis Framework