• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Insurance

7 Financial Choices That Seem Safe Until They Aren’t

January 24, 2026 by Brandon Marcus Leave a Comment

7 Financial Choices That Seem Safe Until They Aren’t
Image source: shutterstock.com

Money mistakes aren’t always the dramatic kind that make headlines. Sometimes, they lurk in plain sight, dressed in the reassuring clothes of “safe decisions.” You think you’re doing everything right—saving diligently, investing carefully, avoiding debt—but a few seemingly innocent choices can actually sabotage your finances without you noticing.

Imagine getting a little shock years down the line because a decision you trusted turns out to have hidden pitfalls. That’s the territory we’re entering today. Let’s pull back the curtain on seven financial moves that might feel harmless or even smart, but are actually ticking time bombs for your wallet.

1. Keeping Cash Under Your Mattress Or In A Checking Account

It sounds crazy, but some people genuinely feel safer holding on to physical cash or keeping all their money in a standard checking account. The problem is, inflation is quietly eroding the purchasing power of that cash every single year. What looked like $10,000 last year might not buy nearly as much today, and that gap widens over time.

Checking accounts also usually pay near-zero interest, meaning your money isn’t working for you at all. There’s no compounding growth, no opportunity to harness investments, and your funds are essentially stagnating. Sure, it’s “safe” from the stock market’s ups and downs, but that safety is deceptive because it doesn’t protect against the invisible thief of inflation. Meanwhile, investing even a portion wisely could have you building real long-term wealth instead of just watching numbers sit still.

2. Relying Only On Employer Retirement Plans

Many people lean heavily on their 401(k) or pension plan and assume that’s enough. Employer plans are great, but they aren’t one-size-fits-all, and they often lack the flexibility needed for changing circumstances. Contribution limits, investment options, and fees can all quietly chip away at your growth potential. Some employees even overestimate how much they’ll need at retirement because they assume their employer will fully cover future inflation or healthcare costs.

If you ignore outside opportunities like IRAs, Roth accounts, or other investment vehicles, you could be leaving significant money on the table. Diversifying your retirement strategy can provide a much safer cushion against market fluctuations and unexpected life events. In short, assuming your employer’s plan is a silver bullet is a surprisingly risky choice.

3. Paying Only The Minimum On Credit Cards

The minimum payment trick seems like a stress-free solution. You only pay what’s required, your account stays current, and you avoid late fees. Sounds safe, right? The reality is far less comforting. High-interest rates compound quickly, and what seems like a manageable balance can balloon into a long-term debt trap. Years can pass, and you might still owe more than you initially borrowed, even while faithfully making those minimum payments.

This slow-motion financial drain is one of the sneakiest forms of “safe” behavior because it looks responsible on the surface. Paying a bit more than the minimum each month can save you tens of thousands in interest over time, creating freedom and peace of mind.
7 Financial Choices That Seem Safe Until They Aren’t
Image source: shutterstock.com

4. Buying “Too Safe” Investments

Certificates of deposit, government bonds, and ultra-conservative mutual funds are often praised as safe bets. While low-risk assets protect your principal, they can also fail to keep up with inflation. Your money might technically be safe, but if it doesn’t grow, your future purchasing power shrinks. Investors sometimes focus so much on avoiding risk that they miss opportunities for modest growth that outpaces inflation.

This is especially important for younger investors who have decades to recover from market dips. The key is balance: a mix of secure and growth-oriented investments can provide both safety and real progress toward financial goals.

5. Co-Signing Loans For Friends Or Family

Helping someone out financially feels noble, but co-signing a loan is one of those decisions that can backfire spectacularly. If the primary borrower misses a payment or defaults, you are legally responsible for the debt. This can impact your credit score, limit your ability to get loans, and even lead to collections actions against you. It’s tempting to trust loved ones, but emotions don’t cancel out financial responsibility.

Understanding the potential consequences fully before putting your signature on the dotted line is critical. Sometimes saying no is actually the safest and kindest choice—for both parties.

6. Ignoring Insurance Or Having The Wrong Coverage

Insurance is boring until you need it. Many people skip coverage thinking it’s an unnecessary expense, or they pick the cheapest plan and assume it’s adequate. The truth is, underinsurance or no insurance can devastate your finances in an instant. Medical emergencies, natural disasters, or liability claims can wipe out savings faster than you can react.

Comprehensive coverage might cost a little more upfront but can save you from catastrophic losses down the line. Regularly reviewing and updating your policies ensures your safety net is both current and sufficient.

7. Overestimating Passive Income Streams

The promise of passive income is seductive—earn money while you sleep, they say—but it’s rarely as simple as it sounds. Rental properties, online businesses, or dividend stocks all require ongoing attention and carry risks that aren’t immediately obvious. Market shifts, tenant vacancies, or regulatory changes can quickly erode the expected income.

People often treat passive income as guaranteed when in reality it’s more like semi-passive; it demands effort, monitoring, and sometimes unexpected financial input. Overreliance on assumed income streams can leave you exposed when reality doesn’t match expectations.

What Decisions Will You Make?

Financial decisions that seem safe can sometimes be the riskiest ones of all. Awareness, research, and a willingness to adapt are your best tools for avoiding long-term pitfalls.

What financial choices have you made that turned out differently than you expected? Or have you spotted “safe” moves that really weren’t?

You May Also Like…

10 Personal Finance Lessons People Learn the Hard Way

What Are The Worst Choices You Can Make As A New Investor?

8 Poor Choices People Make When They Make Too Much Money

How a Solid Estate Plan Can Protect Your Finances

Tired Of Being Single? Avoid These 5 Career Choices


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Finance Tagged With: cash, finance, financial choices, financial decisions, Insurance, insurance premiums, investing, investments, Money, money issues, overspending, Passive income, passive income stream, Retirement, retirement accounts, retirement planning, safe financial choices, safe investments, safe spending, spending

The One Household Appliance That Will Spike Your Insurance Premiums if Discovered During Inspection

January 18, 2026 by Brandon Marcus Leave a Comment

This Is The One Household Appliance That Will Spike Your Insurance Premiums if Discovered During Inspection
Image source: shutterstock.com

Your home is your sanctuary, but what if one seemingly innocent appliance could turn your cozy haven into a red flag for insurance companies? Most people think about home insurance in terms of fire, flood, or burglary, but there’s one specific appliance that can send premiums soaring faster than a popcorn kernel in a hot pan.

It’s not a flashy new gadget, and it doesn’t beep or flash in neon lights—but insurers treat it like a ticking time bomb. Understanding why this appliance is so problematic can save you a lot of money and, more importantly, a lot of stress.

Why Insurance Companies Fear This Appliance

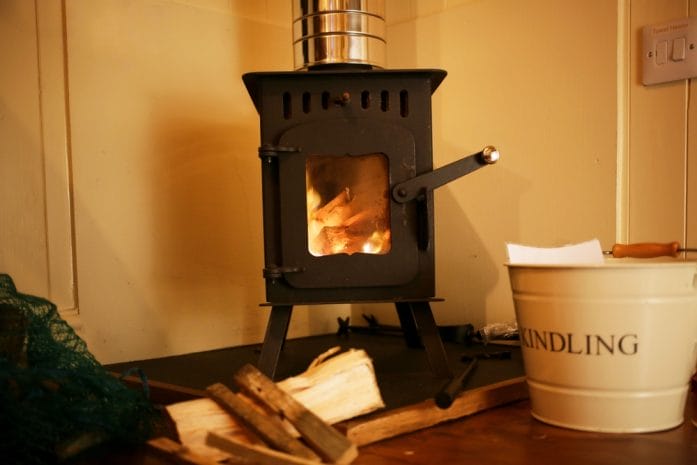
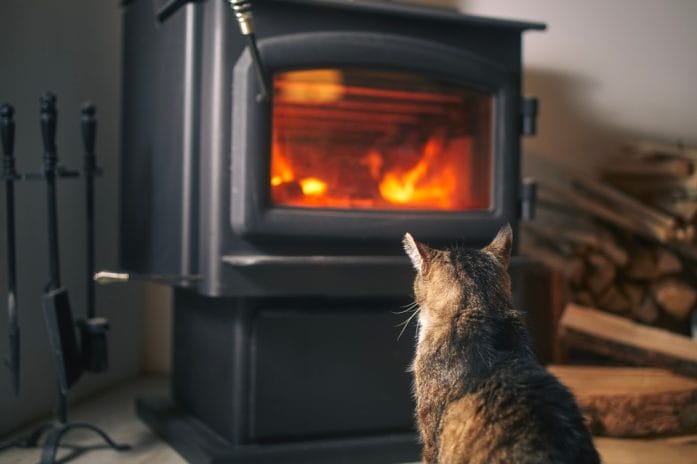
Insurance companies operate on risk assessment, plain and simple. They look at the likelihood that something in your home could cause a claim, and some appliances immediately raise red flags. The one appliance that consistently triggers higher premiums is the indoor wood-burning stove or fireplace insert. These devices, while cozy and charming, have a track record for fire hazards and smoke damage. Insurers worry because even a small ember that escapes or a buildup of creosote in a chimney can lead to catastrophic damage. In other words, a single moment of negligence or poor maintenance could turn a dream of a warm, crackling fire into a costly nightmare.

Beyond fire, these appliances can impact air quality, create unseen smoke damage in walls, and even void certain parts of a home insurance policy if installed incorrectly. Insurance adjusters are trained to spot these stoves, and if one is found during an inspection, they often consider it high-risk. That can translate to immediate premium hikes, expensive add-ons, or even outright refusal to cover your home until modifications are made.

Common Mistakes Homeowners Make With High-Risk Appliances

Many homeowners don’t realize just how many small errors can turn an indoor stove from a cozy feature into an insurance headache. One of the biggest mistakes is improper installation. Some homeowners try DIY projects, failing to comply with local building codes or manufacturer instructions. This alone can lead to denied claims if a fire occurs. Another common error is neglecting regular cleaning and chimney inspections. Creosote buildup is extremely flammable, and insurers see it as a ticking time bomb. Even using the wrong type of wood or overloading the stove can make your policy more expensive or even invalidate it.

Some people also install stoves in spaces that are too confined or lack proper ventilation. While it may look stylish, insurers know that confined stoves dramatically increase fire risk. Even accessories like hearth pads or protective barriers must meet code. Skipping these details is tempting for a homeowner who wants a seamless look, but insurers notice—and they react with higher premiums.

How To Legally Protect Your Premiums

If you absolutely love the ambiance of a wood-burning stove or fireplace, there are steps you can take to minimize insurance complications. First and foremost, hire a certified professional for installation. Insurers trust professionally installed units, and proper permits and inspections can make a huge difference. Regular maintenance is crucial, too. Have your chimney swept and inspected annually, and follow the manufacturer’s guidelines for wood and fuel usage. These steps don’t just protect your home—they protect your wallet.

It’s also smart to inform your insurer upfront if you plan to install one of these appliances. Transparency allows the company to properly adjust your coverage and may prevent future disputes if a claim arises. Some insurers offer discounts for certain safety measures, like carbon monoxide detectors, spark guards, or high-efficiency stoves that produce less creosote. By following code and implementing safety measures, you show your insurer that you’re mitigating the very risks that could otherwise spike your premium.

Alternative Options That Won’t Break Your Budget

If the potential premium increase feels too steep, there are creative alternatives that still give you warmth and ambiance without triggering insurance headaches. Electric or gas fireplace inserts mimic the visual appeal of a traditional stove but are far safer in the eyes of insurers. These options have a lower fire risk, don’t produce creosote, and often come with built-in safety features. Portable heaters and bioethanol fireplaces are other alternatives that provide warmth and style without major insurance implications.

Many homeowners overlook the fact that decorative stoves or fake fireplace setups can deliver the same cozy vibe for a fraction of the risk. While they won’t produce the same crackling fire experience, they provide atmosphere without jeopardizing your coverage. Insurance companies love it when risk is minimized, and these alternatives are often treated just like any other standard appliance.

This Is The One Household Appliance That Will Spike Your Insurance Premiums if Discovered During Inspection
Image source: shutterstock.com

The Bottom Line On Household Appliances And Insurance

The key takeaway is simple: not all appliances are created equal in the eyes of insurers. While a wood-burning stove can transform your living room into a scene from a rustic magazine, it can also transform your insurance bill into something much less cozy.

Being proactive, following code, and prioritizing maintenance can protect both your home and your wallet. For many homeowners, understanding the potential financial implications before installation is the smartest move. After all, a warm home isn’t worth much if it comes with a sky-high insurance premium or denied claims in the event of an accident.

Have you ever had to adjust your home insurance because of an appliance, or do you have tips for staying cozy without raising premiums? Tell us about your experiences and thoughts in the comments below. Learning from each other’s real-life stories is a great way to navigate the tricky intersection of home comfort and insurance.

You May Also Like…

These 6 Appliances Are Now Banned in Certain States—Do You Own One?

6 Dangerous Home Appliances That You’re Using Every Day

7 Costs That Sneak Up on Fixed-Income Households

7 Fine-Print Exclusions in Your Homeowner’s Policy That Could Cost You Everything

5 Reasons Boomers Are Staying Home Instead of Retiring Away

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: appliances, Home, home and garden, home appliances, Home insurance, homeowners, homeownership, household essentials, household expenses, household finances, household items, Insurance, insurance companies, Life, Lifestyle, stove, wood-burning stove

The Florida Premium Spike: Why Your ‘Affordable’ Health Plan Just Quadrupled in Cost Overnight

January 16, 2026 by Brandon Marcus Leave a Comment

The Florida Premium Spike: Why Your 'Affordable' Health Plan Just Quadrupled in Cost Overnight
Image source: shutterstock.com

The bill arrived like a thunderclap on a sunny afternoon. One day, your Florida health plan felt manageable, even responsible. The next, the premium looked like it belonged to a luxury sports car lease instead of a routine monthly expense. Phones lit up, inboxes flooded, and dinner conversations turned into financial post-mortems.

This wasn’t a slow creep or an annual nudge upward; it felt instant, dramatic, and deeply personal. Welcome to Florida’s premium spike, where “affordable” suddenly became a loaded word.

How Florida Became Ground Zero For Premium Shock

Florida has long been a unique beast in the health insurance world, and not always in a good way. The state relies heavily on the Affordable Care Act marketplace, yet it also has one of the highest percentages of residents paying full price for coverage. Insurers in Florida face a population that skews older, has higher rates of chronic illness, and uses more health services than many other states.

That combination alone pushes premiums upward before any policy changes even enter the conversation. When insurers recalculate risk each year, Florida often lands on the expensive end of the spectrum. The result is a market where even small shifts can produce jaw-dropping numbers.

The Subsidy Cliff That Turns A Hill Into A Canyon

For many Floridians, the real shock comes from losing financial help rather than from insurers raising base prices alone. Premium tax credits are income-based, and even modest income changes can sharply reduce or eliminate them. A raise, a side gig that did well, or a spouse returning to work can quietly push a household over a subsidy threshold.

When that happens, the government contribution shrinks or disappears, revealing the plan’s full, unsubsidized cost. What felt like a four-figure annual plan can instantly become a five-figure one. To the consumer, it looks like the plan quadrupled overnight, even though the underlying price was always there, hiding behind subsidies.

Insurer Repricing And Plan Restructuring Shake The Table

Insurance companies don’t just tweak prices; they also redesign plans from the ground up. Networks change, deductibles move, and cost-sharing formulas get reshuffled. In Florida, several insurers have responded to rising medical costs by repricing aggressively or exiting certain counties altogether. Less competition almost always means higher premiums for the plans that remain.

Even staying with the “same” insurer doesn’t guarantee stability, because that plan may no longer exist in its previous form. When consumers are auto-enrolled into a similar but more expensive option, the increase can feel sudden and unfair, even though it followed industry rules.

Age, Location, And Health Costs Quietly Pile On

Health insurance pricing is deeply personal, even if it doesn’t feel that way. Age plays a major role, and premiums are legally allowed to increase significantly as policyholders get older. Florida’s county-by-county pricing adds another twist, since local hospital costs and provider pricing vary widely. A move across county lines can change a premium more than switching cars or cell phone plans ever could.

Add in Florida’s high use of emergency care and specialty services, and insurers factor those costs into future rates. None of this happens in isolation, and together it can turn a routine renewal into a financial shockwave.

The Florida Premium Spike: Why Your 'Affordable' Health Plan Just Quadrupled in Cost Overnight
Image source: shutterstock.com

Why This Feels So Sudden Even When It Is Not

Part of the outrage comes from timing and communication. Renewal notices often arrive close to the enrollment deadline, leaving little time to digest or compare options. Insurance language is dense, and many people understandably tune it out until the dollar amount forces attention. When multiple factors hit at once, such as subsidy changes, age increases, and plan restructuring, the math compounds quickly. The consumer experience feels like a trapdoor opening rather than a staircase you saw coming. That emotional whiplash is real, and it explains why so many Floridians feel blindsided rather than merely annoyed.

What Happens Next Is A Conversation About Florida’s Health

The Florida premium spike isn’t just about numbers on a statement; it’s about trust, transparency, and how people plan their lives around healthcare costs. Understanding the mechanics doesn’t erase the frustration, but it does restore a bit of control. Every renewal season tells a slightly different story, shaped by policy decisions, insurer behavior, and personal circumstances.

If this spike caught you off guard, you’re far from alone. The comments section below is open for your experiences, questions, and reflections on how this sudden change has affected your household.

You May Also Like…

The Florida Insurance Trap: Why “Safe” Neighborhoods Are Facing a $500 Monthly Payment Hike This Week

Why South Carolina is Beating Florida in Retirement Relocation

Legacy Insider: 4 Estate Secrets Wealthy Families Use

Retiring Early? Here Are Your Best Health Insurance Options Explained

8 Critical Questions You Must Ask Before Buying Long-Term Care Insurance

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: America, best type of insurance, Florida, health, health and safety, health and wellness, health costs, health insurance, health insurance premium, healthcare, Insurance, insurance premiums, Life, Lifestyle, United States

The Florida Insurance Trap: Why ‘Safe’ Neighborhoods Are Facing a $500 Monthly Payment Hike This Week

January 15, 2026 by Brandon Marcus Leave a Comment

The Florida Insurance Trap: Why 'Safe' Neighborhoods Are Facing a $500 Monthly Payment Hike This Week
Image Source: Shutterstock.com

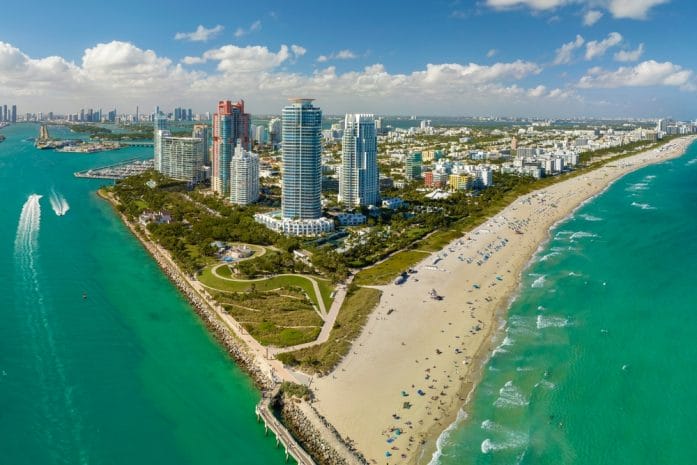
Florida has always had a reputation for sunshine, sandy beaches, and palm trees swaying in the breeze. But lately, homeowners are noticing another phenomenon sweeping the state—not storms or hurricanes, but a shocking spike in insurance costs.

If you live in a neighborhood with manicured lawns, low crime rates, and a tight-knit community vibe, you might think you’re safe from financial surprises. Think again.

This week, many residents are staring at a potential $500 monthly increase in their insurance bills, and it’s stirring anxiety, confusion, and frustration across the state.

Why Florida’s Insurance Market Is Exploding

The Florida insurance market is currently in a state of chaos. Years of mounting natural disasters, fraudulent claims, and risky investments by insurance companies have created a perfect storm.

Carriers are raising premiums aggressively, and even traditionally “safe” areas are feeling the heat. Homeowners who never worried about hurricanes or flooding are now being hit with sudden, jaw-dropping increases. Insurers argue that they need to cover growing risks, but for residents, it feels like punishment for simply living somewhere peaceful. This isn’t just about one company or one neighborhood; it’s a statewide shake-up that’s redefining what “affordable insurance” means in the Sunshine State.

Catastrophe Modeling And Risk Assessment Gone Wild

Insurance companies rely heavily on catastrophe modeling to predict losses from natural disasters. While these models sound like scientific wizardry, they’re imperfect, and in Florida, they’ve consistently underestimated the risk—or sometimes overreacted to it. Rising sea levels, stronger storms, and unpredictable weather patterns have pushed carriers to label previously “safe” areas as high-risk zones.

The result? Monthly premiums skyrocketing, sometimes by hundreds of dollars. For residents who’ve never filed a claim in their lives, this feels arbitrary, even unfair. And with competition thinning as some insurers pull out of the state entirely, homeowners have fewer choices and less negotiating power than ever before.

Fraud And Its Hidden Impact On Premiums

Florida’s insurance woes aren’t just about Mother Nature—they’re also about human nature. The state has long struggled with insurance fraud, including staged property damage and inflated claims. These scams cost insurers billions annually, and the financial fallout trickles down to regular homeowners. When a company pays out for fraudulent claims, it has to recoup those losses, and that often means raising premiums across the board. Unfortunately, this hits law-abiding citizens in safe neighborhoods the hardest. People who take care of their properties and avoid risky behavior suddenly find themselves subsidizing fraudsters, and the frustration is palpable.

Legal Battles And Regulatory Chaos

Another layer fueling these increases is Florida’s unique legal and regulatory environment. Lawsuits against insurance companies have exploded, often resulting in massive payouts. To protect themselves, insurers have been forced to hike premiums, tighten policies, or even leave the market altogether. Regulatory reforms have tried to curb these trends, but the process is slow and messy, leaving homeowners caught in the middle. Policies that once seemed affordable are now costly gambles, and navigating the insurance system feels like walking a tightrope. For anyone who thought living in a quiet, low-risk neighborhood offered peace of mind, the current reality is anything but.

The Florida Insurance Trap: Why 'Safe' Neighborhoods Are Facing a $500 Monthly Payment Hike This Week
Image Source: Shutterstock.com

The $500 Monthly Shock And How It Hits Families

The numbers are staggering. Some homeowners who once paid $250–$400 monthly for insurance are suddenly facing bills north of $900. Families budgeting carefully for mortgages, groceries, and other essentials now face a financial headache that feels impossible to manage. The emotional toll is real, with homeowners scrambling to understand their policies, appeal hikes, or even consider selling homes they’ve invested in for decades. This isn’t a small adjustment; it’s a seismic shift that can impact life decisions, retirement plans, and long-term financial stability.

What Homeowners Can Actually Do

Despite the grim headlines, there are steps residents can take. Shopping around for a different insurer, bundling policies, and improving home resilience to storms can help mitigate the impact. Some are exploring state-backed insurance options, while others are considering policy adjustments like higher deductibles. Staying informed about legislative changes, fraud trends, and catastrophe predictions is crucial.

While these actions don’t erase the pain of a $500 monthly jump, they do provide homeowners with some control in an otherwise turbulent environment. Knowledge, preparedness, and vigilance have never been more valuable for Florida residents.

Your Voice Matters On This Insurance Change Matters

Florida’s insurance crisis is reshaping neighborhoods once considered safe and predictable. The combination of natural disasters, fraud, regulatory shifts, and market instability has created a perfect storm that leaves many homeowners paying far more than expected. This week’s $500 hike is not just a number—it’s a wake-up call.

We want to hear from you. How are you managing these rising costs? Have you had experiences with sudden hikes or policy challenges? Leave your thoughts and stories in the comments section below and contribute to the conversation shaping the future of Florida homeownership.

You May Also Like…

Why South Carolina is Beating Florida in Retirement Relocation

Setting Realistic Expectations: What Will Building a Home in Florida Cost You?

6 Reasons Your Car Insurance Company Can Legally Drop You After One Claim

The “Act of God” Clause Insurance Companies Are Using to Reject Storm Damage Claims

8 Critical Questions You Must Ask Before Buying Long-Term Care Insurance

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Lifestyle Tagged With: Florida, health insurance, Insurance, insurance costs, Insurance policy, insurance trap, insurance traps, Life, life insurance, Lifestyle, neighborhoods, risk assessment

Why Are Prescription Costs Catching So Many People Off Guard

January 12, 2026 by Brandon Marcus Leave a Comment

Why Are Prescription Costs Catching So Many People Off Guard
Image Source: Shutterstock.com

The pharmacy counter used to be a quick stop between errands. Now it can feel like the dramatic climax of a movie you didn’t buy tickets for. You hand over a prescription, tap your foot, scroll your phone, and then—bam—the total flashes on the screen like a plot twist nobody warned you about. Eyes widen. Brows furrow. Wallets quietly panic.

Across kitchen tables, group chats, and waiting rooms, people are asking the same stunned question: how did everyday medications turn into budget-blowing surprises? The answer is layered, complicated, and honestly kind of wild.

The Price Tag Shock At The Pharmacy Counter

One of the biggest reasons prescription costs feel so jarring is that the final price often appears out of nowhere. Most people walk into a pharmacy assuming their insurance has everything neatly handled, only to discover that “covered” does not always mean “affordable.” Copays, deductibles, and coinsurance can stack together in ways that feel more like a puzzle than a plan. Even longtime medication users can be caught off guard when a refill suddenly costs double what it did last month. Formularies change, coverage tiers shift, and pharmacies update prices more often than most people realize.

Because these changes happen quietly, the shock hits right at the register, when there’s little time to process or plan. That moment of surprise is what makes prescription costs feel personal, immediate, and stressful.

Insurance Isn’t As Predictable As It Sounds

Insurance is often described as a safety net, but it can feel more like a trampoline with unpredictable bounce. Plans differ wildly in what they cover, how much they cover, and when coverage actually kicks in. A medication that was affordable under one employer’s plan might become painfully expensive after a job change, even if nothing else changes in your life. High-deductible plans have become more common, meaning patients may pay full price for prescriptions until they hit a spending threshold that feels very far away. Prior authorizations can delay access and sometimes push people toward more expensive alternatives. All of this creates a sense that insurance rules are written in pencil, not ink. When the ground keeps shifting, it’s no wonder people feel blindsided.

Drug Pricing Is A Maze With Too Many Turns

Behind every prescription price is a complex system that most patients never see. Drug manufacturers set list prices, but those numbers are only the beginning of the story. Pharmacy benefit managers, wholesalers, pharmacies, and insurers all play roles that influence what someone ultimately pays. Rebates and negotiations happen behind closed doors, which can lead to higher list prices even when discounts exist somewhere in the system. Generic options help, but they are not always available or dramatically cheaper. New medications often enter the market with premium pricing, especially if they treat chronic or hard-to-manage conditions.

From the outside, it looks chaotic, and from the inside, it’s even more complicated. That complexity makes it hard for patients to predict costs or understand why two people taking the same drug might pay very different amounts.

Chronic Conditions Turn Surprise Into Ongoing Stress

For people managing long-term health conditions, prescription costs are not a one-time shock. They are a recurring line item that can quietly reshape a household budget. Monthly refills mean monthly reminders that prices can rise without warning. Skipping doses or stretching medication becomes a tempting but risky strategy when costs climb. The emotional toll adds another layer, as people weigh their health against financial pressure. Parents managing medications for children or caregivers supporting aging relatives feel this stress even more intensely.

Over time, the surprise turns into vigilance, with patients bracing themselves every time they approach the counter. That constant uncertainty is exhausting, and it explains why prescription pricing has become such a hot-button issue.

Why Are Prescription Costs Catching So Many People Off Guard
Image Source: Shutterstock.com

Why It Feels Worse Now Than It Used To

Prescription costs have existed for decades, so why does it feel more shocking now? Part of the answer lies in visibility. People talk more openly about money and healthcare experiences than they did years ago, so stories travel fast. Social media amplifies individual moments of sticker shock into shared outrage. At the same time, wages have not always kept pace with healthcare expenses, making price jumps harder to absorb.

More medications are used to manage conditions over longer lifespans, increasing total spending even when individual prices hold steady. Add in economic uncertainty, and every unexpected expense feels heavier. The surprise isn’t just about the number on the receipt; it’s about timing, context, and the feeling that control has slipped away.

Let’s Talk About The Real Cost Of Staying Healthy

Prescription costs catch people off guard because they combine surprise, complexity, and deeply personal stakes. They show up at moments when people are focused on feeling better, not decoding billing systems. Understanding why these costs feel so unpredictable is the first step toward navigating them with more confidence. Conversations matter, especially when they bring hidden frustrations into the open.

If you’ve had a moment at the pharmacy counter that left you stunned, or if you’ve found creative ways to manage medication expenses, add your thoughts or stories in the comments section below.

You May Also Like…

7 Clever Ways Grandparents Save on Family Vacations

Expense Spike: 8 Healthcare Costs That Hit Harder in Later Life

The Prescription Scandal No One Wants to Talk About

Navigating the Sandwich Generation: Caring for Kids, Aging Parents & Yourself

8 Tips for Talking With Your Partner About Health, Finances & Legacy


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Health & Wellness Tagged With: chronic conditions, drug pricing, drugs, generic drugs, health, health and wellness, health insurance, healthcare, healthcare costs, Insurance, medical expenses, medicine, over-the-counter drugs, prescription, prescription drugs, prescriptions, Smart Spending, spending

Why Do Medical Bills Feel So Hard to Plan Around

January 9, 2026 by Brandon Marcus Leave a Comment

Why Do Medical Bills Feel So Hard to Plan Around
Image Source: Shutterstock.com

Walking into a doctor’s office or hospital can feel like stepping into a parallel universe. One minute, you’re there for a routine checkup, the next, you’re navigating a maze of forms, codes, and numbers that seem to have been designed to make your head spin.

Even if you have insurance, medical bills can appear out of nowhere, like pop quizzes in a class you didn’t know you were taking. One procedure can lead to five separate charges, each with its own due date, explanation of benefits, and a cryptic description that leaves you wondering if you actually got what you paid for.

The unpredictability of medical costs makes budgeting feel almost impossible, and the emotional toll of seeing a bill that’s hundreds or thousands of dollars more than expected can be staggering. But why does this happen? Why do medical bills feel like a riddle wrapped in a financial nightmare? Let’s break it down.

The Mystery Of Medical Coding

Medical billing begins with something called coding, and it’s here that the confusion often starts. Every procedure, test, and diagnosis is assigned a specific code, which insurance companies use to determine how much they will pay. These codes can be maddeningly complex, with different codes for slight variations of the same procedure. If the wrong code is used—or if your insurance provider interprets it differently—you might get billed incorrectly, and suddenly a simple blood test costs triple.

These codes are constantly updated, so even seasoned medical billing professionals can get tripped up. This complexity creates a domino effect: one small error can ripple across multiple bills, leaving patients frustrated and financially stressed. Understanding medical coding is a deep dive most people aren’t prepared for, and that’s just the tip of the iceberg.

Hidden Costs And Extra Fees Everywhere

Even after coding, there’s a tangle of hidden costs that makes bills unpredictable. Hospitals often charge separate fees for the building, the equipment, the staff, and even the supplies used during your visit. Need an X-ray? You might get billed separately for the technician’s time, the image, and the radiologist’s review. And don’t forget facility fees, lab fees, and sometimes, “administrative processing” fees that feel like they were pulled out of thin air.

These extra costs can add up quickly, especially for someone dealing with chronic conditions or unexpected emergencies. Because these fees aren’t always transparent upfront, planning your budget around them is like trying to hit a moving target in the dark. People often find themselves scrambling to pay bills they didn’t even know existed.

Insurance Plans That Act Like Mazes

If you think insurance will make things easier, think again. Insurance plans come with deductibles, copays, coinsurance, and out-of-pocket maximums, all of which affect what you actually owe. Some services are covered partially, some not at all, and some only if certain conditions are met. The same hospital visit could cost one patient a few hundred dollars and another thousands, depending on plan details. Navigating insurance paperwork is like learning a foreign language, complete with exceptions, fine print, and multiple layers of approval.

Even with online tools and explanations, people often end up guessing how much a procedure will actually cost them. This uncertainty makes it almost impossible to plan ahead financially because you never know which portion you’ll be responsible for until the bill arrives.

Unexpected Emergencies Throw Plans Out The Window

Life doesn’t stop for budgeting, and neither do emergencies. A broken bone, sudden illness, or car accident can instantly derail any financial plan you’ve carefully crafted. Even with emergency savings, medical costs can easily exceed what you’ve set aside. Because hospitals often bill for each element separately, the total can balloon unexpectedly. This unpredictability can create stress and anxiety, making it hard to feel in control of your finances. Emergency situations strip away your ability to shop around or negotiate prices, leaving patients vulnerable to whatever costs arise. It’s not just the financial burden; it’s the emotional rollercoaster of trying to process both your health and your finances simultaneously.

The Lag Between Service And Billing

One of the most frustrating aspects of medical bills is the timing. Unlike a grocery store purchase where you know instantly what you owe, medical billing can take months. You might have a procedure in January and not see the first statement until April, with final costs not determined until June. By then, it’s easy to forget what services you actually received or why certain charges are there. This lag makes budgeting difficult because bills arrive after the fact, often in chunks rather than as one final amount. Patients sometimes receive multiple statements for the same procedure, each with slightly different numbers. This delay not only causes confusion but can also increase stress when trying to reconcile what you expected to pay with what you actually owe.

Psychological Weight Of The Unknown

The unpredictability of medical bills carries a psychological toll as heavy as the financial one. Uncertainty triggers anxiety and stress, which can affect both physical and mental health. When you don’t know how much a visit will cost or when the bill will arrive, it’s hard to make other financial decisions. People put off important medical care, skip necessary medications, or make choices based on fear of cost rather than health needs. The mental load of constantly anticipating unexpected bills can feel overwhelming, making planning your life around them nearly impossible. Understanding the emotional impact of this uncertainty is crucial, because it’s not just money at stake—it’s peace of mind.

Why Do Medical Bills Feel So Hard to Plan Around
Image Source: Shutterstock.com

Your Turn To Reflect

Medical bills can feel like an unpredictable storm, but understanding why they are so hard to plan around can help take some of the mystery out of the experience. From complex coding and hidden fees to confusing insurance plans, unexpected emergencies, delayed statements, and the psychological weight of financial uncertainty, there are many layers contributing to the challenge. While we may not be able to make them disappear, we can at least approach them with more awareness and practical strategies.

Have you ever faced a medical bill that completely threw your budget off? What was your experience like navigating the maze? Drop your thoughts or experiences in the comments section below—we’d love to hear how you’ve tackled this universal headache.

You May Also Like…

The Medical Bill Mistake That Can Cripple Your Credit for a Decade

7 Clever Ways Grandparents Save on Family Vacations

6 Aggressive (But Legal) Tactics Hospitals Use to Collect on Medical Debt

7 Outrageous Truths About Medical Debt

How Can Medical Bills Wipe Out Savings Faster Than a Market Crash

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Health & Wellness Tagged With: billing, doctors, emergency medical care, emergency rooms, health insurance, healthcare, healthcare issues, Insurance, insurance plans, medical billing, medical bills, medical bills after death, medical checkups, medical coding, medical costs, medical debt, medical expenses, medicine

7 Costs That Sneak Up on Fixed-Income Households

January 8, 2026 by Brandon Marcus Leave a Comment

Here Are 7 Costs That Sneak Up on Fixed-Income Households
Image Source: Shutterstock.com

A steady paycheck may stop, but life never takes a coffee break. For millions of households living on pensions, Social Security, annuities, or other fixed incomes, the budget can feel like a carefully stacked tower of blocks—stable, precise, and always one unexpected nudge away from wobbling. Expenses don’t announce themselves with confetti cannons. They arrive quietly, disguised as small increases, new fees, or “just this once” purchases that somehow keep happening.

Today, we are going to shine a bright light on seven costs that tend to creep into the picture, drain energy from monthly budgets, and leave people wondering where their money went. Knowing what to watch for can turn surprise into strategy and stress into confidence.

1. Rising Utility Bills And Seasonal Spikes

Utility costs are famous for refusing to sit still. Electricity, natural gas, water, and trash service often inch upward year after year, even when usage stays the same. Seasonal changes make things trickier, as heat waves and cold snaps push bills into uncomfortable territory. Many fixed-income households feel pressure to keep homes at safe temperatures, especially for health reasons, which limits flexibility.

Rate adjustments approved by local regulators can land without much warning. Even small monthly increases add up over time, quietly eating into grocery or medication budgets. Over a year, utilities alone can turn into one of the most underestimated expenses around.

2. Healthcare Costs Beyond Insurance

Insurance provides a safety net, but it rarely catches everything. Copays, deductibles, uncovered services, and prescription tiers can surprise even the most organized planner. Routine appointments can multiply when new health concerns pop up or chronic conditions need closer monitoring. Dental care, vision exams, hearing aids, and mobility equipment often live outside standard coverage. Transportation to medical appointments adds another layer, especially when specialized care isn’t nearby. For fixed-income households, these ongoing out-of-pocket expenses can feel relentless and hard to predict.

3. Home Maintenance And Repair Surprises

Homes age just like people, and they occasionally demand attention at inconvenient times. A leaky roof, failing water heater, or aging HVAC system can turn into a major expense overnight. Even smaller repairs, like plumbing fixes or appliance replacements, carry price tags that sting. Labor and materials costs have risen, making do-it-yourself less practical for many homeowners. Renters aren’t immune either, as landlords often pass along maintenance-related increases through higher rent. Home-related expenses tend to arrive without warning and rarely wait for the budget to catch up.

4. Food Prices And Subtle Shrinkflation

Grocery shopping used to be predictable, but those days are long gone. Prices rise, packages shrink, and favorite staples quietly cost more for less. Fixed-income households often notice that the same cart of groceries somehow totals more each month. Fresh produce, meat, and pantry basics fluctuate based on supply chains and seasonal factors. Eating healthier can feel especially expensive, even though it saves on healthcare later. Over time, food inflation becomes one of the most emotionally frustrating costs because it touches daily life so directly.

Here Are 7 Costs That Sneak Up on Fixed-Income Households
Image Source: Shutterstock.com

5. Transportation And Mobility Expenses

Transportation costs don’t stop just because commuting does. Gas prices swing wildly, and routine vehicle maintenance keeps marching on. Insurance premiums can rise even without accidents or claims. Public transportation fares increase, and ride services add fees that weren’t there before. For those with limited mobility, specialized transportation services may be necessary and costly. Staying independent often means paying more than expected just to get where life happens.

6. Technology And Communication Costs

Modern life runs on technology, and opting out isn’t always realistic. Internet access, mobile phones, and streaming services have become everyday necessities for staying connected and informed. Service providers frequently adjust pricing, introduce new fees, or phase out older plans. Devices eventually need replacing, whether it’s a phone battery that won’t hold a charge or a laptop that can’t handle updates. Even basic tech support can come with a cost. These expenses tend to feel small individually but add up quickly over a year.

7. Gifts, Events, And Social Obligations

Life doesn’t pause its celebrations for anyone’s budget. Birthdays, weddings, graduations, and holidays bring joy—and expenses. Fixed-income households often feel pressure to participate fully, even when funds are tight. Travel, lodging, attire, and gifts can pile up around certain seasons. Charitable giving, community events, and family support requests also play a role. These costs are deeply emotional, making them some of the hardest to manage or limit.

Staying Ahead Of The Quiet Drains

Fixed incomes demand creativity, awareness, and a little humor when the unexpected pops up. Recognizing these common costs makes it easier to plan, adjust, and breathe easier month to month. No two households experience them the same way, and strategies vary widely depending on lifestyle and priorities. Awareness turns surprise expenses into manageable challenges rather than budget-breaking shocks.

If you’ve encountered any of these costs—or found clever ways to handle them—add your thoughts or stories in the comments below. Your experience could help someone else feel a little more prepared.

You May Also Like…

Expense Spike: 8 Healthcare Costs That Hit Harder in Later Life

Debt Alert: 6 Ways Holiday Spending Could Trigger a January Credit Score Crisis

6 Silent Money Leaks in the Average Household

Why Do Some Households Keep Paying for Empty Storage Units

12 Ways to Beat Back the Guilt of Spending on Yourself Finally


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: Budget, budgeting, costs, daily spending, expenses, health insurance, healthcare, household budget, household items, household responsibilities, household spending, Insurance, Life, Lifestyle, seasonal spending, spending, unexpected costs, utility bills

7 Monthly Bills That Keep Rising Even When You Use Less

January 7, 2026 by Brandon Marcus Leave a Comment

7 Monthly Bills That Keep Rising Even When You Use Less
Image Source: Shutterstock.com

Ever feel like you’re playing a game where the rules keep changing, and no matter how careful you are, your bills just keep climbing? You’re not imagining it. Some monthly expenses have a mysterious talent for growing even when you turn off lights, skip streaming shows, or cut back on usage. It’s like they have their own secret life—quietly inching up, keeping your wallet on edge.

Understanding why these bills rise, even when we think we’re conserving, is a little like unlocking a puzzle. Here’s the inside scoop on the seven bills that love to defy logic.

1. Electricity Bills That Don’t Obey Your Switches

You could practically live by candlelight, yet that electricity bill might still spike. Why? Utilities often raise rates due to infrastructure upgrades, regional demand, or seasonal pricing changes. Even small fees, like connection charges or environmental surcharges, can add up over a year. Plus, smart meters track usage differently than old meters, sometimes creating surprises on your bill. Energy efficiency helps, but it can’t always fight the creeping power of rising rates.

2. Water Bills With Their Own Agenda

Cutting your showers from 10 minutes to 5 might feel heroic, but water bills have their own agenda. Many municipalities charge more per gallon as consumption tiers increase—or even just to cover maintenance and repair costs. Water treatment and pipeline upgrades aren’t cheap, and those costs often appear on your bill regardless of your usage. Seasonal droughts or local policy changes can also send rates upward unexpectedly. It’s a tricky balance: conserving water is vital, but it doesn’t guarantee a smaller bill.

3. Internet Bills That Grow Like Wild Vines

You might have slashed streaming hours or turned off devices, but internet bills often march upward independently. ISPs regularly increase base rates due to infrastructure investment, competition, or inflation. Add in equipment rental fees for modems or routers, and the total climbs even if your data consumption drops. Promotions expire, bundles change, and suddenly your “cheaper” plan isn’t so cheap anymore. Internet is the lifeline of modern life, but apparently, it’s also a stealthy wallet drainer.

4. Streaming And Cable Subscriptions That Inflate Silently

Think cutting the movie nights will trim this bill? Not always. Platforms raise prices, add premium channels, or introduce new features that automatically inflate monthly costs. Even if you pause or cancel one subscription, another might replace it with an intro rate that soon escalates. Advertisers and content deals can also drive increases, especially for popular bundles. Streaming is irresistible, but your wallet may need a subscription strategy just to keep up.

5. Phone Bills That Climb Without Extra Calls

Text less, talk less, use Wi-Fi for everything—yet your phone bill might still creep up. Carriers frequently adjust plans, add hidden fees, or roll out new taxes that appear mysteriously. Upgrades to networks like 5G, plus government-imposed fees for emergency services, can inflate the cost even when your usage is minimal. International or even regional charges can sneak in without warning. Mobile service is essential, but it’s also a fine-tuned machine designed to nibble at your budget.

7 Monthly Bills That Keep Rising Even When You Use Less
Image Source: Shutterstock.com

6. Health Insurance Premiums With Their Own Logic

Cutting out appointments or skipping extra services doesn’t necessarily lower your monthly health insurance premium. Insurers raise rates based on the overall cost of care, inflation in medical services, and policy updates mandated by law. Even when individuals use fewer services, administrative costs, hospital expenses, and prescription drug price hikes affect everyone. Some plans automatically increase with age or health risk assessments. Health coverage is vital, but it doesn’t always reward frugal behavior immediately.

7. Property Taxes That Keep Climbing

You might live in a modest home and keep it immaculate, yet property taxes often rise regardless. Local governments reassess property values, infrastructure costs, and public service needs, which can push taxes upward. Even if your personal property or home improvements stay the same, neighborhood growth and municipal budgets play a huge role. Tax rates can also change independently of usage or ownership. Owning property is rewarding, but taxes are the ultimate “unchallenged” monthly bill.

When Bills Don’t Follow Logic

Watching bills climb despite careful usage can feel frustrating, but understanding why they rise gives you power over your finances. These seven expenses—from utilities to insurance—each have unique reasons for growth that don’t always align with personal habits.

Have you noticed your own bills creeping up despite doing everything right? Tell us your experiences and observations in the comments. Your story might just help someone else decode their own mysterious monthly expenses.

You May Also Like…

Expense Overflow: 4 Retirement Bills That Catch People Off Guard

Tax Surge: 4 Income Types That Trigger Hidden Tax Bills

Here’s When It’s Okay To Let Kids Move Back Home To Pay Off Bills

Why You Should Never, Ever Skip Paying Your Bills

8 Shocking Costs of Ignoring Small Medical Bills


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: bills, health insurance, household responsibilities, Insurance, internet bills, Life, Lifestyle, monthly bills, phone bills, Smart Spending, spending, streaming apps, streaming services, streaming subscriptions, utility bills

Legacy Insider: 4 Estate Secrets Wealthy Families Use

January 3, 2026 by Brandon Marcus Leave a Comment

Legacy Insider: 4 Estate Secrets Wealthy Families Use
Image Source: Shutterstock.com

High society isn’t just about yachts, penthouses, and private jets—it’s about playing a long game that most people don’t even see coming. Behind the velvet curtains and polished smiles, wealthy families operate with strategies that would make ordinary mortals’ heads spin. While the rest of us are busy worrying about bills and budgeting, these families are quietly crafting multi-generational empires that survive crises, taxes, and even family feuds. It’s not luck. It’s precision, planning, and a little-known playbook they guard like a national treasure.

Today, we’re pulling back the curtain to reveal four estate secrets that the rich rely on to keep their legacies intact—and you’re about to get insider access.

1. Leveraging Trusts To Shield Wealth

Trusts aren’t just legal mumbo-jumbo. Instead, they’re the Swiss Army knife of the ultra-wealthy. Families use trusts to control assets while minimizing taxes, avoiding probate, and protecting wealth from lawsuits. For example, a “dynasty trust” can stretch across multiple generations, ensuring grandchildren and great-grandchildren benefit without the estate ever being taxed heavily. It’s not just about hiding money—it’s about strategic control, giving the family the ability to dictate when and how heirs access funds. Savvy families even use irrevocable trusts to separate ownership and benefits, meaning the assets aren’t technically theirs anymore but still work for them.

2. Gifting Strategically To Multiply Benefits

The wealthy don’t just hand money to their heirs. They orchestrate transfers with a master plan. Annual gifting allowances let families legally move large sums out of taxable estates without raising red flags with the IRS. Beyond that, advanced strategies like “grantor retained annuity trusts” allow them to gift appreciating assets while retaining income streams, which sounds complex because it is—but it works brilliantly. By gifting strategically, they reduce estate taxes while still keeping control and even enjoying financial benefits themselves. Essentially, it’s a game of chess: each move reduces tax exposure while maximizing generational wealth.

3. Using Family Offices To Centralize Control

While most people rely on a single financial advisor, the wealthiest families build entire family offices. These are private companies that manage everything from investments and real estate to philanthropic projects and legal affairs. A family office ensures that all money decisions align with long-term goals, and it allows heirs to focus on legacy rather than day-to-day finances. Some offices employ dozens of professionals—CPAs, lawyers, investment managers—so every asset, down to the smallest collectible, is accounted for and optimized. This isn’t just management; it’s a fortress of wealth strategy, making sure the family fortune thrives no matter what external storms hit.

4. Leveraging Life Insurance As A Tax Tool

Life insurance is often seen as simple protection. But wealthy families treat it like a secret weapon. Certain types of policies can be used to transfer wealth tax-free. This creates liquidity for heirs to pay estate taxes without liquidating assets. It can also fund trusts, supplement charitable giving, or even act as an investment vehicle, depending on the policy type.

The combination of estate planning and life insurance creates a buffer that ensures no fortune gets eaten away by taxes unexpectedly. For families with complex holdings like businesses or art collections, life insurance can be the difference between keeping the legacy intact or being forced to sell key pieces.

Your Thoughts On Legacy Planning

Estate planning isn’t just for billionaires. Understanding these strategies can give anyone a leg up on securing their family’s future. Trusts, gifting strategies, family offices, and life insurance aren’t just tools—they’re part of a mindset that treats wealth as something to nurture, protect, and grow across generations. Whether you’re actively building wealth or just curious about how the other half operates, these secrets provide insight into a world few ever see. Now that you’ve had a peek behind the velvet rope, we’d love to hear your thoughts or experiences with estate planning in the comments section below.

How do you approach protecting your future, and which of these strategies sparks your curiosity the most?

You May Also Like…

How a Solid Estate Plan Can Protect Your Finances

Am I the Only One Who Thinks Estate Planning Is Deeply Terrifying?

Is Estate Planning The Only Way To Preserve Your Legacy?

Review Your Estate Planning Documents and Update Beneficiaries Promptly

7 Things That Must Be in Your Will to Prevent Vicious Family Fights


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Estate Planning Tagged With: Estate plan, Estate planning, family legacy, family trusts, family wealth, Insurance, legacy, life insurance, taxes, trusts, Wealth, wealthy families

9 Monthly Expenses That Will Cost More Starting in January

December 16, 2025 by Brandon Marcus Leave a Comment

Some Monthly Expenses Will Cost More Starting in January
Image Source: Shutterstock.com

January has a funny way of arriving with confetti in one hand and a bill in the other. While everyone else is talking about fresh starts and bold resolutions, your monthly budget is quietly bracing for impact. New calendars don’t just bring new goals; they often come with higher prices baked into everyday essentials.

Some increases are obvious, others sneak in quietly, but together they can turn a manageable budget into a monthly headache. Before your wallet gets blindsided, let’s break down the monthly expenses that are likely to demand more of your money starting in January.

1. Rent And Housing Costs

January is a popular time for landlords and property managers to roll out rent increases, especially for renewed leases. Higher property taxes, maintenance costs, and insurance premiums are often passed directly to tenants. Even homeowners aren’t immune, as HOA fees and condo association dues frequently rise at the start of the year. Housing markets may cool or heat up depending on location, but monthly housing costs have a habit of only moving in one direction. Whether you rent or own, shelter usually becomes a little more expensive once the calendar flips.

2. Health Insurance Premiums

Health insurance changes often kick in right after the New Year, making January an expensive wake-up call. Premiums commonly increase due to rising healthcare costs, new coverage requirements, or plan adjustments. Even if your premium stays the same, deductibles and out-of-pocket maximums often reset, which can feel like a price hike all on its own. Employer-sponsored plans and individual policies alike tend to update pricing annually. The result is that healthcare almost always demands more money at the beginning of the year.

3. Car Insurance Payments

Auto insurance providers love January for rolling out rate adjustments. Changes in accident data, repair costs, and inflation all influence how much drivers pay each month. Even a clean driving record doesn’t guarantee protection from a higher bill. New fees or revised coverage standards can quietly increase your premium without much warning. When the New Year starts, many drivers notice their car insurance costs creeping upward.

4. Utilities And Energy Bills

Winter weather alone can push utility bills higher, but January pricing adjustments add another layer. Energy providers often update rates annually to reflect infrastructure upgrades and fuel costs. Heating, electricity, and natural gas bills can spike even if usage stays relatively steady. Water and trash services may also introduce higher monthly fees at the start of the year. By mid-January, many households are already paying more just to keep the lights on and the house warm.

Some Monthly Expenses Will Cost More Starting in January
Image Source: Shutterstock.com

5. Streaming And Subscription Services

Streaming services have become masters of the quiet January price increase. New content investments and licensing fees often lead to higher monthly subscription costs. Some services raise prices directly, while others eliminate lower-priced tiers or add fees for features that used to be free. Fitness apps, music platforms, and digital tools frequently follow the same pattern. By the end of January, those small monthly subscriptions can add up to a noticeably bigger total.

6. Internet And Mobile Phone Plans

Telecom companies frequently adjust pricing at the start of the year. Promotional rates may expire, pushing customers onto higher standard pricing. Added fees, regulatory charges, or equipment rental costs can sneak into your monthly bill. Even modest increases feel painful when they hit essential services you rely on every day. January is often when your internet and phone bills quietly become more expensive.

7. Childcare And Education Costs

Many childcare providers and educational programs revise tuition and fees annually in January. Higher staffing costs, insurance, and supplies often drive these increases. Even after-school programs and tutoring services may raise monthly rates. Parents can feel these changes immediately, especially if multiple children are involved. The New Year frequently brings a higher price tag for learning and care.

8. Grocery And Household Essentials

Grocery prices don’t reset magically with a new calendar, but January often reflects updated supplier contracts and transportation costs. Staples like bread, dairy, and cleaning supplies may cost more than they did just weeks earlier.

On top of that, manufacturers sometimes introduce smaller packages at the same price, which effectively raises your monthly spending. Seasonal promotions disappear after the holidays, removing temporary discounts. Over a month, these subtle changes can stretch your grocery budget thin.

9. Memberships And Professional Fees

Gym memberships, professional organizations, and club dues commonly increase at the start of the year. January is peak season for fitness centers, making it an ideal time for price adjustments. Professional licensing fees and monthly service retainers may also update annually.

Even if the increase is small, it becomes a permanent part of your monthly expenses. By February, many people realize their memberships are costing more than they planned.

New Year, New Budget Reality

January may symbolize fresh starts, but it also brings financial realities that are hard to ignore. From housing and insurance to groceries and subscriptions, higher monthly expenses can pile up faster than expected. Knowing where these increases are likely to appear gives you a chance to prepare instead of panic. A proactive look at your budget can help you adjust, negotiate, or cut back where possible.

Let us know your thoughts or personal experiences with rising monthly costs in the comments section below.

You May Also Like…

Debt Alert: 6 Ways Holiday Spending Could Trigger a January Credit Score Crisis

Could Your Advisor Be Overlooking The Biggest Risk Hiding In Your Portfolio This Winter?

These 8 Wedding Expenses Look Harmless – Until You See the Final Bill

6 Expenses That Quietly Multiply After Buying a Home

10 Expenses That Quietly Rise When You Move Abroad


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Spending Habits Tagged With: car insurance, childcare, energy bills, groceries, health insurance, Holidays, household essentials, housing, Housing Costs, Insurance, Internet, January, monthly essentials, monthly expenses, Rent, spending, spending habit, Spending Habits, streaming apps, utilities, winter

  • « Previous Page
  • 1
  • 2
  • 3
  • 4
  • …
  • 11
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • 10 Tactics for Building an Emergency Fund from Scratch by Vanessa Bermudez
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald

Copyright © 2026 · News Pro Theme on Genesis Framework