• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Debt

The Best, Low Maintenance Way to Invest 30K

December 2, 2020 by Jacob Sensiba Leave a Comment

If you’ve been building your savings to start investing and you’ve managed to put aside $30K, you may be wondering what your next step should be. How do I invest 30k? What is the best, low maintenance approach?

Here are some great ways to apply that 30K towards growing your wealth.

Pay Off Debt

First and foremost, use some of the money to pay off any debt you may have. It will save you money in the long-run. If you’re carrying a $10K credit card balance with a 15% interest fee, you’ll be paying an extra $1500/year in interest. That’s money that can be better spent on investments down the road. If you want to invest 30k, first start by getting rid of debt.

Emergency Fund

If you don’t already have one, put some of your money aside in an emergency fund so you know you’ll be able to manage if something unexpected happens. You should have 3-6 months’ worth of expenses put aside in an easily accessible account like a savings account. Just make sure it’s not linked to your debit card so you can’t spend it. The period of time you need to cover varies based on how long you think it would take you to find another job should something happen to your current job.

Earning return

What’s next has all to do with three things: risk tolerance, time horizon, and investment objectives. As a matter of fact, that’s how all of your investment decisions are made.

There are several different vehicles you can utilize, so what I’m going to do is give each vehicle its own section, explain what it is, and then give a little more detail as to when it could be used.

Certificate of Deposit (CD)

A bank product with a specified interest rate and a specified maturity. CDs are used to hold money for a specified period of time in a virtually risk-free fashion. More about CDs.

You’ll choose a CD for two reasons. The first is if you want a safe, federally insured vehicle to stash away some cash. The other reason is if you do not want to touch that money for a specified period. For example, you’re going to buy a house in three years and you don’t want to jeopardize that down payment. You buy/invest in a 3 year CD. At the end of year three, you’ll get back your principal (what you put in) and some accrued interest. Early withdrawal penalties apply.

Savings/Money Market Accounts

Typically used for your emergency fund. Easily accessible, and able to earn a little interest.

That’s pretty much it when it comes to these accounts. The interest they offer will be (not always) pretty low, but, like the CD, it offers a very safe place to store your cash until you need it. Unlike the CD, however, there are no early withdrawal penalties.

Qualified accounts

Basically any retirement account. Traditional IRA, Roth IRA, and employer-sponsored plans (401k, Simple IRA, etc.). There are contribution limits associated with these accounts.

With these accounts, as I said, contribution limits are something to pay attention to. With your Traditional and Roth IRA, there’s a $6,000 contribution limit ($7,000 if you’re 50 and older). 401ks have a limit of $19,500 (25,500 for 50 and older). Simple IRA limit is $13,500 ($16,500 for 50 and older).

This is a long term investment solution, as early withdrawal penalties apply. There are several ways to “exempt” yourself from that penalty, however, such as a first home purchase. For an extensive list of these exemptions, click here.

These accounts are also called “tax-advantaged” accounts because, as the name suggests, there are tax advantages. You either lower your taxable income with your contributions or have the ability to withdraw the funds “tax-free” (barring an early withdrawal penalty, of course).

Non-Qualified Accounts

Brokerage accounts or any investment vehicle that doesn’t have any tax benefits. Meaning, you pay taxes on any capital gains and dividends you receive. No contribution limits.

Honestly, the only advantage to these accounts is there is no contribution limit. For example, if you’ve maxed your contribution for your employer-sponsored plan and your IRA, then you can dump the rest of your money here.

Health Savings Account (HSA)

Accounts specifically designed to help you with your medical expenses. Money that you contribute to this account is “tax-free” or “tax-deductible”, which means it lowers your taxable income. Also, the funds, if used for qualified medical expenses, are tax-free.

With some, not all HSAs, you can invest what you’ve contributed. So if you have 30k to invest, I’ll point you to the below section to help with that. There are contribution limits with the HSA, however, so keep that in mind.

Asset allocation

After you’ve selected an investment vehicle (this section does not apply to CDs, savings accounts, or money market accounts), it’s time to invest your capital.

Asset allocation is my preferred method to invest, and I’ve written extensively on it here. So if you want to invest 30k, here’s what you need to ask yourself. How long until I need these funds? What is my ultimate goal for these funds? What am I willing to lose?

If your time period is less than 5 years, ignore this section and stick your money in a savings account or a CD. The risk/reward is unfavorable in this scenario.

If you have, ideally, 10+ years, then you have some options. The next question is about risk tolerance. What kind of portfolio are you comfortable with? Using the stocks/bonds/cash breakdown, are you a 60/40/0 type of person? Maybe you’re quite tolerant and prefer an 80/20/0 approach.

For those of you that are not tolerant of risk and/or you have a shorter number of years until you need to access these funds. Your portfolio should start at 50/50/0, and then adjust as you see fit. The cash portion in this breakdown should be used as investable cash for when you see a buying opportunity and/or funds you’ll need access to in the near future (unriskable capital).

Risk Tolerance

If you really want to know what your unique risk tolerance is, take our quiz!

I know I didn’t really give a concrete answer to what’s posed in the headline, but that’s the thing about investing – it’s incredibly personal. You need to do what’s best for you.

If time is on your side, max your retirement contribution, then put the rest in a savings account until next year. At that time, max it again.

If time isn’t your friend, a CD isn’t a bad idea. As I said earlier, paying down/off debt is incredibly worth it. That’s an automatic 15% return on your money if you pay off your credit card. Money that can be used more effectively going forward.

Read our articles, ask for advice, and do what’s best for you. That’ll help you answer the question: how do you invest 30k?


**Securities offered through Securities America, Inc., Member FINRA/SIPC. Advisory services offered through Securities America Advisors, Inc. Securities America and its representatives do not provide tax or legal advice; therefore, it is important to coordinate with your tax or legal advisor regarding your specific situation. Please see website for full disclosures: www.crgfinancialservices.com

Jacob Sensiba
Jacob Sensiba

Jacob Sensible is a financial advisor with decades of experience in the financial planning industry.  His journey into finance began out of necessity, stepping up to support his grandfather during a health crisis. This period not only grounded him in the essentials of stock analysis, investment strategies, and the critical roles of insurance and trusts in asset preservation but also instilled a comprehensive understanding of financial markets and wealth management.  Jacob can be reached at: jake.sensiba@mygfpartner.com.

mygfpartner.com/jacob-sensiba-wisconsin-financial-advisor/

Filed Under: Investing, money management, Personal Finance, risk management, successful investing, tax tips Tagged With: Debt, emergency fund, invest, investing

What Happens if Debt Is Sold to a Collection Agency?

November 11, 2020 by Jacob Sensiba Leave a Comment

When debt is sold to a collection agency, it’s incredibly common to get upset and/or worried. Odds are, you’ll start getting calls, emails, and text messages about you paying what’s owed.

In today’s post, we’ll discuss what leads to debt going to collections, what to do, what the collections agency can do, and what happens to your credit.

Why does debt go to collections?

Debt goes into collections when you’re behind a certain period of time (usually 30+ days) on your payment.

The lender will either use their own debt collectors or hire a third party to collect. What might also happen is your debt is sold to a collection agency, where they buy the debt from the lender (at a reduced amount than what you actually owe) and then attempt to collect on that amount.

Mortgages

With regard to mortgages, there are certain time periods to keep in mind:

  • 1 – 15 days – Typical grace period. Your payment must be paid in this period.
  • 16 30 days – You’ll start getting reminders, and you’ll likely pay a small late fee. No damage to your credit.
  • 31 – 59 days – Reminder calls and letters will increase. Your credit will reflect your current late status and your credit score will fall.
  • 60 – 90 days – The reminder calls and letters will stop. Someone from your lender will come to your house.

Read more on this subject, here.

What to do when your debt is sold to a collection agency

Don’t ignore it. The best thing you can do is get ahead of it. Gather information about the debt in question. Have them send it to you in writing.

Contact the creditor. Dispute it if you believe there are inaccuracies, or if it’s just not your debt. If it is your debt and everything is accurate, try to negotiate with the lender – they prefer to receive some of what you owe!

If the collection agency is harassing you, submit a request in writing for them to stop.

What if you’re at your wit’s end and don’t know what to do? Hire an attorney. All correspondence, going forward, has to go through them. If anything, get a consultation from an attorney (which is often offered for free) and see what they recommend.

What can they do?

When it comes to collections and the law, there are a few things they can do and several things they can’t do. If you want to know more about that, click here.

Your credit

There are two important things to know when it comes to collections and your credit report.

  1. A collection (or a charge off) hurts your credit score. Not only that, but your payment history (number one factor when calculating your score) will no longer be 100%, and that’s damaging as well.
  2. A collection will stay on your credit report for 7 years. You can implement strategies to improve your score, but you’ll only be able to do so much while that collection is on there.

Having a debt sold to a collection agency isn’t the end of the world. There are several things you can do to rectify it, dispute, or recover from it.

Related reading:

What You Need To Know About Bankruptcy

Deep Dive Into Credit Cards

What Affects Your Credit Score

Jacob Sensiba
Jacob Sensiba

Jacob Sensible is a financial advisor with decades of experience in the financial planning industry.  His journey into finance began out of necessity, stepping up to support his grandfather during a health crisis. This period not only grounded him in the essentials of stock analysis, investment strategies, and the critical roles of insurance and trusts in asset preservation but also instilled a comprehensive understanding of financial markets and wealth management.  Jacob can be reached at: jake.sensiba@mygfpartner.com.
mygfpartner.com/jacob-sensiba-wisconsin-financial-advisor/

Filed Under: credit cards, credit score, Debt Management, money management, Personal Finance Tagged With: credit, credit score, Debt, Debt Collectors

How to Utilize Rewards

July 29, 2020 by Jacob Sensiba Leave a Comment

On this site, we talk about credit, investing, and how to pay off debt. One thing that’s often missed around the debt subject is rewards.

Rewards are incentives to keep going. It’s something we can use to motivate us on our journey, no matter what that journey is.

Whether we are trying to pay off debt, lose weight, or just, straight up, improve our life. You need to reward yourself, otherwise, it’s go go go, all the time.

In this article, we’ll talk about when it’s a good time to reward yourself, how, and things to look out for.

Habits

A reward should be centered around two things. Habit formation or commitment, and goals.

If you are trying to make an improvement on something, whether it’s your health or your finances, you have to develop good habits.

If you want to exercise more, do it six days in a row, then take a break. That break can be your reward. If you want to eat better, do it for six days and then take a little break with a cheat meal.

The first step is creating the habits to get yourself to that better place.

Goals

The next reward will come when you hit goals. You want to get to a certain place, say saving $20,00 for a down payment, eliminating your debt, or losing 20 pounds.

Those are great goals, but you should put in place incremental ones to help you get there. That could be a reward for every $5,000 saved, every $5,000 paid down, or every 5 pounds lost.

It’s a lot like Dave Ramsey’s “Snowball Method” with applications in different areas of life. The goal with that method is to give you small wins to keep you motivated.

How to reward

If you put those habits in place and hit those goals, it’s time for the reward. The great, but the challenging part about that is everyone defines reward differently.

So when you create a reward for yourself, you should keep two things in mind. Make sure it’s good enough to release some dopamine, but small enough that it doesn’t set you back on what you are trying to accomplish.

If you’re trying to lose weight, your reward should be a little cheat meal or a day off from working out. Not a day of binge eating or a week without breaking a sweat.

If you’re trying to save money or pay down debt, don’t let whatever the reward is negate you from saving that month or add to your debt.

Large enough to make you feel good, but small enough so you stay on course.

What to watch for

The biggest thing to watch for is the size/duration of the reward. It mustn’t be too big or too small.

It’s a fine line and may require a little trial and error before you get it right. Start small and work your way up.

As I mentioned, it shouldn’t detract you from the pursuit of your goals, but it should also make you feel good about the progress that you’ve made or the habits you’ve created.

How I handle rewards

I won’t lie to you, rewards are a challenge for me. I’m very much a black and white type of person.

I keep junk food out of the house because I can’t be tempted with it. I make regular transfers from checking to savings in order to keep “discretionary money” out of my bank account for fear of spending it away (mostly on take-out, honestly).

It’s hard for me to put the pedal to the floor and take it off for a day. I’m either all on or all off, but I’m starting to figure it out. It really just takes some practice, a little will power, and some self-awareness.

Related Reading:

The Psychology of Money

Diving Deep into Debt

Money Anxiety

My Life and How I Manage Stress

Jacob Sensiba
Jacob Sensiba

Jacob Sensible is a financial advisor with decades of experience in the financial planning industry.  His journey into finance began out of necessity, stepping up to support his grandfather during a health crisis. This period not only grounded him in the essentials of stock analysis, investment strategies, and the critical roles of insurance and trusts in asset preservation but also instilled a comprehensive understanding of financial markets and wealth management.  Jacob can be reached at: jake.sensiba@mygfpartner.com.
mygfpartner.com/jacob-sensiba-wisconsin-financial-advisor/

Filed Under: money management, Personal Finance, Productivity, Psychology Tagged With: Debt, goals, habits, motivation, rewards, Saving

How Long Does Bankruptcy Stay on Credit Report?

July 8, 2020 by Jacob Sensiba Leave a Comment

Filing for bankruptcy is a tough decision to make. It can provide relief when you’re drowning in debt, but it does have consequences when it comes to your credit. How long does bankruptcy stay on your credit report?

We’re going to explore the answer to that question, as well as a few other items, in this article.

What is bankruptcy?

It’s a legal proceeding when an individual or an entity is relieved from some or all of their debts. Whether it’s all or some, and how that process takes place depends on the type of bankruptcy that’s filed.

  • Chapter 7 – Liquidable assets are sold in order to pay off debts. When those assets are exhausted, the remaining debt is discharged.
  • Chapter 11 – The most expensive option, which is usually used by companies (General Motors and J.C. Penny, for example). This is a reorganization plan that enables companies to remain open while getting their financial obligations situated.
  • Chapter 13 – Only available to individuals. The person filing implements a payment plan and is typically able to keep their assets (house, car, etc.). The debt must be paid off in 3 to 5 years.

Federal student loans are often excluded from being discharged, so you’ll be on the hook for that.

Let’s take a look at how bankruptcy affects your credit report.

How it affects credit

I’ll state the obvious by telling you that bankruptcy negatively affects your credit. Typically, you can expect your score to drop by 20-25%. This also depends on your current credit score and credit strength.

Discharges on more accounts and/or accounts with higher balances will affect your score more than discharges on a small number of accounts and/or low balances.

Delinquency usually proceeds bankruptcy and those stay on your report for 7 years. Chapter 7 bankruptcy stays on your credit report for 10 years, while chapter 13 stays on for 7 years.

What to do after

Inspect your credit report with a fine-toothed comb. Make sure that the debts discharged were actually discharged. If you find errors, go through the proper channels to get those corrected.

Once you’ve filed, you can immediately start building your credit back up. The first step is to ALWAYS pay your bills on time. I’ve stated before that on-time payment history is the number one factor when calculating your credit score.

The next step is to open a credit account. This should be something small and manageable. I often suggest a secured credit card. With this type of account, you make a deposit and that deposit acts as your credit limit.

Establish a positive payment history and keep your utilization well below 30%.

Bankruptcy on your report

You don’t have to do anything to remove the bankruptcy from your credit report. It will fall off on its own.

Review your credit report once the 7 or 10 year period ends. At that point, depending which type you filed, the bankruptcy should come off.

Give it a few months as your credit report often lags a little after the activity actually took place.

Stay diligent. Bankruptcy is not a death sentence, it’s a fresh start. Pay on time, keep your utilization low, and keep your spending in check.

Related reading:

How to Answer a Civil Summons for a Credit Card

What You Need to Know About Bankruptcy

What Affects Your Credit Score

Jacob Sensiba
Jacob Sensiba

Jacob Sensible is a financial advisor with decades of experience in the financial planning industry.  His journey into finance began out of necessity, stepping up to support his grandfather during a health crisis. This period not only grounded him in the essentials of stock analysis, investment strategies, and the critical roles of insurance and trusts in asset preservation but also instilled a comprehensive understanding of financial markets and wealth management.  Jacob can be reached at: jake.sensiba@mygfpartner.com.

mygfpartner.com/jacob-sensiba-wisconsin-financial-advisor/

Filed Under: credit score, Debt Management, money management, Personal Finance Tagged With: bankruptcy, credit, credit report, Debt

How to Answer a Civil Summons for Credit Card Debt

June 24, 2020 by Jacob Sensiba Leave a Comment

How to Answer a Civil Summons for Credit Card Debt

You do what you can, but sometimes debt gets out of control. If you get far enough behind on your credit card payments, eventually, the lender or a debt collector will file a suit against you to get what they’re owed. In this article, we’ll explore what a civil summons is and what to do when you’re faced with one.

What is a civil summons?

Generally speaking, a civil summons is when a governing body, individual, or organization files a lawsuit or judgment against another individual or organization.

The document indicates the reason for the suit or administrative action. It also listed pertinent information, such as the time and date of the first hearing, details about the plaintiff and defendant, and the amount of time the defendant has to respond.

A civil summons with regard to credit card debt usually occurs when the account reaches “charge off” status. Charge-off status usually happens between 120 and 180 days.

With that said, here are the steps you need to take.

Don’t ignore it

This is the worst thing you can do. The suit will continue, whether or not you respond. If you don’t respond, the court will issue a ruling in favor of the lender.

That means you will be forced to pay what’s owed. They may also tack on attorney fees, court fees, and interest to your balance.

Negotiate

Get in touch with the lender/collector that filed the suit, and see if they will accept a lower amount.

The filer may ask for a lump sum or a series of payments. The negotiated amount can range from 40% to 80% of the original balance.

Who filed the suit also makes a difference in negotiation. If the lender is after you, they will be less willing to negotiate a lower amount than a debt collector that bought the debt at a discount.

Research

If negotiation doesn’t work, it’s time to build your defense. Get a hold of the lender or collector again and gather information.

  • Check through your records to confirm if the debt owed belongs to you – do the amount and the original lender match up? Is it yours?
  • Get a chain of custody records – does the filer have the legal right to do so?
  • How long have you owed the debt – the statute of limitations could forbid the suit based on how long you’ve owed it
  • Get proof from the filer – are their records accurate? Is the information listed correctly? If the filer has missing or incorrect information, this can work in your favor.
  • Get copies of everything – accurate and complete documentation is very important

Talk with a professional

Get a consultation. Often, these are free. At the very least, it’ll help get a better understanding of what you’re up against and what you should do.

If money is tight, there are organizations, like lawhelp.org, that will provide an attorney that volunteers their time.

If money isn’t as tight, vet and hire an attorney to help your cause.

Go to court

If negotiation and settling outside of court don’t work, then it’s time to go to court. Here’s what you have to do.

  • Formally answer the summons with the court. This has to be in writing and generally, you have to answer within 20 to 30 days of receiving the summons.
  • In your reply, you have three answer options: admit, deny, or lack of knowledge. Admit it’s your debt, deny it’s your debt (only if you’re 100% sure), or attest that you don’t have enough information to say otherwise.

Options after court

If the ruling goes your way, there’s not much else to do. However, there may be terms you need to settle on, depending on what the judgment was, so you may not be completely out of the woods yet.

If the ruling doesn’t go your way, you have a few options.

  1. Try negotiating with the lender/collector again.
  2. Pay the amount mandated by the court
  3. Argue the ruling by filing an appeal
  4. File for bankruptcy
    1. This is the last resort and should only be used if there’s no way to pay back what you owe.

Credit score

Your credit score will take a big hit throughout this process.

  • Prior to 30 days late, it won’t affect your credit score, but you will be charged late fees (most likely).
  • After 30 days, a late payment will show on your report. On-time payment is the number 1 factor when calculating your score, so expect a significant drop.
  • The impact late payment has on your credit gets worse as you pass 60 and 90 days.
  • As stated, a suit normally isn’t brought against you until 180 days late. At that point, the account is listed in “charge off” status and that will really hurt your score.

Obviously, you want to do everything possible to prevent being served a summons for your being behind on your credit card bills, but if you get there, these are the steps you need to take.

Related reading:

What Happens When You Fall Behind On a Mortgage?

What You Need To Know About Bankruptcy

Ways Debt Can Hurt You

What Affects Your Credit Score

How To Pay Off Credit Card Debt

Jacob Sensiba
Jacob Sensiba

Jacob Sensible is a financial advisor with decades of experience in the financial planning industry.  His journey into finance began out of necessity, stepping up to support his grandfather during a health crisis. This period not only grounded him in the essentials of stock analysis, investment strategies, and the critical roles of insurance and trusts in asset preservation but also instilled a comprehensive understanding of financial markets and wealth management.  Jacob can be reached at: jake.sensiba@mygfpartner.com.

mygfpartner.com/jacob-sensiba-wisconsin-financial-advisor/

Filed Under: credit cards, Debt Management, money management, Personal Finance Tagged With: card, civil, civil summons, credit, credit card, Debt, summons

Job Loss: What to do

May 13, 2020 by Jacob Sensiba Leave a Comment

Losing your job is like a big punch to the gut. At first, it’s hard to process, but then your head starts spinning. What will I do for work? How will I pay my bills and put food on the table? What will my family do?

Taking a deep breath is a good first step. After that, it’s time to put a plan into action. Many of you could be experiencing this right now, given what the world looks like today.

In this article, I’m going to lay out how to financially prepare before and in the midst of a job loss.

First thing

As I said, this will be a big shock to absorb. Give yourself some time to realize what has happened. More than likely, you’ll go through the 5 stages of grief.

Unemployment

One of the first things you should do is apply for unemployment. There might be some hoops that you have to jump through, but one imperative item you need to confirm with your old employer is that you were let go and without cause. Resigning or being fired for cause disqualifies you from collecting unemployment.

Set money aside for taxes. Unemployment does not withhold FICA taxes or state income tax (if applicable). If you normally receive a refund, you might get a reduced refund or none at all. Plan accordingly.

Severance

The next step has to do with severance. If you were let go or fired without cause, your company will, most likely, offer it to you. It isn’t required by law, but most companies do it. Take severance home and review it closely. Don’t sign right away. Once you’ve reviewed it, take it back and negotiate.

Job Search

Starting looking for a new job right away. It does not pay to wait. All jobs are first come first served, set get searching as soon as possible.

Be picky, but pick up a job of some sort that will provide you with some cash flow.

Is now the time for a career change? Have you been dissatisfied with your industry or line of work? Do you have the skills and/or qualifications to make such a change? These could be questions to consider.

Finances

With regard to any debts that you have outstanding, call your creditors and see if they will let you defer payments, or at least make reduced payments, for a while. Also, make the minimum on your debt payments. Having cash available for other necessary items is more important.

Relentlessly cut expenses and review your budget with fine-toothed comb. Again, cash flow is your friend in your new situation so the more liquidity you have the better.

Pad your emergency fund. Obviously, this is something that needs to be done before you lose your job, so it’s imperative that you listen. Common advice is to save 3-6 months’ worth of expenses. If you’re self-employed and are responsible for payroll and other business expenses, it’s prudent to have 6-12 months worth saved.

HELOC? That stands for Home Equity Line of Credit. Is that something you are able to do? Is that something that you want to do? A HELOC turns the equity you’ve accumulated on your home into a loan.

Insurance

Life and disability insurance are very important coverages to have, but a just loss and loss of income could derail those coverages. There is a rider that can be added (waiver of premium) at the time of application so your policy stays in force while you are unable to make payments. *Be advised: this has to be done when you sign up, not after the fact.*

Healthcare is another important item to take care of. First off, if you have any appointments you were waiting to schedule, do it now before your coverage changes. The next step is to find a suitable replacement for your current coverage. This could be taking your spouse’s insurance, finding new coverage on the marketplace, or signing up for COBRA.

Retirement

Avoid dipping into retirement savings – this should be your last resort. Retirement savings accrues most effectively when you leave it alone. That’s when compounding works the best. Not only that, withdrawing funds prematurely will subject you to income taxes and an early withdrawal penalty.

Do you have 401(k) loans? If the answer is yes, you’ll be required to pay that loan back in its entirety in the next 60 days, otherwise, it’ll be considered a withdrawal. Again, taxes and a penalty.

Make a decision on what to do with the old retirement plan – Do you roll it to your new employer, roll it to an IRA, or leave it with the current institution. If you have a lower account balance, your HR department could require you to transfer it or cash out. Each company is different.

Related reading:

Employer/Employee Negotiations

Why Financial Literacy is Important

Your Go-To Budget Guide

Jacob Sensiba
Jacob Sensiba

Jacob Sensible is a financial advisor with decades of experience in the financial planning industry.  His journey into finance began out of necessity, stepping up to support his grandfather during a health crisis. This period not only grounded him in the essentials of stock analysis, investment strategies, and the critical roles of insurance and trusts in asset preservation but also instilled a comprehensive understanding of financial markets and wealth management.  Jacob can be reached at: jake.sensiba@mygfpartner.com.
mygfpartner.com/jacob-sensiba-wisconsin-financial-advisor/

Filed Under: budget tips, Cash Reserve, Debt Management, Personal Finance, Retirement, tax tips Tagged With: Debt, emergency fund, finance, job, job loss, job search, severance, unemployment

How People with Bad Credit Can Survive the Storm

January 12, 2016 by Joe Saul-Sehy Leave a Comment

Credit ScoreThe upcoming storm of rising interest rates and increasing lender cautiousness makes life difficult for people with already bad credit ratings. In the coming year, you will have to tighten up and you will have to make a new start to get your credit rating back on track. Forget about the mistakes of the past and read our tips for how people with bad credit can survive the storm.

Don’t Cancel Your Credit Cards 

Do you have a spending bug you can’t seem to beat? The worst thing you can do is to cancel your credit cards. Unbelievably, this is a sign of panic and lenders will kick your credit score in the pants for doing it. The alternative is to leave these lines of credit open, but cut up the card. That way you’ve effectively closed your account without hurting your credit score.

Can You Kick a Debt Quick?

The reason why so many people have bad credit is spiraling debt. They get into a situation where they have so many bills coming in they can’t pay them all off and they barely remember who they owe and how much they have to pay.

Start the next year by hitting a debt right between the eyes. Get together a lump sum and pay off some debts in their entirety. This is a form of debt consolidation that will make it easier to rebuild your credit rating later on.

Talk to Your Lenders

It’s amazing how many borrowers won’t speak to the people who have leant them money. Nevertheless, this is a powerful tool in your resource. If you’re having problems paying your debts or rebuilding your credit rating, talk to these people. Tell them your difficulties.

They’ll often work out a different agreement to help you make your repayments. They don’t care about anything except getting their money back, so any chance to make a formal arrangement will be grasped with both hands.

Too Many Loans?

This is the first step. We’re not saying that you need to stop taking out all loans. You need some lines of credit if you’re going to rebuild your score. However, what people need to understand is that in the future lenders are going to be more stringent than ever before. Every rejected application leaves a stain on your credit record; therefore, you should only apply for loans you’re practically guaranteed to receive. A good choice might be a company like the scottishtrustdeed.co.uk where their focus is to help people find personal loans with bad credit.  Interest rates will be higher but again your best bet is to not apply for loans.

Get a “Bad Credit” Credit Card

Someone with bad credit has the problem of not being able to easily get any new lines of credit. They need a higher rating. This is where “bad credit” credit cards come in. These are types of cards designed specifically for people with bad credit.

Here are some characteristics of these cards:

  • Higher interest rates.
  • Lower limits.
  • Lack of choice.

As you can see, the upcoming debt storm isn’t a reason to panic. Keep a cool head and you should have no problems getting out of that pit of bad credit.

Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: Debt Management, Featured, Planning Tagged With: bad credit, credit score, Debt

4 Tips to Pay Down Student Loan Debt

August 21, 2013 by The Other Guy 1 Comment

I can’t think of a better way to start of one’s adult life than to do so with over $35,000 worth of debt, can you?  Doesn’t the idea of starting your career already knee-deep in the hole sound wonderful?  In the words of Lloyd Christmas from Dumb and Dumber, “mmm..that sounds good.  I’ll have that.”

Or I won’t.

The average college graduate now leaves college with over $35,000 worth of student loan debt — many have said that the student loan bubble, which now tops $1 trillion (yes, that is trillion with a “T”) is the next major “crisis” in America.  I submit that it’s not the next major crisis. It’s already here.  In June, Congress couldn’t figure out what to do about student loans, so in  their infinite collective wisdom, they decided to let interest rates double from 3.4% to 6.8%.  Thanks.  We all appreciate that.

If you’re one of the umpteen thousands of people paying off oodles of student loan debt – how do you take care of it?

OG’s Student Loan Debt Tips

Step 1:

Be realistic with how much you owe.  Get an accurate count of a) who you owe; b) how much and c) the interest rates.  Many people have government and private loans spread hither and yon.  Before you create a repayment plan, you have to be honest about how much you have.

Step 2:

Build your personal financial plan.  This includes student loans, but also should include building a cash reserve, family planning, retirement planning, and other financial goals.  Having a singular mindset of  “I’m paying off my student loans before I do anything else… could lead to burn out and could impact how fast you reach your true goals.  Plus, depending on your career choice, you may be eligible for deferment or outright forgiveness.

Step 3:

Create a debt payment plan.  You have two options when it comes to paying off student loan debt: pay based on your income, or pay based on your indebtedness.  Visit www.studentloans.gov and compare payments to determine what’s best for you and your personal financial situation.

Step 4:

Work your plan and throw off discouragement.  Follow through with your well thought out plan.  You did steps 1 through 3, now just execute.  It will become tiresome and you will feel at times like you’ll never get it done – but you will.  Track your progress monthly and watch the balances fall.

Student loan debt can seem insurmountable, but with the right well-thought out plan based on your personal financial goals, you can pay those off quickly and efficiently and move on to your other financial goals!

Enhanced by Zemanta

Filed Under: College Planning, Debt Management Tagged With: Debt, debt strategy, Loan, repay, Student loan, United States

Post-Holiday Distress: Did You Spend Too Much?

December 27, 2012 by Joe Saul-Sehy 27 Comments

Stop. Take a deep breath. That feeling of dread? It’s just the holiday spirit leaving your body with each passing breath. It’s your own fault… everyone knows not to look at the receipts on the day after!

If you were smart, you planned ahead. You created a holiday account at the beginning of the year so by the time November rolled around, you had cash on hand for cherry-picking the best deals.

If you were smart, you stuck to your budget and didn’t let stress, competition, irresistible deals, or last-minute price hikes to knock you off your plan. You made a list of people and charities you wanted to recognize, set a price per gift, stuck to your list, and got your shopping done early.

That’s if you were smart.

But if your candy cane and cookie euphoria is dissipating with every thought of your credit card statement, you’re not alone. It’s engrained in our culture: Thanksgiving is to overeating as Christmas is to overspending – lavish spending you’d never consider otherwise.

The pressure to GIVE is powerful; our senses may leave us entirely. When we shop, we anticipate the warm embrace and feeling of joy WE create when a gift is received. It’s awfully noble. But if you’re like me, today is the day you watch your kids and realize just how little use your gift will get (I will never buy a robotic pet again!).

So what’s next?

Budgets are fluid. They require constant reevaluation. If you overspent, it’s time to reconsider your budget for the coming months. You won’t be able to see any viable options without a clear picture. If you didn’t before, go back and write down what you spent.

Chances are, it’ll make you feel better. You’ll realize that, while you had a bad month for your budget, you aren’t completely out in the cold. Because, you see, most of the year… You were smart.

If you’re not feeling better, take solace knowing that it’s possible to mount a comeback.

A few years back, holiday spending tipped my credit card balances over the edge. I wasn’t smart. I thought I was – it makes sense to open up store credit cards to save 10%, right? Wrong. It wasn’t until too late that I realized I wouldn’t be able to make the minimum payments on so many cards.

I knew enough to see that with accumulating interest, everything I could afford to pay towards my various credit card bills would be going straight into the creditors’ pockets while my debt level remaind constant. Classic debt spiral.

What did I do? Consolidate. Debt consolidation sounds ominous, but it’s far worse for your credit to fall behind on payments. You can take advantage of low interest rates on balance transfers and merge your debt to one account, or seek a consolidation loan to pay off your principal balances. If you have good credit history, you may be able to achieve a lower interest payment or a longer payment period. Managable. You can handle that.

The moral of the story? I’ll say it again:

Stop. Take a breath. Enjoy what’s left of the holidays. You’ve got options.

Photo: TopGold

Thanks to Jennifer Willard for taking over the blog responsibilities today while Joe & OG search for more egg nog. Jennifer has a new blog, Crayons & Coins. She also writes for Credit Guard, a non-profit debt counseling company.

Enhanced by Zemanta
Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: budget tips, Debt Management, money management Tagged With: Balance transfer, Christmas, credit card, Debt, debt consolidation, Payment

So You Want to Manage Your Own Money?

September 4, 2012 by Joe Saul-Sehy 29 Comments

A friend texted me this morning.

“We should talk soon. Julie is coming around to the idea of us managing our own money.”

It seems easy, right? My initial reaction to my friend was, “That’s awesome!” because it is. There are few things more satisfying than achieving your financial dreams and knowing that you climbed the money management mountain yourself.

No “money-god” came down and did it for you.

You didn’t need the Powerball numbers.

You actually plotted a financial course and landed safely at your destination.

For my friend, and for you if you’re about to embark on this journey, there’s good news and bad news: the good news is that it isn’t difficult to manage your own money.

The bad news is that to effectively manage your own money you’ll need to be ready to face some fairly difficult tasks.


Two Types of People


When I was a professional advisor, I’d meet some smart people who wanted to jump into their own money management and wanted an expert with an opinion to look over their shoulder, hold them accountable, and make sure they didn’t miss any “I” dotting or “T” crossing.

…and then there were other, often equally-smart people who wanted to hand it over to me and have someone else take care of it for them.

Believe it or not, most advisors I knew preferred the latter type of client and loathed the first one. Someone questioning their motives? Someone asking “why are we doing it this way?” all the time? That’s preposterous!

But if you’re going to ever learn how to manage your own money, you’ll need to be the first type, not the latter.

The steps aren’t difficult:


The Steps to Managing Your Own Money


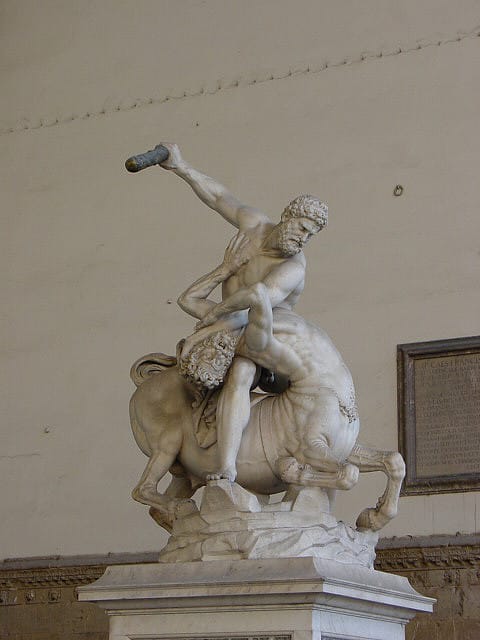
My kids are reading myths in school. In the story of Hercules, he faces a series of challenges to achieve is goal.

I look remarkably like the guy on top, but I’m a little paler and not quite as naked. And I have less hair.

You’ll have a series of gauntlets in your way too, if you want to manage your own money.

1) Write out your goals. I’m not talking about writing:

Retirement

College

New Boat

Fall Deeper in Love

Real goal writing has a specific time, dollar amount and vision attached.

I want to be able to live on $65,000 per year (in today’s dollars) by age 65 without having to work every day. With this money I’d like to: (here you write your bucket list, which should include visiting every NASCAR track in the country).

That’s a goal you can shoot for and be excited about (except for visiting the track at Pocono, which I thought was pretty overrated).

2) Next, you write out all the hurdles in your way.

– I have $25,000 in credit card debt (separate by interest rate, term, amount)

– I have to put two children through college

– I know nothing about money management

3) Then, you find one of the nearly bazillion financial calculators online (you can use our powerful little PlanWise calculator here on the site!) and figure out how much you need to save to reach your goal.

– I need to save $250 per month to reach my dream if I achieve an 8% return.

Armed with your money management return information, now you figure out how to come up with $250 per month.

– Tweak your budget

– Pay down debt

– Take on more work

4) Before investing, though, you have a big problem. You have to insure yourself against some of the huge “what if’s” out there for you and your family:

What if you die?

What if you are disabled?

What if you have a car accident?

You’ll need to create a will and evaluate insurances.

5) Finally, you begin the heavy task of research to find investments that have historically achieved 8%.


No Step is Difficult, You Just Shouldn’t Miss One


As you can see, when you take on the hard task and decide to manage your own money, getting it right will be difficult. Each area demands time and energy:

– Planning, milestones and tracking

– Budget, income advancement and debt reduction

– Insurance need projection and comparison analysis

– Estate planning

– Investment allocation, picking and monitoring

These are five basic money management steps, but each packs a punch!


I Don’t Mean To Imply You Can’t Do It


As soon as I finish this piece I’m calling my buddy and talking him through these points. Before he takes on the task, he should know how long the financial security road really is. Going in with your eyes wide open is half the battle if you plan to win the “manage your own money” game.

He can do it, and so can you!

Enhanced by Zemanta
Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: money management, Planning, successful investing Tagged With: Budget, Debt, finance, Financial services, Insurance, Investment, manage your money, money management

  • « Previous Page
  • 1
  • …
  • 19
  • 20
  • 21
  • 22
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework