• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for money tips

The IRS’s “Math Error” Notice Could Cost You More Than You Think

May 17, 2026 by Brandon Marcus Leave a Comment

The IRS’s “Math Error” Notice Could Cost You More Than You Think
A letter from the IRS – Shutterstock

The IRS rarely makes big announcements without consequences hiding behind the fine print, and the “Math Error” notice stands out as one of the most overlooked. This notice often arrives after a tax return review and signals that something on a return does not add up according to IRS systems. Many taxpayers assume it means a simple typo or harmless correction, but the reality can feel much sharper once the numbers change.

Refunds shrink, balances jump, and penalties can appear faster than expected. The biggest surprise comes from how quickly the IRS can adjust a return without needing a full audit. That speed leaves little room for hesitation or confusion. A small mistake on paper can snowball into a costly financial shift if no one responds in time.

What the IRS Math Error Notice Really Means

The IRS sends a math error notice when its automated systems detect discrepancies in calculations, credits, or reported income. The agency does not need to open a full audit to make adjustments, which allows it to correct returns rapidly. These changes often involve missed income, incorrect dependents, or miscalculated credits like the Child Tax Credit or Earned Income Tax Credit. The notice explains the adjustment and shows how the IRS changed the return. Many taxpayers miss the importance of the response window, which usually lasts only 60 days.

The IRS treats this notice as a legal adjustment unless the taxpayer responds with proof or disagreement. That detail matters because silence locks in the change automatically. Taxpayers often overlook the fact that the IRS already assumes its calculation stands correct unless challenged. The notice may appear routine, but it carries real financial consequences that demand immediate attention. A quick review can reveal whether the IRS made a simple correction or a costly mistake.

Why a Small IRS Adjustment Can Turn Into a Bigger Bill

A math error notice rarely stays small once penalties and interest enter the picture. The IRS recalculates the return based on its findings and immediately adjusts the refund or balance owed. Interest starts accruing on unpaid amounts, even if the taxpayer disagrees with the adjustment. That timeline creates pressure because delays increase the final amount due. Many taxpayers underestimate how fast those extra charges grow.

The financial impact often surprises people because the IRS does not wait for confirmation before applying changes. A refund that looked solid on paper can shrink by hundreds or even thousands of dollars overnight. A balance due can also appear out of nowhere when credits get removed or reduced. The system prioritizes speed and correction over negotiation at this stage. That structure means quick action becomes the only real defense against rising costs.

Common Triggers That Lead to IRS Math Error Notices

Several common filing issues trigger these notices every tax season. Incorrect Social Security numbers for dependents often lead the list, especially when parents mix up digits during filing. Misreported income from W-2s or 1099s also creates mismatches between IRS records and tax returns. Taxpayers sometimes claim credits without meeting eligibility rules, which instantly flags the return. Even small math mistakes in manual entries can trigger automatic corrections.

The IRS also flags returns when filing status does not match supporting documentation. For example, claiming head of household status without qualifying criteria often leads to adjustments. Missing or duplicate income entries create another major trigger point. Tax software reduces some errors, but it does not eliminate taxpayer input mistakes. Careful review before filing can prevent many of these issues from ever reaching the IRS system.
The IRS’s “Math Error” Notice Could Cost You More Than You Think
A woman reading a letter from the IRS – Shutterstock

How to Respond Before the IRS Locks In the Change

The IRS gives taxpayers a limited window to respond, and that window plays a critical role in protecting refunds or reducing balances owed. A taxpayer can agree with the notice and accept the correction, or disagree and submit documentation to support the original return. Supporting records might include W-2 forms, dependent verification, or corrected 1099 statements. Clear and organized evidence increases the chance of reversing the adjustment. Speed matters because delays often strengthen the IRS position.

Tax professionals often recommend responding immediately instead of waiting to gather information later. The IRS already assumes the adjustment stands, so silence removes negotiation power. A written response with clear proof can reopen the case for review. Many taxpayers regain lost refunds simply by providing missing or corrected documentation. A proactive response often changes the outcome entirely.

Protecting Yourself From IRS Math Error Surprises in the Future

Taxpayers reduce risk significantly when they double-check every entry before submitting a return. Accuracy in Social Security numbers, income reporting, and credit eligibility prevents most math error notices. Reviewing IRS transcripts after filing also helps catch mismatches early. Filing early gives more time to fix issues before deadlines close response windows. Small habits like these create a strong defense against unexpected adjustments.

Tax filing software helps, but it does not replace careful human review. Many errors still come from rushed inputs or assumptions about eligibility rules. Organized recordkeeping throughout the year makes tax season smoother and less stressful. Staying alert to IRS mail notices ensures quick responses when issues arise. A careful approach keeps money where it belongs instead of letting corrections drain it away.

What steps would make tax season feel less stressful and more predictable for your household? We want to hear your thoughts below in our comments.

You May Also Like…

The IRS Is Sending More “Math Error” Notices—Here’s What They Really Mean

7 “Trigger Words” the IRS Uses to Flag Returns Faster

7 New IRS Changes That Could Delay Your 2026 Tax Refund

6 Mistakes People Make When Appealing an IRS Identity Check

Estate Portability Warning: Why One IRS Form Protects a Surviving Spouse’s $15M Exemption

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: tax tips Tagged With: IRS, IRS audit, IRS correspondence, IRS notice, math error notice, money tips, Personal Finance, tax filing, tax penalties, tax refund, tax return mistakes

The IRS’s New 1099-K Threshold Could Catch Side Hustlers Off Guard

May 9, 2026 by Brandon Marcus Leave a Comment

The IRS’s New 1099-K Threshold Could Catch Side Hustlers Off Guard
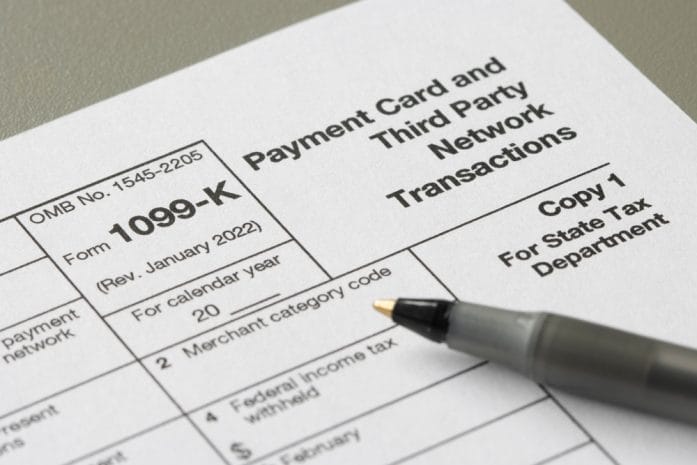
A pen laying on 1099-K tax forms – Shutterstock

Side income has exploded in recent years, and so has the attention it gets from tax reporting systems. What once felt like “small money on the side” now sits squarely in the IRS spotlight, especially when payment apps get involved. A simple weekend hustle selling clothes online or freelancing a few gigs can suddenly trigger paperwork that many people never expected.

The shift centers on how payment platforms report income through the 1099-K form. This change doesn’t just affect full-time business owners—it reaches deep into everyday earners who never considered themselves “self-employed.” The rules now aim to capture more digital transactions, and that means more people could see tax forms in their mailbox or inbox for the first time.

What Changed With the 1099-K Threshold and Why It Matters

The IRS designed the 1099-K form to track money earned through third-party payment networks like PayPal, Venmo, and similar platforms. For years, only certain earners received these forms, but recent updates changed reporting thresholds.

Under new rules, earners fly under the radar unless they earn over $20,000 and complete more than 200 transactions. This matters because a 1099-K does not mean extra tax automatically, but it does mean the IRS now sees the income. That visibility increases the chance of audits, mismatches, or follow-up questions if income doesn’t appear on tax returns. People who ignore these forms risk penalties or unexpected tax bills later.

The biggest change isn’t just paperwork—it’s awareness. More income streams now connect directly to IRS systems without extra effort from the taxpayer. That means every digital payment platform becomes part of a broader financial reporting network.

Who Gets Affected the Most by These Changes

Side hustlers feel this shift first, especially people selling products online or offering services through apps. Gig workers also land squarely in this group, especially those who drive, deliver food, or complete short-term jobs through apps. Many of these workers already receive 1099 forms, but payment app income adds another layer of reporting complexity. That combination increases the chance of confusion during tax season.

Freelancers who accept payments through digital wallets also face increased reporting visibility. A graphic designer, tutor, or consultant who gets paid through third-party platforms may receive multiple 1099 forms from different sources. That creates a patchwork of income records that requires careful tracking.

Even casual sellers who only declutter their homes can get caught off guard. A few high-value transactions can trigger reporting even if the activity feels personal rather than business-related. The IRS focuses on payment activity, not intent.

The IRS’s New 1099-K Threshold Could Catch Side Hustlers Off Guard
A man holding a clipboard with a 1099-K tax form – Shutterstock

Common Misconceptions That Lead to Tax Surprises

Many people assume a 1099-K means extra tax on top of everything else, but that assumption causes unnecessary panic. The form simply reports income; it does not calculate taxes owed. Tax liability depends on total income, deductions, and filing status. Another common misunderstanding involves thinking “small sales don’t count.” In reality, repeated small transactions can add up quickly and cross reporting thresholds without warning. That surprise often hits during tax season when forms arrive unexpectedly.

Some people also believe personal payments stay off the radar, but mixed use of payment apps complicates that idea. Sending money to friends differs from receiving payment for goods or services, and platforms track those differences. Mislabeling transactions can lead to confusion in reported income.

There’s also confusion about whether tax forms mean money has already been taxed. A 1099-K only reports gross payments, not profit. That means expenses still matter, and proper documentation can significantly reduce taxable income.

Recordkeeping Habits That Make Tax Season Easier

Strong recordkeeping helps prevent stress when 1099-K forms arrive. Side hustlers who track income and expenses throughout the year avoid scrambling at tax time. Simple spreadsheets or budgeting apps can create a clear financial picture. Separating personal and business transactions also reduces confusion. Using one payment account for income and another for personal transfers helps keep records clean. That separation makes it easier to match IRS forms with actual earnings.

Saving receipts and transaction details strengthens deductions. Costs like materials, mileage, or platform fees can reduce taxable income when properly documented. Without proof, those deductions often disappear during filing. Consistency matters more than complexity. Regular monthly tracking works better than last-minute sorting. That habit turns tax season from a stressful event into a manageable process.

How to Prepare Before Tax Season Hits Hard

Preparation starts with reviewing all payment platforms used throughout the year. Every app that sends or receives money for work or sales deserves attention. That review helps identify potential 1099-K forms before they arrive.

Next, side hustlers should estimate total annual income early. That estimate helps prevent surprises when forms show up with higher-than-expected numbers. Planning ahead also helps set aside money for possible tax obligations. Working with a tax professional can reduce errors, especially for people juggling multiple income streams. Professionals spot deductions and reporting issues that many individuals miss. That guidance often saves money in the long run.

Finally, staying updated on IRS rule changes prevents outdated assumptions from causing problems. Tax rules continue to evolve as digital payments grow. Awareness keeps income reporting accurate and stress levels lower.

Knowing The IRS 1099-K Shift Before It Catches You

The 1099-K changes reflect a broader shift toward transparency in digital income reporting. Side hustlers now operate in a system where even small earnings leave a financial footprint. That reality makes awareness and organization more important than ever.

People who track income carefully, understand reporting rules, and prepare early avoid most of the surprises. The IRS does not aim to punish side hustles, but it does expect accurate reporting. Staying proactive turns a confusing system into a manageable part of earning extra income.

What part of the new 1099-K rules feels most confusing or surprising for side hustlers today?

You May Also Like…

9 Side Hustles That Sound Great but Are a Complete Waste of Your Time

Millions of Gig Workers May Be Missing This Key IRS Requirement

1099-K Reality Check: Which Payments Are Always Reported

Selling a Long-Term Home Can Lead to Capital Gains Taxes—Even for Retirees

3 Tax Filing Mistakes That Can Trigger IRS Penalties

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: tax tips Tagged With: 1099-K, freelance income, gig economy, IRS, IRS rules, money tips, payment apps, side hustle, Small business, tax forms, tax reporting, taxes

Dormancy Rule: Accounts Inactive for 3–5 Years Can Be Sent to the State

May 7, 2026 by Brandon Marcus Leave a Comment

Dormancy Rule: Accounts Inactive for 3–5 Years Can Be Sent to the State
A stack of cash locked away from its owner – Shutterstock

Money doesn’t always disappear with a dramatic twist; sometimes it simply drifts out of sight, quietly waiting in accounts that haven’t been touched in years. Across the United States, financial institutions follow strict dormancy rules that allow them to flag inactive accounts and eventually transfer those funds to the state.

That process, called escheatment, catches millions of people off guard every year, especially those who assume their money will just sit safely forever. The truth carries a bit more urgency, and ignoring it can mean extra paperwork, delays, and unnecessary stress.

Why Banks Don’t Let Your Money Sit Forever

Banks don’t operate as long-term storage lockers for forgotten funds, and regulations require them to actively monitor account activity. When an account sits untouched for a certain period, usually between three and five years depending on the state, it gets labeled as dormant. That label triggers a countdown toward escheatment, where the bank must transfer the funds to the state treasury for safekeeping. Financial institutions follow these rules to prevent abandoned money from sitting indefinitely without oversight or ownership verification. This process protects consumers in theory, but it also creates complications when people lose track of accounts they assumed were still accessible.

That timeline can feel surprisingly short when life gets busy and accounts fall off the radar. A savings account opened years ago for a specific goal, a forgotten checking account from a previous job, or even a small investment account can all slip into dormancy faster than expected. Banks often attempt to notify account holders before transferring funds, but those notices don’t always reach the right address or email. Once the state takes control, accessing that money becomes possible but far less convenient than simply logging into a bank account. Staying active with accounts prevents this entire chain of events from ever starting.

What Counts As “Activity” Might Surprise You

Many people assume deposits and withdrawals represent the only meaningful account activity, but banks define activity more broadly than that. Logging into your account, updating contact information, or even making a small transfer can reset the dormancy clock. On the flip side, automatic transactions like recurring payments or interest deposits may not count as user-initiated activity in some cases. That distinction trips up account holders who believe their accounts remain active when they technically are not. Small misunderstandings like this often lead to accounts slipping into dormancy without warning.

Real-world scenarios make this issue even more relatable and frustrating. Someone might open a savings account for an emergency fund, set up automatic transfers, and then stop checking it regularly because everything feels “set and forget.” Years later, that same person may discover the account no longer exists at the bank because it was transferred to the state. Reclaiming those funds requires filing a claim, providing identification, and waiting through a verification process that can take weeks or longer. Taking a few minutes each year to interact with every financial account avoids this headache entirely.

Dormancy Rule: Accounts Inactive for 3–5 Years Can Be Sent to the State
Someone engaged in online banking – Shutterstock

The State Doesn’t Keep Your Money—But It Doesn’t Make It Easy Either

When funds get transferred to the state, they don’t vanish into a black hole, but they also don’t stay conveniently accessible. Each state holds unclaimed property in dedicated programs designed to safeguard assets until the rightful owner claims them. That sounds reassuring, but the process of reclaiming funds often feels anything but simple. Claimants must search state databases, verify ownership, and submit documentation that proves their identity and connection to the account. Delays can happen, especially when records are outdated or incomplete.

The experience becomes even more complicated for people who move frequently or change names over time. A missed notification, an old mailing address, or a forgotten account tied to a previous employer can all create barriers during the claims process. States do not actively track down every owner, so the responsibility falls on individuals to search for their own unclaimed funds. Millions of dollars sit in state databases because people never realize they need to claim them. Keeping accounts active eliminates the need to navigate this process in the first place.

Why Dormancy Rules Hit More People Than Expected

Dormancy rules don’t just affect careless account holders; they impact organized, financially responsible people as well. Life changes quickly, and accounts tied to old jobs, past relationships, or previous financial goals can slip through the cracks. Many people juggle multiple accounts across banks, credit unions, investment platforms, and apps, which increases the chance that one gets overlooked. Even small balances can trigger dormancy rules, and those smaller accounts often receive less attention. Over time, that neglect turns into a bigger issue.

Consider how easy it becomes to forget about a small account opened years ago for a specific purpose. Maybe it held travel savings, a side hustle fund, or leftover money from a closed business venture. Without regular interaction, that account quietly moves toward dormancy while attention shifts elsewhere. Financial institutions don’t distinguish between a forgotten $50 account and a larger balance when applying these rules. Every inactive account follows the same path, which makes regular check-ins essential no matter the balance.

Simple Moves That Keep Your Money Right Where It Belongs

Avoiding dormancy doesn’t require complicated strategies, but it does require consistency and awareness. Setting calendar reminders to log into every financial account at least once or twice a year keeps activity current and prevents accounts from going dormant. Consolidating accounts can also reduce the chances of forgetting about smaller balances scattered across multiple institutions. Keeping contact information updated ensures that any notifications from banks actually reach you before issues arise. These small habits create a strong safety net against dormancy rules.

Technology offers additional tools that make this process easier than ever. Financial apps can track multiple accounts in one place, giving users a clear view of their entire financial picture. Email alerts and account notifications can also serve as reminders to stay engaged. For those who prefer a more hands-on approach, maintaining a simple list of all active accounts provides clarity and control. These proactive steps take minimal effort but deliver long-term peace of mind.

Don’t Let Your Money Wander Off Without You

Dormancy rules exist for a reason, but they can still catch people off guard when attention drifts elsewhere. Staying connected to every account ensures that your money stays exactly where you expect it to be. A few minutes of attention each year can prevent weeks of frustration later. Financial awareness doesn’t require constant effort, but it does require intentional habits that keep everything visible and accessible. The payoff comes in the form of control, confidence, and fewer unpleasant surprises.

Money should work for you, not quietly disappear into a system you have to chase down later. What’s one account you haven’t checked in a while that might deserve a quick look today?

You May Also Like…

Why Seniors Are Seeing More “Account Access” Text Scams

North Carolina’s Flat Tax Savings in 2026: Why Everyday Costs Still Matter

8 Hidden Fees That Can Eat Away at Your Retirement Savings

Bank Teller Warning: Here’s When It Actually Makes Sense to Pull From Your Savings

Risk Proaction: 5 Steps to Stress-Test Your Finances for Worst-Case Scenarios

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Personal Finance Tagged With: asset recovery, bank accounts, banking rules, dormant accounts, escheatment laws, forgotten funds, money tips, Personal Finance, Planning, savings accounts, state treasury, unclaimed money

Warren Buffett Says If You’re Going to Splurge, Make It These 3 Things

April 28, 2026 by Brandon Marcus Leave a Comment

Warren Buffett Says If You’re Going to Splurge, Make It These 3 Things
Image Source: Unsplash.com

Money creates pressure when every dollar feels like it must be guarded or restricted. Warren Buffett flips that mindset by showing that spending well can actually strengthen long-term financial success. Instead of chasing impulse buys or flashy upgrades, smart spending advice focuses on areas that create real, lasting value. That shift turns money from something stressful into something strategic.

Buffett built his fortune through discipline, but he never promoted a life of constant deprivation. He consistently highlights that certain expenses deserve more weight because they shape future opportunities. When money flows into the right places, it multiplies its usefulness instead of disappearing into forgettable purchases.

1. Investing in Yourself Builds the Highest Return Over Time

Buffett repeatedly emphasizes that personal growth delivers the strongest return of any investment. Education, training, and skill development expand earning power and decision-making ability over a lifetime. Experts highlight Buffett’s belief that improving yourself produces compounding benefits that no stock or asset can match.

Buffett once stated that the best investment develops the individual, and that idea carries serious financial weight. Courses, certifications, and hands-on learning often open doors that remain closed without those skills. Smart spending advice pushes individuals to treat self-improvement as a non-negotiable priority. Over time, those investments shape careers, confidence, and financial stability.

2. Valuable Tools and Stocks Reward Quality Over Cheap Choices

Buffett’s famous line, “Price is what you pay; value is what you get,” applies far beyond the stock market. The principle behind it shows that cheaper options often cost more in the long run. Reliable tools, strong technology, and well-researched investments create smoother performance and fewer setbacks. Smart spending advice highlights this mindset as a way to avoid constant replacements and inefficiency.

Professionals often see major gains when they upgrade essential equipment instead of settling for low-cost alternatives. A dependable laptop or premium software can improve productivity and reduce daily frustration. Buffett’s approach rewards patience, research, and a willingness to invest in quality.

3. A Home That Fits Comfortably Creates Financial Stability

Buffett once described his home purchase as one of his best investments, not because it brought luxury, but because it brought stability. A home should support life, not strain finances or limit flexibility. Smart spending advice strongly warns against overextending for a house that stretches budgets too thin.

A well-chosen home creates breathing room for savings, investing, and daily living without stress. Homeownership becomes a foundation rather than a burden when costs stay within comfort levels. This idea focuses on balance, not excess or restriction. Buffett’s perspective reinforces that stability often delivers more value than status-driven purchases.

Warren Buffett Says If You’re Going to Splurge, Make It These 3 Things
Image Source: Unsplash.com

Why Buffett’s Spending Logic Still Wins in Real Life

Buffett’s philosophy doesn’t reject spending—it refines it into a strategy. Every dollar gains purpose when directed toward growth, quality, or stability. Smart spending advice helps filter out distractions that drain money without improving life. This approach builds financial confidence by removing emotional decision-making from major purchases.

Many people fall into the trap of chasing upgrades that impress others but add little personal value. Buffett’s framework cuts through that noise and focuses on outcomes that actually matter.

The Power Behind Buffett’s Smart Spending Advice

Buffett’s guidance works because it aligns money with long-term thinking instead of short-term impulses. Each of the three areas—self-investment, quality tools, and affordable housing—builds a stronger financial foundation. Good advice turns ordinary decisions into opportunities for growth and stability. This mindset reduces waste while increasing life satisfaction.

Money works best when it follows direction instead of emotion, and Buffett’s philosophy proves that every time. Smart spending advice turns everyday purchases into meaningful steps toward long-term success.

What would you prioritize first if applying Buffett’s spending strategy today? Let’s chat about it below.

You May Also Like…

Federal Spending Crackdown: Why Several States Are Now at Risk of Losing Family Assistance Funds

Maryland Seniors: Filing Errors on Local Tax Credits Are Causing Residents to Lose Key Savings

Why 70% of Lottery Winners Lose It All — And Never See It Coming

8 Hidden Fees That Can Eat Away at Your Retirement Savings

Legacy Insider: 4 Estate Secrets Wealthy Families Use

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Personal Finance Tagged With: budgeting, financial habits, financial wisdom, investing advice, lifestyle choices, long-term investing, money tips, Personal Finance, saving advice, Smart Spending, Warren Buffett, Wealth Building

I Saved $5,000 in Change — Then Found Out Banks Might Not Take It

April 28, 2026 by Brandon Marcus Leave a Comment

I Saved $5,000 in Change — Then Found Out Banks Might Not Take It
Image Source: Unsplash.com

A jar of loose coins rarely gets much respect, but over time, it can quietly grow into something impressive. Many households toss spare quarters, dimes, and pennies into containers without thinking twice, only to discover years later that those coins add up to thousands of dollars. That kind of slow, steady accumulation feels almost effortless, which makes it one of the simplest saving habits around. The surprise doesn’t come from the saving itself—it comes at the moment someone tries to cash it in.

Banks, which seem like the obvious destination for turning coins into usable cash, don’t always welcome large quantities of change. Policies have shifted over the years, and not every branch handles coins the same way anymore. Some institutions have removed coin-counting machines entirely, while others charge fees or impose strict limits. That leaves savers stuck in an unexpected situation, holding onto a pile of money that suddenly feels harder to access than expected.

Why Some Banks Refuse Large Coin Deposits

Banks operate with efficiency in mind, and handling massive amounts of loose change disrupts that flow more than most people realize. Counting coins takes time, requires specialized machines, and demands extra labor from staff who already juggle multiple responsibilities. Many financial institutions decided the cost and hassle outweigh the benefits, especially as digital banking continues to dominate everyday transactions. As a result, some banks simply stopped offering coin-counting services altogether.

Even banks that still accept coins often impose conditions that frustrate customers. They may require coins to be rolled in specific denominations, limit how much can be deposited at once, or charge service fees that eat into savings. Credit unions sometimes offer better options, but policies vary widely depending on location and membership status. The end result feels ironic: someone can save diligently for years, only to face roadblocks when trying to use that money.

The Hidden Costs of Cashing In Coins

Turning coins into spendable cash doesn’t always come free, and those fees can add up quickly. Coin-counting machines found in grocery stores or retail locations often charge around 10% to 12% of the total amount. On a $5,000 stash, that means losing hundreds of dollars just to convert coins into bills or digital funds. That kind of loss stings, especially after years of careful saving.

Some services offer fee-free options, but they usually come with trade-offs. For example, certain machines provide store gift cards instead of cash, which limits how the money can be used. While that works for regular shoppers, it doesn’t help someone who needs flexibility. These hidden costs turn what seemed like a smart, painless saving method into a situation that requires strategy and planning.

I Saved $5,000 in Change — Then Found Out Banks Might Not Take It
Image Source: Pexels.com

Smart Ways to Convert Coins Without Losing Money

Avoiding unnecessary fees starts with exploring all available options before cashing in. Local banks and credit unions still offer free coin services in some cases, especially for account holders. Calling ahead can save time and prevent frustration, since policies vary widely between branches. Some institutions even provide coin-counting machines exclusively for members, making them a valuable resource for frequent savers.

Another effective approach involves rolling coins manually, even though it takes effort. Banks that don’t offer counting services often accept rolled coins without charging fees, provided they meet standard packaging requirements. This method requires patience, but it preserves the full value of the savings. For those with large amounts, spreading deposits over multiple visits can also help avoid limits or scrutiny.

Why Saving Change Still Works in a Digital World

Despite the challenges of cashing in, saving loose change remains a surprisingly powerful habit. It creates a form of “invisible saving” where small amounts accumulate without impacting daily budgets. People rarely miss a handful of coins, but over time, those small contributions grow into meaningful sums. That psychological advantage makes coin saving accessible to almost anyone, regardless of income level.

Digital tools may dominate modern finance, but physical cash still plays a role in building financial discipline. Dropping coins into a jar creates a tangible reminder of progress, which motivates continued saving. Unlike automated transfers, this method feels hands-on and rewarding. Even with the inconvenience of cashing in, the long-term benefits often outweigh the drawbacks.

Common Mistakes That Can Cost You Money

Many savers make avoidable mistakes when handling large coin collections, and those missteps can reduce the total value. Waiting too long to check bank policies often leads to last-minute scrambling and unnecessary fees. Assuming all banks offer the same services also creates frustration, since policies differ significantly between institutions. A little research early on can prevent these headaches.

Another common error involves overlooking damaged or foreign coins mixed into the collection. Coin-counting machines may reject these, slowing down the process or causing discrepancies. Sorting coins beforehand ensures a smoother experience and avoids confusion at the deposit stage. Small details like this make a big difference when dealing with large amounts of change.

The Real Lesson Behind a $5,000 Coin Surprise

Saving money doesn’t always follow a straight path, and even the simplest habits come with unexpected twists. A pile of coins may seem straightforward, but turning it into usable funds requires awareness and planning. Financial institutions continue to evolve, and their policies don’t always align with traditional saving methods. Staying informed helps avoid surprises and keeps hard-earned money intact.

What would happen if a hidden jar in your home turned into thousands of dollars tomorrow—would you know the best way to cash it in? Let’s chat about it below in our comments.

You May Also Like…

A Big Change to Medicare Prior Authorization: 7‑Day Deadline Now Mandatory

9 Rare Coins Sitting in Your Change Worth a Small Fortune

4 Hidden Costs in Zero-Premium Medicare Plans

Pennies Are Disappearing — Here’s What You Should Do With Yours

Banks Are Moving Toward All-Digital Payments — What That Means for Your Money

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Banking Tagged With: banking rules, banks and fees, Budgeting Tips, cash savings, coin collecting, coin counting machines, financial habits, loose change, money tips, Personal Finance, saving money, saving strategies

Is Your Bank Balance ‘Normal’? Here’s What Americans Really Have Saved in Their Accounts

April 24, 2026 by Brandon Marcus Leave a Comment

Is Your Bank Balance ‘Normal’? Here’s What Americans Really Have Saved in Their Accounts
Image Source: Shutterstock.com

A quick glance at a bank app can spark pride one day and panic the next. Numbers alone rarely tell the full story, yet they still shape how people judge their financial progress. Headlines toss around averages that sound impressive, but those figures often hide massive gaps between high earners and everyone else.

Real insight comes from digging into what typical households actually keep in their accounts and how those balances shift with age, income, and life stage. This breakdown cuts through the noise and reveals what a truly “normal” bank balance looks like today—and what it should mean for real-life financial decisions.

What the Average Savings Balance Really Looks Like Across America

The average savings balance in the United States often lands in the tens of thousands, but that number skews heavily due to wealthier households. Median savings tells a more grounded story, with many Americans holding far less than flashy averages suggest. Surveys show that a large percentage of households keep under $10,000 in liquid savings. Younger adults and lower-income families tend to sit at the lowest end of the spectrum, often due to rising living costs and stagnant wages. These figures highlight a key reality: the “average savings balance” does not represent the typical experience.

Age plays a huge role in shaping the average savings balance across different groups. People in their 20s and early 30s often prioritize debt repayment and career building, which limits their ability to save. By the time households reach their 40s and 50s, savings balances usually grow due to higher earnings and more stable financial habits. Retirees often shift their money into different accounts, which can reduce visible cash savings even if overall wealth remains strong. These trends show that comparing savings across age groups rarely delivers a fair or accurate benchmark.

Why Comparing Your Savings to Others Can Backfire

Comparing personal finances to national averages creates unnecessary stress and often leads to poor decisions. A high average savings balance can make someone feel behind even when they follow a solid financial plan. On the flip side, low averages might encourage complacency when more aggressive saving would better support long-term goals. Financial health depends more on consistency and strategy than on hitting a specific number that fits everyone. Numbers without context rarely lead to smart financial moves.

Lifestyle choices and regional costs dramatically affect how much people can realistically save. Someone living in a high-cost city may struggle to build savings despite earning a strong salary. Meanwhile, a household in a lower-cost area may build a healthy average savings balance on a more modest income. Debt levels, family size, and unexpected expenses all shape savings outcomes in ways that averages cannot capture. Real progress comes from aligning savings goals with personal circumstances instead of chasing national benchmarks.

What Experts Say You Should Actually Aim For

Financial professionals rarely focus on the average savings balance when offering advice. Instead, they recommend building an emergency fund that covers three to six months of essential expenses. This approach creates a safety net that protects against job loss, medical bills, or sudden repairs. Beyond emergency savings, experts suggest setting aside money for short-term goals like travel or major purchases. Clear goals matter far more than comparing balances with strangers.

Consistency remains the most powerful driver of savings growth over time. Small, regular contributions can build a strong financial cushion even when income fluctuates. Automating transfers into a savings account helps remove the temptation to spend extra cash. Over time, this disciplined approach often leads to a higher-than-average savings balance without requiring extreme lifestyle changes. The strategy works because it focuses on behavior rather than comparison.

Is Your Bank Balance ‘Normal’? Here’s What Americans Really Have Saved in Their Accounts
Image Source: Shutterstock.com

Common Reasons Savings Fall Below the Average

Many households struggle to reach even a modest average savings balance due to rising expenses. Housing, healthcare, and food costs have climbed steadily, leaving less room for saving. Student loan debt and credit card balances also drain potential savings for millions of Americans. These financial pressures create a cycle where saving feels impossible, even with steady income. The challenge often lies in structural costs rather than poor money habits.

Unexpected life events can also derail savings plans in an instant. A medical emergency or job loss can wipe out months or even years of progress. Families often prioritize immediate needs over long-term savings during these periods, which makes recovery difficult. Without a financial buffer, rebuilding savings becomes a slow and frustrating process. These realities explain why many people fall below the average savings balance despite strong intentions.

How to Build a Savings Balance That Actually Works for You

Building a meaningful savings balance starts with a clear and realistic plan. Setting a monthly savings target based on income and expenses creates a manageable path forward. Even small contributions can add up quickly when they happen consistently over time. Tracking spending habits can reveal hidden opportunities to redirect money into savings. This approach puts control back in the hands of the saver.

Creating separate accounts for different goals can make saving more effective and less stressful. One account can handle emergencies, while another can fund vacations or large purchases. This structure prevents the temptation to dip into critical savings for non-essential expenses. Over time, this method helps grow a stable and purposeful average savings balance. The result feels more satisfying because every dollar serves a clear purpose.

The Measure of Financial Progress Isn’t a Number

A “normal” bank balance does not exist in any meaningful sense because financial lives vary so widely. Progress depends on stability, preparedness, and the ability to handle unexpected challenges. A strong average savings balance can help, but it should never define financial success on its own. Confidence comes from knowing that savings align with real needs and future plans. That mindset creates lasting financial security rather than temporary reassurance.

What does your savings strategy look like right now—and does it actually match your lifestyle and goals? Let’s talk about it in the comments below.

You May Also Like…

North Carolina’s Flat Tax Savings in 2026: Why Everyday Costs Still Matter

Banks Are Reducing Credit Limits for Older Customers During Risk Reviews

Banks Are Closing Accounts During ‘De-Risking’ Reviews—Often Without Warning

5 Budgeting Apps That Integrate With Biometric Banking

Starting Retirement Savings at 30 With $0 — Is Catching Up Still Possible?

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Banking Tagged With: average savings balance, budgeting, emergency fund, money tips, Personal Finance, Planning, savings

The Retirement Age Just Hit 67 — What That Means for Your Monthly Check

April 12, 2026 by Brandon Marcus Leave a Comment

The Retirement Age Just Hit 67 — What That Means for Your Monthly Check
Image Source: Unsplash.com

Turning 67 just became a lot more important than it used to be. That number now carries serious financial weight, shaping how much money shows up each month in retirement and how long it takes to unlock the full benefit. The shift didn’t happen overnight, but it now stands fully in place, and it changes the way millions of people need to think about timing, strategy, and expectations. That monthly Social Security check doesn’t just appear out of thin air—it responds directly to when benefits start, and that decision carries long-term consequences. The difference between claiming early and waiting can add up to thousands of dollars over time, which makes this far more than just a technical detail.

This change also brings a reality check that feels impossible to ignore. Retirement planning no longer revolves around a single “magic age” that works for everyone, because the system now rewards patience in a very real way. Waiting longer can mean a bigger check, but it also means working longer or leaning on savings in the meantime.

Why 67 Became the New Magic Number

The idea of a “full retirement age” didn’t always point to 67, and that shift tells an important story about how Social Security evolved. Decades ago, 65 marked the moment when full benefits kicked in, and that number stuck in the public imagination for generations. Lawmakers later adjusted the system through legislation passed in 1983, gradually raising the full retirement age to account for longer life expectancies and financial pressure on the program. That change didn’t hit all at once, but it phased in over time, and it now fully applies to anyone born in 1960 or later.

Reaching 67 now unlocks 100 percent of the calculated Social Security benefit, which the Social Security Administration bases on lifetime earnings. Claiming before that age reduces the monthly payment, while waiting beyond it increases the benefit through delayed retirement credits. This structure encourages people to hold off if possible, because each additional year can boost the monthly check in a meaningful way. The system essentially rewards patience, but it doesn’t force it, which leaves room for personal strategy.

That flexibility sounds great in theory, but it introduces complexity in practice. Not everyone can wait until 67, especially if health issues or job loss enter the picture. Others might prefer to claim earlier and enjoy more years of benefits, even if the monthly amount shrinks. The key lies in understanding that 67 doesn’t represent a deadline—it represents a benchmark. Knowing how that benchmark fits into a broader financial plan makes all the difference.

Claim Early, Pay the Price: The Reality of Starting at 62

The earliest age to claim Social Security retirement benefits remains 62, and that option grabs attention quickly. Starting at 62 delivers income sooner, which can help cover expenses or reduce the need to draw from savings. That early access feels appealing, especially for anyone eager to step away from full-time work. But that decision comes with a permanent trade-off that deserves serious consideration.

Claiming at 62 reduces the monthly benefit by as much as 30 percent compared to waiting until 67. That reduction sticks for life, which means every single check arrives smaller than it otherwise would. Over a long retirement, that gap can add up to a significant amount of money left on the table. The system applies this reduction because it expects to pay benefits for a longer period, so it spreads the total value across more years.

This choice can still make sense in certain situations, but it requires a clear-eyed look at the numbers. Health concerns, shorter life expectancy, or an immediate need for income can justify an earlier claim. On the flip side, strong savings or continued employment can make waiting a smarter move. Anyone considering this option should run the math carefully and think about how that lower monthly payment will feel ten or twenty years down the road.

Wait It Out, Cash In: The Power of Delayed Retirement Credits

Patience pays off in a very literal way when it comes to Social Security. Waiting beyond full retirement age increases the monthly benefit through delayed retirement credits, which grow the payment by about 8 percent per year until age 70. That increase stacks up quickly, turning a decent benefit into a significantly larger one over time. For anyone who can afford to wait, this option offers one of the most reliable ways to boost guaranteed income in retirement.

Delaying benefits doesn’t just increase the monthly check—it also creates a stronger financial cushion later in life. Larger payments can help cover rising healthcare costs, inflation, and other expenses that tend to grow with age. This strategy essentially shifts more financial security into the later years, which can provide peace of mind when other resources start to thin out. That long-term perspective matters, especially as life expectancy continues to rise.

Of course, waiting until 70 doesn’t work for everyone. Some people prefer to enjoy their retirement years earlier, while others may not have the financial flexibility to delay income. The decision hinges on personal circumstances, including savings, health, and lifestyle goals. Still, the math behind delayed credits makes a compelling case for patience, and it deserves a spot in any serious retirement strategy.

The Factors That Shape Your Monthly Check

Social Security benefits don’t rely on age alone, and several other factors quietly influence the final number. Lifetime earnings play the biggest role, because the system calculates benefits based on the highest 35 years of income. Higher earnings generally lead to higher benefits, while gaps in employment or lower wages can bring the average down. That formula means every working year counts, especially those with stronger income.

Inflation adjustments, known as cost-of-living adjustments, also affect monthly payments over time. These increases aim to help benefits keep up with rising prices, although they don’t always match real-world expenses perfectly. Taxes can also enter the picture, depending on total income during retirement. Up to 85 percent of Social Security benefits can become taxable under certain conditions, which can reduce the net amount received.

Work decisions during early retirement can further complicate things. Earning income while collecting benefits before full retirement age can temporarily reduce payments due to the earnings test. Once full retirement age arrives, those reductions stop, and benefits adjust accordingly. Understanding these moving parts helps avoid surprises and allows for smarter planning.

Smart Moves to Make the Most of Your Benefits

A strong strategy can turn Social Security into a powerful financial tool instead of just a basic safety net. One of the most effective moves involves coordinating benefits with a spouse, because timing decisions can affect total household income. Spousal benefits and survivor benefits add layers of opportunity that can increase overall payouts when used strategically. Planning together often leads to better results than making isolated decisions.

Another smart approach involves bridging the gap between early retirement and delayed benefits. Savings, part-time work, or other income sources can help cover expenses while waiting for a larger Social Security check. This strategy allows for delayed claiming without sacrificing financial stability in the short term. It requires planning, but it can pay off significantly over time.

Staying informed also makes a big difference. Checking benefit estimates through the Social Security Administration website provides a clearer picture of what to expect at different ages. Adjusting plans based on updated information keeps the strategy flexible and aligned with real-world conditions. Retirement planning doesn’t need to feel rigid—it can evolve as circumstances change.

The Retirement Age Just Hit 67 — What That Means for Your Monthly Check
Image Source: Shutterstock.com

The Number Isn’t the Finish Line—It’s the Starting Strategy

Age 67 now stands as a milestone, not a finish line, and that distinction changes everything about retirement planning. That number marks the point where full benefits become available, but it doesn’t dictate the best choice for every situation. Each person brings a different mix of health, savings, goals, and priorities to the table, and those factors shape the ideal strategy. The smartest approach treats 67 as one piece of a much larger puzzle.

Does claiming early feel worth the smaller check, or does waiting for a bigger payout make more sense in the long run? We want to hear your thoughts, strategies, or even your biggest retirement questions in the comments.

You May Also Like…

How Seniors Jeopardize Their Social Security Right After Retirement

10 Retirement States That No Longer Cater to Retirees

Why Your Social Security Payment Was Delayed: Common Oversights and Fast Fixes

8 Mistakes That Can Trigger a Social Security Overpayment Notice

Social Security, 401(k)s, and Market Swings: Why Retirement Feels Riskier Than Ever

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Retirement Tagged With: aging workforce, Delayed Retirement Credits, early retirement, Full Retirement Age, money tips, monthly benefits, Personal Finance, Planning, Retirement, retirement income, Social Security, SSA

Missed Deadlines, Missed Dollars, Government Dates You Can’t Afford To Ignore

April 7, 2026 by Brandon Marcus Leave a Comment

Missed Deadlines, Missed Dollars, Government Dates You Can't Afford To Ignore
Image Source: Shutterstock.com

The calendar does not care how busy life gets. It keeps marching forward, quietly stacking up dates that carry real financial consequences. Miss one, and the penalty does not come with a polite reminder or a gentle second chance. It comes with late fees, lost benefits, or money that never shows up at all. That sounds dramatic, but it is also reality for millions every year. Knowing the right dates turns confusion into control, and that control often translates directly into dollars.

This is not about memorizing a boring list of deadlines that blur together. This is about spotting the handful of government dates that can make or break a budget. Some of them hit every year like clockwork, while others sneak in depending on life changes, income shifts, or policy updates.

Tax Day Isn’t Just a Date, It’s a Financial Line in the Sand

Tax season carries a reputation for stress, but it also offers a chance to reset finances if handled right. The federal tax filing deadline usually lands in mid-April, and missing it can trigger penalties and interest that start stacking up immediately. Filing late without an extension can lead to a failure-to-file penalty, which grows quickly and feels anything but minor. Even if paying the full amount feels impossible, filing on time still reduces the damage. That simple move keeps penalties lower and opens the door to payment plans that ease the burden over time. People who expect a refund face a different kind of risk, because waiting too long can delay money that could already sit in a bank account earning interest or covering expenses. That refund does not arrive automatically, and the government will not chase anyone down to hand it over.

Extensions offer breathing room, but they come with a catch that often surprises people. Filing later does not mean paying later, and any owed taxes still need to be estimated and paid by the original deadline. Missing that detail creates a situation where penalties apply even with an approved extension. Planning ahead helps avoid that trap, especially by gathering documents early and estimating any owed amount well before the deadline hits. Free filing tools and tax assistance programs can also help those who qualify, cutting down on both stress and cost. Keeping an eye on state tax deadlines matters too, because they do not always match federal timelines. A little organization turns tax season from a scramble into something manageable, and that shift can save a surprising amount of money.

Benefit Deadlines That Quietly Decide Your Income

Government benefits often follow strict timelines, and missing them can mean waiting months for another opportunity. Programs like Social Security, unemployment benefits, and certain tax credits require timely applications or renewals to keep payments flowing. A delay in filing paperwork can interrupt income streams that people rely on for daily expenses. That gap can stretch longer than expected, especially when processing times increase during busy periods. Staying proactive with renewal dates helps maintain steady support without unnecessary interruptions. Marking those dates clearly on a calendar keeps them from slipping through the cracks.

Changes in income, family size, or employment status can also trigger deadlines that demand quick action. Reporting those changes late can lead to overpayments, which the government may later demand back. That situation creates a stressful cycle where money received in good faith suddenly turns into a debt. On the flip side, failing to report changes might mean missing out on increased benefits that could make a real difference. Keeping records updated and responding quickly to notices helps avoid both extremes. A little attention here protects income and prevents unpleasant surprises later.

Quarterly Payments: The Schedule That Catches People Off Guard

Not everyone pays taxes once a year. Self-employed workers, freelancers, and some investors must handle estimated quarterly tax payments, and these dates arrive four times annually. Missing one does not just delay a payment; it can trigger penalties even if the full amount gets paid later. That structure often catches people off guard, especially those new to freelance or gig work. Each payment covers income earned during a specific period, and the deadlines typically fall in April, June, September, and January. Keeping track of those windows ensures taxes stay manageable instead of piling up into one overwhelming bill.

Setting aside a percentage of income throughout the year helps make those payments less painful. Many financial advisors suggest saving around 25 to 30 percent of earnings for taxes, though the exact number depends on individual circumstances. Using a separate savings account for taxes keeps that money from getting mixed into everyday spending. Automated reminders or calendar alerts can also make a big difference, especially when work schedules stay unpredictable. Paying a little at a time keeps cash flow steady and avoids the shock of a massive bill. That steady approach turns a stressful obligation into a routine task that fits neatly into the year.

Enrollment Windows That Open and Slam Shut

Certain government programs only accept applications during specific enrollment periods, and missing those windows can leave people stuck waiting. Health insurance marketplaces, Medicare enrollment, and other programs follow strict timelines that do not bend easily. Missing an open enrollment period can mean going without coverage or paying higher costs until the next window opens. Special enrollment periods exist for major life events like marriage, childbirth, or job loss, but they come with their own deadlines that require quick action. Knowing those timelines ahead of time makes it easier to act fast when life changes.

Preparation plays a huge role here, especially when gathering documents and comparing options before the window opens. Waiting until the last minute often leads to rushed decisions that may not fit long-term needs. Taking time to review coverage options, costs, and benefits ensures a better outcome. Many programs also offer assistance through navigators or online tools, making the process less confusing. Staying informed about upcoming enrollment periods keeps options open and prevents last-minute stress. That awareness can protect both health and finances in a meaningful way.

Missed Deadlines, Missed Dollars, Government Dates You Can't Afford To Ignore
Image Source: Shutterstock.com

The Dates That Decide Credits, Refunds, and Extra Cash

Tax credits and government payments often come with deadlines that determine eligibility. Credits like the Earned Income Tax Credit or Child Tax Credit require filing within specific timeframes, and missing those windows can mean leaving money unclaimed. Some credits also depend on filing accurate information, which makes early preparation even more important. Waiting too long increases the risk of errors, and correcting those errors later can delay payments significantly. That delay can feel especially frustrating when that money could help cover essential expenses.

Refund timelines also matter more than they seem at first glance. Filing early often leads to faster refunds, especially when choosing direct deposit. That speed can make a real difference when budgets feel tight or unexpected costs appear. On the other hand, filing late during peak periods can slow everything down due to processing backlogs. Keeping documents organized and filing promptly helps avoid those delays. Staying ahead of deadlines ensures that every available dollar actually makes it into the bank instead of getting lost in missed opportunities.

Don’t Let the Calendar Win

Deadlines will never slow down, but staying ahead of them changes everything. A simple system of reminders, organized documents, and a little forward planning can protect income, reduce stress, and keep finances on track. The difference between missing a deadline and meeting it often comes down to preparation, not luck. Those who stay aware of key dates tend to keep more of their money and avoid unnecessary penalties. That control feels empowering, especially in a world where financial surprises seem to pop up everywhere.

What strategies keep everything organized and on time? Drop thoughts, ideas, or even hard-learned lessons in the comments and keep the conversation going.

You May Also Like…

Unclaimed Benefits: Are You Missing Out On Government Money

Retirement Healthcare Costs Are Climbing Again — What the Average Couple Now Needs

Banks Are Moving Toward All-Digital Payments — What That Means for Your Money

Charity Strategy: 9 Giving Moves That Bring Tax Benefits Many People Ignore

April Food Alert: How to Use SNAP’s Medical Expense Deduction if Your Benefits Suddenly Dropped

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Finance Tagged With: benefits, budgeting, deadlines, filing taxes, government deadlines, IRS, money tips, Planning, Social Security, stimulus checks, tax season, taxes

7 Hidden Costs That Are Eating Away at Retirement Income

March 30, 2026 by Brandon Marcus Leave a Comment

7 Hidden Costs That Are Eating Away at Retirement Income
Image Source: Shutterstock.com

Retirement doesn’t fail in dramatic fashion. It rarely crashes and burns in one catastrophic moment that sends alarm bells ringing. Instead, it erodes slowly, almost politely, with small expenses nibbling away at carefully built savings until the numbers stop adding up the way they once did. That polished retirement plan that looked airtight on paper can lose its shine when real life steps in and starts charging admission.

That reality doesn’t need to feel discouraging, though—it should feel empowering. Knowing where money quietly slips away gives anyone a chance to push back and reclaim control. The goal isn’t perfection or extreme frugality; it’s awareness with a bit of strategy sprinkled on top. These hidden costs don’t announce themselves, but once they show up on the radar, they become much easier to manage. Let’s dig into the ones that tend to do the most damage.

1. Healthcare Isn’t Just Expensive—It’s Relentless

Healthcare doesn’t simply sit still in retirement; it keeps moving, growing, and occasionally surprising even the most prepared planners. Many people account for insurance premiums, but they often underestimate the ongoing parade of out-of-pocket costs like co-pays, prescriptions, dental work, vision care, and specialized treatments. Those smaller bills don’t look intimidating on their own, but they stack up quickly and refuse to take a break. A single unexpected procedure can throw off a monthly budget that once felt comfortable.

Long-term care deserves a spotlight of its own because it can reshape finances almost overnight. Assisted living, in-home care, or nursing facilities carry significant price tags that many plans don’t fully absorb. Insurance helps, but it rarely covers everything, and gaps can grow wide. Planning ahead with dedicated savings or long-term care insurance can soften that blow, but ignoring it creates risk that compounds over time. Staying proactive with preventative care also reduces long-term costs, even though it requires consistency and attention.

Healthcare inflation adds another layer that many people underestimate. Costs tend to rise faster than general inflation, which means today’s estimates won’t hold steady over the next decade. Building flexibility into a retirement plan makes a huge difference here. Setting aside a buffer specifically for medical expenses keeps surprises from turning into crises. Regularly reviewing insurance coverage and comparing plans can also uncover savings that many overlook year after year.

2. Taxes Don’t Retire When You Do

Income might change in retirement, but taxes don’t pack up and leave. Withdrawals from retirement accounts like traditional IRAs and 401(k)s still count as taxable income, and that reality can catch people off guard. Many assume that a lower income automatically leads to a lower tax bill, but required minimum distributions can push income higher than expected. That shift can even bump retirees into higher tax brackets if they don’t plan withdrawals carefully.

Social Security benefits also come with a tax twist that surprises many. Depending on total income, a portion of those benefits can become taxable, which adds another layer of complexity. Coordinating withdrawals between different account types—taxable, tax-deferred, and tax-free—can help control that burden. A thoughtful withdrawal strategy can stretch retirement income further without requiring drastic lifestyle changes.

Property taxes deserve attention too, especially for homeowners who plan to stay put long-term. Local governments adjust rates, and rising property values can drive bills higher even when income stays fixed. Some areas offer relief programs or exemptions for retirees, but those benefits often require proactive applications. Staying informed and reviewing tax strategies regularly can prevent unnecessary strain and keep more money available for everyday living.

3. Inflation: The Slow Burn That Never Stops

Inflation doesn’t knock loudly, but it quietly reshapes purchasing power year after year. What feels affordable today may feel noticeably heavier a decade into retirement. Groceries, utilities, transportation, and entertainment all creep upward in cost, and that steady climb can outpace fixed income streams. Even modest inflation rates can erode buying power significantly over a long retirement.

Many retirement plans rely on conservative estimates, but those estimates can fall short when inflation accelerates. Investments that generate growth become essential to offset that erosion. Keeping a portion of a portfolio in assets that historically outpace inflation helps maintain balance. Playing it too safe with all-cash or low-yield investments can actually increase long-term risk.

Adjusting spending habits along the way helps counteract inflation without sacrificing quality of life. Reviewing recurring expenses, renegotiating service contracts, and exploring alternatives can keep costs manageable. Staying flexible and open to small lifestyle tweaks makes a big difference over time. Inflation doesn’t need to win—it just needs to be acknowledged and addressed with intention.

4. Helping Family Can Come With a Price Tag

Supporting family often feels natural, but it can quietly reshape retirement finances in ways that don’t always show up in initial plans. Financial gifts, helping with education costs, or stepping in during emergencies can add up quickly. Many retirees prioritize family support, which speaks to strong values, but those contributions need boundaries to avoid long-term strain.

Adult children may face economic challenges that lead to ongoing support rather than one-time assistance. That shift can turn occasional help into a recurring expense that chips away at savings. Clear communication and realistic limits protect both sides of the relationship. Generosity works best when it aligns with a sustainable plan.

Grandchildren can also bring joy—and unexpected costs. Contributions to education funds, travel expenses for visits, or covering extracurricular activities can stretch budgets further than anticipated. Setting aside a specific “family support” fund within a retirement plan keeps these expenses from spilling into essential living costs. That approach allows for generosity without sacrificing financial stability.

7 Hidden Costs That Are Eating Away at Retirement Income
Image Source: Shutterstock.com

5. Housing Costs Don’t Freeze in Place

Owning a home in retirement doesn’t eliminate housing expenses; it simply changes their shape. Maintenance, repairs, insurance, and property taxes continue to demand attention, and those costs can increase as homes age. A new roof, plumbing issues, or appliance replacements can appear suddenly and require immediate funding. These expenses don’t follow a predictable schedule, which makes them easy to underestimate.

Downsizing often gets pitched as a solution, but it doesn’t always deliver instant savings. Moving costs, real estate fees, and higher prices in desirable retirement areas can offset expected benefits. Even smaller homes come with ongoing expenses that require careful budgeting. Evaluating total costs rather than just square footage helps avoid surprises.

Renters face their own version of uncertainty with rising rents and limited control over increases. Long-term leases can provide stability, but they don’t eliminate future adjustments. Exploring different housing options, including shared living arrangements or age-friendly communities, can offer both financial and social benefits. Housing decisions carry long-term impact, so they deserve thoughtful consideration.

6. Lifestyle Creep Doesn’t Retire Either

Retirement often brings more free time, and that freedom can encourage spending in subtle ways. Dining out more frequently, traveling, or picking up new hobbies can gradually increase monthly expenses. None of these choices feel excessive in isolation, but together they can shift a budget significantly. Lifestyle creep doesn’t announce itself—it simply becomes the new normal.

That shift doesn’t mean cutting out enjoyment; it means staying aware of patterns. Tracking expenses regularly helps identify trends before they become problems. Setting a flexible “fun budget” allows for experiences without derailing long-term plans. Balance matters more than restriction. Subscriptions and recurring charges deserve special attention as well. Streaming services, memberships, and automatic renewals can quietly pile up over time. Reviewing these expenses every few months can uncover easy savings without sacrificing much. Small adjustments here can free up funds for more meaningful experiences elsewhere.

7. Investment Fees Can Quietly Drain Growth

Investment fees don’t grab attention, but they steadily chip away at returns over time. Management fees, fund expense ratios, and advisory costs can reduce overall growth, especially over long periods. Even small percentages make a noticeable difference when compounded year after year. Many retirees don’t realize how much they pay unless they actively review their accounts.

Actively managed funds often carry higher fees compared to index funds, and those costs don’t always translate into better performance. Exploring lower-cost alternatives can improve net returns without increasing risk. Transparency matters here—knowing exactly what each investment costs helps make smarter decisions. Working with a financial advisor can still provide value, but that value should justify the cost. Fee-only advisors or flat-rate structures can offer more predictable expenses compared to percentage-based fees. Regular portfolio reviews ensure that investments stay aligned with goals while minimizing unnecessary costs. Keeping fees in check allows more money to stay invested and working over time.

Awareness Changes Everything

Retirement doesn’t demand perfection—it rewards awareness and adaptability. These hidden costs don’t need to derail financial plans when they get the attention they deserve. A thoughtful approach, regular check-ins, and a willingness to adjust can keep income flowing in the right direction. Small changes made early can create a ripple effect that strengthens financial stability over the long haul.

Which of these hidden costs feels the most surprising or relevant right now? Drop thoughts, strategies, or even personal experiences in the comments—there’s always something new to learn from each other.

You May Also Like…

Retirement Accounts Are Triggering Unexpected Taxes — What Some Investors Overlook

Retirement Healthcare Costs Are Climbing Again — What the Average Couple Now Needs

Is it Too Late at 45? How to Use the Mega Backdoor Roth to Dump Tens of Thousands into Retirement in One Year

Starting Retirement Savings at 30 With $0 — Is Catching Up Still Possible?

The Retirement Honeymoon Phase — Planning for Years 1 and 2

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Retirement Tagged With: budgeting, healthcare costs, hidden costs, Inflation, investments, money tips, Personal Finance, Planning, retirement income, retirement planning, senior living, taxes

6 Times Your Bank Can Reject a Transaction Without Warning

March 29, 2026 by Brandon Marcus Leave a Comment

6 Times Your Bank Can Reject a Transaction Without Warning
Image Source: Shutterstock.com

A payment gets blocked in seconds, and suddenly everything grinds to a halt. One moment, everything feels smooth and under control, and the next, a simple tap or swipe turns into a confusing dead end that demands attention immediately. That tiny “transaction declined” message carries way more power than it should, especially when it shows up at the worst possible time. Nobody plans for it, nobody expects it, and yet it happens far more often than people realize.

Banks don’t randomly hit the brakes just to cause chaos. They rely on systems, patterns, and risk signals that operate behind the scenes, making decisions faster than anyone could react in real time. Those decisions protect accounts, prevent fraud, and enforce rules, but they also leave plenty of room for surprise interruptions that feel completely out of left field.

1. That Purchase Looks Suspicious (Even If It’s Not)

Banks constantly scan transactions for unusual behavior, and they don’t hesitate to step in when something feels off. A purchase that falls outside normal spending patterns can instantly trigger a block, even if everything about it feels perfectly legitimate. Buying an expensive item out of nowhere, shopping in a new location, or suddenly making multiple purchases in a short period can all raise red flags. These systems don’t rely on context or explanations, so they treat anything unexpected as a potential threat. That means a completely normal purchase can look risky if it breaks the usual routine.

The problem intensifies when timing and location don’t line up with recent activity. A transaction from a new city or country can look especially suspicious if no travel notice exists on the account. Even online purchases from unfamiliar retailers can trigger a decline if the system flags the merchant or notices unusual behavior patterns. Banks prioritize safety, so they would rather block a legitimate purchase than allow a fraudulent one to slip through. That approach protects money, but it can also feel frustrating when everything about the purchase makes sense on a personal level.

Staying ahead of this issue requires a little planning. Setting travel notices before leaving town gives banks a heads-up that spending patterns will shift. Keeping contact information updated ensures quick verification when a bank reaches out to confirm a transaction. Using the same card consistently for regular purchases also helps build a predictable pattern that reduces false alarms. These small steps create a smoother experience and keep transactions moving without unnecessary interruptions.

2. You Hit Your Limit Without Realizing It

Every account comes with limits, and those limits don’t always match what someone expects. Daily spending caps, withdrawal limits, and credit limits all play a role in whether a transaction goes through. A purchase that exceeds any of these thresholds can get declined instantly, even when enough money exists in the account overall. That disconnect often confuses people because the balance looks fine, yet the transaction still fails.

Debit cards often include daily spending limits that reset every 24 hours. Large purchases or multiple transactions within the same day can push spending past that cap without any obvious warning. Credit cards work differently but still enforce strict limits based on available credit, not total credit. Once spending approaches that ceiling, even a small additional charge can tip things over and trigger a decline. These limits exist to manage risk and protect both the bank and the account holder, but they can feel restrictive when timing matters.

Avoiding this situation means staying aware of both balances and limits. Checking available credit instead of just the total limit helps prevent surprises on credit cards. Reviewing daily debit limits and requesting adjustments when necessary can provide more flexibility for larger purchases. Planning big transactions ahead of time, especially for things like travel or major expenses, reduces the chance of hitting an invisible ceiling at the worst moment.

3. Your Account Doesn’t Have Enough Available Funds

Available balance and actual balance don’t always match, and that difference can cause a transaction to fail even when it looks like money should be there. Pending transactions, holds, and scheduled payments all reduce the amount of money that can be used immediately. A purchase that fits within the total balance might still exceed the available balance, leading to an unexpected decline. That gap catches many people off guard because it doesn’t show up clearly without checking the details.

Holds from hotels, gas stations, and rental services can temporarily lock up funds. Those holds often exceed the final charge, which creates a temporary squeeze on available money. Automatic payments scheduled for later in the day can also reduce available funds before they officially process. These behind-the-scenes adjustments happen quietly, but they have a real impact on whether a transaction succeeds or fails. Banks rely on available balance to approve transactions, not the total amount sitting in the account.

Keeping a buffer in the account helps absorb these temporary holds and pending charges. Regularly reviewing transaction history provides a clearer picture of what funds are actually available. Turning on balance alerts can also give a quick heads-up when available funds drop below a certain level. These habits create a cushion that keeps transactions flowing smoothly, even when holds and pending charges come into play.

4. The Merchant Triggers a Red Flag

Not all declines come from the account side of things. Sometimes, the issue comes from the merchant itself. Banks maintain lists of high-risk merchants and industries that carry a higher chance of fraud or disputes. Transactions involving these merchants can get blocked automatically, even when everything looks fine from a personal standpoint. Online retailers with limited history or poor reputations often fall into this category.

Certain types of purchases, such as those involving digital goods, subscriptions, or international sellers, can also trigger additional scrutiny. Banks analyze patterns across millions of transactions, and they flag merchants that frequently appear in fraud reports. When a card gets used at one of these merchants, the system may decline the transaction as a precaution. That decision happens instantly, with no time for explanation or review in the moment.

Choosing reputable retailers reduces the chance of running into this problem. Looking for secure payment indicators, verified reviews, and established brands adds an extra layer of confidence before making a purchase. If a transaction gets declined due to a merchant flag, contacting the bank can often resolve the issue quickly. That step confirms the purchase as legitimate and allows future transactions with that merchant to go through more smoothly.

5. Technical Glitches and System Errors

Technology runs the modern banking system, but it doesn’t always run perfectly. Network issues, system outages, and processing errors can all cause transactions to fail without warning. These glitches can happen on the bank’s side, the merchant’s system, or somewhere in between during the payment process. Even a brief interruption in communication can prevent a transaction from going through.

Card readers, payment terminals, and online checkout systems all rely on stable connections to process transactions. When something disrupts that connection, the system may default to declining the transaction instead of risking an error. Maintenance updates and system upgrades can also temporarily affect transaction processing. These issues usually resolve quickly, but they can create confusion in the moment when a payment suddenly doesn’t work.

Trying the transaction again often solves the problem if a glitch caused the decline. Using a different payment method, such as another card or a mobile payment option, can also provide a quick workaround. Keeping a backup payment method available ensures that one failed transaction doesn’t derail an entire plan. Staying flexible in these situations keeps things moving, even when technology decides to take a brief break.

6 Times Your Bank Can Reject a Transaction Without Warning
Image Source: Shutterstock.com

6. Your Card or Account Has Been Restricted

Banks can place restrictions on accounts or cards for a variety of reasons, and those restrictions can stop transactions immediately. Suspicious activity, missed payments, or verification issues can all lead to temporary blocks. Once a restriction goes into place, transactions will continue to fail until the issue gets resolved. These restrictions often come with notifications, but they don’t always arrive before the first declined transaction.

Verification requests can also play a role in these situations. Banks may require updated identification, confirmation of recent activity, or responses to security questions before allowing further transactions. Ignoring these requests can lead to ongoing declines, even when everything else looks normal. These measures protect accounts from unauthorized use, but they require quick action to restore full access.

Responding promptly to any communication from the bank helps resolve restrictions faster. Keeping identification and contact details up to date ensures that verification processes go smoothly. Setting up account alerts can also provide early warnings before restrictions escalate into declined transactions. Taking these steps keeps accounts in good standing and reduces the chance of unexpected interruptions.

Stay One Step Ahead

Bank declines don’t have to feel like random disruptions that show up out of nowhere. Each one ties back to a specific rule, pattern, or safeguard designed to protect money and maintain system integrity. Understanding those triggers turns frustration into strategy, and that shift creates a smoother, more predictable experience with every transaction. Small habits, like monitoring balances, updating account information, and planning ahead for large purchases, make a noticeable difference over time.

What’s the most surprising reason a transaction has ever been declined, and what strategy worked best to fix it? Drop your experience or tips in the comments and get the conversation going.

You May Also Like…

What to Do After Discovering a Secret Credit Card

7 Reasons Why Many “Buy Now, Pay Later” Users Are Actually Paying With Debit Cards

The Danger of Using Debit Cards While Traveling Abroad

Customers Beware: Banks Are Tightening Fraud Rules and Freezing Accounts Faster Than Ever

Banks Are Still Charging Daily Overdraft Fees After Accounts Go Negative

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Banking Tagged With: banking, banking errors, budgeting, credit card, Debit card, declined transaction, finance advice, financial habits, fraud prevention, money tips, payment issues, Personal Finance

  • « Previous Page
  • 1
  • 2
  • 3
  • 4
  • …
  • 8
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • 10 Tactics for Building an Emergency Fund from Scratch by Vanessa Bermudez
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald

Copyright © 2026 · News Pro Theme on Genesis Framework