• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for money tips

Why Credit Card APRs Only Dropped 0.35% Even After Three Fed Rate Cuts in 2025

February 2, 2026 by Brandon Marcus Leave a Comment

Why Credit Card APRs Only Dropped 0.35% Even After Three Fed Rate Cuts in 2025
Image source: shutterstock.com

If you watched the Federal Reserve cut rates three times in 2025 and thought, “Finally, some breathing room,” you weren’t alone. Millions of cardholders expected lower balances, cheaper interest, and at least a noticeable dip in those brutal APR numbers.

Instead, many people saw their credit card rates barely move, dropping by only a fraction of a percent, which felt less like relief and more like a financial prank. The frustration makes sense, but credit card APRs play by a very different set of rules, and those rules are not designed with everyday consumers in mind.

The Fed Doesn’t Control Credit Card APRs The Way People Think

The Federal Reserve controls the federal funds rate, not the rates lenders charge you directly. Credit card APRs are tied loosely to benchmarks like the prime rate, but banks layer their own margins, risk pricing, and profit targets on top of that base. Even when the Fed cuts rates, lenders decide how much of that benefit they actually pass on to customers.

For credit cards, which are considered high-risk, unsecured debt, banks protect their margins aggressively. That means small Fed cuts often translate into tiny APR changes, if any, especially compared to mortgages or auto loans. If you’re waiting for Fed policy alone to rescue your credit card balance, you’re waiting on the wrong lever of the financial system.

Banks Price Risk, Not Just Interest Rates

Credit card lending isn’t treated like home loans or business financing because there’s no collateral backing it. If someone stops paying a mortgage, the lender has a house; if someone defaults on a card, the bank has nothing but a loss. That risk gets baked into APRs through higher pricing, regardless of what the Fed does.

In uncertain economic conditions, lenders often tighten standards and keep rates elevated to offset potential defaults. Even small signs of economic instability make banks defensive, not generous. That’s why APRs stay stubbornly high even when broader rates move downward.

Profit Margins Matter More Than Consumer Relief

Credit cards are one of the most profitable products that banks offer. Interest revenue, late fees, balance transfer fees, and interchange fees create massive income streams that shareholders expect to keep growing. When the Fed cuts rates, banks don’t feel pressure to sacrifice profits unless competition forces them to. Because most major issuers move together, there’s little incentive to slash APRs aggressively.

The result is a slow, symbolic drop that looks good in headlines but barely helps cardholders. The system rewards stability and profits, not consumer relief.

Variable APRs Move Slowly By Design

Most credit cards use variable APR formulas tied to benchmark rates plus a fixed margin. When rates rise, increases hit fast; when rates fall, decreases move like molasses. That asymmetry isn’t accidental—it’s structural. Lenders update rates based on internal schedules, billing cycles, and risk assessments, not real-time Fed announcements.

Even multiple cuts can get absorbed into those systems gradually. So while headlines talk about rate changes, your statement tells a much slower story.

Inflation Still Shapes Lending Behavior

Even with rate cuts, inflation expectations continue influencing how lenders price credit. If banks believe costs will rise or economic pressure will persist, they protect their interest income. Lower rates don’t erase operational costs, fraud losses, or charge-offs from defaults.

Credit card APRs reflect long-term risk outlooks, not short-term monetary policy shifts. Until inflation feels truly under control at a structural level, lenders will keep pricing defensively. That caution shows up directly in your APR.

What You Can Actually Do Instead Of Waiting

Waiting for macroeconomic policy to fix personal finance problems rarely works. If high APRs and interest rates are hurting your budget, proactive moves matter more than headlines. Balance transfer offers with 0% introductory rates can create breathing room if used strategically. Credit unions often offer lower APRs than major banks and are worth exploring.

Negotiating directly with your card issuer sometimes works, especially if your payment history is strong. And paying more than the minimum, even in small extra amounts, dramatically reduces long-term interest costs.

Why The 0.35% Drop Feels Like An Insult

A tiny APR drop feels offensive because it highlights how disconnected consumer debt is from economic optimism. People hear “rate cuts” and expect relief, not symbolic gestures. That emotional disconnect fuels frustration and financial fatigue. But the system isn’t broken—it’s operating exactly as designed. Understanding that design gives you power instead of confusion.

Why Credit Card APRs Only Dropped 0.35% Even After Three Fed Rate Cuts in 2025
Image source: shutterstock.com

Why Financial Control Beats Financial Hope

Hope feels good, but control works better. Fed policy will always move more slowly than personal financial needs. Small APR drops won’t fix big balances. Real progress comes from strategy, not headlines. The people who win financially focus on leverage, not luck.

If credit card APRs barely budged after three Fed rate cuts, what does that say about how much control consumers actually have over their financial lives—and what’s the next move you’re willing to make to change yours?

You May Also Like…

8 Times “0% Interest” Credit Cards Turn Into Financial Traps

8 Hidden Risks People Overlook When Financing a Car at High APR

6 Foolish Mistakes That Can Lead to High APRs When Buying a Used Car

Why Closing an Old, Unused Credit Card Can Wreck Your Credit Score

Why Does Interest Rate Talk Suddenly Affect Everyday Spending

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: credit cards Tagged With: APR, budgeting, consumer finance, credit cards, Debt Management, federal reserve, financial literacy, Inflation, interest rates, money tips, Personal Finance

8 Choices Rich People Will Never Make, But Poor People Make Everyday

January 31, 2026 by Brandon Marcus Leave a Comment

These Are 8 Choices Rich People Will Never Make, But Poor People Make Everyday
Image source: shutterstock.com

Have you ever wondered why some people seem to effortlessly climb the financial ladder while others stay stuck on the same rung for years? It’s not luck, genetics, or secret handshakes—it’s choices. Wealthy people don’t stumble into riches; they make deliberate, sometimes uncomfortable decisions every single day that protect and grow their money.

Meanwhile, habits that might seem harmless or convenient to the average person can quietly drain income, time, and opportunities. By examining the differences in mindset and action, you can start steering your own life toward financial freedom. So grab your coffee, buckle up, and get ready to learn eight choices rich people never make—and why these decisions matter more than you think.

1. Ignoring the Power of Compound Interest

You’ve probably heard of compound interest, but ignoring it is one of the most common financial traps. Poorer individuals often leave their money in checking accounts or spend windfalls immediately, missing out on decades of potential growth. Wealthy people, on the other hand, invest consistently, letting even modest sums snowball over time. A dollar invested wisely today can be worth ten, twenty, or even a hundred dollars decades later. It’s not magic—it’s patience, discipline, and smart financial planning.

Start small if you need to; even $50 a week invested in index funds can grow substantially over 30 years. Don’t wait for the “perfect moment” because, in investing, time is your superpower.

2. Living Paycheck to Paycheck

It may feel normal to spend every dollar you earn, but living paycheck to paycheck is a choice with huge consequences. Emergencies, unexpected expenses, or sudden job loss can create financial chaos. Wealthy individuals prioritize building a safety net before indulging in luxuries. They understand that security isn’t about cutting all fun—it’s about controlling the chaos.

Creating a buffer of even three to six months’ worth of expenses can be life-changing. Once you’ve built a cushion, you’ll find yourself making bolder, smarter financial decisions without the constant stress.

3. Ignoring the Difference Between Assets and Liabilities

A Ferrari may look impressive on Instagram, but it’s not an asset—it’s a liability. Poorer people often confuse possessions with wealth, buying things that depreciate while ignoring investments that generate income. Rich people focus on acquiring assets: rental properties, stocks, businesses, and intellectual property that put money in their pocket while they sleep. The key distinction is cash flow versus consumption.

Learning the difference can help you shift your spending habits, turning purchases into tools for growth rather than traps for debt. Start small—invest in something that earns rather than something that merely impresses.

4. Letting Small Debts Snowball Into Big Problems

Carrying credit card balances or payday loans may seem manageable at first, but high-interest debt grows like a snowball rolling downhill. Wealthy people rarely, if ever, allow debt to pile up—they pay off balances aggressively or avoid unnecessary debt altogether. They understand that a few hundred dollars in interest today can become thousands over time.

Debt is not inherently bad; strategic borrowing for education, property, or business is smart. The difference is avoiding high-interest, low-value obligations that quietly rob your financial future. Track every loan, interest rate, and due date—awareness alone can save you thousands.

5. Failing to Prioritize Learning and Self-Improvement

Rich people are lifelong students. They read, attend seminars, hire mentors, and continually expand their knowledge and skills. Many people struggling financially neglect personal development, assuming school or formal training is enough. But skills, knowledge, and strategic thinking compound over time just like money.

The more you know, the better decisions you make, whether in investments, career moves, or starting your own business. Even dedicating 20 minutes a day to learning can set you apart in the long run. Knowledge isn’t just power—it’s financial leverage.

6. Reacting Instead of Planning

Poor financial choices are often reactive: paying bills at the last minute, splurging after a stressful week, or following impulse trends. Wealthy people plan ahead, budgeting and projecting cash flow, taxes, and expenses months or even years in advance. Strategic foresight prevents stress and maximizes opportunity.

Planning doesn’t mean eliminating fun; it means scheduling indulgences, investments, and emergencies thoughtfully. A little preparation can turn chaos into control and stress into opportunity. Start with one aspect of your finances—like monthly spending—and build a habit of proactive management.

7. Ignoring Health as a Wealth Factor

Money and health are more connected than most realize. Poor health leads to expensive medical bills, lost income, and reduced quality of life, yet many people neglect diet, exercise, and mental wellness. Wealthy individuals treat health as an investment, not an afterthought. Regular exercise, preventive care, and stress management aren’t just about feeling good—they save money and protect your ability to earn.

Think of your body as a high-yield asset; maintaining it pays dividends in energy, productivity, and longevity. Small, consistent choices—like walking, drinking water, or reducing sugar—compound into major savings over time.

These Are 8 Choices Rich People Will Never Make, But Poor People Make Everyday
Image source: shutterstock.com

8. Chasing Instant Gratification Over Long-Term Rewards

If it feels urgent to buy the latest gadget, a designer bag, or take a luxury vacation, you’re not alone—but wealthy people resist the temptation. They understand the long-term payoff of delayed gratification: investing, saving, or pursuing education instead of fleeting pleasure. Psychology studies show that the ability to delay rewards is strongly correlated with financial success.

Each choice to prioritize future gains over immediate satisfaction adds up, creating freedom and wealth over time. Start small by waiting 24 hours before major purchases—you’ll be surprised how often the urge fades.

Stop Letting Everyday Decisions Control Your Financial Future

Money doesn’t magically appear in bank accounts; it’s the sum of countless small choices, repeated day after day. Wealthy people are deliberate, informed, and disciplined about how they handle money, time, and energy. By avoiding the eight mistakes above, you can take control of your financial destiny. Start by identifying just one habit to change this week. Turn your financial awareness into action and watch your life transform over time.

What’s the one daily choice you make that could be quietly draining your potential wealth? Share your thoughts in the comments.

You May Also Like…

7 Lesser-Known Ways Rich People Protect Their Money

7 “Boring” Businesses That Make People Quietly Rich

Why Wealthy Families Are Moving Cash Out of Traditional Banks Before Jan 31st

Legacy Design: 5 Ways to Pass on Wealth Without Passing on Pressure

10 Traits the Rich and Poor Surprisingly Share

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Spending Habits Tagged With: compound interest, Debt Management, financial freedom, financial habits, financial literacy, investing, lifestyle choices, money tips, Personal Finance, saving money, Wealth Building, wealth mindset

Why More Americans Are Being Charged Fees They Never Explicitly Agreed To

January 29, 2026 by Brandon Marcus Leave a Comment

Why More Americans Are Being Charged Fees They Never Explicitly Agreed To
Image source: shutterstock.com

Every day, millions of Americans open a bill or glance at a bank statement and wonder how the final amount ended up so much higher than expected. That sting you feel isn’t just in your imagination — it’s baked into the way many modern companies structure hidden fees in contracts, services, and even basic financial products.

These charges pop up across many industries and weren’t explained clearly at the point of agreement, leaving consumers scrambling to understand why their hard‑earned money is evaporating. The truth is that the proliferation of tucked‑away fees isn’t just annoying—it’s now a widespread economic reality, costing households billions each year.

Drip Pricing Tricks Consumers With Gradual Fee Disclosure

One of the most effective ways companies sneak hidden fees into your bill is through drip pricing, where businesses advertise a low headline price and disclose extra charges only later in the buying process. This means you may invest time or emotional momentum before seeing the final cost, making you more likely to click “Buy Now” even when the real price surprises you at checkout.

Drip pricing distorts comparison shopping because online platforms and ads often show the low initial amount, not the full cost you’ll actually pay. Economists and regulators argue that this practice confuses consumers and undermines straightforward pricing. The result? You think you’re agreeing to one thing and end up on the hook for more, simply because the structure made it hard to see the true price upfront.

Credit Card And Bank Accounts Charge Fees Built Into Fine Print

Banks and credit card companies are notorious for charging fees that feel unexpected because customers didn’t review the full terms when signing up. Terms like overdraft fees, returned payment charges, and inactivity fees are technically disclosed, but many people never scroll through pages of dense contract language.

Financial regulators, including the Consumer Financial Protection Bureau (CFPB), have identified these practices as part of higher‑level industry dynamics where hidden fees contribute substantially to profits. When a monthly statement shows overdraft or service charges, it can feel like a surprise — but legally the company usually disclosed it somewhere in your agreement.

Travel And Ticketing Fees Inflate Costs After You Agree

Have you ever clicked book on a flight or concert ticket only to be hit with baggage, facility, service, or “processing” fees you didn’t expect? These are classic examples of hidden fees that were not made clear at the beginning of the transaction. Federal regulations aim to require airlines to show standard pricing, including certain fees so passengers aren’t misled, but these new laws continually get caught up in court.

Meanwhile, hotel resort fees and ticket service charges can push your total significantly higher than the initial price you saw. Regulators like the U.S. Department of Transportation have stepped in to make some of these costs clearer, but it’s still up to consumers to verify total amounts before completing purchases.

Subscription Services Use Auto‑Renewals And Add‑Ons That Stack Costs

Subscription fatigue is real. Hidden fees make it worse when extra charges drop into your monthly bill without a fresh signature. It may be an app subscription with an “enhanced service” add‑on. Maybe it’s a software tool with a training package tacked on, or a premium feature rolled into your plan after a free trial ends. Ultimately, these additions quietly increase your cost.

Companies lean on auto‑renewal language that most people accept once and never revisit, which means the total bill can creep upward over time. Reviewing your subscriptions every few months keeps fees visible and intentional. Figuring out which services to cancel and disabling auto-renewal when possible will help you stay ahead of unexpected charges.

Telecom And Utility Bills Filled With Service Charges

Cell phone plans, internet service, and utility bills are classic havens for hidden fees that seem to appear out of nowhere. Cable and broadband providers have been documented charging extra fees labeled as “infrastructure,” “network enhancement,” or similar vague descriptions that don’t clearly explain what you’re paying for. These fees can add high costs each month and often exceed advertised promotional rates once the initial period ends.

Consumer advocacy groups have found that many Americans now pay more in these charges than they did five years ago, precisely because companies structure billing to sneak them in. The best defense is to ask your provider to explain every line item and negotiate or change plans if the fees outweigh the benefits.

Retail Surcharges And Processing Fees Add Up At Checkout

You’re probably familiar with point‑of‑sale charges like card‑processing fees, checkout fees, or “convenience” fees that show up just before payment. Although retailers legally can add fees for optional services or third‑party processing, they must disclose them before you pay. The problem is that many businesses don’t make this transparent enough. This leaves consumers feeling blindsided when the final price jumps.

If a surcharge seems unreasonable, you can often refuse it. Or you can choose a different vendor or pay with another method to sidestep that extra cost.

Why More Americans Are Being Charged Fees They Never Explicitly Agreed To
Image source: shutterstock.com

Debt Collectors And Loan Servicers Push Unauthorized Charges

Companies you never directly choose — debt collectors or servicers for loans — may impose fees when they take over your account. The CFPB has called this practice unlawful. They say debt collectors cannot legally add arbitrary “collection fees” or “pay‑to‑pay” charges unless your contract explicitly allows such fees. So far, the courts have enforced this.

If you encounter such charges, dispute them under consumer protection laws and seek documentation for any fee claimed.

Lack Of Upfront Disclosure Makes Comparison Shopping Almost Impossible

What’s at the root of the explosion in hidden fees? It comes down to a pricing environment where companies don’t have to show total pricing upfront. This makes it nearly impossible for consumers to compare offers fairly or anticipate what they’ll actually pay.

Regulators like the Federal Trade Commission have proposed stricter rules to require companies to include mandatory costs in advertised prices. But until these policies are fully in place and enforced, consumers must remain vigilant. Always demand clarity: ask for total prices including fees and question ambiguous charges before you ever hand over your card.

Take Control By Making Fees Visible

Hidden fees have become a systemic issue in the U.S. From airlines to banks to your favorite subscription services, they are not going away on their own. Being proactive keeps you in control of what you pay and why.

Are there hidden fees you’ve been hit with that left you baffled, and how did you handle them? Make sure that you share them with other readers in our comments section below.

You May Also Like…

6 Major Banks Just Raised “Maintenance Fees”—Here is the List of Who to Ditch

The Quiet Credit Score Rule Change That’s Raising Borrowing Costs for Older Americans

Tax Blindspot: 4 Deductions Many Americans Miss During December

5 Bank Fees That Are Secretly Draining Hundreds From Your Account Annually

Are You Prepared For The Tax-Law Changes Arriving Sooner Than Most Americans Expect?


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Lifestyle Tagged With: Americans, billing, CFPB, consumer rights, contracts, Hidden Fees, junk fees, Life, Lifestyle, money tips, Personal Finance

9 Rare Coins Sitting in Your Change Worth a Small Fortune

November 18, 2025 by Travis Campbell Leave a Comment

coins
Image source: shutterstock.com

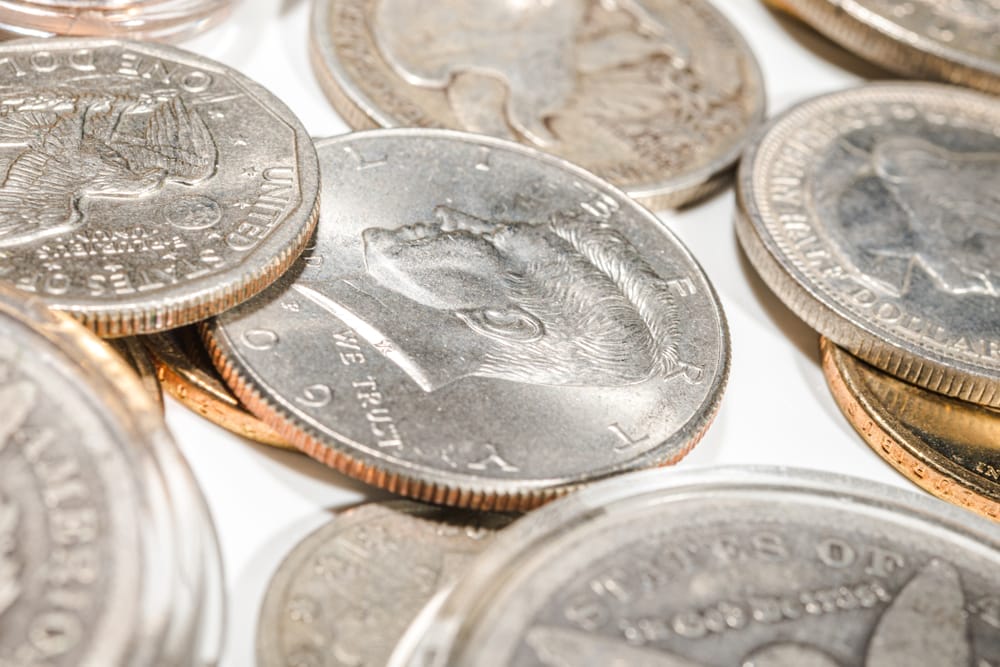
People unknowingly carry large amounts of money in their wallets at all times. Rare coins that are valued between hundreds and thousands of dollars move through cash registers and vending machines and piggy banks throughout the United States every day. The coins that museums protect as ancient artifacts are often found in your everyday change. Your ability to identify rare coins determines the value difference between an ordinary dime and a dime worth $2000. People fail to inspect their coins properly, which results in valuable coins disappearing from their possession. Your understanding of pocket change will change significantly after learning about rare coins that can be found in circulation.

1. 1943 Copper Lincoln Penny

During World War II, the U.S. Mint switched to steel pennies to save copper for ammunition. However, a few copper planchets from 1942 were accidentally struck with 1943 dates. Only about 20 of these rare coins exist today. If you find a copper-colored 1943 penny, test it with a magnet first—steel pennies stick to it, while copper ones don’t. These error coins have sold for over $372,000 at auction, making them one of the most valuable pennies in existence.

2. 1955 Doubled Die Penny

The 1955 doubled die penny shows dramatic doubling on “LIBERTY” and “IN GOD WE TRUST” that’s visible without magnification. This rare coin error happened during an overnight shift at the Philadelphia Mint when a flawed die went unnoticed. Thousands entered circulation, many handed out as change in cigarette packs in the Northeast. The doubling is clean and rounded—not the flat, shelf-like appearance of mechanical doubling. In uncirculated condition, these rare coins can fetch between $10,000 and $125,000.

3. 1969-S Doubled Die Obverse Penny

Perhaps the rarest doubled die penny, the 1969-S, shows profound duplication on the motto and date. When first discovered in the early 1970s, the Secret Service seized some examples under suspicion of counterfeiting. Once the U.S. Mint authenticated them, their value skyrocketed. There are fewer than 100 examples, with only 40 ever certified. These rare coins have sold for over $126,500, cementing their place among the most valuable pennies in circulation.

4. 1972 Doubled Die Obverse Penny

The 1972 doubled die penny features visible doubling on the date and motto with rounded separation in the lettering. There are seven recognized doubled die varieties for 1972, but only one exhibits dramatic doubling worth serious money. This rare coin error shows a clockwise rotation doubling pattern that’s ideal for teaching collectors how to identify valuable pennies. Top specimens graded MS-65 Red have realized up to $14,400 at auction.

5. 1982 No Mint Mark Roosevelt Dime

These dimes were the first U.S. business strike coins that accidentally left the Mint without their designated mint mark. A Philadelphia Mint employee failed to add the “P” mintmark onto an obverse die, and the error went unnoticed during inspection. Approximately 8,000 to 10,000 rare coins were reportedly found in Sandusky, Ohio, handed out as change at Cedar Point Amusement Park. While some sources claim values of up to $2,000, experts say these dimes typically fetch between $100 to $300.

6. 1999-P Connecticut Broadstruck Quarter

State quarters revolutionized coin collecting when they launched in 1999. The Connecticut quarter occasionally shows broadstrike errors where the coin wasn’t properly contained in the collar during striking. This causes the coin to spread beyond its normal diameter. These rare coins can be worth significantly more than face value, especially in higher grades. Broadstruck errors are dramatic and easy to spot—the coin looks wider and thinner than normal quarters.

7. 2004 Wisconsin State Quarter with Extra Leaf

The 2004 Wisconsin quarter features an ear of corn on the reverse, but some show an extra leaf below the main ear. Two varieties exist: “Extra Leaf High” and “Extra Leaf Low,” referring to the leaf’s position. These rare coins caused a sensation when discovered, with collectors scrambling to find examples. The error likely resulted from die damage or intentional die alteration.

8. 2005 “In God We Rust” Kansas Quarter

A grease-filled die created this amusing error on some 2005 Kansas quarters. When dies become clogged with grease and debris, letters can appear incomplete or missing. On these rare coins, the “T” in “TRUST” didn’t strike properly, making it read “In God We Rust.” While not as valuable as some other errors, these quarters still command premiums of $50 to $100 from collectors who appreciate the humor.

9. 2000 Sacagawea “Cheerios” Dollar

In early 2000, General Mills placed 5,500 special Sacagawea dollars in Cheerios boxes as a promotion. These rare coins feature enhanced tail feathers on the eagle—significantly more detailed than regular strikes. The difference is subtle but important. Only a fraction of the original 5,500 have been recovered and authenticated. These rare coins have sold for $5,000 to $25,000, making them one of the most valuable modern dollar coins.

Your Change Could Change Everything

The coins in your pocket possess a value that exceeds their nominal worth. People often fail to inspect their coins properly, allowing valuable coins to remain in circulation undetected. Check your pennies for doubled dies and your dimes for missing mint marks and your quarters for extra leaves or broad strikes. Take a few seconds to inspect your change at the grocery store checkout. A typical coin collection contains hidden treasures that can be worth hundreds or thousands of dollars. Your ability to identify rare coins, combined with your keen observation skills, will enable you to locate hidden, valuable objects.

Have you ever found an unusual coin in your change? What was the most valuable coin you discovered, and where did you locate it?

What to Read Next…

  • Why Even Wealthy Families Are Now Fighting Over Heirlooms
  • Why Are So Many Boomers Dying Millionaires And Leaving No Will
  • 7 Siblings Who Lost Inheritance Over A 1 Title Error
  • 9 Estate Planning Moves That End Up In Heated Probate Cases
  • 10 Ways You’re Wasting Money Just Trying To Keep Up Appearances
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Finance Tagged With: change hunting, coin collecting, money tips, Personal Finance, rare coins

Generate Extra Monthly Cash Flow Starting With These Side Hustle Ideas

October 25, 2025 by Catherine Reed Leave a Comment

Generate Extra Monthly Cash Flow Starting With These Side Hustle Ideas
Image source: shutterstock.com

With inflation, rising rent, and unpredictable expenses, many people are looking for ways to create extra monthly cash flow. Whether you want to pay off debt, build an emergency fund, or simply have more spending freedom, a reliable side hustle can make a big difference. The beauty of today’s gig economy is that you don’t need a business degree or tons of startup money—just a bit of creativity and consistency. If you’re ready to take control of your finances and put your spare time to good use, these side hustle ideas can help you start generating extra monthly cash flow right away.

1. Freelance Skills Online

One of the fastest ways to create extra monthly cash flow is to turn your professional skills into freelance income. Platforms like Upwork, Fiverr, and Freelancer let you offer writing, design, coding, or administrative services to clients worldwide. Even a few projects each month can generate hundreds of dollars, especially if you specialize in a niche. The flexibility of freelancing makes it perfect for evenings, weekends, or any schedule that fits your lifestyle. As you build a reputation, you can increase your rates and establish a steady stream of extra income.

2. Rent Out What You Already Own

Creating extra monthly cash flow doesn’t always require hard labor—sometimes, it’s about maximizing what you already have. If you own a car, you can list it on apps like Turo or HyreCar when it’s not in use. Spare rooms can be rented on Airbnb, and even tools or equipment can earn cash through local rental platforms. These assets often sit idle but have real earning potential when shared responsibly. This passive-style income allows you to generate profit with minimal daily effort.

3. Deliver or Drive on Your Own Schedule

If you enjoy being on the move, delivery services are a reliable way to boost monthly cash flow. Companies like DoorDash, Uber Eats, and Instacart let you set your own hours while earning per delivery. Drivers often make extra tips, and high-demand times like weekends can increase earnings quickly. You can also drive for rideshare companies like Uber or Lyft if you prefer passenger transport. It’s a simple, flexible way to monetize your free time while maintaining control over when you work.

4. Sell Handmade or Vintage Items

For creative or thrifty individuals, turning hobbies into income is an excellent way to build extra monthly cash flow. Selling handmade jewelry, crafts, or artwork on Etsy—or flipping vintage finds on eBay or Poshmark—can be surprisingly profitable. The key is to focus on what you enjoy making or collecting, so it doesn’t feel like a chore. Social media platforms can help you promote your products and attract loyal customers. Over time, even a modest side shop can evolve into a dependable income stream.

5. Offer Tutoring or Teaching Services

If you have expertise in a subject, tutoring can be both rewarding and profitable. Parents are often eager to pay for academic help, especially in math, science, or language skills. Online teaching platforms like VIPKid, Wyzant, and Outschool make it easy to connect with students worldwide. Teaching music, art, or test prep can also generate a steady extra monthly cash flow. Beyond the money, tutoring allows you to share knowledge and make a meaningful impact on others’ success.

6. Manage Social Media for Small Businesses

Many local businesses know they need an online presence but lack the time or skills to manage it. If you’re familiar with Instagram, Facebook, or TikTok, offering social media management can create a strong extra monthly cash flow. You can help businesses post content, engage with followers, and run basic advertising campaigns. The demand for digital marketing help is growing, and even one or two clients can provide a consistent income. This side hustle blends creativity with business strategy, making it both fun and financially rewarding.

7. Start a Pet Sitting or Dog Walking Service

Animal lovers can turn their affection for pets into a reliable side hustle. Apps like Rover and Wag connect pet owners with trusted walkers and sitters, allowing you to earn extra monthly cash flow while spending time with furry companions. This type of work is flexible and often less stressful than traditional jobs. You can walk dogs during lunch breaks or care for pets overnight while their owners travel. Building a reputation in your local community can lead to repeat clients and referrals.

Turning Spare Time Into Financial Freedom

Finding creative ways to build extra monthly cash flow can be a game changer for your financial goals. Whether it’s freelancing, tutoring, or renting assets, each option helps diversify your income and reduce financial stress. The secret is to start small, stay consistent, and reinvest your earnings wisely—perhaps toward debt, savings, or new opportunities. With time, your side hustle could become more than just a backup plan; it could become a gateway to long-term financial independence.

Which of these side hustle ideas sounds most realistic for your lifestyle? Share your favorite ways to earn extra monthly cash flow in the comments below!

What to Read Next…

  • 7 Income Streams You’d Laugh At—Until They Out-earned Your Salary
  • 6 Income Sources People Don’t Try But Should
  • 7 Unconventional Ideas for Earning Extra Income Reliably
  • 6 Financial Dangers of Relying on One Income
  • Is It Really Passive Income: 5 Lies About Making Money While You Sleep
Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.

Filed Under: side hustles Tagged With: budgeting advice, cash flow ideas, extra income, financial freedom, money tips, Personal Finance, side hustles

6 Income Sources People Don’t Try But Should

October 23, 2025 by Catherine Reed Leave a Comment

6 Income Sources People Don’t Try But Should
Image source: shutterstock.com

Most people rely heavily on one or two income streams—usually a job and maybe a savings account—but in today’s unpredictable economy, that can be risky. Expanding how you earn money doesn’t just increase your wealth; it adds stability, flexibility, and security when the unexpected happens. Surprisingly, there are several income sources people don’t try that are accessible, low-cost, and often underutilized. By exploring these overlooked opportunities, you can start building financial resilience without making drastic lifestyle changes.

1. Peer-to-Peer Lending Platforms

One of the most overlooked income sources people don’t try is peer-to-peer lending, which allows individuals to lend money directly to others in exchange for interest payments. Online platforms handle the logistics, letting you invest in personal loans with small contributions rather than large sums. Returns can be higher than traditional savings accounts, but there’s also some risk of default. The key is diversifying your investments across many borrowers to minimize losses. For people who want passive income and don’t mind moderate risk, peer-to-peer lending can be a smart, modern alternative to traditional investing.

2. Renting Out Storage Space

Not everyone has an extra room to rent, but many homeowners have unused garage or shed space that can be turned into income. Apps now make it easy to list storage areas for people who need temporary space for furniture, tools, or seasonal items. This is one of those simple income sources people don’t try because it feels unconventional, yet it requires minimal effort once the agreement is set. It’s a great option for suburban homeowners or anyone with secure space that sits empty most of the year. Think of it as being a landlord—without the tenants.

3. Selling Digital Downloads

Creating digital downloads—like planners, templates, or educational resources—can generate steady passive income once the initial work is done. Sites such as Etsy or Gumroad make it easy to sell without needing your own website. This is among the income sources people don’t try because they underestimate how valuable their knowledge or creativity can be. Even simple spreadsheets, design templates, or printable checklists can appeal to niche audiences online. Once uploaded, these products continue to sell with minimal maintenance, offering an ongoing trickle of income.

4. Renting Equipment or Tools

If you own lawn equipment, power tools, cameras, or even camping gear, you might be sitting on a profitable side income. Many people buy expensive equipment that spends most of its life gathering dust, unaware they can rent it to others for a fee. Platforms now exist to handle the rental process, including insurance and user verification. It’s one of the easiest income sources people don’t try because they assume demand is low, but the reality is that many people prefer renting over buying for short-term needs. Renting equipment lets you recoup costs while helping others save money.

5. Dividend Reinvestment Plans (DRIPs)

Dividend-paying stocks aren’t exactly new, but Dividend Reinvestment Plans—known as DRIPs—are income sources people don’t try often enough. Instead of taking cash payouts, these plans automatically reinvest dividends to purchase additional shares, compounding your returns over time. Many large, stable companies offer DRIPs with low or no fees, making them ideal for beginners. The beauty of this approach is that it quietly grows your portfolio without requiring constant attention. Over years, the reinvested dividends can snowball into significant wealth while still producing long-term passive income.

6. Micro-Investing Apps

Micro-investing apps round out the list of income sources people don’t try but should, especially for those who think investing is only for the wealthy. These apps round up your everyday purchases and invest the spare change in diversified portfolios. The amounts are small, but over time, they build real value—especially if you add recurring contributions. They’re also educational, helping new investors learn about markets without feeling overwhelmed. Micro-investing makes wealth-building approachable, proving that small habits can grow into meaningful financial gains.

Turning Small Opportunities into Long-Term Security

The beauty of exploring income sources people don’t try lies in the simplicity of getting started. None of these ideas require quitting your job or taking big financial risks. Instead, they let you turn what you already have—space, tools, time, or creativity—into assets that work for you. Diversifying income is more than a financial strategy; it’s a mindset shift toward independence and flexibility. The sooner you start experimenting with new income sources, the faster you’ll build a foundation for lasting financial security.

Have you discovered any unique income sources people don’t try that worked for you? Which idea from this list would you consider trying next? Share your thoughts in the comments below!

What to Read Next…

12 Different Ways to Structure Your Portfolio for Income Generation

7 Unconventional Ideas for Earning Extra Income Reliably

Top 7 Passive Income Ideas for Young Adults Looking to Grow Wealth

Is It Really Passive Income: 5 Lies About Making Money While You Sleep

7 Ways to Turn Peer-to-Peer Lending Into a Passive Income Machine

Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.

Filed Under: side hustles Tagged With: financial independence, income streams, investing, money tips, Passive income, Personal Finance, side income, Wealth Building

Freebies and Huge Discounts: 11 Places You’re Overpaying Without Realizing It

October 9, 2025 by Travis Campbell Leave a Comment

discounts
Image source: shutterstock.com

It’s easy to miss out on savings when you don’t know where to look. Many people end up spending more than necessary on everyday expenses, simply because they’re unaware of available freebies and huge discounts. Whether it’s out of habit or convenience, these overlooked costs can add up quickly over time. Identifying areas where you might be overpaying can make a noticeable difference in your budget. This article highlights the most common places where you’re likely missing out on freebies and huge discounts—so you can keep more cash in your pocket.

1. Subscription Services

Monthly subscription services can sneak up on your wallet. From streaming platforms to meal kits, it’s common to forget about services you rarely use. Many companies offer freebies and huge discounts to new users, but once the trial ends, the price jumps. Audit your subscriptions regularly, cancel what you don’t use, and look for introductory offers if you want to try something new. Sometimes, simply reaching out to customer service can help you score a retention discount.

2. Gym Memberships

Gyms often lure you in with special deals, but after the initial period, you may be paying for services you barely use. Many fitness centers offer free trial classes or discounted rates during certain times of the year. Check for community centers or local parks that offer free or low-cost fitness classes. By taking advantage of these freebies and huge discounts, you can stay active without overspending.

3. Cell Phone Plans

Cell phone bills are a common area where people overpay. With frequent updates to plans and promotions, it’s easy to miss out on huge discounts. Compare your current plan to what’s available. You may find that switching providers or negotiating with your carrier leads to significant savings. Don’t forget to ask about discounts for students, military, or bundling services.

4. Grocery Shopping

Shopping without a list or ignoring store loyalty programs can cost you. Many grocery stores offer exclusive freebies and huge discounts through their apps or membership cards. Clip digital coupons, check for weekly specials, and consider buying store brands, which often offer the same quality at a lower price. Planning meals around sales can also help you avoid overpaying.

5. Restaurants and Takeout

Dining out can drain your budget if you’re not careful. Many restaurants have loyalty programs or apps that reward frequent customers with freebies and huge discounts. Sign up for email lists to receive special offers or birthday treats. Ordering directly from the restaurant instead of third-party apps can also save on extra fees.

6. Online Shopping

Impulse purchases online often mean paying full price. Before checking out, search for promo codes, cashback offers, or browser extensions that find discounts automatically. Many retailers give out freebies and huge discounts for first-time shoppers or newsletter sign-ups. Take a moment to compare prices on different sites or wait for seasonal sales to get the best deals.

7. Travel and Accommodation

Booking flights or hotels without comparison shopping can lead to overpaying. Use travel aggregator sites to compare prices and set alerts for drops. Some credit cards offer exclusive travel freebies and huge discounts, such as free checked bags or hotel upgrades. Consider flexible travel dates to take advantage of off-peak rates.

8. Car Insurance

Many drivers stick with the same insurer for years, missing out on lower rates elsewhere. Compare quotes from multiple companies every year. Some insurers offer discounts for bundling policies, safe driving, or even for being a good student. Don’t forget to ask about any available freebies and huge discounts before renewing your policy.

9. Prescription Medications

Medication costs can vary widely from one pharmacy to another. Many pharmacies offer loyalty programs or discount cards, and there are online tools that help you find the lowest price. Ask your doctor if generic alternatives are available, and check if your health plan covers mail-order options for additional savings.

10. Utility Bills

Most people don’t realize their utility providers may offer freebies and huge discounts for things like energy efficiency upgrades or paperless billing. Some areas have programs that provide free energy audits or rebates for installing efficient appliances. Contact your provider to ask about current offers and see if you qualify for lower rates or special programs.

11. Entertainment and Cultural Events

Concerts, museums, and local attractions often have discounted or free admission days. Public libraries frequently offer free passes to cultural sites or host events at no cost. Websites like Eventbrite list free community happenings in your area. Take advantage of these opportunities to enjoy entertainment without straining your budget.

Maximizing Savings with Freebies and Huge Discounts

Paying attention to where your money goes can reveal surprising opportunities to save. By being proactive and seeking out freebies and huge discounts, you’ll stretch your budget further and avoid unnecessary expenses. Small changes, like signing up for loyalty programs or regularly reviewing your bills, can add up to big savings over time.

Where have you found unexpected freebies and huge discounts in your daily life? Share your favorite money-saving tips in the comments below!

What to Read Next…

  • 7 Tactics Grocery Stores Use to Keep You From Thinking About Price
  • Are These 8 Money Saving Tricks Actually Keeping You Broke
  • 6 Online Freebies That End in Identity Theft
  • Are These 7 Little Expenses Quietly Costing You Thousands a Year
  • 5 Invisible Service Charges Eating Into Your Bank Balance
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Frugal Living Tagged With: budgeting, discounts, freebies, money tips, Personal Finance, savings, spending

5 Quick Fixes for Common Cash Flow Problems Immediately

October 9, 2025 by Travis Campbell Leave a Comment

cash flow
Image source: shutterstock.com

Few things feel more stressful than running into cash flow problems. When your outflows start to outpace your inflows, it can throw your whole financial life off balance. Maybe you’re facing an unexpected expense, waiting on a late payment, or just noticing your bank balance shrinking faster than you’d like. These situations can quickly spiral if left unchecked.

Cash flow problems aren’t just a headache for business owners. Individuals and families can feel the pinch just as sharply. The good news? You don’t have to make dramatic changes to see fast improvements. Sometimes, small tweaks can make a big difference—right away. Here are five quick fixes to address common cash flow issues immediately.

1. Slash Non-Essential Spending Right Away

When cash flow problems hit, the first thing to do is trim the fat. Take a close look at your recent bank and credit card statements. Identify recurring payments and discretionary expenses that aren’t strictly necessary. Streaming subscriptions, takeout meals, and impulse online orders often add up more than you realize.

Cancel or pause anything you can live without, even if just temporarily. For example, put gym memberships on hold and swap expensive hobbies for free alternatives. Redirect that money to cover essentials. You’ll be surprised how much breathing room you can create with a few quick cancellations and spending swaps.

2. Accelerate Incoming Cash

If your cash flow problems are due to slow or irregular income, accelerating receivables can make a significant difference. If you’re self-employed or freelance, send invoices promptly and clearly outline the payment terms. Consider offering small discounts for early payments to incentivize clients.

For individuals, look for ways to generate income quickly and efficiently. Sell unused items on local marketplaces or online platforms. Take on a short-term gig or side hustle—many apps make it easy to find quick, flexible work. Even if the earnings are modest, every bit helps plug the gap when cash flow problems strike.

3. Negotiate with Creditors and Service Providers

Don’t wait for overdue notices or penalties to roll in. If cash flow problems make it hard to pay bills on time, reach out to creditors, landlords, or service providers immediately. Many companies are willing to work with you, especially if you communicate effectively early on.

Ask about payment plans, extensions, or temporary reductions. Some utility companies and lenders even offer hardship programs if you’re facing a short-term crunch. Being proactive can help you avoid late fees and protect your credit score while giving you more time to get back on track.

4. Tighten Up Your Budget—Even for Just a Month

When you’re facing cash flow problems, tracking every dollar becomes crucial. Set a bare-bones budget for the next 30 days. Focus on absolute essentials: rent or mortgage, utilities, groceries, transportation, and minimum debt payments.

Use a budgeting app or a simple spreadsheet to track your daily spending. If you’re sharing finances with a partner or family, consider holding a brief meeting to ensure everyone is on the same page. When everyone knows the plan, it’s easier to avoid unplanned expenses and keep your cash flow problems from getting worse.

5. Tap Into Emergency Funds or Credit Wisely

If you have an emergency fund, this is exactly what it’s for. Use it strategically to cover essentials and avoid high-cost borrowing. Don’t drain your savings for non-urgent expenses, but don’t hesitate to use them if you’re facing cash flow problems that threaten your ability to pay for housing, utilities, or food.

If you don’t have savings, consider a low-interest credit option as a last resort. Avoid payday loans or cash advances with high fees. Instead, look for a 0% intro APR credit card or a small personal loan from a reputable lender. Have a plan for how you’ll repay the debt, and only borrow what you truly need to bridge the gap.

Staying Ahead of Future Cash Flow Problems

Fixing cash flow problems immediately is about more than just putting out fires. The steps you take now can help you build habits and systems that prevent money stress down the road. Regularly reviewing your budget, maintaining a savings buffer, and communicating early with creditors are all habits that pay off in the long run.

Have you used any of these strategies to solve a cash flow problem? What quick fix worked best for you? Share your story or tips in the comments below!

What to Read Next…

  • 5 Emergency Repairs That Could Force You Into Debt Overnight
  • Are These 7 Little Expenses Quietly Costing You Thousands a Year?
  • 6 Monthly Bills You Should Cancel Immediately Even If You Can Afford Them
  • Are These 8 Money Saving Tricks Actually Keeping You Broke?
  • 5 Things That Instantly Decrease Your Credit Score by 50 Points
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Finance Tagged With: budgeting, Cash flow, Debt Management, emergency fund, money tips, Personal Finance

12 Unique Ways to Reward Yourself Without Destroying Savings

October 6, 2025 by Travis Campbell Leave a Comment

gift
Image source: pexels.com

Sticking to a budget can feel like a grind, especially if you never give yourself a break. Many people worry that treating themselves will undo their progress. But rewarding yourself doesn’t have to mean overspending or draining your savings. In fact, finding unique ways to reward yourself without destroying savings can help you stay motivated and make your financial journey more enjoyable. The key is to celebrate small wins in ways that feel special—without guilt or a big price tag. Here are twelve creative ideas that let you enjoy the moment and keep your savings goals on track.

1. Plan a Nature Adventure

Spending time outdoors can be incredibly rewarding and almost always free. Whether it’s a hike in a local park, a bike ride, or a day at the beach, nature offers a refreshing change of pace. Bring a homemade picnic and unplug for a few hours. You’ll return feeling recharged, and your wallet will thank you.

2. Host a Movie Night at Home

Skip the theater prices and create a cozy cinema experience in your living room. Pick a favorite movie or try something new, pop some popcorn, and dim the lights. You can even invite friends and make it a themed night. This is a fun way to reward yourself without destroying savings, and you’ll avoid the pricey snacks and tickets.

3. Try a New Recipe

Cooking a special meal at home can feel like a treat. Choose a recipe you’ve always wanted to try or recreate a restaurant dish. Not only do you get to enjoy something delicious, but you also learn a new skill. Plus, it’s much cheaper than dining out.

4. Take a Day Off Technology

Give yourself the gift of a digital detox. Turn off your phone, step away from social media, and spend the day doing something offline—read a book, take a walk, or work on a hobby. This simple act can feel like a luxury and helps you reconnect with yourself, all without spending a dime.

5. Explore Free Local Events

Check out community calendars for free concerts, art shows, or workshops in your area. Many cities offer no-cost events, especially during weekends or holidays. It’s a unique way to reward yourself without destroying savings, and you might discover something new about your community.

6. Start a Creative Project

Dive into a creative activity you’ve been putting off—whether it’s painting, writing, or crafting. Use materials you already have at home or swap supplies with friends. The joy of creating something with your own hands can be deeply satisfying and costs very little.

7. Treat Yourself to a Fancy Coffee—at Home

Instead of spending $5 on a coffee shop drink, make your own fancy beverage at home. Try a new blend, add some whipped cream, or experiment with flavors. Put it in your favorite mug and enjoy a café experience without the high price tag.

8. Swap Skills with a Friend

Everyone has a talent to share. Maybe you’re great at baking, and your friend is a yoga pro. Set up a skill swap: you teach them something, and they return the favor. It’s a fun way to learn, connect, and reward yourself without destroying savings.

9. Take a Long, Relaxing Bath

Transform your bathroom into a spa for an evening of relaxation. Light some candles, play soft music, and soak in a warm bath. Add Epsom salts or a few drops of essential oil, if available. This simple routine can melt away stress and feel luxurious, all for a few cents.

10. Download a Free Audiobook or Podcast

There’s a world of free entertainment out there. Download an audiobook from your local library’s app or find a new podcast series. Set aside time to listen with a cup of tea or during a walk. It’s a great way to reward yourself without destroying savings while expanding your mind.

11. Practice Mindful Meditation

Mindfulness doesn’t cost a thing, but the benefits are huge. Take 10–20 minutes to meditate, breathe deeply, or do some gentle stretching. Free guided meditations are available online, and this simple practice can help you reset and feel appreciated.

12. Write a Letter to Your Future Self

Sit down and write a note to yourself about your progress and what you’re proud of. Seal it in an envelope to open in a few months. This reflective exercise is a meaningful way to mark your achievements and can reinforce your commitment to not destroying savings.

Small Rewards, Big Motivation

Finding unique ways to reward yourself without destroying savings keeps your financial goals within reach while making life more enjoyable. These small acts of self-kindness help you stay on track and remind you that progress deserves recognition. By celebrating your wins thoughtfully, you reinforce good habits and make the journey to financial wellness more sustainable.

What are your favorite unique ways to reward yourself without overspending? Share your ideas in the comments below!

What to Read Next…

  • Are These 6 Helpful Budget Tips Actually Ruining Your Finances?
  • Are These 8 Money Saving Tricks Actually Keeping You Broke?
  • 10 Ways You’re Wasting Money Just Trying To Keep Up Appearances
  • 7 Tactics Grocery Stores Use To Keep You From Thinking About Price
  • 6 Monthly Bills You Should Cancel Immediately Even If You Can Afford Them
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Frugal Living Tagged With: budgeting, Financial Wellness, frugal living, money tips, Personal Finance, self-care

6 Financial Dangers of Relying on One Income

September 30, 2025 by Catherine Reed Leave a Comment

6 Financial Dangers of Relying on One Income
Image source: 123rf.com

For many households, living on a single paycheck feels manageable—until an unexpected event exposes just how risky it really is. Whether it’s by choice or circumstance, the reality is that putting all financial pressure on one stream of income leaves families vulnerable. Without a safety net, even minor disruptions can trigger major financial stress. Understanding the financial dangers of relying on one income can help families prepare better and avoid long-term setbacks. Here are six risks every household should be aware of.

1. Job Loss Creates Immediate Crisis

One of the most significant financial dangers of relying on one income is the risk of unemployment. Losing a job doesn’t just mean a temporary gap in earnings—it can completely derail a family’s budget. Expenses like rent, utilities, and groceries don’t pause just because income does. Severance packages and unemployment benefits often fall short of covering real needs. Without a second income, households face financial strain much faster than dual-income families.

2. Limited Savings and Investment Growth

When only one paycheck supports the entire household, there’s less room to set aside money for the future. Saving for retirement, emergencies, or big goals like buying a home becomes more difficult. Investments that grow wealth over time may be postponed or skipped entirely. This creates a compounding problem, as money not invested early misses out on years of growth. Reduced contributions to savings is a hidden but powerful financial danger of relying on one income.

3. Higher Risk of Debt Accumulation

Unexpected expenses can quickly push single-income families into debt. Without extra cash flow, emergencies often mean turning to credit cards or loans. Over time, interest payments make it even harder to regain stability. Medical bills, car repairs, or sudden household costs hit harder when one paycheck has to stretch. This reliance on borrowing highlights another one of the financial dangers of relying on one income.

4. Increased Stress on the Sole Earner

Relying on one person to provide financially creates emotional and physical pressure. The sole earner may feel trapped in a job they dislike, unable to take risks or pursue new opportunities. Burnout becomes more likely when all responsibility falls on one individual. Stress can affect not just finances but also health and relationships within the household. The human toll is a less visible but serious financial danger of relying on one income.

5. Limited Lifestyle Flexibility

Families often underestimate how restrictive a single income can be. Travel, education, or even small luxuries may be harder to afford without financial backup. When opportunities arise—such as moving for a better job or paying for advanced training—the lack of extra funds can hold families back. This limitation reduces long-term growth for everyone in the household. Missing out on opportunities is another financial danger of relying on one income.

6. Vulnerability to Inflation and Rising Costs

Prices for essentials like housing, food, and healthcare continue to rise, sometimes faster than wages. With only one income, households are less able to absorb these increases without making sacrifices. Even small spikes in expenses can upset a carefully balanced budget. Dual-income families often have more cushion against inflation, while single-income households struggle. Rising costs make inflation one of the sneakiest financial dangers of relying on one income.

Building Stability with Multiple Streams

The financial dangers of relying on one income are clear, but they don’t have to define your family’s future. Building stability starts with diversifying—whether through a second paycheck, side hustles, or investments that generate passive income. Creating an emergency fund, reducing debt, and budgeting strategically also provide important safeguards. Families who take steps to expand income sources give themselves more security and freedom. Ultimately, diversifying income is about protecting both money and peace of mind.

Have you experienced the financial dangers of relying on one income in your own household? Share your story and tips in the comments below.

What to Read Next…

The Financial Advice That Works—But Almost No One Follows

Why Do High Earners Still Struggle With Emergency Savings

8 Shocking Costs of Delaying Retirement

6 Silent Money Leaks in the Average Household

7 Strange Truths About Middle-Class Spending Habits

Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.

Filed Under: Personal Finance Tagged With: Debt Management, family budgeting, financial dangers of relying on one income, income security, money tips, Planning, single income risks

  • « Previous Page
  • 1
  • 2
  • 3
  • 4
  • 5
  • 6
  • …
  • 8
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • 10 Tactics for Building an Emergency Fund from Scratch by Vanessa Bermudez
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald

Copyright © 2026 · News Pro Theme on Genesis Framework