• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for money tips

You Paid the Credit Card Minimum on Time. So Why Is Your Balance Barely Moving?

September 2, 2026 by Brandon Marcus Leave a Comment

You Paid the Credit Card Minimum on Time. So Why Is Your Balance Barely Moving?
A credit card statement can reveal why a balance barely moves, including the minimum payment, interest charges, APR, and payoff estimate. Paying more than the minimum and limiting new charges can help accelerate debt repayment – Shutterstock

Paying the minimum on your credit card by the due date feels like checking an important box. It is, because making at least the minimum payment on time helps you avoid the consequences of a late payment, but it doesn’t necessarily make much progress against the balance. In fact, a surprisingly large chunk of that payment can disappear into interest before it makes much of a dent in what you actually owe.

That creates one of the most frustrating credit card experiences: the payment goes through, the account shows a nice green “paid” message, and yet the balance looks like it barely noticed. The problem usually does not involve a missing payment or some mysterious credit card trick. The minimum payment simply represents the amount required to keep the account current, not an amount designed to get the debt out of your life quickly.

The Minimum Payment Is a Floor, Not a Finish Line

Credit card companies calculate minimum payments according to the terms of the account, and the formula can include interest, a percentage of the balance, fees, or other factors. That means the minimum can remain relatively small compared with the total amount owed, particularly when the balance carries a high interest rate. Paying that amount satisfies the immediate requirement, but the remaining balance continues to generate interest according to the card’s terms.

Think of the minimum payment as the financial equivalent of keeping the engine running, not reaching the destination. It keeps the account from becoming delinquent when you make the payment on time, but it does little to accelerate the payoff. Your statement may even show how long repayment could take if you make only minimum payments and stop adding new charges, which offers a useful reality check.

Interest Can Eat More of the Payment Than Expected

Credit card interest can work on a daily basis, and many issuers calculate interest using an average daily balance or another daily balance method. So while a payment reduces what you owe, interest can continue accumulating based on the balance and the terms of the account. That creates a frustrating tug of war where the payment pushes the balance down while interest pulls part of it back up.

Consider a card carrying a balance while the cardholder makes only the minimum payment and keeps using the account for everyday purchases. The payment may reduce the balance, but new charges can replace that progress almost immediately, while interest continues to add another layer. This explains why someone can faithfully make every required payment and still feel like the debt has glued itself to the account.

New Purchases Can Undo the Progress

One of the easiest ways to make a credit card balance feel immortal involves paying it down while continuing to charge new purchases. A payment reduces the existing balance, but a grocery run, restaurant bill, streaming subscription, or unexpected repair can push the balance right back up. If the cardholder routinely charges more than the payment reduces, the account can stay stuck in roughly the same neighborhood for a very long time.

There is another wrinkle worth checking because carrying a balance can affect the card’s grace period for new purchases. With a grace period, paying the statement balance in full by the due date generally lets a cardholder avoid interest on purchases, while carrying a balance can change how interest applies under the card’s terms. Cash advances also commonly follow different interest rules, so they deserve special attention.

The Best Fix Starts With the Statement

The first useful move involves opening the actual credit card statement instead of relying on the account’s big balance number. Look for the APR, interest charge, minimum payment, statement balance, and any section showing how long repayment could take with minimum payments. Those details reveal whether interest, new spending, fees, or a combination of them keeps the balance from falling faster.

Then pick a payment amount that goes beyond the minimum whenever the budget allows, while avoiding new charges that recreate the balance. Even paying earlier in the billing cycle can reduce interest in situations where the issuer calculates interest using daily balances, although the exact effect depends on the card’s terms. If several balances carry different APRs, check the payment-allocation rules because amounts paid above the minimum generally go first toward the highest-interest balance.

A Tiny Payment Can Become a Very Long Relationship

There is nothing wrong with making the minimum payment when money is tight, especially because keeping payments current matters. The trouble starts when the minimum becomes the permanent strategy rather than a temporary safety net. A credit card company can consider the account current while the borrower watches the balance crawl downward at a pace that feels almost comically slow.

That makes the statement’s payoff information one of the most useful tools on the page. It can show the difference between making only the minimum and paying a larger amount toward the existing balance, assuming no additional charges. The goal does not require heroic payments or an overnight debt makeover, but every extra dollar directed toward principal can shorten the road ahead and reduce the interest paid along the way.

Make the Minimum the Backup Plan, Not the Strategy

A credit card minimum payment does exactly what its name promises, and that distinction matters. It keeps the account current when paid on time, but it does not promise rapid debt reduction, low interest costs, or a quick escape from the balance. When interest continues accumulating and new purchases keep landing on the account, even consistent minimum payments can produce painfully little visible progress.

The smartest next step involves studying the statement, stopping unnecessary new charges, and increasing the payment whenever the household budget can handle it. If the balance still refuses to move despite payments and little new spending, check the interest charges, fees, promotional terms, and individual APR categories for clues. The minimum payment keeps the door from slamming shut, but paying more is what starts moving the furniture out of the room.

What has been the biggest surprise about paying down a credit card balance, and what strategy has actually helped make the number fall?

You May Also Like…

3 in 10 Americans Owe More on Credit Cards Than They’ve Saved — Here’s Which to Tackle First

6 Purchases Financial Experts Say You Shouldn’t Put on a Credit Card

You Can Afford the Car Payment. Can You Afford the Car?

IRS Proposes New Eligibility Rules for Refundable Payments From 4 Tax Credits

What to Do After Receiving a Social Security Overpayment Notice

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: credit cards Tagged With: Credit card debt, credit cards, debt payoff, interest charges, minimum payments, money tips, Personal Finance

7 Things to Do With an Unexpected $1,000, Ranked From Smartest to Riskiest

August 14, 2026 by Brandon Marcus Leave a Comment

7 Things to Do With an Unexpected $1,000, Ranked From Smartest to Riskiest
An unexpected $1,000 can strengthen an emergency fund, reduce high-interest debt, support long-term investing, cover a necessary purchase, or fund a carefully planned splurge. The riskiest move involves chasing fast profits without accepting the possibility of losing the money – Shutterstock

An unexpected $1,000 can feel like a tiny financial lottery win, but what happens next matters more than the excitement. The smartest move usually does not involve buying something shiny, booking a spontaneous trip, or turning the money into a pile of scratch tickets.

That thousand dollars can instead become a financial pressure valve, a debt killer, an investment, or a very expensive lesson. Here are seven ways to use it, ranked from the smartest choices to the riskiest, with one simple goal: make that surprise money improve life instead of disappearing mysteriously by next Tuesday.

1. Build or Strengthen an Emergency Fund

If an emergency fund has a glaring hole, putting the entire $1,000 into savings usually ranks as the strongest move. An emergency fund can cover unpleasant surprises such as a major car repair, urgent home expense, insurance deductible, or sudden income disruption without forcing a credit card into the conversation.

Keep the money somewhere safe and accessible, such as a federally insured savings account at a bank or an eligible deposit account at a credit union. The goal does not involve earning bragging-rights returns, because emergency money needs reliability more than excitement. A separate savings account can also create enough friction to prevent casual spending. When the next financial curveball arrives, that $1,000 can turn a crisis into an inconvenience.

2. Pay Down High-Interest Debt

High-interest credit card debt can quietly eat through money faster than most people realize. Using an unexpected $1,000 against a costly balance can reduce future interest charges while giving the monthly budget some breathing room.

This move works especially well when the debt carries a high variable interest rate and the borrower already has enough cash to handle small emergencies. Paying down a balance also creates a psychological win because the money produces an immediate financial result instead of sitting somewhere as an abstract future benefit. However, draining every dollar of savings to attack debt can create a nasty rebound if an emergency arrives next month. A balanced approach might split the windfall between a starter emergency fund and debt repayment.

3. Invest for a Long-Term Goal

Once immediate financial fires have gone out, investing can give that $1,000 a much longer job description. A diversified investment portfolio can include broad-market index funds or other investments that match the investor’s time horizon, risk tolerance, and overall plan.

The important word here involves long-term, because investments can lose value, sometimes dramatically, over shorter periods. Money needed for rent, tuition, next month’s mortgage payment, or an upcoming car purchase does not belong in a stock-heavy portfolio simply because the market has produced attractive returns in the past. A tax-advantaged account may also offer useful benefits depending on the person’s circumstances and available contribution room. The best investment choice starts with the purpose of the money, not with whichever financial product currently gets the loudest internet hype.

4. Fund a Necessary Purchase You Already Planned

Sometimes the smartest financial move looks suspiciously like spending money. If a person already needs new tires, a reliable appliance, professional equipment, or another necessary item, an unexpected $1,000 can eliminate the need to borrow for that purchase.

This strategy works because it replaces future financial strain with cash already sitting in the account. It also avoids the classic windfall mistake of inventing a new purchase simply because extra money appeared. Before spending, compare prices, warranties, repair options, and total ownership costs rather than grabbing the first convenient option. A planned expense can make excellent use of unexpected money when it solves a genuine need without creating a new monthly payment.

5. Spend It on Something That Saves Money Later

A carefully chosen expense can also reduce future costs, which makes this category more interesting than a simple shopping spree. Energy-efficient equipment, preventive home maintenance, useful work tools, or services that eliminate recurring expenses can sometimes turn a one-time payment into ongoing savings.

The trick involves doing the math before reaching for the wallet. A fancy gadget does not become an investment merely because someone calls it one in an advertisement. Look at the actual purchase price, expected savings, maintenance costs, and how long the item should remain useful. If the numbers make sense and the purchase addresses a real need, the $1,000 can pull double duty.

6. Put It Toward a Fun Goal

Money does not exist solely to sit in an account and glare sternly at every unnecessary purchase. Using some or all of an unexpected $1,000 for a meaningful experience, hobby, celebration, or personal goal can make sense when the rest of the financial picture remains stable.

The danger appears when “fun money” quietly transforms into “whatever looks good online.” A defined spending limit can keep the windfall enjoyable without letting the entire amount evaporate through dinners, gadgets, subscriptions, and impulse purchases. Consider setting aside a portion for enjoyment while directing the remainder toward savings or debt. That approach gives the money a job without turning personal finance into a joyless spreadsheet prison.

7. Chase a Quick Profit

At the bottom of the ranking sits the temptation to turn $1,000 into $2,000 quickly. That might mean speculative trading, betting on a hot investment, chasing cryptocurrency price swings, or putting the money into an unfamiliar business opportunity promising unusually fast returns.

Risk does not automatically make an investment bad, but risk without a clear plan can make a windfall disappear remarkably fast. Promises of guaranteed profits, pressure to act immediately, secret strategies, and requests to send money through unusual payment methods should trigger serious skepticism. Anyone considering a speculative move should assume the possibility of losing the money entirely and never risk cash needed for essential expenses. A surprise $1,000 deserves better than becoming tuition for a lesson that a few minutes of research could have prevented.

Give That $1,000 a Job Before It Finds One

The best use for an unexpected $1,000 depends on the financial situation surrounding it, not on a universal rule carved into a money-management tablet. Someone carrying expensive debt faces a different decision from someone with a healthy emergency fund, steady income, and a long investing horizon.

The biggest mistake involves treating unexpected money as money without a purpose. Give the cash a specific assignment before spending begins, whether that means building financial security, reducing debt, investing for the future, handling a necessary purchase, or enjoying a carefully chosen treat. A $1,000 windfall can vanish quickly, but it can also become the start of something much more valuable.

Which of these seven moves would you make with an unexpected $1,000, and why?

You May Also Like…

6 End-of-Summer Money Tasks That Can Prevent a Costly Year-End Rush

4 Personal Finance Moves People Are Making Right Now Before Interest Rates Shift Again

HSA & FSA Increases Mean Tax-Free Savings—But You Must Plan Ahead

9 Investing Assumptions That Fail When Markets Stay Flat for Years

Bank Teller Warning: Here’s When It Actually Makes Sense to Pull From Your Savings

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Personal Finance Tagged With: budgeting, Debt, emergency fund, investing, money tips, Personal Finance, saving money, windfall

Halfway Through 2026: The Money Moves to Make Before the December 31 Deadline

June 25, 2026 by Brandon Marcus Leave a Comment

Halfway Through 2026: The Money Moves to Make Before the December 31 Deadline
Midyear 2026 brings higher 401(k) and IRA contribution limits, giving savers more room to grow retirement funds before the December 31 deadline approaches – Shutterstock

Halfway through 2026, financial choices feel more urgent as deadlines approach faster than expected. Many savers overlook retirement contribution limits until the final weeks of the year, when opportunities become harder to maximize. The IRS has already confirmed updated contribution limits that shape how much money can move into tax-advantaged accounts before December 31.

These updates directly affect both workplace retirement plans and individual retirement accounts in a way that rewards early planning. Acting before the year closes can help align contributions with long-term savings goals while avoiding last-minute financial stress. The window to adjust strategies remains open right now, but it will not stay that way forever. So, before it’s too late, here are several money moves you need to make before the year is over.

401(k) Shift for 2026 Savers

The 401(k) contribution limit increased to $24,500 for 2026, creating more room for pre-tax or Roth savings inside workplace plans. This change matters for employees who rely on payroll deductions to steadily build retirement security. Higher limits also give high earners a chance to shelter more income before taxes reduce take-home pay.

Employers may adjust payroll systems, but individuals still need to choose contribution percentages that match their goals. Reviewing contribution rates before the final quarter helps prevent missed opportunities that cannot be recovered later. Small percentage changes early in the year can quietly reshape long-term retirement outcomes.

IRA Contributions Offer Another Layer of Opportunity

The IRA contribution limit rose to $7,500 for 2026, expanding access to tax-advantaged savings outside workplace plans. This increase supports both traditional and Roth IRA strategies, depending on income level and tax planning goals. Many savers use IRAs to supplement employer-sponsored plans or to maintain retirement contributions during job changes.

Contribution timing matters because IRA deposits must be completed before the tax deadline to count for the year. Planning ahead ensures contributions land on time and align with broader retirement strategies without last-minute pressure. Staying proactive with IRA funding helps avoid rushed decisions that can reduce overall savings efficiency.

Strategic Money Moves Before December 31 Arrives

The months leading to December 31 often determine whether savers fully capture available retirement benefits for the year. Adjusting contribution percentages early allows payroll systems to spread savings more smoothly across remaining pay periods. Coordinating IRA deposits alongside 401(k) contributions helps balance tax advantages across multiple accounts.

Reviewing budgets at midyear helps identify extra cash flow that can boost retirement savings without disrupting essentials. Small adjustments made now often outperform larger, rushed contributions made during the final weeks of the year. Consistent contributions also reduce the emotional pressure that often comes with year-end financial decisions.

Why Midyear Action Changes Year-End Outcomes

Midyear creates a powerful window for aligning retirement contributions with updated IRS limits before the calendar year closes. The combination of higher 401(k) and IRA limits gives savers more flexibility to build long-term financial strength. These adjustments work best when implemented gradually instead of waiting until deadlines force quick decisions.

Waiting until December often limits options and increases the risk of missed contributions. Early action keeps retirement planning steady, intentional, and less reactive to end-of-year pressure. Financial momentum builds most effectively when decisions happen before deadlines tighten and choices shrink.

The Year-End Advantage Belongs to Early Movers

Retirement planning in 2026 rewards those who act while time still feels abundant rather than scarce. The updated $24,500 401(k) limit and $7,500 IRA limit create expanded opportunities that work best with steady contribution habits. Savers who adjust early gain more control over taxes, cash flow, and long-term growth without scrambling near deadlines.

End-of-year financial success rarely comes from last-minute effort alone, but from consistent decisions made throughout the year. Midyear offers a natural checkpoint to recalibrate and strengthen retirement strategy before the final stretch begins. Those who move now set up a smoother path toward December 31 without the usual pressure and uncertainty.

What changes could make retirement saving feel easier for you before the year ends, and which small adjustment could you start today? Let’s chat about it below.

You May Also Like…

The 2026 401(k) Limit Is $24,500: 6 Ways Workers Can Use the Higher Cap Before Year-End

5 Reasons Your 401(k) Could Trigger a Tax Surprise Next Year

Early Claimers Are Locked Into a Permanently Reduced Benefit — Even After Full Retirement Age

Original Medicare vs. Advantage: More Retirees Are Switching Back — And Here’s Why

The Retirement Confidence Drop: Why More Americans Say They’re Less Prepared Than They Were a Year Ago

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Retirement Tagged With: 401k 2026, IRA contributions, IRS updates, money tips, Personal Finance, retirement planning, savings strategy, tax planning

Unclaimed Refunds Expire After 3 Years — Billions Go Unrecovered Every Summer

June 8, 2026 by Brandon Marcus Leave a Comment

Unclaimed Refunds Expire After 3 Years — Billions Go Unrecovered Every Summer
Tax refund deadlines can erase unclaimed money after three years, leaving billions uncollected each summer. Regular checks and timely filings help ensure taxpayers recover every dollar owed to them. Shutterstock

Unclaimed refunds sound harmless at first, but they quietly drain billions of dollars from taxpayers every year. Governments across North America place strict time limits on claiming tax refunds, and most people never realize the clock even starts ticking. Once that deadline passes, the money does not wait around and instead flows back into government accounts.

Every summer, agencies report large piles of unclaimed funds sitting untouched because taxpayers miss simple filing windows. This creates a surprising financial gap where money belongs to individuals but never reaches their pockets. The rules stay simple, but the consequences hit harder than most expect.

Why Refunds Disappear After Three Years

Tax agencies enforce a three-year limit to keep systems organized and financially balanced. The IRS follows strict timelines that cut off refund claims after the deadline passes. This rule ensures that governments close older tax years and prevent endless reopenings of past records. Once the window closes, the money officially loses its claim status and returns to public funds. That means taxpayers who delay filing or forget paperwork risk losing real cash with no exceptions.

Many people assume refunds automatically arrive, but systems only release funds when someone files correctly and on time. Life events like moving, changing jobs, or switching banks often interrupt the process and cause missed filings. Some taxpayers also skip filing when they believe they owe nothing, which accidentally blocks their refund eligibility. The three-year clock does not pause for confusion or personal circumstances, so timing matters more than most realize. Once that deadline hits, recovery becomes impossible, even with proof of overpayment.

How Billions Slip Through the Cracks Every Year

Every year, tax authorities report billions in unclaimed refunds sitting in government accounts. Many of these refunds belong to low-income workers, students, and part-time employees who file inconsistently. Seasonal workers often move between jobs and forget to submit old tax returns, which adds to the growing pool of unclaimed money. Some individuals also assume small refunds do not matter, so they skip filing altogether and lose the chance to collect later. Over time, these small amounts add up into massive totals that never reach their rightful owners.

Government reports show that simple administrative delays cause a large portion of these losses. People who change addresses without updating tax records often miss important notices and refund updates. Others fail to track multiple income slips from different employers, which leads to incomplete filings. Even digital filing systems cannot fix missing information when taxpayers do not initiate claims. This gap between eligibility and action creates one of the most overlooked financial leaks in the system.

How to Check for Missing Refunds Before Time Runs Out

Tax agencies offer online portals that allow users to check refund status quickly and securely. The CRA My Account and IRS “Where’s My Refund” tools help taxpayers track past filings and identify unclaimed balances. These platforms also display previous tax years, which makes it easier to spot missing refunds before deadlines expire. Regular checks prevent money from slipping away unnoticed, especially for people with changing income sources. A few minutes of review each year can protect hundreds or even thousands of dollars.

Professional tax preparers also help identify forgotten refunds from earlier years. Many accountants run retroactive checks that reveal overlooked credits or missed deductions. This process often uncovers refunds that taxpayers never realized existed. Filing amended returns within the allowed window keeps money within reach and avoids permanent loss. Consistent review habits create a strong defense against expired claims.

Simple Habits That Protect Refund Money Long-Term

Organized recordkeeping plays a major role in preventing lost refunds. Keeping digital copies of tax slips, employment records, and previous filings ensures easy access when needed. People who store documents in secure cloud folders reduce the risk of losing important financial information. This habit also speeds up future filings and reduces errors that delay refunds. A strong organization builds a safety net that protects money year after year.

Setting annual reminders before tax season helps keep refund timelines on track. Many taxpayers use calendar alerts to review previous filings and confirm accuracy. This simple step prevents missed deadlines and encourages early action on corrections. Families who coordinate tax reviews together often catch mistakes faster and recover more money. Small routines like these turn into powerful financial habits over time.

The Deadline That Decides Whether Money Comes Back or Disappears

The three-year refund rule creates a strict cutoff that leaves no room for extensions or appeals. Once the deadline passes, even strong documentation cannot reopen the claim. This policy makes timing just as important as accuracy when it comes to tax filing. Millions of dollars disappear each year simply because people delay action or forget to file. Awareness of this rule changes how taxpayers approach every filing season.

Financial experts continue to stress the importance of early review and consistent filing habits. People who act quickly increase their chances of recovering every dollar owed to them. Governments enforce deadlines to maintain system efficiency, but individuals hold full responsibility for claiming their refunds. The difference between collecting and losing money often comes down to a simple calendar check. Staying proactive keeps refunds where they belong—in taxpayers’ hands.

What habits help keep tax refunds on track, and how often should people check for missing money?

You May Also Like…

Gig Workers Who Didn’t Set Aside Taxes Last Summer Are Facing Bills Right Now

Tennessee Residents Still Pay Federal Taxes on Investment Income Despite State Changes

South Carolina Newcomers Are Paying Higher Property Taxes Until Homestead Eligibility Kicks In

New IRS Matching Technology Is Catching Income Discrepancies That Used to Slip Through

Cryptocurrency Owners Are Getting IRS Letters — Even for Small Trades

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: tax tips Tagged With: CRA, financial advice, IRS, money tips, Personal Finance, savings, tax deadlines, tax refunds, unclaimed refunds

Joint Filers Are Losing Refunds Over One Spouse’s Debt — Without Prior Warning

June 5, 2026 by Brandon Marcus Leave a Comment

Joint Filers Are Losing Refunds Over One Spouse's Debt — Without Prior Warning
Joint filers can lose an entire tax refund when one spouse’s debt triggers an IRS offset, often without advance notice, making early debt checks and strategic filing decisions essential for protecting household finances. Shutterstock

Tax season often brings hope for a refund, but joint filers now face an unexpected financial shock that catches many couples off guard. One spouse’s old debt can suddenly drain an entire refund before it ever hits a bank account. The IRS does not always send clear warnings before redirecting the money, which leaves couples scrambling for answers.

This issue affects everyday households, not just high-income earners or complex tax situations. Understanding how this process works helps prevent frustration and financial strain when filing jointly.

How One Spouse’s Debt Can Hijack a Joint Refund

Couples often choose joint filing to unlock tax benefits and simplify their paperwork, but this choice also ties both spouses to each other’s financial obligations. When one spouse owes back taxes, child support, or certain federal student loans, the Treasury Offset Program can step in. That program intercepts refunds and applies them directly to the debt without splitting responsibility. Many couples only discover the offset after checking their refund status and seeing a reduced or zero payout. This surprise creates tension because both partners expect equal access to the refund.

The IRS treats a joint refund as a single combined payment, not two separate shares, which creates complications when debt enters the picture. Even if only one spouse created the debt, the system can still apply the entire refund toward it. Some relief options exist, such as Innocent Spouse Relief, but those require separate filings and strict qualifications. Couples often miss these options because they do not receive clear upfront guidance during tax preparation. This structure leaves many families feeling blindsided during what should feel like a straightforward process.

Why the IRS Rarely Gives Advance Notice of Offsets

The IRS does not directly control all refund offsets, which surprises many taxpayers during filing season. Instead, other federal and state agencies notify the Treasury Offset Program when debts qualify for collection. Once that notification enters the system, the refund can get reduced or fully seized before any direct alert reaches the couple. This timing gap creates confusion because taxpayers often see the adjustment only after checking refund tools online. The lack of proactive communication makes the process feel abrupt and unpredictable.

Government agencies prioritize debt collection efficiency, which means refunds move quickly once flagged for offset. Notices often go to the debtor’s last known address, which may not reflect current living situations or shared household updates. Couples filing jointly rarely receive a combined warning that clearly explains the full impact on their refund. This communication gap leads to misunderstandings between spouses when money disappears unexpectedly. Financial experts often recommend checking debt status early in the tax season to reduce surprises.

Smart Ways Couples Can Protect Their Refund Before Filing

Couples can reduce risk by reviewing outstanding federal and state debts before submitting a joint tax return. Checking student loan status, unpaid taxes, and child support obligations helps reveal potential offsets early. Tax professionals often recommend using the IRS “Where’s My Refund” tool alongside the Treasury Offset Program contact line for added clarity. Couples who communicate openly about financial obligations often avoid last-minute shocks during refund season. Awareness creates more control over how and when a refund gets applied.

Filing separately sometimes helps protect one spouse’s portion of a refund, depending on income and deduction differences. However, separate filing can also reduce certain tax benefits, so couples need to weigh both outcomes carefully. Some spouses qualify for partial relief through IRS Form 8379, which helps injured spouses recover their share of a joint refund. Filing this form early improves the chance of receiving at least part of the refund back. Strategic planning before tax season often makes the biggest difference in avoiding financial loss.

What This Means for Joint Filers Moving Forward

Joint filing continues to offer tax advantages, but it also increases exposure to shared financial risks that many couples underestimate. One spouse’s debt can override expectations and reshape a household budget in seconds once the IRS processes an offset. Families who treat tax filing as a shared financial checkpoint often reduce surprises and improve long-term planning. Clear communication about debt and refund expectations strengthens financial stability during tax season. Couples who stay proactive gain more control over how their money moves through the system.

This issue highlights how important financial transparency becomes in shared tax decisions, especially when debts exist in either spouse’s name. Couples who ignore potential liabilities often face sudden disruptions that affect bills, savings, or planned expenses. Understanding how offsets work helps households prepare instead of reacting after money disappears. Tax season rewards preparation, not guesswork, and informed filers protect more of their refund. Staying alert to these rules keeps financial surprises from turning into financial setbacks.

What steps should couples take before filing jointly to avoid refund surprises like these?

You May Also Like…

Your Refund Could Be Redirected to State Debt Without a Single Notice From the IRS

Colorado TABOR Refunds Are Reduced When Residents Owe State Debts

Joint Tax Liability Rules Mean Spouses Can Still Owe Shared Tax Debts

11 Social Security Surprises That Hit You After Losing a Spouse

23% of Americans With Credit Card Debt Don’t Believe They’ll Ever Pay It Off

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Debt Management Tagged With: debt collection, IRS, joint filing, money tips, Planning, student loans, tax refunds, tax season, taxes

Smaller Refunds Are Hitting Filers Who Made One Specific Change Last Year

June 4, 2026 by Brandon Marcus Leave a Comment

Smaller Refunds Are Hitting Filers Who Made One Specific Change Last Year
Many taxpayers see smaller refunds after adjusting their W-4 withholding, even though they received more money in each paycheck throughout the year. Shutterstock

Tax season keeps surprising millions of filers, and this year delivers a particularly frustrating twist for many households expecting a comfortable refund. Many taxpayers open their results only to find a much smaller number than they planned for, and the shock often traces back to a single decision made last year. That decision usually involves how income tax withholding got set up or adjusted on a W-4 form, especially after people tried to fine-tune their take-home pay. A small shift in how employers pull taxes throughout the year can dramatically change what shows up at refund time. As a result, more money may have stayed in paychecks during the year, leaving less available when filing season arrives.

This situation creates confusion because many people assume refunds represent “bonus money” from the government rather than a reconciliation of taxes already paid. When withholding changes, the timing of tax payments shifts instead of the total tax bill necessarily changing.

One Small W-4 Change That Quietly Reshaped Refunds

Many workers adjusted their W-4 forms last year after trying to improve their monthly cash flow, especially during periods of rising costs. That adjustment often involved claiming different allowances, updating dependents, or increasing take-home pay by reducing withheld tax per paycheck. Employers then followed those instructions precisely, sending less money to the IRS throughout the year. That decision created a more even paycheck experience but also reduced the buffer that often generates large refunds.

When tax season arrives, the IRS calculates total tax liability and compares it to what has already been paid through withholding. A smaller refund often signals that withholding aligned more closely with actual tax owed instead of overpaying throughout the year. This shift does not necessarily create a penalty or loss, but it does change expectations built around previous refund patterns. Many filers feel surprised because they remember larger refunds as the norm rather than the result of over-withholding.

Why Refund Shrinks Feel Bigger Than They Actually Are

Refund reductions often trigger stronger emotional reactions than they logically deserve because people tend to anchor expectations around past years. A $2,000 refund feels comfortable, while a $600 refund feels like something went wrong, even when the total annual tax liability stayed identical. Behavioral finance explains this reaction through loss perception, where missing expected money feels more painful than never receiving it at all. That mindset makes smaller refunds feel like setbacks instead of neutral adjustments.

Another factor comes from household budgeting habits that rely on refund timing for major expenses. Many families plan vacations, debt payments, or large purchases around expected refund amounts. When that refund shrinks, the entire financial plan can feel disrupted even if the monthly income stayed more stable throughout the year. This disconnect highlights how withholding decisions shape not just tax outcomes but also spending psychology.

How Payroll Adjustments Shifted Cash Flow All Year Long

Changes to withholding do not operate in isolation because they directly affect paycheck size every pay period. When workers adjust their W-4 to reduce taxes withheld, they receive more money throughout the year instead of waiting for a lump sum refund. That approach improves liquidity for day-to-day expenses and helps manage inflation-driven costs more comfortably. However, it also reduces the likelihood of a large refund at filing time.

This trade-off confuses many filers because they compare last year’s refund number without comparing monthly income changes. A smaller refund often pairs with higher take-home pay across twelve months, which can actually improve overall cash flow stability. The key issue arises when people focus only on tax season instead of tracking yearly totals. Once the full picture becomes clear, the refund drop looks less like a loss and more like a redistribution of timing.

What This Refund Shift Really Signals About Tax Planning

Smaller refunds often signal a shift toward more accurate tax planning rather than a problem with filing or income. The IRS prefers withholding accuracy because it reduces the chance of large refunds or unexpected tax bills. Filers benefit when paycheck deductions match real tax liability more closely, even if the psychological comfort of a big refund disappears. This balance represents a more efficient system, even if it feels less exciting in April.

Tax refunds may feel smaller this year, but the story behind them often points to one simple truth: money already flowed differently throughout the year. Once filers connect paycheck changes to refund outcomes, the numbers start to make a lot more sense, and less stress follows.

What changes have you noticed in your tax refunds this year, and how have those shifts affected your budgeting plans?

You May Also Like…

Tennessee Residents Still Pay Federal Taxes on Investment Income Despite State Changes

Selling a Long-Term Home Can Lead to Capital Gains Taxes—Even for Retirees

Refunds Are Being Frozen Over a New IRS Identity Flag — And It’s Happening to More Filers Than Ever

Tax Strategies for Creative Professionals: Maximizing Returns and Minimizing Liabilities

Texas Has No Income Tax — But Property Taxes Can Get Close To 2% in Some Areas

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: tax tips Tagged With: budgeting, IRS, money tips, Personal Finance, Planning, tax refunds, tax season, taxes, W-4, withholding

Side Hustle Income From Last Summer Is Catching Up With Filers Right Now

June 3, 2026 by Brandon Marcus Leave a Comment

Side Hustle Income From Last Summer Is Catching Up With Filers Right Now
Side hustle earnings from last summer now appear on official tax forms, catching many filers off guard as gig platforms and freelance apps finalize income reports that reshape tax season outcomes. Shutterstock

Last summer’s extra income is finally showing up in a big way, and tax filers feel the impact right now. Gig apps, freelance platforms, and payment services now report earnings that many people forgot or underestimated. That forgotten weekend delivery shift or casual freelance project suddenly looks very real on official tax documents. Tax forms arrive late, corrected, or consolidated, which creates confusion during filing season. Many filers now scramble to match their records with what companies already sent to the IRS.

The timing hits hard because many people have already spent that money months ago. Side hustle income often blends into everyday spending, which makes tracking harder than expected. Platforms like delivery apps, online marketplaces, and payment processors now share more detailed reports than ever before. These reports do not wait for convenience; they arrive when companies finalize compliance schedules.

Why Last Summer’s Side Hustle Cash Shows Up Months Later

Tax documents rarely arrive in real time, which creates a gap between earning money and reporting it. Companies like gig platforms finalize annual totals only after reviewing refunds, adjustments, and transaction disputes. That process pushes many side hustle earnings into late winter or early spring tax paperwork. Filers then discover income they barely tracked during the busy summer months. The delay creates a mismatch between memory and official records.

This gap grows wider when workers use multiple apps at the same time. One person might drive for a rideshare service, sell items online, and complete freelance tasks across different platforms. Each platform sends separate tax forms, which often arrive at different times. Filers then piece together a financial puzzle with missing edges. That scattered reporting system turns last summer’s hustle into this season’s tax headache.

The Surprises Filers Keep Running Into

Many filers now notice income totals that exceed their expectations, especially from small, repeated gigs. A few dollars per delivery or quick freelance job adds up faster than most people realize. Tax forms consolidate these small payments into one large number, which shocks people who never tracked totals closely. Some filers even forget about dormant accounts that still generate income. That combination creates sudden spikes in reported earnings.

Another surprise comes from missing or incomplete expense tracking. Many side hustlers forget to log mileage, supplies, or platform fees during busy work periods. Without those deductions, taxable income looks much higher than reality. Tax rules allow deductions in many cases, but only when records exist to support them. This gap pushes some filers into higher tax brackets or larger tax bills than expected.

Smart Moves That Help Clean Up Side Hustle Tax Issues

Strong recordkeeping now plays a major role in fixing side hustle tax confusion. Filers who organize receipts, mileage logs, and platform statements can quickly match official documents with real earnings. That clarity reduces stress and helps identify errors before filing deadlines. Many people now use budgeting apps or spreadsheets to reconstruct last summer’s activity. That habit turns chaos into a clear financial snapshot.

Some filers also need to amend returns when income mismatches appear. The IRS allows corrections, but filers must act quickly to reduce penalties or interest. Accurate reporting protects against audits and avoids long-term complications. Tax professionals often recommend reviewing all 1099 forms before submitting final returns. That extra review step prevents small mistakes from turning into expensive problems.

What This Wave of Side Hustle Income Really Signals

This situation shows how fast the gig economy reshapes personal finances. Side income no longer stays “extra” in a casual sense because tax systems now track it closely. Platforms report more detailed earnings data every year, which increases transparency for both filers and tax agencies. That shift forces people to treat side income with the same attention as regular wages. Financial habits now matter more than ever in this environment.

The growing visibility of side hustle income also highlights the importance of year-round planning. People who track earnings monthly avoid the shock that arrives during tax season. Small habits like saving a portion of each payout create smoother financial outcomes later. The system no longer hides extra income in the background, so awareness becomes a financial advantage. Anyone earning extra money now benefits from staying organized before tax forms arrive.

Side hustle income from last summer continues to surface in unexpected ways, and that trend shows no sign of slowing down. Filers who stay proactive now avoid stress later and keep more control over their financial outcomes.

What strategies help manage side hustle income more effectively during tax season, and how do different platforms change the way people track earnings?

You May Also Like…

The IRS Is Cracking Down on Side Hustle Income Again in 2026

Millions of Gig Workers May Be Missing This Key IRS Requirement

8 Financial Changes Coming Before July That Could Affect Retirees on Fixed Incomes

IRS Will Freeze Your Refund Without Correct Bank Info—And Won’t Send a Paper Check Until You Fix It

Generate Extra Monthly Cash Flow Starting With These Side Hustle Ideas

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Career Tagged With: 1099, freelance income, gig economy, IRS, money tips, Personal Finance, side hustle, tax filing, taxes

The Retirement Confidence Drop: Why More Americans Say They’re Less Prepared Than They Were a Year Ago

May 31, 2026 by Brandon Marcus Leave a Comment

The Retirement Confidence Drop: Why More Americans Say They’re Less Prepared Than They Were a Year Ago
Seniors used to feel confident about retiring soon, so what changed? – Shutterstock

Retirement expectations across the country continue to shift in a surprising direction, and the mood feels noticeably less optimistic than just a year ago. Rising living costs, volatile markets, and uncertainty around long-term benefits have pushed many households to rethink their financial future in real time. A growing number of workers now report feeling less prepared for retirement, even if they actively saved during previous years. That change signals more than just anxiety; it reflects real pressure on everyday budgets that leave less room for long-term planning. Financial confidence no longer grows automatically with age, and that shift creates ripple effects across generations.

This growing unease also shows up in conversations at kitchen tables, office break rooms, and financial planning meetings. Many people describe a gap between what they expected retirement to look like and what current savings actually support. Younger workers worry about starting too late, while older workers question whether they saved enough during peak earning years. The idea of a “comfortable retirement” feels less certain when prices for housing, healthcare, and essentials continue climbing. That tension now defines the retirement conversation in ways that feel both personal and widespread.

Why Retirement Confidence Keeps Sliding Downward

Retirement confidence drops because financial pressure hits households from multiple directions at the same time. Inflation pushes up grocery bills, rent, utilities, and insurance costs, which reduces the money available for retirement contributions. Stock market swings also shake confidence, especially for people who rely heavily on 401(k) or IRA balances to build long-term security. Workers see account balances rise and fall quickly, which makes long-term planning feel unpredictable. That constant uncertainty weakens confidence even when people continue contributing regularly.

Job stability also plays a major role in retirement expectations. Many workers now switch jobs more frequently, which disrupts consistent retirement contributions and employer matching programs. Some people cash out retirement accounts during job changes, which creates long-term setbacks that feel hard to recover from later. Economic shifts also affect wages, and stagnant paychecks limit the ability to increase savings rates. These combined factors create a steady erosion of confidence that builds quietly over time rather than through one single event.

Inflation and Healthcare Costs Create a Double Squeeze

Inflation continues to reshape retirement planning because it hits both current expenses and future projections at the same time. Everyday costs rise faster than many retirement models anticipated, which forces households to rethink how far their savings will actually stretch. Even small increases in rent or mortgage payments can reduce monthly savings contributions significantly. That pressure forces many people to delay retirement targets or reduce expectations for lifestyle spending later in life. Financial planners now stress that inflation does not just affect today’s budget; it reshapes decades of future planning.

Healthcare costs add another layer of stress that many retirees underestimate until later in life. Medical expenses often rise faster than general inflation, especially for individuals nearing retirement age. Prescription costs, long-term care, and insurance premiums create unpredictable financial burdens that eat into fixed incomes. Many people now plan for healthcare as one of the largest retirement expenses rather than a secondary concern. That shift forces households to save more aggressively, even when current budgets already feel tight.

The Retirement Confidence Drop: Why More Americans Say They’re Less Prepared Than They Were a Year Ago
The rising costs of healthcare are eating into retirement confidence among seniors – Shutterstock

Everyday Money Habits That Quietly Undermine Retirement Plans

Small financial habits often create large long-term consequences for retirement readiness. Many people prioritize short-term spending goals like travel, upgrades, or lifestyle improvements while delaying consistent retirement contributions. Credit card debt also drains monthly income through interest payments that reduce savings capacity. Even modest debt balances can slow retirement progress significantly when they persist for years. These patterns do not always feel dangerous in the moment, but they compound over decades.

Behavioral patterns around savings also shape long-term outcomes more than many realize. Some workers increase contributions only after pay raises, while others leave contribution rates unchanged for years despite higher earnings. Many people also underestimate how long retirement may last, especially with life expectancy increasing. That miscalculation leads to savings targets that fall short of actual needs. Strong retirement planning requires consistent adjustments, not one-time decisions made early in a career.

How Workers Can Rebuild Retirement Confidence Without Panic

Retirement confidence improves when workers break long-term goals into smaller, actionable steps. Increasing contributions by even one or two percent can create meaningful growth over time without drastically affecting take-home pay. Automating savings also removes emotional decision-making, which helps people stay consistent during uncertain economic periods. Diversifying investments across different asset classes can reduce the impact of market volatility. These strategies help rebuild a sense of control even when broader economic conditions feel unpredictable.

Planning also improves when individuals regularly reassess retirement timelines and adjust expectations realistically. Many financial advisors encourage annual check-ins that compare current savings with projected needs based on updated expenses. Delaying retirement by a few years can also significantly increase financial stability for some households. Working longer part-time or transitioning into phased retirement options can extend income while reducing stress on savings. These approaches give people more flexibility and reduce the pressure of a single fixed retirement date.

How To Solve Falling Retirement Confidence

Retirement confidence declines because financial reality now shifts faster than long-term plans can adapt. Inflation, healthcare costs, job changes, and behavioral habits all stack together and reshape expectations in real time. Many households feel the gap between savings and future needs widening, even when they actively contribute to retirement accounts. That gap creates stress, but it also highlights the importance of adjusting strategies early rather than late. Financial stability depends less on perfect timing and more on consistent, informed decisions across decades.

What steps feel most realistic for rebuilding retirement confidence in today’s economy, and which challenges feel the hardest to overcome? Share thoughts and experiences in the comments below.

You May Also Like…

Why Financial Advisors Are Warning About a ‘Retirement Shock’ Hitting Americans Over 62

The Medicare Premium Increase That Could Consume Nearly One-Third of Some Retirees’ COLA Boost

7 Retirement Budget Categories Rising Faster Than Inflation in 2026

Why More Americans Are Delaying Retirement as Medicare Premiums Approach $200 Per Month

6 Retirement Planning Errors That Could Cost You Thousands Under New Tax Rules

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Retirement Tagged With: 401(k), Financial Security, Inflation, IRA, money tips, Personal Finance, Retirement, retirement planning, savings, Social Security

4 Personal Finance Moves People Are Making Right Now Before Interest Rates Shift Again

May 30, 2026 by Brandon Marcus Leave a Comment

4 Personal Finance Moves People Are Making Right Now Before Interest Rates Shift Again
Before interest rates shift again, many people are making smart financial choices that can help them – Shutterstock

Interest rates rarely sit still for long, and financial markets already hint at another shift on the horizon. That uncertainty pushes households to rethink how they borrow, save, and invest before conditions change again. Every adjustment in rates reshapes credit card bills, mortgage costs, and savings returns in ways that hit everyday budgets fast.

Smart financial moves today can help people lock in advantages before lenders and banks reset the rules. The race to stay ahead of rate changes has already started, and it rewards those who act early rather than react late.

1. Locking in Fixed-Rate Debt Refinancing Opportunities

Homeowners across many markets actively explore refinancing options to secure fixed-rate mortgages before potential rate increases. Lenders often adjust offers quickly when economic forecasts shift, so timing plays a major role in savings potential. A locked-in rate protects households from unpredictable payment spikes that strain monthly budgets. Many borrowers compare multiple lenders within short time windows to capture the most favorable deal. This strategy reduces long-term financial pressure and brings stability to household planning.

Credit experts also encourage borrowers to review personal loan terms and auto loans for similar opportunities. Fixed rates remove uncertainty and allow clearer long-term budgeting decisions. Some borrowers combine refinancing with debt consolidation to simplify multiple payments into one predictable bill. Careful comparison shopping often reveals differences that translate into thousands of dollars over time. This move helps households gain control before the lending environment tightens further.

2. Boosting Emergency Savings Before Borrowing Costs Shift

Households now prioritize emergency savings because higher interest rates can quickly increase borrowing costs during financial shocks. Savings buffers help people avoid credit card reliance when unexpected expenses arise. Many financial planners recommend building at least three to six months of essential expenses in a liquid account. Strong savings cushions also reduce pressure when economic conditions change suddenly. This approach gives people breathing room when rates climb and credit becomes more expensive.

High-yield savings accounts attract more attention during uncertain rate cycles because they often adjust upward quickly. Savers shift idle cash into accounts that generate better returns without locking funds away long term. Some households automate weekly or monthly transfers to build momentum without relying on manual discipline. This steady strategy helps balances grow faster than sporadic contributions. Strong liquidity creates stability when financial conditions shift in unpredictable ways.

3. Paying Down High-Interest Variable Debt Aggressively

Credit card balances with variable rates now receive extra attention as borrowers try to avoid rising interest charges. Even small rate increases can significantly raise monthly payments on revolving debt. Many people focus on eliminating high-interest balances first to reduce financial drag. This strategy improves credit health while freeing up future income for savings or investing. Faster repayment also limits exposure to future rate hikes.

Debt payoff plans often target cards with double-digit interest rates because they create the heaviest financial burden. Some households use balance transfers to temporarily lower costs, but they also track expiration dates carefully. Others adopt structured repayment methods like the avalanche approach to maximize interest savings. Consistent extra payments shorten payoff timelines and reduce total interest paid over time. This aggressive approach strengthens financial resilience before credit conditions tighten further.

4 Personal Finance Moves People Are Making Right Now Before Interest Rates Shift Again
Paying down debt it always smart, but especially when you think an interest rate change is coming – Shutterstock

4. Diversifying Cash and Short-Term Investments

Investors now spread cash across multiple short-term instruments to capture better yields while preserving flexibility. Treasury bills, money market funds, and short-duration bonds often attract attention during shifting rate cycles. These options help balance safety with improved returns compared to traditional savings accounts. Many investors adjust portfolios to respond quickly when rates change again. Flexibility becomes a key advantage in uncertain financial environments.

Short-term diversification also protects against locking money into low-return products for too long. Some individuals ladder investments to create steady access to maturing funds throughout the year. Others shift portions of cash into conservative instruments that respond quickly to rate increases. This strategy helps maintain liquidity while still taking advantage of improved yields. A balanced approach allows investors to adapt without sacrificing financial stability.

The Big Financial Window Before Rates Move Again

Financial decisions feel more urgent when interest rates sit near a turning point. People who refinance early, build strong savings, reduce expensive debt, and reposition cash often gain the most control over future outcomes. Each move works together to reduce financial stress while improving long-term flexibility. Households that act proactively tend to avoid the worst surprises when lending conditions shift. The current environment rewards preparation, not hesitation.

What financial move feels most urgent right now before rates change again? If you have some financial advice that can help others, please share it below in our comments.

You May Also Like…

7 Warning Signs a Retiree’s Finances Are Starting to Spiral

High-Risk Investment Shift: 7 Assets Now Considered Riskier in 2026 Markets

Nevada’s Low Median Property Tax — Weighing Investment Appeal

Keeping Finances Separate in Marriage — What Works and What Doesn’t

10 Personal Finance Lessons People Learn the Hard Way

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Personal Finance Tagged With: budgeting, Debt Management, Inflation, interest rates, investing, money tips, Personal Finance, Planning, saving money

The IRS’s “Math Error” Notice Could Cost You More Than You Think

May 17, 2026 by Brandon Marcus Leave a Comment

The IRS’s “Math Error” Notice Could Cost You More Than You Think
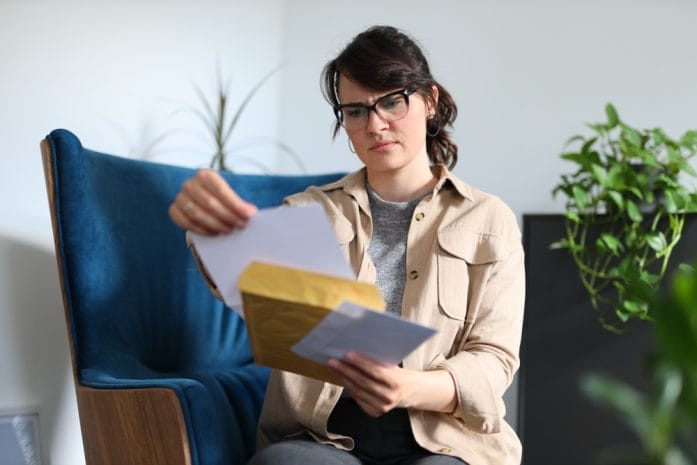
A letter from the IRS – Shutterstock

The IRS rarely makes big announcements without consequences hiding behind the fine print, and the “Math Error” notice stands out as one of the most overlooked. This notice often arrives after a tax return review and signals that something on a return does not add up according to IRS systems. Many taxpayers assume it means a simple typo or harmless correction, but the reality can feel much sharper once the numbers change.

Refunds shrink, balances jump, and penalties can appear faster than expected. The biggest surprise comes from how quickly the IRS can adjust a return without needing a full audit. That speed leaves little room for hesitation or confusion. A small mistake on paper can snowball into a costly financial shift if no one responds in time.

What the IRS Math Error Notice Really Means

The IRS sends a math error notice when its automated systems detect discrepancies in calculations, credits, or reported income. The agency does not need to open a full audit to make adjustments, which allows it to correct returns rapidly. These changes often involve missed income, incorrect dependents, or miscalculated credits like the Child Tax Credit or Earned Income Tax Credit. The notice explains the adjustment and shows how the IRS changed the return. Many taxpayers miss the importance of the response window, which usually lasts only 60 days.

The IRS treats this notice as a legal adjustment unless the taxpayer responds with proof or disagreement. That detail matters because silence locks in the change automatically. Taxpayers often overlook the fact that the IRS already assumes its calculation stands correct unless challenged. The notice may appear routine, but it carries real financial consequences that demand immediate attention. A quick review can reveal whether the IRS made a simple correction or a costly mistake.

Why a Small IRS Adjustment Can Turn Into a Bigger Bill

A math error notice rarely stays small once penalties and interest enter the picture. The IRS recalculates the return based on its findings and immediately adjusts the refund or balance owed. Interest starts accruing on unpaid amounts, even if the taxpayer disagrees with the adjustment. That timeline creates pressure because delays increase the final amount due. Many taxpayers underestimate how fast those extra charges grow.

The financial impact often surprises people because the IRS does not wait for confirmation before applying changes. A refund that looked solid on paper can shrink by hundreds or even thousands of dollars overnight. A balance due can also appear out of nowhere when credits get removed or reduced. The system prioritizes speed and correction over negotiation at this stage. That structure means quick action becomes the only real defense against rising costs.

Common Triggers That Lead to IRS Math Error Notices

Several common filing issues trigger these notices every tax season. Incorrect Social Security numbers for dependents often lead the list, especially when parents mix up digits during filing. Misreported income from W-2s or 1099s also creates mismatches between IRS records and tax returns. Taxpayers sometimes claim credits without meeting eligibility rules, which instantly flags the return. Even small math mistakes in manual entries can trigger automatic corrections.

The IRS also flags returns when filing status does not match supporting documentation. For example, claiming head of household status without qualifying criteria often leads to adjustments. Missing or duplicate income entries create another major trigger point. Tax software reduces some errors, but it does not eliminate taxpayer input mistakes. Careful review before filing can prevent many of these issues from ever reaching the IRS system.

The IRS’s “Math Error” Notice Could Cost You More Than You Think
A woman reading a letter from the IRS – Shutterstock

How to Respond Before the IRS Locks In the Change

The IRS gives taxpayers a limited window to respond, and that window plays a critical role in protecting refunds or reducing balances owed. A taxpayer can agree with the notice and accept the correction, or disagree and submit documentation to support the original return. Supporting records might include W-2 forms, dependent verification, or corrected 1099 statements. Clear and organized evidence increases the chance of reversing the adjustment. Speed matters because delays often strengthen the IRS position.

Tax professionals often recommend responding immediately instead of waiting to gather information later. The IRS already assumes the adjustment stands, so silence removes negotiation power. A written response with clear proof can reopen the case for review. Many taxpayers regain lost refunds simply by providing missing or corrected documentation. A proactive response often changes the outcome entirely.

Protecting Yourself From IRS Math Error Surprises in the Future

Taxpayers reduce risk significantly when they double-check every entry before submitting a return. Accuracy in Social Security numbers, income reporting, and credit eligibility prevents most math error notices. Reviewing IRS transcripts after filing also helps catch mismatches early. Filing early gives more time to fix issues before deadlines close response windows. Small habits like these create a strong defense against unexpected adjustments.

Tax filing software helps, but it does not replace careful human review. Many errors still come from rushed inputs or assumptions about eligibility rules. Organized recordkeeping throughout the year makes tax season smoother and less stressful. Staying alert to IRS mail notices ensures quick responses when issues arise. A careful approach keeps money where it belongs instead of letting corrections drain it away.

What steps would make tax season feel less stressful and more predictable for your household? We want to hear your thoughts below in our comments.

You May Also Like…

The IRS Is Sending More “Math Error” Notices—Here’s What They Really Mean

7 “Trigger Words” the IRS Uses to Flag Returns Faster

7 New IRS Changes That Could Delay Your 2026 Tax Refund

6 Mistakes People Make When Appealing an IRS Identity Check

Estate Portability Warning: Why One IRS Form Protects a Surviving Spouse’s $15M Exemption

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: tax tips Tagged With: IRS, IRS audit, IRS correspondence, IRS notice, math error notice, money tips, Personal Finance, tax filing, tax penalties, tax refund, tax return mistakes

  • 1
  • 2
  • 3
  • …
  • 8
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • 10 Tactics for Building an Emergency Fund from Scratch by Vanessa Bermudez
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald

Copyright © 2026 · News Pro Theme on Genesis Framework