• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Brandon Marcus

Legacy Blueprint: 5 Estate Mistakes Lawyers Still See Constantly

December 28, 2025 by Brandon Marcus Leave a Comment

Legacy Blueprint: 5 Estate Mistakes Lawyers Still See Constantly
Image Source: Shutterstock.com

Estate planning sounds like something reserved for millionaires with yachts and complicated family trees, but the truth is far more relatable and far more urgent. Every day, attorneys watch ordinary families stumble into preventable chaos because of tiny oversights that quietly snowball into legal nightmares. Wills get written, forgotten, and then quietly betray their owners years later. Heirs argue, courts intervene, and the plan meant to create peace ends up causing stress, expense, and resentment.

The good news is that most of these disasters are completely avoidable once you know where people go wrong and why. Let’s break down the most common estate mistakes lawyers still see constantly, and how smarter planning can turn confusion into clarity.

1. Failing To Update Beneficiaries After Life Changes

Life changes fast, but estate documents rarely keep up unless someone forces the issue. Marriages, divorces, births, deaths, and even strained relationships can instantly make old beneficiary designations dangerously outdated. Lawyers often see ex-spouses accidentally inheriting retirement accounts because no one updated a form sitting in a dusty drawer. Courts usually follow the paperwork, not your intentions, no matter how awkward or unfair the result feels. Keeping beneficiaries current is one of the simplest tasks in estate planning, yet it causes some of the most painful surprises.

2. Relying On DIY Documents And Internet Templates

Online templates promise speed, savings, and simplicity, but estate law is not a one-size-fits-all situation. A document that works perfectly in one state or family setup can fail completely in another. Lawyers frequently see DIY wills that conflict with state laws, omit key language, or accidentally disinherit loved ones. These documents often look official while quietly creating legal chaos behind the scenes. Saving money upfront can cost heirs exponentially more later when courts must untangle the mess.

3. Forgetting To Fund Trusts And Coordinate Assets

Creating a trust is only half the job, yet many people stop there and assume they are finished. Assets must actually be transferred into the trust, or the trust does nothing at all. Lawyers regularly encounter beautifully drafted trusts that sit empty while assets pass through probate anyway. Bank accounts, real estate, and investment accounts all need proper coordination to work as intended. Without follow-through, a trust becomes a decorative folder instead of a powerful planning tool.

4. Ignoring Tax Consequences And State-Specific Rules

Estate planning is never just about federal law, yet many people act as if it is. States have their own tax rules, probate processes, and quirks that can dramatically change outcomes. Lawyers see families blindsided by unexpected taxes or delays simply because state-specific planning was ignored. Even states without estate taxes may have inheritance rules that complicate distributions. Smart planning accounts for where you live now and where you might live later.

5. Avoiding Conversations That Prevent Family Conflict

Silence might feel polite, but in estate planning it often fuels confusion and resentment. When families don’t understand intentions, they fill in the gaps with assumptions and emotions. Lawyers frequently watch siblings fight not over money itself, but over what they believe a parent “would have wanted.” Clear conversations during life can defuse conflict long before documents are ever opened. Transparency, even when uncomfortable, often preserves relationships far better than secrecy.
Legacy Blueprint: 5 Estate Mistakes Lawyers Still See Constantly
Image Source: Shutterstock.com

The Legacy You Leave Is More Than Paper

Estate planning is not about predicting death; it is about protecting the people who live on after you. The most painful cases lawyers see usually involve good intentions paired with inaction or outdated decisions. A thoughtful plan, kept current and clearly communicated, can spare loved ones unnecessary stress and expense. Your legacy is shaped not just by what you leave behind, but by how smoothly life continues without you.

If you’ve experienced any of these mistakes or have insights of your own, feel free to give your thoughts or stories in the comments below.

You May Also Like…

Why Young People Don’t Think About Estate Planning

Am I the Only One Who Thinks Estate Planning Is Deeply Terrifying?

7 Excuses Millennials Use to Delay Estate Planning (and Why It’s Risky)

Legacy Risk: 6 Estate Myths That Put Families in Financial Danger

Estate Shift: 4 Overlooked Documents That Could Trigger Major Tax Headaches


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Estate Planning Tagged With: beneficiaries, beneficiary, death, end-of-life, estate, Estate plan, Estate planning, Family, family issues, family planning, Funds, important documents, tax issues, taxes, trusts

At What Age Should You Seriously Start Thinking About Retirement?

December 27, 2025 by Brandon Marcus Leave a Comment

At What Age Should You Seriously Start Thinking About Retirement?
Image Source: Shutterstock.com

Retirement sounds like something that lives in a far-off land where alarm clocks don’t exist and every weekday feels like a Saturday. It’s a word that can spark excitement, dread, denial, or all three at once, depending on your age and bank account. Some people imagine it as a beach chair and a drink with a tiny umbrella, while others see a terrifying spreadsheet filled with question marks.

The truth is, retirement planning isn’t a single moment of adulthood enlightenment—it’s a long, evolving relationship with your future self. And the sooner you understand when to take it seriously, the more freedom you give that future version of you.

Your Twenties: Laying The Groundwork Without Losing Your Mind

Your twenties are less about maxing out retirement accounts and more about building habits that won’t sabotage you later. This is the decade where learning how money works matters more than how much you have. Even small contributions to a retirement account can snowball impressively thanks to compound interest doing its quiet magic. At this stage, time is your greatest financial asset, even if your paycheck isn’t. Thinking about retirement now isn’t about sacrifice; it’s about giving yourself options.

Your Thirties: When “Later” Starts Feeling Real

By your thirties, retirement stops being theoretical and starts feeling like a real chapter with a rough outline. Careers tend to stabilize, incomes often rise, and lifestyle inflation begins knocking loudly at the door. This is the decade when consistent investing becomes more important than clever investing. You’re still young enough to recover from mistakes, but old enough that ignoring the future starts to get expensive. Taking retirement seriously here often means aligning your long-term goals with how you actually live, not how you wish you did.

Your Forties: The Decade Of Clarity And Course Correction

Your forties are where financial awareness tends to sharpen dramatically. You can see retirement on the horizon, but it’s still far enough away to adjust course if needed. Many people in this stage reassess risk, rebalance investments, and finally calculate what retirement might actually cost. This is also when competing priorities like kids, mortgages, and aging parents can complicate planning. Thinking seriously now is about protecting momentum and avoiding panic later.

Your Fifties: Turning Intentions Into Strategy

In your fifties, retirement planning shifts from abstract planning to concrete execution. You’re close enough that timelines matter, but far enough out to make meaningful improvements. Catch-up contributions, clearer retirement age targets, and realistic lifestyle expectations take center stage. This is also when people often reassess what retirement means beyond money, including health, purpose, and daily structure. Serious planning here can turn uncertainty into confidence.

At What Age Should You Seriously Start Thinking About Retirement?
Image Source: Shutterstock.com

Your Sixties And Beyond: Refinement, Not Reinvention

By your sixties, retirement is no longer a distant idea—it’s a calendar event. The focus shifts from accumulation to preservation and smart withdrawals. Decisions about Social Security timing, healthcare, and income streams carry real weight now. This stage rewards preparation more than perfection, because flexibility becomes a powerful asset. Thinking seriously at this age is about protecting your independence and enjoying what you’ve built.

So When Should You Really Start Thinking About Retirement?

The honest answer is that there’s no single “right” age, only a right level of awareness for each stage of life. The earlier you start thinking, the more options you create, but it’s never too late to improve your trajectory. Retirement isn’t a finish line; it’s a transition that reflects decades of choices, habits, and values. Starting early reduces stress, starting later demands focus, and starting at all is what truly matters. The best time to think about retirement is when you’re willing to take your future seriously.

Your Future Self Is Already Watching

Retirement planning isn’t about predicting every detail of your future life; it’s about respecting it enough to prepare. Whether you’re 22 or 62, the decisions you make today echo forward in ways that are often invisible until they aren’t. Small steps, taken consistently, beat dramatic moves made too late.

The real goal isn’t perfection, but progress and peace of mind. If this topic sparked a thought, memory, or question, drop it in the comments below and let the conversation grow.

You May Also Like…

Pension Shock: 9 Myths About Social Security That Could Derail Your Retirement

Risk Exposure: 9 Stress Tests Every Soon-to-Retire Investor Should Run

Pension Shock: 9 Myths About Social Security That Could Derail Your Retirement

Savings Fallout: 4 Hidden Expenses That Quietly Drain Retirement Budgets

Is Your Retirement Timeline Still Safe If The Market Drops Again Before New Year’s Eve?


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Retirement Tagged With: finance, finances, Financial plan, general finance, Money, money choices, money issues, Planning, retire, Retirement, retirement plan, retirement planning, retirements discussions, young people

Regulation Checklist: 9 Conversations Advisors Are Having With Clients Right Now

December 27, 2025 by Brandon Marcus Leave a Comment

Regulation Checklist: 9 Conversations Advisors Are Having With Clients Right Now
Image Source: Shutterstock.com

The financial world is buzzing, shifting, and occasionally doing backflips, and advisors are right in the middle of the action. New rules, sharper enforcement, and faster-moving technology have turned routine check-ins into strategic conversations with real consequences. Clients are asking smarter questions, regulators are asking tougher ones, and advisors are balancing clarity with compliance at record speed.

This moment feels less like paperwork and more like a high-stakes chess match where every move matters. These are the nine conversations shaping portfolios, trust, and decision-making right now.

1. Fiduciary Duty And What It Really Means Today

Clients want to know whether their advisor is legally and ethically obligated to act in their best interest at all times. Advisors are clarifying how fiduciary standards apply across accounts, products, and planning relationships. The conversation often includes where conflicts can exist and how they are disclosed or mitigated. Many clients are surprised to learn that not all advice is governed by the same rules. This discussion builds trust by replacing jargon with transparency.

2. Fee Transparency And Cost Justification

Fees are no longer a background detail; they are front and center in client conversations. Advisors are explaining exactly what clients pay, how those costs are structured, and what value they receive in return. This includes advisory fees, fund expenses, and potential transaction costs. Clients are increasingly comparing services, so clarity matters more than ever. The best conversations frame cost as an investment in guidance, not a mystery deduction.

3. Regulation Best Interest And Practical Impact

Regulation Best Interest sounds technical, but its real-world effects are very personal. Advisors are explaining how recommendations must align with a client’s goals, timeline, and risk tolerance. This often leads to deeper conversations about life changes, not just market performance. Clients want to know how these rules protect them in real scenarios. When explained well, the regulation feels less like red tape and more like a safety net.

4. Data Privacy And Cybersecurity Expectations

Clients are more aware than ever of data breaches and digital risk. Advisors are now expected to explain how personal and financial information is protected. This includes secure portals, encryption, and internal access controls. The conversation also covers what clients can do to protect themselves. Trust grows when security is treated as a shared responsibility, not a footnote.

5. AI, Automation, And Human Oversight

Artificial intelligence is no longer futuristic; it is part of daily financial operations. Advisors are discussing where automation helps and where human judgment remains essential. Clients want reassurance that algorithms do not replace accountability. These talks often highlight how technology enhances efficiency without removing personal connection. The goal is confidence, not confusion, about who is really making decisions.

Regulation Checklist: 9 Conversations Advisors Are Having With Clients Right Now
Image Source: Shutterstock.com

6. ESG, Values, And Regulatory Scrutiny

Environmental, social, and governance considerations continue to spark interest and debate. Advisors are navigating new disclosure rules while helping clients align investments with personal values. The conversation now includes how ESG claims are defined and verified. Clients want clarity without greenwashing or vague promises. Regulation has turned values-based investing into a more structured dialogue.

7. Retirement Rule Changes And Long-Term Planning

Shifting retirement regulations mean old assumptions no longer always apply. Advisors are walking clients through updated contribution limits, distribution rules, and tax implications. These discussions often uncover opportunities that were previously overlooked. Clients appreciate proactive guidance instead of last-minute surprises. Planning becomes more dynamic when rules evolve.

8. Marketing, Testimonials, And Online Presence

Advisors are now more visible online, and regulations are keeping pace. Clients are curious about what testimonials mean and how reviews are monitored. Advisors explain what can and cannot be said publicly and why compliance matters. This transparency helps clients interpret online information more critically. Trust grows when marketing feels honest rather than promotional.

9. Documentation, Disclosures, And Decision Trails

Behind every recommendation is a trail of documentation designed to protect both advisor and client. Advisors are explaining why certain forms exist and how records support accountability. Clients are learning that documentation is not bureaucracy for its own sake. It creates clarity if questions ever arise later. Good records turn complex decisions into well-supported ones.

The Conversations That Shape Confidence

Regulation may sound dry, but these conversations are anything but. They reveal how trust is built, how decisions are protected, and how advisors and clients move forward together with clarity. Each discussion strengthens the relationship and sharpens expectations on both sides.

If you have experiences, insights, or moments where one of these conversations made a difference, add your thoughts in the comments below. Your perspective helps keep this evolving conversation real and relevant.

You May Also Like…

6 Ways Your Financial Advisor Can Help With Your New Year’s Resolutions

9 Outdated Pieces of Financial Advice That Are Now Dangerous

The Financial Advice That Works—But Almost No One Follows

Could Your Advisor’s Advice Change If They Knew More About Your Personality

Why Do So Many Clients Demand Advice About Buying Cars Instead of Homes


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Financial Advisor Tagged With: artificial intelligence, Automation, cost justification, data, digital safety, fee, fee transparency, finance, finances, financial advisors, general finance, human oversight, Interest, invest, investing, Investment, investments, privacy, privacy issues

Behavior Habit: 5 Daily Money Moves That Build Long-Term Wealth

December 27, 2025 by Brandon Marcus Leave a Comment

Behavior Habit: 5 Daily Money Moves That Build Long-Term Wealth
Image Source: Shutterstock.com

Money habits don’t usually explode into your life with fireworks and drumrolls. They sneak in quietly, shape your choices, and then—years later—reveal whether they were working for you or against you the whole time. The good news is that wealth isn’t reserved for geniuses, lottery winners, or people who wake up at 4 a.m. to journal in linen pants. It’s built by ordinary people making small, repeatable decisions that quietly compound into something powerful.

The most successful money builders aren’t obsessing over secret formulas; they’re mastering daily behavior. And once you see how simple these habits really are, it becomes much harder to unsee them.

1. Automate Saving Before You Touch Your Money

The most powerful wealth move happens before your brain even has time to interfere. Automating savings removes emotion, procrastination, and decision fatigue from the equation entirely. When money flows automatically into savings or investments, you stop relying on willpower and start relying on systems. This habit flips the script from “save what’s left” to “spend what’s left,” which is a psychological game-changer. Over time, these quiet transfers grow into a financial safety net that feels almost magical because you barely had to think about it.

2. Track Spending Without Obsessing Over It

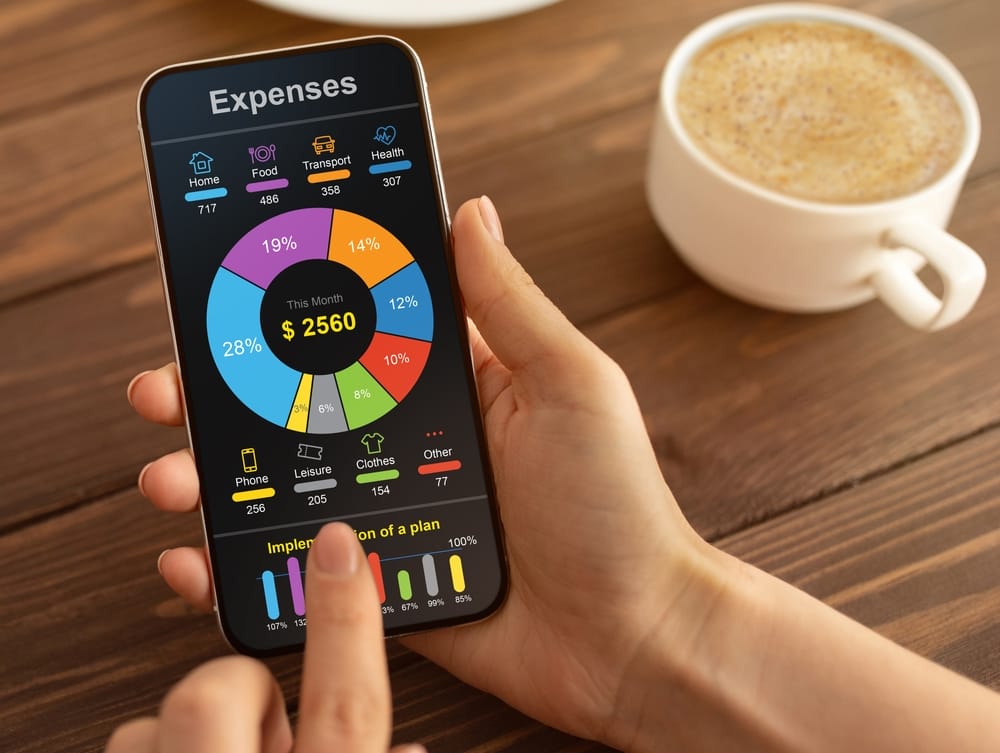
Knowing where your money goes is like turning the lights on in a messy room—you may not love what you see, but clarity is power. Tracking spending doesn’t mean punishing yourself or eliminating joy; it means understanding patterns so you can make smarter choices. When you review your spending regularly, you begin to spot leaks that quietly drain your progress. This awareness creates natural behavior shifts without guilt or restriction. Over time, mindful spending becomes second nature, not a chore.

3. Invest Consistently Even When It Feels Boring

Wealth isn’t built by dramatic, perfectly timed moves—it’s built by showing up consistently. Investing regularly, even in small amounts, allows compound growth to do the heavy lifting over time. The market rewards patience far more than brilliance, and boring consistency often beats flashy strategy. This habit trains you to think long-term instead of reacting emotionally to short-term noise. Eventually, the boring routine becomes exciting when you see momentum working in your favor.

4. Increase Your Value, Not Just Your Income

Chasing raises without upgrading your skills is like trying to pour more water into a cracked bucket. Long-term wealth grows faster when you invest in yourself through learning, skill-building, and strategic growth. Whether it’s improving communication, mastering a technical skill, or expanding leadership ability, your earning power rises with your value. This habit compounds across decades because higher-value people attract better opportunities. Money follows usefulness, and usefulness can be learned.

5. Make Daily Money Decisions With Future You In Mind

Every financial choice is a quiet conversation between present you and future you. When you pause and ask, “Will tomorrow-me thank me for this?” behavior begins to shift naturally. This mindset doesn’t eliminate fun; it simply balances it with intention. Over time, future-focused decisions stack up into stability, confidence, and options. Wealth, at its core, is the ability to give your future self more freedom.

Behavior Habit: 5 Daily Money Moves That Build Long-Term Wealth
Image Source: Shutterstock.com

Small Habits & Big Financial Futures

Wealth rarely arrives in dramatic bursts—it sneaks in through daily behaviors repeated with intention. The five habits above aren’t flashy, but they’re powerful precisely because they’re sustainable. When practiced consistently, they reshape how you think about money, risk, and opportunity. Over time, these small actions turn into momentum that feels almost unfair in the best way.

If you’ve discovered habits that changed your financial life or learned lessons the hard way, drop your thoughts or experiences in the comments below and keep the conversation going.

You May Also Like…

10 Money Moves That Look Smart but Lead to Regret

8 Times Your Brain Lied to You About Smart Money Moves

Legacy Shift: 5 Ways to Pass on Wealth Without Passing on Conflict

Regulation Echo: 10 Under-the-Radar Rules Affecting Future Wealth

Market Calm: 4 Quiet Moves Wealthy Clients Are Making Before the Holidays

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Wealth Building Tagged With: investing, Investment, investments, Money, money issues, money moves, saving money, savings account, Smart Spending, spending, track spending, tracking your spending, Wealth, Wealth Building, wealth choices, wealthy people

Are You Missing Opportunities Because You’re Too Focused On Day-To-Day Market Noise?

December 27, 2025 by Brandon Marcus Leave a Comment

Are You Missing Opportunities Because You’re Too Focused On Day-To-Day Market Noise?
Image Source: Shutterstock.com

The market doesn’t whisper—it screams, flashes, buzzes, and vibrates every second of the day. Red candles spark panic, green candles spark greed, and your phone becomes a tiny casino living in your pocket. One tweet, one earnings miss, one analyst downgrade, and suddenly your long-term plan feels like it’s on trial.

That emotional whiplash is exactly what keeps so many smart people stuck reacting instead of building. The real tragedy isn’t missing a perfect trade—it’s missing the bigger opportunities hiding behind the noise.

The Daily Market Circus And Why It Feels So Urgent

Financial news is designed to feel urgent because urgency keeps you watching, clicking, and reacting. Every headline is framed like a crisis or a breakthrough, even when it’s just another normal fluctuation. This constant stimulation tricks your brain into believing every movement matters equally. In reality, most daily market changes are statistical static, not meaningful signals. When you treat background noise like breaking news, long-term clarity quietly slips away.

Short-Term Thinking Versus Long-Term Wealth Creation

Short-term thinking thrives on emotion, while long-term wealth is built on patience and probability. The market rewards those who allow compounding to do its slow, unglamorous work. Focusing on daily swings often leads investors to buy high, sell low, and repeat the cycle with confidence. Long-term strategies, by contrast, benefit from time smoothing out mistakes, downturns, and bad headlines. Wealth usually grows quietly, not loudly.

Why Your Brain Loves Noise More Than Strategy

Your brain evolved to respond to immediate threats, not 30-year investment horizons. Market volatility triggers the same fight-or-flight response as physical danger, even though your survival isn’t actually at risk. News alerts and price charts hijack your attention because novelty feels important. Strategy, however, requires boredom, discipline, and delayed gratification. The market rewards the mind that can sit still while everything else screams for action.

The Hidden Cost Of Constant Reaction

Every impulsive move has a cost, even if it doesn’t show up as a visible loss. Trading fees, taxes, missed rebounds, and emotional exhaustion quietly chip away at performance. Constant reaction also fractures confidence, making every decision feel heavier than the last. Over time, you stop trusting your plan and start chasing reassurance. Ironically, the more you try to stay “on top” of the market, the further behind you often fall.

Are You Missing Opportunities Because You’re Too Focused On Day-To-Day Market Noise?
Image Source: Shutterstock.com

How Zooming Out Reveals Better Opportunities

When you zoom out, patterns replace panic and trends replace turbulence. Big opportunities often appear boring in the moment because they unfold slowly and steadily. Long-term investors benefit from economic growth, innovation, and human progress rather than daily drama. By focusing on fundamentals instead of fluctuations, you give yourself room to think clearly. Zooming out doesn’t mean ignoring risk—it means seeing it in proper proportion.

Reframing Success Beyond Daily Wins And Losses

Success in investing isn’t measured by how often you’re right this week, but by how resilient your strategy is over years. A well-constructed plan absorbs bad days without derailing your goals. When you define success as consistency instead of excitement, stress loses its grip. This mindset shift allows patience to become a competitive advantage. The calmer you stay, the more opportunity you can actually recognize.

Step Back To Move Forward

The market will always be loud, emotional, and unpredictable, but you don’t have to match its energy. Real opportunity often lives just beyond the reach of daily noise, waiting for those willing to slow down and think bigger. By shifting your focus from constant reaction to intentional direction, you give your strategy room to breathe and grow. The goal isn’t to ignore the market, but to stop letting it shout you off course.

If you’ve ever felt torn between staying informed and staying sane, your perspective could help others—drop your thoughts or experiences in the comments below.

You May Also Like…

Should You Switch Advisors Before The New Year Or Wait Until Markets Stabilize?

5 Clues That It’s Time To Pull Your Investment

Why Investing Apps Will Remain Popular in 2026

Market Frame: 4 Visual Techniques Advisors Use to Explain Risk Better

Market Blindspot: 8 Global Shifts Investors Aren’t Watching But Should


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Investing Tagged With: beginning investing, invest, investing, investing choices, Investment, investments, market, market choices, stock market

Market Wave: 6 Sector Themes Building Momentum Heading Into 2026

December 27, 2025 by Brandon Marcus Leave a Comment

Market Wave: 6 Sector Themes Building Momentum Heading Into 2026
Image Source: Shutterstock.com

The market doesn’t whisper when change is coming — it hums, buzzes, and eventually roars. Right now, that sound is getting louder as investors, innovators, and everyday consumers feel the ground shifting under long-established industries. New technologies are colliding with changing demographics, evolving regulations, and a global appetite for efficiency and resilience.

Some sectors are quietly stacking momentum, while others are sprinting ahead like they know something the rest of us don’t. If you’re paying attention, the next few years won’t feel random at all — they’ll feel like a wave building offshore, just waiting to break.

1. Artificial Intelligence Moves From Hype To Infrastructure

Artificial intelligence is no longer a flashy experiment; it’s becoming core infrastructure across industries. Businesses are embedding AI into logistics, customer service, cybersecurity, and financial forecasting, making it less optional and more operational. The biggest momentum isn’t in chatbots alone but in automation tools that quietly increase margins and productivity. As regulation slowly matures, companies that focus on explainability and trust will separate from the hype-chasers. By 2026, AI will feel less like magic and more like electricity — invisible, essential, and everywhere.

2. Energy Transition Gets Practical And Profitable

Clean energy is entering a more grounded phase where scalability matters as much as idealism. Governments and corporations are shifting from lofty climate pledges to tangible investments in grids, storage, and efficiency. Battery technology, nuclear revival conversations, and next-gen solar are all converging into a more reliable energy ecosystem. Investors are increasingly favoring companies that solve real bottlenecks instead of selling futuristic promises. The transition isn’t slowing down; it’s simply growing up and becoming economically unavoidable.

Market Wave: 6 Sector Themes Building Momentum Heading Into 2026
Image Source: Shutterstock.com

3. Healthcare Tech Rewrites The Patient Experience

Healthcare innovation is moving from hospital-centered to patient-centered at remarkable speed. Wearables, remote monitoring, and AI-assisted diagnostics are reducing friction in how care is delivered and measured. Aging populations and staffing shortages are accelerating the need for smarter systems rather than bigger ones. Preventative care is becoming data-driven instead of guesswork, shifting incentives across the entire sector. By 2026, healthcare technology won’t just save lives — it will save time, money, and sanity.

4. Defense And Cybersecurity Enter A New Era

Geopolitical instability has turned defense and cybersecurity from background considerations into strategic necessities. Governments and private companies alike are spending aggressively to protect digital and physical infrastructure. Cyber threats now move at machine speed, forcing equally fast responses powered by automation and AI. Defense innovation is expanding beyond weapons into logistics, communications, and space-based systems. This sector’s growth is driven less by fear and more by the realization that resilience is a competitive advantage.

5. Consumer Finance Gets Smarter And More Personal

Financial services are undergoing a quiet but powerful transformation. Fintech platforms are using data to tailor experiences, from personalized budgeting to adaptive lending models. Younger generations expect transparency, speed, and control, forcing traditional institutions to evolve or partner up. Embedded finance is blurring the lines between banks, apps, and everyday services. By 2026, money management will feel less like paperwork and more like a real-time conversation.

6. Advanced Manufacturing Makes A Comeback

Manufacturing is shedding its old image and embracing automation, robotics, and localized production. Supply chain shocks taught businesses that efficiency without resilience is a liability. Smart factories are using AI, sensors, and digital twins to optimize output in real time. Governments are incentivizing domestic production to reduce dependency and create skilled jobs. The result is a manufacturing renaissance that blends high-tech innovation with economic strategy.

Riding The Momentum Without Losing Your Balance

The themes shaping the road to 2026 aren’t isolated trends — they’re interconnected forces reshaping how the world works. Technology, policy, and human behavior are moving together in ways that reward adaptability and long-term thinking. Whether you’re an investor, entrepreneur, or curious observer, understanding these shifts offers a powerful lens into what’s coming next.

Momentum doesn’t guarantee success, but awareness creates opportunity. Drop your thoughts, reactions, or personal experiences in the comments below and keep the conversation moving.

You May Also Like…

Should You Switch Advisors Before The New Year Or Wait Until Markets Stabilize?

Market Turn: 4 Signals That the Next Bull Cycle Could Look Different

Market Frame: 4 Visual Techniques Advisors Use to Explain Risk Better

Asset Migration: 5 Emerging Market Trends Retirees Should Know Before January

Crisis Proof: 10 Buffer Strategies Advisors Use to Protect Clients From Market Shock


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: artificial intelligence, consume finance, cybersecurity, finance, finances, general finances, healthcare, healthcare tech, invest, investing, Investment, investments, manufacturing, market, stock market

5 Ways To Easily Boost Your Income In 2026

December 26, 2025 by Brandon Marcus Leave a Comment

Here Are 5 Ways To Easily Boost Your Income In 2026
Image Source: Shutterstock.com

The financial world in 2026 is more dynamic, fast-moving, and exciting than ever before. From AI-driven tools to side hustles that pay while you sleep, the opportunities to increase your income are staggering—and many of them are easier than you think. What used to take months of networking, long hours, or luck can now be achieved with strategy, creativity, and a little tech know-how.

Imagine adding extra cash to your bank account without completely rearranging your life. Ready to turn the next year into a financial game-changer? Let’s dig into five exciting ways to boost your income in 2026.

1. Leverage AI Tools To Increase Productivity

Artificial intelligence isn’t just a buzzword—it’s a literal money-making engine. Tools that can automate repetitive tasks, generate content, or analyze financial data are making it easier than ever to focus on high-value work. By using AI to handle the mundane, you free up hours to take on more projects, freelance gigs, or investments that pay better. Even small businesses can see a dramatic jump in revenue by streamlining operations with AI assistants. In 2026, ignoring AI could mean leaving money on the table, and nobody wants that.

2. Monetize Your Skills Online

The internet is a treasure trove for anyone willing to offer their expertise. Platforms for teaching, consulting, or creating digital products allow you to earn income without geographical limits. Whether you’re coding, crafting, writing, or coaching, there’s an audience willing to pay for your knowledge. Micro-consulting, online courses, and virtual workshops can turn hobbies into steady income streams. The best part? Once the content is created, it can generate revenue long after your initial effort.

3. Invest In High-Growth Opportunities

Smart investing remains one of the fastest ways to grow your wealth, especially in 2026’s ever-changing markets. Stocks, ETFs, cryptocurrency, and even real estate crowdfunding are accessible to everyday investors like never before. Learning how to diversify and manage risk can turn even modest amounts of money into substantial growth over time. Apps and robo-advisors now make research and portfolio management almost effortless. With a little knowledge and patience, your money can start working as hard as you do.

Here Are 5 Ways To Easily Boost Your Income In 2026
Image Source: Shutterstock.com

4. Start A Side Hustle That Fits Your Lifestyle

Side hustles have evolved beyond delivering food or ridesharing. In 2026, digital opportunities like social media management, print-on-demand, and affiliate marketing can be tailored to fit your schedule and interests. The key is to choose something scalable, enjoyable, and aligned with your existing skills. Even dedicating a few hours a week can bring in hundreds or even thousands of extra dollars monthly. Flexibility is the ultimate bonus, allowing you to earn more without burning out.

5. Maximize Passive Income Streams

Passive income isn’t a myth—it’s a strategy that anyone can implement with a little planning. Rental properties, dividend-paying stocks, and online content that earns royalties are just a few ways to create revenue that keeps flowing. Subscription-based services, apps, and digital downloads allow for continuous income with minimal ongoing effort. Combining multiple passive streams can create a safety net while you focus on other projects. In 2026, building passive income isn’t just smart; it’s essential for financial resilience.

Your 2026 Income Adventure Starts Now

Boosting your income in 2026 doesn’t require magic—just a mix of strategy, tech, and creativity. Whether you dive into AI tools, monetize your skills online, invest smartly, start a side hustle, or build passive income, there’s no shortage of options. The opportunities are fast, flexible, and designed to fit modern lifestyles, meaning anyone can start increasing their earnings right away.

The only limit is your willingness to experiment and commit. Tell us your thoughts, experiences, or successful strategies in the comments below—we’d love to hear what works for you!

You May Also Like…

Income Pivot: 8 Income Streams Retirees Are Adding Before Rates Change Again

13 Intriguing Ideas for Generating Passive Rental Income Streams

7 Income Streams You’d Laugh At—Until They Out-earned Your Salary

5 Income Goals That Professionals Wish They Hit by 35

12 Different Ways to Structure Your Portfolio for Income Generation


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Lifestyle Tagged With: boost your income, boosted income, careers, earn more income, financial plans, Income, investing, investments, job, jobs, Life, Lifestyle, multiple income streams, Planning, side gig, side hustle

Income Threshold: 4 Hidden Taxes That Hit Once You Cross Certain Limits

December 26, 2025 by Brandon Marcus Leave a Comment

Income Threshold: 4 Hidden Taxes That Hit Once You Cross Certain Limits
Image Source: Shutterstock.com

Earning more money is usually exciting—raises, promotions, side hustles finally paying off. But what if your bank account gains triggered sneaky traps that weren’t in the paycheck memo? These hidden taxes can strike the moment your income passes certain thresholds, quietly shrinking your take-home pay.

From disappearing deductions to stealthy surtaxes, they hit in ways that make your wallet flinch. Let’s dive into four surprising taxes that you might not know are lurking just above your financial comfort zone.

1. Social Security Tax Cap And Its Sneaky Effect

Social Security taxes feel straightforward at first glance. But once you cross a specific income cap, you stop paying Social Security taxes on additional earnings. Sounds like a break, right? Not entirely, because the sudden cessation affects long-term benefits, since your retirement check is calculated based on your lifetime earnings. High earners may find themselves paradoxically paying less in the short term but potentially receiving lower proportional benefits later.

2. Medicare Surtax That Hits The Top Bracket

Medicare usually takes 1.45% of your paycheck, and your employer contributes the same. Yet for individuals earning more than a certain amount, an additional Medicare surtax applies. This tax doesn’t end at a cap—it keeps taking from every extra dollar earned above that threshold. It’s an often-overlooked bite for high-income earners, especially those juggling bonuses or side income streams. Ignoring it can result in a shock when you file your taxes, turning extra earnings into unexpected deductions.

3. The Phaseout Of Itemized Deductions

Deductions are your best friends, trimming taxable income and lightening your tax bill. But once your income surpasses a certain limit, many itemized deductions begin to phase out. For example, higher-income taxpayers may lose deductions for state and local taxes, mortgage interest, or charitable contributions. This stealthy withdrawal increases taxable income without any overt notice in your paycheck. Essentially, the more you earn past a threshold, the fewer deductions you can claim, quietly inflating your effective tax rate.

4. Net Investment Income Tax: The Silent Siphon

The net investment income tax (NIIT) is like a secret toll booth on passive income. Individuals with modified adjusted gross income over a certain amount pay an additional tax on investment earnings. That includes interest, dividends, capital gains, rental income, and certain passive business income. For investors, this can drastically change the net return on a well-planned portfolio, especially if multiple income streams push you above the threshold. Many people don’t realize that this tax operates independently of ordinary income tax, so it’s easy to underestimate its bite.

Income Threshold: 4 Hidden Taxes That Hit Once You Cross Certain Limits
Image Source: Shutterstock.com

Why Timing And Planning Matter More Than Ever

Crossing these thresholds isn’t just a numbers game; it’s a timing and strategy issue. Earning a bonus or selling an investment at the wrong moment can push you over a critical line. Smart tax planning—like deferring income, bunching deductions, or leveraging tax-advantaged accounts—can mitigate these hidden hits. Professionals and self-employed earners especially benefit from proactive planning, as small moves can save thousands. Understanding when and how these thresholds apply keeps your hard-earned money from evaporating unnoticed.

Keep An Eye On Changes Every Year

Tax laws are rarely static—they shift, sometimes subtly, each year. The IRS annually updates income limits, caps, and thresholds, affecting Social Security, Medicare, deductions, and investment taxes. What applied last year may not hold true this year, so relying on outdated information can be costly. Staying informed ensures you’re prepared for each threshold, rather than surprised at filing time. Vigilance transforms these hidden taxes from stealthy penalties into manageable considerations in your financial plan.

What Do You Think About Hidden Taxes?

Hidden taxes often hit without warning, but knowledge is your best defense. Understanding income thresholds, surtaxes, phaseouts, and investment taxes can help you strategize and protect your earnings.

Have you ever encountered a surprise tax when you crossed an income line? Tell us your thoughts or stories in the comments section below. The more you know, the better you can plan—and maybe even keep more of what you earn.

You May Also Like…

Income Pivot: 8 Income Streams Retirees Are Adding Before Rates Change Again

13 Intriguing Ideas for Generating Passive Rental Income Streams

7 Income Streams You’d Laugh At—Until They Out-earned Your Salary

5 Income Goals That Professionals Wish They Hit by 35

12 Different Ways to Structure Your Portfolio for Income Generation

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: tax tips Tagged With: deductions, extra income, fees, fixed income, Hidden Fees, hidden taxes, high income, income threshold, Medicare, net investment income tax, Social Security, Tax, tax limit, tax tips, taxes

Risk Observation: 5 Quiet Signals Indicating Trouble Ahead for Mid-Life Investors

December 26, 2025 by Brandon Marcus Leave a Comment

Risk Observation: 5 Quiet Signals Indicating Trouble Ahead for Mid-Life Investors
Image Source: Shutterstock.com

The world of investing is thrilling, but it can also be sneaky. One minute your portfolio is cruising along like a luxury sports car, and the next, subtle signs hint at trouble ahead. Mid-life investors, often juggling retirement planning, mortgages, and the occasional splurge on fancy coffee machines, need to stay vigilant.

Ignoring these quiet signals can turn what seemed like a secure ride into a bumpy, nerve-racking journey. Understanding these warning signs early is like spotting a speed bump in the dark—it saves you from a hard stop later.

1. Portfolio Volatility Outpaces Comfort Levels

Volatility is part of investing, but when your portfolio swings like a rollercoaster more than a merry-go-round, it’s time to pay attention. Mid-life investors often have fewer years to recover from big losses, so extreme fluctuations can silently eat into your retirement plans. If checking your account leaves you sweaty and wide-eyed, your risk tolerance might be misaligned with your investments. Ignoring this mismatch can quietly chip away at your wealth without obvious red flags. The smartest approach is to periodically assess whether your current investments match your comfort and timeline.

2. Reliance On High-Risk “Quick Wins”

The allure of fast, high-return investments can sneak up on even the most disciplined investors. Mid-life professionals might feel pressure to catch up on retirement savings, prompting riskier moves. Relying heavily on speculative stocks or exotic instruments is like playing with fire while wearing gasoline-soaked gloves. While occasional calculated risk is healthy, consistent dependence signals a potential problem. Investors should ask themselves if their strategy prioritizes stability or adrenaline.

3. Ignoring Cash Flow Realities

A portfolio can look impressive on paper, but if your day-to-day cash flow feels tight, trouble may be lurking behind the scenes. Mid-life investors often juggle family expenses, mortgage payments, and college tuition, and neglecting liquidity can create silent stress. If you’re dipping into long-term investments to cover short-term needs, the warning bells are ringing quietly. Proper planning ensures that your cash flow and investments coexist without one undermining the other. Understanding your income, expenses, and liquidity needs is crucial to avoiding unexpected financial shocks.

4. Emotional Investment Decisions

Even experienced investors aren’t immune to emotion-driven mistakes. Buying in a frenzy during market hype or selling in panic during dips can quietly erode long-term gains. Mid-life investors, who often feel the ticking clock of retirement, may experience heightened emotional responses to market swings. Recognizing patterns of fear or overexcitement is a key signal that your strategy needs recalibration. A disciplined, rules-based approach can reduce emotional pitfalls and keep your portfolio on track.

Risk Observation: 5 Quiet Signals Indicating Trouble Ahead for Mid-Life Investors
Image Source: Shutterstock.com

5. Lack Of Regular Portfolio Review

Out of sight doesn’t mean out of trouble. Neglecting regular reviews allows risks to grow unnoticed and opportunities to slip by. Mid-life investors may feel busy, but skipping scheduled portfolio check-ins can silently compromise long-term goals. Small shifts in market conditions, tax laws, or personal circumstances can quietly alter your risk landscape. Setting aside time each quarter to evaluate your holdings ensures problems are spotted early and adjustments are timely.

Your Financial Radar Matters

Staying alert to these quiet signals is essential for any mid-life investor who wants to avoid nasty surprises. Volatility, risky dependencies, cash flow issues, emotional investing, and lack of regular review are not just abstract concepts—they’re actionable warning signs. By tuning into these indicators, you can navigate the investment landscape more confidently and protect your retirement goals.

Every portfolio has its ups and downs, but recognizing subtle warning signs early keeps you ahead of trouble. Now it’s your turn to leave your thoughts and experiences in the comments section below.

You May Also Like…

Funding Gap: 8 Ways Rising College Costs Are Changing Mid-Life Financial Planning

Behavior Risk: 4 Psychological Traps Mid-lifers Fall Into When Markets Turn Choppy

Regulation Echo: 10 Under-the-Radar Rules Affecting Future Wealth

How To Start Your 2026 Investing Journey With A Bang

8 Bold Strategies for Investing During Periods of High Inflation


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Investing Tagged With: emotional investing, investing, Investment, investments, investors, market risk, mid-life investing, mid-life investments, portfolio, portfolio diversification, portfolio management, stock market

Asset Pivot: 6 Real-World Allocation Moves Advisors Are Using This Month

December 26, 2025 by Brandon Marcus Leave a Comment

Here Are 6 Real-World Allocation Moves Advisors Are Using This Month
Image Source: Shutterstock.com

Investing doesn’t have to feel like wandering through a foggy maze with a blindfold on; in fact, right now markets are buzzing, dialing up excitement and opportunity for those who know where to look. This month, advisors everywhere are making bold, strategic allocation pivots that are not just reactive to headlines, but responsive to real economic signals, fresh data, and evolving risk‑reward dynamics in global markets.

With inflation narratives changing like dance partners at a wedding, fixed income yields flirting with long‑dormant highs, and sectors such as energy, technology, and alternatives showing distinct trajectories, savvy professionals are steering client portfolios in ways that could have real impact.

1. Increasing Exposure To Short‑Duration Bonds

Advisors are shifting part of their fixed income allocations into short‑duration bonds to help manage interest rate risk while still capturing attractive yields in the current rate regime. With central banks signaling a willingness to stand firm on policy until inflation is squarely back at target, longer maturities are carrying greater volatility that many clients would rather avoid. Shorter durations typically mean reduced price sensitivity when rates move, which is a key consideration for those who want steadier income without excessive swings.

Many advisors are layering in high‑quality corporate and municipal short bonds to balance safety with return potential, particularly for clients nearing retirement. This move also reflects a broader understanding that liquidity and flexibility are increasingly valuable in unpredictable markets.

2. Embracing Real Assets Like Infrastructure And Commodities

Tangible assets such as infrastructure and commodities have seen a resurgence in advisor conversations as inflation hedges and diversifiers in traditional portfolios. Infrastructure investments—spanning transportation, utilities, and communication networks—offer the promise of stable, inflation‑linked cash flows that can support long‑term financial goals. Meanwhile, commodities from energy to agriculture provide exposure to real economic activity and can perform well when financial assets lag. Advisors are crafting allocations that blend these real assets with equities and bonds to improve overall portfolio resilience. For investors willing to accept some extra complexity, real assets can be an engaging avenue to capture growth in the physical economy.

3. Tilting Toward Quality Growth Stocks

Equities remain a central pillar of most portfolios, but the flavor of choice has shifted toward quality growth stocks that exhibit robust earnings, strong balance sheets, and sustainable competitive advantages. Advisors are advising clients to reconsider high‑beta, speculative names in favor of companies with proven performance and durable business models that can weather turbulence. This doesn’t mean eliminating all risk, but rather channeling risk into names with higher probability of long‑term success, especially in sectors like health care, technology, and consumer staples where innovation continues unabated.

Many firms are also integrating environmental, social, and governance (ESG) metrics to align quality with purpose and risk management. This pivot underscores a broader market wisdom that not all growth is created equal, and that disciplined selection often trumps broad exposure.

4. Allocating To International Markets With Selectivity

Global diversification is back in the spotlight as advisors explore regions and markets that may offer compelling valuations outside the domestic arena. Emerging markets, particularly in Asia, are attracting attention due to demographic advantages, technological adoption, and cyclical rebounds in key industries. Europe, with its unique economic composition and policy shifts, offers opportunities for investors who can tolerate currency and geopolitical nuance.

At the same time, select developed markets are appealing for their stability and dividend yields, making them attractive complements to U.S. holdings. The overarching theme is not indiscriminate global buying, but rather thoughtful allocation to regions poised for differentiated growth while managing exposure to risk factors like inflation, trade tensions, and monetary policy divergence.

Here Are 6 Real-World Allocation Moves Advisors Are Using This Month
Image Source: Shutterstock.com

5. Boosting Alternative Investments For Diversification

Alternative investments such as private equity, hedge funds, and non‑traditional credit are increasingly part of advisor conversations as tools to enhance diversification and potentially improve risk‑adjusted returns. These strategies can behave differently from public equities and fixed income, offering cushioning effects when traditional markets are choppy or correlated. For instance, certain hedge fund strategies aim to profit from volatility or inefficiencies in markets where traditional asset classes struggle, adding strategic value for client portfolios. Private credit is gaining traction as banks retrench from certain lending spaces, providing yield‑seeking investors with access to bespoke opportunities. Advisors are, nevertheless, balancing these allocations with liquidity considerations and client goals, recognizing that not every investor is suited for long lockups or complexity.

6. Integrating Thematic Plays Around Innovation And Sustainability

Thematic investing remains a popular way to align portfolios with long‑term megatrends in areas like artificial intelligence, clean energy, and sustainable agriculture. Advisors are structuring allocations that allow clients to tap into innovation without becoming overconcentrated in any single theme or company. For instance, funds focused on AI infrastructure, robotics, or renewable energy are being blended with core holdings to capture growth while maintaining broad diversification. Sustainable investments also resonate with clients who prioritize environmental and social impact alongside financial returns, creating engagement and long‑term alignment. These thematic pivots are not about chasing every trend, but about thoughtfully integrating forward‑looking sectors that have structural support from technological adoption and policy incentives.

Reflecting On Allocation Moves And Your Financial Journey

Now that you’ve explored six real‑world allocation moves advisors are using this month, you might be buzzing with ideas about how these strategies could influence your own financial approach or spark thoughtful conversations with your advisor. These allocation changes reflect a dynamic investment landscape that rewards both discipline and creativity, and they remind us that flexibility and awareness are vital tools in any investor’s toolkit.

Are you contemplating a similar pivot in your own strategy, or have you already begun making changes that feel timely and smart? We’d love to hear your thoughts or any stories about how these kinds of moves have played out in your experience.

You May Also Like…

6 Ways Your Financial Advisor Can Help With Your New Year’s Resolutions

Market Frame: 4 Visual Techniques Advisors Use to Explain Risk Better

Could Your Advisor’s Advice Change If They Knew More About Your Personality

Why Do So Many Clients Demand Advice About Buying Cars Instead of Homes

Asset Migration: 5 Emerging Market Trends Retirees Should Know Before January


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Financial Advisor Tagged With: advisors, allocation, alternative investments, assets, bonds, commodities, diversify, financial advisor, financial advisors, growth stocks, international investing, Money, money advice, money issues, money matters, stock market, stocks

  • « Previous Page
  • 1
  • …
  • 143
  • 144
  • 145
  • 146
  • 147
  • …
  • 157
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework