• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Personal Finance

11 Anxiety Triggers Caused By Living Paycheck-to-Paycheck Still

October 19, 2025 by Travis Campbell Leave a Comment

paycheck to paycheck
Image source: pexels.com

Living paycheck-to-paycheck still is a reality for many households, even as expenses and economic pressures keep rising. It’s not just about money—it’s about the daily stress and emotional toll that comes with it. When you’re always waiting for the next payday, even small surprises can feel overwhelming. This cycle can trigger anxiety, making it hard to focus or plan for the future. Understanding these triggers is the first step to breaking free from the stress that comes with living paycheck to paycheck.

1. Unexpected Expenses

One of the biggest anxiety triggers for people living paycheck-to-paycheck is still unexpected bills. Whether it’s a car repair, medical emergency, or home maintenance, even a small, unplanned cost can throw your budget into chaos. The fear of not having enough to cover these expenses can keep you up at night.

2. Fear of Job Loss

When you have no financial cushion, the thought of losing your job is terrifying. Living paycheck-to-paycheck still means that even a short period without income could lead to missed bills, eviction, or worse. This constant worry can drain your energy and impact your performance at work.

3. Rising Cost of Living

Inflation and rising prices for essentials like groceries, gas, and utilities make it even harder to stretch each paycheck. If your income isn’t keeping up, you may feel like you’re falling further behind, which can cause persistent anxiety about meeting your basic needs.

4. Overdraft and Late Fees

When your account balance is always low, it’s easy to slip into overdraft or miss a payment. These fees add up quickly, making it even harder to get ahead. The stress of watching your balance and worrying about bank fees is a constant companion for many living paycheck-to-paycheck.

5. Lack of Emergency Savings

Not having an emergency fund is a major source of stress. Without any savings, you’re always one emergency away from financial disaster. This ongoing risk is a huge anxiety trigger and makes it hard to feel secure in your day-to-day life.

6. Social Pressure

It’s tough when friends or family want to go out or plan trips, and you know you can’t afford it. The pressure to keep up can lead to guilt, embarrassment, or even spending money you don’t have. Living paycheck-to-paycheck can still make social situations uncomfortable and stressful.

7. Credit Card Reliance

Many people turn to credit cards to cover gaps between paychecks. While this can provide short-term relief, it often leads to mounting debt and high interest payments. The cycle of borrowing and repaying can create a constant sense of dread and anxiety.

8. Difficulty Planning for the Future

It’s hard to think about retirement, buying a home, or even taking a vacation when you’re struggling to cover today’s bills. Living paycheck-to-paycheck still makes long-term planning feel impossible, which can be discouraging and stressful.

9. Impact on Mental Health

Financial stress doesn’t just affect your wallet—it can take a toll on your mental health. Anxiety, depression, and trouble sleeping are common among people living paycheck-to-paycheck still. The cycle of worry can feel never-ending.

10. Relationship Strain

Money problems are one of the top causes of tension in relationships. When you and your partner are both anxious about making ends meet, arguments and resentment can build. This added strain can make living paycheck-to-paycheck still even more difficult to handle.

11. Limited Access to Opportunities

When every dollar is accounted for, it’s hard to invest in yourself or your future. Whether it’s a class, a business idea, or a move for a better job, living paycheck-to-paycheck still means many doors stay closed. This realization can be a major source of anxiety and frustration.

Breaking the Cycle of Living Paycheck-to-Paycheck Still

If you’re living paycheck-to-paycheck still, you’re not alone—and it’s not hopeless. Small steps like tracking your spending, building a basic emergency fund, or finding ways to increase your income can help reduce anxiety over time. Even minor changes can make a difference in your sense of control and security.

There are resources that can help, from budgeting apps to community programs and online financial education. For more ideas, check out practical tips from the CFPB or explore advice on breaking the paycheck-to-paycheck cycle. Remember, taking action—no matter how small—can help lower anxiety and give you hope for the future.

What anxiety triggers have you faced while living paycheck-to-paycheck, and how have you managed them? Share your thoughts in the comments below.

What to Read Next…

  • 10 Signs You’re Living Above Your Means Without Realizing
  • Are These 6 Helpful Budget Tips Actually Ruining Your Finances?
  • Are These 8 Money Saving Tricks Actually Keeping You Broke?
  • 7 Tactics Grocery Stores Use to Keep You From Thinking About Price
  • Are Budgeting Apps Designed to Push You Into Debt?
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.
Filed Under: Personal Finance Tagged With: anxiety, budgeting, emergency fund, financial stress, money management, Personal Finance

Why Your $1,000 Emergency Fund Is Not Nearly Enough for 2026

October 19, 2025 by Travis Campbell Leave a Comment

emergency fund
Image source: pexels.com

For years, the $1,000 emergency fund has been a standard starting point for personal finance advice. It’s simple, achievable, and feels like a safety net. But as we look ahead to 2026, that number just doesn’t cut it anymore. Rising living costs, unpredictable economic shifts, and bigger financial risks mean a $1,000 emergency fund is not nearly enough. If you want true peace of mind and real financial security, it’s time to rethink what you need in your emergency fund. Let’s break down exactly why that old target falls short and what you should do about it.

1. Inflation Has Changed the Game

Inflation keeps pushing the cost of everything higher, from groceries to rent to medical bills. What $1,000 could cover even five years ago barely scratches the surface today. In 2026, your $1,000 emergency fund will buy less than ever before. This shrinking power means you may not be able to cover a single urgent car repair, let alone several unexpected expenses at once. If your emergency fund doesn’t keep pace with inflation, it’s not doing its job.

2. One Expense Can Wipe Out Your Fund

Think about the last time your car broke down or you needed a sudden home repair. Many common emergencies—like replacing a major appliance or paying for an urgent dental procedure—can cost well over $1,000. If you dip into your emergency fund for any one of these, you’re left with nothing for the next crisis. Relying on a $1,000 emergency fund is like walking a tightrope with no safety net underneath.

3. Medical Costs Are on the Rise

Healthcare expenses are unpredictable and increasing every year. Even with insurance, deductibles and out-of-pocket costs can be steep. A single trip to the emergency room or an unexpected surgery can easily cost thousands of dollars. In 2026, a $1,000 emergency fund won’t come close to covering a medical emergency. If you want to be prepared, you’ll need to set aside much more.

4. Job Losses Take Longer to Recover From

Job security isn’t what it used to be. Layoffs and furloughs can happen suddenly, and finding a new job often takes longer than expected. In the past, experts suggested saving three to six months’ worth of expenses as an emergency fund. If you lose your job in 2026, $1,000 won’t even cover your rent or mortgage for a month, let alone food, utilities, and other essentials. Preparing for this possibility means building a larger cushion.

5. More People Are Freelancing and Gig Working

More Americans are turning to freelance work and gig jobs for income. While flexible, these roles often come with unpredictable pay and fewer benefits. If you’re a freelancer or gig worker, you’re even more likely to face income gaps or slow months. A $1,000 emergency fund simply isn’t enough to get you through lean times. Building a more substantial emergency fund can help you weather these ups and downs without resorting to high-interest debt.

6. Credit Cards Aren’t a Backup Plan

Some people believe they can rely on credit cards if their $1,000 emergency fund runs out. But using credit cards for emergencies can lead to debt spirals, especially with interest rates climbing higher. Instead of falling back on expensive credit, aim to grow your emergency fund to a more realistic level. For advice on managing debt and building savings, you might check resources like the Consumer Financial Protection Bureau.

7. Natural Disasters and Climate Risks Are Rising

Wildfires, hurricanes, floods, and other natural disasters are becoming more common. These events can force you out of your home, damage property, or interrupt your income. The costs of evacuation, temporary lodging, and repairs can quickly exceed $1,000. If you live in an area prone to disasters, your emergency fund needs to reflect that extra risk. Planning ahead can help you bounce back faster when the unexpected hits.

How Much Should Your Emergency Fund Be in 2026?

The old $1,000 emergency fund rule is outdated for 2026. Most experts now recommend saving at least three to six months’ worth of living expenses. If your monthly expenses are $3,000, aim for $9,000 to $18,000 in your emergency fund. This larger cushion will help you handle inflation, medical bills, job loss, and other surprises without derailing your financial goals.

Building up your emergency fund takes time, especially if you’re starting small. Begin by tracking your expenses and setting a realistic savings goal. Automate transfers to a high-yield savings account so your money grows while it sits.

Are you rethinking your emergency fund for 2026? How much do you think is enough? Share your thoughts or experiences in the comments below!

What to Read Next…

  • What Happens When a Medical Emergency Outpaces Your Emergency Fund
  • Why Some People Feel Rich But Can’t Afford a $400 Emergency
  • 5 Emergency Repairs That Could Force You Into Debt Overnight
  • Are These 7 Little Expenses Quietly Costing You Thousands a Year
  • 6 Money Habits That Backfire After You Turn 60
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.
Filed Under: Finance Tagged With: budgeting, emergency fund, Personal Finance, Planning, savings

6 Uncomfortable Discussions That Save Marriages and Net Worth

October 19, 2025 by Travis Campbell Leave a Comment

mariage
Image source: shutterstock.com

Money is one of the top reasons couples argue and even separate. It’s not always about not having enough—it’s about how we talk (or avoid talking) about it. Facing financial issues as a team can strengthen your relationship and your bank account. But these conversations can feel awkward, especially if you grew up in families that didn’t talk openly about money. Still, having honest discussions now can prevent bigger problems later. Addressing the tough topics together is key to building trust and protecting your net worth.

1. Setting Shared Financial Goals

It’s easy to assume your partner’s financial dreams match yours. But assumptions can lead to disappointment and resentment. Sit down and talk about your long-term and short-term goals. Do you want to buy a home, travel, retire early, or start a business? How do you both define financial security? This conversation may reveal differences, but that’s okay. Finding common ground helps you work as a team and sets a clear direction for your money. Aligning on financial goals early can save your marriage and net worth by avoiding costly detours later.

2. Debt: What You Owe and How You’ll Tackle It

Debt is a source of stress for many couples. Whether it’s student loans, credit cards, or medical bills, ignoring it only makes it worse. Be honest about what you owe and how you feel about it. Are you comfortable carrying debt, or does it keep you up at night? Make a plan together to pay it down. This might mean creating a budget, consolidating loans, or cutting back on spending. Facing debt as a team builds trust and protects your net worth from ballooning interest payments.

3. Spending Habits and Budgeting Styles

Everyone has different attitudes toward spending and saving. One partner may be a saver, the other a spender. These differences can create tension—unless you talk about them openly. Discuss your habits without judgment. How much can each of you spend without checking in? Will you have joint accounts, separate accounts, or both? Set up a budget that feels fair to both of you. Regular money check-ins help keep spending in line with your shared financial goals. Open communication prevents misunderstandings and helps your net worth grow.

4. Family Obligations and Financial Boundaries

Supporting family members can strain your relationship and your finances. Maybe one of you feels obligated to help a sibling, parent, or child. The other partner might worry about how this affects your own goals. Set clear boundaries about how much you can give, and when. Talk about what happens if a family member asks for a loan or needs to move in. Being upfront about family obligations helps you protect your marriage and net worth. It also ensures you’re both on the same page when tough choices come up.

5. Planning for the Unexpected

No one likes to think about illness, job loss, or accidents. But life happens. Discuss how you’ll handle emergencies. Do you have enough insurance? How much should you keep in your emergency fund? What’s your plan if one of you can’t work for a while? These conversations might feel grim, but they’re essential for protecting your net worth and your marriage. Planning ahead means you’re less likely to panic or argue when life throws a curveball. If you need help, check out resources like the Consumer Financial Protection Bureau for tips on building emergency savings and understanding insurance basics.

6. Estate Planning and End-of-Life Wishes

This is often the most uncomfortable money conversation—and the most important. Who gets what if something happens to one of you? Do you have wills, powers of attorney, or life insurance? What are your wishes for medical care or guardianship of children? Talking about these topics now can save your marriage from future bitterness and protect your net worth from legal battles or unexpected expenses. It’s a gift to your partner and your family to make your wishes clear.

Building a Stronger Future Together

Uncomfortable money conversations may never feel easy, but they’re essential for a healthy marriage and a growing net worth. Tackling the tough topics now helps you avoid surprises, resentment, and costly mistakes. When you work together, you build a foundation of trust and teamwork. That’s the real secret to a strong relationship and financial success. The more you practice these discussions, the easier they get—and the more your net worth benefits.

What’s the toughest financial conversation you’ve had with your partner? Share your experience or tips in the comments below.

What to Read Next…

  • 7 Signs Your Marriage and Finances Are Quickly Failing
  • What Financial Planners Know About Divorce That Most Couples Don’t
  • Here Are 8 Things You Should Never Tell Your Spouse About Your Personal Finances
  • Why Are More Couples Using Prenups After Getting Married?
  • 10 Money Mistakes People Make After Losing a Spouse
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.
Filed Under: relationships Tagged With: budgeting, Debt, Estate planning, Marriage, money conversations, Net worth, Personal Finance

7 Signs Your New Partner Is Horrible With Money

October 19, 2025 by Travis Campbell Leave a Comment

money couple
Image source: shutterstock.com

Getting into a new relationship is exciting, but it also means blending your life with someone else’s habits—especially when it comes to finances. How your partner manages their money can have a huge impact on your own financial health and your future together. Noticing red flags early can save you a lot of headaches, stress, and even financial loss down the road. If you’re seeing troubling patterns, it’s worth paying attention. Here are seven signs your new partner is horrible with money, plus what you can do about it.

1. They Never Know Where Their Money Goes

One of the clearest signs your new partner is horrible with money is if they have no idea where their paycheck disappears each month. If they’re always surprised by a low bank balance or can’t explain what happened to their last paycheck, this is a big warning sign. People who don’t track their spending often struggle to save, pay bills on time, or set financial goals. It’s not about being perfect—it’s about being aware.

2. They Consistently Live Paycheck to Paycheck

Living paycheck to paycheck isn’t always a choice, but if your partner earns enough to cover basic expenses and still ends up broke every month, it’s time to take notice. This pattern often means they’re not budgeting, overspending, or ignoring savings entirely. Over time, this can lead to bigger problems, like debt or missed opportunities. If your partner shrugs off suggestions to build an emergency fund or budget together, that’s a sign their money habits could drag you down, too.

3. They Rely Heavily on Credit Cards (and Not for Rewards)

Some people use credit cards wisely, racking up points and paying off the balance each month. But if your partner uses credit cards as a lifeline, frequently carries a balance, or pays only the minimum, it’s a red flag. This behavior is a classic sign of someone who is horrible with money. High-interest debt can spiral quickly, and if they’re not working toward paying it off, it can hurt both their credit and your shared financial future.

4. They Hide Purchases or Lie About Spending

Honesty is important in any relationship, especially when it comes to finances. If you catch your partner hiding purchases, lying about what they’ve bought, or getting defensive when you ask about money, it’s time to pay attention. Financial secrecy, also known as financial infidelity, is a major sign that your partner is horrible with money. This behavior can destroy trust and make it nearly impossible to plan a future together.

5. They Don’t Save—At All

Saving money, even a little at a time, is key to financial stability. If your partner doesn’t save anything, not even for emergencies or retirement, that’s a big problem. People who are horrible with money often live only for today, ignoring the future and leaving themselves (and possibly you) vulnerable. If your partner dismisses the idea of saving or thinks it’s unnecessary, it’s time to talk.

6. They Make Big Purchases Without a Plan

Impulse buying on a small scale is common, but if your partner regularly makes large purchases—like a new phone, car, or vacation—without a plan or budget, it’s a sign they’re horrible with money. This kind of behavior can lead to debt, resentment, and serious financial setbacks. If they justify these purchases with “I deserve it” or “I’ll figure it out later,” be cautious. Responsible adults make big spending decisions with care, not on a whim.

7. They Avoid Talking About Money

If your partner shuts down every time you bring up money, refuses to discuss budgets, or gets angry when you ask questions about their finances, this is a major warning sign. Open communication is essential for any healthy relationship, especially when it comes to money. People who avoid this topic often have something to hide or are simply unwilling to grow. That’s a recipe for trouble, especially if you’re considering a future together.

Building a Strong Financial Partnership

Spotting signs your new partner is horrible with money doesn’t mean you have to give up on the relationship, but it does mean you need to address the issue early. Talk honestly about your concerns and see if they’re open to learning better habits or working together on a financial plan. Sometimes, people just haven’t had the right guidance and are willing to change. Other times, you may need to decide if their habits are a deal-breaker for your own financial goals.

Remember, your financial well-being matters just as much as your emotional health. Don’t be afraid to set boundaries and protect your future.

Have you ever dated someone who was horrible with money? How did you handle it? Share your experiences and advice in the comments below!

What to Read Next…

  • 10 Signs You’re Living Above Your Means Without Realizing
  • Are These 6 Helpful Budget Tips Actually Ruining Your Finances?
  • 7 Signs Your Marriage and Finances Are Quickly Failing
  • What If the Person Managing Your Finances Can’t Be Trusted?
  • 7 Hidden Fees That Aren’t Labeled as Fees at All
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: relationships Tagged With: budgeting, Dating Advice, Financial Red Flags, money management, Personal Finance, relationships, warning signs

9 Painful Realizations You Need to Accept Before Getting Rich

October 19, 2025 by Catherine Reed Leave a Comment

9 Painful Realizations You Need to Accept Before Getting Rich
Image source: shutterstock.com

Everyone dreams of financial freedom, but few truly understand what it takes to achieve it. The path to wealth isn’t paved with shortcuts or luck—it’s built on discipline, risk, and hard truths that most people avoid facing. If you’re serious about getting rich, you’ll need to confront some uncomfortable realities that will challenge your mindset, habits, and priorities. Accepting these truths early on can make the difference between fleeting success and lasting wealth.

1. No One Is Coming to Save You

The first painful truth about getting rich is that no one else will do it for you. Waiting for the right job, a windfall, or someone’s approval keeps you trapped in financial stagnation. Wealth comes from personal accountability and a willingness to take control of your future. Once you stop expecting help and start acting decisively, opportunities begin to appear. The moment you accept that your financial destiny depends solely on your decisions, real growth begins.

2. Discipline Beats Motivation Every Time

Motivation feels great but fades fast, while discipline keeps you consistent when the excitement wears off. People chasing wealth often underestimate how much self-control it takes to budget, invest, and delay gratification. Getting rich isn’t about one big win—it’s about hundreds of small, disciplined choices made over time. Learning to stick to your plan, even when it’s boring, separates achievers from dreamers. Building systems and habits will sustain you long after the initial spark of motivation burns out.

3. You’ll Have to Take Calculated Risks

There’s no path to getting rich that doesn’t involve some level of risk. Whether it’s starting a business, investing in markets, or changing careers, wealth requires stepping into uncertainty. Playing it too safe keeps your money stagnant and your potential capped. The key is not to gamble but to take educated, calculated risks based on research and preparation. People who learn to manage fear instead of avoiding it entirely are the ones who move ahead financially.

4. You Can’t Please Everyone Along the Way

When you start making choices that prioritize long-term financial gain, not everyone will understand. Friends might criticize your frugality, and family members may question your ambitions. But getting rich means setting boundaries and saying no to distractions that pull you off track. People who achieve success often lose the approval of those who prefer comfort over change. Accepting that not everyone will support your journey is part of growing beyond what’s familiar.

5. Time Is More Valuable Than Money

One of the hardest lessons about getting rich is realizing that time—not money—is your most precious asset. Many chase income without considering how their lifestyle eats up their hours. True wealth means creating systems that let you earn without sacrificing your freedom. This could mean building passive income streams, delegating tasks, or learning to say no to low-value activities. Once you start valuing time as your ultimate currency, your financial strategy shifts for the better.

6. Comfort Is the Enemy of Progress

Comfort is where most financial dreams go to die. The habit of settling for “good enough” keeps people from pushing toward excellence or growth. Getting rich requires embracing discomfort—learning new skills, facing rejection, and making tough sacrifices. It’s about trading short-term ease for long-term abundance. The people who thrive financially are those who step outside their comfort zone again and again, even when it’s inconvenient.

7. You’ll Fail—Probably More Than Once

Failure isn’t a detour on the road to wealth; it’s part of the map. Every successful person has lost money, made bad investments, or launched ideas that didn’t work. What separates the wealthy is their ability to learn, adjust, and keep moving forward. Getting rich demands resilience—the willingness to see setbacks as lessons rather than dead ends. Each failure teaches you something valuable about yourself and the process of building lasting success.

8. You Need to Master Emotional Control

Money triggers strong emotions—fear, greed, anxiety, and excitement—that can derail even the smartest investor. Those serious about getting rich must learn to manage emotions instead of reacting to them. Panic selling, impulsive spending, or chasing trends all stem from emotional decisions. The wealthy develop patience and perspective, allowing logic to guide their financial choices. Emotional discipline is what turns a good strategy into a lasting fortune.

9. Wealth Won’t Fix Everything

Getting rich can solve many problems, but it won’t fill emotional voids or guarantee happiness. Money amplifies who you already are—it can bring freedom and comfort, but also loneliness or pressure if not managed wisely. Many people reach financial success only to realize they never defined what fulfillment truly meant. Building wealth should be part of a balanced life, not the entire goal. Understanding this helps you pursue money with clarity, purpose, and emotional health.

The Wealth Mindset That Lasts a Lifetime

Real wealth isn’t just about numbers in a bank account—it’s about growth, responsibility, and self-awareness. Each of these painful realizations prepares you to make wiser choices and handle success with confidence. Getting rich takes more than talent or luck; it requires humility, grit, and an honest look at your habits and fears. When you accept these truths and act on them, financial success becomes not just possible—but sustainable. The journey may be uncomfortable, but the freedom it brings is worth every challenge.

Which of these hard truths about getting rich resonates most with you? Share your experiences or lessons in the comments below!

What to Read Next…

  • How Much Money Is Enough to Be Considered Truly Wealthy Nowadays?
  • 13 Profound Insights Into The Psychology of Wealth Creation
  • 10 Signs You Have a Subconscious Fear of Becoming Wealthy
  • 12 Important Truths About How Wealthy People Manage Time
  • Top 7 Passive Income Ideas for Young Adults Looking to Grow Wealth
Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.

Filed Under: Wealth Building Tagged With: financial independence, getting rich, investing, money management, Personal Finance, success habits, wealth mindset

8 Cruel Truths About Debt That Nobody Wants to Hear Loudly

October 19, 2025 by Travis Campbell Leave a Comment

debt
Image source: shutterstock.com

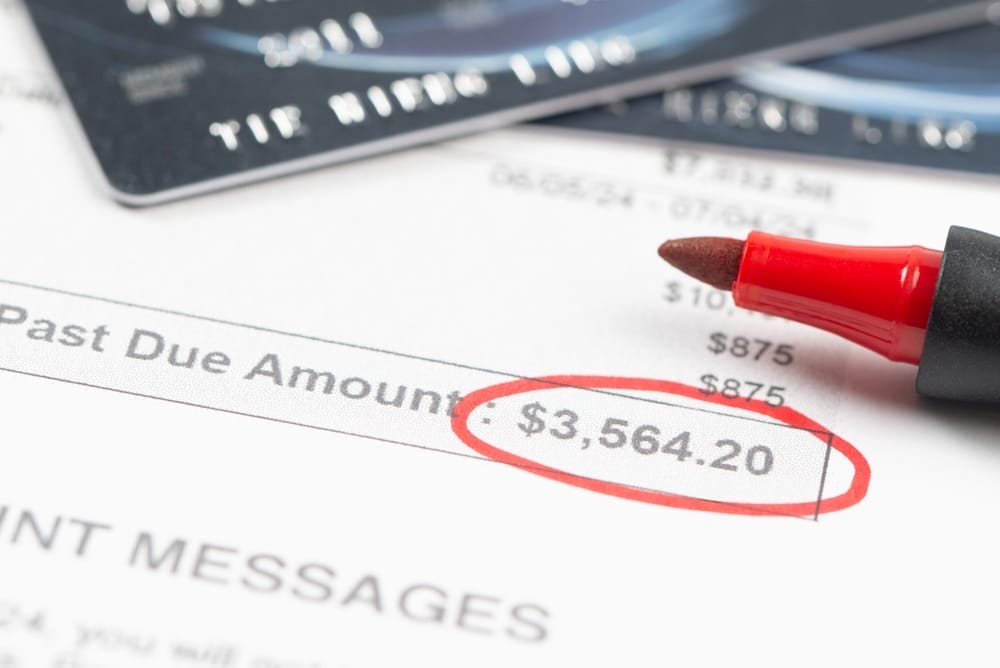
Debt is a topic most people prefer to avoid, yet it affects millions of households every day. Facing the realities of debt can be uncomfortable, but ignoring them only makes things worse. Understanding the true impact of debt is key to breaking free from its grip and building a healthier financial future. If you’re tired of sugarcoated advice, it’s time to dig into the facts that really matter. Here are eight cruel truths about debt that nobody wants to say out loud—but everyone should hear. Facing these realities can help you make smarter choices and avoid common pitfalls.

1. Debt Is Easy to Get Into, Hard to Escape

Getting into debt can happen fast. Credit card offers, personal loans, and buy-now-pay-later schemes make borrowing simple. But climbing out is a slow, painful process. High interest rates and fees can turn a small balance into a long-term burden. The truth is, it often takes years to pay off what only took minutes to borrow. Escaping debt requires discipline, sacrifice, and a plan.

2. Interest Is the Silent Enemy

Many people underestimate the power of compound interest when it comes to debt. While it can work wonders for investments, with debt, it works against you. Interest quietly adds up month after month, often outpacing your minimum payments. That means you can pay hundreds or even thousands extra over time—just for the privilege of borrowing. This is one of the cruelest debt truths because it’s easy to overlook until it’s too late.

3. Minimum Payments Keep You Trapped

Paying only the minimum on your credit cards or loans may seem manageable, but it’s a trap. Minimum payments are designed to keep you in debt longer, maximizing profit for lenders. The result? Years of payments, with little progress made on the actual balance. If you want to break free from debt, you need to pay more than the minimum—even small extra amounts can make a big difference.

4. Debt Limits Your Choices

Debt doesn’t just affect your wallet—it restricts your options. When you’re carrying balances, it’s harder to save for emergencies, invest for the future, or make big life changes like switching careers or moving. Debt can force you to stay in jobs you dislike or delay important milestones. It’s a financial leash, and the longer it’s on, the less freedom you have to make choices that matter to you.

5. Not All Debt Is “Good Debt”

Some financial experts talk about “good debt” versus “bad debt.” While certain debts—like mortgages or student loans—can help build your future, they’re still debts. Every loan comes with risk and costs, and there’s no guarantee of a payoff. Even so-called good debt can become unmanageable if your circumstances change. The reality is, all debt carries the potential to derail your finances if not handled carefully.

6. Debt Affects Your Mental Health

One of the least discussed debt truths is its impact on mental well-being. The stress of unpaid bills, collection calls, and mounting balances can lead to anxiety, depression, and even physical health problems. Money worries can strain relationships and make daily life feel overwhelming. If you’re struggling, know that you’re not alone. Seeking help—from a professional or a trusted friend—can make a difference. You can also find support through organizations like the National Foundation for Credit Counseling.

7. Ignoring Debt Makes It Worse

It’s tempting to avoid looking at your balances or skip opening bills, but denial only increases the pain. Late fees, penalty interest rates, and damage to your credit score pile up fast. The sooner you face your debt and make a plan, the better your chances of turning things around. Facing the cruel truths about debt head-on gives you the power to take back control, even if it feels uncomfortable at first.

8. Debt Can Outlast Your Income

Job loss, illness, or unexpected expenses can happen to anyone. If your income drops, debt payments don’t stop—they can quickly overwhelm your budget. In some cases, people end up using new debt just to pay off old debt, creating a dangerous cycle. Planning for the unexpected and building an emergency fund is crucial, but debt can make that nearly impossible. This is a reality that’s hard to swallow, but it’s better to prepare than to be caught off guard.

Taking Control Starts with Honesty

The harsh realities of debt are tough to hear, but knowing them is the first step to freedom. It’s not about shame or blame—it’s about understanding what you’re up against so you can make better choices. Facing the truth about debt gives you the power to change your story, one step at a time. There are resources to help, like the Consumer Financial Protection Bureau, and you’re never alone on this journey.

What’s the hardest debt truth you’ve had to face? Share your story or tips in the comments below.

What to Read Next…

  • The Benefits Of Taking Personal Loans And Their Impact On Credit Scores
  • 5 Emergency Repairs That Could Force You Into Debt Overnight
  • Are Budgeting Apps Designed To Push You Into Debt
  • 5 Things That Instantly Decrease Your Credit Score By 50 Points
  • Why Are So Many Seniors Being Sued Over Student Loans They Didn’t Take Out
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.
Filed Under: Debt Management Tagged With: credit, Debt, financial freedom, mental health, Personal Finance

7 Things A Fraudulent Financial Advisor Would Tell You to Do

October 19, 2025 by Catherine Reed Leave a Comment

7 Things A Fraudulent Financial Advisor Would Tell You to Do
Image source: shutterstock.com

Not every financial advisor has your best interests at heart. While many professionals are trustworthy and ethical, a fraudulent financial advisor can use charm and confidence to lure unsuspecting clients into costly mistakes. These bad actors often rely on manipulation, half-truths, and pressure tactics to control your money for their own gain. Knowing what to watch for can help you protect your assets, your retirement, and your peace of mind. Here are seven common red flags that signal you may be dealing with a fraudulent financial advisor—and what to do instead.

1. “You Don’t Need to Worry About the Details”

One of the most common phrases from a fraudulent financial advisor is an attempt to keep you in the dark. They’ll tell you not to worry about paperwork or disclosures because “it’s too complicated” or “they’ll handle everything.” Transparency is the foundation of ethical financial advising, so anyone discouraging you from reading documents or asking questions should raise suspicion. Real advisors take time to explain your investments and ensure you understand where your money is going. If someone avoids specifics, it’s a sign they may be hiding fees, misusing funds, or selling unsuitable products.

2. “You Need to Act Fast Before You Miss Out”

A fraudulent financial advisor thrives on urgency. They may present a “once-in-a-lifetime” investment opportunity that requires immediate action to prevent you from seeking a second opinion. This high-pressure tactic preys on fear of missing out, convincing you to skip your usual due diligence. Legitimate investments rarely disappear overnight, and credible advisors will encourage you to take time to review materials. When someone insists you decide today, it’s often because they don’t want you to discover the truth tomorrow.

3. “I Can Guarantee You Huge Returns with No Risk”

Anytime someone promises sky-high profits without risk, it’s almost certainly a scam. A fraudulent financial advisor may boast about insider knowledge or “special access” to exclusive deals. They’ll paint a picture of effortless growth to make the offer irresistible. But in reality, all investments carry some degree of risk, and reputable advisors are upfront about that. Guaranteed returns are a fantasy—so if it sounds too good to be true, it probably is.

4. “You Don’t Need to Involve Anyone Else”

Isolation is a key control tactic for a fraudulent financial advisor. They may discourage you from discussing your finances with family, friends, or other professionals. By cutting off outside input, they eliminate potential interference that could expose their lies. A trustworthy advisor, on the other hand, welcomes collaboration with accountants, attorneys, or spouses to ensure your plan aligns with your total financial picture. If someone insists you keep your decisions “between us,” consider that a major red flag.

5. “All Your Money Should Be in This One Investment”

Diversification is a fundamental rule of sound investing, yet fraudulent financial advisors often push clients to put everything into a single product or opportunity. They might claim it’s the “safest” or “most profitable” option available. In truth, concentrating your money in one place increases your exposure to loss—and makes it easier for scammers to control or steal it. Ethical advisors always design balanced portfolios that match your goals, risk tolerance, and time horizon. If you’re being told to put all your eggs in one basket, walk away.

6. “You Don’t Need to See Account Statements”

A fraudulent financial advisor will do anything to keep you from tracking your money. They might claim statements are delayed, unnecessary, or “handled internally.” This lack of transparency is how they hide unauthorized transactions or nonexistent investments. Genuine advisors ensure you have direct access to your accounts through a verified financial institution, not through them personally. If you can’t independently verify your balance or investment performance, it’s time to demand documentation—or end the relationship.

7. “You Can Trust Me, I’ve Been Doing This Forever”

Experience doesn’t always equal honesty. Fraudulent financial advisors often use charm, longevity, or fake credentials to gain trust quickly. They may flaunt impressive titles or claim to be affiliated with well-known organizations that they actually have no connection to. Instead of taking their word, always verify licenses through official channels like FINRA’s BrokerCheck or the SEC’s Investment Adviser Public Disclosure database. A credible advisor welcomes scrutiny because they have nothing to hide.

Protecting Your Finances Starts with Asking Questions

The best defense against a fraudulent financial advisor is education and vigilance. Always ask questions, request documentation, and verify everything independently. Don’t let fear, pressure, or charisma cloud your judgment when it comes to money. A legitimate advisor empowers you with knowledge, while a dishonest one hides behind secrecy and urgency. By staying informed and trusting your instincts, you can protect your wealth from those who try to exploit it.

Have you ever encountered a fraudulent financial advisor or a suspicious investment pitch? What warning signs did you notice? Share your experience in the comments below!

What to Read Next…

  • Are There Tax-Saving Strategies My Current Advisor Completely Missed?
  • 6 Signs Your Financial Advisor Is Just a Salesperson in Disguise
  • 9 Surprising Ways Your Advisor Is Making Money Off Your Insurance
  • 6 Hints You Have An Honest Financial Advisor
  • 4 Quick Methods to Verify Advisor Backgrounds Using Public Tools
Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.

Filed Under: Financial Advisor Tagged With: financial advisor red flags, financial literacy, financial scams, investment fraud, investor awareness, money protection, Personal Finance

When to Have “The Money Talk”: 5 Conversations Every New Couple Needs to Have

October 19, 2025 by Travis Campbell Leave a Comment

money couple
Image source: shutterstock.com

Starting a new relationship is exciting, but it also comes with important decisions. One of the biggest is when to have the money talk. Money can be a sensitive topic, but ignoring it can lead to misunderstandings or conflict down the road. The earlier you start, the easier it is to build trust and set healthy habits. Whether you’re just moving in together or thinking about a future as a couple, these five conversations can help you get on the same page. Let’s look at when and how to have the money talk, so your relationship starts with honesty and clarity.

1. Sharing Your Financial History

Before merging finances or making big commitments, it’s important to share your financial history. This means being honest about any debt, credit scores, savings, and spending habits. The money talk isn’t just about numbers—it’s about understanding where each of you comes from.

Set aside time for a relaxed, judgment-free conversation. Talk about student loans, credit card balances, and any financial mistakes you’ve made. You don’t need to share every detail on the first date, but before you move in together or combine finances, this transparency is key. When to have the money talk about your history? Ideally, before any joint financial decisions, so there are no surprises later.

2. Day-to-Day Spending Styles

Everyone has a different approach to spending and saving. Some people track every penny, while others are more spontaneous. Discussing your day-to-day money habits can prevent arguments and resentment in the future.

Talk about how you handle daily expenses—do you budget, use cash, or rely on credit? How do you feel about splurging on restaurants or hobbies? Sharing your expectations around spending helps you find common ground. This money talk is best had early, especially if you’re starting to share expenses or planning trips together.

3. Setting Joint Financial Goals

Once you’re comfortable talking about your personal finances, the next step is to set joint financial goals. Whether it’s saving for a vacation, a home, or paying off debt, having shared goals keeps you motivated and accountable.

Ask each other what you want to achieve in the next year, five years, or even longer. Do you want to build an emergency fund? Are you both interested in investing? Make a list of priorities and decide how you’ll work toward them together. This conversation should happen as your relationship gets more serious, especially if you’re considering major commitments like buying property or starting a family. Having the money talk about goals ensures you’re moving in the same direction.

4. Managing Bills and Shared Expenses

When you start living together or sharing expenses, it’s time for a practical money talk about managing bills. Decide how you’ll split rent, utilities, groceries, and other recurring costs. Will it be 50/50, or based on income? Who pays which bills, and how will you track them?

Consider setting up a joint account for shared expenses or using apps to keep things organized. Talk about what happens if someone’s income changes or an unexpected bill comes up. Clear communication now can prevent misunderstandings later. Have this conversation before you sign a lease or open joint accounts, so you both feel comfortable and informed.

5. Planning for the Future and Emergencies

Life is unpredictable, so it’s important to talk about how you’ll handle emergencies and plan for the future. This includes topics like insurance, wills, and what happens if one of you gets sick or loses a job. It might not be the most romantic money talk, but it’s one of the most important.

Discuss your expectations for supporting each other during tough times. Do you have enough saved for emergencies? What kind of insurance coverage do you have, and do you need more? If you have kids or plan to, talk about how you’ll save for their education or care. Addressing these issues early makes it easier to face challenges together as a team.

Building a Strong Financial Foundation Together

Having the money talk isn’t a one-time event—it’s an ongoing conversation that grows with your relationship. By tackling these five key discussions, you build trust and set yourselves up for financial success. Remember, every couple is different, so tailor your conversations to what feels right for you both.

When to have the money talk? The answer is: sooner rather than later. Honest conversations now can save stress and heartache in the future. What money conversations have you had with your partner, and how did they go? Share your thoughts in the comments below!

What to Read Next…

  • Why Are More Couples Using Prenups After Getting Married?
  • Here Are 8 Things You Should Never Tell Your Spouse About Your Personal Finances
  • 7 Signs Your Marriage and Finances Are Quickly Failing
  • What Financial Planners Know About Divorce That Most Couples Don’t
  • 10 Money Mistakes People Make After Losing a Spouse
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.
Filed Under: relationships Tagged With: Communication, couples finance, money talk, new couples, Personal Finance, Planning, Relationship Advice

8 Genius Hacks to Beat Inflation While Maintaining Security

October 18, 2025 by Catherine Reed Leave a Comment

8 Genius Hacks to Beat Inflation While Maintaining Security
Image source: shutterstock.com

Inflation can quietly chip away at your purchasing power, making groceries, gas, and even simple pleasures feel more expensive every year. But while you can’t control the economy, you can control your response to it. With a few smart financial strategies, it’s possible to beat inflation while maintaining security in both your savings and lifestyle. These practical hacks help you stretch your dollars, protect your investments, and safeguard your long-term financial health—even when prices keep climbing.

1. Optimize Your Budget for Inflation-Proof Living

Start by reevaluating where your money goes each month. Inflation can make small expenses balloon quickly, so trimming unnecessary costs keeps you one step ahead. Review subscriptions, recurring fees, and spending habits to identify easy cuts without sacrificing comfort. When you adjust your budget with intention, you create breathing room to beat inflation while maintaining security in your overall finances. Every dollar saved can be redirected toward investments or emergency reserves that strengthen your financial position.

2. Focus on High-Interest Savings and Short-Term Investments

Leaving cash in a standard savings account during inflation means losing purchasing power over time. Instead, explore high-yield savings accounts, money market funds, or short-term Treasury bills. These options offer higher interest rates while keeping your funds accessible in case of emergencies. This balanced approach allows you to beat inflation while maintaining security, ensuring that your money continues to grow without unnecessary risk. The key is finding the right mix of liquidity and return that matches your comfort level.

3. Diversify with Inflation-Resistant Assets

A diversified portfolio is one of the best tools to beat inflation while maintaining security. Consider assets that historically perform well during inflationary periods—like real estate, commodities, and Treasury Inflation-Protected Securities (TIPS). These investments can act as a buffer against rising prices while providing stable returns over time. Diversification doesn’t just protect your wealth; it creates opportunities for growth even in uncertain markets. By spreading your investments across multiple sectors, you reduce exposure to volatility and maintain long-term stability.

4. Strengthen Income Streams Beyond Your Day Job

Relying solely on one paycheck makes inflation feel even more painful. Look for ways to boost income through side hustles, freelance work, or passive earnings like rental properties or dividend stocks. Extra income not only offsets rising costs but also gives you the flexibility to invest more aggressively. Creating multiple revenue streams is a smart way to beat inflation while maintaining security in your household finances. Even small efforts—like tutoring, reselling items, or offering online services—can add up to significant gains over time.

5. Pay Off High-Interest Debt Before It Drains Your Finances

Debt with variable or high interest rates becomes even more burdensome during inflationary periods. Prioritizing repayment now saves you from paying inflated costs later. Focus on credit cards, personal loans, and other high-interest balances that eat into your budget. By reducing debt, you free up funds for savings and investments that actually build wealth instead of draining it. This proactive step helps you beat inflation while maintaining security by keeping your financial foundation strong and stress-free.

6. Shop Smarter with Strategic Bulk and Timing

Every day inflation hits hardest at the grocery store and gas pump, but a few smart shopping habits can make a big difference. Buying nonperishables and household essentials in bulk before price hikes can save money long-term. Use rewards apps, discount programs, and off-season sales to get the best deals. Planning purchases instead of reacting to them is a subtle but powerful way to beat inflation while maintaining security in your daily spending. The key is combining timing, awareness, and consistency to keep costs predictable.

7. Review Insurance and Utility Plans Regularly

Many people overlook how inflation quietly impacts premiums and service costs. Reviewing your insurance policies and utility plans at least once a year can uncover opportunities to save hundreds of dollars. Compare providers, bundle where possible, and adjust coverage levels based on your current needs. Even small reductions in monthly bills compound over time, helping you beat inflation while maintaining security in essential services. Keeping these costs optimized ensures you’re not paying for outdated or unnecessary coverage.

8. Stay Invested in Yourself and Your Skills

The most valuable hedge against inflation isn’t just financial—it’s personal growth. Acquiring new skills, certifications, or education can increase your earning potential and open doors to higher-paying roles. Investing in yourself is one of the few strategies that consistently outpaces inflation over time. Career development ensures you remain adaptable in changing markets and less vulnerable to economic pressures. It’s a forward-thinking way to beat inflation while maintaining security for both your wallet and your future opportunities.

Building Long-Term Resilience Against Rising Costs

Inflation may be a constant force, but it doesn’t have to dictate your financial future. By combining smart budgeting, diversified investments, and intentional spending, you can beat inflation while maintaining security and confidence in your finances. These hacks aren’t just about surviving economic shifts—they’re about thriving despite them. Small, consistent actions today can create lasting protection for tomorrow. The power to preserve your purchasing strength starts with the decisions you make right now.

Which of these strategies have you used to beat inflation while maintaining security? Share your best money-saving hacks in the comments below!

What to Read Next…

  • Could Ignoring Inflation Erase Decades of Savings
  • 9 Shocking Ways Inflation Affects the Middle Class First
  • 10 Times Inflation Changed What Families Could Afford Overnight
  • Could the Cost of Raising Pets Outpace Inflation Itself
  • 10 Hidden Truths About How Inflation Really Works
Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.

Filed Under: Personal Finance Tagged With: Budgeting Tips, Financial Security, Inflation, investing, money management, Personal Finance, savings strategies

Is It Too Late to Start Saving Aggressively for a Comfortable Retirement?

October 18, 2025 by Catherine Reed Leave a Comment

Is It Too Late to Start Saving Aggressively for a Comfortable Retirement?
Image source: shutterstock.com

Many people reach their 40s or 50s and suddenly realize their retirement savings aren’t where they should be. Life expenses—kids, mortgages, and career shifts—can delay financial planning longer than expected. The good news is that it’s rarely too late to start saving aggressively for a comfortable retirement. With smart strategy, discipline, and the right mindset, you can make up for lost time and still build a strong nest egg that supports the lifestyle you want later in life.

1. Assess Where You Stand Financially Right Now

Before saving aggressively for a comfortable retirement, you need a clear picture of your current situation. Start by listing all your savings, investments, and retirement accounts, along with any outstanding debts. Understanding your cash flow—how much you earn, spend, and can realistically save—creates a foundation for your next steps. Even if your balance looks smaller than you hoped, don’t let that discourage you; clarity is the first step toward progress. Once you know your starting point, you can set specific, measurable goals that fit your timeline and lifestyle.

2. Maximize Every Available Retirement Contribution

If you’re behind on retirement savings, tax-advantaged accounts are your best friend. Use your 401(k), IRA, or Roth IRA to its fullest capacity every year. Workers over 50 can take advantage of “catch-up” contributions, which allow higher annual deposits—an essential tool when saving aggressively for a comfortable retirement. Contributing the maximum not only accelerates your savings but also reduces your taxable income. Automating your contributions ensures consistency and helps you stay committed even when other expenses tempt you to cut back.

3. Reduce High-Interest Debt Before It Erodes Progress

Debt is one of the biggest roadblocks to saving aggressively for a comfortable retirement. High-interest credit card balances and loans drain your cash flow and limit how much you can invest each month. By prioritizing debt repayment, you free up more income to put toward your future. Consider the avalanche method (tackling the highest-interest debt first) or the snowball method (starting with smaller balances for quick wins). Once those debts are gone, redirect the freed-up payments directly into your retirement accounts to accelerate growth.

4. Adjust Your Investment Strategy for Growth

When time is limited, your investments need to work harder for you. Review your portfolio to ensure it’s appropriately balanced between risk and reward. Many people saving aggressively for a comfortable retirement in their 40s or 50s may benefit from slightly higher exposure to stocks or growth-oriented funds—though risk tolerance should always be considered. Diversification remains key, but avoid being overly conservative if your timeline allows for market recovery. Consulting a financial advisor can help fine-tune your investment mix for the best potential returns without taking on unnecessary risk.

5. Reevaluate Lifestyle and Spending Habits

Every dollar saved today is a step closer to financial security tomorrow. Take a hard look at your monthly expenses to identify areas where you can cut back—subscriptions, luxury purchases, or dining out can all quietly drain your budget. Redirecting even small amounts toward retirement can add up significantly over time, especially when invested consistently. Those committed to saving aggressively for a comfortable retirement often find satisfaction in delayed gratification, knowing it supports long-term freedom. A temporary spending reset can create lifelong financial peace of mind.

6. Explore Alternative Income Streams

Earning more money is one of the most effective ways to accelerate retirement savings. Side hustles, consulting work, or rental income can provide extra funds that go directly into your investment accounts. This additional income can make a noticeable difference, especially if you’re playing catch-up later in life. When saving aggressively for a comfortable retirement, it’s important not to rely solely on cutting expenses—growing income multiplies your efforts. Even part-time freelance or seasonal work can create a meaningful boost to your financial goals.

7. Plan to Work Longer or Redefine Retirement

For some, extending their career by just a few years can dramatically change their retirement outlook. Delaying retirement allows your investments more time to grow while reducing the number of years you’ll need to draw from savings. Some people choose phased retirement, scaling back hours rather than stopping work completely. Others pivot to passion projects or part-time consulting that still generates income. This approach not only strengthens your finances but also keeps you mentally and socially active while saving aggressively for a comfortable retirement.

It’s Never Too Late to Secure Financial Peace

No matter where you are in life, progress is always possible. The key is consistency, commitment, and a willingness to make changes that align with your financial goals. While starting early has advantages, those who begin saving aggressively for a comfortable retirement later in life can still achieve impressive results through focus and discipline. Every adjustment—no matter how small—moves you closer to the comfort and independence you deserve. The best time to start was yesterday; the next best time is right now.

Have you recently started saving aggressively for a comfortable retirement? What strategies have helped you catch up? Share your experience in the comments below!

What to Read Next…

  • 12 Important Considerations When Deciding Where to Retire Overseas
  • 8 Benefits Most People Don’t Know Military Retirees Get
  • Why Do Families Pay More for Private Schools Than Retirement
  • Could Your Retirement Be at Risk From Rising Utility Costs
  • 9 Expenses That Quietly Rise After Retirement
Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.

Filed Under: Retirement Tagged With: budgeting, catch-up contributions, financial freedom, investing, Personal Finance, retirement planning, savings strategy

  • « Previous Page
  • 1
  • …
  • 75
  • 76
  • 77
  • 78
  • 79
  • …
  • 190
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework