• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Insurance

6 Reasons The Hospital Won’t Give You An Itemized Bill

May 13, 2025 by Travis Campbell Leave a Comment

hospital
Image Source: pexels.com

Have you ever left the hospital and received a bill that seemed more mysterious than your diagnosis? You’re not alone. Many patients are shocked to discover that getting an itemized bill from a hospital can feel like pulling teeth, without anesthesia. Yet, understanding exactly what you’re being charged for is crucial, especially when medical bills cause financial stress in America. Hospitals often provide a summary bill, but when you ask for a detailed breakdown, you might encounter resistance, delays, or outright refusals. Why is it so hard to get an itemized bill, and what can you do about it? Let’s pull back the curtain on this frustrating process and empower you to take control of your healthcare finances.

If you’ve ever wondered why hospitals seem so reluctant to hand over a clear, itemized bill, you’re in the right place. Here are six reasons hospitals might not want you to see every line item—and what you can do to advocate for yourself.

1. Complex Billing Systems Make It Difficult

Hospital billing systems are notoriously complex, often involving multiple departments, third-party vendors, and insurance companies. Each service, medication, and supply used during your stay is tracked separately, but the final bill is usually consolidated into broad categories. This complexity isn’t just confusing for patients—it’s also a headache for hospital staff. Generating an itemized bill requires extra time and effort, and many hospitals simply aren’t set up to do it quickly. Even billing professionals sometimes struggle to decipher these charges. The result? Hospitals may avoid providing itemized bills to save themselves the hassle.

2. They Don’t Want You to Spot Errors or Overcharges

Let’s face it: medical billing errors are common. Studies have found that up to 80% of medical bills contain mistakes, from duplicate charges to services you never received. When you request an itemized bill, you’re more likely to catch and challenge these errors. Hospitals know this, and some may be reluctant to provide detailed bills because it opens the door to disputes, corrections, and potentially lost revenue. Keeping the bill vague reduces the chances you’ll question the charges.

3. Insurance Negotiations Complicate Transparency

Hospitals negotiate different rates with each insurance company, and these rates are often confidential. When you ask for an itemized bill, you might see the “list price” for services, which can be dramatically higher than what your insurer actually pays. Hospitals may worry that providing this information could lead to confusion or disputes with both patients and insurers. Additionally, they may fear that greater transparency could undermine their negotiating power with insurance companies. This lack of transparency can leave patients in the dark about what they truly owe and why.

4. They Hope You’ll Just Pay the Summary Bill

Hospitals know that most patients are overwhelmed after a medical event and just want to move on. By sending a summary bill with a lump sum, they’re betting you’ll pay it without asking too many questions. The process to request an itemized bill can be time-consuming and frustrating, which discourages many people from pursuing it. Hospitals may intentionally make it difficult to get a detailed bill, hoping you’ll give up and pay the amount due. This tactic works surprisingly well, especially when patients are dealing with the stress of recovery.

5. Administrative Costs and Staffing Limitations

Providing itemized bills isn’t just about printing a longer document—it often requires additional administrative work. Hospitals may need to pull records from multiple systems, verify charges, and ensure accuracy before sending the bill to you. Many hospitals prioritize other tasks over detailed billing requests due to staffing shortages and tight budgets. This is especially true in smaller facilities or those with limited resources. The extra work involved in producing itemized bills can be a deterrent, leading hospitals to avoid offering them unless absolutely necessary.

6. They Want to Avoid Disputes and Negotiations

When you see every charge spelled out, you’re more likely to question high prices or ask for discounts. Hospitals know that itemized bills can lead to more disputes, negotiations, and even formal complaints. By keeping the billing process opaque, they maintain more control over the conversation and reduce the likelihood of having to justify their prices. This lack of transparency can be frustrating, but it’s a deliberate strategy to minimize pushback and keep the payment process as smooth as possible for them.

Take Charge: How to Get the Itemized Bill You Deserve

The first step toward financial empowerment is understanding why hospitals hesitate to provide itemized bills. But you don’t have to accept a vague summary bill. Start by requesting an itemized bill in writing, either by email or certified mail, and keep records of all your communications. If you encounter resistance, remind the hospital that you have a right to see a detailed breakdown of your charges. In some states, hospitals are legally required to provide itemized bills upon request—check your local regulations for specifics. If you spot errors or questionable charges, don’t hesitate to dispute them. You can also seek help from a medical billing advocate or contact your state’s consumer protection office for assistance. For more tips on navigating medical bills, visit the Centers for Medicare & Medicaid Services’ guide to understanding your medical bills.

Remember, the more you know about your hospital bill, the better equipped you are to protect your finances and avoid unnecessary expenses. Don’t let the complexity of the system intimidate you—ask questions, demand transparency, and advocate for your right to an itemized bill.

Have you ever struggled to get an itemized hospital bill? What did you discover when you finally saw the details? Share your story in the comments below!

Read More

4 Ways to Prevent Dental Costs from Bankrupting You

Strategies for Handling Unexpected Expenses

Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Health & Wellness Tagged With: financial advice, healthcare costs, hospital billing, Insurance, itemized bill, medical bills, medical errors, patient rights

7 Things You Should Know Before Filling Another Prescription

May 12, 2025 by Travis Campbell Leave a Comment

Assorted pharmaceutical medicine pills, tablets and capsules and
Image Source: 123rf.com

Have you ever found yourself standing at the pharmacy counter, prescription in hand, wondering if you’re making the right choice for your health and your wallet? You’re not alone. With the rising healthcare costs and the increasing complexity of medications, it’s more important than ever to be an informed consumer. Filling a prescription isn’t just a routine task—it’s a decision that can impact your finances, your well-being, and even your long-term health. Before you hand over your insurance card or swipe your credit card, you should know a few crucial things. Before filling another prescription, let’s dive into the seven things you should always consider.

1. Understand What You’re Taking

Before filling any prescription, ensure you know exactly what the medication is for and how it works. Don’t be afraid to ask your doctor or pharmacist questions like, “What does this medication do?” or “How will it help my condition?” Understanding your prescription can help you spot potential side effects, avoid drug interactions, and avoid unnecessary medications. According to the FDA, knowing your medications is the first step in preventing harmful drug interactions. Remember, knowledge is power—especially when it comes to your health.

2. Check for Generic Alternatives

Did you know that generic drugs can be just as effective as their brand-name counterparts, but often cost a fraction of the price? Before filling your prescription, ask your doctor or pharmacist if a generic version is available. The FDA regulates generics to ensure they meet the same standards for quality, strength, and purity as brand-name drugs. According to GoodRx, switching to generics can save you hundreds of dollars yearly without sacrificing effectiveness. Always check if you can make the switch—it’s a simple way to keep your healthcare costs in check.

3. Review Your Insurance Coverage

Prescription drug coverage can be confusing, but knowing what your insurance will and won’t pay for is essential. Before you fill your prescription, check your plan’s formulary (the list of covered drugs) to see if your medication is included. If it’s not, you could be stuck with a hefty bill. Some insurance plans require prior authorization or have preferred pharmacies that offer lower copays. Taking a few minutes to review your coverage can save you from unexpected expenses and headaches down the road.

4. Ask About Potential Side Effects

Every medication has potential side effects, some mild and some more serious. Before you fill your prescription, ask your healthcare provider or pharmacist about the most common side effects and what to watch out for. This knowledge can help you spot problems early and seek help if needed. For example, some medications can cause drowsiness, upset stomach, or even more severe reactions. Being proactive about side effects can help you stay safe and avoid unnecessary discomfort.

5. Compare Prices at Different Pharmacies

You might be surprised to learn that the price of the same prescription can vary widely from one pharmacy to another. Before you fill your prescription, take a few minutes to compare prices at local and online pharmacies. Tools like GoodRx and pharmacy discount cards can help you find the best deal. Sometimes, paying cash with a discount card is cheaper than using your insurance. Don’t assume your regular pharmacy always offers the lowest price—shopping around can lead to significant savings.

6. Consider Mail-Order Pharmacies

If you take a medication regularly, mail-order pharmacies can be a convenient and cost-effective option. Many insurance plans offer mail-order services that deliver a 90-day supply of your medication right to your door, often at a lower cost per dose. This can save you time, money, and trips to the pharmacy. Just make sure to plan ahead, as mail-order prescriptions can take a week or more to arrive. If you’re interested, ask your insurance provider or pharmacist how to get started with mail-order prescriptions.

7. Double-Check for Drug Interactions

If you’re taking more than one medication, it’s crucial to check for potential drug interactions. Some drugs can interact in ways that reduce effectiveness or cause harmful side effects. Always provide your pharmacist with a complete list of your medications, including over-the-counter drugs and supplements. The FDA recommends reviewing your medication list regularly to avoid dangerous combinations. Don’t leave your safety to chance—double-check for interactions every time you fill a new prescription.

Make Every Prescription Count

Filling a prescription is more than just a quick errand—it’s an opportunity to take control of your health and your finances. You can make smarter, safer choices by understanding what you’re taking, checking for generics, reviewing your insurance, asking about side effects, comparing prices, considering mail-order options, and double-checking for drug interactions. Remember, being proactive about your prescriptions can lead to better health outcomes and more money in your pocket. The next time you’re at the pharmacy, take a moment to ask questions and explore your options. Your health—and your wallet—will thank you.

What’s your best tip for saving money or staying safe with prescriptions? Share your experiences in the comments below!

Read More

How to Take Control of Your Finances and Get Out of Debt

5 Important Things to Consider Before Making an Investment Decision

Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.
Filed Under: Health & Wellness Tagged With: drug interactions, generic drugs, healthcare costs, Insurance, medication safety, Personal Finance, pharmacy tips, prescription drugs

Rain, Snow, Fire: Bad Weather Is Changing the Insurance Industry

March 28, 2025 by Latrice Perez Leave a Comment

Bad Weather
Image Source: 123rf.com

The year 2025 has witnessed an unprecedented surge in severe weather events, fundamentally altering the landscape of the insurance industry. This article explores how extreme weather conditions are driving up premiums, causing record losses, and reshaping market dynamics. It examines the adjustments insurers are making to adapt to an era marked by uncertainty and environmental challenges. Read on to understand the profound impact of climate change on insurance practices.

Escalating Insurance Premiums

The increasing frequency and severity of natural disasters have forced insurers to raise property and casualty premiums, particularly in high-risk areas. Homeowners in states like Tennessee have seen significant premium hikes due to recent storms and tornadoes. These adjustments are a direct response to the escalating costs associated with higher claim volumes. Insurers are recalibrating risk models to better reflect the current climate realities. Consumers must now navigate a market where insurance is becoming an increasingly expensive necessity.

Record-Breaking Wildfire Losses

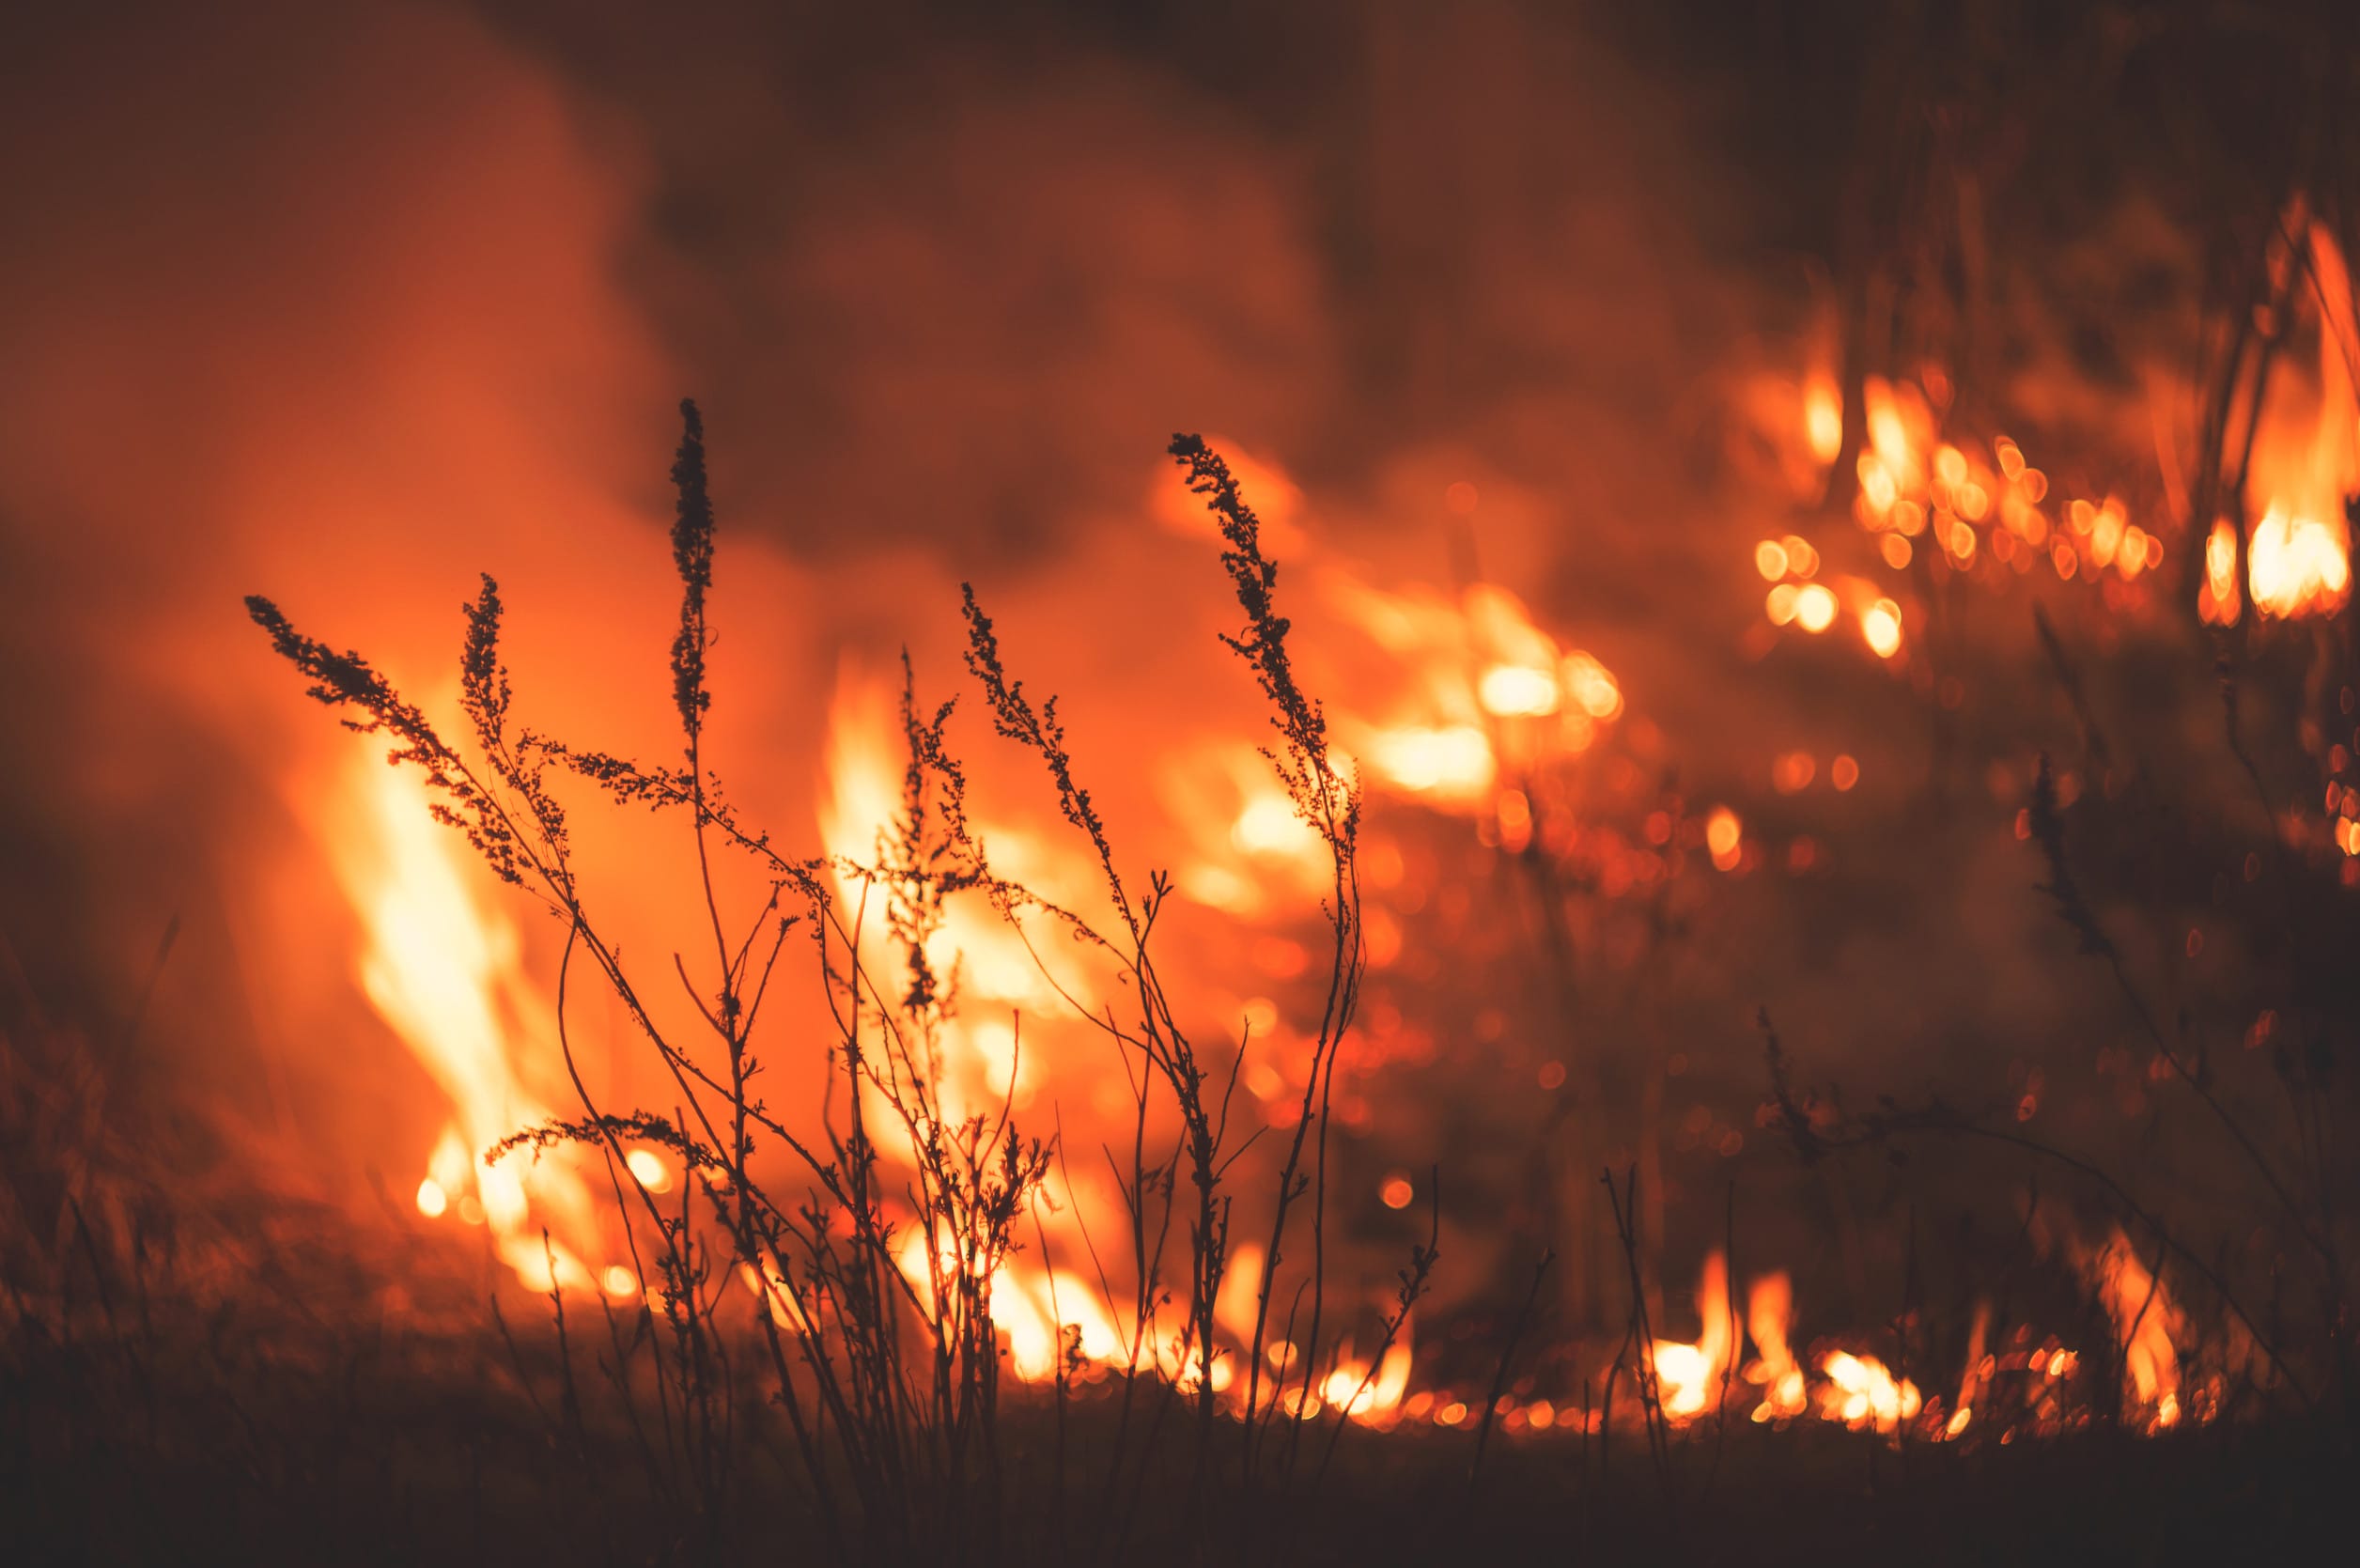
The raging flame of fire burn in the fields, forests and black thick acrid smoke. Big spring wildfire close-up.
Image Source: 123rf.com

Recent wildfires, particularly in Southern California, have led to record-breaking insured losses that exceed previous historical benchmarks. The devastation from these fires has strained insurers and forced a reevaluation of risk models. With losses projected to surpass $20 billion, the financial impact on the industry is immense. These events underscore the vulnerability of regions prone to wildfires and the need for improved preventive measures. The situation has sparked urgent discussions about better disaster management and policy structuring.

Increased Reinsurance Costs

Global reinsurers are now facing mounting losses as a result of climate change-induced disasters, driving up reinsurance costs. These increased costs are often passed down to consumers in the form of higher premiums. For example, the recent Los Angeles wildfires have had a noticeable impact on reinsurance rates. This ripple effect makes insurance less affordable for many policyholders. As a result, the overall landscape of insurance pricing is undergoing significant transformation.

Emergence of Insurance Deserts

In regions frequently affected by extreme weather, insurers are reassessing their willingness to provide coverage, leading to the emergence of so-called ‘insurance deserts.’ Homeowners in these high-risk areas may find it increasingly difficult to secure affordable coverage. This trend raises concerns about the accessibility of essential insurance for those most in need. The lack of available options can exacerbate the financial vulnerability of affected communities. Addressing this challenge requires coordinated efforts between regulators and insurers.

Regulatory Responses and Market Stabilization Efforts

In response to the volatile insurance landscape, lawmakers in various states are proposing measures to stabilize the market. Initiatives such as state-backed funds and regulatory reforms aim to keep insurance accessible and affordable. These efforts are designed to address the dual challenges of rising premiums and increasing claim volumes. Collaborative measures between the public and private sectors are essential for long-term market stability. Consumers and insurers alike are closely watching these regulatory developments for signs of relief.

The Weather Has Reshaped The Insurance Industry

The severe weather events of 2025 have reshaped the insurance industry in profound ways, from escalating premiums to the emergence of insurance deserts. As climate change continues to influence weather patterns, both insurers and consumers must adapt to a new financial reality. Proactive measures, improved risk assessments, and regulatory interventions are vital for navigating these changes. The evolving landscape calls for a reassessment of traditional insurance models.

How have recent weather challenges affected your insurance experience? Share your insights in the comments below!

Read More:

False Sense of Security: Why Relying Solely on a Fence Could Leave You Vulnerable

Think You’re Safe Without Flood Insurance? 7 Dangerous Lies Insurance Companies Tell

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.

Filed Under: Insurance Industry Tagged With: climate change, Insurance, market trends, premium increases, risk assessment, severe weather

In Defense of Financial Advisor Fees

August 28, 2023 by Joe Saul-Sehy 20 Comments

I was a fee hater.

Like a younger, more handsome John Bogle, I would rail on fees. I’d stand on every rooftop screaming about avoiding fees at all cost.

For this reason, when I was a financial advisor, I provided what I thought was top-notch service and undercharged for it every day.

How much did I charge? My minimum fee was $500 per year.

Undercharged? There is no such thing, Joe! Less fees = better. Duh! You should have charged $300!

Think so, do you? Sit close, young padewan, while Uncle Joe tells you a story:

My Experience With Fees

Early in my career I lucked into the opportunity to give speeches on behalf of one of the top advisors in the country. I’d fly wherever he wished and spoke to rooms full of people about good planning. In exchange, he allowed me to move my offices into his suite.

Awesome! What a break for a new advisor; I’d get to see the inner workings of a well-honed operation and maybe glean some tips.

At first I was disappointed. All I saw was what looked like a cookie-cutter assembly line of advice and deliverables. Many clients received offshoots of similar advice. The firm never stuck their neck out. They avoided complex situations at all cost.

That lead me to believe that he was among the best in the country only because he could “sell” people on ways he’d jack up their fees.

…and jack he did. I rarely saw him charge less than $2,500 for planning, then garner asset management fees on top of that. He was a fee-based selling machine.

One day the operations manager and I were talking. I asked a polite question about how redundant their process management workflow seemed. To give you an idea of what I thought about this guy: I’m sure the term “cocky smartass” wouldn’t be far off the mark.

He said, “Have you noticed that we charge five times what you charge?”

I smiled. “Yes.” What a loser. I could never charge what they did! They were just leeches, skimming off of their client’s blood.

He said, “We charge five times more because we’re five times better than you.”

I took it personally.

I shouldn’t have.

Three months later, we were in agreement:

he was five times better than me.

Why He Was Better

This planner was so good, I’d worked right under his nose and hadn’t noticed his skill. The systems were sublime. Where I’d seen cookie-cutter assembly lines before, now I saw a brilliant asset allocation arrangement. Where I’d believed he was charging excess dollars to put boring plans in place, he was dotting every “I” and crossing every “T” for clients…mostly doing the boring stuff that usually was swept under the rug.

In short, he had a proven system of asset management and plan building. If you wanted that service, he covered his costs with his fees. If you didn’t want it, you should probably look elsewhere.

He didn’t try to be everything to everyone.

What You Can Learn

You don’t have to pay $2,500 or more to some advisor if you’re willing to perform the critical tasks that this advisor captained for his clients:

1) Design a plan that covers the six areas of financial planning and rigorously maintain the plan according to a set schedule. Make sure everyone involved is up-to-speed with the details.

2) Build a system to check and maintain your assets against your plan. He had systems in place to notify him when assets deviated too much from the plan. Build your own set of alarms.

3) Carefully guard against taxes and excess fees. This seems like an oxymoron, because this advisor charged a ton of money, but his fees were largely performance based. To increase his fees (and his client’s net worth) he had to ensure the plan was a lean-mean-return-gathering-machine. The only way to do that was to develop a comprehensive tax strategy (example: tax efficient investments outside of IRAs while tax-eaters inside shelters) and low-cost investments.

4) Scour insurances for opportunities. This advisor would review all of his client’s insurances regularly (every two years) to find wasted money. He’d also use insurances wisely to plug holes. One place he nearly always recommended: disability coverage.

5) Build legacies. He was the adamant that everyone either had a family or charitable organization they’d want to have flourish if they couldn’t use their own money. He’d make sure that the estate plan was air-tight and (as with insurance) review these plans every two years.

6) Set communication systems. Clients received a newsletter every six weeks. There was a conference call scheduled for two quarters of the year, along with two face to face meetings. Generally, the face to face meetings were comprehensive and the phone calls were “just checking up.” While he “allowed” only one member of a marriage to take part in phone calls, he was adamant that both spouses attend meetings. He’d become especially irate if one didn’t understand finances and didn’t want to participate. His thinking: if the knowledgeable spouse passed away, the other was screwed.

He also wasn’t afraid to call every client when markets imploded. During the 2002 and 2008 crisis, his whole team was on the phone non-stop, sharing information and passing along strategies. Usually, he wasn’t changing course, because his asset allocation model was already designed to weather downturns. However, clients loved hearing from him.

Was some of this overkill? Maybe. Often insurance and estate planning needs didn’t change. However, when something did, the advisor was on top of it fairly quickly.

It’s a Choice

During my 16 years as an advisor, there were many clients who refused to pay fees even though they would have been far better off had they paid this advisor. It’s fine to accomplish your financial goals without an advisor (in fact, if you’re willing to complete the six steps above, I’d recommend it). But if you decide not to, make sure you’ve designed systems for success and aren’t just being cheap.

Financial planning is just one example. Are there areas of your life where you’d be better off paying a fee and you just can’t do it? Are you cheap?

(Photo credit: Hands Clenching Dollars, Muffett, Flickr; Couple and Advisor, Jerry Bunkers, Flickr)

Enhanced by Zemanta
Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: Hiring Advisors, money management, Planning, successful investing Tagged With: advisor fees, Assembly line, Asset, Fee (remuneration), Financial adviser, financial planner fees, financial planning fees, Financial services, Insurance, John Bogle, what do advisors charge

Five Financial Questions Women Should Ask About

June 9, 2022 by Claire Hunsaker Leave a Comment

It’s no secret that women face unique financial challenges. From the gender pay gap, to managing household finances, it can be tough for us to make informed decisions about our money. To empower ourselves and make sure we’re on the right track financially, we need to ask the right questions. Here are some of the most important ones.

What Insurance Should I Have?

Insurance is a big (and often surprising) topic for women: we live longer, are more likely to experience a disability that impacts our earnings, and are more likely to support children or elders. We have a stronger need for a safety net.

As a high-level guide: max out any employer-sponsored coverage (like through your job) and then get an individual policy for the remainder of your need, as your budget accommodates.

Life Insurance

Life insurance is a tax-free gift you give the next generation, and term life insurance is inexpensive. Buy what you can afford, on the private market or through your employer.

Disability Insurance

Disability insurance is so important for women – it will replace a portion of your income if you can’t work, and you want to target 60% and 70%. Especially if you are a single mom or supporting family. To achieve this target, you will probably need a private policy in addition to any coverage from your employer (if available).

Long-Term Care Insurance

And finally, if you’re approaching retirement, long-term care insurance is important if you want to make sure you don’t have to spend all of your savings on health care in retirement. It can be very expensive, so don’t purchase this til you’re older and approaching the need for it.

These are just general guidelines – there’s no one right answer when it comes to insurance. It’s important to talk to an expert (like a financial planner) about what kind of coverage makes sense for you given your unique circumstances.

What is the Best Way to Budget?

There’s no one right way to budget your money – find the method that works best for you and stick with it! Consistency is much more important than perfection.

The Envelope Method

Some people use the “envelope system” where you put a certain amount of cash into an envelope for each category (like groceries, entertainment, and transportation). That’s all you get for that category for the month. This is great if you have to be very careful and want to stay away from credit cards entirely. It’s also a great system if you like using a physical planner over software/apps.

Budgeting Apps

If you prefer using technology to manage your finances, there are a number of great budgeting apps out there that can help you track your spending and set goals. Some popular options include Mint, You Need a Budget (YNAB), and EveryDollar.

Spreadsheet Budgeting

For those who like having more control over their budget (and who are comfortable with Excel or Google Sheets), creating a budget in spreadsheet form can be a great option. This method gives you a lot of flexibility to track your spending in the way that makes the most sense for you.

Pay Yourself First

One of the best ways to make sure you’re saving enough money is to “pay yourself first.” This means that as soon as you get paid, you put some money into savings before you spend any of it. This can be difficult at first, but if you make it automatic (i.e., set up a direct deposit from your paycheck into your savings account), it will become easier over time.

What is the best way to save money?

Again, there is no one right answer to this question – it depends on your goals and financial situation. But the upshot is that you can build an emergency fund or improve your generational wealth. Here are some general tips that can help you get started:

Increase Your Income

It can be very challenging, but to save money, you need to bring in more money than you spend. You can lower your costs and watch your spending, but you can also increase your income through a side hustle, a raise at work, or a promotion. You could sell extra things around your house. You don’t need to make a huge commitment – even small improvements in your earnings can make a big difference.

Automate Your Savings

Set up automatic transfers from your checking account to your savings account so that you’re automatically putting away money each month. This is a great way to make sure you’re always saving something, even if you don’t have a lot of extra money.

Join a Savings Challenge

A savings challenge is a great way to encourage you to save more money and get some community support. There are all kinds of challenges out there (like the 52-week challenge, where you save $52 in week one, $51 in week two, and so on), but the important thing is that you find one that works for you and stick with it. Dasha Kennedy at the Broke Black Girl runs a great year-long savings challenge to help women save $1000.

How Much Do Women Need to Save For Retirement?

As much as you can.

Women retire disadvantaged: we generally receive lower social security benefits due to lower earnings. We also tend to live longer (which means more years in retirement), and we’re more likely to experience a period of disability. All of this points to the need to have a larger retirement nest egg.

Target 20% Savings

Controversial opinion: I encourage all women to target 20% of pre-tax household income for savings. That is a lot. But most of us are playing catch up, and starting from lower earnings. Build up to it by increasing your savings rate little by little, and remember that even small amounts add up over time.

Invest Your Savings

You want to make sure your money is working hard for you, and one of the best ways to do that is to invest it. Investing can be intimidating, but on average, female investors outperform by 1% because we are less likely to panic. 1% is what professional investment advisors charge. Set up auto investment, choose low fee index funds and increase your contribution little by little. Like saving, successful investing is about consistency and patience.

What Biggest Money Mistake Should Women Avoid?

The biggest mistake you can make is to hand your finances off to a partner and ignore them. Women are socialized to do this (and it’s changing, slowly) but we pay for it. If you are widowed or experience divorce, you will be adding a terrifying and steep learning curve to a personal crisis.

Additionally, and I say this as Chief Financial Officer of our family, financial decisions will be better with your input! Even though I do this for a living, my husband often has great insight and our decisions benefit from his involvement. Don’t discount your ability or perspective, especially given that women are better investors.

Claire Hunsaker
Claire Hunsaker

Claire Hunsaker, ChFC®, is a Chartered Financial Consultant featured in American Express, Forbes, Parents, Real Simple, and Insider. She offers free financial planning for single women through AskFlossie, where she is CEO. Claire holds an MBA from Stanford and is an IRS-certified Tax Preparer. She has 20 years of business and leadership experience and approaches money topics with real talk and real humor.

askflossie.com/

Filed Under: budget tips, Insurance, money management, Personal Finance, Planning, Retirement Tagged With: emergency fund, Financial plan, Insurance, investing, life insurance, retirement planning, saving money

Every Homeowner Should Have Flood Insurance-Here’s Why!

May 17, 2021 by Tamila McDonald Leave a Comment

every homeowner should have flood insurance

No homeowner imagines being the victim of a natural disaster. A serious flood can be devastating. Floods can damage your home and personal property with surprising speed. However, not having flood insurance can make the entire situation worse. Without the right coverage, your losses may not be covered. If you’re wondering why every homeowner should have flood insurance. Here’s what you need to know.

What Flood Insurance Is and What It Covers

Flood insurance is a type of coverage that is separate from a traditional homeowners insurance policy. Anyone who lives in an area with flood risk can potentially purchase this supplemental policy.

It specifically focuses on flood-related damage caused by natural disasters, as well as other causes. Usually, flood insurance covers damage in specific categories.

First, flood insurance will commonly handle structural damage to your home. This includes the actual building, as well as some related systems, like electrical, plumbing, and HVAC.

Second, flood insurance may cover your personal property. This includes damaged furniture that isn’t salvageable and similar household items, as well as clothing. However, this isn’t always part of the starting flood insurance policy, so you may need to request it be added if you want this protection.

Now, certain high-value items may not be fully covered by base flood insurance. This can include art, antiques, jewelry, firearms, or electronics above a certain value. In those cases, you may need flood insurance riders to add that coverage, just as you do with traditional homeowners policies.

Additionally, it’s important to note that every policy is different. Before you make assumptions about your coverage, review your flood insurance policy carefully. Ask questions about what is and isn’t protected, and request add-ons if needed to provide you with the level of protection you’re after.

Why Homeowners Need Flood Insurance

Typically, flood insurance fills a gap that many homeowners have in the primary policy. While homeowners insurance does cover some types of water damage under the hazard insurance segment of their policy, flooding events usually aren’t classified as the covered kind of hazard. As a result, damage caused by a flood may not be covered, leaving you without financial support to repair your home or replace your personal property.

Essentially, if you don’t have flood insurance, you’ll have to handle all related costs out of pocket. For most homeowners, this simply isn’t feasible. Flood repairs to a structure can be incredibly costly. Similarly, replacing all of your damaged personal belongings could take thousands and thousands of dollars.

It’s also important to note that homeowners with mortgages who live in higher-risk areas may be required by their lender to have flood insurance. This is especially true for anyone who uses government-backed financing sources, as there are federal laws requiring the coverage for properties they finance in high-risk zones. However, other lenders often follow suit, even if there isn’t a legal requirement.

The mandate for flood insurance through a company like this Minneapolis water damage restoration service, is similar to them requiring homeowners insurance in general. It ensures the property is protected should a flood event occur and, since the lender is technically the owner until you pay off the mortgage, they have a vested interest in protecting its value.

How to Find Out if You’re in a High-Risk Flood Area

If you want to see if a property is in a high-risk flood area, the simplest way is to use the Federal Emergency Management Agency (FEMA) Flood Map Service Center. Simply enter your address into the search bar, and the site will display a map that identifies your home’s risk level.

You may be able to turn to other state and local resources as well. State emergency management agencies may have flood maps, for example, so they can be worth checking if you find the FEMA results lacking.

Should Low-Risk Property Owners Skip Flood Insurance?

No, homeowners in low-risk areas shouldn’t skip flood insurance. Even if you live in a low-risk area, going without flood insurance means you aren’t protected should the unexpected occur.

Low-risk doesn’t mean risk-free. Many natural events are unprecedented. But even if they weren’t deemed likely, your base homeowners policy won’t cover the related damage if it is excluded in your policy.

Additionally, risk levels can change over time. An area that wasn’t previously flood-prone can suddenly become so for a variety of reasons. Climate change, land development, and similar shifts can alter water flow through regions, turning areas that previously didn’t experience flooding into moderate or high-risk areas.

Where to Get Flood Insurance

If you need flood insurance, you can call your homeowners insurance company to see if they offer it. Some insurers have flood insurance riders, while others may require a separate policy for that specific kind of coverage.

However, not all insurance companies offer flood insurance. If that’s the case, you may not be able to secure flood insurance through your homeowners policy provider. Instead, you’ll turn to the National Flood Insurance Program, a system run by FEMA, that can help you find a provider that covers homeowners in your area.

Do you think every homeowner should have flood insurance?  Have you decided to risk it and go without flood insurance? Has flood insurance ever saved you from financial hardship? Share your thoughts in the comments below.

Read More:

  • Which Life Insurance Fits Your Needs Best
  • Top Reasons You Need Car Insurance
  • Is Cheap Insurance Worth It?
Tamila McDonald
Tamila McDonald

Tamila McDonald is a U.S. Army veteran with 20 years of service, including five years as a military financial advisor. After retiring from the Army, she spent eight years as an AFCPE-certified personal financial advisor for wounded warriors and their families. Now she writes about personal finance and benefits programs for numerous financial websites.

Filed Under: Insurance, Personal Finance Tagged With: flood insurance, Insurance

Lower Your Homeowners Insurance Costs by Getting a CLUE

September 12, 2013 by Joe Saul-Sehy 2 Comments

Scoring a CLUE report might help you avoid nasty surprises with your homeowners coverage.

The majority of homeowners do not have a clue when it comes to the insurance industry database known as CLUE, despite the fact that this computerized tracking system can significantly impact their insurance premiums. If your property becomes red flagged within the system, for example, you may see your rates skyrocket for no apparent reason.

What is CLUE?

The Comprehensive Loss Underwriting Exchange is essentially a vast computer database that keeps track of insurance claims for properties all over the United States. Insurance companies who pay a fee to subscribe to CLUE are provided with up-to-date reports related to information about damage to properties or insurance claims to pay for repairs. Those insurers can then use that data to help them make decisions about who to insure, how much to charge for insurance, and so forth. CLUE also offers similar services to track auto insurance information.

Your Home’s Track Record

In a way, CLUE is kind of like a credit reporting agency. Each of us has a credit history, or should, and credit bureaus keep track of that history by filling our confidential files with information pertaining to things like income, our ability to repay loans on time, and how much debt we carry. When you apply for credit the lender will analyze your credit report and decide whether or not to lend to you. Similarly, insurance companies rely on CLUE to help them manage their risks when issuing homeowner’s or auto insurance policies. There are no laws that prohibit this kind of reporting and it is perfectly legal for insurers to use the data for underwriting or rating purposes.

What’s in a CLUE Property Report

Your home’s CLUE report will contain information like the name on your homeowner’s policy and a description of the home that’s insured. Beyond that basic data, however, it also shows claim information. If you filed a claim after a tree fell on your house during a hurricane, for instance, the CLUE report will probably show the date you filed your claim and how much the insurance company paid you to cover your losses. CLUE maintains those kinds of records for up to seven years. The insurance company will check your CLUE report when you apply for insurance and if they find you have multiple expensive claims, they may be reluctant to insure your home or even raise your premiums.

Nightmare Scenarios

About 10 years ago, when the use of CLUE was gaining widespread acceptance and popularity within the insurance industry, several news outlets reported on some of the more harrowing CLUE-related homeowner experiences. One couple said they bought a home, for example, and two months later their homeowner’s insurance premiums rose by more than $200. The insurance company explained that, three years prior to purchasing the property, there was a claim against it, and based on that claim the premium had been adjusted upward. Before long, the insurance company dumped them and cancelled the policy.

Negative Impact Even without Filing Claims

Other consumers said they wound up in the database even though they never filed a claim. Some homeowners told their insurance agents that there was damage to their home after vandalism or an accident, but that they were going to pay for the repairs out of pocket instead of filing an official claim. Just because they shared that information with the insurer, however, the damage report went into their CLUE report. One homeowner said that after he paid for flood damage himself – but told his insurance company about the incident – they cancelled his policy. That was despite the fact that he never filed a claim in 30 years as a loyal customer.

Access to Your CLUE Report

The bottom line is that if you own a home, it’s a good idea to obtain a copy of your CLUE report and scan it for errors that could impact your insurance. If you are planning to buy a home, you may want to ask the seller to show you a copy of a recent CLUE report, just to make sure you aren’t buying a property that could have exceptionally high insurance costs. CLUE reports are, incidentally, protected by the Fair Credit Reporting Act and can only be accessed by the owner or lender for the property.

To receive your report, call toll free at 1-866-312-8076 or visit the website personalreports.lexisnexis.com, and request it. Should you discover any mistakes or discrepancies, you can report them directly to LexisNexis – the company that now operates CLUE. They will be obligated to get in touch with your insurance company, investigate your complaint, and notify you of the results of their inquiry within 30 days. You also have the right to submit an explanation in writing – basically telling your side of the story – so that LexisNexis can include that statement in future CLUE reports.

Tom Kerr writes for CompareWallet.com in addition to others. He has been an avid writer for years, even winning awards for work he’s done.

Enhanced by Zemanta
Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: Insurance Tagged With: CLUE, coprehensive loss underwriting exchange, Fair Credit Reporting Act, Financial services, Home insurance, Insurance, LexisNexis

Three Steps to an Iron-Clad Protection Plan

April 18, 2013 by The Other Guy 11 Comments

“No one knows the day or the hour…”

Unfortunately, that phrase is so true.  We here in the O.G. house, along with the whole FFA crew, join those across the world in thinking about (dare I say ‘praying for’) those impacted by the terrorism in Boston, the terrible storms in the Midwest, and the explosion in Texas.  The phrase “when it rains, it pours” comes to mind.

These recent events have encouraged me–nay, they’ve compelled me, to write another bit about protection planning.  There are three crucial pieces to a well-designed protection plan and collectively, they are the single most important part of your overall financial plan.  I don’t care what funds you use, what your company 401(k) match is, or even how many pre-IPO shares of Google you own – without an adequate protection plan in place, you have nothing.

Are you worried about your protection strategy? Here are three steps to an iron-clad protection plan.


Step 1:  Forget the 6 months notion – head right to 12 months of cash


Many financial professionals suggest three to six months worth of expenses in a cash reserve position.  That’s baloney.  If you were sick or injured, would you want to be counting backwards from 90 until you run out of money?  I didn’t think so.  Skip three months and six and head right to 12 months of lifestyle-sustaining cash reserve, especially if you work for yourself or in an unstable industry…and what industry ISN’T unstable these days?  This will take some work to figure out, because it’s not just your annual salary, but rather what you need to sustain your lifestyle for the next 12 months.  We’ve discussed saving in a Roth IRA as a dual-purpose account HERE if that suits you better.

Why do you need so much in cash?

First of all, what exactly is “so much” anyway?  Obviously, “so much” is a relative and personal term – I have one client who “only” has $90,000 in his savings.  That’s on top of the “nearly empty” checking account with $55,000 in it.  Oh, and he spends $60,000 a year  – 100% covered by his pension.  Cash is king.  It allows you to negotiate (doctors have different “cash” prices – as do other businesses) and is easily accessible.  The last thing you want in an emergency is to be floating credit card balances while your insurance company decides how and when they’re going to pay.  Get emergency cash now.  Make a plan and do it.


Step 2:  Buy disability insurance beyond what your company provides


This is an increased cost, no doubt, but who among us could live on less than 50% of your current income?  I know things around here would get a little tight, for sure!  Remember what I said a few minutes ago about “lifestyle-sustaining” income?  If something tragic happens, should that mean that your kids can’t play soccer anymore?  What about dance class?  If you’re no longer able to work for the rest of your life, do you think you should continue to build up a retirement nest-egg?  Disability coverage only usually pays until age 65!  Then what will you do?

It’s usually best to find your own outside coverage in addition to what your employer provides.  Group coverage will be 100% taxable when you receive it.  Coverage paid for entirely by you is 100% tax-free.

Take this example:

Let’s say you make $80,000 a year as an electrical engineer.  You have group disability of 60% that kicks in after you’ve exhausted all your vacation and sick time.  Sixty-percent of $80,000 is $48,000, right?  Now, let’s subtract 25% for taxes, so that leaves you with $36,000, or roughly $3,000 a month.  You were making $5,000 a month after tax.  Can you today cut two grand out of your household budget?  No?  I didn’t think so.  Everyone’s cost may be different, but let’s say a disability policy that pays you $2,000/mo DI costs $150/mo.  That’s $1,800 a year…is it worth it?  Let’s put it another way:  Your boss says, “Hey Jimmy, we’re going to cut your salary from $80,000 to $78,200 from now on, but if you even get sick or can’t work ‘cause you’re too hurt, you’ll get all your pay until you retire.”  What would you think? I think you’d take that plan.

Go, right now, do not pass go, do not collect $200, go now and acquire an disability application.  Fill said application out and send in the first month’s premium.  Do it now.


Step 3:  Buy a gazillion dollars of life insurance.


I won’t spend a ton of time on this – we’ve discussed this many times before….but whatever you think you need for life insurance, double it…then double it again.  Too many people buy only a minimal amount of life insurance. If people rely on you for money now or in the near future, go online to a life insurance wholesale shop (if you can’t think of any, in the US, google “buy life insurance”…there are a lot of interesting blogs about life insurance. If you are based in UK, then I recommend reading this blog for latest news and updates related to life insurance.) and purchase a policy.  Twenty or thirty years should do it and the policy had better have lots of zeros (at least 6) and a number bigger than 1 at the beginning.  Does that sound like too much coverage? If you ask any financial planner who’s had a client die–who’s had the unfortunate task of delivering a life insurance check to a widow or survivor–they all know that the survivor nearly always says the same thing: “Is that it?  How am I supposed to make it on that?”

If you want to get technical, read this to figure out how much you’ll need.

I hate that these evil and terribly tragic things happen.  I, in no way shape or form, can justify them or even begin to make sense of them.  In the days and weeks ahead, we’ll hear from the culprits and it still won’t make sense.  What I do know is this:  We cannot ever predict the future.  We can only have a plan on the shelf to execute once tomorrow is here.

Enhanced by Zemanta

Filed Under: Insurance Tagged With: Boston, Disability insurance, Financial services, Insurance, life insurance, Roth IRA

So You Want to Manage Your Own Money?

September 4, 2012 by Joe Saul-Sehy 29 Comments

A friend texted me this morning.

“We should talk soon. Julie is coming around to the idea of us managing our own money.”

It seems easy, right? My initial reaction to my friend was, “That’s awesome!” because it is. There are few things more satisfying than achieving your financial dreams and knowing that you climbed the money management mountain yourself.

No “money-god” came down and did it for you.

You didn’t need the Powerball numbers.

You actually plotted a financial course and landed safely at your destination.

For my friend, and for you if you’re about to embark on this journey, there’s good news and bad news: the good news is that it isn’t difficult to manage your own money.

The bad news is that to effectively manage your own money you’ll need to be ready to face some fairly difficult tasks.


Two Types of People


When I was a professional advisor, I’d meet some smart people who wanted to jump into their own money management and wanted an expert with an opinion to look over their shoulder, hold them accountable, and make sure they didn’t miss any “I” dotting or “T” crossing.

…and then there were other, often equally-smart people who wanted to hand it over to me and have someone else take care of it for them.

Believe it or not, most advisors I knew preferred the latter type of client and loathed the first one. Someone questioning their motives? Someone asking “why are we doing it this way?” all the time? That’s preposterous!

But if you’re going to ever learn how to manage your own money, you’ll need to be the first type, not the latter.

The steps aren’t difficult:


The Steps to Managing Your Own Money


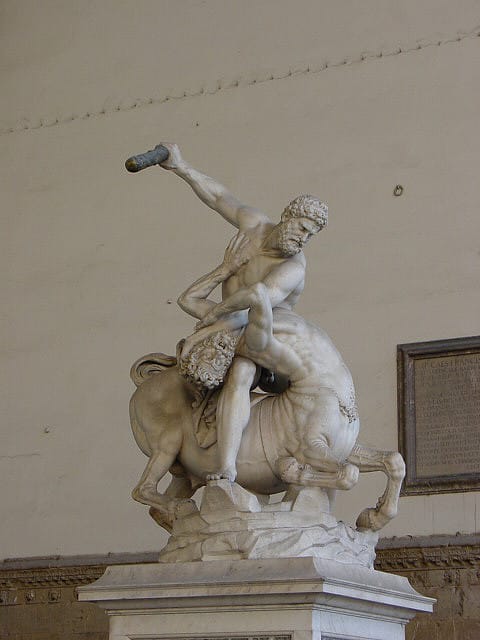
My kids are reading myths in school. In the story of Hercules, he faces a series of challenges to achieve is goal.

I look remarkably like the guy on top, but I’m a little paler and not quite as naked. And I have less hair.

You’ll have a series of gauntlets in your way too, if you want to manage your own money.

1) Write out your goals. I’m not talking about writing:

Retirement

College

New Boat

Fall Deeper in Love

Real goal writing has a specific time, dollar amount and vision attached.

I want to be able to live on $65,000 per year (in today’s dollars) by age 65 without having to work every day. With this money I’d like to: (here you write your bucket list, which should include visiting every NASCAR track in the country).

That’s a goal you can shoot for and be excited about (except for visiting the track at Pocono, which I thought was pretty overrated).

2) Next, you write out all the hurdles in your way.

– I have $25,000 in credit card debt (separate by interest rate, term, amount)

– I have to put two children through college

– I know nothing about money management

3) Then, you find one of the nearly bazillion financial calculators online (you can use our powerful little PlanWise calculator here on the site!) and figure out how much you need to save to reach your goal.

– I need to save $250 per month to reach my dream if I achieve an 8% return.

Armed with your money management return information, now you figure out how to come up with $250 per month.

– Tweak your budget

– Pay down debt

– Take on more work

4) Before investing, though, you have a big problem. You have to insure yourself against some of the huge “what if’s” out there for you and your family:

What if you die?

What if you are disabled?

What if you have a car accident?

You’ll need to create a will and evaluate insurances.

5) Finally, you begin the heavy task of research to find investments that have historically achieved 8%.


No Step is Difficult, You Just Shouldn’t Miss One


As you can see, when you take on the hard task and decide to manage your own money, getting it right will be difficult. Each area demands time and energy:

– Planning, milestones and tracking

– Budget, income advancement and debt reduction

– Insurance need projection and comparison analysis

– Estate planning

– Investment allocation, picking and monitoring

These are five basic money management steps, but each packs a punch!


I Don’t Mean To Imply You Can’t Do It


As soon as I finish this piece I’m calling my buddy and talking him through these points. Before he takes on the task, he should know how long the financial security road really is. Going in with your eyes wide open is half the battle if you plan to win the “manage your own money” game.

He can do it, and so can you!

Enhanced by Zemanta
Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: money management, Planning, successful investing Tagged With: Budget, Debt, finance, Financial services, Insurance, Investment, manage your money, money management

2 Guys & Your Money Episode 9: NerdWallet, Buying a House, Insurance Costs & Combining Family Finances

September 3, 2012 by Joe Saul-Sehy 8 Comments

Never listened to a podcast before? You can tap the button above to enjoy the show on your computer, use iTunes to subscribe for free (new shows will load automatically!), or listen through Stitcher.

For information on how to subscribe through iTunes.

For information on how to listen through Stitcher.


Holy Ton of Topics, Batman!

On this special Labor Day edition of the podcast, we introduce a new reality show coming via NerdWallet, Kathleen from Frugal Portland joins the roundtable team for a rousing discussion of couple’s finances, and PK tells you why your insurance premiums are high (and of course, draws the correlation to “too big to fail”…always the overachiever).


Show Notes

<Open> Hello, Stitcher listeners!

Details on listening to the show through Stitcher: www.stitcher.com

Thanks to ING Direct for the show sponsorship. $50 off to open an account, details here.

Home Ownership: Is now the time? Here’s the FRED chart that spurred this discussion.

<> PK’s Fractional Sense: Insurance premiums & Too Big To Fail

<> Let’s Give Something Away. Congrats to our winner, John @ Married (With Debt).

To enter the September drawing for a copy of the board game The Settlers of Catan;, guess the voice in the show and send your answer to joe (at) the free financial advisor (dot) com. We’ll choose from the correct answers one winner on the last day of September.

Will Weaton’s TableTop show episode featuring Settlers of Catan:


<> Roundtable: Thanks to Kathleen from FrugalPortland for joining us this week.

Our topic: Married couples: should they combine finances?

The ClubThrifty Posts that spurred this discussion: Greg’s Article & Holly’s Article.

<> Interview withAmelia Granger: Nerdwallet.

<> End Show: Joe saw The Campaign (wait for DVD), watching on Netflix:Louie: Season One; w/ comedian Louis C.K. (likes a lot, but you have to be comfortable w/ rated R situations and humor)


And then, a link you may-or-my-not need for this show: Sri Lanka referenced article in the-segment-that-shall-not-be-named


For more information on our weekly contributors: PK, Carrie Smith, Dominique Brown, Len Penzo and Dr. Dean, here’s their bio page.

Would you like to be on the show? Have a topic for the show? Like to advertise on the show? Write to Joe (at) thefreefinancialadvisor.com.

Speaking of advertisers, if you’d like to take advantage of the ING $50 sign up bonus, visit www.thefreefinancialadvisor.com/ING50.

Enjoy the show!

Enhanced by Zemanta
Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: Podcast Tagged With: Carrie Smith, financial podcast, FrugalPortland, Insurance, money podcast, NerdWallet, Settlers of Catan, two guys and your money

  • « Previous Page
  • 1
  • …
  • 8
  • 9
  • 10
  • 11
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • 10 Tactics for Building an Emergency Fund from Scratch by Vanessa Bermudez
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald

Copyright © 2026 · News Pro Theme on Genesis Framework