• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Insurance

2 Guys & Your Money Episode #007: Jeff Rose Interview – The Life Insurance Movement

August 20, 2012 by Joe Saul-Sehy 6 Comments

Nearly as suave as some other 007 you may know, this episode features the one, the only: Jeff Rose from GoodFinancialCents.com. He’s leading the tsunami of financial posts coming your way Wednesday, as the Life Insurance Movement roars across the blogosphere. Jeff talks about the movement, why life insurance, and common misconceptions, tricks and tips around life insurance policies.

OG & Average Joe discuss Roshawn Watson’s post on poverty at RoshawnWatson.com. What does it mean to be poor in America?

PK from DQYDJ.NET wonders if people with more money have more leisure. You might be surprised by his findings.

We give away Dave Ramsey’s book the Total Money Makeover by answering a simple audio quiz. Who is the person in the audio segment (hint: it’s a current or former person on the show).

And, of course, we can’t forget the roundtable team of Len Penzo, Dominique Brown and Carrie Smith who answer the questions: 1) What is your idea of a good coach (financial or otherwise); and 2) What’s going on in your financial life right now? We’ll talk planning, money surprises and refinancing during this segment.

Find more information about our contributors here: Our Podcast Team

Thanks for listening, everyone!

Show Notes:

<> Open: Poverty in America, a discussion of Roshawn Watson’s Do Americans Know What Poverty Is?

<9:25> Fractional Cents w/ PK from DQYDJ.NET: The Cost of Leisure

<13:02> Let’s Give Something Away: Dave Ramsey’s classic book: The Total Money Makeover. Guess the name of the person in our soundclip. Send your answer to joe@thefreefinancialadvisor.com. One correct winner will win the book!

<18:53> Roundtable with Carrie Smith (CarefulCents.com), Dominique Brown (YourFinancesSimplified.com) and Len Penzo (Len Penzo dot Com).

Topic #1: Let’s talk financial coaches. What are the characteristics of a good coach. Are you a good coach?

Topic #2: What’s going on in your personal financial house?

<37:28> Jeff Rose from GoodFinancialCents.com interview: Life Insurance Movement

<50:10> End of Show. Movies!

OG: Caddyshack (again) (Thumb up)

Joe: Hope Springs (Thumb up), The Red Violin on Netflix (Thumb Way Up), headed to see Bourne Legacy tonight.



Enhanced by Zemanta
Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: Podcast Tagged With: 2 guys and your money, Caddyshack, Carrie Smith, Dave Ramsey, financial podcast, Financial services, Hope Springs, Insurance, Jeff Rose, life insurance, life insurance movement, life insurance podcast, money podcast, two guys and your money

Meeting an Advisor? Understand Fees by Bringing This Checklist

May 23, 2012 by Joe Saul-Sehy 9 Comments

Yesterday I posted a riveting story about advisor fees.

How do you know all the fees an advisor may charge?

The good news: this isn’t my first fee-rodeo, so I’ve meticulously prepared and will present to you, hot out of the oven, a fee checklist. Now when you meet an advisor you can ask intelligent questions about what fees you may pay.

Isn’t this exciting? Of course it is. Let’s begin:


___ Advisory fee. This fee is an umbrella fee for services rendered.

What services are included?

  • Financial plan?          Yes  /  No  (how often is the plan updated?)
  • Budget review?         Yes  /  No  (will you advise on line items?)
  • Net worth review?     Yes  /  No  (do you make suggestions on assets for the fee?)

Often advisors say they will recommend new homes for assets, however, those new places are through them, garnering the advisor another fee. Will they make recommendations of funds/ETFs/other investments outside of their control?

  • Insurance review?     Yes  /  No  (In many states advisors can’t review insurances for a fee. However, they can make recommendations on appropriate amounts of insurance.)
  • 1040 review?             Yes  /  No (Again, advisors have to be careful here. Some aren’t allowed to give specific tax advice.)
  • Tax strategy?             Yes  /  No (Will you recommend comprehensive tax plan?)
  • Asset allocation?       Yes  /  No (Many advisors will calculate where your assets lie on an Ibbotson efficient frontier and recommend asset changes based on your goals.)
  • Estate review?           Yes  /  No


___ Wrap fees on personally managed funds. Sometimes an advisor will charge fees based on the percentage of assets inside of an account. Often, these fees range from 0.5% to 2.0% Remember that funds inside these plans have fees also, so ask what the average fee is for funds inside the account and add it to the fee.


___ Wrap fees on outside managed funds. Often advisors will recommend outside advisors to manage all or a portion of your assets. Fees generally range from 0.5% to 3.0% of assets managed, per year.

Wrap accounts are easy to remember if you think of plastic wrap around your assets managed in the account. Instead of trading and holding fees, you’ll pay the “wrap” fee on the entire amount inside of the wrapper.


__ Trading costs. Are there commissions for trades? What would those be?


__ Commissions to buy funds. Does the advisor use mutual funds? Are there fees to buy, sell or hold the fund? What are those fees?


__ Insurance commissions. If the advisor completes an insurance analysis, are you expected to buy insurance through them or do you go outside? What types of insurance does the advisor make recommendations on?

When I was an advisor, I’d recommend an insurance amount needed. Then I’d prepare quotes through companies I represented and recommended my clients shop other firms, such as Zander insurance (Dave Ramsey’s company).


__  Annuities, Private REITs and Limited Partnerships. Does the advisor recommend these product types? Do they receive commissions when they recommend these products? Annuities may pay up to a 9 percent commission. Often REITs (real estate investment trusts) will pay nearly the same amount to the advisor.


__ Cash products. Do you recommend savings accounts, CDs and other similar cash accounts? Are these through you, banks or credit unions? How do they work?


__ Mortgages, auto loans and revolving credit. Do you recommend these products for a commission?


__ Other outside experts. Should I expect to pay other experts, such as attorneys (estate plan) or CPAs (tax review)? If so, it’s important to know that there may be even more fees after you write your first check.

Enhanced by Zemanta
Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.
joesaulsehy.com/

Filed Under: Hiring Advisors, Planning Tagged With: advisor fees, Fee (remuneration), Financial adviser, Insurance, Limited partnership, Mutual fund, what fees do I pay an advisor

Disability Insurance Optional? I Think Not. – Our Boner of the Week!

January 2, 2012 by Joe Saul-Sehy 6 Comments

Hey, it’s always fun to say stuff off the cuff with friends, but when you have readers who take your words seriously and act on them….it’s probably best to do some research first. Our Boner of the Week! Is the most outrageous thing I’ve read on the internet in the last seven days.

…and we’re back to personal finance blogs!

A well-known blogger this week described disability insurance as “optional” in an article about types of insurance you should pursue. Really? Maybe it’s “optional” in the same way other insurances may be bypassed if you have other forms of coverage, but I don’t think it’s “optional” like the guacamole on my nachos at Buffalo Wild Wings. Don’t get me wrong, I’m not really a guacamole or disability insurance lover, but I can safely pass on the former. The latter….well, let us see for ourselves…..

When you’re deciding which insurances you need, disability coverage should be at the top of your list.

Here are the reasons why:

– If you can’t work, you can’t feed yourself without income. Unless you’re hoping for that awesome government check every month, disability insurance will protect your family and your things. Know why? You’ll still have income.

– Don’t think it’s going to happen to you? Think again. There’s some great news when it comes to auto accidents. Roads are becoming safer. There were just over 33,000 highway accident fatalities in 2009, as compared to over 43,000 in 2005. Instead of dying, people are just maimed.

seinfeldcd
Gratuitous Kind-of-Funny Picture to Break Up the Post!

Need Statistics? How about these eye-popping numbers on disability:

o As of 2009, persons in the U.S. have a 12 percent chance of suffering a disability. (Cornell University)

o Just over 1 in 4 persons who are 20 years old today will suffer a disability. (Council for Disability Awareness)

o Over 12 percent of the population is currently disabled. (CDA)

o 61 percent of wage earners personally know someone who has been disabled for three months or longer during their working career. (CDA)

Insurance is about odds. I dislike insurance policies as much as the next guy. That’s why my goal is to only buy insurances that I’ll probably need and avoid those that I won’t. Because I’m determining the chance of risk, it makes sense for me to check the probability of the occurance of need.

So, let’s examine the chances of a disability vs. other types of insurance listed in the piece:

Disability: 1:12 (Cornell University, listed above)

Auto: 5.67:100 (collision claims, according to Insurance Information Institute)

Home: 6:100 (Insurance Information Institute)

In fact, the author of the piece acknowledges the high rate of disability but still lists it as optional insurance. I can’t understand this logic.

Life insurance isn’t considered optional in her piece…in fact it’s listed as the third most important type of coverage (behind auto and health). But to express it in the most crude terms possible….isn’t your family better off if you’re dead than if you’re sucking down food and taking up space? They’ll have to cart you to the doctor and help you with basic activities. You’ll use electricity as you watch television or listen to the radio instead of work. It’s not fun for you and expensive for your family.

Not working? Long Term Care coverage isn’t even mentioned in the blogger’s piece and represents a huge hole in the financial plans of retirees who have enough money to protect but not enough to withstand the huge costs associated with custodial care on a daily basis. I won’t go into these facts here, because it’s slightly off-topic.

I’m tired of:

– “financial professionals” describing insurances and listing disability policies as the stepchild of the industry.

– consumers saying “I have disability through work, so I’m all set.” Workplace disability coverage often is capped at a staggeringly low amount of coverage. Why? Because a disability is expensive and insurance to cover a disability is expensive. Do your homework before flippantly deciding that “my insurance through work is enough.”

Still, maybe the blogger is off the hook. Here’s when you don’t need disability coverage:

1) if you have enough money to cover a disability, you can self-insure.

2) if your income stream comes from places that would be unaffected by your disability, and your health care coverage will tackle additional costs.

I’d like to believe that when she wrote “optional” next to disability insurance she meant to write “optional” next to every insurance coverage. Otherwise, I’m sure she meant that you should explore disability insurance as thoroughly as you would health, auto, home and life insurance.

Dearest minions,

When some professional writer, television talking head, or paid advisor tells you to look past an insurance type, always reach for statistics. Although I’m as bad at math as the next personal financial blogger, the numbers will usually find a way to lead me to the truth. The truth in this case: find adequate disability coverage.

Now it’s your turn. What insurances aren’t “optional” in your life? Which do you skip and take the risk?

Enhanced by Zemanta
Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: Planning, risk management, smack down! Tagged With: Disability, Disability insurance, Insurance, Long-term care

Tennessee Family Expected Insurance For Nothing – Boner of the Week!

December 12, 2011 by Joe Saul-Sehy 8 Comments

The Boner of the Week! is awarded every Monday to the most outrageous event, quote or story I read about this week.

Usually I discuss outlandish or erroneous quotes in the Boner of the Week! segment. This time, let’s tackle an event.

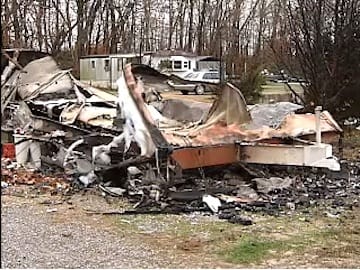
home after fire According to this story, a Tennessee family living in a rural area without fire protection didn’t pay a $75 annual fee to a nearby city to receive services. When their home went up in flames, firefighters stood by and watched the couple’s home burn to the ground.

At first glance, this appears to be a fire department and government politics problem. “On further review,” to quote the highbrow program Monday Night Football, I believe the Boner of Week! occurred when the family opted not to pay–what now appears to have been—a pretty important ‘insurance” bill before their house fire occurred.

Here’s my rationale:

1) They don’t live inside the city in question and.

2) Homeowners inside the city boundaries pay taxes for fire protection. Those outside are asked to pay a small fee to receive house fire support.

3) The family opted not to pay the fee, in essence declining the city’s coverage plan.

Don’t think I’m heartless. We’re experiencing a similar situation personally. Nearly ten years ago my in-laws met with me to discuss long term care insurance. My father in law, a smart man who’s always been a good friend, was vehemently opposed to it.

He said, “I’m not paying for that overpriced insurance. It’s a rip-off.”

Yesterday wife returned from Detroit, where she was helping my mother in law decide on options for home health care, because he’s suffered a major stroke. My mother in law is meeting with elder law attorneys, looking for ways to cut down on costs while keeping his quality of life high.

There aren’t many options now, because they made a critical decision back then to decline coverage.

It’s fair to assume that my in-laws will now spend about $70,000 per year (or more) of their own money on his care. Just like this family declined fire protection, had they purchased a long term care policy ten years ago, the break-even point on buying “that overpriced insurance” would have been only several months into the nursing home stay.

They chose to self insure. Now they’re faced with the consequences.

So is the Tennessee family that decided to opt out of fire “insurance.” They had a house fire and no fire protection coverage.

Maybe there are larger societal implications here. Maybe not. Maybe it’s that we live in a time when everyone seems to want someone else to take care of us. I believe this event is simply another wake up call: nobody cares about your situation more than YOU. Take care of yourself. Make your choice and live with the consequences.

What steps should you take to prevent making poor insurance coverage decisions?

1) Examine the probability of an event, such as a long term care situation or house fire.

2) Evaluate the cost to cover the probability

3) Decide whether it should be insured, or if you can handle it yourself.

In this case, seventy-five bucks might have saved a ton of personal property from this house fire. Often people will forego insurance because they don’t have the funds to pay the premium. Insurance is created specifically for times when funds are short. If there’s enough money to cover the unlikely need for fire protection and you follow some fire prevention safety tips, maybe it makes sense to avoid the fee.

Enhanced by Zemanta
Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.
joesaulsehy.com/

Filed Under: Insurance, Meandering, risk management, smack down! Tagged With: Boner of Week, free financial advice, free financial advisor, Insurance, Tennessee fire, Tennessee house burns

Life Insurance: What’s the Right Type of Life Insurance?

November 29, 2011 by Joe Saul-Sehy 6 Comments


I’m not a big television watcher, so I’m sorry to say that I don’t see much Dancing with the Stars. I know, you had such high hopes for me. My wife watches the show, so sometimes when I’m playing around on “the Twitter” I’ll sit with her on the sofa. On more than one occasion, I’ve half-witnessed a total breakdown by the “star” because the workouts were too hard. What’s interesting is that these “stars” end up achieving nothing on the show while the harder working pairs continue on. Even if they don’t win, those stars that worked hard talk about how rewarding it was to learn something new.

That’s what we’re going to do today: throw out rules of thumb and learn how insurance works. I am totally an analogy ninja.

He did so well last time, The Other Guy is back to write another scintillating post on insurance. If you missed his last one, you may want to start here: Find the Right Amount of Life Insurance in 10 Minutes.

Everyone wants to use rules of thumb, or “what I heard from my friend” to decide which insurance is best. Why throw a dart when it’s nearly as easy and far more profitable to just do the homework?

I hear experts tell us to always buy term insurance. Or they moan that universal life coverage is a rip-off. I agree that there is one type of insurance that’s best for everyone, but:

The best type depends on what you’re going to use the coverage for and how long you’ll need it.

Decisions …so before you believe someone telling you that one type of insurance is better than another, minions, know the available types and how they work! Last week I shared a quick formula to determine how much coverage you’ll need. Let’s use another quick method to understand your choices when it comes to life insurance.

Just as a carpenter needs to know the difference between a hammer and a drill, you’ll need to know all the types of insurance to pick the best kind. Don’t worry, I’ll keep it entertaining.

Term Insurance is probably that most well known type of coverage. Because it’s stripped down coverage, it’s often the only type available in workplace plans. Term insurance is nearly as easy to understand as first grade math: you pay for a specific amount of insurance which covers a set amout of time, called a ‘term’.

Helpful example: Barry Manilow purchases a $250,000 10-year term policy. If he dies during the term, Mandy, his beneficiary would receive $250,000 tax free simoleons. If Barry expires one minute after the term ends, the insurance company owes Mandy nothing.

Whole Life Insurance is equally well known. These plans began decades ago as an alternative to term coverage mainly because the coverage lasts…wait for it…your whole life. Awesome, huh? I know. Marketing and naming wizards, those insurance companies. Most whole life policies contain a “cash value” component that can be cashed in by the owner. Whole life policies require payment for their…drum roll please…whole life, unless you buy a policy that can be “paid up” early. Generally speaking, whole life = coverage for your whole life and premiums for your whole life.

What’s awesome about whole life insurance? Guarantees! If you continue to pay the premium to the insurance company and keep your account in good standing, it’s guaranteed to last. The cash value grows at a guaranteed rate, so you don’t need to worry about interest rate fluctuation much. It’s a wonderful policy type for the super-nervous people of the world.

Universal Life Insurance is a variation on whole life – at some point insurance people said, “Wouldn’t it be cool if the payments to the policy and death benefit could be partially flexible?” Maybe they didn’t ask that exact question, but it makes the point. People who own this insurance pay extra (just like with whole life coverage) to add money to a cash value portion of the policy.

Once enough cash value accumulates, you can sit back and let the cash cover the costs instead of paying more money from your wallet. Many policies allow you to raise or lower the amount of coverage without having to purchase another one.

What’s another key difference between universal life and whole life insurance? Okay, I’ll tell you: universal policy interest rates on cash often float with interest rates. Awesome during 1980 when CDs were paying over 10 percent. Now, though, with the value of savings through the floor, universal policy rates are Coyote Ugly. And no, that’s not code for awesome, like the model-bar.

Variable Universal Life is the newest of the 4 major types. Those crazy insurance companies were getting smoked because the average saver decided to invest money into the financial markets. Marketing people said, pulling their hair out, “what will we do to keep business coming in?” Once again, the phrasing is off, but VUL policies (as they’re known in insurance lingo) were a reaction to the widespread use of mutual funds and other investment tools.

Initially developed in the late 70’s and early 80’s, these types of contracts allow for investment in various stock/bond accounts (similar to mutual funds, but not the same). The major draw of VUL? Flexibility of investments became the name of the game – and the opportunity to have market-like returns right inside your very own life insurance policy. In the go-go 1990’s, this was awesome. Since then, many investors have had middling returns and unpredictable results.

Which is best for the salesman?

In the interest of fair disclosure, I’m going to let you in on a little secret. Life insurance is a BIG commission check…I mean GIGANTIC. You wouldn’t believe how much. Let me give you an example: If you’re a 40-year old man buying a term policy that costs $100/mo; your insurance sales person gets around $850-$900 cash for the first year of your premium payments. Yes, you read that right, you basically pay a year’s worth of premiums to cover the commission amount. I don’t mean to infer that this is bad…it’s just how things operate.

Just thought you’d like to know.

Whole Life, Universal Life, and Variable Universal Life are even bigger payers. I remember receiving a check for over $25,000 for a single $400,000 Variable policy I sold early in my career. I also remember a $70,000 commission check for a $2 million policy. Big money.

My goal isn’t to make you angry. It’s to help you know the broker’s game.

…which brings brings us to the “One Question You Should Ask Before You Buy Anything”:

“Mr. Broker, how much money are you going to make if I buy this insurance?”

I was never ashamed to admit to my clients how much money I’d earn…a good advisor has no reason to be deceptive. But, if he hems and haws…maybe this “complex insurance investment strategy” that sounded pretty cool benefits him more than you. In my opinion, the actual commission is irrelevant – it could be $2 or $20,000, I don’t care – it’s how he answers the question.

All Insurance Types Cost The Same

Sometimes insurance agents will mention that permanent policies, such as universal or whole life, are less expensive than term insurance. I’ll lay it out and let you decide:

Sure, like some margarines are saltier than others, some carriers offer better premiums for smokers, race-car drivers, or 45-year olds. That’s true. However, insurance ‘costs’ among competitors are far closer than you’d initially imagine.

In the above example you’ll see the differences between permanent and term. Notice additional fees (in the right chart, 5 percent is deducted as an additional charge—this fee can be higher or lower depending on the carrier).

Here’s how all insurance costs are similar:

Insurance is sold in $1,000 increments. Imagine pulling up to the insurance store drive thru and ordering 500 $1,000 units of insurance. The cashier calculates the cost based on two factors: your age and the number of $1,000 units you’re purchasing. I hate to disclose this secret: actuarially you’re more likely to die every year you age.

With permanent life insurance, your “cash value” grows over time, reducing the amount of life insurance you buy from the insurance company – which makes it seem like you’re paying less for coverage.

A second handy example: if Jeff Gordon races to buy $500,000 of coverage and he stuffs $50,000 of cash into the policy – his beneficiary would receive $450,000 of insurance and $50,000 OF JEFF’S OWN MONEY to total $500,000.

Permanent life insurance is only cheaper because you’re paying extra into cash when you’re young, which lowers the amount you’re buying later on when it’s expensive.

Whole life, UL and VUL insurances in many ways are forced savings accounts added to life insurance.

Which Should You Buy?

So…which one is best? Well, that’s a loaded question – but here’s what I think. Start by determining how long you’ll need coverage. For the vast majority of savers, maxing out a Roth IRA and 401(k) plan and buying term insurance is the right answer. If you have a long term need and have a maxed out Roth IRA, 401(k) and you still have money left over…well then maybe a permanent policy may be a better choice.

For this reason, using term insurance for succession planning needs at work or estate liquidity needs to cover estate taxes usually ends in disaster. These policies need to be in-force when you die, so permanent insurance works best.

If you’re a worrier about outliving your insurance and want forced savings, whole life, UL and VUL aren’t the enemy. I’ve had clients purchase permanent insurance only because they wanted security and were comfortable paying a lot of money for it. These policies work, but for a cost.

Because most families need life insurance for a fixed amount of time and have other ways to save money, term is often the best choice.

Related articles
  • Find the Right Amount of Life Insurance in 10 Minutes (thefreefinancialadvisor.com)
Enhanced by Zemanta
Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: Insurance, Planning, risk management Tagged With: Barry Manilow, buying life insurance, free advisor, free financial advisor, Insurance, Insurance policy, life insurance, Universal Life, Universal Life Insurance, whole life insurance

Find the Right Life Insurance Amount in 10 Minutes

November 23, 2011 by Joe Saul-Sehy 6 Comments

Another note from AverageJoe’s Thanksgiving visit to the in-laws:

Dear blog diary,

I’ve just trounced my mother-in-law at Scrabble again. It was absolute luck that the triple word score was open for my play of “austerity.” Of course, I had to hide a U and Y in my sleeve to place a nine-letter score. Luckily, we’ve both had enough “holiday cheer” that she didn’t notice. I know that to be a good son-in-law I should let her win, but not until I get a chance to play the word “bailout.”

Between all this winning and making Rice Krispies Turkey Pop Treats, I totally can’t be bothered to post anything today. Instead, I’ve opened the basement and let out The Other Guy, so named because he’s still a practicing financial advisor and doesn’t understand that being associated with me would totally be good for business. Whatever.

We’ll have a special piece tomorrow, but will completely understand if you don’t have time to read it. Safe travels, everyone!

Now, on to the Other Guy:


A couple of weeks ago, after being sick for about 10 days, I finally went to the doctor. Apparently, I have ‘walking pneumonia.’ I told the doctor that I don’t do any physical exercise, including walking, so I couldn’t possibly have “walking” anything.

In any event, I didn’t feel well. I began to contemplate my own mortality and then an idea popped in my mind: let’s spend a couple of days talking about life insurance! It’s obviously everyone’s favorite topic…and as a financial advisor who doesn’t like to be sold some insurance, I make the perfect teacher. As AverageJoe did with the “evaluate a mutual fund in 10 minutes” post, I’m going to break it down nice and easy for ya’.

Here goes:

Before anything, let’s not waste time evaluating coverages if we don’t have to. All too often, insurance sales professionals and financial advisors will just make the assumption that you need it and proceed to sell it to you. Here’s an easy way to determine if you need life insurance at all:

Questions to ask:

Does anyone rely on you for financial support, either right this moment or if you got hit by lightning?

If you’re single and/or have no dependents, there’s almost a zero point zero percent chance that you need life insurance. I might be convinced that a small group policy so that someone can bury you is adequate. If you have charitable intentions, there are insurance strategies that work really well….but that’s all. Nothing more.

Don’t let an insurance salesman tell you otherwise.

For those of you who have people relying on you for financial support here’s an easy way to calculate how much you need. Is this the best way? Nope. However, once we walk through these steps you’ll be on your way to making a good insurance decision.

Every life insurance discussion contains assumptions. You’ll need to make some to decide what amount is right for you. At the least, you’ll need to know where assumptions have been made, so you’re able to change directions if you need to.

Here are a few assumptions:

If married, I usually assume with clients that they’ll want the mortgage paid off when they die. Even if both spouses have a full time job and can still afford the house, I’ve seen too many people “go off the deep end” when their spouse dies to determine whether everything will remain stable at work and home. I can understand leaving this out, but at the least I’d evaluate your insurance cost with and without this cost before deciding to drop it.

You may find the additional cost is worth the pain.

If you have children, I assume you’ll want them to go to college, and you’ll want it paid for . Maybe not Harvard or Yale, but you want them to have some level of in-state public university education. Since college costs increase 8-10 percent per year on average, this is one of the most expensive budget items a family can face.

Let’s have the discussion here that we’ll have in client meetings: Maybe you paid for your own college expenses. Evaluate your children and savings and not your personal situation when you went to school. With costs rising quickly, do you want them to have this burden?

Here’s how much life insurance you’ll need…plus or minus the assumptions above plus a few more below.

Add together all of your debts, including your mortgage: $__________________

I’ve done the math on an average in-state tuition in the chart below. Add in these costs: $__________________

Next, we’re going to give your family basic income to live on. Here are where we need to make some large assumptions. Take your annual post tax (take home) income and multiply by 80%. This assumes that your family will live on 80 percent of your current salary if you’ve died. There are better ways to do this. Instead, determine what percent your family would need in the event of your death and use that percentage.

Divide this amount by .05. This means that you’ll need to peel off 5 percent to live on. This single number creates (again) huge assumptions. The biggest? It’s that you’ll continue to live on this income stream even as inflation skyrockets. Once again, we’re trying to get in the ballpark, so if you’re trying to do this the “quick and dirty” way, we’ll be close, but there are better ways.

Place your answer here: $__________________

Add up these 3 lines, that’s how much you need.
$__________________

Now, often, I’ve seen insurance salespeople stop at this point. Not good. Remember, you have some current savings! The goal of insurance in most situations is to replace income that you don’t yet have.

Subtract the amount of money you already have saved from the final number.

$__________________
Buy the difference.

Education Chart

Age$ needed todayAge$ needed today
0$78,855.8711$64,200.32
1$77,395.5712$63,011.43
2$75,962.3213$61,844.55
3$74,555.6114$60,699.28
4$73,174.9515$59,575.22
5$71,819.8616$58,471.98
6$70,489.8617$57,389.16
7$69,184.5018$56,326.40
8$67,903.3019$34,071.75
9$66,645.8320$23,139.91
10$65,411.6521$11,792.45

Later, we’ll have a discussion on the various types of insurance you should consider and the #1 question you should ask before you buy anything from any insurance sales person.

As always, this exercise is more about understanding the variables that go into making a good decision as much as it is about the final product. Plug in your own unique situation and evaluate many types of coverage thoroughly before buying life insurance.

Enhanced by Zemanta
Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: Insurance, Planning, risk management Tagged With: Agents and Marketers, Business, Financial adviser, Financial services, Insurance, Insurance policy, Life, life insurance

  • « Previous Page
  • 1
  • …
  • 9
  • 10
  • 11

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • 10 Tactics for Building an Emergency Fund from Scratch by Vanessa Bermudez
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald

Copyright © 2026 · News Pro Theme on Genesis Framework