• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for pensions

Two Retirees Spend $5,000 a Month — One Needs $1 Million More Than the Other. Here’s Why

October 10, 2026 by Brandon Marcus Leave a Comment

Two Retirees Spend $5,000 a Month — One Needs $1 Million More Than the Other. Here’s Why
Two retirees can spend the same $5,000 each month yet need dramatically different portfolios because guaranteed income can cover a large share of their expenses – Shutterstock

Two retirees can each spend $5,000 a month and still face dramatically different savings targets. The difference may have little to do with their lifestyles and everything to do with how much dependable income arrives before either one touches an investment account.

Consider a simple example. Both households need $60,000 a year to cover their retirement spending. One receives $40,000 a year from Social Security and a pension. The other receives no guaranteed retirement income. Using a 4% withdrawal rate as an illustration, the first household needs roughly $500,000 from its portfolio to cover the remaining $20,000. The second needs about $1.5 million to produce the full $60,000.

Same spending. Same withdrawal assumption. One million dollars more in savings.

That is why a retirement number pulled from a calculator can look wonderfully precise while missing the part of the equation that actually matters.

The Portfolio Does Not Have To Pay Every Bill

Retirement spending gets much easier to analyze after separating expenses from income. A household might spend $5,000 a month, but its investments do not necessarily need to produce $5,000 every month.

Social Security can cover part of the grocery bill, utilities, insurance premiums and other recurring expenses. A pension can cover another slice. An annuity or other income source may contribute as well. The portfolio then fills the gap rather than carrying the entire household.

That gap determines the size of the nest egg. If dependable income covers $3,333 a month, only about $1,667 remains for investments to fund. At $20,000 a year, a 4% withdrawal rate points to approximately $500,000. A household with no comparable income stream faces a much larger assignment because its investments must generate the entire $60,000.

The distinction becomes especially powerful over a long retirement. Every dollar of reliable income reduces the amount the portfolio needs to supply year after year.

$1 Million Sounds Huge Because It Is

The $1 million difference in this example does not come from some magical retirement formula. It comes from multiplying an annual income gap by the amount of invested assets needed to support that gap. At a hypothetical 4% withdrawal rate, every $10,000 of annual portfolio income corresponds to about $250,000 of savings. Need another $20,000 a year? That adds roughly $500,000 to the target. Need another $40,000? The figure reaches approximately $1 million.

That arithmetic gives the headline its punch. A $40,000 difference in annual guaranteed income can translate into a $1 million difference in portfolio requirements under the same simplified withdrawal assumption.

Of course, 4% does not represent a promise. Investment returns vary, inflation changes purchasing power, taxes affect what retirees actually keep, and a retiree’s spending pattern can change over time. A withdrawal strategy also needs to account for market conditions and the possibility of a very long retirement.

Social Security Can Change The Shape Of The Problem

Social Security often gets treated as an extra check that helps with retirement. For planning purposes, it can function more like a partial replacement for a portfolio.

Suppose two households each need $5,000 monthly. Household A receives $3,000 monthly from Social Security and another $333 from a pension. Its portfolio needs to supply the remaining $1,667. Household B has the same spending but must withdraw the entire $5,000.

The first household therefore faces a much smaller portfolio burden. It also has a source of income that does not rise and fall with the stock market.

That does not make Social Security a complete retirement solution. Benefits may cover only part of a household’s expenses, and the amount varies by individual earnings history and claiming decisions. Still, treating guaranteed income as part of the retirement-income engine can produce a much more realistic savings target than focusing on expenses alone.

Housing Can Quietly Change The Math Again

There is another wrinkle hiding inside that $5,000 monthly budget: housing. Two retirees might both report $5,000 in monthly spending, but their budgets can have very different levels of flexibility. One may own a mortgage-free home and spend $1,000 a month on property taxes, insurance, utilities and maintenance. Another may still have a large mortgage payment.

That difference matters because housing costs rarely behave like a fixed subscription. Property taxes can rise. Insurance premiums can jump. A roof eventually demands attention, usually with spectacularly poor timing.

Healthcare creates another moving piece. Medicare does not make every medical expense disappear, and premiums, deductibles, supplemental coverage, prescriptions and out-of-pocket costs can vary considerably. A retirement plan that works perfectly on a spreadsheet may need more breathing room once real household expenses enter the picture.

A Bigger Nest Egg Is Not Always The Better Goal

It can be tempting to chase a giant savings number because a larger portfolio feels safer. Yet retirement planning involves more than accumulating the biggest possible balance. A household with $1.5 million invested and no meaningful guaranteed income has a different risk profile from a household with $500,000 invested plus substantial Social Security and pension income. The second household may have less money in the brokerage account but a stronger stream of predictable cash flow.

That difference also affects how retirees react to market declines. If essential bills already receive substantial coverage from dependable income, a retiree may have less need to sell investments during a bad market simply to pay the electric bill or buy groceries.

Conversely, someone who depends heavily on portfolio withdrawals has fewer places to hide when markets fall. The sequence of investment returns can therefore matter greatly, particularly during the early years of retirement.

The Retirement Number Needs More Than One Number

A retirement target should start with spending, but it should not end there. List the expected annual expenses, then identify the income sources that can cover those expenses without requiring investment sales.

Next comes the gap. That figure deserves more attention than the headline portfolio balance.

A retiree who needs $60,000 annually but receives $45,000 in reliable income has a $15,000 portfolio gap. Someone spending the same $60,000 without that income has four times the annual gap. Using the same 4% illustration, the first person would need about $375,000 to fund that gap, while the second would need about $1.5 million.

That is a $1.125 million difference created without changing the spending budget at all.

The Real Retirement Target Is The Unfunded Part

Retirement savings become easier to evaluate once the giant, intimidating number gets broken into pieces. Spending tells you what the household needs. Guaranteed income tells you what already has a funding source. The portfolio only needs to handle what remains, although taxes, inflation, market risk and unexpected expenses still deserve room in the plan.

The most useful retirement number may not be the size of the nest egg at all. It may be the annual gap between what retirement costs and what reliable income already pays for.

Could you retire comfortably with less savings if more of your expenses were covered by guaranteed income? Share your thoughts in the comments.

You May Also Like…

Retirees Are Already Recalculating Their Budgets Ahead of the 2027 COLA

Retirement Coping Skills Most People Don’t Know They Need

Your House Makes You a Millionaire on Paper — Here’s the Retirement Trap That Creates

Home Insurance Renewal Changes Retirees Can Challenge or Compare

At What Point Does Saving More for Retirement Stop Improving Your Life?

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Retirement Tagged With: investing, pensions, Personal Finance, retirement income, retirement planning, retirement savings, Social Security

Would You Rather Retire With a Pension or $1 Million in Investments?

August 29, 2026 by Brandon Marcus Leave a Comment

Would You Rather Retire With a Pension or $1 Million in Investments?
A pension can provide predictable retirement income, while a $1 million investment portfolio offers greater flexibility and control. The right choice depends on factors such as inflation protection, taxes, survivor benefits, spending needs, and investment risk – Shutterstock

Would you rather retire with a pension that sends money to the bank every month or a $1 million investment portfolio sitting in an account with your name on it? The question sounds like a simple showdown between guaranteed income and a giant pile of money, but retirement rarely behaves that neatly. A pension can make monthly budgeting remarkably straightforward, while a portfolio can offer flexibility, growth potential, and something many retirees value enormously: control.

That makes the choice less about which number looks bigger and more about what each option can actually do for a lifetime. A traditional pension, or defined benefit plan, promises a specified retirement benefit based on the plan’s formula, often using factors such as salary and years of service. Meanwhile, $1 million in investments does not arrive with a built-in paycheck, so the retiree has to decide how much to withdraw, how to invest the money, and how to handle market downturns.

The Pension Wins the Predictability Contest

A pension’s biggest advantage might also seem almost boring, which becomes a compliment once retirement bills start arriving every month. Instead of watching an investment account rise and fall, a retiree can build a budget around the pension’s scheduled payments, assuming the plan provides the expected benefit and the retiree chooses an appropriate payment option. That predictability can make expenses such as housing, groceries, utilities, and insurance easier to manage without constantly checking an investment balance. The IRS describes a defined benefit plan as a plan that provides a fixed, pre-established benefit based on a formula, which gives pensions their distinctive appeal.

The catch involves the pension’s details, because not every pension offers the same protections or features. A retiree needs to examine whether the pension includes a cost-of-living adjustment, what happens to the benefit after death, and whether a spouse can receive survivor income. Those details can dramatically change the value of the promise on paper. A pension without inflation adjustments, for example, can lose purchasing power over a long retirement even while the monthly payment remains unchanged. The plan’s summary documents should answer these questions, and the IRS notes that those documents explain survivor annuity and death-benefit provisions.

The Million-Dollar Portfolio Brings Flexibility

Now comes the flashy option: $1 million in investments. Unlike a pension check that follows the rules of a particular plan, an investment portfolio gives its owner control over withdrawals and investment choices. That flexibility can prove useful when spending changes from one year to another, especially when retirement includes occasional large expenses such as home repairs, travel, or helping family. The portfolio can also remain an asset that a retiree may leave to heirs, although the tax and inheritance consequences depend on the account type and the applicable rules.

That freedom comes with a job description nobody requested: portfolio manager. A retiree must decide how much money to withdraw, which investments to hold, how much cash to keep available, and what to do when markets tumble. Selling investments after a sharp decline can lock in losses and leave fewer assets available for future growth, creating an especially unpleasant combination during retirement. A $1 million portfolio therefore represents substantial financial resources, but it does not guarantee a particular monthly income for life.

The Real Question Is How Long the Money Must Last

A pension has one enormous psychological advantage: it can separate everyday spending from market performance. If the pension covers essential expenses, a retiree may have less reason to sell investments during a market slump. That can make the remaining portfolio easier to manage because the retiree does not need to turn every downturn into a financial emergency. The pension effectively handles part of the income job before investments enter the conversation.

The investment portfolio faces the opposite challenge because withdrawals reduce the amount remaining to generate future returns. Market performance can also arrive in an inconvenient order, with poor results early in retirement potentially causing more damage than the same results later. That sequence-of-returns risk makes retirement withdrawals more complicated than simply dividing a portfolio by the number of years someone expects to live. A thoughtful retirement plan therefore considers spending needs, other income sources, taxes, investment allocation, and the possibility of living much longer than expected. No portfolio calculator can remove those uncertainties entirely.

Inflation, Taxes, and Survivor Benefits Can Change the Winner

Inflation deserves a starring role in this debate because retirement can last for decades. A pension that never adjusts its payment may gradually buy less as everyday costs rise, while an investment portfolio can potentially grow over time and provide some protection against inflation. However, investments do not automatically beat inflation, and taking too much risk can create an entirely different problem. The key question involves how the pension adjusts over time and whether the investment strategy can support rising withdrawals without taking unreasonable risks.

Taxes also muddy the comparison, because the headline value of an account does not necessarily equal the amount available for spending. Retirement-plan distributions can create taxable income, while properly structured rollovers can avoid immediate taxation in many circumstances. Survivor benefits deserve equal attention because a pension may offer different payment choices depending on whether the retiree chooses an individual or joint-life option. A retiree should compare the after-tax income, inflation protection, survivor provisions, and investment flexibility rather than simply comparing a pension’s estimated lifetime payments with the $1 million headline number.

The Best Choice May Not Be Either-Or

The most useful twist in this debate comes from the fact that retirement does not have to rely entirely on one source. Someone with a pension may still keep investments for flexibility, emergencies, major purchases, and inheritances. Someone with $1 million in investments may also use other guaranteed income sources to cover essential expenses. Combining predictable income with a diversified portfolio can reduce the pressure on either source to do every job.

The right choice ultimately depends on the pension’s actual terms and the retiree’s financial priorities. A person who values predictable income and dislikes market uncertainty may prefer the pension, while someone who values control, liquidity, and potential inheritance value may prefer the portfolio. Neither option deserves the automatic title of “better” simply because one sounds safer or the other sounds richer.

If given the choice between a pension and $1 million in investments, which would you choose, and what would matter most in making that decision? Share your thoughts in the comments.

You May Also Like…

At What Point Does Saving More for Retirement Stop Improving Your Life?

What Would Break Your Retirement Plan First?

The Retirement Tax Trap Married Couples Rarely Plan For: What Changes When One Spouse Dies

7 Reasons Taking the Pension Lump Sum Could Be the Wrong Move

You Have Enough Money to Retire — But Do You Have Enough Money to Stay Retired?

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Retirement Tagged With: investments, pensions, Personal Finance, Planning, Retirement, retirement income, retirement planning

7 Reasons Taking the Pension Lump Sum Could Be the Wrong Move

August 22, 2026 by Brandon Marcus Leave a Comment

7 Reasons Taking the Pension Lump Sum Could Be the Wrong Move
A pension lump sum can offer flexibility, but retirees also take on investment, tax, spending, and longevity risks that a lifetime annuity may handle more simply – Shutterstock

A pension lump sum can look awfully appealing when the number arrives on paper. One big check feels tangible, flexible, and somehow more satisfying than a monthly deposit that quietly shows up for years.

But that lump sum also turns a pension into a personal retirement project. Instead of the pension plan carrying much of the investment and longevity risk, the retiree takes on more responsibility for making the money last. The Pension Benefit Guaranty Corporation notes that a lump sum can leave retirees responsible for managing investments and avoiding the risk of outliving their money.

1. The Lump Sum Has to Last for Life

A pension annuity solves one particularly annoying retirement problem: figuring out how long retirement will last. A lifetime annuity can provide monthly income for as long as the retiree lives, while a lump sum requires that person to turn an investment balance into a reliable income stream.

That distinction matters more than the size of the check might suggest. Someone who retires at 62 and lives well into their 90s faces a very different challenge from someone who needs the money for a much shorter retirement, and the lump sum has to survive every market wobble, unexpected expense, and extra year.

2. Investment Risk Moves Onto Your Shoulders

With a lump sum, the money needs a job, and that job usually involves investing it or carefully drawing it down. A poorly timed market decline early in retirement can create a nasty combination because withdrawals can force an investor to sell investments after they have fallen. PBGC specifically identifies investment risk as one of the risks that can shift from a pension plan to someone who accepts a lump sum.

An annuity changes that equation because the retiree receives the scheduled monthly benefit instead of managing a portfolio to manufacture each payment. That does not make an annuity perfect, since inflation, survivor benefits, health, and other factors still matter, but it can remove one enormous chore from retirement planning.

3. The Tax Bill Can Sneak Up Fast

A lump sum can create a tax headache if the money goes directly to the retiree instead of moving through a direct rollover. The IRS generally requires 20% federal withholding on taxable eligible rollover distributions paid directly to the recipient, even when that person intends to roll the money into another retirement account later.

That withholding does not necessarily represent the final tax bill, either. If someone receives the money personally and wants to roll over the entire distribution, that person generally needs to replace the withheld amount with other funds, while any taxable portion left outside the rollover can count as income for the year.

4. A Big Check Can Encourage Big Spending

There is something psychologically different about seeing a large balance sitting in an account compared with receiving a pension payment every month. A new car, home renovation, expensive trip, generous gift, or ambitious investment idea can suddenly feel affordable when the money sits there looking available. PBGC lists paying large debts and leaving money as an inheritance among potential advantages of a lump sum, but those benefits come with the responsibility of deciding how much money can safely leave the account.

The danger does not require reckless spending, either. A series of perfectly reasonable withdrawals can quietly add up over decades, particularly when retirement lasts longer than expected. A pension payment creates a natural spending boundary, while a lump sum gives the retiree considerably more freedom, and freedom can get expensive when nobody has to say, “Maybe not this month.”

5. Survivor Benefits Can Change the Math

Married retirees need to look beyond the monthly amount offered to the retiree and examine what happens after death. Pension plans can offer joint-and-survivor options that continue payments to a spouse, although choosing survivor protection can reduce the retiree’s monthly benefit.

A lump sum can provide an inheritance opportunity because whatever remains can potentially pass to beneficiaries, but that does not automatically make it better for a spouse. The retiree must consider how much income the surviving spouse would need, how the money would get invested, and whether either spouse could comfortably manage the account alone.

6. The Lump Sum May Look Bigger Than It Really Is

Pension plans calculate lump sums by converting a stream of future payments into a present value, using factors such as interest rates and mortality assumptions. That means the lump sum does not simply represent a pile of cash the plan would otherwise hand over one month at a time.

This creates an easy trap when comparing the options. A person might see a large lump sum and mentally compare it with the first year’s pension payments, but the real comparison involves decades of potential income, investment returns, taxes, inflation, survivor benefits, and personal spending needs.

7. Retirement Gets Harder When the Paycheck Ends

A steady pension can serve as an anchor for the rest of a retirement income plan. Social Security, personal savings, part-time income, and other assets can then work around that predictable monthly amount instead of carrying the entire burden of replacing it. PBGC recommends considering other steady income, savings, living expenses, debt, health, and taxes when comparing a lump sum with an annuity.

That does not mean taking the lump sum always makes a mistake. Someone with substantial assets, strong investment skills, limited need for guaranteed income, or specific estate-planning goals might reasonably prefer greater control over the money. The key involves treating the decision as a lifetime-income choice rather than simply deciding whether a big check feels better than a smaller monthly payment.

Before Saying Yes to the Big Check

A pension lump sum can offer flexibility, control, and potential inheritance value, but those advantages come with responsibilities that a lifetime pension payment handles automatically. Before choosing, compare the actual monthly annuity options, survivor provisions, inflation considerations, taxes, other retirement income, expected spending, and the investment plan for the lump sum. The IRS also makes clear that direct rollovers can avoid the mandatory 20% withholding that generally applies when an eligible distribution goes directly to the recipient.

Would you rather have the security of a monthly pension payment or the flexibility of controlling a lump sum, and why?

You May Also Like…

Money Moves Michigan Retirees Should Check After the 2026 Pension Withholding Change

The Retirement Expense Nobody Budgets for: Helping Adult Children

Should You Count Your Home in Your Retirement Net Worth?

Average Social Security Benefits for 81-Year-Old Retirees in 2026

7 Questions to Ask Before Using Dividend ETFs to Create a Retirement Paycheck

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Retirement Tagged With: annuity, investing, lump sum, pensions, Personal Finance, retirement income, retirement planning, Social Security

Government Pension Offset Is Wiping Out Spousal Benefits for Thousands of Retirees

June 12, 2026 by Brandon Marcus Leave a Comment

Government Pension Offset Is Wiping Out Spousal Benefits for Thousands of Retirees
Government Pension Offset rules can significantly reduce or eliminate spousal Social Security benefits, leaving retirees with unexpected income gaps and forcing major adjustments to retirement budgets and long-term financial plans. Shutterstock

Retirement planning takes a sharp turn when rules tied to public pensions collide with Social Security spousal benefits. The Government Pension Offset continues to reshape expectations for thousands of retirees who count on spousal income as part of their long-term financial stability. Many workers who spent careers in public service discover that their retirement checks reduce or even eliminate benefits they expected from a spouse’s Social Security record. That surprise often hits hardest when retirees already built budgets around fixed incomes and rising living costs.

This rule does not operate quietly in the background; it actively reshapes household retirement income in a way many people never anticipate. Families across the country face sudden shortfalls when they learn how strongly the offset applies. The impact spreads beyond individuals and affects entire households that planned for dual-income retirement security. That financial shock pushes many retirees to rethink budgets, delay plans, or seek additional income sources.

Why the Government Pension Offset Cuts Into Spousal Benefits

The Government Pension Offset reduces Social Security spousal or survivor benefits for individuals who receive a pension from non-covered government employment. Social Security applies a formula that subtracts two-thirds of the government pension from the spousal benefit amount. This reduction often eliminates the entire benefit for retirees with moderate or higher public pensions. Many retirees discover this rule only when they file for benefits, which creates frustration and financial strain.

The policy aims to balance public pensions with Social Security payments, but the outcome often feels harsh for affected households. Workers in education, public safety, and local government roles face the most noticeable reductions. The offset does not consider household expenses or individual financial need, which creates uneven pressure on retirement planning. This structure forces many retirees to adjust expectations after years of contributing to public service careers.

Who Feels the Biggest Financial Impact

Retirees with strong public-sector careers often feel the most significant reductions from the Government Pension Offset. Teachers, municipal workers, and state employees frequently fall into this category due to pension systems that do not contribute to Social Security. Many of these individuals expect spousal benefits to supplement modest pensions, especially after decades of service. Instead, the offset can eliminate that additional income stream entirely.

Spouses who relied on dual-benefit planning often face sudden budget gaps when retirement begins. Households that expected combined Social Security and pension income find themselves recalculating basic living expenses. Fixed costs such as housing, healthcare, and utilities quickly consume a larger share of reduced income. This financial pressure often forces retirees to delay travel, relocation, or other long-planned retirement goals.

How Retirees Experience Unexpected Budget Shifts

Retirees frequently report major shifts in monthly income after the Government Pension Offset takes effect. A spouse expecting a $900 monthly benefit may receive little or nothing once the calculation applies. That loss forces households to adjust spending habits almost immediately after retirement begins. Many families turn to savings accounts earlier than planned to fill the gap.

Healthcare costs intensify the strain because Medicare premiums and out-of-pocket expenses continue regardless of benefit reductions. Some retirees cut discretionary spending such as travel, dining, or hobbies to maintain essential expenses. Others delay major financial decisions like relocating or downsizing due to uncertain income stability. These adjustments often reshape retirement lifestyles in ways that feel unplanned and restrictive.

Strategies That Help Reduce the Financial Strain

Retirees facing the Government Pension Offset often explore alternative income strategies to stabilize their budgets. Some households increase withdrawals from retirement savings, although that approach requires careful planning to avoid long-term depletion. Others focus on part-time work or consulting roles that align with past careers. These strategies help offset lost spousal benefits without relying solely on Social Security income.

Financial planners often encourage early retirement modeling that includes the GPO reduction from the start. That planning approach helps retirees avoid surprise income gaps and adjust savings targets in advance. Couples also review benefit timing strategies to maximize available Social Security options before retirement begins. Strong preparation helps reduce the emotional and financial shock when offset rules apply.

What This Means for Future Retirement Planning

The Government Pension Offset continues to reshape how public-sector workers approach retirement income decisions. Many future retirees now factor the rule into their planning decades before leaving the workforce. This shift encourages more aggressive savings habits and broader investment strategies outside of pension systems. Retirement planning increasingly relies on diversified income sources rather than expected spousal benefits.

Retirement income stability depends heavily on understanding how policies like the Government Pension Offset interact with pensions and Social Security benefits. How should retirees better prepare for these reductions before leaving the workforce?

You May Also Like…

Working While Collecting Before Full Retirement Age Reduces Your Check More Than You Think

Joint Filers Are Losing Refunds Over One Spouse’s Debt — Without Prior Warning

7 Spousal Consent Rules That Can Disinherit Your Partner

CP2000 Notices Are Arriving for Income People Forgot They Reported — What to Do

5 Retirement Costs Financial Advisors Say Still Blindside Americans Over 60

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: social security Tagged With: Government Pension Offset, pensions, Retirement, retirement planning, Social Security, Social Security offset, spousal benefits

Survivor Benefits Are Being Miscalculated — And Widows Are Paying the Price

June 9, 2026 by Brandon Marcus Leave a Comment

Survivor Benefits Are Being Miscalculated — And Widows Are Paying the Price
Survivor benefit miscalculations can quietly reduce monthly income for widows, making it essential to review earnings records and payment statements carefully to protect long-term financial stability. Shutterstock

For many households, survivor benefits act like a financial lifeline after the loss of a spouse. These payments should provide stability, predictability, and a sense of security during an already difficult transition. However, recent concerns have highlighted a troubling issue: calculation errors inside survivor benefit systems can quietly reduce monthly payments. Even small mistakes can add up to thousands of dollars lost over time. Widows and surviving spouses often discover the problem only after years of underpayment. That delay creates financial strain that feels both sudden and overwhelming.

These miscalculations don’t always come from obvious mistakes. They often stem from outdated earnings records, incorrect benefit formula inputs, or overlooked eligibility adjustments. In some cases, the issue begins the moment the original retirement benefit gets calculated, which then carries forward into survivor benefits. Because most recipients trust the system to be accurate, they rarely double-check the math. That trust, while understandable, can leave major gaps unnoticed for years.

How Small Calculation Errors Snowball Into Big Financial Losses

Survivor benefits rely on a complex formula tied to the deceased spouse’s lifetime earnings. A single missing year of income or incorrectly recorded salary can shrink the final benefit amount significantly. Even minor data entry issues inside government records can reduce monthly payments without any obvious warning. Over time, these reduced payments stack up into a serious financial shortfall. Many widows only realize something is wrong when comparing their benefits to a friend’s or reviewing an annual statement closely.

The system also adjusts benefits based on age, claiming timing, and household status, which introduces even more room for mistakes. A widow who claims benefits at 60 instead of full retirement age may already receive a reduced amount, but an additional calculation error can deepen the loss. In some cases, remarriage history or dependent status gets recorded incorrectly, which further distorts payment levels. These issues rarely trigger automatic corrections. Instead, they require manual review, which many recipients never request.

Why Widows Often Miss the Warning Signs

Most widows trust official benefit letters and deposit amounts without questioning the math behind them. That trust creates a gap where errors can continue unchecked for years. The benefit system does not always clearly flag discrepancies in a way that stands out to recipients. A slightly lower monthly payment might look like a standard adjustment instead of a calculation problem. Over time, that “small difference” turns into a major financial gap that affects rent, groceries, and medical costs.

Another challenge comes from emotional and administrative overload after losing a spouse. Paperwork, legal documents, and financial accounts already demand attention during a stressful period. Benefit verification often falls low on the priority list. Many people also assume corrections require complicated legal steps or lengthy appeals, so they avoid challenging the system. This hesitation allows errors to persist far longer than they should. In reality, reviewing earnings records and benefit statements can reveal issues much earlier.

The Real-World Impact on Household Stability

Miscalculated survivor benefits don’t just affect monthly income—they reshape long-term financial security. A reduction of even a few hundred dollars per month can force difficult lifestyle changes. Some widows delay medical care, reduce essential spending, or take on unexpected debt to compensate for missing funds. These adjustments ripple through every part of household budgeting. Over time, financial stress compounds the emotional strain already tied to loss.

Retirement planning also takes a hit when survivor benefits fall short. Many households rely on these payments as a foundation for fixed-income stability. When that foundation weakens, savings accounts and emergency funds get depleted faster. Inflation makes the problem even worse, since reduced benefits don’t always keep pace with rising costs. Financial advisors often stress the importance of verifying benefit accuracy early to prevent long-term instability. Even a small correction can restore thousands of dollars over a lifetime.

Protecting Survivor Benefits Before Errors Drain Income

Careful record-keeping plays a major role in preventing or correcting benefit miscalculations. Reviewing the deceased spouse’s earnings history through official statements can reveal missing or incorrect data. Cross-checking benefit letters against expected calculations can also highlight inconsistencies. If something feels off, requesting a formal review can trigger a correction process. While the system may seem intimidating, persistence often leads to adjustments and back payments when errors exist.

Financial professionals also encourage widows to reassess benefits after major life changes. Changes in income, age milestones, or updated eligibility rules can all impact payment accuracy. Keeping detailed records of correspondence with benefit offices helps build a stronger case if disputes arise. Many corrections do not happen automatically, so proactive monitoring becomes essential. Staying informed turns confusion into control and reduces the risk of long-term underpayment.

The Bottom Line on Survivor Benefit Accuracy

Survivor benefits should provide steady financial support, but calculation errors can quietly undermine that promise. Widows and surviving spouses often lose money simply because they trust the system without verifying the details. Small inaccuracies grow into major financial gaps over time, affecting everyday stability and long-term planning. Careful review, timely corrections, and awareness of potential issues can prevent unnecessary losses. Financial security after loss depends not just on eligibility, but also on accuracy.

As more people examine these concerns, the importance of benefit transparency continues to grow. Families deserve clarity when it comes to the income they rely on for daily living. Even small corrections can restore stability and confidence in long-term planning.

Have benefit calculations ever surprised you or someone you know? Share your thoughts in the comments below.

You May Also Like…

SNAP Alert: Why Some Seniors Are Seeing Lower Food Benefits This Month — and What to Check Before June Deposits Arrive

Congress Is Considering a $200 Social Security Boost—What It Could Mean for Retirees

Why Some Retirees Are Claiming Social Security Early Despite Smaller Check Warnings

Born Late in the Month? Seniors with Birthdays 21–31 Wait the Longest for May Social Security Checks

The 2027 Social Security COLA Forecast Just Jumped — Here’s What Could Still Reduce Your Check

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: social security Tagged With: pensions, Planning, Retirement, retirement income, Social Security, SSA errors, survivor benefits, widows

7 Ways Retirees Accidentally Trigger Higher Medicare Premiums

May 18, 2026 by Brandon Marcus Leave a Comment

7 Ways Retirees Accidentally Trigger Higher Medicare Premiums
A couple of reitrees seeing a doctor – Shutterstock

Retirement often feels like a financial finish line, but Medicare premiums don’t always stay predictable once income enters the picture. Many retirees discover that past financial decisions can echo forward in unexpected ways, especially when tax rules start interacting with healthcare costs. The system looks at income data from two years earlier, which means today’s choices can shape tomorrow’s premiums. Even small shifts in income can push monthly Medicare costs higher than expected.

Many retirees assume Medicare stays stable after enrollment, yet income-related adjustments often tell a different story. Certain financial moves trigger IRMAA surcharges that quietly increase Part B and Part D premiums. These increases rarely appear immediately, which makes them even more surprising when they arrive. Knowing the most common triggers helps retirees stay ahead of avoidable costs.

1. Reporting Higher Income from a One-Time Event

Medicare premiums often jump when retirees report unexpected income spikes. A single event like a Roth conversion or large capital gain can push income into IRMAA brackets. This surprise often hits hardest when retirees sell assets or unlock retirement funds in a single tax year. One decision can ripple through Medicare costs for years.

Social Security and Medicare rely on tax returns from two years prior to calculate premiums. That delay often catches retirees off guard when they make large financial moves without planning ahead. Even a one-time boost in income can set a higher premium baseline for multiple years. Careful timing of major financial events helps smooth income and reduce unnecessary Medicare surcharges.

2. Taking Large Required Minimum Distributions (RMDs)

Required Minimum Distributions can quietly push retirees into higher Medicare premium tiers. These withdrawals begin at age 73 under current federal rules. Many retirees underestimate how quickly these mandatory withdrawals increase taxable income. The size of traditional IRA balances often determines the severity of the impact.

Large RMDs frequently stack on top of other retirement income sources, creating a higher overall tax picture. Medicare uses that combined income to calculate monthly adjustments. This system often surprises retirees who thought withdrawals would only affect taxes, not healthcare costs. Strategic withdrawal planning earlier in retirement can reduce long-term premium pressure.

3. Selling Investments Without Tax Planning

Selling stocks or mutual funds without planning can create sudden taxable gains. Those gains often raise modified adjusted gross income for Medicare purposes. Even strong market performance can backfire when retirees realize profits all in one year. Timing becomes just as important as investment selection.

Capital gains often combine with other income sources, pushing retirees over key thresholds. Medicare premiums increase when income crosses those lines, even by a small margin. Many retirees overlook how quickly a few profitable trades can shift their tax profile. Spreading sales across multiple tax years often helps control premium increases.

4. Missing the Impact of Interest and Dividends

Interest income and dividends can quietly accumulate and push income higher. Many retirees underestimate how these “small” earnings build up over time. High-yield savings accounts and brokerage portfolios often create steady taxable income streams. These streams feel harmless until they combine into a larger total.

Medicare uses combined income to determine premium levels, not just wages or pensions. That means passive income plays a bigger role than many retirees expect. Even modest increases in interest rates can shift totals enough to matter. Regular financial reviews help keep income aligned with long-term Medicare planning.

7 Ways Retirees Accidentally Trigger Higher Medicare Premiums
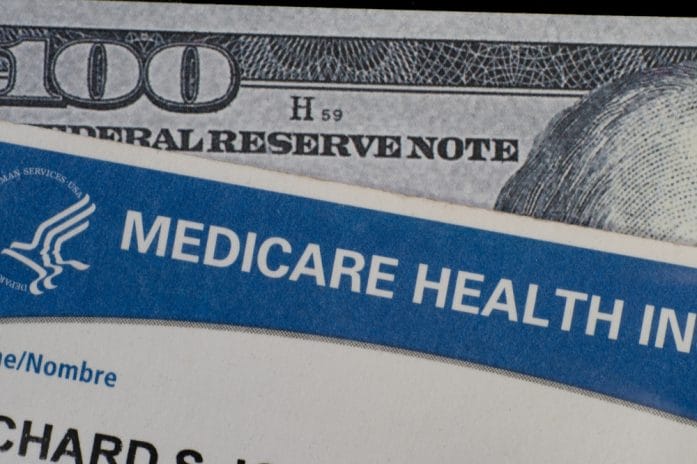
A $100 bill sitting behind a Medicare health card – Shutterstock

5. Underestimating Spousal Income Effects

Medicare calculates premiums based on household income, not just individual earnings. A spouse’s income can therefore trigger higher premiums unexpectedly. This situation often surprises retirees when one partner continues working longer than planned. Joint income creates a combined financial picture that Medicare evaluates together.

Working spouses can unintentionally raise both partners’ Medicare costs. Retirees sometimes overlook how tax filing status influences premium calculations. Even part-time income can push household totals into higher brackets. Coordinated retirement timing between spouses helps reduce unexpected financial pressure.

6. Overlooking Taxable Pension Changes

Changes in pension income can shift retirees into higher Medicare brackets. Cost-of-living adjustments or lump-sum payouts often create unexpected tax consequences. Many retirees assume pensions stay predictable, but adjustments often tell a different story. These changes can arrive gradually or in sudden financial bursts.

Some pension increases raise taxable income more than retirees initially expect. That added income feeds directly into Medicare’s calculation formula. Even small annual increases can accumulate into higher long-term premiums. Reviewing pension statements each year helps retirees stay ahead of potential cost jumps.

7. Not Managing Retirement Account Conversions Carefully

Roth conversions often trigger higher Medicare premiums when done without strategy. These conversions increase taxable income in the year they occur. Many retirees pursue conversions for long-term tax benefits but overlook short-term Medicare effects. Timing plays a critical role in how these conversions affect overall costs.

Large conversions can unintentionally push retirees into higher IRMAA tiers. Spreading conversions across several years often reduces financial strain. Even partial conversions require careful income forecasting to avoid surprises. Smart planning turns conversions into a tool instead of a costly mistake.

Keeping Medicare Premiums Under Control

Medicare premiums often rise because income planning slips through the cracks. Retirees gain more control when they track taxable income throughout the year. Strategic timing of withdrawals, sales, and conversions makes a major difference in long-term costs. Even small adjustments today can prevent expensive premium surprises later. Proactive planning helps retirees protect income while keeping healthcare costs more predictable.

What financial move surprised most retirees when it affected Medicare costs? Share your thoughts and experiences in the comments below.

You May Also Like…

5 Medicare Services Seniors Are Losing Coverage For in 2026

6 Costly Medicare Enrollment Mistakes Retirees Keep Making

The Next Medicare Premium Shock Could Hit Retirees Harder Than Expected

The “Forever Home” Problem Is Trapping More Retirees Financially

Florida’s Insurance Spike: Why Retirees Are Seeing “Rebuild Fees” on May Statements

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Retirement Tagged With: capital gains, dividend income, interest income, IRMAA, Medicare, Medicare premiums, pensions, Planning, retirees, retirement income, retirement savings, RMDs, Roth conversion, Social Security, taxes in retirement

High-Tax States vs Low-Tax States — Where Retirees Keep More Money

April 13, 2026 by Brandon Marcus Leave a Comment

High-Tax States vs Low-Tax States — Where Retirees Keep More Money
Image Source: Shutterstock.com

A retirement plan can look perfect on paper and still fall apart the moment state taxes enter the picture. Numbers shift, expectations wobble, and suddenly that dream of stretching savings over decades feels less certain. Geography doesn’t just influence weather and scenery; it directly impacts how long money lasts and how comfortably life unfolds after work ends. Some states welcome retirees with lighter tax burdens, while others quietly chip away at income through multiple layers of taxation.

The contrast between high-tax and low-tax states creates a financial tug-of-war that shapes everyday decisions, from housing to healthcare to leisure. A retiree might earn the same income in two different states yet experience wildly different lifestyles based on what remains after taxes. That difference can mean more travel, more security, or simply less stress about monthly expenses. The stakes feel real because they are real, and understanding the landscape offers a powerful advantage for anyone planning the next chapter.

The Tax Tug-of-War: What Actually Gets Taxed?

Retirement income comes from multiple streams, and each state treats those streams differently. Social Security benefits often escape state taxation, but several states still impose taxes depending on income levels, which can catch people off guard. Pension income, a lifeline for many retirees, faces taxation in some states while others offer full or partial exemptions. Investment income, including dividends and capital gains, frequently falls under state tax rules, adding another layer of complexity that can quietly reduce yearly income.

Sales taxes also play a huge role, even though they don’t show up as clearly as income taxes. Everyday purchases, from groceries to appliances, can add up quickly in states with higher rates, especially when local taxes stack on top of state taxes. Property taxes bring another major factor into the equation, and they can vary dramatically even within the same state. A retiree who owns a home may feel that pressure more than someone renting, especially in areas where property values continue to rise. These combined taxes create a financial ecosystem that requires careful navigation rather than guesswork.

Understanding what gets taxed helps retirees avoid surprises and build a more accurate budget. A state with no income tax might still lean heavily on sales or property taxes, which can offset the apparent savings. Some states design tax systems that appear friendly at first glance but reveal hidden costs over time. Others provide targeted relief programs for seniors, such as property tax freezes or credits, which can significantly ease the burden. The smartest approach involves looking at the full picture rather than focusing on a single tax category.

High-Tax States: The Trade-Off Between Lifestyle and Cost

High-tax states often deliver undeniable appeal, offering top-tier healthcare systems, vibrant cultural scenes, and strong infrastructure. Places like California and New York attract retirees who value access to world-class amenities and diverse communities. However, those benefits come at a price, and that price often shows up in income taxes, property taxes, and high living costs. Retirees who choose these states need to plan carefully to ensure their income can support the lifestyle they want without constant financial strain.

Property taxes in certain high-tax states can hit particularly hard, especially in desirable areas where home values remain elevated. Even retirees who paid off their mortgages may still face significant annual tax bills that eat into fixed incomes. Add in higher costs for healthcare, transportation, and everyday goods, and the financial pressure can build quickly. Some states do offer tax breaks for seniors, but those benefits don’t always fully offset the broader tax burden.

Despite these challenges, high-tax states still make sense for some retirees. Proximity to family, access to specialized medical care, and lifestyle preferences often outweigh financial considerations. The key lies in entering retirement with eyes wide open and a clear understanding of how taxes will affect long-term sustainability. Strategic planning, such as downsizing or adjusting spending habits, can help balance the equation and make high-tax environments more manageable.

Low-Tax States: Stretching Every Dollar Further

Low-tax states present a compelling alternative for retirees who want their money to go further. States like Florida, Texas, and Tennessee attract attention because they don’t impose state income taxes, allowing retirees to keep more of their earnings. This advantage can make a noticeable difference, especially for those relying on pensions, investments, or withdrawals from retirement accounts. Lower tax burdens often translate into greater financial flexibility and the ability to enjoy retirement without constant budget stress.

Cost of living also tends to run lower in many of these states, which amplifies the benefits of reduced taxation. Housing costs, utilities, and general expenses often align with the goal of stretching income over a longer period. Retirees can allocate more funds toward travel, hobbies, or simply building a financial cushion for unexpected expenses. That breathing room can transform retirement from a cautious balancing act into a more relaxed and enjoyable phase of life.

However, low-tax states don’t automatically guarantee financial perfection. Some rely more heavily on sales taxes, which can impact spending over time, and certain areas may lack the infrastructure or healthcare options found in higher-tax regions. Retirees need to weigh these trade-offs carefully, considering both financial and lifestyle factors. A lower tax bill feels great, but it works best when paired with a location that supports overall well-being and long-term needs.

High-Tax States vs Low-Tax States — Where Retirees Keep More Money
Image Source: Shutterstock.com

Strategies to Maximize Retirement Income

Planning ahead can make a huge difference in how taxes impact retirement. Choosing the right state often represents one of the most powerful decisions, but timing also matters. Moving before retirement can simplify tax transitions and help establish residency in a more favorable location. Retirees should also explore state-specific tax benefits, such as exemptions for certain types of income or credits designed for seniors.

Diversifying income sources can help manage tax exposure more effectively. Relying solely on taxable income streams can increase overall tax liability, while a mix of taxable and non-taxable income can provide greater flexibility. Strategic withdrawals from retirement accounts, timed carefully, can also reduce tax burdens and preserve savings. Consulting with a financial advisor who understands state tax nuances can provide valuable insights and prevent costly mistakes.

Lifestyle adjustments can also play a role in maximizing retirement income. Downsizing a home, relocating within a state to a lower-tax area, or adjusting spending habits can create meaningful savings. Even small changes, such as taking advantage of local tax exemptions or senior discounts, can add up over time. Retirees who approach these decisions proactively often find themselves in a stronger financial position and better prepared for the years ahead.

Finding the Right Balance for Your Retirement

Choosing between high-tax and low-tax states ultimately comes down to balance. Financial considerations matter, but they don’t exist in isolation, and the right decision depends on individual priorities and goals. Some retirees thrive in vibrant, high-cost environments because they value access and activity, while others prefer quieter, more affordable locations that allow their savings to stretch further. No single answer fits everyone, and that flexibility creates both opportunity and responsibility.

Which matters more in retirement: keeping more money or living exactly where the heart feels at home? Share thoughts, strategies, or experiences in the comments and keep the conversation going.

You May Also Like…

The Retirement Age Just Hit 67 — What That Means for Your Monthly Check

How Seniors Jeopardize Their Social Security Right After Retirement

How Medicare’s Income-Related Surcharge Sneaks Up On Retirees

8 Hidden Fees That Can Eat Away at Your Retirement Savings

Retirement Accounts Are Triggering Unexpected Taxes — What Some Investors Overlook

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: tax tips Tagged With: budgeting, Cost of living, financial freedom, pensions, Personal Finance, relocation, retirement income, retirement planning, savings strategies, Social Security, state taxes, taxes

Why Your Pension Check Could Shrink – Triggers and Solutions

April 9, 2026 by Brandon Marcus Leave a Comment

Why Your Pension Check Could Shrink - Triggers and Solutions
Image Source: Shutterstock.com

An unexpected drop in retirement income doesn’t just sting—it disrupts absolutely everything. That carefully planned budget suddenly looks shaky, grocery runs feel heavier, and long-term security starts to feel like a moving target. Pension checks carry a promise of stability, yet that promise can bend under pressure from factors many never see coming. This isn’t about fear—it’s about awareness, because knowing what causes those changes puts control back where it belongs.

Plenty of people assume pensions stay fixed once they start rolling in, like a steady metronome ticking through retirement years. That assumption misses a big truth: pensions live in a world that keeps changing, and those changes don’t always work in your favor. Economic shifts, policy updates, and even personal decisions can quietly chip away at that monthly number. The good news? Every trigger has a counter-move, and understanding both sides turns uncertainty into strategy.

The Inflation Squeeze That Doesn’t Let Go

Inflation barges in and eats away at purchasing power one dollar at a time. Even when pension payments stay technically the same, rising prices can make them feel smaller with every passing month. Groceries, utilities, and healthcare costs often climb faster than expected, and that imbalance creates a gap that keeps widening if no adjustments step in. Some pensions include cost-of-living adjustments, often called COLA, but not all plans offer them, and even when they do, they don’t always match real-world price increases.

That gap between income and expenses forces tough choices, especially when fixed incomes can’t stretch the way they used to. A pension that covered everything comfortably five years ago may now struggle to keep up with essentials. The key here lies in proactive planning, not reactive scrambling. Building a buffer through savings or diversified income streams can soften inflation’s impact before it hits hard.

Smart moves include reviewing spending regularly and identifying areas where costs can shrink without sacrificing quality of life. Some people lean into part-time work or passive income streams to offset the squeeze, while others shift investments toward assets that historically keep pace with inflation. No single strategy fits everyone, but doing nothing guarantees that inflation wins the tug-of-war.

Why Your Pension Check Could Shrink - Triggers and Solutions
Image Source: Shutterstock.com

Early Retirement Decisions That Come With Trade-Offs

Retiring early sounds like a dream, but that dream often comes with a financial trade-off that shows up in smaller pension checks. Many pension systems calculate benefits based on years worked and age at retirement, so leaving the workforce sooner typically reduces monthly payouts. That reduction doesn’t disappear over time—it sticks around for the long haul, which means less income year after year.

Those early years of freedom can feel incredible, but the long-term math demands attention. A smaller pension combined with a longer retirement period can stretch finances thin if no backup plan exists. This doesn’t mean early retirement always leads to trouble, but it does mean the decision deserves careful calculation and realistic expectations.

Balancing the desire for early retirement with financial stability often involves creative solutions. Some choose phased retirement, working part-time while beginning to draw partial benefits, which helps bridge the income gap. Others build larger savings cushions before stepping away from full-time work. The goal isn’t to avoid early retirement—it’s to step into it with eyes wide open and a plan that supports the lifestyle that follows.

Policy Changes That Rewrite the Rules

Pension systems don’t operate in a vacuum; governments and organizations adjust rules over time, and those changes can ripple directly into monthly payments. Legislative updates may alter benefit formulas, tax rates, or eligibility criteria, and those adjustments can increase or decrease the amount received. While not every change leads to a reduction, enough do that staying informed becomes essential.

Taxes deserve special attention because they often fly under the radar until they take a bite out of income. Depending on where someone lives and how their pension gets taxed, a change in tax policy can quietly reduce take-home pay. That reduction doesn’t show up as a smaller pension on paper, but it feels exactly the same in everyday life.

Staying ahead of policy changes requires a bit of vigilance, but it pays off. Regularly checking updates from pension providers or financial advisors can prevent unpleasant surprises. Adjusting financial plans in response to new rules helps maintain stability, even when the system shifts. Knowledge turns policy changes from a shock into something manageable.

Investment Performance That Shapes the Outcome

Not all pensions guarantee fixed payments; some depend on investment performance, and that introduces another layer of unpredictability. Market downturns can impact pension funds, especially those tied to defined contribution plans or hybrid structures. When investments underperform, future payouts may shrink or fail to grow as expected.

Even traditional pension funds feel the effects of broader economic conditions, since they rely on investment returns to sustain payouts over time. Poor performance can lead to funding gaps, and those gaps sometimes force adjustments to benefits. This doesn’t happen overnight, but the impact builds gradually, often becoming noticeable only after several years.

Diversification offers one of the strongest defenses against this risk. Spreading investments across different asset classes can reduce the impact of any single downturn. Keeping a close eye on pension statements and understanding how funds get managed also adds a layer of control. Awareness turns investment risk into something that can be navigated rather than feared.

Life Changes That Shift the Numbers

Personal circumstances can influence pension payments more than expected. Divorce, remarriage, or survivor benefit elections can all affect how much money flows each month. Some pensions reduce payments to provide ongoing benefits to a spouse, while others adjust based on changes in household structure.

Healthcare costs also play a major role, especially as retirement progresses. Rising medical expenses can eat into pension income quickly, even if the payment itself doesn’t change. Long-term care needs can amplify that pressure, creating a situation where income feels smaller simply because expenses climb so high.

Planning for these life changes involves more than just paperwork—it requires thoughtful decisions about the future. Choosing the right survivor benefit option, maintaining adequate insurance coverage, and setting aside funds for healthcare can help preserve financial stability. These decisions may feel complex, but they provide a safety net that keeps retirement on solid ground.

Protecting the Check Without Losing Sleep

No one wants to spend retirement worrying about shrinking income, and the good news is that several strategies can help keep things steady. Diversifying income sources stands out as one of the most effective approaches, since relying on a single stream creates vulnerability. Combining pensions with savings, investments, or even small side income streams can create a more resilient financial picture.

Budgeting plays a bigger role than many expect, especially when it comes to tracking spending patterns and adjusting before problems arise. Small tweaks, like reducing unnecessary subscriptions or optimizing utility usage, can free up cash without making life feel restricted. These adjustments may seem minor, but they add up quickly over time.

Regular financial check-ins can make a huge difference, too. Reviewing income, expenses, and long-term goals helps catch potential issues early, when solutions remain simple and effective. Retirement doesn’t have to feel uncertain or fragile—it can feel stable and even empowering with the right approach in place.

What Deserves Your Attention

Pension checks don’t shrink without a reason, and every reason comes with a chance to respond. Inflation, early retirement decisions, policy changes, investment performance, and personal life shifts all play a role in shaping retirement income. Ignoring those factors leaves too much up to chance, while understanding them opens the door to smarter decisions and a stronger financial footing.

What strategies have made the biggest difference in keeping your retirement income steady, or what concerns still feel unresolved? Give us your thoughts, ideas, or personal approaches in the comments.

You May Also Like…

How Seniors Jeopardize Their Social Security Right After Retirement

10 Retirement States That No Longer Cater to Retirees

5 Tax Mistakes Retirees Make and How To Fix Them Before It’s Too Late

Retirees Are Rethinking Second Homes — Why the “Snowbird Lifestyle” Is Getting Too Expensive

Retirees Are Rethinking Second Homes — Why the “Snowbird Lifestyle” Is Getting Too Expensive

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Retirement Tagged With: budgeting, COLA, Cost of living, income protection, Inflation, pension cuts, pensions, Planning, retirement income, Retirement Tips, seniors finance, Social Security

5 Ways to Review Your Retirement Plan 5 Years Before Leaving Work

March 19, 2026 by Brandon Marcus Leave a Comment

5 Ways to Review Your Retirement Plan 5 Years Before Leaving Work
Image Source: Shutterstock.com

Five years. That’s not some distant, hazy future anymore—that’s right around the corner. Retirement stops being an abstract dream and starts acting like a deadline, and every financial decision suddenly carries real weight. This is the moment where a solid plan either holds strong or starts to wobble, and ignoring that reality can cost more than just peace of mind.

This stage calls for focus, clarity, and a willingness to look at numbers without flinching. A strong review doesn’t mean tearing everything apart. It means tightening the bolts, fixing weak spots, and making sure nothing slips through the cracks at the worst possible time. These next five years can turn a “maybe” retirement into a confident, ready-to-go launch.

1. Get Brutally Honest About Your Numbers

A retirement plan only works when it reflects reality, not hopeful guesses or outdated assumptions. Start by digging into current savings, investment balances, and expected income streams, and make sure every number tells the truth. Look at retirement accounts, pensions, and any other assets that will fund life after work, and calculate where things stand right now. This step doesn’t leave room for rounding up or ignoring gaps, because small inaccuracies can snowball into major shortfalls.

Once those numbers sit clearly on the table, compare them against expected expenses in retirement. Housing, healthcare, food, travel, and everyday living costs all deserve a place in that estimate, and underestimating any of them creates risk. Inflation also needs attention, since prices will not stay frozen over the next five years. Adjust projections to reflect realistic growth in expenses, not wishful thinking. That honest comparison between savings and spending reveals whether the plan stays on track or needs immediate attention.

After that, stress-test the plan with different scenarios, including market dips or unexpected costs. A strong plan handles bumps without falling apart, and this step helps uncover weak spots before they cause damage. Consider working with a financial advisor to double-check calculations and assumptions, since a second set of eyes can catch what gets missed. This process may feel uncomfortable, but clarity always beats surprises later. Facing the numbers head-on builds confidence and gives every future decision a stronger foundation.

2. Tighten Your Investment Strategy Before It Matters Most

The five-year mark demands a shift in how investments get handled, because the timeline for recovery shrinks fast. Growth still matters, but protecting what’s already built starts to take priority. That doesn’t mean pulling everything out of the market, but it does mean adjusting risk levels to match the shorter horizon. A portfolio loaded with high-risk assets may deliver gains, but it also carries the potential for sharp losses at the worst possible moment.

Rebalancing becomes essential here, especially if investments have drifted away from their original allocation. Stocks may have grown to dominate the portfolio over time, and that imbalance increases risk as retirement approaches. Bringing things back into balance helps protect gains while still allowing for growth. Bonds, cash equivalents, and other lower-risk assets can play a bigger role during this phase, depending on individual goals and comfort levels.

Sequence of returns risk also deserves serious attention, since early losses in retirement can damage long-term sustainability. Adjusting the portfolio to reduce volatility helps guard against that scenario. Consider creating a “bucket strategy,” where short-term expenses sit in safer assets while long-term funds remain invested for growth. This structure provides stability and flexibility at the same time. A thoughtful investment adjustment now can prevent stress and financial strain later.

3. Lock In Your Retirement Income Game Plan

Savings alone don’t carry retirement across the finish line—income does. Five years out, it’s time to map out exactly how money will flow once paychecks stop. Start by identifying all potential income sources, including retirement accounts, pensions, and government benefits. Each source comes with its own rules, timelines, and tax implications, so understanding how they work together becomes essential.

Timing decisions can make a significant difference in total income. Delaying certain benefits, for example, can increase monthly payments, while early withdrawals may reduce long-term security. Weigh those choices carefully, considering both immediate needs and future stability. Withdrawal strategies also matter, since pulling money from the wrong accounts at the wrong time can increase tax burdens unnecessarily.

Creating a structured withdrawal plan helps maintain balance and control. Decide which accounts to tap first, how much to withdraw annually, and how to adjust during market changes. This approach reduces guesswork and prevents reactive decisions during stressful moments. A clear income strategy turns a pile of savings into a reliable financial engine, and that shift makes retirement feel real and manageable.

4. Eliminate Financial Loose Ends That Can Trip You Up

Loose ends don’t just create inconvenience—they create risk. Debt stands at the top of that list, especially high-interest balances that can eat into retirement income. Paying down or eliminating debt before leaving work can free up cash flow and reduce stress significantly. Even manageable debts deserve attention, since fixed payments can limit flexibility later.

Insurance coverage also needs a careful review, particularly health insurance and long-term care considerations. Healthcare costs tend to rise with age, and failing to plan for them can derail even a strong financial plan. Evaluate existing coverage, explore options, and make adjustments where needed. This step may not feel exciting, but it plays a crucial role in protecting financial stability.

Estate planning should also move to the front of the line during this phase. Wills, beneficiary designations, and power of attorney documents all need to stay current and aligned with current goals. Outdated documents can create confusion and unintended consequences down the road. Taking care of these details now removes uncertainty and keeps everything running smoothly later. Cleaning up these loose ends may not deliver instant gratification, but it removes obstacles that could cause serious problems in the future.

5 Ways to Review Your Retirement Plan 5 Years Before Leaving Work
Image Source: Shutterstock.com

5. Build A Lifestyle Plan That Matches Your Money

Retirement planning isn’t just about numbers—it’s about how life will actually look and feel. Five years out, it’s time to get specific about daily routines, spending habits, and lifestyle choices. A vague idea of “relaxing” won’t cut it when it comes to budgeting and planning. Define what retirement will include, whether that means travel, hobbies, part-time work, or something entirely different.

That vision should connect directly to financial decisions. Travel plans, for example, can significantly impact spending, while staying close to home may reduce costs. Housing choices also play a major role, especially if downsizing or relocating becomes part of the plan. Each decision carries financial implications, so aligning lifestyle goals with available resources becomes critical.

Testing the lifestyle before retirement can provide valuable insight. Try living on a projected retirement budget for a few months and see how it feels. This experiment can reveal gaps, highlight unnecessary expenses, and build confidence in the plan. Adjust as needed based on real experience rather than assumptions. A clear, realistic lifestyle plan ensures that money supports the life ahead instead of limiting it.

Turn The Final Stretch Into Your Strongest Move Yet

Five years might sound short, but it holds incredible power when used wisely. This window offers a chance to sharpen every detail, strengthen every weak point, and walk into retirement with clarity instead of uncertainty. Every adjustment made now carries real impact, and those changes can mean the difference between stress and confidence.

Momentum matters during this stage, and consistent action builds that momentum quickly. Small improvements stack up, and smart decisions compound over time. The goal isn’t perfection—it’s progress with purpose. With the right focus, these final years can transform a decent plan into a rock-solid one.

What changes feel most important right now, and which strategies have already made a difference along the way? Share thoughts, ideas, or lessons in the comments and keep the conversation moving forward.

You May Also Like…

The Retirement Honeymoon Phase — Planning for Years 1 and 2

Think You Need $2 Million to Retire? Think Again (It’s Much Lower)

Starting Retirement Savings at 30 With $0 — Is Catching Up Still Possible?

Is Mississippi the Cheapest Place to Retire?

Waiting on Social Security? Why Thousands of Retirees Are Stuck in Payment Limbo Right Now


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Retirement Tagged With: budgeting, investing, life planning, long term planning, money tips, pensions, Personal Finance, Planning, retirement income, retirement planning, savings strategy, Wealth management

Income Stability: 6 Retirement Income Moves That Aren’t as Safe as They Seem

January 2, 2026 by Brandon Marcus Leave a Comment

Income Stability: 6 Retirement Income Moves That Aren’t as Safe as They Seem
Image Source: Shutterstock.com

Retirement is often sold as the great exhale of life — the moment when the clock stops yelling, the calendar loosens its grip, and your money finally works for you instead of the other way around.

But beneath that glossy vision of beach chairs and morning coffee freedom sits a quieter reality: not all “safe” income strategies are actually safe. Some are built on assumptions that worked in yesterday’s economy, not today’s faster, stranger, and more expensive world. Others look stable on paper but wobble when inflation, taxes, or timing enter the room. And a few are downright comforting illusions dressed up as financial wisdom.

If your retirement plan leans on anything that “everyone says” is reliable, it might be time to take a closer look before confidence turns into costly surprise.

1. Relying Too Heavily On Social Security Alone

Social Security feels dependable because it’s familiar, predictable, and government-backed, but that doesn’t mean it’s sufficient. The average benefit replaces only a portion of pre-retirement income, often far less than people expect when real-world expenses show up. Cost-of-living adjustments help, but they rarely keep pace with healthcare, housing, and lifestyle inflation over decades. Claiming early can permanently shrink your benefit, while waiting too long may strain savings unnecessarily. Treating Social Security as a foundation is smart, but building your entire retirement house on it is risky.

Income Stability: 6 Retirement Income Moves That Aren’t as Safe as They Seem
Image Source: Shutterstock.com

2. Assuming Pensions Are Untouchable

Pensions used to be the gold standard of retirement security, yet today they’re far from bulletproof. Many private and even public pensions face underfunding, management issues, or benefit adjustments that retirees never saw coming. Some plans reduce payouts, freeze cost-of-living increases, or shift risks onto participants without much warning. Relying on a pension as if it’s immune to economic or political change can create a false sense of permanence. A pension can be powerful, but it should be one pillar, not the whole structure.

3. Treating Dividend Stocks Like Guaranteed Paychecks

Dividend stocks feel comforting because they produce regular income without selling shares. The problem is dividends are optional, not promises, and companies can reduce or eliminate them during downturns. Market volatility, industry disruption, or poor leadership can quickly turn “reliable income” into shrinking payments. Chasing high yields often means taking on hidden risk that only becomes obvious when it’s too late. Dividend investing works best when balanced with diversification and realistic expectations, not blind trust.

4. Believing Annuities Are Always Safe Havens

Annuities are often marketed as worry-free income machines, but the fine print can tell a different story. Fees, surrender charges, and complex terms can quietly erode returns over time. Some annuities lock money away so tightly that accessing it in an emergency becomes expensive or impossible. Others rely heavily on the financial health of the issuing company, which is not guaranteed forever. Annuities can play a role, but only when the structure truly fits the retiree’s needs.

5. Counting On Real Estate To Always Pay Off

Rental income sounds like the ultimate passive income dream, until repairs, vacancies, and market shifts show up uninvited. Property values don’t always rise, and selling at the wrong time can mean locking in losses instead of gains. Taxes, insurance, and maintenance often grow faster than rental income, especially in later years. Real estate can absolutely be a strong income source, but treating it as foolproof ignores its very real volatility. Owning property still requires active management, even in retirement.

6. Ignoring Inflation Because “It Hasn’t Been That Bad”

Inflation rarely feels dangerous until it suddenly is. Even modest inflation can quietly cut purchasing power in half over a long retirement. Fixed income streams that feel generous today may struggle to cover basics 15 or 20 years from now. Healthcare, food, and housing often inflate faster than official averages, hitting retirees especially hard. Planning without accounting for inflation is like sailing with a slow leak you don’t notice until the boat starts tilting.

Stability Comes From Awareness, Not Assumptions

Retirement income isn’t about finding one perfect solution; it’s about building flexibility into a long and unpredictable chapter of life. The most dangerous plans are the ones that feel “set it and forget it,” because they quietly ignore how fast the world changes. Real stability comes from understanding the risks, diversifying income sources, and revisiting decisions as life evolves. When you question what seems safe, you give yourself the power to adjust before problems grow teeth.

If you’ve had a retirement surprise — good or bad — or learned a lesson the hard way, drop your thoughts or experiences in the comments below and keep the conversation going.

You May Also Like…

Savings Leap: 9 Mid-Life Moves That Boost Long-Term Retirement Odds

8 Harsh Truths Why Boomers Can’t Change Their Retirement Plans Now

Expense Overflow: 4 Retirement Bills That Catch People Off Guard

At What Age Should You Seriously Start Thinking About Retirement?

Savings Base: 6 Foundational Moves That Keep Retirement Plans Stable


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Retirement Tagged With: annuities, Dividends, Income, income moves, pensions, retire, retiree, retirees, Retirement, retirement income, retirement planning, retirement plans, senior citizens, seniors, Social Security, stock market, stocks

  • 1
  • 2
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework