• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Lifestyle

Escrow Shortages Are Adding $100–$300 to Monthly Mortgage Payments

February 14, 2026 by Brandon Marcus Leave a Comment

Escrow Shortages Are Adding $100–$300 to Monthly Mortgage Payments
Image source: shutterstock.com

Escrow shortages are no longer a math problem only accountants care about; they’re wreaking real havoc on homeowners’ wallets.

Imagine sitting down one morning, coffee in hand, only to discover your mortgage payment just jumped by a couple of hundred bucks. You didn’t refinance, your interest rate didn’t change — yet boom, there it is: a $100–$300 (or sometimes more) increase that wasn’t exactly party-planned. Here’s the mess behind that surprise and how homeowners can actually navigate it with their sanity intact.

Escrow 101: Not Just Another Line Item

An escrow account isn’t some mysterious vault your lender squirreled away — it’s the financial bucket that collects a slice of your monthly mortgage payment to cover your property taxes and homeowners insurance. Lenders require this because they want to make sure those big bills get paid on time, even if you, the homeowner, sometimes forget to dust off that insurance renewal. Every year, your servicer performs what’s called an “escrow analysis” to see if the funds you’ve stuffed into the bucket match what actually came due. If your escrow bucket doesn’t have enough in it — that’s when the shortage alarm bell rings.

Even if your mortgage interest rate stays locked like a vault, this escrow portion can still swing wildly. That’s because it doesn’t hinge on the bank’s influence so much as real-world bills delivered by your local tax authority or insurance company. If those bills rise faster than the money going in, your payment balance gets blown out of proportion.

Why Shortages Show Up When You Least Expect Them

Most homeowners think escrow adjustments happen only if they miss a payment or forget to update their policy. That’s wrong. In reality, escrow shortages occur because the actual amounts owed for taxes and insurance outstrip the amounts your lender estimated when they set up your account. When that mismatch shows up during the annual review, it triggers a shortage.

Property taxes are one of the biggest culprits here. Local governments reassess values and change tax rates, often without warning. That $2.4K bill last year might become $3K this year, and that translates into a bigger escrow requirement. If the lender underestimated what taxes and insurance would cost — or if those costs sprinted ahead of projections — there simply isn’t enough in escrow to cover those bills, and you’ve got to make up the difference.

And let’s not forget homeowners insurance premiums. These have been on the rise across the country due to inflation, expensive catastrophic claims, and higher reconstruction costs. When your policy renewal rolls out at a higher rate than last year, your escrow contribution must follow suit — and that’s another payday for your lender and a headache for you.

The Sneaky Way Your Monthly Payment Climbs

Once your lender identifies a shortage, they don’t just want a check for the missing amount. They often give you two options: pay the whole balance up front or spread the shortage across your next 12 monthly mortgage payments. If you choose the second — which most people do because dumping a big lump sum isn’t exactly convenient — you’ll see your monthly payment go up by $100–$300 or sometimes far more.

That’s why so many homeowners with fixed-rate mortgages feel blindsided. You’re not actually paying higher interest; you’re just paying more into that escrow bucket to refill it and get it back on track.

How to Fight Back (Without Losing Sleep)

Nobody enjoys shelling out more money every month, but you do have options. First, you can try to pay the shortage in full upfront. Yes, that hits hard once, but it often means a smaller monthly payment going forward because you don’t have the shortage tacked onto your monthly costs over a year. That strategy doesn’t undo the higher tax or insurance rates, but it keeps you from paying that extra chunk on top of them.

Another strategy: talk to your lender about escrow projections before they lock them in. Some servicers offer mid-year reviews if you spot problematic increases early. Being proactive rather than reactive can reduce nasty surprises.
Escrow Shortages Are Adding $100–$300 to Monthly Mortgage Payments
Image source: shutterstock.com

Understanding Escrow Means Financial Power

Escrow isn’t a cosmic conspiracy. It’s a practical mechanism to make sure property taxes and insurance get paid on time. However, when the math behind it gets misaligned, it pushes your mortgage payment higher — and rapidly. The best weapon you have isn’t rage or despair; it’s clarity. Review your escrow statements, understand the underlying causes for increases, and take action earlier rather than later.

Escrow shortages are adding $100–$300 to monthly mortgage payments, but they don’t have to add panic to the equation. With awareness and a bit of planning, you can keep control of your financial ship even when escrow tides rise.

What’s the biggest surprise you have faced in your mortgage payment recently? Make sure you share your thoughts and pointers in the comments section below.

You May Also Like…

Florida Escrow Payments Continue Rising as Insurance Costs Climb

California Insurance Crisis: 13% of Home Sales Failed Due to No Coverage Available

The $2,000 Average National Homeowner Premium — Highest Share of Mortgage Payment Ever

The Texas Mortgage Shock: Why Your Monthly Payment Just Jumped $400 Without Warning

Why a Mortgage Protection Network Matters in Today’s Advice Market

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: escrow shortage, homeowners insurance, homeownership costs, housing market trends, Life, Lifestyle, monthly budget, mortgage escrow account, mortgage payments, Mortgage Tips, Planning, property taxes

Ground Ambulance Bills Still Fall Outside Federal Surprise Billing Protections

February 12, 2026 by Brandon Marcus 1 Comment

Ground Ambulance Bills Still Fall Outside Federal Surprise Billing Protections
Image source: shutterstock.com

Few things feel more universal than calling an ambulance in an emergency. It’s a moment driven by urgency, fear, and the basic human instinct to get help as fast as possible. Nobody pauses to ask about network status, billing codes, or insurance contracts while sirens are blaring and paramedics are doing their jobs. That’s why so many people are stunned later when a life-saving ride turns into a financial gut punch.

Even after sweeping federal reforms designed to protect patients from surprise medical bills, ground ambulance services are still largely excluded. That means a single ride to the hospital can still cost hundreds or even thousands of dollars, even for people who are insured and doing “everything right.”

The No Surprises Act: A Win With a Very Big Asterisk

The federal No Surprises Act, which took effect in 2022, was a landmark moment for healthcare consumers. It protects patients from surprise bills when they unknowingly receive out-of-network care in emergencies or at in-network hospitals. Air ambulances were included, which was a big deal, because those bills were notoriously massive and unpredictable.

But ground ambulances? They were left out. That omission wasn’t an accident—it was a political and logistical compromise. Ground ambulance services are often run by a complex mix of private companies, municipalities, fire departments, and local authorities. Regulating them under a single federal billing framework would require untangling a web of state laws, contracts, and funding models. So while patients gained protections in many areas of emergency care, the most common form of emergency transportation remained outside the shield.

Why Ground Ambulance Billing Is So Complicated

Ground ambulance services don’t operate like typical healthcare providers. Some are private companies. Others are city-run. Then others are tied to fire departments, while some rely on local taxes to survive.

This patchwork system means pricing, coverage, and billing rules vary wildly by location. One town may have regulated rates and consumer protections, while the next county over might have none. Insurance companies also often treat ambulance services differently from hospitals and physicians, sometimes paying limited amounts or classifying them as out-of-network by default.

The result is a system where the cost of a ride isn’t driven by patient choice or consumer behavior, but by geography, contracts, and local policy structures. From a patient perspective, that feels less like healthcare and more like a lottery.

What This Means for Patients in Real Life

For everyday people, this gap in protection creates a simple but painful reality: you can still be legally billed for out-of-network ground ambulance services, even in a true emergency. That includes balance billing in many states, where patients are charged the difference between what insurance pays and what the ambulance provider bills.

Some states have passed their own consumer protection laws that limit these charges, but coverage is uneven and inconsistent. Federal law doesn’t override those state systems when it comes to ground ambulances, so protections depend heavily on where you live. Two people in identical emergencies can have completely different financial outcomes based solely on their zip code.

Policy Is Catching On, But Slowly

The good news is that policymakers are aware of the problem. Federal advisory committees have studied ground ambulance billing, and multiple proposals have been discussed to bring these services under broader surprise billing protections. Some states are experimenting with rate-setting systems or dispute resolution models to control costs and limit patient exposure.

But healthcare reform moves slowly, especially when funding models are complex and local governments are involved. Ambulance services often argue, with some justification, that underpayment from insurers and public programs forces them to bill patients directly to survive. Policymakers, meanwhile, are trying to balance financial sustainability with consumer protection.

Ground Ambulance Bills Still Fall Outside Federal Surprise Billing Protections
Image source: shutterstock.com


How To Protect Yourself (As Much As Possible)

There’s no perfect shield, but there are smarter ways to navigate the system. Checking your insurance policy for ambulance coverage details is a good starting point, even if it’s not thrilling reading material. Some plans have specific limits, copays, or reimbursement caps that matter more than people realize.

If you receive a large ambulance bill, don’t assume it’s final. Ask for an itemized statement. Contact your insurer. Ask about appeals and dispute processes. In some cases, bills can be reduced, negotiated, or reprocessed under different coverage rules. It’s not glamorous, but persistence matters.

What Actually Matters

Ground ambulance bills still falling outside federal surprise billing protections isn’t just a policy flaw—it’s a real-world financial risk that affects ordinary people in vulnerable moments. The system currently prioritizes structural complexity over patient clarity, leaving consumers exposed in situations where they have zero control and zero choice.

What do you think—should ground ambulance services be included in federal surprise billing protections, and how would you change the system if you could? Talk about it in our comments section below.

You May Also Like…

Expense Spike: 8 Healthcare Costs That Hit Harder in Later Life

Why Do Medical Bills Feel So Hard to Plan Around

The Medical Bill Mistake That Can Cripple Your Credit for a Decade

8 Shocking Costs of Ignoring Small Medical Bills

7 Outrageous Truths About Medical Debt

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: Consumer Protection, emergency services, ground ambulance, healthcare costs, healthcare policy, insurance gaps, Life, Lifestyle, medical billing, medical debt, No Surprises Act, out-of-network billing, patient rights, surprise billing

9 Everyday Costs Rising Faster Than Seniors’ Income

February 11, 2026 by Brandon Marcus Leave a Comment

These Are 9 Everyday Costs Rising Faster Than Seniors’ Income
Image source: shutterstock.com

Retirement is supposed to feel like a long exhale after decades of working, saving, and juggling responsibilities. Yet for many older adults, that peaceful chapter is being interrupted by a financial reality that feels more like a slow tightening of the belt. Prices keep climbing, but income—especially for those relying on Social Security—just isn’t keeping pace.

And while everyone feels the pinch of inflation, seniors often feel it more sharply because their budgets don’t have the same flexibility they once did.

1. The Grocery Bill That Just Won’t Sit Still

Food prices have been one of the most persistent sources of frustration for retirees. Even though inflation has cooled from its peak, grocery costs remain significantly higher than they were just a few years ago. Essentials like bread, eggs, produce, and meat have seen some of the steepest increases, and those jumps add up quickly when you’re shopping on a fixed income. Seniors who cook at home to save money are discovering that even the basics stretch their budget more than they used to.

It’s worth exploring store brands, loyalty programs, and weekly sales—not because it’s fun, but because it genuinely helps keep spending under control.

2. Healthcare Costs That Keep Climbing

Healthcare is one of the biggest expenses in retirement, and unfortunately, it’s also one of the fastest‑growing. Premiums, deductibles, prescription drugs, and out‑of‑pocket costs have all trended upward. Even with Medicare, many seniors find themselves paying more each year for the same treatments and medications. This is especially challenging for retirees managing chronic conditions, who can’t simply “cut back” on care.

Staying proactive with preventive appointments, reviewing Medicare plans annually, and asking providers about lower‑cost alternatives can help soften the blow.

3. Housing Expenses That Refuse to Level Off

Even if a mortgage is paid off, housing costs don’t disappear. Property taxes, homeowners insurance, utilities, and maintenance have all risen sharply. Renters face even steeper challenges, with rental prices in many areas increasing faster than Social Security’s annual cost‑of‑living adjustments.

Downsizing or relocating can help, but those are big decisions that require time, planning, and emotional readiness. For homeowners, energy‑efficient upgrades and regular maintenance can prevent small issues from becoming expensive emergencies.

4. Utility Bills That Seem to Have a Mind of Their Own

Electricity, natural gas, water, and internet costs have all crept upward, and seniors feel the impact every month. Extreme weather patterns have also pushed energy usage higher in many regions, making bills even more unpredictable. While you can’t control the weather or utility rates, you can take steps to reduce consumption.

Simple changes—like sealing drafts, adjusting thermostats, or switching to LED bulbs—can make a noticeable difference over time. Many utility companies also offer senior discounts or budget billing programs worth exploring.

5. Transportation Costs That Keep Rolling Higher

Even if you’re not commuting to work anymore, transportation remains a major expense. Gas prices fluctuate constantly, and repairs and maintenance have become more expensive due to rising labor and parts costs. For seniors who rely on their vehicles for independence, these increases can be especially frustrating.

Public transit, senior ride programs, or carpooling with friends can help reduce costs without sacrificing mobility. If driving less is an option, it can also extend the life of your vehicle and lower insurance premiums.

These Are 9 Everyday Costs Rising Faster Than Seniors’ Income
Image source: shutterstock.com

6. Insurance Premiums That Quietly Increase

Insurance rarely gets cheaper with age. Homeowners insurance, auto insurance, and supplemental health insurance have all seen steady increases. Insurers cite everything from rising repair costs to more frequent severe weather events as reasons for higher premiums.

While you can’t control those factors, you can shop around, bundle policies, or raise deductibles to find savings. It’s also smart to review coverage annually to make sure you’re not paying for protections you no longer need.

7. Dining Out That Costs More Than Ever

Eating out has become noticeably more expensive, even at casual restaurants. Menu prices have risen due to higher labor and ingredient costs, and many seniors who enjoy the occasional meal out are feeling the difference. While dining out is still a great way to socialize and treat yourself, it may require a bit more planning.

Choosing lunch instead of dinner, sharing dishes, or taking advantage of weekday specials can help keep the experience enjoyable without straining your budget.

8. Personal Care Items That Add Up Quickly

Toiletries, cleaning supplies, and household essentials have all increased in price, often without much warning. These aren’t glamorous purchases, but they’re necessary, and the rising costs can catch retirees off guard.

Buying in bulk, using coupons, or switching to more affordable brands can help stretch your dollars further. It’s also worth keeping an eye on sales cycles—many stores discount these items at predictable times throughout the year.

9. Entertainment Costs That Aren’t So Entertaining Anymore

Streaming services, movie tickets, hobbies, and recreational activities have all become more expensive. Even small increases can add up when you’re juggling multiple subscriptions or outings.

Entertainment is an important part of a fulfilling retirement, so cutting it entirely isn’t the goal. Instead, consider rotating streaming services, taking advantage of senior discounts, or exploring free community events. You can still enjoy your favorite activities without overspending.

What This All Means for Today’s Retirees

The rising cost of everyday living is reshaping what retirement looks like for many seniors. While you can’t control inflation, you can take steps to stay informed, adjust your spending, and make choices that protect your financial stability.

Awareness is the first step toward empowerment, and small changes can add up to meaningful relief over time. Retirement should feel rewarding, not stressful, and understanding these trends helps you stay in control of your future.

What rising costs have you noticed the most in your own life? How are you looking out for the seniors in your life? Tell us about it in the comments section below.

You May Also Like…

The Retirement Income Assumption That Breaks Down First During Inflation Cycles

Why Fixed Income Doesn’t Feel Fixed Anymore for Retirees in 2026

Why More Retirees Are Being Flagged for “Excess Assets” by Benefit Programs

The Surprising Way Virtual Reality Is Bringing New Connections to Seniors in Their 60s

Why Financial Stress Feels Worse After Retirement Instead of Better

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: budgeting, Cost of living, fixed income, Income, Inflation, Life, Lifestyle, Personal Finance, Retirement, retirement planning, rising prices, senior lifestyle, seniors, Social Security

Repayment Assistance Plan Launches July 2026: New Income-Based Option for Borrowers

February 10, 2026 by Brandon Marcus Leave a Comment

Repayment Assistance Plan Launches July 2026: New Income-Based Option for Borrowers
Image source: shutterstock.com

Every once in a while, a policy change comes along that feels like someone finally noticed how complicated and stressful loan repayment can be. The Repayment Assistance Plan launching in July 2026 is one of those rare moments. It’s designed to give borrowers a clearer path forward, especially those whose payments feel like they’re competing with rent, groceries, and every other part of modern life that insists on being expensive.

Instead of relying on rigid payment structures, this new option adjusts what you owe based on your income, which means your monthly bill becomes something you can actually plan around. For anyone who’s ever stared at a loan statement and wondered how they’re supposed to make everything work, this plan could be a welcome shift toward stability.

A Fresh Take on Income-Based Repayment

Income-based repayment isn’t new, but the version arriving in 2026 aims to simplify the experience for borrowers who’ve struggled with confusing rules and inconsistent calculations. This plan ties your monthly payment directly to your income, creating a structure that adjusts as your financial situation changes.

Instead of feeling locked into a number that no longer fits your life, you’ll have a payment that moves with you. The goal is to make repayment more predictable and less overwhelming, especially for borrowers whose income fluctuates. If you’ve ever felt like your loan payment was designed without any awareness of your actual budget, this new approach may feel like a breath of fresh air.

Why July 2026 Matters for Borrowers

The launch date isn’t just a bureaucratic milestone—it gives borrowers time to prepare, compare options, and understand how this plan fits into their long-term financial goals. Many people rush into repayment choices without fully understanding how they’ll affect their budget years down the line.

With a clear timeline, borrowers can review their current repayment plan, estimate how their payments might change, and decide whether switching makes sense. It also gives financial counselors, loan servicers, and employers time to update their systems and provide accurate guidance. If you want to make the most informed decision possible, now is the perfect time to start gathering information.

How Payments Will Be Calculated Under the New Plan

One of the most important features of this plan is how it determines your monthly payment. Instead of using a one-size-fits-all formula, the calculation is based on your income. This means that if your income drops, your payment can adjust accordingly. What a relief.

The plan is designed to prevent borrowers from being overwhelmed by payments that no longer match their financial reality. It also encourages people to stay engaged with their loan servicer, since updating your information ensures your payment stays accurate.

Who Stands to Benefit the Most

While the plan is open to a wide range of borrowers, it’s especially helpful for people whose income doesn’t follow a predictable pattern. Young freelancers, gig workers, early-career professionals, and anyone navigating a major life transition may find that this plan offers more flexibility than traditional repayment options.

It’s also beneficial for borrowers carrying high balances relative to their income. The payment cap prevents monthly bills from becoming unmanageable. Even those who are currently comfortable with their payments may want to compare the long-term benefits. The key is understanding how the plan aligns with your goals, both now and in the future.

What Borrowers Should Do Before Enrollment Opens

Even though the plan doesn’t launch until July 2026, there’s plenty you can do now to prepare. Start by reviewing your current repayment plan. Check whether your income has changed since you last updated your information.

It’s also helpful to estimate what your payment might look like under an income-based structure. This can give you a clearer sense of whether switching makes sense. Borrowers should also keep an eye on official updates, since details about enrollment and eligibility may evolve as the launch date approaches.

Repayment Assistance Plan Launches July 2026: New Income-Based Option for Borrowers
Image source: shutterstock.com

How This Plan Fits Into the Bigger Picture of Borrower Relief

The Repayment Assistance Plan is part of a broader effort to make student loan repayment more manageable and more responsive to real-life financial challenges. Over the past several years, policymakers have focused on creating systems that reduce confusion. They have also worked to prevent delinquency and help borrowers stay on track.

This new plan reflects that shift by offering a structure that adapts to your circumstances rather than expecting you to adapt to it. While it won’t erase your balance or eliminate the need for careful budgeting, it does offer a more realistic path forward. For many borrowers, that alone can make a meaningful difference.

Moving Toward a More Manageable Future

The arrival of this plan signals a shift toward repayment options that feel more humane and more aligned with the financial realities people face today. By giving borrowers a payment structure that adjusts with them, the plan offers a sense of stability that’s been missing from the system for far too long. If you’re looking for a repayment option that feels like it was designed with real people in mind, this one is worth keeping on your radar.

What part of this upcoming repayment plan are you most curious about? Is it something you’re excited to try? Give us your thoughts in the comments.

You May Also Like…

The Student Loan Servicer Transfer That “Lost” Payments and Triggered Defaults

Student Loans Forgiven Are Now Taxable In 2026 — Set Money Aside for Tax Bills

Student Loan Interest Resumed August 2025 — Costing SAVE Borrowers $300/Month

The Income-Driven Repayment Plans That End July 1, 2028 Under New Law

Student Loan Default Crisis: Millions Of Borrowers Are Now Delinquent or in Default

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Lifestyle Tagged With: borrower relief, budgeting, debt planning, education costs, financial aid, income-based repayment, Life, Lifestyle, loan management, Personal Finance, repayment assistance, repayment options, student loans

Student Loan Interest Resumed August 2025 — Costing SAVE Borrowers $300/Month

February 4, 2026 by Brandon Marcus Leave a Comment

Student Loan Interest Resumed August 2025 — Costing SAVE Borrowers $300/Month
Image source: shutterstock.com

Imagine waking up to find that the student debt monster you thought was sleeping has started to stretch, yawn, and gobble up your financial future one dollar at a time.

That’s exactly what happened in August 2025 when interest resumed on federal student loans under the Saving on a Valuable Education (SAVE) plan — a move that could tack on roughly $300 or more to the monthly cost for millions of borrowers who had grown used to a 0% interest break.

This isn’t just a financial blip; it’s a shift that demands attention, strategy, and action if you want to keep your debt from snowballing out of control.

What Exactly Changed on August 1, 2025?

For quite a while, borrowers enrolled in the SAVE plan — an income-driven repayment program designed to make monthly payments more affordable — enjoyed a rare thing in the world of student loans: no interest while on administrative forbearance.

But on August 1, 2025, that interest pause ended, and interest began accruing on loan balances once again. No, you didn’t imagine it: the monster did wake up, and it woke up hungry for your money.

Your balance is quietly growing every single day. Interest isn’t retroactive, thankfully. However, going forward, it sticks to your principal like gum on a shoe. That means more to pay down later.

Why This Matters: The $300 Monthly Impact

Let’s talk numbers. Analysts estimate that the typical borrower under SAVE could see about $300 more in monthly costs as interest accrues on their loans. That’s a big chunk of change you might not have planned for. Over a year, that’s roughly $3,500 in added interest charges before you even pay a penny of principal. Suddenly that “manageable” debt feels a lot heavier.

Interest is compounding — which, in debt terms, is about as friendly as a porcupine in your backpack. Every dollar in interest that isn’t paid gets added to your principal balance, and then interest starts charging interest on that too. That can put you on a treadmill where the total amount you owe keeps creeping up even if you’re doing everything else right.

What This Means for Your Loan Balance (Spoiler: It Grows)

If your loan was enjoying the bliss of 0% interest forbearance, here’s the harsh reality: that party is officially over.

Beginning August 1, interest accrues daily on your outstanding principal, and the clock won’t stop.  Right now, borrowers are functionally in forbearance, not active repayment, meaning the usual SAVE benefits aren’t in play. So the interest you accrue now becomes interest you owe. In other words, it’s time to start paying because your financial situation will only get worse.

Options to Escape the Interest Boom (Yes, You Still Have Them)

All is not lost. You have choices that can help you manage this shift instead of letting it bury you.

Switch to another income-driven repayment plan like IBR or the upcoming Repayment Assistance Plan (RAP) to restart qualifying payments and avoid growing debt without direction. These plans calculate payments based on income and family size, though they might result in higher monthly amounts than you’re used to under SAVE.

Or you can pay the accruing interest now to prevent your balance from ballooning. This can be emotionally tough but financially smart.

Each option comes with tradeoffs — but taking no action is probably the most expensive one. So don’t wait until your balance feels unrecognizable.

Student Loan Interest Resumed August 2025 — Costing SAVE Borrowers $300/Month
Image source: shutterstock.com

Interest Isn’t Waiting — And Neither Should You

Interest resuming on SAVE loans isn’t just a footnote in the news — it’s a financial shift that could add roughly $300 (or more!) to what you need to solve each month. Whether you decide to switch repayment plans, make interest payments now, or tackle principal the moment you can, having a plan beats watching your balance balloon.

Ready to talk strategy? What’s your biggest worry about the return of interest — the growing balance, future payment amounts, or something completely different? Share your thoughts in the comments.

You May Also Like…

7 Million Student Loan Borrowers Must Switch Plans as SAVE Program Ends

The SAVE Plan Settlement: Why Pending Applications Were Just Denied

Student Loan Default Crisis: Millions Of Borrowers Are Now Delinquent or in Default

9 Outrageous Truths About Student Loan Interest

Could Student Loan Forgiveness End Up Costing Borrowers More Later?

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: Debt Management, Education, Education Department, federal aid, income‑driven repayment, interest accrual, Life, Lifestyle, loan forgiveness, loan repayment, monthly payments, Personal Finance, Planning, SAVE Plan, student loans

6 Benefit Changes Taking Effect in 2026 That Reduce Monthly Support

February 4, 2026 by Brandon Marcus Leave a Comment

These Are 6 Benefit Changes Taking Effect in 2026 That Reduce Monthly Support
Image source: shutterstock.com

Imagine waking up, checking your bank account, and wondering why that familiar support check doesn’t stretch as far as it used to. If you’re someone who relies on government benefits—whether Social Security retirement income, food support, disability payments, or healthcare subsidies—some big changes are coming that could quietly nibble away at your monthly support.

This news isn’t meant to scare you, it’s meant to help prepare you. Keep reading for important information you’ll want to know, with a dash of clarity and yes, a little storytelling flare.

1. Social Security’s Cost-of-Living Adjustment Isn’t Enough After Medicare Premiums Bite Back

Each year, the Social Security Administration adjusts benefits to keep up with inflation, and in 2026 that adjustment—the so-called cost-of-living adjustment (COLA)—comes in at 2.8%. On paper, that sounds like a win, bumping the average monthly check up by roughly $56. But Medicare Part B premiums are rising sharply in 2026, around 10% to roughly $202.90 per month, and that increase is automatically deducted from Social Security checks for most beneficiaries.

So instead of feeling richer with that COLA bump, many folks end up with a net increase far smaller than expected—or in some cases, almost no extra spending money at all once healthcare costs are taken out. This is one of those changes where the numbers look good until you read the fine print and realize your actual take-home support is being squeezed.

2. SNAP Work Requirements Expand, Cutting Off Support for Many

Food assistance via the Supplemental Nutrition Assistance Program (SNAP) is a lifeline for millions of households. But in 2026, expanded work requirements are rolling out in more states, meaning that able-bodied adults without dependents must work, volunteer, or train for at least 80 hours per month to keep their benefits.

What does this mean in real life? If you live in a state that implements these rules and don’t meet the work or training requirements, your monthly SNAP support could dry up—even if you struggle with transportation, caregiving, health issues, or local job availability.

3. Earnings Limits That Can Reduce Social Security Checks Are Increasing—but Still Bite

If you’re claiming Social Security early and continue to work, the government uses an earnings test that can withhold part of your monthly benefit if your income exceeds certain limits. In 2026, these limits rise but the basic rule stays the same: earn too much and part of your check gets clipped.

That sounds straightforward but remember this isn’t a temporary freeze. Benefits withheld under the earnings test might be added back later, but short-term reductions in monthly support can still bite your everyday budget, especially if you count on that monthly check for current living costs.

4. Medicare Part B Premium Hikes Eat Into Your Disposable Dollars

Yes, we mentioned Medicare Part B earlier in relation to the COLA—because it’s hard to overstate how big a deal this is. In 2026, Part B premiums jump to their highest level yet, and for many people, that means a bigger automatic deduction from your monthly Social Security benefit.

For individuals with higher incomes, this surcharge can be even steeper thanks to the Income-Related Monthly Adjustment Amount (IRMAA), meaning the more you make, the more you could lose in support each month. It’s one thing to get a bigger sticker price on your Medicare card—another to see it reflected in less cash in your pocket.

These Are 6 Benefit Changes Taking Effect in 2026 That Reduce Monthly Support
Image source: shutterstock.com

5. Higher Income Could Mean Less Benefit Through Medicare Surcharges

Speaking of income: depending on what you earn, your Medicare premium could spike even more due to income-related adjustments, which then further reduces your monthly support. This isn’t a flat fee; it’s tied to your reported income from previous years, so smart tax planning and budgeting in advance could make a difference in what you net each month.

This kind of change doesn’t always get front-page attention, but it’s very real for the folks who suddenly find their benefit checks trimmed because their income nudged them into a higher premium bracket.

6. SSI and Related Monthly Support Face Stricter Income/Asset Rules

Supplemental Security Income (SSI) and similar need-based monthly supports already have strict income and asset limits. While COLA changes technically increase payments for SSI recipients, deductions like rising healthcare premiums or asset reclassification rules can offset any nominal increase, effectively reducing the support that shows up in your checking account.

Those on SSI still benefit from a COLA adjustment, but many people on tight budgets find that higher living costs fight right back against any nominal benefit increase, leaving them feeling like they have less breathing room each month.

What to Watch (and What You Can Do)

If you or someone you love relies on monthly support, 2026 is a year to be proactive. Review eligibility rules early, track your earnings if you work while collecting benefits, and pay attention to healthcare premium notices in the fall.

The good news? Knowledge is power: understanding how these changes interact—especially the pesky policy details—can help you preserve your support as much as possible.

Now we want to hear from you: Which of these 2026 benefit changes will affect your monthly support the most—and what are you doing to prepare? Share your experience or strategy in the comments section.

You May Also Like…

Charity Strategy: 9 Giving Moves That Bring Tax Benefits Many People Ignore

Is Your Social Security Spousal Benefit Getting Slashed Without You Realizing?

The Medicare Part B Increase That’s Reducing Social Security Checks By About $185/Month in 2026

The COLA Theft: Why Half of Your Social Security Raise Just Vanished into Medicare This Morning

8 Disqualifications That Keep Veterans From Getting the Benefits They Earned

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Lifestyle Tagged With: 2026 benefits, benefit cuts, benefits, cost-of-living adjustment, earnings limits, government policy, Life, Lifestyle, Medicare Part B increase, retirement income, SNAP work requirements, Social Security changes 2026, SSI changes

7 Million Student Loan Borrowers Must Switch Plans as SAVE Program Ends

February 3, 2026 by Brandon Marcus Leave a Comment

7 Million Student Loan Borrowers Must Switch Plans as SAVE Program Ends
Image source: shutterstock.com

So, you’ve been cruising through your student loan repayment journey on the SAVE plan — the cushy, income-driven setup that kept your payments low and forgiveness goals in sight. Then reality hits. That safety net is being pulled away, and up to 7 million borrowers are suddenly on the clock to change course before the financial ground shifts beneath their feet.

If that sounds like a plot twist you didn’t sign up for, you’re not alone. But don’t panic. This moment doesn’t have to mean chaos — it can mean clarity, strategy, and smarter choices if you understand what’s happening and act intentionally. Whether you’re fresh out of school, deep into repayment, or counting the months toward forgiveness, the end of the SAVE program is something you need to understand — and prepare for.

Why the SAVE Plan Is Ending — And What That Really Means

The SAVE (Saving on a Valuable Education) plan quickly became a favorite for borrowers. It lowered monthly payments based on income and created a smoother path toward loan forgiveness. For many people, it wasn’t just a repayment plan — it was financial breathing room. But legal challenges and court rulings have changed its future. A proposed settlement involving the U.S. Department of Education is set to formally end the program, block new enrollments, deny pending applications, and transition current borrowers into other repayment options.

For millions of people, this isn’t just a bureaucratic change — it’s a shift in financial reality. The plan you assumed you’d be on for years may no longer exist at all.

Where You Can Move Your Loans Next

Here’s the good news: the end of SAVE doesn’t mean you’re out of options. Federal borrowers still have access to other income-driven repayment plans. A new option called the Repayment Assistance Plan (RAP) is expected to launch in 2026 and will eventually replace several existing plans.

But this is where strategy matters. Not all repayment plans are created equal. Some plans keep payments low but extend repayment timelines. Others shorten timelines but raise monthly costs. And if you do nothing, there’s a real chance you could be moved into a standard repayment plan that doesn’t adjust for income.

The biggest mistake borrowers can make right now is assuming the system will automatically move them into the best option for their situation. It won’t. If you want affordability, forgiveness eligibility, and long-term flexibility, you’ll need to make that choice intentionally.

When You’ll Need to Act (And Why Waiting Could Cost You)

One of the most stressful parts of this transition is the uncertainty around timing. While the settlement still requires court approval, the Department of Education has already made it clear that SAVE is on its way out. Most borrowers will be notified with instructions in the coming months. Most projections point toward early to mid-2026 as the period when large-scale transitions will occur, especially as new repayment systems begin rolling out.

Waiting comes with risks. Interest has already resumed on many loans that were placed into administrative forbearance, meaning balances can grow even while borrowers aren’t making payments. At the same time, loan servicers are facing the reality of processing millions of plan changes. Experts have warned that if too many borrowers wait until the last minute, application backlogs could stretch for months — or even years.

This creates a dangerous combination of rising balances, delayed processing, and financial uncertainty. Acting earlier doesn’t just give you peace of mind — it gives you leverage, flexibility, and options when the system becomes overwhelmed.

What You Should Do Next

The smartest thing you can do right now is get informed and proactive. Log into your Federal Student Aid account and confirm your current loan status, repayment plan, and whether you’re in forbearance or active repayment. Use the federal loan simulator tools to compare how different repayment plans would affect your monthly payments, total interest, and forgiveness timelines.

If your priority is affordability and long-term forgiveness, switching to a qualifying income-driven repayment plan sooner rather than later may protect you from payment shocks and processing delays. Waiting until changes are forced on you increases the risk of mistakes, delays, and lost progress.

Most importantly, don’t treat this as a passive change. This is one of those moments where being proactive can literally save you thousands of dollars over the life of your loans.

7 Million Student Loan Borrowers Must Switch Plans as SAVE Program Ends
Image source: shutterstock.com

This Shift Is Inevitable — But Financial Chaos Isn’t

The end of the SAVE program isn’t just a policy update — it’s a turning point for millions of borrowers. But it doesn’t have to be a financial disaster. With the right information, the right timing, and the right strategy, this transition can become an opportunity to reset your repayment path in a way that actually works for your life, your income, and your future goals.

The system is changing whether we like it or not. But how it affects you is something you still have control over.

So what’s your plan? Wait it out and hope for the best, or take the reins and choose your next move on your terms? Share your thoughts, concerns, and strategies in the comments because your story might help someone else navigate this change too.

You May Also Like…

The SAVE Plan Settlement: Why Pending Applications Were Just Denied

The Estate Planning Shortcut That Saves Time but Costs Families More in the Long Run

Student Loan Wage Garnishment Could Return After 5-Year Pause — 15% of Paychecks at Risk

Will I Ever Be Able to Afford a House With My Current Student Loan Burden?

9 Outrageous Truths About Student Loan Interest

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: borrower tips, federal loans, IBR, income‑driven repayment, Life, Lifestyle, loan forgiveness, RAP, repayment plans, SAVE Plan, SAVE program ending, student debt, student loans, U.S. Department of Education

Student Loan Default Crisis: Millions Of Borrowers Are Now Delinquent or in Default

February 2, 2026 by Brandon Marcus Leave a Comment

Student Loan Default Crisis: Millions Of Borrowers Are Now Delinquent or in Default
Image source: shutterstock.com

The student loan system in the U.S. isn’t just strained — it’s buckling under the weight of a repayment restart that collided with the most expensive cost‑of‑living environment in a generation. Millions of borrowers are now behind on payments, and a rapidly growing share are slipping into delinquency or edging dangerously close to default.

For many people, student debt no longer feels like a manageable monthly bill; it feels like a financial shadow that follows every job change, rent increase, and grocery run. This crisis isn’t just about money — it’s about stress, stalled life plans, delayed homeownership, and mental exhaustion.

When the Payment Pause Ended, Budgets Snapped

The pandemic‑era payment pause offered temporary relief, but it also reshaped budgets in ways no one fully anticipated. For more than three years, millions of borrowers lived without student loan payments and built entire financial lives around that reality. When payments resumed, they collided with higher rent, higher food costs, and higher everything else. Wages didn’t keep up. Savings were thin.

Suddenly, hundreds of dollars in new monthly obligations felt impossible to absorb. For borrowers already living paycheck to paycheck, the restart didn’t feel like a return to normal — it felt like a financial ambush.

Today, it is estimated that about 5.3 million borrowers are in default, while another 4.3 million are in “late stage delinquency.” The number is already high, but it is only growing as this quiet plague sweeps across America. Millions of borrowers are already in default, and millions more are in late‑stage delinquency.

Delinquency Is Quiet — And That’s What Makes It Dangerous

Delinquency doesn’t announce itself. Miss one payment and nothing dramatic happens. No alarms. No flashing warnings. Life keeps moving. But behind the scenes, interest keeps growing, credit scores start slipping, stress compounds, and options shrink.

Many borrowers fall behind not because they’re careless, but because the system is confusing, servicers make mistakes, and repayment options feel overwhelming. A missed notice or a misunderstood plan can snowball into months of delinquency before someone even realizes what’s happening. Checking your loan status regularly and setting up alerts can stop a small slip from becoming a long‑term setback.

Default Isn’t Just a Financial Event — It’s a Life Event

Default reshapes a person’s financial life in ways most people don’t understand until it hits. Wage garnishment, tax refund seizure, damaged credit, blocked access to housing or car loans, and even lost eligibility for certain jobs or security clearances all become real consequences.

And then there’s the emotional toll of student loan debt and missing payments.  Shame, fear, avoidance, and the feeling of being trapped all pile up. Default also limits access to repayment plans and forgiveness programs that could otherwise help. If you’re nearing default, reaching out to your servicer early isn’t weakness — it’s self‑preservation.

Income‑Driven Repayment Isn’t Perfect — But It’s a Lifeline

Income‑driven repayment (or IDR) plans get a bad reputation for being confusing, but for millions of borrowers, they’re the difference between staying afloat and drowning. These plans adjust payments based on income and family size, making them more realistic for people with unstable or lower earnings.

Student Loan Default Crisis: Millions Of Borrowers Are Now Delinquent or in Default
Image source: shutterstock.com

Interest may still accrue, and the paperwork can be frustrating, but staying in good standing protects your credit and keeps you eligible for future relief. If your payments feel impossible, exploring IDR is one of the smartest moves you can make.

The System Was Built for an Economy That No Longer Exists

Student loan repayment was designed decades ago for a world with lower housing costs, lower healthcare costs, stable career paths, and predictable wages. Today’s economy looks nothing like that world. Gig work, contract jobs, layoffs, and unpredictable income make fixed payments harder than ever.

Meanwhile, the cost of living keeps rising. The result isn’t just debt — it’s financial suffocation for millions. This crisis isn’t about irresponsibility. It’s about a system that hasn’t kept up with reality.

The Psychological Weight No One Talks About Enough

Student loan debt doesn’t just drain bank accounts — it drains emotional energy. Borrowers carry shame, anxiety, guilt, and fear of the future. People delay marriage, children, homeownership, career changes, and entrepreneurship because debt feels like an anchor. Silence makes it worse. Talking about it openly and honestly is an act of resilience.

Smart Moves That Actually Help Right Now

You don’t need a miracle. You need momentum. Small, strategic actions matter. For example, setting up autopay prevents accidental delinquency. Also, updating your income ensures your payments reflect your real situation. Keeping copies of all communications protects you from administrative errors. Exploring consolidation, deferment, or forbearance can buy time during financial crises.

Most importantly, staying engaged with your loans keeps you in control instead of reacting to emergencies. Progress doesn’t come from perfect decisions — it comes from consistent, informed ones.

Why This Moment Matters More Than Ever

This isn’t just a spike in missed payments — it’s a turning point. How borrowers respond now will shape their financial futures for decades. Ignoring the problem deepens the damage. Facing it creates options. The crisis may feel overwhelming, but it also creates a moment for change, education, and smarter systems. Financial freedom doesn’t start with paying everything off. It starts with understanding, strategy, and action. The earlier it begins, the more control you regain.

Do you have anything to add to this story? Tell us about your student loan debt repayment woes and successes in the comments below.

You May Also Like…

Will I Ever Be Able to Afford a House With My Current Student Loan Burden?

9 Outrageous Truths About Student Loan Interest

6 Hidden Dangers of Taking Out Student Loans Too Young

5 Reasons You Should Never Co-Sign a Loan (Not Even for Family)

Should Financial Education Be Required Before You Can Get a Credit Card?

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: debt relief, federal loans, financial stress, Higher education, income‑driven repayment, Life, Lifestyle, loan default, loans, Personal Finance, student debt crisis, student loans, young adults

The SAVE Plan Settlement: Why Pending Applications Were Just Denied

February 2, 2026 by Brandon Marcus Leave a Comment

The SAVE Plan Settlement: Why Pending Applications Were Just Denied
Image source: shutterstock.com

If you applied for the federal SAVE Plan and feel like you’ve been stuck in limbo, you’re not imagining it. Millions of borrowers are navigating a repayment system that’s been challenged in court and reinterpreted more times than anyone can count.

What was supposed to be the most affordable income‑driven repayment plan in history has instead turned into a maze of political fights, legal uncertainty, and inconsistent communication. And now, unfortunately, it’s coming to an end. This leaves borrowers with frustration—but a choice about moving forward.

For borrowers who were counting on SAVE to stabilize their budgets, the last year hasn’t felt like relief. It’s felt like whiplash.

What the SAVE Plan Was Designed to Do — And Why Borrowers Flocked to It

The SAVE Plan — Saving on a Valuable Education — was meant to replace REPAYE and become the new standard for income‑driven repayment. It promised lower monthly payments, interest protections that prevented balances from ballooning, and shorter forgiveness timelines for borrowers with smaller balances. The program was very popular, and millions enrolled quickly, hoping to finally get a repayment plan that matched their income instead of crushing it.

Then, due to lawsuits with multiple states, the Department of Education announced a proposed end to SAVE, pending court approval. Thankfully, borrowers already enrolled continue to receive the benefits that remain legally authorized, but those waiting for approval are out of luck.

Why Borrowers Are Seeing Mixed Messages

The SAVE Plan hasn’t been dismantled for those already approved, but it has been shut off to newcomers. For months, courts have questioned whether certain provisions exceed the Department of Education’s authority without congressional approval.

Due to a new settlement agreement, the Department of Education will not enroll any new borrowers in the SAVE plan and will deny any pending applicants. Those currently enrolled in the program will be moved to different repayment plans, although the timeline and mechanics of that are not yet finalized.

The Legal Fight That Put SAVE in Limbo

For many, this wasn’t a shock. The lawsuits challenging SAVE didn’t come out of nowhere. Several states argued that the Department of Education expanded repayment and forgiveness authority beyond what Congress explicitly allowed. Courts issued injunctions that paused certain features of SAVE while the cases moved forward. Then, in December of 2025, an official end to the program was announced.

Along the way, this legal uncertainty left borrowers caught between policy goals and legal boundaries. Everything was slowed and then halted. It wasn’t a paperwork issue. It was a structural one.

What Borrowers Should Expect in 2026

There are possibilities for those left behind by the end of SAVE. Borrowers can still choose from other repayment plans like IDR, which remain fully authorized under federal law. These plans calculate payments differently than SAVE, and they may result in higher monthly bills, but they offer stability.

The SAVE Plan Settlement: Why Pending Applications Were Just Denied
Image source: shutterstock.com

Borrowers who were counting on SAVE’s lowest‑payment features or fastest forgiveness timelines may need to adjust expectations, but they shouldn’t give up hope on a repayment plan that works for them.

What This Moment Really Means for Borrowers

The SAVE Plan is gone, but options remain. Sadly, borrowers are the ones feeling the strain. This change feels frustrating, but it doesn’t leave you powerless. Understanding what’s gone and what alternatives exist gives you the ability to make informed decisions instead of reacting to surprises.

The student‑loan system is changing again in 2026, but your strategy doesn’t have to fall apart with it. The more you understand your options, the more control you regain over your financial future.

Are you ready to choose the repayment plan that actually fits your life right now — or will you let the system choose for you? What will you do now that SAVE is gone? Share your stories and your challenges in the comments section below.

You May Also Like…

Student Loan Wage Garnishment Could Return After 5-Year Pause — 15% of Paychecks at Risk

Will I Ever Be Able to Afford a House With My Current Student Loan Burden?

8 Outrageous Truths About Student Loan Repayments

How Can Student Loans Quietly Shape Life Decisions for Decades

Why Are So Many Seniors Being Sued Over Student Loans They Didn’t Take Out?

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: borrowers, College, college costs, college education, Education, federal loans, financial advice, IDR plans, income‑driven repayment, Life, Lifestyle, repayment tips, SAVE Plan, student loan denial, student loan settlement, student loans, students

Why Major Insurers Are Quietly Canceling 2026 Policies Using Satellite Photos

February 1, 2026 by Brandon Marcus Leave a Comment

Why Major Insurers Are Quietly Canceling 2026 Policies Using Satellite Photos
Image source: shutterstock.com

One day, you may open your mailbox expecting junk mail and maybe a coupon for pizza, and instead find a crisp, official letter from your insurance company saying they’re ending your policy. No claim. No accident. Just a snapshot taken from space—or so they say.

It sounds like the setup to a pulp thriller where Big Brother has upgraded from street cameras to satellites, but this is the real world of home insurance in 2026. Nobody wants their roof to be judged by a fly‑over photo, yet that’s exactly the high‑tech twist unfolding in the market right now.

When Underwriting Goes Up… Literally

You might have heard insurance companies send inspectors for a property visit back in the day—someone with a clipboard driving up your driveway, taking pictures of the roof, the siding, and maybe complimenting your landscaping.

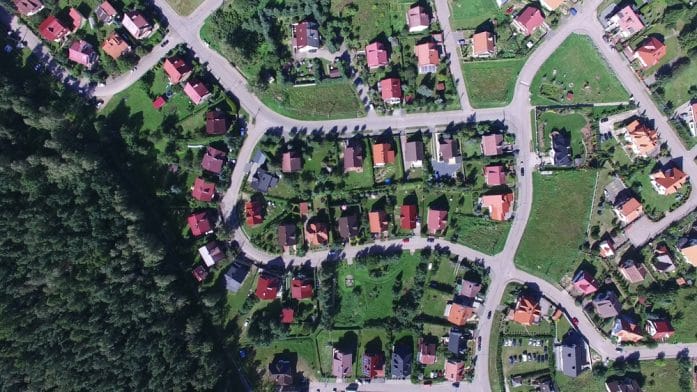
Well, those days are fading fast. Today, insurers are tapping aerial imagery sourced from satellites, drones, and AI‑analyzed photos to evaluate risk and make decisions about your policy without ever stepping foot on your lawn. It’s faster, cheaper, and increasingly common—but also controversial.

Instead of a local adjuster inspecting one house at a time, companies can scan thousands of rooftops in minutes. But like any technology, it has limitations—and that’s where things get messy for homeowners.

The “Satellite Snapshot” That Can Sink Your Policy

Companies are sometimes basing non‑renewals, cancellations, or rate hikes on what they see from above. If a roof looks discolored, shadows make it appear damaged, or nearby trees cast ominous silhouettes, algorithms might flag those as risk factors. In some cases, insurers have even issued letters demanding repairs based on these aerial images—or sent non‑renewal notices without any physical inspection.

To be clear, aerial imagery can be a valid tool for assessing property condition, and many insurers pair it with additional checks before making a final call. But rapid data processing and AI scoring systems have, in some instances, triggered policy actions before a human reviews the case—which leaves homeowners scrambling for answers.

Why Major Insurers Are Quietly Canceling 2026 Policies Using Satellite Photos
Image source: shutterstock.com

The Invisible Premium Pressure Pump

It’s not just about cancellations. Insurance costs have been climbing for years, and the trend is continuing into 2026. Some data suggests average policies are still rising significantly, putting pressure on homeowners’ wallets. While not every insurer is dropping policies en masse, this combination of rising costs and tighter underwriting can feel like a “trap” when you get hit with a surprise non‑renewal or hefty price jump at renewal time.

This pressure is partly driven by higher claim costs nationwide and the need for insurers to rebalance their portfolios. By focusing on micro‑risks at the ZIP‑code or even property level, companies are making decisions in what feels like hyper‑local detail—sometimes with minimal explanation.

What Rights You Have (And What You Don’t)

So what happens when you get one of these letters? First, it’s important to know that insurers can non‑renew policies at the end of a term for many reasons, but they usually give notice.

Some states and regulators have issued guidelines urging carriers to use aerial photos responsibly and to share them with policyholders, allowing homeowners to contest inaccuracies. These measures stem from documented cases where outdated or misleading images led to erroneous policy actions.

But for now, your rights vary depending on where you live, and many homeowners find themselves in unfamiliar territory when contesting a non‑renewal. That makes being proactive—and informed—all the more important.

How You Can Fight Back (And Stay Insured)

Don’t panic, but do pay attention. If you receive a non‑renewal or an unexpected rate hike, there’s a strategy that can help.

If your insurer used an aerial photo to make a decision, request to see it. Knowing the exact image and timestamp gives you a fighting chance to correct errors or explain changes. Many insurers will comply if asked—even if they aren’t required to.

Keep up‑to‑date photographs, repair receipts, and professional inspection reports. If an aerial image looks misleading, your own documentation can counter it. It’s like having your own high‑def rebuttal ready.

If you can’t convince one insurer to renew, start shopping for others before your policy expires. A gap in coverage can be costly and make future coverage harder to find.

Understanding the New High‑Tech Insurance Reality

Home insurance in 2026 isn’t your parents’ old policy anymore. With satellites, drones, and AI tightening the underwriting microscope, the industry has entered a new era where a pixel in the sky can influence your financial security. But armed with knowledge, documentation, and a proactive mindset, you don’t have to be at the mercy of unseen eyes.

What’s the craziest insurance letter you’ve ever received? Have you ever been hit with a non‑renewal or rate hike based on imagery you thought was unfair? Share your story below.

You May Also Like…

The Tax Document Most Homeowners Fail to Update That Triggers Surprise Liens

How to File an Insurance Claim After a Car Accident (Step-by-Step Guide to Maximizing Your Payout)

The Home Insurance Review Clause That’s Triggering Surprise Policy Cancellations in 2026

7 Fine-Print Exclusions in Your Homeowner’s Policy That Could Cost You Everything

The Florida Insurance Trap: Why “Safe” Neighborhoods Are Facing a $500 Monthly Payment Hike This Week

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: 2026 insurance trends, aerial imagery, Consumer Protection, drone inspections, Home, homeowner, homeowners, homeowners insurance, homeownership, homeownership tips, insurance premiums, Life, Lifestyle, policy cancellation, satellite photos, underwriting technology

  • « Previous Page
  • 1
  • 2
  • 3
  • 4
  • …
  • 11
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework