• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Brandon Marcus

The Hidden Cost of Keeping Money in Savings at 2.4% Inflation

March 4, 2026 by Brandon Marcus Leave a Comment

The Hidden Cost of Keeping Money in Savings at 2.4% Inflation
Image Source: Shutterstock.com

Money sitting in a savings account feels safe, responsible, even wise. But when inflation runs at 2.4%, that calm sense of security starts to crack. The numbers may look steady on a bank statement, yet the true value of that cash slowly erodes in the background. What looks like stability often hides a quiet loss of purchasing power, and that loss deserves serious attention.

Inflation at 2.4% might not spark headlines like the surges seen in 2022, when U.S. inflation climbed above 9% at its peak, but even modest inflation steadily chips away at cash reserves. The math never takes a day off. If a savings account earns less than the inflation rate, the real return turns negative. That gap between interest earned and prices rising creates a hidden cost that many people underestimate.

The Math That Changes Everything

Start with a simple example. A savings account offers 1% annual interest, while inflation holds at 2.4%. On paper, that account grows by 1%. In reality, purchasing power falls by roughly 1.4% over the same period. After one year, $10,000 grows to $10,100, but goods, services, and everyday groceries that cost $10,000 now cost $10,240. That difference may look small in year one, yet it compounds over time. That hidden cost can make all the difference for a struggling household.

Extend that scenario over five years, and the impact grows more noticeable. Inflation compounds just like interest does. A steady 2.4% annual inflation rate reduces the real value of money by more than 11% over five years. Without higher returns, savings lose ground every single year. This dynamic often surprises people because nominal balances increase. Bank statements show higher numbers, which creates a sense of progress. But real wealth depends on what money can buy, not what the account displays. When returns trail inflation, savers move backward even while numbers climb upward.
The Hidden Cost of Keeping Money in Savings at 2.4% Inflation
Image Source: Shutterstock.com

Safety Feels Good, But It Comes at a Price

Savings accounts serve an important role. They provide liquidity, stability, and peace of mind. Federal deposit insurance protects balances up to legal limits, which removes the fear of losing principal due to bank failure. That security matters, especially for emergency funds. However, safety carries a trade-off. Banks typically invest deposits in loans or securities and pay savers a portion of what they earn. When central banks set lower interest rates, savings yields often fall as well. Even when rates rise, many traditional savings accounts lag behind.

High-yield savings accounts sometimes offer rates closer to prevailing market levels, and in certain periods they even exceed inflation. But not all savers take advantage of those options. Many leave money in legacy accounts earning fractions of a percent. At a 2.4% inflation rate, any account earning less than that threshold guarantees a loss in real terms.

Inflation Does Not Ask for Permission

Inflation reflects the broad increase in prices across the economy. The U.S. Bureau of Labor Statistics tracks this through the Consumer Price Index, which measures changes in the cost of goods and services such as housing, food, transportation, and medical care. When that index rises 2.4% year over year, it signals that everyday expenses cost more than they did twelve months earlier.

Even modest inflation affects long-term goals. Consider someone planning to spend $40,000 per year in retirement. At 2.4% inflation, that spending level rises to roughly $51,000 in ten years. Anyone who ignores inflation when planning risks underestimating future needs.

Cash loses value because it does not grow on its own. It requires interest or investment returns to maintain purchasing power. Inflation never pauses simply because money sits in a bank account. It continues reshaping the economy, pushing prices upward in housing markets, grocery stores, and service industries.

The Opportunity Cost That Hurts Even More

Beyond the direct impact of inflation, another cost emerges: opportunity cost. Money sitting in low-yield savings does not participate in potential growth elsewhere. Over long periods, diversified stock market investments have historically delivered average annual returns above inflation, although they fluctuate and carry risk. Bonds, certificates of deposit, and Treasury securities can also offer higher yields than standard savings accounts, depending on the rate environment.

That does not mean every dollar should move into the stock market. Risk tolerance, time horizon, and financial goals all matter. However, parking large sums in cash for years without a clear purpose can stunt wealth building. For example, someone who keeps $50,000 in a savings account earning 1% while inflation runs at 2.4% effectively loses purchasing power every year. If that person invests a portion in a diversified portfolio aligned with long-term goals, the potential for growth increases. Over decades, the difference between earning 1% and earning 6% or 7% compounds dramatically.

Inflation Awareness Creates Financial Power

Understanding inflation shifts financial decision-making from reactive to proactive. Instead of focusing solely on nominal returns, attention shifts toward real returns, which subtract inflation from interest or investment gains. That mindset change transforms how savings strategies evolve. Inflation does not always remain at 2.4%. It can rise higher or fall lower depending on economic conditions, supply chains, labor markets, and monetary policy. Staying informed about trends helps shape better choices. When inflation rises, protecting purchasing power becomes even more urgent.

Tracking expenses also matters. If personal costs rise faster than the official inflation rate, the pressure intensifies. Housing, insurance, and healthcare often increase at different rates than the overall index. A realistic financial plan accounts for those variations.

What Should Your Money Be Doing Right Now?

Money should serve a purpose. Some dollars guard against emergencies. Some dollars wait patiently for near-term goals. Others need to grow aggressively to support decades of future spending. Allowing large balances to sit in low-yield savings while inflation runs at 2.4% means accepting a guaranteed loss in purchasing power. That choice may feel comfortable, yet comfort does not build wealth. Thoughtful allocation, periodic review, and alignment with clear goals create a stronger foundation.

Inflation will continue to influence every financial plan, whether acknowledged or ignored. Taking control starts with a simple step: compare current savings rates to the inflation rate and calculate the real return. If the result falls below zero, it may signal time for a strategic shift.

Does every one of your dollars currently sit where it can truly keep up with the rising cost of living, or do some of them deserve a better assignment? Give us all of your financial thoughts in the comments below.

You May Also Like…

6 Reasons Middle-Class Budgets Are Breaking Under “Slow Inflation”

Insurance Premium Increases Continue Outpacing Inflation

Why Is Saving Money Harder Now Than It Was Ten Years Ago

Modern Taxation Explained: Filing, Records, and Savings

8 Bold Strategies for Investing During Periods of High Inflation

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: saving money Tagged With: emergency fund, high-yield savings, Inflation, interest rates, investing basics, money management, Personal Finance, Planning, purchasing power, savings accounts, Wealth Building

10 Hidden 401(k) Fees That Can Eat Into Your Retirement Savings

March 4, 2026 by Brandon Marcus Leave a Comment

These Are 10 Hidden 401(k) Fees That Can Eat Into Your Retirement Savings
Image Source: Shutterstock.com

A 401(k) can serve as one of the most powerful tools for building long-term wealth. Tax advantages, automatic payroll deductions, and employer matching create a system that rewards consistency. But behind that polished surface, layers of fees can chip away at hard-earned savings year after year. A fraction of a percent may sound harmless.

Over decades, that fraction compounds into thousands, sometimes tens of thousands, of dollars that never make it into a retirement account. Truly comprehending where those fees hide gives investors real power. Here are ten common 401(k) costs that deserve attention and a closer look.

1. Expense Ratios That Quietly Compound

Every mutual fund or exchange-traded fund inside a 401(k) charges an expense ratio. That percentage covers management, administration, and operating costs. Fund companies deduct it directly from returns, which means no monthly bill ever arrives to grab attention. An expense ratio of 1 percent instead of 0.10 percent might not feel dramatic. Over 30 years, that gap can reduce a retirement balance by tens of thousands of dollars. Low-cost index funds often carry much lower expense ratios than actively managed funds, and many retirement plans now include at least a few affordable options.

Anyone reviewing a 401(k) lineup should scan the expense ratios first. Even small reductions can boost long-term growth in a meaningful way. This is one of the most painful fees that sadly slips through the cracks for many people.

2. Administrative Fees That Keep the Plan Running

Plan administrators handle recordkeeping, customer service, compliance testing, and other behind-the-scenes tasks. Those services cost money, and plan sponsors pass the expense on to participants in different ways. Sometimes the plan charges a flat annual fee. Other times, administrators bundle the cost into fund expenses, which makes it harder to spot. A summary plan description outlines those charges clearly, but many people skip that document entirely.

Taking a few minutes to review administrative costs can reveal whether a plan charges more than average. If fees run high, an employee may still benefit from the employer match but could consider investing additional retirement dollars elsewhere, such as in an IRA with lower overall costs.

3. Individual Service Fees That Add Up

Certain actions inside a 401(k) can trigger extra charges. Loans, hardship withdrawals, paper statements, or processing certain transactions often come with individual service fees. Each fee may look small, but frequent transactions can turn those charges into a recurring drain. A loan, for example, usually carries both an origination fee and ongoing maintenance costs.

Careful planning reduces the need for these services. Building an emergency fund outside of the 401(k) can prevent unnecessary loans or withdrawals and keep retirement savings intact.

4. Investment Management Fees Beyond the Basics

Some plans offer managed account services or target-date funds that include an additional management layer. That extra oversight may appeal to investors who prefer a hands-off approach, but it rarely comes free.

Target-date funds bundle multiple investments and automatically adjust risk over time. While convenient, they sometimes carry higher expense ratios than building a simple portfolio of low-cost index funds. Managed accounts that provide personalized allocation advice can cost even more. Convenience matters, but investors should weigh the benefit of guidance against the long-term cost of higher fees.

5. Sales Loads That Still Linger

Most modern 401(k) plans avoid sales loads, but some older plans still include funds with front-end or back-end sales charges. A front-end load reduces the amount invested at the start, while a back-end load applies when someone sells shares. These loads reward brokers or advisors for selling specific funds. Over time, that structure reduces the total amount invested and slows growth.

Employees should examine fund details carefully and look for no-load options whenever possible. Many employers have shifted toward lower-cost institutional share classes, but verifying that fact makes sense.

6. Revenue Sharing Arrangements

Revenue sharing occurs when a mutual fund company pays part of its fees back to the plan administrator. Administrators often use that money to offset plan costs, but the arrangement can obscure the true cost of investments. Participants may never see a line item labeled revenue sharing, yet the expense ratio already reflects it. In some cases, higher-cost funds remain in the lineup because they generate more revenue sharing.

Transparency matters here. Asking the human resources department or plan administrator how revenue sharing works within the plan can provide clarity and encourage better decisions.

7. Advisor Fees Within the Plan

Some employers hire financial advisors to provide education sessions, asset allocation models, or one-on-one guidance. While advice can help, someone has to pay for it. Sometimes the employer absorbs the cost. But in far too many cases, the plan spreads the fee across participants as a percentage of assets.

Reviewing fee disclosures will show whether the plan includes an advisory fee. If so, participants should decide whether they use and value that service enough to justify the expense. If it’s something you don’t plan to use, you shouldn’t have to pay for it.

These Are 10 Hidden 401(k) Fees That Can Eat Into Your Retirement Savings
Image Source: Shutterstock.com

8. High Trading Costs Inside Actively Managed Funds

Actively managed funds buy and sell securities more frequently than index funds. That activity generates trading costs, which do not appear directly in the expense ratio. High portfolio turnover can reduce returns over time. While active managers aim to outperform the market, many struggle to beat low-cost index funds consistently after fees.

Investors who prefer simplicity and cost efficiency often gravitate toward broad market index funds. Lower turnover usually translates into lower hidden costs and steadier long-term performance.

9. Recordkeeping and Custodial Fees

Behind every 401(k) stands a custodian that holds assets and processes transactions. Recordkeepers maintain account balances and track contributions. Plans sometimes bundle these services into overall administrative fees, but in certain cases, participants see separate line items. A small annual custodial fee may not cause alarm, yet over decades, even modest recurring charges chip away at growth.

10. Redemption Fees and Short-Term Trading Penalties

Some funds impose redemption fees if investors sell shares within a short time frame. Fund managers use these fees to discourage rapid trading, which can disrupt long-term strategy. Participants who rebalance frequently or move money in response to market swings may run into these penalties. Even a 1 or 2 percent redemption fee can sting.

Sticking to a disciplined, long-term investment strategy reduces the likelihood of triggering these charges and keeps more money invested for growth. Although quickly trading isn’t encouraging, paying heavily because of them shouldn’t throw you off your financial plans.

Protecting What You Earn

A 401(k) can anchor a solid retirement plan, but attention to detail determines how well that anchor holds. Fees never announce themselves with flashing lights. They sit quietly in disclosures, expense ratios, and plan documents, slowly shaping long-term outcomes.

Taking control starts with reviewing the plan’s fee disclosure statement, which federal law requires employers to provide. Comparing expense ratios across available funds, favoring low-cost index options when appropriate, and avoiding unnecessary transactions can preserve significant wealth over time. Contributing enough to capture the full employer match still makes sense in most cases, even in a higher-fee plan, because that match represents an immediate return.

Which of these fees surprised you the most, and what steps will you take to keep more of your money working toward the future? We want to hear your thoughts in our comments section below.

You May Also Like…

5 Genius Moves to Maximize Your 401k Match Aggressively

7 Sun Belt Retirement Towns Seeing Significant Price Corrections

Running Out of Money in Retirement? 9 Planning Errors Advisors See Every Day

Is There Any Way to Temporarily Stop 401k Contributions in an Emergency Situation

Is There Any Way to Get Your 401k Before The Age of 59?

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Retirement Tagged With: 401(k), employer benefits, expense ratios, Financial Wellness, Hidden Fees, investing, long-term investing, money management, mutual funds, Personal Finance, retirement planning, Wealth Building

The $3,000 Property Tax Reality Facing the Average U.S. Household

March 4, 2026 by Brandon Marcus Leave a Comment

The $3,000 Property Tax Reality Facing the Average U.S. Household
Image Source: Shutterstock.com

A $3,000 bill lands on the average U.S. household every year, and it doesn’t buy a single new appliance, vacation, or streaming subscription. It covers property taxes. That number, drawn from national housing data, represents the typical annual property tax paid by homeowners across the country.

It may not spark the same panic as a market crash or a spike in mortgage rates, but it quietly shapes budgets, retirement plans, and even decisions about where families choose to live. Anyone who owns a home—or plans to—needs to understand what that $3,000 really means and how to keep it from climbing higher.

The Number That Hides in Plain Sight

The median annual property tax bill in the United States sits between $2,900 and $3,200, according to national reporting figures. In some states with high home values and strong public services, annual bills stretch far beyond $6,000 or even $10,000. In other regions with lower property values or different tax structures, homeowners pay under $1,500 a year.

Local governments calculate property taxes by multiplying a home’s assessed value by the local tax rate, often referred to as a millage rate. County assessors estimate what a property would likely sell for in the current market. Local officials then apply tax rates that fund public schools, police departments, fire services, road maintenance, and other community needs. When home values climb, assessed values often follow, and tax bills rise along with them.

That hefty average masks sharp differences across the country, but it still offers a clear message: property taxes demand serious attention in any household budget. Anyone who treats them as an afterthought risk feeling blindsided when the bill arrives.

Why Property Taxes Keep Climbing

Home prices surged across much of the country over the past several years. When market values rise, assessments often increase as well, which pushes property tax bills higher. Even if tax rates stay flat, a higher assessed value leads directly to a larger bill. Local governments also adjust tax rates to meet budget needs. School districts may seek additional funding for new buildings or teacher salaries. Counties may need more revenue for infrastructure repairs or emergency services. When voters approve bonds or levies, property owners often shoulder much of that cost.

Inflation adds another layer of pressure. The cost of materials, labor, and public services continues to rise, and municipalities respond by adjusting budgets. That reality often flows down to homeowners in the form of higher property taxes.

Anyone watching housing trends can see how quickly values can shift. A house purchased for $250,000 a decade ago might now carry a market value of $400,000 or more in certain areas. That appreciation builds wealth on paper, but it can also inflate the annual tax bill in ways that strain cash flow.

The True Cost of Owning a Home

Many buyers fixate on mortgage rates and monthly payments, yet property taxes often rival or exceed homeowners insurance in annual cost. Lenders typically collect property taxes through escrow accounts, which means homeowners pay a portion each month as part of their mortgage payment. When tax bills rise, lenders adjust escrow requirements, and monthly payments jump.

That increase can feel jarring. A homeowner who budgeted carefully for a fixed-rate mortgage may suddenly face an extra $150 or $200 per month because the county reassessed the property. That shift can squeeze families already juggling childcare costs, student loans, and rising grocery prices. Prospective buyers should always calculate the full cost of ownership before making an offer. That calculation includes principal, interest, property taxes, insurance, maintenance, and utilities. Ignoring property taxes creates an unrealistic picture of affordability.

Savvy buyers review the current tax bill and ask how much the assessed value differs from the purchase price. If the home sells for significantly more than its assessed value, the next tax bill may rise sharply after reassessment. That knowledge allows buyers to plan ahead rather than scramble later.

The $3,000 Property Tax Reality Facing the Average U.S. Household
Image Source: Shutterstock.com

How to Challenge an Assessment Without Losing Your Mind

Homeowners often assume that the county’s assessment reflects an untouchable verdict. It does not. Local governments allow property owners to appeal assessments if they believe officials overvalued their homes. The process usually begins with a review of the property record card, which lists details such as square footage, number of bedrooms, lot size, and improvements. Errors in those details can inflate an assessment. A homeowner who spots incorrect information should gather documentation and request a correction.

Comparable sales also matter. If similar homes in the neighborhood sold for less than the assessed value, that evidence can support an appeal. Most counties set clear deadlines and provide forms for filing appeals, often through the assessor’s office website.

Persistence plays a crucial role. An appeal may require attending a hearing or submitting additional documentation. Homeowners who prepare carefully and present clear evidence often secure reductions. Even a modest reduction in assessed value can save hundreds of dollars each year.

Smart Strategies to Manage the Property Tax Reality

Homeowners cannot eliminate property taxes, but they can take steps to manage them wisely. First, investigate exemptions. Many states and counties offer homestead exemptions for primary residences, which reduce the taxable value of a home. Seniors, veterans, and people with disabilities may qualify for additional exemptions or tax freezes.

Next, set aside money proactively. Even with escrow, homeowners benefit from tracking their annual tax amount and preparing for potential increases. A small monthly savings cushion can soften the blow of a higher bill. After that, pay attention to local elections and ballot measures. Property taxes often rise when voters approve new school funding or infrastructure bonds. Staying informed about local proposals allows homeowners to understand how those decisions will affect future bills.

Finally, consider location carefully when buying a home. Two houses with identical prices can carry dramatically different tax bills depending on the county or school district. Comparing effective property tax rates across nearby areas can reveal opportunities to save thousands over time.

The Story Behind the Bill

Property taxes fund essential services that shape daily life. Public schools educate children. Fire departments respond to emergencies. Road crews repair potholes. Parks departments maintain green spaces. Every dollar collected supports some piece of the local community. That reality does not make writing the check easier, but it does provide context. Communities with strong schools and well-maintained infrastructure often attract higher home values. In many cases, higher property taxes correlate with robust public services and amenities.

Still, balance matters. Homeowners deserve transparency from local officials about how they spend tax revenue. Attending town meetings, reviewing budget reports, and asking questions helps ensure accountability.

Financial awareness turns a frustrating bill into a manageable obligation. Anyone who understands how property taxes work can plan more effectively, advocate for fair assessments, and make informed decisions about buying, selling, or staying put.

When $3,000 Becomes a Turning Point

That average annual bill of around $3,000 carries weight far beyond its four digits. It influences where families settle, how retirees plan their futures, and how communities grow. Ignoring it invites stress, but understanding it opens the door to smarter choices.

Property taxes will not disappear, and home values will continue to shift with the market. Preparation, research, and proactive planning give homeowners control in a system that often feels rigid. A clear-eyed look at assessments, exemptions, and local tax rates can transform a confusing expense into a predictable part of financial life.

So when your next property tax statement arrives, will it feel like a shock or a number that fits into your well-prepared plan? Let’s discuss this in the comments below.

You May Also Like…

Why Nashville Property Tax Bills Keep Rising Even With Tennessee’s Rate Cap Proposal

Avoid These Pitfalls: First-Time Homeownership Mistakes That Can Cost You

Property Tax Exemptions Expiring Automatically in Multiple States

Colorado Escrow Payments Continue Climbing — Homeowners Face Higher Monthly Costs

8 Homeowner Insurance Denials Based on Aerial Photos

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: tax tips Tagged With: Budgeting Tips, Cost of living, financial literacy, homeowners, homeownership, Housing Costs, local government, mortgage, Personal Finance, property taxes, Real estate, tax planning

The 2026 Housing Shift: Why Renting May Make More Financial Sense Right Now

March 4, 2026 by Brandon Marcus Leave a Comment

The 2026 Housing Shift: Why Renting May Make More Financial Sense Right Now
Image Source: Shutterstock.com

A house once symbolized stability, success, and a smart financial move all wrapped into one. In 2026, that assumption deserves a serious second look. For decades, conventional wisdom pushed homeownership as the ultimate milestone. Buy as soon as possible, build equity, watch property values climb, and enjoy the rewards. That formula worked beautifully in certain eras, especially when mortgage rates hovered near historic lows and home prices rose steadily. Today’s market tells a more complicated story, and that complexity demands clear-eyed thinking rather than emotional attachment to tradition.

Renting, which many once framed as “throwing money away,” now carries strategic advantages that can protect cash flow, reduce stress, and even support long-term wealth building. The shift unfolding in 2026 does not erase the value of owning property. It simply challenges the idea that buying always wins.

Mortgage Rates Changed the Math

Mortgage rates sit far above the ultra-low levels seen in 2020 and 2021, and that reality reshapes affordability overnight. When rates climb, monthly payments surge even if home prices hold steady. A buyer who qualifies comfortably at 3 percent may struggle at 7 percent, even with the same income and credit profile. Lenders calculate debt-to-income ratios with ruthless precision, and higher rates stretch those ratios quickly.

Higher borrowing costs also mean buyers pay dramatically more interest over the life of a loan. That interest does not build equity. It goes straight to the lender. Anyone who runs the numbers on a 30-year mortgage at current rates often feels a jolt of sticker shock after seeing the total repayment amount. Renters avoid that interest burden entirely. They write a monthly check and move on with life. That difference alone creates breathing room in many budgets. Instead of funneling thousands of extra dollars into interest, renters can direct that money toward retirement accounts, investments, or emergency savings.

Home Prices Refuse to Cool Quickly

While some markets show modest price corrections, many areas continue to post high median home prices. Years of limited housing inventory created intense competition, and that supply shortage did not vanish overnight. Builders face high material costs and labor shortages, which slow new construction and keep pressure on prices.

Buyers entering the market in 2026 often confront bidding wars in desirable neighborhoods. That competition encourages aggressive offers, waived contingencies, and slim negotiation margins. Buyers who stretch too far financially to secure a property may regret that decision when maintenance costs and property taxes arrive.

Renters, on the other hand, can choose neighborhoods without committing to a massive upfront investment. They can test out a location, evaluate commute times, and assess local amenities without tying up savings in a down payment. In a market where prices remain elevated, flexibility carries real value.

The True Cost of Owning Adds Up Fast

Homeownership involves far more than a mortgage payment. Property taxes rise in many municipalities as local governments adjust assessments to reflect higher home values. Insurance premiums climb as insurers respond to climate risks and construction costs. Maintenance never stops. Roofs wear out, HVAC systems fail, and appliances break at the worst possible moment.

A homeowner must budget for routine upkeep and unexpected repairs. Financial advisors often recommend setting aside 1 to 2 percent of a home’s value each year for maintenance. On a $500,000 property, that translates to $5,000 to $10,000 annually. That figure surprises many first-time buyers who focus solely on the monthly mortgage payment.

Renters shift those repair responsibilities to landlords. When a water heater fails or a roof leaks, the landlord handles the bill. That arrangement protects renters from sudden financial shocks and preserves liquidity. Liquidity matters in uncertain economic times, and 2026 offers no shortage of economic variables.

Job Mobility Matters More Than Ever

The modern workforce looks nothing like it did twenty years ago. Remote work expanded dramatically in recent years, and many companies now embrace hybrid or fully remote models. Professionals change roles more frequently, chase better compensation packages, and relocate for career growth without hesitation.

Homeownership can complicate that mobility. Selling a home involves agent commissions, closing costs, staging expenses, and potential capital gains taxes. A slow market can trap a homeowner who needs to move quickly. Even in a healthy market, selling requires time and coordination.

Renting supports agility. When a lease ends, a renter can pack up and pursue a new opportunity in another city without navigating a complex sales process. That flexibility holds tangible financial value, especially for younger professionals or anyone working in fast-moving industries.

Investing the Difference Can Build Real Wealth

The argument for buying often centers on equity. Over time, homeowners build ownership in an appreciating asset. That principle remains true. However, equity builds slowly in the early years of a mortgage because lenders apply most of each payment to interest rather than principal.

A disciplined renter can invest the difference between rent and the total cost of ownership. That difference includes not only the mortgage payment but also taxes, insurance, maintenance, and closing costs. When invested consistently in diversified portfolios such as low-cost index funds, that capital can compound over decades.

Stock market returns fluctuate, and no one can guarantee future performance. Still, historical data shows that long-term equity investing often generates meaningful growth. Renters who commit to automatic investing plans can capture that growth without concentrating wealth in a single property. Diversification reduces risk, and 2026 reminds everyone that concentrated bets can backfire.

The 2026 Housing Shift: Why Renting May Make More Financial Sense Right Now
Image Source: Shutterstock.com

Renting Reduces Financial Stress in Uncertain Times

Economic cycles bring expansions and contractions. Inflation pressures household budgets, and layoffs sometimes follow periods of rapid corporate hiring. In such an environment, large fixed expenses create stress. A homeowner must pay the mortgage every month regardless of job status. Lenders do not accept flexibility as an excuse. While forbearance programs exist in extreme cases, those measures often come with strict rules and long-term consequences.

Renters typically face lower upfront commitments and shorter lease terms. They can downsize more easily if income changes. They can move to a more affordable unit at the end of a lease. That adaptability reduces risk exposure and supports financial resilience.

Lifestyle Goals Should Lead the Decision

Financial math matters, but lifestyle goals deserve equal weight. Some individuals crave the stability of planting roots, customizing a living space, and building a long-term community presence. Others value travel, flexibility, and the freedom to pivot quickly. In 2026, choosing to rent does not signal failure or lack of ambition. It signals strategic thinking. The housing market no longer rewards blind commitment to ownership at any cost. It rewards thoughtful analysis that aligns housing decisions with career plans, savings goals, and personal priorities.

Anyone weighing the decision should run detailed numbers, compare total ownership costs to rent, and consider likely career moves over the next five years. A spreadsheet may reveal that renting preserves thousands of dollars annually. That money can fund investments, education, or entrepreneurial ventures.

The Smart Move in a Shifting Market

The 2026 housing landscape challenges old assumptions and invites a more nuanced approach to wealth building. High mortgage rates inflate monthly payments, elevated home prices demand larger down payments, and ownership costs stretch far beyond principal and interest. Renting, once dismissed as a temporary step, now offers financial flexibility, mobility, and investment potential that rival traditional homeownership strategies.

Housing decisions should reflect current market conditions rather than outdated advice. Anyone standing at the crossroads between renting and buying holds the power to analyze numbers, evaluate lifestyle goals, and choose the path that protects both peace of mind and long-term finances. In a market that rewards agility and clear thinking, renting may represent not a compromise but a calculated advantage.

Does renting feel like a temporary pause, or does it look like a smart financial play in today’s market? What are your financial plans for housing? Let’s talk about them in the comments section below.

You May Also Like…

6 Reasons Renting Is Now Smarter Than Buying in Many US Cities

Avoid These Pitfalls: First-Time Homeownership Mistakes That Can Cost You

Colorado Escrow Payments Continue Climbing — Homeowners Face Higher Monthly Costs

The End of the 3% Mortgage: Why “Assumable Loans” Are A Smart Way to Buy a House in 2026

Why Do People Think Renting Furniture Is a Good Deal


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: Cost of living, economic outlook, homeownership, housing market 2026, mortgage rates, Personal Finance, Planning, property taxes, real estate trends, rental market, renting vs buying, Wealth Building

6 Questions You’re Avoiding With Your Financial Advisor

March 4, 2026 by Brandon Marcus Leave a Comment

These Are 6 Questions You’re Avoiding With Your Financial Advisor
Image Source: Shutterstock.com

Money conversations shape the rest of your life. They influence when work ends, where home feels comfortable, and how confidently the future unfolds. Yet too many meetings with financial advisors drift toward polite updates, glossy charts, and reassuring nods.

Real financial progress demands sharper questions, the kind that challenge assumptions and force clarity. Avoiding them might keep things comfortable, but comfort rarely builds wealth.

1. Are You Acting as a Fiduciary at All Times?

Not all financial advisors operate under the same standard. Some follow a fiduciary duty, which legally requires them to place a client’s interests ahead of their own. Others operate under a suitability standard, which allows them to recommend products that fit a general profile even if better options exist. That difference matters more than most people realize.

The Securities and Exchange Commission defines a fiduciary as someone who must provide advice in the best interest of the client, disclose conflicts of interest, and seek best execution on trades. That sounds obvious, but the financial industry includes brokers, registered investment advisers, insurance agents, and hybrid models, each governed by different rules. Clarity around this point prevents confusion later.

A direct question about fiduciary status signals seriousness. It invites transparency about compensation, incentives, and product recommendations. It also sets the tone for every future conversation. If an advisor hesitates or offers vague explanations, that response reveals valuable information. Trust thrives on clarity, not on assumptions.

2. How Exactly Do You Get Paid?

Fees rarely appear dramatic at first glance. A one percent annual fee on assets under management might sound small, but compound that over decades and the cost becomes significant. According to research from the U.S. Department of Labor, even a one percent difference in fees can reduce retirement savings by tens of thousands of dollars over time.

Advisors typically earn income through fee-only structures, commissions on financial products, or a combination of both. Fee-only advisors charge a flat fee, hourly rate, or percentage of assets, and they do not earn commissions on product sales. Commission-based advisors may earn compensation when clients purchase certain investments or insurance policies. Each model carries different incentives.

Clear understanding of compensation allows smarter evaluation of recommendations. If an advisor suggests an annuity, mutual fund, or insurance product, ask how that product affects their compensation. That question does not accuse; it simply ensures alignment. Financial decisions deserve sunlight.

3. What Risks Am I Taking That I Don’t See?

Every portfolio carries risk. Market risk, inflation risk, interest rate risk, sequence-of-returns risk in retirement, and even behavioral risk all shape outcomes. Many conversations focus heavily on projected returns while giving risk a quick summary. That imbalance can create trouble.

A healthy financial plan begins with an honest assessment of risk tolerance and risk capacity. Risk tolerance reflects emotional comfort with volatility. Risk capacity reflects the financial ability to withstand losses without derailing long-term goals. These two do not always match. Someone may feel calm during market swings but rely heavily on portfolio withdrawals in early retirement, which increases vulnerability.

Requesting a clear breakdown of downside scenarios sharpens understanding. Ask how the portfolio might perform during a severe downturn similar to 2008. Ask how inflation above historical averages could impact purchasing power. Ask what adjustments the advisor would recommend if markets dropped significantly. Specific answers reveal whether the strategy accounts for real-world stress.

4. What Happens If the Market Crashes Tomorrow?

Optimism drives investing, but preparation protects it. Markets move in cycles. The S&P 500 has experienced multiple bear markets over the past several decades, and history shows that downturns arrive without much warning. A financial plan that depends on smooth, uninterrupted growth invites disappointment. A thoughtful advisor should outline a disciplined strategy for volatile periods. That may include rebalancing to maintain target asset allocation, maintaining a cash buffer for near-term expenses, or adjusting withdrawal strategies in retirement. Clear planning reduces emotional decision-making during turbulent times.

This question also exposes whether the strategy relies heavily on market timing. Research consistently shows that attempting to predict short-term market movements rarely succeeds over long horizons. Strong advisors emphasize diversification, cost control, tax efficiency, and disciplined rebalancing rather than bold predictions. Confidence should come from preparation, not guesswork.

These Are 6 Questions You’re Avoiding With Your Financial Advisor
Image Source: Shutterstock.com

5. How Does This Plan Change as My Life Changes?

Life refuses to sit still. Careers shift. Families grow. Health evolves. Goals transform. A financial plan that worked five years ago may not fit current priorities. Static plans slowly lose relevance. A strong advisor schedules regular reviews and proactively revisits assumptions about income, savings rate, retirement age, tax bracket, and estate planning goals. Major life events such as marriage, divorce, inheritance, business ownership, or relocation should trigger plan updates. Tax law changes and economic shifts may also require adjustments.

Clarity about flexibility prevents stagnation. Ask how often the plan undergoes a comprehensive review. Ask how the advisor tracks progress toward specific goals rather than focusing only on portfolio performance. Financial planning should feel dynamic and responsive, not frozen in time.

6. What Am I Not Asking That I Should Be?

This question may feel uncomfortable because it invites vulnerability. Yet it opens the door to deeper insight. Experienced advisors see patterns across many clients. They understand common blind spots, whether related to underestimating healthcare costs in retirement, overlooking long-term care planning, or neglecting beneficiary designations.

Healthcare expenses alone can significantly affect retirement planning. Fidelity has estimated that a 65-year-old couple retiring today may need hundreds of thousands of dollars to cover healthcare costs throughout retirement, excluding long-term care. Ignoring that reality creates strain later.

By asking what questions remain unasked, clients encourage advisors to share broader wisdom. That conversation can expand beyond investments to include tax strategies, estate planning coordination, charitable giving, and risk management. Comprehensive financial planning reaches far beyond stock selection.

The Courage to Ask Changes Everything

Financial advisors bring expertise, but strong outcomes require active participation. Questions drive clarity. Clarity builds confidence. Confidence supports disciplined action during both calm and chaotic markets.

Avoiding hard conversations may preserve short-term comfort, but direct questions create long-term strength. A transparent advisor will welcome thoughtful scrutiny and respond with clear explanations backed by data and experience. That dynamic forms the foundation of a true partnership.

Which of these questions feels the hardest to bring up at the next appointment? Tell us how you’ll be brave and ask them anyway in our comments section below.

You May Also Like…

10 Things Financial Advisors Didn’t Warn Baby Boomers About That Are Now Costing Them Thousands

Some Of Your Parents’ Financial Advice Was Smart

Regulation Impact: 6 Rules That Could Change How You Pay for Financial Advice

Financial Advisor Confession: 7 Things I’m Now Required by Law to Tell My Clients (That I Couldn’t Say in 2025).

7 Strange Questions Financial Advisors Secretly Love to Answer

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Financial Advisor Tagged With: fiduciary, financial advisor, investing, investment fees, long-term investing, money management, Personal Finance, Planning, portfolio strategy, retirement planning, risk tolerance, Wealth Building

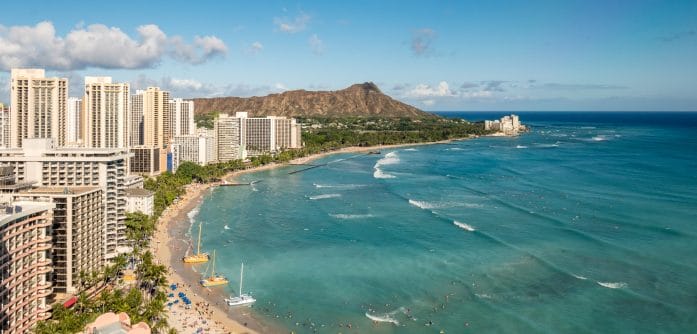
Hawaii Residents Face Some of the Tightest Margins in America — What It Takes to Make It Work in 2026

March 3, 2026 by Brandon Marcus Leave a Comment

Hawaii Residents Face Some of the Tightest Margins in America — What It Takes to Make It Work in 2026
Image Source: Unsplash.com

Hawaii looks like paradise on a postcard, but paradise comes with a price tag that reshapes every financial decision. In 2026, the average single resident faces living costs of about $4,500 per month, or roughly $55,000 per year, which is 84 percent higher than the U.S. average. Housing alone costs about $3,624 per month for a single person, more than double the national average.

After covering rent, groceries, utilities, transportation, and healthcare, many residents are left with only a few hundred dollars per month in true discretionary income. That number varies widely by island, household size, and income level, but the reality is consistent: disposable income in Hawaii is tight, and stretching it requires intention, creativity, and discipline.

The Real Cost of Living in the Aloha State

Hawaii remains the most expensive state in the country in 2026. Housing drives most of the pressure. Limited land, high demand, and geographic isolation keep prices elevated. Groceries follow the same pattern. Shipping costs inflate prices on staples like milk, eggs, and meat. Residents feel the difference every time they shop.

Utilities add another layer. Electricity rates remain among the highest in the nation because Hawaii still relies heavily on imported fuel. Even modest air‑conditioning use can push monthly bills far above mainland norms.

When basic living costs consume more than $50,000 per year for a single person, disposable income becomes a fragile margin rather than a comfortable cushion.

Housing: The Budget Anchor That Shapes Everything

Housing determines whether a Hawaii budget sinks or floats. With average rents far above national norms, many residents spend well over 30 percent of their income on shelter alone. Some move farther from urban centers to find lower rent. Others share housing with roommates or extended family, a common and culturally rooted approach that provides both emotional and financial support.

A slightly cheaper rental can free up thousands of dollars per year. That difference may fund an emergency savings buffer, cover travel between islands, or simply reduce stress in a high‑cost environment.

Food, Fuel, and the Everyday Reality Check

Groceries cost more in Hawaii because most food is imported. Weekly bills climb quickly, especially for families. Residents who stretch their budgets often rely on farmers markets, local produce, and community‑supported agriculture programs, which can offer competitive prices and fresher options.

Transportation adds another challenge. Gas prices typically sit above mainland averages due to shipping and refining costs. Many residents combine errands, carpool, or use public transit to reduce fuel spending.

Turning Limited Disposable Income into Real Progress

Even when discretionary income is slim, intentional planning can turn it into forward momentum. A clear budget gives every dollar a purpose. Emergency savings matter most. With living costs so high, even a small, unexpected expense can destabilize a household. Building a starter emergency fund, then gradually expanding it, protects against setbacks.

Retirement savings also deserve attention. Contributing to a 401(k) or IRA, especially when an employer offers matching funds, helps build long‑term security. Even modest monthly contributions compound over time. Setting aside money for enjoyment—like dining out or exploring other islands—helps maintain balance. A sustainable budget includes room for living, not just surviving.

Lifestyle Choices That Make or Break the Budget

Hawaii offers endless ways to spend money, from oceanfront dining to boutique shopping. Without boundaries, discretionary spending can disappear quickly. Many residents embrace low‑cost or free activities instead. Beaches, hiking trails, and community events offer world‑class experiences without draining the budget. Cooking at home, limiting subscriptions, and reviewing insurance policies also help stretch limited disposable income.

Every recurring expense deserves scrutiny. When someone treats their remaining income as a resource to protect, financial stability becomes more attainable.

Hawaii Residents Face Some of the Tightest Margins in America — What It Takes to Make It Work in 2026
Image Source: Unsplash.com

Building Resilience in a High‑Cost Environment

Living in Hawaii requires flexibility. Tourism shifts, economic changes, and natural events can influence job markets and household budgets. Side income streams are common. Freelance work, seasonal jobs, and small business ventures help residents supplement earnings. Hawaii’s creative and entrepreneurial culture supports everything from handmade crafts to digital services.

Community plays a major role. Shared childcare, bulk buying, bartering, and multigenerational living reduce individual financial pressure. In a state where costs run high, collective resilience matters.

Income, Opportunity, and Perspective

Hawaii’s high median household income does not translate into easy living. Elevated costs erode purchasing power quickly. A paycheck that looks strong on paper may feel thin in practice. Understanding that tension helps residents make informed decisions about careers, housing, and long‑term goals. Some choose to relocate for affordability. Others stay for lifestyle, family, or cultural connection, accepting tighter margins in exchange for the benefits of island life.

Perspective matters. Even limited disposable income can support stability when aligned with values and managed intentionally.

Paradise With a Plan

Hawaii’s beauty attracts dreamers, but thriving in the islands requires strategy. With average living costs exceeding $54,000 per year for a single person, disposable income is precious. Housing choices, grocery habits, transportation decisions, and disciplined saving all shape the outcome.

Residents who succeed financially treat every dollar as part of a larger plan. They balance enjoyment with responsibility, question recurring expenses, and commit to long‑term goals even when temptation surrounds them.

What part of Hawaii’s cost structure do you think deserves the most attention—housing, groceries, utilities, or income trends? Do you think you could be a full-time resident of the state? Let’s talk about it in the comments section below.

You May Also Like…

How Trump’s New Fed Pick Could Change Your Interest Income Forever

How The SALT Deduction Caps Squeezed Many Middle-Income Taxpayers

The IRS Timing Rule That Can Push Income Into a Different Tax Year

9 Everyday Costs Rising Faster Than Seniors’ Income

The Income-Driven Repayment Plans That End July 1, 2028 Under New Law

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Finance Tagged With: budgeting, Cost of living, Disposable Income, groceries, Hawaii, Honolulu, Housing Costs, Island Living, Lifestyle, Personal Finance, Planning, saving money, utilities

How Inheriting $100K Can Disappear in Months — Lessons From Rapid Wealth Loss

March 3, 2026 by Brandon Marcus Leave a Comment

How Inheriting $100K Can Disappear in Months — Lessons From Rapid Wealth Loss
Image Source: Pexels.com

$100,000 looks like a safety net big enough to change everything. It feels solid, powerful, almost untouchable. For a brief moment, it can create the illusion that money problems belong to the past and a new chapter has begun.

Yet time and again, six-figure inheritances evaporate in less than a year, leaving behind confusion, regret, and a bank balance that looks shockingly familiar. Understanding how that happens—and how to prevent it—can mean the difference between a fresh start and a financial relapse.

The Lifestyle Upgrade Trap

The first place a $100,000 inheritance often disappears sits right in plain sight: lifestyle inflation. A bigger apartment, a newer car, upgraded furniture, spontaneous travel, and generous gifts to family members can each feel reasonable on their own. Stack them together, and they form a fast-moving drain on cash.

Consider housing. A modest rent increase of $800 per month adds up to $9,600 a year. Add a car payment of $600 per month, which totals $7,200 annually, plus higher insurance premiums and maintenance costs. Suddenly, nearly $20,000 per year supports a new standard of living. If that lifestyle sticks, the inheritance becomes a temporary subsidy rather than a permanent improvement.

Behavioral finance research consistently shows that people adapt quickly to higher living standards. After a few months, the upgraded lifestyle feels normal rather than luxurious. The money that once seemed abundant now feels insufficient, which can trigger even more spending. Anyone who inherits a large sum should pause before making permanent changes to recurring expenses. A 30-day waiting period before major purchases can slow down impulsive decisions and protect long-term goals.

The Tax Surprise That Hits Hard

Many people assume that every inheritance arrives tax-free, but the reality depends on the type of asset. Cash from a life insurance policy often comes without federal income tax. However, inherited retirement accounts such as traditional IRAs or 401(k)s carry income tax obligations when distributions occur. The SECURE Act, passed in 2019, generally requires most non-spouse beneficiaries to withdraw the full balance of an inherited retirement account within 10 years, which can create significant taxable income.

If someone inherits a $100,000 traditional IRA and withdraws large portions quickly, that income adds to their existing salary and can push them into a higher tax bracket. A 24 percent federal tax rate on $100,000 equals $24,000 in federal taxes alone, not counting state taxes. Without a strategy, a sizable chunk of the inheritance can disappear before it funds a single long-term goal.

A smart approach involves working with a tax professional to plan distributions over several years, keeping income within manageable tax brackets when possible. Even without professional help, reviewing IRS guidance and understanding how withdrawals affect taxable income can prevent unpleasant surprises.

Debt Payoff Without a Plan

Paying off debt can feel like the most responsible move, and in many cases it makes sense. High-interest credit card balances, for example, can charge 20 percent or more annually, which makes eliminating them a powerful financial win. However, wiping out every debt without considering cash flow and emergency savings can create new problems.

Imagine someone uses $60,000 of a $100,000 inheritance to pay off student loans and auto loans. That decision reduces monthly payments, which sounds positive. Yet if that person fails to build an emergency fund and then faces a job loss or medical bill, they may return to credit cards to cover expenses. The inheritance solves one problem while leaving another untouched.

Financial planners often recommend building three to six months of essential expenses in an emergency fund. Before aggressively paying down lower-interest debt, allocating part of the inheritance to a high-yield savings account can create a buffer that prevents future borrowing. The goal involves balance: eliminate expensive debt while protecting liquidity.

Risky Investments in the Name of Growth

A sudden windfall can trigger overconfidence. Someone who never invested before may suddenly feel ready to chase hot stocks, cryptocurrency trends, or speculative real estate deals. Social media and financial headlines often highlight dramatic gains while ignoring the equally dramatic losses.

History offers repeated lessons about speculative bubbles, from the dot-com boom in the late 1990s to more recent cryptocurrency volatility. When markets surge, stories of overnight wealth dominate headlines. When prices crash, silence often follows. Investing a large portion of an inheritance into a single high-risk asset can wipe out tens of thousands of dollars in months.

Diversification remains one of the most reliable principles in investing. Broad-based index funds, such as those tracking the S&P 500, spread risk across hundreds of companies. A long-term strategy that matches personal risk tolerance and time horizon stands a far better chance of preserving and growing wealth than a bet on the next big thing. Before investing, setting clear goals—retirement, home purchase, education—can guide decisions and prevent emotional reactions to market swings.

How Inheriting $100K Can Disappear in Months — Lessons From Rapid Wealth Loss
Image Source: Pexels.com

Emotional Spending and Grief

Inheritance often follows loss. Grief can cloud judgment and fuel spending decisions that provide short-term comfort. Large purchases can feel symbolic, like honoring a loved one or marking a new chapter. Unfortunately, emotional spending rarely aligns with long-term financial security.

Psychologists recognize that major life events—death, divorce, job changes—can alter decision-making patterns. During emotionally intense periods, people often seek control or distraction through financial choices. That dynamic can lead to generosity beyond sustainable limits or purchases that fail to deliver lasting satisfaction.

Creating a cooling-off period helps. Placing inherited funds in a separate account and avoiding major financial moves for several months can allow emotions to settle. Consulting a financial advisor or trusted third party can introduce objectivity when emotions run high.

The Illusion of Endless Cushion

$100,000 sounds like a lifetime of security. In reality, it equals less than two years of living expenses for many households in the United States. According to data from the Bureau of Labor Statistics, average annual household spending often exceeds $70,000, depending on location and family size. At that pace, $100,000 can vanish in under 18 months without any major splurges.

Inflation adds another layer of pressure. Rising costs for housing, food, healthcare, and transportation erode purchasing power over time. Without investment growth or disciplined budgeting, a cash inheritance shrinks both in nominal terms and real value.

Creating a written financial plan can counter this illusion. Listing short-term needs, medium-term goals, and long-term objectives clarifies priorities. Allocating portions of the inheritance to each category—emergency savings, debt reduction, retirement investment—turns a lump sum into a structured strategy.

Protecting a Windfall With Structure and Intent

Preserving an inheritance requires intentional design. Automatic transfers into investment accounts can remove temptation. Separating funds into labeled accounts—“Emergency,” “Retirement,” “Future Home”—can reinforce purpose and discourage random spending.

Professional guidance can add value, especially for complex assets. A certified financial planner can assess tax implications, risk tolerance, and long-term projections. However, even without paid advice, using reputable educational resources and low-cost diversified investments can protect against common pitfalls.

Most importantly, aligning money with values creates durability. If financial freedom, flexibility, and security matter more than status purchases, spending decisions will reflect those priorities. A windfall should support a life plan, not replace it.

The Real Value Of $100K Lies in Restraint

A six-figure inheritance can transform a financial trajectory, but only if discipline guides the process. Quick upgrades, tax missteps, emotional decisions, and speculative investments can dismantle it in months. Careful planning, diversified investing, controlled lifestyle choices, and a strong emergency fund can stretch its impact for decades.

What would your first move be if a six-figure windfall landed in the bank tomorrow? Let’s maturely discuss all things finance in our comments below.

You May Also Like…

8 Ways Baby Boomers Should Leave Their Inheritance That Helps Families Keep The Peace

The Inheritance Mistakes That Turn Siblings Into Legal Enemies After a Parent Dies

Legacy Trap: How Your Kids Might Inherit More Tax Than Wealth Without Realizing It

5 Inheritance Tricks That Make Your Heirs Love You Forever

Your Attorney Isn’t the Only One Who Needs Your Will Details: 5 Conversations That Prevent Family Disputes

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Finance Tagged With: budgeting, Debt Management, emergency fund, financial literacy, Inheritance, investing basics, Lifestyle Inflation, money mistakes, Personal Finance, Planning, taxes, Wealth management

4 Signs Your Parents May Be Hiding a Financial Crisis

March 3, 2026 by Brandon Marcus Leave a Comment

4 Signs Your Parents May Be Hiding a Financial Crisis
Image Source: Pexels.com

Money stress rarely announces itself with a dramatic confession. It creeps into daily routines, reshapes habits, and quietly alters behavior long before anyone says a word. Parents who once handled every bill with confidence may start dodging conversations about expenses or brushing off simple questions about retirement.

Pride, fear, and a desire to protect their children often keep them silent, even when the numbers start slipping out of control. Spotting the signs early can make the difference between a manageable course correction and a full-blown financial collapse.

1. Bills Pile Up or Paperwork Starts to Disappear

Stacks of unopened mail often tell a story that no one wants to voice. A parent who once paid every bill on time may suddenly miss due dates or accumulate late notices. Utilities might send reminders, credit card companies may increase calls, and important financial statements could remain sealed on the kitchen counter. That shift rarely happens by accident.

Financial disorganization can stem from cognitive decline, rising debt, or a simple sense of overwhelm. Older adults face a higher risk of financial exploitation and fraud, which can drain savings quickly and leave chaos in its wake. When paperwork goes untouched, it can signal confusion, shame, or mounting balances that feel too big to face.

Look for practical changes. Does the house lack essentials even though income should cover them? Do subscriptions continue charging long after they stop getting used? Gently offering to help set up automatic bill payments, review monthly statements, or consolidate accounts can restore order without stripping away independence. The key involves approaching the topic with respect rather than suspicion.

Encourage a full financial checkup. Suggest reviewing credit reports together through AnnualCreditReport.com, which federal law makes available for free each year. That step can uncover missed payments, unfamiliar accounts, or identity theft before the situation spirals further.

2. Retirement Plans Suddenly Shift Without Clear Reason

A sudden decision to delay retirement, return to work, or cash out investments should raise thoughtful questions. Market ups and downs can influence retirement timing, but drastic changes often reflect deeper strain. If parents once spoke confidently about retirement and now avoid specifics, something may have shifted behind the scenes.

Many older adults carry debt into retirement, including mortgages, credit cards, and even student loans taken out for children or grandchildren. Rising healthcare costs and inflation can also pressure fixed incomes. When savings projections fall short, some parents quietly adjust plans instead of admitting concern.

Watch for withdrawals from retirement accounts earlier than expected. Early withdrawals from certain accounts, such as traditional IRAs or 401(k)s before age 59½, can trigger penalties and taxes. Even after that age, large unplanned withdrawals can erode long-term security. Selling long-held investments or property in a rush may also suggest a need for immediate cash.

Offer support by suggesting a meeting with a certified financial planner or a fiduciary advisor who must legally act in the client’s best interest. Frame the conversation around optimization rather than rescue. A neutral third party can help evaluate Social Security timing, healthcare planning, and sustainable withdrawal rates without emotional tension.

3. Lifestyle Changes Don’t Match Their Income

Every family adjusts spending habits from time to time, but sharp, unexplained cutbacks can signal trouble. Parents who once enjoyed occasional travel or dining out may suddenly cancel plans and avoid social gatherings that involve spending. On the flip side, some may overspend in ways that seem out of character, which can point to emotional stress or even financial scams.

The National Council on Aging reports that millions of older adults struggle to meet basic economic needs, especially when living on fixed incomes. Rising property taxes, insurance premiums, and medical bills can quietly squeeze budgets. If a parent begins skipping medical appointments, delaying home repairs, or rationing groceries, that shift deserves immediate attention.

At the same time, unexpected generosity can also hint at risk. Large gifts to new acquaintances, sudden investments in unfamiliar ventures, or urgent wire transfers can indicate fraud. Scammers often target older adults with convincing stories and high-pressure tactics, leaving families stunned by losses.

Start with observation and empathy. Ask open-ended questions about recent changes rather than accusing anyone of mismanaging money. Offer to review monthly expenses together and identify areas where assistance programs, refinancing, or downsizing could ease the burden. Sometimes a simple audit of recurring expenses can free up significant cash flow without drastic sacrifice.

4. Defensive Reactions Around Money Conversations

Tone often reveals more than spreadsheets ever could. A parent who bristles at basic questions about finances may feel exposed or afraid. Sharp defensiveness, abrupt topic changes, or exaggerated reassurance that everything remains “fine” can mask deeper anxiety.

Money carries emotional weight. It represents security, identity, and years of hard work. Admitting financial difficulty can feel like admitting failure, especially for parents who built their self-worth around providing for the family. That emotional layer complicates even the most practical discussion.

Avoid confrontations. Instead of demanding numbers, express concern about long-term stability and future planning. Suggest collaborative steps, such as organizing important documents, updating wills, or creating a durable power of attorney for finances. These actions protect everyone involved and do not require a crisis to justify them.

If cognitive decline raises concerns, consider a medical evaluation. Financial missteps sometimes signal early memory issues, and catching them early can protect assets. Professional guidance from elder law attorneys or financial advisors can also clarify legal protections and prevent further damage.

4 Signs Your Parents May Be Hiding a Financial Crisis
Image Source: Pexels.com

The Wake-Up Call That Strengthens Families

Financial strain in later years does not have to end in disaster. Early awareness creates room for thoughtful planning, practical solutions, and honest conversations that strengthen trust rather than erode it. Families who act with compassion and clarity often discover that the situation feels less catastrophic than it first appeared.

Start small. Offer help with organizing accounts, explore community resources, and encourage professional advice when necessary. Maintain dignity at every step. Parents who feel respected and included in decisions are far more likely to accept support.

What signs have stood out in your own family when it comes to financial stress? We want to hear all of the advice you have to share in our comments section below.

You May Also Like…

The Federal Reserve Rate Cut That Did Nothing for Credit Card Holders

IRS Changes for Seniors: What’s Actually New on the 1040‑SR for 2026

Why More Seniors Are Getting Surprise Social Security Overpayment Notices

Waiting on Social Security? Why Thousands of Retirees Are Stuck in Payment Limbo Right Now

The Retirement Income Assumption That Breaks Down First During Inflation Cycles

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Finance Tagged With: aging parents, budgeting, Debt, elder care, family conversations, family finances, Financial Red Flags, financial warning signs, money management, Personal Finance, retirement planning, retirement security

Is Your “Little Treat” Habit Costing You $2,500 a Year? The Real Spending Math

March 3, 2026 by Brandon Marcus Leave a Comment

Is Your “Little Treat” Habit Costing You $2,500 a Year? The Real Spending Math
Image Source: Unsplash.com

A five-dollar habit does not feel like a financial turning point. It feels like a reward. It feels earned. And it feels small enough to ignore.

Yet run that same five dollars through a full year, and the numbers tell a different story. Add a few more “little” extras each week, and the total climbs fast enough to compete with a vacation, a credit card balance, or a serious dent in an emergency fund. The question is not whether small treats matter. The real question asks how much they actually cost when they show up every single day.

The $5 Illusion: Why Small Numbers Trick the Brain

A five-dollar coffee, a seven-dollar sandwich, a quick ten-dollar online order—none of these purchases trigger alarm bells on their own. Most people do not think in annual totals while standing in line or tapping a checkout button. The brain loves small numbers because they feel manageable and low risk.

Behavioral economists often talk about “mental accounting,” a concept popularized by Nobel Prize–winning economist Richard Thaler. People mentally sort money into different buckets, and they treat each bucket differently. A small daily expense slides into a harmless category labeled “treat” or “self-care.” That label lowers defenses.

The math does not care about labels. Spend $7 a day on coffee and snacks, and that equals $49 a week. Multiply that by 52 weeks, and the total hits $2,548 in a year. That figure does not include interest or potential investment growth. It simply reflects routine spending that felt minor in the moment.

Once numbers move from daily to annual, they suddenly demand attention. Two thousand five hundred dollars does not feel like a throwaway amount. It feels like tuition, rent, a plane ticket, or several months of groceries.

The Real Annual Breakdown: Let’s Do the Math

Start with a simple scenario. Imagine a $6 latte purchased five days a week. That equals $30 a week. Over a month, that reaches about $130. Over a year, that totals roughly $1,560.

Now add a $12 takeout lunch twice a week. That adds $24 weekly, or about $1,248 annually. Combine that with the latte habit, and the yearly total jumps to $2,808. No exaggeration. No dramatic rounding. Just straightforward multiplication.

Recent surveys show that households spend thousands of dollars annually on food away from home. That category includes coffee runs, fast-casual lunches, and last-minute takeout dinners. For many households, food away from home represents one of the largest flexible expenses in the budget.

Flexibility matters because flexible expenses offer room for change. Rent and insurance demand fixed payments. Daily treats leave room for choice. That does not mean cutting every joy. It means recognizing the scale of those joys over time.

The Comfort Trap: When Treats Turn Into Routine

A treat should feel occasional. When it turns into a daily ritual, it shifts from luxury to routine expense. Lifestyle inflation plays a role here. As income rises, spending often rises right along with it. That new job, that raise, that bonus—each milestone invites a small upgrade. A nicer coffee. A better lunch. Faster shipping. None of these changes feel reckless. Together, they reshape a budget.

Habits build quickly because repetition removes friction. The first $8 smoothie feels indulgent. The twentieth feels normal. Normal spending rarely sparks scrutiny.

That normalization explains why “little treat culture” gained traction online. Social media platforms like TikTok amplify the idea that small daily rewards protect mental health and boost motivation. While occasional rewards support well-being, daily spending without limits can quietly crowd out bigger goals.

What $2,500 Could Actually Do Instead

Two thousand five hundred dollars holds real power when redirected with purpose. Place $2,500 into a high-yield savings account earning 4 percent annual interest, and that money generates about $100 in interest over a year without additional contributions. Invest $2,500 in a diversified index fund averaging a historical annual return of around 7 percent after inflation, and that amount could grow to roughly $4,900 in ten years, assuming no additional deposits and steady returns. Markets fluctuate, and returns never come guaranteed, but long-term growth historically rewards consistency.

That same $2,500 could wipe out high-interest credit card debt. Many credit cards charge interest rates above 20 percent. Paying down a $2,500 balance at 20 percent interest saves hundreds of dollars in future interest payments.

The number also covers a solid emergency fund starter. Many financial planners recommend saving three to six months of essential expenses. A $2,500 cushion can prevent a job loss or medical bill from turning into long-term debt.

Is Your “Little Treat” Habit Costing You $2,500 a Year? The Real Spending Math
Image Source: Unsplash.com

How to Keep the Joy Without Losing the Cash

Eliminating every small pleasure often backfires. Extreme restriction leads to burnout, and burnout leads to splurges that undo progress. Balance works better than deprivation.

Start by tracking spending for one month. Use a budgeting app or a simple spreadsheet. Write down every coffee, snack, and impulse purchase. Awareness alone often reduces spending because it removes the illusion of smallness. Next, set a monthly “treat fund.” Allocate a fixed amount—maybe $100 or $150—and spend it guilt-free. Once that fund runs out, pause until the next month. This strategy keeps joy in the budget while protecting long-term goals.

Experiment with swaps. Brew coffee at home four days a week and buy one café drink as a weekly ritual. Pack lunch three days a week and enjoy one intentional takeout meal. Small adjustments maintain pleasure without draining thousands annually.

A Quick Reality Check on “It’s Just $5”

Five dollars feels harmless because it does not threaten immediate survival. Yet scale changes meaning. Five dollars a day equals $35 a week, $182 a month, and $1,825 a year. Increase that daily amount to $8, and the annual total climbs to $2,920. This math does not argue against comfort. It argues for conscious choice.

Every dollar spent daily locks in a pattern. Every dollar redirected reshapes a future balance sheet. Personal finance rarely hinges on one dramatic decision. It builds on repeated behavior.

Financial experts consistently emphasize that small, consistent actions drive long-term results. Regular investing, steady saving, and controlled spending outperform sporadic grand gestures. The same principle applies in reverse. Small, consistent overspending erodes progress more effectively than one big splurge.

Tiny Choices, Big Totals

Small purchases carry big consequences when they repeat daily. A few dollars here and there can quietly total thousands over twelve months, enough to fund savings, reduce debt, or build real security. No one needs to abandon joy or live on strict austerity. Thoughtful limits and clear goals create room for both pleasure and progress.

Take a close look at the last 30 days of spending. Add up every “small” indulgence. Does that total surprise you, or does it confirm what you suspected all along? Let’s share our financial findings in the comments below.

You May Also Like…

6 Reasons Middle-Class Budgets Are Breaking Under “Slow Inflation”

7 Budget Foods Americans Rely On That Doctors Say Create Bigger Problems Later

Modern Taxation Explained: Filing, Records, and Savings

The “Safe” Budget Rules That Quietly Stop Working After Age 60

5 Budgeting Tools That Trick You Into Higher Spending

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Spending Habits Tagged With: Budgeting Tips, coffee spending, financial goals, Financial Wellness, frugal living, impulse buying, Lifestyle Inflation, money management, Personal Finance, saving money, smart shopping, Spending Habits

Stop Using the 50/30/20 Rule — Here’s What’s Not Working in 2026

March 3, 2026 by Brandon Marcus Leave a Comment

Stop Using the 50/30/20 Rule — Here’s What’s Not Working in 2026
Image Source: Pexels.com

The 50/30/20 rule had a good run. It felt clean, organized, and reassuring in a world that seemed manageable on a spreadsheet. Split income into needs, wants, and savings. Stay disciplined. Build wealth. Easy. But 2026 laughs at tidy pie charts.

Housing costs swallow paychecks in many cities. Grocery bills jump without warning. Insurance premiums creep up. Student loan payments restart and shift. Healthcare expenses stretch budgets thin. The neat little formula that once felt empowering now leaves too many people feeling like they failed at math instead of recognizing that the math changed.

The 50/30/20 rule, popularized by Elizabeth Warren and her daughter in the book All Your Worth, helped millions rethink spending priorities. It pushed people to cap essentials at 50 percent, enjoy 30 percent, and save 20 percent. The structure brought clarity. The simplicity made it sticky.

When “Needs” Blow Past 50 Percent

The biggest flaw in 2026 comes down to one word: housing. In many metropolitan areas across the United States, rent alone consumes 35 to 50 percent of take-home pay. Add utilities, transportation, insurance, and groceries, and that 50 percent cap on “needs” collapses before the month even starts. No one overspent on lattes. No one splurged on concert tickets. The budget just never stood a chance.

Inflation over the past several years reshaped everyday expenses. Even though inflation rates cooled compared to their peak in 2022, prices for essentials like food, rent, and auto insurance remain elevated relative to pre-2020 levels. Wages increased in some sectors, but they did not rise evenly or fast enough to match cost-of-living spikes everywhere.

When needs hit 60 or 65 percent of income, the 50/30/20 rule labels that situation as failure. That framing hurts more than it helps. A budgeting system should reflect reality, not shame it.

Instead of forcing needs into an outdated box, track fixed and variable essentials separately. Break down housing, transportation, food, and insurance line by line. Then look for strategic adjustments. Consider refinancing insurance policies. Explore roommate options. Evaluate relocation if job flexibility allows. The key involves analyzing specifics, not clinging to an arbitrary ceiling.

The 20 Percent Savings Target Feels Unrealistic for Many

Saving 20 percent of income sounds admirable. Financial planners still recommend aggressive saving rates for retirement and emergencies. The math behind compound growth supports that advice. But here’s the problem: many households cannot consistently hit 20 percent without sacrificing stability.

Emergency savings alone require three to six months of essential expenses. In high-cost areas, that fund could equal tens of thousands of dollars. Add retirement contributions, health savings accounts, and debt repayment, and the 20 percent slice often falls short of what financial security truly demands—or feels impossibly high for those juggling debt and rising expenses.

The 50/30/20 rule treats savings as one tidy bucket. Real life divides savings into layers. Emergency funds serve one purpose. Retirement investments serve another. Short-term goals like a down payment or relocation require separate strategies.

Instead of locking into 20 percent, adopt a priority ladder. First, build a starter emergency fund of at least $1,000 to cover unexpected shocks. Next, capture any employer 401(k) match, since that match delivers immediate returns. Then attack high-interest debt, especially credit cards with rates above 20 percent. After stabilizing those areas, increase retirement contributions gradually toward 15 percent or more over time. Flexibility wins.

The 30 Percent “Wants” Category Creates False Guilt

The “wants” category causes more confusion than clarity in 2026. Streaming subscriptions, gym memberships, dining out, vacations, hobbies, and tech upgrades all land here. But some expenses blur the line between need and want. Reliable internet supports remote work. A decent smartphone enables banking, job searches, and two-factor authentication. Mental health activities protect productivity and stability.

Rigidly labeling 30 percent for wants can push people into guilt spirals. Spend 32 percent on lifestyle choices, and the formula signals irresponsibility. But financial health depends on sustainability. Budgets that squeeze out all enjoyment tend to collapse.

Rather than fixating on a percentage, measure lifestyle spending against personal values and long-term goals. Track discretionary spending for three months. Identify which purchases delivered real satisfaction and which faded quickly. Then cut the low-impact expenses without apology. Keep the meaningful ones.

Stop Using the 50/30/20 Rule — Here’s What’s Not Working in 2026
Image Source: Pexels.com

Income Volatility Breaks the Formula

The 50/30/20 rule assumes stable income. That assumption no longer fits a workforce shaped by freelancing, gig platforms, contract roles, and variable bonuses. Many households manage fluctuating paychecks month to month. In those situations, percentage-based budgets tied to each paycheck feel chaotic. A high-earning month creates false confidence. A low-earning month triggers panic.

Instead, build a baseline budget around the lowest reliable monthly income. Cover fixed essentials with that number. During higher-income months, direct surplus funds toward savings buffers, debt reduction, and future tax obligations.

Freelancers and gig workers benefit from maintaining a separate tax savings account and calculating estimated quarterly taxes carefully. Irregular income demands proactive planning, not static ratios.

The Rule Ignores Debt Reality in 2026

Credit card balances remain elevated nationwide, and average interest rates exceed 20 percent in many cases. Student loan repayment structures shifted again after pandemic pauses ended. Auto loans stretch longer than ever, often reaching six or seven years.

The 50/30/20 rule does not prioritize debt strategy. It lumps debt repayment into “needs” or “savings” depending on interpretation. That ambiguity weakens its usefulness.

High-interest debt acts like a financial emergency. Paying minimums while allocating 30 percent to lifestyle spending rarely makes sense when interest compounds aggressively. A more effective framework emphasizes debt hierarchy. Pay minimums on all debts. Direct extra cash toward the highest-interest balance first. After eliminating toxic debt, reallocate those payments toward savings and investments.

Retirement Math Changed

Longer life expectancy and rising healthcare costs demand stronger retirement planning. Social Security replaces only a portion of pre-retirement income for most workers. Market volatility reminds investors that growth never moves in a straight line.

A flat 20 percent savings rule does not account for age, starting point, or goals. Someone beginning retirement savings at 22 faces a different path than someone starting at 42.

Modern financial planning requires customized projections. Use reputable retirement calculators from major brokerage firms or nonprofit financial education organizations. Factor in expected Social Security benefits based on current estimates. Adjust contributions annually.

A Better Approach for 2026: Adaptive Budgeting

So what works now? Start with a zero-based mindset. Assign every dollar a job before the month begins. Cover essentials first. Fund emergency savings. Contribute to retirement at least up to any employer match. Tackle high-interest debt aggressively. Allocate lifestyle spending intentionally, not automatically.

Review spending monthly. Adjust categories based on real data, not aspirations. Increase savings percentages gradually as income grows. During raises or bonuses, direct at least half of the increase toward financial goals before upgrading lifestyle.

Build flexibility into the system. Economic conditions shift. Personal priorities evolve. Income changes. A good budget bends without breaking.

Rewrite the Rulebook, Don’t Worship It

The 50/30/20 rule introduced millions to intentional money management, and that achievement deserves credit. But 2026 demands more nuance, more personalization, and more realism.

Rigid formulas ignore rising housing costs, volatile income streams, complex debt burdens, and evolving retirement needs. Financial stability grows from adaptability, awareness, and consistent adjustments.

What changes would make a budgeting system finally feel realistic instead of restrictive to you? Let’s talk about it in our comments below.

You May Also Like…

6 Reasons Middle-Class Budgets Are Breaking Under “Slow Inflation”

7 Budget Foods Americans Rely On That Doctors Say Create Bigger Problems Later

The Retirement Budget Trap: Why Expenses Spike Between Ages 62 and 70

10 Budget Mistakes That Create Long-Term Pressure

Why Are Everyday Essentials Taking Up More of the Budget

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Personal Finance Tagged With: 50/30/20 rule, Budgeting Tips, Cost of living, debt payoff, financial independence, inflation 2026, investing basics, money management, Personal Finance, Planning, saving strategies, Smart Spending

  • « Previous Page
  • 1
  • …
  • 110
  • 111
  • 112
  • 113
  • 114
  • …
  • 157
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba
  • How Can I Get Rid of Wells Fargo PMI on My Home Loan? by Tamila McDonald
  • Is It Safe to Throw Away Bank Statements? by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework