• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Personal Finance

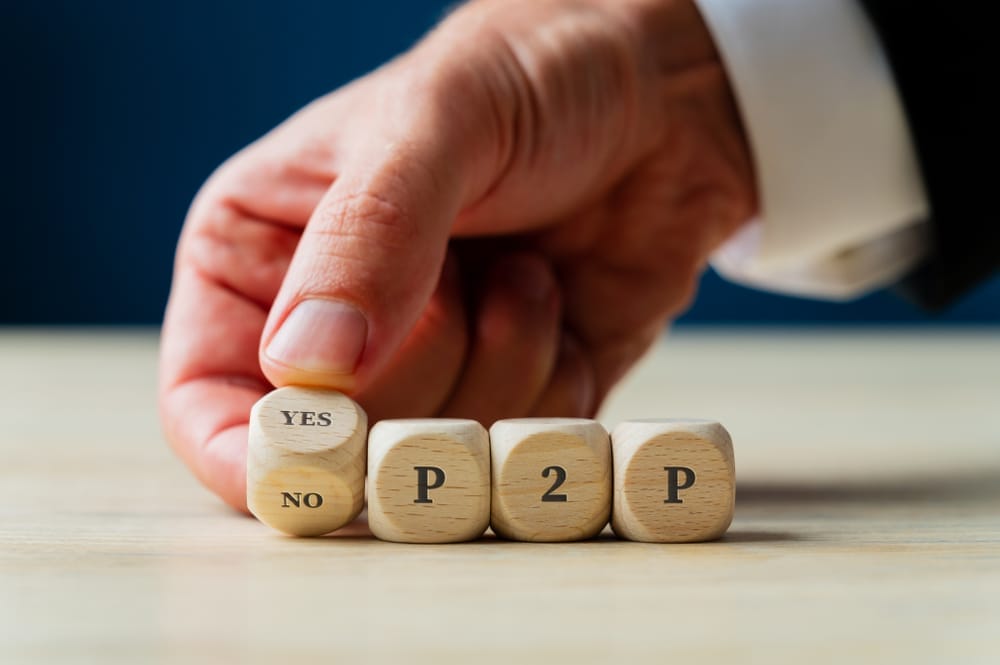
7 Honest Assessments of Peer-to-Peer Lending Platforms Today

October 26, 2025 by Travis Campbell Leave a Comment

p2p lending
Image source: shutterstock.com

Peer-to-peer lending platforms have changed how people borrow and invest. They connect borrowers directly with investors, cutting out traditional banks. This can mean better rates and more options for both sides. But with more choices comes more responsibility. Not all platforms are the same, and knowing what to expect is crucial. If you’re thinking about using peer-to-peer lending platforms, honest assessments can help you make informed decisions.

1. Accessibility for Borrowers and Investors

One of the biggest draws of peer-to-peer lending platforms is how easy they are to use. You can often apply for a loan or start investing with just a few clicks. Most sites have simple sign-up processes and transparent fee structures. This is a welcome change compared to the paperwork and waiting times at banks. However, easy access doesn’t guarantee approval. Borrowers still need to meet certain credit standards, and investors should be aware that not all loans are low risk.

2. Risk and Reward Trade-Offs

Peer-to-peer lending platforms offer the potential for higher returns than traditional savings accounts or CDs. But these higher returns come with higher risks. There’s always a chance that borrowers may default on their loans. Some platforms have reserve funds or buyback guarantees, but these protections are not foolproof. Investors should diversify their portfolios and be prepared for the possibility of losses. It’s essential to understand the balance between risk and reward before committing money.

3. Transparency Varies by Platform

Not all peer-to-peer lending platforms are equally transparent. Some provide detailed information on borrowers, loan performance, and default rates. Others are less forthcoming. Transparency helps investors make better decisions and builds trust. Before signing up, review how much information the platform shares. The more open a platform is about its track record and fees, the better for everyone involved.

4. Fees Can Eat Into Returns

While peer-to-peer lending platforms can be cost-effective, fees still apply. These might include origination fees for borrowers or service fees for investors. Fees vary widely from platform to platform, and they can add up over time. Some sites are upfront about their charges, while others may have hidden costs. Always read the fine print and factor fees into your expected returns. It’s one of the most honest assessments you can make before investing.

5. Loan Quality and Screening Processes

Loan quality is a key factor in peer-to-peer lending platforms. Some sites have strict credit checks and thorough vetting processes. Others may accept riskier borrowers to boost volume. This directly impacts the likelihood of defaults. As an investor, look for platforms that disclose their screening methods. Higher loan quality usually means lower default rates, but also potentially lower returns. Decide what balance works for your risk tolerance.

6. Regulatory Oversight Is Still Evolving

The peer-to-peer lending industry is relatively new, and regulations are still catching up. In some countries, oversight is strong. In others, it’s minimal. Regulatory changes can affect how platforms operate and how safe your investments are. Stay updated on the latest news and be cautious of platforms operating in loosely regulated environments.

7. Customer Support and User Experience

Good customer support can make a big difference, especially if you’re new to peer-to-peer lending platforms. Some sites offer live chat and quick responses, while others are slow or hard to reach. User experience also matters—clear dashboards and easy navigation help you track your investments or loan status. Take time to try out demo accounts or read reviews to gauge support quality. A positive user experience can save you time and stress down the line.

Making Smart Choices with Peer-to-Peer Lending Platforms

Peer-to-peer lending platforms have opened new doors for both borrowers and investors. They offer flexibility, transparency (on the best sites), and the chance for higher returns. But they also come with risks, fees, and a learning curve. Before diving in, compare platforms carefully and understand their features. Read honest assessments, check regulatory updates, and talk to other users if possible.

Have you tried peer-to-peer lending platforms? What was your experience like? Share your thoughts or questions in the comments below!

What to Read Next…

  • The Benefits of Taking Personal Loans and Their Impact on Credit Scores
  • 7 Credit Card Features Disappearing Without Any Notice
  • 9 Surprising Penalties for Paying Off Loans Too Early
  • 7 Financial Loopholes That Lenders Exploit Behind the Scenes
  • What Are Banks Really Doing With Your Personal Spending Data?
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.
Filed Under: Investing Tagged With: borrowing, investing, peer-to-peer lending, Personal Finance, platform reviews, Risk management

Is Estate Planning The Only Way To Preserve Your Legacy?

October 25, 2025 by Catherine Reed Leave a Comment

Is Estate Planning The Only Way To Preserve Your Legacy?
Image source: shutterstock.com

When people think about leaving something behind for their loved ones, estate planning often comes to mind first. A will, a trust, or beneficiary designations seem like the key tools for protecting wealth and ensuring assets are handled properly. But preserving your legacy involves more than just documents and legal structures—it’s about passing on values, traditions, and financial habits that last for generations. While estate planning provides a foundation, there are many other ways to ensure that what truly matters to you lives on.

The Financial Foundation of Estate Planning

Estate planning is the backbone of legacy protection because it clearly outlines how assets will be distributed after death. It prevents confusion, family disputes, and unnecessary legal costs while making sure your intentions are honored. Through wills, trusts, and power of attorney designations, families can secure their financial future and reduce stress during an already emotional time. Without these tools, even well-meaning heirs can find themselves entangled in probate or disagreements over property. In this sense, estate planning isn’t just about wealth—it’s about peace of mind.

Teaching Financial Literacy to the Next Generation

Beyond estate planning, one of the most impactful ways to preserve your legacy is through financial education. Children who understand money management are more likely to protect and grow what they inherit. Teaching budgeting, saving, and investing skills ensures your hard-earned wealth doesn’t disappear within a generation. Many families lose their financial stability not because of bad luck, but because future generations weren’t prepared to handle it responsibly. Passing on financial literacy can be as valuable as passing on money itself.

Building a Legacy Through Philanthropy

Charitable giving is another powerful complement to estate planning. Creating a scholarship, supporting a cause, or setting up a charitable trust allows your influence to extend far beyond your lifetime. These gestures show future generations that legacy isn’t just about wealth—it’s about making a difference in the world. Philanthropy can also be an opportunity to involve children and grandchildren in meaningful decision-making. By encouraging generosity, you instill values that reflect your life’s priorities while creating a positive impact for others.

Preserving Family Stories and Traditions

Financial assets can be replaced, but personal stories and family traditions are priceless. Preserving them is another essential part of legacy building beyond estate planning. Writing memoirs, recording family histories, or maintaining photo archives keeps your heritage alive for future generations. These efforts help children understand where they come from and strengthen family bonds over time. A well-documented legacy of values and experiences can provide more emotional security than any inheritance alone.

Creating Intergenerational Experiences

Experiences often leave stronger memories than financial gifts. Families who prioritize shared experiences—like vacations, reunions, or service projects—build a legacy of connection and belonging. These gatherings reinforce the values and relationships that money alone can’t sustain. Even small traditions, like weekly dinners or annual get-togethers, can carry immense significance. While estate planning focuses on the future, investing in shared experiences ensures your family feels united in the present.

Investing in Family-Owned Businesses or Projects

For families with entrepreneurial roots, continuing a business or funding new ventures can be an effective way to preserve a legacy. Estate planning helps structure ownership and succession, but active mentorship and involvement matter just as much. Guiding younger generations through the responsibilities of leadership creates continuity and purpose. It also allows your principles—like hard work, integrity, and innovation—to live on in tangible form. A thriving family enterprise can serve as both financial security and a symbol of shared accomplishment.

The Emotional Side of Legacy Preservation

While estate planning covers logistics, emotional legacy preservation focuses on communication and connection. Writing letters to loved ones, sharing life lessons, or recording personal reflections helps bridge emotional gaps after you’re gone. These gestures allow your loved ones to feel supported and guided, even when you’re no longer physically present. Many families underestimate how comforting a few words of wisdom can be for future generations. A legacy rooted in love and understanding lasts far longer than one based solely on money.

True Legacy Extends Beyond Paperwork

Estate planning is essential, but it’s only one piece of a much larger puzzle. The real power of a legacy lies in how you live, what you teach, and the relationships you nurture. Combining a solid estate plan with emotional, educational, and philanthropic efforts ensures that your impact endures in every sense. By thinking holistically about your legacy, you can create something far greater than financial stability—you can create meaning that lives on through the people you love.

How do you want your legacy to be remembered—through financial stability, shared values, or both? Share your thoughts in the comments below!

What to Read Next…

  • Protect Your Legacy by Drafting a Simple, Legal Will This Weekend
  • 8 Legacy Plans That Fail When Heirs Aren’t Informed
  • 10 Overlooked Financial Questions That Can Ruin Your Legacy
  • Leave A Purposeful Legacy: 7 Strategies to Guide You In Your Philanthropic Financial Planning
  • 11 Essential Items for Your Financial Binder Documentation Kit
Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.

Filed Under: Estate Planning Tagged With: Estate planning, family legacy, financial literacy, generational wealth, legacy building, Personal Finance, wills and trusts

Generate Extra Monthly Cash Flow Starting With These Side Hustle Ideas

October 25, 2025 by Catherine Reed Leave a Comment

Generate Extra Monthly Cash Flow Starting With These Side Hustle Ideas
Image source: shutterstock.com

With inflation, rising rent, and unpredictable expenses, many people are looking for ways to create extra monthly cash flow. Whether you want to pay off debt, build an emergency fund, or simply have more spending freedom, a reliable side hustle can make a big difference. The beauty of today’s gig economy is that you don’t need a business degree or tons of startup money—just a bit of creativity and consistency. If you’re ready to take control of your finances and put your spare time to good use, these side hustle ideas can help you start generating extra monthly cash flow right away.

1. Freelance Skills Online

One of the fastest ways to create extra monthly cash flow is to turn your professional skills into freelance income. Platforms like Upwork, Fiverr, and Freelancer let you offer writing, design, coding, or administrative services to clients worldwide. Even a few projects each month can generate hundreds of dollars, especially if you specialize in a niche. The flexibility of freelancing makes it perfect for evenings, weekends, or any schedule that fits your lifestyle. As you build a reputation, you can increase your rates and establish a steady stream of extra income.

2. Rent Out What You Already Own

Creating extra monthly cash flow doesn’t always require hard labor—sometimes, it’s about maximizing what you already have. If you own a car, you can list it on apps like Turo or HyreCar when it’s not in use. Spare rooms can be rented on Airbnb, and even tools or equipment can earn cash through local rental platforms. These assets often sit idle but have real earning potential when shared responsibly. This passive-style income allows you to generate profit with minimal daily effort.

3. Deliver or Drive on Your Own Schedule

If you enjoy being on the move, delivery services are a reliable way to boost monthly cash flow. Companies like DoorDash, Uber Eats, and Instacart let you set your own hours while earning per delivery. Drivers often make extra tips, and high-demand times like weekends can increase earnings quickly. You can also drive for rideshare companies like Uber or Lyft if you prefer passenger transport. It’s a simple, flexible way to monetize your free time while maintaining control over when you work.

4. Sell Handmade or Vintage Items

For creative or thrifty individuals, turning hobbies into income is an excellent way to build extra monthly cash flow. Selling handmade jewelry, crafts, or artwork on Etsy—or flipping vintage finds on eBay or Poshmark—can be surprisingly profitable. The key is to focus on what you enjoy making or collecting, so it doesn’t feel like a chore. Social media platforms can help you promote your products and attract loyal customers. Over time, even a modest side shop can evolve into a dependable income stream.

5. Offer Tutoring or Teaching Services

If you have expertise in a subject, tutoring can be both rewarding and profitable. Parents are often eager to pay for academic help, especially in math, science, or language skills. Online teaching platforms like VIPKid, Wyzant, and Outschool make it easy to connect with students worldwide. Teaching music, art, or test prep can also generate a steady extra monthly cash flow. Beyond the money, tutoring allows you to share knowledge and make a meaningful impact on others’ success.

6. Manage Social Media for Small Businesses

Many local businesses know they need an online presence but lack the time or skills to manage it. If you’re familiar with Instagram, Facebook, or TikTok, offering social media management can create a strong extra monthly cash flow. You can help businesses post content, engage with followers, and run basic advertising campaigns. The demand for digital marketing help is growing, and even one or two clients can provide a consistent income. This side hustle blends creativity with business strategy, making it both fun and financially rewarding.

7. Start a Pet Sitting or Dog Walking Service

Animal lovers can turn their affection for pets into a reliable side hustle. Apps like Rover and Wag connect pet owners with trusted walkers and sitters, allowing you to earn extra monthly cash flow while spending time with furry companions. This type of work is flexible and often less stressful than traditional jobs. You can walk dogs during lunch breaks or care for pets overnight while their owners travel. Building a reputation in your local community can lead to repeat clients and referrals.

Turning Spare Time Into Financial Freedom

Finding creative ways to build extra monthly cash flow can be a game changer for your financial goals. Whether it’s freelancing, tutoring, or renting assets, each option helps diversify your income and reduce financial stress. The secret is to start small, stay consistent, and reinvest your earnings wisely—perhaps toward debt, savings, or new opportunities. With time, your side hustle could become more than just a backup plan; it could become a gateway to long-term financial independence.

Which of these side hustle ideas sounds most realistic for your lifestyle? Share your favorite ways to earn extra monthly cash flow in the comments below!

What to Read Next…

  • 7 Income Streams You’d Laugh At—Until They Out-earned Your Salary
  • 6 Income Sources People Don’t Try But Should
  • 7 Unconventional Ideas for Earning Extra Income Reliably
  • 6 Financial Dangers of Relying on One Income
  • Is It Really Passive Income: 5 Lies About Making Money While You Sleep
Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.

Filed Under: side hustles Tagged With: budgeting advice, cash flow ideas, extra income, financial freedom, money tips, Personal Finance, side hustles

What Happens When You Don’t Have Enough Money To Get Through Retirement

October 25, 2025 by Catherine Reed Leave a Comment

What Happens When You Don't Have Enough Money To Get Through Retirement
Image source: shutterstock.com

For many people, retirement is imagined as a reward for years of hard work—a time to relax, travel, and enjoy life without financial stress. But for others, the reality can be much different. If you don’t have enough money to get through retirement, the dream can quickly turn into daily anxiety about bills, medical costs, and long-term stability. Understanding what can happen when retirement savings fall short is the first step toward preparing and protecting your future. Here’s what to expect—and what you can do to change course before it’s too late.

The Risk of Outliving Your Savings

One of the most common challenges people face when they do not have enough money to get through retirement is simply running out of funds too soon. Increased life expectancy means that retirees often need savings that can last 20 to 30 years, but many underestimate how long their money must stretch. Once retirement accounts are depleted, individuals often must rely on Social Security alone, which rarely covers full living expenses. This financial strain can lead to difficult choices about housing, healthcare, and lifestyle. Planning for longevity—not just the short term—is essential to avoid this painful reality.

The Strain of Rising Healthcare Costs

Healthcare is one of the biggest financial burdens for those who do not have enough money to get through retirement. Even with Medicare, out-of-pocket expenses for prescriptions, long-term care, and specialized treatments can quickly drain limited resources. Unexpected medical issues often lead retirees to dip into emergency savings or take on debt. Some may even delay essential care or skip medications to save money. Creating a realistic healthcare budget and considering supplemental insurance can make a critical difference in financial stability.

The Challenge of Maintaining Housing and Independence

When you do not have enough money to get through retirement, housing becomes one of the most immediate concerns. Many retirees face the prospect of downsizing, relocating, or relying on family members for help. Rising rent and property taxes can make staying in a longtime home unsustainable. Even for homeowners, maintenance costs and utilities can add up fast. Proactive planning—such as paying off a mortgage early or moving to a lower-cost area—can help preserve independence without sacrificing comfort.

The Emotional Toll of Financial Stress

The financial pressure of realizing you may not have enough money to get through retirement can be emotionally devastating. Worrying about bills, unexpected expenses, or becoming a burden to loved ones can take a serious toll on mental health. Many retirees experience anxiety, guilt, or even depression as financial challenges mount. These feelings are compounded by the sense of losing control after decades of independence. Seeking financial guidance early—and discussing concerns openly—can help reduce stress and create a more confident plan for the future.

The Need to Return to Work After Retiring

A growing number of retirees are reentering the workforce because they do not have enough money to get through retirement. While some enjoy the social and mental benefits of part-time work, others return out of financial necessity. Finding suitable employment can be difficult for older adults facing health issues or age discrimination. However, flexible jobs, consulting roles, and remote work opportunities are becoming more accessible. Earning supplemental income can help bridge the gap while preserving savings and maintaining a sense of purpose.

The Importance of Adjusting Your Lifestyle

When savings fall short, making lifestyle adjustments is often unavoidable. People who do not have enough money to get through retirement may need to cut back on travel, dining out, or entertainment. While these changes can feel discouraging, small adjustments can have a big impact over time. Prioritizing essential expenses and reducing nonessential costs can help stretch available funds further. Financial advisors can help retirees develop sustainable budgets that preserve quality of life without jeopardizing long-term security.

How to Regain Financial Control Before It’s Too Late

Even if you realize you may not have enough money to get through retirement, there are ways to take back control. The first step is to evaluate your current spending, debt, and income sources to identify where adjustments can be made. Consider delaying retirement, maximizing Social Security benefits, or exploring part-time work options to supplement income. Downsizing housing or moving to a lower-cost region can also provide lasting financial relief. The key is to act early and seek professional advice rather than waiting for circumstances to worsen.

Have you considered what would happen if your savings didn’t last through retirement? What steps are you taking now to secure your future? Share your thoughts in the comments below!

What to Read Next…

  • 9 Hidden Retirement-Plan Mistakes That Can Cost You Tens of Thousands
  • 12 Distinctive Advantages of Self-Directed Retirement Accounts
  • Is It Too Late to Start Saving Aggressively for a Comfortable Retirement?
  • 13 Secret Worries About Retirement That Keep You Awake at Night
  • 7 Surprising Expenses Nobody Expects After Retirement
Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.

Filed Under: Retirement Tagged With: Budgeting Tips, Financial Security, money management, Personal Finance, retirement planning, retirement savings, senior living

4 Quick Guides to Understanding Complex Annuity Contracts Better

October 25, 2025 by Travis Campbell Leave a Comment

Annuity
Image source: shutterstock.com

Retirement planning brings a mix of hope and uncertainty. For many, annuities seem like a reliable solution to ensure a steady income stream later in life. But when you start reading the fine print, you might realize that complex annuity contracts are, well, complex. Terms like surrender charges, riders, and guaranteed minimums can make your head spin. Getting clear on these details is crucial because mistakes in choosing or managing an annuity can be costly and hard to fix. This guide breaks down the key aspects of complex annuity contracts, so you can make informed decisions and feel more confident about your financial future.

1. Know the Types: Fixed, Variable, and Indexed Annuities

The first step in understanding complex annuity contracts is knowing the main types. Fixed annuities offer predictable returns and stable payments, making them attractive for conservative investors. Variable annuities, on the other hand, let you invest in sub-accounts similar to mutual funds. Returns will fluctuate with the market, so your payments can vary. Indexed annuities split the difference: returns are linked to a market index, like the S&P 500, but typically offer downside protection.

Each type has its own risk profile, return potential, and set of fees. Complex annuity contracts often combine features from these types or offer extra options (called riders) for things like long-term care or enhanced death benefits. Before signing anything, ask yourself: Do you want guaranteed income, or are you willing to trade some certainty for the chance at higher returns?

2. Understand Surrender Charges and Liquidity Limits

Surrender charges are one of the trickiest parts of complex annuity contracts. If you withdraw money during the contract’s surrender period—usually the first 5 to 10 years—you’ll pay a hefty penalty. These charges often start high (sometimes 7% or more) and decrease each year. The goal is to discourage early withdrawals, but it can also tie up your money longer than you expect.

Liquidity restrictions don’t stop at surrender charges. Many contracts only let you withdraw a small percentage (often 10%) each year without penalty. If you need access to your funds in an emergency, these rules can be a problem. Make sure you understand exactly how much flexibility you have before committing to a complex annuity contract.

3. Decode Riders and Optional Features

Riders are extra features you can add to complex annuity contracts for an additional cost. Common riders include guaranteed lifetime withdrawal benefits, long-term care coverage, or enhanced death benefits. These options can add real value, but they also make your contract more expensive and harder to understand.

For example, a guaranteed income rider can lock in a minimum payout for life, even if your investments perform poorly. But fees for these riders can eat into your returns. Read the fine print and do the math: Are you paying more in fees than you’re likely to gain in benefits? Ask questions and don’t hesitate to seek an independent opinion.

4. Watch the Fees and Understand Tax Implications

Fees in complex annuity contracts can be easy to overlook, but they can have a huge impact on your returns. You’ll typically see mortality and expense charges, administrative fees, investment management fees (for variable annuities), and costs for any riders. These can add up quickly, sometimes totaling 2% to 4% or more each year.

Taxes are another key factor. While your money grows tax-deferred inside an annuity, withdrawals are taxed as ordinary income—not at the lower capital gains rate. If you withdraw funds before age 59½, you could face an additional 10% IRS penalty. Understanding these rules helps you avoid surprises and plan smarter for retirement.

Making Sense of Complex Annuity Contracts

Complex annuity contracts can be intimidating, but taking the time to break down their features pays off. By understanding the basic types, liquidity limits, riders, and fee structures, you’ll be better equipped to choose an annuity that fits your goals. Remember, no contract is one-size-fits-all. Your needs and risk tolerance are unique, so what works for your neighbor may not work for you.

When in doubt, consult a financial advisor who can explain the details and help you compare options. It’s your retirement, and you deserve clarity and confidence when making decisions about complex annuity contracts.

Have you ever considered or purchased an annuity? What questions or concerns do you have about these contracts? Share your thoughts in the comments below!

What to Read Next…

  • 10 Annuity Clauses That Lock You Out Of Future Changes
  • 6 Ways Inflation Is Secretly Eating At Your Annuity Payouts
  • Are Lifetime Guarantees On Financial Products Too Good To Be True?
  • 10 Financial Questions That Could Undo Your Entire Retirement Plan
  • How Financial Planners Are Recommending Riskier Portfolios In 2025
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.
Filed Under: Finance Tagged With: annuities, financial literacy, investment contracts, Personal Finance, retirement planning, tax strategies

7 Personal Money Questions Advisors Can’t Believe Are Real

October 25, 2025 by Travis Campbell Leave a Comment

Consulting money
Image source: shutterstock.com

Financial advisors hear a lot of questions, but some personal money questions are so surprising that they make even seasoned professionals pause. These queries highlight how complex—and sometimes misunderstood—personal finance can be. Asking the right questions leads to better decisions, but asking truly unusual ones can reveal gaps in financial education. By reviewing some of the most head-scratching personal money questions advisors encounter, you can avoid similar confusion and strengthen your own financial knowledge. Let’s look at seven personal money questions that seem too wild to be real, but have actually been asked.

1. Can I Retire If I Win the Lottery?

It’s tempting to dream about a sudden windfall, but this is one of those personal money questions that reveals wishful thinking more than planning. Many people believe that winning the lottery automatically means financial security for life. However, research shows that lottery winners often struggle to manage their newfound wealth and may even end up broke. Advisors have to gently explain that retiring after a lottery win depends on the payout, spending habits, taxes, and long-term planning. It’s not a guaranteed ticket to freedom—without a sound plan, the money can disappear faster than you think.

2. If I Marry Someone With Debt, Does It Become Mine?

This is a classic among personal money questions, and it’s rooted in confusion about how marriage and finances mix. In most cases, marrying someone with debt does not automatically make you responsible for what they owe. However, joint accounts, co-signed loans, or living in a community property state can change things. Advisors often find themselves explaining the difference between individual and shared debt. Understanding these details can prevent future financial headaches and surprises in your relationship.

3. Can I Write Off My Dog as a Dependent?

Pets are family, but the IRS doesn’t see it that way. Some clients genuinely ask if they can claim their dog, cat, or even goldfish as a dependent on their taxes. This personal money question might sound silly, but it’s more common than you’d think. The answer is no—only human dependents qualify for tax deductions. However, there are rare cases where pets can be considered business expenses, like for guard dogs or service animals. Still, for the average pet owner, Fido won’t help you at tax time.

4. Should I Take Out a Loan to Invest in Stocks?

This question pops up when people want to jump into the market quickly. Borrowing money to invest is risky, and most advisors strongly caution against it. The stock market is unpredictable, and using borrowed funds can magnify your losses. This is one of those personal money questions that shows a lack of understanding about risk and reward. Instead, focus on building an investment portfolio over time with money you can afford to lose. It’s safer and less stressful in the long run.

5. Is It Okay to Pay My Credit Card With Another Credit Card?

It sounds like a clever workaround, but paying off one credit card with another is a sign of trouble. This personal money question often comes from people struggling with debt. While balance transfers exist, they aren’t a magic fix. Shuffling balances around doesn’t solve the underlying issue of overspending or poor financial habits. Advisors encourage clients to create a plan for paying down debt, budgeting, and avoiding new charges. There’s no shortcut—real progress takes discipline.

6. Can I Avoid Taxes by Moving Money Overseas?

Some clients believe that stashing money in a foreign bank account will help them dodge taxes. This is one of the most alarming personal money questions advisors hear. Not only is it illegal to hide income offshore, but the IRS has strict reporting requirements for foreign accounts. Failing to comply can lead to hefty fines and even criminal charges. Instead of looking for loopholes, it’s best to work within the law and explore legal ways to reduce your tax burden.

7. If I Ignore My Student Loans, Will They Go Away?

This personal money question is more common than you might think, especially among recent graduates. Unfortunately, ignoring student loans won’t make them disappear—they’ll just grow larger with interest and penalties. Advisors stress the importance of communicating with loan servicers and exploring options like income-driven repayment or consolidation. Taking action early can prevent long-term damage to your credit.

Learning From Unbelievable Personal Money Questions

These personal money questions might seem unbelievable, but they highlight real misunderstandings about personal finance. By asking questions—no matter how strange—they open the door to learning and better decision-making. If you’re unsure about any aspect of your finances, don’t be afraid to reach out to a professional. The only bad question is the one you’re too embarrassed to ask. Take the time to educate yourself and avoid common pitfalls to build a stronger financial future.

What’s the most unusual personal money question you’ve ever heard—or asked? Share your story in the comments below!

What to Read Next…

  • 9 Things You Should Never Tell a Financial Planner
  • 10 Questions Bad Financial Advisors Are Afraid You May Ask Them
  • 8 Signs Your Financial Advisor Is Not Acting in Your Best Interest
  • 10 Financial Questions That Could Reveal You’re Being Advised Poorly
  • 7 Ill Advised Advisor Tips That Trigger IRS Audits
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.
Filed Under: Financial Advisor Tagged With: advisors, Debt, financial literacy, money questions, Personal Finance, Planning, taxes

11 Key Metrics to Analyze Before Buying Into Any ETF Option

October 25, 2025 by Travis Campbell Leave a Comment

ETF
Image source: shutterstock.com

Buying into an ETF option can be a smart way to diversify your investments, but not all ETFs are created equal. Before committing your money, it’s crucial to understand the key metrics that determine an ETF’s quality and suitability for your goals. These metrics go beyond just past performance; they shine a light on costs, risk, and how the ETF fits in your portfolio. Knowing what to look for can help you avoid costly mistakes and make more informed decisions. Whether you’re a beginner or a seasoned investor, analyzing these factors is essential for long-term success. Let’s break down the 11 key metrics you should check before buying into any ETF option.

1. Expense Ratio

The expense ratio is one of the most important numbers to look at when considering an ETF option. This percentage reflects the annual cost of managing the fund, deducted directly from your returns. Lower expense ratios mean more of your money stays invested and grows over time. Always compare the expense ratio of your chosen ETF to similar funds to ensure you’re not overpaying for management.

2. Tracking Error

Tracking error measures how closely the ETF follows its benchmark index. A low tracking error indicates that the ETF is doing a good job of mirroring its target. High tracking error may suggest issues with fund management or unexpected costs. For those who want predictable returns that match the index, tracking error is a critical metric when evaluating any ETF option.

3. Liquidity

Liquidity tells you how easily you can buy or sell shares of the ETF without affecting its price. Look at the average daily trading volume and bid-ask spread. Highly liquid ETFs are easier to trade at fair prices, while less liquid funds may have wider spreads and less favorable execution. Pay attention to this metric, especially if you plan to enter or exit positions quickly.

4. Underlying Holdings

Understanding what’s inside the ETF matters. Review the underlying holdings to make sure they align with your investment goals and risk tolerance. Some ETFs may hold hundreds of stocks, while others are more concentrated. Check for overlap with your existing portfolio to avoid unintended risks or concentration in certain sectors.

5. Assets Under Management (AUM)

Assets under management indicate the total amount of money invested in the ETF. Higher AUM usually means better liquidity and more stability, as large funds attract more investors and tighter bid-ask spreads. Be cautious with very small ETFs, as they may be at risk of closure or have trading difficulties.

6. Dividend Yield

If income is part of your strategy, check the dividend yield of the ETF option. This metric shows the annual income you can expect as a percentage of the share price. Compare yields across similar funds, but also consider the sustainability of those dividends. Chasing the highest yield isn’t always the best move if it comes with higher risk or volatility.

7. Historical Performance

While past performance doesn’t guarantee future results, it can provide context. Look at the ETF’s returns over different time frames and compare them to its benchmark and peers. Consistent outperformance or underperformance may signal something about the fund’s management or strategy. Just remember, don’t rely solely on this metric when evaluating an ETF option.

8. Sector and Geographic Exposure

Every ETF has a unique mix of sector and geographic exposure. Check where the fund invests, both by industry and by country. This helps you manage risk and ensure your overall portfolio isn’t too concentrated in one area. For example, a tech-focused ETF option may be riskier than a broad market fund, especially during sector downturns.

9. Fund Structure

ETFs can be structured in different ways—physically replicating the index or using derivatives (synthetic replication). Some are open-ended, while others are unit investment trusts or grantor trusts. The structure affects risks, tax treatment, and how the ETF operates. Make sure you understand how your chosen ETF option is built before investing.

10. Tax Efficiency

Tax efficiency measures how well the ETF minimizes taxable events for shareholders. Some ETFs are designed to avoid distributing capital gains, which can reduce your tax bill. Look into the fund’s history of capital gains distributions and its structure. Tax efficiency is especially important if you’re investing in a taxable account.

11. Issuer Reputation and Stewardship

The issuer’s reputation can affect how well the ETF is managed and whether it stands the test of time. Well-known issuers typically offer better transparency, robust risk controls, and reliable customer service. Check the provider’s track record and stewardship practices.

Putting It All Together Before You Buy an ETF Option

Evaluating an ETF option isn’t just about glancing at its chart or hunting for the highest recent returns. It means digging into these 11 key metrics and weighing them against your personal goals and risk tolerance. This approach helps you avoid surprises, reduce costs, and build a more resilient portfolio. The more you know about an ETF before you buy, the better your odds of long-term success.

Don’t be afraid to compare multiple funds and seek out additional resources. Take your time, ask questions, and remember that every metric offers a piece of the bigger picture.

What key metric do you always check before buying an ETF option? Share your thoughts or questions in the comments below!

What to Read Next…

  • Why ChatGPT May Be Generating Fake Financial Advice And Getting Away With It
  • How Financial Planners Are Recommending Riskier Portfolios In 2025
  • 7 Investment Loopholes That Can Be Closed Without Warning
  • Identifying Underpriced Stocks Using The Graham Formula
  • 10 Hidden Profit Sharing Clauses In Investment Products
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.
Filed Under: Investing Tagged With: ETF analysis, ETF option, investing basics, investment strategy, Personal Finance, portfolio management

6 Charges You’re Paying for… But Getting Nothing in Return

October 25, 2025 by Travis Campbell Leave a Comment

atm fees
Image source: shutterstock.com

When it comes to personal finance, every dollar counts. Yet, many of us are losing money to charges that offer absolutely nothing in return. These costs slip under the radar, quietly draining your bank account without providing any value. Understanding these unnecessary expenses is the first step toward smarter money management. By identifying and eliminating them, you can keep more of your hard-earned cash. Let’s take a closer look at six charges you’re paying for… but getting nothing in return.

1. Monthly Maintenance Fees on Checking Accounts

Monthly maintenance fees are one of the most common unnecessary charges. Banks often charge $5 to $15 per month just to keep your account open. In many cases, you get nothing extra for this fee—no better service, no higher interest, nothing. Some banks waive these charges if you meet certain requirements, like maintaining a minimum balance or setting up direct deposit. But if you’re paying this fee every month, it’s time to shop around. Many online banks and credit unions offer no-fee checking accounts with the same features, minus the cost. Stop letting money slip away for a service that should be free.

2. ATM Fees from Out-of-Network Withdrawals

Using an ATM outside your bank’s network can cost you $2 to $5 per transaction. Sometimes, both the ATM owner and your own bank charge a fee, doubling the pain. What do you get for this charge? Absolutely nothing extra—just access to your own money. These costs add up quickly, especially if you use cash often. To avoid this, use your bank’s locator tool to find fee-free ATMs or switch to a bank that reimburses out-of-network ATM fees. There’s no reason to pay for basic access to your cash.

3. Paper Statement Fees

Many banks and service providers now charge $2 to $5 a month for sending paper statements. This fee is often hidden in the fine print. In return, you get a piece of paper you might not even need. With secure digital statements available, there’s rarely a good reason to pay this charge. Opting for electronic statements not only saves you money but also helps the environment. If you still need a paper record, most institutions let you print statements from their website for free.

4. Credit Card Payment Protection Plans

Credit card issuers often pitch payment protection plans as a safety net if you lose your job or become ill. These plans can add up to $20 a month to your bill. But the reality is, most people never use them. Even if you do, the benefits can be hard to claim and are often limited. For the charge, you get peace of mind that may never pay off. Instead, consider building an emergency fund. It’s a more flexible, cost-effective way to protect yourself from financial setbacks.

5. Extended Warranties on Electronics

When you buy electronics, you’re often offered an extended warranty for an extra fee. Retailers push these hard because they’re big money-makers—for them, not you. Most products rarely break within the warranty period, and if they do, the manufacturer’s standard warranty usually covers it. So, this charge typically gives you nothing extra. Instead, check if your credit card offers free extended warranty protection. You can also self-insure by saving the money you’d spend on these plans.

6. Unused Subscription Services

Subscription services are everywhere—streaming, gym memberships, apps, and even meal kits. The average person pays for several subscriptions they rarely or never use. These recurring charges can quietly drain your budget, and you get nothing in return if you’re not actively using the service. Take a few minutes each month to review your bank statements and cancel anything you don’t need. Tools like subscription management apps can help you track and eliminate wasteful spending.

Take Control of Unnecessary Charges

Paying unnecessary charges is like throwing money out the window. Each of these fees—whether it’s monthly maintenance, ATM access, or unused subscriptions—chips away at your financial health. The good news? Most of these charges you’re paying for… but getting nothing in return are completely avoidable. With a little attention, you can spot these costs and cut them for good.

Take a close look at your statements this month. Where are you losing money for no real benefit? Cutting out these wasteful charges is one of the easiest ways to boost your savings and improve your personal finance habits. What hidden charges have you found and eliminated? Share your thoughts in the comments below!

What to Read Next…

  • 7 Hidden Fees That Aren’t Labeled As Fees At All
  • 6 Monthly Bills You Should Cancel Immediately Even If You Can Afford Them
  • Are These 7 Little Expenses Quietly Costing You Thousands A Year?
  • 8 Everyday Services That Are Slowly Becoming Subscription Only
  • Are Automatic Renewals Draining More Than You Realize?
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Finance Tagged With: bank fees, budgeting, money management, Personal Finance, savings, subscriptions, unnecessary charges

Review Your Estate Planning Documents and Update Beneficiaries Promptly

October 24, 2025 by Catherine Reed Leave a Comment

Review Your Estate Planning Documents and Update Beneficiaries Promptly
Image source: shutterstock.com

Estate planning isn’t something most people enjoy thinking about, but keeping your estate planning documents up to date is one of the smartest financial decisions you can make. Life changes quickly—marriages, divorces, births, deaths, and even new financial accounts can alter how your assets should be distributed. Yet, too many people set up a will or trust once and never revisit it. Neglecting updates can lead to unintended heirs, family disputes, or even lost assets. Reviewing your documents regularly and updating beneficiaries promptly ensures your legacy is handled exactly the way you want.

1. Life Events Can Outdate Your Estate Planning Documents Fast

Major life changes are the number one reason to revisit your estate plan. Marriage, divorce, or the birth of a child can dramatically shift how you want your assets distributed. If you fail to update your estate planning documents after these events, your old designations might not reflect your current wishes. For instance, an ex-spouse could still be listed as a beneficiary on an insurance policy, or a new child could be left out entirely. A quick review after each major life milestone prevents these kinds of heartbreaking oversights.

2. Beneficiary Designations Override Your Will

One of the most misunderstood aspects of estate planning documents is how beneficiary designations work. Even if your will states that assets should go to certain people, the designations on accounts like 401(k)s, IRAs, or life insurance policies take precedence. That means if an outdated beneficiary remains on file, those assets will go to them—no matter what your will says. Regularly confirming these details with your financial institutions can prevent serious conflicts later. Taking 15 minutes to check and update beneficiaries can save your family from years of frustration and legal challenges.

3. Outdated Estate Planning Documents Can Create Legal Complications

When estate planning documents are inconsistent or outdated, it can cause confusion for your executor and family members. Conflicting instructions between old wills, trusts, and financial accounts may require court intervention to resolve. This not only delays asset distribution but also adds unnecessary legal fees and emotional strain. By keeping your documents clear and updated, you simplify the process for your loved ones. Think of it as an act of care that saves your family stress during an already difficult time.

4. New Laws and Financial Rules May Affect Your Plan

Tax laws and estate regulations change more often than most people realize. If your estate planning documents haven’t been reviewed in five or ten years, they may no longer take advantage of current legal benefits. Updates to estate tax exemptions, retirement account rules, or state inheritance laws could change how your assets are handled. Working with an attorney or financial planner to periodically review your plan ensures you stay compliant and maximize protection. Staying proactive keeps your estate plan aligned with both your personal goals and the law.

5. Digital Assets and Modern Accounts Need Inclusion

In today’s digital world, your estate planning documents should cover more than just bank accounts and property. Many people overlook online investments, cryptocurrency, digital photo collections, or subscription-based accounts that hold value. Without clear instructions, these assets may become inaccessible after your passing. Including them in your estate plan ensures your executor can locate and manage them effectively. A thorough plan today prevents confusion about digital property tomorrow.

6. Keeping Beneficiaries Updated Strengthens Family Harmony

Family conflict is one of the most common consequences of poor estate planning. When beneficiaries aren’t updated or when unexpected names appear, emotions can run high, and relationships may suffer. Clear, current estate planning documents reduce misunderstandings and make your intentions undeniable. They also give your family peace of mind, knowing that your wishes were deliberate and up to date. Open communication combined with prompt updates ensures that wealth passes smoothly and respectfully to the right people.

Safeguard Your Legacy Through Consistent Review

Your estate planning documents aren’t meant to be static—they should grow and adapt with your life. Reviewing them every few years, or after major changes, keeps your legacy secure and your loved ones protected. An outdated estate plan can undo years of careful financial management, but regular updates preserve everything you’ve worked for. Treat it as an ongoing responsibility, not a one-time task. When your documents and beneficiaries reflect your current life, you can rest easy knowing your future plans are clear, accurate, and complete.

When was the last time you reviewed your estate planning documents or updated your beneficiaries? What changes might you need to make today? Share your thoughts in the comments below!

What to Read Next…

5 Subtle Estate-Tax Traps the Government Quietly Introduced

Are Inherited Digital Assets Treated as Estate in Every State?

11 Essential Components of a Bulletproof Estate Plan Document

Why Do Some Households Ignore Estate Planning Until It’s Too Late

10 Financial Dangers of Ignoring Estate Planning

Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.

Filed Under: Estate Planning Tagged With: beneficiary updates, Estate planning, family finance, legal advice, Personal Finance, Planning, retirement planning, wills and trusts

7 Income Streams You’d Laugh At—Until They Out-earned Your Salary

October 24, 2025 by Catherine Reed Leave a Comment

7 Income Streams You’d Laugh At—Until They Out-earned Your Salary
Image source: shutterstock.com

Most people assume that serious money only comes from serious jobs, but the modern economy is full of surprises. Some of the most profitable ventures started as hobbies, jokes, or side projects that no one took seriously. These unconventional income streams often grow quietly in the background until they begin to rival—or even surpass—a full-time paycheck. Whether it’s tapping into niche markets or monetizing everyday habits, these examples prove that creativity can pay off in big ways. The trick is spotting potential where others see something too small or too silly to try.

1. Selling Digital Stickers and Emojis

It might sound trivial, but selling custom digital stickers and emojis has become one of the most unexpected income streams online. Designers and illustrators are cashing in by uploading packs to platforms like LINE, Telegram, and Etsy. With minimal upfront costs and unlimited scalability, one viral set can generate thousands in passive income. The demand for personalized, expressive content shows no sign of slowing down, especially among younger users. What seems like digital doodling can turn into a steady business for anyone with a creative streak and basic design skills.

2. Renting Out Personal Items You Rarely Use

From lawnmowers to power tools, people are earning extra cash by renting out things collecting dust in their garages. Peer-to-peer rental apps make it easy to list your belongings safely and set your own prices. These low-effort income streams can quietly add up, especially when the items would otherwise sit idle. Some renters even expand by purchasing more equipment specifically to rent out, turning side gigs into full-fledged micro-businesses. It’s proof that you don’t always need to sell something new—you just need to make better use of what you already own.

3. Voice Acting and Audio Work from Home

You don’t need to be a Hollywood actor to make money with your voice. With the rise of audiobooks, podcasts, and digital marketing, freelance voice work is one of the most overlooked income streams available today. All it takes is a decent microphone, quiet space, and the ability to follow direction. Many beginners start on platforms like Fiverr or Voices.com and quickly build portfolios that attract repeat clients. What begins as reading scripts in your spare time can eventually lead to lucrative ongoing projects—and sometimes, full-time income.

4. Creating Print-on-Demand Merchandise

Many artists, meme creators, and even hobby photographers have turned print-on-demand stores into profitable income streams. Platforms like Redbubble, Teespring, and Society6 let anyone design products without worrying about inventory or shipping. You earn a percentage of each sale, and your designs can live online indefinitely, generating passive income. The funniest part is that some of the most successful sellers make humorous or absurd designs that go viral. That “inside joke” T-shirt or quirky coffee mug might end up funding your next vacation—or your retirement.

5. Turning Pet Photography into Profit

Yes, taking cute pictures of animals can be one of those income streams you laugh at—until you realize how much pet owners are willing to spend. With the pet industry booming, professional photoshoots for dogs and cats have become incredibly popular. Even part-time photographers can earn thousands by offering themed sessions or selling digital portraits online. Social media also provides a free marketing platform, as adorable pets practically advertise themselves. All it takes is patience, creativity, and a love for four-legged models.

6. Licensing Simple Music Loops and Sound Effects

If you’ve ever played video games, watched YouTube videos, or opened an app, you’ve probably heard licensed sound effects—and someone got paid for those. Musicians and sound designers create short clips and loops that sell repeatedly through licensing sites like AudioJungle or Pond5. These often-overlooked income streams reward creators who focus on volume and variety over complexity. Even simple background music or notification tones can generate steady income for years. Once uploaded, your sound library can keep earning with no extra effort.

7. Running Tiny Niche Newsletters

You don’t need a massive following to earn from a newsletter—just a dedicated audience. Many people now make impressive income streams by writing about obscure topics, from vintage watches to urban gardening. Platforms like Substack and Patreon allow creators to charge subscribers directly or earn through sponsorships. A loyal community of just a few hundred readers can turn into a sustainable income source. The best part? You can start for free, write about what you love, and build gradually without quitting your day job.

Finding Wealth in the Weirdest Places

The most surprising income streams are often the ones we underestimate. What starts as a side hustle, creative outlet, or experiment can become a legitimate business with time and consistency. The key is staying open to opportunity, even when it looks unconventional. Every income stream on this list began as something small—and in many cases, a little silly. But when approached strategically, those ideas prove that laughter and profit sometimes go hand in hand.

Have you ever tried one of these unusual income streams or discovered another that worked better than expected? Share your stories in the comments below!

What to Read Next…

12 Common Mistakes in Passive Income Planning

7 Unconventional Ideas for Earning Extra Income Reliably

Budgeting For Irregular Income: Freelancers And Gig Workers

6 Financial Dangers of Relying on One Income

Keep More Of Your Paycheck By Taking These 5 Steps

Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.

Filed Under: side hustles Tagged With: creative business, entrepreneurship, financial freedom, income streams, Passive income, Personal Finance, side hustles, Wealth Building

  • « Previous Page
  • 1
  • …
  • 70
  • 71
  • 72
  • 73
  • 74
  • …
  • 190
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework