• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for credit

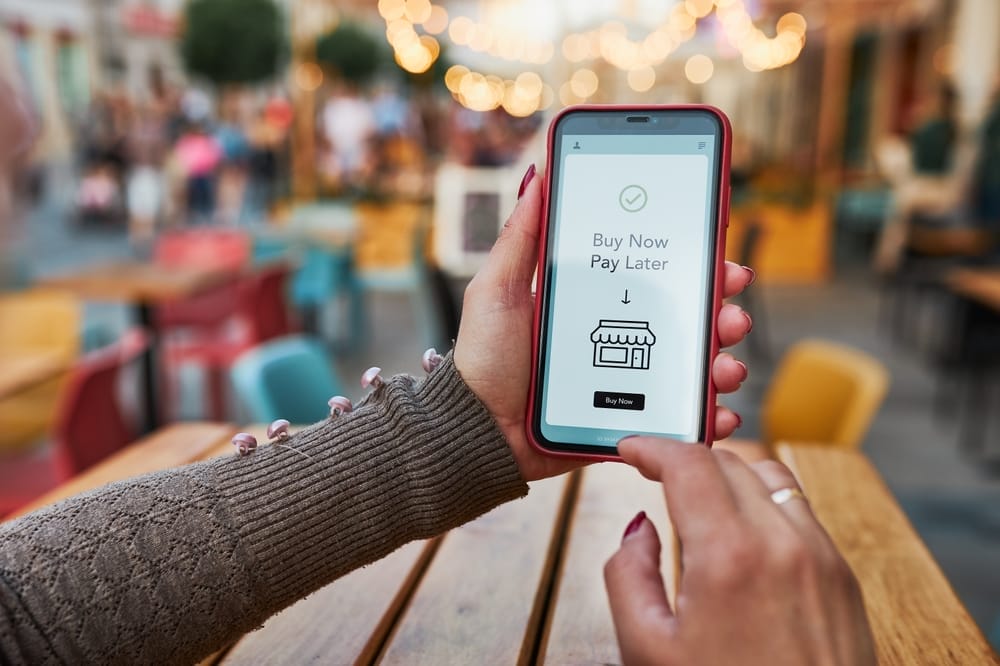
The “Buy Now, Pay Later” Trap That’s Drowning People in Hidden Debt

October 12, 2025 by Travis Campbell Leave a Comment

Bnpl
Image source: pexels.com

The rise of “Buy Now, Pay Later” (BNPL) services has changed the way people shop. At checkout, it’s tempting to split a purchase into smaller payments instead of paying the full price upfront. It feels painless and budget-friendly. But behind the scenes, these services can quietly stack up hidden debt. Many shoppers don’t realize how quickly these small payments add up. If you’re not careful, you could find yourself in a financial hole that’s hard to climb out of. Understanding the risks of the buy now, pay later trap is more important than ever.

1. The Illusion of Affordability

One of the biggest dangers of the buy now, pay later trap is how easy it becomes to justify purchases. A $200 jacket doesn’t look so bad when you only have to pay $50 today. The remaining payments are pushed into the future, and that makes it feel like you’re spending less. But you’re not saving money—you’re just delaying the pain. This illusion of affordability encourages overspending. It’s easy to lose track of how much you owe when your purchases are split into bite-sized chunks.

BNPL services bank on this psychology. The more you use them, the easier it is to think you can afford more. But every “small” payment is another obligation on your plate. If you’re not careful, you can end up with several ongoing payments at once, all stacking up into a bigger financial burden.

2. Hidden Fees and Penalties

Many buy now, pay later providers advertise “no interest” or “zero fees.” But the reality can be very different. If you miss a payment, you might get hit with late fees or penalty charges. Some services even report missed payments to credit bureaus, which can hurt your credit score. These fees are often buried in the fine print, making them easy to overlook.

The trap is set when you assume you’ll always pay on time. Life happens—maybe your paycheck is late or you forget a due date. Suddenly, that “interest-free” purchase gets expensive. Always read the terms before you agree, and remember that the buy now, pay later trap isn’t just about the payments you expect—it’s also about the costs you don’t see coming.

3. Multiple Accounts, Multiple Headaches

It’s easy to sign up for several buy now, pay later services. Each one might seem harmless on its own, but together they can create a confusing web of payments and due dates. You might have a payment due to one provider on the 15th, another on the 18th, and a third on the 22nd. Juggling all these can be a nightmare.

Miss a single payment and you could trigger fees, credit dings, or even debt collection calls. The buy now, pay later trap grows as you lose track of your obligations. Some people end up with four, five, or even more BNPL accounts running at the same time. That’s a recipe for financial chaos.

4. Impact on Your Credit and Budget

When you use a buy now, pay later service, you’re taking on debt—even if it doesn’t feel like it. Some providers run soft credit checks, while others report your payments to major credit bureaus. If you fall behind, your credit score could take a hit. This can affect your ability to get loans, rent an apartment, or even land certain jobs.

Even if your credit isn’t directly affected, your monthly budget definitely is. Every BNPL payment reduces your available cash. If you’re juggling several plans, you might find yourself short on money for essentials. The buy now, pay later trap can quietly squeeze your finances until you’re left scrambling to make ends meet.

5. Encouraging Impulse Buying

The buy now, pay later trap doesn’t just create debt—it encourages habits that can make your financial situation worse. When you know you don’t have to pay the full amount upfront, it’s easier to buy things you don’t really need. The barrier to spending is lower, so you’re more likely to make impulse purchases.

Retailers love this. Studies show that shoppers spend more when BNPL is available. That’s great for their bottom line, but not always for yours. If you regularly use BNPL, it’s worth asking yourself: are you buying because you need something, or because it’s easy to delay the cost?

6. Lack of Consumer Protections

Traditional credit cards come with a host of consumer protections, including dispute resolution and fraud protection. Many buy now, pay later services don’t offer the same safety nets. If your item never arrives or doesn’t match the description, getting your money back can be a hassle.

Some BNPL providers have their own policies, but they may not be as robust as those offered by credit card networks. Before you choose BNPL over a credit card, weigh the risks. You might find yourself stuck paying for something you never received.

What You Can Do to Avoid the Buy Now, Pay Later Trap

The buy now, pay later trap is easy to fall into, but you can avoid it with some practical steps. First, treat every BNPL offer as a loan. Ask yourself if you’d still make the purchase if you had to pay the full amount today. If the answer is no, it’s probably not worth it.

Keep a list of any BNPL accounts and payment schedules. Set reminders so you never miss a due date. Most importantly, don’t use BNPL to buy things you can’t afford. Remember, every payment is a future obligation. If you’re struggling with debt, consider reaching out to a nonprofit credit counselor for guidance.

How has using buy now, pay later services affected your finances? Share your experience in the comments below!

What to Read Next…

  • The Benefits Of Taking Personal Loans And Their Impact On Credit Scores
  • Are Budgeting Apps Designed To Push You Into Debt?
  • 5 Things That Instantly Decrease Your Credit Score By 50 Points
  • 7 Hidden Fees That Aren’t Labeled As Fees At All
  • 7 Financial Loopholes That Lenders Exploit Behind The Scenes
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Finance Tagged With: buy now pay later, credit, Debt, Hidden Fees, Personal Finance, Spending Habits

Here’s What It Really Means to Have an Unconventional Loan

October 10, 2025 by Travis Campbell Leave a Comment

money
Image source: shutterstock.com

When you think about getting a loan, you probably imagine the usual suspects: mortgages, auto loans, or personal loans from a bank or credit union. But what if your situation doesn’t fit into those neat boxes? That’s where an unconventional loan comes into play. Unconventional loans can open doors for people who don’t qualify for traditional lending or need creative solutions. Understanding what it really means to have an unconventional loan is important before you sign on the dotted line. These loans can help you achieve your goals, but they come with their own set of rules, risks, and rewards. Here’s what you need to know if you’re considering this less-traveled financial path.

1. What Is an Unconventional Loan?

An unconventional loan is any type of financing that falls outside the standard guidelines set by traditional lenders like banks and credit unions. These loans are also called non-conforming loans. People with unique financial situations often use them—maybe you’re self-employed, have a low credit score, or want to buy a property that doesn’t fit the mold.

The primary SEO keyword here is unconventional loan. Lenders may look at your ability to repay, but they’ll use different criteria or may be willing to take on more risk. While this flexibility is appealing, it’s important to understand the potential downsides, such as higher interest rates or stricter terms.

2. Who Typically Uses Unconventional Loans?

Unconventional loans are popular with borrowers who don’t meet the requirements for conventional loans. If you’re a freelancer, real estate investor, or someone with a recent bankruptcy, you might find that traditional banks won’t work with you. Maybe you have an irregular income stream or your credit history is less than perfect. In these cases, an unconventional loan could be a solution.

People who want to buy unique properties—like tiny homes, fixer-uppers, or mixed-use buildings—often turn to these loans as well. Sometimes, even business owners looking for a quick influx of cash will seek out unconventional options. The key is that these loans are designed for situations where the “normal” route just doesn’t fit.

3. Types of Unconventional Loans

There’s no single formula for an unconventional loan. They come in many shapes and sizes, including:

  • Stated income loans, which rely more on your stated earnings than on documented proof.
  • Hard money loans are secured by property and are often used by real estate investors.
  • Balloon loans have low initial payments followed by a large lump sum at the end.
  • Interest-only loans, where you pay just the interest for a set period before starting on the principal.
  • Peer-to-peer loans are where individuals lend to other individuals through online platforms.

Each type of unconventional loan serves different needs and comes with its own pros and cons. It’s smart to research thoroughly before deciding which route to take.

4. Pros and Cons You Need to Know

One major advantage of an unconventional loan is access. If you can’t get a regular mortgage or personal loan, these alternatives can help you bridge the gap. The approval process is often faster, and the requirements can be less rigid.

On the flip side, be prepared for higher interest rates and additional fees. Lenders take on more risk, so they charge more to offset it. You might also face shorter repayment terms or stricter penalties for late payments. Before you commit, review every detail so you’re clear about what you’re getting into.

5. How to Qualify for an Unconventional Loan

Qualifying for an unconventional loan isn’t always easier—it’s just different. Lenders might focus on your assets, property value, or projected cash flow instead of your credit score or W-2 income. You’ll likely need to provide more documentation to prove your ability to repay. Sometimes, you’ll need a larger down payment or collateral to secure the loan.

It pays to shop around and compare offers from different lenders. Get everything in writing, and don’t be afraid to ask questions. If possible, work with a financial advisor or mortgage broker who understands the unconventional loan landscape.

6. Risks to Watch Out For

Unconventional loans aren’t for everyone. The biggest risk is cost: you could end up paying much more over the life of the loan compared to a conventional option. Some loans, like hard money or balloon loans, can put you in a tough spot if you can’t make the big payments when they’re due.

Regulation is another issue. Some unconventional lenders operate with less oversight, which means you need to be extra cautious. Read all the fine print and check lender reviews.

What to Consider Before You Apply

Before you jump into an unconventional loan, take a step back and look at your full financial picture. Ask yourself if you really need this type of loan, or if there’s a way to qualify for a traditional product with better terms. Sometimes, improving your credit score or saving a larger down payment can open up more options.

It’s also wise to compare offers and check for hidden fees or high prepayment penalties. Remember, the flexibility of an unconventional loan comes at a price.

Have you ever considered an unconventional loan, or have you used one in the past? Share your experience or questions in the comments below!

What to Read Next…

  • The Benefits Of Taking Personal Loans And Their Impact On Credit Scores
  • 9 Surprising Penalties For Paying Off Loans Too Early
  • What Happens When You Co Sign A Friends Loan By Accident
  • 7 Financial Loopholes That Lenders Exploit Behind The Scenes
  • 8 Signs Your Financial Advisor Is Not Acting In Your Best Interest
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Finance Tagged With: alternative loans, credit, lending, mortgages, Personal Finance, Risk management, unconventional loan

What Happens When You Don’t Read Loan Fine Print

September 26, 2025 by Travis Campbell Leave a Comment

loan agreement
Image source: pexels.com

Taking out a loan can feel like a relief, whether you’re buying a car, paying for college, or covering emergency expenses. But many people skip over the loan fine print, eager to get funds quickly. That’s a risky move. The details buried in those pages can dramatically impact your finances. Ignoring the fine print might lead to unexpected fees, higher payments, or even legal trouble. Understanding what happens when you don’t read loan fine print can save you money, stress, and regret.

1. Hidden Fees and Costs

Loan agreements often include fees that aren’t obvious at first glance. If you don’t read the loan fine print, you might be surprised by origination fees, late payment penalties, or prepayment charges. These extra costs can add up quickly, making your loan more expensive than you planned. Some lenders even charge for things like paper statements or payment processing. Always check the fee schedule before you sign. It’s not just about the interest rate—you need to know the total cost of borrowing.

2. Changing Interest Rates

Many loans come with variable interest rates, but this detail is sometimes buried in the fine print. If you skip reading, you might think your rate is fixed, only to see your payments jump later. That can wreck your budget. When you don’t read the loan fine print, you might miss how and when your rate can change. Look for sections about rate adjustments, index rates, and how often your lender can revise the terms. Even a small increase in your rate can mean hundreds or thousands more over the life of the loan.

3. Unfavorable Repayment Terms

Repayment rules can be tricky. Some loans have short grace periods, while others require large balloon payments at the end. If you don’t read the loan fine print, you might not realize how soon you need to start paying or how much your payments will be. Missing these details can lead to late payments, penalties, or even default. Be clear about your repayment schedule, the amount due each month, and what happens if you pay late. Understanding these terms ahead of time gives you more control over your finances.

4. Tricky Clauses and Traps

Loan documents sometimes include clauses that protect the lender more than you. For example, there might be mandatory arbitration agreements, which limit your ability to sue if there’s a problem. Or there could be cross-default clauses, meaning if you default on one loan, you automatically default on others with the same lender. When you don’t read loan fine print, you may agree to terms you’d never accept if you understood them. Take the time to look for legal jargon, and don’t be afraid to ask for clarification before signing.

5. Credit Score Surprises

Your loan agreement may explain how your payments (or missed payments) are reported to credit bureaus. If you don’t read the loan fine print, you might not realize that even a single late payment could hurt your credit score. Some lenders report late payments after just a few days, while others give you a longer grace period. Understanding this can help you protect your credit and avoid long-term financial consequences. If you’re unsure, ask the lender how they report to credit agencies before you commit.

6. Prepayment Penalties

Paying off a loan early seems like a good thing, but not always. Some lenders charge prepayment penalties if you pay off your balance ahead of schedule. If you don’t read the loan fine print, you might end up paying extra just for being financially responsible. These penalties can eat into any interest savings you hoped to gain by paying off your loan faster. Always check if your loan has a prepayment penalty and how it’s calculated. This is especially important for mortgages and auto loans, where the amounts can be significant.

7. Loss of Collateral

Many loans are secured by collateral, such as your car or home. The fine print spells out what happens if you default. If you don’t read the loan fine print, you might not understand how quickly you could lose your property. Some contracts allow lenders to repossess assets after just one missed payment, with little warning. Protect yourself by knowing exactly what’s at risk and what your rights are if you fall behind.

8. Legal and Collection Risks

Loan agreements usually detail what happens if you break the contract. If you don’t read the loan fine print, you may not see clauses about collections, court costs, or wage garnishment. Some lenders move quickly to collect unpaid debts, hiring collection agencies or taking legal action. This can add major stress and cost to your life. Understanding these consequences before you sign helps you make informed choices and avoid future hassles.

How to Protect Yourself When Borrowing

It’s tempting to rush through paperwork, but reading the loan fine print is essential. Take your time, and don’t hesitate to ask questions if something isn’t clear. Get a copy of the agreement and review it at home, away from pressure. Consider consulting with a trusted advisor or a lawyer if the terms are complex.

Remember, lenders count on borrowers skipping the fine print. Knowing what happens when you don’t read loan fine print gives you the power to avoid surprises and protect your money.

Have you ever been caught off guard by a loan’s fine print? Share your experience or questions in the comments below!

What to Read Next…

  • The Benefits of Taking Personal Loans and Their Impact on Credit Scores
  • 9 Surprising Penalties for Paying Off Loans Too Early
  • 7 Hidden Fees That Aren’t Labeled as Fees at All
  • What Happens When You Co-Sign a Friend’s Loan by Accident
  • What Happens When Your Bank Changes the Terms Without Warning
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Debt Management Tagged With: borrowing, credit, Debt, fine print, interest rates, loans, Personal Finance

7 Tricks Collection Agencies Use To Get You To Pay Off Old Debt

September 21, 2025 by Travis Campbell Leave a Comment

money
Image source: pexels.com

If you’ve ever had old debt hanging over your head, you know how stressful it can be. Collection agencies are experts at getting people to pay off old debt, and they have a toolbox full of tactics to make it happen. Sometimes, these methods can leave you feeling pressured or uncertain about your rights. Knowing how collection agencies operate helps you protect yourself and make smarter choices. By spotting their tricks, you can keep control of your finances and handle old debt on your terms.

1. Restarting the Clock on Old Debt

One of the most common tricks collection agencies use to get you to pay off old debt is trying to restart the statute of limitations. Each state has laws about how long a collector can sue you for a debt. If you make a small payment or even acknowledge that you owe the money, you might reset the clock, giving them more time to take legal action. Collectors might push you to pay just a few dollars or sign a payment plan, but this can actually put you in a worse position legally.

2. Using Urgent or Threatening Language

Collection agencies know that fear is a powerful motivator. They might use urgent language or even threats to pressure you into paying off old debt quickly. You could hear phrases like “final notice,” “immediate action required,” or threats about damaging your credit report. In some cases, collectors cross the line and imply legal action is imminent, even if it’s not. Remember, while they can sue, they can’t threaten you or harass you under the Fair Debt Collection Practices Act (FDCPA).

3. Offering “Settlements” That Aren’t Always a Deal

It’s common for collection agencies to offer a settlement, promising to accept less than the full amount owed. While this can seem like a good way to pay off old debt, these offers sometimes come with strings attached. The agency might not clearly state whether the settled debt will be marked as “paid in full” on your credit report, or whether you’ll owe taxes on the forgiven amount. Always get settlement offers in writing and make sure you understand the terms before sending any money.

4. Calling Friends, Family, or Employers

Some collectors will contact people you know to embarrass you or increase the pressure to pay. They might call your family, friends, or workplace, claiming they’re trying to reach you. While they can ask for your contact information, they can’t discuss your debt with others. This tactic is meant to make you uncomfortable enough to pay off old debt quickly, but it’s important to know your rights and file a complaint if a collector crosses the line.

5. Misrepresenting Their Authority

Collection agencies sometimes act as if they have more power than they really do. They might suggest they’re working with law enforcement, or imply they can garnish your wages without a court order. These statements are often misleading or outright false. Under the FDCPA, collectors cannot misrepresent themselves or their ability to collect.

6. Flooding You with Calls and Letters

Persistence is a favorite strategy for collection agencies. They may call multiple times a day, send repeated letters, and use different phone numbers to get through. The goal is to wear you down so you’ll pay off old debt just to stop the constant contact. While collectors are allowed to reach out, they must respect your request to stop if you ask in writing.

7. Using Confusing or Vague Documentation

Sometimes, agencies will send unclear or incomplete paperwork about the debt they claim you owe. This can make it hard to know if the debt is real, if the amount is correct, or if you’re even legally responsible. They might hope you’ll pay off old debt just to avoid the hassle. Always ask for written verification of the debt and don’t pay until you’re sure everything checks out. This step protects you from paying a debt you don’t owe or restarting the statute of limitations by mistake.

Know Your Rights Before You Pay Off Old Debt

Collection agencies have many tricks to get you to pay off old debt, but you don’t have to fall for them. Understanding your rights and the rules collectors must follow gives you the confidence to handle their tactics. Take your time to verify any debt, and never let pressure or fear force you into a payment you’re not sure about. If you feel overwhelmed, consider reaching out to a nonprofit credit counselor or legal aid group for support.

Have you ever dealt with a collection agency? What tricks did they use, and how did you handle it? Share your experience in the comments below!

What to Read Next…

  • 5 Things That Instantly Decrease Your Credit Score By 50 Points
  • The Benefits Of Taking Personal Loans And Their Impact On Credit Scores
  • 7 Credit Card Features Disappearing Without Any Notice
  • Why Are More Seniors Ditching Their Credit Cards Completely?
  • Why Credit Limits Are Being Lowered Without Consent
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Debt Management Tagged With: collection agencies, consumer rights, credit, debt collection, old debt, Personal Finance

7 Shocking Financial Moves People Make Out of Desperation

September 20, 2025 by Travis Campbell Leave a Comment

financial stress
Image source: pexels.com

When money gets tight, it’s tempting to make choices you’d never consider under normal circumstances. Bills pile up, stress levels shoot through the roof, and it feels like you’re out of options. In these moments, some people turn to risky, even shocking, financial moves out of desperation. While the urge to act quickly is understandable, these decisions can have long-lasting consequences. Understanding the most common desperate financial moves can help you avoid falling into the same traps. Let’s look at seven mistakes people often make when they’re feeling the financial squeeze.

1. Taking Out High-Interest Payday Loans

Payday loans seem like a quick fix when you need cash fast. The application process is simple, and you can walk out with money in hand within hours. But the cost is steep. Payday lenders charge astronomical interest rates—sometimes over 400% APR. What starts as a small loan can balloon into an unmanageable debt cycle. People desperate for relief often end up renewing the loan or taking out new ones just to pay off the old debt. Before considering a payday loan, explore alternatives like local credit unions or community assistance programs.

2. Draining Retirement Accounts Early

When bills are overdue and collection calls won’t stop, some people cash out their 401(k) or IRA. The logic is simple: it’s your money, so why not use it in an emergency? The problem is, early withdrawals usually come with taxes and a 10% penalty if you’re under age 59½. Even worse, you lose out on the future growth of those funds. This desperate financial move can set your retirement plans back by years, making it much harder to catch up later.

3. Falling for Get-Rich-Quick Schemes

When you’re backed into a corner, promises of easy money are especially tempting. Scammers know this and target people in financial distress with “can’t-miss” investment opportunities or work-from-home gigs. These schemes often require upfront fees, personal information, or both. The result? You end up losing more money, and sometimes your identity, too. If something sounds too good to be true, it probably is. Always research before handing over your cash or data.

4. Using Credit Cards for Everyday Expenses—Then Only Paying the Minimum

Credit cards can help bridge the gap when cash is low, but relying on them for groceries, utilities, and gas quickly leads to ballooning balances. Only making the minimum payment each month means you’ll rack up interest charges, sometimes at rates exceeding 20%. Over time, your balance grows instead of shrinking, and your credit score takes a hit. Desperate financial moves like this can turn a short-term problem into a long-term debt spiral.

5. Pawning or Selling Essential Belongings

In tough times, people sometimes pawn or sell items they rely on, like laptops, tools, or even their car. The cash is immediate, but the loss can be lasting. Without a vehicle, it’s harder to get to work. Without a computer, remote work or job searching becomes a struggle. While it might seem like a necessary step, selling essential items often creates new obstacles down the road.

6. Skipping Insurance Payments

When money is tight, insurance premiums may seem like an easy expense to cut. Some people let their health, auto, or home insurance lapse to free up cash for other bills. This desperate financial move can backfire in a big way. One accident, illness, or disaster can leave you with bills far larger than the premiums you tried to avoid. Keeping basic insurance coverage is critical, even when you’re struggling.

7. Taking on Risky Side Hustles or Unregulated Gigs

Desperate times can push people toward side hustles that are risky or even illegal. Examples include gambling, unlicensed ridesharing, or working for cash under the table. These options might seem like a fast way to bring in money, but they can lead to fines, legal trouble, or worse. Instead, look for reputable gig work through platforms like Upwork that offer some protection and transparency.

Building Better Habits for Financial Stability

It’s easy to judge desperate financial moves from the outside, but anyone can find themselves in a tough spot. The key is to pause before making a decision that could have long-term consequences. If you’re facing financial hardship, reach out for help—whether that’s talking to a nonprofit credit counselor or exploring assistance programs in your area. Small steps, like building a budget or negotiating with creditors, can help you avoid the pitfalls of desperation and move toward stability.

Have you ever made a desperate financial move you later regretted? What did you learn from the experience? Share your story in the comments below.

What to Read Next…

  • 5 Emergency Repairs That Could Force You Into Debt Overnight
  • Are These 8 Money Saving Tricks Actually Keeping You Broke?
  • 10 Ways You’re Wasting Money Just Trying to Keep Up Appearances
  • 5 Financial Habits That Make You Look Struggling Even When You’re Not
  • 7 Financial Assumptions That Collapse After One Health Emergency
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.
Filed Under: Personal Finance Tagged With: credit, Debt, financial mistakes, payday loans, Personal Finance, Retirement, side hustles

These 3 Loans Are Worse Than Pay Day Loans

September 20, 2025 by Travis Campbell Leave a Comment

loans
Image source: pexels.com

When you’re short on cash, it’s tempting to grab the first loan that promises quick approval. Payday loans get a bad reputation for their high interest rates and predatory fees, and for good reason. But the truth is, there are loans even worse than payday loans lurking out there. These financial traps can dig you into a deeper hole, making it nearly impossible to get ahead.

Understanding the risks is critical. Some loans might seem like an easy fix, but their hidden costs and complex terms can lead to long-lasting debt. Knowing which loans to avoid can help you make smarter decisions and protect your financial future. Here are three loans that are actually worse than payday loans—and why you should steer clear.

1. Car Title Loans

Car title loans are a type of secured loan where you use your vehicle as collateral. They’re marketed as a fast way to get cash, often without a credit check. But the dangers are significant. Interest rates on car title loans can soar to triple digits—sometimes even higher than payday loans. If you can’t repay on time, you risk losing your car entirely.

The loan amounts are usually small compared to your car’s value, but the fees and interest add up quickly. Lenders may charge additional fees for processing or late payments, making it even harder to pay off. According to the Federal Trade Commission’s guide to predatory lending, many borrowers end up renewing their loans multiple times, racking up more debt and fees. If you depend on your car for work or family, losing it can have devastating effects on your daily life and finances.

Car title loans are worse than payday loans because losing your vehicle can disrupt your entire livelihood, and the debt cycle is just as brutal—if not worse.

2. Tax Refund Anticipation Loans

Tax refund anticipation loans, or RALs, are short-term loans offered by tax preparation companies. They promise quick access to your expected tax refund—often within a day or two. While this sounds convenient, the costs can be outrageous. Lenders charge high fees and interest, eating up a significant chunk of your refund before you even receive it.

You’re essentially paying a steep price to borrow your own money a little sooner. If your refund is delayed or less than expected, you might end up owing the lender even more. Some companies tack on hidden fees for processing, document preparation, or even “application” costs.

There are safer alternatives. Many banks and credit unions offer early direct deposit for tax refunds at no extra charge. If you can wait a week or two, you’ll get your full refund without unnecessary fees. RALs are loans worse than payday loans because you’re paying for something you should get for free—and risking extra debt if things don’t go as planned.

3. Rent-to-Own Agreements

Rent-to-own agreements might not look like traditional loans, but they’re just as dangerous. These contracts let you “rent” furniture, electronics, or appliances with the promise of ownership after a set number of payments. The catch? The total cost is often several times the actual retail price.

Rent-to-own companies rarely disclose the true cost up front. Low weekly or monthly payments might draw you in, but over time, you’ll pay exorbitant interest and fees. If you miss a payment, the company can repossess the item—even if you’re just a few payments away from owning it. This makes rent-to-own agreements essentially disguised payday loans. Instead of building equity or improving your credit, you’re stuck in a cycle of paying for items that never truly become yours until the very end.

For those with poor credit or limited cash, rent-to-own seems like a lifeline. But it’s a costly way to get essential items. Saving up or buying secondhand is almost always cheaper in the long run. The high cost and risk of losing your items make these agreements a terrible alternative to payday loans.

Protect Yourself from the Worst Lending Traps

It’s easy to fall into the trap of loans worse than payday loans when you’re desperate for cash. But these options often come with higher fees, more aggressive collection practices, and greater risks to your assets or income. Before signing any agreement, read the fine print carefully. Ask questions about interest rates, fees, and what happens if you can’t pay on time.

Look for safer alternatives like community credit unions, local assistance programs, or even negotiating payment plans with creditors. You can also explore resources such as the Consumer Financial Protection Bureau for guidance on avoiding predatory loans and making informed choices. Protecting your finances means steering clear of loans worse than payday loans—and choosing options that build your financial health instead of tearing it down.

Have you ever been caught in a loan trap? What advice would you give to someone considering one of these options? Share your thoughts in the comments below!

What to Read Next…

  • The Benefits Of Taking Personal Loans And Their Impact On Credit Scores
  • 9 Surprising Penalties For Paying Off Loans Too Early
  • What Happens When You Co Sign A Friends Loan By Accident
  • 7 Financial Loopholes That Lenders Exploit Behind The Scenes
  • 5 Financial Habits That Make You Look Struggling Even When Youre Not
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Debt Management Tagged With: credit, Debt, financial traps, loans, money management, Personal Finance, predatory lending

8 Little-Known Costs of Filing for Divorce

September 17, 2025 by Travis Campbell Leave a Comment

divorce
Image source: pexels.com

Filing for divorce is rarely just about ending a marriage. The process comes with a range of expenses, many of which aren’t obvious at first glance. While most people expect to pay for lawyers and court fees, there are plenty of hidden or unexpected costs that can catch you off guard. Understanding these little-known costs of filing for divorce can help you budget more accurately and avoid financial surprises. Whether you’re just starting to consider divorce or already in the process, knowing what to expect is crucial. Let’s break down the often-overlooked expenses that can impact your finances during and after a divorce.

1. Increased Housing Expenses

One of the most significant little-known costs of filing for divorce is the change in housing expenses. Moving out of a shared home means you’ll likely need to rent or buy a new place. Even if you stay put, you may lose the financial benefit of splitting mortgage or rent payments. The cost of setting up a separate household—security deposits, utility hookups, furniture—can add up fast. These expenses are often underestimated and can strain your budget just as you’re adapting to a new financial reality.

2. Health Insurance Adjustments

Health insurance is another area hit by divorce. If you were covered under your spouse’s plan, you’ll need to seek new coverage. COBRA can temporarily extend your existing insurance, but it’s usually expensive. Alternatively, you may have to shop for a plan on the marketplace, which can mean higher premiums and out-of-pocket costs. Medical expenses during this transition period can be a shock, especially if you have ongoing health needs or children to cover.

3. Tax Implications and Penalties

Divorce can change your tax filing status, potentially bumping you into a higher tax bracket or affecting deductions. You might lose the benefit of filing jointly or claiming certain credits. If you have to sell assets or withdraw funds early from retirement accounts to divide them, there could be capital gains taxes or early withdrawal penalties. These little-known costs of filing for divorce don’t show up until tax season, making them easy to overlook but potentially costly.

4. Retirement Account Division Fees

Splitting retirement accounts usually requires a qualified domestic relations order (QDRO), which comes with its own set of fees. Financial institutions may charge for processing these orders, and you could face penalties if the division isn’t handled correctly. These administrative costs, combined with potential investment losses from early withdrawals, can erode the value of your retirement savings. It’s wise to factor in these details when negotiating your settlement.

5. Childcare and Child-Related Expenses

The cost of raising children often goes up after a divorce. Even with child support, you may find yourself paying for additional childcare, transportation, or extracurricular activities. If both parents are working, after-school care or summer camps may become necessary. These expenses can change quickly as kids grow, and they’re rarely included in the initial divorce calculations. Planning ahead for these ongoing costs can help you avoid financial stress down the line.

6. Counseling and Support Services

Emotional support is just as important as legal support during a divorce. Hiring a therapist or counselor for yourself or your children is a smart move, but it can get expensive. Support groups, co-parenting classes, and mediation services also come with fees. These little-known costs of filing for divorce are often overlooked, yet they play a vital role in helping families adjust and move forward in a healthy way.

7. Legal Document and Processing Fees

Beyond attorney fees, there are various administrative costs tied to filing for divorce. These include court filing fees, process server charges, and fees for obtaining certified copies of legal documents. If your divorce involves complex assets or out-of-state issues, the paperwork can multiply—and so can the costs. Even uncontested divorces can rack up hundreds of dollars in documentation fees alone. Staying organized can help minimize repeat charges or delays.

8. Credit and Debt Management Costs

Divorce can impact your credit and lead to unexpected debt-related expenses. Joint accounts may need to be closed or refinanced, which can involve application fees or penalties. If one spouse fails to pay a shared debt, both credit scores could take a hit. You might also need to work with a financial advisor or credit counselor to rebuild your finances.

Preparing for the Full Financial Picture

The little-known costs of filing for divorce can easily add thousands to your total expenses. By understanding these hidden fees and planning for them, you can better protect your financial future. It’s also smart to seek guidance from professionals who can help you navigate these challenges.

Have you experienced any unexpected costs during a divorce? Share your story or questions in the comments below.

What to Read Next…

  • What Financial Planners Know About Divorce That Most Couples Don’t
  • 7 Signs Your Marriage and Finances Are Quickly Failing
  • 10 Quiet Retirement Scams Targeting Women Who Just Got Divorced
  • 10 Money Mistakes People Make After Losing a Spouse
  • Here Are 8 Things You Should Never Tell Your Spouse About Your Personal Finances
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Marriage & Money Tagged With: budgeting, credit, divorce, family law, hidden costs, Personal Finance, Retirement, taxes

Why Do Middle-Class Families Pay More for Credit Than the Wealthy

September 16, 2025 by Travis Campbell Leave a Comment

credit
Image source: pexels.com

Credit is a tool that can help families manage cash flow, buy homes, or cover emergencies. But not everyone pays the same price for borrowing money. The gap between what middle-class families and the wealthy pay for credit is wide—and growing. This matters because the cost of credit affects how families build wealth, manage financial setbacks, and plan for the future. Understanding why middle-class families pay more for credit than the wealthy can help you make smarter financial decisions and advocate for fairer lending practices.

The reasons behind this gap are complex but not mysterious. Let’s break down the main factors that put middle-class borrowers at a disadvantage when it comes to the cost of borrowing.

1. Credit Scores and Access to Favorable Rates

The primary factor lenders use to determine the interest rate they offer is your credit score. Wealthy borrowers often have higher credit scores, which unlock lower rates and better loan terms. Middle-class families might have good credit, but they are more likely to have missed payments, carry higher credit card balances, or lack a long credit history. All of these factors can lower a score, even if only slightly, and that translates into higher rates on everything from mortgages to car loans.

Even a small difference in a credit score can mean paying thousands more in interest over the life of a loan. This is one of the clearest reasons why middle-class families pay more for credit than the wealthy.

2. Limited Borrowing Options

Wealthy individuals have access to a broader range of credit products, including personal lines of credit, low-interest loans, and exclusive credit cards with better rewards and lower fees. Middle-class families are often limited to mainstream products, which tend to come with higher rates and more restrictive terms.

For example, a wealthy borrower might have a private banker who can arrange a low-rate line of credit secured by investments. Middle-class families typically rely on credit cards or unsecured personal loans, both of which charge much higher interest rates. The lack of access to alternative credit options keeps borrowing costs higher for the middle class.

3. Smaller Down Payments and Higher Loan-to-Value Ratios

When buying a home or a car, the size of your down payment matters. Wealthy borrowers can often put down substantial amounts, reducing the lender’s risk. Middle-class families, on the other hand, might only be able to afford the minimum down payment. This results in a higher loan-to-value ratio, which lenders see as riskier.

To offset the risk, lenders charge higher interest rates or require private mortgage insurance (PMI), adding to the overall cost. This is another key reason why middle-class families pay more for credit than the wealthy, even when buying the same items.

4. Higher Reliance on High-Interest Credit Cards

Credit cards are one of the most expensive ways to borrow. Middle-class families are more likely to carry balances on high-interest credit cards, especially during financial emergencies. In contrast, the wealthy can pay off balances each month or use cheaper forms of credit. Carrying a balance month to month means interest charges pile up quickly, making everyday borrowing much more expensive for the middle class.

High credit card rates can trap borrowers in a cycle of debt, where much of their payment goes toward interest rather than the principal. This cycle is much less common among the wealthy, who have more resources and flexibility.

5. Lower Financial Cushion and Emergency Savings

When an unexpected expense arises, middle-class families may not have enough savings to cover it. They’re forced to rely on credit, often at unfavorable terms. Wealthy people, by contrast, can tap into savings or investments and avoid borrowing altogether. This difference means that middle-class families pay more for credit simply because they need to use it more often—and often at the worst possible times.

Over time, these higher borrowing costs eat into the ability of middle-class families to save and build wealth, reinforcing the cycle.

6. Less Negotiating Power with Lenders

Wealthy borrowers can shop around, negotiate better rates, or threaten to move their business elsewhere. Lenders are eager to keep high-net-worth clients and may offer preferential deals. Middle-class borrowers don’t have the same leverage. They may feel pressure to accept the first offer or lack the time and resources to negotiate aggressively.

This lack of negotiating power means that middle-class families pay more for credit than the wealthy, even when they are just as reliable borrowers.

What Can Middle-Class Families Do?

The reality that middle-class families pay more for credit than the wealthy isn’t fair, but it isn’t unchangeable. Improving your credit score, paying down high-interest debt, and shopping around for the best rates can help lower your borrowing costs. Consider working with a local credit union or community bank, which sometimes offer more favorable terms than big banks.

While it’s true that income and wealth open doors, knowledge and persistence can help close the gap. Taking control of your credit profile and borrowing decisions is the best way to ensure you’re not overpaying compared to the wealthy.

What strategies have you used to lower your credit costs? Share your experiences in the comments below!

What to Read Next…

  • The Benefits of Taking Personal Loans and Their Impact on Credit Scores
  • 5 Things That Instantly Decrease Your Credit Score by 50 Points
  • 7 Credit Card Features Disappearing Without Any Notice
  • Why Credit Limits Are Being Lowered Without Consent
  • 7 Financial Loopholes That Lenders Exploit Behind the Scenes
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Banking Tagged With: borrowing, credit, interest rates, loans, middle class, Personal Finance, wealth gap

9 Hidden Costs of Switching Banks Nobody Warns You About

September 15, 2025 by Travis Campbell Leave a Comment

change banks
Image source: pexels.com

Thinking about switching banks? It seems simple: close your old account, open a new one, and move your money. But the reality is more complicated. The hidden costs of switching banks often catch people off guard. These little-known fees and hassles can add up, making your financial transition more stressful than expected. Before you make the leap, it’s important to understand what’s really involved. Here are nine unexpected expenses and headaches you might encounter when changing your bank.

1. Overlapping Monthly Fees

One of the most common hidden costs of switching banks is overlapping monthly account fees. If you open your new account before closing the old one, you could end up paying maintenance fees for both. Sometimes, banks require a minimum balance to waive these fees, and transferring your funds too soon might cause you to dip below the threshold. Make sure to time your account closure carefully and double-check all fee schedules before moving your money.

2. Lost Interest During Transfers

When you move money between accounts, there may be a few days when your cash isn’t earning any interest. This is especially true if you’re transferring funds by check or through slower ACH transfers. If you have a large balance, even a few days without earning interest can mean real money lost. Consider the timing and ask both banks about potential interest gaps before making the switch.

3. Automatic Payment Disruptions

Changing banks means updating all your automatic payments. Miss one, and you could face late fees from service providers or lenders. Worse, if a bill payment tries to process from your old account after you’ve closed it, you might get hit with returned payment fees. Make a detailed list of every automatic withdrawal and update your information with each company before closing your old account.

4. Check Reordering and Stationery Costs

Even in the digital age, you might still use checks for rent, gifts, or certain bills. When you open a new account, you’ll need new checks, deposit slips, and perhaps address labels. Banks rarely offer these for free. These small costs add up, especially if you use personalized or business checks. Don’t forget to destroy your old checks to avoid confusion or potential fraud.

5. Early Account Closure Penalties

Some banks charge a fee if you close your account soon after opening it—sometimes within 90 or even 180 days. If you’re switching banks because of a sign-up bonus or a better rate, this penalty can wipe out your gains. Review your current bank’s policies before making any moves. If you’re not sure, call customer service and ask directly about early closure penalties.

6. Missed Rewards and Loyalty Benefits

Many banks offer rewards for long-term customers, such as reduced loan rates or fee waivers. By switching banks, you could lose these perks. Some institutions even have relationship pricing that benefits you the longer you stay. If you’re considering a switch, weigh the value of these rewards against the potential savings at your new bank. Sometimes, staying put is the better financial move.

7. Transfer and Wire Fees

Moving your money from one bank to another isn’t always free. Some banks charge for outgoing wire transfers or even for standard electronic transfers above a certain amount. If you have to move large sums, these fees can be significant. It’s wise to ask both your old and new banks about their transfer fee policies. You don’t want to be surprised by a $25 charge just to move your own money.

8. Time and Hassle Costs

Not all costs are financial. The time you spend updating direct deposits, automatic payments, and account information can add up quickly. You might need to visit branches, fax documents, or spend hours on the phone. If you run a small business, these hidden costs of switching banks are even greater. Consider whether the benefits of your new account outweigh the effort required to make the transition smooth.

9. Impact on Your Credit and Financial Records

Switching banks can affect your credit and financial records more than you might think. If you close an account with a linked overdraft line of credit, it could impact your credit utilization ratio. A missed automatic loan payment due to a switch can also hurt your credit score. Additionally, if you’re applying for a mortgage or loan soon, lenders may want to see a stable banking history. Plan your timing—it’s safer to switch banks when you don’t have major financial events on the horizon.

Smart Moves When Facing the Hidden Costs of Switching Banks

The hidden costs of switching banks don’t have to derail your financial plans. Start by making a checklist of all the accounts, payments, and services connected to your old account. Take your time moving automatic deposits and withdrawals to your new bank. These extra steps can save you money and frustration.

It’s also helpful to research new banks thoroughly before making a move. Compare fee schedules, online reviews, and customer service options. By being proactive, you can minimize the hidden costs of switching banks and make your transition as smooth as possible.

Have you encountered any unexpected costs or hassles when changing banks? Share your experience in the comments below!

What to Read Next…

  • What Are Banks Really Doing With Your Personal Spending Data?
  • What Happens When Your Bank Changes The Terms Without Warning?
  • Could A Bank Freeze Your Account Without Telling You?
  • 7 Hidden Fees That Aren’t Labeled As Fees At All
  • 5 Invisible Service Charges Eating Into Your Bank Balance
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Banking Tagged With: automatic payments, banking, credit, fees, money management, Personal Finance, switching banks

8 Outrageous Myths People Still Believe About Debt

September 8, 2025 by Travis Campbell Leave a Comment

debt
Image source: pexels.com

Debt is one of those topics that everyone seems to have an opinion about, but not all of those opinions are rooted in reality. While managing debt is a regular part of many people’s financial lives, there are persistent myths that make it harder to make informed decisions. These misconceptions can lead to poor choices, unnecessary stress, or even financial setbacks. Understanding the truth about debt is key to building a healthy relationship with your finances. By clearing up these myths, you can take control and make smarter choices for your financial future. Let’s tackle eight of the most outrageous myths people still believe about debt.

1. All Debt Is Bad

This is probably the most common debt myth around. Not all debt is created equal. Some types of debt, such as mortgages or student loans, can actually help you build wealth or increase your earning potential. What matters is how you manage it. Responsible use of debt can open doors, while reckless borrowing can close them. The key is to understand the difference between “good” debt and “bad” debt, and use it wisely.

2. You Should Never Use Credit Cards

Credit cards have a bad reputation, but they aren’t inherently evil. Used responsibly, they can help you build credit, earn rewards, and provide a safety net in emergencies. The real trouble comes from carrying a balance and paying high interest rates. If you pay off your balance in full each month, credit cards can actually work in your favor. It’s not the credit card itself that’s the problem—it’s how you use it.

3. Checking Your Credit Hurts Your Score

Many people avoid checking their credit report because they think it will lower their score. In reality, checking your own credit is a “soft inquiry” and has no impact on your credit score. Regularly reviewing your credit report can help you spot errors or signs of identity theft early. Only “hard inquiries,” like when you apply for a new loan or credit card, can temporarily lower your score by a few points.

4. Debt Settlement Is Always the Best Way Out

Debt settlement companies often promise a quick fix, but the reality is more complicated. Settling your debt for less than you owe can trash your credit score and lead to unexpected taxes. Sometimes, negotiating directly with your creditors or seeking help from a nonprofit credit counseling agency is a better option. Before you choose debt settlement, make sure you understand the long-term consequences and explore all your options.

5. Paying Off Small Debts First Is Always Best

The “debt snowball” method, where you pay off small balances first, can be motivating—but it’s not always the smartest move. Sometimes, focusing on debts with the highest interest rates, known as the “debt avalanche” method, saves you more money in the long run. The best approach depends on your personality and what will keep you motivated to stick with your debt payoff plan. Don’t assume one method is always superior; pick the one that works for you and your unique situation.

6. Bankruptcy Ruins Your Life Forever

Bankruptcy is a serious step, but it’s not the end of the road. While it does have a significant impact on your credit, it’s also a legal tool designed to give people a fresh start. Many people bounce back from bankruptcy and go on to rebuild their financial lives. With time and responsible habits, your credit can recover. It’s important to educate yourself about bankruptcy and not let fear or misinformation keep you from making the best choice for your situation.

7. You Can’t Get a Mortgage if You Have Debt

Some believe that having any debt at all means you’ll never qualify for a mortgage. The truth is, lenders look at your overall financial picture, especially your debt-to-income ratio. Having some debt, like a car loan or student loans, doesn’t automatically disqualify you. In fact, showing that you can manage debt responsibly can help your chances. What matters most is your payment history, income, and how much debt you have compared to your earnings. If you’re planning to buy a home, focus on managing your existing debt wisely and keeping your credit healthy.

8. Paying Off Debt Will Instantly Improve Your Credit Score

While paying off debt is always a good thing, it doesn’t always result in an instant boost to your credit score. Your score is influenced by several factors, including your payment history, credit utilization, and length of credit history. Sometimes, closing a paid-off account can actually drop your score if it reduces your available credit. Be patient and focus on maintaining good habits over time.

Getting Real About Debt Myths

Debt myths can be stubborn, but facing the facts is essential for making smart financial decisions. Believing false information about debt can keep you from taking positive steps toward your goals. The truth is, debt is a tool—how you use it makes all the difference. By understanding what’s real and what’s not, you’re better equipped to handle your finances and avoid costly mistakes. The more you know about debt, the more confident you’ll be in your money choices.

Which debt myth have you heard the most? Share your thoughts or questions in the comments below!

What to Read Next…

  • The Benefits Of Taking Personal Loans And Their Impact On Credit Scores
  • 5 Emergency Repairs That Could Force You Into Debt Overnight
  • Are Budgeting Apps Designed To Push You Into Debt
  • 5 Things That Instantly Decrease Your Credit Score By 50 Points
  • Why Are So Many Seniors Being Sued Over Student Loans They Didn’t Take Out
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Debt Management Tagged With: credit, credit score, Debt, debt payoff, financial myths, money management, Personal Finance

  • « Previous Page
  • 1
  • 2
  • 3
  • 4
  • 5
  • 6
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework