• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for successful investing

Stock Market Punishment: The First Lesson of 2013

January 7, 2013 by Joe Saul-Sehy 38 Comments

The podcast team is giving the interns a well-deserved week off, so lucky reader….YOU get a FREE extra blog post from Average Joe. I know. Pinch yourself. It’s real. Almost like our awesome rare Saturday post this week.

Look at what the media did to you again.

The sky is falling! Fiscal cliff! Doom! Stock market will be in shambles! Hide your children!

Big ratings for the financial channels, huh?

If you listened and moved your money out of the market, it destroyed your chances for a great return in 2013.

MAYBE you’ll recover if you jumped out before the big two-day run up in stocks. The chances, though, are against you: historically, if you miss the 10 best days in the stock market, you lose about 5.18%, or nearly half your return for the year. If you paid trading fees to avoid the “fiscal cliff disaster,” this only exacerbated your problem.

Here’s what the panicked investor missed in the S&P 500 last week:

December 31: 1.7%

January 2: 2.5%

January 3: –.03%

January 4: .05%

In short, if you missed two days last week you lost out on 4.2%. Those types of returns don’t come around often.

By the way, don’t go in the comments and tell me that “all you lost was a little time….” go back and read the stats above first. You lost a ton.


let’s calculate the cost of listening to the media on this one


Suppose you’re 25 years old and you have managed to save $10,000 into your 401k plan. You lost out on $420. Sounds like no big deal, right?

Let’s use the rule of 72 to determine just how much you really lost:

The rule of 72 says that if you divide the interest rate you think you’ll achieve into 72, you’ll come up with the approximate number of years it’ll take your money to double. Cool, huh?

Assuming that you wanted this money for retirement (401k, right? That’s not your “mad money” account….I hope), we’ll use age 70 for your withdrawal. We’ll also use a realistic return assumption of 8%.

8% / 72 = 9 years for your money to double.

So, that $420 you lost wasn’t really $420, was it?

It would have doubled when you were 34, 43, 52, 61, 70.

Your “little” $420 wasn’t $420. By 32 it was $820. At 41 it was $1,640. By age 50 you’d lost $3,280. At 59 the gap was $6,560. When you went for the money at 69 you had $13,200 less.


it gets worse


If you’re 30 and gambled $50,000 that the market would tank, it’s uglier. Let’s also use 9% rather than 8%, since people looking long term historically have used 10% as their assumption (which I believe is too high, BTW).

Check out what more money and a “little” one percent difference do to your loss:

Rule of 72 = 8 years for money to double.

Funds double at 38, 46, 54, 62, 70

$2,100 lost during two day run-up in market.

= 4,200 loss at 38, 8,400 loss at 46, 16,800 at 54, 33,600 at 62 and

…$67,200 at age 70.

On our “What Did We Learn in 2012” podcast, expert after expert told you the same thing: don’t listen to national media finance porn and don’t chase short term results.

If you did, I’m going to play Dr. Phil now: How’s that workin’ out for ya?


Photo: Joe Shlabotnik
Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.
joesaulsehy.com/

Filed Under: investing news, Retirement, risk management, successful investing Tagged With: best 10 days in stock market, lessons of 2013, stock market 2013 lessons, stock market punishment

Investing Myths: Four Traps That Catch Amateurs

December 13, 2012 by The Other Guy 24 Comments

Why do so many do-it-yourself investors perform far worse than they should? How do you make sure and avoid some of the potholes that most amateurs seem to step in?

In theory, people managing their own funds should do well. Today’s investor has access to more tools, more research, and more information than ever before.  You can easily view data in near-real time, putting the average person on par with professional brokers and large brokerage businesses on Wall Street.  It’s easy to track company performance, get up-to-date and late breaking information just by opening an app on your phone.  What a world!

But, with all this information available, you’ll need to filter out truisms, half-truths and outdated ideas. Managing your own money isn’t tough, but it’s easy to fall into traps.

Let’ s walk through some top myths today’s investors need to realize aren’t true anymore.

First, a diamond may mean forever, but buy and hold isn’t.  You shouldn’t just buy a stock and close your eyes.  Occasionally, good companies have badly performing stocks.  Instead of “buy and hold” investors should “buy and pay attention.”  You should carefully select your positions based on the information at hand, but be sure to have a well-thought out exit plan before you buy the stock.

Second, performance isn’t the only thing that matters….and I’m not just saying that because I’m a guy. Historical performance is worth noting, but it’s not, as they say, indicative of future performance.  We do believe, however, that performance does persist – there is investment momentum.  What matters more than past performance? Simply put, volatility, tax considerations and overall asset allocation should be equally considered. It’s paramount to create a portfolio that compliments your long-term investing goals. Remember that the ones that shoot up fast are also the ones that crash quickly. Volatility is a two way street.

Listen to ways your investments could be more successful on our podcast: 2 Guys & Your Money Episode 15: Top 5 Ways to Improve Your Investment Returns

Third, charts don’t only make sense for professionals.  Some people believe only “technical traders” use charts or that they’re somehow outdated relics from a bygone era.  Not true.  Charts can tell investors a great deal about what’s going on in the markets and with any particular holding.  Charts aren’t crystal balls – but they can help you manage risk. How much volatility has a position had in the past? How does today’s price compare with past prices? When does the position pay dividends? How has this position grown relative to its peers? All of these are easily answered by reviewing a few charts.

Finally, don’t try to always buy at the bottom.  This one’s really dangerous.  How do you know it’s the bottom?  Investors are egotistical beasts; we think that because it looks like the stock/bond/real estate/whatever is going to turn around, our few dollars are boing to be perfectly placed. We’ve seen investors buy stocks at $10 that once were $100, only to find out that they were not even close to the bottom.  Remember two things: 1) you’re nobody in the market, and your brain is too small to call the bottom of the market (sorry if that offends you); and 2) investment prices fall for a reason. If a position is “on sale,” it’s important to know why it’s fell before you make a bet that it will rise again from the ashes. The person who buys a stock that’s near its yearly low is betting their purchase is going to be the reason it turns around.  Unless you’re Warren Buffet, I wouldn’t be too sure.

The biggest rule when it comes to investing is not to try to ”win big” but rather “lose small.”  Manage and know your risk before establishing a position and you’ll go a long way toward becoming a more successful investor.

Filed Under: investment types, risk management, successful investing

A Look Into the Post-Election Crystal Ball

November 8, 2012 by The Other Guy 17 Comments

The votes are in and I’d like to congratulate President Obama on his re-election.

This was a hard-fought campaign on both sides, and since we now know who will occupy the White House for the next four years and the Senate and House for the next two years, some of the uncertainty we’ve been experiencing in the stock market should finally begin to dissipate.

Many of you are wondering what the future holds for stocks and the market – and while no one knows for sure – including me, I do have a couple of themes that I think will emerge (or continue) over the next few years.

Theme #1 – Corporate Cash on balance sheets

There are trillions of dollars sitting on corporation’s balance sheets that were awaiting the outcome of the election.  Many were anticipating a Romney election which would’ve brought with it likely corporate easing, but now these large multi-national companies have to do something else with the cash sitting overseas.  If they repatriate it, they’ll be subject to double taxation, much like they are when they issue dividends, and at the highest corporate tax rate in the world.  What I expect in the near term is an increase in company stock buy-backs, which have the immediate impact of lowering supply of that company’s corporate stock.

Immediate effect: Stocks with large cash positions might be worthy investment positions and short term winners.

Theme #2 – CNBC’s Fiscal Cliff

The producers at CNBC can’t help themselves. The phrase “Fiscal Cliff” sells heaps of advertising, so you’ll hear this over and over in the upcoming weeks.  Since the House controls the country’s purse strings, and the President and the House have very different ideas on how to spend money, I expect continued gridlock up to and through the so-called “fiscal cliff.”  Obviously, this will be resolved at some point, but it will provide uneasiness in the markets until it’s behind us.

Immediate effect: Lots of waves in the financial markets. Probably higher VIX (volatility) index.

Theme #2 ½  – Budgetary Issues Related to the Above

I don’t know if it will be a retaliatory-type reaction, or just purely out of ideology, but I expect the continued gridlock in Washington to impact all of the sun setting provisions that have been put in different tax-law extension bills over the last several years.  For example, I think the severe defense cuts will take effect at the beginning of the year and the entitlement spending to continue.

Immediate effect: See Theme #2.

Theme #3 – Weak Dollar and Quantitative Easing

The U.S.’s credit has been downgraded twice already, and it appears headed for another downgrade as we reach our self-imposed borrowing limit of $16 trillion.  Obviously, the Congress and the President will just kick that down the road a bit, but that means continued weakness of the dollar compared to other currencies worldwide.  This is bad news if you’re travelling to Japan or Europe for vacation, because our weak dollar buys less Euros and Yen, but the large, multi-national companies we discussed earlier will benefit from a weak U.S. dollar since they make money in all currencies.  Secondly, our fearless economic leader, Big Ben, has promised to continue to print vast amounts of dollars as long as the government continues to run deficits.  Looks like Ben’s printing money for a long, long time…which could lead to inflation

Potential Headwinds

If there are any market headwinds, it will be the short-term issues relating to the pending fiscal cliff and their respective tax increases.  Undoubtedly, the 3.8% tax on interest, dividends and capital gains that takes effect in 2013 will have an impact as well as the continued implementation of Obamacare.  Since healthcare is mandatory for those employees who work over 30 hours per week, expect to see companies continue to reduce their workforce’s hours to 29,as the CEO of Darden Restaurants (Olive Garden, Red Lobster, etc.) has already announced.

So What Does That Mean for Me?

I think the best bet for many investors is to continue to chase yield.  With bank accounts earning nearly 0% and no rate increase on the horizon, the fact that the S&P 500 averages 2.2% will provide some base level of market support over the coming years.  As confidence comes back, the market should also bounce back accordingly.  It’s sad, but President Obama is probably a “lame duck” president, at least over the next two years, as the House will continue to block all attempts he makes at advancing his agenda.

Ultimately, it’s more of the same.  The uncertainty should be ending, the weak dollar means good things for the large multi-national companies.  I know many were surprised by the outcome, but we are a country that comes together.  Let’s focus on the future and not on the past.

Filed Under: investing news, Planning, successful investing

Old Savings Bonds Might Be Your Most Valuable Investment

September 20, 2012 by The Other Guy 14 Comments

It’s Thursday. I’m grabbin’ some coffee while OG takes the driver’s seat….

Recently, a client emailed me a peculiar list of dollar amounts and dates. Each was followed by a one or two letter symbol.

What the heck?

Finally the lightbulb went off – this was a list of US Savings Bonds we’d discussed months earlier that she’d “found” in her safety deposit box. Her question: What to do with all those bonds?  Cash them in?  Keep them?


The Savings Bond Conundrum


Clients raise this question at least once every couple months – and I’ll bet as more and more baby-boomers head into retirement the frequency is only going to increase.  For some reason, people seem to think analyzing savings bond interest is a complicated financial problem that only the best advisors can solve.  Nothing could be further from the truth – let me show you exactly how I determine whether to keep or cash in each bond.

Small Numbers of Bonds

If you own only a few bonds, I’d recommend using the US Treasury’s savings bond calculator. This tool helps you  quickly estimate the value, interest accumulated, yield, next interest payment date, and final payment date.  All you’ll need is the issue type (E, EE, or I), face amount, and the month and year.  All of that information is found on the face of the bond.

Lots of Bonds?

If you’re the Donald Trump of savings bonds, or if you want to track the bond’s value over longer periods, you should download the government’s Savings Bond Wizard tool found at http://www.treasurydirect.gov/indiv/tools/tools_savingsbondwizard.htm.  The Savings Bond Wizard allows you to save the file and refresh it each month with the most updated values. Here you can store information about each of your bonds and easily compare interest rates and the total value of your savings bond empire.

Is Your Bond Still Making Money?

Here’s a tip: don’t hold on to bonds that no longer pay interest.

After thirty years, US Savings Bonds mature and the government shuts you off like a disinherited trust fund baby.  Most bonds reach their face value somewhere between 12 and 15 years after issue and continue to pay interest until year 30.

It’s foolish to keep a bond past 30 years.  Don’t do it.

One client brought in a savings bond that stopped paying interest before Kennedy was president! Imagine how much money that’s cost him.


The Moment of Truth

After you’ve used all of your fingers and toes (AND one and a half neighbors’ fingers and toes) to determined whether or not it’s still paying interest (let’s assume it is), now it’s judgment time:

Can you invest the proceeds at a better rate of return than you’re receiving from the government?  

The yield on your savings bond is risk free.  Those two words are hard to beat.  I’ve seen bonds from the 80’s paying 6%. Can’t beat that. I’d keep those.

Final Step

Set a reminder to review your bonds again a few years down the line.  If you have a bond or two that you’d like to redeem, schedule it in advance.  Don’t forfeit interest because you procrastinated.  Keep an updated bond inventory and review it periodically just as you would any other part of your portfolio.

Savings bonds are one of the best ways to lock in guaranteed interest – especially if you have some from ten or twenty years ago.  Many clients are surprised when I tell them to keep their bonds; sometimes it’s in their best interest to do so!  Many times people think savings bonds are a waste of time and money. My take:  In today’s low interest rate environment yesterday’s bonds may just be a gold mine.

Filed Under: Banking, Cash Reserve, investment types, successful investing Tagged With: bond evaluation tools, cash in old bonds, evaluate old bonds, savings bond, savings bond interest rate, savings bond yield

Why You Shouldn’t Invest Like President Obama

September 18, 2012 by Joe Saul-Sehy 25 Comments

Imagine my surprise over the weekend when I discovered President Obama’s portfolio holdings. Although I’m crafty, I didn’t sneak into the West Wing; the President is required to file tax returns and investment documentation. Most investment strategies show up on these forms.

The biggest surprise?

The President can pick fights with Wall Street because he largely doesn’t rely on them for investment returns. Less than 10% of his portfolio is in equity investments, far less than is recommended for most people his age.

After fighting in the trenches as a financial advisor for well over a decade, I can see the method behind his madness. Don’t try to invest like he does. It probably won’t improve your retirement.

Let’s review:

The President’s Portfolio

– Around $500k in cash

– Between $50k and $100k in Vanguard S&P 500 Fund

– Over $1M in Treasury Bills and Notes

– 529 College Savings Plans


Here are the top five take aways:

1) His version of “safety” and yours probably aren’t the same. The President’s massive investment in Treasury Bills suggests that he’s looking to preserve capital, not grow his nest egg. Treasuries are among the lowest risk/lowest reward investments available.

Why he’s different than you:

You probably can’t afford to keep such a large percentage of your portfolio in low-earning investments. A President stands to make millions in the future on book deals, speaking engagements and consulting. His future investment plan can easily include some HUGE assumptions for future cash infusions.

If you’ve calculated your personal returns based on future income, are you sure that your numbers are realistic? I often see plans showing individuals working well into their 70s. Even if you’re healthy enough to work that late in life, do you want to include it in your plan? My clients working in their 70s largely did so because they enjoyed it, not because they needed some benjamins to pay the electric bill.

2) You can tweak your returns without adding much risk. He helps his anemic rate of return by moving some of his huge government bond exposure to Treasury Notes. The difference between treasury bill and treasury note gives him an extra 0.5% in this climate because of the longer duration.

How this applies to you:

For you and I, an extra 0.5% doesn’t help, but we can take similar steps. I wrote this spring about how adding high yield bonds can boost returns while not appreciably increasing risk. Look for investments where the perceived risk is higher than the actual risk and find greater returns. (I’d also put GNMA bonds in this category. They garner a much higher return than Treasuries and the actual risk, while greater than Treasuries, isn’t appreciably higher for the average investor).

3) Watch your fees. The President bets on the US economy by investing in the S&P 500. Instead of relying on investment managers for a return, he uses the Vanguard S&P 500 Index mutual fund.

Here’s a better method than the President uses:

In some cases, an exchange traded fund can lower fees even further. The iShares ETF version of the S&P 500, IVV, features an incredibly low 0.09% cost ratio, while the Vanguard fund the President uses has a still-low internal expense of 0.17%. The only difference? You’ll probably pay trading costs to buy the iShares ETF, while the Vanguard fund is free to purchase in most brokerage accounts. If you’re buying over only a few trades and plan to hold the fund for a long period of time, IVV might be a more cost-effective option.

4) He keeps a large cash reserve. $500k in cash is clearly too large for the average person, but that would be nice, wouldn’t it? Conservative investors should keep enough money to endure a long layoff in money market accounts.

Check out Don’t Be the Emperor With No Emergency Fund for more details on why this is important.

5) Invest in what you know. The President is betting big on future income streams, not on investment returns. As it sits, his portfolio isn’t huge for a man of his office, but I’m sure he knows that it will be in the future. Speaking engagements, consulting and book deals should allow him access to plenty of money without risking his investments in the stock, real estate, or commodities markets.

An example that might be closer to home:

I had clients once who herded cattle. They earned a 10% return year-over-year on their herd, without a ton of variation. We kept that the centerpiece of their portfolio, while creating a diverse mix of other investments to round out their returns. They were surprised I wanted them to continue buying cows. “Investment advisors want you to only use stocks,” Bryan said. I agreed with him. “I’m a fee-based advisor. You paid me money to give you the right direction. I don’t need to make money on convincing you to invest through my firm. If I were you, I’d stick with cattle because it earns a great return and it’s what you know.”

My last takeaway (and I won’t number this one):

The President appears to need a good investment advisor. He either isn’t comfortable with a suitably well-rounded portfolio or just doesn’t have the time. Either way, he’s lost considerable money to either not being educated in investments or to being too busy to care. The right advisor can help him boost returns, tweak his tax strategy and still focus on his “day job” so he doesn’t feel like a Wall Street trader. Investment advisors aren’t for everyone, but in this case, I think it’s warranted and a great idea.

Mr. President, although I’m no longer practicing, I’m ready if you need help. I’m sure the Secret Service can figure out my phone number.


That’s my story, now it’s your turn: What investments could you improve in your portfolio?

Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: successful investing Tagged With: diversification, obama investments, president uses treasuries, treasury bills, treasury notes

So You Want to Manage Your Own Money?

September 4, 2012 by Joe Saul-Sehy 29 Comments

A friend texted me this morning.

“We should talk soon. Julie is coming around to the idea of us managing our own money.”

It seems easy, right? My initial reaction to my friend was, “That’s awesome!” because it is. There are few things more satisfying than achieving your financial dreams and knowing that you climbed the money management mountain yourself.

No “money-god” came down and did it for you.

You didn’t need the Powerball numbers.

You actually plotted a financial course and landed safely at your destination.

For my friend, and for you if you’re about to embark on this journey, there’s good news and bad news: the good news is that it isn’t difficult to manage your own money.

The bad news is that to effectively manage your own money you’ll need to be ready to face some fairly difficult tasks.


Two Types of People


When I was a professional advisor, I’d meet some smart people who wanted to jump into their own money management and wanted an expert with an opinion to look over their shoulder, hold them accountable, and make sure they didn’t miss any “I” dotting or “T” crossing.

…and then there were other, often equally-smart people who wanted to hand it over to me and have someone else take care of it for them.

Believe it or not, most advisors I knew preferred the latter type of client and loathed the first one. Someone questioning their motives? Someone asking “why are we doing it this way?” all the time? That’s preposterous!

But if you’re going to ever learn how to manage your own money, you’ll need to be the first type, not the latter.

The steps aren’t difficult:


The Steps to Managing Your Own Money


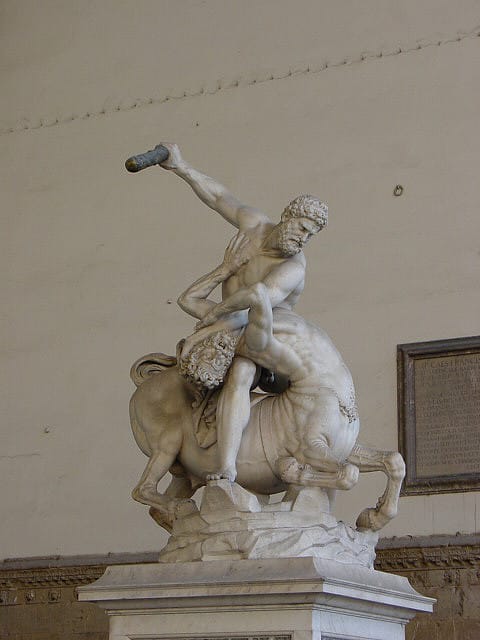
My kids are reading myths in school. In the story of Hercules, he faces a series of challenges to achieve is goal.

Marble statue of Hercules battling the centaur Nessus
I look remarkably like the guy on top, but I’m a little paler and not quite as naked. And I have less hair.

You’ll have a series of gauntlets in your way too, if you want to manage your own money.

1) Write out your goals. I’m not talking about writing:

Retirement

College

New Boat

Fall Deeper in Love

Real goal writing has a specific time, dollar amount and vision attached.

I want to be able to live on $65,000 per year (in today’s dollars) by age 65 without having to work every day. With this money I’d like to: (here you write your bucket list, which should include visiting every NASCAR track in the country).

That’s a goal you can shoot for and be excited about (except for visiting the track at Pocono, which I thought was pretty overrated).

2) Next, you write out all the hurdles in your way.

– I have $25,000 in credit card debt (separate by interest rate, term, amount)

– I have to put two children through college

– I know nothing about money management

3) Then, you find one of the nearly bazillion financial calculators online (you can use our powerful little PlanWise calculator here on the site!) and figure out how much you need to save to reach your goal.

– I need to save $250 per month to reach my dream if I achieve an 8% return.

Armed with your money management return information, now you figure out how to come up with $250 per month.

– Tweak your budget

– Pay down debt

– Take on more work

4) Before investing, though, you have a big problem. You have to insure yourself against some of the huge “what if’s” out there for you and your family:

What if you die?

What if you are disabled?

What if you have a car accident?

You’ll need to create a will and evaluate insurances.

5) Finally, you begin the heavy task of research to find investments that have historically achieved 8%.


No Step is Difficult, You Just Shouldn’t Miss One


As you can see, when you take on the hard task and decide to manage your own money, getting it right will be difficult. Each area demands time and energy:

– Planning, milestones and tracking

– Budget, income advancement and debt reduction

– Insurance need projection and comparison analysis

– Estate planning

– Investment allocation, picking and monitoring

These are five basic money management steps, but each packs a punch!


I Don’t Mean To Imply You Can’t Do It


As soon as I finish this piece I’m calling my buddy and talking him through these points. Before he takes on the task, he should know how long the financial security road really is. Going in with your eyes wide open is half the battle if you plan to win the “manage your own money” game.

He can do it, and so can you!

Enhanced by Zemanta
Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: money management, Planning, successful investing Tagged With: Budget, Debt, finance, Financial services, Insurance, Investment, manage your money, money management

The Markets Reach 4-Year Highs…Now What? Protect Your Investments!

August 23, 2012 by The Other Guy 26 Comments

OG grabs the reins for his usual Thursday rant!

This week, the US equity markets quietly reached a “four-year high,” prompting many (including me) to question the validity of this recent rally.  The market is up nearly 26% over the past 12 months. During this same time we’ve had:

– the dreaded “downgrade” of the US debt,

– the Eurocrisis, Spain, Italy, Ireland, and of course Greek near-defaults

yet most people won’t feel much richer if you ask them “how’s the market doing?”.

As a practicing advisor, whenever I hear “lowest ever” or “best ever” or “all-time” anything, I automatically consider the inverse.  As CNBC, Fox News, CNN and  Bloomberg keep us glued to their networks with fear and greed, I’m left wondering…

So I’ve begun thinking about protection strategies.
Today, lets talk about about a powerful tool: the Put Option.

Wait! Don’t run away! It’s actually a good way to shelter your investments AND it isn’t nearly as difficult as you might imagine. While many option strategies are pure speculation, this one is designed for the conservative investor…the one who wants to insure everything.

Let’s say the S&P 500 closed at 1420. We can go out and buy an S&P 500 index fund that mimics the index, (ticker – SPY).  If you look up SPY on any finance site you’ll see today’s closing price and you’ll notice it trades at 1/10th of the actual index’s price.  Since we assumed the S&P closed at 1420, the SPY would close at 142.

Now let’s further assume that you’re okay with day-to-day volatility of a few percent here and there, but you want to prevent the catastrophic loss of 20% or more over a few trading days – the so called “Black Swan” event.  What we want to do then is to protect our current account against future loss, or said another way, we want “the ability (or option!) to sell at today’s prices sometime in the future.”

Wouldn’t it be nice to say “I want a do-over” if the market collapses and our funds slide?

The tool that accomplishes this is called a put option and it allows us to do exactly that.  We have to pay for this option, so let’s explore what that would cost. It might not be worth the price.

If we pull up January 13 Put Options for $130, we’ll see that we can buy those for $3.  January 13 Put Option means that we can sell the options for $130 anytime we want between now and the third Friday in January.  This represents about a 9.5% decline from today’s prices and the $3 price per contract means that we’ll lose another 2% to cover the investment.


Here’s how I figure all this out


1)    I determine the amount at risk.  There are many risks, but in this case we’re talking about stock market risk. If your portfolio is $100,000 and you have 50% in stocks, your amount at risk is $50,000.

2)    Next, I decide how much downside I’m comfortable accepting.  As we discussed, a 10% decline is tolerable, but a 20% loss is catastrophic.  I decide to insure everything below a 10% loss.

(side note – why don’t I just insure it for the current price? The cost to do this is nearly always huge. It’s like insuring your house….having a deductible of 10% is much cheaper than insuring every instance.)

3)    Next, I’ll find prices.  Using today’s numbers, it would cost me $3 per share to cover everything below a 10% loss.

4)    Fourth, I do the math, which isn’t difficult. Don’t let it scare you.  My amount at risk is $50,000 divided by $142 (todays SPY price) is 352 hypothetical shares of SPY.  Although options are priced per share, they’re purchased per 100 shares. I need to buy four contracts to insure all my amount at risk.

4 (contracts) x $3 x 100 = $1,200 or roughly 2.4%.

5)    Now I make my decision, weighing each outcome.  Lets list them:

Outcome #1 – the market stays flat or increases through January 2013.  If this happens, I’ll forfeit the entire $1,200 paid for the option contracts, but would’ve had the piece of mind.  Basically, an automatic 2.4% loss for insurance that I didn’t use.

Outcome #2 – The market declines, but less than 10%.  In this scenario, because of my “deductible” amount,  I also lose the entire amount invested in the option contracts. Insurance that I didn’t use.

Outcome #3 – The market declines greater than 10%.  In this scenario, my total loss is limited to just 10%.  If the market goes down 20% over the next several months, I cash in my option contracts to recoup some of those losses at anytime I want through January 2013.

6)    Finally, I decide whether to pull the trigger.  If so, let’s try to find an “up” day to do the trade to lower your cost a little. If not, I have to be comfortable with my decision and move on.

So now it’s your turn.  What outcome would you choose?  Would you buy the insurance?  What do you do when you start thinking about “protecting” some gains?

Photo: Stock Market Bull – thetaxhaven

Filed Under: investing news, successful investing

A Shaky Earnings Season Might Be Your Wallet’s Best Friend

July 10, 2012 by Joe Saul-Sehy 11 Comments

There’s baseball season, football season, the holiday season and, of course, earnings season. While the first three may fill you with happiness and (in the holiday case) good cheer, earnings season fills new investors with confusion.

Why do I bring this up?

I woke yesterday morning to a nerve-wracking CNBC.com headline: Investors Brace for Shaky U.S. Earnings Season.


What is Earnings Season? Is It Contagious?


The good news: earnings season affects you directly, but not in the harmful way you may think.

Earnings season is the time (quarterly) when the majority of companies that move financial markets with their results declare how well they’ve performed recently. This news is for the prior quarter.

It’s important, when listening to reports about earnings, to listen for any future forecasting and to also determine what might have been the culprit behind a great or lousy prior quarter. If it’s increased sales on the same-old widget the company’s always sold, fantastic! If the company had a one-time mistake, things might still be looking up. If products just aren’t selling or management is quitting, it might spell bad news.


What Do I Need to Know?


Corporate earnings reports drive the stock market. Sure, financial markets respond to other pressures, but over time the stock market is simply a reflection of the economy. So, if you reread the headline above, Investors Brace for Shaky U.S. Earnings Season, what does that really mean?

Based on the information I told you above, it means this: companies didn’t have stellar profits last quarter.

That’s not nearly as shocking a headline, is it? In fact, I’ll bet you already knew that.


Move On, Nothing to See Here…..


Many investors read the CNBC headline above and think: I’ve gotta sell right now! If you’ve read my ramblings before, you’ll know that I think the opposite. I’m looking to buy when prices are low and sell when they’re high.

Here’s what I recommend instead of having a panic attack:

1) Rebalance your portfolio. Here’s how it works: if you’ve determined how much stock and bond exposure you want (among other asset classes), skim off the areas that have done well to fill in non-performing areas. Low markets are ideal times to rebalance because you’ll reaffirm your long term strategy, take gains from performing spots and redeploy in assets you already own that are low today. Smart move. Then, schedule another rebalance six months from now on your calendar.

2) Look for buying opportunities. If you’re interested in investing, shaky markets are a great place to place your first buys. Make your list of stocks to watch. Wait for earnings reports. Read what companies report, and make your move! Don’t make a common mistake and go whole-hog on a “can’t lose” investment. I’ve been involved with too many “can’t lose” things. I also told my dad I couldn’t lose my hair like he did. Glad I didn’t bet on that….

Not excited to make your own stock picks? Read our pieces on how to evaluate mutual funds and how Exchange-Traded Funds work.

3) If you’re nervous, put defensive measures in place. Use stop losses on individual stocks and exchange traded funds. Monitor fund results more frequently and establish a “worst case scenario” strategy. Remember this: never buy or sell everything on one day or at one time. It’s safer to march in slowly and march out slowly. An orderly walk toward the exit beats a panicked race to the door. Often, down markets rebound quickly.

CNBC, like other publications, is in the business of selling advertising. If the elevator is labeled “Up” or “Down” it’ll be a smooth and steady ride, but I’m sure CNBC knows that “Soar” and “Plummet” garner readers…and then advertiser dollars.

Enhanced by Zemanta
Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: investing news, successful investing Tagged With: earning season, Exchange-traded fund, Financial market, Investor, Mutual fund, rebalancing portfolio, shaky earnings season, stock market, when to make stock changes

My Experience in Landlording 101, or I’m Not Donald Trump

July 6, 2012 by Joe Saul-Sehy 7 Comments

I’ve been renovating my rental property this week and haven’t had enough time to pick a Blog Post of the Week! Instead, you get obscure ramblings from an over-caffeinated blogger….I’ll have a Blog Post of the Week! again next week for you. Have a great weekend!

I Never Wanted To Be A Landlord

When I was an advisor, I’d hear horror stories from my clients with tenants. Early on I learned that I probably didn’t have the stomach for some of the negotiation and strong-arming that it takes to work with tenants. I prefer REITs for my real estate exposure.

But, after my home didn’t sell when we moved to Texas, I realized that I had two choices: short sale or try my hand at tenants. I opted for choice #2. I wasn’t completely green. I’d read extensively about landlord/tenant contracts, strategies and tactics so I could be useful to clients. While “fun” might not be the right word, it’d be educational to try it first hand.

The surprise? I didn’t know how much I’d like it.

I’m no Donald Trump and am still too much of a pushover. I want to be a little more callous with my tenants because they realize they can get away with stuff (and do). An example: my tenant the last three years was late with her rent EVERY MONTH. The good news is that I wrote a $100 late fee into the contract, which she gladly paid EVERY MONTH. I got used to her checks two weeks late and came to enjoy the $1,200 extra income from her.

Lessons Learned From Landlording

Is landlording a word? Probably not (Pages doesn’t think so….), but I’m running with it. That’s the kind of rebel I am.

  1. Don’t rent a furnished place unless you’re okay with everything being ruined OR you write penalties into the contract. None of our furniture matched our new house (of course, that would be made too much sense….), so we left most of the furniture there. My tenant, a school teacher, was excited about getting a home with nice stuff. Imagine my surprise three years later when my sofa, living room chair and desk were all destroyed. She apologized a ton, but no cash exchanged hands.
  2. Bolster your reserves or keep credit handy for surprises. We had a water leak, tree fall down, bathroom fan breakdown and flooding in the basement. If I didn’t have a reserve, there would have been trouble.
  3. Either live close to your rental or find reliable help. There are many people who will collect rent, fix up the house or manage the property, but most aren’t very good (according to my clients who were in real estate). You need great help or have to do as much work as possible yourself. I live halfway across the country from my rental, but have a great handyman, Dave, who is a quick call away, charges reasonable fees and responds lightening fast. To make sure he’s happy, I pay him the SECOND his bill arrives (that’s overstatement, but you know what I mean).
  4. Try to complete each “fix it” project yourself at least once, even if you’re going to find help.
  5. Remember that it’s a relationship with your tenant. My main goal is to have my tenant stay in the house. I’ve tried to make sure the house is well-maintained and I’m accessible so my tenant stays around. That said, I also need to keep up with economics. I’ve looked at rental prices in the area and raised the rent once in the past three years. I was poised to raise it again before I found out she had to move out (through no fault of mine…her son wants her to stay in his house while he’s away on business for two years. I can’t beat “free rent.”)

Are you a landlord? Have you rented from a good or bad landlord? Share your success or horror stories in the comments!

Photos: For Rent: Charleston’s The Digitel

Enhanced by Zemanta
Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.
joesaulsehy.com/

Filed Under: investment types, Real Estate, successful investing Tagged With: Contract, Donald Trump, Economic rent, Landlord, Real estate, Renting

5 Summer Activities to Create Money Savvy Kids: High School

June 26, 2012 by Joe Saul-Sehy 29 Comments

Ah, we made it! It’s most rewarding yet the most challenging to work with high school students on money management.

While these activities are the most fun for parents, high school students are more difficult to engage than younger children.

If you don’t have high school age children yet, you may not know this, but your brains will disappear for about four or five years.

Looking for tips for younger children? Try:

5 Educational Summer Activities For Kids – Early Elementary

or

5 Summer Activities to Create Money Savvy Kids: Upper Elementary to Middle School


5 Great High School Activities


1) Family book club. Right now, my 17 year old kids and I are reading I Will Teach You To Be Rich by Ramit Sethi. If you haven’t read this book yet, by all means, start now. It contains powerful advice wrapped in easy-to-understand language.

Every day the kids read a chapter. Then, at dinner, we discuss that day’s reading. Sometimes these conversations devolve (“why does a stock go up or down?” “what’s a good Roth IRA investment?”), but I love it. Who doesn’t want to have relaxed conversations about money with a curious 17 year old?

Why I like it: I get to ensure my kids get to college with some clue about money before they arrive. Because I made sure the book was fun and easy to read, and because I don’t preach, we’re able to have great talks about money.

2) Engage kids in the Family Meeting. If you’ve read this blog before, you’ll know that I love the idea of a family meeting. Budgets within a family are more about good communication than about counting pennies. If everyone is on the same page spending each day will be more careful, and life is made up of these little crisp 24 hour periods.

Some people have a violent reaction to this advice. “Show my kid my bills and my savings? That’s none of their business.” You are correct, but lets challenge your assumptions: why is it taboo to talk about your financial situation with others, especially those as close as your teenager.

Boundaries must be drawn. You’ll have to explain what happens when the whole street learns about your finances. But in the bigger picture, if they help you pay the bills, evaluate savings and plan large purchases, you’ll hand them a lifetime of knowledge that they’ll appreciate down the road.

Why I like it: When we began talking frankly with our children about bills and savings, they began to see how tight every month is for the average family. Next year we were planning on going to France for their graduation. The reality of two children in college at once has set in and we’re downgrading the vacation plan to a rental house on Lake Michigan for seven days. No groans from the kids because they understand the math behind the decision.


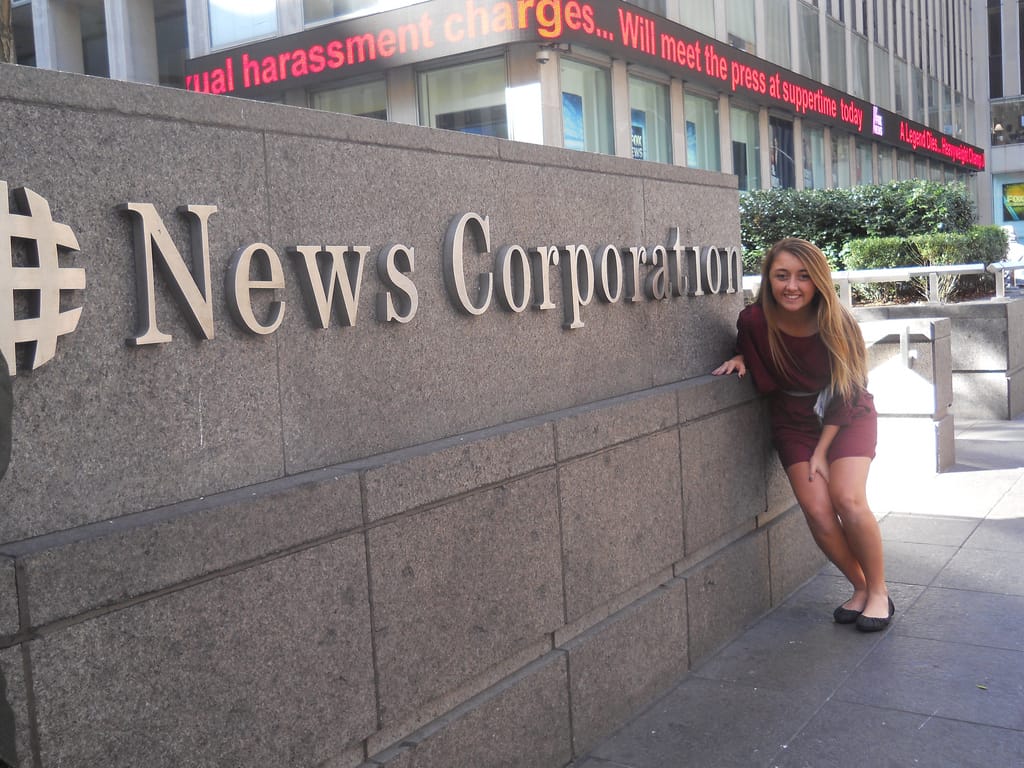
Young woman posing beside the News Corporation building sign during an internship

3) Find a job. I’m not talking about grabbing the local Dairy Queen gig (if I had that summer job I’d weigh about 750 pounds!). I’m talkin’ about helping junior through the process of fighting for a summer internship at a resume-building position. If they’re interested in engineering, try to find opportunities with a large local company. If law or medicine, apply at  the hospital, a law firm, or the local doctor’s office.

There’s a ton that junior learns while creating a resume, dressing appropriately and speaking well. The training involved in competing for these positions is a good primer in adult life skills.

Why I like it: By working in a professional environment, high school kids get a first hand look at how business works. Studies have shown that people who work in “real jobs” before college are more likely to do well in the classroom because they know how their learning might apply in the real world.

4) Scholarship hunt. Finding money for college is a full time job. The internet is brimming with opportunities for money, but you have to know who to ask and what scholarships to pursue. Most high schoolers only scratch the surface when it comes to searching for scholarships.

Instead of one-offing each opportunity, we found quickly that many of the scholarship opportunities were similar. My kids could write a couple of basic essays and then modify them to fit each particular offer. Most needed references from teachers and community members. We didn’t just learn about scholarship, we learned about creating systems to efficiently attack more quickly.

Why I like it: By formulating essays and asking for letters of reference, kids learn about the importance of written and verbal communication. They also realize that “going it alone” isn’t usually a good idea. It makes sense to find some powerful friends to help you….AND my kids were surprised that most powerful people want to help.

5) Board games. I’m back with more board games to teach the family about money. This time the games are downright fun for adults. Games such as Acquire can teach simple mergers and acquisitions. Power Grid is a modern-day version of monopoly involving power companies. And, in this year when the politics of the nation are up for grabs, 1960: The Making of a President is a good primer on the campaign process while also serving as a fun way to learn some history.

Why I like it: Board games are a great way to spend time with your kids. Instead of arguing or fighting about curfews and money, you’ll enjoying each other’s company over a communal activity.

How do you teach high school kids about money? Let’s have some more ideas in the comments below!


Photo Credit: Reading: NannySnowflake; Internship: ChesCrowell

Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: College Planning, kids and money, money management, Planning, successful investing

  • « Previous Page
  • 1
  • 2
  • 3
  • 4
  • 5
  • 6
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework