• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for tax planning

LLC Changes Most Small Business Owners Still Haven’t Accounted For

January 29, 2026 by Brandon Marcus Leave a Comment

The 2026 LLC Tax Changes Most Small Business Owners Still Haven’t Accounted For
Image source: shutterstock.com

Starting a small business is usually fueled by excitement, not spreadsheets. For many owners, forming an LLC feels like checking the “official” box and moving on.

Taxes and rules, however, have a way of sneaking back into the picture when you least expect them, especially when regulations shift quietly instead of with big announcements. Over the years, several important LLC-related tax and rule changes have taken effect or begun phasing out, and many owners are still operating as if nothing has changed. That can mean smaller deductions. It can also lead to higher tax bills, or compliance headaches that come as an unpleasant surprise.

These are the sort of surprises a small business owner does not want. A little knowledge can go a long way.

The Big Misunderstanding About How LLCs Are Taxed

One of the most common points of confusion is that an LLC is not taxed the same way for everyone. That hasn’t changed, but the impact of that flexibility has. By default, single-member LLCs are taxed like sole proprietorships. Meanwhile, multi-member LLCs are taxed like partnerships, meaning profits pass through to the owners’ personal tax returns.

LLCs can also choose to be taxed as an S corporation or a C corporation, which can change how income and payroll taxes work. What’s new is that changes in deductions and thresholds make these choices more important than they used to be. If you set your LLC tax structure years ago and never revisited it, now is a smart time to review whether it still fits your income and goals.

Proven and dedicated LLC owners will consistently reevaluate the latest tax laws to ensure they are in compliance. Anything short of following the rule correctly could lead them into hot water with the federal government. That can bring any business, no matter the size, to a screeching halt.

Bonus Depreciation (For Some) Is Here To Stay

Many LLC owners built their expectations around generous deductions that are changing. Bonus depreciation, which allows businesses to immediately deduct some or all of the cost of certain equipment purchases, has been made permanent by recent legislation. But that is only for specific equipment and machinery, also referred to as “qualified property,” purchased after January 19, 2025.

This is a reversal of previous plans that called for a “phase-out” over 20% annually. This change is a blessing to some companies. However, some LLC owners aren’t aware of the change, leading to unnecessary budgeting and planning.

A smart move for owners is to dig into their purchase history and ensure that their depreciation qualifies.
LLC Tax Changes Most Small Business Owners Still Haven’t Accounted For
Image source: shutterstock.com

New Reporting Rules That Catch Owners Off Guard

New reporting rules have become a major blind spot for LLC owners, and it’s leading to some wasting their precious time.

As of March 2025, LLCs are not required to report beneficial ownership information, also known as BOI, to the federal government. Previously, they were tasked with identifying who actually owns or controls the business. Now, only foreign entities are subject to BOI reporting—at least for now.

What was once true is not anymore, and knowing about this change could save business owners a ton of energy. However, it’s important to remember that these rules could change again. That’s another reason why business owners need to stay up-to-date.

The One Habit That Helps LLC Owners Stay Ahead

The most important takeaway from all of this is that LLC taxes and regulations are no longer something you can set and forget. Rules change gradually, and rollout takes time. Sometimes, the rollouts are completely reversed, meaning business owners need to pay close attention. Meanwhile, deductions fade away quietly, and reporting obligations expand or contract without much notice.

Owners who schedule regular check-ins, even once or twice a year, are far less likely to be caught off guard. Keeping basic records organized and asking direct questions about what’s changed can make a real difference. Staying curious and proactive is often the simplest way to protect your business and your peace of mind.

Have you ever been surprised by a tax, rule, or filing requirement you didn’t know applied to your LLC? Share your experience in the comments.

You May Also Like…

Is Forming an LLC the Right Move for Your Rental Property?

7 “Boring” Businesses That Make People Quietly Rich

14 Money Warnings Every Small-Business Owner Needs to Hear Right Now

10 Budget-Friendly Ways to Upgrade Your Company Office Space

9 Clever Strategies to Protect Assets From Future Lawsuits

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Business Tagged With: Business, business compliance, business practices, business rules, IRS rules, LLC tax, LLC taxes, pass-through income, R&D expensing, small business basics, small business taxes, Tax Deductions, tax planning

The IRS Reporting Threshold Change That Just Created a Tax Risk for Millions in 2026

January 26, 2026 by Brandon Marcus Leave a Comment

The IRS Reporting Threshold Change That Just Created a Tax Risk for Millions in 2026
Image source: shutterstock.com

If you’ve ever sold a vintage jacket on an app, picked up extra cash doing freelance work, or split dinner with friends via Venmo, you might have heard rumblings about a tax reporting change that could have snared millions of everyday Americans into unexpected IRS reporting paperwork in 2026.

The chatter about a strict new $600 rule had everyone from Etsy flippers to neighborhood babysitters biting their nails — but then Congress stepped in with a twist that changed the story entirely. And just like a tax-season plot twist, the IRS reporting threshold that once seemed so imminent has now shifted — in a big way.

The $600 Rule That Almost Was

For years, the IRS had been working toward lowering the reporting threshold for Form 1099-K, the tax document that payment processors like PayPal and Venmo send to both you and the IRS to report income received through their platforms. Under the American Rescue Plan Act of 2021, that threshold was slated to plummet to just $600, with no minimum transaction count attached — meaning that even a handful of casual transactions could have triggered a 1099-K form in 2026.

Tax professionals and everyday sellers alike were alarmed. Selling a couch, doing some freelance work, or even collecting contributions for a group gift suddenly looked like it could generate IRS paperwork. Millions of people stood on the brink of receiving tax forms for what they considered ordinary financial behavior — and that’s a recipe for confusion.

Enter The One Big Beautiful Bill Act

Then came a curveball: the One Big Beautiful Bill Act of 2025 — a massive tax and spending law signed July 4, 2025. Among its many provisions, it rewrote how 1099 reporting thresholds work. Instead of embracing the $600 threshold, Congress essentially hit rewind.

Under the new law, the 1099-K reporting threshold no longer drops to $600. Instead, it reverts to the old school standard that was in place before all this turmoil: you’ll receive a Form 1099-K only if you have more than $20,000 in gross payments and more than 200 transactions on a single payment platform in a calendar year.

That’s the rule that originally existed before the American Rescue Plan Act stirred the pot — and this reinstatement is retroactive for reporting years going back to 2022.

Why This Is Huge (But Not In The Way You Think)

Let’s be candid: for most folks, that old-school requirement of $20,000 and 200 transactions was already pretty high. Casual sellers, hobbyists, and part-time gigsters were rarely hitting both of those marks on a single platform in a year. So repeating that threshold makes a huge difference for day-to-day people.

Suddenly, that tiny Etsy shop selling handmade postcards — or that spinach quiche you flipped after thrift-shopping — probably won’t generate a 1099-K heading to your mailbox. But this doesn’t mean the IRS thinks the money isn’t taxable. It just means you won’t automatically get a tax form from PayPal or another processor for smaller totals.

It’s worth repeating: even if you don’t get a 1099-K, all income is still taxable. That’s tax law 101 — the presence (or absence) of a form doesn’t dictate your obligation to report income on your return.

The IRS Reporting Threshold Change That Just Created a Tax Risk for Millions in 2026
Image source: shutterstock.com

The New 1099 Thresholds For Businesses And Freelancers

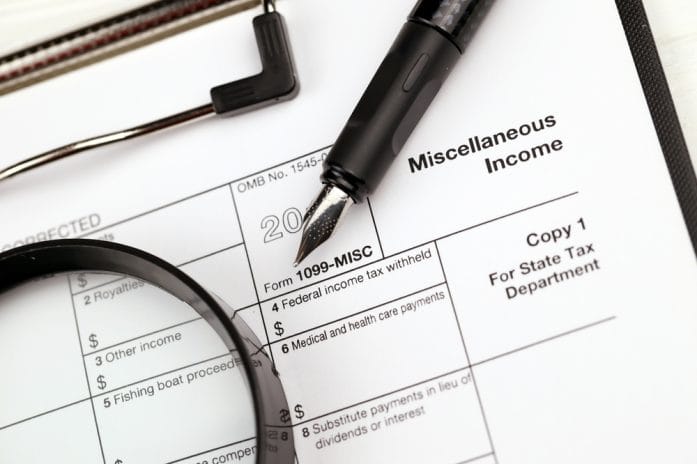
But wait — the tax fun doesn’t stop with Form 1099-K. The same law made other changes to reporting forms that matter to small businesses and freelancers. Specifically, the reporting threshold for Form 1099-MISC and Form 1099-NEC — used to report payments to contractors, landlords, and miscellaneous income — has been increased. Starting in 2026, businesses generally won’t need to issue these forms unless the total payments reach at least $2,000 in a year, and this threshold will be adjusted for inflation in future years.

This is a big deal for small outfits and side hustlers. Under the old $600 rule, a small business that paid a freelancer $800 could have had to send out a 1099-NEC. Now? Not until payments hit that higher $2,000 mark. That’s less paperwork, fewer forms flying around, and fewer opportunities for innocent mistakes to turn into IRS penalties.


What Do You Think?

This change in tax reporting thresholds for 2026 is one of those rare moments when tax law manages to ease confusion rather than amplify it. Between reinstating the $20,000/$200 1099-K standard and raising the bar on other 1099 forms, the law reshapes how everyday earners interact with IRS reporting. We’ve covered the facts, the history, and the implications — now we want to hear from you.

Tell us what this change means to you, how it might affect your side hustle or business, or even the tax tales you’ve lived through — drop your thoughts or experiences in the comments below!

You May Also Like…

IRS Warning: That Venmo Payment for Your Garage Sale Just Triggered a Surprise Tax Bill

What Your First Budget Of The Year Should Include

8 Tax Moves That Save You When You Can’t Pay the IRS on Time

5 Reasons To Talk To Your Kids About Taxes

6 Advanced Techniques to Lower Your Capital Gains Taxes Legally

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: tax tips Tagged With: 2026, 2026 laws, 2026 taxes, family finances, family money, finance, finances, general finance, Internal Revenue Service, IRS, IRS reporting, Money, money issues, tax planning, tax risk, tax risks, tax tips, taxes

Why Wealthy Families Are Moving Cash Out of Traditional Banks Before Jan 31st

January 14, 2026 by Brandon Marcus Leave a Comment

Why Wealthy Families Are Moving Cash Out of Traditional Banks Before Jan 31st
Image Source: Shutterstock.com

The financial world is buzzing with whispers, and not the boring kind that happens at a quiet dinner party. Imagine champagne bubbles of strategy popping in high-rise offices and sprawling estates, as wealthy families make moves that could change the way money flows in 2026. Suddenly, bank statements aren’t just numbers—they’re puzzles, and the puzzle solvers are plotting their moves before January 31st.

The stakes feel almost cinematic: hedge funds, tax incentives, and the looming presence of regulatory changes are all playing into a high-stakes game that affects fortunes, lifestyles, and yes, even the way you might think about your own checking account.

Changing Banking Habits Among The Wealthy

Over the past decade, there’s been a subtle but dramatic shift in how affluent families handle their liquid assets. Traditional banks, once the gold standard for safety and convenience, are now being scrutinized in a whole new way. With rising inflation, interest rate volatility, and new tax legislation, keeping large sums of money parked in conventional accounts is starting to look less like security and more like opportunity cost.

Wealth advisors are advising clients to diversify holdings, not just into investments like stocks and real estate, but into instruments that offer both protection and growth potential. The result? Families are moving cash into private banking solutions, alternative investment vehicles, and trusts designed to keep funds working harder than a savings account ever could. Timing is critical—January 31st isn’t just a date on the calendar; it’s a financial deadline that can influence tax outcomes and liquidity strategies.

Tax Planning Is Driving Urgency

One of the primary motivators behind these moves is tax strategy. The end of January often signals the close of certain fiscal opportunities for the previous year, especially for those who operate with complex estate plans or international assets. By transferring money out of traditional banks before this date, wealthy families can reduce exposure to specific taxes or take advantage of deductions and exemptions that vanish after the month ends. This isn’t about evading taxes—it’s about precision planning.

Wealthy families hire teams of tax attorneys and accountants who can choreograph financial maneuvers down to the exact day. In this context, the difference between moving cash on January 30th versus February 1st can amount to tens of thousands, sometimes even hundreds of thousands, of dollars in tax savings. The intensity of this timing creates a ripple effect, influencing financial behavior across sectors, from real estate to private equity.

Alternative Banking And Private Solutions Are Trending

Traditional banks offer convenience, but when money reaches the multi-million-dollar mark, families often crave more tailored solutions. Private banks, family offices, and alternative banking services provide options that standard accounts simply cannot. This can include higher-yield savings alternatives, structured products, or sophisticated hedging strategies designed to preserve wealth while generating returns. By moving funds before January 31st, families ensure they position themselves optimally for investment opportunities that only present themselves at the start of the calendar year.

These alternative solutions also offer enhanced privacy, more personalized advisory services, and sometimes exclusive investment opportunities that are simply inaccessible through conventional banking channels. In essence, it’s a move from mass-market convenience to boutique financial craftsmanship, and timing is everything.

Why Wealthy Families Are Moving Cash Out of Traditional Banks Before Jan 31st
Image Source: Shutterstock.com

The Role Of Economic Uncertainty

Economic uncertainty is another factor fueling this behavior. Interest rate changes, stock market fluctuations, and geopolitical tensions all play into how cash is managed at the highest levels. For families with substantial wealth, parking large sums in a traditional bank can feel like leaving money on a table in a casino where the odds are stacked against you. Moving money into more dynamic financial vehicles mitigates risk while opening doors to strategic opportunities. Advisors stress that proactive movement of funds is not reactive panic; it’s careful navigation. The period leading up to January 31st is critical because it aligns with financial reporting deadlines, investor cycles, and the release of new investment products, making timing not just strategic but essential. In a world where even a 1% difference in yield can represent millions, precision becomes almost an art form.

Estate Planning And Multi-Generational Strategy

For many wealthy families, moving cash isn’t just about the present—it’s about legacy. Estate planning often drives the redistribution of assets into trusts, family foundations, and intergenerational funds. By acting before January 31st, families can set up these structures in a way that maximizes both current tax benefits and long-term growth for heirs. It’s a delicate dance: ensure compliance with regulations, protect wealth from market volatility, and align with philanthropic goals. These actions often involve collaboration between legal teams, financial advisors, and investment managers, orchestrating a complex symphony of wealth preservation. This isn’t simply about money changing hands; it’s about shaping financial futures and ensuring that legacies endure across generations.

Technology And Data Are Changing The Game

Finally, technological tools have made these transitions smoother, faster, and more strategic than ever before. High-net-worth individuals now rely on sophisticated platforms to track global assets, automate transfers, and analyze tax implications in real time. Data analytics can simulate hundreds of scenarios, pinpointing the exact timing for optimal financial outcomes. This tech advantage magnifies the urgency of acting before January 31st, as algorithms crunch numbers that would take humans days to analyze manually. In this way, the movement of money is no longer just a practical necessity; it becomes a game of strategy where timing, intelligence, and foresight converge.

What’s Your Banking Take?

The January 31st deadline is more than a date—it’s a financial landmark that has families, advisors, and investors buzzing. Whether it’s about taxes, alternative banking, economic uncertainty, or legacy planning, the reasons wealthy families are moving cash out of traditional banks are varied, sophisticated, and fascinating.

If you’ve witnessed, been part of, or even just pondered the strategies behind such financial maneuvers, the floor is open. Drop your thoughts or stories in the comments below and let’s dive into the world where money, strategy, and timing intersect.

You May Also Like…

7 Unfavorable Truths About Marrying Into a Wealthy Family

5 Outrageous Fees Hidden in Everyday Banking Services

5 Warning Signs It’s Time To Change Banks

What Happens if Adult Children Control Your Online Banking Credentials

What Happens if Adult Children Control Your Online Banking Credentials


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Wealth Building Tagged With: banking, banking costs, banking habits, banking policies, Banks, Family, family advice, family issues, family money, money issues, tax planning, traditional banks, Wealth, wealthy families

Tax Foresight: 6 Planning Moves That Could Save You Money Soon

January 5, 2026 by Brandon Marcus Leave a Comment

Tax Foresight: 6 Planning Moves That Could Save You Money Soon
Image Source: Shutterstock.com

Fireworks don’t usually go off when someone mentions taxes, but this is where the story flips. Smart tax planning can feel like unlocking a secret level where the rewards are real cash, less stress, and way more control. Instead of scrambling at filing time, a little foresight lets you play offense, not defense, with your money.

These moves aren’t about loopholes or gimmicks; they’re about using existing rules wisely and confidently. Listen closely, because the right planning today can make future-you very glad you paid attention.

1. Maximize Retirement Contributions Early

Putting more into retirement accounts can reduce taxable income while building long-term wealth at the same time. Contributions to traditional 401(k)s and IRAs are often tax-deductible, which can lower what you owe this year. Starting early in the year spreads the impact across paychecks and feels less painful than a late rush. Many employers also match contributions, which is essentially free money with tax advantages. Over time, tax-deferred growth can turn consistent planning into serious savings.

2. Harvest Investment Losses Strategically

Tax-loss harvesting allows investors to sell underperforming assets to offset taxable gains elsewhere. This move can help reduce capital gains taxes without changing long-term investment strategy. Losses beyond gains may even offset a portion of ordinary income, within IRS limits. Timing matters, especially around year-end and wash sale rules. Done carefully, this strategy turns market dips into a planning advantage instead of a frustration.

3. Use Health Accounts As Stealth Tax Shields

Health Savings Accounts are one of the most tax-efficient tools available when paired with eligible health plans. Contributions are typically pre-tax, growth is tax-free, and qualified withdrawals avoid taxes entirely. Few accounts offer this triple benefit, which makes HSAs powerful long-term planning vehicles. Funds can roll over year after year, unlike flexible spending accounts. Treating an HSA as an investment account can quietly protect thousands from future taxes.

4. Time Income And Deductions With Intention

When income or expenses can be shifted, timing becomes a powerful planning lever. Deferring income to a later year may reduce exposure to higher tax brackets. Accelerating deductions, like charitable gifts or business expenses, can increase immediate tax benefits. This approach works especially well for freelancers, business owners, and retirees with flexible income streams. Thoughtful timing can smooth out tax bills and prevent unpleasant surprises.

Tax Foresight: 6 Planning Moves That Could Save You Money Soon
Image Source: Shutterstock.com

5. Take Credits Seriously, Not Casually

Tax credits directly reduce taxes owed, making them more valuable than deductions in many cases. Credits for education, childcare, energy efficiency, and dependent care can add up quickly. Eligibility rules matter, so awareness is key to claiming what’s allowed. Some credits are refundable, meaning they can boost refunds even if taxes owed are low. Missing credits often means leaving real money on the table.

6. Review Withholding And Estimated Payments Regularly

Withholding that’s too high gives the government an interest-free loan, while too low can trigger penalties. Regular reviews help align payments with actual tax obligations as life changes. Job shifts, side income, bonuses, and investments can all throw off estimates. Adjusting throughout the year keeps cash flow predictable and stress levels lower. This simple habit can prevent last-minute panic and unexpected bills.

Plan Ahead And Stay Curious

Tax planning doesn’t require obsession, but it does reward attention and curiosity. Each move builds on the idea that informed choices today can unlock savings sooner than expected. Everyone’s situation is different, which makes learning from others especially valuable.

If you’ve tried any of these strategies or learned something the hard way, the comments section below is waiting. Your experiences might spark someone else’s next smart move.

You May Also Like…

Income Threshold: 4 Hidden Taxes That Hit Once You Cross Certain Limits

9 Georgia Counties Where Property Taxes Are Set to Rise the Fastest

9 Financial Dangers of Ignoring Property Taxes

Tax Surge: 4 Income Types That Trigger Hidden Tax Bills

Income Stability: 6 Retirement Income Moves That Aren’t as Safe as They Seem

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Tax Planning Tagged With: 401(k), deductions, filing taxes, health accounts, Income, income taxes, retirement accounts, retirement contributions, retirement savings, tax planning, tax plans, tax tips, taxes

5 Reasons To Talk To Your Kids About Taxes

January 5, 2026 by Brandon Marcus Leave a Comment

Here Are 5 Reasons To Talk To Your Kids About Taxes
Image Source: Shutterstock.com

Taxes might sound like a snooze-fest, but they’re actually a secret superhero origin story for your kids’ financial future. This topic is packed with real-world drama, everyday relevance, and just enough mystery to spark curiosity at the dinner table. Kids already notice money leaving their wallets through games, apps, and allowances, so taxes are the next logical plot twist.

When you pull back the curtain early, you turn confusion into confidence and anxiety into “oh, I get it now.” Talking about taxes can be surprisingly fun, wildly empowering, and way more exciting than it gets credit for.

1. Taxes Teach Kids How The Real World Works

Taxes are woven into almost every grown-up money decision, so learning about them helps kids understand how society functions. Roads, schools, libraries, and parks suddenly make sense when kids see how dollars turn into shared benefits. This knowledge builds awareness that money isn’t just personal, but communal too. Kids begin connecting their daily experiences to larger systems around them. That connection helps them feel informed rather than confused as they grow.

2. Early Tax Talks Build Financial Confidence

When kids hear about taxes early, money stops feeling mysterious and intimidating. They learn that deductions, income, and paychecks are just concepts, not monsters. Confidence grows when kids realize adults are also learning and adapting, not magically born knowing everything. These conversations create a safe space for questions without embarrassment. Over time, kids trust their ability to handle real financial choices.

3. Taxes Encourage Smart Earning And Spending Habits

Understanding taxes helps kids see the difference between gross money and take-home money. That realization makes budgeting feel practical instead of restrictive. Kids start thinking ahead about saving, spending, and planning instead of impulse-buying everything in sight. They also learn that earning more doesn’t always mean keeping all of it. This perspective encourages thoughtful decisions long before adulthood hits.

Here Are 5 Reasons To Talk To Your Kids About Taxes
Image Source: Shutterstock.com

4. Tax Knowledge Sparks Curiosity About Careers And Goals

Talking about taxes opens the door to conversations about jobs, entrepreneurship, and side hustles. Kids discover that different careers are paid in different ways, each with unique tax responsibilities. This insight can spark curiosity about what they want to do and how they want to earn. It also introduces the idea that planning matters as much as passion. Suddenly, future goals feel tangible and exciting.

5. Taxes Teach Responsibility And Civic Awareness

Taxes show kids that being part of a community comes with responsibilities as well as benefits. They learn that contributing helps support things everyone relies on. This lesson encourages empathy, accountability, and awareness beyond personal gain. Kids begin to see themselves as active participants in society. That mindset sticks with them long after the conversation ends.

Turning Tax Talk Into A Family Superpower

Talking to your kids about taxes isn’t about drilling rules or memorizing forms, but about opening doors to understanding. These conversations can be light, playful, and surprisingly empowering when framed the right way. They help kids grow into adults who feel capable, informed, and ready for real-world challenges.

If you’ve had a funny moment, a tough question, or a big win while explaining taxes to your kids, we’d love to hear it. Drop your thoughts or stories in the comments below and keep the conversation rolling.

You May Also Like…

Income Threshold: 4 Hidden Taxes That Hit Once You Cross Certain Limits

9 Georgia Counties Where Property Taxes Are Set to Rise the Fastest

6 Advanced Techniques to Lower Your Capital Gains Taxes Legally

Legacy Debt: 5 Family Conversations That Help Prevent Wealth From Becoming a Burden

6 Bad Money Habits Families Show During The Holidays


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: tax tips Tagged With: children., families, Family, family issues, family money, financial choices, financial confidence, financial discussions, income taxes, kids, overspending, Smart Spending, spending, Spending Habits, tax planning, taxes

Tax Finale: 6 Year-End Moves to Complete Before New Rules Arrive

January 1, 2026 by Brandon Marcus Leave a Comment

Tax Finale: 6 Year-End Moves to Complete Before New Rules Arrive
Image Source: Shutterstock.com

The clock is ticking, the calendar is flipping, and tax season is creeping closer than you think. But before the champagne corks pop and the New Year kicks off, savvy taxpayers know there’s a final sprint to financial finesse that can save serious money.

This is not your average dull accounting lecture—this is a high-stakes, year-end tax finale where strategy meets opportunity. From clever deductions to timing income, every move you make now can be a game-changer. Today, we’re diving into six essential maneuvers that could protect your wallet before new rules shake everything up.

1. Max Out Retirement Contributions For Maximum Benefits

Contributing to retirement accounts isn’t just about securing your future—it’s an immediate tax shield. IRAs, 401(k)s, and other retirement vehicles allow you to potentially lower your taxable income before the year ends. If you haven’t maxed out your contributions, now is the perfect moment to catch up and claim those tax advantages. Even a few extra thousand dollars funneled into these accounts can significantly reduce your 2025 tax liability. Don’t wait until January; every dollar counted this year could make a real difference.

2. Harvest Tax Losses To Offset Gains

Investors, this one’s for you. Selling underperforming investments before year-end allows you to claim a tax loss, which can offset capital gains and even reduce ordinary income up to certain limits. Known as tax-loss harvesting, this tactic is a powerful way to lower your tax bill while keeping your portfolio aligned with long-term goals. Remember, you can carry over unused losses into future years, extending the benefit beyond 2025. Check your investment statements carefully, because strategic sales now could save you big in April.

3. Accelerate Or Delay Income Strategically

Timing is everything when it comes to taxable income. If you expect to be in a higher tax bracket next year, consider accelerating deductions and deferring income to reduce your current-year liability. Conversely, if your income might spike this year, delaying certain receipts until the next tax year can lower your immediate tax exposure. Even bonuses, freelance payments, or consulting fees can be shifted with careful planning. Consulting a tax professional ensures these maneuvers follow IRS rules without triggering unwanted penalties.

4. Review Charitable Contributions For Extra Deductions

Charitable giving isn’t just about goodwill; it can also be a smart tax strategy. Cash donations, appreciated stocks, and even certain expenses can qualify as itemized deductions, reducing your taxable income. Be sure to document everything carefully with receipts and acknowledgment letters from the charities. Consider bunching contributions into a single year to surpass the standard deduction and maximize savings. Doing a year-end charitable review could turn your generosity into a strategic financial win.

Tax Finale: 6 Year-End Moves to Complete Before New Rules Arrive
Image Source: Shutterstock.com

5. Check Flexible Spending And Health Savings Accounts

Your FSA and HSA balances aren’t just numbers—they’re potential tax savers. Use up remaining FSA funds on eligible medical or dependent care expenses before they vanish, as many accounts have a “use-it-or-lose-it” policy. Contributions to HSAs can be made until the tax filing deadline, offering both immediate tax deductions and long-term growth potential. Investing in healthcare expenses now not only benefits your health but also reduces taxable income. Review deadlines and eligible expenses carefully to avoid missing out on these hidden benefits.

6. Reevaluate Estate And Gift Planning Moves

Estate planning isn’t just for the ultra-wealthy—it’s a tool anyone can leverage for tax efficiency. Gifts up to the annual exclusion amount may be tax-free, helping reduce your taxable estate while benefiting loved ones. Consider strategies like 529 plan contributions for education or gifting appreciated assets instead of cash to maximize tax advantages. Reviewing trusts, wills, and beneficiary designations ensures everything aligns with your current goals. Year-end is the perfect checkpoint to make sure your estate strategy is both effective and compliant.

Last-Minute Tax Moves Can Make A Big Difference

Year-end tax planning may feel overwhelming, but taking action now can pay dividends in both savings and peace of mind. These six moves—maxing retirement contributions, harvesting losses, timing income, boosting charitable deductions, checking FSAs/HSAs, and reviewing estate strategies—are all tools in your financial toolkit. Waiting until the new rules take effect could mean missed opportunities and higher tax bills.

Take a proactive approach, assess your finances carefully, and consult a professional if needed. Let us know your thoughts or any experiences you’ve had with year-end tax planning in the comments section below.

You May Also Like…

Income Threshold: 4 Hidden Taxes That Hit Once You Cross Certain Limits

9 Georgia Counties Where Property Taxes Are Set to Rise the Fastest

Can Your Taxes Be Cut In Half By You Simply Incorporating Your Name?

What Happens When Small Business Owners Skip Taxes

Regulation Spotlight: 8 New Advice Rules Clients Must Prepare For


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: tax tips Tagged With: charitable contributions, Estate plan, Estate planning, flexible spending, gift plan, gift planning, health savings account, Income, retirement accounts, retirement contributions, retirement plan, retirement planning, tax losses, tax plan, tax planning, tax regulations, tax rules, tax tips, taxes

Tax Ahead: 4 Strategic Moves If You Think Congress Will Rewrite Tax Rules

December 30, 2025 by Brandon Marcus Leave a Comment

Tax Ahead: 4 Strategic Moves If You Think Congress Will Rewrite Tax Rules
Image Source: Shutterstock.com

Congress is like that unpredictable relative who shows up to dinner unannounced, changes the rules mid-meal, and somehow leaves you scrambling to adjust. When it comes to taxes, the stakes are even higher. One minute your strategy seems solid, the next a new proposal or legislative tweak could flip your financial plan upside down.

For anyone who wants to keep more of their hard-earned money and avoid last-minute panic, understanding potential changes—and acting before they happen—is crucial.

1. Reassess Your Retirement Contributions Immediately

If Congress hints at changing tax treatment for 401(k)s, IRAs, or other retirement vehicles, waiting until the last minute could cost you thousands. By reassessing contributions now, you can maximize tax-deferred growth before any new limits or rules hit. Consider whether shifting from a traditional account to a Roth account—or vice versa—aligns with potential legislative changes. Tax-free withdrawals in the future could be a game-changer if rates go up. Staying proactive now allows you to adapt smoothly without scrambling when new rules become law.

2. Reevaluate Capital Gains Strategies

Capital gains taxes are notoriously sensitive to legislative tinkering. If Congress starts talking about raising rates or changing how gains are calculated, it’s wise to examine your investments. Harvesting losses strategically can offset gains and reduce tax liability, even before any law changes take effect. Long-term planning, such as holding assets for over a year, might save you from higher future rates. Working with a financial advisor now ensures your portfolio is positioned to ride out potential changes without unnecessary losses.

3. Explore Timing Large Deductions Or Expenditures

The timing of deductions can suddenly become a high-stakes game when tax rules are in flux. If new legislation limits deductions or alters thresholds, accelerating deductible expenses now could lock in savings. Charitable donations, mortgage interest, and state taxes paid might be especially worth front-loading. Conversely, some taxpayers may benefit from deferring expenses if future rules allow higher deductions. Paying attention to timing isn’t just strategic—it can transform potential tax headaches into manageable planning wins.

Tax Ahead: 4 Strategic Moves If You Think Congress Will Rewrite Tax Rules
Image Source: Shutterstock.com

4. Reconsider Business And Investment Structures

Business owners and investors should treat potential tax reforms like a chessboard. Changing how corporations, partnerships, or LLCs are taxed can dramatically impact take-home profits. Evaluating the structure of your business or investment accounts now could avoid costly restructuring later. Shifts in pass-through taxation, qualified business income deductions, or international tax rules are not far-fetched under current congressional conversations. Taking action early helps you stay flexible and potentially minimize liabilities while Congress debates new rules.

Take Control Before Rules Change

Waiting until Congress finalizes new tax laws is like waiting for a storm to hit before closing the windows—you’ll almost always regret it. The smartest taxpayers act preemptively, reassessing contributions, investments, deductions, and business structures now. Planning ahead can turn uncertainty into opportunity, saving money and stress. By taking deliberate steps today, you position yourself to adapt without scrambling.

Let us know your thoughts, experiences, or strategies in the comments section below—we’d love to hear how you approach shifting tax landscapes.

You May Also Like…

Income Threshold: 4 Hidden Taxes That Hit Once You Cross Certain Limits

9 Georgia Counties Where Property Taxes Are Set to Rise the Fastest

10 Lesser-Known Tax Rules That Cost Households Big Money

Is Your Social Security About to Shrink Unless Congress Acts Fast?

7 ATM Withdrawal Behaviors That Raise Government Surveillance Flags


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Tax Planning Tagged With: capital gains, Congress, deductions, Government, government policy, retirement account, retirement contribution, retirement plan, retirement planning, Tax, tax moves, tax planning, tax rules, taxes, United States

Tax Blindspot: 4 Deductions Many Americans Miss During December

December 21, 2025 by Brandon Marcus Leave a Comment

Tax Blindspot: 4 Deductions Many Americans Miss During December
Image Source: Shutterstock.com

December isn’t only about amazing holiday lights, frantic gift shopping, and cookie overload. Instead, this time of year is also a secret window for sneaky tax savings.

While most Americans are busy decking the halls, a lot of valuable tax deductions quietly slip through their fingers. Ignoring these opportunities can cost you hundreds, even thousands, of dollars when April rolls around. But here’s the good news: knowing where to look and what counts could turn your end-of-year chaos into financial brilliance.

We’re about to turbocharge your tax knowledge and show you deductions you probably didn’t even know existed.

1. Charitable Contributions Count More Than You Think

Donating to your favorite charity isn’t just good karma—it’s a tax move that often goes unnoticed. If you’ve been generous with gifts or cash in December, you may qualify for deductions even if you didn’t itemize earlier in the year. Keep careful records, receipts, and donation confirmations to ensure Uncle Sam knows you’re giving with good intentions. Cash donations, clothing, and even certain household items can all count toward this deduction. Timing is everything, so getting your contributions in before December 31 could make a real difference on your tax bill.

2. Medical Expenses Can Be Sneaky Deductibles

Most people assume medical expenses are only relevant when a doctor’s visit is long past, but December is prime time to review them. Costs that aren’t reimbursed by insurance, including prescription medications, dental work, and certain vision care, can be deducted if they surpass a specific percentage of your adjusted gross income.

Some Americans forget that last-minute medical bills or even over-the-counter purchases with proper documentation can qualify. Review your records carefully and consider scheduling appointments or purchasing necessary medical items before the year ends. These small moves can quietly chip away at what you owe the IRS.

3. Tax-Loss Harvesting Isn’t Just For Wall Street Pros

If you have investments, December might be your golden opportunity for tax-loss harvesting—a fancy term for selling losing investments to offset gains. Many investors overlook this strategy until it’s too late, missing out on lowering their taxable income. You can use losses to offset capital gains and even deduct a portion against ordinary income. But be mindful of the “wash-sale” rule, which prevents you from buying the same stock back too quickly. Strategically reviewing your portfolio before the year’s close can create a substantial end-of-year tax advantage without any drastic moves.

Tax Blindspot: 4 Deductions Many Americans Miss During December
Image Source: Shutterstock.com

4. Flexible Spending Accounts: Don’t Let Your Money Vanish

Flexible Spending Accounts (FSAs) are like little time bombs—you contribute pre-tax dollars for health expenses, but if you don’t use them, they often disappear. December is crunch time: if you still have a balance, use it for eligible items like glasses, contact lenses, or even certain medical equipment. Some plans allow a short grace period or a small rollover, but don’t assume you’ll get an automatic extension. By spending FSA funds wisely before the deadline, you essentially reduce your taxable income without touching your regular cash. It’s like finding free money for your wallet—one of the few December gifts that actually pays you back.

Don’t Let These Deductions Slip Away

End-of-year tax planning isn’t glamorous, but it can feel exhilarating once you realize how much you might save. Charitable contributions, medical expenses, investment losses, and FSA balances are all often overlooked ways to trim your tax bill. Act now, because December is your last chance before the calendar flips. By taking a few focused steps, you can turn ordinary holiday chaos into a strategic financial win.

If you’ve ever uncovered a deduction that surprised you or made a real difference in your tax return, we’d love for you to tell us about it in the comments section below.

You May Also Like…

Tax Freeze: 6 Immediate Actions to Lock In Lower Rates Before Reforms Hit

Should You Make A Roth Conversion Now Or Wait For January’s Tax Environment To Settle?

Savings Game: 5 Ways to Boost Your Emergency Fund Before December Ends

Tax Bonanza: The Tax Move That Saves Thousands—But Only If You Do It Before December 31st

Why Do Middle-Class Families End Up Paying the Most Taxes


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: tax tips Tagged With: 2025 taxes, America, Americans, December, file taxes, financial plans, Planning, Tax, tax blindspot, tax deadlines, tax deduction, Tax Deductions, tax laws, tax planning, taxes, United States, winter

The Gig Economy Tax Nightmare: Why So Many Freelancers End Up Owing the IRS

October 30, 2025 by Travis Campbell Leave a Comment

taxes
Image source: shutterstock.com

The gig economy continues to grow rapidly as more people choose to work as freelancers. Flexible hours and the chance to be your own boss are appealing. Freelancers discover a surprising truth about taxes when they need to file their taxes. The gig economy tax nightmare is real, and it’s catching thousands of independent workers off guard. Freelancers who work independently will often discover they need to pay the IRS more than their initial estimates, which can result in substantial additional amounts.

Why does this happen? The situation resulted from a combination of public confusion, insufficient preparation, and complex tax regulations. The following explanation identifies the primary reasons gig workers face tax issues, helping you avoid these common mistakes.

1. No Taxes Withheld Upfront

Traditional employees have federal and state taxes withheld from every paycheck. Freelancers, on the other hand, usually receive the full amount for every job. Platforms like Uber, DoorDash, or Upwork don’t automatically deduct taxes. That means it’s up to you to set money aside for the IRS. This is a core part of the gig economy tax nightmare. It’s easy to forget, and even easier to spend the money you should be saving for taxes. Many freelancers don’t realize the IRS expects them to pay quarterly. By the time April comes, the tax bill can be overwhelming.

2. Misunderstanding Self-Employment Tax

Gig workers are considered self-employed. This means you’re responsible for both the employer and employee portions of Social Security and Medicare taxes. That’s a total of 15.3% on top of your regular income tax. Many freelancers focus only on income tax and forget about self-employment tax. The result? They seriously underestimate how much they owe. When the IRS calculates the full amount, the bill can be hundreds or even thousands of dollars more than expected.

3. Inconsistent Income Makes Planning Hard

Unlike a steady paycheck, gig work income can fluctuate from month to month. Some months are great, others are slow. This makes it hard to predict how much to set aside for taxes. Many freelancers guess or wait until the end of the year to figure it out. But the IRS doesn’t care if your income is unpredictable. If you don’t make estimated payments on time, you could get hit with penalties and interest. This unpredictability is a major part of the gig-economy tax nightmare for many independent workers.

4. Overlooking Deductible Expenses

Freelancers can deduct business expenses, which lowers taxable income. But many gig workers don’t track these costs or don’t realize what counts as a deductible expense. Missed deductions mean you pay more tax than necessary. Common expenses include mileage, supplies, home office costs, and even part of your phone bill. Not keeping good records or not knowing the rules means you leave money on the table—and that’s money that could help cover your tax bill.

5. Confusion Over 1099 Forms and Reporting

Freelancers often receive multiple 1099-NEC or 1099-K forms from clients and platforms. Some income might not be reported at all if it’s under $600, but you’re still legally required to report it. Many gig workers don’t realize this and fail to include all their earnings. The IRS gets copies of those forms, and mismatches can trigger audits or penalties. This confusion adds to the gig economy tax nightmare and makes tax time stressful for freelancers.

6. Not Making Estimated Quarterly Tax Payments

The IRS expects self-employed workers to pay taxes throughout the year, not just in April. If you owe more than $1,000 in taxes, you’re supposed to make estimated payments quarterly. Many freelancers skip this step, either because they don’t know about it or because cash flow is tight. Missing these payments can lead to penalties and interest. By the time you file your tax return, you may owe a lot more than just your original tax bill. This is a painful surprise for many in the gig economy.

7. State and Local Taxes Are Easy to Forget

Federal taxes are only part of the story. Many states also require estimated payments or have their own tax rules for freelancers. Some cities and counties also impose business taxes or licenses. If you don’t keep up, you could owe back taxes at the state or local level as well.

Staying on top of all these requirements is tough, especially if you work gigs in multiple states. This adds another layer to the gig economy tax nightmare, making it even more complicated for freelancers to stay compliant.

How to Tame the Gig Economy Tax Nightmare

The gig economy tax nightmare doesn’t have to be inevitable. Most financial experts recommend reserving a portion of each payment for taxes, typically 25% to 30%. Use a separate savings account if possible. Every business expense needs to be tracked, regardless of size, and all receipts should be stored either digitally or physically. You should make quarterly payments to both the IRS and your state government, even though your income levels change throughout the year. You should use a tax professional or reputable tax software when you are unsure about tax rules or payment amounts.

The gig economy offers people independence, but they must handle all the responsibilities that come with it. Freelancers who understand the tax rules for their work can plan their finances to avoid unexpected tax bills, which often leave gig economy workers owing money to the IRS.

Have you experienced a gig economy tax nightmare? What specific actions have you taken to prevent tax problems when working as a freelancer? Share your story in the comments!

What to Read Next…

  • 5 Account Transfers That Unexpectedly Trigger IRS Penalties
  • 7 Ill Advised Advisor Tips That Trigger IRS Audits
  • 9 Mistakes That Turned Wealth Transfers Into IRS Nightmares
  • What Tax Preparers Aren’t Warning Pre Retirees About in 2025
  • 6 Tax Breaks That Vanished Before Anyone Noticed
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Tax Planning Tagged With: 1099, freelancers, gig economy, IRS, Self-employment, tax planning, taxes

8 Effective Strategies for Utilizing Donor Advised Funds Wisely

October 24, 2025 by Travis Campbell Leave a Comment

donor funds
Image source: shutterstock.com

Using donor advised funds wisely can make a big difference in how you support causes you care about. These funds offer flexibility, tax advantages, and a practical way to organize your charitable giving. But with so many options and rules, it’s easy to feel overwhelmed. Making thoughtful choices ensures your contributions have the strongest impact and align with your financial goals. Let’s look at eight effective strategies for utilizing donor advised funds wisely, so you can make the most of your philanthropy.

1. Set Clear Philanthropic Goals

Before contributing to a donor advised fund, take time to define your charitable mission. What causes matter most to you? Are you interested in supporting local organizations, education, health, or international aid? By clarifying your priorities, you can focus your giving and avoid spreading resources too thin. Clear goals also help you measure your impact over time, making it easier to see the results of your generosity.

2. Time Your Contributions for Maximum Tax Benefit

One of the most appealing features of donor advised funds is their tax efficiency. You can contribute cash, stocks, or other appreciated assets and take an immediate tax deduction. To utilize donor advised funds wisely, consider making larger contributions in high-income years or when you have significant capital gains. This approach can reduce your tax bill and allow you to give more. Talk with a tax advisor to plan the best timing for your situation.

3. Donate Appreciated Assets Instead of Cash

Donating appreciated stocks, mutual funds, or other assets directly to your donor advised fund is often more tax-efficient than giving cash. When you transfer these assets, you avoid paying capital gains taxes and can deduct the full fair market value. This strategy frees up more money for your favorite charities and helps you diversify your portfolio at the same time.

4. Involve Your Family in Giving Decisions

Utilizing donor advised funds wisely isn’t just about tax planning—it’s also a great way to engage your family in philanthropy. Involve your children or other relatives in deciding which organizations to support. This can help pass down your values, teach financial responsibility, and create a shared sense of purpose. Many families use donor advised funds as a tool for multigenerational giving and legacy building.

5. Take Advantage of Investment Growth

Most donor advised funds allow you to invest your contributions, so the balance can grow tax-free over time. By selecting suitable investment options, your fund may increase in value and provide even more for charity in the future. Review your investment choices regularly to ensure they align with your risk tolerance and giving timeline. Taking a long-term approach helps you utilize donor advised funds wisely and maximize their impact.

6. Research Charities Thoroughly Before Recommending Grants

Before recommending a grant from your donor advised fund, take time to research the charities you want to support. Look at their financial health, transparency, and effectiveness. Tools like Charity Navigator make it easy to compare organizations. This extra step ensures your grants go to trustworthy groups that align with your values and make real progress toward their missions.

7. Consider Bunching Contributions for Greater Tax Impact

If your annual charitable giving doesn’t always exceed the standard deduction, consider bunching several years’ worth of donations into a single year. By doing this, you can itemize deductions and potentially lower your taxes in the year you contribute. Then, you can recommend grants to charities from your donor advised fund gradually over time. This approach is especially useful for those who want to utilize donor advised funds wisely and plan ahead for future giving.

8. Stay Informed About Rules and Fees

Every donor advised fund has its own policies, minimums, and fee structures. Some charge administrative fees or have restrictions on grant amounts and eligible charities. Review the terms carefully before opening or adding to your fund. Staying informed helps you avoid surprises and ensures you’re getting the most value for your contributions.

Making Your Donor Advised Fund Work for You

Utilizing donor advised funds wisely is about more than just the tax break. With clear goals, careful planning, and ongoing involvement, you can make your charitable giving more effective and meaningful. These strategies help you organize your philanthropy, get the most from your assets, and support the causes you care about for years to come.

How do you use your donor advised fund to support your favorite organizations? Share your experiences and tips in the comments!

What to Read Next…

  • 7 Times Generosity Has Legal Consequences for Seniors
  • Why Some Charitable Bequests Are Being Rejected in Probate Court
  • What Trusts Experts Say Should Never Share Digital Assets
  • 8 Legacy Plans That Fail When Heirs Aren’t Informed
  • 7 Inheritance Mistakes That Financial Advisors Warn Against
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: charitable giving Tagged With: charitable giving, donor-advised funds, family finance, investment strategies, philanthropy, Planning, tax planning

  • « Previous Page
  • 1
  • 2
  • 3
  • 4
  • 5
  • 6
  • …
  • 10
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework