• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Personal Finance

6 Shocking Things Debt Collectors Are Legally Allowed to Do

October 11, 2025 by Travis Campbell Leave a Comment

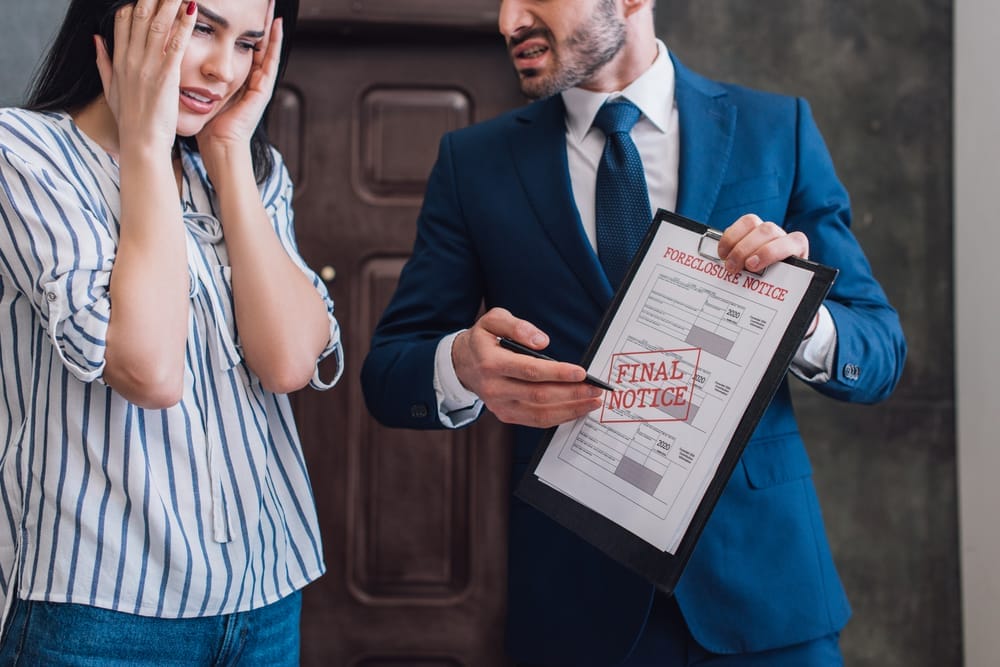
debt collectors
Image source: shutterstock.com

If you’ve ever fallen behind on a bill, you might have experienced the stress of hearing from a debt collector. These calls and letters can feel intimidating, but knowing your rights is crucial. Many people are surprised to learn just how much power debt collectors actually have under the law. Understanding what debt collectors are legally allowed to do can help you protect yourself and make informed decisions. This knowledge may even help you avoid unnecessary anxiety or costly mistakes. Let’s break down six shocking things debt collectors are permitted to do—and what you can do about it.

1. Contact You Repeatedly—Within Limits

One of the most surprising things about debt collectors is how persistent they can be. The Fair Debt Collection Practices Act (FDCPA) allows debt collectors to contact you by phone, mail, email, or even text message. As long as they follow certain rules, they can reach out multiple times a week. However, they are not allowed to harass you or call at unreasonable hours (typically before 8 a.m. or after 9 p.m.).

While it might feel overwhelming, these repeated contacts are legal as long as collectors avoid threats or abusive language. If you want the calls to stop, you can request in writing that the debt collector only communicate in certain ways, or not at all. Keep a record of your communications to protect yourself if the situation escalates.

2. Discuss Your Debt With Your Spouse or Attorney

Many people assume that debt collectors must keep your information completely private. In reality, collectors are allowed to discuss your debt with your spouse or your attorney. This is especially true if you live in a community property state, where spouses may share responsibility for certain debts.

However, debt collectors cannot share information about your debt with unauthorized third parties, such as your employer or neighbors. If they do, that could violate your rights under the FDCPA. If you have legal representation, direct the collector to speak with your attorney to avoid further direct contact.

3. Seek Payment for Old Debts

Another shocking thing debt collectors are legally allowed to do is try to collect on debts that are many years old. These are often called “zombie debts.” Even if the statute of limitations has expired, a collector can still ask you to pay. The catch? They can’t sue you to collect the debt if it’s past the statute of limitations, but they can keep contacting you and requesting payment.

Be very careful before making any payments or promises on old debts. In some states, making a payment or acknowledging the debt can restart the statute of limitations, making you legally responsible for it again. If you’re unsure about your rights, consult a consumer protection attorney or reach out to a reputable resource like the Consumer Financial Protection Bureau.

4. Report Your Debt to Credit Bureaus

Debt collectors can report your unpaid debts to the major credit bureaus, which can damage your credit score. This is one of the most powerful tools they have. Negative information can stay on your credit report for up to seven years, even if the debt is eventually paid off or settled.

This legal power is a major reason why it’s important to address debt collection issues quickly. Ignoring a debt collector doesn’t make the problem go away—it can make things worse by hurting your ability to borrow money, rent an apartment, or even get a job in some cases. Regularly check your credit report to see what information is being reported, and dispute any errors you find.

5. Sue You for Unpaid Debts

Yes, debt collectors are legally allowed to take you to court to try to collect what you owe. If you ignore their attempts to contact you, they may file a lawsuit. If you fail to respond to the court summons, the collector can win the case by default, which could lead to wage garnishment or liens on your property.

It’s vital to respond to any legal notices you receive, even if you think the debt isn’t valid. Show up in court with any evidence you have. Sometimes collectors don’t have the proper paperwork, which may allow you to get the case dismissed. If you’re sued, consider seeking help from a legal aid organization or a consumer attorney familiar with debt collection laws.

6. Negotiate Settlement Offers

It may surprise you to learn that debt collectors are legally allowed to negotiate and settle debts for less than the full amount owed. This means you can often work out a payment plan or a lump-sum settlement that resolves the debt for a lower amount.

This flexibility gives you some leverage. If you’re struggling to pay, don’t be afraid to negotiate. Get any settlement agreement in writing before sending money. Keep all records of your communication and payments. Remember, settling a debt for less than you owe may still impact your credit, but it can help you move forward financially.

Know Your Rights With Debt Collectors

Understanding what debt collectors are legally allowed to do can help you take control of your financial situation. The primary keyword here is “debt collectors,” and knowing their limits is essential for protecting your rights. While some of their powers may seem extreme, there are clear boundaries in place to prevent abuse.

Stay proactive: keep records, respond promptly, and never ignore legal notices. If you ever feel a collector is crossing the line, don’t hesitate to seek help or file a complaint. Being informed puts you in a stronger position to resolve debts and rebuild your financial future.

Have you had a surprising experience with debt collectors? Share your story or questions in the comments below!

What to Read Next…

  • 5 Emergency Repairs That Could Force You Into Debt Overnight
  • 5 Things That Instantly Decrease Your Credit Score By 50 Points
  • Why Are So Many Seniors Being Sued Over Student Loans They Didn’t Take Out?
  • What Happens If Your Spouse Has Secret Debt You Didn’t Know About?
  • 7 Legal Loopholes That Let Authorities Freeze Assets Without Warning
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Debt Management Tagged With: consumer rights, credit report, debt collection, Debt Collectors, Personal Finance, statute of limitations

8 Different Ways to View Money as a Tool, Not a Tyrant

October 11, 2025 by Travis Campbell Leave a Comment

money tool
Image source: shutterstock.com

Money can feel overwhelming. For many, it brings stress, anxiety, or even guilt. But what if you changed your relationship with money? Instead of letting it control you, you can learn to see money as a tool. This mindset shift helps you make better decisions and reduces emotional baggage. When you view money as a tool, not a tyrant, you gain confidence and clarity. It’s about using money intentionally, not letting it dictate your happiness or self-worth. Here are eight practical ways to put this perspective into action.

1. Set Clear Intentions for Your Money

When you see money as a tool, you give it a purpose. Decide what you want your money to do for you—whether that’s paying off debt, building an emergency fund, or funding a dream vacation. Setting clear intentions keeps you focused. It turns spending and saving into conscious choices, not random reactions. This approach helps you avoid drifting or feeling powerless about your finances.

2. Align Spending With Your Values

Think about what matters most to you. Is it family, freedom, learning, or security? Use money to support those values. For example, if health is a priority, you might invest in a gym membership or nutritious food. If travel excites you, save for meaningful trips. Aligning your spending with your values ensures that money works for you, not against you. This is a key part of learning to view money as a tool, not a tyrant.

3. Break Free From Scarcity Thinking

Scarcity thinking makes money feel like a constant source of worry. Instead, remind yourself that money is renewable. You can earn more, save more, and learn new skills. Viewing money as a tool means recognizing its potential rather than its limits. This mindset shift opens you up to opportunities and helps you avoid making fear-based decisions. You become proactive instead of reactive.

4. Use Budgets as Empowerment, Not Restriction

Budgets often get a bad rap. They seem restrictive, like a diet for your wallet. But a budget is just a plan for using your money as a tool to reach your goals. It gives you control and clarity. When you track your spending, you know exactly where your money goes. This empowers you to make changes if needed, without guilt or shame. A budget is a roadmap, not a prison.

5. Invest in Experiences and Growth

Money can buy things, but it can also open doors to new experiences and personal growth. Spending on education, travel, or hobbies can enrich your life far more than accumulating stuff. When you view money as a tool, you see its power to help you learn, connect, and grow. These investments can pay off for years to come—sometimes in ways you never expected.

6. Separate Self-Worth From Net Worth

It’s easy to let your bank balance influence your self-esteem. But your value as a person isn’t tied to your financial status. Viewing money as a tool, not a tyrant, means recognizing that money is just one resource among many. It’s useful, but it doesn’t define you. Celebrate progress, not perfection. Focus on healthy financial habits, not just numbers on a screen.

7. Prepare for the Unexpected

Life is full of surprises—some good, some not so much. Use money as a tool to build an emergency fund or get the right insurance. This gives you a safety net and peace of mind. Preparation isn’t about expecting disaster; it’s about being ready for whatever comes your way. When you’re prepared, money loses its power to scare you. You stay in control.

8. Seek Reliable Guidance and Tools

You don’t have to figure it all out alone. There are plenty of resources that can help you improve your financial literacy and make better choices. For example, you might use a free budgeting app or follow advice from trusted sources like the Consumer Financial Protection Bureau. Learning from others helps you use money as a tool more effectively. Reach out to professionals, read books, or join online communities for support.

Money as a Tool: The Path to Financial Freedom

Changing your mindset takes time, but it pays off. When you consistently view money as a tool, not a tyrant, you take charge of your financial future. You make decisions with intention, confidence, and flexibility. Money becomes a means to an end—not the end itself. This shift reduces stress and helps you reach your goals on your own terms.

How have you learned to use money as a tool in your life? Share your experiences and tips in the comments below!

What to Read Next…

  • Are These 8 Money Saving Tricks Actually Keeping You Broke?
  • 8 Things Rich People Never Finance And You Shouldn’t Either
  • 10 Ways You’re Wasting Money Just Trying To Keep Up Appearances
  • Are These 6 Helpful Budget Tips Actually Ruining Your Finances?
  • 7 Tactics Grocery Stores Use To Keep You From Thinking About Price
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.
Filed Under: Personal Finance Tagged With: budgeting, financial freedom, financial literacy, Mindset, money management, Personal Finance, values

5 Immediate Changes to Make After a Big Income Reduction

October 10, 2025 by Travis Campbell Leave a Comment

broke
Image source: shutterstock.com

Experiencing a big income reduction can feel overwhelming and stressful. Whether it’s due to a job loss, a pay cut, or a change in family circumstances, your financial stability may suddenly feel shaky. The good news is that you can take practical steps to regain control. Acting quickly and thoughtfully can help you avoid debt, protect your savings, and keep your financial goals within reach. In this article, we’ll cover five immediate changes you should make after a big income reduction. These steps will help you stabilize your finances and adjust to your new reality with confidence.

1. Reevaluate and Prioritize Your Expenses

The first step after a big income reduction is to take a hard look at your spending. Start by listing all your monthly expenses, from housing and utilities to groceries and entertainment. Separate your needs from your wants. Essentials like rent, mortgage payments, utilities, and basic groceries should come first. Non-essential expenses—like dining out, streaming subscriptions, and impulse purchases—should be reduced or eliminated for now.

Review your bank and credit card statements to spot recurring charges you might have forgotten about. Cancel subscriptions or memberships that you no longer use or can temporarily live without. Remember, these cuts don’t have to be permanent, but trimming your budget immediately can help you weather the storm.

2. Adjust Your Budget Immediately

With your new list of prioritized expenses, it’s time to create a fresh budget that reflects your reduced income. Use a budgeting tool or a simple spreadsheet to map out your new monthly cash flow. Make sure that your essential expenses fit within your new income limits. If they don’t, you’ll need to make deeper cuts or look for ways to bring in extra money.

It’s important to be honest about your situation. Overestimating your income or underestimating expenses can lead to overdrafts or credit card debt. If you have difficulty creating a budget, consider using free online resources or apps designed to help people manage money after a big income reduction.

3. Communicate With Creditors and Service Providers

If you’re worried about making payments on time, don’t wait until you’ve missed one. Reach out to your mortgage lender, landlord, utility companies, and credit card issuers. Many organizations offer hardship programs, forbearance options, or payment plans, especially if you’ve experienced a big income reduction. Being proactive can help you avoid late fees, hits to your credit score, and unnecessary stress.

When you contact creditors, explain your situation honestly and ask about available options. Document your conversations and keep copies of any agreements. Every bit of flexibility you gain will make it easier to manage your reduced income.

4. Pause or Reduce Non-Essential Savings and Investments

While saving for retirement, college, or other goals is important, you may need to pause or reduce these contributions temporarily. After a big income reduction, your priority should be covering essential living expenses and maintaining a basic emergency fund. If your employer offers a 401(k) match, try to contribute enough to get the match, but don’t feel guilty if you can’t right now.

Consider redirecting automatic transfers from savings or investment accounts back into your checking account. This can provide a financial cushion and help you avoid dipping into high-interest debt. Once your income stabilizes, you can resume your regular savings and investment plan.

5. Seek Additional Income Sources

After trimming expenses and adjusting your budget, you may still find it challenging to make ends meet. This is the time to explore new income sources. Look for part-time work, freelance gigs, or temporary jobs. You can also consider selling items you no longer need online or offering services in your community.

Don’t overlook support programs or benefits for those who have experienced a big income reduction. Unemployment insurance, food assistance, and local nonprofit programs can provide much-needed relief.

Staying Resilient Through a Big Income Reduction

Adjusting to a big income reduction is never easy, but acting quickly can make a significant difference. Remember that this situation is temporary for many people. By reevaluating your expenses, updating your budget, communicating with creditors, pausing non-essential savings, and seeking new income sources, you can protect your financial health and reduce stress.

Support and information are available from organizations like the U.S. government’s unemployment resources. Revisit your plan regularly and make changes as your situation evolves. Staying proactive and flexible will help you get through this challenging time and prepare for a better financial future.

Have you faced a big income reduction recently? What immediate steps helped you the most? Share your experience or tips in the comments below.

What to Read Next…

  • Are These 7 Little Expenses Quietly Costing You Thousands A Year?
  • 6 Monthly Bills You Should Cancel Immediately Even If You Can Afford Them
  • 8 Everyday Services That Are Slowly Becoming Subscription Only
  • Are These 6 Helpful Budget Tips Actually Ruining Your Finances?
  • 10 Signs You’re Living Above Your Means Without Realizing
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Personal Finance Tagged With: budgeting, emergency planning, Financial Tips, income reduction, Personal Finance

7 Best Practices for Using Credit Cards Like the Rich Do

October 10, 2025 by Travis Campbell Leave a Comment

Credit
Image source: shutterstock.com

Ever wondered how wealthy people seem to benefit from credit cards without falling into debt? The difference isn’t just about having more money—it’s about using credit cards strategically. When managed wisely, credit cards can unlock perks, improve your financial standing, and even help build wealth. But if you use them carelessly, they can just as quickly become a burden.

Credit card best practices aren’t a secret reserved for the rich. Anyone can learn to use credit cards in a way that boosts their finances instead of draining them. In this article, we’ll break down the seven best practices for using credit cards like the rich do. You’ll learn practical steps to maximize rewards, avoid common pitfalls, and make your cards work for you.

Ready to approach credit cards like a pro? Let’s dive in.

1. Pay the Full Balance Every Month

This is the golden rule of credit card best practices. Wealthy individuals almost never carry a balance. Instead, they pay off their cards in full every month. Why? Because interest rates on credit cards are notoriously high. If you only pay the minimum, those interest charges add up fast, eroding any rewards you might earn.

By clearing your balance each month, you avoid interest entirely. This habit protects your credit score and keeps your financial life stress-free. Set up automatic payments if you can, so you never miss a due date.

2. Maximize Rewards and Perks

The rich pay attention to credit card rewards programs, and so should you. From cash back to travel points, the right card can offer significant benefits. But don’t just chase sign-up bonuses. Look for ongoing perks that match your lifestyle—like airport lounge access, purchase protections, or extended warranties.

To get the most out of these programs, use your card for regular expenses you’d pay anyway, like groceries or gas. Then, redeem your rewards strategically. Some cards offer better value for travel bookings, while others shine with statement credits or gift cards.

3. Monitor Spending Closely

Wealthy cardholders don’t leave their statements unchecked. They review their transactions regularly to spot any unauthorized charges or errors. This not only protects against fraud but also helps keep spending in check.

Many credit cards offer budgeting tools or instant alerts. Use them to categorize expenses and set limits. Staying aware is a key part of credit card best practices. If you notice a problem, report it right away to avoid liability.

4. Choose Cards That Fit Your Lifestyle

Not all credit cards are created equal. The rich tend to be selective, choosing cards that align with their spending habits and financial goals. For example, frequent travelers might opt for a premium travel card, while big families could benefit from generous cash-back cards for groceries and gas.

Before applying, compare features like annual fees, interest rates, and reward structures. Make sure the card’s benefits outweigh any costs.

5. Leverage Introductory Offers—But Don’t Overspend

Introductory bonuses can be tempting. The rich take advantage of these offers, but they never let them dictate their spending. If a card offers a big sign-up bonus for spending a certain amount in the first few months, make sure those purchases fit your normal budget.

Don’t buy things you don’t need just to earn points. Instead, time big planned purchases—like insurance payments or home improvements—to coincide with these offers. This way, you benefit from the bonus without going overboard.

6. Protect Your Credit Score

Your credit score affects everything from loan approvals to insurance rates. The rich know this and treat their credit with care. Key credit card best practices include keeping your credit utilization low—ideally under 30% of your total available credit. This shows lenders you’re responsible and can boost your score over time.

Also, don’t open too many new cards at once. Each application triggers a hard inquiry, which can temporarily lower your score. Space out new applications and keep old accounts open, as a longer credit history works in your favor.

7. Use Credit Cards for Security and Convenience

Credit cards offer better fraud protection than debit cards or cash. The wealthy often use their cards for online shopping, travel, and large purchases. If a fraudulent charge appears, it’s easier to dispute and resolve with a credit card.

Some cards even offer zero liability for unauthorized transactions. Using credit cards wisely means you get peace of mind and added convenience—without the risks of carrying cash.

Building Wealth With Smart Credit Card Habits

Practicing these credit card best practices doesn’t require a huge bank account. It’s about discipline, awareness, and making your cards work for you—not the other way around. By paying in full, maximizing rewards, monitoring spending, and protecting your credit score, you set yourself up for financial success. Over time, these habits help you save money, earn valuable perks, and avoid costly mistakes.

Don’t be afraid to compare new card offers or switch when your needs change. Start treating your credit cards like tools for building wealth, not just spending.

How do you use your credit cards to get ahead financially? Share your favorite tips or questions in the comments below!

What to Read Next…

  • 7 Credit Card Features Disappearing Without Any Notice
  • 6 Credit Card Perks That Come With Under The Radar Stringent Conditions
  • Why Are More Seniors Ditching Their Credit Cards Completely
  • 5 Things That Instantly Decrease Your Credit Score By 50 Points
  • What Are Banks Really Doing With Your Personal Spending Data
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.
Filed Under: credit cards Tagged With: credit cards, credit score, Debt Management, Personal Finance, rewards programs, Wealth Building

6 Hints You Have An Honest Financial Advisor

October 10, 2025 by Travis Campbell Leave a Comment

financial advisors
Image source: shutterstock.com

Choosing the right financial advisor can make or break your financial future. Trust is everything when you’re sharing personal details and entrusting someone with your money. But how do you know if you have an honest financial advisor? The stakes are high: a dishonest advisor could steer you into poor investments, charge hidden fees, or simply not have your best interests at heart. With so many options out there, it’s easy to feel overwhelmed. That’s why knowing the signs of an honest financial advisor is crucial for your peace of mind and financial well-being.

1. They Explain Fees Clearly and Upfront

An honest financial advisor doesn’t dodge questions about how they get paid. Whether it’s a flat fee, hourly rate, or commission, they lay it all out before you sign anything. If you ever feel confused about what you’re paying for, your advisor should be able to break down each cost in plain language. This transparency is a hallmark of a trustworthy professional. It’s also a good idea to compare their fee structure with industry standards to make sure there aren’t any hidden surprises.

2. They Put Your Interests First—Always

Honest financial advisors act as fiduciaries, meaning they’re legally obligated to put your interests ahead of their own. If your advisor is a fiduciary, they’ll mention it without hesitation and can show you proof. They’ll recommend investments or strategies that fit your goals, not their commission. This commitment is a key sign you’re working with someone who values your financial health over their own gain. If you’re ever unsure, ask your advisor directly: “Are you a fiduciary?”

3. They Communicate Openly and Regularly

Open communication is a cornerstone of an honest financial advisor. They keep you informed about market changes, your portfolio’s performance, and any adjustments they recommend. You won’t be left in the dark or scrambling for information. Regular check-ins—at least once or twice a year—show they’re proactive and truly care about your progress. If you reach out with a question, you get a prompt, clear response. This ongoing dialogue builds trust and keeps your financial plan on track.

4. They Don’t Promise Unrealistic Returns

If your financial advisor promises to “beat the market” or guarantees high returns, that’s a big red flag. An honest financial advisor will talk about risk and reward honestly. They’ll explain that investing always carries some risk, and they’ll help you set realistic expectations based on your goals and risk tolerance. Instead of hyping up “can’t-miss” investments, they focus on sound strategies that make sense for you. This level-headed approach helps you avoid costly mistakes and disappointment down the road.

5. They Provide References and Credentials

Trustworthy financial advisors are proud of their qualifications and happy to share them. They’ll provide references from other clients (with permission) and show you their licenses, certifications, and professional memberships. Common credentials include CFP (Certified Financial Planner) or CFA (Chartered Financial Analyst). You can also verify their background through resources like FINRA’s BrokerCheck or NAPFA’s advisor search tool. This openness about their experience and credentials is a strong indicator of honesty.

6. They Educate, Not Just Advise

An honest financial advisor doesn’t just tell you what to do—they help you understand why. They take time to explain investment options, risks, and strategies in language you can grasp. If you have a question, they don’t brush it off or use jargon to confuse you. Instead, they want you to feel confident and informed about every decision. This educational approach empowers you and shows that your advisor values transparency over quick sales.

Building a Relationship with Your Honest Financial Advisor

Having an honest financial advisor can make a huge difference in your financial journey. The right advisor offers clear communication, transparency, and a commitment to your best interests. Each of these signs—whether it’s explaining fees or providing credentials—helps you build a relationship based on trust. Don’t be afraid to ask questions and expect straightforward answers. Your financial advisor should be your partner, not just a salesperson.

What qualities do you look for in an honest financial advisor? Share your thoughts or experiences in the comments below!

What to Read Next…

  • 6 Reasons Your Financial Advisor May Not Be Acting In Your Best Interest
  • 8 Signs Your Financial Advisor Is Not Acting In Your Best Interest
  • 10 Financial Questions That Could Reveal You’re Being Advised Poorly
  • 10 Warning Signs In Financial Advisor Contracts You Shouldn’t Ignore
  • What Should You Do If Your Financial Advisor Stops Returning Your Calls?
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Fashion advice Tagged With: fiduciary, financial advisor, investing, money management, Personal Finance, Planning

9 Surprising Ways Your Advisor Is Making Money Off Your Insurance

October 10, 2025 by Catherine Reed Leave a Comment

9 Surprising Ways Your Advisor Is Making Money Off Your Insurance
Image source: shutterstock.com

When you buy a life, auto, or home insurance policy, you expect your advisor to act in your best interest. But what many consumers don’t realize is that advisors and brokers often earn more than just a simple commission from these products. In fact, there are multiple ways an insurance advisor profits from policies—sometimes without you even knowing. These hidden income streams can create conflicts of interest that influence the recommendations you receive. Understanding how your advisor gets paid can help you make more informed financial decisions and keep your money where it belongs.

1. Commissions on Policy Sales Add Up Fast

The most common way an insurance advisor earns money is through commissions paid by the insurance company for every policy sold. These commissions can range from a few percent of the premium to as much as 120% of the first year’s payment on certain products like whole life insurance. Advisors may be tempted to recommend higher-priced policies or unnecessary add-ons to increase their payout. While commissions themselves aren’t unethical, lack of transparency often is. Always ask your advisor exactly how they’re compensated for the policies they sell.

2. Renewal Commissions Keep the Money Flowing

Even after the initial sale, many advisors continue earning money through renewal commissions. Every time you renew or maintain your policy, a small portion of your premium goes back to the insurance advisor as residual income. These payments can last for years, making long-term policies particularly profitable. While that encourages advisors to keep you as a client, it can also discourage them from helping you shop for better deals. Be wary if your advisor insists on sticking with one insurer indefinitely.

3. Bonuses for Hitting Sales Targets

Some insurance companies offer lucrative bonuses when advisors meet specific sales goals. These rewards can include cash incentives, luxury trips, or exclusive perks that have little to do with client satisfaction. While your advisor may appear to be recommending what’s “best,” their real motivation might be hitting a quarterly quota. These programs can subtly push advisors toward certain products or insurers. The best way to avoid bias is to work with an advisor who charges a transparent fee instead of relying on performance-based rewards.

4. Overrides from Subordinate Agents

Advisors who manage or oversee other agents often receive overrides—extra commissions based on the sales performance of those under them. This means your insurance advisor could earn money not just from your policy but from the sales of their entire downline. While this structure rewards leadership, it can also promote aggressive sales tactics across teams. Some organizations even pressure agents to prioritize products that yield higher override percentages. Clients end up footing the bill through inflated premiums.

5. Selling Riders and Add-Ons Boosts Income

Your advisor might recommend policy “enhancements” like accidental death riders, disability coverage, or child protection add-ons. While some of these can be useful, they also come with additional commissions. Advisors often earn higher percentages on these optional extras than on basic policies. That financial incentive can lead to over-insuring, where clients pay for coverage they don’t truly need. Before saying yes to add-ons, review each one carefully and compare the actual benefits to the extra cost.

6. Revenue-Sharing with Insurance Companies

Many large firms that employ advisors participate in revenue-sharing agreements with insurance companies. Under these arrangements, insurers pay firms additional fees in exchange for promoting their products more aggressively. Your advisor might not even see this money directly—but their company benefits when you choose certain policies. This setup can create subtle but powerful biases in which products are presented as “best in class.” Asking if your firm has such arrangements can reveal whether advice is truly impartial.

7. Selling Cash-Value Life Insurance for Bigger Payouts

Not all insurance policies are created equal when it comes to advisor compensation. Cash-value products, like whole life or universal life insurance, often pay much higher commissions than simpler term life plans. Because these policies are complex and long-term, clients may not fully understand the fees and benefits. Some advisors exploit this confusion to sell pricier products that generate large upfront payments. Always compare term and permanent policies before committing to one, and request written details on commission structures.

8. Cross-Selling Other Financial Products

An insurance advisor often acts as a gateway to other financial services, including investment accounts, annuities, and retirement plans. While this may seem convenient, cross-selling allows advisors to earn additional commissions and management fees from multiple products. You might be encouraged to bundle services under the same provider, even when it’s not financially advantageous. These bundled arrangements can limit your flexibility and increase long-term costs. Make sure each recommendation stands on its own merit, not just as part of a package deal.

9. Policy Churning Generates Repeat Commissions

One of the most concerning practices among some insurance advisors is “churning,” or encouraging clients to replace existing policies with new ones unnecessarily. Each time you switch, the advisor earns a fresh commission, even if the new policy offers little or no benefit over the old one. This tactic is often disguised as an “upgrade” or “better fit” for your needs. In reality, frequent replacements can reset surrender charges and cost you thousands in fees. If your advisor regularly recommends switching, ask for a clear, written comparison of both policies.

How to Protect Yourself from Hidden Conflicts

Transparency is the foundation of any trustworthy financial relationship. While it’s normal for an insurance advisor to earn commissions, the key is knowing exactly how and when they’re paid. Request a written disclosure of compensation before purchasing any policy, and don’t hesitate to ask follow-up questions. Fee-based or fiduciary advisors, who are legally obligated to act in your best interest, may provide more objective guidance. Understanding how the system works ensures you’re buying protection—not padding someone else’s profit.

Have you ever wondered how your insurance advisor makes money from your policy? Share your experiences and insights in the comments below!

What to Read Next…

How Do I Know If My Advisor Is Qualified to Handle My Complex Situation?

4 Quick Methods to Verify Advisor Backgrounds Using Public Tools

9 Worrying Gaps In Your Advisor’s Knowledge Base Revealed

12 Different Strategies Advisors Use to Minimize Their Liability

7 Things Your Financial Advisor Will NEVER Tell You About Your Portfolio

Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.

Filed Under: Financial Advisor Tagged With: commissions, fiduciary advice, insurance advisor, insurance tips, life insurance, money management, Personal Finance, Planning

4 Key Rules for Lending Money to Loved Ones Safely

October 10, 2025 by Travis Campbell Leave a Comment

money
Image source: shutterstock.com

Lending money to loved ones is never as simple as handing over cash and waiting for repayment. It can bring up old family dynamics, create awkwardness, or even damage relationships if things go wrong. Financial help can be a lifeline, but without clear rules, it can also become a source of stress and resentment. That’s why it’s important to approach lending money to family and friends with caution and a plan. By setting boundaries and following a few key rules, you can protect your finances and your relationships. Here are four essential rules for lending money to loved ones safely.

1. Set Clear Terms in Writing

When it comes to lending money to loved ones, clarity is your best friend. It’s tempting to rely on trust alone, but misunderstandings are common, even among close family and friends. Always put the terms of the loan in writing. This doesn’t have to be a complex legal document—a simple note outlining the amount, repayment schedule, interest (if any), and consequences for missed payments is enough. Both parties should sign it.

This written agreement helps everyone remember what was promised, making it easier to discuss repayment without feeling awkward. If the loan is large, consider using an online template or consulting a lawyer to make sure everything is covered. This step may feel formal, but it protects both you and your loved one from confusion or hurt feelings down the line. Setting clear terms is the foundation of safe lending to family and friends.

2. Only Lend What You Can Afford to Lose

This rule is non-negotiable. Lending money to loved ones should never jeopardize your own financial stability. Before you agree to help, take a close look at your budget and ask yourself if you can truly afford to lose this money. Life is unpredictable, and even with the best intentions, your loved one might not be able to pay you back on time—or at all.

If the loss of this money would put you in a bind, it’s better to say no or offer a smaller amount. Remember, your primary responsibility is to your own financial well-being. Lending money to family and friends should not come at the expense of your emergency fund, retirement savings, or essential expenses. Be honest about your limits, and don’t let guilt push you into a risky situation.

3. Treat the Loan Like a Business Transaction

It’s easy to let emotions take over when helping someone you care about. But for the sake of both your relationship and your finances, treat the loan as a business transaction. This means discussing every detail openly, from repayment plans to interest rates. If you expect to be paid back by a certain date, say so. If you’re charging interest, explain why and how much.

Maintaining this level of professionalism helps set boundaries and keep expectations realistic. It also signals to your loved one that you take the transaction seriously. This doesn’t mean you have to be cold or unfeeling—just clear and consistent. By handling lending money to family and friends this way, you reduce the risk of misunderstandings and resentment.

4. Communicate Openly—Before, During, and After

Good communication is essential for lending money to loved ones safely. Before you agree to lend, talk honestly about why they need the money, how they plan to use it, and what their plan is for repayment. Don’t be afraid to ask questions—this is about protecting both parties.

Once the loan is made, keep in touch about payments. A quick monthly check-in can prevent misunderstandings and keep things on track. If your loved one is struggling to repay, encourage them to be honest about their situation. It’s better to adjust the plan together than to let things fester. Open communication keeps the relationship strong and helps ensure the loan doesn’t become a source of stress or resentment.

Protecting Relationships While Lending Money to Family and Friends

Lending money to family and friends can be a generous and meaningful act, but it comes with real risks. By following these four key rules, you can lend money safely—without putting your own finances or relationships in jeopardy. Remember, setting boundaries and communicating openly are not signs of mistrust; they’re signs of respect for both yourself and your loved one.

Lending money to loved ones does not have to end badly. With clear terms, honest conversations, and a willingness to walk away if you can’t afford it, you can help without hurting yourself. Have you ever lent money to a family member or friend? How did you handle it? Share your experiences and insights in the comments below.

What to Read Next…

  • The Benefits of Taking Personal Loans and Their Impact on Credit Scores
  • 7 Times Generosity Has Legal Consequences for Seniors
  • What Happens If You Forget to Update a Power of Attorney Before Moving States
  • What Happens When You Co-Sign a Friend’s Loan by Accident
  • 6 Legacy Loans Families Regret Granting in Trust Documents
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.
Filed Under: Debt Management Tagged With: family loans, financial boundaries, lending money, money management, Personal Finance, relationships

10 Life Principles That Promote Consistent Financial Growth

October 10, 2025 by Catherine Reed Leave a Comment

10 Life Principles That Promote Consistent Financial Growth
Image source: shutterstock.com

Sustainable wealth doesn’t come from luck or one-time windfalls—it comes from consistent, disciplined habits practiced over time. Whether you’re building your first savings account or managing multiple investments, the foundation of financial growth lies in mindset as much as money management. By following a few timeless life principles, you can create lasting stability and open the door to greater opportunities. These principles are simple but powerful, helping anyone stay grounded, focused, and steadily moving forward.

1. Live Below Your Means Without Feeling Deprived

The first and most essential rule for financial growth is spending less than you earn. It’s not about living a joyless life—it’s about finding satisfaction within your means. When you prioritize needs over wants, your savings and investments naturally grow. The key is balance: enjoy small luxuries occasionally but keep your overall expenses sustainable. Living modestly today ensures flexibility and freedom tomorrow.

2. Treat Saving as a Non-Negotiable Habit

Most people wait to save “what’s left over,” but true financial growth begins when saving comes first. Setting aside a fixed percentage of every paycheck—no matter how small—builds momentum over time. Automating deposits into savings or investment accounts helps remove temptation and keeps you consistent. The magic lies in compound interest, where small contributions grow exponentially with time. When saving becomes automatic, financial security becomes inevitable.

3. Prioritize Financial Education

Knowledge fuels every stage of financial growth. Understanding topics like compound interest, credit management, and investment diversification empowers you to make smarter choices. Instead of fearing money, you learn to direct it. Reading financial books, listening to podcasts, or following reputable advisors can make a major difference in how your wealth grows. The more you know, the more confident and capable you become with each financial decision.

4. Diversify Income Streams

Relying solely on one paycheck or business can limit your potential for financial growth. Multiple income streams—like side gigs, rental properties, or dividend-paying stocks—create stability and expand your opportunities. This principle protects you from economic downturns or job loss. Even small streams add up, easing financial stress and accelerating savings. When income is diversified, you gain both security and flexibility for the future.

5. Avoid High-Interest Debt Like the Plague

Debt can sabotage even the best efforts toward financial growth. High-interest credit cards and payday loans drain resources and limit your ability to save or invest. Paying off debt aggressively frees up cash flow for long-term goals. The key is distinguishing between productive debt—like a mortgage or business loan—and destructive debt that only funds short-term gratification. Freedom from interest payments is one of the fastest ways to boost financial stability.

6. Set Clear, Measurable Goals

Without direction, money tends to disappear on autopilot. Goal setting gives every dollar a purpose, turning vague intentions into actionable plans that support financial growth. Whether it’s saving $10,000, paying off student loans, or retiring early, clarity matters. Break big goals into smaller milestones to stay motivated and track progress. Consistent progress—even if slow—beats occasional bursts of effort every time.

7. Keep Emotions Out of Financial Decisions

Emotional spending and impulsive investing are two of the biggest threats to financial growth. When excitement or fear takes over, logic goes out the window. Learning to pause before making major money moves can save thousands in the long run. This applies to both panic-selling during market dips and overspending during stressful times. Calm, rational decisions build wealth steadily—emotional reactions often destroy it.

8. Invest in Yourself Continuously

Your earning potential is directly tied to your personal growth. Education, skill development, and professional networking all contribute to better opportunities and higher income. Even small investments in self-improvement can lead to exponential rewards over time. Prioritizing your health and mental well-being also ensures the energy to pursue financial goals. When you grow as a person, your finances naturally follow.

9. Build a Long-Term Mindset

Patience is a defining factor in financial growth. Quick gains often fade, but consistent, long-term strategies deliver lasting results. This applies to everything from retirement accounts to business building. Focusing on steady progress helps you avoid risky trends and impulsive decisions. Remember: wealth built slowly tends to stay longer because it’s rooted in discipline and thoughtful planning.

10. Surround Yourself with Financially Responsible People

Your environment plays a huge role in shaping your habits. Spending time with financially responsible people can reinforce discipline, accountability, and smart decision-making. Friends who value saving, investing, and goal-setting will inspire you to stay on track. Conversely, being surrounded by impulsive spenders can normalize debt and poor money habits. Choose company that encourages your pursuit of financial growth rather than distracting you from it.

Building Wealth That Lasts a Lifetime

The path to consistent financial growth isn’t about perfection—it’s about persistence. Following these ten life principles helps you make intentional decisions that compound in value over time. When saving, learning, and disciplined spending become part of your lifestyle, financial independence stops being a dream and becomes an attainable reality. It’s not just about growing wealth—it’s about creating peace of mind and lasting security.

Which of these life principles has had the biggest impact on your financial growth? Share your thoughts and experiences in the comments below!

What to Read Next…

Why “It’s Just a Few Bucks” Is the Most Dangerous Lie in Personal Finance

6 Surprising Reasons People Refuse to Create a Simple Budget

Budgeting For Irregular Income: Freelancers And Gig Workers

7 Financial Goals People Never Think to Update With Their Advisor

13 Essential Steps to Repair Damage From Past Financial Mistakes

Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.

Filed Under: Personal Finance Tagged With: budgeting, financial goals, Financial Growth, investing, money mindset, Personal Finance, saving money, Wealth Building

9 Bold Actions to Take Against Financial Oppression Systemically

October 10, 2025 by Travis Campbell Leave a Comment

money
Image source: shutterstock.com

Financial oppression systemically affects millions of people every day. It shows up as unfair lending, wage gaps, predatory fees, and barriers to ownership. These issues often feel too big for one person to tackle, but collective and strategic actions can challenge the status quo. By learning about the roots of financial oppression and taking bold steps, you can help create a fairer system for everyone. Whether you’re directly impacted or simply want to be an ally, your choices matter. Here are nine bold actions you can take to push back against the financial oppression systemically.

1. Educate Yourself and Others

Knowledge is a powerful tool against the financial oppression systemically. Start by learning how the financial system works, including how policies and historical practices have created and maintained inequality. Read books, attend workshops, and follow trusted sources that break down complex topics in plain language. Share what you learn with friends and family—conversations can spark awareness and inspire action. The more people understand the system, the harder it becomes for unjust practices to continue unchecked.

2. Support and Use Community Banks or Credit Unions

Large financial institutions have a history of practices that can perpetuate a financial oppression systemically, like redlining or predatory lending. By moving your money to community banks or credit unions, you support organizations that often invest directly in local neighborhoods. These institutions are more likely to offer fair rates, transparent fees, and better access to credit for underserved populations. Even if you keep a main account elsewhere, opening a savings or checking account at a local credit union can make a difference over time.

3. Advocate for Fair Lending Laws

Unfair lending practices, such as payday loans with sky-high interest rates, trap people in cycles of debt. Contact your local representatives to support fair lending laws that protect vulnerable borrowers. Get involved in campaigns that push for caps on interest rates or demand transparency from lenders. Advocacy doesn’t require a law degree—sending an email, signing a petition, or showing up at a town hall meeting can help drive change. Remember, laws and regulations shape the way financial oppression systemically impacts communities.

4. Demand Pay Equity and Wage Transparency

Wage gaps based on gender, race, or background are a core part of systemic financial oppression. At work, support or initiate conversations about pay equity and wage transparency. Encourage your employer to conduct pay audits and publish salary ranges for all positions. If you’re a business owner or manager, lead by example and set fair pay policies. When workers can see and compare pay, it becomes much harder for discrimination to hide.

5. Invest in Organizations Fighting Financial Injustice

Many nonprofits and grassroots groups are dedicated to fighting financial oppression systemically. Consider donating money, volunteering time, or offering skills to these organizations. Your support can help provide financial education, legal aid, or advocacy for those most affected. Research groups in your area or national organizations like the Prosperity Now network are available. Even small contributions, when combined with others, can fuel important work for change.

6. Promote Financial Literacy in Your Community

Lack of financial knowledge can keep people trapped in cycles of debt or poverty. Organize or volunteer for financial literacy workshops in your neighborhood, school, or workplace. Teach basic skills like budgeting, understanding credit, and avoiding predatory loans. When more people have the tools to navigate the system, the financial oppression systemically loses its grip.

7. Support Policies for Affordable Housing and Healthcare

High housing and healthcare costs are major drivers of financial oppression systemically. Advocate for policies that increase access to affordable housing, cap rent hikes, or expand healthcare coverage. Join local housing coalitions or attend city council meetings to voice your support. Even signing petitions or writing letters can influence policy decisions. When basic needs are met, families have more freedom and stability to build wealth and break cycles of oppression.

8. Leverage Your Vote and Civic Engagement

Voting is one of the most direct ways to influence systems that create or maintain financial oppression. Learn about candidates’ positions on economic justice, banking reform, and consumer protection. Vote in local, state, and federal elections—not just presidential races. Attend community forums, participate in budget hearings, or join neighborhood associations. Civic engagement helps ensure the voices of those affected by systemic financial oppression are heard and respected.

9. Mentor and Sponsor Underrepresented Individuals

Systemic barriers often limit access to networks and opportunities. Offer mentorship or sponsorship to individuals from marginalized backgrounds, especially in fields like finance, law, or business. Help them navigate career paths, understand workplace dynamics, and build valuable connections. By lifting others as you climb, you chip away at the financial oppression systemically and help create a more inclusive system for future generations.

Taking Action Together

Challenging the financial oppression systemically is not a one-person job. Real change happens when individuals, families, and communities join forces and push for a fairer financial system. You don’t need to do everything at once, but every step counts. Start where you are, use your strengths, and connect with others who share your vision for justice. Financial freedom should be possible for everyone, not just a privileged few.

Which actions have you tried, or what bold steps would you add to this list? Share your thoughts in the comments below!

What to Read Next…

  • 7 Financial Loopholes That Lenders Exploit Behind The Scenes
  • 8 Everyday Scams Seniors Are Falling For Right Now
  • 6 Online Freebies That End In Identity Theft
  • 7 Legal Loopholes That Let Authorities Freeze Assets Without Warning
  • Why Are So Many Seniors Being Sued Over Student Loans They Didn’t Take Out?
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.
Filed Under: Finance Tagged With: advocacy, community banking, financial literacy, financial oppression, pay equity, Personal Finance, systemic inequality

Here’s What It Really Means to Have an Unconventional Loan

October 10, 2025 by Travis Campbell Leave a Comment

money
Image source: shutterstock.com

When you think about getting a loan, you probably imagine the usual suspects: mortgages, auto loans, or personal loans from a bank or credit union. But what if your situation doesn’t fit into those neat boxes? That’s where an unconventional loan comes into play. Unconventional loans can open doors for people who don’t qualify for traditional lending or need creative solutions. Understanding what it really means to have an unconventional loan is important before you sign on the dotted line. These loans can help you achieve your goals, but they come with their own set of rules, risks, and rewards. Here’s what you need to know if you’re considering this less-traveled financial path.

1. What Is an Unconventional Loan?

An unconventional loan is any type of financing that falls outside the standard guidelines set by traditional lenders like banks and credit unions. These loans are also called non-conforming loans. People with unique financial situations often use them—maybe you’re self-employed, have a low credit score, or want to buy a property that doesn’t fit the mold.

The primary SEO keyword here is unconventional loan. Lenders may look at your ability to repay, but they’ll use different criteria or may be willing to take on more risk. While this flexibility is appealing, it’s important to understand the potential downsides, such as higher interest rates or stricter terms.

2. Who Typically Uses Unconventional Loans?

Unconventional loans are popular with borrowers who don’t meet the requirements for conventional loans. If you’re a freelancer, real estate investor, or someone with a recent bankruptcy, you might find that traditional banks won’t work with you. Maybe you have an irregular income stream or your credit history is less than perfect. In these cases, an unconventional loan could be a solution.

People who want to buy unique properties—like tiny homes, fixer-uppers, or mixed-use buildings—often turn to these loans as well. Sometimes, even business owners looking for a quick influx of cash will seek out unconventional options. The key is that these loans are designed for situations where the “normal” route just doesn’t fit.

3. Types of Unconventional Loans

There’s no single formula for an unconventional loan. They come in many shapes and sizes, including:

  • Stated income loans, which rely more on your stated earnings than on documented proof.
  • Hard money loans are secured by property and are often used by real estate investors.
  • Balloon loans have low initial payments followed by a large lump sum at the end.
  • Interest-only loans, where you pay just the interest for a set period before starting on the principal.
  • Peer-to-peer loans are where individuals lend to other individuals through online platforms.

Each type of unconventional loan serves different needs and comes with its own pros and cons. It’s smart to research thoroughly before deciding which route to take.

4. Pros and Cons You Need to Know

One major advantage of an unconventional loan is access. If you can’t get a regular mortgage or personal loan, these alternatives can help you bridge the gap. The approval process is often faster, and the requirements can be less rigid.

On the flip side, be prepared for higher interest rates and additional fees. Lenders take on more risk, so they charge more to offset it. You might also face shorter repayment terms or stricter penalties for late payments. Before you commit, review every detail so you’re clear about what you’re getting into.

5. How to Qualify for an Unconventional Loan

Qualifying for an unconventional loan isn’t always easier—it’s just different. Lenders might focus on your assets, property value, or projected cash flow instead of your credit score or W-2 income. You’ll likely need to provide more documentation to prove your ability to repay. Sometimes, you’ll need a larger down payment or collateral to secure the loan.

It pays to shop around and compare offers from different lenders. Get everything in writing, and don’t be afraid to ask questions. If possible, work with a financial advisor or mortgage broker who understands the unconventional loan landscape.

6. Risks to Watch Out For

Unconventional loans aren’t for everyone. The biggest risk is cost: you could end up paying much more over the life of the loan compared to a conventional option. Some loans, like hard money or balloon loans, can put you in a tough spot if you can’t make the big payments when they’re due.

Regulation is another issue. Some unconventional lenders operate with less oversight, which means you need to be extra cautious. Read all the fine print and check lender reviews.

What to Consider Before You Apply

Before you jump into an unconventional loan, take a step back and look at your full financial picture. Ask yourself if you really need this type of loan, or if there’s a way to qualify for a traditional product with better terms. Sometimes, improving your credit score or saving a larger down payment can open up more options.

It’s also wise to compare offers and check for hidden fees or high prepayment penalties. Remember, the flexibility of an unconventional loan comes at a price.

Have you ever considered an unconventional loan, or have you used one in the past? Share your experience or questions in the comments below!

What to Read Next…

  • The Benefits Of Taking Personal Loans And Their Impact On Credit Scores
  • 9 Surprising Penalties For Paying Off Loans Too Early
  • What Happens When You Co Sign A Friends Loan By Accident
  • 7 Financial Loopholes That Lenders Exploit Behind The Scenes
  • 8 Signs Your Financial Advisor Is Not Acting In Your Best Interest
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.
Filed Under: Finance Tagged With: alternative loans, credit, lending, mortgages, Personal Finance, Risk management, unconventional loan

  • « Previous Page
  • 1
  • …
  • 82
  • 83
  • 84
  • 85
  • 86
  • …
  • 190
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework