• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Lifestyle

Retroactive Rule Changes: How New Laws Can Quietly Cost You Money

April 10, 2026 by Brandon Marcus Leave a Comment

Retroactive Rule Changes: How New Laws Can Quietly Cost You Money
Image Source: Shutterstock.com

A rule changes today, and suddenly yesterday looks different. That idea sounds upside down, almost unfair at first glance, yet it plays out more often than most expect. Governments adjust tax codes, update regulations, and reinterpret existing laws in ways that reach backward instead of forward. That shift doesn’t always grab headlines, and it rarely comes with flashing warning signs. It simply appears in the fine print, waiting for someone to notice that the past just got more expensive.

Money moves fast, and rules try to keep up, but they don’t always stay in their lane. Retroactive changes can reshape decisions that already happened, turning what looked smart last year into a costly surprise today. That dynamic creates a strange kind of financial time travel where actions feel locked in, yet the consequences keep shifting. Anyone who cares about keeping more of their money needs to understand how this works, because the impact can sneak into taxes, benefits, business decisions, and even everyday financial planning.

When Yesterday’s Decisions Get Rewritten

Retroactive laws flip the usual script by applying new rules to past actions, and that twist changes everything. Most people expect laws to apply going forward, giving everyone a chance to adjust behavior before consequences kick in. Retroactive changes skip that courtesy and go straight to the result, which can feel jarring even when it follows legal standards. Courts in many places allow certain retroactive tax laws, especially when lawmakers frame them as clarifications or necessary adjustments. That legal footing doesn’t soften the financial impact, though, especially when it lands without much warning.

Tax policy provides some of the clearest examples of this effect in action. Governments sometimes pass legislation that adjusts deductions, credits, or rates for a tax year that has already ended. That means a return that once looked complete can suddenly need revisions, or a refund expectation can shrink without much room to react. Businesses feel this even more sharply, especially when investment decisions relied on earlier rules that no longer apply. A strategy that made perfect sense under one set of regulations can lose its edge overnight when lawmakers redraw the boundaries.

This kind of change doesn’t always signal bad intent, but it does demand attention. Governments often use retroactive adjustments to close loopholes, fix drafting errors, or respond to economic shifts. Those goals might make sense on paper, yet they still create ripple effects for individuals and companies that acted in good faith. Staying aware of pending legislation and proposed changes helps reduce the shock, even if it doesn’t eliminate the risk entirely. Knowledge won’t stop retroactive rules, but it can soften the landing.

The Tax Code’s Favorite Plot Twist

Taxes love complexity, and retroactive changes fit right into that pattern. Lawmakers regularly tweak tax provisions, sometimes with effective dates that reach back to the start of the year or even earlier. That approach allows governments to align policy with broader economic goals, but it also creates confusion for anyone trying to plan ahead. A deduction that looked available in January might disappear by December, leaving a gap that didn’t exist when decisions got made.

Credits and incentives often sit at the center of these shifts. Governments introduce them to encourage certain behaviors, like investing in energy efficiency or supporting specific industries. Then, if those incentives cost more than expected or fail to deliver results, lawmakers might scale them back retroactively. That move can reduce expected savings and force adjustments to financial plans that already relied on those benefits. It doesn’t just affect large corporations either, because individuals can feel the impact through changes in income thresholds, credit eligibility, or reporting requirements.

Smart planning helps, but flexibility matters just as much. Keeping detailed records, staying updated on proposed tax legislation, and avoiding overreliance on any single credit or deduction can reduce exposure. Consulting a tax professional during periods of legislative change adds another layer of protection, especially when major reforms loom on the horizon. No strategy eliminates uncertainty completely, but a proactive approach can turn a potential financial hit into a manageable adjustment.
Retroactive Rule Changes: How New Laws Can Quietly Cost You Money
Image Source: Shutterstock.com

Business Moves That Suddenly Look Risky

Companies thrive on predictability, and retroactive rule changes disrupt that stability in a big way. A business might invest heavily in a project based on current regulations, only to face new rules that alter the expected return. That shift can affect everything from hiring plans to expansion strategies, especially in industries that depend on government incentives or strict compliance standards. When the rules change after the fact, the math changes too, and not always in a favorable direction.

Regulatory updates often hit sectors like finance, healthcare, and energy with particular force. Governments might tighten reporting requirements, adjust compliance thresholds, or reinterpret existing rules in ways that apply to past actions. That can lead to unexpected penalties, additional paperwork, or the need to restructure operations. Smaller businesses often feel this pressure more intensely because they operate with fewer resources to absorb sudden changes. What looked like a smart, efficient move at the time can suddenly carry new costs that weren’t part of the original plan.

Preparation becomes a strategic advantage in this environment. Businesses that monitor regulatory trends and maintain flexible plans can pivot more easily when changes arise. Building a financial cushion, diversifying investments, and seeking legal guidance before making major decisions can also reduce vulnerability. No one can predict every policy shift, but a mindset that expects change can handle it far better than one that assumes stability.

Everyday Finances Aren’t Immune Either

Retroactive rule changes don’t stay confined to boardrooms and tax filings, because they can filter into everyday financial life as well. Adjustments to benefits programs, student loan policies, or housing regulations can reach back and affect prior eligibility or repayment terms. That can change monthly budgets in ways that feel sudden, even if the legal groundwork was developed over time. A benefit that seemed secure can shrink or disappear, forcing a quick recalibration of expenses and priorities.

Retirement planning also feels the impact when rules shift. Changes to contribution limits, withdrawal requirements, or tax treatment of retirement accounts can apply to previous periods in certain cases. That can alter long-term projections and require updates to carefully built strategies. People who stay engaged with their financial plans tend to adapt more smoothly because they already track the moving parts and understand where adjustments might fit.

Staying informed offers one of the strongest defenses here. Following credible financial news, reviewing official government updates, and checking in regularly on personal accounts can catch changes early. Building flexibility into a budget, such as maintaining an emergency fund or avoiding overcommitment, creates room to adjust when rules shift. Everyday finances might feel routine, but they still sit within a system that evolves constantly.

The Playbook for Staying One Step Ahead

Retroactive rule changes won’t disappear, so the smartest move involves learning how to navigate them with confidence. Start by treating financial decisions as part of a moving landscape instead of a fixed set of rules. That mindset encourages regular check-ins and adjustments instead of a one-and-done approach. It also reduces the shock when something changes, because change already sits on the radar.

Diversification plays a powerful role in reducing risk. Spreading investments, income sources, and financial strategies across different areas can prevent a single rule change from causing major disruption. Keeping organized records also proves essential, especially when retroactive adjustments require documentation or amended filings. That preparation can save time, money, and frustration when dealing with unexpected updates.

Professional advice adds another layer of protection, particularly during periods of significant legislative activity. Financial advisors, accountants, and legal experts track changes closely and can offer guidance tailored to specific situations. Combining that expertise with personal awareness creates a strong defense against the uncertainty that retroactive rules bring. Staying flexible, informed, and proactive turns a potentially stressful situation into something far more manageable.

Rules That Refuse to Stay Still

Rules don’t always wait politely for the future, and money doesn’t get a rewind button when they change. Retroactive laws reshape outcomes after decisions have already get made, and that reality demands attention from anyone who wants to stay in control of their finances. A sharp eye, a flexible plan, and a willingness to adapt can make the difference between getting caught off guard and staying one step ahead. Financial confidence doesn’t come from predicting every change, but from preparing to handle whatever comes next.

How often does your financial strategy get a checkup, and what would happen if yesterday’s rules changed tomorrow? Share your thoughts, experiences, or strategies in the comments.

You May Also Like…

The Silent Cost Of Co-Signing Loans For Families & What The Rules Don’t Tell You

Regulation Impact: 6 Rules That Could Change How You Pay for Financial Advice

Texas Grocery Warning: New Anti-Fraud Rules Mean More ID Checks at Checkout Starting in April

Regulation Shakeup: 6 Laws That Could Impact Your 401(k) Next Year

Texas Property Alert: The New 2026 Law That Allows Police to Remove Squatters in 24 Hours

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: budgeting, compliance, financial awareness, government policy, legal risks, legal updates, money management, Personal Finance, Planning, retroactive laws, tax changes, tax rules

The “Too Late” Rule: When Missed Government Doors Close Forever

April 9, 2026 by Brandon Marcus Leave a Comment

The "Too Late" Rule: When Missed Government Doors Close Forever
Image Source: Shutterstock.com

The clock does not slow down, offer second chances, or whisper reminders when a life-changing deadline inches closer. Government systems run on firm timelines, and once those timelines expire, they rarely bend, no matter how good the reason sounds. Some deadlines come with penalties, others come with fees, but a handful come with something much harsher: a permanent lockout.

That’s where the “Too Late” rule quietly changes lives. Missing certain government deadlines doesn’t just create inconvenience; it can erase opportunities entirely, closing doors that never reopen. These aren’t minor oversights either, but moments that can affect retirement income, legal rights, or access to benefits for years to come.

The Deadlines That Don’t Forgive

Not all government deadlines carry the same weight, and that distinction matters more than most people realize. Some agencies allow late filings with penalties, giving people a chance to recover if they act quickly. Others, however, draw a sharp line in the sand, and once that line gets crossed, options disappear completely. That’s where the danger lives, because these rules often hide in fine print instead of flashing warning signs.

Take retirement benefits as an example. Certain programs require applications within specific windows, and delaying beyond those windows can permanently reduce or even eliminate benefits. Social Security survivor benefits, for instance, often depend on filing within a defined timeframe, especially for specific categories of eligibility. Missing that window can mean forfeiting money that cannot be reclaimed later, no matter how strong the case might seem. The system doesn’t negotiate with hindsight.

Tax-related deadlines create another high-stakes scenario. While many people know about penalties for late filing, fewer realize that some tax elections, credits, or refund claims come with strict expiration rules. The IRS generally allows a three-year window to claim a refund, and after that, the money stays with the government permanently. That reality turns procrastination into a costly mistake, especially for those who assume they can circle back later. In these situations, “later” simply doesn’t exist.

When Paperwork Becomes Power

Government paperwork might look boring, but it carries serious authority. Forms, filings, and applications serve as the gateway to benefits, protections, and rights that people often take for granted. Missing a deadline doesn’t just delay processing; it can strip away eligibility altogether, especially when statutes or regulations require strict compliance.

Immigration processes highlight this reality in a big way. Many visa renewals, status adjustments, or appeals operate under rigid timelines that leave no room for delay. Missing a filing date can lead to loss of legal status, forcing individuals to restart processes or even leave the country. These aren’t small setbacks, but life-altering consequences tied directly to paperwork timing. Staying organized and proactive becomes essential in navigating these systems successfully.

Student loan programs and forgiveness plans also rely heavily on deadlines that demand attention. Certain repayment plans or forgiveness opportunities require annual recertification or timely applications. Missing those dates can reset progress or disqualify participants from benefits they worked toward for years. That kind of setback hits hard, especially when it results from something as simple as overlooking a reminder email or forgetting a date. Organization doesn’t just help here; it protects long-term financial goals.

Appeals, Exceptions, and the Myth of Flexibility

People often assume that government systems allow room for explanation, especially in cases involving emergencies or honest mistakes. While some processes do include appeals or exception requests, those options don’t apply universally. In many cases, the right to appeal itself comes with its own deadline, creating a second layer of risk that catches people off guard.

Legal filings offer a clear example of this structure. Court deadlines, administrative appeals, and benefit disputes all operate under strict filing windows. Missing the deadline to file an appeal can end a case before it even begins, regardless of its merit. Judges and agencies follow procedural rules closely, and failing to meet those requirements can shut down opportunities for review. The system prioritizes consistency over flexibility, which leaves little room for late action.

Even when exceptions exist, they often require proof that meets a high standard. Simply forgetting or misunderstanding a deadline rarely qualifies as a valid reason for leniency. Agencies may require documentation of extraordinary circumstances, and even then, approval is far from guaranteed. That uncertainty makes relying on exceptions a risky strategy. Planning ahead and meeting deadlines remains the only dependable way to protect access to important programs and rights.

The "Too Late" Rule: When Missed Government Doors Close Forever
Image Source: Shutterstock.com

Smart Moves That Keep Doors Open

Avoiding the “Too Late” trap doesn’t require perfection, but it does require awareness and action. The first step involves identifying which deadlines carry permanent consequences and treating them as non-negotiable. That means going beyond surface-level knowledge and digging into the specific rules tied to benefits, taxes, or legal processes. Understanding those timelines turns confusion into clarity.

Setting up a system for tracking deadlines can make a huge difference. Digital calendars, reminder apps, and even simple written planners can help keep important dates visible and manageable. Adding multiple reminders, spaced out over time, reduces the chance of something slipping through the cracks. That kind of structure creates a safety net, especially for deadlines that only come around once a year or even once in a lifetime.

Seeking professional guidance also plays a key role in staying ahead. Financial advisors, tax professionals, and legal experts understand the nuances of government rules and can flag deadlines that might otherwise go unnoticed. They don’t just provide information; they offer context that helps people prioritize what matters most. Investing in that kind of support often prevents much larger losses down the road.

The Moment That Matters Most

Deadlines rarely announce their importance with flashing lights or urgent warnings, yet they hold the power to shape financial futures, legal outcomes, and access to essential benefits. The “Too Late” rule doesn’t exist to punish, but it operates with a level of finality that leaves no room for second chances. Recognizing that reality changes how people approach paperwork, timelines, and long-term planning.

What strategies work best for you when keeping track of important deadlines, and which systems actually stick over time? Share your thoughts, experiences, or even close calls in the comments.

You May Also Like…​

Missed Deadlines, Missed Dollars, Government Dates You Can’t Afford To Ignore

Unclaimed Benefits: Are You Missing Out On Government Money

6 Ways Criminals Are Using AI to Impersonate Banks and Government Agencies

6 Government Benefit Checks That Could Be Delayed Under New Fraud Reviews

How to Inherit an IRA Without Handing Half of It to the Government

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: Applications, benefits, bureaucracy, compliance, filing rules, government deadlines, legal deadlines, missed deadlines, Planning, public policy, Retirement, Social Security, taxes

The Real Reason Your Utility Bill Is Skyrocketing and What You Can Do

April 7, 2026 by Brandon Marcus Leave a Comment

The Real Reason Your Utility Bill Is Skyrocketing and What You Can Do
Image Source: Shutterstock.com

Electric bills aren’t just creeping up anymore—they’re charging forward like they’ve got something to prove. Numbers that once felt manageable now look like a monthly shock, and the explanation rarely feels clear. Blaming “higher costs” sounds vague, and vague doesn’t help when the total jumps again. The truth hides behind a mix of global shifts, local infrastructure, and everyday habits that quietly stack up over time. Understanding what actually drives those numbers gives far more power than simply bracing for the next bill.

Big energy changes don’t stay behind the scenes anymore; they show up in homes, apartments, and bank accounts. Rising costs don’t come from one single cause, and that’s exactly why they feel so frustrating. A mix of supply issues, aging systems, extreme weather, and lifestyle patterns pushes prices higher from multiple directions at once. That layered reality means quick fixes won’t cut it, but smart adjustments absolutely can. Once the real drivers come into focus, cutting costs stops feeling like guesswork and starts feeling like strategy.

The Hidden Forces Driving Your Bill Higher

Energy prices don’t just rise randomly; global supply and demand shifts push them up in ways that ripple into everyday life. When fuel costs increase, electricity providers pass those increases along almost immediately, and that impact hits every household regardless of usage habits. Infrastructure also plays a massive role, because many power grids rely on aging systems that require expensive maintenance and upgrades. Those upgrades cost money, and utility companies recover those expenses through higher rates. Weather adds another layer of pressure, especially during extreme heat or cold when demand spikes dramatically. Increased demand forces utilities to generate more power quickly, which often costs more and drives rates upward. Even water bills feel the pressure, as drought conditions and water treatment expenses raise costs in many regions.

Government policies and environmental regulations also influence utility pricing, often with long-term goals that carry short-term cost increases. Cleaner energy initiatives, for example, require investment in renewable systems, and that transition doesn’t come cheap. While those changes aim to reduce environmental impact, they often increase bills during the transition period. Population growth in certain areas strains local resources, forcing utilities to expand capacity and infrastructure faster than planned. That expansion again feeds into higher costs for consumers. On top of that, energy markets fluctuate constantly, and those fluctuations create unpredictable pricing patterns. When all these forces combine, bills rise steadily rather than dramatically, which makes the increases feel relentless instead of sudden.

The Everyday Habits That Quietly Add Up

Daily routines shape utility bills far more than most people expect, and small patterns often create surprisingly large impacts over time. Leaving lights on in multiple rooms, running appliances during peak hours, and keeping devices plugged in all day steadily increase electricity usage. Even modern homes packed with energy-efficient devices still waste power through standby consumption, sometimes called “phantom energy.” That constant drain may seem minor, but it adds up every single day. Heating and cooling habits also make a massive difference, especially when thermostats stay fixed instead of adjusting with the weather or time of day. A few degrees higher or lower can shift energy use significantly across an entire month. Laundry habits, water heater settings, and even cooking methods all contribute to the total.

Water usage creates another major piece of the puzzle, especially in homes with older fixtures or unnoticed leaks. A dripping faucet or running toilet may not seem urgent, but those small issues waste gallons of water daily and quietly inflate bills. Long showers, frequent laundry cycles, and inefficient dishwashing routines also push usage higher than necessary. Seasonal changes amplify these habits, especially during summer when air conditioning and water use both increase. Many households don’t adjust routines to match those seasonal shifts, which leads to spikes that feel unexpected. Awareness alone can start to shift those patterns in a meaningful way. Once habits come into focus, simple changes begin to lower costs without sacrificing comfort.

Smart Moves That Actually Lower Costs

Cutting utility bills doesn’t require drastic lifestyle changes; it starts with targeted, practical adjustments that deliver real results. Switching to energy-efficient lighting, such as LED bulbs, immediately reduces electricity use without affecting brightness or comfort. Smart thermostats offer another powerful tool by automatically adjusting temperatures based on daily routines. That kind of automation eliminates wasted energy without constant manual changes. Running appliances like dishwashers and washing machines during off-peak hours can also reduce costs in areas with time-based pricing. Sealing windows and doors prevents air leaks, which keeps heating and cooling systems from working overtime. Even unplugging unused devices helps eliminate phantom energy loss.

Water-saving upgrades also make a noticeable difference, especially when paired with smarter usage habits. Low-flow showerheads and faucets reduce water consumption without sacrificing pressure, which keeps comfort intact while lowering costs. Fixing leaks quickly prevents long-term waste and avoids unnecessary charges that build over time.

Adjusting water heater temperatures slightly downward reduces energy use while still providing plenty of hot water. Outdoor water use deserves attention too, especially for homes with gardens or lawns. Watering during early morning or evening hours minimizes evaporation and improves efficiency. These changes don’t require major investments, yet they consistently deliver measurable savings.

The Real Reason Your Utility Bill Is Skyrocketing and What You Can Do
Image Source: Shutterstock.com

Why Timing Matters More Than You Think

Utility costs often fluctuate throughout the day, and timing plays a bigger role than many people realize. Peak hours typically occur when demand hits its highest point, often in the late afternoon and early evening. During those times, electricity costs more because utilities must generate additional power quickly. Running high-energy appliances during those peak periods drives bills higher even if overall usage stays the same. Shifting those activities to off-peak hours reduces costs without reducing comfort or convenience. Many utility providers now offer time-of-use plans that reward this kind of behavior with lower rates.

Seasonal timing also affects energy costs in a big way, especially during extreme weather months. Summer heat drives air conditioning use, while winter cold increases heating demand, and both scenarios push energy consumption upward. Preparing for those seasonal shifts ahead of time helps control costs before they spike. Simple steps like servicing HVAC systems, improving insulation, and adjusting thermostat schedules can make a noticeable difference.

Even cooking habits matter, since using ovens during hot months adds extra heat that forces cooling systems to work harder. Paying attention to timing transforms energy use from reactive to strategic. That shift alone often leads to lower bills without major sacrifices.

You DO Have Control

Rising utility bills don’t come from a single cause, and that complexity makes them feel overwhelming at first glance. Once the real drivers come into focus—global energy shifts, infrastructure costs, everyday habits, and timing—those numbers start to make more sense. More importantly, they start to feel manageable instead of mysterious. Small, consistent changes create real impact, especially when they target the biggest areas of energy and water use. Smart habits, efficient upgrades, and better timing combine into a strategy that works month after month. No dramatic overhaul required, just smarter decisions stacked together.

If you’re in Texas, the deregulated energy market means you can compare and switch providers like Energy Texas to potentially lower your monthly bill.

Which change feels easiest to try first, and what strategies have already made a difference? Drop your thoughts, ideas, or personal wins in the comments and keep the conversation going.

You May Also Like…

Seniors Receiving ‘Utility Shutoff’ Calls With Exact Account Numbers — Here’s How Criminals Are Stealing Them

Utility Companies Are Ending Paper Billing — How It Will Change Your Monthly Payments

Utility Billing Cycle Changes Causing Double Charges

Adult Kids Beware: Some States Can Sue You for Your Parents’ Medical Bills

From Medicare to Medicaid: Why Billing Glitches Are Causing Unexpected Medical Bills Nationwide

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: budgeting, Cost of living, electricity prices, energy costs, Energy Efficiency, home tips, Inflation, saving money, smart home, sustainability, utility bills, water bills

Medicare Mishaps: Costly Enrollment Errors Most People Don’t See Coming

April 6, 2026 by Brandon Marcus Leave a Comment

Medicare Mishaps: Costly Enrollment Errors Most People Don't See Coming
Image Source: Shutterstock.com

The clock does not tick quietly when it comes to Medicare. It practically shouts, flashing deadlines and fine print that can cost thousands if ignored. One wrong move during enrollment can lock in penalties that stick around for years, quietly draining retirement savings without warning. That sounds dramatic, but it reflects the reality of a system packed with timelines, rules, and exceptions that rarely announce themselves clearly. This is not just paperwork; it is a financial decision that can ripple through decades.

Excitement might not be the first emotion tied to Medicare, but it should at least command attention. The choices made during enrollment shape access to doctors, prescription costs, and monthly budgets in ways that feel immediate and long-lasting. Too many people assume everything will fall into place automatically, only to discover later that Medicare expects careful timing and active decisions. A little awareness now can prevent major headaches later, and yes, it can even save serious money. .

The Enrollment Window That Waits for No One

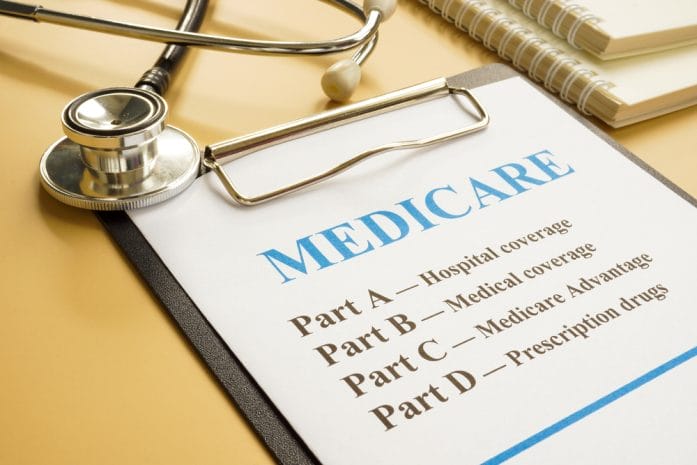
Medicare runs on a strict timeline, and it refuses to bend for latecomers. The Initial Enrollment Period opens for seven months around a person’s 65th birthday, including the three months before, the birthday month, and the three months after. That window feels generous at first glance, but it closes quickly, especially for anyone juggling work, family, or other life transitions. Missing that window does not just mean a delay; it often triggers permanent penalties that quietly add up over time.

The Part B late enrollment penalty increases monthly premiums by 10 percent for every full 12-month period someone delays enrollment without qualifying coverage. That penalty does not fade away after a year or two; it sticks for as long as Part B coverage continues. The system assumes individuals will act on time, and it rarely offers second chances without financial consequences. Waiting for a reminder in the mail or assuming automatic enrollment can create a costly misstep. Staying ahead of that timeline with a calendar alert or a checklist can prevent a mistake that feels small at first but grows into a long-term burden.

“I’m Still Working, So I’m Covered”… Not Always

Employer coverage feels like a safety net, but it does not always align perfectly with Medicare rules. Many people assume they can delay Medicare because they still work or receive insurance through a spouse’s job, but the size of the employer matters. If the employer has fewer than 20 employees, Medicare often becomes the primary payer, and failing to enroll in Part B can lead to denied claims and unexpected bills. That kind of surprise can hit hard, especially after years of assuming everything stayed covered.

Even with larger employers, coordination rules can create confusion. Some plans require Medicare enrollment to maintain full coverage, while others allow delays without penalties. The details hide in plan documents that rarely get a full read, and that is where mistakes begin. Checking directly with the employer’s benefits administrator or a licensed Medicare advisor can clear up the confusion before it turns into a financial mess. Taking a proactive approach here beats dealing with denied coverage later, especially when medical bills do not wait for paperwork corrections.

The Prescription Drug Gap That Sneaks Up Fast

Prescription coverage under Medicare, known as Part D, comes with its own set of rules and timelines. Skipping enrollment because medications seem unnecessary at the moment might feel like a smart way to save money, but that decision can backfire quickly. Medicare expects continuous “creditable” drug coverage, meaning coverage at least as good as Part D. Without it, a late enrollment penalty applies, and that penalty increases for every month without coverage.

That penalty does not disappear once someone finally enrolls; it sticks around and increases premiums indefinitely. The system essentially rewards consistency and punishes gaps, even if those gaps made sense at the time. A person might feel healthy at 65, but health needs can change rapidly, and enrolling late can make prescriptions far more expensive than expected. Reviewing current coverage and confirming whether it meets Medicare’s standards can prevent this hidden cost. A simple phone call or plan comparison can make a huge difference.

Free Isn’t Always Free: The Part A Assumption Trap

Many people hear that Medicare Part A comes with no premium and assume that means automatic enrollment and no decisions required. That assumption causes trouble, especially for those who continue contributing to a Health Savings Account. Enrolling in Part A makes someone ineligible to keep contributing to an HSA, and contributions made after enrollment can trigger tax penalties. That detail rarely appears in bold print, yet it can create a complicated tax situation.

Delaying Part A might make sense for those still working and contributing to an HSA, but that decision requires careful timing. Medicare allows retroactive Part A coverage for up to six months when someone finally enrolls, which can complicate HSA contributions even further. Planning ahead and stopping HSA contributions in time can prevent a tax headache that no one wants to deal with later. It might sound like a technical detail, but it carries real financial consequences that deserve attention.

Medicare Mishaps: Costly Enrollment Errors Most People Don't See Coming
Image Source: Shutterstock.com

Choosing the Wrong Plan… and Getting Stuck With It

Medicare does not offer a one-size-fits-all experience, and that flexibility creates both opportunity and risk. Original Medicare, Medicare Advantage, and supplemental plans each come with different costs, provider networks, and coverage rules. Picking a plan based on a quick glance or a catchy advertisement can lead to frustration when coverage does not match actual healthcare needs. The wrong choice can limit doctor options or increase out-of-pocket costs in ways that only become clear after the fact.

Switching plans does not always offer an easy fix. While Medicare provides an Annual Enrollment Period, some changes come with restrictions, and certain supplemental plans may require medical underwriting outside specific windows. That means a rushed decision today can limit options tomorrow. Taking time to compare plans based on prescriptions, preferred doctors, and expected healthcare needs can make a huge difference. Using Medicare’s official plan finder tool or consulting a licensed advisor can turn a confusing process into a more confident decision.

The Paperwork Problem That Causes Big Delays

Paperwork might not feel like the most exciting part of Medicare, but it plays a critical role in avoiding delays and coverage gaps. Missing forms, incorrect dates, or incomplete employer verification can slow down enrollment and push coverage start dates further out than expected. That delay can leave someone temporarily uninsured or responsible for unexpected medical bills. It sounds simple, but even small errors can create frustrating setbacks.

Keeping organized records can prevent these issues from spiraling. Copies of employment history, proof of coverage, and enrollment confirmations can make the process smoother and faster. Submitting forms early and double-checking details before sending them can eliminate unnecessary stress. Medicare does not always move quickly when fixing errors, so accuracy on the first attempt matters more than most people expect. A little extra attention here can save weeks of waiting and a lot of unnecessary worry.

Playing Medicare Smart From the Start

Medicare does not reward guesswork, and it certainly does not forgive missed deadlines easily. Staying informed, asking questions, and planning ahead can transform a confusing process into a manageable one. Every decision, from enrollment timing to plan selection, carries weight, and treating those choices seriously can prevent long-term financial strain. The good news is that most of these costly mistakes remain completely avoidable with a bit of preparation and awareness.

What strategies have worked, or what surprises have popped up along the way? Share thoughts, experiences, or hard-earned lessons in the comments and keep the conversation going.

You May Also Like…

How to Enroll in Medicare Without Getting Hit With the IRMAA “Stealth Tax”

Social Security 2026 COLA: Why Your 2.8% Raise Disappeared After Medicare Deductions

The Hidden Medicare Rule Turning 3-Day Hospital Stays Into $10,000–$15,000 Surprise Bills

6 Income Thresholds That Can Trigger Higher Medicare Premiums

More Retirees Are Seeing Higher Medicare Costs—And It’s Tied to Income From Years Ago

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: health insurance tips, healthcare costs, Medicare, Medicare enrollment, Medicare mistakes, Medicare Part A, Medicare Part B, Medicare penalties, Planning, retirement planning, seniors, Social Security

Unclaimed Benefits: Are You Missing Out On Government Money

April 6, 2026 by Brandon Marcus Leave a Comment

Unclaimed Benefits: Are You Missing Out On Government Money
Image Source: Shutterstock.com

Somewhere out there, money sits with your name on it. Not metaphorically. Not as a feel-good slogan. Actual, real funds that governments set aside for everyday people who qualify but never step forward to claim them. Every year, billions of dollars go untouched, quietly waiting while paperwork confusion, outdated assumptions, or simple lack of awareness keep people from cashing in. That gap between eligibility and action creates one of the strangest financial realities around: people struggle financially while help literally waits for them.

That idea sparks curiosity for a reason. Government programs rarely feel exciting, and nobody wakes up thrilled about forms or eligibility requirements, yet those same programs often hold the exact relief people search for. Tax credits, healthcare subsidies, housing support, and direct payments can ease pressure in ways that budgeting alone cannot fix.

The Hidden Treasure Chest No One Talks About

Government agencies across the country manage a wide range of financial support programs, and many of them go underused every single year. The Earned Income Tax Credit, for example, consistently ranks as one of the most overlooked benefits despite offering thousands of dollars to qualifying households. Many people assume they earn too much, or they think filing taxes will not benefit them, which leads them to skip it entirely. That assumption costs real money, and it happens more often than expected. Eligibility rules change over time, and income thresholds shift, so a past rejection does not guarantee a current one.

Unclaimed property programs add another surprising layer to this hidden treasure chest. State governments hold billions in forgotten funds from things like old bank accounts, uncashed checks, insurance payouts, and utility deposits. These funds remain accessible, and anyone can search for their name through official state websites. The process takes minutes, yet millions of people never try it. That disconnect highlights a bigger issue: many assume “if it existed, someone would have told me,” which simply does not hold true when it comes to financial benefits.

Unclaimed Benefits: Are You Missing Out On Government Money
Image Source: Pexels.com

Healthcare subsidies also fall into this category, especially through marketplace plans tied to income levels. People often overestimate the cost of insurance and skip exploring options altogether, missing out on reduced premiums or even free coverage. Programs like Medicaid expand eligibility in many regions, yet outdated assumptions still prevent people from applying. A quick eligibility check can reveal options that dramatically reduce monthly expenses, and those savings stack up fast over a year.

Why So Many People Walk Away From Free Money

A strange mix of psychology and bureaucracy keeps people from claiming what they deserve. Confusion plays a huge role, especially when forms use technical language that feels intimidating. People see long applications and assume the process will take hours, when in reality many programs now offer streamlined online systems. That initial hesitation becomes a barrier that stops action before it even begins. Once someone decides something feels complicated, they rarely revisit it.

Misinformation also spreads quickly, especially through word of mouth. Someone hears that a neighbor got denied for a benefit and assumes the same outcome will apply to them. That leap ignores differences in income, household size, and eligibility updates. Government programs evolve frequently, and relying on outdated information leads to missed opportunities. A quick check with official sources often reveals a completely different reality than what people expect.

Pride and perception quietly influence decisions as well. Some view benefits as something meant only for extreme situations, even though many programs target working individuals and families. Tax credits reward employment, not the absence of it, yet stigma still lingers. That mindset keeps people from exploring options that exist specifically to support them. Breaking that mental barrier can unlock access to resources that improve financial stability without compromising independence.

The Most Overlooked Programs Worth Checking Today

Several programs consistently fly under the radar, even though they offer meaningful financial relief. The Earned Income Tax Credit leads the list, but the Child Tax Credit also delivers substantial benefits for families. These credits can reduce tax bills or even generate refunds, which makes them powerful tools for boosting income. Many families underestimate their eligibility or assume they need high-level tax knowledge to claim them, which simply does not reflect reality.

Supplemental Nutrition Assistance Program benefits often surprise people with their flexibility and reach. Income limits adjust based on household size and expenses, and many working households qualify without realizing it. Grocery costs continue to climb, so even modest assistance can ease monthly pressure. Applying online takes less time than most expect, and approval can open the door to consistent savings.

Housing assistance programs, including vouchers and rental support, also remain underutilized in many areas. Waiting lists can create the impression that nothing remains available, yet local programs and grants often operate alongside federal options. Checking with local housing authorities or community organizations can uncover opportunities that never appear in national headlines. Energy assistance programs deserve attention as well, especially during extreme weather seasons when utility bills spike. These programs help cover heating and cooling costs, offering relief exactly when expenses hit hardest.

How To Actually Claim What Belongs To You

Taking action requires a simple shift: replace assumptions with verification. Start with official government websites, which provide up-to-date eligibility guidelines and application portals. Many states offer centralized benefit checkers that allow users to input basic information and receive a list of programs they may qualify for. That single step can reveal opportunities that never crossed the radar before. Setting aside thirty minutes for this process can lead to hundreds or even thousands of dollars in support.

Tax preparation services also play a key role in uncovering benefits. Free assistance programs, often run by community organizations, help individuals file taxes while identifying credits they might miss on their own. These services target people with moderate or low incomes, and they often operate during tax season with certified volunteers. Taking advantage of these resources removes guesswork and ensures nothing gets left behind.

Staying organized makes a noticeable difference as well. Keeping documents like pay stubs, rent receipts, and utility bills ready speeds up applications and reduces frustration. Many programs require similar information, so gathering it once creates a smoother process across multiple applications. Setting reminders to recheck eligibility each year also helps, since life changes such as income shifts or family size adjustments can open new doors. Consistency turns a one-time effort into an ongoing advantage.

Stop Letting Money Slip Through Your Fingers

Money should not sit untouched while financial pressure builds elsewhere, yet that exact scenario plays out every day. Government programs exist to provide support, and many people qualify without realizing it. A quick search, a short application, or a simple eligibility check can unlock resources that make a real difference. Ignoring these opportunities leaves money on the table, and that choice rarely makes sense once the facts come into focus.

What programs have you checked recently, and what surprises have you found along the way? Drop your thoughts, strategies, or even frustrations in the comments and keep the conversation going.

You May Also Like…

April Food Alert: How to Use SNAP’s Medical Expense Deduction if Your Benefits Suddenly Dropped

6 Ways Criminals Are Using AI to Impersonate Banks and Government Agencies

6 Government Benefit Checks That Could Be Delayed Under New Fraud Reviews

What are ETFs and How do They Benefit the Average Investor?

Charity Strategy: 9 Giving Moves That Bring Tax Benefits Many People Ignore

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Lifestyle Tagged With: assistance programs, benefits eligibility, financial help, Financial Tips, government benefits, Personal Finance, public assistance, saving money, Social Security, stimulus programs, tax credits, unclaimed money

Pharmacies Are Moving Prescriptions to App-Only Refills — What Seniors Need to Know

April 3, 2026 by Brandon Marcus Leave a Comment

Pharmacies Are Moving Prescriptions to App-Only Refills — What Seniors Need to Know
Image Source: Shutterstock.com

It’s happening faster than many people expected: the pharmacy counter is going digital, and not everyone feels ready for the switch. Major pharmacy chains now steer customers toward mobile apps for refilling prescriptions, tracking medications, and even managing insurance details. That shift promises convenience and speed, but it also raises a real question—what happens to people who prefer a phone call, a face-to-face chat, or a simple paper reminder? This change doesn’t just tweak how prescriptions get filled; it reshapes the entire experience of managing health. For seniors who built routines around personal service, this shift can feel less like progress and more like a barrier.

The truth sits somewhere in the middle. Pharmacy apps can simplify life in powerful ways, yet they also create confusion, frustration, and sometimes risk when people feel locked out of the system. The good news is that nobody needs to feel stuck or left behind.

Why Pharmacies Are Pushing Apps So Hard

Pharmacies have not made this move on a whim, and the reasons behind the push matter more than they might seem at first glance. Digital systems allow pharmacies to process refills faster, reduce human error, and manage inventory more efficiently, which helps keep medications in stock when they are needed most. Apps also let customers refill prescriptions at any hour without waiting on hold or standing in line, which sounds like a clear win in a busy world. On top of that, automated reminders can prevent missed doses or forgotten refills, a feature that healthcare providers strongly support because consistency saves lives. Insurance integration within apps adds another layer of convenience, allowing users to check coverage or copay amounts instantly without extra paperwork. Pharmacies also reduce staffing pressure by shifting routine tasks into digital channels, which has become especially important as healthcare systems deal with worker shortages.

Despite these benefits, the push toward app-only refills creates a noticeable gap for seniors who rely on traditional methods. Not everyone owns a smartphone, feels comfortable downloading apps, or wants to navigate passwords and notifications just to refill a prescription. Some people prefer speaking to a pharmacist directly, especially when they have questions about side effects or dosage changes. Others worry about privacy and do not trust storing personal health data on a device. Pharmacies sometimes scale back phone support or in-person services as they invest more in digital tools, which can leave people feeling pushed aside. That sense of being rushed into technology without enough guidance creates frustration and even anxiety around something as critical as medication.

The Hidden Risks: When Convenience Starts to Complicate Care

Switching to app-based refills introduces a set of risks that do not always show up in marketing materials or cheerful advertisements. Missed notifications can lead to missed refills, especially if someone does not check their phone regularly or accidentally silences alerts. Confusing interfaces can cause people to order the wrong medication or select the wrong dosage, which creates serious health concerns. Some seniors struggle with small text, complex menus, or multi-step verification processes that require juggling passwords or codes. Even a simple glitch or forgotten login can delay access to essential medication, which turns a minor inconvenience into a potential health issue.

Another concern revolves around communication. When people rely on apps, they often lose those spontaneous conversations with pharmacists that catch potential problems early. A quick question at the counter might reveal a drug interaction, a side effect, or a dosage concern that an app cannot flag clearly enough. Without that human connection, some individuals feel less confident about their medication routines. Family members who help manage medications also face challenges if they do not have access to the same app or login information. These small gaps can add up quickly, especially for people managing multiple prescriptions or chronic conditions.

How to Stay in Control Without Going Fully Digital

No one needs to accept an all-or-nothing approach when it comes to prescription refills, and that fact opens the door to practical, empowering solutions. Many pharmacies still offer phone refills, even if they promote their apps heavily, so asking directly about alternatives can uncover options that are not advertised upfront. Setting up automatic refills provides another simple workaround, as it reduces the need to interact with apps altogether while keeping medications on schedule. Some pharmacies also allow caregivers or family members to manage accounts, which can bridge the gap for those who prefer help with technology. Using a basic calendar or pill organizer alongside pharmacy services adds another layer of protection against missed doses.

Local independent pharmacies often maintain a stronger focus on personal service, which makes them a valuable option for people who want human interaction. Transferring prescriptions to a pharmacy that offers better support can make a noticeable difference in day-to-day comfort. Community programs, senior centers, and even libraries frequently offer basic tech training that helps people feel more confident using apps at their own pace. Pharmacists themselves can walk customers through app features step by step, so asking for a demonstration during a visit can turn confusion into clarity. Taking small, manageable steps builds confidence without overwhelming anyone.

What to Ask Your Pharmacy Before You Feel Stuck

Walking into a pharmacy with the right questions changes everything, and it puts control back where it belongs. Asking whether phone refills remain available helps clarify options immediately and prevents unnecessary stress. It also helps to ask about automatic refill programs, delivery services, and reminder calls, which many pharmacies still provide even if they do not highlight them. Questions about privacy and data security can ease concerns about using apps, especially when pharmacists explain how information stays protected. Clarifying how to reach a pharmacist directly ensures that important conversations do not disappear in the digital shuffle.

Understanding how to link multiple prescriptions under one profile can simplify medication management for those who decide to use apps. Asking about caregiver access opens the door for family members to assist when needed. Pharmacies can also explain how to receive alerts in ways that feel comfortable, whether through text messages, phone calls, or app notifications. These conversations take only a few minutes, yet they can eliminate confusion and build confidence quickly. Taking the time to ask questions turns a frustrating system into something that actually works.

Pharmacies Are Moving Prescriptions to App-Only Refills — What Seniors Need to Know
Image Source: Shutterstock.com

Staying Independent in a Digital Pharmacy World

This shift toward app-based prescription refills will not slow down anytime soon, but it does not need to take away independence or peace of mind. Pharmacies may lean heavily into digital tools, yet patients still hold the power to choose how they interact with those systems. Knowing the available options, asking the right questions, and exploring simple alternatives can keep medication routines safe and stress-free. Technology should serve people, not the other way around, and that mindset makes all the difference. With a few adjustments, even the most traditional routine can adapt without losing its reliability.

What strategies have worked when dealing with digital changes at pharmacies, and what challenges still feel frustrating or unclear? Share thoughts, tips, or personal experiences in the comments.

You May Also Like…

The Hidden Medicare Rule Turning 3-Day Hospital Stays Into $10,000–$15,000 Surprise Bills

More Retirees Are “Aging in Place” — But Many Homes Aren’t Built for It

What Your Pharmacy Isn’t Telling You About Your Pills

6 Government Benefit Checks That Could Be Delayed Under New Fraud Reviews

7 Expenses That Are Rising Faster Than Most People Expected

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: aging, digital health, healthcare access, healthcare tips, medication management, medication refills, mobile apps, patient safety, pharmacies, prescriptions, seniors, technology

Think Items Are Going Missing? 6 Signs You May Be Living With a Thief

April 2, 2026 by Brandon Marcus Leave a Comment

Think Items Are Going Missing? 6 Signs You May Be Living With a Thief
Image Source: Pexels.com

There comes a moment when coincidence stops feeling like coincidence. One missing item turns into two, then three, and suddenly the pattern starts staring back like a blinking warning light that refuses to be ignored. That uneasy feeling creeps in quietly at first, but it builds fast once small losses start stacking up into something bigger. People often shrug it off in the early stages, telling themselves it must be forgetfulness, bad luck, or simple misplacement. But when things keep disappearing without explanation, that instinct to question what’s really happening deserves attention instead of dismissal.

Living under the same roof should feel safe, predictable, and steady, not like a low-grade mystery that never quite resolves. Yet when belongings vanish in ways that don’t make sense, the situation shifts from frustrating to deeply unsettling. Trust becomes shaky, and even ordinary routines start to feel off-balance. Recognizing the signs early can prevent things from spiraling into bigger problems, especially when theft tends to escalate over time rather than stop on its own.

1. The “Now You See It, Now You Don’t” Pattern That Keeps Repeating

A one-time disappearance can feel like a fluke, but repeated losses tell a completely different story. When items vanish in a consistent way—especially things you use often—that pattern signals something more deliberate than forgetfulness. Small, everyday objects like cash, chargers, or clothing pieces often go first because they attract less attention and create plausible deniability. Over time, those missing items begin to form a trail that feels too structured to ignore.

Pay attention to frequency rather than size, because thieves often start small to avoid suspicion. Someone testing boundaries may remove low-value items first, then gradually move toward things that matter more. This gradual escalation doesn’t happen randomly; it reflects a calculated approach that relies on hesitation and doubt from others in the home. When multiple items disappear over weeks or months, especially from the same spaces, that pattern rarely comes from coincidence.

Another key detail involves timing, because missing items often line up with specific absences or routines. If belongings disappear when certain people stay home alone or have access to your space, that detail adds another layer of concern. The pattern doesn’t need to feel dramatic to matter—it just needs to repeat consistently. Tracking those instances mentally or even jotting them down can bring clarity faster than relying on memory alone.

2. Your Space Starts Feeling… Disturbed

There’s a difference between a messy room and one that feels subtly off. When drawers sit slightly ajar, belongings shift out of place, or personal items appear handled differently, that feeling of disturbance becomes hard to ignore. It doesn’t always scream “something’s wrong,” but it whispers it just loudly enough to create discomfort. That subtle disruption often points to someone going through your belongings without permission.

People who take items rarely leave things exactly as they found them, even when they try. Small details—like folded clothes that now sit differently or bags that look rummaged through—can signal unauthorized access. These clues matter because they show intent rather than accident, especially when they happen repeatedly. Even shared spaces can reveal patterns when certain areas look consistently disturbed after someone else uses them.

Trust that instinct when something feels off, because that gut reaction often picks up on details before logic catches up. Ignoring that feeling can delay action and allow the behavior to continue. Instead of brushing it aside, take note of when and where those disruptions occur. Over time, those observations can paint a clearer picture of what’s really happening.

3. Money and Valuables Begin to Shrink in Sneaky Ways

Cash doesn’t leave a trail, which makes it one of the first targets in many theft situations. When small amounts go missing from wallets, purses, or loose storage spots, it can feel easy to second-guess the loss. Maybe it got spent and forgotten, or maybe it never existed in the first place—at least that’s what the situation tries to suggest. But consistent shortages, even small ones, often indicate intentional removal rather than simple oversight.

Valuables don’t always disappear all at once either. Jewelry, electronics, or collectible items might go missing one at a time, spaced out to avoid detection. This slow approach allows someone to take more over time without raising immediate alarm. That strategy relies on hesitation and uncertainty, which gives the person responsible more opportunity to continue.

Keeping track of valuables becomes essential in these situations, not out of paranoia but out of practicality. Simple habits like photographing items or noting where they stay can help establish clarity if something disappears. These steps don’t accuse anyone directly, but they create a record that removes doubt. When losses stop feeling random and start following a pattern, documentation can make all the difference.

Think Items Are Going Missing? 6 Signs You May Be Living With a Thief
Image Source: Pexels.com

4. Defensive Behavior That Feels a Little Too Strong

When suspicion enters a shared space, behavior often shifts—and not always in subtle ways. Someone who reacts with immediate defensiveness, anger, or exaggerated denial when the topic of missing items comes up may raise concern. Strong reactions don’t prove guilt on their own, but they can signal discomfort with the subject. That discomfort sometimes comes from knowing more than they admit.

Watch for overreactions that don’t match the situation, especially when no direct accusation has been made. A casual mention of missing items shouldn’t trigger hostility or intense emotional responses. When it does, that mismatch can feel like a red flag worth paying attention to. It suggests that the conversation touches a nerve in a way that feels disproportionate.

Changes in routine can also reveal something deeper. Someone may start avoiding shared spaces, limiting interactions, or becoming unusually private. These shifts don’t confirm wrongdoing, but they add context when combined with other signs. Looking at behavior as part of a larger pattern helps separate coincidence from something more intentional.

5. Excuses That Keep Changing Shape

Everyone misplaces things occasionally, but explanations shouldn’t constantly evolve or contradict themselves. When someone offers different reasons each time an item goes missing, that inconsistency can point toward dishonesty. A believable explanation usually stays stable, even when questioned. Shifting stories, on the other hand, often signal an attempt to cover something up.

Pay attention to details within those explanations. Do timelines change? Do locations suddenly shift? Do reasons feel overly complicated for a simple situation? These inconsistencies don’t always stand out immediately, but over time they create a pattern that becomes harder to ignore. The more the explanation changes, the less reliable it becomes.

Consistency matters in everyday life, and that includes accountability. When explanations feel like they adjust to fit the moment, that flexibility can raise serious questions. Instead of accepting each new version at face value, compare them against previous ones. That comparison can reveal gaps that weren’t obvious at first glance.

6. You Start Locking Things… and It Actually Helps

One of the clearest indicators comes from a simple test: securing your belongings. When items suddenly stop disappearing after you lock them away, that change speaks volumes. It suggests that access—not coincidence—played a major role in the problem. This shift often provides the strongest confirmation that something deliberate has been happening.

Locking things up doesn’t solve the root issue, but it does create a boundary that limits opportunity. People who take advantage of easy access often stop when that access disappears. That reaction doesn’t require confrontation to understand what’s going on. The absence of new losses can act as its own form of evidence.

Taking practical steps like using lockboxes, securing rooms, or limiting access can protect belongings while you figure out next steps. These actions focus on safety rather than accusation, which helps keep the situation grounded. If theft continues even after those measures, that escalation signals an even more serious issue that may require outside help.

The Moment Everything Starts Adding Up

Once the signs begin lining up, the situation stops feeling like a guessing game and starts looking like a pattern with clear direction. Missing items, disturbed spaces, inconsistent explanations, and behavioral changes rarely occur in isolation when something isn’t right. Each piece alone might feel small, but together they create a picture that becomes difficult to ignore. Acting early can prevent further loss and reduce the emotional toll that comes with ongoing suspicion.

Have you ever noticed patterns like this in your own space, or found a surprising way to confirm what was really going on? Share your thoughts, strategies, or experiences in the comments—someone else might need that exact insight.

You May Also Like…

Why Does Financial Confidence Feel Fragile?

7 Financial Choices That Seem Safe Until They Aren’t

7 Signs Your Identity Has Been Stolen and What to Do Immediately

5 Warning Signs Someone Is Using Your Social Security Number

5 Simple Methods to Protect Your Identity From Cyber Theft

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: home safety, household conflict, missing items, personal security, roommate issues, safety tips, stolen belongings, suspicious behavior, theft prevention, theft warning signs, trust issues

I Moved to a Tax-Free State And Here Are 10 Costs No One Warned Me About

April 2, 2026 by Brandon Marcus Leave a Comment

I Moved to a Tax-Free State And Here Are 11 Costs No One Warned Me About
Image Source: Unsplash.com

There’s a genuine thrill that comes with the phrase “tax-free.” It sounds like a cheat code to adult life, a golden ticket where paychecks stretch further and financial stress fades into the background. The idea practically sells itself: no state income tax means more money stays where it belongs. It feels like a smart move, a strategic upgrade, the kind of decision that screams financial savvy. On paper, it looks like a clean win.

But reality loves complexity, and tax-free states come with a plot twist. That missing income tax doesn’t disappear into thin air—it reappears in ways that feel less obvious but hit just as hard. The excitement of relocating quickly meets the reality of everyday expenses that quietly stack up. Some costs creep in slowly, while others make a dramatic entrance right after moving day. What starts as a financial victory lap can turn into a budgeting puzzle that demands attention and strategy.

1. The Property Tax Plot Twist That Hits Hard

Property taxes often take center stage in tax-free states, and they do not play around. Without income tax revenue, many states lean heavily on property taxes to fund schools, infrastructure, and public services. That means homeowners often face higher-than-expected annual bills, even if the home price itself looked reasonable. The initial excitement of buying a home can fade quickly when that first property tax statement lands.

Renters do not escape this either, even though it might feel like they should. Landlords typically pass those higher property taxes along through increased rent, which means monthly payments climb quietly over time. That steady increase can catch people off guard, especially those who moved expecting overall savings. Budgeting for housing suddenly requires a closer look at long-term trends instead of just upfront costs.

A smart move involves researching property tax rates before committing to a location. Some neighborhoods or counties carry significantly higher rates than others, even within the same state. Looking beyond the listing price and digging into annual tax obligations can prevent unpleasant surprises. A little homework upfront saves a lot of stress later.

2. Sales Tax: The Silent Budget Drainer

Shopping feels different when sales tax climbs into the picture with enthusiasm. Tax-free states often rely more heavily on sales tax, and those percentages can stack up fast. Every grocery run, clothing purchase, or home upgrade quietly chips away at that “extra” income people expected to keep. The effect doesn’t feel dramatic at first, but it builds over time.

Daily spending habits suddenly matter more than ever. A casual lunch out or a quick online order carries a slightly heavier financial weight than expected. Over a year, those extra percentages can add up to a significant amount, especially for households with higher spending patterns. It becomes clear that “no income tax” doesn’t mean “no tax impact.”

3. Insurance Costs That Refuse to Stay Quiet

Insurance costs often rise in tax-free states, especially in areas prone to natural risks like hurricanes, floods, or extreme weather. Homeowners insurance can come with higher premiums, and in some cases, additional coverage becomes necessary. Flood insurance, for example, might not come standard but quickly becomes essential depending on the location.

Car insurance can also spike depending on local factors like traffic patterns, accident rates, and weather conditions. Even drivers with clean records might notice a jump compared to previous states. That increase can feel frustrating, especially when it wasn’t part of the initial relocation plan.

4. Utility Bills That Bring the Heat—or the Cold

Utility costs can swing wildly depending on the climate of a tax-free state. Hot regions often demand heavy air conditioning use, while colder areas rack up heating bills that stretch through long winters. Either way, energy consumption tends to rise, and so do monthly bills.

Homes built in certain climates might lack the insulation or efficiency features that keep costs down. That means even moderate usage can lead to surprisingly high bills. New residents often underestimate how much climate impacts their daily expenses until the first few utility statements arrive. Energy efficiency becomes a valuable strategy. Upgrading insulation, using smart thermostats, and maintaining HVAC systems can help manage costs. Even small habits, like adjusting thermostat settings or sealing drafts, can add up over time. Staying proactive keeps those bills from spiraling.

I Moved to a Tax-Free State And Here Are 11 Costs No One Warned Me About
Image Source: Shutterstock.com

5. Higher Fees for Everyday Services

States without income tax often rely on fees to fill revenue gaps, and those fees show up in unexpected places. Vehicle registration, driver’s licenses, and local permits can cost more than anticipated. Even routine services like waste collection or public amenities might carry higher price tags.

These costs rarely grab attention during the moving process, but they quickly become part of everyday life. Paying more for basic services can feel frustrating, especially when it wasn’t factored into the initial decision. Over time, those fees create a steady drain on finances. Planning ahead helps soften the impact. Researching common fees in a new area provides a clearer picture of ongoing expenses. Setting aside a small buffer in the budget ensures these costs don’t catch anyone off guard. Preparation turns a surprise into a manageable detail.

6. Housing Demand That Drives Prices Up

Tax-free states often attract a steady stream of new residents, and that demand pushes housing prices higher. The appeal of lower taxes creates competition, which can drive up both home prices and rent. What looks like a good deal at first glance might actually reflect a heated market.

Limited inventory adds to the pressure. Buyers and renters often face bidding wars or quick decision timelines, which can lead to higher costs or compromises. That fast-paced environment can feel overwhelming, especially for those who expected a smoother transition. Taking time to explore different neighborhoods can reveal better options. Expanding the search radius or considering less competitive areas might lead to more affordable choices. Patience and flexibility can make a big difference in finding the right fit without overspending.

7. Transportation Costs That Sneak Up Fast

Getting around can cost more than expected in many tax-free states. Public transportation options might be limited, which means relying heavily on a personal vehicle. That brings fuel, maintenance, and insurance costs into sharper focus.

Longer commutes also play a role, especially in sprawling regions where distances between work, home, and amenities stretch out. More driving means more wear and tear on vehicles, along with higher fuel expenses. Those costs build steadily over time.

Planning routes and considering fuel-efficient vehicles can help manage expenses. Carpooling or combining errands reduces unnecessary trips. Small adjustments can keep transportation costs from becoming overwhelming.

8. Groceries That Cost More Than Expected

Food prices can vary significantly depending on the region, and tax-free states sometimes carry higher grocery costs. Factors like transportation, climate, and local supply chains influence pricing. That means everyday staples might cost more than anticipated.

Dining out can also feel pricier, especially when combined with higher sales tax. Regular meals at restaurants or takeout orders quickly add up. What once felt like a casual habit can turn into a noticeable expense. Cooking at home more often can help balance things out. Planning meals and shopping strategically reduces waste and saves money. Even small changes in grocery habits can lead to meaningful savings over time.

9. Tourism Taxes That Hit Locals Too

Popular tax-free states often double as major tourist destinations, and that brings its own set of costs. Hotels, entertainment, and dining frequently include tourism-related taxes or higher base prices. While these target visitors, residents often feel the impact as well.

Local businesses may price services higher due to demand from tourists. That means everyday experiences, from dining out to attending events, can cost more than expected. Living in a desirable destination comes with a premium. Seeking out local deals or off-peak options can help reduce costs. Exploring lesser-known spots often leads to more affordable and enjoyable experiences. A little creativity keeps entertainment budgets in check.

10. Healthcare Costs That Vary Widely

Healthcare expenses can differ significantly depending on the state and local infrastructure. Some tax-free states offer fewer public healthcare programs or higher private insurance costs. That creates variability that can surprise new residents.

Access to providers and facilities also plays a role. Limited options in certain areas can lead to higher costs or longer travel times for care. That adds both financial and logistical challenges.

Reviewing healthcare options before moving helps avoid surprises. Comparing plans and understanding local resources ensures better preparedness. Taking control of this aspect early makes a big difference.

The Real Cost of “Saving Money” Might Surprise You

The promise of tax-free living carries undeniable appeal, but it demands a closer look. Each of these hidden costs tells part of the story, and together they paint a more complete picture. Saving on income tax doesn’t guarantee overall savings, especially when other expenses rise to fill the gap. Smart planning turns that realization into an advantage instead of a setback.

What surprised you most about the idea of tax-free living, and what strategies would you use to stay ahead of these hidden costs? Drop your thoughts, ideas, or experiences in the comments and get the conversation going.

You May Also Like…

How Utilities Affect Colorado’s Low Property Tax Rate

Texas vs. Florida: Which No-Income-Tax State Actually Leaves You With More Money?

Texas Grocery Warning: New Anti-Fraud Rules Mean More ID Checks at Checkout Starting in April

The Texas Mortgage Shock: Why Your Monthly Payment Just Jumped $400 Without Warning

6 Advanced Techniques to Lower Your Capital Gains Taxes Legally

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: budgeting, Cost of living, hidden expenses, Housing Costs, lifestyle costs, moving tips, Personal Finance, Planning, property taxes, relocation advice, tax-free states

Utility Companies Are Ending Paper Billing — How It Will Change Your Monthly Payments

April 1, 2026 by Brandon Marcus Leave a Comment

Utility Companies Are Ending Paper Billing — How It Will Change Your Monthly Payments
Image Source: Shutterstock.com

The mailbox just lost one of its most reliable tenants. Utility bills, those predictable envelopes that showed up month after month, now face extinction as companies push hard toward digital-only billing. This shift doesn’t just clean up clutter or save paper; it reshapes how households track spending, avoid late fees, and even think about money. The familiar ritual of tearing open an envelope and scanning a printed total starts to feel like something from another era, and that change comes with both convenience and a few surprising challenges.

The move away from paper billing signals a bigger transformation in how everyday finances operate. Utility companies want faster payments, fewer administrative costs, and tighter integration with apps and automated systems, and digital billing delivers all of that. At the same time, households must adjust quickly or risk missed due dates, confusion over fluctuating charges, and less visibility into monthly expenses. This transition doesn’t ask for permission; it already moves forward at full speed.

The Quiet Disappearance of Paper Bills

Utility companies didn’t flip a switch overnight, but the direction feels unmistakable. Many providers now charge extra fees for paper statements, while others require customers to opt in just to keep receiving them. This shift reduces printing and mailing costs for companies, but it also nudges households toward digital habits whether they feel ready or not. Environmental messaging often supports the change, and it resonates with many people who want to cut down on waste. Still, the financial motivation behind the scenes plays an equally strong role, as digital billing trims operational expenses significantly.

That disappearance changes more than the format of a bill; it alters the way people engage with their finances. A physical bill demands attention in a way that an email notification sometimes does not, especially when inboxes overflow with promotions and updates. Without that tangible reminder sitting on a kitchen counter, some households find it easier to forget or delay payments. Others embrace the change and enjoy instant access to statements, searchable records, and fewer piles of paperwork. The key difference lies in how intentional someone becomes about checking and managing those digital alerts.

The shift also affects households that rely on traditional systems, including those who prefer in-person payments or lack consistent internet access. Utility companies often provide alternatives, but those options sometimes come with extra steps or limitations. This transition doesn’t treat everyone equally, and it places more responsibility on individuals to adapt quickly. Keeping track of account logins, passwords, and billing cycles becomes part of the new routine, whether anyone asked for it or not.

Autopay Takes Center Stage — For Better or Worse

Digital billing almost always pairs with a strong push toward automatic payments. Utility companies highlight autopay as the easiest, most reliable option, and they often sweeten the deal with small discounts or incentives. That setup ensures bills get paid on time, which helps avoid late fees and service interruptions. For many households, autopay removes a layer of stress and keeps everything running smoothly in the background. It turns bill-paying into something that happens quietly rather than something that demands attention every month.

That convenience, however, comes with trade-offs that deserve attention. Automatic withdrawals can catch people off guard when utility costs spike due to seasonal changes or unexpected usage. A higher-than-usual bill might slip through without immediate notice, especially if no one checks the account regularly. This situation can strain budgets quickly, particularly when multiple bills withdraw at different times. Staying aware of account balances and reviewing statements becomes essential, even when autopay handles the actual transaction.

Setting up alerts offers a simple but powerful way to stay in control. Many utility providers allow users to receive notifications when bills exceed a certain amount or when payments process. Taking advantage of these tools helps bridge the gap between convenience and awareness. Reviewing statements at least once a month ensures that errors or unusual charges don’t go unnoticed. Autopay works best when it operates alongside active oversight rather than replacing it entirely.

Utility Companies Are Ending Paper Billing — How It Will Change Your Monthly Payments
Image Source: Shutterstock.com

Budgeting Feels Different Without That Paper Trail

Paper bills used to create a natural rhythm for budgeting. Each envelope served as a physical checkpoint, prompting a quick review of charges and a mental note of how much money needed to go out. Digital billing changes that rhythm completely, and it requires a more proactive approach to tracking expenses. Without a stack of statements to flip through, everything lives inside apps and online accounts, which can feel less immediate and sometimes less memorable.

This shift pushes households toward digital budgeting tools, which can actually improve financial awareness when used consistently. Apps that categorize expenses, track trends, and send reminders offer a level of insight that paper bills never could. Still, these tools demand setup and regular engagement, and they don’t work automatically without some effort. Those who ignore them risk losing sight of how much utilities actually cost month to month, especially when payments happen quietly in the background.

Creating a simple routine helps keep everything on track. Setting a specific day each month to review all utility accounts builds a new habit that replaces the old paper-based system. Downloading or saving digital statements also creates a record that remains easy to access later. Even something as straightforward as jotting down monthly totals in a notebook can restore a sense of control. The format may change, but the goal stays the same: understanding where money goes and why.

Security, Scams, and the Digital Learning Curve

Moving bills online introduces a new set of concerns that didn’t exist with paper statements. Email notifications and online portals create opportunities for phishing scams and fraudulent messages that mimic legitimate utility companies. These scams often look convincing, and they can trick people into sharing sensitive information or making payments through fake websites. Staying cautious becomes essential, especially when dealing with unexpected emails or urgent payment requests.

Learning how to spot red flags makes a huge difference in avoiding these traps. Checking the sender’s email address, avoiding suspicious links, and logging in directly through official websites rather than email prompts all help reduce risk. Utility companies often provide guidance on recognizing scams, and taking a few minutes to review that information can prevent costly mistakes. Digital billing offers convenience, but it also requires a sharper awareness of online security.

Password management plays a bigger role than ever in this new system. Each utility account needs a strong, unique password, and reusing the same credentials across multiple sites increases vulnerability. Using a password manager simplifies this process and keeps everything organized. Enabling two-factor authentication adds another layer of protection, making it harder for unauthorized users to access accounts. These steps may feel like extra work at first, but they quickly become part of a safer, more confident digital routine.

What This Shift Means for the Future of Payments

The move away from paper billing doesn’t stand alone; it connects to a broader evolution in how financial systems operate. Utility companies continue to integrate with mobile apps, smart home devices, and real-time usage tracking tools. This integration allows households to monitor energy or water consumption more closely and adjust habits in response. Payments may soon feel less like monthly events and more like ongoing, dynamic interactions with services.

This future brings both opportunities and challenges. Real-time data can help reduce waste and lower costs, but it also requires consistent attention and engagement. Subscription-style billing models may become more common, smoothing out seasonal spikes but changing how expenses appear month to month. Staying flexible and open to new tools will help households adapt as these changes unfold. The key lies in understanding how each new feature affects both convenience and control.

Adapting early often makes the transition smoother. Exploring available apps, setting up notifications, and reviewing account settings all help build confidence in the new system. Asking questions and seeking support from utility providers can also clear up confusion and prevent mistakes. This shift doesn’t need to feel overwhelming; it simply requires a willingness to adjust habits and embrace new ways of managing everyday finances.

The Bill Isn’t Gone — It Just Changed Shape

Paper bills may disappear, but the responsibility behind them stays exactly the same. Digital billing offers speed, convenience, and powerful tools, yet it also demands more awareness and intentional habits. Ignoring that shift can lead to missed payments, surprise charges, or security risks, while embracing it can create a smoother, more efficient system for handling monthly expenses. The difference comes down to how actively someone engages with the process.

What changes feel most exciting or frustrating about this shift to digital billing, and what strategies have worked best for staying on top of monthly payments? Share your thoughts, ideas, or personal approaches in the comments and keep the conversation going.

You May Also Like…

From Medicare to Medicaid: Why Billing Glitches Are Causing Unexpected Medical Bills Nationwide

6 Ways to Lower Your Tax Bill Under 2026 OBBBA Updates

Ground Ambulance Bills Still Fall Outside Federal Surprise Billing Protections

Why Do Utility Bills Keep Rising Even When Usage Stays the Same

Here’s When It’s Okay To Let Kids Move Back Home To Pay Off Bills

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: Autopay, bill pay apps, Budgeting Tips, digital payments, energy bills, finance trends, household expenses, money management, online billing, paper billing, Personal Finance, utility bills

Texas Grocery Warning: New Anti-Fraud Rules Mean More ID Checks at Checkout Starting in April

April 1, 2026 by Brandon Marcus Leave a Comment

Texas Grocery Warning: New Anti-Fraud Rules Mean More ID Checks at Checkout Starting in April
Image Source: Unsplash.com

A routine grocery run just got a little more complicated. Starting in April, shoppers across Texas will notice a shift at checkout that feels small at first but carries big implications for everyday purchases. Cashiers will pause more often, ask more questions, and request identification in situations that once moved along without a second thought. That quick swipe-and-go rhythm many people rely on will slow down, and the reason behind it sits at the center of a growing problem that retailers refuse to ignore any longer.

Fraud has surged, and retailers have decided to respond with tighter controls that land directly at the checkout counter. These new anti-fraud rules aim to protect both businesses and customers, but they also bring a noticeable change in how transactions unfold. Grocery stores will now enforce stricter ID verification for certain purchases, especially when payment methods raise red flags or involve higher risk. That means shoppers need to stay alert, prepared, and patient as stores adjust to this new normal.

Checkout Just Got Serious: What’s Actually Changing?

Texas grocery stores have started tightening their checkout procedures in response to rising fraud cases tied to stolen cards, digital payment abuse, and identity theft. Retailers now require cashiers to verify identification more frequently, particularly when shoppers use credit cards, debit cards without PINs, or contactless payments that trigger system alerts. These checks do not apply randomly; stores use fraud detection software that flags transactions based on patterns like unusual spending amounts, mismatched purchase behavior, or suspicious card activity. When the system flags a purchase, the cashier must step in and confirm identity before completing the sale.

This shift means shoppers will encounter more pauses during checkout, even for everyday purchases like groceries, household items, or quick convenience runs. Stores want to reduce chargebacks and financial losses, which have climbed sharply in recent years due to increasingly sophisticated fraud tactics. Retailers have also faced pressure from payment processors and financial institutions to improve transaction security. As a result, these new rules reflect a broader industry push rather than a single-store policy.

The changes do not mean every transaction will involve an ID check, but shoppers should expect more frequent requests than before. Stores will focus especially on higher-value purchases, gift cards, and transactions that involve multiple payment attempts. That means grabbing a cart full of groceries could now include a brief identity verification step if something about the payment triggers concern. It adds a layer of friction, but it also aims to prevent unauthorized use of someone else’s financial information.

Why Stores Are Cracking Down Hard Right Now

Retailers have reached a tipping point with fraud, and they no longer treat it as a background issue. Organized retail crime has expanded, and fraudsters have become faster, smarter, and harder to detect. Stolen card data circulates quickly online, and criminals often test cards with small purchases before making larger ones. Grocery stores, with their steady flow of transactions, have become a prime testing ground for these schemes. That reality has forced companies to act quickly and decisively.

Payment technology has evolved, but fraud tactics have evolved right alongside it. Contactless payments, mobile wallets, and self-checkout lanes have added convenience, yet they have also introduced new vulnerabilities. Retailers now balance speed with security, and that balance has started to tilt toward tighter controls. These new ID requirements reflect that shift, as stores aim to stop fraudulent transactions before they go through instead of dealing with the fallout afterward.

Financial losses from fraud do not just hit corporations; they ripple outward and affect pricing, staffing, and store operations. When fraud increases, businesses often respond by raising prices or cutting costs elsewhere. That means these new checkout rules could help stabilize prices over time by reducing losses. While the immediate experience may feel inconvenient, the long-term goal focuses on protecting both the business and the shopper from larger financial harm.

What Shoppers Need to Do to Stay Ahead

Preparation now plays a bigger role in a smooth grocery trip. Carrying a valid photo ID has become just as important as bringing a wallet or phone. Shoppers who rely heavily on contactless payments or credit cards should keep identification easily accessible to avoid delays. This small habit can make a noticeable difference when a cashier asks for verification, especially during busy shopping hours when lines move quickly.

Using secure payment methods can also reduce the chances of triggering an ID check. Entering a PIN for debit transactions often signals a lower risk compared to signature-based payments. Sticking to familiar stores and consistent spending patterns can help as well, since fraud detection systems tend to flag unusual behavior. While shoppers cannot control every factor, they can reduce friction by keeping transactions predictable and straightforward.

It also helps to stay patient and aware of what cashiers deal with during these checks. Employees must follow store policies, and they often have little flexibility once a system flags a transaction. Getting frustrated will not speed things up, but being prepared can keep the process smooth. A quick ID check may only take a few seconds, and it could prevent a much bigger issue down the line, such as unauthorized charges or frozen accounts.

Texas Grocery Warning: New Anti-Fraud Rules Mean More ID Checks at Checkout Starting in April
Image Source: Shutterstock.com

The Checkout Experience Is Changing

The rhythm of grocery shopping will shift in subtle but noticeable ways. Shoppers who breeze through checkout today may find themselves pausing for verification tomorrow, especially during peak hours. That pause might feel awkward at first, but it will likely become part of the routine as more stores adopt similar measures. Over time, the extra step could feel as normal as inserting a chip card or entering a PIN.

Self-checkout lanes may also see adjustments, as some stores begin adding employee oversight or prompts for ID verification when needed. This could slow down what many people consider the fastest option in the store. However, retailers want consistency across all checkout types, which means even self-service options will not escape these new rules. That consistency ensures fraud prevention does not depend on which lane a shopper chooses.

Despite the added steps, the goal remains simple: protect transactions and reduce risk. Most shoppers will adapt quickly, especially once they understand the reason behind the changes. The inconvenience will likely fade into the background, replaced by a new expectation that verification may happen at any time. In a world where digital fraud continues to rise, that expectation may start to feel less like a burden and more like a necessary safeguard.

A Small Change With Big Implications

These new checkout rules may feel like a minor tweak, but they signal a larger shift in how everyday transactions work. Grocery stores have moved from passive observation to active verification, and that approach will likely spread beyond Texas as other regions watch the results. Shoppers now play a more visible role in fraud prevention, whether they realize it or not. That role comes with small responsibilities, like carrying ID and staying alert, but it also offers added protection in return.

Will these new rules feel like a hassle, or will they bring a sense of reassurance knowing someone watches out for fraud in real time? Share thoughts, experiences, or strategies for handling these new checkout moments in the comments—what works, what frustrates, and what should change next?

You May Also Like…

How To Regularly Save Money At The Grocery Store

The $140,000 Oversight: The Missing Texas Tax Paperwork That Is Costing Homeowners Thousands This Week

The Texas Mortgage Shock: Why Your Monthly Payment Just Jumped $400 Without Warning

Power to Choose: Exploring Wind Energy Options in Texas Electricity Market

Power to Choose: Exploring Wind Energy Options in Texas Electricity Market

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Lifestyle Tagged With: checkout rules, consumer tips, credit cards, debit cards, fraud prevention, grocery stores, ID checks, payment security, retail policy, retail trends, shopping changes, Texas news

  • « Previous Page
  • 1
  • …
  • 9
  • 10
  • 11
  • 12
  • 13
  • …
  • 32
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • 10 Tactics for Building an Emergency Fund from Scratch by Vanessa Bermudez
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald

Copyright © 2026 · News Pro Theme on Genesis Framework