• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Investing

Should You Care About Warren Buffet’s Stock Trades

December 7, 2020 by Tamila McDonald Leave a Comment

warren buffett's stock trades

Warren Buffett is a bastion in the world of investment. The billionaire has a reputation for making smart choices. As a result, many investors wonder if they should mimic his moves or if keeping an eye on his trades would help them achieve better results. If you are trying to figure out if you should care about Warren Buffett’s stock trades, here’s what you need to know.

Why Investors Follow Warren Buffett’s Stock Trades

Generally speaking, when an investor spends time tracking Warren Buffett’s stock trades, their main goal is usually to snag similar results. Following the investment moves of a legend usually seems like a great idea. Many think that, by using an approach that mimics the Oracle of Omaha’s strategy, they can reach the same level of success.

However, some many also watch Warren Buffett’s stock trades for other reasons. For example, instead of attempting to follow his moves directly, they may use his trades to identify sectors that could be poised for gains or losses. At times, investors simply enjoy seeing how their strategy aligns with or differs from what others are doing, including individuals with some fame.

Changing Your Investment Approach to Match Warren Buffett

As mentioned above, some people watch Warren Buffett stock trades in hopes of following his strategy to increase their gains. In reality, that isn’t always a great idea.

One of the biggest reasons why you may not want to follow in Warren Buffett’s footsteps is that his investment goals may differ from your own. For example, he isn’t stashing cash for retirement, while that may be your main objective. As a result, his choices may not align with your preferred risk level.

Additionally, there are certain moves that he can make that are out of the reach of the vast majority of investors. For instance, he can establish massive stakes in companies that are household names, something that most investors can’t pull off.

Finally, Warren Buffett can make deals that an individual investor just can’t. For example, his $5 billion investment in Goldman Sachs in 2008 – which many considered to be a bailout – resulted in a $3+ billion gain when he unloaded it. But he didn’t purchase Goldman Sachs’s stock the way a normal investor would when that happened, putting him in a different position.

Generally, Warren Buffett’s unique position means that he can make moves that nearly everyone else can’t. Mimicking his approach is, therefore, practically impossible.

Overall, all of the points above suggest that changing your investment approach to match Warren Buffett isn’t a great idea. His strategy doesn’t rely on traditional kinds of investing, so it may not be compatible with you.

Warren Buffett’s Stock Trades: Should You Care?

Even if you shouldn’t copy Warren Buffett stock trades directly, that doesn’t mean keeping an eye on what he does is a bad idea. You may be able to use his choices to figure out options that you were previously overlooking, like an emerging sector.

The trick is to make sure that, even if you want Warren Buffett’s trade activity, you only make moves that align with your strategy, goals, and risk tolerance. That way, you’re doing what’s right for you and not just copying a billionaire whose unique position gives them different kinds of options.

Do you think investors should care about Warren Buffett’s stock trades? Why or why not? Share your thoughts in the comments below.

Read More:

  • Is It Too Late to Invest in FAANG Stocks?
  • The Pros and Cons of Index Investing
  • How Should I Invest for Retirement at Age 50?
Tamila McDonald
Tamila McDonald

Tamila McDonald is a U.S. Army veteran with 20 years of service, including five years as a military financial advisor. After retiring from the Army, she spent eight years as an AFCPE-certified personal financial advisor for wounded warriors and their families. Now she writes about personal finance and benefits programs for numerous financial websites.

Filed Under: Investing Tagged With: investing, stock trades

The Best, Low Maintenance Way to Invest 30K

December 2, 2020 by Jacob Sensiba Leave a Comment

If you’ve been building your savings to start investing and you’ve managed to put aside $30K, you may be wondering what your next step should be. How do I invest 30k? What is the best, low maintenance approach?

Here are some great ways to apply that 30K towards growing your wealth.

Pay Off Debt

First and foremost, use some of the money to pay off any debt you may have. It will save you money in the long-run. If you’re carrying a $10K credit card balance with a 15% interest fee, you’ll be paying an extra $1500/year in interest. That’s money that can be better spent on investments down the road. If you want to invest 30k, first start by getting rid of debt.

Emergency Fund

If you don’t already have one, put some of your money aside in an emergency fund so you know you’ll be able to manage if something unexpected happens. You should have 3-6 months’ worth of expenses put aside in an easily accessible account like a savings account. Just make sure it’s not linked to your debit card so you can’t spend it. The period of time you need to cover varies based on how long you think it would take you to find another job should something happen to your current job.

Earning return

What’s next has all to do with three things: risk tolerance, time horizon, and investment objectives. As a matter of fact, that’s how all of your investment decisions are made.

There are several different vehicles you can utilize, so what I’m going to do is give each vehicle its own section, explain what it is, and then give a little more detail as to when it could be used.

Certificate of Deposit (CD)

A bank product with a specified interest rate and a specified maturity. CDs are used to hold money for a specified period of time in a virtually risk-free fashion. More about CDs.

You’ll choose a CD for two reasons. The first is if you want a safe, federally insured vehicle to stash away some cash. The other reason is if you do not want to touch that money for a specified period. For example, you’re going to buy a house in three years and you don’t want to jeopardize that down payment. You buy/invest in a 3 year CD. At the end of year three, you’ll get back your principal (what you put in) and some accrued interest. Early withdrawal penalties apply.

Savings/Money Market Accounts

Typically used for your emergency fund. Easily accessible, and able to earn a little interest.

That’s pretty much it when it comes to these accounts. The interest they offer will be (not always) pretty low, but, like the CD, it offers a very safe place to store your cash until you need it. Unlike the CD, however, there are no early withdrawal penalties.

Qualified accounts

Basically any retirement account. Traditional IRA, Roth IRA, and employer-sponsored plans (401k, Simple IRA, etc.). There are contribution limits associated with these accounts.

With these accounts, as I said, contribution limits are something to pay attention to. With your Traditional and Roth IRA, there’s a $6,000 contribution limit ($7,000 if you’re 50 and older). 401ks have a limit of $19,500 (25,500 for 50 and older). Simple IRA limit is $13,500 ($16,500 for 50 and older).

This is a long term investment solution, as early withdrawal penalties apply. There are several ways to “exempt” yourself from that penalty, however, such as a first home purchase. For an extensive list of these exemptions, click here.

These accounts are also called “tax-advantaged” accounts because, as the name suggests, there are tax advantages. You either lower your taxable income with your contributions or have the ability to withdraw the funds “tax-free” (barring an early withdrawal penalty, of course).

Non-Qualified Accounts

Brokerage accounts or any investment vehicle that doesn’t have any tax benefits. Meaning, you pay taxes on any capital gains and dividends you receive. No contribution limits.

Honestly, the only advantage to these accounts is there is no contribution limit. For example, if you’ve maxed your contribution for your employer-sponsored plan and your IRA, then you can dump the rest of your money here.

Health Savings Account (HSA)

Accounts specifically designed to help you with your medical expenses. Money that you contribute to this account is “tax-free” or “tax-deductible”, which means it lowers your taxable income. Also, the funds, if used for qualified medical expenses, are tax-free.

With some, not all HSAs, you can invest what you’ve contributed. So if you have 30k to invest, I’ll point you to the below section to help with that. There are contribution limits with the HSA, however, so keep that in mind.

Asset allocation

After you’ve selected an investment vehicle (this section does not apply to CDs, savings accounts, or money market accounts), it’s time to invest your capital.

Asset allocation is my preferred method to invest, and I’ve written extensively on it here. So if you want to invest 30k, here’s what you need to ask yourself. How long until I need these funds? What is my ultimate goal for these funds? What am I willing to lose?

If your time period is less than 5 years, ignore this section and stick your money in a savings account or a CD. The risk/reward is unfavorable in this scenario.

If you have, ideally, 10+ years, then you have some options. The next question is about risk tolerance. What kind of portfolio are you comfortable with? Using the stocks/bonds/cash breakdown, are you a 60/40/0 type of person? Maybe you’re quite tolerant and prefer an 80/20/0 approach.

For those of you that are not tolerant of risk and/or you have a shorter number of years until you need to access these funds. Your portfolio should start at 50/50/0, and then adjust as you see fit. The cash portion in this breakdown should be used as investable cash for when you see a buying opportunity and/or funds you’ll need access to in the near future (unriskable capital).

Risk Tolerance

If you really want to know what your unique risk tolerance is, take our quiz!

I know I didn’t really give a concrete answer to what’s posed in the headline, but that’s the thing about investing – it’s incredibly personal. You need to do what’s best for you.

If time is on your side, max your retirement contribution, then put the rest in a savings account until next year. At that time, max it again.

If time isn’t your friend, a CD isn’t a bad idea. As I said earlier, paying down/off debt is incredibly worth it. That’s an automatic 15% return on your money if you pay off your credit card. Money that can be used more effectively going forward.

Read our articles, ask for advice, and do what’s best for you. That’ll help you answer the question: how do you invest 30k?


**Securities offered through Securities America, Inc., Member FINRA/SIPC. Advisory services offered through Securities America Advisors, Inc. Securities America and its representatives do not provide tax or legal advice; therefore, it is important to coordinate with your tax or legal advisor regarding your specific situation. Please see website for full disclosures: www.crgfinancialservices.com

Jacob Sensiba
Jacob Sensiba

Jacob Sensible is a financial advisor with decades of experience in the financial planning industry.  His journey into finance began out of necessity, stepping up to support his grandfather during a health crisis. This period not only grounded him in the essentials of stock analysis, investment strategies, and the critical roles of insurance and trusts in asset preservation but also instilled a comprehensive understanding of financial markets and wealth management.  Jacob can be reached at: jake.sensiba@mygfpartner.com.

mygfpartner.com/jacob-sensiba-wisconsin-financial-advisor/

Filed Under: Investing, money management, Personal Finance, risk management, successful investing, tax tips Tagged With: Debt, emergency fund, invest, investing

The Pros and Cons of Index Investing

November 18, 2020 by Jacob Sensiba Leave a Comment

What Are Index Funds?

If you are tired of trying to beat the stock market, index investing may be the best solution for you. Index funds work by investing your money into an index of stocks. (You may have heard of S&P 500 or the Dow.) When you put money into an index fund, you are investing in all of the companies that make up that particular index’s portfolio.

This is an alternative to choosing and investing in particular stocks. The same risks exist for you as those who buy stocks individually. However, investing in an index can provide broad diversification for your equity investments. Instead of putting your eggs in a few baskets, you’re putting one egg in 500 baskets (using the S&P 500 as an example).

Pros:  

They are inexpensive

There are usually no hidden fees or sales commissions with index funds. They have low annual fees- much more insignificant than the large fees that hedge funds and other alternatives charge. You can also increase your investments regularly without facing additional charges. Avoid indexes that do charge investors extra.

They Allow You to Invest in A Diverse Selection of Stocks

A well-balanced portfolio is key, and index funds aim to achieve this. As an individual, our investment opportunities are far more limited. By teaming up in an index fund we are able to share in the investments of many different stock companies. This is a much more attainable goal when we are part of an index fund.

They’re Efficient

Index funds financially outperform the majority of mutual funds. Although solo investors enjoy trying to “beat” the stock market and outsmart the institution, research has shown time after time that index fund earnings are much more consistent.

On top of bringing in more earnings, they are also user-friendly and easy. You can link your bank account to the index fund and it will automatically withdraw on a regular basis for you. No work on your part at all! Not only do you avoid having to study the stock market, but you also do not have to move the money over regularly.

It’s A No-Brainer

For anyone who is a newbie when it comes to investing, index funds are a life-saver. You don’t have to pick individual stocks or worry about the market rising and falling. All you have to do is provide the money, and the market should grow over time.

Cons of index investing: 

They Can be Vague

The assets making up a fund’s portfolio are constantly changing. It can be difficult to see exactly what you own and exactly how much you have made by investing. This is due to the fluctuating values in the underlying stocks and the index itself.

Limited Upside

Although investing in individual stocks can be messy and dangerous, some investors have a special eye for it. The professionals can often beat the market and get ahead of the game. In an index fund, you will never beat the market, because you will only grow consistently alongside it.

You’re Not in Charge

If you like to be in control, it could be difficult to learn to trust your money with strangers. Your index fund managers will be the ones in charge of what the fund gains in assets. You will likely never be personally able to call the shots in an index fund, and that is something you will have to come to terms with.

Not Suitable For All Investors

One of the most obvious cons of index investing is the “blanket” suitability for all investors. That’s, simply, not the case. The risk/return relationship suggests that higher return investments usually involve higher risk. Index funds are typically designed to capture the median performance of markets such as the S&P 500 or the Russell 2000.

As a result, they usually return market performance – no more and no less. If you want a very risky investment strategy, say, for example, investing in reverse convertible bonds, you likely won’t find index funds a suitable investment vehicle.

There Can be Fees

Some index funds do charge high fees and commissions. Be sure to stay clear of these.

My Concern

Generally speaking, index funds are great. They offer broad exposure to the market and do an incredible job at limiting fees.

But, in my mind, there are two more cons of index investing:

  1. Accidental concentration – As the market ebbs and flows, some sectors and industries will do better than others. For example, over the last 10+ years, the technology sector has outperformed the broader market by a large margin. As a result, tech makes up a greater portion of the index. If that sector experiences a pullback, the index as a whole will fall.
  2. Liquidity concerns – This mainly applies to index ETFs, but if the market, as a whole, drops, inexperienced investors will sell out of their positions to limit their losses. When there is a rush for liquidity, these ETFs need to sell underlying positions to provide investors with that liquidity. This can lead to an acceleration of losses. Investors sell, portfolio managers sell to give individuals their money, so underlying assets drop. This can cause more investors to sell, and again, portfolio managers to sell more. It’s a domino effect

Related reading:

Can you afford not to use index funds?

Robo-advisers: What I like and what I don’t like

Jacob Sensiba
Jacob Sensiba

Jacob Sensible is a financial advisor with decades of experience in the financial planning industry.  His journey into finance began out of necessity, stepping up to support his grandfather during a health crisis. This period not only grounded him in the essentials of stock analysis, investment strategies, and the critical roles of insurance and trusts in asset preservation but also instilled a comprehensive understanding of financial markets and wealth management.  Jacob can be reached at: jake.sensiba@mygfpartner.com.

mygfpartner.com/jacob-sensiba-wisconsin-financial-advisor/

Filed Under: Investing, investment types, low cost investing, Personal Finance Tagged With: index, Index fund, Index Funds, low fee investments

Is It Too Late to Invest In FAANG Stocks?

November 16, 2020 by Tamila McDonald Leave a Comment

is it too late to invest in FAANG stocks

If you explore any information about the stock market, you’ll be hard-pressed not to trip across an article talking about a FAANG stock or two. These tech behemoths are always movers and shakers, at times for better, at times for worse. But when you see the price tags associated with these investment options, you may be wondering, “Is it too late to invest in FAANG stocks?” If you fall into that category, here’s what you need to know.

[Read more…]

Tamila McDonald
Tamila McDonald

Tamila McDonald is a U.S. Army veteran with 20 years of service, including five years as a military financial advisor. After retiring from the Army, she spent eight years as an AFCPE-certified personal financial advisor for wounded warriors and their families. Now she writes about personal finance and benefits programs for numerous financial websites.
Filed Under: Investing Tagged With: FAANG Stocks, investing

Do Stock Splits Make Sense in 2020?

September 28, 2020 by Tamila McDonald Leave a Comment

history of stock splits

When a company is publicly traded, it has a set number of outstanding shares. This limits the number of potential investors, as there is only so much stock to go around. Additionally, it can, at times, hinder a company’s ability to bring in money. However, businesses do have the ability to practically create more shares out of thin air. With a stock split, they can increase the total number of shares available. The move can be financially beneficial, but it also comes with risk. If you are wondering, “Do stock splits make sense in 2020?” here’s what you need to know.

[Read more…]

Tamila McDonald
Tamila McDonald

Tamila McDonald is a U.S. Army veteran with 20 years of service, including five years as a military financial advisor. After retiring from the Army, she spent eight years as an AFCPE-certified personal financial advisor for wounded warriors and their families. Now she writes about personal finance and benefits programs for numerous financial websites.
Filed Under: Investing Tagged With: investing, stock splits

What Makes Gold So Valuable?

September 14, 2020 by Tamila McDonald Leave a Comment

why is gold so valuable

At some point, every would-be or current investor hears that they should consider adding gold to their portfolio. Gold often has a substantial amount of allure, a psychological impact that affects how people perceive its value, stemming back to ancient times when it was highly coveted. It’s also viewed as a form of safe haven, an investment that remains stable even during tumultuous times. If you are wondering what makes gold so valuable, and if its value is deserved, here’s a look at it from an investment perspective.

[Read more…]

Tamila McDonald
Tamila McDonald

Tamila McDonald is a U.S. Army veteran with 20 years of service, including five years as a military financial advisor. After retiring from the Army, she spent eight years as an AFCPE-certified personal financial advisor for wounded warriors and their families. Now she writes about personal finance and benefits programs for numerous financial websites.

Filed Under: Investing Tagged With: gold, valuable metals

When Are Manufactured Homes a Good Investment?

September 8, 2020 by Tamila McDonald 1 Comment

are manufactured homes a good investment

Manufactured homes are a popular option for budget-conscious people who want to own a house. However, they don’t always have the best reputation. And they certainly have their quirks. As a result, figuring out if buying one is a smart move isn’t easy. As with all real estate-oriented purchases, the value can vary depending on a wide range of factors. If you are wondering, “Are manufactured homes a good investment?” Here’s what you need to know.

What Is a Manufactured Home?

A manufactured home is a form of housing that’s built in a factory. They are usually built on a steel frame, instead of on-site. After a person purchases one. The structure is brought to the buyer’s property. Which could include land they own or a rental plot, such as in a manufactured or mobile home park. Once on-site. It is assembled and secured to a base. The type of which can vary.

Some argue that manufactured housing and mobile homes are different. This is true to a degree. Technically, to be a mobile home, the structure must have been constructed before 1976. Anything after that point is a manufactured home. Additionally, manufactured homes had to meet different building standards. These standard are higher than what their pre-1976 counterparts had to follow.

However, they are both factory-built structures that are usually assembled before being placed on the owner’s land or rental plot. Further, each of these housing types may not be on permanent foundations, depending on the requirements set forth by the state when they were placed. As a result, the general public usually uses the terms interchangeably.

There is also a third category of factory-built housing: the modular home. These can be similar to manufactured homes but are typically delivered in pieces and put together on site. They are also more likely to resemble a stick-built home and more commonly have a traditional foundation.

The Benefits of Owning a Manufactured Home

Manufactured homes are often appealing because they can cost less than a comparably sized and appointed stick-built house. Since they are factory-made en masse, the production costs are lower. Some of that savings is passed on to the buyer.

Many of the construction materials used are also similar to other kinds of houses. Depending on the requirements in your area, the building codes may be equal to, or even more stringent than, stick-built homes, too.

At times, buying a manufactured home may even cost less than being a renter in certain areas. To include if you have to purchase land. However, this isn’t universally true. So it’s important to examine the costs on both fronts before committing to a manufactured home purchase.

The Drawbacks of Investing in a Manufactured Home

There are some drawbacks that come with purchasing a manufactured home. Usually, if it isn’t on (or being placed upon) a permanent foundation. You may not be able to get a traditional mortgage to buy one. Similarly, if you don’t own the land – or aren’t in the process of buying it as well – most mortgage lenders won’t finance the purchase.

Even if you do buy land and want to put down a permanent foundation. You may not be able to place a manufactured home just anywhere. Local zoning laws may prohibit them in certain areas. If that’s the case, getting an exception can be incredibly challenging, and may not even be possible.

There can also be insurance concerns. Manufactured home insurance is generally more expensive than typical homeowners’ policies. They may not be at risk of greater damage during certain kinds of catastrophic events, such as fire, high winds, and floods. In some regions, manufactured houses have a higher rate of theft claims, something that causes elevated insurance rates for all owners in the area.

Negative Opinions About Manufactured Housing

Additionally, while some people are beginning to view manufactured homes more favorably, others still have negative opinions of them. This harms their resale value significantly. Even when they are on permanent foundations and can qualify for mortgage loans. When they aren’t on permanent foundations. The situation is usually worse.

Now, local market conditions, maintenance and upkeep, and similar factors can help manufactured homes retain value. Similarly, the value of the land can rise. Thus, offsetting some losses. However, this is almost universally an uphill battle. So it’s important to keep that in mind.

Finally, if you don’t intend to purchase land, that means you’ll have to rent a property. With this, permanent foundations usually aren’t an option. Plus, renting plots at mobile home parks can be costly, and some neighborhoods may not be the nicest options.

It can also put you at the mercy of the property owner. Especially, since moving a manufactured home once it has been set in place can be costly, structurally devastating, or both. As a result, you may not have a choice but to deal with plot rent price increases, neighborhood quality declines, or other potential issues that could arise.

Are Manufactured Homes a Good Investment?

As you can see, whether a manufactured home is a good investment depends on your goals. Paying for a manufactured house (even with land) may cost less than renting a comparable-sized space. Additionally, the value of your land may rise. Which is one aspect that could work in your favor.

However, the structure itself will typically decline in value. This is something that doesn’t always occur with stick-built homes. There can also be issues with obtaining a loan. As most don’t qualify for traditional mortgages. Not only can this be troublesome for would-be buyers, particularly when it comes to finding a reasonable interest rate.  It also means you’ll face hurdles if you ever want to sell.

Additionally, while many may call them mobile homes, moving them may not be an option, or may be incredibly costly. If you were considering placing a manufactured home on a rented lot, you could be making a long-term commitment to that arrangement, and that may not work in your favor over time.

Do you think that a manufactured home can be a good investment? Why or why not? Share your thoughts in the comments below.

Read More:

  • How to Make Money Investing in Pre-Construction Real Estate
  • Hard Money Loans: Benefits for Real Estate Investors
  • How to Invest in Real Estate Without Getting Your Hands Dirty

Advertisers Note: If you are reading this article because you’re interested in financial options, consider a loan from Max Cash Title Loans.  Max Cash Title Loans is American’s largest network of title loan providers.  Visit them today for your title loan needs!

Tamila McDonald
Tamila McDonald

Tamila McDonald is a U.S. Army veteran with 20 years of service, including five years as a military financial advisor. After retiring from the Army, she spent eight years as an AFCPE-certified personal financial advisor for wounded warriors and their families. Now she writes about personal finance and benefits programs for numerous financial websites.
Filed Under: Investing Tagged With: manufactured homes, real estate investing

Down Payment, Rainy Day, Be Prepared

August 12, 2020 by Jacob Sensiba Leave a Comment

rainy day

During the month of June, I wrote an article Down Payment or Investment Opportunities. It was my perspective on what to do with my savings, as I want to buy a home as soon as possible, but I also saw incredible opportunities to make money in the stock market.

Review a previous post

I thought I would revisit this topic, but my mindset shifted a little bit. That’s not to say that I’m proceeding in a different way than I thought I would, but now I’m thinking about it differently.

In that post, I said that I wanted to save $25,000 (I think) for a down payment, and wanted to do it in 4 years.

That meant that I would have to set aside a decent chunk each month to make that a possibility. The caveat to that is I would forego many chances to put money to work in the stock market.

Saving money for a down payment versus actively participating in the market is not the smartest financial decision (in my opinion), but in terms of what’s best for my family and for my psyche, this is the right move.

Because I have conviction in my decision now, my “regret” for not participating in the market has gone away.

When I first made the decision to save for a home instead, I often felt regret because the opportunities to make money were so great. Just from when I wrote that post (June 17) to now, the S&P 500 index ETF (SPY) is up 7.5%.

But I know this is the right choice, so I’m better able to focus my efforts on this goal. I’m eating out much less, I reviewed my budget to see where I could save more, and I’m finding bargains or buying second-hand items where I can.

Rainy day

While we are on the topic of saving money, I want to stress the importance of having some set aside for a rainy day.

As we’ve seen over the past few months, life can get pretty ugly. Now economic and humanitarian events of this scale don’t happen very often, but that’s not the point.

What I’m trying to convey here is that life is unpredictable. You don’t know what’s going to happen, or when. You don’t know how bad it’s going to be, so it’s important you have something set aside if things do get bad.

What’s more, it’s clear that the majority of businesses and corporations don’t have hardly any money set aside when disaster strikes. We like to think that if we put our time and energy working for a company, that they’ll take care of us when the time comes, but it’s clear now that most businesses won’t do that. They’ll protect the bottom line, and that’s that.

Obviously, not every company is like that, but I think it’s safe to say that the majority of organizations operate in this fashion.

Now, I do believe that this event will change how businesses operate. They’ll back away from the lean and mean operations, and start focusing on supply chain redundancy, as well as paying a little more for the security of their products and their people.

Be prepared

What I’m trying to say here is you need to look out for yourself and your family first. Sometimes, it’s necessary to forego big vacations, big expenses, or take out.

I think there’s room to be optimistic but also plan for the worst. I think it’s necessary to do both.

Living a life full of optimism is great, but you become a deer in the headlights when something bad happens. Taking the other side of things, being pessimistic, turns you into a cynic, and that has to be a depressing way to live.

Find room for both. Expect the worst, hope for the best, and save for a rainy day.

Related reading:

Everything You Need to Know to Set Up Your Own Emergency Fund

Jacob Sensiba
Jacob Sensiba

Jacob Sensible is a financial advisor with decades of experience in the financial planning industry.  His journey into finance began out of necessity, stepping up to support his grandfather during a health crisis. This period not only grounded him in the essentials of stock analysis, investment strategies, and the critical roles of insurance and trusts in asset preservation but also instilled a comprehensive understanding of financial markets and wealth management.  Jacob can be reached at: jake.sensiba@mygfpartner.com.

mygfpartner.com/jacob-sensiba-wisconsin-financial-advisor/

Filed Under: budget tips, Investing, money management, Personal Finance Tagged With: be prepared, down payment, investment opportunities, rainy day, saving money

ClickTrades Review – Broad Coverage of Asset Classes

June 22, 2020 by Justin Weinger Leave a Comment

ClickTrades Overview

Owned by KW Investments Limited, authorized and regulated by the Seychelles Financial Services Authority (FSA), ClickTrades is an online trading services provider establishing accounts for customers all around the world, except for the USA, Canada, and Japan residents.

With a long track record in the industry, it has become a reputable trading brand, constantly upgrading its services to meet the demands of the fast-changing markets. ClickTrades is well-known for its innovative and proprietary trading software, the 0-commission trading, useful educational resources, and a broad range of trading tools, including the popular Trading Central.

Asset Classes Covered

Diversity is one of the keywords when it comes to ClickTrades Assets. Customers using the WebTrader will have access to 2,100+ instruments, ranging from CFDs on FX, stocks, indices, commodities, cryptocurrencies, bonds, and ETFs. At the time of writing, there are 50+ CFDs based on currency pairs supported, , including majors, minors, and exotic pairs. Traders will have access to up to 1:300 leverage and fixed spreads for more of the FX pairs.

Due to increased interest in the stock markets, most of the ClickTrades offer is comprised of CFDs on shares from some of the popular markets around the world. USA, Germany, Australia, Switzerland, France, Canada, and CFDs on shares from many other markets are included right now. Up to 1:10 leverage, variable spreads, and 0 commission are some of the reasons why traders should choose this offer.

For traders wanting to get exposure on the stock markets, but prefer more liquid instruments, both CFDs on indices and ETFs have been included in the ClickTrades asset offer. S&P500, DAX30, Swiss 20, Sweden 30, VIXX, and the US dollar index, plus ETFs like QQQ, DIA, EWT, IDU, or FAS can be traded with leverage and variable spreads.

Commodities had been very active in 2020 and traders need access to as many instruments as possible. With ClickTrades, customers will be able to trade CFDs on cocoa, coffee, corn, rice, soybean, Brent oil, crude oil wheat, gold, silver, copper, and many other industrial or agricultural commodities, with up to 1:200 leverage and variable spreads.

Lastly, CFDs on bonds on 10Y German Treasuries, Gilt 10Y Bonds, US TBond 30Y, and the US TNote 10Y are covered for traders interested in the bond market. At the same time, CFDs on some of the popular cryptocurrencies like Bitcoin, Bitcoin Cash, Dash, Ethereum, Litecoin, and Ripple.

ClickTrades Trading Software

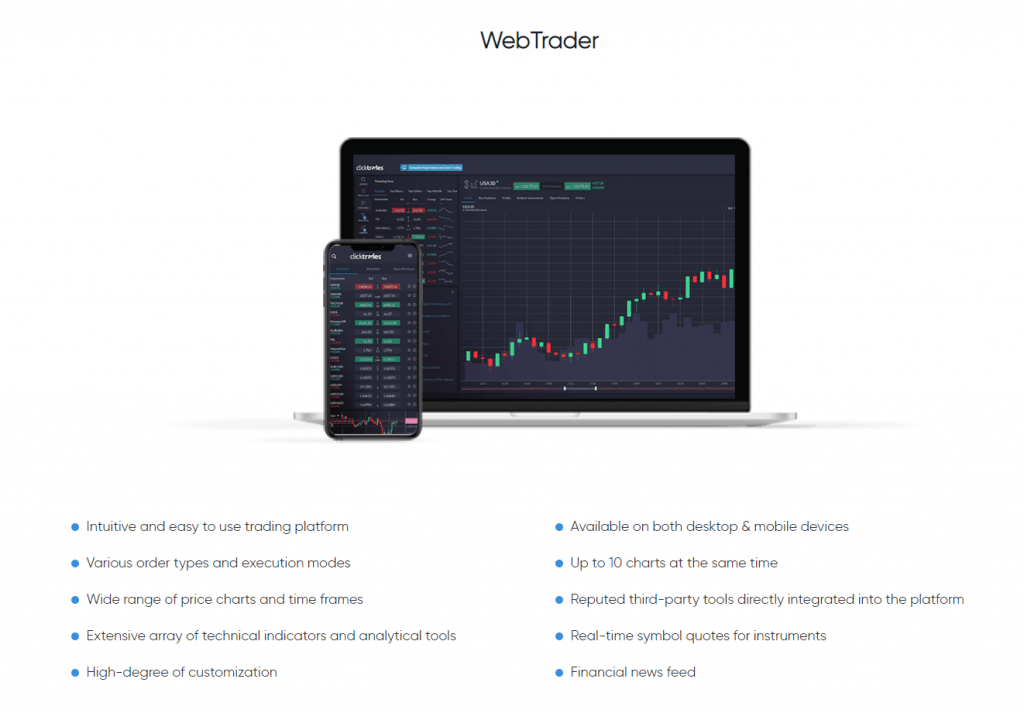
To get access to all of the above-mentioned instruments, traders will have to use the ClickTrades WebTrader, a proprietary and intuitive trading platform, available on both desktop and mobile devices. This is a platform designed to keep traders connected to the markets on the go or from the comfort of their workspace while accessing world-class assets.

Versatile, adaptable, as well as powerful 3rd party tools like Trading Central, make the WebTrader a complete gateway to the markets, integrating a full pack of features suited for many different trading strategies. With this platform, ClickTrades’ goal is to create the optimal trading environment and be a client-focused broker.

Also, the broker has support for the popular MetaTrader 5 platform, one of the most reliable platforms in the world, integrating many trading tools. It’s easy to access, has fast trade execution, is available on both desktop or mobile, and comes with an extensive package of analysis tools (built-in indicators, custom indicators, different time frames, and charts).

Summary

ClickTrades had proven over the years to be a reliable trading partner for customers. With 2,100+ instruments, reliable proprietary trading software, as well as many trading tools such as Trading Central, the broker continues to be a suitable choice for traders looking for diversified trading services.


Risk Warning: The materials contained on this document are not made by ClickTrades but by an independent third party and should not in any way be construed, either explicitly or implicitly, directly or indirectly, as investment advice, recommendation or suggestion of an investment strategy with respect to a financial instrument, in any manner whatsoever. Trading CDF’s involves significant risk of loss.


Justin Weinger
Justin Weinger

A married father of three, Justin Weinger works in private equity as a Corporate Finance Manager, he is also an avid blogger and personal finance enthusiast with a strong history of working in the automotive and publishing industry.

Filed Under: Investing

Down Payment or Investment Opportunities?

June 17, 2020 by Jacob Sensiba Leave a Comment

Down Payment or Investment Opportunities

The current dilemma I am having is whether to stash my savings for a down payment on a house or contribute to my Roth so I have cash available for buying opportunities.

I’m pinching pennies, and I’m saving money wherever I can so that cash is accessible when I need it. I just don’t know what to do with it.

Do I put it towards a down payment or set it aside for investment opportunities. Like most things in life, the answer will lie somewhere in the middle.

Down payment

I’ve mentioned in prior reflections that I’m renting right now.

I’m renting because I got divorced and exhausted all of my savings on the down payment for my house. That house is currently being rented by another family, and my ex-wife and I still own it.

That’ll help build equity into the house so we receive more if/when we decide to sell, which is good.

I’m happy with my current living arrangements. I like the place. I like the neighborhood. My commute to work is 2 minutes, and I’m close to all of my family and friends. All good things.

The only bad part is I have no outdoor space to call my own. I have no yard.

I’m trying to frame it positively by saying that I’m not spending my time on yard work, and instead, have more time to spend with my son/work on myself when he’s not here. These are both very good things.

However, I want to give my son a space to play. A place to put a jungle gym and a sandbox. A place where he can just run around and have fun.

I want to give him that because he deserves it. I want to use my savings for a down payment on a house so we can have a place to call our own. 

Investment opportunities

Here’s the second part of my dilemma. I see a lot of chances to put my money to work in the market.

I’m able to play the long game because of my investment philosophy and my training. The best investors I have long-term time horizons.

What I mean to say is I can see past the present and I have an idea of what my investments can do over the long term, and the [possible] reward for investing now can’t be ignored.

That’s why I’m having a difficult time deciding what to do.

What will I do?

As a parent, you want to give your kids everything. I want to have a place we can call our own.

At the same time, I know how valuable it is to start saving and investing early so I can take advantage of compounding returns.

So here’s what I’m thinking. I’m going to develop a “savings plan”. I’ll take the dollar amount for an ideal down payment and how far in the future (in terms of years) when I’ll want to use it.

I’m thinking of $25,000 for a down payment and four years until I’ll use it. I’ll, then, divide $25k by 48 to get my monthly savings goal. Anything over that number I’ll put in my Roth.

That’ll take care of saving for a house and for retirement.

My Last Reflection:

My Experience with Life Insurance

Related reading:

Your Go-To Budget Guide

What is Time Horizon and Risk Tolerance?

My Life and How I Manage Stress

My House and What Brought Me Here

Jacob Sensiba
Jacob Sensiba

Jacob Sensible is a financial advisor with decades of experience in the financial planning industry.  His journey into finance began out of necessity, stepping up to support his grandfather during a health crisis. This period not only grounded him in the essentials of stock analysis, investment strategies, and the critical roles of insurance and trusts in asset preservation but also instilled a comprehensive understanding of financial markets and wealth management.  Jacob can be reached at: jake.sensiba@mygfpartner.com.

mygfpartner.com/jacob-sensiba-wisconsin-financial-advisor/

Filed Under: Investing, money management, Personal Finance, Real Estate Tagged With: down payment, investing, Investment, Money, Real estate, savings

  • « Previous Page
  • 1
  • …
  • 22
  • 23
  • 24
  • 25
  • 26
  • …
  • 30
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • 10 Tactics for Building an Emergency Fund from Scratch by Vanessa Bermudez
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald

Copyright © 2026 · News Pro Theme on Genesis Framework