• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Investing

How To Find Money Management Success – Create a Dashboard

May 17, 2015 by Joe Saul-Sehy Leave a Comment

I just answered a question on Facebook about a recent podcast interview featuring some bill pay app creators. My interviewees had discussed just how difficult it can be to quickly and efficiently pay bills. “I don’t understand the problem these guys are presenting,” the poster said (I’m paraphrasing….). “I just go to my bank and use their bill pay app every other week. No problem.”

I wish it were that easy for everyone.

Let’s face it. Most of us have one big problem with our financial profile: we’re disorganized. After 16 years in the financial trenches, I’ve seen it far too often to think it’s anything other than a widespread problem. Most of us pay bills on sixteen different sites and have two old 401k plans with former employers, our current job’s plan AND different 529 plans for each child. It’s impossible to manage everything. I’d ask people with all of these different investments and bill paying problems how they juggle everything, and the answer I most often heard was, “I manage it very poorly.”

Yet moving investments to a single provider is a scary proposition. We’ve all heard of Bernie Madoff and don’t want to trust one person with our money. We also have all heard of diversification. Having different plans ensures that I won’t have all of my eggs in one basket.
So we have two problems: safety and diversification….and the fact that by having your assets spread out it’s impossible to track. How do we reconcile these two ideas?

It’s easier than you think.
dashboard
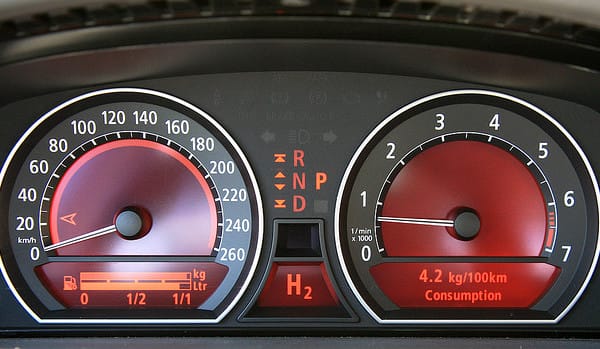
Could you drive a car with three different dashboards?

Think About Driving A Car

When you drive a car, do you have one set of gauges or several? Of course, you only have one set of gauges. It’d be impossible to drive if you had five different dashboards. Imagine! Yet, when you think about your car, it’s a diversified collection of inputs, all working independently. However, when you put it all together, these gauges make your car easier to drive. You get the right data at the appropriate time.
That’s what we’re looking for with money management success….we don’t want to get rid of diversification. Our goal is to create a single dashboard.

In Your Personal Life

There are three areas you should look at with your money:

– Budget and bill tracking. Budgets fail when you’re making decisions about spending without knowing where your money goes each month. Items like a mortgage or rent payment and grocery bills are easy to track, but how much do you spend each week on entertainment? If you don’t track your expenses, it’s difficult to project the future or find any money management success. The gauge you’re looking for to help with daily money management is an app like Mint or Yodlee, that will automatically track your expenses so when you’re planning next week’s expenses you know how you’ve spent money in the past.

For budgets, Mint will allow you to set up alerts so that you’re notified when going over budget categories. YNAB (paid subscription) will help you think differently about your budget and keeping every area in check. People who like the old-fashioned envelope system may be attracted to MVelopes, an automatic way of instituting envelope budgets so you don’t have cash sitting around your home.

– Investments. Many apps will help you track your investment life. In particular, Mint can create a pie chart of your overall diversification so you can easily make investment decisions. Companies like Jemstep allow investors to input their goals and then recommends investment shifts. FeeX will look at all of your investments across platforms and tell you how much you’re paying in fees….an important gauge to see when investing. Zillow has a cool app that will track any real estate properties you own. NVestly is a social media site that not only helps you see results across your whole portfolio, but also makes investing social (you can see others investment pies…but not the amounts of money they have in any investment). While each of these is different, using a couple of these apps can help you make better investment decisions without worrying about having too much money at a single brokerage account.

That said, brokerage houses all offer a diversified collection of investments through different companies. Just because your portfolio is housed as Fidelity, for example, doesn’t mean you have to have all Fidelity investments. They work with a wide range of providers….and you only have to visit one brokerage site to see everything. One dashboard but still diversification!

– Big Picture. You should be able to see how your net worth is growing at a glance. Mint and Yodlee, among others, will give you that quick at-a-glance overall picture.

With Your Business or Side Gig

If you’re self employed, you’re even more crunched for time. You have your personal books AND business metrics to track. As a fan of the excellent management book The E-Myth Revisited: Why Most Small Businesses Don’t Work and What to Do About It, I know that the keys to business success are in systems and data. How much data you have and how quickly you can use that data to your advantage are important. That means three things:

– Platform. If your business or side-gig project isn’t build on a solid footing, you’re hurting. A web presence built by experts like 1and1.com means that you won’t have to worry about the “bones” of your business being difficult for customers or employees to navigate.

– Reporting. Using your bank’s application to track inflows and outflows (as well as setting up a Mint or Yodlee account for your business) can help you stay on top of business expenditures and inflows. Ask your accountant about great business tracking apps and software that they recommend.

Overall

Staying diversified doesn’t mean having money scattered all over. By focusing on systems, building a dashboard, and reliable business help, you’ll find that you’re able to more quickly make financial decisions that move the needle. That’s how you build long-term wealth!

Photo: Steve Jurvetson
Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: Featured, Investing, Planning, successful investing, Uncategorized Tagged With: apps, Budget, cash, finance, Money

How To Choose the Best Investment For Your Goal

May 8, 2015 by Joe Saul-Sehy 1 Comment

Here’s the most-asked question I get asked at parties: where do you put your money to make it grow best?
It seems like an easy question but the answer is complicated, isn’t it?
Gurus who want to keep you in the dark use labels for investing like “hard” and “difficult”….and it can be. However, on the most basic level, it also can be the easiest thing in the world. You just need to start.
But why don’t people start? Most people I worked with were worried they be wasting their money on horrible investments. They were frozen and couldn’t choose the right path. I can see their point: the last thing anyone wants to do is invest all of their money and lose it quickly.
The good news? It is’t too late to start. At any age you can let your money start making you money. If you don’t want to go it alone, let’s talk about how to choose investments and finding good help.

Lots of Reasons To InvestInvesting

To us all, the idea of investing seems foreign at first. “I put my money in this thing and it makes money on it’s own? How does that work?” At first, ideas like “bonds”, “stocks”, “REITs” and others are like reading a new language.
That’s why you don’t start with the types of investments.
Start with your goals. Some people invest to make money quickly in the stock market while others are trying to make money slowly over time. Once you know your goal, then determine your risk. Different options offer different risks/rewards, so starting with what you want out of an investment drives the decision of where to invest. Investors with large sums might choose to invest in individual businesses while smaller investors can pool their money by buying into a mutual fund or exchange traded fund.

How Should You Invest Your Money….Personally?

Here’s the deal: I don’t know.
Since there are so many investment options and an unlimited number of goals you could be trying to achieve, you might decide to hire a consultant. Good helpers in your corner can help you decide what is best for what you want and the time-line you are looking at. When I was an advisor, I’d limit the choices to the ones that really mattered so my clients could focus on making money instead of worrying about just how many choices there were. Skilled advisors don’t just throw investments your way….they think of strategies that you may not have considered. Investing decisions might need to happen quickly, and if you don’t monitor your investments you could end up not only losing money but losing confidence in your strategy, which is even worse.
How do you find a good firm? I’d talk to friends first. Conduct interviews with advisors using some great tools like this checklist from FINRA. Good investment firms expect to be asked about their performance, how they work with clients and specifically what you’ll need from them. A good firm should feel like you’re hiring a partner more than buying a sales pitch.

What Else Can An Investment Company Provide?

I was always surprised when people would only want to deal with me for one or two investments. In fact, I became adamant that I knew about your whole portfolio, whether I was helping “babysit” your money or not. Every company is different, but many offer more than just investment consultation. Instead of finding someone to help you invest (something you can do on your own), look for someone to help you monitor your investment, give you advice along the way, and help you manage your tax liability, estate planning and budget issues. Not only should your advisor help you make the right decision based on your wants and needs, but they should make sure that you manage your portfolio well when markets turn sour (and they will).  Without a firm hand on the rudder, you might spend too much time looking at your investment and trying to determine if it is going well. Investment statements and prospectuses can also be ugly beasts as well and a good company can help decipher what’s important information and what’s garbage.
Ultimately, your investment decisions are up to you but a good pro can add to the bottom line. Find a company that can earn your trust and start letting your money make money.
Photo: Trading Academy
Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.
joesaulsehy.com/

Filed Under: Featured, Investing, Planning

5 Benefits of Investing in Real Estate Through Private Lending

May 8, 2015 by Joe Saul-Sehy 11 Comments

Real estate investing is a key ingredient for creating a long-term investment plan that will maximize your wealth and can even lessen your risk. But it seems like there are limited options available to you, considering most investors don’t have the necessary time or experience to do it successfully. You can:

Purchase your home. Although this is considered more consumption than investment, this is still an investment in real estate with potential appreciation.

Purchase rental property. Most people have heard about the ups and downs of owning rental properties, but collecting monthly rent from tenants is great way to generate income. The downside is the need to manage the property yourself or hire a property manager to directly handle tenant and property issues.

Purchase REITs. Similar to purchasing stocks, a real estate investment trust is a corporation that raises money by trading on major exchanges, and it pays investors 90 percent of its taxable profits via dividends.

Buying real estate doesn't necessarily mean dropping a ton of cash into the ground.
Buying real estate doesn’t necessarily mean dropping a ton of cash into the ground.

Besides these options, there’s another that the majority of real estate investors are unaware of: investing in real estate through private lending. As a private lender, you essentially become the bank. You lend your money to other investors (borrowers) and charge an appropriate interest rate for the use of your money. Here are some of the benefits of real estate private lending:

1) Monthly cash flow: The borrower pays you interest every month, which is typically between 8 and 15 percent.

2) Security: Your investment is secured by a lien on a tangible piece of real estate. That gives you collateral when lending your money, aside from just the soundness of the borrower. Typically, you shouldn’t loan more than 75 percent of the property’s current market value, giving you some cushion in the event that the property’s value decreases.

3) Diversification: Real estate private lending gives you the ability to diversify your portfolio — and not only from a real estate perspective. If you want to create current income, it’s another fixed-income option.

4) Lower volatility: You can better manage the market risk if you keep your real estate loans short term.

5) Passive investment: Instead of learning the nuances of real estate development, construction, management, etc., you can lend to other experienced real estate investors who do all the work. You just act as the bank and receive interest payments, and your money is returned at the end of the investment.

Being a real estate private lender is a great way to get exposure to real estate without doing all the work. But you still have to understand some of the risks involved. The market value can cause properties to quickly increase or decrease in value due to local and national factors.

Borrower credit can also be volatile; you need to make sure the borrower is in stable financial condition and can pay back the loan. Also, verify that the borrower’s investment strategy is solid.

Finally, make sure you have good legal representation to draft loan documents, coordinate the transaction, ensure your loan is properly recorded, and see that agreements are in place to protect you as the lender.

Real estate private lending is a great way to get exposure to real estate and generate passive income for your investment portfolio. As with any investment, you need to understand the risks involved and do your homework before jumping in headfirst. But if done right, real estate private lending can generate some of the best risk-adjusted returns in the marketplace.

Jeff Carter is the managing director and founder of Grand Coast Capital Group, where he oversees all aspects of the business. Grand Coast Capital Group is a national private lending firm based in Boston that provides creative short-term financing to real estate investors, builders, and developers across the country.

Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: Featured, Investing, investment types, Real Estate, successful investing

Evaluating a Single UK Stock–a Beginner’s Walkthru

April 20, 2015 by Joe Saul-Sehy Leave a Comment

I recently discovered a the UK stock Playtech, so I looked it up at BigCharts.com (link). Imagine my surprise when I saw this:

Screenshot 2015-04-17 13.30.16


Wow! So, is this a good company? Well, there are some issues I need to look at, especially since I’m in the US and this company is in the UK. First, I discussed in a post today over at Stacking Benjamins the importance of evaluating the macro conditions that exist around a stock….like the economy and how the sector’s performing as a group. Besides that, I also need to dig into the numbers and see how this stock would look in my portfolio.

Before I actually begin digging into this company, traded on the London Stock Exchange, I also need to evaluate something else: my experience with this stock is going to be different than that of a UK based investor. Why?

Because I’m investing dollars and not British pounds.

Trading dollars for this company makes my transaction a little more complicated. I could actually have a horrible return even though the stock performs well if the dollar falls in value against the British pound. Many investors who jump on international companies forget that this is an important part of success or failure over the short run when choosing international positions.

….so, let’s take a look.


The Dollar Is Strong

Let’s take a quick look at free site DollarstoPounds.com to measure how the dollar compares:

Screenshot 2015-04-17 13.53.40


As you can see, the dollar has been strengthening. According to this interesting piece on TheStreet.com, it appears that any Fed move should make the dollar even stronger. That’s good news for international investments, and especially in this case for an investment in the UK if I’m an American investor.


The Company – A Profile

According to their website, Playtech is the world’s largest provider of online gaming solutions. They work with many different gaming companies, from big names like Sky and Titanbet to much smaller firms.

Because we already looked at gaming companies from a macro level in our Stacking Benjamins piece, let’s dive into the numbers.


Fundamental Analysis

Looking at the numbers is called “Fundamental Analysis” by investors. That means we’re going to research how the company makes money and evaluate just how sound things are financially. Just like you know more about a family by looking at their budget, cash flow and debt, we’ll get a better feel for how this company performs by looking at this data. Most probably, we’ll create a list of questions we should ask ourselves before we invest. I’m always surprised by my digging….it feels a little like financial CSI. Ha!


How To Look For Fundamental Data

If you’re just going to take a cursory look at a company (the scope of today’s article), many people like using Yahoo! Finance. I don’t. Why not? Because what I’m interested in are trends. I want to see revenues improving. I also want earnings to be improving, and I want to compare debt levels against prior years. These numbers will tell me a quick story about the company. I may not get the full story, but just a set of current data at Yahoo! doesn’t help me at all.

Instead, I went to my brokerage site, which happens to be TDAmeritrade. I also have an account at Scottrade. Let’s compare.

First, it’s difficult to make sure that you’ve got the right company when you’re looking at foreign investments. At TDAmeritrade, they show two different stocks:

Screenshot 2015-04-17 14.04.59

Luckily, I know, these are actually two ways you can buy the same company. We’ll go into that another day…..but for now, I want to use the one that gives me the most data. Clicking the depositary receipt investment gives me no data. The other gives me what I’m looking for.

At Scottrade, when I ask for Playtech, it actually shows me three…..and I go with the Grey Market one (middle). It’s the same company.

The middle one is our winner!


At Scotttrade I also can look at prior year data…..I just prefer the graphs at TDAmeritrade that Scottrade omits.

While this gives me all the data...I love graphs. Yum.
While this gives me all the data…I love graphs. Yum.


So What Do We See? Good Stuff?

Revenues will show us if the company is making more money every year. We want a company that’s growing sales. Is that the case for Playtech?

You can see above, that revenues have grown year for the last four years. That’s good news.

In many cases your investigation will spur questions. In this case, it’s “if revenues are going up, are expenses staying in check?” We’ll need to find an answer to that before investing.


Earnings

One quick way to look at expenses is through the eyes of earnings. Revenues are “top line” numbers. It’s money coming in the front door. But if a company spends all that revenue and doesn’t make a profit, who cares? We don’t want more sales alone….we also want to see more money going to investors. We can monitor that through looking at earnings. If a company grows sales they might have acquired another company that had solid sales or they may have hired a ton more people. If earnings don’t rise also, we have a problem.

Let’s switch over to TDAmeritrade to look at earnings. Here it is:

Earnings last year were down. Hmmm....
Earnings this year are expected to be down. Hmmm….


As you can see, earnings are good so far, but next year they expect them to drop. That gives us MORE questions….why is the stock so hot if everyone expects the company to earn less in the future?


Debt

While I don’t see debt as a negative all the time, just like it can sink your personal financial situation, too much debt can sink a company. Let’s take a look:

Where the heck did that debt come from?


Where did this new “long term debt” line item come from in Q4 of last year? The stock is up AND there’s new debt AND analysts expect earnings to drop? There’s clearly something going on.

…and So On….

We’re not nearly done, but can you see how we’re forming questions about the stock as we read the numbers? Sharon Lechter (co-author of Rich Dad Poor Dad) told me on our Stacking Benjamins podcast that numbers tell a story that you want to learn how to read. In this case, I go to the news on Playtech and find this: Playtech Enters Foreign Exchange Market. Investors clearly like the synergy that this might create, even though over the short term they think the company will have lower earnings and had to take on debt for the transaction.


So Do I Buy?

In this case, I’m going to hold. The inconsistent earnings growth and new acquisition frighten me. There’s too much up in the air about how successful Playtech can be marketing Forex trading to it’s online gambling clients. I don’t think they’ll fail….I just don’t know…..and that’s enough of a reason for me to look elsewhere.


Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: Featured, Investing

3 Smart Things 20-Somethings Can Do With a Tax Refund

January 24, 2015 by Joe Saul-Sehy 3 Comments

Unless you left with an accounting degree, filing your first tax return after college can be a little deceiving. A couple government checks in the mail this summer might feel like a consolation prize for a dues-paying job, and you deserve to be king for a day, right?

Hold on a minute. We have a few ways you 20-somethings can make the best use of your tax refund.

Perhaps the Most Underrated: Start Saving

If you get your refund deposited directly in your bank account, it’ll just “show up” one day, like someone just dropped a gift card in your lap. Saving isn’t the most appealing option, but it will be the most rewarding when it’s time to rent a new apartment or put a deposit down on a car. Building your current account isn’t always enough incentive, so here are two ways to keep at it:

  • Open a savings account. Already have one? Open another. A hundred dollars buys you a reason to put disposable income aside exclusively for emergencies or other big (but necessary) expenses.
  • U.S. savings bonds are another convenient option, allowing you to redirect your tax return into an account that earns ample interest and is safe from inflation. According to TreasuryDirect, classified Series I bonds opened just four years ago this month, and this route requires a simple request via IRS form 8888.

Invest It in Your Retirement

Start building an investment portfolio now. If you feel you don’t have the know-how to purchase stock, the following two retirement investments are ripe alternatives for someone your age. Planning for retirement should always start as early as possible.Woman and piggy bank

  • Open an IRA, or individual retirement account. This is a personal account you contribute to each year, and the amount you contribute is tax-deductible. While you have more freedom to adjust and personalize investments like stocks, mutual funds and CDs, you can’t make withdrawals. With a Roth IRA, on the other hand, you pay taxes upfront and then you can make tax-free withdrawals.
  • Invest in a company-sponsored 401(k). Don’t miss out on the retirement plan your company offers. Many companies use a safe harbor or match plan. Safe harbor means that if your company contributes to your plan, the funds are yours even if you leave the company a couple months later. A matching plan means the company matches whatever you put into the plan. Some companies will even match up to 6 percent of your salary, according to DailyWorth.com. It’s basically free money.

Pay off Your School Loans

If you owe on student loans, put your refund on that debt. Paying off loans isn’t optional—you have to find a way to pay them anyway—and paying up front and on time is a bigger deal than you might think.

Funding your next bill with a tax return reinforces your credit history, yielding low interest rates on future big-ticket items like a new car, and keeps you paying loan interest at levels that can qualify you for education-based deductions as defined by the IRS later on. Whenever you can contribute a large chunk of money to paying down your student loan debt, do it—whether it comes from your tax refund, an unexpected financial windfall such as lottery winnings or inheritance or selling a structured settlement. The faster you pay them off the more you’ll save on interest, and that’s like money in the bank.

Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: Feature, Featured, Investing, Lists

7 Killer Personal Finance Lessons to Go From Couch Potato to IRONMAN

November 26, 2014 by Joe Saul-Sehy 1 Comment

Humans by nature have a competitive drive that compels them to succeed. Great athletes are committed to their training because they want to be the best, and anything less than a championship isn’t enough.

If you’re not an athlete, this urge to prove yourself often manifests itself in the car you drive or the house you live in. But to properly manage your money, you need the dedication of a pro athlete to train your mind and create winning habits.

But if you’re the financial equivalent of a couch potato, you can’t expect to become an IRONMAN overnight. You need to start from where you are and create a plan that works for you.

How to Get Startedpersonal finance ironman the free financial advisor

To reach your personal finance goals, you need to train your mind to stay within a specific budget and have the commitment to stick to your goals. Here are four steps you can take to prepare for the marathon of personal finance:

1.     Put your goals in writing. Many athletes have their team to hold them accountable, but since personal finance is usually a solo venture, writing down your goals can help. Maybe you just want to be debt-free by a certain date, or perhaps you’re trying to save a specific amount for retirement.

When setting goals, it’s important to be specific and realistic about how much of your income you’ll be able to save or put toward paying off your credit card each month.

If you’re thinking of buying a new home or a nice car, do some research to figure out exactly how much it’s going to cost. (This includes taxes, insurance, maintenance, etc.) Don’t leave anything out! Give yourself some cushion in your financial planning for times when unforeseen expenditures interfere with your plans.

2.     Assess where you are compared to where you want to be. World-class runners always know the race times they want to achieve, and they train with that goal in mind. Once you’ve listed your current expenses and goals, brainstorm possible ways to cut spending to reach your ideal financial situation. Where are you now compared to where you want to be?

3.     Consider possible ways to increase your income. Evaluate how a second job, a promotion at your current job, or furthering your education could help you reach your personal finance goals. Carefully evaluate whether the income generated from these options will be worth your time and investment.

4.     Put your plan into action. No matter what level you’re at, you’ve got to start somewhere. For Rocky, it was just a matter of getting out of bed, putting on his sweats and sneakers, and training before the sun rose. Put your routine into action, and stay committed — even if your plan falters from time to time.

3 Lessons for Winning in Finance

Once you put your plan into action, it’s important to maintain a winning mindset. It takes many athletes up to eight years of training to make an Olympic team, so it’s crucial to have the tools in place to maintain motivation.

 1.     Remember: Financial success is a marathon, not a sprint. Most athletes will tell you that a slice of cake once a month isn’t going to kill you. But if you indulge in a slice every other day, it starts to become detrimental. The same rule of moderation in the long haul applies to amassing wealth.

To remain financially healthy, you need to develop the foresight to see how unnecessary expenditures can derail your financial goals in the long term. It’s OK to treat yourself every once in a while, but those weekly shopping sprees and daily lattes add up. Reaching your personal finance goals is an exercise in patience and long-term dedication.

2.     Winners never quit, and quitters never win. You’ve heard this one before, right? Even the best experience failure, but how well you bounce back from setbacks and learn from them ultimately determines whether you reach your goals.

“I’ve missed more than 9,000 shots in my career,” said Michael Jordan. “I’ve lost almost 300 games. 26 times, I’ve been trusted to take the game-winning shot and missed. I’ve failed over and over again in my life. And that is why I succeed.”

Don’t use your failures as an excuse to put your dreams on hold. Just get back on track, and keep moving forward.

3.     There’s no “I” in team. Tim Rees asked nearly 200 elite golfers about their support systems. He found that during stressful matches, golfers with strong support systems performed better than those without. Similarly, your spouse and loved ones can be huge sources of support and motivation in your financial journey. Make sure your family understands your goals and is committed to helping you reach them.

Just as athletes don’t expect to win every single game, you shouldn’t expect to become a millionaire overnight. The road to financial success is a rocky one, and life will throw you unexpected curveballs. The key is a consistent, long-term commitment to saving and spending wisely. If you can do that, you’ll retire with plenty of wins under your belt.

Daniel Wesley is the founder of DebtConsolidation.com, a website that specializes in debt-relief services for businesses and individuals.

Photo: Patrick Theander

Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: Featured, Investing, Lists

5 Apps To Simplify Your Finances

October 2, 2014 by Joe Saul-Sehy 1 Comment

Online chartOnly 30 percent of Americans prepare a long-term financial plan including investment goals, states a poll by Gallup. That means 70 percent of people are figuring out their financial plans as they go and hoping the numbers add up somewhere along the way. If you want to be part of the 30 percent, there are ways to simplify the financial planning process from paying bills to knowing where to invest. Take the tedium out of creating a budget and savings plan by downloading a few apps to your smartphone to put you on the right track.

Mint

Simplify your banking and savings accounts, investments, credit cards and loans by having them all in one place. With Mint you can set up your accounts and get an easy-to-read, simplified graph to show how much you’re spending and where. Mint also lets you design a budget, and it will alert you when you’ve gone over or when you’re getting close. It is ideal for those working towards a financial goal like paying off a credit card or a trip abroad because it allows you to set a plan and watch your progress. Seeing how close you’re getting also can help motivate you to push harder towards your finish line.

LikeFolio

Don’t let the overwhelming amount of investment advice stop you from taking action. LikeFolio figures out which companies you and your friends like and talk about most so you can invest in them. The idea is that you should invest in companies you already know and love. LikeFolio pours through your social media status updates for any mentions of brands and products, and then helps give you more information for your potential investments.

Expensify

Expensify is for anyone who hates expense reports and wants to streamline the process. It’s free to upload or email an unlimited amount of receipts, and it allows you to quickly add cash expenses and import your credit and debit card transactions. You also can add mileage, time and other billable expenses as needed. Use their SmartScan process to help separate receipts and type out the following information on your behalf. It shows the merchant name, transaction date and amount. The first month is free, and $5 per month after that.

Check

Pay all your bills in one place with the free app called Check. Get instant alerts for upcoming bills, finance charges and other financial activity. It takes a little time to set-up all of your accounts, but once it’s set, Check does all the work for you. When bills are due, simply log in on your smartphone or other device and pay quickly and safely. The app promises bank-level security and real time alerts so you can monitor large expenses and deposits.

Wally

This highly intuitive app makes financial management easy with a 360 degree view of your money. Wally consistently gets rave reviews for its simple interface, which is both pleasant to look at and use. Get a glimpse of all your activity from spending to savings while Wally helps you figure out where your money is going. Like Expensify, Wally also has an InstaScan feature to scan a receipt for an expense report or your own records.

Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: Featured, Investing, Lists, money management

Answers to the Most Common Questions About Structured Settlements

March 8, 2014 by Joe Saul-Sehy 3 Comments

Why so much confusion about structured settlement?

Structured settlements are becoming highly popular these days, partly due to the benefits they provide and partly due to the flexibility they offer to the holder. According to Einstein Structured Settlement, Structured settlements are regarded much well as compared to other types of investment in the sense that they are oriented towards the needs of the owner. Despite all the advantages many people have doubts about this financial instrument when it comes to make an investment. They have many questions regarding the investment and handling of structured settlement that they want to answer before making any decision.

The questions are countless but a few, that are continuously haunting the minds of those who want to invest in structured settlement, are answered below:

What is the effect of inflation on structured settlement?

The biggest worry for the investors these days is inflation, which is chomping off their plans to save for their future. The investors need to mark up their investment for their future with the expected rise in inflation. Without a proper calculation their investment will not pay them as per their expectations. Annuity is no exception for this truth. Annuity sure pays a comfortable annual income but it does not promise to do so after a time of 10 years, as the purchasing power is expected to change with the rise in inflation. The value of the annual payment of structured settlement can drastically reduce due to the effect of inflation. In this case most of the people decide to sell this financial instrument to a structured settlement company in exchange of cash that they can invest in some other instruments to fight off inflation.

Is the income from structured settlement taxable?

Legally a person does not have to pay tax on the any amount of money received as the compensation of physical damage caused to him/her. This money is not treated as the source of actual income and thus is exempt from tax. In legal terms this money is for the compensation for recovery from that particular damage. In fact, the tax free nature of the structured settlement amounts is among the most highly regarded benefits of this financial scheme. But this income from the structured settlement is tax free only as long as the payee is alive. In case of the death of the payee, the income becomes taxable as per the law of Inheritance. This is because the source of income is now transferred to the descendent of the actual payee who did not suffer any damage. Thus this money coming as a source of income becomes taxable.

In some cases this financial instrument is tax deferred, which means the taxes on the income through structured settlement are delayed for a specific period of time only. After that period of time the income becomes taxable. If the payee decides to make a withdrawal, in this case the amount withdrawn is taxable.

What if the holder wants to sell only a portion of structured settlement?

It can be seen very often that the holders of the structured settlement sell only a portion of the structured settlement to fulfill their immediate financial needs. It is also possible for the holder of the structured settlement to sell this instrument in portions on different occasions throughout their lifetime as per their need and convenience. There are many individuals and companies that are ready to purchase these portions of structured settlement in exchange of a good amount of cash.  This option gives the holder a flexibility of handling it and gets the holders higher amount of liquidity on their holdings.

What are the things to be considered before selling structured settlement?

While making the decision to sell the structured settlement, it is necessary for the holder to consider some important factors which are sure to affect their deal.

  • The very first thing that the seller of the structured settlement needs to consider is the legal restrictions involved in the deal.
  • The holder also needs to look for the contractual restrictions, which sometimes do not allow the holder to sell the structured settlement.
  • When a structured settlement is sold for cash, the amount of money received becomes taxable and the plaintiff is exposed to an immediate tax liability.
  • The seller of the structured settlement should be aware of the low offers that are often made by the buyers of the instruments.

Should one consult a lawyer in the deal related to structured settlement?

It is very wise to take help from a lawyer before making any deal related to structured settlement. He will ensure that the rights of the holder are protected against any type of fraud or he/she is not held responsible for anything outside his/her control. The lawyer will help the plaintiff with the purchase or selling agreement.


Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: Featured, Investing

Forgetting to Rebalance Makes You Wobbly

November 21, 2013 by The Other Guy 4 Comments

Quick question:

What does a good investor have in common with a good tightrope walker?

They both remember to rebalance!

HA!

I’m here all week folks.  Don’t forget to tip your wait staff!

Forgetting to rebalance is just as dreadful for an investor as it is for a circus performer.  Let’s talk about why.

First, let’s dispense with a definition.   My definition of rebalancing is this:

Rebalancing is the act of periodically putting one’s portfolio back to one’s previously well thought-out asset allocation based on one’s unique risk tolerance, time frame, goals, and objectives. 

Fun, huh? Disecting each part of that definition results in the following:

1 )   …act of… – this means that rebalancing is an action.  You.  Must.  Do.  It.  (or at least cause it to be done through automatic programming).  Rebalancing is something that must be done, by you.

2)   …periodically…this doesn’t mean whenever you feel like it or whenever you remember.  It means you need to select that time and mark it in your calendar.  We prefer annually, but semi-annually is OK, too.  Quarterly…eh…you’re probably wasting time.  Any more frequently than quarterly and you’re doing market timing by a different name.

3)   …putting…portfolio back… This next part is relatively easy.  You’re putting it back – the way it was.  No  thought required here.  Just like I tell my kids.  Put your toys back the way they were.  In the places they were before you played with them.

4)   …previously well thought-out… During your rebalancing activities, you do not need to redesign your model.  You’ve already done that.  Previously.  And it was well though-out.

5)   …asset allocation based on unique… We could spend hours here, but here’s where you should’ve spent some serious thinking time around your risk and goals.  Rebalancing is only rebalancing if it’s back to an asset allocation.

What can happen if one doesn’t rebalance?

That’s easy – anecdotally, consider the late 90s or late 2007.  A big run up in one area of the market (say the Large Cap stocks of the 90s) could mean they’re overvalued.  What happens when something’s overvalued?  It eventually becomes undervalued!  Rebalancing can help to sell winners at a gain and buy more shares of positions that are undervalued.

One of the “tricks” professionals have up their sleeves is rebalancing.  It is a automatic process designed to take the thinking and emotion out of investing and allow investors to capture profits and reposition those dollars where they can buy the most shares of undervalued investments.  Use rebalancing to your favor!

PS: The US stock market is up HUGE this year.  Is it time you rebalanced???

Photo: quinn.anya

Filed Under: Featured, Investing

Following the Herd: Great in Nature, Not So in Finance

October 29, 2013 by The Other Guy Leave a Comment

Have you ever been to a fishery?  I’m talking about the giant fish ladders where all the salmon are swimming/jumping and splashing?  It seems like there’s a never ending stream (pardon the pun) of fish – and they’re all heading in the same direction.

Following the herd works well if you’re a fish – or nearly any animal in nature – because there are strength in numbers.  But does it work well in investing?

Not so fast, my friends!

When any asset class soars, investors can’t help themselves and jump right in. Pick a category: large cap stocks in the early 90s, technology stocks in the late 90s, real estate in the mid-2000s, or more recently gold, to name the latest few…the higher prices climb, the more people want in.

That’s completely backward.

Legendary investor Warren Buffett has a beautiful quote on the subject: “Be greedy when others are fearful – and fearful when others are greedy.”

What he means is simply this: When the market is peaking and prices are increasing day in and day out, it’s best to stay on the sidelines.  Don’t follow the herd.

In fact, the primary driver to investors’ investment performance has nothing to do with selection of great investments, but rather the behavior of investors.  According to Morningstar, investors in U.S. stocks mutual funds earned 2.3 percentage points per year less than the funds themselves.  Why is that?  That’s simple: Investors tend to get all wishy-washy as asset classes either “soar” or “plunge” and then react based on emotion and/or what the “herd” is doing.

How do you avoid “Following the herd?”

Professionals call it an “investment policy statement,” but it’s more simple than the name sounds. Make yourself some ironclad rules that you promise never to break no matter the circumstances.

For example, you could set up a systematic investment plan that continues no matter what happens day-to-day in the market.  You could promise yourself to keep only 30% of your assets in large company stock funds and never more than 10% of your portfolio in any single investment. These rules will help you manage your money wisely with the long view in mind.

More importantly, they’ll help prevent you from being part of the herd!

Filed Under: Investing

  • « Previous Page
  • 1
  • …
  • 26
  • 27
  • 28
  • 29
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • 10 Tactics for Building an Emergency Fund from Scratch by Vanessa Bermudez
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald

Copyright © 2026 · News Pro Theme on Genesis Framework