• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for money management

The ‘Emergency Fund Fatigue’ Trend: Why More Households Are Spending Savings Faster Than They Can Rebuild It

May 30, 2026 by Brandon Marcus Leave a Comment

The ‘Emergency Fund Fatigue’ Trend: Why More Households Are Spending Savings Faster Than They Can Rebuild It
Why are so many families tired of making and keeping emergency funds? The reasons may surprise you – Shutterstock

Emergency fund habits are shifting across households as financial pressure keeps stacking faster than paychecks can catch up. Rising prices, surprise expenses, and income instability keep pushing savings accounts into constant recovery mode instead of growth mode. Many families now watch their emergency funds refill briefly, only to drain again within weeks or months. This cycle creates a growing pattern of financial exhaustion that reshapes how people plan for stability. The idea of “safe savings” starts to feel temporary instead of dependable.

Financial behavior trends show a noticeable shift away from long-term buffer building and toward short-term survival spending. Emergency funds still exist, but they no longer stay untouched for long stretches like they once did. Everyday costs compete directly with savings goals, and urgent expenses win more often than planned contributions. This new reality pushes households into a loop where rebuilding savings feels harder than ever. That loop defines what many now call emergency fund fatigue.

Rising Costs Turn Savings Into a Temporary Stopover

Inflation continues to push essential costs higher, and households absorb those increases through their emergency funds when income falls short. Grocery bills, rent adjustments, utilities, and transportation costs all stretch monthly budgets beyond their limits. When budgets break, savings accounts step in as the first line of defense instead of a last resort. That constant pressure turns emergency funds into temporary stopovers rather than long-term protection tools.

Unexpected expenses also arrive more frequently, especially with aging vehicles, home repairs, and medical costs that insurance does not fully cover. Each withdrawal weakens the buffer and forces households to restart the rebuilding process again. Many families try to rebuild quickly, but rising expenses consume any extra income before it reaches savings. The cycle continues without a clear break, leaving little room for financial recovery momentum.

Income Pressure and Life Shocks Speed Up Withdrawals

Stagnant wages collide with rising costs, and that gap forces households to rely on savings more often than planned. Paychecks no longer stretch as far, so even small emergencies create immediate strain. Job instability and reduced work hours amplify the pressure, especially in industries sensitive to economic shifts. Each disruption pushes families to pull from emergency funds just to stay current on bills.

Life shocks also arrive without warning, including medical visits, urgent travel, or sudden home maintenance issues. These events rarely wait for convenient timing, and they often cluster together within short periods. One withdrawal often leads to another as households try to stabilize competing financial demands. This pattern speeds up depletion and slows down recovery, creating a cycle that feels hard to escape.

Emotional Spending Cycles Drain Recovery Momentum

Financial stress affects decision-making in ways that reduce consistency in rebuilding savings. After a major withdrawal, households often experience urgency relief followed by delayed rebuilding efforts. That delay creates a gap where everyday expenses take priority over replenishing funds. Over time, that gap turns into a pattern where saving feels optional instead of essential.

Behavioral psychology also plays a strong role in emergency fund fatigue. People often treat replenished savings as “available again” when new expenses appear. That mindset leads to repeated withdrawals that prevent long-term accumulation. Emotional fatigue builds when households feel stuck in a constant reset cycle, making disciplined saving harder to maintain.
The ‘Emergency Fund Fatigue’ Trend: Why More Households Are Spending Savings Faster Than They Can Rebuild It
Emergency funds are important, but many families are burnt out about the idea of building and maintaining one – Shutterstock

Practical Strategies That Break the Drain-and-Rebuild Cycle

Households gain more control when they automate small, consistent contributions into emergency savings instead of relying on leftover money. Even modest weekly transfers build momentum over time and reduce the temptation to skip saving altogether. Budget structures that prioritize savings before discretionary spending create stronger protection against sudden expenses. This approach helps stabilize progress even during high-cost months.

Side buffers also strengthen resilience by separating short-term repair funds from full emergency reserves. A smaller “mini buffer” handles predictable surprises like minor car repairs or school expenses. That separation protects the main emergency fund from frequent depletion. Over time, households regain a sense of progress as savings grow without constant interruption.

What Is Causing Emergency Fund Fatigue Today

Emergency fund fatigue reflects a broader shift in financial reality where stability requires constant adjustment instead of passive security. Households now face repeated cycles of saving, spending, and rebuilding that never fully pause. Inflation, income pressure, and unpredictable life costs all interact to keep savings in motion rather than stillness. That movement defines the modern challenge of financial resilience.

What strategies help rebuild savings faster in today’s high-cost environment, and how do different households manage emergency fund pressure in daily life?

You May Also Like…

Most People Fail the Emergency Fund Test And It’s Not About the Amount

Federal Spending Crackdown: Why Several States Are Now at Risk of Losing Family Assistance Funds

Arizona Homeowners Are Spending More on Water Than Expected This Year—and It’s Affecting Household Budgets

5 Hidden Medicare Costs That Can Reduce Your Monthly Budget

Build an Ironclad Emergency Fund That Can Withstand Any Crisis

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Personal Finance Tagged With: budgeting, emergency fund, household finances, Inflation, money management, Personal Finance, Planning, savings

How AI Is Changing Personal Finance Faster Than Most Consumers Realize

May 29, 2026 by Brandon Marcus Leave a Comment

How AI Is Changing Personal Finance Faster Than Most Consumers Realize
AI is everywhere, including in many of the personal finance tools that we use daily – Shutterstock

Artificial intelligence now sits inside everyday money tools and reshapes financial decisions at a speed that surprises most users. Budgeting apps, investment platforms, and lending systems all rely on machine learning models that process behavior in real time. These systems no longer wait for monthly reports or human input to adjust financial guidance. Instead, they react instantly to spending patterns, income changes, and even subtle habits like subscription activity. That speed creates a financial environment where decisions form before users even notice the shift.

This change does not stay hidden in the background anymore, because AI actively shapes what people see on their screens. Personalized insights, automated savings rules, and predictive alerts now guide millions of users each day. Financial platforms compete by offering smarter recommendations that feel tailored and intuitive. That competition pushes AI deeper into personal finance tools at a rapid pace.

AI Is Quietly Rewriting Budgeting Apps

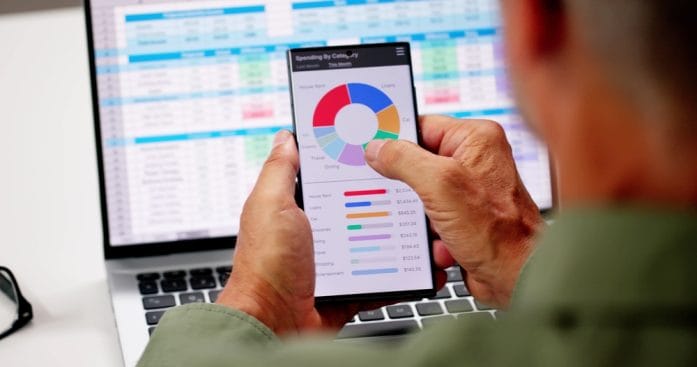
Budgeting apps now act less like simple trackers and more like active financial assistants that learn from user behavior. AI systems categorize transactions instantly and adjust spending insights based on evolving habits. These platforms highlight risks such as rising food costs or sudden subscription spikes before users manually review statements. That real-time feedback loop encourages faster financial decisions and reduces reliance on end-of-month reviews. Many apps now predict future cash flow based on historical spending patterns and income timing.

These tools also push users toward better habits through subtle behavioral nudges that feel natural rather than forced. AI models detect when users overspend in certain categories and automatically suggest corrective actions. Some platforms even adjust savings goals dynamically when income fluctuates or expenses increase. That flexibility creates a more responsive financial system that adapts to real life rather than fixed budgets. Consumers often notice improved financial stability without realizing how many automated decisions drive those results.

Smarter Investing Tools That React in Real Time

Investment platforms now use AI to analyze market movements faster than any human trader can react. Algorithms scan global news, earnings reports, and trading patterns to identify opportunities within seconds. These systems then adjust portfolio recommendations based on risk tolerance and market volatility. That constant recalibration creates a dynamic investing environment that evolves throughout the day. Many retail investors now rely on AI-driven insights without needing deep financial expertise.

Robo-advisors also use machine learning to rebalance portfolios automatically and reduce emotional decision-making. These platforms remove hesitation during market dips by following pre-set risk models powered by AI analysis. Some systems even simulate long-term financial outcomes to guide investment choices with more precision. That predictive capability helps users avoid panic-driven decisions that often hurt returns. The combination of speed and automation transforms investing into a more structured and data-driven experience.

How AI Is Changing Personal Finance Faster Than Most Consumers Realize
From budgeting to investing, AI is changing the way smartphone apps work – Shutterstock

AI Credit Scores and Lending Decisions Move Faster Than Humans

Credit scoring no longer depends only on traditional reports because AI expands the range of data points lenders analyze. Machine learning models evaluate spending behavior, payment timing, and financial consistency in real time. That expanded analysis allows lenders to make faster approval decisions with more personalized risk assessments. Borrowers often receive credit offers within seconds instead of waiting days for manual review. This speed changes how people access loans, credit cards, and financing options.

Lending platforms also use AI to adjust interest rates based on continuous risk evaluation. That system rewards consistent financial behavior while tightening terms for higher-risk activity. Some fintech companies now update credit insights daily instead of monthly, which increases transparency for consumers. That frequent updating helps users track how financial decisions influence their credit health. The result creates a more dynamic credit system that reacts to behavior almost immediately.

What This Shift Means for Everyday Money Decisions

AI-driven finance tools now shape nearly every aspect of personal money management, from budgeting to borrowing. These systems reduce friction by automating decisions that once required manual effort or financial expertise. Users gain convenience, but they also rely more heavily on algorithms that influence outcomes behind the scenes. That reliance makes transparency and awareness more important than ever for financial confidence. People who track how these tools operate often make more informed decisions about their money habits.

What do you think about AI taking a bigger role in personal finance decisions? It’s an important topic, so now is the time to talk about it in our comments.

You May Also Like…

Cost Effective Strategies in Nursing Education and Trainings

Why Banks Are Watching Large Transfers More Closely Than Ever

Could Everyday Technology Be Quietly Stealing Wealth

8 Personal Finance Beliefs That No Longer Apply

10 Personal Finance Lessons People Learn the Hard Way

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Technology Tagged With: AI, budgeting apps, credit scores, fintech, investing, money management, Personal Finance

The Hidden Cost of Convenience: Why Faster Delivery, Auto-Pay, and One-Click Checkout Are Wrecking Budgets

May 28, 2026 by Brandon Marcus Leave a Comment

The Hidden Cost of Convenience: Why Faster Delivery, Auto-Pay, and One-Click Checkout Are Wrecking Budgets
In the modern age, some of the most convenient ways to spend can be the most dangerous for your budget – Shutterstock

Convenience has turned into a silent spending accelerator that reshapes how money leaves wallets every day. Fast checkout buttons, subscription renewals, and lightning-speed delivery options remove friction from buying decisions. That removal of friction also removes the pause that normally protects budgets from impulse decisions. Small purchases stack up faster when decisions take seconds instead of minutes. Financial stress often grows quietly because these systems feel helpful while quietly encouraging overspending.

Modern digital shopping platforms design experiences that prioritize speed over reflection, and that shift changes consumer behavior. People often notice the impact only after monthly statements reveal unexpected totals. The speed of digital spending creates a false sense of control because each purchase feels insignificant. Over time, those micro-decisions form patterns that consistently push spending above intended limits.

The Illusion of Effortless Spending That Tricks Everyday Decisions

Digital platforms shape behavior by making every purchase feel instant and effortless, which removes natural spending hesitation. That hesitation once gave people time to reconsider nonessential purchases and compare alternatives. Now, checkout buttons sit one tap away, reducing the mental steps required to complete transactions. This frictionless environment creates a psychological blind spot where spending feels smaller than it actually is.

Retailers design interfaces that highlight speed and simplicity to keep users engaged in buying loops. Each streamlined interaction reduces the emotional weight tied to spending money. When decisions happen quickly, people lose track of cumulative costs across multiple purchases. Over time, this environment encourages habitual spending that feels harmless in the moment but grows into a serious budget strain.

One-Click Checkout Turns Split-Second Choices Into Long-Term Costs

One-click checkout systems eliminate barriers that once forced shoppers to pause and evaluate purchases. That missing pause leads directly to more impulse buying, especially during late-night browsing or emotional moments. Shoppers often complete purchases before fully processing the need or value behind the item. This structure rewards speed and punishes reflection, even when budgets demand careful planning.

Studies on consumer behavior consistently show that reduced friction increases spending frequency and total cart value. The brain responds strongly to immediate rewards, especially when no extra steps interrupt the buying process. That reward loop strengthens every time a purchase completes without resistance. Over weeks and months, those rapid transactions accumulate into noticeable financial leakage.

Auto-Pay Subscriptions Quietly Drain Budgets in the Background

Auto-pay systems simplify bill management, but they also remove active decision-making from recurring expenses. Many subscriptions continue long after users stop engaging with the service. Streaming platforms, fitness apps, and software tools often rely on this inertia to maintain revenue. The convenience of “set it and forget it” turns into a budget leak that runs silently every month.

Financial strain grows when multiple subscriptions stack together without regular review. People often underestimate total recurring costs because each charge appears small in isolation. Once combined, those charges can rival essential monthly expenses like groceries or utilities. Without active oversight, auto-pay systems create a steady drain that feels invisible until bank balances tighten.

Fast Delivery Culture Pushes Impulse Buying Into Overdrive

Same-day and next-day delivery options reshape expectations around urgency and desire. Shoppers no longer wait for needs to become pressing because products arrive almost instantly. That speed encourages emotional buying, especially when boredom or stress drives online browsing. The excitement of rapid arrival often outweighs rational budgeting decisions.

Retailers use delivery speed as a psychological trigger that increases conversion rates. When shoppers know items arrive quickly, they feel less pressure to justify the purchase fully. This mindset leads to frequent small orders that bypass traditional shopping lists. Over time, those repeated fast deliveries create higher shipping fees, more frequent purchases, and weaker financial discipline.

The Hidden Cost of Convenience: Why Faster Delivery, Auto-Pay, and One-Click Checkout Are Wrecking Budgets
Fast delivery times are a blessing, but they can be very expensive too – Shutterstock

Hidden Fees and Micro-Leaks That Quietly Break Monthly Budgets

Small fees often hide inside transactions, making them easy to overlook during budgeting. Service charges, delivery fees, platform surcharges, and currency conversions add frictionless costs that accumulate quickly. Each individual fee appears minor, but repeated transactions multiply their impact. Many users only notice these charges after reviewing monthly statements in detail.

These micro-leaks create financial erosion that rarely triggers immediate concern. Platforms often bundle fees into checkout flows, which reduces visibility and awareness. That design choice keeps users focused on final purchase completion instead of total cost breakdowns. Over time, these hidden additions can consume a significant portion of discretionary income without clear warning signs.

Breaking the Convenience Cycle Without Losing Everyday Ease

Budget control improves when spending systems reintroduce intentional friction into financial decisions. Turning off one-click checkout features creates a pause that forces reconsideration before purchases. Removing saved payment methods from shopping apps also reduces impulsive spending triggers. These small adjustments rebuild awareness without eliminating convenience entirely.

Regular subscription audits help identify services that no longer provide value. Setting calendar reminders for monthly or quarterly reviews strengthens financial awareness and prevents long-term waste. Slowing down delivery expectations also reduces urgency-driven purchases and encourages planned shopping habits. These changes restore balance between convenience and control, which protects long-term financial stability.

Why Convenience Becomes Expensive Without Intentional Guardrails

Convenience tools reshape financial behavior by removing barriers that once protected spending discipline. Each feature—one-click checkout, auto-pay, and fast delivery—works alone, but together they create a powerful spending ecosystem. That ecosystem rewards speed, not reflection, which pushes budgets toward silent overload. Awareness of these systems helps reduce their influence and restore intentional decision-making.

Smart spending habits emerge when convenience gets balanced with conscious pauses and regular financial reviews. People regain control when they treat friction as a budgeting tool instead of an inconvenience. Small adjustments build stronger financial stability over time without requiring dramatic lifestyle changes. Long-term success depends on recognizing how convenience quietly reshapes money habits.

What spending habit feels hardest to control in today’s convenience-driven world? We definitely want your experiences and advice shared below in our comments.

You May Also Like…

The New Banking Trend That Could Make Paper Checks Harder to Use

Arizona Homeowners Are Spending More on Water Than Expected This Year—and It’s Affecting Household Budgets

7 Retirement Budget Categories Rising Faster Than Inflation in 2026

The “Loud Budgeting” Trend and Transparent Money Conversations

Autopay Secrets: 11 Ways To Successfully Use Autopay To Simplify Your Bills

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Personal Finance Tagged With: budgeting, consumer psychology, money management, Online shopping, Personal Finance, Spending Habits, subscription traps

Why More Americans Are Checking Their Bank Accounts Daily in 2026—and It’s Not Just Because of Spending

May 28, 2026 by Brandon Marcus Leave a Comment

Why More Americans Are Checking Their Bank Accounts Daily in 2026—and It’s Not Just Because of Spending
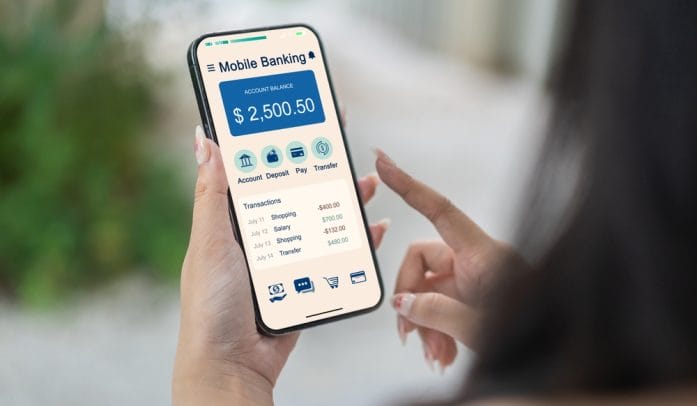
More and more Americans are checking their banks accounts multiple times a day, for various reasons – Shutterstock

Bank apps now sit at the center of daily financial life, and millions of Americans open them every single day without even thinking twice. The habit has shifted from occasional balance checks to constant monitoring, and the reasons stretch far beyond shopping or bill payments. In 2026, financial anxiety, smarter technology, and faster-moving money systems all push people toward frequent account check-ins.

The behavior reflects a new era where money feels more digital, immediate, and unpredictable than ever before. This trend reveals a deeper story about trust, control, and the modern economy.

Digital Banking Alerts Changed the Game Completely

Mobile banking apps now push notifications for every swipe, deposit, and subscription charge, which keeps financial activity constantly visible. These alerts create a real-time feedback loop that encourages people to open their accounts repeatedly throughout the day. Banks also design apps to highlight spending patterns, upcoming bills, and account changes in bold, attention-grabbing formats. That constant stream of updates makes financial awareness feel like part of everyday scrolling habits. Over time, checking balances becomes less of a decision and more of a reflex triggered by notifications.

Technology companies and financial institutions also compete to keep users engaged, and that competition shapes user behavior in subtle ways. Features like instant transaction updates, spending summaries, and predictive balance warnings pull attention back into the app again and again. Many people now feel a strong need to confirm that transactions went through correctly, especially after using tap-to-pay systems. That reassurance loop strengthens the habit of checking accounts multiple times per day. What once required a bank visit now happens in seconds, and that speed fuels even more frequent monitoring.

Rising Fraud Fears Keep Financial Eyes Wide Open

Fraud concerns play a huge role in daily banking checks, especially as digital scams grow more sophisticated each year. Cybercriminals now use cloned websites, fake subscription charges, and automated phishing attempts that target everyday users. People respond by checking accounts more often to catch suspicious activity early before damage spreads. That behavior reflects a shift in mindset where financial vigilance feels necessary rather than optional. Trust in digital systems exists, but constant verification now shares the spotlight.

Banks report increasing cases of unauthorized transactions, which pushes consumers to stay alert throughout the day. Even small unfamiliar charges trigger immediate account reviews, especially when tied to subscription services or trial offers. Many users now treat their banking apps like security dashboards instead of simple balance tools. That change reflects a broader cultural shift toward personal responsibility for financial safety. The more digital money becomes, the more people rely on frequent checks to feel protected.

Budgeting Culture Turns Into a Daily Financial Routine

Budgeting apps and banking tools now encourage users to track every expense in real time, which reinforces daily account checking habits. People set spending limits, categorize purchases, and monitor cash flow with a level of detail that previous generations never experienced. This constant visibility turns financial management into a daily routine instead of a monthly task. Many users adjust their behavior mid-day after seeing spending updates, which further increases app engagement. That loop creates a strong connection between awareness and action.

Social media also plays a role by popularizing budgeting trends like cash stuffing, no-spend challenges, and weekly money resets. These trends encourage people to stay constantly aware of their balances and spending categories. Financial discipline now spreads through short videos and posts that make budgeting feel interactive and social. That visibility drives more frequent account checks as people compare habits and track progress. The result turns personal finance into a daily performance rather than a private monthly review.

Why More Americans Are Checking Their Bank Accounts Daily in 2026—and It’s Not Just Because of Spending
It’s important to keep tabs on your bank account, but how many times is too much? – Shutterstock

Economic Pressure Makes Every Dollar Feel More Important

Inflation shifts, interest rate changes, and unpredictable costs make many households more sensitive to small financial changes. People now monitor accounts closely to catch rising expenses before they spiral out of control. Grocery bills, utility costs, and subscription services all fluctuate more frequently, which increases the need for constant oversight. That pressure creates a mindset where every dollar matters in real time. Financial awareness becomes a survival tool rather than just a planning habit.

Wage growth does not always keep pace with rising expenses, which adds another layer of urgency to daily account monitoring. Many households track deposits and withdrawals carefully to avoid overdrafts or missed payments. Unexpected costs, such as medical bills or car repairs, push people to check balances multiple times per day during stressful periods. That behavior reflects a desire to stay ahead of financial surprises instead of reacting after the fact. Economic uncertainty strengthens the habit of staying connected to banking apps throughout the day.

Real-Time Money Culture Redefines Financial Control

Instant payments, peer-to-peer transfers, and digital wallets now move money faster than traditional banking ever allowed. That speed creates a culture where financial activity feels continuous rather than periodic. People no longer wait for statements because every transaction appears instantly on their phones. That immediacy encourages repeated checking as users verify every movement in real time. Financial life now operates on a live feed rather than a delayed report.

This real-time system also changes how people think about control and stability. Frequent account checks create a sense of control, even when external conditions remain uncertain. Many users associate visibility with security, which reinforces the habit further. Financial institutions design interfaces that highlight clarity and transparency to support that expectation. As a result, checking accounts daily becomes less about curiosity and more about maintaining a sense of stability in a fast-moving financial world.

The New Normal of Financial Awareness in 2026

Daily banking checks now reflect a combination of technology, psychology, and economic pressure working together. People use banking apps not just for transactions but for reassurance, planning, and protection. The habit continues to grow as digital finance becomes more integrated into everyday life. Financial awareness now operates at a constant pace that matches the speed of modern money movement. This shift shows how deeply financial behavior has adapted to a connected, always-on economy.

What do you think—does checking bank accounts daily feel like smart control or digital overload in today’s world?

You May Also Like…

The New Banking Trend That Could Make Paper Checks Harder to Use

IRS Won’t Automatically Reissue Paper Checks for Rejected Direct Deposits—You Must Update Bank Info

10 Warning Signs Your Banking App Was Compromised

Medicare’s Fast-Track Review Standard: Why Some Requests Must Be Approved or Denied Within 72 Hours

5 Digital Banking Changes That May Be Adding New Fees Without Notice

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Banking Tagged With: banking habits, budgeting, consumer trends, digital banking, Financial Security, money management, Personal Finance, savings advice

The New Banking Trend That Could Make Paper Checks Harder to Use

May 25, 2026 by Brandon Marcus Leave a Comment

The New Banking Trend That Could Make Paper Checks Harder to Use
Paper checks are still around, but they are becoming harder to use due to banking trends – Shutterstock

Paper checks are quietly losing their grip on everyday financial life as banks roll out faster, more digital-friendly systems. A major shift in banking technology now pushes money through real-time networks that process payments in seconds instead of days.

This change does not just speed things up; it also reshapes how banks view older payment methods like paper checks. Many financial institutions now prioritize instant verification and digital transfers over manual processing. As this momentum builds, paper checks start to feel more like a backup option than a standard tool.

Why Banks Now Favor Faster Digital Payment Networks

Banks now push real-time payment systems because customers demand instant access to funds and clearer transaction tracking. Systems like real-time settlement networks reduce waiting periods and eliminate uncertainty around when money arrives. Financial institutions also cut operational costs when they move transactions away from paper-based processing. These systems help banks reduce errors while improving fraud monitoring through automated tools.

Paper checks struggle to compete in this environment because they depend on physical handling and delayed verification steps. Digital payments allow banks to confirm identity, funds, and authorization within seconds instead of days. This speed gives banks stronger control over transaction accuracy and reduces disputes between senders and receivers. As a result, banks increasingly guide customers toward electronic options during account setup and service updates.

Real-Time Payments Change Expectations for Money Movement

Real-time payment systems reshape how people expect money to move in daily life. Workers now receive wages faster through direct deposit systems that update instantly instead of waiting for traditional clearing cycles. Businesses also prefer instant settlement because it improves cash flow and reduces uncertainty in operations. These expectations now influence how banks design their services and customer interfaces.

Paper checks feel slower in comparison because they cannot match the speed or transparency of digital transfers. A mailed check may take several days to arrive, and additional days often pass before funds clear. This delay creates frustration for recipients who need immediate access to funds. As expectations shift toward instant transactions, checks lose their practical appeal in many financial situations.

How Banks Tighten Rules Around Check Processing

Banks now tighten check processing rules to reduce fraud and improve compliance with financial regulations. Many institutions impose stricter verification steps for large checks or unfamiliar account activity. These safeguards help protect customers, but they also increase delays and administrative friction for check users. Financial institutions now invest more in automated fraud detection systems that prioritize digital transaction data.

Check deposits often face longer holds because banks must verify legitimacy through manual review processes. Digital payments bypass many of these steps because systems validate data in real time. This difference creates a clear preference for electronic methods within banking operations. As rules continue to evolve, checks face increasing limitations in speed, acceptance, and convenience.

Everyday Bill Payments Shift Toward Digital First Systems

Bill payment systems now lean heavily toward digital-first options that prioritize speed and automation. Utility companies, landlords, and service providers encourage direct debit or online payment portals over mailed checks. These systems reduce processing delays and improve payment tracking for both sides of a transaction. Customers benefit from fewer late payments and clearer recordkeeping.

Paper checks introduce timing risks that digital systems eliminate through scheduled and recurring payments. A lost or delayed check can lead to penalties, while automated systems execute payments on time without manual effort. Many service providers now phase out check acceptance altogether to streamline operations. This shift pushes everyday consumers to adopt digital tools as the default method for routine payments.

The Growing Risks of Relying on Paper Checks Today

Paper checks carry higher fraud risks compared to modern digital payment methods. Criminals can alter check details or intercept mail, which exposes sensitive banking information. Banks now report fewer check transactions overall, but they still see a higher fraud rate per check compared to electronic payments. These risks push financial institutions to discourage check usage in everyday transactions.

Delays also create financial stress when checks take longer to clear or go missing in transit. A bounced or delayed check can trigger fees, service interruptions, or strained financial relationships. Digital systems reduce these risks by providing instant confirmation and real-time tracking. As risk awareness grows, more users shift away from checks for security and reliability.

The New Banking Trend That Could Make Paper Checks Harder to Use
Changes in the banking world might make paper checks harder and harder to use – Shutterstock

How Consumers Can Adapt to the New Banking Reality

Consumers now adapt by embracing mobile banking apps, digital wallets, and instant transfer services. These tools offer faster payment delivery and clearer visibility into account activity. Many banks also provide built-in budgeting features that help track spending in real time. This shift makes financial management more interactive and responsive.

Learning new payment tools now becomes part of everyday money management. Most apps guide users through setup steps that simplify direct deposits, bill payments, and peer transfers. Banks also offer customer support and tutorials to ease the transition away from checks. As adoption grows, digital methods become the default rather than the alternative.

What the Future of Banking Looks Like Without Checks

Banks continue investing in systems that remove friction from money movement and reduce reliance on paper-based tools. Future banking platforms will likely focus on instant settlement, biometric security, and fully automated financial tracking. These systems aim to create a seamless experience where payments happen in the background without manual input. Paper checks will likely remain only for niche or legacy use cases.

Financial innovation continues to reshape expectations around speed, security, and convenience. Younger generations already rely heavily on digital-first payment habits, which accelerates the decline of traditional checks. Banks follow these behaviors by redesigning services around mobile and real-time platforms. The direction of change points clearly toward a check-free financial ecosystem.

Navigating the New Banking Shift

The banking world now moves toward instant, digital-first transactions that leave paper checks struggling to keep up. Faster systems, stronger fraud protection, and evolving customer habits all push financial institutions away from manual payment methods. Consumers who adapt early gain smoother financial experiences and fewer payment delays. Paper checks still exist, but their role continues to shrink in everyday money management. Staying flexible with digital tools helps ensure smoother financial control in a rapidly changing system.

What do you think about the decline of paper checks—does convenience outweigh tradition in modern banking habits?

You May Also Like…

IRS Will Freeze Your Refund Without Correct Bank Info—And Won’t Send a Paper Check Until You Fix It

The Paper Trail: A 2026 Protocol for Cashing Deceased Relative’s Savings Bonds

Why Your Direct Deposit Could Be Frozen If You Don’t Update Your Banking Information

6 Mistakes People Make When Appealing an IRS Identity Check

Why Your Pension Check Could Shrink – Triggers and Solutions

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Banking Tagged With: banking technology, banking trends, digital payments, fintech, money management, paper checks, Personal Finance, real-time payments

Why Some Retirees Are Claiming Social Security Early Despite Smaller Check Warnings

May 23, 2026 by Brandon Marcus Leave a Comment

Why Some Retirees Are Claiming Social Security Early Despite Smaller Check Warnings
More and more American retirees are looking to claim their Social Security early, despite smaller checks – Shutterstock

Retirement used to follow a predictable script. People worked into their mid-60s, collected a gold watch, and filed for Social Security at full retirement age. That neat timeline has started to disappear. Millions of Americans now claim Social Security as early as age 62, even though experts constantly warn about permanently reduced monthly checks.

That decision often shocks financial planners because waiting can significantly increase lifetime benefits. Someone who delays benefits until age 70 can receive hundreds more per month compared to filing at 62. Still, retirees continue to take the early option in huge numbers. Real life rarely fits neatly inside retirement calculators, and many seniors make choices based on immediate needs, personal goals, health concerns, and economic pressure rather than maximizing every dollar decades down the road.

Rising Costs Are Pushing Retirees to File Earlier

Inflation has hammered retirees from nearly every angle over the past few years. Grocery bills climbed sharply, utility costs jumped, and housing expenses kept stretching budgets thinner. Many older Americans entered retirement with savings that looked solid on paper in 2019 but suddenly felt much smaller after several years of rising prices. Social Security became the fastest available lifeline for covering basic monthly expenses.

Some retirees also discovered that part-time work no longer covered the gap between expenses and savings withdrawals. A retired warehouse worker in Ohio, for example, may have planned to wait until age 67 before filing benefits while working seasonal jobs. Higher gas prices, prescription costs, and rent increases can quickly destroy that plan. Filing early suddenly becomes less about strategy and more about survival. Financial experts may dislike the move, but retirees facing mounting bills often prioritize immediate stability over future optimization.

Health Concerns Change the Retirement Math

Many retirees do not feel confident about waiting years for larger checks because health problems create uncertainty about the future. Chronic illnesses, physical limitations, and family medical history heavily influence retirement decisions. A person battling heart disease or severe arthritis may decide collecting benefits sooner simply makes more sense than gambling on longevity.

This issue especially affects workers in physically demanding industries. Construction workers, nurses, truck drivers, and factory employees often reach their early 60s with bodies that feel decades older. Continuing to work until full retirement age may not feel realistic. Some retirees also fear missing out entirely if serious illness shortens their lifespan. While delaying benefits may produce larger checks over time, that strategy loses appeal for people who value immediate financial support and flexibility during healthier years of retirement.

Many Americans Simply Want Out of the Workforce

Retirement burnout has become a huge factor behind early Social Security claims. After decades of long commutes, demanding schedules, and workplace stress, many older workers hit a breaking point. The pandemic intensified that feeling for millions of Americans who reevaluated priorities and decided time mattered more than squeezing every dollar from Social Security.

Age discrimination also creates major problems for older workers trying to stay employed. A 63-year-old professional who loses a job may struggle to land another position with comparable pay. Employers often favor younger candidates, even when older applicants bring extensive experience. Some retirees spend months searching for work only to accept lower-paying jobs or leave the workforce entirely. Social Security then becomes a bridge that helps replace lost income while restoring some control over daily life.

Why Some Retirees Are Claiming Social Security Early Despite Smaller Check Warnings
Retirement burnout is real, and it’s leading to many seniors claiming Social Security early – Shutterstock

Fear About the Future of Social Security Plays a Role

Concerns about Social Security’s long-term stability continue shaping retirement decisions. Headlines about trust fund depletion and potential benefit reductions make many Americans nervous about waiting. Even though experts expect the program to continue operating, constant political battles over Social Security create uncertainty that influences behavior.

Some retirees believe claiming benefits early guarantees access to money while the system still looks relatively stable. They worry lawmakers could eventually raise retirement ages, reduce benefits, or change eligibility rules. Financial planners often point out that current retirees and near-retirees likely face minimal disruption, but fear still drives decision-making. Retirement involves emotion just as much as math, and anxiety about future government policy pushes some Americans toward filing sooner rather than later.

Spousal Benefits and Family Situations Affect Timing

Household dynamics frequently complicate Social Security decisions. Married couples often coordinate claiming strategies based on age differences, income history, and health concerns. In some cases, one spouse files early because the household needs immediate cash flow while the other delays benefits to maximize future income.

Family caregiving responsibilities also force many retirees into earlier filings. Grandparents increasingly help raise grandchildren or care for aging spouses and relatives. Those responsibilities may reduce work hours or eliminate employment entirely. A woman caring for a husband with dementia, for instance, may decide early Social Security benefits offer more practical value than continuing stressful work for several additional years. These deeply personal situations rarely fit the standard advice found in retirement planning brochures.

Savings Shortfalls Leave Few Other Options

Retirement savings gaps remain one of the biggest drivers behind early Social Security claims. Many Americans reached retirement age with far less saved than experts recommend. According to multiple retirement studies, a large percentage of workers nearing retirement hold less than $100,000 in savings. That amount disappears quickly when retirees face healthcare costs, housing expenses, and daily living needs.

Pensions have also largely vanished from the private sector, leaving Social Security as the primary guaranteed income source for many households. Previous generations often relied on employer pensions alongside Social Security, but today’s retirees frequently depend on personal savings accounts vulnerable to market swings. A sharp stock market downturn can scare retirees into claiming Social Security earlier to reduce pressure on investment withdrawals. That choice may reduce long-term monthly benefits, but it can also preserve shrinking retirement accounts during uncertain economic periods.

What’s Behind These Early Claims?

The debate around early Social Security claims often sounds simple in financial headlines. Wait longer, collect bigger checks, and enjoy more income later. Real retirement decisions rarely work that neatly. Health concerns, caregiving duties, rising living costs, job loss, emotional burnout, and savings shortfalls all push retirees toward choices that financial calculators may not fully capture.

What do you think about claiming Social Security early? Smart move, risky decision, or something that depends entirely on personal circumstances? Give us your thoughts and experiences in the comments below.

You May Also Like…

Why More Americans Are Delaying Retirement as Medicare Premiums Approach $200 Per Month

The 5 Most Expensive Retirement Mistakes Americans Over 60 Are Making During This Inflation Spike

Texas Retirees: Property Insurance Premiums Rose Over 20% in Some Counties Last Year — Here’s What Seniors Are Cutting to Keep Up

7 Ways Retirees Accidentally Trigger Higher Medicare Premiums

Is it Too Late at 45? How to Use the Mega Backdoor Roth to Dump Tens of Thousands into Retirement in One Year

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: social security Tagged With: early retirement, money management, Personal Finance, Planning, Retirement, retirement income, seniors, Social Security, SSA benefits

The 5 Most Expensive Retirement Mistakes Americans Over 60 Are Making During This Inflation Spike

May 20, 2026 by Brandon Marcus Leave a Comment

The 5 Most Expensive Retirement Mistakes Americans Over 60 Are Making During This Inflation Spike
Seniors are engaging in costly retirement mistakes during this period of inflation. – Shutterstock

Retirement was supposed to feel like a reward, not a financial juggling act under rising grocery bills and shrinking purchasing power. Yet inflation keeps reshaping daily life for Americans over 60, turning once-stable budgets into unpredictable puzzles. Essentials like housing, food, insurance, and healthcare continue climbing faster than many fixed incomes can adjust. As a result, even well-prepared retirees now face hidden financial traps that slowly drain savings. The biggest danger comes not just from rising prices, but from decisions that quietly amplify the pressure.

Smart retirement planning now requires sharper awareness than ever before. Many Americans assume their old financial habits still work, but today’s inflation cycle tells a different story. Small missteps can snowball into major long-term losses, especially when savings no longer grow fast enough to keep pace. These mistakes often feel harmless in the moment, which makes them even more dangerous.

1. Withdrawing Retirement Funds Too Aggressively

Many retirees pull more money from their savings than their portfolios can comfortably handle during high inflation. Rising prices push people to increase withdrawals without recalculating long-term sustainability. This creates a silent drain that shortens the lifespan of retirement accounts far earlier than expected. Financial planners often warn that even a small withdrawal increase can significantly impact long-term stability when markets fluctuate. Inflation makes this even more dangerous because it erodes purchasing power at the same time.

A retiree who once withdrew 4% annually may suddenly need 6% or more just to maintain the same lifestyle. That extra pressure forces investments to work harder while markets remain unpredictable. Over time, accounts shrink faster than expected, leaving fewer options later in retirement. Adjusting spending habits instead of increasing withdrawals helps protect long-term financial security. Many retirees underestimate how quickly this mistake compounds in a high-cost environment.

2. Delaying Downsizing the Family Home

Holding onto a large family home often feels emotionally rewarding, but it can quietly drain retirement funds. Property taxes, maintenance, utilities, and insurance costs continue rising alongside inflation. Many retirees avoid downsizing because of memories tied to their homes or fear of change. However, those ongoing expenses can consume a surprising portion of fixed income. The longer the delay, the more money gets locked into an underutilized asset.

Smaller homes or retirement-friendly communities often free up thousands of dollars each year. That extra cash can strengthen savings or cover rising healthcare costs. In many cases, retirees discover they barely use half their living space anyway. Market conditions in certain U.S. regions have even made downsizing financially advantageous due to strong home equity values. Ignoring this option often becomes one of the most expensive emotional decisions in retirement.

3. Overlooking Healthcare Inflation Costs

Healthcare costs in the United States continue rising faster than general inflation, creating a major blind spot for retirees. Many people budget for basic Medicare coverage but underestimate out-of-pocket expenses like prescriptions, dental care, and specialist visits. Unexpected medical bills can quickly disrupt even carefully planned retirement finances. Inflation in healthcare services often outpaces annual Social Security adjustments, widening the gap each year. This mismatch creates long-term pressure that many retirees fail to anticipate.

A single health event can shift financial stability dramatically, especially without supplemental insurance. Routine care that once felt affordable now requires careful budgeting and planning. Many retirees also overlook long-term care possibilities, which can cost thousands per month. Preventive care planning and supplemental coverage choices play a critical role in protecting savings. Ignoring healthcare inflation often leads to one of the fastest forms of retirement fund depletion.

4. Keeping Too Much Cash in Low-Yield Accounts

Holding large amounts of cash might feel safe, but inflation quietly reduces its real value every year. Many retirees prefer savings accounts or CDs because they appear stable and risk-free. However, when inflation rises faster than interest rates, purchasing power steadily declines. This creates a hidden loss that often goes unnoticed until later in retirement. Security without growth can become a financial disadvantage over time.

A retiree keeping significant cash reserves may effectively lose thousands in value annually during high inflation periods. Investment strategies that include diversified assets often help counterbalance this erosion. Even conservative portfolios can include inflation-protected securities or income-generating investments. The goal involves balancing safety with modest growth to maintain long-term stability. Excessive caution with cash often becomes an expensive long-term mistake.

The 5 Most Expensive Retirement Mistakes Americans Over 60 Are Making During This Inflation Spike
Inflation is affecting retirement plans in huge ways, and it’s leading to major mistakes. – Shutterstock

5. Ignoring Social Security Timing Strategies

Many retirees claim Social Security benefits as soon as they become eligible, without evaluating long-term payout differences. Early claiming reduces monthly income permanently, which becomes especially costly during inflation spikes. Delaying benefits can significantly increase lifetime income, yet many overlook this strategy due to immediate financial pressure. Inflation makes timing even more important because fixed monthly payments lose value faster when started too early. Strategic planning can make a meaningful difference in long-term financial resilience.

A delayed claim often results in noticeably higher monthly checks, which can help offset rising living costs. However, many retirees focus on short-term needs rather than long-term optimization. Understanding spousal benefits and timing options adds another layer of potential income protection. Financial advisors frequently highlight this decision as one of the most impactful retirement choices. Missing this opportunity often leads to avoidable long-term income loss.

Protecting Retirement Stability in a High-Inflation Era

Retirement security now depends on adaptability rather than static planning. Inflation exposes weak points in financial strategies that once seemed reliable. Each mistake compounds over time, slowly eroding the comfort retirees worked decades to build. Small adjustments in spending, housing decisions, healthcare planning, asset allocation, and benefit timing can significantly strengthen financial resilience. Awareness remains the strongest defense against long-term financial strain.

What financial adjustment would make the biggest difference in your retirement stability right now?

You May Also Like…

6 Retirement Planning Errors That Could Cost You Thousands Under New Tax Rules

5 Financial Rules That Can Reduce Retirement Income Faster Than Expected

The Retirement Age Just Hit 67 — What That Means for Your Monthly Check

10 Retirement States That No Longer Cater to Retirees

8 Hidden Fees That Can Eat Away at Your Retirement Savings

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Retirement Tagged With: 401(k), budgeting, Cost of living, elderly finances, Inflation, money management, Personal Finance, Planning, Retirement, retirement mistakes, retirement savings, seniors, Social Security

8 Tax Filing Habits That Are Quietly Triggering Refund Delays

May 17, 2026 by Brandon Marcus Leave a Comment

8 Tax Filing Habits That Are Quietly Triggering Refund Delays
A tax refund on top of a 1040 form – Shutterstock

Tax season often feels like a race against the clock, but rushing through it can quietly cost time instead of saving it. Many Americans expect their refunds to land quickly, yet small mistakes frequently push those payments into long delays. The IRS processes millions of returns, and even minor errors can bump a file into the “needs review” pile. That delay can stretch from days into weeks, especially during peak filing season. Smart filing habits can make the difference between a smooth refund and a frustrating wait.

Understanding what slows down refunds gives taxpayers a real advantage. Most delays don’t come from audits or major issues but from simple, preventable missteps. These habits often repeat year after year, creating unnecessary stress for households counting on their refund. Fixing them early helps ensure the IRS processes returns without interruptions.

1. Rushing Through Early Filing Without Double-Checking Details

Filing early can speed up refunds, but rushing through forms creates costly mistakes that slow everything down. Many taxpayers enter incorrect numbers, skip sections, or forget to review auto-filled data from tax software. The IRS system flags inconsistencies quickly, which forces manual review and delays processing. A careful second look before submitting reduces these risks significantly. Accuracy always beats speed when it comes to tax filing.

Taking a few extra minutes to review Social Security numbers, income entries, and spelling prevents major setbacks. Simple errors in these areas often trigger rejection or adjustment notices. A calm, deliberate filing approach keeps refunds moving through the system without interruption.

2. Entering Incorrect Personal Information

Small identity errors often create surprisingly long refund delays. A mismatched name, wrong Social Security number, or outdated address can stop processing instantly. The IRS must verify identity before releasing any funds, and mismatches slow that verification process. Even a missing middle initial can create unnecessary complications. Precision matters more than most taxpayers realize.

Taxpayers should always compare their return details with official documents before submitting. W-2 forms, Social Security cards, and government IDs should match exactly. Consistency across all records helps the IRS approve refunds without additional review steps.

3. Miscalculating Income or Forgetting Tax Forms

Income reporting errors rank among the most common causes of refund delays. Missing a W-2, 1099, or side income entry creates mismatches in IRS systems. The agency cross-checks employer submissions, and discrepancies trigger automatic holds. Even small underreporting mistakes can slow down refund approval. Accuracy in income reporting keeps the process smooth.

Taxpayers should gather all income documents before starting their return. Double-checking totals against employer statements helps prevent mismatches. Organized records reduce confusion and help filings move through quickly.

4. Providing Incorrect Bank Account Information

Direct deposit speeds up refunds, but incorrect banking details can completely derail them. A wrong digit in an account or routing number sends refunds into processing limbo. The IRS may reject the deposit or send a paper check instead, which takes much longer. These errors often go unnoticed until the refund fails to arrive. Precision in banking information protects refund timing.

Reviewing account numbers carefully before submitting prevents unnecessary delays. Taxpayers should avoid copying outdated information from previous years. Updated banking details ensure refunds land in the correct account without interruption.

5. Ignoring IRS Letters or Requests for Verification

IRS notices often require quick action, yet many taxpayers delay responding or overlook them entirely. These letters usually request identity confirmation or missing documentation. Ignoring them freezes refund processing until the issue gets resolved. The longer the delay in response, the longer the refund sits on hold. Fast replies keep the process moving.

Reading all IRS mail carefully helps avoid unnecessary setbacks. Responding with the correct documents ensures faster resolution. Staying alert to these notices prevents refunds from getting stuck in review cycles.

8 Tax Filing Habits That Are Quietly Triggering Refund Delays
A letter from the IRS – Shutterstock

6. Choosing the Wrong Filing Status

Filing status mistakes can change refund calculations and trigger processing delays. Selecting the wrong category, such as single instead of head of household, often creates mismatches with IRS records. These errors may require manual correction before the refund gets released. Even small misunderstandings of eligibility rules can slow everything down. Correct filing status ensures smoother processing.

Taxpayers should review IRS guidelines before selecting their status. Life changes like marriage, divorce, or dependents can affect eligibility. Accurate selection helps avoid unnecessary corrections later.

7. Missing Out on Supporting Documents for Deductions

Claiming deductions without proper documentation often leads to refund delays. The IRS may request proof for charitable donations, education expenses, or business costs. Without records, the agency pauses processing until verification arrives. This step can stretch refunds out for weeks. Organized documentation speeds up approval.

Keeping receipts and records throughout the year simplifies filing. Taxpayers who prepare early reduce the risk of missing important proof. Strong documentation supports faster and cleaner processing.

8. Using Outdated or Incompatible Tax Software

Old or unreliable tax software can create hidden filing errors that delay refunds. Software updates often include new tax law changes, and outdated versions may miscalculate returns. Submission errors from technical glitches also trigger IRS rejections. These issues often confuse taxpayers who assume everything submitted correctly. Reliable software reduces these risks.

Updating software before filing ensures accurate calculations and smooth submission. Choosing trusted platforms helps prevent technical interruptions. A stable digital filing process leads to faster refund approval.

A Smarter Filing Mindset That Keeps Refunds Moving

Tax refund delays rarely come from one major issue; they usually come from a pattern of small, avoidable habits. Careful attention to details like personal information, income accuracy, and documentation dramatically improves processing speed. The IRS system works efficiently when returns arrive clean and complete. Taxpayers who slow down slightly during filing often get paid faster in the end. Smart preparation consistently beats rushed submission every time.

What tax filing habit has caused the most frustration for you in past seasons, and what strategies help prevent it now?

You May Also Like…

The IRS Is Sending More “Math Error” Notices—Here’s What They Really Mean

7 “Trigger Words” the IRS Uses to Flag Returns Faster

6 Mistakes People Make When Appealing an IRS Identity Check

Waiting on a Refund? New IRS Identity Flags Are Pulling More Returns

Refunds Are Being Frozen Over Missing Bank Details—And Some Filers Won’t Get Paid for Weeks

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: tax tips Tagged With: American taxpayers, direct deposit issues, filing taxes, Financial Tips, IRS, IRS processing, money management, refund delays, tax credits, tax filing mistakes, tax refunds, tax season

What Happens If You Cash Out a 529 Plan in 2026?

May 15, 2026 by Brandon Marcus Leave a Comment

What Happens If You Cash Out a 529 Plan in 2026?
A notebook with the words “529 plan” written on it – Shutterstock

College costs continue to climb faster than a summer gas bill, so millions of Americans stash money inside 529 plans to protect their future budgets. Those accounts offer juicy tax advantages, flexible investment choices, and powerful long-term growth, but cashing one out without a strategy can create a financial mess in a hurry. Families often assume they can pull money whenever they want without consequences, then discover the IRS waited patiently around the corner with a calculator and a penalty form.

New rule changes in recent years added flexibility to 529 plans, yet plenty of confusion still surrounds withdrawals, rollovers, and non-education spending. Anyone who plans to tap a 529 account in 2026 needs a clear roadmap before touching a single dollar.

The IRS Still Wants Its Slice of the Pie

A qualified withdrawal for tuition, books, housing, and approved education expenses usually slides through without federal taxes, which explains why 529 plans remain wildly popular with parents and grandparents. Trouble starts when account holders cash out funds for vacations, credit card debt, luxury purchases, or random expenses that carry zero educational connection. The IRS taxes the earnings portion of a non-qualified withdrawal as ordinary income, and the government also slaps a 10% penalty on those earnings in most situations. Someone who contributed $40,000 and grew the account to $55,000 would owe taxes and penalties only on the $15,000 gain instead of the original contribution amount. That detail softens the blow slightly, although the final bill can still sting harder than a surprise root canal.

Many families forget that states often jump into the action too, especially when residents claimed state tax deductions during earlier contribution years. Several states demand repayment of those tax breaks after a non-qualified withdrawal, which can pile extra costs onto an already painful federal hit. Financial advisors frequently warn clients about this double-whammy because state clawbacks catch people off guard every single year. Timing matters as well because a large withdrawal can push taxable income higher and create ripple effects across tax credits or financial aid calculations. A quick cash-out decision during a stressful moment can easily turn a helpful savings account into an expensive headache.

New 529 Flexibility Changes the Game in 2026

Recent federal rule updates gave 529 plans a much-needed glow-up by expanding the ways families can use leftover money. Starting in 2024, eligible beneficiaries gained the ability to roll unused 529 funds into a Roth IRA under specific conditions, and that option continues in 2026 with lifetime rollover limits attached. Families who feared overfunding a college account suddenly gained a backup plan that rewards long-term saving instead of punishing cautious parents. The rollover still requires careful attention because the account must meet age requirements and annual Roth contribution limits still apply. Smart savers now view 529 plans less like a rigid education vault and more like a flexible financial tool with several escape routes.

That flexibility does not create a free-for-all, however, because strict guidelines still control how these transfers work. The beneficiary must own earned income during the rollover year, and account holders cannot simply dump massive balances into a Roth IRA overnight. Congress designed these rules to encourage education savings rather than create a giant tax shelter for wealthy investors. Financial planners increasingly recommend reviewing older 529 accounts now because some families may benefit more from a gradual rollover strategy than a straight cash withdrawal. A thoughtful plan can preserve tax advantages, avoid penalties, and keep long-term retirement goals moving in the right direction.

Scholarships and Other Exceptions Can Save Money

Several exceptions allow families to dodge the dreaded 10% penalty even after a non-qualified withdrawal, which surprises people who assume the IRS never shows mercy. Scholarship recipients can withdraw an amount equal to the scholarship without paying the additional penalty, although ordinary income taxes on earnings still apply. Military academy attendance, disability, and certain death-related circumstances can also trigger penalty exceptions under federal rules. These carveouts create breathing room for families whose original education plans shifted unexpectedly after years of careful saving. A student who lands a full-ride scholarship should celebrate first and panic about the 529 balance much later.

Families often overlook another important strategy that avoids penalties entirely by changing the beneficiary to another eligible relative. A younger sibling, cousin, spouse, or even future grandchild can use those funds later without resetting the entire account. That flexibility helps multigenerational families keep educational money working instead of surrendering chunks of growth to taxes and penalties. Parents who rushed into cashing out leftover balances during previous years sometimes regretted the move once younger children approached college age. Patience often pays better returns than panic when a large 529 balance remains after graduation season ends.

What Happens If You Cash Out a 529 Plan in 2026?
A bunch of coins and small graduation cap, symbolzing a scholarship – Shutterstock

Cashing Out at the Wrong Time Can Wreck a Budget

A giant 529 withdrawal can create unexpected tax complications that spill far beyond the account itself. Higher taxable income may reduce eligibility for valuable credits, increase Medicare premium costs later, or create bigger tax bills than families anticipated during retirement planning. Investment markets add another layer of risk because cashing out during a downturn can lock in losses after years of disciplined contributions. Savvy account holders usually coordinate withdrawals with tuition schedules, market conditions, and yearly tax planning instead of making emotional decisions. Financial professionals constantly stress that timing matters almost as much as the withdrawal reason itself.

Families also need to track receipts carefully because the IRS expects documentation that matches qualified education expenses with withdrawal dates. Sloppy recordkeeping creates unnecessary stress during tax season and raises the risk of audits or reporting mistakes. Many experts recommend keeping digital copies of tuition bills, housing invoices, and textbook purchases for several years after withdrawals occur. A few extra minutes of organization can save hundreds or thousands of dollars later when questions arise about account activity. Strong planning, careful timing, and detailed records transform a 529 plan from a confusing financial puzzle into a powerful money-saving tool.

The Smartest Move Starts Before the Withdrawal

529 plans still rank among the strongest education savings tools available in America, but cashing one out carelessly can torch valuable tax advantages in record time. Families who study the rules, review recent law changes, and coordinate withdrawals with broader financial goals usually keep far more money in their pockets. The rise of Roth IRA rollover options gives savers more flexibility than previous generations ever enjoyed, which makes thoughtful planning even more important in 2026. Every withdrawal decision carries tax consequences, timing concerns, and long-term financial effects that deserve serious attention before anyone hits the transfer button. A little preparation today can prevent a painful tax surprise tomorrow and keep years of hard-earned savings working exactly as intended.

What would happen to a leftover 529 balance in your household, and would a Roth IRA rollover change the way your family saves for college?

You May Also Like…

The Sandwich Generation Crunch: Saving for College While Supporting Parents

Missed Notices, Lost Credits: How Student Loans Are Trapping Borrowers Again

New FAFSA Rules in Could Change When — and How — Families Save for College

Student Loans Forgiven Are Now Taxable In 2026 — Set Money Aside for Tax Bills

9 Financial Plans That Collapse the Moment Real Life Gets Involved

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: 529 plans, College Savings, education savings, family finances, investing, IRS rules, money management, Personal Finance, Planning, savings accounts, taxes, tuition costs

7 Financial Red Flags That Could Freeze Your Accounts Without Warning

May 15, 2026 by Brandon Marcus Leave a Comment

7 Financial Red Flags That Could Freeze Your Accounts Without Warning
A bank notifying its customer that their bank card is being frozen – Shutterstock

Some bank account freezes feel random from the outside, but banks rarely act without a reason. Financial institutions in the U.S. use automated systems and compliance rules that flag unusual activity fast. A single unusual deposit, transfer, or pattern shift can trigger a review that locks access temporarily. That interruption can hit at the worst possible moment, like payday or rent week. Knowing what triggers those red flags helps prevent frustrating and stressful surprises.

Modern banking relies heavily on fraud detection and anti-money-laundering systems that scan activity 24/7. These systems do not care about intent; they care about patterns, consistency, and risk signals. Even normal behavior changes can look suspicious when compared to a long history of “typical” spending.

1. Large or Unusual Deposits That Break Your Normal Pattern

Banks pay close attention when deposits suddenly spike far above normal income levels. A $500 paycheck history followed by a $10,000 deposit often triggers an automatic review. Systems flag the change because fraud and money laundering often start with unexpected cash inflows. Even legitimate windfalls, like selling a car or receiving a gift, can cause temporary holds. Consistency matters more than the source in many automated checks.

Small steps help reduce issues when large deposits occur. Notifying the bank ahead of time or keeping documentation ready can speed up verification. Regular patterns build trust with financial systems over time. Sudden changes without context create friction that can freeze access temporarily. Predictability protects account access more than most people realize.

2. Frequent Transfers Between Unrelated Accounts

Moving money back and forth between accounts that do not share obvious connections raises suspicion. Banks look for layering patterns that sometimes signal laundering or fraud. Multiple quick transfers in short time windows increase the risk score in monitoring systems. Even harmless “balancing” between personal accounts can trigger automated alerts. Systems do not always distinguish convenience from risk behavior.

Staying consistent with transfer patterns helps reduce unnecessary flags. Keeping transfers limited to known accounts and clear purposes builds a cleaner financial footprint. Sudden bursts of activity between unrelated accounts often prompt review teams to step in. That review can temporarily restrict access while verification takes place. Simple, steady habits help avoid that disruption.

3. Mismatched Personal Information or Identity Changes

Banks freeze accounts when identity details do not match their records. A new address, name change, or outdated Social Security information can all trigger alerts. Even minor mismatches between documents and account profiles can cause verification holds. Fraud prevention systems prioritize identity accuracy above all else. Any inconsistency signals potential account takeover risk.

Updating information quickly after life changes prevents unnecessary disruptions. Moving, marriage, or legal name updates should always reflect in banking profiles immediately. Delays in updating records often confuse automated systems. That confusion can temporarily lock access until verification completes. Clean, current records keep accounts running smoothly.

4. Suspicious Online or Cross-Border Activity

Banks closely monitor logins and transactions that originate from unfamiliar locations. A sudden login from another state or country can trigger security freezes. International purchases or transfers also raise flags when they do not match past behavior. Fraud systems often assume account compromise first and investigate later. That protective approach prioritizes safety over convenience.

Travel notifications or consistent usage patterns help reduce interruptions. Regular international activity should appear predictable in account history. Sudden changes in geography create uncertainty for fraud detection tools. Temporary freezes often follow until identity confirmation occurs. Predictability across locations keeps access stable.

5. Repeated Chargebacks or Payment Disputes

High numbers of chargebacks signal risk to banks and payment processors. Fraudulent transactions, disputes, or refunds can all contribute to this pattern. Even legitimate customer disputes can raise a merchant’s or account holder’s risk score. Too many reversals suggest instability or potential abuse of payment systems. Banks react quickly to protect themselves from liability.

Keeping transactions clean and well-documented reduces dispute frequency. Clear communication with buyers or merchants helps prevent misunderstandings. Each chargeback adds weight to a risk profile that banks track closely. A high dispute rate can lead to account restrictions or freezes. Stable payment behavior builds long-term account trust.

6. Overdraft Abuse or Negative Balance Patterns

Frequent overdrafts signal financial instability to banking systems. Repeated negative balances suggest risk of default or misuse. Even small overdrafts, when constant, create concern for account health. Banks may step in to limit exposure or enforce restrictions. Patterns matter more than isolated incidents.

Maintaining a buffer balance helps avoid these issues entirely. Monitoring spending habits reduces accidental overdrafts that trigger alerts. Financial systems track consistency and discipline over time. Repeated strain on accounts increases the chance of restrictions. Stability keeps accounts in good standing.

7 Financial Red Flags That Could Freeze Your Accounts Without Warning
A magnifying glass looking at an overdrafted account – Shutterstock

7. Inactive Accounts Suddenly Reactivated with High Activity

Dormant accounts that suddenly show heavy activity often trigger automatic freezes. Banks expect inactivity to remain consistent unless properly updated. A sudden burst of transactions after months of silence appears suspicious. Fraudsters often target dormant accounts because monitoring decreases over time. Systems react quickly to protect against unauthorized access.

Reactivating accounts gradually helps avoid unnecessary interruptions. Updating banks before using old accounts prevents confusion. Even legitimate activity can look risky when it breaks long inactivity streaks. Verification steps often follow sudden usage spikes. Controlled reactivation keeps access smooth and uninterrupted.

Protecting Your Account Access

Banks do not freeze accounts randomly; they respond to patterns that signal risk. Most red flags come from changes in behavior, not actual wrongdoing. Small habits like consistency, updated information, and predictable transactions reduce friction with financial systems. Awareness of how banks interpret activity helps prevent sudden disruptions. Financial stability starts with understanding how those systems “see” money movement.

A few mindful adjustments can keep accounts active, secure, and accessible without stress. Predictability builds trust with banking systems over time. Even simple awareness of these seven red flags prevents most unexpected freezes. Financial confidence grows when account behavior stays clean and consistent. Staying ahead of these triggers protects access when it matters most.

What financial habits have caused the most unexpected banking issues in your everyday life? Hop into our comments to chat about it.

You May Also Like…

California Alert: Why Random Amazon Packages Are a Red Flag for Identity Theft in Santa Clara County

Dormancy Rule: Accounts Inactive for 3–5 Years Can Be Sent to the State

How a Greener Home Can Boost Your Bank Account

What To Look For When Opening A Bank Account For Your Teen

8 Rules Around Health Savings Accounts That Still Confuse Seniors

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Finance Tagged With: account freeze, AML laws, banking, banking rules, banking tips, credit behavior, direct deposit, financial mistakes, Financial Security, fraud alerts, money management, Personal Finance

  • « Previous Page
  • 1
  • …
  • 3
  • 4
  • 5
  • 6
  • 7
  • …
  • 48
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • 10 Tactics for Building an Emergency Fund from Scratch by Vanessa Bermudez
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald

Copyright © 2026 · News Pro Theme on Genesis Framework