• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for loans

The 2026 Interest Rate Forecast Could Change Borrowing Costs for Millions

February 18, 2026 by Brandon Marcus Leave a Comment

The 2026 Interest Rate Forecast Could Change Borrowing Costs for Millions
Image source: shutterstock.com

Interest rates sit at the center of almost every financial decision you make, whether you think about them daily or not. When they move, they shift mortgage payments, reshape credit card bills, alter auto loan offers, and even change how much your savings account earns. As 2026 continues, economists, investors, and policymakers all focus on one question: where will rates go next?

The answer carries real weight. The Federal Reserve raised rates aggressively in 2022 and 2023 to fight inflation, pushing its benchmark federal funds rate to the highest levels in more than two decades. In 2024, inflation cooled compared with its 2022 peak, and the Fed signaled that it expects to lower rates gradually if inflation continues to ease toward its 2 percent target. That path sets the stage for 2026, when borrowing costs could look very different from what households have grown used to.

The Fed Holds the Steering Wheel

No single institution shapes U.S. interest rates more directly than the Federal Reserve. The Fed sets a target range for the federal funds rate, which influences short-term borrowing costs across the financial system. Banks use that benchmark to price credit cards, home equity lines of credit, adjustable-rate mortgages, and many business loans. When the Fed raises or lowers rates, it sends a signal that ripples across the economy.

Over the last few years, the Fed lifted rates rapidly to combat the highest inflation in decades. That strategy slowed demand and helped cool price growth. Policymakers have made it clear that they will adjust rates based on incoming data, especially inflation and labor market strength. If inflation continues to trend downward and the job market softens modestly, the Fed has indicated that it could continue cutting rates.

However, the Fed will not slash rates just to make borrowing cheaper. Officials want to avoid reigniting inflation, so they will likely move cautiously. That careful approach means 2026 may not bring rock-bottom rates like those seen in 2020 and 2021, when the Fed cut rates near zero to support the economy during the pandemic. Instead, many analysts expect rates to settle at a more “neutral” level, high enough to keep inflation in check but lower than recent peaks.

Mortgage Rates Could Finally Ease, but Don’t Expect a Time Machine

Mortgage rates do not follow the federal funds rate perfectly, yet they respond to similar forces. Lenders base 30-year mortgage rates largely on longer-term Treasury yields, especially the 10-year Treasury note. Those yields reflect expectations about inflation, economic growth, and Fed policy. When investors believe inflation will cool and the Fed will ease policy, long-term yields often fall, which can push mortgage rates lower.

Prospective buyers should not wait for a perfect number that may never arrive. If rates decline in 2026, refinancing could make sense for homeowners who locked in loans at recent highs. Buyers should focus on affordability rather than chasing the lowest theoretical rate. That means reviewing your budget, comparing lenders, and understanding how even a half-point change can affect monthly payments over 30 years.

Credit Cards and Variable Loans Feel Every Move

If you carry credit card debt, interest rate forecasts matter immediately. Most credit cards carry variable rates tied to the prime rate, which closely tracks the federal funds rate. When the Fed raises rates, card issuers increase annual percentage rates within one or two billing cycles. When the Fed cuts rates, those APRs typically fall just as quickly.

In 2022 and 2023, average credit card rates climbed to record highs as the Fed tightened policy. That increase raised the cost of carrying balances dramatically, especially for households already stretched by higher prices. The Fed will hold rates through May of 2026, but if they cut rates in the early summer, card APRs should decline, offering some relief. Even so, they will likely remain high by historical standards, because credit card rates include large margins above the prime rate to cover risk and profit.

Borrowers should not rely solely on future rate cuts to solve debt problems. Paying down high-interest balances now delivers a guaranteed return that few investments can match. If you qualify, a balance transfer card or a personal loan with a fixed rate could help consolidate debt. Taking action today protects you from uncertainty and gives you control regardless of where rates land.
The 2026 Interest Rate Forecast Could Change Borrowing Costs for Millions
Image source: shutterstock.com

The Wild Cards That Could Rewrite the Forecast

Interest rate forecasts always carry uncertainty, and 2026 will prove no different. Inflation could reaccelerate if energy prices spike, supply chains face new disruptions, or consumer demand rebounds sharply. In that case, the Fed might pause rate cuts or even raise rates again. On the other hand, a sharp economic slowdown or rising unemployment could prompt faster and deeper cuts than current projections suggest.

Global events also play a role. Geopolitical tensions, trade policy shifts, and financial market stress can influence investor demand for U.S. Treasury bonds, which in turn affects long-term yields. Fiscal policy decisions, including federal spending and deficits, can also influence the broader interest rate landscape. No forecast exists in isolation from these forces.

What 2026 Really Means for Your Financial Game Plan

The 2026 interest rate outlook does not promise dramatic extremes; it points toward gradual adjustment after a historic tightening cycle. If inflation continues to cool and the economy remains stable, borrowing costs may ease modestly, offering relief to homeowners, credit card users, and businesses. At the same time, savers may see their returns taper as the Fed moves away from restrictive policy.

You do not need to predict the exact federal funds rate to make smart choices. Focus on the levers you control: your debt levels, your savings habits, and the structure of your loans. Run the numbers on refinancing scenarios. Compare fixed and variable options carefully. Treat every forecast as guidance, not gospel.

What steps are you taking now to prepare for where rates might land next? Talk about this tricky financial situation in our comments below.

You May Also Like…

The Federal Reserve Rate Cut That Did Nothing for Credit Card Holders

Credit Card Interest Rates Average 23.79% in January 2026 Despite Fed Rate Cuts

Why Does Interest Rate Talk Suddenly Affect Everyday Spending

Could Ignoring Rising Interest Rates Destroy Your Budget

Why Do Poorer Families Pay Higher Interest Rates Than Wealthy Ones

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Finance Tagged With: 2026 forecast, borrowing costs, credit cards, economy, federal reserve, Housing Market, Inflation, interest rates, loans, mortgage rates, Personal Finance, savings rates

Why Good Credit (670–739 Score) Gets You 21%–24% APR in 2026

February 4, 2026 by Brandon Marcus Leave a Comment

Why Good Credit (670–739 Score) Gets You 21%–24% APR in 2026
Image source: shutterstock.com

You did everything right. You paid your bills on time. You kept your balances under control. You worked your way into the “good credit” range with a score between 670 and 739, expecting better rates, better offers, and better financial breathing room. And then 2026 shows up… and your APR offers land between 21% and 24%.

Here’s the truth most lenders won’t say out loud: “good credit” doesn’t mean “cheap money.” It means “less risky than average,” and in today’s financial environment, that distinction matters more than ever. This isn’t about you messing up — it’s about how modern lending, inflation pressure, and risk models collide in a world where money simply costs more to borrow.

The Economy Changed the Game, Not Your Credit Score

APR doesn’t exist in a vacuum. It’s tied to broader interest rates, inflation trends, and how expensive it is for lenders themselves to access capital. When base rates stay elevated, everything built on top of them rises too, including credit card APRs, personal loan rates, and revolving credit costs.

In 2026, lenders aren’t pricing loans based on how responsible you feel, they’re pricing them based on systemic risk and funding costs. Even borrowers with solid histories now live in a higher-rate ecosystem where “cheap debt” is no longer the default. A 670–739 score still signals reliability, but it doesn’t override macroeconomic reality.

Risk Models Don’t See “Good,” They See “Probability”

Lenders don’t think in emotional categories like “good” or “bad.” They think in probabilities, data sets, and default risk curves. A 670–739 score still statistically carries more risk than a 760+ borrower, even if you’re financially responsible in real life.

That gap matters because lending algorithms price risk in percentages, not personalities. You might be a stable earner with great habits, but models look at aggregated behavior across millions of borrowers. If people in your score range default more often during economic pressure cycles, rates rise accordingly.

“Good Credit” Is a Marketing Term, Not a Pricing Tier

Always remember that credit categories are designed for consumers, not for lenders. Labels like “fair,” “good,” and “excellent” simplify complexity, but lenders use internal tiers that are far more granular. Your 710 score might look great on an app, but in underwriting systems, it’s often grouped into mid-risk pricing brackets.

That’s why you can work hard for “good credit” and still see 22% APR offers. From a lender’s perspective, the premium rates are attached to ultra-low-risk profiles — long credit history, high income stability, low utilization, diverse credit mix, and top-tier scores. Everyone else pays the risk tax. The label feels flattering, but the pricing tells the real story.

Inflation Didn’t Just Raise Prices — It Repriced Borrowing

Inflation doesn’t just hit groceries and rent, it changes the entire cost structure of money. When inflation stays elevated, lenders build protection into their APRs to preserve profitability and manage default exposure.

Therefore, even responsible borrowers feel squeezed. In 2026, APR inflation is less about borrower behavior and more about systemic financial caution. The lending industry is in defensive mode, and “good credit” borrowers are no longer shielded the way they once were.

Why 21%–24% APR Is the New “Normal Good”

A decade ago, 21% APR felt punitive. Today, it’s increasingly standard for mid-tier borrowers. Lenders know demand for credit still exists, even at higher rates, and consumer borrowing behavior hasn’t slowed enough to force widespread repricing.

As long as people keep using credit, offers stay elevated. The system responds to behavior, not outrage. And because most borrowers in the 670–739 range still qualify — even at higher rates — the pricing structure holds. Accessibility doesn’t equal affordability, and that gap defines modern credit markets.

Smart Borrower Moves in a High-APR World

If 21%–24% APR is the environment, strategy matters more than ever. Carrying balances becomes expensive fast, so utilization discipline isn’t optional anymore. Paying your statements in full, avoiding long-term revolving debt, and using credit cards as tools instead of funding sources becomes crucial.

It also means shopping aggressively for offers, using pre-qualification tools, and leveraging competition between lenders. Credit unions, relationship banking, and secured products often offer better terms than national issuers. You’re not powerless, but you do need to be intentional.

Why Good Credit (670–739 Score) Gets You 21%–24% APR in 2026
Image source: shutterstock.com

The Emotional Side of “Good Credit” in 2026

There’s a psychological hit that comes with doing everything right and still feeling punished by the system. That frustration is real. The promise of credit scoring was fairness: better behavior equals better outcomes. But modern lending blends behavior with macroeconomics, and the result feels less personal and more mechanical.

Understanding that shift matters, because it reframes the story. You didn’t fail. The system evolved. And adapting to it means changing expectations, not just chasing numbers. Financial literacy now includes understanding the environment, not just your score.

Good Credit Still Matters — Just Not the Way You Think It Does

Good credit in 2026 doesn’t buy you low rates — it buys you entry into the system. And that distinction changes everything. APRs are shaped by economic forces bigger than any single borrower, but smart decisions still shape outcomes.

Give us your thoughts! Should “good credit” still mean affordable credit, or is the entire system due for a rethink? Drop your thoughts in the comments, and let’s talk about it.

You May Also Like…

The Credit Score That Adds $2,000/Year to Florida Homeowner’s Insurance Premiums

The Quiet Credit Score Rule Change That’s Raising Borrowing Costs for Older Americans

Why Credit Card APRs Only Dropped 0.35% Even After Three Fed Rate Cuts in 2025

Why Major Banks Are Quietly Lowering Credit Limits for Customers With Holiday Debt

Retail Store Credit Cards Now Charging 30% APR on Average

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: credit score Tagged With: APR, borrowing, credit cards, credit health, credit score, debt strategy, financial literacy, interest rates 2026, loans, money tips, Personal Finance

Student Loan Default Crisis: Millions Of Borrowers Are Now Delinquent or in Default

February 2, 2026 by Brandon Marcus Leave a Comment

Student Loan Default Crisis: Millions Of Borrowers Are Now Delinquent or in Default
Image source: shutterstock.com

The student loan system in the U.S. isn’t just strained — it’s buckling under the weight of a repayment restart that collided with the most expensive cost‑of‑living environment in a generation. Millions of borrowers are now behind on payments, and a rapidly growing share are slipping into delinquency or edging dangerously close to default.

For many people, student debt no longer feels like a manageable monthly bill; it feels like a financial shadow that follows every job change, rent increase, and grocery run. This crisis isn’t just about money — it’s about stress, stalled life plans, delayed homeownership, and mental exhaustion.

When the Payment Pause Ended, Budgets Snapped

The pandemic‑era payment pause offered temporary relief, but it also reshaped budgets in ways no one fully anticipated. For more than three years, millions of borrowers lived without student loan payments and built entire financial lives around that reality. When payments resumed, they collided with higher rent, higher food costs, and higher everything else. Wages didn’t keep up. Savings were thin.

Suddenly, hundreds of dollars in new monthly obligations felt impossible to absorb. For borrowers already living paycheck to paycheck, the restart didn’t feel like a return to normal — it felt like a financial ambush.

Today, it is estimated that about 5.3 million borrowers are in default, while another 4.3 million are in “late stage delinquency.” The number is already high, but it is only growing as this quiet plague sweeps across America. Millions of borrowers are already in default, and millions more are in late‑stage delinquency.

Delinquency Is Quiet — And That’s What Makes It Dangerous

Delinquency doesn’t announce itself. Miss one payment and nothing dramatic happens. No alarms. No flashing warnings. Life keeps moving. But behind the scenes, interest keeps growing, credit scores start slipping, stress compounds, and options shrink.

Many borrowers fall behind not because they’re careless, but because the system is confusing, servicers make mistakes, and repayment options feel overwhelming. A missed notice or a misunderstood plan can snowball into months of delinquency before someone even realizes what’s happening. Checking your loan status regularly and setting up alerts can stop a small slip from becoming a long‑term setback.

Default Isn’t Just a Financial Event — It’s a Life Event

Default reshapes a person’s financial life in ways most people don’t understand until it hits. Wage garnishment, tax refund seizure, damaged credit, blocked access to housing or car loans, and even lost eligibility for certain jobs or security clearances all become real consequences.

And then there’s the emotional toll of student loan debt and missing payments.  Shame, fear, avoidance, and the feeling of being trapped all pile up. Default also limits access to repayment plans and forgiveness programs that could otherwise help. If you’re nearing default, reaching out to your servicer early isn’t weakness — it’s self‑preservation.

Income‑Driven Repayment Isn’t Perfect — But It’s a Lifeline

Income‑driven repayment (or IDR) plans get a bad reputation for being confusing, but for millions of borrowers, they’re the difference between staying afloat and drowning. These plans adjust payments based on income and family size, making them more realistic for people with unstable or lower earnings.

Student Loan Default Crisis: Millions Of Borrowers Are Now Delinquent or in Default
Image source: shutterstock.com

Interest may still accrue, and the paperwork can be frustrating, but staying in good standing protects your credit and keeps you eligible for future relief. If your payments feel impossible, exploring IDR is one of the smartest moves you can make.

The System Was Built for an Economy That No Longer Exists

Student loan repayment was designed decades ago for a world with lower housing costs, lower healthcare costs, stable career paths, and predictable wages. Today’s economy looks nothing like that world. Gig work, contract jobs, layoffs, and unpredictable income make fixed payments harder than ever.

Meanwhile, the cost of living keeps rising. The result isn’t just debt — it’s financial suffocation for millions. This crisis isn’t about irresponsibility. It’s about a system that hasn’t kept up with reality.

The Psychological Weight No One Talks About Enough

Student loan debt doesn’t just drain bank accounts — it drains emotional energy. Borrowers carry shame, anxiety, guilt, and fear of the future. People delay marriage, children, homeownership, career changes, and entrepreneurship because debt feels like an anchor. Silence makes it worse. Talking about it openly and honestly is an act of resilience.

Smart Moves That Actually Help Right Now

You don’t need a miracle. You need momentum. Small, strategic actions matter. For example, setting up autopay prevents accidental delinquency. Also, updating your income ensures your payments reflect your real situation. Keeping copies of all communications protects you from administrative errors. Exploring consolidation, deferment, or forbearance can buy time during financial crises.

Most importantly, staying engaged with your loans keeps you in control instead of reacting to emergencies. Progress doesn’t come from perfect decisions — it comes from consistent, informed ones.

Why This Moment Matters More Than Ever

This isn’t just a spike in missed payments — it’s a turning point. How borrowers respond now will shape their financial futures for decades. Ignoring the problem deepens the damage. Facing it creates options. The crisis may feel overwhelming, but it also creates a moment for change, education, and smarter systems. Financial freedom doesn’t start with paying everything off. It starts with understanding, strategy, and action. The earlier it begins, the more control you regain.

Do you have anything to add to this story? Tell us about your student loan debt repayment woes and successes in the comments below.

You May Also Like…

Will I Ever Be Able to Afford a House With My Current Student Loan Burden?

9 Outrageous Truths About Student Loan Interest

6 Hidden Dangers of Taking Out Student Loans Too Young

5 Reasons You Should Never Co-Sign a Loan (Not Even for Family)

Should Financial Education Be Required Before You Can Get a Credit Card?

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Lifestyle Tagged With: debt relief, federal loans, financial stress, Higher education, income‑driven repayment, Life, Lifestyle, loan default, loans, Personal Finance, student debt crisis, student loans, young adults

Are Payday Loans Still A Big Problem?

December 8, 2025 by Brandon Marcus Leave a Comment

Payday Loans Are Still A Big Problem
Image Source: Shutterstock.com

The second you hear the phrase payday loan, your brain probably lights up with memories of neon signs, desperate decisions, and financial advice articles screaming “DON’T DO IT.”

Payday loans have a reputation that could make even the boldest risk-taker flinch, yet millions of people continue turning to them every year. It’s the kind of financial trap that feels outdated—like floppy disks or dial-up internet—but somehow refuses to disappear. And despite reforms, regulations, and endless warnings, these short-term, high-interest loans are still woven into the financial survival strategies of many Americans.

The real question isn’t whether payday loans exist—it’s why they’re still thriving in a world full of budgeting apps, credit-builder programs, and financial education resources.

Why Payday Loans Became So Popular

People don’t wake up and decide a payday loan sounds fun. These loans exploded because they offered something traditional banks didn’t: instant cash with zero judgment. For someone facing an emergency, a shut-off notice, or a sudden bill, payday lenders felt like the only ones willing to help. The convenience, speed, and no-questions-asked nature of these loans made them tempting, even when the risks were obvious. Over time, their popularity grew not because they were good, but because many people felt they had no better option.

How The Debt Cycle Traps Borrowers

The biggest issue with payday loans isn’t that they’re expensive—it’s how quickly they snowball. Borrowers often can’t repay the full amount on their next paycheck, which forces them to roll the loan over with even more fees. This cycle can turn a small loan into a financial black hole that keeps growing with each extension. Many borrowers end up paying far more in fees than the original loan amount. The tragic part is that the system is designed this way, making repeat customers the backbone of the industry.

The Role Of Regulation In Slowing The Industry Down

Regulation has stepped in many times, hoping to rein in predatory lending without completely eliminating emergency financial options. Some states have capped interest rates, while others have imposed stricter repayment rules or outlawed payday lending altogether. These measures helped reduce the most extreme abuses, but they didn’t eliminate the problem. Lenders often find loopholes or rebrand themselves under new categories like installment loans or cash advances. Even with tougher rules, the core issue—people lacking affordable short-term credit—continues to fuel demand.

Why Payday Loans Haven’t Disappeared

Despite years of warnings, payday loans are still around for one simple reason: financial desperation hasn’t gone anywhere. Many households live paycheck to paycheck, and when an emergency hits, options are limited. Traditional banks don’t offer tiny short-term loans because they aren’t profitable. Credit cards require approvals many consumers can’t get. So payday loans fill a gap—an extremely costly gap, but a gap nonetheless—and until that need is addressed, they’re unlikely to fade away.

Payday Loans Are Still A Big Problem
Image Source: Shutterstock.com

The Digital Transformation That Complicates Everything

Just when regulators thought they had payday loans somewhat contained, the industry went digital. Online payday lenders exploded, offering nationwide access, instant approvals, and ways to bypass state regulations. With the entire process happening behind a screen, transparency became murkier and oversight became harder. Digital borrowers can take out multiple loans without realizing how deep they’ve gone. The shift online made payday lending faster, easier, and in some cases even more dangerous.

The Human Impact Behind The Statistics

Every payday loan customer has a story filled with stress, fear, or desperation. For many, it starts with something small that spirals—like a car repair, a medical bill, or an unexpectedly short paycheck. The shame surrounding payday loans often keeps borrowers silent, creating a private struggle that feels isolating and unfixable. These loans don’t just drain bank accounts; they drain confidence, security, and peace of mind. When you zoom out from the dollar signs, what emerges is a deeply human problem tied to systemic financial inequalities.

Are Alternatives Actually Helping?

In recent years, alternatives have begun popping up—credit unions offering micro-loans, employers providing wage advances, and apps that help users avoid overdraft charges. Some banks have finally started introducing small-dollar loan programs with reasonable terms. These options are promising but not yet widespread, and many consumers still don’t know they exist. Financial literacy programs also help, but education alone can’t fix income instability. Until alternatives become accessible, familiar, and widely trusted, payday loans will continue filling the void.

The Future Of Payday Lending

The future of payday loans depends heavily on policy, technology, and the economy. If incomes rise, emergency savings become normal, and alternative lending grows, payday loans could lose their foothold. But if wages stay stagnant and financial emergencies remain common, people will keep seeking fast cash, no matter the cost. New fintech companies may offer safer solutions, but they must compete with the convenience and simplicity payday lenders mastered long ago. The next decade will reveal whether payday loans shrink into irrelevance—or simply evolve into something harder to regulate.

Why The Problem Still Matters Today

Many people assume payday loans are a relic of the early 2000s, something we’ve collectively moved past. But millions of Americans still rely on them, which means the problem is far from solved. Payday lenders thrive where financial vulnerability thrives, and that vulnerability remains widespread. Understanding how these loans work, why they persist, and who they hurt is crucial for building better solutions. The payday loan problem isn’t about borrowing—it’s about the conditions that make such borrowing necessary.

 Share Your Thoughts Below

Payday loans may not dominate headlines like they used to, but they continue to shape the financial lives of those living on the edge. They’re a symptom of deeper problems—income instability, a lack of short-term credit options, and the ongoing struggle many people face in managing unexpected expenses. Reform has helped, but it hasn’t erased the core issue.

What’s your experience with payday loans? Share your thoughts, personal stories, or questions in the comments below.

You May Also Like…

5 Hidden Costs of Relying on Payday Loans

Why Do People Ignore the Risks of Cosigning Loans

These 3 Loans Are Worse Than Pay Day Loans

6 Hidden Dangers of Taking Out Student Loans Too Young

Why Do Families Rely on Payday Loans in Emergencies


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: dangerous loans, financial dangers, financial matters, lending money, Life, Lifestyle, Loan, loaning money, loans, Money, money issues, payday loans

The Pawn Shop Trap: Why It’s One of the Worst Ways to Get Cash

October 29, 2025 by Travis Campbell Leave a Comment

pawn shop
Image source: mikeledray / Shutterstock.com

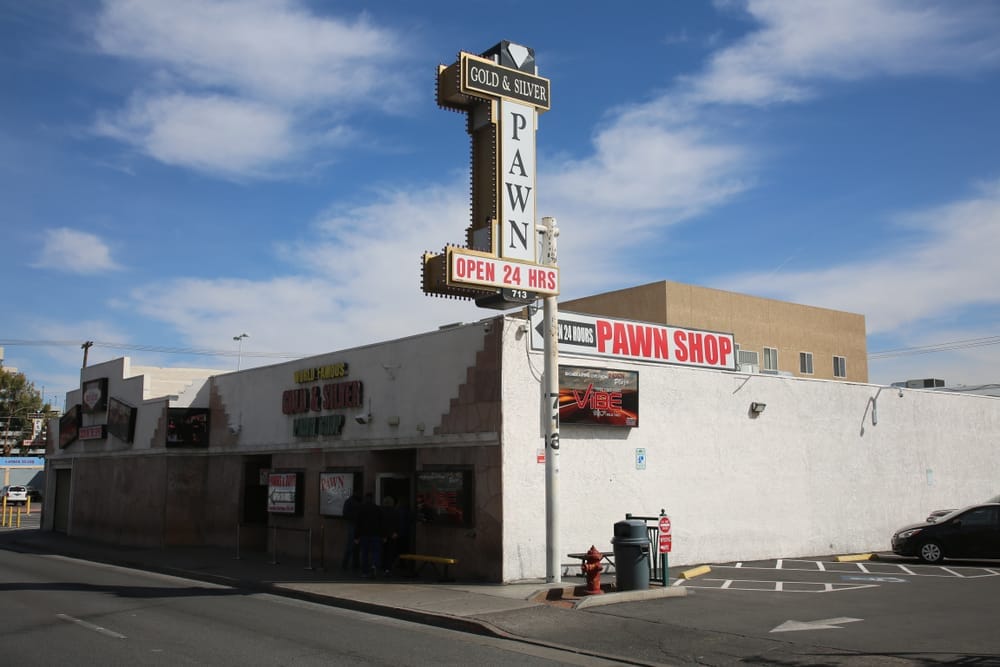
People visit pawn shops because they require instant financial assistance to obtain cash right away. The service delivers cash instantly and does not perform credit checks. But is it really a good idea? Using a pawn shop for immediate financial needs will end up costing you more than what you initially borrow. Most people remain unaware of the actual process of pawn shop loans and their complete set of expenses. Before handing over your valuables, it’s important to know why the pawn shop trap is one of the worst ways to get cash and what you might be sacrificing in the process.

1. Extremely High Interest Rates and Fees

The primary reason the pawn shop trap is so dangerous is the steep cost of borrowing. Pawn shops typically charge interest rates far higher than banks or even payday lenders. It’s not unusual to see monthly interest rates between 10% and 25%, plus additional fees. Over a few months, these charges add up fast. If you borrow $100 and pay 20% interest per month, you’ll owe $140 after just two months—often more with fees. That’s a huge price to pay for a short-term loan.

Many borrowers don’t realize how quickly these costs can spiral. If you can’t repay on time, you could end up losing your item and still not have solved your cash problem. That’s why the pawn shop trap is such an expensive option for getting cash.

2. Risk of Losing Your Valuables

When you pawn something, you’re putting up a valuable item—like jewelry, electronics, or tools—as collateral. If you can’t repay the loan (plus interest and fees) by the deadline, the pawn shop keeps your property. For many people, these items have sentimental value or are hard to replace. The risk is very real: about 15% of pawned items are never reclaimed.

Even if you intend to get your item back, unexpected expenses or delays can make it impossible. You could end up losing a family heirloom or something essential just for a small amount of cash.

3. You Get Far Less Than Your Item Is Worth

Pawn shops make money by paying you as little as possible for your valuables. They typically offer only 25% to 60% of an item’s resale value. If you bring in a $500 watch, you might get just $125 to $300. The shop needs to cover its risks and make a profit, so you’ll never get full value.

Even if you’re confident you’ll repay the loan, you still walk out with a fraction of your item’s worth. If you end up defaulting, the shop resells your property at a hefty markup. This is yet another reason why the pawn shop trap is a poor way to access cash.

4. Short Repayment Windows

Pawn loans are meant to be short-term—often just 30 to 60 days. That doesn’t leave much time to get your finances back on track and repay what you owe. If you miss the deadline, your item is gone. Some shops offer extensions, but they’ll charge you even more in interest and fees. This adds pressure at a time when you’re already stressed and strapped for cash.

Many borrowers end up paying to extend their loans multiple times, paying far more than they ever borrowed in the first place. The short term of pawn shop loans is a key reason they can quickly become a financial trap.

5. No Credit Building or Financial Progress

Pawn shops don’t report your loan or repayment to credit bureaus. That means even if you repay on time, you’re not building credit or improving your financial situation long-term. If you need cash again in the future, you’ll be back where you started—without better options.

Other types of loans, like credit cards or personal loans, can at least help you build a positive credit history if managed well. With the pawn shop trap, you’re stuck in a cycle that doesn’t help you move forward financially.

Better Alternatives to Pawn Shops

Before you fall into the pawn shop trap, consider other ways to get cash. Selling items outright through online marketplaces like eBay or local listing sites can net you more money than pawning. You keep the full sale amount and avoid high fees. If you have a steady income, you may qualify for a small personal loan from a credit union or online lender—often at much lower rates than pawn shops charge.

Some communities offer nonprofit programs or payday alternative loans to help people in a pinch. Even asking friends or family for a small loan can be less costly and risky than a pawn shop. If you’re struggling with debt or ongoing financial problems, talking to a nonprofit credit counselor can help you find a sustainable solution. The key is to avoid the pawn shop trap so you don’t lose your valuables or end up paying far more than you borrowed.

Think Twice Before You Pawn

Pawn shops serve as a fundamental financial solution, providing immediate cash access to people who need it. The pawn shop trap is one of the most dangerous ways to obtain money because it involves significant costs, potential risks, and lasting consequences. You should explore alternatives rather than choosing the first option that comes to mind. You should handle pawning carefully because it protects your valuable possessions and your financial security.

Have you ever visited a pawn shop to get quick access to cash? What was your experience? Share your thoughts or questions below.

What to Read Next…

  • The Benefits Of Taking Personal Loans And Their Impact On Credit Scores
  • 5 Things That Instantly Decrease Your Credit Score By 50 Points
  • Are These 8 Money Saving Tricks Actually Keeping You Broke?
  • 7 Hidden Fees That Aren’t Labeled As Fees At All
  • 5 Invisible Service Charges Eating Into Your Bank Balance
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Debt Management Tagged With: alternatives, Debt, interest rates, loans, pawn shops, Personal Finance, quick cash

5 Reasons You Should Never Co-Sign a Loan (Not Even for Family)

October 11, 2025 by Catherine Reed Leave a Comment

5 Reasons You Should Never Co-Sign a Loan (Not Even for Family)
Image source: shutterstock.com

When a friend or family member asks you to co-sign a loan, it might sound like a simple favor—a quick signature to help them get approved. But agreeing to co-sign a loan is one of the riskiest financial decisions you can make, even with someone you trust completely. The reality is that you’re not just vouching for their character—you’re legally guaranteeing the debt. If they fail to pay, the responsibility shifts entirely to you. Before putting your name on any dotted line, it’s crucial to understand exactly what’s at stake.

1. You’re 100% Responsible If They Don’t Pay

The biggest reason you should never co-sign a loan is that you become legally obligated for the entire balance if the borrower defaults. Lenders don’t care about who was “supposed” to make the payments—they only care about who can. Once you co-sign, you’re just as liable as the primary borrower, meaning your credit, income, and assets are on the line. Even one missed payment can harm your credit score and make future borrowing more difficult. In the worst cases, lenders can pursue collection efforts or even lawsuits against you.

2. Your Credit Score Can Take a Major Hit

When you co-sign a loan, it immediately appears on your credit report as if it were your own debt. That means your credit utilization, debt-to-income ratio, and payment history are all affected. If the borrower misses a payment or pays late, your score suffers just as much as theirs. Even if they pay on time, having that additional loan on your report can make lenders view you as a higher risk. Over time, this can impact your ability to qualify for mortgages, auto loans, or even credit cards.

3. Family and Friendships Can Fall Apart Over Money

One of the most painful consequences of agreeing to co-sign a loan is the potential damage it can cause to relationships. When financial struggles arise, even the closest bonds can quickly sour. You might feel resentful if the borrower stops making payments or hides financial problems from you. They might feel embarrassed, defensive, or avoid communication altogether. Money issues can strain emotional trust in ways that are hard to repair—especially when debt collectors start calling.

4. Your Own Borrowing Power Shrinks

Lenders consider all outstanding debts you’re tied to—including those you co-sign—when evaluating new credit applications. Even if the borrower never misses a payment, that co-signed loan still counts as your liability in the eyes of banks and credit unions. This can reduce how much you’re approved to borrow for your own needs, like buying a home or refinancing existing loans. You might find yourself rejected for credit or offered higher interest rates because of someone else’s financial situation. Co-signing essentially ties your financial future to another person’s behavior.

5. It’s Nearly Impossible to Remove Yourself Later

Once you co-sign a loan, getting your name off it is far more complicated than most people realize. Unless the borrower refinances the loan solely in their name—or pays it off completely—you remain legally attached to it. Some lenders may promise a “release” after a certain number of on-time payments, but these clauses are rare and not guaranteed. Even selling the collateral, like a car, doesn’t automatically clear your obligation if the sale doesn’t cover the loan balance. In many cases, co-signers stay trapped for years, long after they intended to help.

The Safer Alternatives to Co-Signing

If someone close to you needs financial help, there are better ways to assist without risking your credit or peace of mind. Offering a smaller personal loan you can afford to lose, helping them budget, or referring them to a reputable credit counselor can make a real difference. Some banks even allow secured loans where the borrower uses savings or assets as collateral instead of a co-signer. These approaches encourage responsibility while protecting your finances. Remember: helping doesn’t mean jeopardizing your own stability.

Protecting Your Finances Means Protecting Your Future

It’s natural to want to help loved ones, but co-signing a loan can quickly turn a kind gesture into long-term regret. The financial consequences—credit damage, strained relationships, and lost opportunities—are often far greater than the borrower or co-signer expects. Saying no doesn’t make you selfish; it makes you smart and cautious about your financial health. You can still offer support in meaningful, practical ways that don’t put your financial future at risk. When it comes to debt, trust isn’t enough—protection matters more.

Have you ever been asked to co-sign a loan for someone? How did you handle the situation? Share your thoughts and experiences in the comments below!

What to Read Next…

  • 5 Financial Nightmares That Start With Cosigning a Loan
  • Why Do People Ignore the Risks of Cosigning Loans
  • 5 Sneaky Financial Costs of Cosigning a Loan
  • 8 Financial Risks of Buying Property With Siblings
  • 5 Cosigning Mistakes That Could Wreck Your Credit for Years
Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.

Filed Under: Personal Finance Tagged With: co-sign a loan, credit score, Debt Management, family money, financial advice, loans, money mistakes, Personal Finance

What Happens When You Don’t Read Loan Fine Print

September 26, 2025 by Travis Campbell Leave a Comment

loan agreement
Image source: pexels.com

Taking out a loan can feel like a relief, whether you’re buying a car, paying for college, or covering emergency expenses. But many people skip over the loan fine print, eager to get funds quickly. That’s a risky move. The details buried in those pages can dramatically impact your finances. Ignoring the fine print might lead to unexpected fees, higher payments, or even legal trouble. Understanding what happens when you don’t read loan fine print can save you money, stress, and regret.

1. Hidden Fees and Costs

Loan agreements often include fees that aren’t obvious at first glance. If you don’t read the loan fine print, you might be surprised by origination fees, late payment penalties, or prepayment charges. These extra costs can add up quickly, making your loan more expensive than you planned. Some lenders even charge for things like paper statements or payment processing. Always check the fee schedule before you sign. It’s not just about the interest rate—you need to know the total cost of borrowing.

2. Changing Interest Rates

Many loans come with variable interest rates, but this detail is sometimes buried in the fine print. If you skip reading, you might think your rate is fixed, only to see your payments jump later. That can wreck your budget. When you don’t read the loan fine print, you might miss how and when your rate can change. Look for sections about rate adjustments, index rates, and how often your lender can revise the terms. Even a small increase in your rate can mean hundreds or thousands more over the life of the loan.

3. Unfavorable Repayment Terms

Repayment rules can be tricky. Some loans have short grace periods, while others require large balloon payments at the end. If you don’t read the loan fine print, you might not realize how soon you need to start paying or how much your payments will be. Missing these details can lead to late payments, penalties, or even default. Be clear about your repayment schedule, the amount due each month, and what happens if you pay late. Understanding these terms ahead of time gives you more control over your finances.

4. Tricky Clauses and Traps

Loan documents sometimes include clauses that protect the lender more than you. For example, there might be mandatory arbitration agreements, which limit your ability to sue if there’s a problem. Or there could be cross-default clauses, meaning if you default on one loan, you automatically default on others with the same lender. When you don’t read loan fine print, you may agree to terms you’d never accept if you understood them. Take the time to look for legal jargon, and don’t be afraid to ask for clarification before signing.

5. Credit Score Surprises

Your loan agreement may explain how your payments (or missed payments) are reported to credit bureaus. If you don’t read the loan fine print, you might not realize that even a single late payment could hurt your credit score. Some lenders report late payments after just a few days, while others give you a longer grace period. Understanding this can help you protect your credit and avoid long-term financial consequences. If you’re unsure, ask the lender how they report to credit agencies before you commit.

6. Prepayment Penalties

Paying off a loan early seems like a good thing, but not always. Some lenders charge prepayment penalties if you pay off your balance ahead of schedule. If you don’t read the loan fine print, you might end up paying extra just for being financially responsible. These penalties can eat into any interest savings you hoped to gain by paying off your loan faster. Always check if your loan has a prepayment penalty and how it’s calculated. This is especially important for mortgages and auto loans, where the amounts can be significant.

7. Loss of Collateral

Many loans are secured by collateral, such as your car or home. The fine print spells out what happens if you default. If you don’t read the loan fine print, you might not understand how quickly you could lose your property. Some contracts allow lenders to repossess assets after just one missed payment, with little warning. Protect yourself by knowing exactly what’s at risk and what your rights are if you fall behind.

8. Legal and Collection Risks

Loan agreements usually detail what happens if you break the contract. If you don’t read the loan fine print, you may not see clauses about collections, court costs, or wage garnishment. Some lenders move quickly to collect unpaid debts, hiring collection agencies or taking legal action. This can add major stress and cost to your life. Understanding these consequences before you sign helps you make informed choices and avoid future hassles.

How to Protect Yourself When Borrowing

It’s tempting to rush through paperwork, but reading the loan fine print is essential. Take your time, and don’t hesitate to ask questions if something isn’t clear. Get a copy of the agreement and review it at home, away from pressure. Consider consulting with a trusted advisor or a lawyer if the terms are complex.

Remember, lenders count on borrowers skipping the fine print. Knowing what happens when you don’t read loan fine print gives you the power to avoid surprises and protect your money.

Have you ever been caught off guard by a loan’s fine print? Share your experience or questions in the comments below!

What to Read Next…

  • The Benefits of Taking Personal Loans and Their Impact on Credit Scores
  • 9 Surprising Penalties for Paying Off Loans Too Early
  • 7 Hidden Fees That Aren’t Labeled as Fees at All
  • What Happens When You Co-Sign a Friend’s Loan by Accident
  • What Happens When Your Bank Changes the Terms Without Warning
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Debt Management Tagged With: borrowing, credit, Debt, fine print, interest rates, loans, Personal Finance

Why Do People Borrow From Retirement for Non-Essentials

September 25, 2025 by Travis Campbell Leave a Comment

retirement
Image source: pexels.com

Borrowing from retirement accounts for non-essentials is a decision that can have long-term consequences. Many people are aware that their retirement funds are intended for the future, yet the temptation to tap into these savings for vacations, home improvements, or major purchases is strong. This behavior can undermine long-term financial security and even result in penalties or taxes. Understanding why people borrow from their retirement funds for non-essential expenses is crucial, especially as more Americans face financial decisions that can impact their futures. By exploring the motivations and risks, you can make smarter decisions about your own retirement savings.

1. Easy Access to Funds

One major reason people borrow from retirement for non-essentials is the convenience. Many 401(k) plans allow loans with minimal paperwork and quick approval. Unlike bank loans, there are usually no credit checks or lengthy applications. This makes it tempting to dip into a 401(k) or similar account for things like a new car, a kitchen remodel, or a trip abroad.

Because the process is so simple, it can feel less risky or serious. People may convince themselves that borrowing from retirement is just a short-term solution, forgetting the long-term impact on their savings and growth potential.

2. Underestimating the True Cost

Borrowing from retirement for non-essentials often seems harmless because you’re “borrowing from yourself.” However, many don’t realize the real costs involved. When you take money out, even temporarily, you miss out on potential investment gains. If the market rises while your funds are out, you lose compounding growth.

Additionally, if you leave your job before repaying the loan, you may be required to repay it quickly or face tax and penalty consequences. Many people only see the immediate benefits and overlook these hidden costs, making it easier to justify borrowing from retirement for non-essential expenses.

3. Social Pressure and Lifestyle Inflation

Keeping up with friends, family, or neighbors can be a powerful motivator. When people see others taking vacations, upgrading homes, or buying new vehicles, they may feel pressured to do the same. If they don’t have enough cash on hand, borrowing from retirement for non-essentials can seem like a reasonable way to maintain a certain lifestyle.

This kind of spending, known as lifestyle inflation, can erode retirement savings over time. The desire to fit in or avoid feeling left out can push people to make financial decisions that don’t align with their long-term goals.

4. Lack of Emergency Savings

Surprisingly, some people borrow from retirement for non-essentials simply because they don’t have enough saved elsewhere. If an unexpected expense comes up—like a car repair or a last-minute trip—they may not have an emergency fund to draw from. As a result, their retirement account becomes the fallback option, even for things that aren’t true emergencies.

This highlights the importance of building an emergency fund separate from retirement savings. Relying on retirement accounts for short-term needs can jeopardize your financial future and lead to a cycle of borrowing that’s hard to break.

5. Misunderstanding the Purpose of Retirement Accounts

Some people don’t fully understand the purpose of retirement accounts. They may see their 401(k) or IRA as just another savings account, rather than a dedicated fund for their future. This misunderstanding can make it easier to justify borrowing from retirement for non-essentials, since it doesn’t feel like a big deal.

Financial education plays a key role here. Knowing the specific goal of retirement savings—and the potential penalties or lost growth from early withdrawals—can help people resist the urge to tap these funds for non-essential expenses.

6. Overconfidence in Repayment Ability

Many borrowers believe they’ll quickly repay any money taken from retirement accounts. They may think, “I’ll pay it back with my next bonus,” or “It’s only for a few months.” This overconfidence can lead to risky decisions, especially if their circumstances change or if they forget about the loan altogether.

Life is unpredictable, and repaying a retirement loan isn’t always as easy as planned. If someone loses their job or faces an unexpected setback, the borrowed money may never be returned. This can result in penalties, taxes, and a smaller nest egg for the future.

7. Attractive Loan Terms

Retirement account loans often have lower interest rates than credit cards or personal loans. For some, this makes borrowing from retirement for non-essentials seem like a smart financial move. The idea of paying interest to yourself, rather than a bank, is appealing.

However, even with lower rates, the opportunity cost is significant. Money removed from retirement accounts doesn’t grow while it’s out, and the overall impact on your long-term savings can be greater than you expect.

How to Protect Your Retirement Savings

Borrowing from retirement for non-essentials might be tempting, but it rarely serves your best interests. Building a solid emergency fund is the first step in avoiding this pitfall. If you know you have cash set aside for unexpected expenses, you’ll be less likely to raid your retirement account.

It’s also helpful to set clear boundaries around your retirement savings. Remind yourself that these funds are meant for your future self, not for today’s wants. Have you ever considered borrowing from retirement for non-essentials? What stopped you, or what did you learn from the experience? Share your thoughts in the comments below!

What to Read Next…

  • The Benefits Of Taking Personal Loans And Their Impact On Credit Scores
  • How Many Of These 8 Retirement Mistakes Are You Already Making
  • Why Your Adult Children Might Fight Over The Family Car
  • Why Do More Adult Children Regret Accepting Early Inheritance
  • 6 Retirement Plans That Kick You Off Federal Aid Without Notice
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Retirement Tagged With: 401(k), Lifestyle Inflation, loans, Personal Finance, Planning, Retirement, retirement savings

These 3 Loans Are Worse Than Pay Day Loans

September 20, 2025 by Travis Campbell Leave a Comment

loans
Image source: pexels.com

When you’re short on cash, it’s tempting to grab the first loan that promises quick approval. Payday loans get a bad reputation for their high interest rates and predatory fees, and for good reason. But the truth is, there are loans even worse than payday loans lurking out there. These financial traps can dig you into a deeper hole, making it nearly impossible to get ahead.

Understanding the risks is critical. Some loans might seem like an easy fix, but their hidden costs and complex terms can lead to long-lasting debt. Knowing which loans to avoid can help you make smarter decisions and protect your financial future. Here are three loans that are actually worse than payday loans—and why you should steer clear.

1. Car Title Loans

Car title loans are a type of secured loan where you use your vehicle as collateral. They’re marketed as a fast way to get cash, often without a credit check. But the dangers are significant. Interest rates on car title loans can soar to triple digits—sometimes even higher than payday loans. If you can’t repay on time, you risk losing your car entirely.

The loan amounts are usually small compared to your car’s value, but the fees and interest add up quickly. Lenders may charge additional fees for processing or late payments, making it even harder to pay off. According to the Federal Trade Commission’s guide to predatory lending, many borrowers end up renewing their loans multiple times, racking up more debt and fees. If you depend on your car for work or family, losing it can have devastating effects on your daily life and finances.

Car title loans are worse than payday loans because losing your vehicle can disrupt your entire livelihood, and the debt cycle is just as brutal—if not worse.

2. Tax Refund Anticipation Loans

Tax refund anticipation loans, or RALs, are short-term loans offered by tax preparation companies. They promise quick access to your expected tax refund—often within a day or two. While this sounds convenient, the costs can be outrageous. Lenders charge high fees and interest, eating up a significant chunk of your refund before you even receive it.

You’re essentially paying a steep price to borrow your own money a little sooner. If your refund is delayed or less than expected, you might end up owing the lender even more. Some companies tack on hidden fees for processing, document preparation, or even “application” costs.

There are safer alternatives. Many banks and credit unions offer early direct deposit for tax refunds at no extra charge. If you can wait a week or two, you’ll get your full refund without unnecessary fees. RALs are loans worse than payday loans because you’re paying for something you should get for free—and risking extra debt if things don’t go as planned.

3. Rent-to-Own Agreements

Rent-to-own agreements might not look like traditional loans, but they’re just as dangerous. These contracts let you “rent” furniture, electronics, or appliances with the promise of ownership after a set number of payments. The catch? The total cost is often several times the actual retail price.

Rent-to-own companies rarely disclose the true cost up front. Low weekly or monthly payments might draw you in, but over time, you’ll pay exorbitant interest and fees. If you miss a payment, the company can repossess the item—even if you’re just a few payments away from owning it. This makes rent-to-own agreements essentially disguised payday loans. Instead of building equity or improving your credit, you’re stuck in a cycle of paying for items that never truly become yours until the very end.

For those with poor credit or limited cash, rent-to-own seems like a lifeline. But it’s a costly way to get essential items. Saving up or buying secondhand is almost always cheaper in the long run. The high cost and risk of losing your items make these agreements a terrible alternative to payday loans.

Protect Yourself from the Worst Lending Traps

It’s easy to fall into the trap of loans worse than payday loans when you’re desperate for cash. But these options often come with higher fees, more aggressive collection practices, and greater risks to your assets or income. Before signing any agreement, read the fine print carefully. Ask questions about interest rates, fees, and what happens if you can’t pay on time.

Look for safer alternatives like community credit unions, local assistance programs, or even negotiating payment plans with creditors. You can also explore resources such as the Consumer Financial Protection Bureau for guidance on avoiding predatory loans and making informed choices. Protecting your finances means steering clear of loans worse than payday loans—and choosing options that build your financial health instead of tearing it down.

Have you ever been caught in a loan trap? What advice would you give to someone considering one of these options? Share your thoughts in the comments below!

What to Read Next…

  • The Benefits Of Taking Personal Loans And Their Impact On Credit Scores
  • 9 Surprising Penalties For Paying Off Loans Too Early
  • What Happens When You Co Sign A Friends Loan By Accident
  • 7 Financial Loopholes That Lenders Exploit Behind The Scenes
  • 5 Financial Habits That Make You Look Struggling Even When Youre Not
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Debt Management Tagged With: credit, Debt, financial traps, loans, money management, Personal Finance, predatory lending

5 Sneaky Financial Costs of Cosigning a Loan

September 17, 2025 by Travis Campbell Leave a Comment

co sign
Image source: pexels.com

Cosigning a loan is one of those financial favors that seems harmless at first glance. Maybe your friend, sibling, or child needs a hand qualifying for a car loan or student loan. You want to help, and your good credit could make all the difference. But before you put your signature next to theirs, it’s smart to take a step back and look at the hidden side of this decision. The financial costs of cosigning a loan often show up in unexpected ways, affecting your money, credit, and even your peace of mind.

Cosigning a loan is a serious commitment. Many people don’t realize the full scope of the risks until it’s too late. Whether you’re thinking about helping someone out or you’ve already signed, knowing the sneaky financial costs of cosigning a loan can help you protect your future. Here are five key areas where cosigning can impact your wallet and your financial well-being.

1. Your Credit Score Takes a Hit—Even If Payments Are Made

One of the biggest financial costs of cosigning a loan is the effect on your credit score. The loan appears on your credit report just as if you took it out yourself. That means the total amount borrowed, the payment history, and the balance all factor into your credit score calculations.

Even if the primary borrower makes every payment on time, your debt-to-income ratio increases. This could lower your score or make it harder for you to qualify for your own credit cards, mortgages, or car loans. If a payment is missed, your score can drop fast. And remember, late payments stay on your report for up to seven years.

2. You Could Be on the Hook for Late Fees and Collection Costs

Most people focus on the loan amount itself, but the financial costs of cosigning a loan go beyond the principal and interest. If the borrower misses a payment, the lender will come after you for the money. And it’s not just the missed payment—they may add late fees, collection costs, and even legal fees to the balance.

These extra charges can quickly add up. If the account goes into collections or legal action is taken, you could be responsible for the full amount owed, plus all the additional costs. This can create a financial burden you never expected, sometimes years after you first cosigned.

3. Your Borrowing Power Shrinks

When you cosign, lenders see the new loan as your responsibility, too. This means your total debt load increases in the eyes of banks and credit card companies. If you want to apply for a mortgage or refinance your home, your application might be denied, or you could be offered less favorable terms because of your higher debt-to-income ratio.

Even if you have a strong credit history, just having the cosigned loan on your record can limit your ability to borrow for your own needs. This is a sneaky way that cosigning a loan can cost you, especially if you have plans to make big purchases in the future.

4. Relationship Strain Can Lead to Personal Costs

Cosigning a loan isn’t just a financial transaction—it’s a relationship risk. If the borrower struggles to make payments or defaults, things can get awkward or even hostile. Money issues often strain family ties and friendships. You may feel resentful, or the other person may feel embarrassed or defensive.

While not a direct financial cost, damaged relationships can have real-world consequences. You may lose trust, emotional support, or even future financial opportunities. These hidden costs are hard to measure but can be just as significant as the dollars and cents.

5. You Might Face Tax Consequences

Few people realize that the financial costs of cosigning a loan can spill over into tax season. If the borrower defaults and the lender forgives the debt, the IRS may consider the amount forgiven as taxable income. You could receive a 1099-C form showing the canceled debt, which you’ll need to report on your tax return.

This surprise tax bill can be substantial, depending on the size of the loan.

How to Protect Yourself Before Cosigning

Cosigning a loan can be a generous gesture, but it’s essential to go in with your eyes wide open. The financial costs of cosigning a loan can ripple through your credit, your savings, and your relationships for years. Before you agree, ask yourself if you can afford to pay back the entire loan amount (plus fees) on your own if necessary. Get a clear agreement with the borrower about how payments will be handled and how you’ll communicate if there’s trouble.

Consider alternatives, such as helping with a down payment or looking for lenders who don’t require a cosigner. You can also review resources like the CFPB’s guide to cosigning for more tips. Remember, protecting your financial future is just as important as helping someone else achieve theirs.

Have you ever cosigned a loan for someone? What was your experience, and would you do it again? Share your thoughts in the comments below!

What to Read Next…

  • Why Some Elder Care Homes Are Requiring Adult Children to Cosign
  • The Benefits of Taking Personal Loans and Their Impact on Credit Scores
  • What Happens When You Co Sign a Friends Loan by Accident
  • 7 Financial Loopholes That Lenders Exploit Behind the Scenes
  • 5 Things That Instantly Decrease Your Credit Score by 50 Points
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Debt Management Tagged With: cosigning, credit score, Debt, loans, Personal Finance, relationships, taxes

  • « Previous Page
  • 1
  • 2
  • 3
  • 4
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework