• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for taxes

Social Security Is Under Pressure — The Worker-to-Retiree Ratio Is Falling

April 13, 2026 by Brandon Marcus Leave a Comment

Social Security Is Under Pressure — The Worker-to-Retiree Ratio Is Falling
Image Source: Shutterstock.com

The numbers do not whisper anymore—they shout. Social Security, one of the most relied-upon programs in the United States, faces a growing imbalance that feels impossible to ignore. Fewer workers now support more retirees, and that shift sends ripples through everything from taxes to retirement plans. This is not a distant problem sitting quietly on a spreadsheet. It’s a real-world issue shaping how millions of people will live in the years ahead.

The worker-to-retiree ratio once offered a comfortable cushion, but that cushion has thinned out dramatically over time. Back in the 1960s, more than five workers supported each retiree, creating a strong foundation for the system. Today, that number hovers closer to about 2.7 workers per retiree, and projections suggest it could drop even further in the coming decades. That steady decline creates pressure, sparks debate, and forces a big question into the spotlight: what happens when fewer people carry a heavier load?

The Math That’s Changing Everything

The worker-to-retiree ratio might sound like dry economics, but it drives one of the most important financial systems in the country. Social Security works on a pay-as-you-go structure, which means current workers fund the benefits for current retirees. When more workers contribute, the system breathes easily and delivers benefits without much strain. When that balance shifts, the system starts to feel the squeeze.

That squeeze comes from a simple but powerful trend: people live longer, and birth rates have declined. Longer life expectancy means retirees collect benefits for more years than previous generations ever did. At the same time, fewer babies born today means fewer workers entering the workforce tomorrow. This double shift stretches the system from both ends, and it does not give much room to recover quickly.

The numbers tell a clear story without any dramatic exaggeration. In 1940, life expectancy in the United States sat around 63 years, while today it pushes closer to the late 70s. Meanwhile, fertility rates have dropped below the replacement level of 2.1 births per woman, which means the population does not replenish itself at the same pace. That combination creates a steady decline in the number of workers available to support each retiree, and it does not look like it will reverse anytime soon.

This situation does not mean Social Security disappears overnight, but it does mean changes will likely come. Policymakers continue to debate solutions like raising the retirement age, increasing payroll taxes, or adjusting benefits. Each option brings trade-offs, and none of them offer a perfect fix. The reality sits somewhere in the middle, where gradual changes try to keep the system stable without shocking those who depend on it.

Understanding this math gives a clear advantage. It allows people to see the direction things are heading and start preparing instead of reacting at the last minute. Waiting for certainty rarely works when it comes to long-term financial planning, especially when the system itself faces ongoing adjustments.

Why Fewer Workers Carry More Weight

The shrinking workforce does not happen by accident—it reflects deeper societal shifts that have unfolded over decades. One major factor comes from changing family dynamics. People choose to have fewer children, often due to rising costs of living, career priorities, and lifestyle preferences. That decision shapes the future workforce in a very real way.

Another key factor lies in the aging baby boomer generation. Millions of people born between 1946 and 1964 have already started retiring or will retire soon. This massive wave of retirees increases demand for Social Security benefits at the exact moment when fewer workers enter the system to support it. The timing creates a perfect storm that puts added strain on the program.

Immigration also plays a role, and it often sparks strong opinions. A steady flow of working-age immigrants can help boost the worker population and ease some pressure on Social Security. However, policy decisions around immigration continue to shift, and that uncertainty makes it difficult to rely on it as a long-term solution. The system needs consistency, and right now, it faces too many moving parts.

Technology and automation add another layer to the story. While innovation drives productivity and economic growth, it also changes the nature of work. Some jobs disappear, others evolve, and new roles emerge that may not contribute to Social Security in the same way traditional employment does. Gig work, freelance careers, and nontraditional income streams complicate how people pay into the system.

All of these factors combine into one clear reality: fewer traditional workers support a growing number of retirees. That imbalance does not fix itself without deliberate action. It requires awareness, planning, and a willingness to adapt to a system that looks very different from what previous generations experienced.

What This Means for Retirement Dreams

The shifting ratio forces a rethink of what retirement looks like. Social Security still plays a crucial role, but it no longer guarantees the same level of support it once did. For many, it serves as a foundation rather than a complete solution. That distinction matters more than ever as the system faces increasing pressure.

Future retirees may need to rely more heavily on personal savings, investments, and employer-sponsored retirement plans. That shift places greater responsibility on individuals to plan ahead and build financial security over time. It also means starting earlier makes a noticeable difference, even if contributions begin small and grow gradually.

Timing also plays a critical role in maximizing benefits. Delaying Social Security claims can increase monthly payments, which helps offset some of the system’s long-term challenges. While not everyone can afford to wait, understanding this option allows for more strategic decisions. Every extra year of delay adds value that compounds over a lifetime.

Diversification becomes more important in this environment. Relying solely on Social Security creates unnecessary risk when the system itself faces uncertainty. Combining different income sources, such as retirement accounts, investments, and part-time work, builds a more resilient financial plan. That approach creates flexibility, which matters when economic conditions shift unexpectedly. Planning does not require perfection, but it does demand attention. Ignoring these trends does not make them disappear, and hoping for the best rarely produces the best outcome. Taking control early, even in small steps, helps create a buffer against the changes already unfolding.
Social Security Is Under Pressure — The Worker-to-Retiree Ratio Is Falling
Image Source: Shutterstock.com

What Comes Next

The worker-to-retiree ratio tells a story that continues to evolve, and it does not wrap up neatly. Social Security will likely remain a cornerstone of retirement, but it will not look exactly the same in the future. Adjustments will come, and those changes will shape how benefits get distributed and funded.

This moment calls for awareness, not panic. The system still functions, and it still provides essential support to millions. However, it demands a more active role from those who depend on it in the future. Staying informed, tracking policy changes, and making thoughtful financial decisions all contribute to a stronger position over time.

What steps feel realistic right now to strengthen a retirement plan in a system that keeps changing? Share thoughts, strategies, or even concerns in the comments—there’s a lot to learn from different perspectives on this one.

You May Also Like…

How Seniors Jeopardize Their Social Security Right After Retirement

Why Your Social Security Payment Was Delayed: Common Oversights and Fast Fixes

Why More Seniors Are Getting Surprise Social Security Overpayment Notices

The Medicare Part B Increase That’s Reducing Social Security Checks By About $185/Month in 2026

The Hidden Tax Rules Shrinking Social Security Checks — What Seniors Need to Know

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: social security Tagged With: aging population, benefits, Demographics, economy, Financial Security, future planning, government policy, Personal Finance, retirement planning, Social Security, taxes, workforce trends

The IRS Doesn’t Warn You Twice — Tax Deadlines That Could Cost You Thousands

April 11, 2026 by Brandon Marcus Leave a Comment

The IRS Doesn’t Warn You Twice — Tax Deadlines That Could Cost You Thousands
Image Source: Shutterstock.com

Miss a deadline with the IRS, and the clock doesn’t pause; it charges. Every day that slips by can quietly stack penalties, interest, and stress until a simple oversight turns into a serious financial hit. The system runs on strict timelines, and it doesn’t slow down to offer reminders or second chances once those dates pass. That reality hits hard, especially when the consequences snowball faster than expected. A missed form, a late payment, or even a misunderstanding of the rules can cost far more than the original tax bill.

Deadlines in the tax world don’t just sit on a calendar; they carry real weight and real consequences. Some trigger penalties immediately, while others start a chain reaction that leads to bigger problems down the line. The tricky part comes from how easy it feels to underestimate them, especially when life gets busy or confusing paperwork piles up. But the IRS doesn’t operate on guesswork or good intentions; it runs on precision and timing.

The April Deadline Isn’t Just a Date — It’s a Financial Line in the Sand

April doesn’t politely suggest action; it demands it. The standard federal tax filing deadline usually lands on April 15, unless it shifts slightly due to weekends or holidays. That date applies to filing a return and paying any taxes owed, and it carries immediate consequences when ignored. Missing it without taking action opens the door to penalties that grow quickly and aggressively. The IRS charges a failure-to-file penalty that can reach up to 5 percent of unpaid taxes per month, and that adds up fast.

Filing an extension sounds like a safety net, and it can help, but it doesn’t solve everything. An extension gives extra time to file paperwork, not extra time to pay what’s owed. Taxes still need payment by the April deadline, or penalties and interest start piling up right away. That distinction trips people up every year, leading to surprise balances that feel much larger than expected. Planning ahead for both filing and payment makes a huge difference, especially when income fluctuates or deductions remain unclear.

Staying ahead of this deadline means getting organized early and estimating payments if necessary. Waiting until the last minute invites errors, missed deductions, and rushed decisions. A simple calendar reminder doesn’t cut it, a clear plan does. Setting aside funds throughout the year and reviewing tax documents in advance creates breathing room. That approach turns a high-pressure deadline into a manageable task instead of a financial scramble.

Quarterly Taxes: The Deadline Most People Forget Until It Hurts

Not everyone gets the luxury of withholding taxes through a paycheck. Freelancers, independent contractors, and many small business owners face a different system that demands quarterly estimated tax payments. These deadlines typically fall in April, June, September, and January, and they require careful planning and accurate income tracking. Missing one doesn’t just create a small issue, it triggers penalties based on underpayment.

The IRS expects taxpayers in this category to pay as income arrives, not in one lump sum at the end of the year. That structure keeps revenue flowing consistently, but it also demands discipline and awareness. Skipping a quarterly payment or underestimating income can lead to penalties that feel frustrating and avoidable. The system doesn’t wait for a year-end reconciliation to fix mistakes, it addresses them as they happen.

Building a habit around these deadlines changes everything. Setting aside a percentage of income from every payment helps avoid last-minute panic. Many financial experts suggest opening a separate savings account just for taxes, creating a clear boundary between spendable income and obligations. That simple step turns quarterly payments into a routine instead of a scramble. Staying consistent here protects against surprises and keeps finances steady.

The IRS Doesn’t Warn You Twice — Tax Deadlines That Could Cost You Thousands
Image Source: Shutterstock.com

Late Payments Don’t Just Sit Quietly — They Grow

Unpaid taxes don’t stay still, they grow with interest and penalties that continue until the balance gets cleared. The failure-to-pay penalty usually adds up to 0.5 percent of unpaid taxes per month, and interest compounds on top of that. That combination can turn a manageable amount into a much larger burden over time. Ignoring the issue only makes it worse, and the IRS keeps track of every passing day.

The key point here involves action, not avoidance. Even if paying the full amount feels impossible, making partial payments reduces the overall penalty and interest. The IRS also offers payment plans that allow taxpayers to spread out what they owe over time. Setting up one of these plans shows intent to resolve the debt and can prevent more aggressive collection actions. That option often gets overlooked, even though it provides a practical path forward.

Taking control early keeps the situation from escalating. Waiting too long can lead to liens, levies, or other collection measures that create even more stress. Addressing the issue head-on, even with small steps, makes a big difference. The system rewards effort and consistency, not silence. Staying proactive protects both finances and peace of mind.

Filing Late Can Cost More Than Paying Late — And That Surprises People

The IRS treats late filing more harshly than late payment, and that catches many people off guard. The failure-to-file penalty climbs faster than the failure-to-pay penalty, reaching up to 5 percent per month compared to 0.5 percent. That difference means filing a return on time, even without full payment, often saves money. It sounds counterintuitive, but it works in favor of those who act quickly.

Filing on time also keeps records accurate and up to date. That accuracy matters for future financial decisions, loan applications, and even simple budgeting. Letting paperwork slide creates confusion and increases the risk of errors. Staying organized and submitting returns promptly avoids those complications and keeps everything running smoothly.

A smart strategy focuses on separating the act of filing from the act of paying. Filing on time locks in compliance and minimizes penalties, while payment plans or partial payments handle the financial side. That approach creates flexibility without ignoring responsibilities. Understanding this distinction gives taxpayers a powerful tool to manage deadlines effectively.

Extensions, Refunds, and the Details That Trip People Up

Extensions create breathing room, but they don’t erase obligations. Filing for an extension before the April deadline gives extra months to submit a return, usually until October. That extra time helps gather documents, double-check numbers, and avoid rushed mistakes. But taxes owed still require payment by April, and missing that part leads to penalties.

Refunds bring a different dynamic that feels less urgent but still matters. Taxpayers generally have three years to claim a refund, after which the money goes to the U.S. Treasury. That deadline might seem generous, but it still requires attention and follow-through. Letting it slip means losing money that rightfully belongs to the taxpayer.

Understanding these timelines adds clarity and confidence. Extensions help with paperwork, not payments, and refunds come with their own expiration date. Keeping track of both ensures that no money gets left behind or unnecessarily paid in penalties. A simple checklist of key dates can prevent costly mistakes and keep everything on track.

Beat the Calendar Before It Beats You

Deadlines don’t need to feel like traps waiting to spring; they can become tools for staying organized and in control. Taking a proactive approach changes the entire experience, turning stress into strategy and confusion into clarity. Setting reminders, tracking income, and planning payments ahead of time builds a system that works instead of one that reacts. That shift makes tax season feel less like a race and more like a routine.

What strategy keeps everything on track for you, and what changes could make tax season feel a lot less stressful next time? Share your thoughts, tips, or hard-earned lessons in the comments.

You May Also Like…

Penalty Traps: Everyday Actions That Trigger IRS Fines

Property Taxes Are Catching Homeowners Off Guard — Especially After Buying or Renovating

Property Taxes Are Catching Homeowners Off Guard — Especially After Buying or Renovating

IRS Refund Delays Surge: Incorrect Bank Info Is Triggering Weeks-Long Payment Holds

The IRS Is Sending More “Math Error” Notices — Why You Could Owe Without Realizing It

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: tax tips Tagged With: filing taxes, Income tax, IRS deadlines, IRS rules, late fees, money management, Personal Finance, Planning, tax penalties, tax season, tax tips, taxes

The IRS Letter You Shouldn’t Ignore – and What To Do If You Get One

April 10, 2026 by Brandon Marcus Leave a Comment

The IRS Letter You Shouldn't Ignore - and What To Do If You Get One
Image Source: Shutterstock.com

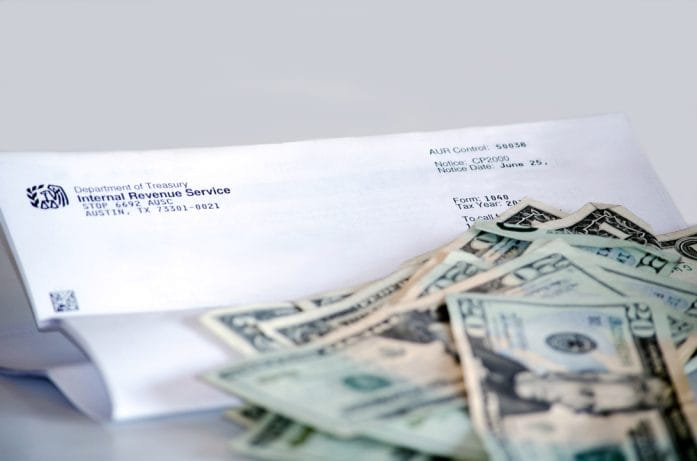
A plain white envelope just landed in the mailbox, and it carries more weight than it looks. The return address reads IRS, and suddenly everything else on the to-do list feels a lot less important. That single piece of mail can trigger a rush of questions, a spike of stress, and a strong urge to pretend it doesn’t exist. That instinct might feel tempting, but it sets up a much bigger problem down the line. Ignoring that letter never makes it disappear, and it rarely ends well.

That envelope doesn’t always mean disaster, though, and that’s where things get interesting. The IRS sends millions of notices every year, and many of them deal with simple issues that have straightforward fixes. Some letters ask for clarification, some correct small errors, and others alert taxpayers to balances owed or refunds adjusted. The key lies in knowing what the letter actually says and acting quickly with a clear plan. A calm, informed approach can turn a nerve-wracking moment into something completely manageable.

Not All IRS Letters Spell Trouble—But Every Single One Demands Attention

That official letter might look intimidating, but it doesn’t automatically signal an audit or a major issue. The IRS uses notices for a wide range of reasons, and many of them fall into routine communication. A letter might point out a math error on a tax return, request additional information, or confirm a change made to a filing. In some cases, the IRS might even send a notice to verify identity or flag potential fraud, which actually protects taxpayers rather than punishes them. That variety makes one thing very clear: the letter matters, even when it doesn’t bring bad news.

Each notice includes a specific code, usually in the upper right corner, and that code tells the story. A CP2000, for example, often means the IRS found a mismatch between reported income and third-party documents like W-2s or 1099s. Other notices, like CP14, typically relate to a balance due, while letters like 5071C deal with identity verification. Understanding that code helps cut through the confusion and points directly to the issue at hand. Skipping that step leaves too much room for guessing, and guessing doesn’t help when dealing with tax matters.

The letter also outlines a deadline, and that deadline matters more than anything else on the page. The IRS expects a response within a set timeframe, often 30 days, and failing to respond can lead to additional penalties or enforced collection actions. That timeline doesn’t leave much room for procrastination. Taking action quickly keeps options open and prevents the situation from escalating into something far more complicated. Even a simple acknowledgment or request for more time can make a big difference.

The Worst Move? Tossing It Aside and Hoping for the Best

That moment of hesitation after opening an IRS letter can turn into full-blown avoidance if left unchecked. Letting the letter sit unopened or unanswered might feel easier in the short term, but it creates a chain reaction that leads to bigger problems. The IRS doesn’t forget, and it doesn’t quietly drop issues when deadlines pass. Instead, penalties can grow, interest can accumulate, and the tone of future notices can become much more urgent.

Ignoring a balance due notice, for example, can lead to additional fees and eventually collection actions such as liens or levies. A lien can attach to property, while a levy can involve wage garnishment or bank account seizures. Those outcomes don’t happen overnight, but they start with missed deadlines and unanswered letters. Addressing the issue early keeps those consequences off the table and preserves more flexibility in how to resolve the situation.

Even when the letter involves something minor, like a request for documentation, ignoring it can escalate the issue unnecessarily. The IRS may adjust a return without input, which could result in a higher tax bill than necessary. Responding with accurate information can correct the record and potentially reduce or eliminate the problem. Taking control early always beats scrambling later when fewer options remain.

What To Do the Moment That Letter Hits Your Hands

The first move involves reading the letter carefully from start to finish, even if the urge to skim feels strong. Every detail matters, including the notice number, the tax year involved, and the specific issue identified. That information sets the stage for everything that follows. Skipping over key points can lead to misunderstandings and incorrect responses, which only complicate matters further.

Next comes verifying the information against personal records. Pull out the relevant tax return, income documents, and any supporting paperwork to compare details. If the IRS claims a discrepancy, check whether the original filing missed something or whether the IRS made an error. Both scenarios happen, and only a thorough review can uncover the truth. That step transforms a vague concern into a clear understanding of what needs to happen next.

After reviewing the details, decide on a response strategy. If the letter requests payment, explore options such as paying in full, setting up an installment agreement, or requesting a temporary delay if financial hardship exists. If the notice disputes information, prepare documentation to support the correct figures and respond within the deadline. Sending a clear, organized response shows engagement and helps move the process forward efficiently. Keeping copies of everything sent also creates a solid paper trail for future reference.

The IRS Letter You Shouldn't Ignore - and What To Do If You Get One
Image Source: Shutterstock.com

When It’s Time to Bring in Backup

Some IRS letters stay simple, while others introduce complexity that requires professional guidance. Notices involving audits, large balances, or legal language often benefit from expert help. Tax professionals such as certified public accountants, enrolled agents, or tax attorneys understand the system and know how to navigate it effectively. That expertise can prevent costly mistakes and reduce stress during the process.

Bringing in help doesn’t mean losing control; it means strengthening the approach. A professional can review the notice, explain options, and communicate with the IRS on behalf of the taxpayer if needed. That support can feel especially valuable when dealing with tight deadlines or unfamiliar terminology. Choosing someone with proper credentials and experience ensures the guidance stays reliable and accurate.

Even in less complicated situations, a quick consultation can provide reassurance and clarity. A professional might confirm that a response looks correct or suggest a better way to present information. That extra layer of confidence can make the entire process smoother and less overwhelming. Investing in guidance at the right moment can save time, money, and frustration.

Turn a Stressful Letter Into a Smart Financial Move

A common IRS letter might not feel like an opportunity at first glance, but it can become one with the right mindset. Addressing the issue promptly can lead to better financial organization, improved recordkeeping, and a clearer understanding of tax obligations. Those benefits extend far beyond the immediate situation and help build stronger habits for the future.

Taking action also creates a sense of control that replaces uncertainty. Instead of worrying about what might happen, a clear plan turns the situation into a series of manageable steps. That shift changes the entire experience from reactive to proactive. Staying organized, meeting deadlines, and communicating effectively with the IRS all contribute to a smoother resolution.

Looking ahead, small adjustments can reduce the chances of future notices. Double-checking tax returns, keeping thorough records, and reporting all income accurately can prevent many common issues. Setting reminders for important tax dates and reviewing filings carefully before submission can also make a big difference. Those habits turn a one-time scare into a long-term advantage.

The Letter That Demands Action—And Rewards It

That IRS envelope carries weight, but it doesn’t have to carry fear. Taking it seriously, understanding its purpose, and responding with clarity can turn a stressful moment into a manageable task. Every notice brings a message, and acting on that message keeps control firmly in hand. Waiting, ignoring, or guessing only adds unnecessary risk, while prompt action opens the door to solutions.

What’s the move? Face it head-on and take control, or let it sit and grow into something bigger than it needs to be? Share your thoughts, strategies, or experiences in the comments and keep the conversation going.

You May Also Like…

Penalty Traps: Everyday Actions That Trigger IRS Fines

IRS Refund Delays Surge: Incorrect Bank Info Is Triggering Weeks-Long Payment Holds

Property Taxes Are Catching Homeowners Off Guard — Especially After Buying or Renovating

5 Reasons To Talk To Your Kids About Taxes

The IRS Is Flagging More Returns This Year—And One Detail Keeps Triggering Reviews

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: tax tips Tagged With: audit, IRS, IRS letters, IRS notice, money advice, Personal Finance, Planning, tax help, tax problems, tax return, tax tips, taxes

How a Change in Marital Status Can Trigger Benefits Reversals

April 9, 2026 by Brandon Marcus Leave a Comment

How a Change in Marital Status Can Trigger Benefits Reversals
Image Source: Shutterstock.com

A wedding ring or a divorce decree does more than change relationship status—it can flip financial benefits upside down overnight. One signature on a legal document can reroute income streams, reduce payments, or unlock new eligibility in ways that feel surprising if no one explained the rules ahead of time. This reality hits especially hard for people who rely on structured benefits like Social Security, tax credits, or need-based programs, because those systems react quickly and sometimes harshly to life changes.

Every major shift in marital status carries a ripple effect that stretches far beyond paperwork. Marriage can boost some benefits while quietly cutting others, and divorce can open doors that once stayed firmly shut. Widowhood introduces a completely different set of rules that can feel both helpful and overwhelming at the same time.

When “I Do” Changes the Math in a Big Way

Marriage brings excitement, shared goals, and often a sense of financial unity, but government benefit systems do not celebrate romance—they calculate income. The moment two people legally marry, agencies often combine incomes when determining eligibility for certain programs. That combined income can push a household above limits for benefits like Supplemental Security Income (SSI), Medicaid, or income-based assistance programs, which means payments can shrink or disappear entirely. Even when both partners earned modest incomes individually, the system may treat them as a higher-earning unit, and that shift alone can trigger reductions.

Social Security introduces its own twist with spousal benefits, which can actually increase payments under the right conditions. A lower-earning spouse may qualify for up to 50 percent of their partner’s benefit at full retirement age, which sounds like a win at first glance. However, that benefit does not stack on top of their own in full; the system adjusts payments based on whichever amount proves higher. This balancing act often confuses people who expect a simple addition but instead receive a recalculated amount that blends both records. Planning ahead matters here, because timing retirement claims can dramatically affect how much money flows into the household.

Taxes also shift quickly after marriage, and those changes can indirectly affect benefits. Filing jointly can move a couple into a different tax bracket, which may alter eligibility for credits or deductions tied to income thresholds. That new tax profile can influence programs that rely on adjusted gross income, creating a chain reaction that reaches far beyond April filings. Couples who take time to run the numbers before tying the knot often avoid unpleasant surprises, especially when benefits form a significant part of their financial picture.

Divorce: A Reset Button With Hidden Advantages

Divorce feels like a financial setback at first glance, but in the world of benefits, it can open unexpected doors. Once a marriage officially ends, each individual returns to separate income calculations, which can restore eligibility for programs that previously cut them off. Someone who lost access to SSI or Medicaid during marriage may suddenly qualify again, simply because their individual income falls below the required limits. That shift alone can make a major difference in monthly stability.

Social Security offers a lesser-known advantage for divorced individuals who meet specific criteria. If a marriage lasted at least ten years, a person can claim benefits based on an ex-spouse’s earnings record without affecting the ex’s payments. This option becomes especially valuable for individuals who earned less during the marriage or spent years out of the workforce. The system allows them to receive up to 50 percent of their former spouse’s benefit at full retirement age, provided they remain unmarried at the time of the claim. That detail matters, because remarriage usually cancels eligibility for those specific benefits.

Timing plays a huge role in maximizing these opportunities. Filing too early can reduce monthly payments permanently, while waiting can increase them. Divorce also creates an opportunity to reassess financial strategy from the ground up, including retirement savings, healthcare coverage, and tax filing status. Taking a proactive approach during this transition can turn a difficult life change into a moment of financial recalibration rather than long-term loss.

How a Change in Marital Status Can Trigger Benefits Reversals
Image Source: Shutterstock.com

Widowhood and Survivor Benefits: A Different Set of Rules

Losing a spouse introduces emotional challenges that no financial system can soften, yet benefit programs step in with specific provisions designed to provide support. Survivor benefits through Social Security allow a widow or widower to receive payments based on the deceased spouse’s earnings record. These benefits can reach up to 100 percent of what the late spouse received or qualified for, which often results in a higher monthly payment than the survivor’s own benefit. That increase can stabilize finances during a time of major life upheaval.

Age and timing again shape the outcome. Survivors can claim benefits as early as age 60, or even earlier if disability applies, but early claims reduce the monthly amount. Waiting until full retirement age unlocks the highest possible benefit, which makes timing decisions especially important. Some individuals choose to take survivor benefits first and switch to their own higher benefit later, or vice versa, depending on which strategy yields more over time. This flexibility creates opportunities, but it also requires careful planning to avoid locking in lower payments unnecessarily.

Other programs also respond to widowhood in ways that may surprise people. Income limits change, household size shrinks, and eligibility for assistance programs may shift as a result. Healthcare coverage, housing assistance, and tax filing status all require updates that can affect monthly expenses and long-term planning. Staying organized and updating records quickly ensures that benefits adjust correctly and that no eligible support slips through the cracks.

Avoiding the Shock Factor: Smart Moves Before and After Status Changes

Preparation makes the difference between a smooth transition and a financial scramble. Before any major marital status change, reviewing current benefits and understanding how income thresholds work can provide a clear picture of what lies ahead. That means checking Social Security estimates, reviewing eligibility for assistance programs, and running tax scenarios based on different filing statuses. A little homework upfront can prevent a cascade of surprises later.

After the change happens, acting quickly keeps everything on track. Reporting marital status updates to relevant agencies ensures accurate benefit calculations and prevents overpayments that may need repayment later. Updating financial plans, including budgets and retirement strategies, helps align spending with the new reality. Seeking guidance from financial advisors or benefits specialists can also clarify complex situations, especially when multiple programs overlap.

Staying flexible matters just as much as staying informed. Life rarely follows a straight line, and benefits systems reflect that unpredictability. Adjusting strategies over time, revisiting decisions, and keeping an eye on policy changes all contribute to better outcomes. People who treat these transitions as opportunities to reassess rather than setbacks often come out ahead in the long run.

Life Changes Fast, So Should Your Strategy

Marital status changes do not just reshape personal relationships—they rewrite financial blueprints in real time. Each transition, whether it involves marriage, divorce, or loss, brings a fresh set of rules that can either strengthen or weaken financial stability depending on how well someone understands the system. Taking control of those changes requires attention, curiosity, and a willingness to ask the right questions before and after the paperwork becomes official.

What strategies have worked when navigating big life changes, and which surprises caught you completely off guard? Share your thoughts, experiences, or tips in the comments.

You May Also Like…

Property Taxes Are Catching Homeowners Off Guard — Especially After Buying or Renovating​

Can You Trust AI With Your Taxes and Investments? 8 Risks No One Explains

5 Reasons To Talk To Your Kids About Taxes

6 Advanced Techniques to Lower Your Capital Gains Taxes Legally

9 Financial Dangers of Ignoring Property Taxes

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Marriage & Money Tagged With: benefits, divorce, government programs, income limits, Marriage, Personal Finance, Planning, Retirement, Social Security, spousal benefits, survivor benefits, taxes

The “Too Late” Rule: When Missed Government Doors Close Forever

April 9, 2026 by Brandon Marcus Leave a Comment

The "Too Late" Rule: When Missed Government Doors Close Forever
Image Source: Shutterstock.com

The clock does not slow down, offer second chances, or whisper reminders when a life-changing deadline inches closer. Government systems run on firm timelines, and once those timelines expire, they rarely bend, no matter how good the reason sounds. Some deadlines come with penalties, others come with fees, but a handful come with something much harsher: a permanent lockout.

That’s where the “Too Late” rule quietly changes lives. Missing certain government deadlines doesn’t just create inconvenience; it can erase opportunities entirely, closing doors that never reopen. These aren’t minor oversights either, but moments that can affect retirement income, legal rights, or access to benefits for years to come.

The Deadlines That Don’t Forgive

Not all government deadlines carry the same weight, and that distinction matters more than most people realize. Some agencies allow late filings with penalties, giving people a chance to recover if they act quickly. Others, however, draw a sharp line in the sand, and once that line gets crossed, options disappear completely. That’s where the danger lives, because these rules often hide in fine print instead of flashing warning signs.

Take retirement benefits as an example. Certain programs require applications within specific windows, and delaying beyond those windows can permanently reduce or even eliminate benefits. Social Security survivor benefits, for instance, often depend on filing within a defined timeframe, especially for specific categories of eligibility. Missing that window can mean forfeiting money that cannot be reclaimed later, no matter how strong the case might seem. The system doesn’t negotiate with hindsight.

Tax-related deadlines create another high-stakes scenario. While many people know about penalties for late filing, fewer realize that some tax elections, credits, or refund claims come with strict expiration rules. The IRS generally allows a three-year window to claim a refund, and after that, the money stays with the government permanently. That reality turns procrastination into a costly mistake, especially for those who assume they can circle back later. In these situations, “later” simply doesn’t exist.

When Paperwork Becomes Power

Government paperwork might look boring, but it carries serious authority. Forms, filings, and applications serve as the gateway to benefits, protections, and rights that people often take for granted. Missing a deadline doesn’t just delay processing; it can strip away eligibility altogether, especially when statutes or regulations require strict compliance.

Immigration processes highlight this reality in a big way. Many visa renewals, status adjustments, or appeals operate under rigid timelines that leave no room for delay. Missing a filing date can lead to loss of legal status, forcing individuals to restart processes or even leave the country. These aren’t small setbacks, but life-altering consequences tied directly to paperwork timing. Staying organized and proactive becomes essential in navigating these systems successfully.

Student loan programs and forgiveness plans also rely heavily on deadlines that demand attention. Certain repayment plans or forgiveness opportunities require annual recertification or timely applications. Missing those dates can reset progress or disqualify participants from benefits they worked toward for years. That kind of setback hits hard, especially when it results from something as simple as overlooking a reminder email or forgetting a date. Organization doesn’t just help here; it protects long-term financial goals.

Appeals, Exceptions, and the Myth of Flexibility

People often assume that government systems allow room for explanation, especially in cases involving emergencies or honest mistakes. While some processes do include appeals or exception requests, those options don’t apply universally. In many cases, the right to appeal itself comes with its own deadline, creating a second layer of risk that catches people off guard.

Legal filings offer a clear example of this structure. Court deadlines, administrative appeals, and benefit disputes all operate under strict filing windows. Missing the deadline to file an appeal can end a case before it even begins, regardless of its merit. Judges and agencies follow procedural rules closely, and failing to meet those requirements can shut down opportunities for review. The system prioritizes consistency over flexibility, which leaves little room for late action.

Even when exceptions exist, they often require proof that meets a high standard. Simply forgetting or misunderstanding a deadline rarely qualifies as a valid reason for leniency. Agencies may require documentation of extraordinary circumstances, and even then, approval is far from guaranteed. That uncertainty makes relying on exceptions a risky strategy. Planning ahead and meeting deadlines remains the only dependable way to protect access to important programs and rights.

The "Too Late" Rule: When Missed Government Doors Close Forever
Image Source: Shutterstock.com

Smart Moves That Keep Doors Open

Avoiding the “Too Late” trap doesn’t require perfection, but it does require awareness and action. The first step involves identifying which deadlines carry permanent consequences and treating them as non-negotiable. That means going beyond surface-level knowledge and digging into the specific rules tied to benefits, taxes, or legal processes. Understanding those timelines turns confusion into clarity.

Setting up a system for tracking deadlines can make a huge difference. Digital calendars, reminder apps, and even simple written planners can help keep important dates visible and manageable. Adding multiple reminders, spaced out over time, reduces the chance of something slipping through the cracks. That kind of structure creates a safety net, especially for deadlines that only come around once a year or even once in a lifetime.

Seeking professional guidance also plays a key role in staying ahead. Financial advisors, tax professionals, and legal experts understand the nuances of government rules and can flag deadlines that might otherwise go unnoticed. They don’t just provide information; they offer context that helps people prioritize what matters most. Investing in that kind of support often prevents much larger losses down the road.

The Moment That Matters Most

Deadlines rarely announce their importance with flashing lights or urgent warnings, yet they hold the power to shape financial futures, legal outcomes, and access to essential benefits. The “Too Late” rule doesn’t exist to punish, but it operates with a level of finality that leaves no room for second chances. Recognizing that reality changes how people approach paperwork, timelines, and long-term planning.

What strategies work best for you when keeping track of important deadlines, and which systems actually stick over time? Share your thoughts, experiences, or even close calls in the comments.

You May Also Like…​

Missed Deadlines, Missed Dollars, Government Dates You Can’t Afford To Ignore

Unclaimed Benefits: Are You Missing Out On Government Money

6 Ways Criminals Are Using AI to Impersonate Banks and Government Agencies

6 Government Benefit Checks That Could Be Delayed Under New Fraud Reviews

How to Inherit an IRA Without Handing Half of It to the Government

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: Applications, benefits, bureaucracy, compliance, filing rules, government deadlines, legal deadlines, missed deadlines, Planning, public policy, Retirement, Social Security, taxes

How Medicare’s Income-Related Surcharge Sneaks Up On Retirees

April 8, 2026 by Brandon Marcus Leave a Comment

How Medicare's Income-Related Surcharge Sneaks Up On Retirees
Image Source: Shutterstock.com

The number looks small at first glance, almost harmless, tucked neatly into a government notice that feels more routine than urgent. Then the math starts to pile up, month after month, year after year, and suddenly that “small” surcharge turns into a budget disruptor with serious staying power. Medicare does not just charge a flat rate for everyone, and that little detail changes everything for retirees who thought they had their healthcare costs nailed down. A quiet recalculation behind the scenes can reshape retirement finances in ways that feel frustratingly out of sync with expectations.

Plenty of people plan for housing, groceries, travel, and even the occasional splurge, yet Medicare’s income-related surcharge rarely gets the same spotlight during those early planning conversations. That oversight creates a perfect setup for surprise, especially because the surcharge depends on income from previous years rather than what someone earns right now. Timing, tax strategy, and even one-time financial moves can all trigger higher premiums without much warning. That is where things get interesting, and a little preparation can go a very long way toward avoiding unnecessary costs.

The Fine Print That Packs a Punch

Medicare’s Income-Related Monthly Adjustment Amount, better known as IRMAA, does not apply to everyone, but it absolutely demands attention from those it does affect. The government uses modified adjusted gross income from tax returns filed two years earlier to determine whether someone pays more for Medicare Part B and Part D premiums. That time lag creates confusion because a retiree’s current income might look modest while an earlier spike still drives up today’s costs. A single strong year, whether from selling property, cashing in investments, or taking large withdrawals, can ripple forward and raise premiums long after the money has settled.

The income thresholds operate in tiers, and crossing into a higher bracket does not just add a few dollars. Each jump can increase monthly premiums significantly, especially when both Part B and Part D adjustments come into play. For married couples filing jointly, those thresholds sit higher than for individuals, but they still catch plenty of households off guard. The structure does not gradually phase in; instead, it moves in noticeable steps that feel abrupt when they hit. That design means careful planning around income levels can make a meaningful difference in total healthcare spending.

The most surprising part often comes from how ordinary financial decisions trigger IRMAA without any dramatic windfall. Required Minimum Distributions from retirement accounts, Roth conversions, or even capital gains from rebalancing a portfolio can push income just high enough to cross a threshold. Those moves might make perfect sense from a long-term tax perspective, yet they still carry short-term Medicare consequences. Without a clear understanding of how those pieces connect, retirees can end up paying more than expected simply because the timing did not line up in their favor.

When “One Good Year” Turns Expensive

A standout income year can feel like a win at the time, especially when it results from smart investing or a well-timed asset sale. Unfortunately, Medicare does not forget that success when it calculates future premiums. Because IRMAA looks back two years, that high-income moment continues to echo into the future, raising monthly costs long after the event itself has passed. That lag creates a disconnect that feels especially frustrating for retirees who now live on a lower, more predictable income.

Consider how a large Roth conversion works in this context. Converting traditional retirement funds into a Roth account often reduces future tax burdens, which sounds like a solid strategy. However, the conversion increases taxable income in the year it happens, which can push someone into a higher IRMAA bracket. Two years later, Medicare premiums rise, even though that conversion might not reflect current financial reality. The same pattern shows up with selling a home that generates significant capital gains or cashing out investments during a strong market year.

Strategic timing becomes the name of the game here, and small adjustments can make a noticeable difference. Spreading out income-generating actions across multiple years instead of stacking them into one can help keep income below key thresholds. Some retirees choose to complete larger financial moves before enrolling in Medicare, which can reduce the risk of triggering higher premiums later. Others work closely with financial planners to coordinate withdrawals and conversions in a way that balances tax efficiency with Medicare costs. Those approaches require a bit more planning upfront, but they can save a meaningful amount over time.

The Appeal Process Most People Ignore

Medicare does offer a way to challenge IRMAA decisions, but many people never take advantage of it. Life does not move in neat, predictable lines, and income can drop suddenly due to retirement, divorce, or the loss of a spouse. When that happens, the income reflected on a tax return from two years ago no longer tells the full story. Medicare recognizes this mismatch and allows individuals to request a reconsideration based on life-changing events, yet awareness of that option remains surprisingly low.

Filing an appeal involves submitting documentation that proves a qualifying event and demonstrates how income has changed. The process might sound intimidating, but it often delivers worthwhile results for those who qualify. A successful appeal can lower premiums back to a more reasonable level, aligning costs with current financial reality rather than outdated numbers. That adjustment can ease pressure on a retirement budget, especially for those dealing with other major life transitions at the same time.

Timing matters here as well, and acting quickly can prevent months of overpaying. Once Medicare processes the appeal, it adjusts premiums moving forward and may even correct past overcharges. Staying organized with financial records and understanding which events qualify can make the process smoother and more effective. Anyone facing a major income shift should take a closer look at this option instead of assuming the higher premium must stick.

The Right Moves That Keep Costs Under Control

A proactive approach to income management can make a real difference when it comes to avoiding IRMAA surprises. Retirement does not eliminate the need for strategy; in many ways, it increases it because income sources become more varied and flexible. Coordinating withdrawals from different accounts, such as taxable, tax-deferred, and tax-free options, allows retirees to shape their overall income more precisely. That control helps keep income within desired thresholds while still meeting spending needs.

Tax planning plays a central role in this balancing act, especially when it comes to decisions like Roth conversions or capital gains harvesting. Breaking those actions into smaller steps across multiple years can help avoid sudden spikes that trigger higher Medicare premiums. Working with a financial advisor or tax professional can provide clarity on how each move affects both taxes and healthcare costs. That kind of collaboration often uncovers opportunities to optimize both areas at once rather than treating them as separate concerns.

Another smart move involves keeping an eye on Required Minimum Distributions, which begin at age 73 under current rules. Those mandatory withdrawals can push income higher than expected, especially for individuals with large retirement accounts. Planning ahead by gradually drawing down those accounts or using strategies like Qualified Charitable Distributions can help manage taxable income more effectively. Every decision ties back to the same goal: maintaining control over income levels to prevent unnecessary premium increases.

How Medicare's Income-Related Surcharge Sneaks Up On Retirees
Image Source: Shutterstock.com

Control the Variables Before They Control You

Medicare’s income-related surcharge does not operate in the shadows, but it definitely rewards those who pay close attention to the details. Understanding how past income affects current premiums opens the door to smarter planning and fewer surprises down the road. Small, thoughtful adjustments to income timing can protect a retirement budget from creeping costs that otherwise feel unavoidable. The system may seem rigid at first glance, yet it leaves room for strategy and control for those willing to engage with it.

What strategies have worked, or what surprises have popped up along the way? Let’s hear your thoughts, experiences, or questions in the comments.

You May Also Like…

Medicare Mishaps: Costly Enrollment Errors Most People Don’t See Coming

How to Enroll in Medicare Without Getting Hit With the IRMAA “Stealth Tax”

Retirement Healthcare Costs Are Climbing Again — What the Average Couple Now Needs

Alaska’s Eye-Popping Healthcare Costs — Planning for Higher Medical Expenses

From Medicare to Medicaid: Why Billing Glitches Are Causing Unexpected Medical Bills Nationwide

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Retirement Tagged With: budgeting, healthcare costs, income brackets, IRMAA, Medicare, Medicare Part B, Medicare Part D, Planning, retirees, retirement planning, senior finances, Social Security, taxes

What Happens if You Forget an RMD? The Costly Consequences Explained

April 8, 2026 by Brandon Marcus Leave a Comment

What Happens if You Forget an RMD? The Costly Consequences Explained
Image Source: Pexels.com

The idea of forgetting something important rarely sparks panic—until that “something” comes with a hefty tax penalty attached. Required Minimum Distributions, better known as RMDs, don’t sit quietly in the background. They demand attention, precision, and timing, and the moment someone misses one, the consequences arrive fast and loud. No one enjoys dealing with the IRS on a normal day, but skipping an RMD can turn a simple oversight into a financial headache that refuses to go away. That reality alone makes this topic worth a closer look.

Retirement accounts often feel like a reward after years of hard work, but they come with rules that don’t bend easily. The government allowed those tax advantages for decades, and eventually, it wants its share. That’s where RMDs step in, forcing withdrawals whether someone needs the money or not. Forgetting one doesn’t just delay a withdrawal—it triggers penalties, paperwork, and stress that can spiral quickly.

The Penalty That Makes People Do a Double Take

For years, missing an RMD carried one of the harshest penalties in the tax code. The IRS used to impose a 50 percent penalty on the amount that should have been withdrawn but wasn’t, and that number shocked just about everyone who learned about it. Recent changes under the SECURE 2.0 Act lowered that penalty to 25 percent, and in some cases even 10 percent if someone corrects the mistake quickly. That adjustment offers some relief, but it still represents a significant financial hit that no one wants to absorb. A missed withdrawal of $10,000 could still lead to a $2,500 penalty if left unresolved. That kind of loss stings, especially when it stems from something as simple as forgetting a deadline.

Deadlines play a huge role in this situation, and they don’t leave much room for error. Most retirees must take their RMD by December 31 each year, although the first RMD allows a one-time delay until April 1 of the following year. That exception creates confusion because delaying the first withdrawal means taking two RMDs in one year, which can bump someone into a higher tax bracket. Missing either deadline triggers the penalty, and the IRS does not send reminders. That responsibility falls entirely on the account holder, which makes organization and awareness essential. Anyone juggling multiple retirement accounts faces an even greater risk of overlooking one.

Fixing the Mistake Before It Gets Worse

A missed RMD doesn’t lock someone into permanent trouble, but quick action makes all the difference. The first step involves taking the missed distribution as soon as possible, even if the deadline has already passed. That move shows good faith and starts the process of correcting the error. Waiting longer only increases the chance of complications, and it signals neglect rather than oversight. Acting quickly keeps the situation manageable and prevents additional stress from building.

After taking the distribution, the next step involves filing IRS Form 5329, which reports the missed RMD and calculates the penalty. This form also allows individuals to request a waiver of that penalty by explaining the mistake and showing that they corrected it promptly. The IRS often grants waivers when someone demonstrates a reasonable error and takes immediate steps to fix it. Clear explanations, accurate documentation, and timely action improve the odds of avoiding the penalty altogether. Ignoring the issue or filing incomplete information almost guarantees a worse outcome.

Why RMDs Catch So Many People Off Guard

RMD rules don’t exactly present themselves in a simple, easy-to-follow package. They depend on age, account type, and changing laws, which creates confusion even among financially savvy individuals. The SECURE Act raised the starting age for RMDs from 70½ to 72, and later legislation pushed it to 73, with another increase scheduled in the future. These shifts create uncertainty, especially for those who planned retirement strategies under older rules. Keeping up with those changes requires attention that many people simply don’t prioritize until it becomes urgent.

Multiple accounts add another layer of complexity that trips people up. Traditional IRAs allow aggregation, meaning someone can calculate the total RMD and withdraw it from one account. Employer-sponsored plans like 401(k)s follow different rules, requiring separate withdrawals from each account. Mixing those requirements often leads to missed distributions, especially when accounts sit with different financial institutions. Without a clear system, it becomes easy to assume everything is handled when it isn’t. That assumption creates the perfect setup for an expensive mistake.

Staying Ahead of the Problem

Avoiding a missed RMD starts with building a system that removes guesswork. Setting calendar reminders months in advance creates a buffer that allows time to act without pressure. Many financial institutions offer automatic RMD services, which calculate and distribute the required amount on schedule. Using those tools reduces the risk of human error and keeps everything running smoothly. Automation doesn’t eliminate responsibility, but it provides a strong safety net that helps prevent costly oversights.

Working with a financial advisor can also make a big difference, especially for those with multiple accounts or complex financial situations. Advisors track changing rules, calculate accurate RMD amounts, and ensure distributions happen on time. That guidance turns a confusing process into a manageable routine. Even without an advisor, regularly reviewing account statements and confirming RMD requirements each year keeps things under control. Staying proactive beats scrambling to fix a mistake every single time.

What Happens if You Forget an RMD? The Costly Consequences Explained
Image Source: Pexels.com

The Ripple Effect on Taxes and Retirement Plans

Missing an RMD doesn’t just trigger a penalty—it can disrupt an entire financial strategy. Required distributions count as taxable income, so skipping one and taking it later can push someone into a higher tax bracket. That shift affects not only federal taxes but potentially state taxes as well. A single oversight can ripple through a tax return in ways that feel frustrating and avoidable. Planning withdrawals carefully helps maintain a steady tax situation instead of creating sudden spikes.

RMD timing also plays a role in long-term retirement planning. Some individuals use strategies like qualified charitable distributions (QCDs) to reduce taxable income while meeting RMD requirements. Missing the deadline eliminates the opportunity to use those strategies effectively for that year. That loss doesn’t just affect taxes—it limits flexibility and reduces control over retirement income. Staying on top of RMDs preserves those options and keeps financial plans on track.

The Important Lesson Behind a Missed RMD

Forgetting an RMD may start as a simple oversight, but it quickly turns into a reminder that retirement accounts come with responsibilities that don’t fade over time. The penalty grabs attention, the paperwork demands action, and the stress pushes financial organization to the top of the priority list. Staying ahead of deadlines, understanding the rules, and using available tools can turn a stressful situation into a manageable routine. No one needs to memorize every detail, but ignoring the basics creates problems that grow fast.

So, what strategies have worked best for keeping your financial deadlines on track, and what lessons have shaped a smarter approach to retirement planning? It’s time to share your thoughts, experiences, or tips in the comments section.

You May Also Like…

How Seniors Jeopardize Their Social Security Right After Retirement

10 Retirement States That No Longer Cater to Retirees

7 Hidden Costs That Are Eating Away at Retirement Income

Retirement Accounts Are Triggering Unexpected Taxes — What Some Investors Overlook

8 Hidden Fees That Can Eat Away at Your Retirement Savings

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Retirement Tagged With: 401(k) withdrawals, IRA rules, IRS penalties, Personal Finance, Planning, required minimum distribution, retirement income, retirement mistakes, retirement planning, RMD rules, tax strategies, taxes

Missed Deadlines, Missed Dollars, Government Dates You Can’t Afford To Ignore

April 7, 2026 by Brandon Marcus Leave a Comment

Missed Deadlines, Missed Dollars, Government Dates You Can't Afford To Ignore
Image Source: Shutterstock.com

The calendar does not care how busy life gets. It keeps marching forward, quietly stacking up dates that carry real financial consequences. Miss one, and the penalty does not come with a polite reminder or a gentle second chance. It comes with late fees, lost benefits, or money that never shows up at all. That sounds dramatic, but it is also reality for millions every year. Knowing the right dates turns confusion into control, and that control often translates directly into dollars.

This is not about memorizing a boring list of deadlines that blur together. This is about spotting the handful of government dates that can make or break a budget. Some of them hit every year like clockwork, while others sneak in depending on life changes, income shifts, or policy updates.

Tax Day Isn’t Just a Date, It’s a Financial Line in the Sand

Tax season carries a reputation for stress, but it also offers a chance to reset finances if handled right. The federal tax filing deadline usually lands in mid-April, and missing it can trigger penalties and interest that start stacking up immediately. Filing late without an extension can lead to a failure-to-file penalty, which grows quickly and feels anything but minor. Even if paying the full amount feels impossible, filing on time still reduces the damage. That simple move keeps penalties lower and opens the door to payment plans that ease the burden over time. People who expect a refund face a different kind of risk, because waiting too long can delay money that could already sit in a bank account earning interest or covering expenses. That refund does not arrive automatically, and the government will not chase anyone down to hand it over.

Extensions offer breathing room, but they come with a catch that often surprises people. Filing later does not mean paying later, and any owed taxes still need to be estimated and paid by the original deadline. Missing that detail creates a situation where penalties apply even with an approved extension. Planning ahead helps avoid that trap, especially by gathering documents early and estimating any owed amount well before the deadline hits. Free filing tools and tax assistance programs can also help those who qualify, cutting down on both stress and cost. Keeping an eye on state tax deadlines matters too, because they do not always match federal timelines. A little organization turns tax season from a scramble into something manageable, and that shift can save a surprising amount of money.

Benefit Deadlines That Quietly Decide Your Income

Government benefits often follow strict timelines, and missing them can mean waiting months for another opportunity. Programs like Social Security, unemployment benefits, and certain tax credits require timely applications or renewals to keep payments flowing. A delay in filing paperwork can interrupt income streams that people rely on for daily expenses. That gap can stretch longer than expected, especially when processing times increase during busy periods. Staying proactive with renewal dates helps maintain steady support without unnecessary interruptions. Marking those dates clearly on a calendar keeps them from slipping through the cracks.

Changes in income, family size, or employment status can also trigger deadlines that demand quick action. Reporting those changes late can lead to overpayments, which the government may later demand back. That situation creates a stressful cycle where money received in good faith suddenly turns into a debt. On the flip side, failing to report changes might mean missing out on increased benefits that could make a real difference. Keeping records updated and responding quickly to notices helps avoid both extremes. A little attention here protects income and prevents unpleasant surprises later.

Quarterly Payments: The Schedule That Catches People Off Guard

Not everyone pays taxes once a year. Self-employed workers, freelancers, and some investors must handle estimated quarterly tax payments, and these dates arrive four times annually. Missing one does not just delay a payment; it can trigger penalties even if the full amount gets paid later. That structure often catches people off guard, especially those new to freelance or gig work. Each payment covers income earned during a specific period, and the deadlines typically fall in April, June, September, and January. Keeping track of those windows ensures taxes stay manageable instead of piling up into one overwhelming bill.

Setting aside a percentage of income throughout the year helps make those payments less painful. Many financial advisors suggest saving around 25 to 30 percent of earnings for taxes, though the exact number depends on individual circumstances. Using a separate savings account for taxes keeps that money from getting mixed into everyday spending. Automated reminders or calendar alerts can also make a big difference, especially when work schedules stay unpredictable. Paying a little at a time keeps cash flow steady and avoids the shock of a massive bill. That steady approach turns a stressful obligation into a routine task that fits neatly into the year.

Enrollment Windows That Open and Slam Shut

Certain government programs only accept applications during specific enrollment periods, and missing those windows can leave people stuck waiting. Health insurance marketplaces, Medicare enrollment, and other programs follow strict timelines that do not bend easily. Missing an open enrollment period can mean going without coverage or paying higher costs until the next window opens. Special enrollment periods exist for major life events like marriage, childbirth, or job loss, but they come with their own deadlines that require quick action. Knowing those timelines ahead of time makes it easier to act fast when life changes.

Preparation plays a huge role here, especially when gathering documents and comparing options before the window opens. Waiting until the last minute often leads to rushed decisions that may not fit long-term needs. Taking time to review coverage options, costs, and benefits ensures a better outcome. Many programs also offer assistance through navigators or online tools, making the process less confusing. Staying informed about upcoming enrollment periods keeps options open and prevents last-minute stress. That awareness can protect both health and finances in a meaningful way.

Missed Deadlines, Missed Dollars, Government Dates You Can't Afford To Ignore
Image Source: Shutterstock.com

The Dates That Decide Credits, Refunds, and Extra Cash

Tax credits and government payments often come with deadlines that determine eligibility. Credits like the Earned Income Tax Credit or Child Tax Credit require filing within specific timeframes, and missing those windows can mean leaving money unclaimed. Some credits also depend on filing accurate information, which makes early preparation even more important. Waiting too long increases the risk of errors, and correcting those errors later can delay payments significantly. That delay can feel especially frustrating when that money could help cover essential expenses.

Refund timelines also matter more than they seem at first glance. Filing early often leads to faster refunds, especially when choosing direct deposit. That speed can make a real difference when budgets feel tight or unexpected costs appear. On the other hand, filing late during peak periods can slow everything down due to processing backlogs. Keeping documents organized and filing promptly helps avoid those delays. Staying ahead of deadlines ensures that every available dollar actually makes it into the bank instead of getting lost in missed opportunities.

Don’t Let the Calendar Win

Deadlines will never slow down, but staying ahead of them changes everything. A simple system of reminders, organized documents, and a little forward planning can protect income, reduce stress, and keep finances on track. The difference between missing a deadline and meeting it often comes down to preparation, not luck. Those who stay aware of key dates tend to keep more of their money and avoid unnecessary penalties. That control feels empowering, especially in a world where financial surprises seem to pop up everywhere.

What strategies keep everything organized and on time? Drop thoughts, ideas, or even hard-learned lessons in the comments and keep the conversation going.

You May Also Like…

Unclaimed Benefits: Are You Missing Out On Government Money

Retirement Healthcare Costs Are Climbing Again — What the Average Couple Now Needs

Banks Are Moving Toward All-Digital Payments — What That Means for Your Money

Charity Strategy: 9 Giving Moves That Bring Tax Benefits Many People Ignore

April Food Alert: How to Use SNAP’s Medical Expense Deduction if Your Benefits Suddenly Dropped

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Finance Tagged With: benefits, budgeting, deadlines, filing taxes, government deadlines, IRS, money tips, Planning, Social Security, stimulus checks, tax season, taxes

How a Small Mistake on Your Tax Form Can Spiral Into Big Trouble

April 7, 2026 by Brandon Marcus Leave a Comment

How a Small Mistake on Your Tax Form Can Spiral Into Big Trouble
Image Source: Shutterstock.com

The moment that tax return gets submitted, a clock starts ticking. Numbers lock into place, records get stored, and suddenly every detail carries weight. A single incorrect digit or missed form does not just sit quietly in a system—it sets off a chain reaction that can grow faster than expected. What looks like a harmless oversight can stretch into penalties, letters, and stress that refuses to fade.

Tax forms demand precision, and the system does not shrug off mistakes just because they seem small. Financial institutions, employers, and government agencies all send their own copies of income records, and those numbers must match. When they do not, red flags pop up fast. That mismatch can lead to questions, delays, and sometimes serious consequences that go far beyond a simple correction.

When One Number Doesn’t Match, Everything Gets Loud

Accuracy matters because tax systems rely on cross-checking. Employers submit wage information through forms like W-2s, while banks report interest income through documents like 1099-INTs. When a tax return shows numbers that do not align with those reports, the system notices immediately. That mismatch does not stay hidden; it creates a discrepancy that demands attention.

The issue often starts with something simple, like leaving out a freelance payment or entering a number incorrectly. Even a small amount of unreported income can trigger a notice because automated systems compare data line by line. Once that notice arrives, the process begins. That process can include requests for clarification, additional documentation, or even a deeper review of the entire return.

Corrections take time and effort, and they often involve more than just fixing one number. Tax authorities may review surrounding details to ensure everything else checks out. That means a small slip can pull more information into focus than expected. The best way to avoid this situation involves double-checking every reported income source, including side gigs, investments, and any irregular earnings that might slip through the cracks.

Penalties Add Up Faster Than Expected

A mistake on a tax form rarely stays just a mistake. When an error results in underpaid taxes, penalties can start building right away. Late payment penalties and interest charges do not wait politely—they accumulate daily. Even a modest underpayment can grow into a much larger amount over time. Interest rates on unpaid taxes change periodically, but they always add pressure. That means delaying a correction makes the situation more expensive. Filing an amended return quickly can reduce the damage, but waiting too long allows those extra costs to stack up. Speed matters when fixing errors.

Beyond financial penalties, repeated mistakes can lead to stricter scrutiny in future filings. Tax authorities may pay closer attention to returns that show patterns of inaccuracies. That increased attention can mean more questions, more documentation requests, and more time spent dealing with the aftermath. Taking time to review every detail before filing helps prevent this snowball effect.

Audits: Rare, But Not Random

Audits do not happen to everyone, but they also do not appear out of nowhere. Certain mistakes increase the chances of an audit, especially when they involve large discrepancies or unusual deductions. Claiming expenses that seem inconsistent with reported income can raise eyebrows quickly.

The process of an audit can feel overwhelming because it requires documentation for nearly every claim. Receipts, bank statements, and records must support every number on the return. Without proper documentation, deductions can disappear, and additional taxes may follow. That situation turns a simple oversight into a complicated financial headache.

Preparation offers the strongest defense. Keeping organized records throughout the year makes it easier to support claims if questions arise. That includes saving receipts, tracking expenses, and maintaining clear documentation for any deductions. Staying organized reduces stress and helps ensure that every number on the return stands on solid ground.

The Hidden Risk of “Harmless” Assumptions

Some of the biggest tax mistakes come from assumptions that seem logical at the time. People often believe that small income amounts do not need reporting or that certain expenses automatically qualify as deductions. These assumptions can lead to incorrect filings that create problems later.

Tax rules change regularly, and what worked one year may not apply the next. Credits and deductions often come with specific requirements, and missing those details can lead to errors. Relying on outdated information or guesswork increases the risk of filing inaccuracies. Staying informed about current tax rules helps avoid these pitfalls.

Using reliable tax software or consulting a qualified tax professional can make a significant difference. These tools and experts help catch errors before submission. They also provide guidance on what qualifies as income or deductions, reducing the chance of making incorrect assumptions. Taking that extra step can prevent costly consequences down the line.

How to Catch Mistakes Before They Catch You

Preventing tax mistakes requires attention to detail and a bit of patience. Reviewing every entry before submitting a return helps catch errors early. That includes verifying personal information, checking income totals, and confirming that all forms match official documents.

Keeping a checklist can simplify the process. That checklist might include confirming all income sources, reviewing deductions, and ensuring that supporting documents are complete. Taking a systematic approach reduces the chance of overlooking important details. It also creates a sense of control over a process that often feels overwhelming.

Filing early can also provide an advantage. Early filing allows time to address any unexpected issues without rushing. It also reduces the risk of identity theft-related tax fraud, which can complicate the filing process even further. A calm, methodical approach leads to more accurate results and fewer surprises.

How a Small Mistake on Your Tax Form Can Spiral Into Big Trouble
Image Source: Shutterstock.com

A Tiny Error Today Can Shape Tomorrow’s Finances

A tax return might seem like just another annual task, but it holds real power over financial stability. Every number carries weight, and every detail contributes to a bigger picture. Small mistakes can ripple outward, creating consequences that extend far beyond a single filing season.

What strategies keep those tiny mistakes from turning into massive problems, and which lessons have proven the most valuable when handling taxes? Share thoughts, tips, or even close calls in the comments.

You May Also Like…

Property Taxes Are Catching Homeowners Off Guard — Especially After Buying or Renovating

IRS Refund Delays Surge: Incorrect Bank Info Is Triggering Weeks-Long Payment Holds

Refunds Are Being Delayed Over New IRS Identity Flags — Why More Returns Are Getting Pulled

5 Reasons To Talk To Your Kids About Taxes

9 Georgia Counties Where Property Taxes Are Set to Rise the Fastest

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: tax tips Tagged With: deductions, Financial Tips, income reporting, IRS, money management, penalties, Personal Finance, tax audit, tax filing, tax mistakes, tax return errors, taxes

5 Tax Mistakes Retirees Make – and How To Fix Them Before It’s Too Late

April 6, 2026 by Brandon Marcus Leave a Comment

5 Tax Mistakes Retirees Make - and How To Fix Them Before It's Too Late
Image Source: Shutterstock.com

Retirement should feel like freedom, not a puzzle filled with tax traps waiting to drain hard-earned savings. Yet many people step into this phase thinking the hardest financial work already sits behind them, only to discover that taxes never really retire. They just change shape, and sometimes they hit harder than expected. Every decision, from when to withdraw money to how investments get structured, carries consequences that ripple through monthly income and long-term security. Ignoring those details can quietly chip away at a lifetime of careful planning.

The good news brings a lot more energy than the bad. A handful of smart adjustments can flip the script completely, turning tax confusion into a powerful advantage. With the right moves, retirees can stretch their savings, protect income, and even create more breathing room for travel, hobbies, and everything that makes retirement worth celebrating. These five common mistakes show up again and again, but each one comes with a fix that puts control back where it belongs.

1. The “I’ll Just Take Money When I Need It” Trap

Plenty of retirees treat their accounts like a simple piggy bank, dipping in whenever expenses pop up without thinking about timing or tax impact. That approach feels easy, but it often leads straight to higher tax bills because withdrawals from traditional retirement accounts count as taxable income. Pull too much in one year, and that income can push someone into a higher tax bracket faster than expected. That jump doesn’t just affect the withdrawal itself, but also other income streams that suddenly face higher rates.

A smarter strategy involves planning withdrawals across multiple years instead of reacting in the moment. Spreading distributions out can help keep income within a lower tax bracket, which keeps more money in your pocket instead of sending it to the IRS. Some retirees also mix withdrawals from taxable accounts, Roth accounts, and traditional IRAs to balance the tax impact. This kind of coordination creates flexibility and reduces surprises when tax season rolls around.

It also pays to think ahead instead of waiting until money runs low. Mapping out a withdrawal plan for five or even ten years helps smooth out income and avoids those sudden spikes that trigger unnecessary taxes. Financial planners often call this “tax-efficient withdrawal sequencing,” but the concept stays simple: control when and how income shows up. That control can mean the difference between steady financial comfort and watching taxes eat into savings year after year.

2. Ignoring Required Minimum Distributions Until It’s Too Late

Required Minimum Distributions, or RMDs, don’t ask politely. They come with firm deadlines and steep penalties for mistakes, and skipping them or miscalculating the amount can cost a significant chunk of money. Once retirees reach the required age, the government expects a minimum withdrawal from certain retirement accounts every year. Missing that requirement used to trigger a massive penalty, and while rules have softened slightly, the consequences still sting enough to demand attention.

Some retirees delay thinking about RMDs because they don’t need the income yet, which creates a problem when the first withdrawal hits. A large RMD can push total income higher, increasing taxes not only on that distribution but also on other income streams. That ripple effect often surprises people who assumed their tax burden would shrink in retirement.

Planning ahead offers a much smoother path. Taking smaller withdrawals before RMD age can reduce the size of future required distributions and spread taxes over time. Another smart move involves converting some traditional IRA funds into a Roth IRA before RMDs begin, which shifts future withdrawals into a tax-free category. These strategies require a bit of foresight, but they prevent that unpleasant moment when a mandatory withdrawal disrupts an otherwise stable financial picture.

3. Forgetting That Social Security Isn’t Always Tax-Free

Social Security often feels like a safety net, but it doesn’t always come tax-free. Many retirees assume those benefits land untouched, only to discover that combined income determines whether a portion becomes taxable. Add in withdrawals from retirement accounts, investment income, or even part-time work, and suddenly up to 85 percent of Social Security benefits could face taxes.

This surprise usually hits when retirees start pulling money from multiple sources without coordinating how it affects total income. That lack of coordination creates a domino effect where one decision triggers another, pushing income above thresholds that increase tax liability. It can feel frustrating, especially after years of careful saving.

A better approach involves managing income levels strategically to stay below key thresholds whenever possible. That might mean delaying Social Security benefits while drawing from other accounts first, or adjusting withdrawals to keep combined income in check. Timing plays a huge role here, and even small adjustments can reduce how much of those benefits get taxed. The goal centers on balance, making sure income flows steadily without accidentally triggering unnecessary tax bills.

5 Tax Mistakes Retirees Make - and How To Fix Them Before It's Too Late
Image Source: Shutterstock.com

4. Overlooking the Power of Roth Conversions

Roth conversions often sit on the table as an option, but many retirees ignore them because they involve paying taxes upfront. That hesitation makes sense at first glance, but skipping conversions can lead to higher taxes later when withdrawals from traditional accounts become unavoidable. Paying some tax now at a lower rate can save a significant amount down the road, especially before RMDs kick in.

Retirees who stay in a relatively low tax bracket early in retirement have a golden opportunity. Converting portions of a traditional IRA into a Roth IRA during those years locks in today’s tax rate and creates a pool of tax-free income for the future. That flexibility becomes incredibly valuable when managing income later, especially when trying to avoid pushing into higher brackets.

Of course, timing and amount matter. Converting too much in a single year can backfire by increasing taxable income more than intended. A steady, measured approach works best, converting just enough each year to stay within a desired tax bracket. This strategy takes a bit of planning, but it offers long-term benefits that go far beyond the initial tax bill.

5. Thinking Investments Don’t Matter for Taxes Anymore

Some retirees believe tax planning ends once paychecks stop, but investments continue to play a major role in shaping tax outcomes. Selling assets, collecting dividends, or realizing capital gains all contribute to taxable income, and those elements can shift a tax situation quickly. Ignoring that reality can lead to unexpected bills that disrupt a carefully planned budget.

Different investments receive different tax treatment, and that opens the door for smarter decision-making. Holding tax-efficient investments in taxable accounts while keeping higher-turnover assets inside tax-advantaged accounts can reduce overall tax exposure. Even the timing of selling investments can make a difference, especially when it comes to capital gains.

Retirees who stay proactive with investment decisions often find more control over their tax situation. Harvesting losses to offset gains, choosing funds with lower turnover, and paying attention to distribution schedules all contribute to a more efficient plan. Every move adds up, and the cumulative effect can protect a significant portion of retirement income over time.

Keep More, Stress Less: The Retirement Tax Game Plan That Actually Works

Retirement doesn’t reward autopilot, especially when taxes sit quietly in the background shaping every financial decision. The difference between a smooth, comfortable retirement and one filled with financial stress often comes down to awareness and timing. Each of these mistakes stems from simple oversights, but each one also comes with a clear path to improvement that puts control back in your hands.

Which of these strategies feels like the easiest win right now, and what approach has worked best in managing taxes during retirement? Drop your thoughts or experiences in the comments and keep the conversation going.

You May Also Like…

Property Taxes Are Catching Homeowners Off Guard — Especially After Buying or Renovating

10 Retirement States That No Longer Cater to Retirees

Retirees Are Rethinking Second Homes — Why the “Snowbird Lifestyle” Is Getting Too Expensive

Waiting on Social Security? Why Thousands of Retirees Are Stuck in Payment Limbo Right Now

More Retirees Are Seeing Higher Medicare Costs—And It’s Tied to

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Retirement Tagged With: investing, IRA withdrawals, Personal Finance, Planning, retirees, retirement planning, retirement taxes, RMD rules, Social Security taxes, tax mistakes, tax strategies, taxes, Wealth management

  • « Previous Page
  • 1
  • …
  • 9
  • 10
  • 11
  • 12
  • 13
  • …
  • 24
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework