• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for stock market

Should You Switch Advisors Before The New Year Or Wait Until Markets Stabilize?

December 24, 2025 by Brandon Marcus Leave a Comment

Should You Switch Advisors Before The New Year Or Wait Until Markets Stabilize?
Image Source: Shutterstock.com

The year is winding down, your portfolio has taken you on a rollercoaster ride worthy of a theme park, and your financial advisor might feel more like a seatbelt than a co-pilot. The clock is ticking toward the new year, tax season is looming, and whispers of market volatility are swirling like confetti in the wind. You might be asking yourself: “Should I switch advisors now or wait until the dust settles?”

It’s not just a question about money—it’s about timing, strategy, and a dash of gut instinct. We’re about to break down everything you need to consider before making the leap.

Understanding Why Timing Matters More Than You Think

Timing is everything, especially when it comes to your finances. Changing advisors at the wrong moment can mean missed opportunities or unnecessary fees, while waiting too long could leave you stuck with strategies that no longer fit your goals. The end of the year is often full of tax implications, bonus payouts, and portfolio rebalancing that can complicate a switch. Advisors themselves often adjust their focus during this period, so you might not get the attention you deserve if you wait. Understanding market cycles, personal financial goals, and your advisor’s availability is crucial to making the right move.

Evaluating Your Current Advisor’s Performance Honestly

Before you even think about jumping ship, take a hard look at your current advisor. Are they actively managing your portfolio in alignment with your goals, or is it more autopilot than strategy? Communication matters—do they explain the “why” behind their decisions in a way you actually understand? Past performance isn’t a guarantee, but it’s a strong indicator of future reliability and attention. Sometimes, a frank conversation can clarify things more than a complete change ever could.

Analyzing Market Conditions And Their Effect On Decision Making

Volatility is the enemy of hesitation, but also the friend of opportunity if you play it right. If markets are swinging wildly, making a sudden change might result in buying or selling at less-than-ideal times. Conversely, waiting for “stability” that may never come could mean postponing beneficial strategic moves. It’s about balance: understanding risk tolerance, market trends, and how your investment horizon fits into both. Sometimes, the best move is proactive rather than reactive, and that requires careful analysis.

Understanding The Costs And Risks Of Switching Advisors

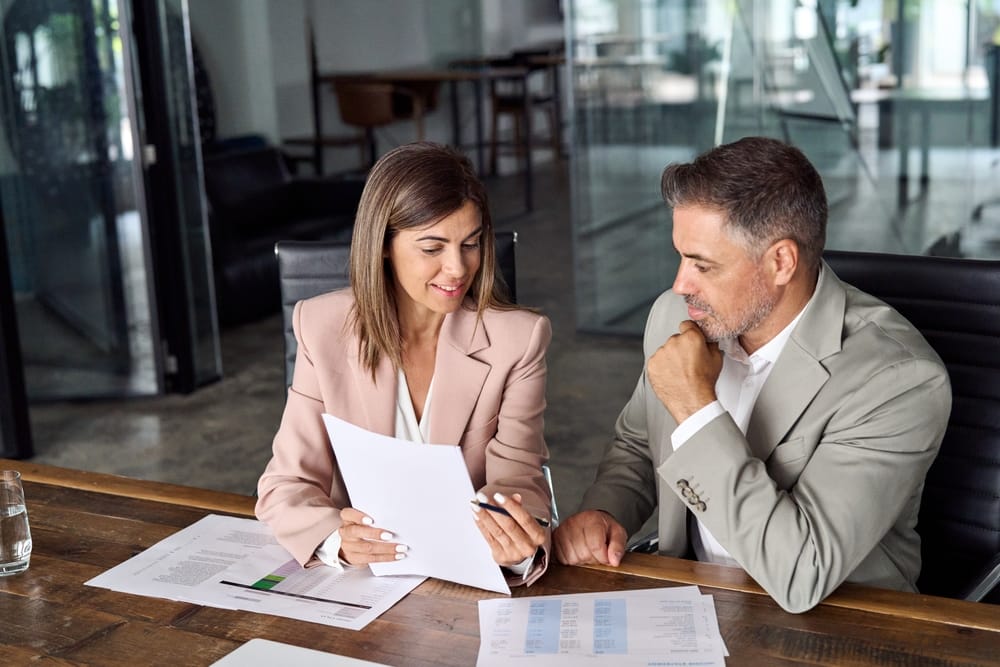
Switching advisors isn’t just a handshake and a new business card—it comes with potential costs and logistical headaches. Account transfers can take weeks, fees may apply, and untimely trades could lock in losses. Additionally, a new advisor will need time to understand your financial picture, which might temporarily slow down active management. The emotional cost of change shouldn’t be underestimated either; financial trust is built over time, not overnight. Knowing these risks allows you to plan your move strategically rather than impulsively.
Should You Switch Advisors Before The New Year Or Wait Until Markets Stabilize?
Image Source: Shutterstock.com

Identifying Red Flags That Suggest Immediate Action

Some situations demand swift action, no matter what the calendar or market says. If your advisor has consistently missed calls, failed to follow up, or executed strategies that contradict your objectives, it may be time to move. Ethical concerns, lack of transparency, or recurring mistakes can jeopardize both your financial health and peace of mind. Recognizing these red flags early prevents minor issues from snowballing into major regrets. Trust your instincts—they’re often grounded in valid observations.

Weighing The Advantages Of Waiting

Waiting can be a strategic choice rather than procrastination. A little patience can allow market volatility to settle, giving you a clearer view of trends and a stronger negotiating position with a new advisor. Year-end bonuses, tax-loss harvesting, and other seasonal financial maneuvers can also be optimized if you stay put temporarily. Waiting gives you time to vet potential new advisors carefully, ensuring you’re making a move based on analysis, not frustration. Sometimes, holding steady is just as proactive as switching.

Planning The Transition Smoothly And Strategically

If the decision is to move forward, planning is everything. Coordinate with both your current and future advisor to ensure accounts are transferred efficiently, assets are managed properly, and no investment opportunities are lost. Communicate clearly about your goals, risk tolerance, and expectations to avoid misalignment early on. Keep an eye on timing—transitions that overlap with critical market events may need extra caution. A structured approach transforms what could be a stressful ordeal into a seamless transition that strengthens your financial future.

Focusing On Your Long-Term Financial Goals

Ultimately, whether you switch now or later, the bigger picture should guide you. Short-term market fluctuations are noisy, but your long-term goals—retirement, homeownership, education funds—are what matter most. Ensure that any advisor you choose aligns with these objectives, communicates clearly, and provides guidance beyond simple portfolio management. Long-term success is rarely about perfect timing—it’s about consistency, strategy, and trust. Remember, advisors are tools, not crutches; the right one enhances your journey rather than dictates it.

Making The Choice That Fits You

Deciding whether to switch advisors before the new year or wait until markets stabilize is a personal strategy game. It requires evaluating your current advisor, understanding market dynamics, considering costs, and weighing emotional and logistical factors. There is no universal “perfect” time—it’s about aligning your move with your financial goals and comfort level. Take your time to analyze, consult, and plan, because your money deserves a thoughtful, strategic approach.

Let us know your thoughts or experiences in the comments section below—how have you approached advisor changes and market timing in the past?

You May Also Like…

Tech-Threat: 5 Ways AI Is Changing What Your Financial Advisor Should Be Doing for You

7 Strange Questions Financial Advisors Secretly Love to Answer

6 Subtle Signs Your Financial Advisor Should Be Fired Immediately

Could Your Real-Estate Holdings Lose Value Faster Than Your Advisor Expects?

11 Cryptocurrencies Your Advisor Doesn’t Want You Researching Alone

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Financial Advisor Tagged With: advice, financial advice, financial advisor, invest, investing, investing advice, market conditions, Money, money advice, money issues, stock market

Market Turn: 4 Signals That the Next Bull Cycle Could Look Different

December 24, 2025 by Brandon Marcus Leave a Comment

Market Turn: 4 Signals That the Next Bull Cycle Could Look Different
Image Source: Shutterstock.com

The stock market has always been a stage for drama, spectacle, and surprises, but right now, the excitement is dialed up to eleven. Investors are buzzing with curiosity, strategists are sharpening their pencils, and the financial world is bracing itself for the next big bull cycle. Unlike past rallies that followed predictable patterns, this one seems poised to rewrite the rulebook. From tech innovations reshaping industries to global economic shifts challenging old assumptions, the next surge could feel completely unfamiliar.

For anyone with skin in the game, knowing the signs early might mean the difference between riding the wave and getting caught in the undertow.

1. Tech Disruption Is Accelerating Market Dynamics

Technology has always been a market mover, but today it’s almost like the rules themselves are being rewritten in real-time. Artificial intelligence, blockchain applications, and quantum computing aren’t just buzzwords—they’re becoming integral drivers of market behavior. Companies that adapt quickly are seeing unprecedented growth, while laggards face rapid obsolescence. This acceleration makes predicting traditional market cycles trickier, as old patterns may no longer hold. Investors need to pay attention to innovation pipelines, not just quarterly earnings, to spot where real momentum is forming.

2. Global Capital Flows Are Shifting

Money doesn’t stay put for long, and the paths it takes are signaling change. Emerging markets are attracting attention in sectors that were previously dominated by developed economies. Sovereign wealth funds and institutional investors are diversifying aggressively, spreading capital in ways that challenge historical norms. Currency fluctuations, geopolitical tensions, and trade realignments all create unexpected ripples that affect stock valuations. Understanding where money is moving, and why, will be critical for anticipating which sectors will lead the next bull cycle.

3. Retail Investors Are Changing the Game

Forget the old image of Wall Street as a closed club; retail investors now wield more influence than ever. Social media platforms, trading apps, and real-time analytics have given everyday traders access to information that used to be reserved for professionals. This democratization of market participation creates volatility, but also opportunity, as coordinated moves by retail investors can send formerly overlooked stocks soaring. Analysts now have to factor in behavior patterns and sentiment indicators alongside traditional fundamentals. Ignoring the impact of retail energy could leave investors flat-footed in the next rally.

Market Turn: 4 Signals That the Next Bull Cycle Could Look Different
Image Source: Shutterstock.com

4. ESG and Sustainability Are Driving Investment Decisions

Environmental, social, and governance considerations aren’t just ethical talking points—they’re shaping real investment flows. Corporations that excel in ESG metrics are attracting long-term capital, while those lagging behind are facing higher scrutiny and risk premiums. The rise of green finance, sustainable bonds, and socially responsible ETFs is creating new winners and losers in unexpected places. Investors who factor ESG into their strategies are likely to see advantages in sectors that previously wouldn’t have been in focus. The next bull market could be as much about values-driven performance as it is about profits and earnings growth.

What This Means For Investors

The next bull cycle is likely to look different from what many are used to, blending technology, global capital movements, retail influence, and ESG factors in ways that make old playbooks less reliable. For savvy investors, that means staying agile, curious, and ready to adapt at a moment’s notice. Market signals are subtle but powerful, offering clues for those willing to read between the lines. Everyone’s experience and approach will vary, and your insights could provide valuable perspective for others navigating this evolving landscape.

Leave your thoughts, experiences, or perspectives in the comments section below—we’d love to hear how you’re preparing for the next wave.

You May Also Like…

Asset Migration: 5 Emerging Market Trends Retirees Should Know Before January

Why Young People Should Invest In The Stock Market

These 5 Stocks Only Perform Well When The Entire Stock Market Does

4 Bold Predictions Regarding the Future of the Stock Market

7 Stock Market Myths That Cost Beginner Investors Their Life Savings


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Investing Tagged With: bull market, capital flows, invest, investing, investing news, Investing Tips, retail, retail industry, retail investing, stock market, stock market strategy, stock market traps

Risk Exposure: 9 Stress Tests Every Soon-to-Retire Investor Should Run

December 23, 2025 by Brandon Marcus Leave a Comment

Risk Exposure: 9 Stress Tests Every Soon-to-Retire Investor Should Run
Image Source: Shutterstock.com

Retirement is supposed to be the golden era of life—lazy mornings, afternoon golf, and endless vacation days. But for many soon-to-retire investors, the reality is a bit more like walking a tightrope over a pit of snapping alligators. One wrong step with your savings, and suddenly the dream of sipping margaritas on a beach in Costa Rica turns into a nightmare of budget spreadsheets and frozen dinners.

The truth is, retirement is the ultimate financial test, and your portfolio needs to be ready for anything. That’s why running “stress tests” isn’t just smart—it’s exhilarating in the way a rollercoaster feels right before the drop.

1. Market Crash Simulation

Every investor knows that markets go up, but few are prepared for the sudden drops. Run a scenario where the stock market loses 30–40% in a matter of months and see how your portfolio holds up. This test will reveal whether you have enough defensive assets, like bonds or cash, to ride out the storm without panicking. Don’t forget to calculate how long it would take to recover from such a downturn before you start withdrawing funds. Knowing your portfolio’s breaking point can turn fear into strategy.

2. Inflation Heat Test

Inflation may not roar like a market crash, but it silently erodes purchasing power over time. Simulate a scenario where inflation hits 5–7% annually for a decade and see if your investments keep up. This helps determine whether your retirement income will maintain your desired lifestyle or gradually shrink. Consider the impact on both fixed income and discretionary spending. Planning ahead can prevent those surprise moments when a latte costs twice as much as it did last year.

3. Interest Rate Shock

Interest rate changes are like sneaky plot twists in a financial thriller—they can change everything in an instant. Stress test your bonds and fixed-income investments against a rapid rise or fall in rates. This will show whether your portfolio is vulnerable to losses in bond value or if you can capitalize on higher yields. Pay attention to mortgage rates if you carry debt; sudden spikes could strain your cash flow. Being aware of rate risk can prevent your dream retirement from turning into a financial headache.

4. Longevity Risk Scan

You might be planning for 20 years of retirement, but what if you live to 95—or even 100? Longevity risk is the chance your money will run out before you do. Run a test that stretches your retirement funds over a longer-than-expected lifespan. Factor in healthcare costs, lifestyle inflation, and unexpected expenses. Preparing for longevity ensures you won’t outlive your portfolio and end up making sacrifices you never anticipated.

5. Healthcare Catastrophe Drill

Medical expenses are the sneaky villains of retirement planning. Conduct a scenario where unexpected medical costs—like surgeries, chronic illness management, or long-term care—skyrocket. Check whether your insurance and emergency savings are sufficient to cover these shocks. Understanding your exposure helps you allocate funds without sacrificing other parts of your lifestyle. A robust plan here could mean the difference between comfort and financial panic in your golden years.

Risk Exposure: 9 Stress Tests Every Soon-to-Retire Investor Should Run
Image Source: Shutterstock.com

6. Withdrawal Rate Test

The classic 4% rule isn’t one-size-fits-all, especially in volatile markets. Stress test various withdrawal rates and see how they impact your portfolio over 30 years. Even a small change in the early years of retirement can dramatically affect long-term sustainability. This test highlights the importance of flexibility and contingency planning. Adjusting your withdrawals proactively can prevent catastrophic depletion of your nest egg.

7. Sequence Of Returns Analysis

Timing is everything in retirement—especially when it comes to market returns. Simulate a scenario where poor market performance occurs early in retirement versus later. This reveals how vulnerable your portfolio is to the “sequence of returns risk.” It’s not just about average returns, but the order in which they happen. Being aware of this risk can guide your investment strategy and withdrawal plan for smoother sailing.

8. Currency And Global Exposure Check

Even if you live comfortably in one country, global markets impact your investments. Stress test your portfolio against currency fluctuations and international economic shocks. This can affect foreign stocks, bonds, and even real estate holdings. Diversifying geographically can protect against sudden collapses in a single economy. Understanding your exposure globally ensures your retirement plan isn’t derailed by events halfway across the world.

9. Lifestyle Shock Test

Finally, stress-test your lifestyle assumptions. What if travel costs double? What if you decide to help family members financially? Simulate various lifestyle shocks and see how your portfolio responds. This exercise ensures your retirement plan is aligned with real-world possibilities, not just idealized dreams. Financial flexibility often comes from anticipating the unexpected, not hoping it never happens.

Your Turn To Weigh In

Retirement stress testing isn’t just a nerdy exercise for financial advisors—it’s a practical, empowering tool for anyone about to take the plunge into the next chapter of life. By running these nine stress tests, you can uncover hidden risks, plan for surprises, and sleep easier knowing your portfolio is battle-tested.

Have you tried any of these stress tests, or do you have your own methods for testing your financial resilience? Drop your thoughts or experiences in the comments section below—we’d love to hear what worked, what didn’t, and what gave you peace of mind.

You May Also Like…

Savings Sprint: 9 Ways to Catch Up on Retirement Savings Before December Ends

Debt Overhang: 8 Ways Carrying Debt Into Retirement Can Undermine Your Progress

Is $8,000 a Year a Sound “Peace of Mind” Investment for Retirement

Can You Afford to Retire Comfortably? Discover How With These Investment Strategies

A Guide to Gold Investment for Retirement Planning


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Investing Tagged With: healthcare, Inflation, interest rate, invest, investing, investing risks, Investor, investors, Longevity, market, market risk, retire, retiree, retirees, Retirement, retirement account, retirement investing, retirement savings, risk, stock market

Market Rust: 4 Aging Industries That Might Surprise Investors Next Cycle

December 19, 2025 by Brandon Marcus Leave a Comment

Market Rust: 4 Aging Industries That Might Surprise Investors Next Cycle
Image Source: Shutterstock.com

The market has a way of keeping us on our toes. One year, tech stocks are strutting like rockstars, and the next, everyone’s scrambling to find the next big thing. But while investors chase shiny new sectors, some of the oldest industries quietly flex muscles that could make them the dark horses of the next market cycle. Don’t be fooled by dust-covered balance sheets or decades-old business models—these “aging” industries might just have a second wind that surprises even the savviest traders.

Fasten your seatbelt, because the sectors we’re about to explore could challenge everything you think you know about mature markets.

1. Energy: Traditional Players With A Green Twist

Oil and gas have been around longer than most modern investors have had portfolios. Yet today, major energy companies are pivoting faster than a Formula 1 car in a hairpin turn. Investments in renewable energy, carbon capture technology, and even hydrogen initiatives are transforming these old-school giants into hybrid powerhouses. Analysts are starting to see revenue streams that didn’t exist five years ago, from solar farms to electric vehicle charging networks. Betting against these companies could mean missing out on a resurgence fueled by both demand and innovation.

2. Utilities: Boring On The Surface, Explosive Underneath

Utilities might not be the life of the Wall Street party, but they’ve got stability and hidden growth opportunities that scream “long-term play.” With the electrification of everything from cars to homes, the need for smart grids, renewable integration, and digital infrastructure is skyrocketing. Companies once considered stodgy are investing billions into technology that modernizes old infrastructure while generating predictable revenue. Investors looking for consistent returns might be surprised to find volatility working in their favor here. As the world leans into sustainability, these companies are quietly positioning themselves as indispensable.

3. Tobacco: Reinventing The Legacy

Tobacco has a checkered history, but the industry isn’t just surviving—it’s evolving. Cigarettes may be declining in popularity, but e-cigarettes, heat-not-burn devices, and alternative nicotine products are gaining traction globally. Forward-thinking companies are using R&D to pivot their offerings, appealing to a younger demographic that still craves nicotine without the same risks. Regulatory hurdles remain, but innovation has opened doors for new revenue streams that weren’t imaginable a decade ago. Savvy investors who overlook this sector might be surprised by its resilience and adaptive strategies.

4. Retail: Classic Giants Embracing Digital

Brick-and-mortar retail often gets dismissed as “dying,” but some old-school giants are rewriting the rules of engagement. By blending physical stores with digital experiences, subscription models, and direct-to-consumer strategies, they’re proving adaptability is alive and well. AI-driven personalization and logistics optimization are transforming inventory and customer experience, giving long-standing brands a competitive edge. These companies have decades of customer loyalty and brand recognition—intangible assets that newer e-commerce players can’t easily replicate. Investors who tune out retail might miss the comeback story of the next cycle.

Market Rust: 4 Aging Industries That Might Surprise Investors Next Cycle
Image Source: Shutterstock.com

Rust Can Shine

The idea that old industries are obsolete is tempting, but reality paints a more nuanced picture. Energy, utilities, tobacco, and retail each have the potential to surprise investors who are willing to look beyond surface-level narratives. Innovation isn’t limited to startups or flashy tech IPOs—sometimes it thrives quietly in sectors that have weathered decades of ups and downs. Next market cycle, the “aging” players might just outperform expectations, leaving many scratching their heads. Investors, weigh your options, do your homework, and keep an eye on these sectors—you might be pleasantly astonished.

We’d love to hear your thoughts and experiences with these industries in the comments section below.

You May Also Like…

Market Blindspot: 8 Global Shifts Investors Aren’t Watching But Should

Why Investing Apps Will Remain Popular in 2026

5 Lessons Young People Should Know About Investing

7 Reasons You Should Be Collecting Cars as Alternative Investments

8 Bold Strategies for Investing During Periods of High Inflation


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Investing Tagged With: energy investments, invest, investing, Investment, investments, investors, retail investments, stock market, tobacco investments, utility investments

How To Start Your 2026 Investing Journey With A Bang

December 18, 2025 by Brandon Marcus Leave a Comment

Here Is How To How To Start Your 2026 Investing Journey With A Bang
Image Source: Shutterstock.com

2026 is knocking, and if your wallet isn’t ready for lift-off, you’re about to miss the rocket. Investing isn’t just for Wall Street wizards or spreadsheet nerds—it’s for anyone ready to take their financial future by the horns and ride it into prosperity. This year, the market is full of opportunities, quirky trends, and unexpected twists that could make your first step feel like a carnival ride. Whether you’re dipping your toes or cannonballing into investing, the key is knowing where to start, how to pivot, and how to make your money work as hard as you do.

Today, we’re about to turbocharge your 2026 investing journey with strategies, tips, and a sprinkle of excitement.

1. Set Clear Goals Before You Dive In

Before you touch a single stock or crypto coin, take a moment to think about what you actually want. Are you aiming for a future nest egg, early retirement, or the thrill of learning about financial markets? Clear goals act like a GPS—they prevent you from wandering into risky territory without knowing it. Break your goals into bite-sized steps that feel achievable but also ambitious. Remember, even small, consistent wins can snowball into a major financial victory over time.

2. Understand Your Risk Appetite

Investing isn’t a one-size-fits-all adventure, and understanding your risk tolerance is like choosing the right rollercoaster. Some investors love the thrill of volatile markets, while others prefer the slow, steady climb of bonds or index funds. Mix in your financial situation, age, and personal comfort to craft a strategy that suits you. Overestimating your risk appetite can lead to stress-induced mistakes, while underestimating it may leave money on the table. A balanced approach often leads to both peace of mind and growth.

3. Educate Yourself Like A Pro

Knowledge is the ultimate superpower in investing, and it doesn’t require a finance degree. Podcasts, online courses, books, and even newsletters can give you insights that keep you ahead of trends. The key is to learn enough to make informed decisions but not get paralyzed by analysis. Follow companies, sectors, or asset classes that interest you—passion makes learning fun. Remember, investing isn’t about memorizing charts; it’s about understanding patterns, risks, and opportunities.

4. Choose Your Investment Platform Wisely

Not all investing platforms are created equal, and your choice can dramatically affect your journey. Look for low fees, easy-to-use interfaces, and strong customer support. Some platforms offer robo-advisors to guide beginners, while others provide advanced tools for DIY enthusiasts. Don’t rush this decision—test out demo accounts if possible and read user reviews. Your platform should feel like a partner, not a confusing obstacle.

Here Is How To How To Start Your 2026 Investing Journey With A Bang
Image Source: Shutterstock.com

5. Diversify, Diversify, Diversify

No one ever made it big by putting all their eggs in a single basket. Diversification spreads risk across different assets, industries, and even geographies. A mix of stocks, bonds, ETFs, and maybe a little crypto can protect you from market swings.

Think of it as building a financial team where each player has unique strengths. The more balanced your portfolio, the more you can weather unpredictable market storms.

6. Keep Emotions Out Of The Equation

Investing can be emotional, but letting fear or greed drive decisions is a fast track to regret. Markets fluctuate, headlines scream, and social media feeds exaggerate trends daily. Stick to your strategy and remember why you started in the first place. Setting rules in advance—like when to buy, sell, or hold—can shield you from impulsive moves. Emotional discipline is often more valuable than any single stock tip you could ever get.

7. Automate Your Investments

Automation is the secret sauce for consistent growth without the drama. Setting up automatic contributions to retirement accounts, index funds, or other investments makes saving effortless. Dollar-cost averaging ensures you buy more when prices are low and less when prices are high. Automation also reduces the temptation to “time the market,” which is usually a recipe for stress. Think of it as a financial autopilot that keeps your journey on track while you focus on life.

8. Monitor And Adjust Regularly

Even the best-laid investment plans need occasional tuning. Set a schedule to review your portfolio—quarterly or semi-annually is a good start. Track performance, rebalance if one asset class grows too dominant, and ensure your investments still align with your goals. Don’t overreact to short-term market swings, but don’t ignore them either. Staying engaged ensures your money works as hard as you do and adapts to changing conditions.

9. Take Advantage Of Tax-Efficient Strategies

Taxes can quietly eat away at your returns if you’re not careful. Utilize tax-advantaged accounts like IRAs, 401(k)s, or HSAs where possible. Consider strategies like tax-loss harvesting to offset gains and keep more money in your pocket. Understanding the basics of investment taxation can make a surprisingly big difference over time. Smart tax planning is like giving your investments a turbo boost without touching the market.

10. Stay Curious And Have Fun

Investing isn’t just about money—it’s about learning, experimenting, and watching your knowledge grow. Explore new sectors, read about global trends, or test out small amounts in emerging markets. Celebrate your milestones, no matter how small, and treat mistakes as lessons rather than disasters. The more curious you remain, the more enjoyable the journey becomes. A little fun goes a long way in building long-term wealth.

Your 2026 Investing Adventure Awaits

2026 is brimming with opportunities, and starting your investing journey now can set the stage for years of financial growth. The key is to combine clear goals, disciplined strategy, ongoing education, and a bit of adventurous spirit. Take these tips, experiment wisely, and watch your portfolio evolve into something that reflects both your ambition and your smart choices. Your journey is unique, and every step you take counts toward building a strong financial foundation.

Let us know your thoughts or experiences in the comments section below.

You May Also Like…

Why Investing Apps Will Remain Popular in 2026

Market Blindspot: 8 Global Shifts Investors Aren’t Watching But Should

Why Young People Should Invest In The Stock Market

These 5 Stocks Only Perform Well When The Entire Stock Market Does

Regulation Alert: 9 Proposed Rules Every Investor Should Watch in 2026


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Investing Tagged With: 2026, bear markets, diversify, financial choices, financial goals, invest, investing, investing journey, Investment, investment platforms, investment portfolio, investments, Money, money issues, stock market

Market Blindspot: 8 Global Shifts Investors Aren’t Watching But Should

December 16, 2025 by Brandon Marcus Leave a Comment

These Are 8 Global Shifts Investors Aren’t Watching But Should
Image Source: Shutterstock.com

The markets love a good headline, but they’re even better at ignoring the slow-burning stories that actually change the future. While investors obsess over interest rate whispers, earnings calls, and daily price swings, enormous global shifts are quietly reshaping how money will move for decades. These aren’t flashy trends you’ll see trending on financial TV, yet they influence labor, capital, innovation, and risk in ways most portfolios aren’t prepared for.

The real danger isn’t volatility—it’s complacency wrapped in familiarity. If investing is about anticipating tomorrow rather than explaining yesterday, these overlooked forces deserve a front-row seat in your thinking.

1. Demographic Collapse In Developed Economies

Across much of the developed world, populations are aging faster than most financial models account for. Shrinking workforces in countries like Japan, Germany, and South Korea are already pressuring productivity, pension systems, and consumer demand. Fewer workers supporting more retirees changes everything from tax policy to corporate margins. Immigration alone cannot fully offset these trends, especially as political resistance grows. Investors ignoring demographics risk misunderstanding long-term growth potential across entire regions.

2. The Silent Fragmentation Of Global Trade

Globalization isn’t ending, but it is quietly fracturing into regional alliances. Supply chains are being redesigned for resilience and politics rather than pure efficiency, pushing costs higher and timelines longer. “Friend-shoring” and “near-shoring” are becoming strategic priorities for governments and corporations alike. This shift favors logistics, infrastructure, and automation while challenging companies built on razor-thin global margins. Investors who still assume frictionless global trade may be pricing assets on outdated assumptions.

3. Energy Transition Bottlenecks Nobody Is Pricing In

Clean energy headlines focus on breakthroughs, but the real story lies in constraints. Mining capacity for copper, lithium, and rare earths is struggling to keep up with demand forecasts. Grid infrastructure in many countries is outdated and unprepared for decentralized energy generation. These bottlenecks create volatility, delays, and unexpected winners and losers across industries. Betting on energy transition themes without understanding these chokepoints can lead to serious misallocations.

4. The Rise Of State Capitalism In Emerging Markets

Many emerging economies are blending market systems with heavier government control over strategic industries. State-backed champions in technology, energy, and finance are reshaping competition on a global scale. This model prioritizes national goals over shareholder returns, often in subtle ways. Traditional valuation metrics struggle to capture political influence and policy risk. Investors chasing emerging market growth without factoring in state power may be underestimating long-term volatility.

5. Labor Power’s Quiet Comeback

For decades, labor was the weakest link in economic negotiations, but that balance is shifting. Worker shortages, unionization efforts, and demographic trends are giving employees more leverage across sectors. Higher wages and better benefits are becoming structural, not temporary, costs for businesses. This pressures profit margins while also boosting consumer spending power in uneven ways. Investors who assume labor costs will normalize may be ignoring a fundamental reset.

6. Data Nationalism And The Splintering Internet

Data is now treated as a strategic national asset rather than a neutral commodity. Governments are imposing stricter rules on where data can be stored, processed, and transferred. This is fragmenting the internet into regulatory zones with different standards and costs. Tech companies face rising compliance expenses and reduced scalability across borders. Investors valuing digital platforms as universally scalable machines may need to rethink growth expectations.

7. Climate Risk Repricing Real Assets

Climate change isn’t just an environmental issue—it’s a valuation issue. Insurance costs are soaring in high-risk regions, altering real estate economics and municipal finances. Infrastructure built for past climate patterns is becoming more expensive to maintain and insure. Some assets may become stranded not by regulation, but by physics. Investors who ignore climate exposure risk sudden repricing events that models failed to anticipate.

These Are 8 Global Shifts Investors Aren’t Watching But Should
Image Source: Shutterstock.com

8. The Global Savings Shift Away From The West

Capital flows are slowly rebalancing as wealth accumulates outside traditional Western centers. Sovereign funds and private capital from Asia and the Middle East are increasingly shaping global markets. These investors often have longer time horizons and different strategic priorities than Western institutions. Their influence effects everything from asset pricing to corporate governance norms. Ignoring who controls capital tomorrow can lead to blind spots in market behavior today.

Seeing What Others Miss

Markets reward attention, patience, and the willingness to question comfortable narratives. These global shifts aren’t predictions; they’re already happening in plain sight, quietly reshaping risk and opportunity. The biggest investing mistakes rarely come from being wrong, but from not noticing what matters until it’s obvious to everyone else.

Staying curious and adaptable is no longer optional in a world moving this fast. Let us know your thoughts, experiences, or observations in the comments section below.

You May Also Like…

Is Your Retirement Timeline Still Safe If The Market Drops Again Before New Year’s Eve?

12 Uncommon Assets That Provide True Diversification Globally

10 Amazing Opportunities in Global Real Estate Markets Now

Why Young People Should Invest In The Stock Market

These 5 Stocks Only Perform Well When The Entire Stock Market Does


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Investing Tagged With: alternative investments, beginner investing, beginning investing, beginning investors, capitalism, global markets, global trade, invest, investments, investors, stock market

Is Your Retirement Timeline Still Safe If The Market Drops Again Before New Year’s Eve?

December 14, 2025 by Brandon Marcus Leave a Comment

Is Your Retirement Timeline Still Safe If The Market Drops Again Before New Year’s Eve?
Image Source: Shutterstock.com

The clock is ticking toward the end of the year, and suddenly, your retirement plan feels a little more like a roller coaster than a steady climb. Stocks are jittery, headlines are dramatic, and every market dip makes you question whether your carefully plotted timeline is still realistic. For anyone relying on investments to fund their golden years, this is the kind of stress that can sneak up faster than holiday shopping lines.

But before panic sets in, it’s worth taking a step back and examining what a market drop really means for your retirement—and what you can actually do about it. Let’s discuss why short-term swings don’t always spell disaster and how you can keep your financial goals on track.

Market Fluctuations Are More Normal Than You Think

Volatility is the stock market’s middle name. Daily swings, sudden drops, and unexpected rallies happen more often than most investors realize. Even when news cycles make it feel like the sky is falling, history shows that markets tend to recover over time. If your retirement horizon is years or decades away, a brief dip isn’t the same as a permanent setback. Understanding that ups and downs are standard can reduce stress and prevent impulsive decisions that might hurt your long-term plan.

Your Timeline Is A Buffer, Not A Deadline

One of the biggest mistakes people make is thinking their retirement date is carved in stone. In reality, your timeline is flexible, and market drops are part of the financial landscape. Many advisors recommend keeping a buffer—both in years and in savings—to weather periods of low returns. If the market drops before New Year’s Eve, it may slow your growth temporarily, but it rarely derails a carefully structured plan. Adjusting your strategy without abandoning your timeline is often enough to keep your retirement goals intact.

Diversification Can Act As A Safety Net

Relying on a single type of investment is risky, especially when the market dips unexpectedly. Diversification—spreading money across stocks, bonds, and other assets—reduces the impact of sudden declines. Balanced portfolios often smooth out volatility, making market drops less painful. Even if one sector tanks, others can help stabilize your overall growth. This principle is why long-term investors rarely need to hit the panic button during temporary downturns.

Emotional Reactions Can Be Costly

Watching numbers plummet on a screen can trigger fear faster than almost anything else. Emotional investing—selling at the bottom or chasing hot trends—often causes more damage than the market itself. Successful retirement planning requires discipline and perspective, not reactionary moves. Understanding that temporary dips are a normal part of investing helps prevent knee-jerk decisions. Keeping calm and reviewing your plan strategically is almost always more beneficial than acting out of panic.

Emergency Funds And Income Streams Are Your Friends

Having an emergency fund isn’t just for unexpected car repairs or medical bills. It can also be a lifeline if the market takes a nosedive and your investments temporarily underperform. Knowing that you have liquid assets to cover immediate needs removes the pressure to sell investments at the worst possible time. Additionally, other income streams, such as pensions or part-time work, create stability regardless of market fluctuations. These safety nets allow you to let your portfolio recover while still maintaining your lifestyle.

Is Your Retirement Timeline Still Safe If The Market Drops Again Before New Year’s Eve?
Image Source: Shutterstock.com

Reviewing Your Asset Allocation Matters

Your retirement investments shouldn’t be “set it and forget it.” Over time, shifts in the market can cause your portfolio to drift away from your target allocation. Regular reviews help you ensure that your risk level aligns with your timeline and comfort zone. If a market drop causes your stocks to underperform, rebalancing can restore balance and reduce future risk. Staying proactive instead of reactive is key to maintaining both growth and peace of mind.

Long-Term Growth Often Outpaces Short-Term Worries

Even the most dramatic end-of-year drops tend to be smoothed out over time. Historically, markets have recovered from downturns and reached new highs, rewarding patient investors. If your retirement is a decade or more away, today’s dip is a small blip in the larger trajectory. Focusing on consistent contributions and staying invested often beats attempting to time the market. The real advantage comes from compounding returns and letting time do the heavy lifting.

Professional Guidance Can Reduce Anxiety

Working with a financial advisor isn’t just about making money—it’s about managing stress and creating a roadmap. Advisors can provide perspective, suggest adjustments, and help you stick to your plan during turbulent times. Knowing that someone is monitoring your strategy and making informed recommendations gives peace of mind that numbers alone can’t provide. Even brief consultations can help you understand whether a drop is significant or just noise. Professional insight ensures that fear doesn’t drive your financial decisions.

Stay Calm, Stay On Track

Short-term market drops before New Year’s Eve may feel alarming, but they don’t automatically derail your retirement plan. Understanding volatility, keeping your timeline flexible, maintaining diversified investments, and leaning on safety nets can keep your goals intact. Emotional reactions are rarely helpful, and focusing on long-term growth usually wins over panic.

Have you ever faced a market drop that shook your confidence? Share your experiences, strategies, or lessons learned in the comments section below.

You May Also Like…

Retirement Redflag: 6 Withdrawal Moves That Could Drain Your Nest Egg Fast

Calculate Your True Retirement Number Using Our Exclusive Online Tool

New Year, New Credit Score: Tips to Improve Your Financial Health

Why Do Families Pretend They Can Afford the Holidays

Why Must I Pay a Percentage of My Assets Even When Markets Fall Hard?


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Retirement Tagged With: Asset Allocation, beginning investors, diversify, emergency funds, Emotional Spending, Holiday Savings, holiday spending, Holidays, income streams, investing, investments, investors, market fluctuations, multiple income streams, reitire, retire, retiree, retirees, Retirement, retirement savings, retirement timeline, saving money, stock market

Charity Strategy: 9 Giving Moves That Bring Tax Benefits Many People Ignore

December 14, 2025 by Brandon Marcus Leave a Comment

There Are Giving Moves That Bring Tax Benefits Many People Ignore
Image Source: Shutterstock.com

Giving to charity isn’t just about making the world a better place—it can also be a surprisingly smart move for your wallet. Many people donate generously without realizing that the way they give could unlock tax benefits that often go unnoticed. With a little strategy, your generosity can be amplified: helping others while potentially saving yourself money.

Understanding the nuances of charitable giving doesn’t require a finance degree—just some savvy planning and a willingness to think creatively. Let’s dig into nine giving moves that can transform both your impact and your tax situation.

1. Donate Appreciated Stock Instead Of Cash

Instead of writing a check, consider giving stocks or other appreciated assets to charity. If you’ve held the stock for over a year, you can deduct its full market value and avoid paying capital gains taxes. This means your contribution could be worth more than if you sold the stock first and donated the cash. Many people overlook this option simply because it feels more complicated than it is. With a quick conversation with your broker or financial advisor, this move can be surprisingly straightforward and highly rewarding.

2. Bundle Smaller Gifts Into One Year

Instead of giving smaller amounts over several years, you can “bunch” donations into a single tax year. By concentrating your charitable contributions, you may exceed the standard deduction threshold, allowing you to itemize and maximize your tax benefits. This strategy works especially well for families or individuals who alternate between standard and itemized deductions each year. Planning ahead and timing your donations can increase both the financial and emotional payoff. Many people give steadily but miss out on the tax advantage of bundling, making this an easy win.

3. Use Donor-Advised Funds

Donor-advised funds, or DAFs, are like a personal giving account that lets you donate now and distribute later. Contributions to a DAF are immediately tax-deductible, even if the actual charitable grants happen years down the line. This flexibility allows you to manage your giving strategically while potentially benefiting from tax advantages in high-income years. It’s also a simple way to involve family members in philanthropy. Savvy donors often forget this tool exists, even though it’s one of the most effective ways to multiply impact.

4. Give Through Your IRA

If you’re over 70½, making charitable donations directly from your IRA can be a tax-smart move. Known as a Qualified Charitable Distribution (QCD), these gifts count toward your required minimum distribution without being taxed as income. This can reduce your taxable income while supporting causes you care about. Many retirees are unaware that this option exists, leaving potential savings on the table. A quick check with your IRA custodian can clarify the rules and make this move painless and beneficial.

5. Donate Items Instead Of Money

Giving clothing, household items, or even vehicles can provide significant tax deductions if properly documented. Many people undervalue or forget the tax implications of donating tangible goods.

By keeping accurate records and obtaining receipts, you can claim deductions based on fair market value. It’s a win-win: your items help someone in need and may reduce your tax bill. The key is organization—without proper documentation, the deduction may not be allowed, so tracking is essential.

There Are Giving Moves That Bring Tax Benefits Many People Ignore
Image Source: Shutterstock.com

6. Pay Tuition Or Medical Expenses For Someone Through A Charity

Certain charitable organizations allow you to cover educational or medical costs for individuals directly through the charity. These contributions may qualify for tax deductions while making a big impact in someone’s life. Many people don’t realize that donations to these programs can be deductible just like traditional cash gifts. The effect is twofold: you provide immediate support and potentially lower your tax liability. Researching qualified organizations that offer these programs can unlock a creative giving strategy.

7. Donate From Your Business

Business owners have a unique opportunity to make charitable giving work for both philanthropy and taxes. Contributions from a business can often be deducted as business expenses, lowering taxable income. This works whether you’re a sole proprietor, partner, or run a corporation, though the rules differ slightly. By integrating charitable giving into your business strategy, you can amplify both your social impact and your financial efficiency. Entrepreneurs sometimes overlook this, treating personal and business giving separately, when combining them could be highly advantageous.

8. Give Appreciated Real Estate

Just like stocks, real estate can be donated to charity in ways that maximize deductions and minimize capital gains taxes. If you’ve held a property for years and its value has appreciated, donating it instead of selling can yield significant tax benefits. It also frees you from ongoing maintenance or management responsibilities. Charities often welcome such gifts because they can sell the property to fund their programs. Many donors assume real estate donations are complicated, but with proper guidance, it can be surprisingly straightforward and impactful.

9. Take Advantage Of State-Level Tax Credits

Federal deductions are well-known, but state-level incentives are frequently ignored. Some states offer tax credits for donations to specific local charities or programs, effectively reducing your state tax bill directly. These credits can sometimes be as valuable—or more valuable—than federal deductions. The challenge is knowing which programs qualify, so research is essential. By exploring state-level incentives, you can unlock extra value from your generosity that many donors overlook entirely.

Maximize Your Giving While Saving

Charitable giving doesn’t have to be purely altruistic—it can be strategically smart as well. From donating stocks and real estate to taking advantage of donor-advised funds and state tax credits, there are many opportunities to combine impact with financial savvy. The key is awareness and planning, ensuring your generosity goes further both for the causes you care about and for your own tax benefits.

Have you used any of these strategies, or do you have a favorite creative way to give? Make sure that you share your experiences, tips, or stories in the comments section below.

You May Also Like…

7 Unexpected Things Smart People Leave to Charity Instead of Family

8 Surprising Reasons People Secretly Hate Donating to Charity

10 Times the Rich Used Charities to Hide Their Wealth

5 Tax Benefits That Disappear if You Downsize Too Late

Can Your Taxes Be Cut In Half By You Simply Incorporating Your Name?


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: charitable giving Tagged With: charitable contributions, Charitable donation, Charitable Donations, charitable giving, Charitable Giving Strategies, charitable tax break, charities, charity, charity donations, donated stocks, donating, donations, Stock, stock market, stocks, tax benefits, tax breaks, taxes

Behavior Risk: 4 Psychological Traps Mid-lifers Fall Into When Markets Turn Choppy

December 13, 2025 by Brandon Marcus Leave a Comment

Here Are Psychological Traps Mid-lifers Fall Into When Markets Turn Choppy
Image Source: Shutterstock.com

Markets are unpredictable.

One moment, everything feels like a smooth ride toward retirement bliss; the next, your portfolio looks like a rollercoaster with no brakes. For mid-lifers, who are juggling mortgages, college funds, and plans for the next chapter of life, market turbulence can trigger reactions that aren’t always rational.

What many investors don’t realize is that our brains have quirks—psychological traps—that can make us act in ways that hurt long-term financial goals. Understanding these behaviors can mean the difference between steady growth and emotional whiplash.

1. Overconfidence In Times Of Stability

It’s easy to feel invincible when markets are steadily climbing. Mid-lifers often assume that past success guarantees future gains, which can lead to excessive risk-taking. Overconfidence can manifest as ignoring diversification, investing too heavily in a single stock, or chasing returns without considering downside. The danger is that when the market inevitably stumbles, the shock can be brutal, both financially and emotionally. Recognizing overconfidence as a trap allows investors to reassess risk realistically and maintain balance.

2. Loss Aversion That Freezes Decision Making

Humans are wired to hate losses more than we enjoy gains, and this tendency intensifies as retirement looms closer. Mid-lifers often cling to underperforming investments, refusing to sell because the idea of locking in a loss feels unbearable. This psychological trap can result in stagnant portfolios, missed opportunities, or even compounding losses over time. Fear-driven inaction is just as damaging as impulsive decisions, because markets reward disciplined movement, not paralysis. Understanding loss aversion helps investors make decisions based on strategy, not fear.

3. Herd Mentality That Fuels Panic Selling

Market downturns often feel like a stampede, and mid-lifers are not immune to the herd instinct. When peers or news outlets scream about crashes, it’s tempting to sell everything in a panic, even if fundamentals remain sound. This trap is dangerous because it’s rarely the market itself that’s the problem—it’s the emotional reaction to it. Selling at the bottom locks in losses and often prevents participation in eventual recoveries. Recognizing when you’re following the herd allows for calmer, more calculated responses instead of knee-jerk reactions.

4. Confirmation Bias That Distorts Reality

We all like to hear what confirms our beliefs, and mid-lifers are especially prone to this when markets become volatile. Investors might only read articles that support their bullish or bearish stance while ignoring contradicting data that could encourage better decisions. This selective attention can reinforce bad habits, like holding on to risky assets or avoiding opportunities because they challenge preconceptions. Over time, confirmation bias clouds judgment and prevents rational portfolio adjustments. Being aware of this trap encourages a more balanced perspective, weighing both risk and reward without emotional distortion.

Here Are Psychological Traps Mid-lifers Fall Into When Markets Turn Choppy
Image Source: Shutterstock.com

Recognize The Traps, Protect Your Portfolio

Financial markets aren’t just about numbers—they’re about human behavior. Mid-lifers often face unique pressures, balancing retirement goals with current obligations, and psychological traps can magnify mistakes during market turbulence. Awareness is the first step: recognizing overconfidence, loss aversion, herd mentality, and confirmation bias can make a huge difference in long-term financial outcomes.

By understanding the ways our brains misfire, investors can respond more strategically, keep panic in check, and maintain confidence through choppy waters.

Have you experienced any of these psychological traps? Write about your thoughts, stories, or tips in the comments section below.

You May Also Like…

8 Hidden Risks People Overlook When Financing a Car at High APR

8 Financial Risks Hidden in Pet Ownership

4 Psychological Hurdles Preventing Your Financial Independence Now

10 Reasons The Lower Middle Class Are Afraid to Invest

7 Clear Paths to Financial Freedom With Minimal Risk Exposure


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Investing Tagged With: beginning investing, confirmation bias, financial advisor risk, financial risk, herd mentality, invest, investing, investors, loss aversion, markets, Money, money issues, psychological traps, stock market

Inflation Pulse: 5 Surprising Assets Performing Well While Everything Else Slows Down

December 11, 2025 by Brandon Marcus Leave a Comment

Here Are 5 Surprising Assets Performing Well While Everything Else Slows Down
Image Source: Shutterstock.com

Inflation is roaring back into headlines, and suddenly, your wallet feels lighter, your groceries cost more, and your bank account seems like it’s on a diet it didn’t sign up for. Investors and everyday savers alike are asking the same question: what actually holds its value when everything else seems to be slowing down?

Surprisingly, not all assets get dragged down by rising prices and economic jitters. Some perform better than expected, quietly defying the trends and proving that even in turbulent times, there are opportunities to grow—or at least protect—your wealth.

1. Precious Metals Shine Brightly

Gold and silver aren’t just shiny collectibles; they’ve historically been safe havens during inflationary periods. When paper money loses purchasing power, tangible metals maintain value, providing a hedge against rising costs. Silver, in particular, benefits from industrial demand alongside its traditional role as a store of wealth, giving it dual support. Even platinum and palladium have seen interesting movements recently due to supply constraints in automotive and tech sectors. For investors looking for a tried-and-true buffer, precious metals often outperform when broader markets stumble.

2. Real Estate Investment Trusts Hold Ground

While some corners of the real estate market may wobble, certain Real Estate Investment Trusts, or REITs, have shown resilience. Rental income often rises with inflation, and commercial properties in high-demand areas continue to generate consistent returns.

Unlike direct property ownership, REITs provide liquidity and diversification, making them an attractive option during uncertain times. Residential and industrial REITs are particularly notable, as they benefit from housing demand and logistics needs, respectively. For those who want exposure to real estate without the headaches of tenants and maintenance, REITs can outperform other slow-moving investments.

Here Are 5 Surprising Assets Performing Well While Everything Else Slows Down
Image Source: Shutterstock.com

3. Inflation-Protected Bonds Offer Steady Gains

Treasury Inflation-Protected Securities, or TIPS, may not sound glamorous, but they do exactly what their name promises. As inflation rises, these bonds adjust their principal, ensuring that investors’ purchasing power doesn’t erode over time. Interest payments also rise with inflation, offering a rare combination of stability and growth. While traditional bonds can lose value in a high-inflation environment, TIPS act as a safety net. For conservative investors, they provide peace of mind without sacrificing potential returns.

4. Commodities Beyond Gold Are Surprising Winners

While gold steals the spotlight, other commodities like oil, natural gas, and agricultural products have performed remarkably well in inflationary periods. Rising demand, supply chain constraints, and geopolitical factors can create strong price momentum, even when stocks or bonds are sluggish. Energy commodities are particularly notable as economies continue to rebound and consume more resources. Agricultural products like wheat, corn, and soybeans also benefit from scarcity and higher food prices. Investors looking to diversify their portfolios often find that these tangible goods provide protection while delivering potential gains.

5. Dividend-Paying Stocks Keep Pushing Forward

Stocks that consistently pay dividends have a unique advantage in an inflationary environment. While stock prices may fluctuate, reliable dividends provide a stream of income that can be reinvested or used to offset rising living costs. Companies in essential sectors, like utilities and consumer staples, tend to maintain steady earnings, allowing dividends to remain consistent or even grow. Dividend aristocrats—companies with a long history of increasing dividends—are especially attractive because they combine stability with inflation-adjusted returns. For investors seeking both growth and a cash flow buffer, dividend-paying stocks often outperform the broader market during slowdowns.

Protecting Value While the World Slows

Inflation doesn’t have to feel like a financial trap. By paying attention to assets that maintain or even grow their value when the economy slows, investors can protect their wealth and seize opportunities others might overlook. Precious metals, REITs, inflation-protected bonds, strategic commodities, and dividend-paying stocks all demonstrate surprising resilience in turbulent times.

Have you tried investing in any of these assets, or have you noticed other strategies that work when inflation hits hard?

You May Also Like…

8 Bold Strategies for Investing During Periods of High Inflation

8 Necessary Steps to Prepare for a Potential Hyperinflation Event

6 Financial Dangers of Ignoring Inflation

The Gig Economy Tax Nightmare: Why So Many Freelancers End Up Owing the IRS

5 Silent Money Traps in the Gig Economy


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: commodities, Dividends, gold, Inflation, investing, investments, Life, Lifestyle, precious metals, Real estate, spending, stock market, stocks

  • « Previous Page
  • 1
  • 2
  • 3
  • 4
  • 5
  • 6
  • 7
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • 10 Tactics for Building an Emergency Fund from Scratch by Vanessa Bermudez
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald

Copyright © 2026 · News Pro Theme on Genesis Framework