• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for saving money

63% of Adults Name Money as A Top Stressor — Practical Ways to Respond

March 12, 2026 by Brandon Marcus Leave a Comment

63% of Adults Name Money as A Top Stressor — Practical Ways to Respond
Image Source: Unsplash.com

Money stress dominates modern life with relentless persistence. Surveys from the American Psychological Association consistently show that about 63% of adults rank money as one of their top stressors. That statistic says a lot about the financial tension humming beneath everyday decisions, from grocery shopping to housing choices. Financial anxiety does not only sit quietly in the background either; it affects sleep, concentration, productivity, and emotional well-being in ways that ripple through daily life. Yet many people assume relief requires a massive raise, a miracle investment, or a sudden lottery win.

In reality, financial calm often grows from simple changes that shift habits, priorities, and mindset in practical ways. Small adjustments create momentum, and momentum builds confidence. A few thoughtful strategies can turn money from a source of dread into something far more manageable.

The Hidden Weight of Financial Stress

Financial stress rarely arrives as a single dramatic crisis. Instead, it creeps into daily routines through dozens of small worries about bills, unexpected costs, and the constant balancing act between income and expenses. A rising grocery bill, a surprise car repair, or a credit card balance that refuses to shrink can make even stable households feel uneasy. Over time, that tension piles up and begins to affect mental and physical health. Researchers link chronic financial stress to higher levels of anxiety, fatigue, and difficulty focusing on everyday tasks.

The psychological impact becomes especially intense because money touches nearly every decision in modern life. Housing, food, healthcare, education, and transportation all depend on financial resources, so worries about money rarely stay confined to a single category. Instead, they spill into every corner of daily planning. When finances feel uncertain, people often experience a constant sense of pressure that follows them from morning alarms to late-night thoughts about tomorrow’s expenses.

Why High Prices Make Stress Feel Unavoidable

In recent years, rising costs have intensified the pressure surrounding money. Groceries, rent, utilities, and transportation have all climbed in price, leaving many households feeling like they run faster each month just to stay in the same place. Even people who manage money responsibly can feel blindsided when everyday essentials suddenly cost significantly more than they did a few years ago.

That environment creates a sense that financial stability requires perfection. Every purchase begins to feel like a high-stakes decision, and even small indulgences can trigger guilt or second-guessing. However, financial resilience rarely comes from eliminating every comfort or joy. Instead, stability grows from clear priorities and systems that help money flow toward what matters most.

A Budget That Actually Works in Real Life

Budgeting often gets a terrible reputation because many plans feel rigid, unrealistic, or overly complicated. Spreadsheets filled with dozens of categories can overwhelm anyone who simply wants to understand where money goes each month. A budget that works well in real life focuses on clarity rather than perfection. Tracking the major categories—housing, food, transportation, savings, and discretionary spending—often provides enough insight to guide smarter decisions.

One effective approach involves examining recent spending patterns without judgment. That simple review reveals where money actually flows rather than where people think it goes. Once that picture becomes clear, adjustments become easier because they target real habits instead of vague assumptions. Even a modest shift in spending priorities can create breathing room that reduces financial tension.

63% of Adults Name Money as A Top Stressor — Practical Ways to Respond
Image Source: Pexels.com

The Quiet Power of Small Financial Wins

Large financial goals can feel intimidating, especially when debt or rising costs dominate the picture. However, small wins often deliver the motivation needed to build lasting progress. Saving an extra twenty dollars each week, canceling a subscription that rarely gets used, or cooking one additional meal at home can create visible improvements over time. These changes may appear minor in isolation, but their combined impact grows surprisingly fast.

Psychology plays an important role here as well. Every small success builds confidence and reinforces the belief that change remains possible. When financial decisions begin to produce positive results, motivation increases naturally. Over several months, those small wins can transform the entire financial outlook of a household.

Cutting Costs Without Feeling Deprived

Many cost-cutting strategies fail because they rely on extreme sacrifice. Plans that remove every source of enjoyment often collapse after a few weeks because they feel unsustainable. A smarter approach focuses on trimming expenses that provide little value while protecting the activities that genuinely improve quality of life. For example, reviewing subscription services, insurance policies, and unused memberships often reveals surprising opportunities for savings.

Energy efficiency also offers a practical way to reduce monthly bills without dramatic lifestyle changes. Simple actions like sealing drafty windows, adjusting thermostat settings, and switching to energy-efficient lighting can lower utility costs over time. These adjustments rarely disrupt daily comfort, yet they quietly strengthen financial stability.

Building an Emergency Fund That Actually Helps

Unexpected expenses represent one of the biggest triggers for financial stress. A sudden medical bill or car repair can derail even carefully planned budgets. An emergency fund acts as a buffer that absorbs these shocks before they spiral into larger financial problems. Financial experts often recommend saving three to six months of living expenses, but that goal can feel overwhelming at the beginning.

A more realistic strategy starts with a smaller target, such as saving five hundred or one thousand dollars. That amount may not cover every emergency, but it provides immediate protection against many common surprises. Consistent contributions gradually grow that cushion over time, and each deposit strengthens financial confidence.

Income Growth Still Matters

Cost control plays an important role in reducing financial stress, but income growth also deserves attention. Exploring opportunities for professional development, additional training, or side income can create powerful long-term benefits. Even modest increases in earnings can dramatically change a household’s financial trajectory.

Side projects, freelance work, and skill-based services often provide flexible ways to boost income without completely overhauling a career. Many people discover valuable talents they never realized could generate income. The key lies in approaching income growth as an ongoing experiment rather than a single high-stakes decision.

The Mindset Shift That Changes Everything

Money stress often shrinks when people shift their mindset from fear to strategy. Financial problems feel overwhelming when they appear unpredictable or uncontrollable. However, clear planning turns uncertainty into a series of manageable steps. Tracking spending, building savings, and exploring income opportunities all transform money from a mystery into something far more understandable.

This shift does not eliminate every financial challenge overnight, but it restores a sense of agency. Instead of reacting to every bill with anxiety, individuals begin to approach money with curiosity and intention. That change alone can dramatically reduce the emotional weight attached to financial decisions.

Turning Financial Stress Into Financial Strength

Financial pressure affects millions of households, yet it does not need to dominate daily life forever. Thoughtful budgeting, strategic cost reductions, steady savings, and income growth can gradually reshape the entire financial landscape. Each small step builds momentum, and that momentum transforms stress into stability over time. Progress rarely arrives overnight, but consistent action creates measurable improvement month after month.

Money may rank as a top stressor for 63% of adults, but it also represents one of the few stressors people can actively reshape with practical habits and deliberate choices. Financial peace often begins with a handful of small decisions that grow into lasting change.

What strategies have helped reduce financial stress or improve financial stability? Share all of your thoughts and personal insights in the comments section.

You May Also Like…

Millions Of Americans Report High Stress And Loneliness Despite Market Gains

Risk Proaction: 5 Steps to Stress-Test Your Finances for Worst-Case Scenarios

Why Financial Stress Feels Worse After Retirement Instead of Better

Why Do So Many People Say Money Stress Is Constant

9 Financial Habits That Look Responsible but Feel Stressful

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Personal Finance Tagged With: budgeting strategies, Budgeting Tips, Cost of living, Debt Management, Financial Health, Financial Wellness, frugal living, money habits, money stress, Personal Finance, Planning, saving money, stress management

7 Steps to Run a Financial Autopsy on Your 2025 Spending

March 6, 2026 by Brandon Marcus Leave a Comment

These Are 7 Steps to Run a Financial Autopsy on Your 2025 Spending
Image Source: Shutterstock.com

Spending money feels exciting at the start, like opening a fresh box of possibilities, yet the excitement fades when bank statements start telling uncomfortable stories. By the time 2025 ended, many people wondered where their money truly went, and the answer often sits buried inside subscriptions, impulse purchases, and everyday leaks that quietly drained wallets.

Performing a financial autopsy means dissecting the year’s expenses with curiosity instead of shame, because numbers reveal habits when people study them carefully. This process does not exist to punish spending but to understand behavior and build smarter financial muscle for the future. Think of it like cleaning a messy room after a long party; the task feels less scary once the music stops and the lights turn on.

1. Gather the Body of Evidence: Pull Every Spending Record Like a Detective

Start by collecting bank statements, credit card histories, digital wallet records, and any payment app logs showing movement of money during 2025. Log into every financial account used, export transaction files if the platform allows it, and organize everything into one master spreadsheet or budgeting app. Do not guess numbers because guessing builds shaky conclusions, and this exercise depends on facts rather than emotional memory.

People often believe they spent less on entertainment or dining until actual records tell a different story about weekend habits. Group expenses into simple categories such as housing, food, transport, subscriptions, shopping, and lifestyle spending so patterns appear clearly. Look for transactions repeating every month since those usually represent automatic commitments or forgotten services still charging fees. Some people feel surprised when they discover small daily purchases turning into large yearly totals after adding them carefully. This step sets the foundation because an autopsy requires accurate specimen collection before any analysis begins.

2. Identify the Silent Killers: Hunt Down Subscription Leaks

Subscriptions behave like quiet house guests who never leave unless someone asks them to pack bags and go. Many people sign up for streaming services, fitness apps, productivity tools, or online memberships and forget them after the first enthusiastic week. Check every recurring payment and ask whether the service delivered real value during 2025. Cancel subscriptions that never got used more than twice per month because money should work harder than unused entertainment.

Some financial apps can scan accounts and list recurring charges, which saves time and reduces manual searching. Write down each subscription’s monthly cost and multiply it by twelve to see the true yearly impact, since small monthly fees often hide bigger annual losses. Consider sharing premium services with family members or switching to lower-cost plans when usage stays low. Treat this step like cutting away unnecessary medical tubing during an autopsy so the real cause of financial strain appears.

3. Track the Impulse Monster: Study Emotional Shopping Moments

Impulse spending usually happens during boredom, stress, celebration, or online scrolling sessions that remove people from intentional decision-making. Review transactions and mark purchases that happened without prior planning or budget allocation. Notice whether late-night browsing sessions, social media ads, or lifestyle envy triggered quick clicks on shopping carts.

Add a small rule for future behavior: wait at least 24 hours before buying nonessential items that cost more than a simple lunch. Some financial coaches recommend keeping a “want list” where interesting products live for a week before purchase decisions happen. This delay gives emotions time to cool down and logic time to speak louder than excitement. People often discover that half of impulse desires disappear after waiting because novelty fades quickly. Control over impulse spending builds stronger long-term wealth than any single lucky investment.

4. Measure the Food Fingerprint: Examine Eating Out Patterns

Food spending often forms one of the biggest lifestyle expenses because eating remains a daily necessity that mixes with convenience and social life. Look at restaurant visits, delivery orders, coffee shop stops, and quick snack purchases across the year. Add all dining expenses together and compare them against grocery spending to see whether cooking at home saves meaningful money.

Dining outside sometimes provides happiness and connection, so cutting it completely does not create balance, but uncontrolled frequency drains budgets fast. Try setting a weekly dining limit or scheduling restaurant visits as planned events instead of spontaneous decisions. Buy basic cooking ingredients in bulk when possible since bulk shopping reduces per-meal cost for many households. Think about food spending like fuel consumption for a car; efficient driving does not mean never driving, but driving smarter.

5. Face the Lifestyle Creep Shadow: Watch Income Growth vs. Expense Growth

Lifestyle creep happens when income increases but spending grows faster than earnings. People feel richer after promotions or bonuses, then upgrade housing, gadgets, clothing, or entertainment without measuring long-term impact. Compare total 2025 income against total 2025 spending growth and check whether expenses climbed proportionally. Good financial health usually shows savings or investment increases whenever income rises.

Make a habit of allocating at least part of every income increase toward savings, investments, or debt reduction before upgrading lifestyle comforts. Remember that wealth grows when money works quietly after people finish working for the day. Treat salary increases as opportunities to strengthen future security rather than permission to spend more immediately. Financial stability usually rewards patience more than speed.

6. Examine Debt Scars: Check Interest That Ate Quietly

Debt does not shout loudly, but interest accumulation behaves like rust spreading across metal over time. Review credit card balances, loan statements, and financing agreements that charged interest during 2025. Pay attention to high-interest debt first since those balances cause the fastest financial damage. Calculate how much interest payment went toward lenders instead of toward actual purchases or investments.

If possible, build a repayment strategy that pays more than minimum required amounts every month. Some people benefit from the debt snowball method where small debts get cleared first to create psychological momentum. Others prefer attacking high-interest debt immediately to reduce total cost. Pick the strategy that matches personal discipline and financial comfort.

7. Perform the Future Forecast: Design 2026 Money Habits Now

After studying past spending behavior, create a simple financial roadmap for the next year. Set three clear targets, such as building emergency savings, reducing debt percentage, or increasing investment contributions. Automate savings transfers whenever possible so money moves away from temptation before lifestyle decisions happen.

Review the plan every three months rather than waiting until year-end since small corrections work better than big emergency fixes. Track progress visually using charts or apps because seeing growth motivates continued discipline. Share financial goals with trusted family members or friends who encourage responsible decisions. Imagine 2026 as a clean financial chapter starting with intention rather than confusion.

These Are 7 Steps to Run a Financial Autopsy on Your 2025 Spending
Image Source: Shutterstock.com

What This Autopsy Really Shows

Running a financial autopsy on 2025 spending teaches that money follows behavior, not hope alone. Numbers tell honest stories when people listen without pride blocking interpretation. Spending patterns usually repeat unless someone interrupts old habits with conscious planning. Small changes across many categories create stronger results than dramatic changes in one area. Financial health grows like a garden when people remove weeds, water useful plants, and watch patiently for progress. The most important discovery often comes from realizing control sits inside daily choices rather than yearly resolutions.

What spending habit surprised you the most when looking back at 2025 expenses? And what plans do you have for the rest of 2026? Let’s hear about it in the comments.

You May Also Like…

Risk Proaction: 5 Steps to Stress-Test Your Finances for Worst-Case Scenarios

6 Reasons Middle-Class Budgets Are Breaking Under “Slow Inflation”

7 Budget Foods Americans Rely On That Doctors Say Create Bigger Problems Later

11 Disturbing Reasons You’re Secretly Terrified of Spending Money

5 Budgeting Tools That Trick You Into Higher Spending

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Spending Habits Tagged With: budgeting 2025, debt control, expense tracking, Financial Health, money tips, Personal Finance, Planning, saving money, smart budgeting, Spending Habits

Hawaii Residents Face Some of the Tightest Margins in America — What It Takes to Make It Work in 2026

March 3, 2026 by Brandon Marcus Leave a Comment

Hawaii Residents Face Some of the Tightest Margins in America — What It Takes to Make It Work in 2026
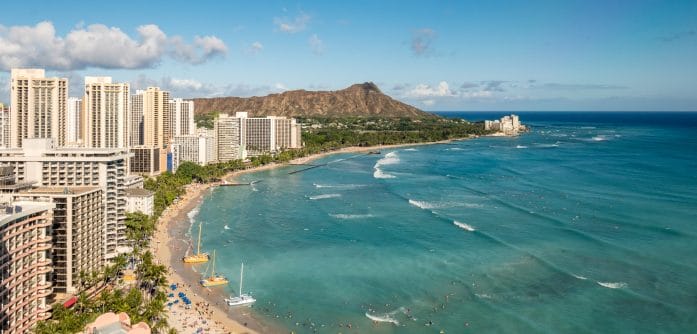
Image Source: Unsplash.com

Hawaii looks like paradise on a postcard, but paradise comes with a price tag that reshapes every financial decision. In 2026, the average single resident faces living costs of about $4,500 per month, or roughly $55,000 per year, which is 84 percent higher than the U.S. average. Housing alone costs about $3,624 per month for a single person, more than double the national average.

After covering rent, groceries, utilities, transportation, and healthcare, many residents are left with only a few hundred dollars per month in true discretionary income. That number varies widely by island, household size, and income level, but the reality is consistent: disposable income in Hawaii is tight, and stretching it requires intention, creativity, and discipline.

The Real Cost of Living in the Aloha State

Hawaii remains the most expensive state in the country in 2026. Housing drives most of the pressure. Limited land, high demand, and geographic isolation keep prices elevated. Groceries follow the same pattern. Shipping costs inflate prices on staples like milk, eggs, and meat. Residents feel the difference every time they shop.

Utilities add another layer. Electricity rates remain among the highest in the nation because Hawaii still relies heavily on imported fuel. Even modest air‑conditioning use can push monthly bills far above mainland norms.

When basic living costs consume more than $50,000 per year for a single person, disposable income becomes a fragile margin rather than a comfortable cushion.

Housing: The Budget Anchor That Shapes Everything

Housing determines whether a Hawaii budget sinks or floats. With average rents far above national norms, many residents spend well over 30 percent of their income on shelter alone. Some move farther from urban centers to find lower rent. Others share housing with roommates or extended family, a common and culturally rooted approach that provides both emotional and financial support.

A slightly cheaper rental can free up thousands of dollars per year. That difference may fund an emergency savings buffer, cover travel between islands, or simply reduce stress in a high‑cost environment.

Food, Fuel, and the Everyday Reality Check

Groceries cost more in Hawaii because most food is imported. Weekly bills climb quickly, especially for families. Residents who stretch their budgets often rely on farmers markets, local produce, and community‑supported agriculture programs, which can offer competitive prices and fresher options.

Transportation adds another challenge. Gas prices typically sit above mainland averages due to shipping and refining costs. Many residents combine errands, carpool, or use public transit to reduce fuel spending.

Turning Limited Disposable Income into Real Progress

Even when discretionary income is slim, intentional planning can turn it into forward momentum. A clear budget gives every dollar a purpose. Emergency savings matter most. With living costs so high, even a small, unexpected expense can destabilize a household. Building a starter emergency fund, then gradually expanding it, protects against setbacks.

Retirement savings also deserve attention. Contributing to a 401(k) or IRA, especially when an employer offers matching funds, helps build long‑term security. Even modest monthly contributions compound over time. Setting aside money for enjoyment—like dining out or exploring other islands—helps maintain balance. A sustainable budget includes room for living, not just surviving.

Lifestyle Choices That Make or Break the Budget

Hawaii offers endless ways to spend money, from oceanfront dining to boutique shopping. Without boundaries, discretionary spending can disappear quickly. Many residents embrace low‑cost or free activities instead. Beaches, hiking trails, and community events offer world‑class experiences without draining the budget. Cooking at home, limiting subscriptions, and reviewing insurance policies also help stretch limited disposable income.

Every recurring expense deserves scrutiny. When someone treats their remaining income as a resource to protect, financial stability becomes more attainable.

Hawaii Residents Face Some of the Tightest Margins in America — What It Takes to Make It Work in 2026
Image Source: Unsplash.com

Building Resilience in a High‑Cost Environment

Living in Hawaii requires flexibility. Tourism shifts, economic changes, and natural events can influence job markets and household budgets. Side income streams are common. Freelance work, seasonal jobs, and small business ventures help residents supplement earnings. Hawaii’s creative and entrepreneurial culture supports everything from handmade crafts to digital services.

Community plays a major role. Shared childcare, bulk buying, bartering, and multigenerational living reduce individual financial pressure. In a state where costs run high, collective resilience matters.

Income, Opportunity, and Perspective

Hawaii’s high median household income does not translate into easy living. Elevated costs erode purchasing power quickly. A paycheck that looks strong on paper may feel thin in practice. Understanding that tension helps residents make informed decisions about careers, housing, and long‑term goals. Some choose to relocate for affordability. Others stay for lifestyle, family, or cultural connection, accepting tighter margins in exchange for the benefits of island life.

Perspective matters. Even limited disposable income can support stability when aligned with values and managed intentionally.

Paradise With a Plan

Hawaii’s beauty attracts dreamers, but thriving in the islands requires strategy. With average living costs exceeding $54,000 per year for a single person, disposable income is precious. Housing choices, grocery habits, transportation decisions, and disciplined saving all shape the outcome.

Residents who succeed financially treat every dollar as part of a larger plan. They balance enjoyment with responsibility, question recurring expenses, and commit to long‑term goals even when temptation surrounds them.

What part of Hawaii’s cost structure do you think deserves the most attention—housing, groceries, utilities, or income trends? Do you think you could be a full-time resident of the state? Let’s talk about it in the comments section below.

You May Also Like…

How Trump’s New Fed Pick Could Change Your Interest Income Forever

How The SALT Deduction Caps Squeezed Many Middle-Income Taxpayers

The IRS Timing Rule That Can Push Income Into a Different Tax Year

9 Everyday Costs Rising Faster Than Seniors’ Income

The Income-Driven Repayment Plans That End July 1, 2028 Under New Law

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Finance Tagged With: budgeting, Cost of living, Disposable Income, groceries, Hawaii, Honolulu, Housing Costs, Island Living, Lifestyle, Personal Finance, Planning, saving money, utilities

Is Your “Little Treat” Habit Costing You $2,500 a Year? The Real Spending Math

March 3, 2026 by Brandon Marcus Leave a Comment

Is Your “Little Treat” Habit Costing You $2,500 a Year? The Real Spending Math
Image Source: Unsplash.com

A five-dollar habit does not feel like a financial turning point. It feels like a reward. It feels earned. And it feels small enough to ignore.

Yet run that same five dollars through a full year, and the numbers tell a different story. Add a few more “little” extras each week, and the total climbs fast enough to compete with a vacation, a credit card balance, or a serious dent in an emergency fund. The question is not whether small treats matter. The real question asks how much they actually cost when they show up every single day.

The $5 Illusion: Why Small Numbers Trick the Brain

A five-dollar coffee, a seven-dollar sandwich, a quick ten-dollar online order—none of these purchases trigger alarm bells on their own. Most people do not think in annual totals while standing in line or tapping a checkout button. The brain loves small numbers because they feel manageable and low risk.

Behavioral economists often talk about “mental accounting,” a concept popularized by Nobel Prize–winning economist Richard Thaler. People mentally sort money into different buckets, and they treat each bucket differently. A small daily expense slides into a harmless category labeled “treat” or “self-care.” That label lowers defenses.

The math does not care about labels. Spend $7 a day on coffee and snacks, and that equals $49 a week. Multiply that by 52 weeks, and the total hits $2,548 in a year. That figure does not include interest or potential investment growth. It simply reflects routine spending that felt minor in the moment.

Once numbers move from daily to annual, they suddenly demand attention. Two thousand five hundred dollars does not feel like a throwaway amount. It feels like tuition, rent, a plane ticket, or several months of groceries.

The Real Annual Breakdown: Let’s Do the Math

Start with a simple scenario. Imagine a $6 latte purchased five days a week. That equals $30 a week. Over a month, that reaches about $130. Over a year, that totals roughly $1,560.

Now add a $12 takeout lunch twice a week. That adds $24 weekly, or about $1,248 annually. Combine that with the latte habit, and the yearly total jumps to $2,808. No exaggeration. No dramatic rounding. Just straightforward multiplication.

Recent surveys show that households spend thousands of dollars annually on food away from home. That category includes coffee runs, fast-casual lunches, and last-minute takeout dinners. For many households, food away from home represents one of the largest flexible expenses in the budget.

Flexibility matters because flexible expenses offer room for change. Rent and insurance demand fixed payments. Daily treats leave room for choice. That does not mean cutting every joy. It means recognizing the scale of those joys over time.

The Comfort Trap: When Treats Turn Into Routine

A treat should feel occasional. When it turns into a daily ritual, it shifts from luxury to routine expense. Lifestyle inflation plays a role here. As income rises, spending often rises right along with it. That new job, that raise, that bonus—each milestone invites a small upgrade. A nicer coffee. A better lunch. Faster shipping. None of these changes feel reckless. Together, they reshape a budget.

Habits build quickly because repetition removes friction. The first $8 smoothie feels indulgent. The twentieth feels normal. Normal spending rarely sparks scrutiny.

That normalization explains why “little treat culture” gained traction online. Social media platforms like TikTok amplify the idea that small daily rewards protect mental health and boost motivation. While occasional rewards support well-being, daily spending without limits can quietly crowd out bigger goals.

What $2,500 Could Actually Do Instead

Two thousand five hundred dollars holds real power when redirected with purpose. Place $2,500 into a high-yield savings account earning 4 percent annual interest, and that money generates about $100 in interest over a year without additional contributions. Invest $2,500 in a diversified index fund averaging a historical annual return of around 7 percent after inflation, and that amount could grow to roughly $4,900 in ten years, assuming no additional deposits and steady returns. Markets fluctuate, and returns never come guaranteed, but long-term growth historically rewards consistency.

That same $2,500 could wipe out high-interest credit card debt. Many credit cards charge interest rates above 20 percent. Paying down a $2,500 balance at 20 percent interest saves hundreds of dollars in future interest payments.

The number also covers a solid emergency fund starter. Many financial planners recommend saving three to six months of essential expenses. A $2,500 cushion can prevent a job loss or medical bill from turning into long-term debt.

Is Your “Little Treat” Habit Costing You $2,500 a Year? The Real Spending Math
Image Source: Unsplash.com

How to Keep the Joy Without Losing the Cash

Eliminating every small pleasure often backfires. Extreme restriction leads to burnout, and burnout leads to splurges that undo progress. Balance works better than deprivation.

Start by tracking spending for one month. Use a budgeting app or a simple spreadsheet. Write down every coffee, snack, and impulse purchase. Awareness alone often reduces spending because it removes the illusion of smallness. Next, set a monthly “treat fund.” Allocate a fixed amount—maybe $100 or $150—and spend it guilt-free. Once that fund runs out, pause until the next month. This strategy keeps joy in the budget while protecting long-term goals.

Experiment with swaps. Brew coffee at home four days a week and buy one café drink as a weekly ritual. Pack lunch three days a week and enjoy one intentional takeout meal. Small adjustments maintain pleasure without draining thousands annually.

A Quick Reality Check on “It’s Just $5”

Five dollars feels harmless because it does not threaten immediate survival. Yet scale changes meaning. Five dollars a day equals $35 a week, $182 a month, and $1,825 a year. Increase that daily amount to $8, and the annual total climbs to $2,920. This math does not argue against comfort. It argues for conscious choice.

Every dollar spent daily locks in a pattern. Every dollar redirected reshapes a future balance sheet. Personal finance rarely hinges on one dramatic decision. It builds on repeated behavior.

Financial experts consistently emphasize that small, consistent actions drive long-term results. Regular investing, steady saving, and controlled spending outperform sporadic grand gestures. The same principle applies in reverse. Small, consistent overspending erodes progress more effectively than one big splurge.

Tiny Choices, Big Totals

Small purchases carry big consequences when they repeat daily. A few dollars here and there can quietly total thousands over twelve months, enough to fund savings, reduce debt, or build real security. No one needs to abandon joy or live on strict austerity. Thoughtful limits and clear goals create room for both pleasure and progress.

Take a close look at the last 30 days of spending. Add up every “small” indulgence. Does that total surprise you, or does it confirm what you suspected all along? Let’s share our financial findings in the comments below.

You May Also Like…

6 Reasons Middle-Class Budgets Are Breaking Under “Slow Inflation”

7 Budget Foods Americans Rely On That Doctors Say Create Bigger Problems Later

Modern Taxation Explained: Filing, Records, and Savings

The “Safe” Budget Rules That Quietly Stop Working After Age 60

5 Budgeting Tools That Trick You Into Higher Spending

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Spending Habits Tagged With: Budgeting Tips, coffee spending, financial goals, Financial Wellness, frugal living, impulse buying, Lifestyle Inflation, money management, Personal Finance, saving money, smart shopping, Spending Habits

Why “Lower” Overdraft Fees Still Hurt Most Customers

February 14, 2026 by Brandon Marcus Leave a Comment

Why “Lower” Overdraft Fees Still Hurt Most Customers
Image source: shutterstock.com

Picture this: a tiny “mistake” in your bank balance turns into a fee that feels like a punch to the gut. You’ve probably heard that some banks have lowered overdraft fees — and on the surface that sounds like relief.

But here’s the thing: in most cases, those lower fees still sting way more than you realize. It’s time to unpack why a “discounted” hit to your bank account is still a blow, and how this whole system really works.

The Illusion of a Lower Fee: Why It Still Stings

Lowering overdraft fees might seem like a win for everyday people, but this is where we need to talk about the bigger picture. Sure, cutting a fee from $35 to $20 sounds like a sweet deal — but what’s the real impact? For many folks living paycheck to paycheck, it’s not just about the number on the fee. It’s about the cascade of financial stress that comes after seeing your balance suddenly worse than you expected.

A fee is supposed to be a discouragement — a reminder to stay on top of your balance — but when your hard-earned dollars get siphoned off for what feels like a bookkeeping technicality, it doesn’t feel like discipline. It feels like a penalty that hits disproportionately hard for people without a cushion. Those “lower” fees still come directly out of your spending money, and because they’re often repeated, they add up fast.

So, How Do Overdraft Fees Work Anyway?

Overdraft fees are basically the bank saying: “You spent more than you had, and we’re going to charge you for the privilege of covering the difference.” Some banks let a transaction go through even when there’s not enough money in your account, and boom — you get hit with a fee.

The key point most people miss is that overdraft isn’t automatic. Many banks offer standard overdraft programs that you’re opted into unless you specifically decline. That means if you don’t know what you’re signed up for, you could be paying fees without even realizing you agreed to them. Some banks charge you not just one fee but multiple fees in a single day if more than one transaction posts when you don’t have enough funds.

Lowering the per‑fee cost doesn’t change the fact that a series of small overdrafts can still drain a checking account quickly.

Why Lower Fees Still Don’t Help the Most Vulnerable

People who struggle most with overdraft fees are the ones who can least afford them. A $20 fee might be easier to swallow than $35, but for someone with a $25 balance, it’s still almost a full paycheck’s worth of spending money gone. The fee doesn’t help them catch up; it keeps them stuck.

Lower fees also don’t change the unpredictable nature of everyday finances. Bills, rent, groceries, travel — life doesn’t pause for budgeting missteps. Imagine you’re a parent juggling expenses: an unexpected overdraft fee, even a reduced one, can be the difference between paying for essentials or not.

The Real Alternatives Banks Offer (and Why They Still Miss the Mark)

In response to criticism, some banks have introduced alternatives: alerts for low balances, grace periods, or even overdraft lines of credit. These sound like improvements, and in some cases, they are slightly better than the old model.

Alerts, for example, can help you avoid overdrafts before they happen — if you actually see them in time. But if you’re juggling work, family, and life, you might miss a text or email notification — and still get hit with a fee.

Grace periods seem reasonable, until you realize there might be limits or conditions tied to it. And overdraft lines of credit? That’s essentially a mini loan with interest — helpful for some, but because it adds debt into the mix, it’s not inherently a kinder alternative.

Real Strategies to Dodge Overdraft Fees

We’ve established that “lower” doesn’t mean “friendly.” What can you actually do to protect yourself? The first step is awareness: know your bank’s overdraft policy inside and out.

Turning on balance alerts is a simple move. But pair it with a routine check‑in on your account, like a quick glance every morning. It’s amazing how a daily habit can prevent a weekly problem.

Finally, consider switching to banks or credit unions that offer “no‑fee” accounts or waive overdraft fees under certain conditions. Online banks and credit unions often have more member‑friendly policies — and making the switch could end up saving you real money over time.

Why “Lower” Overdraft Fees Still Hurt Most Customers
Image source: shutterstock.com

Why the Fee Debate Matters Now More Than Ever

We’re living in a time when the cost of banking — things like fees and minimum balances — is getting more attention. Regulatory scrutiny and consumer advocacy are pushing banks to rethink their practices. Lower overdraft fees are a step, but we’re learning they’re only a step, not the solution.

For many people, the goal isn’t just to pay a smaller fee — it’s to avoid being penalized for financial ebbs and flows that are normal parts of life. A banking system that charges for ordinary mistakes isn’t just outdated; it’s a tax on uncertainty and a barrier to stability.

Taking Control of Your Money

Lower overdraft fees may feel like a nod toward fairness, but they rarely solve the core issue. For most people, they’re still a setback that drains funds, stresses budgets, and creates cycles that are hard to escape.

A smarter approach is less about letting banks lower fees and more about empowering yourself with the knowledge and tools to keep fees from happening at all. That means understanding your accounts, setting up protections that work for your life, and being proactive about where your money goes.

What’s one move you’ve made (or want to make) to avoid overdraft fees and keep more money in your wallet? Talk about it with others in our comments section.

You May Also Like…

Big Banks Are Still Collecting Billions in Overdraft and NSF Fees

Credit Card Annual Fees Jumped in 2025 — Some Up to $200

Why More Americans Are Being Charged Fees They Never Explicitly Agreed To

6 Major Banks Just Raised “Maintenance Fees”—Here is the List of Who to Ditch

12 Practical Tips for Minimizing Brokerage Account Fees Effectively

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Banking Tagged With: bank fees, banking costs, checking accounts, consumer tips, finance education, Financial Wellness, money mistakes, overdraft fees, Personal Finance, saving money

9 Financial Plans That Collapse the Moment Real Life Gets Involved

February 12, 2026 by Brandon Marcus Leave a Comment

These Are 9 Financial Plans That Collapse the Moment Real Life Gets Involved
Image source: shutterstock.com

Most people assume life will behave, emergencies will wait their turn, and emotions won’t interfere with logic. On paper, common financial strategies look clean, responsible, and impressively adult.

In reality, real life is loud, unpredictable, emotionally messy, and allergic to spreadsheets. A lot of popular financial plans aren’t bad ideas, but they are fragile ones. They depend on perfect behavior, perfect timing, and perfect discipline in a world that specializes in chaos. If you’ve ever wondered why “smart” money plans keep falling apart, it’s not because you’re broken — it’s because the plans were never built for real humans.

1. The “Every Dollar Has a Job” Fantasy

This plan sounds airtight: assign every dollar a purpose, track every expense, and control your financial destiny. In reality, it assumes life will stay neatly categorized, predictable, and calm. Emergencies don’t fit clean categories, emotional spending doesn’t respect spreadsheets, and spontaneous opportunities don’t wait for budget meetings.

The moment stress, exhaustion, or surprise enters the picture, rigid budgeting systems start cracking. People don’t fail these systems because they’re irresponsible — they fail because humans aren’t machines. A better approach is flexible structure: guidance without rigidity, direction without punishment.

2. The Emergency Fund Debacle

The idea of a pristine emergency fund sounds responsible, disciplined, and financially mature. But real emergencies are emotional events, not accounting exercises. When your car breaks down, your dog needs surgery, or your income suddenly drops, logic takes a back seat to survival. People don’t spend wisely, they don’t rely on their emergency funds like they’re supposed to, and they don’t rebuild once the crisis has passed.

On top of that, the problem isn’t using the money — it’s pretending emergencies will be rare, small, and neatly defined. A realistic plan expects usage and focuses on rebuilding the emergency fund instead of feeling guilty about using it.

These Are 9 Financial Plans That Collapse the Moment Real Life Gets Involved
Image source: shutterstock.com

3. The “I’ll Invest Later” Strategy

Delaying investing until life feels stable is one of the most common financial traps. The problem is that life rarely feels stable in a permanent way. There’s always another bill, another goal, another reason to wait. Meanwhile, time — the most powerful investing tool — keeps moving forward.

This plan collapses because it depends on a future version of life that magically becomes calm and predictable. The smarter move isn’t waiting for perfection; it’s starting imperfectly and adjusting as life evolves.

4. The Debt Snowball That Ignores Burnout

Paying off debt aggressively sounds empowering and clean, but emotional burnout is real. Hyper-focus strategies often ignore mental fatigue, motivation crashes, and financial exhaustion. People start strong, feel empowered, and then slowly lose momentum as life stress stacks up.

When the plan only values speed and not sustainability, it becomes fragile. Long-term success comes from plans that allow breathing room, flexibility, and small wins — not financial marathons fueled by guilt and pressure.

5. The Lifestyle Freeze Illusion

Freezing your lifestyle while your income grows is financially smart in theory and psychologically brutal in practice. Humans naturally adjust to improved circumstances, and pretending otherwise sets up long-term frustration.

This plan collapses because it frames enjoyment as failure instead of balance. When people feel deprived for too long, they often rebound hard and spend impulsively. Sustainable financial growth includes room for enjoyment, not just restraint.

6. The Side Hustle Will Save Me Plan

Side hustles can be powerful tools, but relying on them as a financial rescue plan is risky. Burnout, inconsistent income, and time exhaustion creep in fast. Many people underestimate how mentally draining it is to stack work on top of work.

When energy runs out, the income stream often follows. Financial stability built on exhaustion isn’t stability — it’s a ticking time bomb. Smart planning builds systems, not survival mode.

7. The “I’ll Just Be Disciplined” Strategy

Discipline is not a system. It’s a finite resource that gets drained by stress, decision fatigue, and emotional overload. Plans built entirely on willpower collapse the moment life gets hard.

Real financial success comes from automation, structure, and simplicity — not constant self-control battles. If your plan requires daily perfection, it’s not a plan, it’s a pressure cooker.

8. The One-Goal Tunnel Vision Plan

Hyper-focusing on one financial goal often causes blind spots everywhere else. People who only chase homeownership, early retirement, or debt freedom sometimes ignore savings, health costs, or mental well-being.

But the truth is that life doesn’t operate in silos, and financial plans shouldn’t either. Tunnel vision creates fragility because it removes adaptability. Always remember that balanced, smarter, and healthier plans survive chaos better than obsessive ones.

9. The Social Media Money Myth

Financial plans built from viral content often collapse fast. Social media has a habit of simplifying complex financial realities into catchy rules, dramatic timelines, and unrealistic expectations.

Real finances involve nuance, personal circumstances, and long-term consistency — not overnight transformations. When expectations don’t match reality, people feel like failures instead of learners. A plan built on comparison rarely survives contact with real life.

Where Real Financial Strength Actually Comes From

True and tested financial stability isn’t built from perfect plans, but from resilient ones. The strongest money strategies expect chaos, not order. They allow for mistakes, rebuilds, restarts, and emotional reality. Financial success doesn’t come from rigid control; it comes from flexible systems that adapt when life shifts.

The goal isn’t flawless execution — it’s long-term sustainability that survives stress, change, and unpredictability. Build plans that bend without breaking, and you’ll stop feeling like your money life is constantly one bad week away from collapse.

What financial rule did you believe in the longest before real life completely rewrote it? What advice can you give our readers? Hop into the comments below to share.

You May Also Like…

The Income-Driven Repayment Plans That End July 1, 2028 Under New Law

7 Million Student Loan Borrowers Must Switch Plans as SAVE Program Ends

The Cruel Reality About Senior Discounts That No One Talks About

8 Wild “What Ifs” That Financial Planners Hear More Often Than You’d Think

Financial Advisor Confession: 7 Things I’m Now Required by Law to Tell My Clients (That I Couldn’t Say in 2025).

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: budgeting, Debt Management, financial habits, financial reality, investing basics, money mindset, money psychology, Personal Finance, Planning, saving money, Wealth Building

Why Paying Only the Minimum Creates $4,200 in Interest on a $5,000 Balance

February 6, 2026 by Brandon Marcus Leave a Comment

Why Paying Only the Minimum Creates $4,200 in Interest on a $5,000 Balance
Image source: shutterstock.com

There’s a moment many people experience: you open your credit card statement, see the minimum payment, and think it’s not so bad. It feels like a tiny financial victory—like the bank is giving you a break.

But behind that deceptively small number is a trap that quietly drains your wallet month after month. Paying only the minimum on a $5,000 balance can lead to over $4,200 in interest, turning a manageable debt into a long‑term financial burden.

Most people don’t realize how this happens until they’ve already paid far more than they borrowed. Let’s break down why minimum payments are so sneaky, how interest piles up, and what you can do to escape the cycle.

Minimum Payments Are Designed to Keep You in Debt Longer

Credit card minimum payments are usually calculated as a small percentage of your total balance—often around 1% to 3% plus interest. That means the payment barely dents the principal. When you pay only the minimum, most of your money goes toward interest, not the actual debt. This is why balances shrink painfully slowly.

Credit card companies aren’t being generous by offering low minimums; they’re ensuring the debt sticks around long enough to generate significant interest. This structure turns a $5,000 balance into a long‑term commitment, even if you never make another purchase. The math works quietly in the background, and unless you’re watching closely, it’s easy to underestimate how much interest is accumulating.

How Interest Snowballs Even When You’re Paying Every Month

Credit card interest is typically calculated using a daily rate based on the card’s annual percentage rate (APR). If your APR is, for example, 20%, that interest compounds every single day. When you only pay the minimum, the principal barely moves, so the next month’s interest is calculated on almost the same balance. This creates a snowball effect where interest keeps building on top of interest.

Even though you’re making payments, the balance doesn’t fall quickly enough to reduce the interest meaningfully. This is how a $5,000 balance can generate more than $4,200 in interest over time. It’s not because you’re doing anything wrong—it’s because the system is designed to stretch out repayment as long as possible.

Why a $5,000 Balance Can Take Years to Pay Off

If you stick to minimum payments, it can take many years to pay off a $5,000 balance. The exact timeline depends on your APR and the minimum payment formula, but it’s common for repayment to stretch well beyond a decade. During that time, interest keeps accumulating, and the total amount you pay ends up being far higher than the original balance.

This is why credit card statements now include a “minimum payment warning” showing how long repayment will take if you only pay the minimum. It’s meant to help consumers understand the long‑term cost of carrying a balance. The numbers can be shocking, but they’re accurate—and they highlight how expensive minimum payments can be.

Why Paying Only the Minimum Creates $4,200 in Interest on a $5,000 Balance
Image source: shutterstock.com

The $4,200 Interest Example: What’s Actually Happening

When a $5,000 balance generates more than $4,200 in interest, it’s because the minimum payment barely reduces the principal each month. For example, if your minimum payment is around $100, a large portion of that goes toward interest. Only a small amount—sometimes just a few dollars—reduces the actual balance.

As a result, the principal decreases slowly, and interest continues to accumulate on a high balance for a long time. Over the full repayment period, the total interest paid can exceed 80% of the original balance. This isn’t a rare scenario; it’s a common outcome for anyone who relies on minimum payments as their primary repayment strategy.

Why Minimum Payments Feel Manageable—But Cost More in the Long Run

Minimum payments are intentionally low to make debt feel manageable. They’re designed to fit easily into a monthly budget, which is why so many people rely on them. But the trade‑off is that low payments extend the life of the debt and increase the total interest paid. It’s a psychological trap: the payment feels small, so the debt feels small, even though the long‑term cost is huge.

This is why financial educators emphasize paying more than the minimum whenever possible. Even small increases—like an extra $20 or $30 a month—can significantly reduce interest and shorten repayment time.

Simple Strategies to Reduce Interest Without Overhauling Your Budget

You don’t need a massive financial overhaul to avoid paying thousands in interest. Small, consistent changes can make a big difference. One strategy is to round up your payment—if the minimum is $100, pay $150 or $200 instead. Another option is to set up automatic payments that exceed the minimum, ensuring you stay on track.

You can also target one card at a time using a focused repayment method, such as paying extra toward the highest‑interest balance. These strategies reduce the principal faster, which lowers the amount of interest charged each month. Over time, the savings add up significantly.

The Power of Paying a Little More Each Month

Paying more than the minimum doesn’t just reduce interest—it gives you control over your financial future. When you chip away at the principal, you shorten the repayment timeline and reduce the total cost of the debt. Even modest increases can save hundreds or thousands of dollars in interest.

It’s not about paying off the entire balance at once; it’s about making steady progress. The key is consistency. Once you get into the habit of paying more than the minimum, the balance starts to fall faster, and the interest becomes less overwhelming. It’s a small shift that leads to big results.

Breaking Free From the Minimum Payment Cycle

Minimum payments may seem convenient, but they come with a hidden price tag. By understanding how interest accumulates and why minimum payments keep you in debt longer, you can make smarter choices that save money over time.

What’s the biggest challenge you’ve faced when trying to pay down credit card debt? Share your experience and story in the comments.

You May Also Like…

Retail Store Credit Cards Now Charging 30% APR on Average

5 Invisible Service Charges Eating Into Your Bank Balance

The Hidden Costs of Balance Transfers You Should Know

Why “Work-Life Balance” Is a Lie for Most People

The Single Late Payment That Raises APR to 29.99% Permanently at Discover

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: credit cards Tagged With: budgeting, consumer finance, credit card tips, credit cards, debt payoff, financial literacy, interest charges, minimum payments, money mistakes, Personal Finance, saving money

8 Choices Rich People Will Never Make, But Poor People Make Everyday

January 31, 2026 by Brandon Marcus Leave a Comment

These Are 8 Choices Rich People Will Never Make, But Poor People Make Everyday
Image source: shutterstock.com

Have you ever wondered why some people seem to effortlessly climb the financial ladder while others stay stuck on the same rung for years? It’s not luck, genetics, or secret handshakes—it’s choices. Wealthy people don’t stumble into riches; they make deliberate, sometimes uncomfortable decisions every single day that protect and grow their money.

Meanwhile, habits that might seem harmless or convenient to the average person can quietly drain income, time, and opportunities. By examining the differences in mindset and action, you can start steering your own life toward financial freedom. So grab your coffee, buckle up, and get ready to learn eight choices rich people never make—and why these decisions matter more than you think.

1. Ignoring the Power of Compound Interest

You’ve probably heard of compound interest, but ignoring it is one of the most common financial traps. Poorer individuals often leave their money in checking accounts or spend windfalls immediately, missing out on decades of potential growth. Wealthy people, on the other hand, invest consistently, letting even modest sums snowball over time. A dollar invested wisely today can be worth ten, twenty, or even a hundred dollars decades later. It’s not magic—it’s patience, discipline, and smart financial planning.

Start small if you need to; even $50 a week invested in index funds can grow substantially over 30 years. Don’t wait for the “perfect moment” because, in investing, time is your superpower.

2. Living Paycheck to Paycheck

It may feel normal to spend every dollar you earn, but living paycheck to paycheck is a choice with huge consequences. Emergencies, unexpected expenses, or sudden job loss can create financial chaos. Wealthy individuals prioritize building a safety net before indulging in luxuries. They understand that security isn’t about cutting all fun—it’s about controlling the chaos.

Creating a buffer of even three to six months’ worth of expenses can be life-changing. Once you’ve built a cushion, you’ll find yourself making bolder, smarter financial decisions without the constant stress.

3. Ignoring the Difference Between Assets and Liabilities

A Ferrari may look impressive on Instagram, but it’s not an asset—it’s a liability. Poorer people often confuse possessions with wealth, buying things that depreciate while ignoring investments that generate income. Rich people focus on acquiring assets: rental properties, stocks, businesses, and intellectual property that put money in their pocket while they sleep. The key distinction is cash flow versus consumption.

Learning the difference can help you shift your spending habits, turning purchases into tools for growth rather than traps for debt. Start small—invest in something that earns rather than something that merely impresses.

4. Letting Small Debts Snowball Into Big Problems

Carrying credit card balances or payday loans may seem manageable at first, but high-interest debt grows like a snowball rolling downhill. Wealthy people rarely, if ever, allow debt to pile up—they pay off balances aggressively or avoid unnecessary debt altogether. They understand that a few hundred dollars in interest today can become thousands over time.

Debt is not inherently bad; strategic borrowing for education, property, or business is smart. The difference is avoiding high-interest, low-value obligations that quietly rob your financial future. Track every loan, interest rate, and due date—awareness alone can save you thousands.

5. Failing to Prioritize Learning and Self-Improvement

Rich people are lifelong students. They read, attend seminars, hire mentors, and continually expand their knowledge and skills. Many people struggling financially neglect personal development, assuming school or formal training is enough. But skills, knowledge, and strategic thinking compound over time just like money.

The more you know, the better decisions you make, whether in investments, career moves, or starting your own business. Even dedicating 20 minutes a day to learning can set you apart in the long run. Knowledge isn’t just power—it’s financial leverage.

6. Reacting Instead of Planning

Poor financial choices are often reactive: paying bills at the last minute, splurging after a stressful week, or following impulse trends. Wealthy people plan ahead, budgeting and projecting cash flow, taxes, and expenses months or even years in advance. Strategic foresight prevents stress and maximizes opportunity.

Planning doesn’t mean eliminating fun; it means scheduling indulgences, investments, and emergencies thoughtfully. A little preparation can turn chaos into control and stress into opportunity. Start with one aspect of your finances—like monthly spending—and build a habit of proactive management.

7. Ignoring Health as a Wealth Factor

Money and health are more connected than most realize. Poor health leads to expensive medical bills, lost income, and reduced quality of life, yet many people neglect diet, exercise, and mental wellness. Wealthy individuals treat health as an investment, not an afterthought. Regular exercise, preventive care, and stress management aren’t just about feeling good—they save money and protect your ability to earn.

Think of your body as a high-yield asset; maintaining it pays dividends in energy, productivity, and longevity. Small, consistent choices—like walking, drinking water, or reducing sugar—compound into major savings over time.

These Are 8 Choices Rich People Will Never Make, But Poor People Make Everyday
Image source: shutterstock.com

8. Chasing Instant Gratification Over Long-Term Rewards

If it feels urgent to buy the latest gadget, a designer bag, or take a luxury vacation, you’re not alone—but wealthy people resist the temptation. They understand the long-term payoff of delayed gratification: investing, saving, or pursuing education instead of fleeting pleasure. Psychology studies show that the ability to delay rewards is strongly correlated with financial success.

Each choice to prioritize future gains over immediate satisfaction adds up, creating freedom and wealth over time. Start small by waiting 24 hours before major purchases—you’ll be surprised how often the urge fades.

Stop Letting Everyday Decisions Control Your Financial Future

Money doesn’t magically appear in bank accounts; it’s the sum of countless small choices, repeated day after day. Wealthy people are deliberate, informed, and disciplined about how they handle money, time, and energy. By avoiding the eight mistakes above, you can take control of your financial destiny. Start by identifying just one habit to change this week. Turn your financial awareness into action and watch your life transform over time.

What’s the one daily choice you make that could be quietly draining your potential wealth? Share your thoughts in the comments.

You May Also Like…

7 Lesser-Known Ways Rich People Protect Their Money

7 “Boring” Businesses That Make People Quietly Rich

Why Wealthy Families Are Moving Cash Out of Traditional Banks Before Jan 31st

Legacy Design: 5 Ways to Pass on Wealth Without Passing on Pressure

10 Traits the Rich and Poor Surprisingly Share

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Spending Habits Tagged With: compound interest, Debt Management, financial freedom, financial habits, financial literacy, investing, lifestyle choices, money tips, Personal Finance, saving money, Wealth Building, wealth mindset

Why Your Emergency Fund Isn’t Protecting You the Way It Did Five Years Ago

January 27, 2026 by Brandon Marcus Leave a Comment

This Is Why Your Emergency Fund Isn’t Protecting You the Way It Did Five Years Ago
Image source: shutterstock.com

Remember when tucking away a few months’ worth of expenses in a savings account felt like financial armor? That shield, once considered indestructible, now seems a little thinner around the edges. If your emergency fund hasn’t been adjusted in years, you might be in for a surprise: what once covered rent, groceries, and a few random emergencies may no longer stretch far enough to keep you truly safe.

The world changes fast, and your emergency plan can’t stay frozen in time. Between rising inflation, housing costs, and everyday expenses creeping higher, that old nest egg might only cover half of what it used to.

Inflation Is Quietly Eating Your Safety Net

Inflation is like that guest at a party who slowly eats all the snacks while you’re distracted. Over the past five years, the cost of groceries has skyrocketed by nearly 30%, while utilities and transportation have steadily climbed, often outpacing the interest your savings account earns.

If your emergency fund hasn’t grown at the same pace as your expenses, its real purchasing power has quietly eroded. This means you might think you’re financially protected, but when the real-world bills come knocking, you’ll notice the difference immediately. It’s not that your money disappeared—it’s that it doesn’t buy as much as it used to.

Interest Rates And Savings Accounts Are No Longer Your Allies

Five years ago, parking money in a high-yield savings account could earn you a respectable return. Those days are largely behind us. Interest rates have fluctuated dramatically, leaving many emergency funds stagnating while costs continue to rise. Meanwhile, prices on essential goods keep climbing, silently chipping away at your financial cushion.

This mismatch between what you earn on savings and what you spend on necessities can turn a seemingly comfortable fund into something worryingly thin. If you’re relying on the same account strategy you used in 2018, it’s time for a serious checkup. Your fund isn’t broken—it’s just outdated.

The Cost Of Housing Has Shifted Dramatically

Renters and homeowners alike have felt the squeeze. In cities across the country, the housing affordability crisis has caused costs to soar, while wages haven’t always kept pace.

For many, the cost of maintaining a home or apartment now takes up a larger slice of the monthly budget than it did five years ago. This shift doesn’t just affect renters—homeowners feel it too, thanks to rising property taxes, insurance, and utility costs. The reality is simple: your old emergency fund was calculated for a different world, and the world has changed.

Healthcare Costs Are A Silent Drain

Medical expenses often lurk in the background until an emergency hits. Over the last few years, healthcare costs, insurance premiums, and prescription prices have climbed steadily, while even minor medical events that once cost a few hundred dollars can now run into the thousands.

If your emergency fund hasn’t been adjusted for these increases, it may not provide enough coverage when a health situation arises. And with healthcare expenses unpredictable and sometimes unavoidable, this silent drain can turn a well-meaning fund into an inadequate safety net. Ignoring these rising costs is a recipe for financial stress the moment life throws a curveball.

This Is Why Your Emergency Fund Isn’t Protecting You the Way It Did Five Years Ago
Image source: shutterstock.com

Unexpected Expenses Are Growing In Scale

Emergencies themselves haven’t gotten smaller. Natural disasters, car repairs, home maintenance, and sudden job changes all tend to cost more than they did half a decade ago.

When people calculate their emergency savings based on old expense numbers, they underestimate the magnitude of today’s unpredictable costs. Life has a way of being more expensive than we imagine, and the gap between your fund and reality can be shockingly wide.

Rethinking Your Emergency Fund For Today’s Reality

The good news is that updating your emergency fund isn’t just necessary—it’s doable. Start by recalculating your essential monthly expenses, including rent, utilities, groceries, insurance, and potential healthcare costs. Factor in any new financial obligations that have popped up since your last review. Then, consider a buffer for unexpected events that could derail your budget, like car repairs, urgent home fixes, or temporary unemployment.

Adjusting your fund to match current realities ensures it can genuinely act as a protective cushion rather than a false sense of security.

Practical Tips To Keep Your Fund Effective

Keeping an emergency fund truly effective goes beyond just numbers. Consider diversifying where you keep your money: a combination of high-yield savings accounts, money market accounts, or short-term, low-risk investments can help your fund maintain its value against inflation.

Regularly reviewing and updating the total amount ensures your fund keeps pace with rising costs and lifestyle changes. Automating contributions can take the pressure off while maintaining steady growth. And don’t underestimate the psychological benefit of knowing your emergency fund is truly ready for today’s world—it can provide a sense of control and calm when financial surprises hit.

Make Your Emergency Fund Work As It Should

Your emergency fund is only as strong as the environment it exists in, and the world around it has changed significantly in the last five years. By accounting for rising costs, inflation, and unexpected emergencies, you can rebuild your financial confidence and avoid the stress of discovering your protection is thinner than you thought.

We’d love to hear about how you’ve adjusted—or plan to adjust—your emergency fund in today’s landscape, or any experiences that taught you the importance of keeping it current. Leave your thoughts and stories in the comments below.

You May Also Like…

Why Are Emergency Funds Harder to Rebuild Than People Expect

9 Budget Categories That Blow Up After One Emergency

Why So Many Retirees Are Being Forced to Spend Savings Faster Than Planned This Year

Savings Strategy: 9 Micro moves That Add Tens of Thousands Over Time

Savings Leap: 9 Mid-Life Moves That Boost Long-Term Retirement Odds

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: saving money Tagged With: bank account, Cost of living, emergency expenses, emergency funds, emergency spending, finance, finances, general finance, healthcare, healthcare costs, Housing Costs, interest rates, medical expenses, Money, money issues, Personal Finance, saving accounts, saving money, savings, unexpected expenses

8 Money Habits That Increase Anxiety Without Helping

January 23, 2026 by Brandon Marcus Leave a Comment

These Are 8 Money Habits That Increase Anxiety Without Helping
Image source: shutterstock.com

Some people think money anxiety is just about not having enough. The truth is, the way you handle money can be just as anxiety-inducing as an empty bank account. Imagine staring at your finances, trying to “stay on top of everything,” only to feel your chest tighten, palms sweat, and brain spiral into “what if?” mode.

It turns out, a lot of our financial stress isn’t caused by dollars and cents—it’s caused by habits that make us feel busy, responsible, or cautious, but do very little to actually improve our situation. Let’s break down eight of these surprisingly counterproductive behaviors.

Obsessively Checking Your Bank Account Multiple Times A Day

It seems harmless, even responsible, right? Checking your balance frequently might make you feel like you’re in control, but it can quickly turn into a vicious cycle. Each glance at your bank app can trigger anxiety spikes, especially if you see pending charges or bills you forgot about.

Research shows that repetitive checking can heighten stress and worsen decision-making because your brain becomes overloaded with micro-worries. Instead of clarity, you get tension, racing thoughts, and sometimes even impulsive spending out of frustration.

Your account balance is a snapshot, not a full story, and obsessing over it rarely helps you plan or save. Creating a schedule for reviewing finances—like once a week—can maintain awareness without turning your day into a mini panic fest.

Comparing Yourself To Others Constantly

Scrolling through social media or talking to friends about money can trigger the comparison trap. “They bought a new car, I’m still paying off last year’s credit card,” is a familiar thought pattern for many.

Comparison doesn’t motivate; it triggers anxiety and self-doubt. Financial situations are deeply personal, shaped by debt, income, savings, and life priorities. Comparing yourself to someone else’s highlight reel is like judging your marathon performance against someone who’s already halfway to the finish line.

It can make you feel inadequate, overworked, and stressed about things that don’t actually matter. Focusing on your own goals, however small, provides measurable progress and relief from constant mental pressure.

Ignoring Budgets Because They Feel Restrictive

Many people avoid creating budgets because they fear it will feel like jail for their money. Ironically, not budgeting can create more anxiety than following one. Without a clear plan, every purchase triggers a moment of guilt or panic.

You’re left guessing whether you can afford things, constantly second-guessing yourself, and carrying the mental load of financial uncertainty. A budget is not a cage—it’s a map.

By defining limits and priorities, you can make confident spending decisions without that nagging “did I overspend?” stress. Over time, seeing your money allocated intentionally can actually be liberating, reducing financial tension.

Making Impulse Purchases As Emotional Therapy

Shopping to feel better is a classic stress-relief trick, but it backfires financially and emotionally. Every time you buy a mood boost, your short-term pleasure is overshadowed by long-term worry.

Credit card balances rise, bills loom, and guilt accumulates faster than the receipts in your wallet. Emotional spending also teaches your brain that money equals comfort, making anxiety worse when you don’t spend.

The smarter approach? Identify your triggers—boredom, stress, loneliness—and find low-cost ways to satisfy them. A walk, a phone call, or even a quick meditation can calm anxiety without jeopardizing your bank account.

Hoarding Receipts And Financial Papers Without Organization

Some people keep stacks of receipts, invoices, and statements because they think it might help later. The truth is, disorganized piles just fuel stress.

When you need information, finding it feels like searching for treasure in a hurricane. Hoarding can also create a sense of looming doom, like something bad will happen if you throw anything away.

Organization doesn’t have to be extreme; a simple filing system, labeled folders, or even a digital scanning habit can cut anxiety dramatically. Knowing where everything is provides mental space, so your brain isn’t constantly running “what if” simulations about lost documents.

These Are 8 Money Habits That Increase Anxiety Without Helping
Image source: shutterstock.com

Overthinking Every Financial Decision

Spending hours deliberating over every minor purchase—$5 coffee or $6?—can be exhausting. Overanalyzing doesn’t guarantee better choices; it breeds indecision and anxiety.

While thoughtful planning is important for big-ticket items, micromanaging tiny transactions is overkill. Constant rumination also hijacks your attention, reducing your mental bandwidth for more meaningful financial planning.

Letting go of the need for perfection in small matters builds confidence and reduces stress. Trusting your judgment on everyday expenses frees mental energy for decisions that actually matter.

Avoiding Professional Advice Out Of Fear Or Pride

Many people think they can figure out finances alone, believing that asking for help is a weakness. Avoiding professional guidance can heighten anxiety, because unresolved questions linger and stress compounds.

Financial advisors, accountants, or even reputable educational resources can provide clarity, reduce errors, and give peace of mind. The trick isn’t blind reliance—it’s informed decision-making.

Getting help often reduces stress immediately, creating a foundation for smarter, calmer financial habits. Pride may feel good temporarily, but clarity feels better in the long term.

Obsessing Over News Headlines And Market Fluctuations

Watching the stock market or economic news obsessively might feel like staying informed, but it’s more likely to spike anxiety than improve your portfolio. Markets fluctuate constantly, and day-to-day news is rarely actionable for long-term financial health.

Consuming too much financial media can create a sense of impending doom, even when your personal finances are stable. Instead, consider limiting exposure to periodic reviews instead of continuous monitoring. Controlled, intentional information intake keeps your mind focused and reduces panic-driven decision-making.

Rethink, Relax, And Reset Your Money Habits

Money stress doesn’t come solely from lack of funds; it often comes from behaviors that keep your mind spinning. By identifying habits that raise anxiety without real benefits—like overchecking balances, comparing yourself to others, or overanalyzing every decision—you can take steps toward calmer, smarter financial management. Experiment with pacing, organization, and professional guidance to reclaim peace of mind.

Now it’s your turn: what money habits have you noticed increasing your stress, and which strategies have helped you breathe easier? Feel free to comment with your experiences, tips, or aha moments. Your insight could be exactly what someone else needs to feel less overwhelmed.

You May Also Like…

7 Common Money Habits That Increase Stress Instead of Reducing It

8 Financial Habits That Quietly Drain Your Checking Account

How To Regularly Save Money At The Grocery Store

8 Toxic Money Habits That Are Silently Poisoning Your Relationship

Why Does Money Anxiety Increase With Age Instead of Decrease

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Finance Tagged With: anxiety, bank account, banking, Budget, budget tips, budgeting, Budgeting Tips, comparison, finance, finances, financial anxiety, financial stress, impulse purchase, impulse spending, Money, money habits, money issues, news headline, overspending, overthinking, professional advice, saving money, Smart Spending, spending

  • « Previous Page
  • 1
  • …
  • 5
  • 6
  • 7
  • 8
  • 9
  • …
  • 23
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • 10 Tactics for Building an Emergency Fund from Scratch by Vanessa Bermudez
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald

Copyright © 2026 · News Pro Theme on Genesis Framework