• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for College Planning

4 Tips to Pay Down Student Loan Debt

August 21, 2013 by The Other Guy 1 Comment

I can’t think of a better way to start of one’s adult life than to do so with over $35,000 worth of debt, can you?  Doesn’t the idea of starting your career already knee-deep in the hole sound wonderful?  In the words of Lloyd Christmas from Dumb and Dumber, “mmm..that sounds good.  I’ll have that.”

Or I won’t.

The average college graduate now leaves college with over $35,000 worth of student loan debt — many have said that the student loan bubble, which now tops $1 trillion (yes, that is trillion with a “T”) is the next major “crisis” in America.  I submit that it’s not the next major crisis. It’s already here.  In June, Congress couldn’t figure out what to do about student loans, so in  their infinite collective wisdom, they decided to let interest rates double from 3.4% to 6.8%.  Thanks.  We all appreciate that.

If you’re one of the umpteen thousands of people paying off oodles of student loan debt – how do you take care of it?

OG’s Student Loan Debt Tips

Step 1:

Be realistic with how much you owe.  Get an accurate count of a) who you owe; b) how much and c) the interest rates.  Many people have government and private loans spread hither and yon.  Before you create a repayment plan, you have to be honest about how much you have.

Step 2:

Build your personal financial plan.  This includes student loans, but also should include building a cash reserve, family planning, retirement planning, and other financial goals.  Having a singular mindset of  “I’m paying off my student loans before I do anything else… could lead to burn out and could impact how fast you reach your true goals.  Plus, depending on your career choice, you may be eligible for deferment or outright forgiveness.

Step 3:

Create a debt payment plan.  You have two options when it comes to paying off student loan debt: pay based on your income, or pay based on your indebtedness.  Visit www.studentloans.gov and compare payments to determine what’s best for you and your personal financial situation.

Step 4:

Work your plan and throw off discouragement.  Follow through with your well thought out plan.  You did steps 1 through 3, now just execute.  It will become tiresome and you will feel at times like you’ll never get it done – but you will.  Track your progress monthly and watch the balances fall.

Student loan debt can seem insurmountable, but with the right well-thought out plan based on your personal financial goals, you can pay those off quickly and efficiently and move on to your other financial goals!

Enhanced by Zemanta

Filed Under: College Planning, Debt Management Tagged With: Debt, debt strategy, Loan, repay, Student loan, United States

College Planning Strategy: A Creative (and Effective) Option

January 22, 2013 by Joe Saul-Sehy 33 Comments

Here’s a cool way one couple–we’ll call them Tim and Shelly–helped teach their children about responsibility AND made sure that none of their children were (in Tim’s words) the partier pumping the keg, hollering, “This one’s on my dad!”

First, some background:

Although Tim was an architect, you can imagine that the budget was stretched thin in a family of seven and saving for college was a difficult task. Somehow they managed. They actually put away enough for college for all five of their children on a $110,000 salary. They also owned fine retirement funds and had a nice house. Debt? No. Surprisingly, not even a mortgage.

I was honored they were my clients.

Tim and Shelly worried aloud about their responsibility to their children. They wanted all of them to attend college, but couldn’t afford any of the lifetime college student stories you hear about (think Van Wilder). So, together, we hatched a plan. They decided to help their child find scholarships and jobs to pay for the first year of college. When each child entered their legal working years (well before college), they helped each one find jobs and save nearly every penny for school.

How did they get a 15 year old to work hard toward college?

From the beginning, Tim and Shelly were clear: “You will pay for the first year of college yourself and we’ll reimburse the cost each year, based on some conditions.”


What Were the Conditions?


In an effort to discourage screwing around in college and have their children graduate in a reasonable timeframe,  they decided to reimburse each A or B with the inflated sum needed the next semester, including that percentage of the cost of room and board.

If college was $7,000 the first semester, junior had to pay that bill. If they received all A’s and B’s, Tim and Shelly reimbursed them 100% of the full cost that they could use the next semester to pay the bill.

While I’m not sure this method works for all children, Tim and Shelly found a way to help their children learn about the working world and responsibility while also paying for college.

When each child applied for college, three of them hadn’t saved enough for the private school they wished to attend. Tim and Shelly filled out the FAFSA form and showed their children how to apply for scholarships. Not one child had to take on student loans. I attribute this to the fact that the rules were clear and Tim and Shelly both helped guide their children.

How did it turn out? All five children graduated with straight A’s and B’s (except one child, who had one C in what Tim described was an incredibly brutal class). When they graduated, Tim and Shelly reimbursed their final semester, which gave each one a nice start for either the working world or for graduate school.

This isn’t the only creative strategy I’ve encountered. With a small amount of money, you could help lower your cost of college by using a quirky real estate-based approach.


The Takeaway


Prepping junior for college isn’t about sticking money into a fund. Sure, that’s important, but this is an easy time to teach your child lessons that she won’t forget. Spend some time deciding how you’ll teach your child the value of school and help them become responsible members of society.

Other college planning stories:

– Find Your Perfect College

– What Are the FAFSA and EFC?

– Maximizing Your Expected Family Contribution

Okay, team…what are some creative college savings strategies you’ve seen? Let’s talk scholarships and fun in the comments.

Photo: CollegeDegrees360

Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: College Planning Tagged With: college planning, creative college planning, creative college strategies, saving for college

Expected Family Contribution: Digging For (and Finding!) Financial Aid

January 14, 2013 by Joe Saul-Sehy 19 Comments

As you’re waiting for that perfect college to give you the nod, “Expected Family Contribution,” or EFC, is a key term you need to understand BEFORE filling out the FAFSA form (…and you should be filling out the FAFSA form NOW).

Expected Family Contribution is the amount you’ll be expected to pay out of pocket toward your education. Here’s the simple formula:

Cost of college – your need = Expected Family Contribution

Sometimes it’s easier to understand what’s being asked by seeing the equation drawn out. Not to be completely obvious, but that equation makes three points clear:

– You can lower your bill by attending a less expensive institution
– You could attend a more expensive school and not pay a dime more if your need covers the difference between the cheaper school and more expensive school.
– You can lower your Expected Family Contribution by attending a less expensive school, increasing your need, or a combination of both.

Like I said, pretty obvious, huh?

If it was SO obvious, though, why do so many people overpay for college? Not my readers, though, right? We’re so lucky we hang out together!


EFC is about Income and Assets:


An overall note about assets: Assets are excluded for most people with adjusted gross income below $50,000.

Child Money – The FAFSA treats dependent student money as MORE IMPORTANT than parent money in the EFC equation.

Rational? While parents may have other priorities, the child has one: graduate.

Therefore: 20% of dependent and independent student assets count against them when calculating EFC. Little Jimmy’s got $10 in his savings? That’s $2 less financial aid school will give him.

The EFC calculation includes an “asset protection allowance” for parents and independent students with children before ANY money counts against their EFC calculation. How much is the allowance? While the amount varies depending on age and marital status, the average family receives a $45,000 allowance. After that, only 12% of assets are used toward the family EFC calculation.

So, to summarize:

– Parents and Independent Students with Children receive an asset protection allowance of around $45,000
– 20% of dependent student assets are used for the EFC calculation
– 12% of parent assets are used
– 7% of independent students with children assets

Got it? Awesome.

What’s the rational for these numbers? Parents and students with children have to make ends meet at home first, and then can focus some of their money on college. Students in college should spend a higher percentage of assets on education.

I hope you’re starting to see that WHERE you save is an important factor when deciding how to save for college. Clearly, keeping money in a parent’s hands vs. saving in junior’s name can be a good idea in many circumstances.

Big Point: It’s illegal for parents (or anyone other than the child) to remove money from junior’s name to avoid horrible EFC consequences (or for another other reason). However, junior can purchase items beyond food, clothing and shelter with his own money. You can also choose to save more money (or an equal amount) into the parent’s name for college.

Also notice – 529 plans….they’re in a parent’s name.

…and that money in life insurance policies? It doesn’t count against you at all. As far as EFC calculations go, it doesn’t exist.

Want more on the best places to save for college? Check out: College Savings Simplified, The Best Places to Save for Education


Income


Expected Family Contribution
Forget full time work for dependent students. It weighs heavily against EFC!

Yeah, I know, you want junior to have a job in college. Guess what? Every dollar junior earns (after a small allowance) counts more severely against his need than income a parent earns. Once again, there’s good rationale for this: junior should be focused on graduating, so if he works, then he should pay every dollar he makes toward school.

As with assets, there is an income protection formula:

– Dependent students receive an income protection amount of $6,000. After that, between 22 and 47% of the amount junior earns is used for EFC calculations. (It’s a sliding scale with percentages rising as the income level rises.
– Independent students with children and parents receive a much more generous allowance. For parents, the number ranges from $16,000 to $55,000 depending on the number of dependents in school and overall family size.

As you can see, parent income counts against need, but once again, parents only have a smaller percentage of their income that counts against EFC.

Rationale? Parents have many priorities besides a dependent student’s education, while dependent students need to save. The EFC allows for a small part time job to learn skills, but punishes students who work full time. Work on graduation!

Good news for me: during the EFC calculation, because I’ll have two in college at the same time, my total parent contribution is divided by two.

Retirement

How do retirement accounts factor into EFC? Money saved into retirement accounts DOES COUNT against EFC. Rationale? You should expect to sacrifice for a short time to help junior through college. If you’re the one headed to school, graduation quickly is your number one priority.


Strategies


If you’re reading this with young children (or just a glimmer in your eye), realize these calculations can change. However, I’ve been teaching clients about EFC since my children were born, and things are roughly the same as they were then. So:

– Save money into the parent name instead of a child’s name.
– Save aggressively into 401k plans BEFORE college years start because you may have to lower your contributions during college years.
– If you’re fairly certain you’ll be a financial aid candidate, cash value life insurance may be an option (although I generally shy away from these products)
– Forget about junior working full time during college. You’ll just elongate the process for him and you.
– Use Junior’s money to buy assets he’ll use during college and for expenses that don’t include food, clothing and shelter. If you’d like, use the money YOU save by NOT covering these non-essentials into a plan in the parent’s name.

Fun, huh? Financial aid programs actually make a ton of sense to me AND it becomes much clearer HOW to save when you know the keys to the FAFSA and EFC.

What parts of financial aid are most confusing to you? Leave them in the comment section and we’ll try and tackle those next.

This is only one piece of an overall college financial plan. Check out: 5 Steps to a Successful College Financial Plan.

Photos: College student w laptop: Ed Yourdon;

Enhanced by Zemanta
Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: College Planning Tagged With: 401k in efc, Asset, Child, EFC, FAFSA, IRA in efc, life insurance in efc, Student financial aid in the United States

Want More Money For College? What the $%#! Are FAFSA and EFC?

January 8, 2013 by Joe Saul-Sehy 22 Comments

Bill & Caitlin want to put their children through college, but like many people, they had other priorities. With three younger children, it’s been a difficult road to save for their oldest. Now Jennifer is a senior in high school, and they were in my office with the same look a football team has when they’re down by five points and have 50 yards to go with only 8 seconds left in the game.  Time for some drastic action.

Luckily, Bill & Caitlin had some room to work with to make their chances of aid better than they’d expected. We also made it easier for them to pay for college by making some changes to their overall financial plan.

But first, there were some crucial terms Bill & Caitlin didn’t understand that we had to define. Their whole college aid strategy would be predicated on knowing the rules of the game, and off these rules were wrapped up the terms “FAFSA” and “EFC.”


The FAFSA


The Free Application for Federal Student Aid is more than the name implies. Although this is the government’s financial aid program to apply for the Pell Grant, it also opens up nearly all need-based aid programs you’ll ask for in traditional college programs. Sure, Bill & Caitlin had heard of the FAFSA form before, but they were about to make a critical mistake: they weren’t going to fill it out because the chances of them receiving federal government aid was highly unlikely.

That would be a huge mistake.

Don’t avoid the FAFSA in your search for college funding options. Here’s a good way to think about financial aid programs (although schools and states wouldn’t present the information this way): schools will not give you financial aid until you bleed the state. The state won’t give you financial aid until you bleed the feds. For this reason, EVERYONE works through the FAFSA form. While most people will be denied a Pell Grant, this is also the form to apply for subsidized and unsubsidized student loans, and unsubsidized student loans programs are open to nearly everyone. It’s also the way to apply for almost every need-based aid through states and schools.

Key point: Fill out the FAFSA form, even if you think you won’t receive any aid. When? Start now.


EFC


This is another “biggie.” Expected Family Contribution (or EFC), is the amount the government says you should be expected to pay out of pocket for school before aid programs kick in. Bill and Caitlin were making some huge mistakes in their money management that was actually costing them EFC dollars.

Your need will be based on the difference between the cost of the college and the amount of your EFC.

            Cost of school minus EFC = need

Based on your need, your school’s financial aid officers will create an aid package.

It’s important to remember that the acronym is eFc (expected FAMILY contribution, not ePc (expected PARENT contribution). Schools will look at the income and assets of the student as well as parents. They’ll also examine how many other family members there are and the number that are also attending college.


Schools may not have the same EFC calculation. There are two. You should ask which your favorite institutions use:

–          Federal EFC calculation. This is the most used number and is determined using the FAFSA.

–          Institution EFC calculation. This calculation is used by individual schools to determine their own EFC. While they may rely on the FAFSA as well, individual schools may have additional criteria they consider when determining aid packages.


Takeaway Information


So, Bill & Caitlin had a ton to consider, but a few points were obvious already:

–          Understanding the basics of the FAFSA before filling it out would help them calculate ways to better reflect their true EFC.

–          Ask schools what EFC calculation each uses and find out any institutional discrepancies from the national EFC calculation BEFORE applying for financial aid.

Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: College Planning

My Favorite Quirky College Saving Strategy

August 14, 2012 by Joe Saul-Sehy 28 Comments

My niece, Madeline, heads to the College of Charleston today. Good luck, Maddie!

Sometimes people don’t want to invest in a 529 college savings plan. I understand that thinking. Once college is over, the investment is gone and what does mom or dad have to show for it? Hopefully you have an educated child with a good enough job to afford a really big house. They might even let you sleep in their guest room if you’re lucky.

What if there was a way to save toward college but keep the investment AFTER junior finished graduation? Wouldn’t that be cool?

There is such a beast, but there are caveats, as there are with any investment:

First, you have to be interested in rental real estate.

Second, you have to have enough money for a down payment on a piece of property.


Here’s how it works:


Find a house near the school junior plans to attend. Make your best deal for the home. There are plenty of sites that discuss how to purchase rental real estate. I recommend you read Paula Pant’s story Is This House a Good Investment at Afford Anything.

Interest rates are low now, so this is an especially good time to jump on this strategy.

Complete the purchase and perform any needed repairs to rent it.

Ask junior if any friends would like to live in the house with him/her. If not, place an advertisement in the local newspaper and on Craig’s list. PT Money recently ran a good story about how to check the credit of your renters (read Find a Tenant: Credit Check and Screening). The kids might not have any credit, but mom or dad probably do.

Rent the house for enough to cover the mortgage costs and upkeep. Even if junior’s friends become your renters, make sure everyone pays a security deposit and signs a lease. Keep it professional.

…and here’s where it gets fun.

Hire junior to be your property manager. For this to work, JUNIOR MUST DO SOME ACTUAL LABOR. Make a list of official duties, create a pay scale, and have junior sign an employment agreement.

Pay junior a wage. You may want to hire a local payroll firm to deduct taxes and create an actual paycheck (this service costs far less than you’d imagine). If he does well, give him bonuses liberally.

Junior uses the wage to pay tuition costs.

At tax time, claim the rental house income and expenses on your taxes. This includes the cost of junior’s labor.


Why this works:


You’re receiving a huge discount on your college expenses AND collecting any excess rent plus keeping any appreciation on the property.

Junior, at best, is collecting the wage while in the 10% tax bracket. You’re probably in the 25% bracket if you’re like most people who read financial blogs. You save 15% off the cost of your college simply by paying junior to take care of your property for you, plus you have a built-in manager (no real out of pocket additional expense…you were going to have to pay that money out anyway for school costs).

Additionally, you receive MORE savings off of the education expense because you’re deducting junior’s salary as an expense from your taxes.

I need to be 100% clear here: this can’t be a tax avoidance strategy. You’re asking for an IRS audit that you’ll lose if you simply buy a house a funnel funds for junior’s college through your property costs.

Your goals should be: 1) own rental real estate; 2) make a gain on your investment by deducting all legal costs of owning property; and 3) employ junior for a fair wage as he/she heads to college. If junior uses this money for school, great.


If not, you’ll have other ways to make your child sorry they didn’t listen to a good parent’s advice!

 
Photo: College: 401k 2012

Enhanced by Zemanta
Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: College Planning, Real Estate Tagged With: 529 plan, college saving plan, college saving strategy, Property manager, quirky college savings, Real estate, Renting

5 Summer Activities to Create Money Savvy Kids: High School

June 26, 2012 by Joe Saul-Sehy 29 Comments

Ah, we made it! It’s most rewarding yet the most challenging to work with high school students on money management.

While these activities are the most fun for parents, high school students are more difficult to engage than younger children.

If you don’t have high school age children yet, you may not know this, but your brains will disappear for about four or five years.

Looking for tips for younger children? Try:

5 Educational Summer Activities For Kids – Early Elementary

or

5 Summer Activities to Create Money Savvy Kids: Upper Elementary to Middle School


5 Great High School Activities


1) Family book club. Right now, my 17 year old kids and I are reading I Will Teach You To Be Rich by Ramit Sethi. If you haven’t read this book yet, by all means, start now. It contains powerful advice wrapped in easy-to-understand language.

Every day the kids read a chapter. Then, at dinner, we discuss that day’s reading. Sometimes these conversations devolve (“why does a stock go up or down?” “what’s a good Roth IRA investment?”), but I love it. Who doesn’t want to have relaxed conversations about money with a curious 17 year old?

Why I like it: I get to ensure my kids get to college with some clue about money before they arrive. Because I made sure the book was fun and easy to read, and because I don’t preach, we’re able to have great talks about money.

2) Engage kids in the Family Meeting. If you’ve read this blog before, you’ll know that I love the idea of a family meeting. Budgets within a family are more about good communication than about counting pennies. If everyone is on the same page spending each day will be more careful, and life is made up of these little crisp 24 hour periods.

Some people have a violent reaction to this advice. “Show my kid my bills and my savings? That’s none of their business.” You are correct, but lets challenge your assumptions: why is it taboo to talk about your financial situation with others, especially those as close as your teenager.

Boundaries must be drawn. You’ll have to explain what happens when the whole street learns about your finances. But in the bigger picture, if they help you pay the bills, evaluate savings and plan large purchases, you’ll hand them a lifetime of knowledge that they’ll appreciate down the road.

Why I like it: When we began talking frankly with our children about bills and savings, they began to see how tight every month is for the average family. Next year we were planning on going to France for their graduation. The reality of two children in college at once has set in and we’re downgrading the vacation plan to a rental house on Lake Michigan for seven days. No groans from the kids because they understand the math behind the decision.


Young woman posing beside the News Corporation building sign during an internship

3) Find a job. I’m not talking about grabbing the local Dairy Queen gig (if I had that summer job I’d weigh about 750 pounds!). I’m talkin’ about helping junior through the process of fighting for a summer internship at a resume-building position. If they’re interested in engineering, try to find opportunities with a large local company. If law or medicine, apply at  the hospital, a law firm, or the local doctor’s office.

There’s a ton that junior learns while creating a resume, dressing appropriately and speaking well. The training involved in competing for these positions is a good primer in adult life skills.

Why I like it: By working in a professional environment, high school kids get a first hand look at how business works. Studies have shown that people who work in “real jobs” before college are more likely to do well in the classroom because they know how their learning might apply in the real world.

4) Scholarship hunt. Finding money for college is a full time job. The internet is brimming with opportunities for money, but you have to know who to ask and what scholarships to pursue. Most high schoolers only scratch the surface when it comes to searching for scholarships.

Instead of one-offing each opportunity, we found quickly that many of the scholarship opportunities were similar. My kids could write a couple of basic essays and then modify them to fit each particular offer. Most needed references from teachers and community members. We didn’t just learn about scholarship, we learned about creating systems to efficiently attack more quickly.

Why I like it: By formulating essays and asking for letters of reference, kids learn about the importance of written and verbal communication. They also realize that “going it alone” isn’t usually a good idea. It makes sense to find some powerful friends to help you….AND my kids were surprised that most powerful people want to help.

5) Board games. I’m back with more board games to teach the family about money. This time the games are downright fun for adults. Games such as Acquire can teach simple mergers and acquisitions. Power Grid is a modern-day version of monopoly involving power companies. And, in this year when the politics of the nation are up for grabs, 1960: The Making of a President is a good primer on the campaign process while also serving as a fun way to learn some history.

Why I like it: Board games are a great way to spend time with your kids. Instead of arguing or fighting about curfews and money, you’ll enjoying each other’s company over a communal activity.

How do you teach high school kids about money? Let’s have some more ideas in the comments below!


Photo Credit: Reading: NannySnowflake; Internship: ChesCrowell

Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: College Planning, kids and money, money management, Planning, successful investing

Why I’m a Upromise Fanboy

February 21, 2012 by Joe Saul-Sehy 6 Comments

Let’s cut to the chase:

1) I love doubling up on point programs. Getting stuff for free that I would have paid for anyway = awesome.

2) It isn’t just a college savings fund, although I have a 529 plan for my kid’s education. After my kids finish school, Upromise will pay me in other ways (a savings account, student loan repayments or a check).

I’ve been a Upromise member since 2004. I knew going in that Upromise is a marketing plan. They want to watch me shop. Normally, this would scare me almost as much as catching my parents skinny dipping. In this case, the rewards justify the means. They aren’t interested in AverageJoe who lives at my particular address. They’re interested in the fact that I’m a 44 year old money nerd with 16 year old twins. I’m a statistic. Sigh.

Signing up is free. There are no strings attached. You won’t get billed later if you decide to stay in the plan. Nothing. Nada. Free.


The Bad News


Whenever there’s a free service, you’re going to somehow pay for it. Upromise is no exception. When you try and sign up, they’ll immediately pitch you their reward credit card. While this isn’t a bad choice of cards, if you’re living a cash only lifestyle, it’s usually a better choice to press the “no thank you” button on the lower right corner of the screen.

You’ll also receive emails from them about partner offers. If you don’t like these, give Upromise an email address that you use for this sort of thing.


The Good News – Double and Triple Dip Point Plans


You can score double or triple rewards with this program. Let me show you how:

1) Let’s say you’re dining out. Before heading for the restaurant, you pull up the Upromise dining plan page. Restaurants are arranged by your zip code, so it’s easy to see what’s close by. Pulling up a random zip code 63108, I find many restaurants that pay Upromise points. Notice also that these restaurants don’t necessarily give points every day. There are so-called black-out dates, so watch for those.

2) Sign up for another program such as iDine. If you head to the iDine website, you’ll be able to pull up their list of restaurants. Go ahead and plug in the random zip code (63108) again…. Wow! Most of the same restaurants are in both plans. With iDine I’ll have to fill out a survey about by experience, but now I’ve received points from Upromise and from iDine.

3) Check out your bank or credit card point plans. You may also receive points by using a card with reward features.

You’ve just triple-dipped points.


More Good News – Upromise Pays for a Wide Range of Merchants


I’ll tell you a secret.

I don’t pay much attention to whether Upromise pays points at a retailer or not.

I could totally game this system like I showed you above, but I don’t as much as I should. However, I still rack up points accidently.

An example: although I’m not really a Walmart fan, there are two in my town. It’s impossible not to end up searching the aisles of Walmart nearly once a week. Walmart used to pay Upromise Rewards at a 1 percent rate. Had I not been writing this article right now, I would have never known they have a promotional rate until 2/23/12 of 5 percent rewards. I would have scored even more rewards doing what I normally do, and not noticed any difference in my lifestyle.

…all because I took 10 minutes to sign up.


How It Works


You’ll accumulate points in the program. Once you reach $10 (in some cases it’ll need to be more), you can sweep your earnings to a high-yield savings account, a 529 plan, pay down a Sallie Mae student loan, or request a check.


To Summarize


  • The plan takes 10 minutes to sign up for
  • I link credit and debit cards to the account
  • Whenever I use those cards at participating retailers, I receive rewards
  • I ALSO get rewards through other programs, such as my credit card or other reward programs
  • I redeem rewards when I hit $10 or more


When I was a practicing advisor, I recommended that all my clients sign up for Upromise. The firm I worked with wasn’t affiliated with Upromise and I received no compensation from them. My job was to help my clients improve their financial situation. I’ve been a Upromise member since 2004. Although I do receive affiliate income from them now, it’s something I’d recommend regardless (similar to Mint and an ING savings account….two other plans I recommend and have enjoyed personally).


How to Find Upromise


Here’s a link to the Upromise website: Upromise Reward Program.


Do you use Upromise? How do you double and triple dip reward points? Join the discussion in the comments below.

Enhanced by Zemanta
Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: College Planning Tagged With: double dip points, double dip rewards, triple dip, triple dip points, triple dip rewards

College Savings Simplified: The Best Places to Save Money For Education

February 14, 2012 by Joe Saul-Sehy 3 Comments

While I tend to do things the hard way, finding college savings isn’t one of the areas where I complicate a task. For some reason, my sixteen year old twins helps me focus on whether a 529 plan, Roth IRA, or savings bonds will treat me right.

So, even though I’ll generally remember to add softener to the washing machine just after it’s finished, I understand how college plans operate up and down.

If you’re saving for college, it’s important to categorically work through the details of each plan to determine which best fits your needs.

…because there IS A right way to save for college, and a wrong way to save.

The bad news? The BEST way to plan college savings differs depending on who you are and what your circumstances may be.

I know that sounds generic and evasive, but it’s true: the best way to save for college will depend on your own income, current savings and college goal, so the best course of action will be this:

Know what plans exist and how they’ll affect your ability for financial aid before investing a dime.

If you haven’t yet, you should read the pieces on:

– 5 Steps to a Successful College Plan – This will guide your plan of attack when creating a college plan.

– Narrow Your College Search – This will focus your college search to those schools which are the best fit, both financially and for your particular interests.

After reading these two thorough primers, you’ll be armed with an idea of the cost and feasibility of your favorite school.


Let’s now save for the goal: education.


Complicated Ways to Save For College


Some methods of saving for college are so fraught with risk that I’m reticent to ever recommend them to people. That doesn’t mean that these college savings plans are bad; on the contrary, they all have some huge upside potential, provided that all the right conditions exist. Here are a few:


In-State Tuition Reimbursement Plans – Many states offer plans which reimburse the cost of college credits at a later date. This can be a fantastic way to lock in the price of a college, provided that everything goes according to plan.

Upside: Paying today’s rates for in-state public institutions. Don’t have to worry about market conditions or returns on investment.

Downside: Have to worry about state plan solvency. More than one state has already notified participants that they might not be able to meet their obligation. In fact, some plans no longer guarantee that your dollars will lock in present rates. Instead, these plans invest your money with state funds. Who wants their state government as a money manager?


Life Insurance – Some life insurance plans, such as whole life and universal life are presented as attractive options for education savings vehicles.

Upside: These plans are financial-aid friendly. When completing a FAFSA application, money inside of life insurance policies doesn’t count against your savings, acting as a nice shelter. Also, if for some reason the insured passes away, money is available for education.

Downside: You may have to cancel your life insurance policy to withdraw education funds. What if you still need the policy? Also, do you really need life insurance? If the answer is yes, and you’re sure that you will no longer need coverage after this incident, then this might be a good option.

Watch out for fees, too. Not only will you pay for insurance, but often a policy which offers stocks and bonds are filled to the brim with fees to manager and (maybe more importantly) to withdraw funds.

Still want life insurance in your account? Read this good article at FinAid.org for a more in-depth argument: Variable Life Insurance Policies.


Annuities – Tax deferred savings may seem like a good option for education planning. Why save into an account that’ll be taxed every year when you can shelter your money?

Upside: These accounts are FAFSA friendly, meaning that they are not usually counted in the equation for financial aid. Many annuities offer some flexible savings options.

Downside: Too many to mention here, but mostly: fees and penalties. Make sure you’re going to be over age 59 1/2 before you remove money, because if not, there’ll be IRA penalties on top of whatever the annuity company may charge.

Taxes can be a bear. Here’s why: when you withdraw cash, dollars in the account are removed in a LIFO (last in-first out) accounting manner. This means that all interest on the account must be taken before principal is removed. Why is this a big deal? Taxes. You’ll pay taxes as if you earned the money in the year you remove the money. This income may also make your chances of receiving financial aid worse in the following year.


Less Complicated But FAFSA or Tax Return Unfriendly


Stocks or Stock Based Mutual Funds – These accounts can be used whenever you wish, assuming the dollars aren’t inside of a tax shelter. In some years there’s a chance of nice returns, too.

Upside: Returns. While there are no guarantees, over long periods of time the instability of a stock or stock-based exchange-traded fund or mutual fund can be countered with a high average annual return.

Downside: Risk. There is a chance you could lose a substantial amount of principal if you don’t monitor or manage your money. Also, this type of investing isn’t FAFSA-friendly. Dollars that aren’t sheltered count directly against your chances of financial aid.


Bonds or Bond-Based Mutual Funds – More stable than stocks, these types of funds have performed attractively over the last ten years.

Upside: Returns with generally less risk than stocks above. Because bonds throw off dividends as one of the main methods of creating returns, these investments often perform more consistently than stocks.

Downside: Taxes. Bonds often throw off an attractive dividend that savers often reinvest. This money, unless it comes from a special type of bond such as a municipal bond fund, is taxable every year, slowing down your return. While there has been tax reduction with capital gains taxes, these are taxed as income, which is a much higher tax bite. These are also FAFSA unfriendly investments, unless you use government savings bonds. These can be good to you tax-wise, as long as they’re titled correctly and cashed in the same year as you’re paying qualified education expenses.


The Easy Way To Save For College


Roth IRA Plans – A Roth IRA is generally a retirement savings vehicle. Money invested gives you no tax benefit today, but can be taken tax free during your retirement years. You’ll have to follow a few rules, but you are allowed to withdraw funds for college. You may also use nearly any time of investment you choose inside of a Roth IRA.

Upside: Tax shelter. This money can grow tax deferred for education, and if you end up not using it can be used later for retirement, tax free.

Downside: Retirement savings. The best use of a Roth IRA is clearly as a retirement savings vehicle. While money can be used for college, why miss out on the main Roth opportunities around retirement?


Coverdell Education Savings Accounts (ESAs) – These plans allow you to save not only for college, but also for earlier years of private school expenses.

Upside: Flexibility. This tax shelter allows you to use money for many types of education options, so it’s great if you’ll have elementary, high school and college savings needs.Classroom

Downside: Funding. Man, these accounts are small. Because you can only place $2,000 per year into this type of account, they often don’t make sense. I’d also meet people with very limited funds in a few different Coverdell IRAs. Who can manage all these little accounts effectively?

The IRS page on Coverdell ESAs is very helpful. Find more details here.


529 Plans – State sponsored education plans offer a good tax shelter, are somewhat FAFSA friendly, and eliminate taxation of dollars as long as funds are used for qualified education expenses.

Upside: Amounts of savings. You can pack tons of money into these plans. Most allow as much as $300,000 to be invested into a 529 account. These accounts can either be in self-directed fund options or can be in age-based options. If you don’t use the money for the primary beneficiary, funds may be used by siblings, parents, children or other close relatives. In these plans your choice of education institutions isn’t limited to a single state. You may use these dollars in any state and still receive the tax benefit.

Downside: Money earned in a 529 plan must be used for education expenses or you’re slammed with penalties. If you aren’t sure about saving for college, funding your Roth IRA first might be a better idea, because while these funds are flexible for college funds, money will be trapped here.


Of these, the savings option I like best is a 529 plan, because of its flexibility, range of schools that accept funds, and tax treatment. While it isn’t best for everyone, for the vast majority it’s where you should save for college.


Here’s How To Evaluation 529 Plans


Just like we’ve told you previously that Morningstar is the best way to evaluate mutual funds, I like savingforcollege.com to evaluate 529 plan options.

Here’s a link to savingforcollege.com. Have a look around to see how thorough this site is on investing for education.

The Good – Lots of information on FAFSA and college savings options. Great reviews on the fees associated with 529 plan savings accounts.

The Bad – While fees are certainly important, I’m about returns. Savingforcollege.com does a poor job of comparing how money managers work unless you’re willing to fork over some money for a premium membership. When compared to more robust money management sites such as Morningstar.com, there’s no reason to pay for this information.


Can I recommend a single-best 529 plan?


Absolutely not.

Check your state’s plan options at savingforcollege.com to see how they stack up. Always evaluate a few national plans to see how they compare against your own state’s options.

My favorite national plan is UPromise, though I also like the T. Rowe Price option.

Why Upromise?

I’ll attack this next week, but here’s a preview: not only is the plan managed better than most options available, but if you sign up your credit and debit cards, but using the Upromise Rewards program (which you can sign up for whether you use a Upromise 529 plan or not) you’ll receive points which can translate into extra money into the 529 plan later. Combine the benefits of low cost investing, good management and extra money, and you’ve found a plan that’s hard to beat.

If you want to compare Upromise with your state’s plans, here’s a link for more information: Upromise is the smart way to save for college!

Enhanced by Zemanta
Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: College Planning, low cost investing, Planning, successful investing, Tax Planning Tagged With: FAFSA, FinAid.org, life insurance, Mutual fund, Roth IRA, Student financial aid in the United States

Find Your Perfect College

February 8, 2012 by Joe Saul-Sehy 15 Comments

There are many unsuccessful methods you could use when choosing a college. I’ve made a list of a few:

  1. Attend the school your boy/girlfriend decides on. Really, it’ll last forever. Promise.
  2. Choose among the fliers that come in the mail. Why search when they can find you?
  3. Great football/basketball/rugby/volleyball team? That must = great academics.

Choosing a college is a decision that can impact your entire life. You should use a better method to decide than those above.

My Story: I worried a ton about what college I should attend, just like you might be right now. I knew the weight of the decision: I might meet my spouse while in college. I would make friends that would last my entire life. Lots of thoughts. Most of them misguided. Hopefully, you’ll do a better job than I did.

In the end, I chose a college based on a running scholarship and the fact that it was a military school far away. It was one of the most half-baked decisions I’ve ever made, and within two years I was back at a state university closer to home. That said, I would never discourage someone from a military college education. It was difficult and enlightening–just what I needed at the time. More about that another day.

While every education decision is intensely personal, here’s what I should have done:


What Are Your Strengths?


Many people ask “what do you want to do” while you’re in high school. I don’t know about you, but I had no clue. I wanted to be an architect because I thought Frank Lloyd Wright was cool. I can’t draw stick people. Slight problem. I wanted to be a lawyer because I thought those shows on television were cool. People were well dressed. I didn’t know that you sat in a room much of the time reading law books. Boring (for me). Another problem. I might have been an engineer if I didn’t think that was just the dude who drove the train.

List your strengths. Had a been realistic, I would have known that:

– I’m creative—not in a drawing or musical way, but I can quickly come up with creative solutions to a problem

– Because I stuttered at a young age, I’d overcompensated and become a good public speaker

– I’m not great in large groups, but thrive in small discussions

– Because of my ADD, I love to dig into problems and bury myself in finding solutions

List yours. What tendencies do you see?


What Schools Match Your Strengths?


Your next task is to eliminate schools that don’t match your taste. There are few ways to figure out what is a good match than to:Cambridge college buildings along the River Cam with a punt on the water

  1. Make a “long list” of colleges you may wish to explore further. How do you do this? Using your strengths list above, go to the Peterson’s College Search: College Compatibility Tool. You’ll see we use Peterson’s a ton for college planning at our house (as I did when I was a practicing financial advisor). The reason for this: it’s a comprehensive, free resource that’s easy to navigate. This site saves you a mountain of time and energy looking for phone numbers, admission info, financial aid, student body facts, and more. I’m not compensated by, nor do I have any affiliation with this company or website. I’m just a huge fan and user. Some people endorse Presidential candidates. I endorse websites. Another point about this website? U.S. News and World Report has a similar program, but they charge around $30. Ouch.
  2. Visit some schools. You’ll begin to see if some scare you because they’re too big or suffocate you because they feel too small. I didn’t do this myself. What a mistake. In fact, both colleges I attended I’d never set foot on before I went there. Use Petersons to link to the Facebook page of a school, find the phone number for admissions, and schedule a tour and briefing on the college.
  3. Read. I swear my twins come from different parents. My daughter reads voraciously about colleges, while my son would rather visit the school. However, once he gets to the college, he studies the literature about the place non-stop. Some of her favorite books are:
    • Treasure Schools: America’s College Gems. We would have NEVER contemplated visiting some of the tough, beautiful little schools across the country if my daughter hadn’t read this book. It succinctly makes the case for a small school education.
    • Colleges That Change Lives: 40 Schools That Will Change the Way You Think About Colleges. This book makes the case that it doesn’t take an Ivy league school to receive an Ivy league-style education. If you match your strengths with some of the 41 schools listed, you’ll find a winner.
    • The Insider’s Guide to the Colleges, 2012: Students on Campus Tell You What You Really Want to Know. Want a simple statement about how awesome this book is? Try this: it’s in the 38th edition. What my kids fear is that there are some hidden reasons not to attend their favorite school. By giving some insight from a student’s perspective, this has worked to quell some fears.
  4. When we visited MIT this summer, they had great advice: read some of the student and faculty blogs attached to the university. You’ll get a great feel for some of the personalities and exciting events on campus. You’ll also read some of the dirt about the school as if you were already there. Don’t just stick with the school-sponsored blogs. A simple search could lead you to some eye-opening blogs from students.


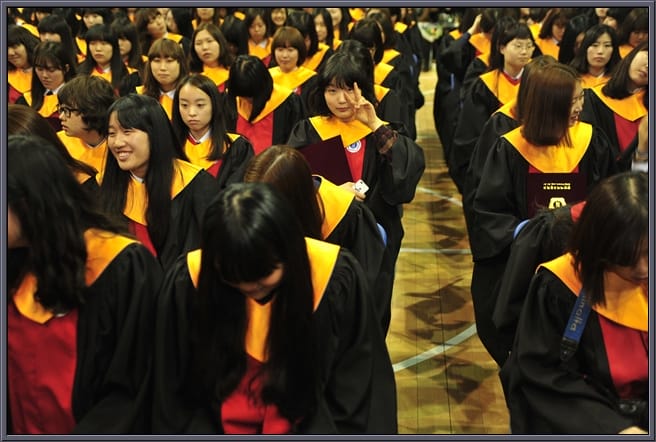
Rows of graduates in black gowns with yellow and red hoods at commencement

How Competitive Are These Colleges and Will I Be Accepted?


If you’ve read and researched, you’ll already know how competitive these schools may be. But, there are two sources which we use to dig further:

 Will I be accepted into the school? There’s no sense pursuing a school if I can’t meet the entrance requirements. For this, we’ll use Petersons again, but this time, we’ll dig into the actual school page. We’re looking for the Admissions page, which tells us testing criteria (how many students beat common scores on the SAT, ACT and possibly others) and what will be required to apply.

You won’t want to apply to every school on your “long” list (which hopefully is shorter by now), because there’s a fee for each one. Only apply to schools you seriously hope to attend.

Is the school competitive? To find out how a school ranks in your particular area of focus, we’ll turn to U.S. News and World Report annual ranking of colleges and universities. This site duplicates some of the Peterson’s information, while also providing additional ranking details in many areas. Much has been made of the U.S. News and World Report rankings and some school’s attempts to manipulate these rankings.

Here’s the deal for us: a school’s ranking isn’t the final factor when choosing a school. However, it is another barometer for us to watch when making a choice.

An example: my son seems to be focusing on engineering programs. He also likes Catholic schools. Unfortunately, Boston College, a school he liked a ton, doesn’t have an engineering program (that’s not the end of the road for Boston College, but it’s a big red mark against it). Notre Dame does have an engineering program, but U.S. News and World Report ranks it in the mid 50’s, while the University of Texas (in—state public) and Texas A&M (in-state public), both rank in the top 10.

While he may be able to secure enough scholarships to attend Notre Dame, and while it certainly is a door-opening name in some circles, he’s more likely to focus now on the less expensive in-state options.


What Do the Schools Cost?


Attending college is a cost/benefit decision. While I’ve had friends who ran off to school without any purpose other than beer and women, or who majored in a degree without employment prospects, it’s probably a better idea to spend your money wisely and study a field that’ll end in gainful employment opportunities.

I strongly believe that you should NOT study something just for the job prospects, though. Keep your focus on your passion and the dollars will follow, as long as there are some jobs available. I’ve met many people who felt they’d wasted their life chasing a dollar instead of their dream.

Research your dream jobs to find out what the employment prospects look like. While dreams are fine, they’re better if they pay. Between two dreams, choose the one that’ll secure your income first.

As a personal example, I’m a recovering financial advisor. I also wanted to write. I spent the first years of my life earning a great living in the financial planning industry. Then, once I’d accumulated enough to support my new career, switched to writing. This way, I’ve been able to chase both dreams, where if I’d become a writer first, it would have been much more of a struggle.

Once again, head to Peterson’s College Search to find out the “retail” cost of colleges. I’ve placed retail in quotes so you don’t have a heart attack when you see the huge difference in price between many private colleges when compared to their public counterparts. While a public school may still end up being more expensive, it’s important to focus on how much you’re going to actually pay when you attend a school. You may be surprised to find that the bottom line isn’t always much different between public and private schools.

While we visited schools this summer, we found a good question to ask was what price the average person pays. You’ll be surprised to find a number far south of the huge expense you anticipated.


What If My Son/Daughter Is Too Young To Know What School To Attend?


While you won’t need to be this specific, you will want to narrow your choices of colleges to focus on the Peterson’s College Search link. By making a list of schools that you’d like to afford, it’ll be easy to begin a program to plan for the future. Make sure and inflate the cost of college. According to FinAid.org, it’s wise to project college costs growing at double the normal inflation rate. This means you should expect an 8 percent per year inflation rate in your college cost planning. This is a good place to start your plan.

For more information on this topic, see our post:

http://www.thefreefinancialadvisor.com/2012/01/5-steps-to-a-successful-college-plan/

(((Two women & map photo: jazzguy Wikimedia Commons; Cambridge Photograph © Christian Richardt, 24 October, 2004)))

That’s my story. Now it’s your turn: What tools did you use to find The Perfect College for you? Dartboard? Lucky ducks?

Enhanced by Zemanta


Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: College Planning, Planning Tagged With: Choosing a College, college choices, college planning, Higher education, Ivy League, U.S. News & World Report

  • « Previous Page
  • 1
  • 2
  • 3

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework