• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for taxes

The Hidden Tax Rules Shrinking Social Security Checks — What Seniors Need to Know

February 20, 2026 by Brandon Marcus Leave a Comment

The Hidden Tax Rules Shrinking Social Security Checks — What Seniors Need to Know
Image Source: Pexels.com

Social Security feels like a fixed number stamped on your monthly statement, a tidy promise you can plan around. But the reality bites a little differently. That check you rely on doesn’t always arrive untouched. Federal taxes can carve away a portion of it, and most people never see it coming until they open their bank account and feel that pinch.

The rules that determine how much of Social Security gets taxed can be confusing, even for the most careful planners. They hinge on income thresholds, filing status, and a calculation that turns your benefits into taxable income in a way that feels counterintuitive. Understanding them isn’t optional if you want to protect what you’ve worked for, because the IRS doesn’t negotiate.

Decoding the “Combined Income” Trap

The IRS doesn’t just look at your Social Security benefits in isolation. Instead, it calculates something called “combined income,” which includes your adjusted gross income, tax-exempt interest, and half of your Social Security benefits. That last piece is where the surprise often hits. Many retirees assume that only wages or retirement account withdrawals count, but even municipal bond interest or rental income can push your combined income over the thresholds.

For singles, if your combined income exceeds $25,000, up to 50% of your Social Security may become taxable. If it exceeds $34,000, that jumps to 85%. Married couples face slightly higher thresholds: $32,000 and $44,000. On paper, those numbers seem reasonable, but in practice, they can turn what you thought was safe, steady income into a tax headache. This structure forces many retirees to juggle income from multiple sources, trying to stay just under the limits, which can feel like a financial balancing act with high stakes.

Retirement Accounts: Friend or Foe?

Retirement accounts add another layer of complexity. Withdrawals from traditional IRAs or 401(k)s count fully toward your adjusted gross income, potentially pushing your combined income into a higher tax bracket for Social Security purposes. That means you might face taxation on benefits that you thought were untouchable. Roth accounts, on the other hand, don’t contribute to combined income, offering a strategic tool to minimize your Social Security tax bite.

The Hidden Tax Rules Shrinking Social Security Checks — What Seniors Need to Know
Image Source: Pexels.com

Strategic planning matters more than ever. For example, delaying IRA withdrawals until after your Social Security starts can reduce immediate taxes. Or, converting some funds to a Roth during lower-income years might feel painful now but can pay off later. Each decision has ripple effects on your monthly benefits, and getting it right can save thousands over the course of retirement.

Consulting a tax professional or financial advisor who understands the interaction between retirement withdrawals and Social Security taxation can make the difference between a comfortable retirement and a month-to-month struggle.

The Impact of Other Income Streams

Social Security taxation isn’t limited to traditional wages or retirement accounts. Many retirees enjoy side income — part-time jobs, consulting, investment dividends, or rental property earnings. Each of these income sources contributes to combined income, potentially increasing the percentage of Social Security that the IRS can tax. It’s easy to underestimate the impact of “little” sources of money, especially when they feel optional or supplemental.

A savvy approach involves mapping out all income sources, even the ones you think are minor. A few hundred dollars in freelance work can nudge you past the taxable threshold. Investment income, particularly capital gains, counts in some cases. Even small adjustments, like holding off on selling a stock until the next tax year, can influence your Social Security tax rate. Being intentional about every dollar entering your accounts matters because the IRS doesn’t ignore what you earn, and small oversights add up over time.

Strategies to Keep More of Your Benefits

Despite the complexity, options exist to protect Social Security checks from excessive taxation. One strategy involves income management. By controlling withdrawals from taxable accounts, sequencing Roth conversions, and planning the timing of dividends or capital gains, you can reduce combined income and keep more of your benefits intact. Another approach involves careful planning of work income if you continue part-time after retirement. Understanding how each source interacts with Social Security taxation can feel like financial chess, but it pays off in the long run.

Additionally, seniors should explore tax credits or deductions that might offset the impact. The standard deduction, charitable contributions, and even certain medical expenses can adjust taxable income downward, indirectly reducing Social Security taxation. Every opportunity counts when the goal is keeping more money in your monthly pocket rather than sending it to Uncle Sam.

Plan Ahead or Pay the Price

The IRS won’t cut you a break just because you’re retired. Social Security taxation is fixed in the code, and once your combined income crosses thresholds, there’s no escaping it. The best defense is preparation. Map out all your income sources, anticipate your withdrawals, and explore strategic timing for Social Security benefits. Even minor adjustments can mean the difference between a comfortable retirement and a check that feels smaller than it should. Ignoring these rules invites unpleasant surprises, and those surprises can be costly over a decade or more of retirement.

Every choice matters — from when you start claiming benefits to how you manage every source of taxable income. While no one can eliminate Social Security taxes entirely, careful planning can minimize the impact. In other words, you can tilt the scales in your favor with foresight and a proactive approach. The difference between a taxed-up benefit and one that stays largely untouched can reach thousands of dollars each year, and that’s real money you can spend on travel, hobbies, or even just peace of mind.

Keeping More of Your Money Feels Better Than Any Bonus

Understanding how Social Security interacts with taxes isn’t glamorous, but it’s powerful. Being proactive, rather than reactive, can preserve more of the income you earned over decades of work. The key lies in awareness, planning, and timely decisions. No one wants to feel like the government is quietly nibbling at their retirement check, and the good news is that you can manage it. By examining every income source, timing your benefits strategically, and using tax-smart withdrawals, you put yourself back in control.

Taxes may shrink your check, but knowledge and preparation expand it again. The better you understand these rules, the more you can avoid unnecessary losses and enjoy your retirement on your own terms.

Which strategy will you tackle first to keep more of your Social Security check? Let’s talk about this vital topic in the comments section.

You May Also Like…

Social Security, 401(k)s, and Market Swings: Why Retirement Feels Riskier Than Ever

Social Security 2026 COLA: Why Your 2.8% Raise Disappeared After Medicare Deductions

Millions of Gig Workers May Be Missing This Key IRS Requirement

The Sunshine State Squeeze: Why Florida Retirees are Seeing Smaller Social Security Checks This Week

Payment Delay Alert: Why Your January Social Security Deposit May Not Hit Your Account Today

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: tax tips Tagged With: Financial Tips, income planning, IRS rules, retirement income, retirement planning, senior finance, senior money advice, Social Security, tax strategies, taxes

Can You Trust AI With Your Taxes and Investments? 8 Risks No One Explains

February 19, 2026 by Brandon Marcus Leave a Comment

Can You Trust AI With Your Taxes and Investments? 8 Risks No One Explains
Image Source: Unsplash.com

Money demands precision. Algorithms promise precision. That sounds like a perfect match—until you realize that your tax return and your retirement account don’t just require math. They require judgment, context, and accountability.

Artificial intelligence now powers tax software, robo-advisors, fraud detection systems, and portfolio management tools. Major firms trumpet efficiency, lower fees, and smarter insights. Platforms integrate AI into tax preparation workflows. Even regulators like the Internal Revenue Service and the U.S. Securities and Exchange Commission use data analytics and machine learning to flag fraud and enforce compliance.

The technology works. It speeds up analysis, processes mountains of data, and identifies patterns that no human could spot in a lifetime. But handing over your financial life to AI without understanding the trade-offs invites risk.

1. Precision Without Context Can Cost You

AI systems excel at pattern recognition, but taxes and investments demand more than patterns. A tax algorithm might correctly categorize income streams based on historical filings, yet it cannot always interpret the nuance of a one-time transaction, a complex business expense, or a life change like divorce or relocation.

When software relies on prior data, it assumes consistency. Real life rarely cooperates. If you start a side business, sell a property, or exercise stock options, the system may guide you through standard prompts but fail to flag strategic opportunities that an experienced tax professional might spot.

You should treat AI-driven tax tools as assistants, not final authorities. If your financial situation includes investments, rental income, or equity compensation, consider a consultation with a certified public accountant who can layer judgment on top of automation.

2. Algorithms Optimize for Averages, Not Your Goals

Robo-advisors typically build portfolios based on risk tolerance questionnaires and modern portfolio theory. That sounds scientific because it is. These systems diversify across asset classes and rebalance automatically. They often charge lower fees than traditional advisors, which makes them attractive.

However, algorithms optimize portfolios for statistical efficiency, not personal ambition. They cannot fully grasp your entrepreneurial streak, your tolerance for volatility during market turmoil, or your desire to overweight a specific sector because you understand it deeply. They measure risk through historical data and probability distributions, not through your lived experience.

Before you let an algorithm allocate your life savings, define your goals in concrete terms. Write them down. Decide whether you want maximum long-term growth, stable income, early retirement flexibility, or capital preservation. Then compare the AI’s allocation with your priorities and adjust when necessary.

3. Data Privacy Is Not a Footnote

Tax returns contain Social Security numbers, bank account details, and income records. Investment accounts store transaction histories and beneficiary information. When you upload this data to AI-powered platforms, you expand your digital footprint.

Companies invest heavily in cybersecurity, yet breaches continue to occur across industries. Even sophisticated firms face attacks. Financial data carries enormous value on the black market, which makes these systems prime targets.

Protect yourself aggressively. Use strong, unique passwords and enable multi-factor authentication on every financial platform. Monitor your accounts regularly, not just at tax time. Consider freezing your credit when you do not actively apply for loans. AI can streamline your finances, but you must guard your data like a vault.

4. Black Box Decisions Limit Accountability

Many AI models operate as complex systems that even their creators struggle to interpret. When an algorithm recommends a specific portfolio shift or flags your tax return for potential issues, it may not provide a clear, human-readable explanation.

This lack of transparency complicates accountability. If a robo-advisor steers your portfolio toward an allocation that underperforms dramatically, you may not understand why the shift occurred. If tax software misclassifies income and you face penalties, you still bear responsibility for the filing.

5. Regulatory Gaps Move Slower Than Innovation

Financial technology evolves quickly. Regulation moves deliberately. Agencies such as the U.S. Securities and Exchange Commission oversee investment advisors, and the Internal Revenue Service enforces tax compliance, but AI-driven tools blur traditional categories.

Some platforms position themselves as software providers rather than fiduciary advisors. That distinction matters. Fiduciaries must act in your best interest under established standards. Software companies may not shoulder the same legal obligations.

6. Overconfidence Amplifies Human Error

AI systems often produce polished charts, probability projections, and confident-sounding outputs. That presentation can create a false sense of certainty. When a model predicts a high likelihood of long-term growth or suggests a low audit risk, you may feel reassured.

However, models depend on assumptions. They rely on historical correlations that may not hold during unprecedented events. Financial crises, pandemics, and geopolitical shocks disrupt even the most carefully constructed forecasts.

Maintain skepticism. Use AI projections as one input among many. Stress-test your investment plan by imagining severe downturns. Ask yourself whether you could stay invested during a 30 percent drop. Technology can inform your decisions, but you must own your risk tolerance.

Can You Trust AI With Your Taxes and Investments? 8 Risks No One Explains
Image Source: Unsplash.com

7. Hidden Conflicts of Interest Can Shape Recommendations

Some AI-driven platforms earn revenue from specific funds, partner products, or payment for order flow. These revenue streams can subtly influence recommendations. Even if the algorithm optimizes for efficiency, the underlying product universe may reflect business incentives.

Traditional financial advisors disclose conflicts of interest, and regulators require certain transparency. Digital platforms may disclose similar details in lengthy terms of service that few people read.

Scrutinize fee structures carefully. Examine whether the robo-advisor restricts portfolios to proprietary funds. Compare expense ratios with independent alternatives. A few basis points compound significantly over decades, and AI will not automatically prioritize cost minimization unless the business model aligns with that goal.

8. Automation Can Erode Financial Literacy

When software handles asset allocation, tax-loss harvesting, and rebalancing, you may feel less urgency to understand the mechanics. Convenience often replaces curiosity. Over time, that dynamic can weaken your financial literacy.

You do not need to master every tax code provision or investment theory, but you should understand core principles. Know how marginal tax brackets work. Recognize the difference between capital gains and ordinary income. Understand why diversification reduces risk and how compounding builds wealth.

The Smart Way to Use AI Without Letting It Use You

AI can absolutely improve tax efficiency and investment management when you approach it thoughtfully. It reduces costs, accelerates analysis, and democratizes access to tools that once required high fees. Ignoring these advantages would make little sense.

Think of AI as a powerful calculator with ambition. It processes information at scale, but it does not live your life, bear your financial stress, or retire on your timeline. You do. Use the technology. Challenge it. Supervise it. Then let it serve your goals instead of quietly steering them.

Would you feel comfortable letting an algorithm make your biggest financial decisions, or do you still want a human in the loop? Share your thoughts in the comments section below.

You May Also Like…

Why Are So Many People Rethinking How They Budget

9 Investing Assumptions That Fail When Markets Stay Flat for Years

5 Clues That It’s Time To Pull Your Investment

4 Bold Predictions About The Future of Personal Finance Technology

9 Surprising Costs That Appear With New Technology

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Investing Tagged With: AI, artificial intelligence, cybersecurity, data privacy, fintech, investing, IRS, Personal Finance, Planning, robo-advisors, SEC, taxes

Millions of Gig Workers May Be Missing This Key IRS Requirement

February 18, 2026 by Brandon Marcus Leave a Comment

Millions of Gig Workers May Be Missing This Key IRS Requirement
Image source: shutterstock.com

You can hustle every day, grind through back-to-back deliveries, finish freelance projects at midnight, and still get blindsided by the IRS if you miss one crucial requirement. Millions of gig workers focus on earning income but ignore the tax rule that keeps that income safe from penalties.

The problem does not come from a lack of effort or ambition. It comes from a misunderstanding of how the IRS treats independent contractors. If you earn money outside of traditional employment, the IRS expects something very specific from you, and ignoring it can cost you more than you think.

The Rule Too Many Gig Workers Ignore: Quarterly Estimated Taxes

When you work as an employee, your employer withholds federal income taxes, Social Security, and Medicare from every paycheck. That system creates a steady drip of payments to the IRS throughout the year. Gig workers and independent contractors operate under a completely different structure. The IRS requires most self-employed individuals to pay estimated taxes quarterly if they expect to owe at least $1,000 in taxes when they file their return.

That rule surprises people who assume they can just settle up in April. The IRS does not operate on a “pay later” philosophy for self-employed income. Instead, it expects you to pay as you earn. The agency sets four estimated tax deadlines each year, generally in April, June, September, and January of the following year. If you skip those payments or underpay, the IRS can assess an underpayment penalty, even if you ultimately pay the full amount when you file your annual return.

You do not need a storefront or a formal business entity to fall under this rule. If you drive for rideshare platforms, deliver food, sell goods online, design logos, tutor students, or complete freelance writing assignments, the IRS sees you as self-employed. That classification triggers the estimated tax requirement.

The 1099 Confusion That Trips People Up

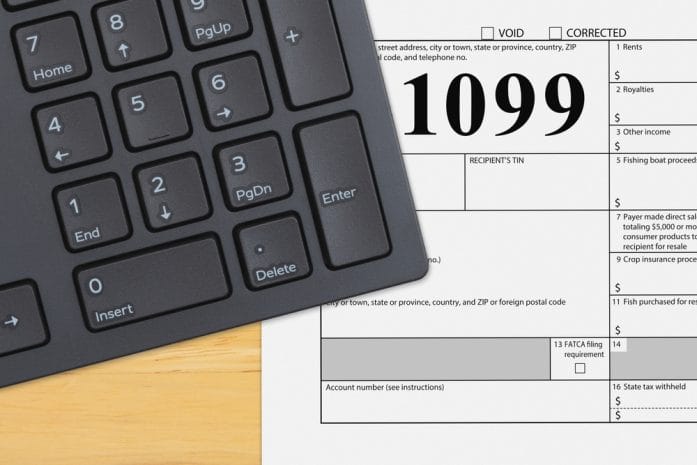
Gig workers often receive Form 1099-NEC or Form 1099-K from platforms or clients. Those forms report income paid to you during the year. Some workers assume that if they do not receive a 1099, they do not need to report the income. That assumption creates serious risk.

The IRS requires you to report all taxable income, even if you do not receive a form. Payment apps and online platforms follow specific reporting thresholds, and those thresholds have changed in recent years. Even if a company does not send you a 1099 because your earnings fall below a reporting limit, you still must include that income on your tax return.

Relying solely on 1099 forms to track your income can also distort your estimated tax calculations. You should track your gross receipts and expenses consistently throughout the year. Waiting for tax documents in January does not help you meet quarterly deadlines that occur long before those forms arrive.

Millions of Gig Workers May Be Missing This Key IRS Requirement
Image source: shutterstock.com

How to Calculate Estimated Taxes Without Losing Your Mind

You do not need to turn into a tax expert overnight, but you do need a plan.

If your income fluctuates significantly, you can adjust your estimated payments each quarter. Gig work often comes with uneven cash flow, so you should review your earnings regularly rather than locking yourself into rigid numbers from January. You can also use accounting software or work with a tax professional who understands self-employment income.

Setting aside a percentage of every payment can simplify the process. Many experienced gig workers automatically move 25 to 30 percent of each deposit into a separate savings account designated for taxes. That habit creates a buffer and prevents the panic that hits when a large quarterly payment comes due.

Deductions: Your Best Friend If You Track Them Properly

Quarterly payments matter, but deductions can dramatically reduce the amount you owe. The IRS allows self-employed individuals to deduct ordinary and necessary business expenses. That includes mileage for business driving, a portion of home office expenses if you meet the requirements, supplies, software subscriptions, marketing costs, and health insurance premiums for self-employed individuals, among others.

Accurate recordkeeping determines whether you can claim those deductions confidently. You should track mileage using a reliable log or app, save receipts for business purchases, and maintain separate accounts for business and personal expenses. If the IRS ever questions your return, organized records will support your claims.

Deductions reduce your net income, which in turn reduces both your income tax and your self-employment tax. That connection makes consistent tracking throughout the year essential. You cannot reconstruct a year’s worth of expenses from memory in March and expect precision.

What Happens If You Ignore This Requirement

The IRS does not send friendly reminders about missed quarterly payments. Instead, it calculates underpayment penalties based on how much you owed and how long you delayed payment. The penalty functions like interest, and it accrues over time. Even if you pay your full balance in April, the IRS can still assess a penalty if you failed to make sufficient quarterly payments.

Repeated noncompliance can also create cash flow chaos. If you owe a large amount at filing time and cannot pay in full, the IRS can impose additional penalties and interest. You can request a payment plan, but that route adds stress and extra cost.

Ignoring estimated taxes does not make the obligation disappear. It simply shifts the burden into the future, where it often grows larger and more disruptive.

Take Control Before the IRS Takes Notice

Gig work offers flexibility and independence, but it also demands discipline. You must treat your tax obligations as a regular business expense, not an afterthought. Mark quarterly deadlines on your calendar, review your income monthly, and set aside money consistently. If you feel overwhelmed, consult a certified public accountant or enrolled agent who specializes in self-employment taxes. A single professional session can save you far more in penalties and missed deductions than it costs.

You built your gig income with effort and persistence. Protect it with the same energy. Estimated taxes do not represent a bureaucratic nuisance; they represent a core responsibility of running your own operation. When you handle them proactively, you gain control and avoid unpleasant surprises.

If you earn income through gig work, when did you last review your estimated tax strategy? It’s time to discuss this very important subject in our comments.

You May Also Like…

Budgeting For Irregular Income: Freelancers And Gig Workers

5 Warning Signs Your “Side Gig” Is Destroying Your Finances

5 Reasons To Talk To Your Kids About Taxes

Can Your Taxes Be Cut In Half By You Simply Incorporating Your Name?

9 Financial Dangers of Ignoring Property Taxes

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: tax tips Tagged With: 1099, Estimated taxes, freelancers, gig economy, Independent contractors, IRS, Planning, self-employment tax, side hustle, tax compliance, tax penalties, taxes

The IRS Timing Rule That Can Push Income Into a Different Tax Year

February 13, 2026 by Brandon Marcus Leave a Comment

The IRS Timing Rule That Can Push Income Into a Different Tax Year
Image source: shutterstock.com

Have you ever thought about how the exact timing of a paycheck or a freelance invoice could drastically alter your tax bill? It might sound like a small detail, but the IRS has rules that can move income from one tax year to the next, and getting them right—or wrong—can have serious implications.

This isn’t about loopholes or tricks; it’s about understanding the rhythm of the tax system, and why knowing when income officially “counts” can make a huge difference in how much you owe.

When Timing Is Everything: Understanding the IRS “Constructive Receipt” Rule

The IRS has a rule called “constructive receipt,” and it’s deceptively simple but incredibly powerful. In essence, income is taxable in the year you have control over it, not necessarily when you actually deposit it in your bank. If a check is in your mailbox, a payment is available electronically, or you have the ability to draw from an account—even if you haven’t yet taken it—the IRS considers that income as received. This means a December 31st invoice can technically count for that year if you could have cashed it before the clock strikes midnight, even if you wait until January.

Understanding constructive receipt isn’t just academic; it can influence real decisions. Freelancers, small business owners, and anyone with irregular payments often strategize around this rule to manage their taxable income, but there are boundaries. You can’t postpone income by choice if it’s available to you—that’s what the IRS specifically warns against. The nuance lies in whether circumstances beyond your control prevent access, like a bank delay or a client holding a check until January. Timing matters, and knowing these boundaries lets you plan with precision rather than guesswork.

Why This Rule Can Save or Cost You Big

Imagine finishing a year with a windfall of income that pushes you into a higher tax bracket. One invoice hitting December instead of January can mean thousands of extra dollars owed to Uncle Sam. Conversely, delaying income until the next year, when it won’t push you over a critical bracket, can save you a significant sum. This is where constructive receipt becomes a financial strategy. Business owners often schedule invoicing, bonuses, or even sales closing dates around this timing.

However, it’s important to note that some payments are automatically recognized as income when issued, such as interest earned in a bank account. For anyone who deals with freelance work, royalties, or commissions, understanding exactly when you have the right to access funds can prevent overpaying taxes in one year or facing penalties for underreporting in another.

Real-World Scenarios Where Timing Changes Everything

Consider a freelance designer who completes a big project in December but agrees with the client to receive payment in January. From the IRS’s perspective, if the designer had no ability to access the funds in December, the income counts for the following year. On the other hand, if the client cut a check in late December and mailed it, but the designer simply didn’t deposit it, the IRS views the income as received in December.

Small business owners often face similar dilemmas with year-end invoices, prepaid services, and bonuses. Strategic timing of issuing and receiving payments can optimize taxable income, but it requires careful tracking and documentation. Without clear records, a simple misunderstanding can trigger audits or unexpected tax bills. Knowing the rule and applying it thoughtfully allows individuals and businesses to make smart decisions that align with both their financial goals and IRS expectations.

Tools and Tactics to Keep Income in the Right Year

Managing income timing doesn’t require a PhD in accounting, but it does require attention to detail. For individuals, it might be as simple as planning when to send invoices or requesting a client to delay payment slightly. For businesses, accounting software that flags income by receipt date versus deposit date can prevent misreporting. Another tactic is communicating clearly with clients or payroll services about payment schedules to avoid accidental constructive receipt.

Additionally, tax professionals can provide guidance specific to your situation. For example, certain retirement contributions or charitable deductions can interact with income timing in ways that either enhance or reduce benefits.

The IRS Timing Rule That Can Push Income Into a Different Tax Year
Image source: shutterstock.com

When the Clock Strikes Midnight

At the end of the day, constructive receipt is a reminder that taxes aren’t just about numbers—they’re about timing and control. Being aware of the exact moment income counts helps avoid surprises and enables smarter decisions around invoicing, bonuses, and other payments. Delaying or accelerating income should always be done within the rules, but the strategic benefit is undeniable: even a few days can make a difference in tax liability.

Documenting payments, tracking when money is legally yours, and consulting professionals when needed ensures compliance and maximizes opportunities. Income is like water flowing into a bucket: the moment it enters, you need to know whose bucket it belongs to for tax purposes.

Timing Isn’t Just a Technicality

Understanding the IRS timing rule on constructive receipt gives individuals and businesses a surprising degree of control over taxable income. While it might seem like a minor bureaucratic detail, it has real-world implications for how much you pay and when. Knowing the difference between having access to money and actually depositing it is a subtle, but powerful, tool in the financial toolkit. By planning and documenting carefully, it’s possible to navigate the rules smoothly, avoid penalties, and even optimize your tax situation without bending any laws.

Have you ever noticed how the timing of your payments or invoices impacted your tax bill? Tell us any IRS tips that you have in our comments section.

You May Also Like…

IRS 1099-K Rules in 2026: Who Must Report Payments This Year

The IRS Reporting Threshold Change That Just Created a Tax Risk for Millions in 2026

5 Reasons To Talk To Your Kids About Taxes

Can Your Taxes Be Cut In Half By You Simply Incorporating Your Name?

9 Financial Dangers of Ignoring Property Taxes

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: tax tips Tagged With: accounting, deductions, income timing, IRS, Personal Finance, Planning, tax planning, tax rules, tax strategy, tax tips, tax year, taxes

The Venmo Privacy Setting That Can Trigger Unwanted Tax Reporting

February 12, 2026 by Brandon Marcus Leave a Comment

The Venmo Privacy Setting That Can Trigger Unwanted Tax Reporting
Image source: shutterstock.com

Venmo feels like the digital equivalent of tossing a few bills to a friend across a table. It’s fast, casual, and so woven into everyday life that most people barely think about it as “financial infrastructure.” But under the hood, Venmo is also a payment processor that plays by the same reporting rules as much bigger financial platforms.

One small setting in the app can quietly change how your payments are categorized, how they’re tracked, and whether they end up on a tax form. If you use Venmo for anything beyond splitting pizza and rent, this is one of those things that’s genuinely worth understanding before it turns into a paperwork headache later.

The Privacy Setting Everyone Clicks Past Without Reading

Venmo’s privacy settings are deceptively simple: public, friends, or private. Most people treat this as a social feature, not a financial one. It feels like choosing who gets to see your emojis and payment notes, not something that could ever affect your taxes. But public transactions do more than broadcast your business to strangers scrolling a feed. They create a visible record of frequent payments, patterns, and activity that can look a lot like business behavior, especially if the descriptions suggest services or sales.

Here’s the important reality: privacy settings themselves do not determine whether Venmo reports income to the IRS. That part is driven by how payments are classified. But visibility does matter in a different way. Public transactions make it easier for platforms, auditors, or even automated systems to identify activity that appears commercial. If your feed looks like a digital storefront instead of casual peer-to-peer transfers, it increases the chances that your activity is flagged as business-related.

The Real Trigger: The “Goods and Services” Switch

The true tax tripwire on Venmo isn’t the privacy toggle, it’s the “goods and services” classification. When a payment is marked as goods and services, Venmo treats it as a commercial transaction, not a personal one. That classification is what feeds into tax reporting systems. Under current IRS rules, payment platforms must issue Form 1099-K for goods and services payments once reporting thresholds are met.

If someone sends you money for design work, tutoring, selling a couch, freelance projects, or any kind of side hustle and it’s tagged as goods and services, that payment becomes part of a reportable total. Privacy settings don’t override that classification. You could have every transaction set to private and still receive a 1099-K if those payments are categorized as commercial. This is where people get blindsided, because the app experience feels casual while the backend reporting system is very much not.

How Casual Payments Start Looking Like Business Income

The line between personal and commercial payments has gotten blurrier. People use Venmo for everything: group trips, event tickets, resale items, hobby income, freelance gigs, and side hustles. Over time, those little payments can stack up into patterns that resemble a business cash flow stream. Multiple payments from different people, consistent amounts, similar descriptions, and repeated activity can all signal commercial use.

The problem isn’t that Venmo is doing something shady. It’s that the platform is required to follow financial reporting laws, and algorithms don’t understand context the way humans do.

Why Public Feeds Add a Layer of Risk

Public visibility doesn’t create tax obligations, but it adds friction and risk. A public transaction history creates a permanent, searchable pattern of activity. If someone is receiving frequent payments with business-like descriptions, that record exists outside of private account data. It becomes part of a broader digital footprint. This doesn’t mean people are actively scanning Venmo feeds for tax enforcement, but in an era of automated systems and data analysis, visibility always increases exposure.

Think of it like this: private transactions live inside a financial system, while public transactions live inside a social system and a financial system at the same time. That dual presence makes them easier to analyze, categorize, and interpret as commercial behavior.

The Venmo Privacy Setting That Can Trigger Unwanted Tax Reporting
Image source: shutterstock.com

Smart Moves to Stay in Control

If you use Venmo casually, the safest habit is to default your privacy setting to private and only switch visibility on when there’s a real reason to share. That keeps your financial activity from becoming part of a public feed. More importantly, always pay attention to how payments are categorized. If you’re receiving money for work, assume it’s taxable income and plan for it accordingly. Keep records, track totals, and don’t treat app-based payments as invisible money.

For side hustlers and freelancers, it’s often cleaner to separate personal and business finances entirely. Using a dedicated payment account for income makes tracking easier and avoids confusion at tax time. For everyday users, the biggest win is awareness.

The Setting That Changes Everything Without Feeling Important

Privacy settings feel cosmetic. Payment labels feel optional. Descriptions feel playful. But those tiny details shape how transactions are categorized, tracked, and reported. The app experience is friendly, but the financial infrastructure behind it is serious, regulated, and data-driven.

What’s your take on digital payment apps becoming part of the tax system—does it feel fair, invasive, or just inevitable? How do you treat Venmo, and do you have any advice to share? Talk about it in our comments section.

You May Also Like…

IRS Warning: That Venmo Payment for Your Garage Sale Just Triggered a Surprise Tax Bill

IRS 1099-K Rules in 2026: Who Must Report Payments This Year

Repayment Assistance Plan Launches July 2026: New Income-Based Option for Borrowers

What Young People Can Teach Their Grandparents About Money

5 Types of Income People Forget to Pay Taxes On

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: tax tips Tagged With: 1099-K, digital payments, financial privacy, fintech, IRS reporting, money apps, online payments, Personal Finance, side hustle, taxes, Venmo

Student Loans Forgiven Are Now Taxable In 2026 — Set Money Aside for Tax Bills

February 7, 2026 by Brandon Marcus Leave a Comment

Student Loans Forgiven Are Now Taxable In 2026 — Set Money Aside for Tax Bills
Image source: shutterstock.com

For years, student loan forgiveness felt like a financial fairy tale — the kind where your debt disappears and everyone rides into the sunset with zero consequences. But starting in 2026, that dream comes with a plot twist that could hit your wallet hard. If your student loans are forgiven in 2026 or later, that forgiven amount is once again considered taxable income under federal law, which means the IRS may want its cut.

That’s right: your “freedom from debt” moment could turn into a surprise tax bill if you’re not prepared. This isn’t a trap — it’s a known rule change, and with the right planning, you can outsmart it instead of getting blindsided.

Why Student Loan Forgiveness Is Taxable Again in 2026

For a brief, beautiful moment in financial history, forgiven student loans were federally tax-free. That came from pandemic-era legislation that temporarily made most federal student loan forgiveness non-taxable. But like many temporary policies, that protection has an expiration date — and in 2026, the tax-free treatment disappears unless new legislation changes it.

What that means in plain English is simple but serious: if you have loans forgiven in 2026, the IRS can treat that forgiven balance as ordinary income. That extra “income” can push you into a higher tax bracket, increase what you owe, and even affect credits and benefits tied to income limits. Forgiveness still helps your long-term finances, but the short-term tax hit can sting if you’re not ready for it.

Who This Impacts the Most

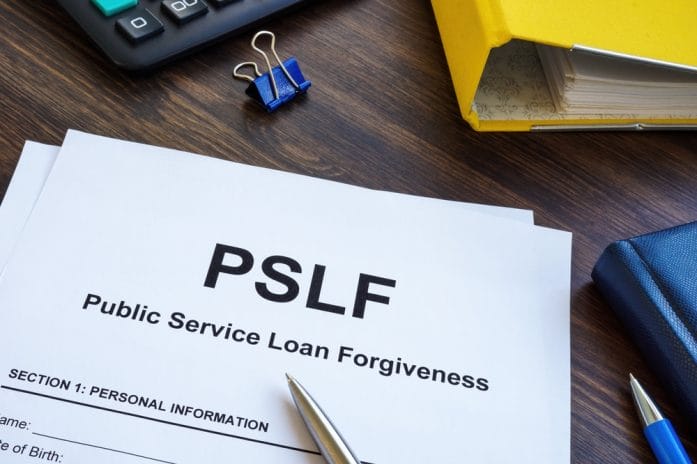
This change doesn’t hit everyone equally. Borrowers on income-driven repayment plans are especially affected. Public Service Loan Forgiveness (PSLF) is still federally tax-free under current rules, but many other forgiveness programs are not.

That means teachers, healthcare workers, nonprofit employees, and private-sector borrowers on income-driven plans could face very different tax outcomes depending on which forgiveness path they’re on. Not everyone will carry the same financial load.

Student Loans Forgiven Are Now Taxable In 2026 — Set Money Aside for Tax Bills
Image source: shutterstock.com

How a “Good Thing” Can Create a Bad Financial Surprise

Here’s the emotional shock that not enough people are talking about: you feel relieved, excited, and free when your loans are forgiven — and then the tax bill arrives. Unlike regular income, no one withholds taxes on forgiven debt. There’s no paycheck deduction, no automatic payment system, and no built-in safety net. The IRS simply expects you to pay what you owe.

This can be especially brutal for borrowers who are already living paycheck to paycheck. A tax bill of several thousand dollars isn’t just inconvenient — it can create real financial stress. The irony is painful: you finally escape student debt, only to be hit with a different kind of financial burden. That’s why planning ahead isn’t just smart — it’s necessary.

Smart Ways to Prepare So You’re Not Caught Off Guard

The most powerful move you can make right now is awareness. If you’re on track for forgiveness in 2026 or later, start treating that future tax bill as a known expense, not a surprise. Even small monthly savings can make a massive difference over time. A separate “tax buffer” savings account can turn a scary bill into a manageable payment.

It’s also worth talking to a tax advisor or financial planner who understands student loan forgiveness. They can help estimate your future tax exposure and show you how it might affect your bracket, deductions, and overall tax strategy.

Your Financial Freedom Moment Deserves a Plan, Not a Panic Attack

Student loan forgiveness should feel like a celebration, not a crisis. If 2026 is part of your forgiveness timeline, now is the moment to get proactive instead of reactive. Build a savings cushion, learn the rules, understand your specific forgiveness program, and stop assuming it will all magically work out.

The truth is simple: forgiven loans can change your life — but only if you’re ready for the tax side of the story. Preparation doesn’t ruin the win. It protects it.

Are you planning for student loan forgiveness in the next few years — and have you started saving for the tax side of it yet? Let’s hear all of your thoughts in the comments.

You May Also Like…

Student Loan Interest Resumed August 2025 — Costing SAVE Borrowers $300/Month

How Can Student Loans Quietly Shape Life Decisions for Decades

The Estate Planning Shortcut That Saves Time but Costs Families More in the Long Run

Student Loan Wage Garnishment Could Return After 5-Year Pause — 15% of Paychecks at Risk

8 Ways You Should Never Use Student Loan Money For

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Personal Finance Tagged With: 2026 taxes, budgeting, debt relief, federal student loans, Income tax, IRS, loan forgiveness, money tips, Personal Finance, Planning, student loans, taxes

Why Estate Plans Written Before 2020 Are Failing Families Today

January 31, 2026 by Brandon Marcus Leave a Comment

Why Estate Plans Written Before 2020 Are Failing Families Today
Image source: shutterstock.com

If your estate plan hasn’t been touched since 2019, it might be quietly plotting chaos for your family. Estate planning sounds boring, almost clinical—but when your will or trust is outdated, it can unleash a storm of confusion, financial headaches, and even family disputes.

Life changes, tax laws shift, and new financial tools emerge, meaning a plan that worked perfectly in 2018 might be a ticking time bomb today. Whether you’re a seasoned investor, a parent, or simply someone who wants to protect their loved ones, understanding why your old estate plan might be failing is essential. Don’t wait for a crisis to realize your family’s safety net has holes.

Life Changes Fast—Has Your Estate Plan Kept Up?

Remember when 2020 seemed like the start of the next decade’s big changes? Well, it was. Since then, countless families have experienced major shifts: marriages, divorces, births, deaths, and relocations. Even if you haven’t moved, the value of your home, investments, or retirement accounts might have changed dramatically.

If your estate plan hasn’t reflected these shifts, your assets could end up in the wrong hands, your heirs could face unexpected taxes, or your intentions might simply be ignored. Updating your estate plan isn’t just a legal chore—it’s a necessary check-in to ensure the blueprint you wrote years ago still makes sense in today’s world. In short, life evolves, and your plan must evolve with it.

Tax Laws Aren’t What They Used To Be

Estate taxes might not dominate dinner conversation, but they can devastate families if overlooked. In 2020, the federal estate tax exemption was $11.58 million per individual, and it’s risen since. Failing to adjust your plan for current exemptions, annual gift limits, or state-specific rules could result in unnecessarily high taxes for your heirs.

Beyond federal law, many states have updated inheritance rules that you need to stay up-to-date on, and outdated trusts may no longer provide the tax protections they promised. A plan that looked brilliant in 2019 might now be riddled with loopholes or blind spots. If you think taxes are boring, try explaining to your children why they lost part of their inheritance—updating your plan prevents these awkward, painful conversations.

Digital Assets Are the New Frontier—and Your Old Plan Ignores Them

Back in 2019, most estate plans didn’t consider digital assets beyond online banking. Today, digital lives are massive: social media accounts, cryptocurrency wallets, cloud storage, and even NFTs. Without explicit instructions, your heirs could struggle—or even fail—to access accounts, unlock funds, or manage online properties.

Courts and companies increasingly demand specific directions in wills and trusts for digital assets. Failing to update your plan could leave your family locked out of assets you didn’t even think were valuable. The digital world moves fast, and your estate plan should sprint right alongside it.

Healthcare Directives and Powers of Attorney May Be Outdated

Many people draft healthcare directives and powers of attorney early, then forget them. Since 2020, medical technology, telehealth, and long-term care options have expanded. Outdated directives may not reflect your current wishes, leaving doctors and family members guessing in high-stress situations. For instance, a power of attorney written before telehealth was mainstream may not allow an agent to manage digital medical portals or virtual care decisions.

Ensuring these documents reflect your current preferences is critical—not just for avoiding confusion, but for keeping control in your hands when you can’t speak for yourself.

Why Estate Plans Written Before 2020 Are Failing Families Today
Image source: shutterstock.com

Family Dynamics Can Shift Without Warning

Families change, and often faster than legal documents adapt. Divorces, remarriages, blended families, or estranged relationships can render old plans confusing—or even contentious. Without updates, your estate plan might unintentionally favor one family branch over another, spark disputes, or trigger legal challenges that drain resources.

A 2019 will likely doesn’t consider modern blended-family realities, like stepchildren or cohabiting partners. Regular reviews and updates after key life events allow you to balance fairness, intention, and protection, ensuring your legacy doesn’t become a battleground.

Modern Estate Tools Are Game-Changers

The estate planning landscape has evolved dramatically since 2019. Tools like revocable and irrevocable trusts, charitable remainder trusts, and even life insurance strategies can optimize asset protection and tax benefits.

If your plan hasn’t been updated, you may be missing opportunities to shield assets from taxes, provide for heirs efficiently, or even support charitable goals while you’re alive. Think of it like upgrading your phone: the old model still works, but the new one unlocks features you didn’t even know existed. Staying current ensures your plan works smarter, not harder.

Don’t Let Your Legacy Become a Mystery Novel

Outdated estate plans are like mystery novels written decades ago—you don’t know what plot twists could leave your family puzzled, upset, or financially hurt. Life evolves, laws evolve, technology evolves, and your estate plan must evolve too.

If your plan was drafted before 2020, now is the perfect time to revisit it, update it, and ensure it works in today’s world. Don’t let your legacy become an unsolvable puzzle. Protect your loved ones, safeguard your assets, and leave behind clarity instead of chaos.

How old is your estate plan, and what surprises might it be hiding for your family? Share your thoughts in the comments below.

You May Also Like…

The Estate Planning Shortcut That Saves Time but Costs Families More in the Long Run

How a Solid Estate Plan Can Protect Your Finances

Why Young People Don’t Think About Estate Planning

7 Excuses Millennials Use to Delay Estate Planning (and Why It’s Risky)

10 Financial Tradeoffs Families Are Making Quietly

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Estate Planning Tagged With: 2026 updates, digital assets, Estate plan, Estate planning, family finance, healthcare directives, Inheritance, modern estate planning, powers of attorney, taxes, trusts, will and testament, wills

5 Pieces of Financial Information Your Accountant Should Never Control Without Limits

January 29, 2026 by Brandon Marcus Leave a Comment

These Are 5 Pieces of Financial Information Your Accountant Should Never Control Without Limits
Image source: shutterstock.com

Money is a tricky beast. It can multiply like rabbits in spring—or disappear faster than ice cream on a hot summer day. That’s why having an accountant is often the smartest move a person or business can make.

But here’s the kicker: entrusting someone with your finances doesn’t mean handing over the keys to your kingdom without a little oversight. Even the most trustworthy number-cruncher can inadvertently steer your financial ship off course if they have unchecked control.

1. Bank Accounts and Cash Flow

First and foremost, your bank accounts are your financial lifeline, and giving someone free rein over them is like letting a stranger drive your Ferrari through a crowded city. Your accountant can absolutely manage transactions, track spending, and help forecast cash flow—but direct, unrestricted access can be risky. Without limits, there’s room for errors to compound or, worse, for someone to act in bad faith.

By establishing clear protocols and periodic audits, you maintain control while still benefiting from professional guidance. Always remember: your cash is your pulse, and it should never beat under someone else’s complete control.

2. Investment Decisions

Your investments are more than just numbers on a screen—they’re your future vacations, college funds, and maybe even that dream retirement cabin in the mountains. When an accountant starts making buy, sell, or hold decisions without your input, they can unintentionally expose you to risk that doesn’t align with your goals.

A great accountant provides analysis and guidance, but investment decisions should always be collaborative, not unilateral. Ask questions, request scenario planning, and never sign off on major moves blindly. Your financial future is far too important to let someone else dictate it solo.

These Are 5 Pieces of Financial Information Your Accountant Should Never Control Without Limits
Image source: shutterstock.com

3. Tax Filings and Strategies

Taxes are the most unavoidable, least glamorous part of financial life, yet they’re a prime area for accountants to wield significant influence. While they are pros at navigating complex tax codes, unchecked authority in this realm can lead to missed deductions, questionable strategies, or even compliance nightmares. It’s essential to stay involved in the discussion, understand the reasoning behind each deduction or credit, and verify deadlines and filings.

Transparency is not just a buzzword here—it’s your safeguard against surprises from the IRS. The mantra should be: informed collaboration, not passive delegation.

4. Debt Management

Debt isn’t inherently bad; in fact, leveraged correctly, it can be a powerful tool. But when your accountant is left to manage loans, credit lines, and repayment schedules without limits, things can quickly get tangled. Decisions about which debts to pay off first, how to structure repayments, or when to consolidate should be guided by your broader financial picture.

Leaving all these choices entirely to someone else risks misalignment with your goals and cash flow realities. Open dialogue ensures debt serves your strategy instead of undermining it, and it keeps surprises from sneaking up like a stealthy ninja.

5. Financial Reporting and Record Keeping

Accurate records are the backbone of any financial plan, and accountants are the architects of this structure. But when the production and interpretation of financial reports are completely controlled by someone else, you may lose visibility into the story your money is telling. Seeking financial transparency, regular report sharing, and mutual review sessions are vital to prevent mistakes or intentional misrepresentation.

Being actively engaged in these reports helps you make smarter decisions, detect anomalies early, and ensures your accountant’s insights are based on a foundation you can actually see. It’s your money, your story, and you deserve to read every chapter.

Taking Charge Without Micromanaging

The core lesson here is simple but powerful: your accountant is a guide, strategist, and partner—not a silent gatekeeper of your financial destiny. By setting clear boundaries around bank access, investment decisions, tax strategies, debt management, and reporting, you create a system that combines professional expertise with personal oversight. Think of it like a co-pilot situation: you want someone who knows the instruments, but you’re still in the cockpit with your hands on the controls.

Which of these five areas do you think is most often mismanaged? Share your thoughts in the comments, and let’s have a conversation about taking control without losing the advantages of your accountant’s expertise.

You May Also Like…

10 Tax Questions Too Embarrassing to Ask Your Accountant

8 Money Habits That Increase Anxiety Without Helping

8 Personal Finance Beliefs That No Longer Apply

7 Financial Choices That Seem Safe Until They Aren’t

Why Does Financial Planning Feel Overwhelming Right Now


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Finance Tagged With: accounting, Debt Management, finance, finances, financial advice, financial choices, financial decisions, Financial Security, investments, money management, Personal Finance, taxes

10 Things Financial Advisors Didn’t Warn Baby Boomers About That Are Now Costing Them Thousands

January 28, 2026 by Brandon Marcus Leave a Comment

These Are 10 Things Financial Advisors Didn’t Warn Baby Boomers About That Are Now Costing Them Thousands
Image source: shutterstock.com

For decades, Baby Boomers were told that saving steadily, paying off a mortgage, and investing for the long term would lead to a comfortable retirement. Many did exactly that, yet a growing number now feel blindsided by expenses and risks they never saw coming.

The financial world shifted dramatically over the past few decades, and advice that once sounded solid did not always age well. There are overlooked realities now draining retirement accounts and monthly budgets.

1. Healthcare Costs Would Rise Faster Than Inflation

Healthcare expenses have consistently grown faster than general inflation, eroding purchasing power year after year. Many retirement projections underestimated premiums, deductibles, and out-of-pocket costs for prescriptions and procedures.

Even with Medicare, uncovered services and supplemental insurance add up quickly. These days, the average retired couple will end up spending hundreds of thousands on healthcare over retirement. However, planning ahead for healthcare costs in retirement, reviewing coverage annually, and budgeting conservatively can help soften the blow.

2. Taxes Would Still Matter In Retirement

A common assumption is that taxes would drop sharply after leaving the workforce. In reality, required minimum distributions, Social Security taxation, and investment income often keep retirees in higher brackets than expected. Tax-deferred accounts eventually create taxable income, whether it is needed or not. This all adds up.

The good news is that strategic withdrawals and Roth conversions can reduce long-term tax exposure. Working with a tax-aware planner rather than a sales-driven advisor can make a meaningful difference.

3. Longevity Would Change Everything

Living longer sounds like good news, until savings must stretch across thirty or more years. Many financial plans underestimate lifespan, especially for couples and healthier individuals.

Longer lives increase exposure to market volatility, healthcare costs, and inflation risk. But running updated projections that assume longer timelines helps reset expectations, and adjusting withdrawal rates early can prevent painful cutbacks later.

4. Inflation Would Quietly Erode Fixed Income

Fixed pensions and conservative bonds once felt safe and dependable. Over time, inflation quietly reduced their real value, shrinking purchasing power without obvious warning signs. Expenses like food, utilities, and insurance rose faster than fixed payouts.

This gap often forces retirees to dip into savings sooner than planned. Incorporating some inflation-aware investments can help balance stability with growth.

5. Helping Adult Children Would Become A Major Expense

Many Boomers expected to support children emotionally, not financially, well into adulthood. Rising housing costs, student debt, and childcare expenses changed that equation. Ongoing assistance can derail even carefully planned retirements. Clear boundaries and honest conversations protect both generations. Supporting loved ones should not come at the expense of long-term financial security.

6. Market Volatility Would Feel Different Without A Paycheck

Market swings feel very different when no paycheck replenishes losses. Sequence-of-returns risk can permanently damage portfolios if downturns hit early in retirement. Many advisors emphasized average returns while downplaying timing risk.

Diversification alone does not eliminate this vulnerability, but holding a cash buffer can reduce the need to sell investments during downturns.

7. Long-Term Care Planning Would Be Overlooked

Long-term care remains one of the most expensive and least planned-for retirement risks. Many assumed that some family help or just basic insurance would be enough for them to get by.

In reality, extended care can cost thousands per month for years. Traditional long-term care insurance became expensive and less available over time. Exploring hybrid policies or dedicated savings strategies can provide more flexibility.

These Are 10 Things Financial Advisors Didn’t Warn Baby Boomers About That Are Now Costing Them Thousands
Image source: shutterstock.com

8. Fees Would Compound Just Like Returns

Small percentage fees often seemed insignificant early on. Over decades, those fees quietly consumed large portions of investment growth. Many retirees now realize they paid far more than expected for active management because fee transparency was not always emphasized in earlier advice models. Reviewing expense ratios and advisory costs can immediately improve outcomes.

9. Housing Would Not Automatically Be A Financial Win

Homeownership was long viewed as a guaranteed retirement asset. Maintenance, taxes, insurance, and repairs often cost far more than anticipated. Some retirees stay in homes that drain cash flow instead of supporting it. Downsizing is emotionally complex and financially nuanced. Evaluating housing through a cash-flow lens brings clarity.

10. Financial Plans Would Need Constant Updating

Many Boomers created a plan and assumed it would carry them through retirement unchanged. Economic shifts, policy changes, and personal circumstances rarely cooperate with static plans.

The truth of the matter is that what worked ten years ago may no longer apply today. Regular reviews allow small adjustments instead of drastic corrections. Flexibility now often matters more than perfection then.

Why Awareness Is The Most Valuable Asset Left

The most expensive surprises often come from outdated assumptions, not poor intentions. Financial awareness empowers better decisions even later in life. Small changes still compound when applied consistently. Curiosity beats regret every time. Staying engaged with finances remains one of the strongest tools available.

Which of these challenges has affected your financial life the most, and what changes have you found helpful?

You May Also Like…

12 Financial Moves Baby Boomers Are Making Right Now and So Should You

Financial Advisor Confession: 7 Things I’m Now Required by Law to Tell My Clients (That I Couldn’t Say in 2025).

8 Essential Items Boomers Should Invest In If They’ll Be Living Alone

8 Harsh Truths Why Boomers Can’t Change Their Retirement Plans Now

7 Money Lessons Baby Boomers Taught That Still Build Wealth

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Financial Advisor Tagged With: adult children, baby boomer, baby boomer trends, baby boomers, boomer finances, expenses, fees, finance, finances, financial advisor, financial advisors, Financial plan, healthcare, healthcare costs, Hidden Fees, household expenses, Inflation, Long-term care, market volatility, paychecks, Planning, property taxes, retiree, retirees, Retirement, taxes

The Tax Document Most Homeowners Fail to Update That Triggers Surprise Liens

January 28, 2026 by Brandon Marcus Leave a Comment

This Is The Tax Document Most Homeowners Fail to Update That Triggers Surprise Liens
Image source: shutterstock.com

Most homeowners worry about mortgage payments, insurance premiums, and interest rates, yet a far quieter risk often slips through the cracks. It does not arrive with flashing warnings or urgent phone calls, and that is precisely why it causes so much damage. Across the country, homeowners discover liens only after refinancing, selling, or checking their credit, long after the problem started.

The root cause usually traces back to one small administrative oversight tied to property taxes. Understanding this seemingly insignificant issue can protect your home, your credit, and your long-term financial plans with far less effort than you might expect.

The Overlooked Property Tax Mailing Address

Many homeowners assume property tax bills automatically follow them when they move, but that assumption causes costly problems. Local tax authorities rely on the mailing address listed in the property tax record, not forwarding instructions from the postal service. If that address remains outdated, tax bills can go unpaid without the homeowner ever realizing it.

Unpaid property taxes can legally result in a lien against the home, even if the homeowner never saw the bill. Updating this record is simple, yet it remains one of the most commonly missed steps after a move or refinancing.

How Missed Tax Bills Turn Into Liens

Property taxes operate on strict timelines set by local governments, and missed payments trigger automatic consequences. Once a bill goes unpaid, penalties and interest often begin accruing almost immediately. If the balance remains unresolved, the taxing authority can place a lien on the property to secure the debt.

A lien does not mean the home is seized, but it does attach a legal claim that must be resolved before selling or refinancing. These liens can also complicate credit and financial planning, making them far more disruptive than many homeowners expect.

Why Escrow Accounts Don’t Always Save You

Many homeowners rely on mortgage escrow accounts and assume property taxes are fully handled on their behalf. Escrow usually works smoothly, but it depends on accurate billing information reaching the lender on time.

If tax bills go to the wrong address, escrow shortages or missed payments can still occur. Lenders may not learn about the issue until penalties have already accumulated. Homeowners trying to improve their finances should analyze their escrow statements annually to confirm taxes are being paid correctly and on schedule.

Common Life Changes That Trigger The Problem

Major life events often disrupt financial paperwork, even for organized homeowners. Moving, refinancing, inheriting property, or placing a home into a trust can all affect tax records. In many cases, ownership updates occur without confirming the associated mailing address for tax notices.

Busy schedules make it easy to assume someone else handled the details. Building a habit of reviewing tax records after any major change supports stronger financial health and prevents avoidable stress.

This Is The Tax Document Most Homeowners Fail to Update That Triggers Surprise Liens
Image source: shutterstock.com

Simple Steps To Protect Your Home And Finances

Homeowners can usually update their property tax mailing address through the local tax assessor or treasurer’s office. The process often takes only minutes and can be completed online or by mail. Reviewing property tax records once a year adds another layer of protection and supports smarter money management.

Setting calendar reminders for all important tax deadlines also helps homeowners stay ahead of potential issues. Small administrative habits like these free up mental energy for bigger financial goals such as saving, investing, or paying down debt.

Why This One Update Matters More Than You Think

Property tax liens rarely stem from irresponsibility, but from silence and outdated information. The system assumes delivery equals awareness, even when that assumption fails. One unchecked record can quietly undo years of careful financial planning. Staying proactive keeps your home protected and your finances predictable. When homeowners control the details, surprises lose their power.

Have you ever uncovered a financial issue that started with a small paperwork oversight, and what did it teach you about managing your money? Let’s hear your story in the comments.

You May Also Like…

The $140,000 Oversight: The Missing Texas Tax Paperwork That Is Costing Homeowners Thousands This Week

7 Fine-Print Exclusions in Your Homeowner’s Policy That Could Cost You Everything

9 Georgia Counties Where Property Taxes Are Set to Rise the Fastest

9 Financial Dangers of Ignoring Property Taxes

Your Ring Doorbell Is Recording Evidence That Could Void Your Homeowner’s Claim

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: tax tips Tagged With: client behavior, escrow, homeowners, homeownership, household items, household responsibilities, ignoring property taxes, liens, missed tax bills, property tax tips, property taxes, tax documents, tax tips, taxes

  • « Previous Page
  • 1
  • …
  • 12
  • 13
  • 14
  • 15
  • 16
  • …
  • 24
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework