• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for 401(k)

Ways Retirement Funds Are Quietly Being Eaten by Fees

July 10, 2025 by Travis Campbell Leave a Comment

retirement funds
Image Source: pexels.com

Retirement funds are supposed to be your safety net. You work for decades, save what you can, and hope your money grows enough to support you later. But there’s a problem many people miss: fees. These costs can quietly chip away at your savings, sometimes without you even noticing. Over time, small fees can add up to thousands of dollars lost. If you want your retirement fund to last, you need to know how fees work and where they hide. Here’s how retirement funds are quietly being eaten by fees—and what you can do about it.

1. Expense Ratios That Seem Small but Add Up

Expense ratios are the annual fees charged by mutual funds and ETFs. They cover the cost of managing the fund. At first glance, a 0.5% or 1% fee doesn’t look like much. But over 20 or 30 years, that small percentage can eat a big chunk of your retirement fund. For example, if you invest $100,000 and your fund charges a 1% expense ratio, you’ll pay $1,000 every year. As your balance grows, so does the fee. Over the decades, this can mean tens of thousands lost. Always check the expense ratio before you invest. Lower is usually better. Even a difference of 0.5% can mean thousands more in your pocket by retirement.

2. Hidden Administrative Fees

Many retirement accounts, like 401(k)s, come with administrative fees. These cover recordkeeping, customer service, and other plan costs. Sometimes, these fees are buried in the fine print or bundled with other charges. You might not notice them unless you look at your statements closely. These fees can be flat or based on a percentage of your assets. Either way, they reduce your returns. Ask your plan administrator for a breakdown of all fees. If your plan is expensive, consider rolling over to an IRA with lower costs when you leave your job.

3. Advisor Fees That Don’t Always Add Value

Some people pay a financial advisor to manage their retirement funds. Advisors often charge a percentage of your assets, usually around 1%. This is on top of the fund fees you already pay. If your advisor isn’t providing clear value—like a solid financial plan or tax advice—you might be paying too much. Robo-advisors and self-directed accounts can be cheaper options. If you use an advisor, ask exactly what you’re paying and what you’re getting in return. Don’t be afraid to shop around or negotiate.

4. Transaction Fees and Trading Costs

Every time you buy or sell an investment, you might pay a transaction fee. Some funds charge sales loads, which are commissions paid when you buy or sell shares. Others have trading fees for each transaction. These costs can add up, especially if you trade often or your plan uses high-turnover funds. Look for no-load funds and accounts with free or low-cost trading. The less you pay in transaction fees, the more of your money stays invested.

5. Account Maintenance and Inactivity Fees

Some retirement accounts charge maintenance fees just for keeping your account open. Others penalize you if you don’t make regular contributions or trades. These fees can be small, but over time, they add up. If you have old accounts from previous jobs, check if you’re being charged for inactivity. Consolidating accounts can help you avoid these fees and make your retirement savings easier to manage.

6. High-Cost Investment Options

Not all investment options in your retirement plan are created equal. Some funds, especially actively managed ones, have higher fees than others. These funds promise better returns, but most don’t outperform cheaper index funds over time. High-cost funds can quietly drain your retirement fund, even if the market is doing well. Stick with low-cost index funds or ETFs when possible. They usually have lower fees and perform just as well, if not better, than expensive alternatives. Morningstar’s research shows that lower-cost funds tend to outperform over the long run.

7. Fees for Early Withdrawals and Loans

Taking money out of your retirement fund before age 59½ usually means paying a penalty, often 10%, plus taxes. Some plans also charge fees for taking loans or making early withdrawals. These costs can take a big bite out of your savings. If you’re thinking about tapping your retirement fund early, look at all the fees and penalties first. Try to find other ways to cover expenses if you can. Your future self will thank you.

8. Inflation-Related Costs Hidden in Fees

Inflation eats away at your purchasing power, but some fees make it worse. If your fund charges high fees, your returns might not keep up with inflation. Over time, this means your money buys less, even if your account balance looks bigger. Focus on keeping fees low so your investments have a better chance of outpacing inflation.

9. Revenue Sharing and Conflicted Advice

Some retirement plans include funds that pay the plan provider to be included in the lineup. This is called revenue sharing. It can lead to higher fees and limited choices for you. Sometimes, advisors recommend funds that pay them more, not what’s best for you. Always ask if your advisor or plan provider receives compensation from the funds they recommend. If so, look for unbiased advice elsewhere.

Protecting Your Retirement Fund from Fee Erosion

Fees are everywhere, but you don’t have to let them eat your retirement fund. Review your statements, ask questions, and compare your options. Even small changes—like switching to lower-cost funds or consolidating accounts—can make a big difference over time. The more you keep, the more you’ll have for the retirement you want.

How have fees affected your retirement savings? Share your story or tips in the comments.

Read More

Researching Mutual Funds (or How to Cure Insomnia)

5 Biggest Refinance Concerns

Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Retirement Tagged With: 401(k), investment fees, IRA, Personal Finance, Planning, Retirement, retirement funds, retirement planning

Here’s What You Should Do With Your 401(k) if You Get Laid Off

June 6, 2025 by Travis Campbell Leave a Comment

401k
Image Source: pexels.com

Losing your job is never easy, and the uncertainty can feel overwhelming, especially when it comes to your finances. One of the biggest questions people face after a layoff is what to do with their 401(k). Should you cash it out, roll it over, or just leave it alone? Making the right decision with your 401(k) can have a huge impact on your long-term financial health. If you’re feeling lost or anxious about your next steps, you’re not alone. This guide will walk you through your options in a clear, friendly way, so you can make the best choice for your future.

1. Don’t Panic—Take a Breath Before Making Any Moves

The first thing to remember after a layoff is not to make any hasty decisions with your 401(k). It’s tempting to act quickly, especially if you’re worried about paying bills or finding your next job. But your 401(k) is a crucial part of your retirement savings, and rash moves can lead to unnecessary taxes and penalties. Take some time to assess your overall financial situation. Review your emergency fund, unemployment benefits, and any severance package you might receive. This breathing room will help you make a thoughtful decision about your 401(k) instead of one driven by stress.

2. Understand Your 401(k) Options After a Layoff

When you leave your job, you generally have four main options for your 401(k): leave it with your former employer, roll it over to a new employer’s plan, roll it into an IRA, or cash it out. Each choice has its pros and cons. Leaving your 401(k) with your old employer can be convenient, but you may have limited investment options or higher fees. Rolling it over to a new employer’s plan can simplify your finances if you find a new job quickly. Moving your 401(k) into an IRA often gives you more control and investment choices. Cashing out should be a last resort, as it usually comes with taxes and a 10% early withdrawal penalty if you’re under 59½.

3. Avoid Cashing Out Unless Absolutely Necessary

It might be tempting to cash out your 401(k) to cover immediate expenses, but this move can seriously hurt your retirement savings. Not only will you owe income taxes on the amount you withdraw, but if you’re under 59½, you’ll also face a 10% early withdrawal penalty. That means you could lose a significant chunk of your hard-earned money right off the bat. Plus, you’ll miss out on the future growth that comes from keeping your money invested. If you’re in a tough spot, look for other sources of funds first—like unemployment benefits, a side gig, or even a personal loan—before tapping into your 401(k).

4. Consider Rolling Over to an IRA for More Flexibility

Rolling your 401(k) into an Individual Retirement Account (IRA) can be a smart move if you want more control over your investments. IRAs typically offer a wider range of investment options and may have lower fees than employer-sponsored plans. The rollover process is usually straightforward, and as long as you do a direct rollover, you won’t owe taxes or penalties. This option also makes it easier to manage your retirement savings in one place, especially if you’ve had multiple jobs over the years. For step-by-step instructions, check out the IRS’s rollover chart.

5. Check for Outstanding 401(k) Loans

A layoff can complicate things if you took out a loan from your 401(k) while you were still employed. Most plans require you to repay the outstanding balance within a short window—often 60 to 90 days—after leaving your job. If you can’t repay the loan in time, the remaining balance is treated as a distribution, which means you’ll owe taxes and possibly a penalty. Review your plan’s rules and contact your former employer’s HR department to clarify your repayment options. If you’re unable to pay it back, factor the tax implications into your financial planning.

6. Keep Your Beneficiaries Up to Date

A job change is a great time to review and update your 401(k) beneficiaries. Life changes like marriage, divorce, or the birth of a child can affect who you want to inherit your retirement savings. Make sure your beneficiary designations reflect your current wishes, as these override your will. Keeping this information current ensures your money goes where you want it to, no matter what the future holds.

7. Stay on Top of Fees and Investment Choices

If you decide to leave your 401(k) with your former employer, don’t just set it and forget it. Take a close look at the fees you’re paying and the investment options available. Some plans charge higher administrative fees or offer limited investment choices, which can eat into your returns over time. Compare these with what you’d pay in an IRA or a new employer’s plan. Even small differences in fees can add up to thousands of dollars over the years, so it’s worth doing your homework.

Your 401(k) Is Still Working for You—Even After a Layoff

Getting laid off is tough, but your 401(k) doesn’t have to be another source of stress. Understanding your options and making informed choices can keep your retirement savings on track. Remember, your 401(k) is designed to help you build a secure future, and the decisions you make now can have a big impact down the road. Take your time, seek advice if you need it, and focus on what’s best for your long-term financial health.

What did you do with your 401(k) after a layoff? Share your story or tips in the comments below!

Read More

How to Split an IRA or 401k in a Divorce

401k Alternatives

Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Retirement Tagged With: 401(k), financial advice, IRA rollover, job loss, layoffs, Personal Finance, retirement planning

8 Retirement Plans That Are More Like Financial Time Bombs

May 17, 2025 by Travis Campbell Leave a Comment

401k word on notepad with calculator and coins.
Image Source: 123rf.com

Retirement planning is supposed to be about peace of mind, not ticking time bombs. Yet, many popular retirement plans can quietly sabotage your future if you’re not careful. With so many options out there, it’s easy to fall into traps that look safe on the surface but hide serious risks underneath. Understanding these pitfalls is crucial whether you’re just starting to save or already have a nest egg. After all, the last thing you want is to discover too late that your “secure” retirement plan is actually a financial disaster waiting to happen. Let’s break down eight retirement plans that could blow up your financial future—and what you can do to avoid them.

1. The “Set-It-and-Forget-It” 401(k)

It’s tempting to enroll in your company’s 401(k), pick a default contribution, and never look back. But this hands-off approach can be a financial time bomb. Many people stick with the default investment options, which may not match their risk tolerance or retirement goals. Worse, they often fail to increase contributions as their salary grows, missing out on years of compounding. To avoid this, review your 401(k) annually, adjust your contributions, and make sure your investments align with your long-term plans.

2. Relying Solely on Social Security

Social Security was never meant to be your only source of retirement income, yet millions of Americans treat it that way. The average monthly benefit in 2024 is just over $1,900, which is hardly enough to cover basic expenses for most retirees. Plus, the future of Social Security is uncertain, with potential benefit cuts looming if the trust fund runs short, according to the Social Security Administration. Relying solely on Social Security is risky—supplement it with personal savings, IRAs, or other investments.

3. The “All Eggs in One Basket” Pension

Traditional pensions sound great: guaranteed income for life. But what happens if your employer faces financial trouble or the pension fund is mismanaged? History is full of stories where retirees lost promised benefits due to bankruptcies or underfunded plans. Even government pensions aren’t immune to cuts. Diversify your retirement savings so you’re not left stranded if your pension falters.

4. Early Retirement Account Withdrawals

Dipping into your retirement accounts before age 59½ might seem like a quick fix for financial emergencies, but it’s a classic financial time bomb. Not only will you face hefty penalties and taxes, but you’ll also lose out on years of potential growth. This can dramatically shrink your nest egg and jeopardize your future security. If you’re tempted to withdraw early, explore other options like personal loans or side gigs before raiding your retirement savings.

5. Overestimating Home Equity

Many people assume their home will be their retirement safety net, planning to downsize or take out a reverse mortgage. However, real estate markets can be unpredictable, and selling your home may not yield as much as expected, especially if you need to sell during a downturn. Plus, reverse mortgages come with fees and risks that can erode your equity. Treat your home as a backup plan, not your primary retirement strategy.

6. The “Do-It-Yourself” Investment Trap

Managing your own retirement investments can save on fees, but it’s easy to make costly mistakes if you’re not experienced. Emotional decisions, poor diversification, and chasing hot stocks can all lead to big losses. Even seasoned investors can fall victim to market swings. If you’re not confident in your investment skills, consider working with a fiduciary financial advisor who puts your interests first.

7. Ignoring Healthcare Costs

Healthcare is one of the biggest expenses in retirement, yet many people underestimate how much they’ll need. Medicare doesn’t cover everything, and out-of-pocket costs can quickly add up. According to Fidelity, the average retired couple may need around $315,000 for healthcare expenses in retirement. Failing to plan for these costs can blow a hole in your budget. Consider a Health Savings Account (HSA) or supplemental insurance to help cover the gap.

8. Banking on Inheritance

Counting on a future inheritance to fund your retirement is a risky move. Long-term care costs, market downturns, or unexpected expenses can deplete family wealth. Plus, inheritances can be delayed or contested, leaving you in limbo. Build your retirement plan as if you’ll receive nothing extra, and treat any inheritance as a bonus, not a necessity.

Build a Retirement Plan That Won’t Explode

The best retirement plan is flexible, diversified, and regularly reviewed. Don’t let complacency or wishful thinking turn your golden years into a financial minefield. Take charge by educating yourself, seeking professional advice when needed, and making adjustments as your life and the economy change. Remember, a secure retirement isn’t about luck—it’s about smart, proactive planning.

What about you? Have you encountered any retirement planning “time bombs” or learned lessons the hard way? Share your stories and tips in the comments below!

Read More

Will My 401k Last for the Rest of My Life?

Will Your Retirement Plan Keep Up with Inflation?

Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Retirement Tagged With: 401(k), financial time bombs, healthcare costs, home equity, Inheritance, pensions, Personal Finance, retirement planning, Social Security

Should You Cash Out Your 401(k) If You Need Help Now?

May 12, 2025 by Travis Campbell Leave a Comment

401k retirement chart graph going up with gold and money
Image Source: 123rf.com

Life has a way of throwing curveballs when we least expect them. Maybe you’ve lost your job, faced a medical emergency, or simply struggled to make ends meet. Your 401(k) might look like a tempting lifeline in these moments. After all, it’s your money, right? But before you hit that “cash out” button, it’s crucial to understand what’s really at stake. Deciding whether to cash out your 401(k) if you need help now is a big financial decision that can have lasting consequences for your future.

If you’re feeling the pressure and wondering if tapping into your retirement savings is right, you’re not alone. Many Americans have faced this dilemma, especially during tough economic times. Let’s break down the pros, cons, and alternatives so you can make the best choice for your situation.

1. Understanding the True Cost of Cashing Out Your 401(k)

It’s easy to see your 401(k) balance and consider it a safety net, but cashing out comes with significant costs. If you withdraw funds before age 59½, you’ll likely face a 10% early withdrawal penalty, plus income taxes on the amount you take out. For example, if you withdraw $10,000, you could lose $1,000 to penalties and even more to taxes, depending on your tax bracket. According to the IRS, these penalties encourage long-term retirement savings, not short-term spending.

But the true cost isn’t just about penalties and taxes. You’re also sacrificing the potential growth money could have earned over time. Compound interest is a powerful force, and taking money out now can mean having much less in retirement.

2. Weighing Immediate Needs Against Long-Term Security

When you’re in a financial crunch, focusing on the present is natural. However, your 401(k) is meant to provide security in your later years. Cashing out now could mean working longer or having less to live on when you retire. According to a study by Vanguard, even a small withdrawal can significantly reduce your retirement nest egg over time.

Ask yourself: Is this a temporary setback or a long-term financial crisis? If it’s temporary, consider other options first. If it’s truly an emergency, weigh the pros and cons carefully.

3. Exploring Alternatives Before Cashing Out

Before you cash out your 401(k), look at other ways to get the help you need. Can you cut expenses, negotiate bills, or find temporary work? Many creditors are willing to work with you if you explain your situation. You might also consider a 401(k) loan, which allows you to borrow from your account and pay yourself back with interest. While not risk-free, a loan doesn’t trigger taxes or penalties if repaid on time.

Other options include tapping into emergency savings, seeking community assistance, or even using a low-interest credit card for short-term needs. Each alternative has its own risks, but they may be less damaging than cashing out your retirement savings.

4. The Impact on Your Future Retirement

It’s easy to underestimate how much a 401(k) withdrawal can impact your future. Every dollar you take out now is a dollar that won’t be growing for your retirement. Over the decades, that can add up to tens of thousands of dollars lost. For example, withdrawing $10,000 at age 35 could mean missing out on more than $40,000 by age 65, assuming a 7% annual return.

This is why financial advisors often call cashing out a “last resort.” Your future self will thank you for protecting your retirement savings, even if it means making tough choices today.

5. Special Circumstances: Hardship Withdrawals and CARES Act Provisions

There are situations where you may qualify for a hardship withdrawal, such as medical expenses, disability, or preventing foreclosure. These withdrawals may waive the 10% penalty, but you’ll still owe income taxes. During the COVID-19 pandemic, the CARES Act allowed penalty-free withdrawals for specific individuals, but those provisions have expired. Always check the latest rules and consult with a financial advisor or plan administrator before moving.

6. Getting Professional Advice

If you’re unsure what to do, don’t go it alone. A certified financial planner can help you weigh your options and find the best path forward. Many advisors offer free consultations, especially if you’re facing a financial emergency. They can help you understand the long-term impact of cashing out your 401(k) and explore alternatives you might not have considered.

Protecting Your Future While Navigating Today’s Challenges

Cashing out your 401(k) if you need help now might seem the easiest solution, but it’s rarely the best. The penalties, taxes, and lost growth can set you back for years to come. Instead, explore every alternative, seek professional advice, and remember that your retirement savings are there to protect your future self. Making a thoughtful decision today can help you weather the storm without sacrificing tomorrow’s security.

Have you ever faced a tough decision about your 401(k)? What did you do? Share your story or advice in the comments below!

Read More

Taxes and Penalties for 401(k) Withdrawals

Should I Tap My Retirement Funds for Medical Expenses?

Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Personal Finance Tagged With: 401(k), early withdrawal, emergency funds, Personal Finance, Planning, Retirement, saving for retirement

10 Things to Consider Before Using Your Retirement Savings Before 59½

April 27, 2025 by Travis Campbell Leave a Comment

retired couple
Image Source: pexels.com

Tapping into your retirement savings early might seem like a quick solution to financial challenges, but it comes with significant consequences. Early withdrawals from retirement accounts before age 59½ typically trigger penalties and taxes that can substantially reduce your hard-earned nest egg. Before making this decision, understanding the full implications is crucial for your long-term financial health. Here’s what you need to know before accessing those funds prematurely.

1. The 10% Early Withdrawal Penalty

Most retirement accounts impose a 10% federal penalty on withdrawals made before age 59½. This penalty applies to traditional IRAs, 401(k)s, and similar qualified retirement plans. For example, withdrawing $10,000 early means immediately losing $1,000 to penalties before any taxes are calculated. This significant cost reduces the effective value of your withdrawal and diminishes your retirement security.

2. Additional Income Tax Consequences

Early withdrawals don’t just incur penalties—they’re also subject to ordinary income tax. Since most retirement contributions are made pre-tax, withdrawals count as taxable income. This could potentially push you into a higher tax bracket, increasing your overall tax burden. A $20,000 withdrawal might result in $5,000 or more in federal and state taxes, on top of the 10% penalty.

3. Qualified Exceptions to Early Withdrawal Penalties

The IRS does provide some penalty exemptions for specific situations. These include first-time home purchases (limited to $10,000), qualified higher education expenses, certain medical expenses exceeding 7.5% of your adjusted gross income, and disability. According to the IRS guidelines, understanding these exceptions might help you avoid penalties, though regular income taxes still apply.

4. The Rule of 55 for 401(k) Plans

If you leave your job in or after the year you turn 55, you might qualify for penalty-free withdrawals from your current employer’s 401(k) plan. This “Rule of 55” doesn’t apply to IRAs or previous employers’ plans. Planning your retirement or job transition around this rule could provide more flexibility in accessing funds if needed.

5. Substantially Equal Periodic Payments (SEPP)

The SEPP program allows penalty-free withdrawals if you commit to taking substantially equal payments based on your life expectancy for at least five years or until age 59½, whichever is longer. This complex option requires careful calculation and commitment, as deviating from the payment schedule reinstates all penalties retroactively.

6. The True Cost of Lost Compound Growth

Perhaps the most significant consideration is the opportunity cost of early withdrawals. Money removed from retirement accounts loses its potential for compound growth. A $50,000 withdrawal at age 45 could represent $150,000 or more in lost retirement funds by age 65, assuming a 6% annual return. This invisible cost often exceeds the immediate penalties and taxes.

7. Impact on Social Security Benefits

Early retirement withdrawals can indirectly affect your Social Security benefits. If withdrawals increase your income significantly in certain years, up to 85% of your Social Security benefits might become taxable. Additionally, depleting retirement savings might force you to claim Social Security earlier than optimal, permanently reducing your monthly benefit amount.

8. Alternative Funding Sources to Consider First

Before tapping retirement funds, explore alternatives like home equity loans, personal loans, or temporarily reducing retirement contributions while addressing current financial needs. According to Bankrate’s financial emergency guide, establishing an emergency fund covering 3-6 months of expenses should be a priority to avoid retirement withdrawals.

9. State-Specific Tax Implications

While federal penalties are consistent nationwide, state tax treatment of early withdrawals varies significantly. Some states impose additional penalties or don’t recognize certain federal exemptions. Others offer more favorable treatment. Before making withdrawal decisions, consulting with a tax professional familiar with your state’s regulations is essential.

10. Loan Options vs. Withdrawals from 401(k) Plans

Many 401(k) plans allow participants to borrow against their balance instead of withdrawing funds. These loans typically must be repaid within five years and don’t trigger taxes or penalties if repayment terms are met. However, outstanding loans typically become due within 60-90 days if you leave your employer, potentially creating a tax crisis if you can’t repay quickly.

Protecting Your Future Self: The Long View on Retirement Funds

Your retirement savings represent financial security for your future self. While current financial pressures may feel overwhelming, depleting these accounts early can create even greater challenges later in life when earning potential diminishes. According to the Employee Benefit Research Institute, Americans consistently underestimate their retirement needs. Preserving these funds should be considered a last resort, undertaken only after careful analysis of all alternatives and long-term implications.

Have you ever faced a financial emergency that tempted you to tap into retirement savings? What strategies did you use to protect your nest egg while addressing immediate needs?

Read More

Will My 401k Last for the Rest of My Life?

Will Your Retirement Plan Keep Up with Inflation?

Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Retirement Tagged With: 401(k), early withdrawal penalty, IRA, Planning, retirement planning, retirement savings, tax implications

Is A 401K Worth It?

July 5, 2022 by Tamila McDonald Leave a Comment

is a 401k worth it

When you’re planning for retirement, classic advice usually states to take advantage of every plan option available to you. However, while a 401K can be an asset, that doesn’t mean it’s the perfect choice for every situation. If you’re wondering if a 401K is worth it, here’s what you need to know.

The Benefits of a 401K

A 401K has specific benefits that can potentially make one a worthwhile addition to your retirement plan. One of the biggest is its tax-deferred status. When you start contributing, you reduce your tax burden immediately since the payments typically come from pre-tax dollars. If you earn more money now than you will in retirement, you’ll potentially come out financially ahead.

Employer matches are another benefit of a 401K. Many companies will match employee contributions up to a specific amount. By contributing enough to capture the maximum, you’re essentially collecting the most “free” money possible for retirement.

In most cases, 401Ks come with a wide array of investment options, too. This allows you to choose a portfolio mix based on your comfort with risk, values, financial goals, and other factors. Plus, there are typically several asset classes available, including stocks, ETFs, money market funds, and more.

Finally, many 401Ks allow people to borrow against the account. Essentially, your account balance acts as collateral, and you can pay the amount back with interest over time. In some cases, these loans offer more favorable rates. Plus, if you repay the full amount before changing to a new employer, it typically won’t impact your income for tax purposes.

The Drawbacks of a 401K

While 401Ks come with some notable benefits, that doesn’t mean there aren’t drawbacks to consider. As a defined contribution plan, you’ll send an amount to the plan every paycheck regardless of market conditions. While the concept of dollar-cost averaging could reduce any harm from investing at inopportune times, it does mean you’ll sometimes invest during periods that aren’t offering the best value.

You may also have to contend with 401K fees. Precisely what that involves varies from one employer to the next, but they can add up surprisingly quickly, offsetting at least some of your earnings or actually causing you to spend more than you make during economic downturns.

It’s also important to note that some 401K plans come with surprisingly few investment options. You may have only a small number of investments to choose from, and most of what’s available may simply be mutual funds, particularly target-date funds.

Finally, while employer matches are typically one of the benefits of 401Ks, not all companies offer one. Additionally, some have very low matches, which can make a high-cost 401K a poor choice for some investors.

Is a 401K Worth It?

Generally speaking, a 401K can be worth it, suggesting you have a plan available that meets your needs. If there is a wide array of investment options, a generous employer match, and a reasonable fee structure, and you’re in a higher tax bracket now than you will be in the future, using a tax-deferred option like a 401K could be worthwhile. However, if none of that applies, there are more flexible options available, and it could be wise to explore them instead.

Do you have a 401K? If so, do you think it’s worthwhile, or do you believe that other retirement savings options are a better fit? How do you make the most of your 401K to ensure your financial future? Share your thoughts in the comments below.

Read More:

  • What You Need to Know About Solo 401(k)s
  • What to Do with Your Old 401k
  • Can an Employer Charge Fees to Turnover Your 401(k) After You Quit a Job?


Tamila McDonald
Tamila McDonald

Tamila McDonald is a U.S. Army veteran with 20 years of service, including five years as a military financial advisor. After retiring from the Army, she spent eight years as an AFCPE-certified personal financial advisor for wounded warriors and their families. Now she writes about personal finance and benefits programs for numerous financial websites.

Filed Under: Personal Finance Tagged With: 401(k), 401k plans

What To Do With Your Old 401k

February 16, 2022 by Jacob Sensiba Leave a Comment

old-401k

When you leave your job and you have a 401k, there are a few things you can do with it. You can leave it there, you can cash it out, you can roll it into an IRA, or you can roll it into a retirement plan with your new employer. So what should you do with your old 401k?

Theoretically, you have four options.

Withdrawing your funds

If you are under the age of 59 ½ and you withdraw the money, you’ll have to pay a tax penalty on it. UNLESS, you meet some of the exceptions: medical expenses, your first, primary residence (up to $10,000), health insurance premiums while unemployed, distributions from an inherited IRA, pay off an IRS tax levy, higher education expenses, as well as a few others.

If you don’t meet any of those criteria and you’re under 59 ½, you’ll have to pay that penalty. It’s not worth it. UNLESS you’re using that money to pay off a credit card. Credit card interest rates are usually well above 10%. So if you’re saving yourself from paying a 27% interest rate, theoretically, you’re making a 17% return on your money (27–10=17). But this calculation doesn’t account for taxes so you might come out even, or behind.

95% of the time, it makes the most sense to pursue other options.

Keep it where it is

Some people will leave their old 401k with their previous employer. I think a lot of that has to do with laziness, but it could be a good, rational decision as well. The primary factor has to do with cost. What are the expenses of the 401k? Typically, if it’s a large employer and/or a large plan with a lot of assets, the fees are going to be low.

That might be a good reason to leave it. The plan might also have good investment options. If the fees are reasonable, or at least average, then the investment options might be reason enough to stay.

Roll it to your new employer

Nine times out of ten, I’ll have people roll their old 401k into their new one. If they’re able to. Some employers don’t allow income transfers. Having everything with one firm makes managing it so much easier.

The only time I don’t think it would be appropriate is if the new firm has high fees, but it’s also important to compare the new fees to the fees of the alternative. That alternative is rolling it into an IRA at a separate firm.

Roll it into an IRA

As an independent financial advisor, this option is best for me, but not typically best for the client. If you take a standard fee for a financial advisor (1.00 %) and compare it to the standard expense paid by a 401k participant. Employers with 2,000 employees pay below 1% and employers with 50 or fewer employees pay 1.25%. Here’s some more info on that.

That might be the case if it’s a small plan. The large plans, however, can have ALL IN fees of around .5%.

As is the case with a lot of things in the finance world, the answer is not black and white. You need to compare and contrast your options and then make a decision. Here are things to consider: cost, investment options, ease of management, and customer service. How do the fees compare? What are the investment options? Do you have everything in one place and is it easy to make changes? Can you get in touch with someone if you have problems/questions?

Related reading:

7 Tips to Get the Most Out of Your 401k v/s Pension

401k Withdrawal Taxes and Penalties

Is your 401k Hurting you or Helping you?

How 401k Fees Impact Your Retirement

Disclaimer:

**Securities offered through Securities America, Inc., Member FINRA/SIPC. Advisory services offered through Securities America Advisors, Inc. Securities America and its representatives do not provide tax or legal advice; therefore, it is important to coordinate with your tax or legal advisor regarding your specific situation. Please see the website for full disclosures: www.crgfinancialservices.com

Jacob Sensiba
Jacob Sensiba

Jacob Sensible is a financial advisor with decades of experience in the financial planning industry.  His journey into finance began out of necessity, stepping up to support his grandfather during a health crisis. This period not only grounded him in the essentials of stock analysis, investment strategies, and the critical roles of insurance and trusts in asset preservation but also instilled a comprehensive understanding of financial markets and wealth management.  Jacob can be reached at: jake.sensiba@mygfpartner.com.

mygfpartner.com/jacob-sensiba-wisconsin-financial-advisor/

Filed Under: Investing, low cost investing, money management, Personal Finance, Planning, Retirement Tagged With: 401(k), 401(k) fees, 401k plans, IRA, old 401k money, Retirement, retirement plan, retirement planning, retirement savings, what to do with a 401k rollover

Investment Tips: How much should I have in my 401(k)?

May 14, 2020 by Susan Paige Leave a Comment

Part of planning for financial freedom is making sure that you are financially protected when you hit retirement. However, only a few know how to maximize their 401(k) in a retirement investment account as part of their overall portfolio.

If you want to explore the basics of investing your 401(k) to increase your retirement benefits, no worries. This article provides you with a summary of the five (5) most useful tips on how your 401(k) can help you retire with more financial security.

What are 401(k) Investments?

Before going into the details, you should know that a 401(k) investment is basically a retirement savings tool sponsored by your employer. This tool allows you to invest a portion of your paycheck into a retirement investment account. Your money will grow tax-free until you are retired, and that’s when you can use it.

The question that many ask is about the portion: how much of one’s paycheck should go into this retirement investment? In addition to that, here are some tips about putting a part of your paycheck to your 401(k) investments.

Invest Early

It is true that you can begin your retirement investment later when you are older. However, the earlier you start investing, the better. In fact, it is best to start contributing to your 401(k) as soon as possible. In doing this, you earn more. That’s just how compound interest works: you gain more interest when you start earlier. If you are a young worker, you have the advantage of the time that older folks will never ever have. Invest early.

See How Much You Can Set Aside

As a rule of thumb, you need to invest a percentage of your earnings that is equivalent to the difference between 100 and your age. For instance, if you are 20 years old, you need to invest 80% of your earnings as savings or into your retirement fund. This is based on the assumption that, at an early age, you still don’t have many responsibilities and can afford to invest more money.

If that amount or percentage is too high, you can decide on a fixed annual amount. For example, you can contribute a max of $19,500 to your 401(k) in 2020 if you are under 50. All you have to do is calculate a fixed amount below the threshold of $19,500.

Hire a Portfolio Manager

Still unsure or want to maximize your investments? You can explore other options such as using a robo-advisor such as Wealthfront or Betterment. This is one of the best options for someone who is unsure or does not know how much they should invest.

The robo-advisor will run the numbers for you to determine the best combination of investments in your 401(k) fund. You can set the target amount you need for retirement and the algorithms will compute how much you need to set aside every month or year so that you can have that amount when you retire.

Match Your Employer

Another way to determine how much you should contribute in your 401(k) is to look at how much your employer is contributing. For instance, if your employer only offers a maximum of 10% of your salary, then you should match your employer and contribute at least 10% as well to get the most out of your 401(k) investments.

Check Investment Types

When you contribute funds to your 401(k), you have to choose which investments it goes to. With each kind of investment, there is a specific percentage of return based on the risk profile. Since the percentage of return is different for each investment, your choice will affect how much you need to contribute in the 401(k) so that you can reach your target retirement funds.

If you have enough in your 401(k), before you start computing, consider the types of investments that you will choose. For instance, if you choose to invest in the stock market, you will earn more and faster but the risk is higher. If you want to do this, you might want to invest a lower amount.

On the other hand, you will have more stable returns if you invest in mutual funds. However, interest will be less so you want to contribute a higher amount to achieve the retirement fund levels that you want.

Takeaways

For dignity and independence, you want to retire with enough funds so that you won’t need to depend on help from your children or other people. With the investment tips summarized in this article, you can think about your best options to save and invest money in your 401(k) for your retirement. The five (5) points summarized in this article should help you begin to find the answers to all your basic questions and concerns.

For more great articles from The Free Financial Advisor, consider these:

Financial Planning Basics – The Financial Pyramid

How Long Should You Keep Financial Records After A Death

What Advantages Are There To Saving Money In The Bank?

How To Recover Paystubs From Your Old Job

Filed Under: money management Tagged With: 401(k), 401k plans, Retirement

Will My 401(k) Last for the Rest Of My Life?

April 23, 2018 by Leave a Comment

If you’re starting to think about retirement, and your career has largely been in the private sector, your 401(k) balance could be the most important factor in determining whether you’re on track to retire or not.

Whether your 401(k) will cover your spending needs until the end of your life will depend on a lot of factors. It’s important to not just pin your hopes on a certain target for an account balance–a million dollars, two million dollars, whatever–and instead look at the whole picture. So let’s start with a few other questions that are just as important.

Are You Saving as Much as You Can in Your 401(k)?

There’s almost no way around it: You have to save money to make money. There is often a bit of a free lunch–call it a free appetizer–when it comes to 401(k)s, though: The amount your employer matches your own contributions. It could be a dollar-for-dollar match up to point, or some percentage of what you contribute yourself that increases over time. Either way, you definitely want to contribute at least this amount, or you’re leaving that free appetizer on the plate.

But that should really only be the beginning of any 401(k) savings plan. Fidelity advises saving 15% of pretax income.  If you’re 30 or 40 years old and haven’t given the issue much thought until now, that number should serve as the minimum you should save.

Get into the habit of increasing your contribution percentage each year. Psychologically speaking, if you never see it hit your paycheck (because it’s going straight to your retirement account), you won’t miss it. Set an annual calendar reminder to increase that contribution, even by a half a percentage point. Between the contribution increases and salary increases, you should be able to put your contributions on a sharp upward trajectory.

What Else have You Got?

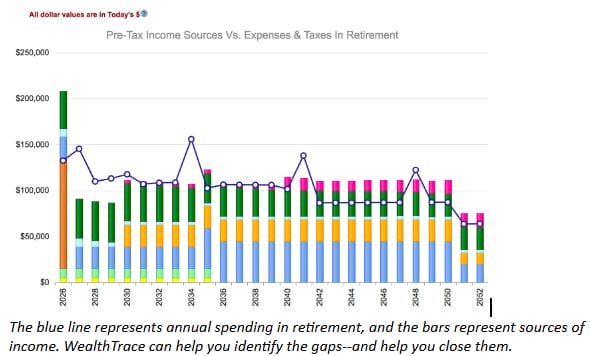
Once you have your plan for annually boosting 401(k) savings in place, consider what other sources of income you are counting on at retirement. Social Security is an obvious one. If you’re lucky you might have a pension of some sort. Brokerage accounts, rental property, or the planned sale of some asset like a business should all be taken into account as well–and will almost certainly affect how long you can expect your 401(k) will last.

Will you run out of 401(k) money in retirement?

Another reason not to simply come up with an arbitrary hit-your-number mark: Spending matters. At the risk of stating the obvious, your 401(k) and other investment assets will generally last longer if you plan to sip rather than gulp.

You’ll want to have a very solid grip on your plan’s MPG–that is, your projected spending in retirement–to get an accurate reading.

Will your 401(k) plan last long enough?

What Is It Costing You?

Even if you are diligent about saving to your 401(k), you probably haven’t considered what the plans might be costing you.

And why would you? The plan administrator’s fees–in addition to the fees paid to the fund companies themselves–are largely out of your control.

But it’s important–especially the further you are from retirement. Fees can really chip away at account balances over time. Consider a 401(k) returning about 7% annually. Here’s what happens if we modify the fees by half a percentage point and assume contributions of $18,000 per year.

Will Your 401(k) Plan Last Long Enough

Your main recourse here is to talk to your HR department and start asking questions. What are the fees of running the plan? How do they compare with fees offered by other plan administrators for companies of your size? Making sure the HR team has done their due diligence on this could mean tens of thousands of dollars to you.

You can also look at the fees charged by the funds themselves. Funds have expense ratios; actively managed funds generally have higher expense ratios than passively managed funds. To keep things really simple, consider a target-date retirement fund, which shifts its asset classes toward less risk the closer you get to retirement. (And if your plan does not offer a target date retirement fund, it should.)

Your 401(k) Is One Piece of a Larger Puzzle

A large 401(k) balance could have a big effect on when you can retire and your living standard when you do. But looking at it in the context of everything else we’ve talked about here is more important than an absolute dollar figure. Total savings, where you plan to invest your assets, the cost of those investments, and your spending habits are all complementary forces that will factor into a successful retirement plan.

Read More

  • How to Split an IRA or 401(k) in a Divorce
  • Five 401(k) Alternatives You Need to Know About
  • Saving to Boost Your 401(k)
  • IRS Announces 2018 Pension Plan Limitations
  • Avoid These Common Mistakes When Planning for Retirement
  • How to Save for Retirement
  • Investing Your Way to Retirement

Filed Under: Retirement, Uncategorized Tagged With: 401(k), Retirement, retirement plan

How to Split an IRA or 401(k) in a Divorce

July 19, 2012 by The Other Guy 11 Comments

Divorce is ugly.  Except under the most limited circumstances, no one wins in the divorce game.  Then, you add the complexity of money into the equation and it gets downright hideous.  In that emotional time, it’s easy to understand why so many people divide IRAs, 401(k)s, and other retirement accounts sub-optimally.

You can’t just “take the money out and give it to my spouse”  That would be a big mistake.  Let me count the ways:

Let’s assume you own a $250,000 401(k) balance.  The judge rules that you’re required to split that 50/50 with your spouse, so you decide it would be easiest to make a phone call and take the money out.  Ouch.  If you do that, you’ll be hit with a 10 percent early withdrawal penalty (yes you, not your spouse, and only if you’re under 59 1/2) and then the amount you removed is added to your taxable income for the year.  Now, for many reading this blog, you’ve just lost 35-45%.

So how do you give $125,000 to someone?  Oh that’s easy – you gift that to them.  But in your haste, you didn’t do this correctly either. To gift it, you either need to reduce your lifetime exemption by filing a form 706 with your income taxes next April, or pay a gift tax of 50%.

Long story short: “taking it out” could be a massive financial mistake.

Instead, consider asking for a QDRO, or Qualified Domestic Relations Order (pronounced quad-row).  A QDRO put together by a competent attorney and signed off on by the judge makes this transfer a ton easier.

First, it directs your retirement plan company to establish another qualified plan in the name of your spouse.  Then, it directs a tax-free transfer to that newly established account.  No taxes, no penalties.  Easy as pie.

Once you’ve begun working on that, you’ll want to make sure the QDRO says that your soon-to-be ex-spouse can’t make any loans or transfers from the account until it’s been split; or you could just pick a date to make the transfer effective on (retroactive) and put a fixed dollar amount based on that date’s plan balance.  This would protect the new beneficiary from being bamboozled by his or her ex.

Finally, don’t forget about pension plans.  A lot of those can be “QDROed” too.  For example, let’s assume your spouse earned a pension at his job of $4,000 during the 30 years he worked.  He was married to you for 20 of those 30 years – making you the owner of 2/3 of his $4,000 per month.  By putting the QDRO in place before he retires, she can have her own pension plan – quite the deal!

At the end of the day, divorce planning with money is just as important as married couple planning.  If you don’t do it, you’ll regret it.  Take the time to review everything – hire a professional and don’t try to cut corners.  The costs are too severe.


Enhanced by Zemanta

Filed Under: money management, Planning, Tax Planning Tagged With: 401(k), divorce, IRA, Marriage, Pension, QDRO, Qualified domestic relations order, Roth IRA, Tax

  • « Previous Page
  • 1
  • …
  • 5
  • 6
  • 7
  • 8
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • 10 Tactics for Building an Emergency Fund from Scratch by Vanessa Bermudez
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald

Copyright © 2026 · News Pro Theme on Genesis Framework