• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for retirement budget

July CPI Numbers Retirees Can Use to Test Their 2026 Spending Plan

August 12, 2026 by Brandon Marcus Leave a Comment

July CPI Numbers Retirees Can Use to Test Their 2026 Spending Plan
July CPI rose 3.4% over the past year, but retirees should look beyond the headline and compare shelter, food, energy and medical costs with their own 2026 spending plan – Shutterstock

July CPI numbers offer retirees something more useful than another inflation headline: a chance to give a 2026 spending plan a reality check. The latest Consumer Price Index from the U.S. Bureau of Labor Statistics shows overall consumer prices rose 3.4% over the 12 months ending in July, while prices excluding food and energy rose 2.5%.

That does not mean every retiree needs to increase every budget category by 3.4%. Far from it. The better move involves looking at where money actually goes each month and comparing those expenses with the parts of the CPI that most closely resemble real household spending. Think of it as taking the retirement budget out for a test drive before a surprise repair bill, grocery run, or utility statement starts making decisions for it.

The Headline Inflation Number Is Only the Starting Line

The July CPI report gives the broad inflation picture, but the headline number can hide some very different price movements underneath it. Overall CPI rose 0.1% in July on a seasonally adjusted basis after falling 0.4% in June, while the 12-month increase eased slightly from June’s 3.5% to 3.4%.

For a retiree, that distinction matters because household budgets rarely resemble the theoretical “average” basket perfectly. Someone who owns a home outright may care much more about food, utilities, gasoline and medical expenses than rent, while a renter may feel shelter costs much more sharply. BLS also notes that CPI-U covers spending patterns for urban consumers, including retired people, but the index still represents a broad population rather than any one household.

Shelter, Food and Energy Deserve Their Own Reality Check

Shelter deserves a particularly close look because it remains one of the largest household expenses, and July brought a 3.2% increase in the shelter index over the previous year. The shelter index rose 0.1% in July, with both rent and owners’ equivalent rent increasing 0.3% for the month.

Food tells a somewhat different story, with the overall food index up 3.0% over the year and food purchased for home consumption up 2.7%. Food away from home climbed 3.4%, which makes restaurant-heavy budgets more vulnerable than grocery-focused ones. Energy deserves an even bigger warning label: the energy index fell 1.5% in July, yet it remained 14.7% higher than a year earlier, with gasoline up 24.6% over that period.

Turn July CPI Into a Personal Budget Stress Test

The simplest test starts with actual spending rather than an inflation calculator. Pull the last several months of bank and credit-card statements, then group expenses into categories such as housing, groceries, restaurants, transportation, utilities, medical care, insurance, travel and entertainment. Next, compare the categories that matter most with the latest CPI movements instead of applying one inflation rate to the entire budget.

Consider a retiree who planned a comfortable monthly budget but left little room for higher gasoline, utility or grocery costs. July’s numbers provide a useful reason to revisit those assumptions, particularly because gasoline rose 24.6% over the year while electricity rose 4.2% and natural gas rose 4.3%. Medical care also deserves attention: the medical care index increased 0.4% in July, while medical care services rose 2.7% over the year.

Don’t Let a Quiet Month Fool the Retirement Plan

One calmer month does not guarantee a calm year, and July offers a perfect example of why retirees should resist making sweeping budget changes from a single CPI release. Gasoline prices fell 2.9% in July, while food at home fell 0.1%, but both categories can move considerably from month to month.

A stronger approach uses July as a checkpoint rather than a prediction machine. If a retirement plan already has room for rising costs, the latest numbers may provide reassurance; if several major expenses already exceed the plan’s assumptions, July offers an early warning to make adjustments while the choices remain manageable. BLS also explains that unadjusted CPI data matters to consumers concerned about the prices they actually pay, while seasonally adjusted figures help analysts examine short-term trends.

Give the 2026 Budget Some Breathing Room

The most useful lesson from July CPI data involves flexibility, not fear. A retirement budget should leave enough room for expenses that refuse to behave politely, especially energy, food, housing and medical costs.

Retirees can use the July report as a simple annual maintenance check: compare actual spending with planned spending, identify categories running hot, and decide whether to trim discretionary expenses, increase the cash cushion or revise future withdrawals. The goal does not involve predicting the next CPI release perfectly, because nobody gets a crystal ball with their Medicare card. The goal involves spotting pressure early enough to make deliberate choices instead of scrambling after the budget breaks. July’s 3.4% overall inflation figure matters, but the numbers hiding underneath it may matter much more to a particular retirement household.

Which part of your 2026 retirement budget has changed the most because of rising prices, and has the latest CPI report changed how you plan to spend for the rest of the year?

You May Also Like…

6 Social Security Earnings-Test Details Workers Near Retirement Often Misread

A Closer Look at Medicare Costs Retirees Should Put Into a 2027 Planning File Now

Why Inflation Data on July 14 Could Shift Retirement and Bond Planning

Why Grocery Inflation Feels Worse at Checkout Than It Looks on Paper

7 Retirement Budget Categories Rising Faster Than Inflation in 2026

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Personal Finance Tagged With: 2026 spending, CPI, Inflation, Personal Finance, retirees, retirement budget, retirement planning, Social Security

6 Retirement Expenses That Can Rise Even When Inflation Slows

August 12, 2026 by Brandon Marcus Leave a Comment

6 Retirement Expenses That Can Rise Even When Inflation Slows
Retirement expenses do not always move with headline inflation, making housing, health care, food, utilities, transportation and insurance important categories to monitor separately – Shutterstock

Inflation can slow without prices actually falling, and that distinction matters enormously in retirement. The latest Consumer Price Index data from the U.S. Bureau of Labor Statistics shows why: overall consumer prices rose 3.5% over the year ending in June 2026, but individual categories moved at very different speeds.

That creates a sneaky retirement-budget problem. A household may spend less on one category while watching another bill quietly creep higher, and a national inflation average cannot tell anyone exactly what their own landlord, doctor, utility company, grocery store or mechanic will charge next. The smart move involves watching the expenses that can put the most pressure on a fixed income rather than assuming every bill will follow the headline CPI.

1. Housing Can Keep Taking a Bigger Bite

Housing ranks among the biggest expenses in many retirement budgets, and it can keep getting more expensive even when overall inflation cools. BLS data showed shelter prices up 3.3% over the year ending in June 2026, with rent of primary residences up 2.8%.

For homeowners, the story looks different because mortgage payments, property taxes, insurance, repairs and utilities each follow their own pricing paths. A retiree who paid off a mortgage still faces the less glamorous parade of roof repairs, plumbing problems, property taxes and insurance renewals. That means a debt-free house does not equal a cost-free house. Building a dedicated home-maintenance reserve can help keep one nasty repair from hijacking an otherwise comfortable monthly budget.

2. Health Care Has a Habit of Staying Important

Health care deserves special attention because retirement often brings more interaction with the medical system, even when a person feels perfectly fine today. BLS reported a 2.9% year-over-year increase in medical care services in June 2026, while hospital services rose 5.1%.

The CPI category also includes professional services, hospital care and health insurance, so the number does not translate neatly into any one retiree’s out-of-pocket bill. Medicare premiums, deductibles, prescription costs, dental work and vision care can all affect a household differently. A practical retirement budget should therefore leave room for medical expenses that do not arrive on a predictable monthly schedule, because knees, teeth and eyeglasses have never shown much respect for spreadsheets.

3. Groceries Can Keep Moving Around

Food prices provide another excellent reminder that inflation does not move like a synchronized marching band. In June 2026, the BLS reported a 3.0% increase in food prices over the previous year, with food at home up 2.7% and food away from home up 3.4%.

Those broad figures still cannot predict what will happen to one person’s grocery receipt. A retiree who buys more fresh produce may notice a different pattern from someone who relies heavily on packaged foods, while restaurant-heavy spending creates another set of price pressures. A flexible food budget works better than treating one year’s grocery bill as a permanent ceiling, especially when a favorite staple suddenly decides to become a luxury item.

4. Utilities Can Refuse to Cooperate

Utility bills can make a retirement budget particularly cranky because weather, household usage and local pricing all matter. The June 2026 CPI showed energy services up 3.9% over the year, while electricity prices rose 4.0% and piped natural gas prices rose 3.0%.

Those national figures do not predict an individual utility bill, and they certainly cannot account for every hot summer, cold winter or rate change. A household that keeps the thermostat comfortable around the clock may experience a very different bill from a household that travels frequently or uses less energy. Retirement planning should include a little breathing room for utilities rather than assuming the current average bill will remain frozen forever.

5. Car Repairs Can Get Expensive Fast

Transportation costs can sneak up on retirees because a vehicle may become less of a commute machine and more of a lifeline for groceries, appointments and everyday errands. BLS data showed motor vehicle maintenance and repair prices up 7.0% over the year ending in June 2026, even as the overall CPI rose at a slower pace.

That does not mean every mechanic will raise prices by that amount, but it does illustrate the danger of using headline inflation as a universal budget-setting tool. One transmission problem, tire replacement or air-conditioning repair can create a surprisingly large expense. Keeping an automobile repair fund separate from ordinary monthly spending can make those four-wheeled surprises considerably less painful.

6. Insurance Bills Can Change Direction

Insurance deserves a spot on the list because premiums do not march neatly in lockstep with overall consumer prices. In fact, the national CPI for motor vehicle insurance fell 4.1% over the year ending in June 2026, which proves an important point: a national category can move down while an individual household’s premium moves up.

Premiums can reflect factors that have little to do with the overall inflation rate, including the policyholder’s circumstances, coverage choices and insurer pricing. Homeowners insurance, auto coverage, and other policies can therefore create budget surprises even during a period of slower broad inflation. Reviewing coverage and premiums periodically makes more sense than assuming a falling national index guarantees a cheaper renewal notice.

The Retirement Budget Needs Its Own Inflation Radar

The biggest lesson from the CPI is simple: slower inflation does not mean cheaper living. BLS defines the CPI as a measure of the average change over time in prices paid by urban consumers for a market basket of goods and services, which makes it useful for tracking broad price trends but less useful as a crystal ball for one household.

Retirees can respond by tracking their own spending categories separately, especially housing, health care, food, utilities, transportation and insurance. A personal budget that leaves room for uneven price increases can prove far more useful than one that assumes every expense will rise at the same rate. The goal is not to predict every bill perfectly, because even the fanciest spreadsheet cannot negotiate with a broken water heater. The goal is to build enough flexibility into retirement spending that one stubbornly expensive category does not throw the entire plan off course.

Which retirement expense has surprised you most when its price climbed faster than expected?

You May Also Like…

5 Retirement Plan Fees That Look Small Until You Calculate the Long-Term Cost

What to Know About Social Security Claiming Assumptions That Can Distort a Retirement Plan

Why Inflation Data on July 14 Could Shift Retirement and Bond Planning

7 Retirement Budget Categories Rising Faster Than Inflation in 2026

6 RMD Planning Errors Retirees Can Still Correct Before Year-End

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Retirement Tagged With: Cost of living, CPI, Inflation, Personal Finance, retirement budget, retirement expenses, retirement planning, senior finances

7 Retirement Budget Categories Rising Faster Than Inflation in 2026

May 22, 2026 by Brandon Marcus Leave a Comment

7 Retirement Budget Categories Rising Faster Than Inflation in 2026
Retired couples are facing a lot of budget problems, thanks to inflation in 2026 – Shutterstock

Retirement finances feel more unpredictable in 2026 as everyday expenses continue to climb at a pace that outpaces many traditional inflation estimates. Many retirees built budgets assuming slow, steady cost increases, yet real-world prices now jump in sharper, uneven waves. Essential categories like healthcare, housing, and food show especially aggressive increases that reshape long-term financial plans. Even modest lifestyle choices now carry heavier price tags, forcing retirees to reassess priorities. The shift does not just affect comfort but also directly impacts financial security over a 20- to 30-year retirement horizon.

The biggest challenge comes from how these rising costs stack together instead of increasing in isolation. One category may strain the budget, but several rising simultaneously creates a compounding effect that surprises many households. Fixed incomes struggle to absorb these changes, especially when Social Security adjustments fail to match real spending increases. Retirement planning now demands sharper attention to category-specific inflation rather than relying on general national averages.

1. Housing Costs Continue to Dominate Retirement Budgets

Housing remains the largest expense for most retirees, and 2026 brings another wave of rising rents, property taxes, and insurance premiums. Even homeowners who paid off mortgages still face escalating costs tied to taxes and maintenance. Insurance companies now adjust premiums more aggressively due to climate-related risks and higher rebuilding costs. Renters experience even sharper pressure in many markets as demand for affordable senior housing outpaces supply.

This category continues to absorb a larger share of retirement income, often surpassing recommended financial planning benchmarks. Many retirees now relocate or downsize earlier than expected to regain control over monthly expenses. Housing assistance programs struggle to keep up with demand, especially in high-growth regions. Financial advisors increasingly recommend setting stricter housing caps within retirement budgets to avoid long-term strain.

2. Healthcare Expenses Push Higher Across All Age Groups

Healthcare costs in 2026 continue to rise faster than overall inflation, placing significant pressure on retirees managing chronic conditions. Prescription drug prices, specialist visits, and diagnostic tests all trend upward at a noticeable pace. Even insured retirees face higher out-of-pocket expenses due to deductibles and copays. Medicare coverage still leaves gaps that require supplemental insurance or personal savings.

Medical innovation drives better treatments, but those advancements often come with higher price tags. Many retirees delay non-urgent procedures to manage costs more effectively. Preventive care helps reduce long-term spending, yet routine visits still add up quickly. This category remains one of the most unpredictable parts of any retirement budget.

3. Long-Term Care Costs Create Major Financial Strain

Long-term care expenses rise sharply in 2026 as assisted living facilities and home care services face staffing shortages and higher wage requirements. These pressures push facility fees upward across many regions. Families now encounter significantly higher costs when a loved one requires daily assistance. Even part-time in-home care services show noticeable price increases compared to previous years.

Insurance policies designed for long-term care often fail to cover full expenses, leaving gaps that retirees must fill. Many families rely on a mix of savings and shared caregiving responsibilities to reduce financial pressure. The demand for aging-in-place services grows, yet supply remains limited in many communities. This category increasingly shapes retirement planning decisions earlier in life.

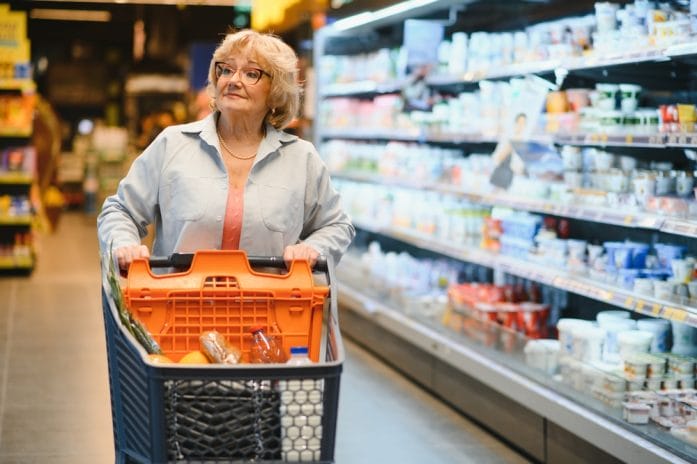
4. Grocery and Food Prices Stay Stubbornly High

Food costs continue to rise faster than general inflation as supply chain disruptions and agricultural challenges persist into 2026. Grocery bills climb even when retirees stick to basic, healthy diets. Fresh produce, lean proteins, and specialty health foods all show noticeable price increases. Eating at home no longer guarantees significant savings compared to previous years.

Many retirees adjust shopping habits by switching brands or buying in bulk to manage costs. Discount grocery stores and membership clubs see increased senior participation. Meal planning becomes more strategic as households try to reduce waste and stretch budgets further. Food inflation directly affects quality of life because it touches every daily routine.

7 Retirement Budget Categories Rising Faster Than Inflation in 2026
Grocery shopping is more difficult than ever for retirees – Shutterstock

5. Utility and Energy Bills Add Monthly Pressure

Utility costs continue their upward trend as energy infrastructure investments and weather volatility increase operational expenses. Electricity and natural gas bills rise in many regions, especially during extreme weather seasons. Water and waste services also adjust pricing structures to meet infrastructure demands. These increases hit retirees on fixed incomes particularly hard.

Energy-efficient upgrades help reduce long-term costs, but upfront investment often discourages immediate action. Many households shift thermostat habits and reduce discretionary usage to control bills. Solar adoption grows slowly among retirees due to installation costs. Utility inflation quietly erodes purchasing power month after month.

6. Transportation and Auto Insurance Costs Accelerate

Transportation expenses rise quickly in 2026 due to higher vehicle prices, maintenance costs, and auto insurance premiums. Even retirees who drive less still face rising fixed costs like coverage and registration fees. Repair shops report higher parts prices and labor shortages that push service bills upward. Public transportation fares also increase in several metropolitan areas.

Many retirees delay vehicle replacement or switch to smaller, fuel-efficient models to manage costs. Ride-sharing services become more attractive for occasional travel despite fluctuating pricing. Insurance companies adjust premiums based on repair costs and risk models. Transportation now takes a larger share of discretionary retirement spending than in previous years.

7. Travel and Leisure Costs Climb for Retirees Seeking Lifestyle Balance

Travel and leisure expenses rise as demand rebounds and service providers adjust pricing after years of volatility. Hotels, airfare, and cruise packages all reflect higher operational costs in 2026. Even local entertainment options like dining out and events show steady price increases. Retirees who prioritize experiences feel these changes most strongly.

Many travelers shift toward off-season trips or shorter vacations to manage budgets. Loyalty programs and early booking strategies help reduce some financial pressure. Leisure spending still plays an important role in retirement satisfaction, so many households preserve this category despite rising costs. Balancing enjoyment with financial discipline becomes a key theme in modern retirement planning.

What These Rising Costs Mean for Retirement Planning Ahead

Retirement budgets in 2026 face pressure from multiple directions at once, not just isolated price increases. Housing, healthcare, and long-term care dominate financial stress, while everyday essentials like food and utilities quietly erode remaining flexibility. Retirees who adapt early often gain more control by adjusting spending categories before costs escalate further. Strategic planning now requires constant review rather than static yearly assumptions. Financial resilience grows stronger when retirees actively track category-specific inflation trends instead of relying on outdated averages.

What changes would make the biggest difference in a retirement budget today, and which rising cost feels the most challenging to manage?

You May Also Like…

California Seniors Face Insurance Renewal Shock as Housing and Utility Costs Continue Climbing

North Carolina Retirees Are Filing for Social Security Earlier as Insolvency Fears Grow

Texas Retirees: Property Insurance Premiums Rose Over 20% in Some Counties Last Year — Here’s What Seniors Are Cutting to Keep Up

7 Medicare Costs Rising Faster Than the 2027 Social Security COLA Forecast

8 Ways Seniors Could Lose Social Security Benefits Without Realizing It

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Retirement Tagged With: 2026 economy, Cost of living, Inflation, Personal Finance, Retirement, retirement budget, senior living

9 Everyday Expenses That Could Consume the Average Senior’s Projected $81 COLA Increase

May 21, 2026 by Brandon Marcus Leave a Comment

9 Everyday Expenses That Could Consume the Average Senior’s Projected $81 COLA Increase
A tight grocery budget can hurt seniors living check to check – Shutterstock

That projected $81 monthly COLA increase might sound like a helpful boost for Social Security recipients, but everyday costs can swallow it fast. Prices keep shifting across essential categories, and many seniors already juggle tight budgets. Small expenses add up quickly when they hit month after month without warning.

The reality is that even modest increases in benefits often struggle to keep pace with real-life spending pressures. Here are nine common expenses that could quietly erase that COLA gain before the month even settles in.

1. Grocery Bills That Refuse to Cool Down

Grocery stores continue to reflect stubbornly high food prices across many basic categories. Seniors often prioritize fresh produce, dairy, and protein, which have seen some of the steepest increases. Even a slight weekly uptick of $10 to $15 can consume a large chunk of that $81 boost. Store loyalty programs help, but they rarely offset inflation entirely. Many shoppers now notice fewer items in the cart for the same budget.

Food costs also fluctuate based on seasonality and supply chain pressures. Staples like eggs, meat, and coffee frequently swing in price without warning. Seniors on fixed incomes feel those changes immediately at checkout. Over a month, those increases often exceed the COLA gain entirely.

2. Prescription Drug Copays and Pharmacy Costs

Prescription medications often come with rising copays, even for insured seniors. A single medication adjustment can add $20 or more per month in out-of-pocket costs. Pharmacies also adjust pricing structures based on insurance coverage tiers. Those small differences create a noticeable dent in limited budgets.

Some seniors require multiple prescriptions, which compounds the issue quickly. Even mail-order discounts fail to fully shield against rising costs. A few medication changes can easily consume the entire COLA increase. Health needs rarely pause for financial planning.

3. Utility Bills That Keep Creeping Up

Electricity and natural gas prices fluctuate based on demand, weather, and regional supply conditions. Seniors often keep heating or cooling systems running longer due to health sensitivity. That habit drives monthly utility bills higher than expected. Even a $10 to $20 increase in energy costs wipes out a significant portion of COLA gains.

Water and sewer fees also trend upward in many municipalities. Utility companies regularly adjust base rates regardless of usage. Seniors on fixed incomes often struggle to reduce consumption further. Basic comfort now competes directly with budget limits.

4. Transportation and Fuel Expenses

Gas prices continue to shift, creating unpredictable transportation costs for seniors who still drive. Even occasional errands can add up quickly when fuel prices spike. A few extra trips per month can easily consume $30 or more. Vehicle maintenance costs also rise alongside aging cars.

Public transportation fares have increased in several regions as well. Seniors who rely on buses or rideshares feel those changes immediately. Mobility remains essential for healthcare visits and daily errands. Transportation costs rarely stay stable long enough to budget comfortably.

5. Home Maintenance and Minor Repairs

Small home repairs often arrive without warning and carry surprisingly high price tags. A leaking faucet, broken appliance, or furnace tune-up can cost $50 to $150 or more. Even minor fixes can wipe out the entire COLA increase in one visit. Homeownership continues to demand ongoing financial attention.

Older homes typically require more frequent maintenance. Aging systems tend to fail at inconvenient times. Seniors often prioritize repairs for safety reasons, regardless of cost. These unexpected expenses disrupt even the most careful budgets.

6. Insurance Premium Adjustments

Home, auto, and supplemental health insurance premiums continue to rise across many regions. Even small monthly increases reduce the value of any COLA adjustment. A $15 hike in a single policy already cuts deeply into the $81 boost. Many seniors carry multiple policies that increase simultaneously.

Insurers often adjust rates based on inflation, repair costs, and risk factors. Seniors rarely have control over those pricing decisions. Switching providers may not always reduce expenses either. Insurance remains a necessary but rising cost category.

7. Internet and Phone Service Fees

Telecom companies frequently adjust monthly service rates and equipment fees. Seniors rely heavily on phone and internet access for healthcare, communication, and banking. Even modest price hikes of $5 to $10 per service quickly stack up. Bundled packages often hide incremental increases.

Contract changes and promotional expirations also affect bills. Many seniors discover unexpected charges after introductory rates expire. Digital access remains essential for modern daily life. Connectivity costs continue to climb quietly in the background.

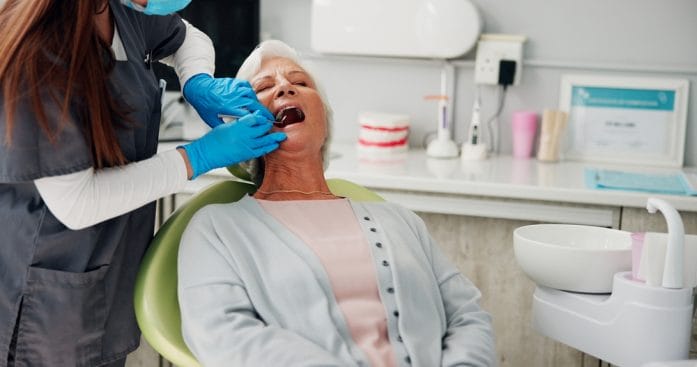
8. Dental and Vision Care Costs

Routine dental cleanings and vision checkups often come with out-of-pocket expenses. Medicare coverage limitations leave many seniors paying directly for these services. A single appointment can consume half or more of the COLA increase. Additional procedures drive costs even higher.

Eyeglasses, contact lenses, and dental work rarely come cheap. Providers also adjust pricing based on materials and technology. Seniors often delay care due to cost concerns. That delay can lead to larger expenses later.

9 Everyday Expenses That Could Consume the Average Senior’s Projected $81 COLA Increase
Regular dental visits can get pricey for seniors living on Social Security – Shutterstock

9. Everyday Convenience Fees and Small Subscriptions

Streaming services, delivery apps, and digital subscriptions continue to multiply in many households. Even $5 to $15 monthly fees add up quickly when stacked together. Seniors often subscribe for entertainment, convenience, or essential services. These recurring charges quietly absorb extra income.

Banking fees and service charges also contribute to monthly expenses. Small automatic payments often go unnoticed until budgets tighten. Canceling subscriptions requires regular review and attention. These micro-costs collectively erase the impact of modest COLA increases.

Where That $81 Really Goes

That projected COLA increase may feel helpful on paper, but daily expenses quickly reshape its impact. Rising costs across essentials like food, healthcare, and utilities leave little breathing room. Seniors often discover that small increases vanish within routine spending cycles. Budget awareness becomes more important than ever in managing fixed income stability. Careful tracking of recurring costs can help protect financial balance even when inflation refuses to slow down.

What everyday expense do you think eats up the biggest share of a fixed income budget today?

You May Also Like…

Over 50? These 6 “Normal” Expenses Could Be Costing You Thousands Every Year

10 Financial Mistakes: What to Avoid After Receiving a Social Security Overpayment Notice

The Retirement Budget Trap: Why Expenses Spike Between Ages 62 and 70

8 Monthly Expenses That Are Harder to Control Than You Think

Social Security Checks Are Getting Smaller for Some Retirees—And It’s Not a Benefit Cut

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: social security Tagged With: Budgeting Tips, COLA increase, Cost of living, healthcare costs, Inflation, retirement budget, senior finances, Social Security

The Retirement Budget Trap: Why Expenses Spike Between Ages 62 and 70

January 26, 2026 by Brandon Marcus Leave a Comment

The Retirement Budget Trap: Why Expenses Spike Between Ages 62 and 70
Image source: shutterstock.com

Retirement is supposed to be the victory lap. The alarm clock is silenced, the calendar opens up, and the long-awaited freedom finally arrives. Then something strange happens: the budget starts puffing up its chest and asking for more money. Not a little more—often a lot more. Between ages 62 and 70, many retirees are caught off guard by a surge in expenses that feels completely backward from everything they were promised.

This is the retirement budget trap, and it has nothing to do with bad math or poor discipline. It’s about timing, behavior, and a life stage that is far more active—and expensive—than most people expect.

The Early Retirement Lifestyle Surge

The early retirement years are not quiet years. They are loud, curious, and packed with plans that were postponed for decades. Travel tends to explode during this window, especially while health and energy are still high. Flights, longer stays, cruises, national park road trips, and visits to friends all stack up quickly. Even retirees who swear they will “travel cheaply” often find that convenience starts winning arguments over frugality.

Daily spending also creeps higher because retirees are home more. More meals at home mean higher grocery bills, and more meals out become part of the new social rhythm. Hobbies that once lived on weekends now get full-time attention, and hobbies almost always come with price tags. Add in entertainment, events, classes, and spontaneous outings, and the lifestyle line item begins to swell.

Healthcare Costs Before And After Medicare

Healthcare is one of the biggest reasons expenses spike between 62 and 70, and the timing could not be trickier. Before age 65, retirees must bridge the insurance gap on their own. Private insurance, COBRA coverage, or marketplace plans can be shockingly expensive, especially without employer subsidies. Premiums rise, deductibles are high, and out-of-pocket costs can feel relentless.

Turning 65 brings Medicare, but it doesn’t bring free healthcare. Medicare premiums, supplemental plans, prescription coverage, dental, vision, and hearing expenses all add up. Higher-income retirees may also face income-related premium surcharges, which arrive quietly and linger for years.

Helping Adult Children And Aging Parents

The sandwich generation doesn’t magically disappear at retirement—it often intensifies. Many retirees in their 60s find themselves supporting adult children who are dealing with housing costs, student loans, or career instability. Financial help may start as a one-time gesture and turn into a recurring line item. It’s given generously and rarely tracked carefully.

At the same time, aging parents may need assistance. Travel for caregiving, home modifications, medical support, or professional care services can quickly strain a retirement budget. These expenses are emotionally driven and deeply personal, which makes them harder to limit.

Big Projects, Big Moves, And Hidden Costs

The early retirement years are prime time for major life adjustments. Downsizing sounds simple, but moving is expensive. Realtor fees, repairs, staging, moving services, and temporary housing can eat into savings faster than expected. Renovations are another common culprit, whether it’s finally remodeling the kitchen or making a home more age-friendly.

New cars, second homes, or recreational vehicles often enter the picture during this phase. These purchases feel justified as “now or never” decisions, and they often are. What gets overlooked are the ongoing costs: insurance, maintenance, taxes, storage, and upgrades.

The Tax And Income Timing Surprise

Between 62 and 70, income sources are often in flux, and taxes become less predictable. Some retirees claim Social Security early, others delay, and many combine part-time work with withdrawals from retirement accounts. These overlapping income streams can push retirees into higher tax brackets than expected. Taxes on Social Security benefits catch many people off guard, especially when combined with investment income.

Required minimum distributions don’t begin until later, but strategic withdrawals often happen earlier, sometimes triggering larger tax bills. Medicare premium surcharges are also based on income from prior years, creating a delayed financial echo. The result is a period where income decisions made with good intentions quietly inflate expenses through taxes and healthcare premiums.

The Retirement Budget Trap: Why Expenses Spike Between Ages 62 and 70
Image source: shutterstock.com

Why The Spike Often Fades After 70

The expense surge between 62 and 70 doesn’t usually last forever. Travel often slows naturally, major projects taper off, and lifestyle spending becomes more predictable. Healthcare costs may stabilize, especially once insurance choices are set. Social circles shrink slightly, routines settle in, and spending becomes less impulsive.

This is why the trap is so dangerous. Retirees may assume these higher expenses are permanent and panic unnecessarily, or they may underestimate them entirely and strain their savings early. Understanding that this phase is often temporary helps retirees plan with realism instead of fear. The key is recognizing that retirement has seasons, and the early years are the most expensive ones.

Seeing The Trap Before It Springs

The retirement budget trap isn’t caused by recklessness or poor planning—it’s driven by a vibrant, transitional stage of life that deserves honesty and foresight. Expenses rise because life is full, generous, and active during these years. Recognizing this pattern helps future retirees prepare without dampening the joy that makes retirement worth waiting for.

If you’ve lived through this phase or are preparing for it now, your experiences can help others navigate it with clearer expectations and fewer surprises. Drop your thoughts or personal stories in the comments below and keep the conversation going.

You May Also Like…

8 Budget Areas That Expand After Retirement

The Sunshine State Squeeze: Why Florida Retirees are Seeing Smaller Social Security Checks This Week

The “Retirement Town” Myth: Why These 5 Dream Locations Are Currently Seeing a Mass Exodus

10 Costs That Make Retirement Budgets Feel Unstable

Savings Leap: 9 Mid-Life Moves That Boost Long-Term Retirement Odds

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Retirement Tagged With: adult children, early retirement, expenses, Family, family issues, healthcare, healthcare costs, Income, Life, Lifestyle, Lifestyle creep, Medicare, retire, retiree, retirees, Retirement, retirement account, retirement budget, retirement income, retirement savings, senior citizens, seniors, taxes

10 Costs That Make Retirement Budgets Feel Unstable

January 12, 2026 by Brandon Marcus Leave a Comment

Here Are 10 Costs That Make Retirement Budgets Feel Unstable
Image Source: Shutterstock.com

Retirement is supposed to feel like a victory lap, not a financial obstacle course. You clock out for the last time, imagine slow mornings and flexible days, and expect your money to finally relax along with you. Then reality taps you on the shoulder with a stack of bills you didn’t see coming.

Some costs arrive loudly, others creep in quietly, but all of them have the power to make a perfectly reasonable retirement budget feel wobbly. Understanding these expenses doesn’t ruin the dream—it actually gives you control over it.

1. Healthcare And Medical Expenses

Healthcare is often the heavyweight champion of retirement costs. Even with Medicare, premiums, deductibles, copays, and uncovered services can pile up faster than expected. Prescription drugs alone can fluctuate wildly from year to year, especially if your health changes. Dental, vision, and hearing care frequently fall outside standard coverage, yet they become more important with age.

A single unexpected diagnosis can reroute thousands of dollars without warning. The uncertainty, not just the size of the bills, is what makes retirees feel uneasy.

2. Housing Repairs And Maintenance

Homes age just like people do, and they tend to demand more attention over time. Roofs wear out, appliances fail, and plumbing issues love to announce themselves at the worst possible moment. Even paid-off homes aren’t “free” when you factor in maintenance, property taxes, and insurance.

Many retirees underestimate how often small fixes turn into big projects. When several repairs hit in the same year, budgets can feel suddenly fragile. Housing costs don’t politely stay put once you retire.

3. Rising Utility Costs

Utilities rarely get the spotlight, but they quietly chip away at monthly cash flow. Energy prices fluctuate, and extreme weather can push heating or cooling costs into uncomfortable territory. Retirees often spend more time at home, which naturally increases electricity, water, and internet usage. Small monthly increases don’t seem scary at first. Over a year, though, those increases can reshape an entire budget. Utilities are predictable enough to forget about, yet unpredictable enough to cause stress.

4. Long-Term Care Needs

Long-term care is one of the most emotionally charged expenses in retirement planning. Assisted living, in-home care, or nursing facilities can cost more per month than many people earned while working. These services often aren’t fully covered by Medicare, leaving families scrambling. The hardest part is timing, since no one knows if or when care will be needed. Planning too little feels risky, but planning too much feels expensive. This uncertainty alone can make even confident retirees uneasy.

Here Are 10 Costs That Make Retirement Budgets Feel Unstable
Image Source: Shutterstock.com

5. Taxes That Don’t Disappear

Retirement doesn’t mean waving goodbye to taxes forever. Withdrawals from traditional retirement accounts are often taxable, sometimes pushing retirees into higher brackets than expected. Property taxes can rise, even on homes that haven’t changed. Social Security benefits may also be taxed depending on total income. Many people assume taxes will shrink dramatically after work ends. When they don’t, it can feel like a budgeting ambush.

6. Inflation’s Slow And Steady Pressure

Inflation doesn’t shout, but it never stops talking. Over time, groceries, insurance, transportation, and everyday services gradually cost more. A budget that felt generous at 65 can feel tight by 75. Fixed incomes struggle to keep pace with rising prices, especially during inflationary spikes. Even modest annual increases add up over a decade or two. Inflation turns time itself into a financial expense.

7. Helping Family Members

Many retirees happily help adult children, grandchildren, or aging parents. Unfortunately, generosity doesn’t always fit neatly into a budget. Covering emergencies, contributing to education, or offering housing support can become ongoing commitments. These expenses are often emotional decisions, not financial ones. They tend to appear suddenly and resist easy limits. Over time, family assistance can quietly destabilize retirement plans.

8. Transportation And Vehicle Costs

Cars don’t retire when you do. Maintenance, insurance, fuel, and eventual replacement still apply, even if you drive less. Older vehicles may require more frequent repairs, which can be unpredictable. Public transportation or ride services can add their own recurring costs. Travel plans, road trips, or visits to family also increase transportation spending. Mobility is freedom, but that freedom has a price tag.

9. Lifestyle And Leisure Spending

Retirement finally opens the door to hobbies, travel, and experiences long postponed. Classes, clubs, trips, and dining out can quickly become regular expenses. Many retirees underestimate how active they’ll want to be. Leisure spending often grows instead of shrinking. While these costs bring joy, they still test financial boundaries. Fun is wonderful, but it isn’t free.

10. Insurance Premium Increases

Insurance rarely stays the same price year after year. Health, home, auto, and supplemental policies often increase with age or market shifts. Even small premium hikes across multiple policies can sting. Retirees may add coverage for peace of mind, further raising costs. Dropping coverage feels risky, yet keeping it strains the budget. Insurance becomes a balancing act between protection and affordability.

Steady Ground Starts With Awareness

Retirement budgets don’t unravel because of one dramatic mistake. They wobble because of many moving parts working together over time. Knowing where instability comes from makes it easier to prepare, adjust, and breathe a little easier. Awareness turns surprise costs into manageable challenges.

If retirement has thrown you a financial curveball, or if you’ve found smart ways to stay steady, we’d love to hear your thoughts or stories in the comments below.

You May Also Like…

Why Does Retirement Feel More Expensive Than People Planned For

Savings Repair: 4 Moves to Catch Up if You’re Within 10 Years of Retirement

Income Stability: 6 Retirement Income Moves That Aren’t as Safe as They Seem

Risk Scenario: 8 What-Ifs Every Pre-Retiree Should Consider

Expense Overflow: 4 Retirement Bills That Catch People Off Guard


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Retirement Tagged With: Budget, budgeting, healthcare, healthcare costs, housing, housing maintenance, housing repairs, liefstyle, Life, Lifestyle creep, medical expenses, retire, retiree, retirees, Retirement, Retirement activities, retirement budget, retirement budgeting, retirement planning, utility costs

Savings Fallout: 4 Hidden Expenses That Quietly Drain Retirement Budgets

December 17, 2025 by Brandon Marcus Leave a Comment

Here Are The Hidden Expenses That Quietly Drain Retirement Budgets
Image Source: Shutterstock.com

Retirement is often sold as the grand finale of working life: more freedom, fewer alarms, and finally the time to enjoy what you’ve built. The problem is that while most people plan for the big-ticket items, the quiet costs slip in like uninvited guests and start eating away at savings before anyone notices. These expenses don’t usually show up in glossy retirement calculators or celebratory send-off speeches.

They creep in slowly, feel harmless at first, and then snowball into something far more serious. If retirement is a marathon, these hidden drains are the tiny pebbles in your shoes that eventually make every step hurt.

1. The Silent Rise Of Healthcare “Extras”

Medicare feels like a financial safety net, but it rarely covers everything retirees actually use. Premiums, supplemental plans, deductibles, copays, dental work, vision care, and hearing aids quietly stack up year after year. Prescription costs alone can swing wildly depending on drug tiers and annual plan changes, catching retirees off guard. Many people underestimate how much out-of-pocket spending increases with age, especially for chronic conditions. Over time, these “extras” can rival or even exceed what some retirees once spent on housing.

2. Lifestyle Inflation Disguised As Freedom

Retirement often brings more time, and more time usually leads to more spending. Lunches out replace packed meals, casual trips turn into frequent getaways, and hobbies evolve from inexpensive interests into costly passions. What feels like well-earned enjoyment can slowly reset a retiree’s baseline lifestyle cost. Because these changes happen gradually, budgets don’t always get adjusted to match the new reality. The result is a spending pattern that looks reasonable month to month but quietly erodes long-term savings.

3. Homeownership Costs That Never Retire

Many retirees enter retirement with their mortgage paid off, expecting housing expenses to shrink dramatically. What they don’t expect is how maintenance, repairs, property taxes, insurance, and utilities can rise with both time and inflation. Aging homes often demand bigger fixes like roofs, HVAC systems, and plumbing upgrades at the worst possible moments. Downsizing isn’t always the immediate solution people think it is, since moving itself brings fees, taxes, and new ongoing costs. The home that once felt like a financial victory can become a persistent drain on cash flow.

Here Are The Hidden Expenses That Quietly Drain Retirement Budgets
Image Source: Shutterstock.com

4. Family Support And “Just This Once” Spending

Retirees are often the financial safety net for adult children, grandchildren, or other relatives. Helping with tuition, covering emergencies, or offering “temporary” assistance can quickly turn into ongoing obligations. These expenses are emotionally driven, which makes them harder to track and even harder to say no to. Small, repeated gestures add up faster than one-time gifts, especially when they aren’t planned for. Over time, generosity without boundaries can quietly undermine even the most carefully built retirement plan.

Spotting The Leaks Before They Sink The Ship

Retirement budgeting isn’t just about predicting the big expenses; it’s about recognizing the subtle ones that slip under the radar. Healthcare add-ons, lifestyle creep, home costs, and family support rarely feel dangerous in isolation, but together they can reshape a retirement faster than expected. Awareness is the first step toward control, because you can’t manage what you don’t notice. Thoughtful planning, regular budget check-ins, and honest conversations can make a real difference.

If any of these hidden expenses have surprised you or reshaped your plans, feel free to add your experiences or perspectives in the comments section below.

You May Also Like…

Is Your Retirement Timeline Still Safe If The Market Drops Again Before New Year’s Eve?

Retirement Redflag: 6 Withdrawal Moves That Could Drain Your Nest Egg Fast

Calculate Your True Retirement Number Using Our Exclusive Online Tool

8 Apps That Are Quietly Stealing Your Retirement Budget

Savings Game: 5 Ways to Boost Your Emergency Fund Before December Ends


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Retirement Tagged With: expenses, healthcare costs, homeowners, homeownership, Inflation, Life, Lifestyle, retire, retiree, retirees, Retirement, retirement accounts, retirement budget, retirement budgets, retirement spending, senior citizens, seniors, Smart Spending, spending

Prepping For Retirement: Do These 10 Things To Have The Happiest Retirement

May 14, 2025 by Travis Campbell Leave a Comment

retirement couple on the beach
Image Source: pexels.com

Retirement is one of life’s biggest milestones—a time to finally enjoy the fruits of your labor, travel, pursue hobbies, and spend more time with loved ones. But the happiest retirement doesn’t just happen by chance. It takes thoughtful planning, a bit of soul-searching, and some practical steps to ensure your golden years are truly golden. Whether you’re a decade away or just around the corner from retirement, prepping for retirement now can make all the difference. Let’s dive into the ten essential things you should do to set yourself up for the happiest retirement possible.

1. Visualize Your Ideal Retirement

Before you crunch any numbers, take time to imagine what your happiest retirement looks like. Do you see yourself traveling the world, volunteering, or spending quiet days gardening? Getting clear on your vision helps you set meaningful goals and prioritize what matters most. This step isn’t just about dreaming—it’s about creating a roadmap for your future. Retirees who plan ahead are more likely to feel satisfied and fulfilled.

2. Assess Your Financial Health

Prepping for retirement means knowing exactly where you stand financially. Review your savings, investments, debts, and expected income sources like Social Security or pensions. Use online calculators or meet with a financial advisor to estimate how much you’ll need. Don’t forget to factor in inflation and unexpected expenses. A clear financial picture gives you confidence and helps you make informed decisions.

3. Maximize Retirement Contributions

If you’re still working, now’s the time to supercharge your retirement savings. Contribute as much as possible to your 401(k), IRA, or other retirement accounts. Take advantage of employer matches—they’re essentially free money! The IRS allows catch-up contributions for those over 50, so don’t leave that benefit on the table. The more you save now, the more freedom you’ll have later.

4. Create a Realistic Retirement Budget

A happy retirement is one where you don’t have to stress about money. Start by tracking your current expenses and projecting what they’ll look like in retirement. Some costs may go down (like commuting), while others (like healthcare) may rise. Build a budget that covers essentials, fun activities, and a cushion for surprises. Sticking to a budget helps you enjoy your retirement without financial anxiety.

5. Plan for Healthcare Costs

Healthcare is often one of the biggest expenses in retirement. Research your options for Medicare, supplemental insurance, and long-term care. According to Fidelity, the average retired couple may need around $315,000 for healthcare expenses in retirement. Planning ahead can help you avoid unpleasant surprises and ensure you get the care you need.

6. Eliminate Debt Before Retiring

Carrying debt into retirement can be a major source of stress. Make a plan to pay off high-interest credit cards, personal loans, and even your mortgage if possible. The less you owe, the more flexibility you’ll have with your retirement income. Being debt-free means you can focus on enjoying life rather than worrying about monthly payments.

7. Diversify Your Income Streams

Relying on a single source of income can be risky. Consider ways to diversify, such as part-time work, rental income, or dividends from investments. Even a small side hustle can provide extra security and keep you engaged. Multiple income streams can help you weather market downturns and unexpected expenses, making prepping for retirement even more effective.

8. Stay Socially and Mentally Active

Retirement isn’t just about money—it’s about well-being. Studies show that retirees who stay socially connected and mentally engaged are happier and healthier. Join clubs, volunteer, take classes, or pick up new hobbies. Staying active helps prevent loneliness and keeps your mind sharp, both of which are key to a happy retirement.

9. Update Your Estate Plan

Prepping for retirement also means making sure your legal affairs are in order. Review your will, power of attorney, and healthcare directives. Update beneficiaries on your accounts and consider meeting with an estate planning attorney. Having these documents in place gives you peace of mind and protects your loved ones.

10. Practice Living on Your Retirement Budget

Before you officially retire, try living on your projected retirement income for a few months. This “test run” can reveal any gaps or challenges and help you adjust your plans. It’s a practical way to ensure your budget is realistic and that you’re truly ready for the transition. Plus, it can ease the anxiety of the unknown and make prepping for retirement feel more tangible.

Your Happiest Retirement Starts With Preparation

The happiest retirement isn’t just about having enough money—it’s about feeling secure, fulfilled, and free to enjoy life on your terms. By prepping for retirement with these ten steps, you’re setting yourself up for a future filled with possibilities. Remember, it’s never too early or too late to start planning. The more intentional you are now, the more you’ll thank yourself later.

What steps are you taking to prep for retirement? Share your thoughts and experiences in the comments below!

Read More

What retirees are really spending their money on in 2025

10 reasons it’s too late for boomers to change their retirement strategies

Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Retirement Tagged With: Estate planning, financial independence, happy retirement, Personal Finance, prepping for retirement, retirement budget, retirement planning, Retirement Tips

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • 10 Tactics for Building an Emergency Fund from Scratch by Vanessa Bermudez
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald

Copyright © 2026 · News Pro Theme on Genesis Framework