• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Personal Finance

9 Ways People Can Immediately Tell That You’re Broke

March 13, 2025 by Latrice Perez Leave a Comment

Man with empty pockets
Image Source: 123rf.com

Struggling financially is nothing to be ashamed of, but whether we like it or not, people can often spot when someone is broke. It’s not always about the car you drive or the clothes you wear—there are small behaviors, habits, and subtle social cues that reveal financial struggles almost instantly. Even if you try to mask it, people pick up on the signs that money is tight. If you recognize yourself in any of these, it may be time to rethink your financial habits and work toward a more stable future.

1. You Always Have an Excuse to Avoid Going Out

When money is tight, social events start feeling like financial landmines. You might find yourself constantly making excuses to avoid going out—whether it’s dinner, drinks, or even casual hangouts that might involve spending. Instead of saying, “I can’t afford it,” you might claim you’re too busy, too tired, or just not in the mood.

People catch on when you consistently dodge outings, especially when you never suggest budget-friendly alternatives. If you’re always the one bailing on plans, people assume money is the issue.

2. Your Card Gets Declined in Public

Few things scream “I’m broke” louder than a declined card at a checkout line or restaurant. Whether it’s due to insufficient funds, a maxed-out credit limit, or an overdraft block, it’s an awkward and telling moment. Even if you try to play it off by pretending it’s a mistake, the embarrassment sticks.

People notice when this happens repeatedly, especially if you scramble to use another card or ask a friend to cover for you. Financial mishaps happen to everyone occasionally, but frequent declines suggest deeper money problems.

3. You Constantly Complain About Money

Talking about finances is normal, but if every conversation revolves around how expensive things are, how unfair bills feel, or how you’re always broke, people take notice. Complaining about money all the time signals to others that you are struggling, even if you never outright say it.

Friends and coworkers may sympathize at first, but over time, constant money talk makes it obvious that your financial situation isn’t great. People who are financially stable don’t usually dwell on these things in every conversation.

4. Your Clothes and Shoes Are Worn Out

You don’t need to wear designer brands to look put together, but if your clothes are consistently faded, stretched out, or falling apart, people notice. Worn-out shoes, frayed collars, and outdated outfits can make it clear that replacing them isn’t in your budget.

Dressing well doesn’t require a lot of money, but when you’re broke, replacing even basic wardrobe items can feel like an unnecessary expense. If your appearance looks consistently neglected, people assume finances are the reason.

5. You Avoid Talking About Travel or Big Purchases

When people talk about vacations, new gadgets, or recent shopping trips, those who are broke often go silent or quickly change the subject. If you never mention upcoming trips, home upgrades, or even small splurges, people can tell that extra spending isn’t an option for you.

Even if no one expects you to take extravagant vacations, avoiding conversations about any kind of spending can make it clear that money is tight. People who are financially comfortable usually have at least one recent purchase or experience to talk about.

6. You Frequently Borrow Small Amounts of Money

Asking to borrow money from friends, coworkers, or even family—especially small amounts—raises red flags. Whether it’s asking for five bucks for coffee, needing a ride because you can’t afford gas, or delaying your share of a group payment, people take note.

Frequent borrowing, even in small amounts, signals that you are living paycheck to paycheck. Over time, people become reluctant to lend or start to avoid situations where they might have to cover for you.

7. You Struggle with Unexpected Expenses

When an emergency expense pops up—like a car repair, medical bill, or a last-minute fee—and you panic or scramble for cash, it’s a clear sign that you have no financial cushion. People who are financially stable usually have some savings or access to emergency funds.

If you always have to borrow money, ask for extensions, or desperately search for a solution every time something unexpected happens, it becomes obvious that money is a major issue. Others might not say anything, but they take mental notes when they see you in constant financial distress.

8. You Never Offer to Pay or Split the Bill
People Dining Out
Image Source: 123rf.com

When dining out, grabbing coffee, or even sharing rides, people notice if you never offer to pay your share. If someone always has to cover for you, it becomes clear that you can’t afford the extra expense. Even if you try to subtly let others take the lead, repeated avoidance makes it obvious.

Being broke doesn’t mean you have to pay for everyone, but not contributing at all—especially in group settings—stands out. People eventually assume that you’re financially struggling or just taking advantage of others’ generosity.

9. You Seem Stressed Every Time Money is Mentioned

People can sense financial stress even when it’s not explicitly stated. If you get tense, frustrated, or overly defensive whenever money is brought up, it’s a sign that things aren’t going well financially.

This can show up in conversations about salaries, budgeting, or even casual talks about spending habits. If you always react negatively or shut down discussions about money, it’s a clear indicator that finances are a major source of stress in your life.

The Signs Are Hard to Hide, But Change is Possible

Most people don’t set out to make it obvious that they’re broke, but financial struggles have a way of showing up in daily habits and interactions. The good news is that recognizing these signs can be the first step toward improving your situation. Cutting unnecessary expenses, creating a budget, and looking for ways to increase income can make a huge difference.

Have you ever noticed these signs in yourself or others? What steps have you taken to improve your financial situation? Share your thoughts in the comments below.

Read More:

12 Private Clubs Only the Wealthy Can Afford

12 Ways Your “Poverty Mentality” Is Hurting Your Financial Future

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.
Filed Under: Personal Finance Tagged With: broke signs, budgeting, debt problems, financial struggles, Financial Wellness, low income life, money habits, money management, Personal Finance, saving money

6 Things Your Parents Wish They’d Taught You About Money So You’d Stay Out of Their Pockets

March 13, 2025 by Latrice Perez Leave a Comment

Talking to kids about money
Image Source: 123rf.com

Most parents want their kids to be financially independent, but not all of them succeed in teaching the skills needed to make that happen. Many young adults find themselves relying on their parents for money well into their 20s, 30s, or even beyond. While some financial help is understandable in emergencies, constantly needing assistance can strain relationships and create long-term dependence. The reality is that many parents wish they had instilled better money habits early on so their adult children wouldn’t keep coming back for financial support. Here are six key lessons they wish they had taught you before it was too late.

1. How to Live Below Your Means

One of the biggest financial mistakes people make is spending more than they earn. Many parents regret not teaching their children how to budget properly and prioritize needs over wants. When young adults develop expensive habits early on—whether it’s dining out regularly, upgrading their phone every year, or financing a car they can’t afford—it often leads to financial struggles later.

Living below your means isn’t about depriving yourself, but about making smart choices. If you spend less than you earn, you create room for savings, investments, and financial stability. Parents who see their adult children struggling to cover basic expenses often wish they had reinforced the importance of disciplined spending habits much earlier.

2. Why Credit Cards Aren’t Free Money

Many young adults get their first credit card with little understanding of how it actually works. They swipe now and worry about the balance later, only to find themselves buried in debt with high-interest rates they can’t afford to pay off. Parents who have had to step in and bail their kids out of credit card debt often wish they had explained the dangers of using credit irresponsibly.

Credit cards can be useful financial tools if managed correctly, but they can also become a major burden if misused. Knowing when and how to use credit is key to avoiding financial dependence on parents or anyone else. Parents who have watched their children rack up debt and struggle with payments often wish they had made this lesson a priority.

3. Unexpected Expenses Require Savings

Unexpected expenses happen to everyone, whether it’s a car repair, medical bill, or job loss. Many parents regret not teaching their children to build an emergency fund early in life. Without savings set aside for emergencies, young adults often turn to their parents when financial trouble hits.

An emergency fund provides a safety net so that when life throws unexpected expenses your way, you don’t have to borrow money or rely on family to bail you out. Parents who see their children constantly in financial distress often wish they had emphasized the importance of setting aside money for the unexpected.

4. Why Keeping Up with Others is a Losing Game

The Word Vacation
Image Source: 123rf.com

One of the fastest ways to go broke is trying to match the lifestyle of friends, coworkers, or influencers on social media. Parents who watch their kids overspend to keep up with trends, vacations, or luxury purchases often wish they had taught them the value of financial independence over appearances.

Comparing yourself to others financially is a trap. The reality is that many people living flashy lifestyles are drowning in debt. Learning to focus on personal financial goals rather than competing with others can prevent unnecessary financial stress. Parents who see their children making purchases they can’t afford often regret not reinforcing this lesson sooner.

5. How to Make Money Work for You

Many parents wish they had taught their children more about investing, saving, and growing wealth instead of just working for a paycheck. A job alone doesn’t create financial security—knowing how to manage and grow money does. Unfortunately, many young adults are never taught about investing, compounding interest, or passive income, leaving them to figure it out on their own later in life.

Understanding how to build wealth early can prevent the cycle of living paycheck to paycheck and needing financial help from family. Parents who have had to support their adult children financially often wish they had instilled the mindset of making money work for them rather than just working for money.

6. That Financial Independence is the Goal

Many parents regret not teaching their children that the ultimate goal is financial independence. Some young adults grow up assuming that if they ever run into financial trouble, their parents will always be there to help. While it’s natural for parents to want to provide support, constantly relying on them well into adulthood can create an unhealthy financial relationship.

True financial independence means being able to support yourself without depending on family for money. Parents who have had to repeatedly step in to cover rent, pay off debts, or fund vacations often wish they had set clearer expectations about financial self-sufficiency. Those who teach their children financial responsibility early are more likely to see them succeed on their own.

It’s Not Too Late to Change Your Habits

If you’ve had to rely on your parents financially more than you’d like, it’s not too late to change your habits. Learning how to live below your means, use credit wisely, and build financial security can help you break the cycle of dependence. While parents want to support their children, they also want to see them succeed on their own. The best way to honor their hard work is by taking control of your financial future.

What financial lessons do you wish you had learned earlier? Share your thoughts in the comments below.

Read More:

Is It Ever a Good Idea To Move Back In With Your Parents To Pay Off Debt?

9 Tough Decisions You’ll Have to Make When Your Parents Can’t Afford to Retire

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.
Filed Under: Personal Finance Tagged With: avoiding debt, Budgeting Tips, building wealth, Credit card debt, emergency fund, financial education, financial independence, money management, Personal Finance, Smart Spending

Check Your Credit Report NOW—5 Signs of Identity Theft

March 11, 2025 by Latrice Perez Leave a Comment

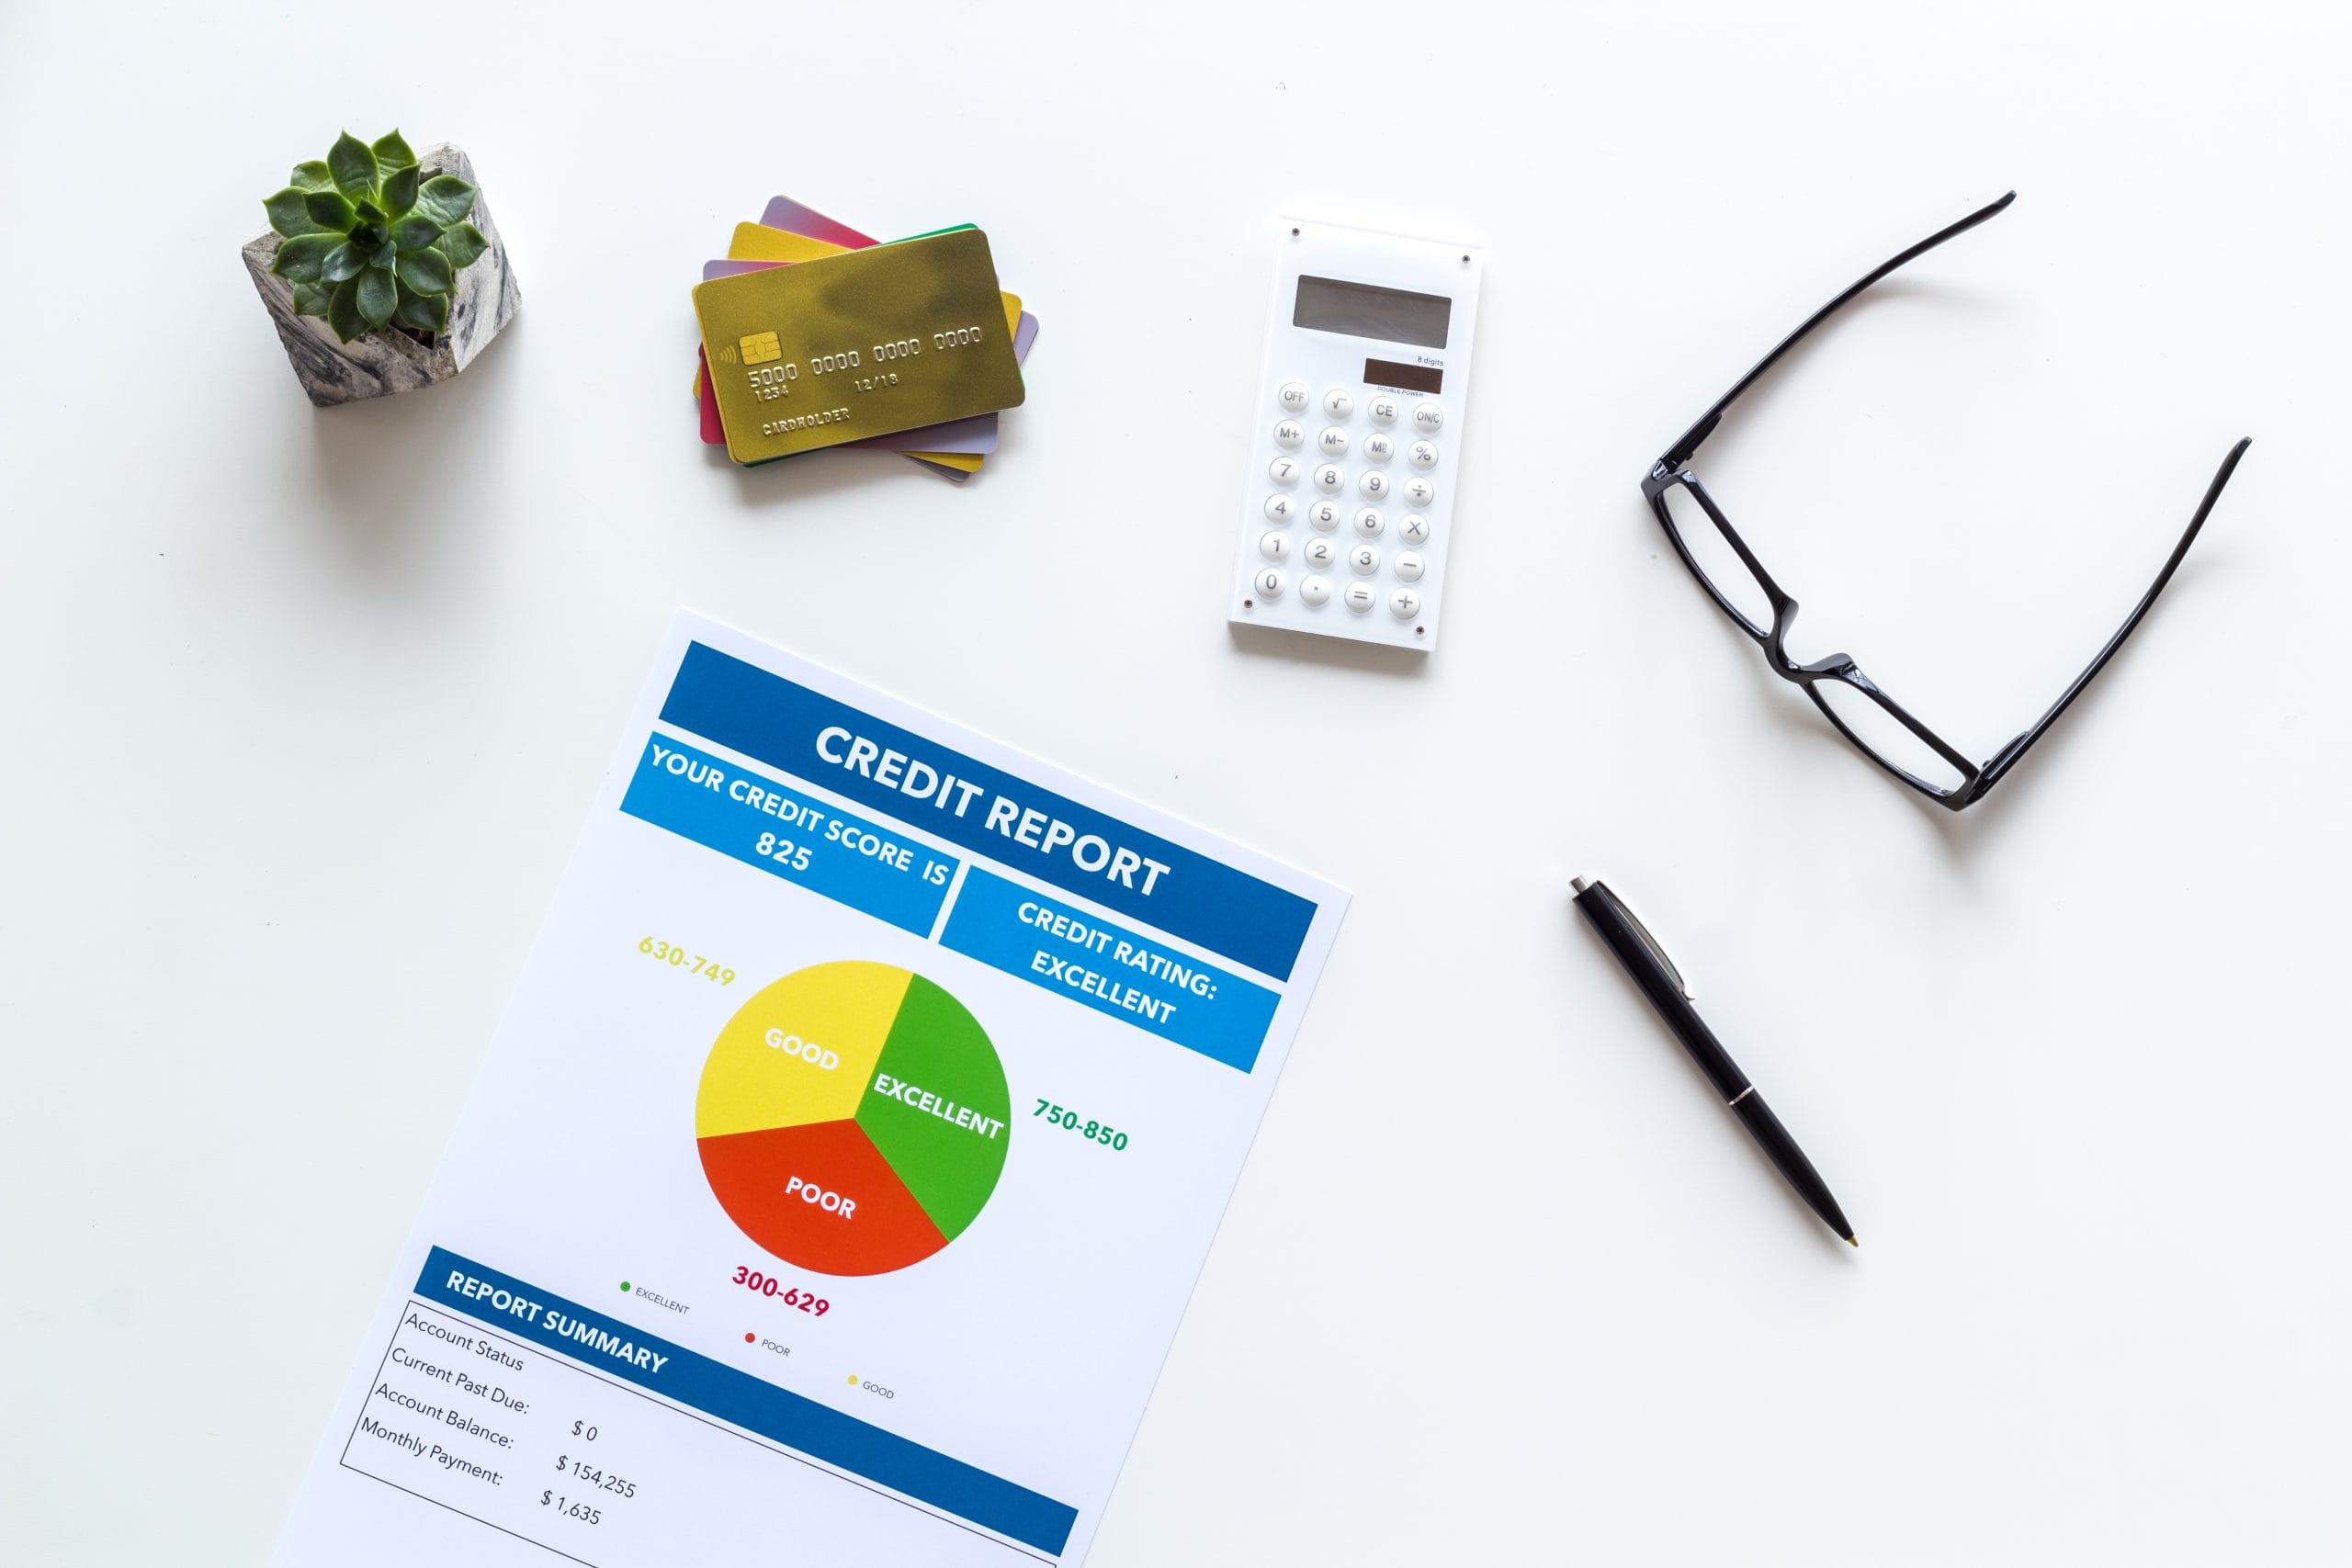
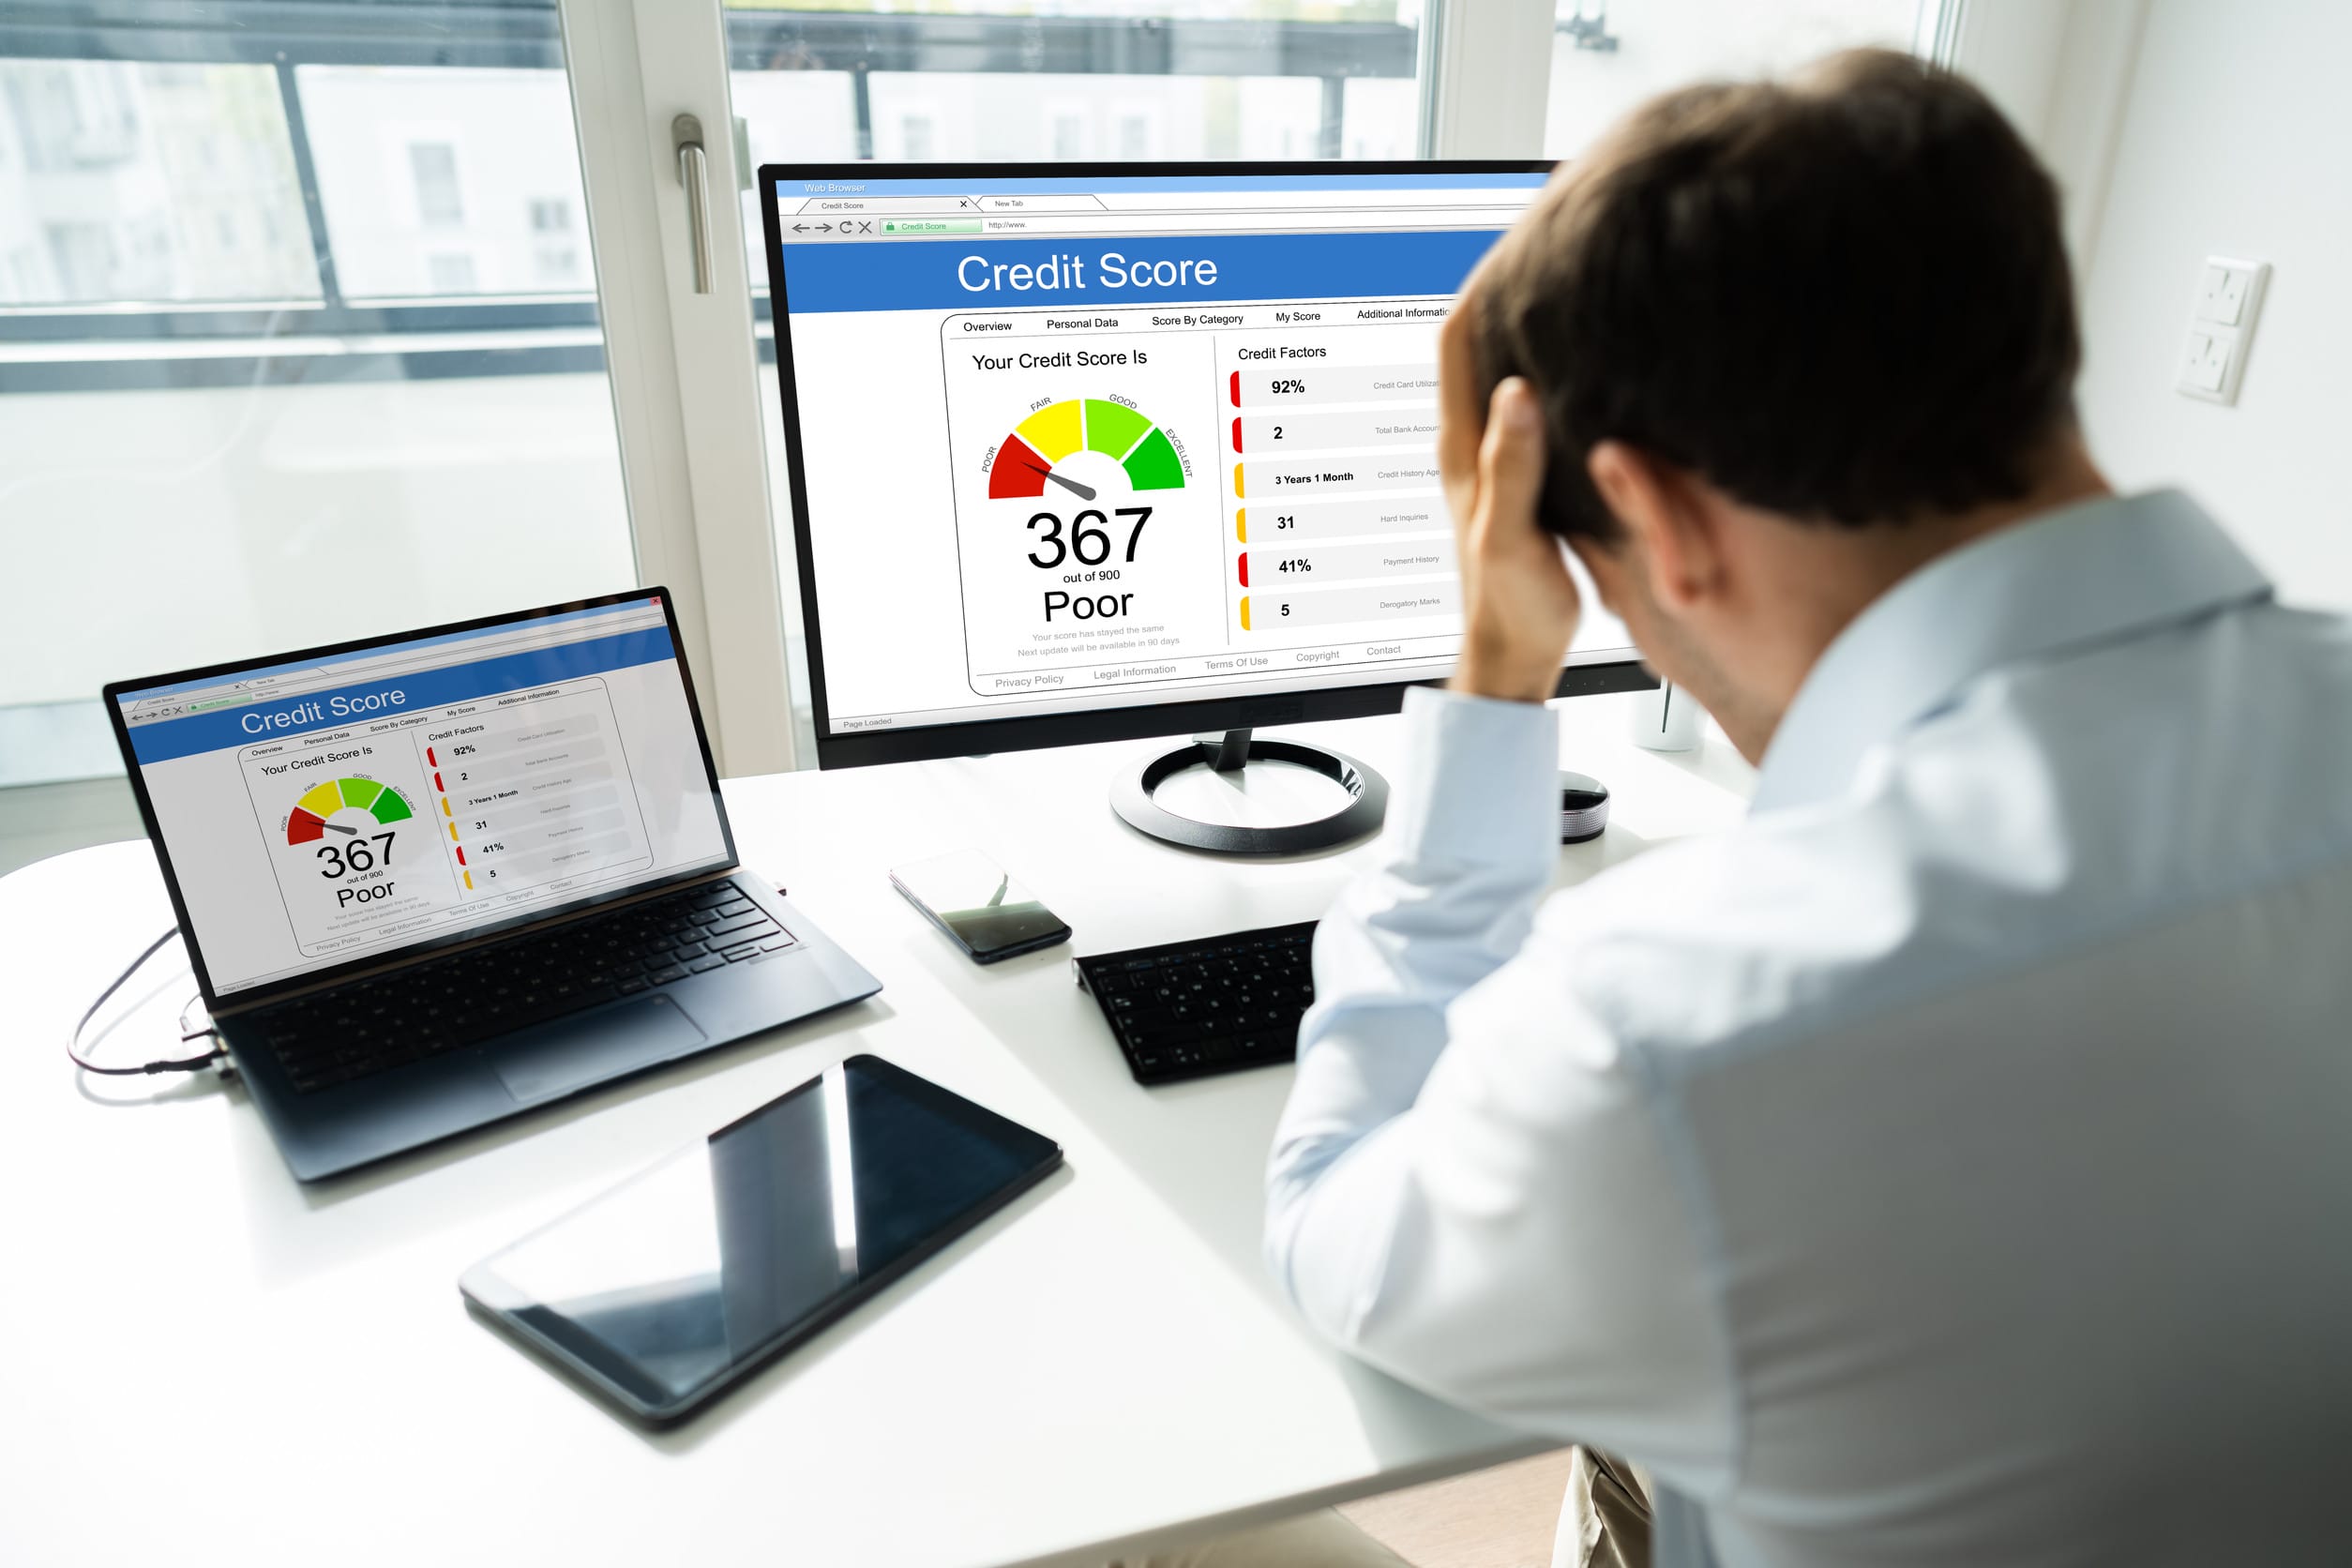
Credit Report
Image Source: 123rf.com

Identity theft isn’t just something that happens to other people—it’s a growing crime that could be targeting you without you realizing it. With personal data being stolen through data breaches, phishing scams, and card skimmers, criminals can open accounts, take out loans, and destroy your credit before you even notice. Your credit report holds the key to detecting identity theft early, but most people don’t check it often enough. If you see any of these five warning signs on your credit report, you need to take action immediately.

1. Accounts You Don’t Recognize

One of the most obvious signs of identity theft is finding credit cards, loans, or accounts you never opened. If your credit report shows a store credit card, personal loan, or a line of credit you never applied for, a scammer may have used your identity to take out money in your name.

Identity thieves use stolen personal information to open fraudulent accounts, and if left unchecked, these accounts can rack up massive debt and ruin your credit score. Even if a fraudulent account has a zero balance, it still means someone has your personal details and could do more damage in the future. If you see an account you don’t recognize, contact the lender immediately and dispute the account with the credit bureaus.

2. Strange Inquiries from Lenders You Didn’t Apply To

Every time you apply for credit, whether it’s a credit card, mortgage, or personal loan, the lender checks your credit. These checks, called hard inquiries, appear on your credit report and can stay there for up to two years. If you see an inquiry from a lender you never applied to, it’s a red flag that someone else is trying to take out credit in your name.

Scammers don’t always succeed in opening fraudulent accounts, but if they attempt to do so, the credit inquiry remains on your report. A single unauthorized inquiry might not seem like a big deal, but it could mean that your personal information has already been sold on the dark web. If you notice unusual inquiries, contact the lender to verify the application and consider freezing your credit to prevent further fraud.

3. A Sudden Drop in Your Credit Score

Poor Credit Score
Image Source: 123rf.com

A sharp drop in your credit score without explanation is a major warning sign of fraud. If your score decreases despite making on-time payments and keeping your balances low, it could be due to a scammer maxing out a stolen credit line or missing payments on an account you didn’t even know existed.

Credit scores drop when:

  • High balances are reported on accounts
  • Late payments occur
  • New accounts are opened
  • Collections are added to your credit report

Even a small dip in your score should prompt you to check your credit report for suspicious activity. If you see any unrecognized accounts, debts, or missed payments, you could be dealing with identity theft.

4. Bills or Collections You Don’t Recognize

Receiving a bill for a service or credit card you never signed up for is a huge red flag. Identity thieves often open accounts and let them go unpaid, resulting in collections being reported on your credit file. You might not even know about the account until you receive a debt collection notice—or worse, get denied for a loan or credit card.

Some scammers even use stolen identities for medical fraud, meaning you could end up with medical bills for treatments you never received. If you see a collections account you don’t recognize, don’t ignore it. Contact the collection agency and dispute the charge with the credit bureaus immediately.

5. Your Personal Information Has Changed on Your Credit Report

If your credit report suddenly shows a different home address, phone number, or employer, it could mean that a scammer has changed your details to cover their tracks. Thieves often update account details to prevent victims from receiving fraud alerts or account statements.

Even small changes, such as a variation in the spelling of your name or an address you don’t recognize, should be taken seriously. If you notice incorrect personal information, contact the credit bureaus to correct it and check for any linked fraudulent activity.

What to Do If You Spot Signs of Identity Theft

If you recognize any of these red flags on your credit report, you need to act quickly to stop the damage. Here’s what to do:

  • Freeze Your Credit: Placing a freeze on your credit report prevents anyone from opening new accounts in your name. You can do this for free with all three major credit bureaus: Experian, Equifax, and TransUnion.
  • Report the Fraud: File an identity theft report with the Federal Trade Commission (FTC) at IdentityTheft.gov. This will help create an official record of the crime.
  • Dispute Fraudulent Accounts: Contact the lender directly to report the fraud and dispute the account with the credit bureaus. They are required to investigate and remove fraudulent accounts.
  • Monitor Your Credit Regularly: Sign up for credit monitoring services or set up free alerts through your bank or credit card provider to track any changes in your credit file.
  • Change Your Passwords and Enable Two-Factor Authentication: If a scammer has gained access to your personal information, secure your accounts by updating passwords and enabling additional security measures.

Checking Your Credit Regularly Can Save You Thousands

Identity theft can cause long-term financial damage, but catching it early makes a huge difference. The best way to protect yourself is to check your credit report regularly. You can access your free credit report from each of the three major credit bureaus once a year at AnnualCreditReport.com. If you space them out, you can check one report every four months for continuous monitoring.

Don’t wait until it’s too late—review your credit report today to make sure no one is using your identity to rack up debt in your name.

Have you ever caught a suspicious charge or account on your credit report? Share your experience in the comments.

Read More:

Would Jesus Use a Credit Card? The Ethics of Debt in a Modern World

Credit Score Killers: 7 Mistakes You’re Probably Guilty Of

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.
Filed Under: Personal Finance Tagged With: credit fraud, credit monitoring, credit scams, cybersecurity, Financial Security, fraud prevention, identity theft, Personal Finance, protect your credit, stolen identity

6 Things That Can Happen If You Die Without a Will (And It’s Not Good)

March 7, 2025 by Latrice Perez Leave a Comment

Last Will and Testament for Estate Planning
Image Source: 123rf.com

When someone dies without a will, they are considered to have died “intestate.” This means the state steps in and decides how their assets are divided based on intestacy laws. These laws typically prioritize spouses, children, and close relatives, but they don’t consider personal wishes, relationships, or promises made during life. This process can create unintended consequences, such as an estranged family member receiving an inheritance while a close friend or partner receives nothing. Without a will, you lose control over who benefits from your hard-earned assets.

Your Partner Could Be Left With Nothing

If you are married, your spouse may not automatically inherit everything, depending on state laws. In some cases, assets are divided between a surviving spouse and children, which can create financial strain. For unmarried couples, the situation is worse—many states do not recognize long-term partnerships without legal documentation. If you wanted your partner to receive financial support or ownership of shared property, a will is the only way to guarantee their rights.

The Court Decides Who Raises Your Children

Raising Children
Image Source: 123rf.com

For parents, one of the most critical aspects of estate planning is naming a guardian for minor children. Without a will, the court will decide who takes care of your children, and the person appointed may not be who you would have chosen. Family members could fight over custody, or worse, your children could end up with a guardian who does not align with your parenting values. Naming a legal guardian in a will ensures that your children are raised by someone you trust.

Your Family Could Face Lengthy Legal Battles

Dying intestate often leads to family disputes, especially if multiple relatives believe they are entitled to a share of your estate. Without clear instructions, conflicts over money and property can escalate, leading to expensive and emotionally draining legal battles. Family relationships may suffer as a result, and the cost of legal proceedings can significantly reduce the amount of money left for your loved ones. A will prevents confusion and minimizes the risk of disputes.

Your Estate Could Be Hit With Unnecessary Taxes and Fees

Without proper estate planning, your heirs may face excessive estate taxes, legal fees, and court costs. These things could have been avoided. A will allows you to plan for tax-efficient distribution of assets and helps ensure that your estate is settled as smoothly as possible. Without it, more of your wealth could go to legal fees and the government instead of your loved ones.

Your Wishes for Special Assets Won’t Be Honored

If you have sentimental or valuable items that you want to go to specific people, a will is the only way. The will ensures those wishes are carried out. Without one, family members may fight over personal belongings.  The state may alsodistribute them in a way that doesn’t reflect your intentions. Items with significant emotional or financial value should be clearly designated in a will to avoid misunderstandings.

Making a Will Protects Your Legacy

A will is a simple but powerful tool that ensures your assets, children, and final wishes are  according to your preferences. Without one, you leave critical decisions up to the courts, and your loved ones may face unnecessary hardship. Drafting a will now can save your family from stress, financial loss, and confusion later.

Do you have a will? Did these article make you reconsider getting one? Let us know your thoughts in the comments below!

Read More:

Do You Know the Estate Planning Essentials to Protect Your Family’s Future?

10 Stupid Things That Nobody Wants You to Leave In Your Will

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.
Filed Under: Estate Planning Tagged With: death planning, Estate planning, family protection, Financial Security, Inheritance, legal advice, legal rights, Personal Finance, probate law, wills

The “$20 Rule” That Could Save You Thousands Every Year

March 7, 2025 by Latrice Perez Leave a Comment

Twenty Dollar Bill
Image Source: 123rf.com

When people think about saving money, they often focus on cutting back on big-ticket expenses like rent, car payments, or vacations. While those certainly play a role, what often goes unnoticed are the small, everyday purchases that add up over time. A coffee here, a quick meal there, an impulse buy at the checkout counter—these minor expenses seem harmless in the moment but can drain your finances faster than you realize. The “$20 Rule” is a simple but effective way to take control of your spending and prevent financial leaks. By following this method consistently, you can save thousands of dollars a year without making drastic lifestyle changes.

What Is the “$20 Rule”?

The “$20 Rule” is a personal finance strategy that helps curb unnecessary spending by implementing a mandatory waiting period before making any purchase under $20. The idea is simple: if something costs $20 or less, you must wait at least 24 hours before buying it. This pause forces you to determine whether the purchase is a necessity or just an impulsive desire. In many cases, people find that after waiting, the urge to buy fades, and they no longer feel the need to make the purchase.

Why $20?

Twenty dollars might not seem like a significant amount, but the reality is that most impulse purchases fall within this price range. Whether it’s a fast-food meal, an extra streaming subscription, or a small gadget you don’t truly need, these purchases add up quickly. If you spend just $20 a day on unnecessary items, that’s $140 a week or over $7,000 a year. Even if you cut just half of those expenses, the savings could be substantial. The $20 limit is an effective psychological benchmark—it’s enough to cover many non-essential purchases, yet small enough to be a frequent financial drain.

How the “$20 Rule” Curbs Impulse Spending

Impulse spending is one of the biggest reasons people struggle to save money. Many purchases happen in the heat of the moment, without much thought about long-term financial consequences. The “$20 Rule” introduces a crucial pause in decision-making, which gives you time to reflect on whether a purchase is truly necessary.

When you see something you want to buy, but it costs under $20, remind yourself that you need to wait 24 hours. If you still want it after a day, you can buy it guilt-free. However, in many cases, the initial excitement of the purchase fades, and you realize that you don’t actually need it. By applying this simple method, you naturally develop better spending habits and become more mindful of where your money goes.

Applying the “$20 Rule” to Everyday Spending

Everyday Spending
Image Source: 123rf.com

This rule is easy to incorporate into daily life, and you can apply it to multiple areas of spending. Here are some common scenarios where it can help save money:

If you often stop for coffee on the way to work, waiting 24 hours before buying that $5 latte can make you rethink whether you really need it. By making coffee at home instead, you can save hundreds of dollars a year. The same applies to fast food. Many people grab quick meals out of convenience, but after waiting a day, you may realize you could cook something at home instead.

Retail shopping is another major area where the “$20 Rule” can be effective. Whether it’s clothes, accessories, or home goods, small purchases at department stores or online retailers add up quickly. If you see an item you like, waiting 24 hours can help you determine whether it’s a need or just an impulse buy.

Subscription services can also be an unnoticed financial drain. Many services cost less than $20 per month, making them easy to overlook. The “$20 Rule” encourages you to pause and evaluate whether you’re actually using a subscription before committing to another monthly charge.

How Much Money Can You Save?

The amount you save with the “$20 Rule” depends on how often you apply it, but the results can be surprising. If you avoid just three unnecessary $20 purchases per week, that’s $60 saved. Over a month, that’s $240, and over a year, you’re looking at nearly $3,000 in savings. If you invest that money or put it toward paying down debt, the long-term financial benefits grow even larger.

Even small changes in spending habits can lead to significant financial improvements. Many people who start using the “$20 Rule” realize just how much they were wasting on unnecessary purchases. Instead of feeling deprived, they feel empowered because they have greater control over their money, thus saving more.

Challenges of Using the “$20 Rule” and How to Overcome Them

Like any financial habit, the “$20 Rule” requires discipline and consistency. Some people may struggle with the waiting period, especially if they are used to making instant purchases. If you find it difficult to stick to the rule, consider using reminders or writing down potential purchases in a spending journal. Seeing a list of things, you wanted to buy but can’t be a powerful motivator to continue saving.

Another challenge is peer pressure. Friends or family members may encourage you to spend money, especially in social situations. If you’re out with friends and everyone is buying something small, it can be hard to stick to your plan. In these cases, remind yourself of your long-term financial goals and suggest free or low-cost alternatives.

The Psychological Benefits of the “$20 Rule”

Beyond the financial savings, the “$20 Rule” also helps build financial awareness and confidence. Many people struggle with money not because they don’t earn enough, but because they don’t manage their spending effectively. This rule trains your brain to think more critically about purchases, which can lead to better financial decisions overall.

Practicing mindful spending reduces financial stress and guilt. When you do decide to buy something, you’ll know that it’s a well-thought-out purchase rather than an impulsive decision. Over time, you may find yourself applying this mindful approach to larger purchases as well, leading to even greater financial stability.

Making the “$20 Rule” a Lifestyle Habit

The key to making this rule work is consistency. Like any habit, it becomes easier with practice. Start by applying it to just one area of spending, such as dining out or retail purchases, and gradually expand it to other categories. If you slip up, don’t get discouraged—focus on long-term progress rather than perfection.

Many people who adopt the “$20 Rule” find that it naturally extends to other financial behaviors. Once you start questioning small purchases, you become more mindful of all your expenses. Over time, this leads to a healthier relationship with money and a stronger financial future.

The “$20 Rule” Can Change the Way You Handle Money

The “$20 Rule” is a simple but powerful way to take control of your spending and boost your savings. By waiting 24 hours before making any purchase under $20, you force yourself to reconsider whether you truly need it. This small shift in thinking can save you thousands of dollars per year and help you build better financial habits.

Money management doesn’t have to be complicated. Sometimes, the simplest strategies are the most effective. Try using the “$20 Rule” for a month and see how much you save. You might be surprised at just how much money was slipping through the cracks.

Have you ever tried the $20 rule? How did it work out for you? Let us know in the comments.

Read More:

Is It Ever Okay To Share Your Subscription Passwords With Friends to Save Money?

No Budget No Money: 7 Reasons You Have No Idea Where Your Money Went

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.
Filed Under: Budgeting Tagged With: Budgeting Tips, Financial Discipline, financial habits, frugal living, Mindful Spending, money management, Personal Finance, saving money, smart shopping, Wealth Building

No Budget No Money: 7 Reasons You Have No Idea Where Your Money Went

March 5, 2025 by Latrice Perez Leave a Comment

No Budget
Image Source: 123rf.com

Ever found yourself staring at an empty bank account, wondering where all your hard-earned money disappeared? Without a structured budget, it’s easy to lose track of spending, leading to financial stress and uncertainty. Let’s delve into seven often-overlooked reasons why your money seems to vanish without a trace.

1. Mental Accounting: The Invisible Money Trap

Many people subconsciously assign different values to money based on its source or intended use—a concept known as mental accounting. For instance, you might treat a tax refund as “fun money” while considering your regular paycheck strictly for bills. This compartmentalization can lead to irrational spending and a distorted view of your financial situation. Without a budget to provide a holistic view, these mental accounts can cause money to slip through the cracks unnoticed.​

2. Lifestyle Creep: The Silent Wallet Drainer

As your income increases, it’s natural to enhance your lifestyle. However, without mindful spending, this can escalate into lifestyle creep, where non-essential luxuries become perceived necessities. Over time, these incremental upgrades—like dining out more frequently or opting for premium services—can consume your income, leaving little room for savings. A budget helps identify and control these subtle spending escalations.​

3. Rounding Down: The Little Lie You Tell Yourself That Costs You Big

Ever grab lunch for $12.75 and tell yourself it was “about ten bucks”? Or round a $47 shopping trip down to “around 40”? This mental trick—where you subconsciously downplay how much you’re actually spending—adds up fast. Over time, constantly underestimating expenses creates a distorted view of your finances, making it feel like money is disappearing into thin air. Without a budget tracking every penny, you could be losing hundreds (or even thousands) simply because your brain is rounding in the wrong direction.

4. Social Pressures: Keeping Up with Appearances

Social media and peer influence can pressure individuals into spending to match others’ lifestyles. This often leads to unnecessary expenses on trendy items, vacations, or dining experiences. Without a budget, it’s challenging to recognize and resist these external pressures, resulting in overspending and financial strain.​

5. Lack of Financial Literacy: Navigating Without a Map

Piggy bank on books
Image Source: 123rf.com

Understanding personal finance is crucial for effective money management. Without basic financial literacy, individuals may struggle with concepts like interest rates, investment options, or debt management. This knowledge gap can lead to poor financial decisions and an inability to track spending effectively. A budget serves as a practical tool to apply financial principles and monitor progress.

6. Irregular Expenses: The Budget Busters

Expenses like annual subscriptions, car repairs, or medical bills can catch you off guard if they’re not anticipated. Without a budget that accounts for these irregular costs, such expenses can disrupt your financial stability. Planning for these contingencies ensures you’re prepared and prevents sudden financial shortfalls.​

7. Emotional Spending: The Hidden Cost of Feelings

Emotions significantly influence spending habits. Whether it’s retail therapy after a tough day or celebrating a success with an extravagant purchase, emotional spending can lead to unplanned outlays. Without a budget to keep your emotions in check, these expenditures can accumulate, leaving you puzzled about where your money went.​

Recognizing Spending Pitfalls

Not knowing where your money goes is a common issue, but it’s one that can be addressed with awareness and proactive measures. By recognizing these subtle spending pitfalls and implementing a structured budget, you can regain control over your finances, reduce stress, and work towards your financial goals with confidence.

Where is your money going? Do you have a budget that helps you keep track of your expenses? Tell us about it in the comments below.

Read More:

7 Signs Your Budget Is Running Your Life—and How to Take Back Control

Your Friend Makes More Money Than You—Now What? Dealing with Financial Jealousy

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.
Filed Under: Budgeting Tagged With: budgeting, financial literacy, impulse spending, Lifestyle creep, mental accounting, Personal Finance

Millionaire Secrets: 7 Weird Money Habits That Actually Work

March 3, 2025 by Latrice Perez Leave a Comment

Millionaire Secrets
Image Source: 123rf.com

Most people assume millionaires live lavishly, but many wealthy individuals follow unconventional money habits to build and protect their fortunes. Their secret? They don’t think about money the same way the average person does. Instead of spending like they’re rich, they embrace unique strategies that seem odd but are surprisingly effective. If you want to grow your wealth, consider adopting these seven millionaire money habits.

They Avoid Lifestyle Inflation at All Costs

When most people earn more, they immediately upgrade their lifestyle—bigger homes, fancier cars, and expensive vacations. Millionaires resist this temptation and keep their expenses low, even when they can afford more. Many self-made millionaires drive older cars, live in modest homes, and avoid unnecessary luxuries. By maintaining a simple lifestyle, they free up more money to invest and grow their wealth.

They Treat Every Dollar Like an Employee

Instead of thinking of money as something to spend, millionaires view each dollar as an employee that should be working for them. This means they prioritize investing over splurging. They put money into stocks, real estate, and businesses that generate passive income. Every dollar is given a job—whether it’s earning interest, compounding in investments, or funding a future project.

They Set “No-Spend” Days Regularly

Many wealthy people schedule days or even weeks where they spend nothing beyond absolute necessities. This practice helps them stay mindful of their expenses and break unnecessary spending habits. It also forces creativity—finding free entertainment, cooking at home, and using what they already have instead of buying more. This habit builds financial discipline and prevents impulse spending.

They Negotiate Everything

Millionaires don’t just accept the first price they’re given—they negotiate. From real estate deals to credit card interest rates, they challenge prices to maximize savings. Even in everyday purchases, they ask for discounts or perks. While negotiating may feel uncomfortable at first, it can save thousands of dollars over time. If you don’t ask, you’ll never know what savings you might get.

They Read More Than They Watch TV

A surprising habit among millionaires is their dedication to reading. Many successful people, like Warren Buffett and Elon Musk, credit much of their knowledge to reading books. Instead of wasting hours on entertainment, they consume information that helps them grow—financial books, biographies of successful people, and industry news. By learning continuously, they make smarter financial decisions and spot opportunities others miss.

They Buy Quality (But Less Often)

Buy Quality
123rf.com

Rather than chasing trends or buying cheap, millionaires focus on quality purchases that last. They prefer durable goods over disposable ones, saving money in the long run. Whether it’s clothing, appliances, or cars, they research before buying and invest in things that provide long-term value. This prevents constant replacements and reduces wasteful spending.

They Automate Their Savings and Investments

Many millionaires remove the temptation to spend by automating their finances. They set up automatic transfers to savings accounts, retirement funds, and investments before they even touch their money. This “pay yourself first” strategy ensures that they consistently build wealth without relying on willpower. Over time, small automated contributions turn into significant financial gains.

Shift Your Mindset

You don’t need to be a millionaire to adopt these habits—you just need to shift your mindset. By treating money as a tool for wealth-building, resisting lifestyle inflation, and making intentional financial choices, you can start accumulating wealth the same way self-made millionaires do. The key isn’t how much you make—it’s how you manage it.

Do you have any millionaire habits that are helping you to shift your mindset? Are you already on your way to becoming a millionaire? Let us know how you’re doing it in the comments below.

Read More:

The Secrets of Self-Made Millionaire Women: 6 Tips You Can Steal

FireAid Concert Raises a Staggering $100 Million for LA Wildfire Relief—Here’s How It Happened

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.
Filed Under: money management Tagged With: budgeting, financial mindset, financial success, millionaire habits, money tips, Personal Finance, saving money, smart investing, Wealth Building

Is Your Partner a Financial Liar? 7 Signs They’re Hiding Money Problems

February 27, 2025 by Latrice Perez Leave a Comment

Financial Liar
Image Source: 123rf.com

Financial dishonesty is one of the leading causes of relationship stress, yet many people don’t realize their partner is hiding money problems. From secret debts to undisclosed spending, financial lies can slowly erode trust and create serious issues. Recognizing the warning signs early can prevent financial disasters and help couples address money issues before they spiral out of control. Here’s how to tell if your partner is being financially dishonest.

They Avoid Talking About Money

A partner who refuses to discuss finances or changes the subject when money comes up may be hiding something. Avoidance can be a sign of hidden debts, reckless spending, or financial instability. Healthy relationships require open and honest financial communication. If your partner is secretive about money, it’s important to address the issue directly.

They Have Unexplained Expenses

If your partner frequently withdraws cash, makes large purchases without explanation, or receives mysterious bills, they may be hiding financial problems. Unexplained expenses often point to secret spending habits, gambling, or even hidden debts. Reviewing financial statements together can help identify where the money is going. Being open about spending habits builds financial trust in a relationship.

They Get Defensive About Their Finances

Defensive
Image Source: 123rf.com

If your partner reacts angrily or defensively when asked about money, they may feel guilty about something. Defensive behavior is a common reaction when someone is hiding financial problems. A healthy response to financial questions should involve openness and problem-solving, not avoidance or hostility. Addressing financial concerns calmly and respectfully can encourage honesty.

Their Financial Stories Don’t Add Up

Inconsistent details about income, expenses, or debts may indicate financial dishonesty. If your partner frequently changes their story about money or avoids giving direct answers, they might be covering up a financial issue. Keeping track of shared financial responsibilities can help detect inconsistencies early. Trust is built through transparency, especially when it comes to finances.

Address Financial Dishonesty Before It’s Too Late

Financial secrets can lead to serious problems in relationships if they aren’t addressed early. If you suspect your partner is being dishonest about money, having an open and honest conversation is the first step. Couples who work together on financial issues build stronger, more stable relationships. Recognizing the signs of financial dishonesty can help prevent future financial and emotional damage.

Were you in a relationship with a financial liar? What were the clues that told you they were being dishonest. Share your story in the comments below.

Read More:

Women Over 30: These 10 Types of Men Make for the Worst Husbands

What Are 7 Financial Red Flags I Should Look Out For In A New Relationship?

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.
Filed Under: Personal Finance Tagged With: couples finance, financial honesty, Financial Red Flags, financial trust, hidden debt, money management, Personal Finance, relationships and money

The Financial Advisor Playbook: What They Don’t Want You to Google

February 26, 2025 by Latrice Perez Leave a Comment

Google Search
Image Source: 123rf.com

Financial advisors have extensive knowledge about money management, but not all of them share everything they know. Some information is kept quiet because it could empower clients to take more control over their finances. The more you know, the more you can avoid unnecessary fees and make smarter investment choices. Here are some of the biggest secrets financial advisors would rather you not Google.

Many Advisors Make More Money When You Do Less

Some financial advisors earn money based on the assets they manage, which means they make more when you leave your money with them. While they may suggest that staying the course is the best strategy, they may not always encourage you to seek better investment opportunities. In some cases, DIY investing in low-cost index funds can outperform managed portfolios with high fees. Understanding how your advisor gets paid ensures you make the best financial decisions.

High-Fee Investments Are Not Always Better

Many advisors push actively managed funds or complex financial products because they generate higher commissions. However, studies show that low-cost index funds often outperform high-fee investments over the long term. Expensive mutual funds and structured products may benefit your advisor more than they benefit you. Researching investment options before committing can save you thousands in fees.

You Don’t Need to Be Wealthy to Invest

Some financial advisors focus on high-net-worth clients, making it seem like investing is only for the rich. The truth is, anyone can start investing with small amounts through fractional shares, low-fee ETFs, and robo-advisors. Delaying investing until you have a large amount of money can result in lost growth opportunities. The key to building wealth is starting early, regardless of income level.

You Can Negotiate Fees

Negotiate Fees
Image Source: 123rf.com

Many clients don’t realize that advisory fees are often negotiable. Some advisors are willing to lower their fees, especially if you have a significant portfolio or plan to invest more. Accepting high fees without negotiation can result in unnecessary expenses over time. Always ask for a breakdown of fees and see if there’s room for adjustment.

Knowledge is Power in Personal Finance

Financial advisors provide valuable services, but knowing their industry secrets helps you make better financial decisions. Understanding how fees work, avoiding unnecessary investment costs, and taking control of your finances empowers you to grow wealth more effectively. By researching financial topics on your own, you can ensure you’re making the smartest money moves.

Do you have a financial advisor? Are they worth the money you’re paying them? Let’s talk about it below.

Read More:

Here’s What Your Financial Advisor Won’t Tell You About Income Investing

10 Subtle Signs It’s Time to Fire Your Financial Advisor

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.
Filed Under: Personal Finance Tagged With: financial advisors, financial strategy, high-fee investments, investment secrets, money management, Personal Finance, smart investing, wealth growth

How to Make Banks Pay You Instead of the Other Way Around

February 26, 2025 by Latrice Perez Leave a Comment

Bank Pay You
Image Source: 123rf.com

Most people assume banks are just a place to store money, but the truth is, banks make billions off their customers through fees, interest, and low-yield savings accounts. The good news? You don’t have to be on the losing side of this equation. With the right strategies, you can flip the script and make banks pay you instead of the other way around. Here’s how.

Choose a High-Yield Savings Account

Traditional savings accounts often offer insultingly low interest rates—sometimes as little as 0.01%. Meanwhile, online banks and credit unions offer high-yield savings accounts with interest rates 10 to 20 times higher.

How to make this work for you:

  • Compare different banks and find an account with at least a 4% APY or higher.
  • Avoid savings accounts with monthly maintenance fees.
  • Set up automatic transfers to take advantage of compound interest over time.

Use Cashback and Rewards Checking Accounts

Many banks now offer checking accounts that pay you to use them, often through cashback on debit card purchases or interest-bearing checking accounts.

How to make this work for you:

  • Look for banks that offer 1-3% cashback on debit purchases.
  • Some banks provide interest rates on checking balances—shop around for those offering at least 1-2% APY.
  • Ensure the account doesn’t have high fees that offset your rewards.

Get Rid of Unnecessary Fees

Overdraft fees, ATM withdrawal charges, and maintenance fees quietly eat away at your money. The less you pay in fees, the more cash stays in your pocket.

Try This:

  • Switch to a fee-free checking account that doesn’t charge for overdrafts or minimum balances.
  • Use in-network ATMs to avoid withdrawal fees.
  • Ask your bank to waive fees—many will remove them if you call and ask.

Take Advantage of Bank Sign-Up Bonuses

Sign Up Bonus
Image Source: 123rf.com

Banks often run promotions where they’ll pay you to open an account, with bonuses ranging from $100 to $500. While they may require a direct deposit or a certain balance, these offers can be a quick way to earn extra cash.

Follow These Steps:

  • Research current bank promotions and find one with a low deposit requirement.
  • Read the fine print to ensure you meet the requirements to receive the bonus.
  • Close old accounts that no longer benefit you to keep your finances streamlined.

Invest Through Your Bank’s Brokerage Services

Many banks offer commission-free investment accounts or partnerships with brokerages where you can earn passive income. Instead of leaving your money idle in a low-interest account, investing allows you to grow your wealth.

Take These Steps:

  • If your bank has a brokerage arm, look into low-cost index funds or ETFs.
  • Set up automatic investments so your money works for you without effort.
  • Compare bank brokerage fees—sometimes using an independent brokerage is more cost-effective.

Use Credit Cards with Cashback and Rewards

Banks make money when you carry a credit card balance, but if you use credit wisely, you can earn cashback and rewards without paying interest.

Take These Steps:

  • Get a no-annual-fee cashback credit card and pay off the balance in full every month.
  • Use a card that offers at least 1.5-2% cashback on everyday purchases.
  • Redeem cashback for statement credits, deposits, or travel rewards.

Flip the Banking System in Your Favor

Banks make money off uninformed customers, but by playing the game strategically, you can turn the tables and make them work for you. With high-yield savings, cashback checking, fee elimination, and sign-up bonuses, you can stop paying banks and start getting paid instead. It’s time to make your money work smarter—not harder.

Have you already used some of these techniques to earn money from your bank? Have you learned of other ways to earn from banking? Let us know in the comments.

Read More:

8 Things You Didn’t Know About Digital-Only Banks (And Why They’re the Future)

Traditional Banking vs. Digital Solutions: What is the Future of Overseas Payments?

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.
Filed Under: Banking & Finance Tagged With: banking tips, cashback rewards, Financial Hacks, high-yield savings, no-fee accounts, Personal Finance, saving money, smart banking

  • « Previous Page
  • 1
  • …
  • 180
  • 181
  • 182
  • 183
  • 184
  • …
  • 186
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework