• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for money management

Budget Nightmares: What Are You Doing At 2 A.M.?

December 17, 2012 by Joe Saul-Sehy 40 Comments

When I left The Citadel (go Bulldogs!) to attend Michigan State (go Spartans!), I said goodbye to a lucrative track and cross country scholarship. I felt bad, but the writing was on the proverbial wall. My coach had given me “one more year” to run better at the end of year one, and I promptly pulled a quadricep muscle early into the fall campaign. I’d been a guy they thought was a (quoting the coach), “Diamond in the rough” anyway. Turns out I was pretty much just rough.

Immediately, I had money problems. My parents couldn’t afford to pay for MSU. I had this general notion that financial aid would cover everything. Imagine my bitterness  when I found out that my dad made too much money to qualify for any need-based aid.  My loan package quickly swelled as my first course of action was to get through school quickly. When I realized what a mess these loans would be, I made the tough decision to become a part time student working three jobs.

Here’s how I made that decision:

During one of my money woes, I tuned in to my favorite late night money talk show hosts on the radio: a guy named Bruce Williams. He sounded like that knowledgeable grandfather who’d give you either an arm around your shoulder or a swift kick in the butt. Maybe listening to him was the idea behind our podcast….I don’t know.

One night, drowning in my own debt and hopeless money situation, I heard a woman call in to the show. She and her husband both worked hard, but they weren’t making ends meet. Bills continually piled up and their reserves dwindled.

“What are you doing at 2 a.m.?” Bruce asked.

The woman stuttered. “What do you mean? We’re sleeping!”

“Why are you sleeping at 2 a.m. when your bills are getting further and further behind?”

The woman quickly answered, “We need all the sleep we can get so we work well at our job in the morning.”

Bruce sighed. “So you’re saying you need your job worse than your house and car? Then why don’t you sell your house or car?”

“I can’t sell my house or my car. Then I wouldn’t have any place to live!”

“My point exactly,” he said. “So, if you like your house and your car, what are you doing at 2 a.m.?”

“What are you getting at? I can’t do more than I’m doing.”

The radio host laughed. He had this chuckle that always sounded a little sad. “What I’m getting at is that you have serious money problems, but you don’t want to change anything. If you’re serious about solving your money problems, you’ll get a night job too, or you’ll find ways to make more money at your day job.”

The woman quickly interjected, “We’re both at the top of our pay scale. That’s why we need to hold on to these jobs.”

“You aren’t listening,” Bruce said. It was one of the few times I’ve ever heard him turning angry on the show. “You can’t work like you do, eat like you do and sleep like you do AND expect something to change.”

Unbelievably, she ranted at him. “I can’t believe this. I call you for serious advice and all you do is blame my job, blame my house, and blame me. We’re doing everything we can do and it isn’t getting any better.”

…and she hung up on him!

Maybe she wasn’t listening, but I sure was. I became a substitute paper boy and redoubled my efforts to advertise my disc jockey service better. I went around to fraternity houses and spoke directly with the social chairmen. I made mixed tapes with some cassettes I had laying around and brought them with me (that dates me, huh? I’m glad I didn’t say reel-to-reel tapes….). Later, I found out that my tapes were a hit around the school. More than that, extra money started to trickle into my hands, and my view of my financial situation changed.


Here’s what I learned:

  1. I’m in charge of my financial destiny.
  2. Sleep is overrated when you’re in over your head.
  3. Financial planning is easy. It’s either an income problem or an expense problem. If you can’t fix one, you have to fix the other by default or the plan won’t work.

If you’re reading this because you’re in broke week (a term coined by my friend Michelle over at See Debt Run), you can either fix it once today and have to fix it again next month, or you can change your money earning skills or spending habits. For short term needs, you could borrow cash, but remember that this isn’t the final solution: it’s duct tape until you’re able to get on your feet.

While we’re talking about duct tape on your financial situation, how about a cool $100 cash or Amazon money? Would that help you avoid your long term plan for a few more days? Ha! Maybe you can use it to buy a radio that’ll change your life, too….

Enter our gigantic giveaway below:

a Rafflecopter giveaway

Enhanced by Zemanta
Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.
joesaulsehy.com/

Filed Under: budget tips, Cash Reserve, Debt Management Tagged With: Bruce Williams, Budget, Home, Money, money management, Personal Finance, radio talk show

So You Want to Manage Your Own Money?

September 4, 2012 by Joe Saul-Sehy 29 Comments

A friend texted me this morning.

“We should talk soon. Julie is coming around to the idea of us managing our own money.”

It seems easy, right? My initial reaction to my friend was, “That’s awesome!” because it is. There are few things more satisfying than achieving your financial dreams and knowing that you climbed the money management mountain yourself.

No “money-god” came down and did it for you.

You didn’t need the Powerball numbers.

You actually plotted a financial course and landed safely at your destination.

For my friend, and for you if you’re about to embark on this journey, there’s good news and bad news: the good news is that it isn’t difficult to manage your own money.

The bad news is that to effectively manage your own money you’ll need to be ready to face some fairly difficult tasks.


Two Types of People


When I was a professional advisor, I’d meet some smart people who wanted to jump into their own money management and wanted an expert with an opinion to look over their shoulder, hold them accountable, and make sure they didn’t miss any “I” dotting or “T” crossing.

…and then there were other, often equally-smart people who wanted to hand it over to me and have someone else take care of it for them.

Believe it or not, most advisors I knew preferred the latter type of client and loathed the first one. Someone questioning their motives? Someone asking “why are we doing it this way?” all the time? That’s preposterous!

But if you’re going to ever learn how to manage your own money, you’ll need to be the first type, not the latter.

The steps aren’t difficult:


The Steps to Managing Your Own Money


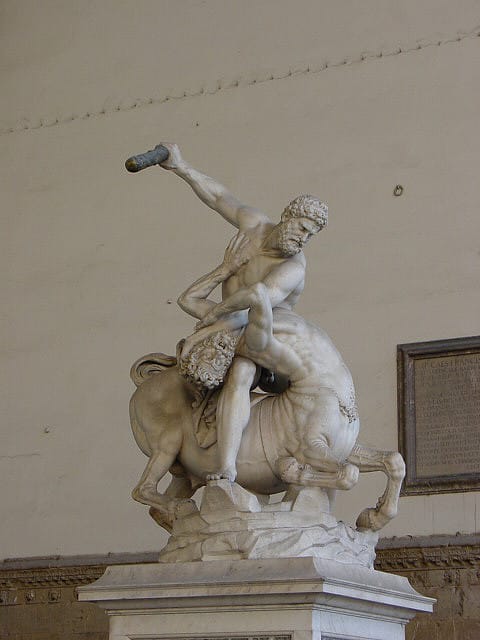
My kids are reading myths in school. In the story of Hercules, he faces a series of challenges to achieve is goal.

I look remarkably like the guy on top, but I’m a little paler and not quite as naked. And I have less hair.

You’ll have a series of gauntlets in your way too, if you want to manage your own money.

1) Write out your goals. I’m not talking about writing:

Retirement

College

New Boat

Fall Deeper in Love

Real goal writing has a specific time, dollar amount and vision attached.

I want to be able to live on $65,000 per year (in today’s dollars) by age 65 without having to work every day. With this money I’d like to: (here you write your bucket list, which should include visiting every NASCAR track in the country).

That’s a goal you can shoot for and be excited about (except for visiting the track at Pocono, which I thought was pretty overrated).

2) Next, you write out all the hurdles in your way.

– I have $25,000 in credit card debt (separate by interest rate, term, amount)

– I have to put two children through college

– I know nothing about money management

3) Then, you find one of the nearly bazillion financial calculators online (you can use our powerful little PlanWise calculator here on the site!) and figure out how much you need to save to reach your goal.

– I need to save $250 per month to reach my dream if I achieve an 8% return.

Armed with your money management return information, now you figure out how to come up with $250 per month.

– Tweak your budget

– Pay down debt

– Take on more work

4) Before investing, though, you have a big problem. You have to insure yourself against some of the huge “what if’s” out there for you and your family:

What if you die?

What if you are disabled?

What if you have a car accident?

You’ll need to create a will and evaluate insurances.

5) Finally, you begin the heavy task of research to find investments that have historically achieved 8%.


No Step is Difficult, You Just Shouldn’t Miss One


As you can see, when you take on the hard task and decide to manage your own money, getting it right will be difficult. Each area demands time and energy:

– Planning, milestones and tracking

– Budget, income advancement and debt reduction

– Insurance need projection and comparison analysis

– Estate planning

– Investment allocation, picking and monitoring

These are five basic money management steps, but each packs a punch!


I Don’t Mean To Imply You Can’t Do It


As soon as I finish this piece I’m calling my buddy and talking him through these points. Before he takes on the task, he should know how long the financial security road really is. Going in with your eyes wide open is half the battle if you plan to win the “manage your own money” game.

He can do it, and so can you!

Enhanced by Zemanta
Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: money management, Planning, successful investing Tagged With: Budget, Debt, finance, Financial services, Insurance, Investment, manage your money, money management

How to Date Your Bank

November 1, 2011 by Joe Saul-Sehy 4 Comments

Before I begin my joyous rant, I must comment that I’m sure there’s no correlation between the massive amount of chocolate I consumed last night and the sleepies I’m feeling today.

None at all.

monkey_dancing But, even a bad case of sugar-low can’t stop me from doin’ my monkey dance after I saw the news that Bank of America is dropping their $5 debit card fee.  Much like Netflix recently was forced to step back from plans to split their service, Bank of America miraculously realized that screwing their customers might not be in their best interest.

Better late than never.

Choosing a bank is a little like choosing a spouse. It’s a tough decision. You don’t just walk in one day and say, “Hey, bank, wanna tie the knot?” You’re going to be together in some capacity nearly every day, so it might be better to date for awhile.

My favorite banks are much like my spouse: intelligent and low maintenance.

But you don’t know that at first. I used to be a Bank of America customer. Bank of America was the pretty girlfriend who said all the right things until I found the cap off the toothpaste. Then she became the wicked Bank of the West. When I wanted to talk about the toothpaste, she disappeared behind a phone bank of polite service people who “didn’t do it.”

To get the best bank possible, you have to date. Play the field a little. Sew your wild oats. Introduce a few of your friends over to see how the New Bank acts around the family.

Here are a few of the qualities I look for when deciding on the perfect bank:

1) Fees. Banks have, among others, checkwriting fees, teller fees, debit card fees, wire transfer fees and overdraft fees. I want a complete fee schedule before deciding on a bank.

2) Convenience. Is it easy to deposit and withdraw money? How responsive is the bank if I have questions? I mentioned that Fidelity will allow me to use my smart phone to deposit checks. How much more sexy can it get than that?

3) Range of services. I want to know what online tools are available. I love online banking, so I’m going to wine and dine these features before settling on a mate. Budget tools are also important to me. I need to be able to easily track my expenses. Banks with robust budget tools are going to get a second look from me.

4) Statements. This might not be important to you. My spouse doesn’t care for online banking, and wants a statement mailed to us. It must be easy to read. I know what you’re thinking. We also have an abacus at home to help the children with their math homework. Call us the Flintstones.

5) Interest rates. Is there a fairly high interest rate money market? I don’t use CDs often, but are their rates competitive? Use resources such as www.bankrate.com to decide if this bank is in the ballpark.

Those are the four most important areas to me. Maybe you have others. Much like dating, to some degree the mix of qualities one looks for in a bank boils down to personal preference. But also like finding a mate, it’s vitally important to become comfortable with the wide range of online and local banks to see what’s available. It’s better to be surprised about how lovely your bank still is many years later, holding your hand at age 80, rather than finding out too late that she’s been in your wallet again, stealing your cash or your breath mints.

Or leaving the cap off the toothpaste.  I’m looking at you, Bank of America.

Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.
joesaulsehy.com/

Filed Under: Banking, money management, Planning Tagged With: Bank of America debit, banking, bankrate.com, dating your bank, five things to look for in a bank, money management, monkey dance, what to look for in a bank

  • « Previous Page
  • 1
  • …
  • 47
  • 48
  • 49

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • 10 Tactics for Building an Emergency Fund from Scratch by Vanessa Bermudez
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald

Copyright © 2026 · News Pro Theme on Genesis Framework