• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Hidden Fees

The Truth About “0% APR” Balance Transfer Cards and Their Hidden Fees

October 17, 2025 by Travis Campbell Leave a Comment

apr
Image source: pexels.com

“0% APR” balance transfer cards are everywhere, promising relief from high-interest debt. If you’re juggling credit card balances, these offers can look like a shortcut to financial freedom. But before you jump in, it’s important to know exactly what you’re signing up for. The truth is, these cards come with fine print that can cost you more than you expect. Understanding the hidden fees and pitfalls can help you make smarter choices with your money. Let’s break down what you really need to know about 0% APR balance transfer cards.

1. The Balance Transfer Fee Isn’t Always Obvious

The term “0% APR” grabs your attention, but the real cost often hides in the balance transfer fee. Most credit card companies charge a fee to move your balance, typically between 3% and 5% of the amount transferred. For example, transferring $5,000 could cost you $150 to $250 right off the bat. This fee is usually added to your balance, so you start with a bigger debt than you intended.

Some cards advertise no balance transfer fee, but those offers are rare and usually come with other trade-offs, like a shorter 0% APR period or higher ongoing interest rates. Always read the fine print and do the math to see if the savings on interest outweigh the upfront cost.

2. The 0% APR Period Is Temporary

The main draw of 0% APR balance transfer cards is the promise of no interest for a set time. But this period is temporary—often 12 to 18 months. After that, any remaining balance will be subject to the card’s regular interest rate, which can be as high as 20% or more. If you don’t pay off your transferred balance before the promotional period ends, you could find yourself back where you started, or worse.

Mark your calendar with the exact date the 0% APR expires. Set a payoff plan that ensures you clear the debt before interest kicks in. Otherwise, you risk undoing any progress you’ve made.

3. New Purchases Might Not Be Interest-Free

It’s easy to assume that every purchase you make with your new card will also benefit from the 0% APR. But in many cases, the promotional rate only applies to balance transfers—not new purchases. Any new spending might rack up interest immediately, at the card’s standard rate. This can make it even harder to pay down your debt.

If you’re using the card to transfer a balance, avoid making new purchases until your transferred debt is paid off. Some cards offer a 0% APR on both transfers and purchases, but not all. Double-check the offer details before you swipe.

4. Late Payments Can End Your 0% APR Early

Missing a payment on your 0% APR balance transfer card can be costly. Many issuers will revoke your promotional rate if you’re late, meaning your entire balance could start accruing interest at the regular rate. You might also face a late fee, which can add up quickly.

To protect your savings, set up automatic payments or reminders. Even one slip-up can erase the benefits of the 0% APR period and leave you with unexpected charges.

5. Your Credit Score Matters—A Lot

Not everyone will qualify for the best 0% APR balance transfer cards. Lenders reserve these offers for people with good to excellent credit. If your credit score is below average, you might get approved for a card with less favorable terms or be denied altogether.

Applying for a new card also creates a hard inquiry on your credit report, which can temporarily lower your score. Plus, opening new accounts and shifting balances can affect your credit utilization ratio. Before applying, check your score and weigh whether the benefits outweigh the risks. If you’re not sure where you stand, you can get a free copy of your credit report from AnnualCreditReport.com.

6. Deferred Interest vs. True 0% APR

Not all “0% APR” offers are created equal. Some cards advertise 0% interest but actually use a deferred interest model. With deferred interest, if you don’t pay off the full balance by the end of the promotional period, you’ll owe interest on the entire original amount—not just what’s left. This can be a nasty surprise.

Be sure to distinguish between true 0% APR, where no interest is charged during the promo period, and deferred interest, which can backfire if you’re not careful. Always read the terms and ask questions if you’re unsure.

7. Hidden Fees Beyond the Transfer

Balance transfer cards can come with other fees that add up fast. Some cards charge annual fees, which can eat into your savings. Others may have cash advance fees, foreign transaction fees, or penalty APRs for certain behaviors. These extra costs can erode the benefits you hoped to gain from your 0% APR balance transfer card.

Before you apply, review all fees listed in the card’s terms and conditions. If you travel or plan to use the card for anything beyond the transfer, factor those charges into your decision.

Making the Most of Your 0% APR Balance Transfer Card

0% APR balance transfer cards can be a smart tool for paying down debt, but only if you know the rules and avoid the traps. By understanding the hidden fees, time limits, and other fine print, you can make an informed decision that actually saves you money. The primary keyword to focus on when researching these offers is “0% APR balance transfer cards,” as that will help you find the most relevant and up-to-date information.

Remember, these cards aren’t a cure-all for debt. They work best when paired with a solid payoff plan and disciplined spending. If you’re strategic, a 0% APR balance transfer card can give you breathing room to tackle your balances, but only if you’re aware of every potential pitfall along the way.

Have you used a 0% APR balance transfer card before? What hidden fees or surprises did you encounter? Share your experience in the comments!

What to Read Next…

  • 7 Hidden Fees That Aren’t Labeled As Fees At All
  • 7 Credit Card Features Disappearing Without Any Notice
  • The Benefits Of Taking Personal Loans And Their Impact On Credit Scores
  • 5 Things That Instantly Decrease Your Credit Score By 50 Points
  • Why Credit Limits Are Being Lowered Without Consent
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.
Filed Under: Finance Tagged With: 0% APR, balance transfers, credit cards, Debt Management, Hidden Fees, Personal Finance

The “Buy Now, Pay Later” Trap That’s Drowning People in Hidden Debt

October 12, 2025 by Travis Campbell Leave a Comment

Bnpl
Image source: pexels.com

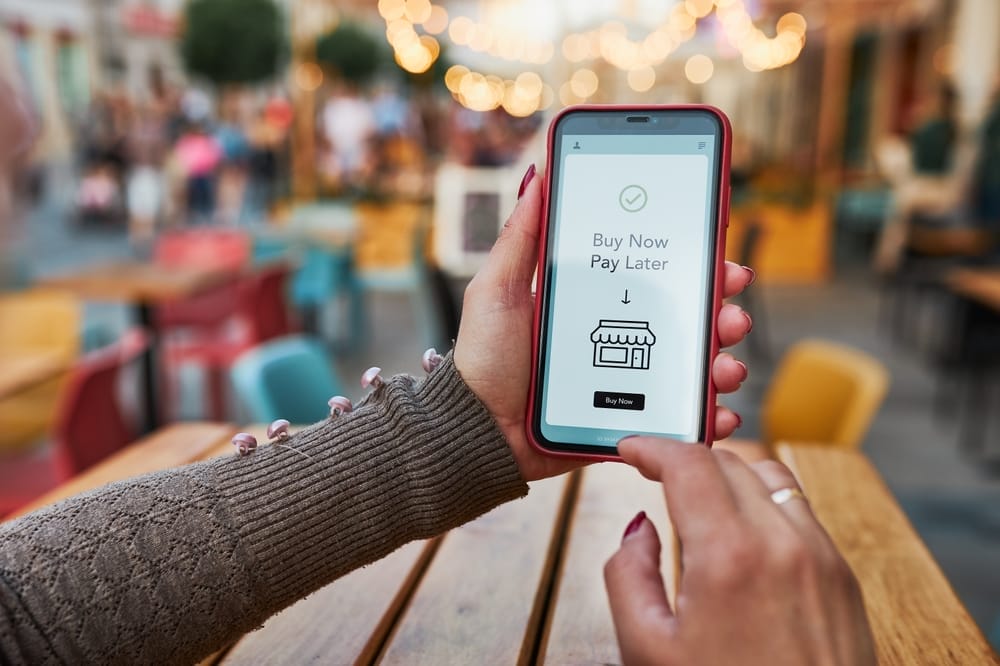
The rise of “Buy Now, Pay Later” (BNPL) services has changed the way people shop. At checkout, it’s tempting to split a purchase into smaller payments instead of paying the full price upfront. It feels painless and budget-friendly. But behind the scenes, these services can quietly stack up hidden debt. Many shoppers don’t realize how quickly these small payments add up. If you’re not careful, you could find yourself in a financial hole that’s hard to climb out of. Understanding the risks of the buy now, pay later trap is more important than ever.

1. The Illusion of Affordability

One of the biggest dangers of the buy now, pay later trap is how easy it becomes to justify purchases. A $200 jacket doesn’t look so bad when you only have to pay $50 today. The remaining payments are pushed into the future, and that makes it feel like you’re spending less. But you’re not saving money—you’re just delaying the pain. This illusion of affordability encourages overspending. It’s easy to lose track of how much you owe when your purchases are split into bite-sized chunks.

BNPL services bank on this psychology. The more you use them, the easier it is to think you can afford more. But every “small” payment is another obligation on your plate. If you’re not careful, you can end up with several ongoing payments at once, all stacking up into a bigger financial burden.

2. Hidden Fees and Penalties

Many buy now, pay later providers advertise “no interest” or “zero fees.” But the reality can be very different. If you miss a payment, you might get hit with late fees or penalty charges. Some services even report missed payments to credit bureaus, which can hurt your credit score. These fees are often buried in the fine print, making them easy to overlook.

The trap is set when you assume you’ll always pay on time. Life happens—maybe your paycheck is late or you forget a due date. Suddenly, that “interest-free” purchase gets expensive. Always read the terms before you agree, and remember that the buy now, pay later trap isn’t just about the payments you expect—it’s also about the costs you don’t see coming.

3. Multiple Accounts, Multiple Headaches

It’s easy to sign up for several buy now, pay later services. Each one might seem harmless on its own, but together they can create a confusing web of payments and due dates. You might have a payment due to one provider on the 15th, another on the 18th, and a third on the 22nd. Juggling all these can be a nightmare.

Miss a single payment and you could trigger fees, credit dings, or even debt collection calls. The buy now, pay later trap grows as you lose track of your obligations. Some people end up with four, five, or even more BNPL accounts running at the same time. That’s a recipe for financial chaos.

4. Impact on Your Credit and Budget

When you use a buy now, pay later service, you’re taking on debt—even if it doesn’t feel like it. Some providers run soft credit checks, while others report your payments to major credit bureaus. If you fall behind, your credit score could take a hit. This can affect your ability to get loans, rent an apartment, or even land certain jobs.

Even if your credit isn’t directly affected, your monthly budget definitely is. Every BNPL payment reduces your available cash. If you’re juggling several plans, you might find yourself short on money for essentials. The buy now, pay later trap can quietly squeeze your finances until you’re left scrambling to make ends meet.

5. Encouraging Impulse Buying

The buy now, pay later trap doesn’t just create debt—it encourages habits that can make your financial situation worse. When you know you don’t have to pay the full amount upfront, it’s easier to buy things you don’t really need. The barrier to spending is lower, so you’re more likely to make impulse purchases.

Retailers love this. Studies show that shoppers spend more when BNPL is available. That’s great for their bottom line, but not always for yours. If you regularly use BNPL, it’s worth asking yourself: are you buying because you need something, or because it’s easy to delay the cost?

6. Lack of Consumer Protections

Traditional credit cards come with a host of consumer protections, including dispute resolution and fraud protection. Many buy now, pay later services don’t offer the same safety nets. If your item never arrives or doesn’t match the description, getting your money back can be a hassle.

Some BNPL providers have their own policies, but they may not be as robust as those offered by credit card networks. Before you choose BNPL over a credit card, weigh the risks. You might find yourself stuck paying for something you never received.

What You Can Do to Avoid the Buy Now, Pay Later Trap

The buy now, pay later trap is easy to fall into, but you can avoid it with some practical steps. First, treat every BNPL offer as a loan. Ask yourself if you’d still make the purchase if you had to pay the full amount today. If the answer is no, it’s probably not worth it.

Keep a list of any BNPL accounts and payment schedules. Set reminders so you never miss a due date. Most importantly, don’t use BNPL to buy things you can’t afford. Remember, every payment is a future obligation. If you’re struggling with debt, consider reaching out to a nonprofit credit counselor for guidance.

How has using buy now, pay later services affected your finances? Share your experience in the comments below!

What to Read Next…

  • The Benefits Of Taking Personal Loans And Their Impact On Credit Scores
  • Are Budgeting Apps Designed To Push You Into Debt?
  • 5 Things That Instantly Decrease Your Credit Score By 50 Points
  • 7 Hidden Fees That Aren’t Labeled As Fees At All
  • 7 Financial Loopholes That Lenders Exploit Behind The Scenes
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Finance Tagged With: buy now pay later, credit, Debt, Hidden Fees, Personal Finance, Spending Habits

5 Bank Fees That Are Secretly Draining Hundreds From Your Account Annually

October 11, 2025 by Catherine Reed 2 Comments

5 Bank Fees That Are Secretly Draining Hundreds From Your Account Annually
Image source: shutterstock.com

You might think your money is safe sitting in a checking or savings account, but the truth is, many banks quietly chip away at your balance through small, recurring charges. These sneaky costs can add up to hundreds of dollars every year without you even noticing. From overdraft charges to maintenance fees, many customers pay more in unnecessary bank fees than they realize. The good news? Once you know where these hidden costs lurk, you can take steps to stop the drain and keep more of your hard-earned money.

1. Monthly Maintenance Fees Add Up Faster Than You Think

One of the most common and costly bank fees comes in the form of monthly maintenance charges. Many traditional banks charge $5 to $25 per month simply for holding your account—unless you meet specific conditions like maintaining a minimum balance or setting up direct deposit. While these amounts may seem small, they can cost you $60 to $300 per year for something that online banks often provide for free. Banks rely on customers overlooking these deductions because they blend in with normal activity. To avoid them, switch to a no-fee account or negotiate directly with your bank for a fee waiver.

2. Overdraft Fees Punish Simple Mistakes

Overdraft fees are some of the most frustrating bank fees, often triggered by small timing errors or forgetfulness. If your account dips below zero—even for a few hours—banks can charge you $30 or more per transaction. That means if multiple payments hit at once, you could face several fees in a single day. Some banks also charge “extended overdraft” penalties if you don’t bring your balance positive within a few days. Avoid this financial pitfall by linking your checking to a savings account for automatic transfers or signing up for overdraft protection alerts.

3. Out-of-Network ATM Fees Chip Away at Savings

When you’re on the go, using an ATM that isn’t part of your bank’s network might seem harmless—but those transactions can get expensive quickly. Most banks charge around $2.50 to $3.50 per withdrawal, while the ATM owner may tack on an additional $3 to $5. That means a single cash withdrawal could cost you up to $8. Over a year, even one or two out-of-network withdrawals per month can easily total $100 or more. The simplest fix is to plan ahead, withdraw cash from your bank’s ATMs, or use a bank that reimburses these fees.

4. Paper Statement Fees Penalize the Old-Fashioned

If you still receive printed bank statements by mail, there’s a good chance you’re paying for them. Many institutions now charge $2 to $5 per month to cover “printing and delivery costs.” While that might sound small, it can total up to $60 a year for a service that’s entirely avoidable. Banks push paper statement fees to encourage digital banking, but some customers simply haven’t realized they can opt out. Switching to e-statements is not only free but also more secure and environmentally friendly.

5. Account Inactivity Fees Hit When You Least Expect It

Account inactivity fees are among the sneakiest bank fees because they target customers who use their accounts infrequently. If your account sits dormant for six to twelve months, some banks charge $10 to $20 per month until activity resumes—or they close the account altogether. This can happen with old savings accounts, unused debit cards, or secondary checking accounts you forget about. Over time, inactivity charges can eat through your balance completely. Avoid them by setting up automatic transfers or small recurring deposits to keep your account active.

Hidden Fees Don’t Stop at the Obvious Ones

Beyond these major categories, banks have a long list of smaller fees that can quietly erode your finances. Foreign transaction charges, early account closure fees, wire transfer costs, and balance inquiry charges can all add up, especially for frequent travelers or small business owners. Even mobile deposit limits can lead to extra charges if you exceed them. The key to minimizing these losses is awareness—read your bank’s fee schedule carefully and check statements regularly for anything unexpected. If something looks off, contact your bank immediately to dispute or clarify the charge.

How to Protect Yourself from Costly Bank Fees

Staying vigilant is your best defense against unnecessary bank fees. Start by reviewing your account’s terms and switching to fee-free or online-only banks that offer better transparency. Setting up alerts for low balances or large withdrawals helps you stay in control and avoid penalties. You can also link accounts strategically to cover shortfalls or maintain required balances. Taking a few minutes each month to review your transactions can save you hundreds by year’s end.

Knowledge Is Your Best Financial Shield

Banks count on customer inattention to keep their fee revenue flowing. But once you understand how these hidden costs work, you can make smarter choices that keep your money where it belongs—earning interest, not paying penalties. By choosing low-fee institutions, automating smart alerts, and monitoring your statements, you can stop the slow leak of bank fees once and for all. A little awareness can go a long way toward building financial peace of mind—and that’s worth far more than any convenience a fee-based account might offer.

Have you ever caught your bank charging hidden fees? How did you handle it? Share your experience and advice in the comments below!

What to Read Next…

  • How Can Small Banking Errors Snowball Into Huge Losses
  • 6 Banking Terms That Invalidate Joint Ownership Intentions
  • What Are the Hidden Dangers of Digital-Only Banking?
  • Privacy Settings You Should Never Ignore on Banking Apps
  • Could Social Media Habits Be Hurting Bank Accounts
Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.

Filed Under: Banking Tagged With: bank fees, budgeting, checking accounts, financial advice, Hidden Fees, money management, Personal Finance, savings tips

7 Outrageous Costs Hiding in Funeral Packages

October 1, 2025 by Travis Campbell Leave a Comment

funeral
Image source: pexels.com

Planning a funeral can be overwhelming, especially when you’re already dealing with grief. Most people don’t realize how expensive funeral packages can get until it’s too late. Many funeral homes bundle services together, making it hard to see what you’re actually paying for. Hidden fees and unnecessary add-ons can drive up the total cost quickly. Understanding these exorbitant costs in funeral packages can help you make more informed choices and avoid overspending during a difficult time.

1. Embalming and Body Preparation Fees

Embalming is often presented as a must-have in funeral packages, but it’s not always legally required. Some states only require embalming if there’s a public viewing or if the body isn’t buried within a certain timeframe. These fees can range from $500 to $1,200 or more. If you’re opting for direct cremation or a closed-casket service, you might not need embalming at all. Always ask what’s necessary and what’s optional before agreeing to these costs.

2. Casket Markups

The casket is usually the biggest single expense in funeral packages. Funeral homes often mark up caskets by hundreds or even thousands of dollars compared to what you’d pay from a third-party retailer. Some packages include a “standard” casket, but upgrading to a more attractive model can add a significant cost. You have the right to buy a casket from elsewhere, so don’t feel pressured to purchase directly from the funeral home.

3. Vault and Grave Liner Charges

Many cemeteries require a burial vault or grave liner to prevent the ground from sinking. Funeral homes often include these in funeral packages, but at a hefty markup. Prices can range from $900 to over $3,000. Some families don’t realize this isn’t always required by law, but by the cemetery itself. Before you agree, contact the cemetery directly to clarify their policies and see if you can shop around for better prices.

4. Pricey Memorial Stationery

Memorial folders, guest books, and printed prayer cards may seem like small expenses, but they quickly add up in funeral packages. Some homes charge $150 or more for basic stationery sets. You can often print these yourself or order online for a fraction of the cost. Don’t assume everything in the package is a necessity—ask for an itemized list and consider which items are significant for your family.

5. Transportation and Hearse Fees

Moving the body from one place to another involves several steps, and each one may incur a separate fee in funeral packages. The hearse, family limousine, and transfer vehicles are often marked up for a premium. Some packages even include charges for moving the body from the funeral home to the cemetery, even if it’s nearby. Always ask for a breakdown of transportation costs, and see if you can eliminate or combine services to save money.

6. Unnecessary Cosmetic Services

Cosmetic services, such as hairstyling and makeup, are often included in funeral packages, especially for open-casket services. While these services can help loved ones say goodbye, they’re not always needed. Fees for cosmetic preparation can range from $100 to $500. If you prefer a closed-casket service or direct cremation, you can skip these services and save significantly. Be clear about your wishes so you don’t pay for extras you don’t need.

7. Overpriced Flowers and Tribute Items

Funeral homes frequently offer floral arrangements and tribute items as part of their packages. Prices for these items are often much higher than what you’d pay at a local florist or online. A single arrangement can cost $200 or more. Some packages also include keepsakes or candles at inflated prices. You can provide your own flowers or tributes to honor your loved one without the markup.

How to Take Control of Funeral Package Costs

Outrageous costs in funeral packages can catch even the savviest planner off guard. The key is to ask for an itemized price list and question every fee. Funeral homes are required by law to provide a General Price List (GPL) that breaks down each service and product. Don’t be afraid to shop around, compare prices, or decline items you don’t want. You have the right to customize funeral packages to fit your needs and budget.

Planning ahead and discussing your wishes with family can also help avoid unnecessary expenses. By understanding the most common outrageous costs in funeral packages, you can make informed choices that honor your loved one without breaking the bank.

Have you encountered unexpected costs in a funeral package? Share your experiences and tips in the comments below.

What to Read Next…

  • 8 Funeral Costs That Catch Families Off Guard Every Year
  • 5 Premium Funeral Plans That Can Scam Families Out of Thousands of Dollars
  • 10 Things People Don’t Realize Will Be Taxed After They Die
  • 10 Money Mistakes People Make After Losing a Spouse
  • 7 Retirement Perks That Come With Shocking Hidden Costs
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Budgeting Tagged With: consumer tips, end-of-life planning, funeral costs, funeral packages, Hidden Fees, Personal Finance, saving money

10 Financial Traps Hidden in Cell Phone Contracts

September 26, 2025 by Travis Campbell Leave a Comment

phone
Image source: pexels.com

Cell phone contracts are designed to look straightforward, but many people find themselves paying much more than expected. Hidden fees and confusing terms can sneak up on even the savviest consumers. Understanding the financial traps in cell phone contracts can help you avoid frustrating surprises and save money in the long run. Before you sign a new agreement, it’s important to know what to watch for. Let’s break down the most common financial traps hidden in cell phone contracts and how you can sidestep them. If you want to keep your monthly bills predictable and fair, this guide is for you.

1. Early Termination Fees

One of the most common financial traps in cell phone contracts is the early termination fee. These charges can be hefty, sometimes running into hundreds of dollars if you decide to cancel your contract before it ends. While some companies prorate these fees, others do not, leaving you with a significant bill if your needs change unexpectedly. Always check the fine print to see how much you’d owe if you need to leave your contract early.

2. Device Payment Plans

Device payment plans may seem like a convenient way to get the latest phone without paying up front. However, these plans often come with high interest rates or hidden fees buried in the contract. If you decide to switch carriers or cancel your service, you might be required to pay off the device balance in one lump sum. This can create financial stress if you’re not prepared. Always calculate the total cost of the device over the life of the plan before agreeing.

3. Data Overage Charges

Many cell phone contracts include a set amount of data each month. Exceeding your data limit can lead to expensive overage charges, sometimes doubling your bill. Some carriers automatically bump you up to a higher data tier if you go over, while others simply add steep fees. Be sure to understand exactly how your plan handles data usage so you can avoid this financial trap in cell phone contracts.

4. Automatic Contract Renewals

Some cell phone contracts renew automatically at the end of the term unless you actively cancel or renegotiate. This can lock you into another year or two of service, sometimes with new fees or less favorable terms. Set a calendar reminder to review your contract before it renews, so you have a chance to shop around or negotiate better terms.

5. Hidden Administrative Fees

Administrative fees, regulatory recovery fees, and other surcharges often appear on your monthly bill. While these fees are usually small, they add up quickly and are rarely advertised up front. Carriers often justify these charges as necessary for regulatory compliance, but in reality, they’re often just extra profit. Scrutinize your bill for recurring charges you don’t recognize and ask your provider to explain each one.

6. International Roaming Costs

Traveling abroad with your phone can result in unexpected charges. International roaming rates are notoriously high, and some contracts don’t make it clear what you’ll pay for calls, texts, or data outside your home country. Even a short trip can result in a bill that’s several times your usual monthly payment. Look for plans with international options or consider using a local SIM card when traveling.

7. Promotional Pricing That Expires

Carriers love to entice new customers with promotional rates, but these discounts often expire after a few months. When the deal ends, your monthly payment can jump dramatically. If you’re not prepared, this can be a nasty shock. Always find out how long promotional pricing lasts and what your bill will be when it ends. Don’t sign a cell phone contract unless you’re comfortable with the regular price.

8. Mandatory Add-Ons and Bundled Services

Some contracts require you to purchase add-ons or bundled services you may not need, like insurance, streaming subscriptions, or cloud storage. These extras can inflate your monthly bill and are often hard to remove later. If a contract includes mandatory add-ons, ask if you can opt out or choose your own services. Don’t pay for features you won’t use.

9. Credit Checks and Security Deposits

Signing a cell phone contract often requires a credit check. If your credit isn’t perfect, you might be asked to pay a security deposit. These deposits can be substantial and are sometimes difficult to get back, especially if you cancel early or if there’s a dispute over your final bill. If you’re concerned about your credit, look for prepaid or no-contract plans that don’t require a deposit.

10. Contract Changes Without Notice

Some providers reserve the right to change your contract terms, fees, or services with little or no notice. This can leave you stuck with higher costs or reduced features. Always read the section about contract modifications and ask your provider how changes will be communicated. If possible, choose a provider that offers a clear, written notice of any changes to your cell phone contract.

Smart Strategies for Navigating Cell Phone Contracts

Understanding the financial traps in cell phone contracts is the first step to protecting your wallet. Take the time to read every detail, ask questions, and compare offers from multiple providers. Don’t be afraid to walk away if a contract feels one-sided or confusing.

It’s also smart to check out the FTC’s advice about marketing and contract rules if you want to know your rights. By staying alert to these financial traps in cell phone contracts, you can avoid costly mistakes and keep your monthly expenses under control. What’s the biggest contract surprise you’ve ever faced? Share your experience in the comments below!

What to Read Next…

  • What Happens to Your Credit Score If Your Cell Provider Changes Ownership
  • 7 Hidden Fees That Aren’t Labeled as Fees at All
  • Are These 8 Money Saving Tricks Actually Keeping You Broke
  • 8 Everyday Services That Are Slowly Becoming Subscription Only
  • 7 Credit Card Features Disappearing Without Any Notice
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Finance Tagged With: cell phone contracts, consumer advice, data overage, early termination, financial traps, Hidden Fees, mobile plans

9 Sneaky Costs That Appear When Kids Leave for College

September 26, 2025 by Travis Campbell Leave a Comment

college
Image source: pexels.com

Sending your child off to college is a proud milestone, but it often comes with a price tag that goes well beyond tuition and textbooks. Many parents focus on the big expenses, but the true cost of college includes a surprising number of hidden fees and unexpected bills. These sneaky costs can catch families off guard, straining budgets and causing stress just when you want to focus on your child’s next big step. If you’re not prepared, you might find your monthly expenses creeping up in ways you didn’t expect. Understanding these hidden college costs in advance can help you make smarter financial decisions and avoid headaches down the road.

1. Dorm Room Must-Haves

Colleges often provide a simple bed, desk, and chair—but your student will need much more to feel at home. Bedding, storage bins, lamps, rugs, kitchen gadgets, and décor can quickly add up in cost. Even basics like a mini fridge or microwave are rarely included. Retailers target college-bound families with “dorm essentials” lists, encouraging them to overbuy. Before you know it, you’re spending hundreds to outfit a small room. To manage these hidden college costs, make a list, stick to essentials, and consider secondhand options or sharing larger items with roommates.

2. Meal Plan Gaps and Eating Out

Most college meal plans don’t cover every meal, especially weekends or late-night cravings. Students often supplement with snacks, takeout, or coffee runs. Even a few extra meals out each week can add up to significant spending over a semester. If your child is living off-campus, the cost of groceries and occasional restaurant meals can be even higher. Budgeting for these non-tuition expenses is crucial to avoiding credit card debt and maintaining your student’s health.

3. Transportation and Travel

Getting to and from campus isn’t always as simple as hopping in the car. Flights, bus tickets, or train rides add up, especially if your student attends an out-of-state school. Parking permits, ride-sharing, and gas for trips home during breaks are common hidden college costs. If your child brings a car, don’t forget insurance, maintenance, and campus parking fees. Planning ahead for travel can help you avoid last-minute, expensive bookings.

4. Technology and Subscriptions

Colleges expect students to have laptops, printers, and sometimes even tablets or specialized software. These aren’t always included in tuition, and tech can break or need upgrades. Add on streaming services, cloud storage, and digital textbooks, and you’re looking at a steady stream of extra expenses. Check with your child’s school for student discounts, and review which tech is truly necessary to keep hidden college costs under control.

5. Health and Wellness Fees

Most colleges charge mandatory health center fees, but those don’t cover everything. Prescription medications, over-the-counter supplies, and unexpected doctor’s visits can catch families off guard. Some schools require students to carry their health insurance, which may not be included in tuition. If your plan doesn’t cover out-of-state care, you might face higher out-of-pocket costs. Research what’s included and budget for extras to avoid surprises.

6. Laundry and Cleaning Supplies

Laundry is rarely free on campus. Washing and drying each load can cost several dollars, and the expenses add up quickly over a semester. Don’t forget detergent, dryer sheets, and quarters (or laundry cards). Cleaning supplies for dorm rooms and apartments—like vacuum rentals, disinfectant wipes, or trash bags—are rarely provided. Factoring these into your budget helps prevent last-minute scrambles and extra spending.

7. Social and Club Expenses

Getting involved in campus life is important, but clubs and activities often come with fees. From Greek life dues to club sports or theater productions, participation costs can be significant. Even “free” events may include requests for donations or additional purchases. Encourage your student to prioritize activities and look for low-cost ways to engage without letting hidden college costs spiral out of control.

8. Course Materials and Lab Fees

Textbooks are notoriously expensive, but many courses require additional materials, such as lab kits, art supplies, or access codes for online homework. Some classes have mandatory field trips or equipment rentals. These costs can sneak up, especially if course syllabi aren’t available until after classes begin. Shop early, compare prices, and consider used or digital options to save money.

9. Changing Household Expenses at Home

It’s easy to assume your household bills will drop when your child leaves, but that’s not always true. You might find yourself sending care packages, paying for extra cell phone data, or keeping the thermostat higher when they visit. Some parents keep their child on their car insurance or cover other shared expenses. These changes are subtle, but they add to the total hidden college costs families face.

Planning Ahead Makes a Difference

The real price of sending a child to college is more than tuition and room and board. Hidden college costs pop up in every corner, from the dorm room to traveling home for holidays. By anticipating these expenses, you can build a more accurate budget and avoid financial stress. Discuss openly with your student the difference between needs and wants, and maintain open communication lines as new expenses arise.

What sneaky costs surprised you when your child went to college? Share your experiences in the comments below!

What to Read Next…

  • 10 Services Adult Children Regret Paying for Their Parents
  • Are These 7 Little Expenses Quietly Costing You Thousands a Year?
  • 6 Monthly Bills You Should Cancel Immediately Even If You Can Afford Them
  • 10 Ways You’re Wasting Money Just Trying to Keep Up Appearances
  • 7 Retirement Perks That Come with Shocking Hidden Costs
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: parenting Tagged With: budgeting, college costs, Hidden Fees, parenting, Personal Finance, student life

8 Outrageous Fees That Appear on Bank Statements

September 26, 2025 by Catherine Reed Leave a Comment

8 Outrageous Fees That Appear on Bank Statements
Image source: 123rf.com

Opening your account online or reviewing your monthly paperwork should give you peace of mind, not frustration. Yet for many people, the sight of surprise charges on bank statements can feel like a financial ambush. Banks may advertise convenience and safety, but behind the scenes, hidden costs quietly eat away at your balance. These fees often appear small at first glance but add up over time, creating unnecessary financial strain. Let’s look at some of the most outrageous fees that sneak into everyday banking.

1. Overdraft Fees That Multiply Quickly

One of the most common complaints about bank statements is overdraft fees. When you accidentally spend more than you have, banks charge anywhere from $25 to $40 per occurrence. The problem is that these fees can multiply if multiple transactions go through while your account is negative. In some cases, customers end up paying more in fees than the original purchase amount. It’s a costly reminder of why monitoring your balance is so important.

2. ATM Fees for “Convenience”

Using an out-of-network ATM can feel harmless until you see the charge on your bank statements. You’re often hit with two fees—one from your bank and one from the machine owner. These small charges, usually $3 to $6, can add up if you withdraw cash frequently. Banks market their ATM networks as a convenience but punish you for stepping outside them. Planning ahead to use in-network machines can help you avoid these sneaky costs.

3. Monthly Maintenance Charges

Some accounts quietly slip in maintenance fees unless you meet certain requirements. If your balance drops too low or you don’t set up direct deposit, you might find a $10 to $25 charge on your bank statements. These fees can feel insulting, especially when the bank profits from holding your money. It’s their way of rewarding loyalty only when you follow specific conditions. Choosing accounts with no maintenance requirements can save you significant money each year.

4. Paper Statement Fees

Want to receive physical copies of your bank statements in the mail? Many banks now charge $2 to $5 per month for the privilege. They frame this as promoting “eco-friendly” behavior, but it’s really a revenue tactic. While going digital is smart for most people, some customers prefer paper records for organization. Charging for a basic service that was once standard feels outrageous.

5. Foreign Transaction Fees

Travelers often notice unfamiliar charges when they return home and review their bank statements. Foreign transaction fees are typically 1% to 3% of each purchase made abroad. Even online purchases from international retailers can trigger these charges. While the percentage may seem small, it adds up quickly on big-ticket items. Using a credit card with no foreign transaction fee is often a smarter choice for travelers.

6. Inactivity Penalties

Believe it or not, some banks punish you for not using your account enough. If an account remains inactive for several months, inactivity fees may suddenly appear on your bank statements. These charges are meant to push customers to close dormant accounts or resume activity. Unfortunately, they often penalize people who were simply saving money quietly. Checking account terms before leaving funds untouched is the best defense.

7. Wire Transfer Fees

Sending or receiving money via wire transfer is often marketed as quick and reliable. However, the fees you’ll see on your bank statements can be shocking. Outgoing transfers may cost $25 to $50, while even incoming wires can carry a charge. Considering these transfers are mostly automated, the high price is hard to justify. Whenever possible, explore alternative methods like ACH transfers or payment apps to cut costs.

8. Account Closing Fees

Yes, some banks even charge you for leaving. If you close an account within a certain timeframe, usually 90 to 180 days, you might face an early closure fee. These charges on bank statements feel particularly frustrating because they penalize customers for making financial choices that work best for them. It’s another way banks try to lock you into accounts that may not serve your needs. Reading fine print before opening an account helps you avoid this trap.

Taking Control of Your Money

Bank statements shouldn’t feel like riddles filled with hidden costs. By understanding the most common outrageous fees, you can take steps to avoid them and keep more of your hard-earned money. Whether it’s switching to a no-fee account, choosing smarter travel cards, or monitoring your activity more closely, the key is staying informed. Banks rely on customers overlooking the small print and ignoring recurring charges. Protecting your finances starts with reviewing every line of your statements and questioning what doesn’t feel right.

Have you ever spotted a fee on your bank statements that caught you by surprise? How did you handle it? Share your experience in the comments.

What to Read Next…

9 Hidden Costs of Switching Banks Nobody Warns You About

5 Outrageous Fees Hidden in Everyday Banking Services

8 New Tools That Collect Bank Info Through Pop-Ups

7 Surprising Risks of Keeping Too Much Cash at Home

Why Do Some People Lose Money by Keeping Too Much in Cash

Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.

Filed Under: Banking Tagged With: ATM Fees, bank statements, banking tips, financial literacy, Hidden Fees, overdraft charges, saving money

6 Financial Risks Hiding in Timeshare Contracts

September 21, 2025 by Travis Campbell Leave a Comment

timeshare
Image source: pexels.com

Timeshare contracts might look like a ticket to affordable vacations, but they often come with hidden pitfalls that can hurt your wallet. Many buyers get swept up by the promise of a lifetime of getaways, only to find themselves locked into complex agreements. The true cost of a timeshare isn’t always clear at first glance, and the fine print can lead to unexpected surprises. If you’re considering a timeshare, it’s essential to understand the financial risks before you sign on the dotted line. This guide breaks down the most common financial risks in timeshare contracts, so you can make an informed decision and avoid long-term regrets.

1. Ongoing Maintenance Fees

One of the most significant financial risks in timeshare contracts is the obligation to pay ongoing maintenance fees. These fees aren’t just a one-time cost—they recur every year, regardless of whether you use your timeshare. Over time, these payments can add up to far more than the original purchase price.

Worse, the contract usually allows the management company to raise these fees. This means your yearly payments can increase unexpectedly, straining your budget. If you’re not prepared for rising costs, you could end up regretting your purchase. Always read the fine print and ask for a detailed schedule of anticipated fees before signing any timeshare contract.

2. Difficulty Reselling or Exiting

Timeshare contracts are notoriously difficult to exit. The secondary market for timeshares is flooded, with far more owners looking to sell than buyers interested in purchasing. This makes it hard to offload your timeshare if your financial situation changes or you simply stop using it.

Some contracts contain clauses that make it nearly impossible to walk away without facing hefty penalties. Others may require you to pay fees even after you stop using the property. For many, this is one of the most frustrating financial risks in timeshare contracts. If you think you may want to sell your timeshare in the future, be aware that you could end up stuck with it for years.

3. Special Assessments and Surprise Costs

In addition to regular maintenance fees, timeshare owners can be hit with special assessments. These are one-time charges for unexpected repairs, upgrades, or emergencies at the property. For example, if a hurricane damages the property or a major renovation is needed, owners are often required to split the bill.

Special assessments can be expensive, and you may have little warning before they appear. Because the contract often gives the management company broad authority to levy these fees, you have little recourse if you think the charges are unfair. This unpredictability adds another layer of financial risk to timeshare contracts.

4. Loan Interest and Financing Traps

Many people finance their timeshare purchase with a loan, often provided directly by the timeshare company. The interest rates on these loans are typically much higher than standard mortgages or personal loans. Over time, the cost of borrowing can dramatically increase the total amount you pay for your timeshare.

If you miss payments, you could face late fees, damage to your credit score, or even foreclosure on your timeshare interest. The loan terms are often less favorable than buyers realize, making financing one of the hidden financial risks in timeshare contracts. Always compare loan offers and consider saving up to pay cash, if possible.

5. Limited Usage Flexibility

Timeshares are often marketed as a flexible way to travel, but the reality can be quite different. Many contracts restrict when and how you can use your unit. If your schedule changes or you want to visit during peak times, you may find your options limited—or unavailable altogether.

Exchanging your week for another location can also come with added fees and limited availability. If you can’t use your timeshare as planned, you might still be on the hook for all the associated costs. This lack of flexibility can turn an anticipated vacation benefit into a financial burden.

6. Long-Term Financial Commitment

Perhaps the most overlooked financial risk in timeshare contracts is the long-term nature of the agreement. Many contracts last for decades, and some have perpetuity clauses that extend the obligation to your heirs. This means your family could inherit the responsibility for maintenance fees and special assessments—even if they don’t want the timeshare.

This long-term commitment can limit your financial flexibility and impact your estate planning. Before signing, consider how a timeshare fits into your broader financial goals. Ask yourself whether you want to be tied to a single vacation property for years—or risk passing on a financial liability to your loved ones.

Smart Steps Before Signing a Timeshare Contract

Understanding the financial risks in timeshare contracts is crucial before making any commitment. Take time to research the company, ask detailed questions about all fees, and consult with a financial advisor. Don’t let high-pressure sales tactics rush your decision—remember, you’re agreeing to a long-term financial obligation.

Taking these steps can help you avoid costly surprises and make a choice that supports your financial well-being.

Have you ever faced unexpected costs or challenges with a timeshare? Share your experiences and tips in the comments below!

What to Read Next…

  • 7 Hidden Fees That Aren’t Labeled As Fees At All
  • 6 Financial Traps Retirees Walk Into Without Questioning
  • 10 Warning Signs In Financial Advisor Contracts You Shouldn’t Ignore
  • 7 Financial Loopholes That Lenders Exploit Behind The Scenes
  • 5 Home Investment Plans That Legal Experts Say To Avoid
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.
Filed Under: Finance Tagged With: contracts, financial risks, Hidden Fees, Personal Finance, timeshare, vacation ownership

7 Outrageous Fees That Sneak Onto Credit Card Bills

September 20, 2025 by Catherine Reed Leave a Comment

7 Outrageous Fees That Sneak Onto Credit Card Bills
Image source: 123rf.com

Credit cards are convenient, but they often come with hidden costs that catch people off guard. Many consumers think paying their balance or avoiding interest is enough to stay safe, but that’s rarely the full picture. Lurking in the fine print are fees that can quietly inflate monthly statements. These extra charges may seem small at first but can snowball into hundreds of dollars over time. Here are seven outrageous fees that sneak onto credit card bills and drain your wallet if you’re not careful.

1. Late Payment Fees

One of the most common culprits on credit card bills is the late payment fee. Even if you’re just a day late, issuers can tack on a hefty charge, often around $30 to $40. Repeated offenses may cause the fee to climb even higher. These charges hit especially hard if your balance is small, making the penalty feel disproportionate. Staying on top of due dates is the only way to avoid this frustrating expense.

2. Over-the-Limit Fees

While many credit card companies have phased these out, some still charge over-the-limit fees if you spend past your credit limit. These fees can run $25 to $35 per occurrence. What makes them tricky is that the purchase itself may still go through, leaving cardholders unaware until they see the bill. It’s essentially a penalty for borrowing more than you should. Monitoring balances closely helps keep this fee from sneaking onto your credit card bills.

3. Foreign Transaction Fees

Travelers often get hit with foreign transaction fees without realizing it. These charges, usually around 3% of each purchase, apply whenever you buy something in a foreign currency or through an international vendor. Over the course of a trip, these small percentages add up quickly. Even online purchases from international retailers can trigger them. Using a travel-friendly card without these charges is the best defense.

4. Cash Advance Fees

Withdrawing cash from an ATM using your credit card may feel convenient, but it comes at a steep price. Cash advance fees are typically 3% to 5% of the amount withdrawn, with added interest rates that start immediately. Unlike normal purchases, there’s no grace period for repayment. This means you’re paying more in both fees and interest from day one. Cash advances are one of the costliest traps hidden in credit card bills.

5. Balance Transfer Fees

Many cards lure consumers with low or zero-interest balance transfer offers. However, the fine print often includes a transfer fee of 3% to 5% of the amount moved. On large balances, this fee can equal hundreds of dollars upfront. While the transfer may still save money compared to high interest, it’s not as free as it appears. Always factor in this fee before using balance transfers as a debt solution.

6. Returned Payment Fees

If your payment bounces because of insufficient funds, your credit card company may charge a returned payment fee. These can be as high as $40, punishing you for an already stressful mistake. On top of that, your bank may also charge a separate overdraft fee. This double hit makes returned payments one of the most painful charges to see on credit card bills. Keeping a close eye on your bank balance helps prevent this situation.

7. Inactivity Fees

It may sound strange, but some issuers penalize cardholders for not using their accounts. Inactivity fees are charged when your card goes unused for a certain period. While less common today, they still exist and can quietly show up after months of nonuse. Essentially, you’re being charged for doing nothing. Reviewing your account terms ensures you won’t be blindsided by this unnecessary charge.

Knowledge Is Your Best Defense

The truth is, credit card companies count on consumers overlooking the fine print. Each of these fees may seem minor alone, but together they can make credit card bills far more expensive than expected. By reading terms carefully, setting reminders for payments, and choosing cards with fewer hidden costs, you can avoid these pitfalls. Protecting your wallet starts with awareness. The more you know about these outrageous charges, the better prepared you’ll be to fight them.

Have you ever spotted an unexpected fee on your credit card bills that caught you by surprise? Share your experience in the comments below.

What to Read Next…

  • 5 Silent Costs of Ignoring Credit Monitoring
  • Could Owning Too Many Credit Cards Destroy Your Score
  • Why Do Some People Refuse to Use Credit Cards but Still Pay More
  • 5 Sneaky Financial Costs of Cosigning a Loan
  • Why Do People Get Trapped by “Buy Now Pay Later” Schemes
Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.

Filed Under: credit cards Tagged With: credit card bills, credit card tips, Debt Management, financial literacy, Hidden Fees, money management, Personal Finance

Could A Free Trial End Up Costing You Hundreds

September 17, 2025 by Catherine Reed Leave a Comment

Could A Free Trial End Up Costing You Hundreds
Image source: 123rf.com

A free trial sounds like a no-risk way to test a product or service, but the reality is often very different. Many companies rely on sign-ups turning into long-term subscriptions, and they make canceling difficult or confusing. What starts as a \$0 offer can quietly transform into charges that drain your bank account month after month. If you’re not careful, a free trial could end up costing you hundreds before you realize what happened. Knowing the financial traps behind these offers can help you protect your money.

1. Free Trial Offers That Rely on Forgetfulness

Companies know that many people will forget to cancel before the trial ends. A free trial may only last a week or two, and the billing kicks in immediately afterward. Once the first charge appears, consumers often overlook it, especially if it seems small. Over time, those charges add up significantly, leaving you paying for a service you don’t use. Staying organized and tracking trial end dates is the best defense.

2. Free Trial Deals with Hidden Fees

Not every free trial is truly free. Some companies tack on “activation” or “shipping” fees that aren’t disclosed upfront. These small charges may not seem like much, but they can add up quickly if you sign up for multiple trials. Worse, once they have your payment information, companies may slip in additional charges under vague descriptions. Reading the fine print carefully helps you avoid surprise costs that make a free trial expensive.

3. Free Trial Subscriptions That Are Hard to Cancel

A common tactic is making cancellation more difficult than sign-up. While it may take only seconds to start a free trial, canceling might involve multiple phone calls, emails, or complicated web forms. Some companies even require written requests. This friction is intentional and designed to keep you paying longer. If you don’t have the patience to push through the process, the free trial will keep draining your wallet.

4. Free Trial Offers That Turn into Annual Plans

Another sneaky danger is when a free trial automatically converts into an annual subscription. Instead of a manageable monthly fee, you might suddenly see a charge for $200 or more. These upfront costs can be shocking, especially if you didn’t realize the terms of the agreement. Many people don’t dispute the charge because they assume it’s their fault for not reading carefully. Avoiding this pitfall requires double-checking whether a plan renews monthly or yearly.

5. Free Trial Apps That Collect Your Data

The financial cost of a free trial isn’t always obvious. Some companies make money by collecting and selling user data. This includes information like your spending habits, location, and browsing behavior. While you may not see direct charges, the hidden cost is a loss of privacy that can lead to targeted scams or unwanted marketing. Protecting yourself means limiting the personal information you provide when signing up.

6. Free Trial Products That Lock You into Bundles

Sometimes a free trial isn’t for a single service but part of a bundled package. Canceling one product may require canceling the entire bundle, which can be confusing. You may think you’re testing just one feature, only to discover you’ve committed to several linked subscriptions. This makes getting out of the contract more complicated and costly. Always clarify whether the free trial stands alone or is tied to other services.

7. Free Trial Offers with Auto-Renewal Tricks

Auto-renewal is one of the most common ways a free trial ends up costing more than expected. Companies set up automatic billing so that unless you actively cancel, you’re locked in. These renewals may continue indefinitely, slowly draining your account. Even worse, some companies change their terms without clear notice, making it harder to track your expenses. Staying alert to auto-renewal clauses is essential to avoid unwanted charges.

8. Free Trial Periods That Shrink Without Notice

Some companies shorten trial periods after you sign up, reducing the time you thought you had to test the product. For example, an advertised 30-day free trial might quietly become 7 days in the fine print. By the time you notice, you’ve already been charged. This tactic is designed to catch consumers off guard and increase profits. Confirming the actual length of the trial before you sign up prevents this trap.

9. Free Trial Offers with Poor Customer Support

If you run into billing problems, poor customer support can make resolving issues nearly impossible. Some companies intentionally under-staff their support teams to delay cancellations and refunds. This forces consumers to give up, allowing the company to keep their money. A free trial with no real customer support is more likely to turn into a costly headache. Checking reviews before signing up can save you from these situations.

10. Free Trial Subscriptions That Overlap

Signing up for multiple free trials at once can multiply the risks. With different start and end dates, it’s easy to lose track and miss cancellations. The result can be hundreds of dollars in unexpected charges hitting your account at the same time. This overlap creates financial stress and complicates your budget. Managing trial subscriptions carefully avoids this common problem.

Protecting Yourself from Costly Free Trials

A free trial can be a helpful way to test a product, but it also carries hidden financial dangers. From auto-renewals and hidden fees to difficult cancellations, the risks are designed to take advantage of forgetfulness and inattention. Staying proactive—by reading the fine print, setting reminders, and limiting how many free trials you accept—can save you hundreds. Treat every free trial as if it’s a financial decision, because in reality, it is.

Have you ever been stuck paying for a free trial you forgot to cancel? Share your story in the comments below.

What to Read Next…

Why Do Consumers Keep Falling for Subscription Traps

10 Financial Traps People Walk Into After Buying a New House

Why Do Some People Refuse to Budget Until It’s Too Late

5 Unsettling Truths About Payday Loan Companies

10 Money Moves That Look Smart but Lead to Regret

Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.

Filed Under: Spending Habits Tagged With: auto-renewal, Budgeting Tips, Consumer Protection, free trial, Hidden Fees, Personal Finance, subscription traps

  • « Previous Page
  • 1
  • 2
  • 3
  • 4
  • 5
  • 6
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • 10 Tactics for Building an Emergency Fund from Scratch by Vanessa Bermudez
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald

Copyright © 2026 · News Pro Theme on Genesis Framework