• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Career Advice

7 Workplace Benefits Employees Forget to Use Before the Year Ends

October 28, 2026 by Brandon Marcus Leave a Comment

7 Workplace Benefits Employees Forget to Use Before the Year Ends
Year-end benefits reviews can uncover unused health care funds, employer education assistance, retirement matching opportunities, and other workplace perks. Check your plan’s rules and deadlines before assuming a benefit will carry over into the new year – Shutterstock

Your employer might owe you money without actually owing you money. Confusing? Welcome to workplace benefits, where free money, discounted services, and useful perks can hide behind a login screen nobody has visited since open enrollment.

As the year winds down, employees often focus on holiday spending, vacation plans, and whether unused vacation days will disappear. Meanwhile, perfectly legitimate benefits sit untouched in company portals, sometimes with expiration dates attached. Some can cover medical expenses, professional development, and commuting costs. Others can help with student loans or personal challenges.

1. Flexible Spending Account Money That Could Disappear

A health care flexible spending account (FSA) lets eligible employees set aside money from their paychecks for qualified medical expenses, generally using pretax dollars. That money can help cover expenses such as prescription medications, eligible medical supplies, dental treatment, and vision care. The catch? Many health FSAs follow a use-it-or-lose-it rule.

Some plans allow a limited carryover into the following year, while others offer a grace period for spending remaining funds. Your employer’s plan determines which arrangement applies, if any. For 2026, eligible health FSAs can generally allow a maximum carryover of $680, although employers may set a lower limit. Don’t assume your account automatically qualifies for that full amount.

Check your balance and review the eligible-expense list before scheduling anything. A needed eye examination, prescription glasses, or a dental appointment might put existing funds to productive use. Just confirm the expense qualifies and falls within your plan’s deadline. Buying things you don’t need to rescue your balance defeats the purpose of saving money.

2. Dependent Care Benefits Hiding in Payroll

Child care can consume a startling amount of a household budget, yet some employees overlook benefits designed specifically to help pay for it. A dependent care flexible spending account allows eligible workers to use pretax earnings for qualifying care expenses, subject to program rules.

For 2026, the federal tax exclusion for qualifying dependent care assistance increased to $7,500 for eligible single filers and married couples filing jointly, or $3,750 for married people filing separately. Your employer must offer an eligible program, and your circumstances must meet the applicable requirements. Qualifying expenses can include certain child care costs that enable you to work, as well as eligible care for qualifying dependents who cannot care for themselves.

If you already contribute to this account, check your remaining balance and submission deadlines. If you haven’t enrolled, don’t assume you can open an account immediately just because December is approaching. Enrollment rules vary, and an unused balance generally doesn’t roll forward automatically. Also, coordinate dependent care benefits with any child care tax credit you claim, because the same expenses cannot support both tax benefits.

3. Employer Money for Courses and Certifications

Your employer might help pay for a certification, job-related course, or college class. Yet professional development benefits can remain untouched because employees assume reimbursement requires an expensive degree or a lengthy approval process.

Ask whether your company offers tuition assistance, certification reimbursement, conference funding, or a professional development budget. A course that improves spreadsheet skills, prepares you for a recognized certification, or builds management experience might qualify under your employer’s rules. Some programs require advance approval, specific grades, proof of completion, or reimbursement requests within a set period.

The IRS allows qualifying employer educational assistance programs to provide up to $5,250 in tax-free assistance per employee annually under current federal rules. Eligible assistance can include qualifying tuition, books, fees, and certain student loan payments. However, your employer must offer an appropriate program, and the expenses must satisfy its requirements.

Before the year closes, find out whether your company has a remaining budget or a deadline for submitting expenses. A course you planned to take eventually could become more affordable if you use a benefit already available through work.

4. Student Loan Assistance You Never Asked About

Student loan benefits don’t always arrive with a dramatic announcement. Some employers contribute toward eligible education expenses or offer student loan repayment assistance through a qualifying educational assistance program.

The federal tax rules permit eligible employers to provide up to $5,250 in tax-free educational assistance annually under the current limit. That amount covers qualifying educational assistance combined, including eligible student loan payments, rather than providing a separate $5,250 allowance for each category. Your employer must offer the benefit, and its plan determines which payments qualify.

Check your benefits handbook for terms such as student loan repayment, educational assistance, or Section 127. If you find a program, ask whether you need to submit loan statements, verify your account, or enroll separately. A benefit that exists only on paper won’t reduce your loan balance. A completed application might.

5. Retirement Contributions That Could Earn More Employer Money

Retirement planning often gets postponed until retirement feels close enough to worry about. Unfortunately, employer matching contributions operate on payroll schedules, not personal motivation.

If your company matches contributions to a 401(k), check whether you’re contributing enough to receive the full match available under your plan. For example, an employer might match a percentage of your contributions up to a specified portion of your salary. Contributing below that threshold could leave some employer money unclaimed.

The year-end detail worth investigating is matching and vesting. Some employers calculate their match each pay period, while others offer a year-end adjustment called a true-up. If your plan lacks a true-up, reaching your annual contribution limit early could affect matching contributions from later paychecks. Plan rules determine the outcome, so don’t assume every employer handles this the same way.

Review your contribution rate, employer match formula, and remaining paychecks. You may still have time to adjust contributions, although payroll deadlines matter. Also check your employer’s vesting schedule, which determines when matching contributions become yours to keep. Retirement benefits rarely reward guesswork, and a few minutes reviewing your plan could reveal an opportunity worth investigating.

6. Commuter Benefits That Make Getting to Work Cheaper

Parking garages and transit passes have a remarkable talent for draining money without providing much entertainment in return. If you commute regularly, your employer might offer a transportation benefit that makes those expenses less painful.

Qualified commuter benefits can let employees pay eligible transit and parking expenses with pretax earnings. For 2026, the federal exclusion limit reaches $340 per month for qualified transit expenses and another $340 for qualified parking. These are separate categories, not a single combined allowance. Employer contributions may also be available, depending on the program.

The year-end opportunity involves reviewing your elections and planning for next year’s commute. If you expect to return to the office more frequently, your current contribution may no longer cover your transportation costs. If you’re switching to remote work, continuing the same deductions might make little sense.

7. Employee Assistance and Wellness Programs

Some workplace benefits address problems that have nothing to do with retirement accounts or reimbursement forms. Employee assistance programs (EAPs), for example, may offer confidential counseling, referrals, and help navigating personal or work-related challenges.

Depending on the employer’s program, resources might address family stress, financial concerns, substance use, or finding local support services. Some programs also provide limited counseling sessions or access to additional resources. Employers don’t have to offer EAPs under federal law, and available services vary by plan.

Employees sometimes overlook these programs because they associate benefits with something tangible, such as a paycheck contribution or an insurance card. But access to counseling or practical support can have real value, particularly when personal problems start interfering with sleep, concentration, or work.

Check your benefits portal for an EAP, wellness reimbursement, fitness subsidy, or other employer-sponsored program. Some wellness benefits impose annual spending limits or reimbursement deadlines, while others remain available throughout the year. Read the eligibility rules before spending money in anticipation of reimbursement. A gym membership isn’t a bargain if your employer’s program doesn’t cover it.

Your Benefits Deserve a Year-End Review

Workplace benefits aren’t a single package with one universal expiration date. Some accounts have strict spending deadlines, some programs reimburse expenses after you submit documentation, and others simply require an updated election for the coming year.

Start with the benefits that could cost you money if you miss a deadline. Check FSA balances, outstanding reimbursement claims, professional development budgets, and any unused wellness allowances. Then review retirement contributions and commuter elections before your employer’s payroll or enrollment deadlines pass.

A short conversation with human resources can clarify confusing rules, particularly if your company uses a third-party benefits administrator. Ask for the plan documents, eligible-expense lists, and exact deadlines rather than relying on a coworker’s recollection. Benefits can vary even between employees at the same company.

Which workplace benefit has saved you the most money, or which one did you discover embarrassingly late?

You May Also Like…

When Work Becomes Religion: The Cult of Careerism

7 Hidden Costs of Switching Careers in Midlife

Medicare and Employer Coverage Don’t Always Work Together the Way Retirees Expect

Your Employer Picks the Investments in Your 401(k) — What Happens When Workers Say They’re Bad Choices?

Your Employer Cuts Your Pay 20% — Quit, Stay or Start Planning an Exit?
Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Career Tagged With: Career Advice, employee benefits, flexible spending accounts, Personal Finance, retirement planning, student loan repayment, workplace benefits

Your Coworker Makes $20,000 More for the Same Job — What Can You Actually Do?

October 26, 2026 by Brandon Marcus Leave a Comment

Your Coworker Makes $20,000 More for the Same Job — What Can You Actually Do?
A coworker earning $20,000 more can be a reason to review your salary, compare market rates, and negotiate based on your responsibilities and results – Shutterstock
Finding out that a coworker earns $20,000 more for doing the same job can turn an ordinary Tuesday into a very different kind of workday. Suddenly, the salary that seemed reasonable during your last performance review looks a lot less impressive. The difference is not pocket change, either. It amounts to about $1,667 a month before taxes, which could cover a car payment, retirement contributions, or a considerable chunk of the household budget.

Before confronting your manager or updating your résumé during lunch, take a breath. A pay gap deserves attention, but the smartest response starts with figuring out what the numbers actually mean. Your coworker’s salary could give you valuable negotiating leverage, reveal an unfair workplace practice, or expose a compensation system that rewards people differently for reasons nobody bothered to explain.

Find Out Whether the Jobs Are Really Comparable

Two employees can share a job title without sharing the same responsibilities. One marketing manager might oversee a small team, while another manages a national budget and handles executive presentations. Their business cards match, but their jobs may not.

Look beyond titles and compare the work itself. Consider experience, specialized skills, supervisory duties, performance expectations, location, and the date each employee joined the company. A coworker hired during a competitive recruiting period might have negotiated a higher starting salary than someone who accepted an offer several years earlier.

That explanation does not automatically make the gap fair. It simply helps identify what you need to challenge. Write down the responsibilities you handle, the projects you lead, and the results you deliver. If you perform the same work at the same level, you will have a stronger case for reviewing your compensation.

Also, separate base salary from total compensation. A coworker might earn more in salary but receive a smaller bonus, fewer stock awards, or less generous benefits. You still deserve to understand the difference, but comparing the full package gives you a more accurate picture.

Build Your Case Before You Schedule a Meeting

A manager can dismiss a vague complaint about unfair pay much more easily than a well-documented request for a salary review. Preparation turns an emotional discovery into a business conversation, even if the discovery itself felt like a personal insult delivered by a spreadsheet.

Start with your recent accomplishments. Gather examples of projects completed, revenue generated, expenses reduced, customers retained, or responsibilities added since your last raise. Use specific results whenever possible, and connect them to the work your employer values.

Next, research the market rate for your position. Look at comparable openings, reputable salary surveys, and compensation information for similar roles in your industry and region. Check whether the figures describe base pay or total compensation, and pay attention to experience requirements. A salary range for a senior specialist will not help much if your position falls into a different level.

Then identify a realistic salary target. If comparable employees earn substantially more, explain why your responsibilities and results support a higher figure. You do not need to prove that your coworker deserves less. Your objective is to show why your own compensation deserves a closer look.

Ask for a Salary Review Without Making It Personal

The temptation to say, “Why does Alex make $20,000 more than me?” is understandable. It also gives your manager an easy opportunity to turn the meeting into a discussion about Alex instead of your salary.

Keep the focus on your role, your performance, and the company’s compensation standards. You might say that recent compensation information suggests your salary falls below the range for comparable responsibilities. Then ask how the company determines pay and what adjustment would bring your salary in line with the role.

Bring your research and accomplishments, but leave room for an actual conversation. Your manager may explain a salary band, identify a promotion requirement, or acknowledge that your pay has fallen behind. Listen carefully, especially if the explanation introduces criteria you can verify.

If the manager agrees that an adjustment makes sense, ask about the proposed amount and timing. If the answer is no, request specific reasons and measurable steps toward a review. “We’ll revisit this later” sounds pleasant, but it becomes much less useful without a date on the calendar.

Know Which Pay Protections Apply to Your Situation

A $20,000 gap does not automatically prove illegal discrimination. However, certain pay differences can violate federal law, and the reason behind the disparity deserves scrutiny.

The federal Equal Pay Act prohibits sex-based wage discrimination between men and women performing substantially equal work under similar working conditions at the same establishment. Employers can justify certain differences through legitimate factors, including seniority, merit, productivity, or another factor unrelated to sex. Federal laws also prohibit compensation discrimination based on protected characteristics such as race, national origin, age, and disability. The rules differ depending on the law and circumstances.

Pay transparency can help uncover a problem. Under the National Labor Relations Act, most private-sector employees can discuss wages with coworkers, although some workers, including supervisors and independent contractors, fall outside its coverage. An employer generally cannot prohibit covered employees from discussing their pay or punish them for protected wage discussions.

If you suspect discrimination, keep records of relevant salary information, job responsibilities, performance evaluations, and conversations with management. Check your state’s employment laws, too, because additional protections and pay-transparency requirements may apply. You can contact the EEOC or an employment attorney to discuss your circumstances. Filing deadlines can apply, so do not let an internal salary discussion delay a time-sensitive legal inquiry.

Decide Whether This Job Still Deserves Your Loyalty

Sometimes a pay review leads to a raise. Sometimes it reveals that your employer has no intention of correcting the gap, regardless of your performance. That second answer can be frustrating, but it gives you information about your future.

Explore outside opportunities while you assess your options. Review job listings with published salary ranges, talk with recruiters, and compare the full compensation packages available elsewhere. A higher advertised salary may come with weaker retirement benefits, expensive health coverage, or a commute that quietly eats into the increase.

You do not need to resign dramatically to make a point. In fact, quitting before securing another offer can turn a frustrating salary discovery into an unnecessary financial emergency. Keep doing your job professionally while deciding whether the employer offers a credible path toward better pay.

An external offer can sometimes strengthen a negotiation, but only if you are genuinely prepared to leave. Some employers will match it; others will decline, and a counteroffer does not guarantee better long-term prospects. Think about whether the workplace will change after the conversation, not just whether the next paycheck looks better.

A Salary Gap Can Tell You More Than a Paycheck Does

Discovering that a coworker earns $20,000 more can sting, especially if you have spent years accepting modest raises and assuming the company rewards loyalty. Still, the discovery gives you a reason to examine your compensation with fresh eyes.

The goal is not to win a contest against a coworker. It is to make sure your pay reflects your work and that you understand the rules shaping your earnings. Sometimes that means negotiating harder. Sometimes it means finding an employer that values your skills more appropriately.

If you discovered that a coworker earned $20,000 more for comparable work, would you ask your manager for a raise first or start looking for another job?

You May Also Like…

Are You Searching For A Job Or A Career?

The New Career Anxiety Crushing Middle-Class Workers

Losing Your Job After 55 Could Threaten Your Retirement—Why Getting Hired Again Is So Difficult

7 Backup Plans That Can Help You Survive a Sudden Job Loss

7 Dead End Jobs That People Believe Make a Great Career

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Career Advice Tagged With: Career Advice, compensation, employee rights, equal pay, Personal Finance, salary negotiation, workplace pay gap

Losing Your Job After 55 Could Threaten Your Retirement—Why Getting Hired Again Is So Difficult

October 25, 2026 by Brandon Marcus Leave a Comment

Losing Your Job After 55 Could Threaten Your Retirement—Why Getting Hired Again Is So Difficult
Losing a job after 55 can affect retirement savings, health insurance, and Social Security decisions. Comparing salary, benefits, and household expenses can help older workers evaluate their next move without rushing into an expensive mistake – Shutterstock

The hardest part of losing a job after 55 may not be the empty calendar. It may be discovering that employers who valued decades of experience suddenly seem more interested in candidates with fewer gray hairs and smaller salary expectations. Meanwhile, retirement savings need time to recover, health insurance still costs money, and the mortgage has no interest in anyone’s career troubles.

For older Americans, an unexpected layoff can turn a familiar financial plan into a much less comfortable calculation. Finding another job can take longer than expected, and accepting a lower-paying position can affect retirement plans for years. The challenge isn’t simply finding work. It’s finding work that pays enough, offers reasonable benefits, and arrives before financial pressure forces an expensive decision.

A Layoff Can Disrupt More Than a Paycheck

A lost paycheck creates an immediate problem, but the longer-term consequences can be harder to spot. Someone in their late 50s might have planned to work another seven or eight years, using each paycheck to build retirement savings and cover household expenses. A layoff can interrupt both goals at once.

Consider what happens when regular income disappears. Contributions to a workplace 401(k) may stop, employer health coverage may end, and emergency savings can begin covering ordinary bills. Even someone with a respectable retirement balance may feel pressure to withdraw money earlier than planned.

Those withdrawals can reduce the amount available for future expenses and eliminate opportunities for investments to grow. Market conditions and the timing of withdrawals also affect the damage. Meanwhile, a worker who planned to retire at 65 might begin considering retirement at 62 simply because the job search has become exhausting.

That decision can carry lasting consequences. Claiming Social Security before full retirement age generally reduces the monthly retirement benefit, compared with waiting until full retirement age. The size of the reduction depends on the person’s birth year and claiming age. A layoff doesn’t automatically ruin retirement. It does, however, shrink the margin for error, especially when a household has limited cash reserves or substantial monthly expenses.

Why Employers May Overlook Experienced Candidates

An experienced applicant can bring years of problem-solving, industry knowledge, and professional judgment to a job. Unfortunately, hiring decisions don’t always reward those qualities as much as workers expect. Some employers may assume an older candidate expects a higher salary, prefers established routines, or will leave soon for retirement. Others may worry about whether the candidate can learn unfamiliar software or adapt to a changing workplace. These assumptions don’t necessarily reflect the applicant’s actual abilities.

Age discrimination also remains a real concern. Federal law generally protects workers and job applicants aged 40 and older from age discrimination under the Age Discrimination in Employment Act. The law covers many employment decisions, including hiring, although coverage and legal circumstances can vary.

The frustrating part is that bias rarely announces itself in a job posting. An employer probably won’t write, “Seeking someone younger who won’t question our new scheduling software.” Instead, an older applicant may receive repeated rejections without a clear explanation.

Not every rejection involves discrimination. Another candidate might have more directly relevant experience, stronger technical skills, or salary expectations that better fit the position. Still, repeated assumptions about age can narrow opportunities for qualified workers, particularly when employers confuse a long career with an unwillingness to change.

The First Job Offer May Come With a Financial Catch

Suppose a former operations manager earned $95,000 a year and receives an offer for $68,000. The new position solves the immediate problem of having no paycheck, but the household budget still needs a serious rewrite. Housing costs haven’t fallen, utilities remain stubbornly uninterested in career changes, and retirement contributions may become harder to maintain.

A lower salary can also affect the value of a job’s benefits. A position with affordable health insurance, an employer retirement match, and predictable hours might prove more valuable than a slightly higher-paying job without those advantages. Comparing offers requires looking beyond the number printed near the top of the employment contract.

Some older workers also encounter a different challenge: employers may view them as overqualified for positions they would happily accept. A hiring manager might worry that someone with extensive experience will leave as soon as a better opportunity appears. Applicants can address that concern by explaining why the role fits their current goals, rather than pretending their previous responsibilities never existed.

Flexibility can help, but desperation can make a poor offer look attractive. Before accepting a position, calculate the take-home pay, commuting costs, insurance premiums, and retirement benefits. A job that pays less can still be a sensible bridge to retirement. The danger comes from accepting one without knowing how much of the financial gap it actually closes.

Health Insurance Can Make The Job Search More Urgent

For Americans who haven’t reached Medicare eligibility, employer-sponsored health insurance can make a layoff particularly expensive. Losing a job may mean losing coverage just as household income falls, forcing two financial problems onto the same monthly budget. COBRA may allow eligible former employees to continue their existing employer-sponsored coverage temporarily. However, they generally must pay the full premium themselves, plus an administrative fee. That can produce an unpleasant surprise for someone accustomed to seeing only their share deducted from each paycheck.

A Marketplace plan offers another possible route. Losing job-based coverage generally qualifies someone for a Special Enrollment Period, and applicants typically have 60 days after losing coverage to enroll. Depending on household income and circumstances, premium tax credits may reduce the cost. Readers can compare their options through HealthCare.gov.

This decision deserves attention early in the layoff process, not after several weeks of job applications. Health coverage affects the amount of cash a household needs each month, which in turn determines how long savings can last. Someone who understands the available options can make a more realistic decision about salary requirements and how quickly to accept another position.

A Different Job Search Can Protect Retirement Plans

Older applicants don’t need to hide their experience. They do need to make its relevance obvious. A résumé that devotes half a page to responsibilities from 1998 can distract from recent accomplishments, current technical skills, and the problems an employer needs solved today.

Focus on results and relevant experience rather than documenting every promotion. If a job requires project management, budgeting, customer relationships, or staff training, highlight concrete examples of those abilities. Keep software skills current and describe recent training when it supports the position. The goal isn’t to look younger on paper. It’s to make the hiring decision easier.

Networking can also help uncover openings that never receive much public attention. Former colleagues, professional associations, industry contacts, and local workforce development programs may offer leads or training opportunities. Temporary assignments, consulting, and contract work can provide income while someone pursues a longer-term position, although these arrangements may not include benefits or steady hours.

Meanwhile, avoid treating Social Security as an automatic emergency fund. Eligible workers can claim retirement benefits starting at 62, but claiming before full retirement age reduces the monthly benefit. The Social Security Administration explains the rules and provides estimates through its retirement benefits guidance. Before making that decision, consider how other income, savings, and expected expenses fit together.

Protect The Years You Still Have Before Retirement

Losing a job after 55 creates a difficult balancing act: find income quickly without making a rushed decision that undermines the retirement years ahead. That doesn’t mean holding out indefinitely for the perfect position. It means comparing realistic options, controlling avoidable expenses, and recognizing which decisions carry consequences beyond the next paycheck.

Retirement plans sometimes need adjusting after a layoff. That can feel unfair after decades of working and saving, but a revised timeline doesn’t automatically mean retirement has failed. A new role, temporary income, or a more gradual transition out of full-time work may help preserve options.

The goal isn’t simply to get hired again. It’s to find a workable path from today’s financial uncertainty to tomorrow’s retirement. That path may look different from the one originally planned, but thoughtful decisions can help keep a difficult career setback from dictating every financial choice that follows.

Have you or someone you know struggled to find a job after 55? What helped, and what surprised you most about the process?

You May Also Like…

Your Doctor Left Your Medicare Network: What Happens to Your Retirement Budget Now?

The Personal Information That Could Put Your Retirement Savings at Risk

Do You Still Pay Federal Taxes on Social Security? What Retirees Should Know Before Filing in 2027

Could You Live on Your Future Retirement Income for 30 Days? Try This Test

Is There Any Way to Get Your 401k Before The Age of 59?

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Retirement Tagged With: 401(k), Age Discrimination, Career Advice, job loss, older workers, retirement planning, Social Security

Your Employer Cuts Your Pay 20% — Quit, Stay or Start Planning an Exit?

October 15, 2026 by Brandon Marcus Leave a Comment

Your Employer Cuts Your Pay 20% — Quit, Stay or Start Planning an Exit?
A 20% salary reduction can mean $15,000 less in annual gross income on a $75,000 salary. Calculate the real monthly shortfall and explore your options before deciding whether to stay or leave – Shutterstock

A 20% pay cut means your employer expects you to do the job for considerably less money. Before handing over a resignation letter, though, figure out what the cut costs, why it happened, and whether your employer deserves another year of your working life.

The math gets ugly fast. Someone earning $75,000 annually would lose $15,000 in gross pay, dropping to $60,000. That’s $1,250 less per month before taxes, retirement contributions, and other payroll deductions enter the picture.

Suddenly, the car payment looks less comfortable, the vacation fund looks fictional, and that grocery bill becomes a much more interesting document. Still, quitting immediately can trade one financial problem for another. The smartest response depends on whether this cut represents a temporary setback, a permanent change, or a warning about the company’s future.

Find Out What That 20% Actually Costs

Start with your take-home pay, not the salary printed on your employment offer. Taxes and payroll deductions mean a 20% gross-pay reduction won’t necessarily shrink your paycheck by exactly 20%. Pull out recent pay stubs and estimate your new net income using the proposed salary.

Next, examine expenses that don’t politely shrink alongside your paycheck. Rent or mortgage payments, insurance premiums, car loans, and childcare costs generally won’t adjust because your employer announced a difficult quarter. A household that comfortably saved $500 monthly might suddenly struggle to cover routine bills.

Consider a worker earning $75,000 who loses $15,000 annually. That worker needs to replace an average of $1,250 in gross monthly income just to restore the former salary. Cutting a few streaming subscriptions won’t bridge that gap, although trimming discretionary spending can buy breathing room.

Calculate the difference between your new take-home pay and essential monthly expenses. Include minimum debt payments, groceries, transportation, utilities, and medical costs. Then check how much cash remains for emergencies, retirement savings, and unexpected repairs. A cut that leaves a healthy surplus presents a different problem from one that forces you to reach for a credit card every month.

Make Your Employer Explain the Decision

Before deciding whether to stay, get the details in writing. Ask whether the reduction affects everyone, only your department, or just your position. Find out when it starts, whether it has an end date, and whether your employer expects to restore salaries later. The explanation matters because different problems call for different responses. A company facing a temporary cash crunch might offer a credible recovery plan. A business losing customers while executives promise everything will soon improve deserves closer scrutiny. Neither a reassuring speech nor a gloomy announcement tells the whole story.

Ask what happens to your responsibilities, working hours, bonuses, commissions, and benefits. If your employer expects the same workload and performance targets for substantially less money, ask why. If the company reduces your hours alongside your salary, calculate whether the arrangement leaves enough income to justify staying.

You can also negotiate. Propose a smaller reduction, a temporary pay cut with a written review date, fewer responsibilities, or a defined return to your previous salary if business improves. Your employer might reject every option, but a specific counteroffer gives both sides something concrete to discuss.

Pay attention to how management responds. Clear answers and documented commitments offer more useful information than vague assurances about loyalty and teamwork. If leadership expects employees to accept a major financial sacrifice without explaining the plan, that tells you something about the working relationship.

Check Whether the Pay Cut Creates a Legal Problem

A pay reduction isn’t automatically illegal in the United States. Federal law generally allows employers to reduce hourly rates prospectively, provided they meet applicable minimum-wage and overtime requirements. State and local laws, employment contracts, union agreements, and other circumstances can impose additional restrictions. U.S. Department of Labor explains the federal rules in its guidance on pay and hour reductions.

The details become especially important for salaried employees classified as exempt from overtime. Those employees must satisfy specific salary and job-duty tests. A reduction in salary can affect exempt status, and employers cannot simply ignore applicable wage and overtime requirements because business has slowed.

Check your offer letter, employment agreement, employee handbook, and any written compensation plan. If your employer changes agreed terms or the reduction appears to violate wage laws, contact your state labor department or an employment attorney. Keep pay stubs and written communications that document the change.

Don’t assume quitting automatically qualifies you for unemployment benefits, either. Eligibility depends on state rules and individual circumstances. A substantial pay reduction might affect the analysis, but it doesn’t guarantee benefits. Before resigning, check your state’s requirements and ask the relevant agency how a voluntary departure could affect your claim.

Decide Whether Staying Buys You Anything

A job offers more than a salary, although a salary does most of the heavy lifting. Employer health insurance, retirement contributions, paid leave, predictable hours, and flexibility can all affect the real value of your compensation. Compare the revised package with what another employer might offer, rather than judging the decision on salary alone.

Consider someone who works remotely, enjoys excellent health coverage, and has a manageable workload. A pay cut might still leave that person better off than a new job with a longer commute, higher childcare costs, and less flexibility. Someone facing a smaller paycheck and heavier responsibilities has fewer reasons to wait around.

Your financial cushion also matters. Several months of essential expenses in savings can give you more freedom to search for a better position. Without that cushion, leaving immediately could force you to accept the first available offer, even if the new job creates problems of its own.

Look at your prospects inside the company, too. Does your employer have a credible plan to recover? Could a transfer, promotion, or different role restore your earnings? If the company keeps losing business and offers no measurable path forward, staying may simply postpone an increasingly difficult decision.

Start Your Exit Plan Before You Need One

You don’t have to resign to begin looking. Update your résumé, reconnect with former colleagues, check salary ranges for comparable positions, and apply selectively. A quiet job search can reveal whether the market offers realistic alternatives before you surrender your current income.

Treat interviews as research, not just auditions. Ask about the salary range, benefits, schedule, performance expectations, and reasons the position became available. Compare the entire package with your reduced compensation. A new job that pays more on paper might offer less value after insurance costs, commuting expenses, or lost retirement contributions.

Meanwhile, adjust your budget to reflect the new income if the cut takes effect. Pause optional purchases, review recurring subscriptions, and reconsider major commitments that depend on your old salary. Avoid financing ordinary expenses with credit cards while waiting for management to deliver a promised recovery.

Keep your job search discreet and professional. Save personal copies of your employment records and compensation documents, but don’t take confidential company information. Before accepting an offer, confirm the written compensation terms and start date. If possible, avoid resigning until the new arrangement looks firm. A deadline can help you avoid drifting indefinitely. Set a date to review your savings, job-search progress, and employer’s promises. If management promised a salary review in three months, put that date on your calendar. Hope works better with a calendar reminder.

A Smaller Paycheck Shouldn’t Require Blind Loyalty

A 20% pay cut deserves a serious response, but it doesn’t demand an immediate resignation. Calculate the real shortfall, question the company’s plan, check your workplace rights, and compare the revised job with available alternatives. Those steps replace a decision driven by anger with one grounded in facts.

Your employer has made a decision about what your work is worth to the business. You get to make a separate decision about whether the revised deal works for you. Neither decision requires a dramatic speech in the break room.

Would you stay with an employer after a 20% pay cut, negotiate for better terms, or start looking for another job immediately? Share your reasoning in the comments.

You May Also Like…

Why a $100K Salary Feels Like $40K in 2026

7 Backup Plans That Can Help You Survive a Sudden Job Loss

Job Worries Are Rising: How Many Months of Cash You Need Before Severance and Unemployment Kick In

Your Employer Picks the Investments in Your 401(k) — What Happens When Workers Say They’re Bad Choices?

5 Everyday Purchases That Quietly Add Up to a Month’s Salary

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Lifestyle Tagged With: budgeting, Career Advice, job hunting, Pay Cut, Personal Finance, Salary Reduction, workplace rights

8 Jobs That AI Will Never Be Able to Take Over

May 29, 2026 by Brandon Marcus Leave a Comment

8 Jobs That AI Will Never Be Able to Take Over
Some jobs, such as teachers, should be safe in the age of AI – but are they? – Shutterstock

Artificial intelligence keeps reshaping industries at lightning speed, but not every job fits neatly into an algorithm. Some careers rely on physical presence, emotional intelligence, or split-second human judgment that machines still struggle to replicate.

While automation continues to grow, certain roles stay firmly anchored in human capability. These jobs also offer long-term stability in an uncertain labor market. The list below highlights careers that continue to thrive even as AI expands.

1. Electricians and Skilled Trades Workers

Electricians work in unpredictable environments where every building presents unique wiring challenges. They troubleshoot real-world problems that change from job to job, and no two houses ever tell the same story. AI can suggest solutions, but it cannot safely climb into an attic or crawl through a tight basement space.

These professionals also interpret building codes, physical layouts, and unexpected hazards in real time. One wrong assumption can lead to serious safety risks, so human judgment drives every decision. Skilled trades continue to grow in demand because infrastructure always needs hands-on expertise.

2. Nurses and Hands-On Healthcare Workers

Nurses provide direct patient care that requires emotional awareness, quick thinking, and physical interaction. They monitor subtle changes in condition that often come from observation rather than data alone. AI can support diagnostics, but it cannot comfort a patient during a difficult night.

Hospital environments shift rapidly, and nurses constantly adjust priorities based on urgency and human need. They also communicate with families in emotionally charged situations that require empathy and clarity. Healthcare will always depend on people who combine skill with compassion.

3. Teachers in Early Education and Special Needs

Teachers shape how students learn, grow, and build confidence in real time. They adjust lesson plans based on mood, behavior, and classroom dynamics that change daily. AI tools can assist with learning materials, but they cannot manage a room full of unpredictable human personalities.

Early education especially depends on emotional connection and trust between teacher and student. Special needs education requires constant adaptation and deep personal engagement. Strong teachers influence lifelong development in ways no software can replicate.

4. Firefighters and Emergency Responders

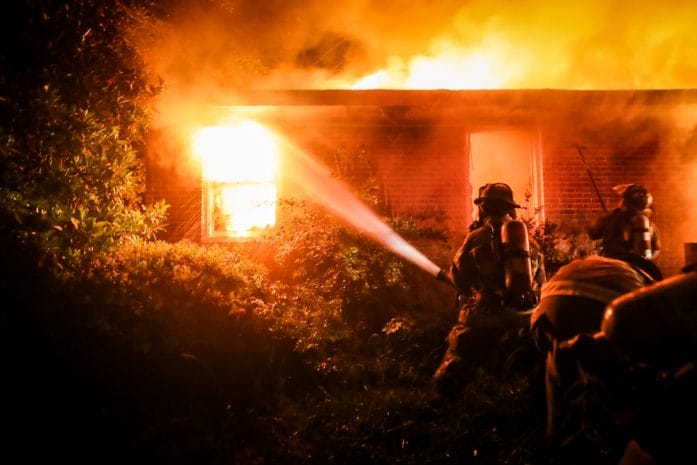
Firefighters face unpredictable danger where every second matters and conditions shift rapidly. They assess structural risks, weather conditions, and human behavior under extreme pressure. AI cannot physically enter a burning building or make split-second rescue decisions.

Emergency responders also coordinate teamwork in chaotic environments where communication must stay clear and immediate. They rely on experience, instincts, and training to save lives in real time. These roles demand courage and presence that technology cannot replace.

8 Jobs That AI Will Never Be Able to Take Over
Sadly, we will always need firefighters, but can AI make an impact on that profession? – Shutterstock

5. Mental Health Professionals and Therapists

Therapists guide people through emotional challenges that require trust, empathy, and deep human connection. They notice tone, body language, and emotional shifts that go far beyond data points. AI chat tools may simulate conversation, but they cannot build genuine therapeutic relationships.

Sessions often involve unpredictable emotional breakthroughs that require careful human response. Mental health professionals also adjust strategies based on lived experience and subtle feedback. Healing conversations rely on presence, not programming.

6. Chefs and Culinary Creators

Chefs transform ingredients into experiences that rely on taste, texture, and creativity. They adjust recipes on the fly based on ingredient quality, customer preferences, and sensory feedback. AI can suggest recipes, but it cannot smell, taste, or plate food with artistic instinct.

Restaurant kitchens also operate under intense pressure where timing and coordination matter. Chefs lead teams, manage chaos, and maintain consistency under stress. Culinary work thrives on human creativity that technology struggles to match.

7. Social Workers and Community Advocates

Social workers handle complex human situations involving families, housing, safety, and emotional distress. They assess real-life circumstances that require compassion and careful judgment. AI can process data, but it cannot walk into a home and build trust with vulnerable individuals.

These professionals also navigate systems like courts, schools, and healthcare providers. Every case involves unique emotional and logistical challenges that demand flexibility. Social work depends on human connection at its core.

8. Artists, Performers, and Creative Professionals

Artists create meaning through expression, emotion, and cultural perspective. They produce work shaped by personal experience, imagination, and social context. AI can generate images or music, but it cannot live a human story.

Performers also connect with audiences through energy, presence, and spontaneity. Every performance changes based on crowd reaction and emotional flow. Creative fields thrive on originality that comes from lived experience.

Why Human Careers Still Hold the Future

Human-centered jobs continue to resist automation because they rely on qualities AI cannot fully replicate. Emotional intelligence, physical presence, and moral judgment drive decisions in unpredictable environments. Many of these roles also involve responsibility for human safety, learning, or well-being. That responsibility requires accountability that machines cannot shoulder. As technology grows, these careers will likely become even more valuable, not less.

What job do you think will stay fully human no matter how advanced AI becomes?

You May Also Like…

Why Banks Are Watching Large Transfers More Closely Than Ever

4 Bold Predictions About The Future of Personal Finance Technology

15 Pieces of Technology Gen Z Can’t Live Without That Are Actually Regressive

11 Careers With Big Money But Zero Appeal

Hidden Hazards: Exploring the Dark Side of Popular Careers

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Technology Tagged With: AI jobs, Career Advice, Education, future of work, healthcare careers, job security, skilled trades, technology trends

4 Moves to Make After a Job Loss in a Tech-Driven Market

March 16, 2026 by Brandon Marcus Leave a Comment

4 Moves to Make After a Job Loss in a Tech-Driven Market
Image Source: Shutterstock.com

A job can disappear overnight, but a career never has to. Technology moves at warp speed, and the job market moves right alongside it. Entire departments shift direction, automation replaces old workflows, and companies reshape their strategies with the push of a button. Headlines regularly highlight layoffs across major firms like Google, Meta, and Amazon, which reminds everyone that even massive tech giants adjust their workforce when the business landscape changes. That reality can feel brutal in the moment, but it also reveals something important about modern work: skills travel farther than job titles.

A sudden job loss might shake confidence for a few days, but it also opens a rare window to reset direction and sharpen a professional strategy. The modern job market rewards people who adapt quickly, build valuable skills, and maintain strong professional networks. A few focused moves can transform an unexpected layoff from a career crisis into a strategic reboot.

1. Regroup Fast and Take Control of the Financial Runway

A sudden job loss delivers an emotional jolt, but the smartest response starts with calm financial clarity. The first step involves mapping out a clear financial runway. That means listing current savings, monthly expenses, severance packages, and unemployment benefits. Many companies provide severance pay or continued health coverage for a limited period, so reviewing those details immediately creates a clearer timeline. Programs administered by organizations like U.S. Department of Labor can provide temporary unemployment benefits that help bridge the gap while the next opportunity develops.

A financial reset does not require panic or extreme lifestyle changes. Instead, smart planning focuses on extending stability. Reducing discretionary spending, pausing large purchases, and adjusting subscription services can stretch savings significantly. Financial advisors often suggest prioritizing essential expenses such as housing, healthcare, and food while temporarily cutting entertainment or travel budgets. That simple shift creates breathing room and removes unnecessary pressure during the job search process.

Once a financial runway appears on paper, the next phase becomes far less stressful. A clear timeline replaces uncertainty with structure. Instead of reacting emotionally to every job listing that appears online, a focused plan allows thoughtful career decisions. That approach helps avoid accepting the first available job simply to stop the financial clock. A carefully managed runway buys time to pursue a position that actually strengthens long-term career prospects.

2. Treat the Job Search Like a Strategic Project

A successful job hunt rarely happens by accident, especially in a technology-driven economy. The strongest candidates treat the job search like a professional project with goals, timelines, and measurable progress. That mindset shifts energy away from frustration and toward purposeful action. A strong starting point involves updating a resume and professional profile to highlight real impact rather than basic job duties. Hiring managers want to see measurable results such as revenue growth, system improvements, cost savings, or project outcomes. A polished professional profile on platforms like LinkedIn dramatically increases visibility to recruiters who search for specific skills. Adding recent accomplishments, certifications, and project highlights helps algorithms surface those profiles to hiring teams more frequently.

Consistency also matters. Setting daily or weekly goals for job applications, networking outreach, and skill development keeps momentum alive. Career coaches often recommend applying to several carefully selected roles each week rather than blasting hundreds of generic applications across the internet. Personalized applications stand out because they demonstrate clear interest in the role and company.

A strategic job search also involves researching industries that continue to grow despite economic uncertainty. Fields like cybersecurity, data analytics, artificial intelligence, and cloud infrastructure continue expanding as organizations digitize operations. Companies across healthcare, logistics, finance, and manufacturing all need professionals who understand modern technology systems. A career pivot within these sectors can unlock new opportunities that did not exist just a few years ago.

4 Moves to Make After a Job Loss in a Tech-Driven Market
Image Source: Shutterstock.com

3. Upgrade Skills Like a Professional Athlete in Training

The technology economy rewards people who constantly sharpen their tools. A job transition creates the perfect opportunity to upgrade skills that increase long-term value in the marketplace. Instead of viewing unemployment as a pause, ambitious professionals treat it like a focused training camp for the next stage of their career.

Online learning platforms now deliver high-quality education from universities and industry leaders around the world. Services like Coursera and Udemy offer courses in programming, data science, project management, cybersecurity, and digital marketing. Many technology certifications can be completed in a matter of weeks, which allows professionals to return to the job market with fresh credentials and updated expertise.

Skill upgrades do not require technical coding knowledge either. Many companies desperately need professionals who can manage complex projects, analyze business data, or translate technical concepts for executive teams. Certifications in project management, data visualization, or digital strategy can dramatically improve hiring prospects. Employers love candidates who demonstrate initiative and curiosity during career transitions.

Real-world practice strengthens those new skills even further. Building a personal portfolio website, volunteering technical help for nonprofits, or contributing to open-source projects can showcase real abilities rather than theoretical knowledge. Hiring managers often appreciate candidates who actively build projects instead of simply listing completed courses. A small portfolio of real work can often speak louder than a long list of credentials.

4. Turn Networking Into a Superpower

Networking often determines how quickly someone lands the next opportunity. Many job openings never appear on public job boards because companies prefer to hire through trusted referrals. Building genuine professional connections dramatically increases access to those hidden opportunities. Reaching out to former colleagues, managers, and industry contacts can open surprising doors. A short message explaining a career transition often sparks helpful conversations or introductions. Professional communities thrive on mutual support, and many people enjoy helping talented professionals land on their feet after unexpected layoffs.

Industry events, virtual conferences, and professional groups also create powerful networking opportunities. Organizations such as TechCrunch events or specialized industry meetups bring together innovators, recruiters, and entrepreneurs who actively seek talented professionals. Participating in those environments often leads to unexpected career opportunities.

Networking works best when approached with curiosity rather than desperation. Asking thoughtful questions about industry trends, technology shifts, or emerging opportunities can spark engaging conversations. Those discussions often evolve into referrals or job leads without feeling forced. Over time, consistent networking builds a powerful professional safety net that protects careers against future market disruptions.

The Comeback Story Starts Right Now

A job loss can feel like a dramatic interruption, but the modern career path rarely follows a straight line anymore. Technology reshapes industries constantly, which means professionals must evolve right alongside those changes. People who respond quickly, sharpen their skills, and maintain strong professional relationships often emerge stronger than before.

A financial reset provides stability. A strategic job search restores momentum. Skill upgrades increase value in the marketplace. Strong networking creates new pathways that never appeared before. Together, those four moves transform an unexpected job loss into a powerful career pivot.

What strategy helped turn a tough career moment into a breakthrough opportunity? Give us your ideas, insights, or personal strategies in the comments.

You May Also Like…

8 Job-Scam Red Flags Everyone Needs to Know in 2025

Are These 6 Trending Jobs Just a Rebranded Pyramid Scheme?

8 Jobs That Let You Work When You Want — and Still Pay Well

11 Careers With Big Money But Zero Appeal

Hidden Hazards: Exploring the Dark Side of Popular Careers

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Career Advice Tagged With: Career Advice, career growth, career pivot, job hunting, job loss, job market trends, job search strategies, networking tips, Personal Finance, professional skills, tech industry layoffs, unemployment advice

7 Phrases to Use When Negotiating a Raise That Almost Always Work

December 8, 2025 by Brandon Marcus Leave a Comment

These Are The Phrases to Use When Negotiating a Raise That Almost Always Work
Image Source: Shutterstock.com

Walking into a raise negotiation can feel like stepping onto a stage you didn’t rehearse for, even if you’ve spent all week practicing in front of your bathroom mirror. Your heart might be pounding, your palms might be sweaty, and suddenly every confidently crafted sentence turns into alphabet soup. But here’s the twist: negotiating isn’t about being perfect—it’s about being prepared with the kinds of phrases that signal confidence, clarity, and undeniable value.

When you have the right wording, the entire conversation shifts from nerve-wracking to empowering. So let’s dig into the seven phrases that can transform your raise request from “I hope this goes okay” to “I’ve got this.”

1. “I’d Like To Discuss My Growth And Compensation Based On The Value I’ve Been Providing.”

This phrase opens the conversation with intention and professionalism, showing that you’re thinking about long-term impact rather than a one-off reward. It immediately frames the discussion around your contributions instead of emotions or personal needs. This signals to your manager that you’ve come prepared with measurable achievements that justify the conversation. It also shifts the tone away from confrontation and toward collaboration, which managers appreciate. When you lead with value, you’re already halfway to a yes.

2. “Over The Past Year, I’ve Taken On Additional Responsibilities That Have Strengthened Our Team’s Results.”

By emphasizing your expanded role, you’re building a case rooted in facts rather than feelings. Managers often overlook how responsibilities quietly pile up, so this phrase brings those shifts into the spotlight. It helps your boss connect your work to the bigger organizational picture. It also primes them to acknowledge that increased responsibility should come with increased compensation. This sentence alone can open their eyes to how much you’ve grown beyond your original job description.

3. “I’d Like My Compensation To Reflect The Impact Of My Performance.”

This phrase is powerful because it’s both assertive and reasonable. You’re not demanding a raise—you’re asking to be compensated in alignment with documented success. It also highlights the cause-and-effect nature of great performance: you’ve delivered results, and now you’re seeking recognition. Managers respect employees who can articulate their worth without sounding entitled. This wording strikes exactly that balance and keeps the negotiation grounded in fairness.

4. “Based On My Market Research, A Competitive Salary For My Role Is Around…”

Referencing market data shows that your request is informed, researched, and aligned with industry standards. Instead of pulling a number out of thin air, you’re backing it with objective benchmarks. This takes the pressure off your manager because it becomes a conversation about market norms rather than personal desires. It also signals that you know your worth and won’t accept being undervalued. When you present external data, you strengthen your position without sounding confrontational.

These Are The Phrases to Use When Negotiating a Raise That Almost Always Work
Image Source: Shutterstock.com

5. “I’m Committed To Continuing To Deliver At A High Level, And This Adjustment Will Help Support My Long-Term Growth Here.”

This phrase reassures your manager that you’re invested in the future of your role and the company. It frames the raise not just as a reward for past work but as fuel for continued performance. Managers love hearing that an employee is thinking ahead and willing to grow with the team. It positions the raise as a smart investment rather than an optional bonus. That subtle shift in perspective can make all the difference in a negotiation.

6. “Can You Help Me Understand What Milestones I’d Need To Meet To Earn This Raise?”

If the answer to your request isn’t immediately yes, this phrase is your golden parachute. It turns a potential rejection into a constructive conversation and gives you a roadmap instead of a dead end. It shows maturity, adaptability, and long-term thinking—three traits every leader values. This approach also puts the responsibility back on your manager to define success clearly, making future negotiations easier. You walk out with clarity instead of confusion, and that alone is a win.

7. “I Appreciate Your Time And Your Support—What Are The Next Steps To Move This Forward?”

Closing with this question keeps the momentum going even if the decision doesn’t happen on the spot. It nudges your manager to clarify timelines, approvals, and follow-up actions. This communicates confidence without pressure, and it ensures the conversation doesn’t drift into limbo. It also shows professionalism and gratitude, both of which leave a strong final impression. Ending with clarity and confidence helps keep the process alive and positions you as someone who handles negotiations with grace.

Your Confidence Is Just As Important As Your Words

Negotiating a raise isn’t about fancy vocabulary or memorized scripts—it’s about choosing phrases that reflect your value, your professionalism, and your commitment to growth. When you use strong, thoughtful wording, you help guide the conversation toward fairness and clarity instead of uncertainty. These phrases open doors, spark constructive dialogue, and give you the footing you need to advocate for yourself effectively. Most importantly, they remind you that your work matters and your voice deserves to be heard.

Have you used any of these lines in your own raise conversations? Share your stories, questions, or negotiation wins in the comments below.

You May Also Like…

How to Transition From Full-Time Work to ‘Semi-Retirement’ Smoothly

7 Obsolete Job Skills That Defined the ’80s Workforce

7 Dream Jobs You Didn’t Know Existed Behind Famous Industries

8 Jobs That Let You Work When You Want — and Still Pay Well

Hidden Hazards: 7 Popular Jobs With Secret Dangers You’d Never Guess


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Workplace & Career Tagged With: asking for a raise, career, Career Advice, job, job hunt, job search, negotiating a raise, promotion, raise, raised wages, salary, work, workplace

5 Income Goals That Professionals Wish They Hit by 35

October 24, 2025 by Travis Campbell Leave a Comment

money goals
Image source: shutterstock.com

Setting clear income goals by certain milestones can make a huge difference in your financial journey. Many professionals find themselves reflecting on what they wish they had achieved by age 35—often realizing they could have aimed higher or planned smarter. Hitting the right income targets early opens doors to more choices, less stress, and a stronger sense of security. If you’re approaching your mid-thirties, or even if you’ve passed that mark, it’s never too late to adjust your financial plan. Let’s look at five income goals that professionals commonly wish they’d reached by 35, and why these targets matter for building long-term wealth.

1. Earning a Consistent Six-Figure Salary

Reaching a six-figure salary is often seen as a key milestone on the path to financial independence. For many professionals, this income goal represents not just higher pay but also career growth, specialized skills, and increased value in their field. Earning $100,000 or more by age 35 can feel like an acknowledgment of your hard work and expertise.

This level of income allows for greater flexibility in budgeting, investing, and saving for major life goals like buying a home, starting a family, or traveling. It also provides a cushion during unexpected life events. While not everyone needs to earn six figures to be successful, many wish they’d set this as a target earlier. If you haven’t reached it yet, consider strategies such as negotiating raises, seeking higher-paying roles, or building new skills to boost your earning power.

2. Building Multiple Streams of Income

Relying solely on one paycheck can feel risky, especially in uncertain economic times. That’s why many professionals set an income goal of adding at least one or two additional income streams by 35. These might include rental income, freelance work, side businesses, or dividend-paying investments.

Having multiple streams of income not only increases your total earnings but also provides a safety net if your main job changes or disappears. It’s a smart way to diversify your financial life and reduce stress. If you’re not sure where to start, explore ways to make money outside your 9-to-5 and see what fits your lifestyle and interests. Even small side hustles can add up over time.

3. Saving at Least One Year’s Worth of Expenses

One of the most practical income goals is to have at least a year’s worth of living expenses saved by age 35. This isn’t just about having money in the bank—it’s about peace of mind. With a solid emergency fund, you can weather job loss, medical emergencies, or even take a sabbatical without immediate financial stress.

To reach this goal, track your monthly expenses and multiply by twelve to see your target savings amount. Consistently setting aside a portion of every paycheck, especially as your income grows, can make this achievable. Professionals who reach this milestone often say it’s one of the most empowering steps on the road to financial independence.

4. Investing 15% or More of Income Annually

Experts frequently recommend investing at least 15% of your pre-tax income each year. By age 35, many professionals wish they’d started investing early and consistently, taking full advantage of compounding returns. This income goal isn’t just about saving—it’s about putting your money to work in the stock market, retirement accounts, or other growth vehicles.

If you’re not sure how to start, consider opening a 401(k), IRA, or brokerage account. Automate your contributions so you don’t have to think about it every month. Over time, investing a steady percentage of your income can build a substantial nest egg.

5. Achieving a Work-Life Balance That Supports Your Income Goals

Income goals aren’t just about the numbers. By 35, many professionals realize that earning more is only valuable if it supports a healthy, balanced life. Chasing ever-higher income can lead to burnout if you’re not careful. The real win is finding a balance where your income supports your values, health, and relationships.

This might mean turning down promotions that require too much overtime, or choosing flexible work arrangements even if they pay a bit less. It’s about using your income to create options, not just obligations. Professionals who achieve this balance early say it leads to greater satisfaction and less regret down the road.

Setting Income Goals for Your Future

Setting and pursuing income goals by your mid-thirties can have a lasting impact on your financial independence and overall happiness. Whether you’re focused on earning a six-figure salary or building multiple streams of income, these targets give you direction and motivation. The earlier you start, the more time you have to enjoy the benefits and adapt as life changes.

Remember, everyone’s path is different. What matters most is choosing income goals that fit your values and support your vision for the future. Which income goal is most important to you, and what steps are you taking to achieve it? Let us know your thoughts in the comments below!

What to Read Next…

  • How Many of These 8 Middle Class Habits Are Keeping You Poor
  • 6 Trends That Suggest the Middle Class Is Dying in Suburbia
  • 10 Signs You’re Living Above Your Means Without Realizing
  • Are These 6 Helpful Budget Tips Actually Ruining Your Finances
  • Are These 8 Money Saving Tricks Actually Keeping You Broke
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Career Advice Tagged With: Career Advice, financial independence, income goals, investing, Personal Finance, Saving, Work–life balance

5 Taboo Topics That Deserve Open Discussion With Family Members

October 20, 2025 by Travis Campbell Leave a Comment

Family money
Image source: shutterstock.com

Every family has its secrets, but some topics are more than just private—they’re downright taboo. Yet, avoiding difficult conversations often leads to confusion, stress, and even resentment. Openly discussing uncomfortable subjects with loved ones can break down barriers and foster trust. When families address these issues head-on, everyone benefits from clearer expectations and stronger relationships. Tackling taboo topics with family members isn’t easy, but it’s essential for long-term harmony and financial well-being.

In this article, we’ll explore five taboo topics that deserve open discussion with family members. These conversations may feel awkward, but they can transform your family’s future and help you avoid misunderstandings. Let’s dive into the essential subjects that shouldn’t stay off-limits.

1. Family Finances

Money is perhaps the most common of all taboo topics that families avoid. Many people grow up believing that talking about family finances is rude or unnecessary. Yet, avoiding these conversations can cause bigger problems down the line. Discussing income, debt, savings, and spending habits helps everyone understand the family’s financial situation. It’s especially important for couples and parents with children who are learning about money management.

Open conversations about family finances can clarify expectations, prevent hidden debt, and teach good habits. For example, being upfront about budgeting for vacations or big purchases ensures there are no surprises. If you’re caring for aging parents or supporting adult children, knowing the full financial picture is crucial. Don’t wait for a crisis, set aside time to talk openly about money, goals, and challenges as a family.

2. End-of-Life Wishes

Few topics make people squirm like discussing end-of-life wishes. But planning ahead is one of the greatest gifts you can give your loved ones. Talking about wills, power of attorney, and healthcare directives can spare your family unnecessary stress if something unexpected happens. It’s not just about dividing assets; it’s about making sure everyone knows your wishes and values.

Start the conversation gently, perhaps by sharing your own wishes or asking about theirs. Explain that discussing end-of-life plans isn’t morbid it’s responsible. The goal is to ensure peace of mind for everyone involved.

3. Mental Health and Emotional Well-Being

Mental health remains one of the most misunderstood taboo topics in many families. There’s often a stigma around discussing depression, anxiety, or other emotional challenges. Yet ignoring these issues can make things worse. Honest conversations about mental health show your family it’s okay to seek help and support each other.

Check in with loved ones about how they’re feeling, especially during stressful times. Share your own experiences and let your family know they’re not alone. If someone is struggling, encourage them to get professional help and offer to assist in finding resources. Open dialogue can reduce shame and pave the way for healing.

4. Family Conflicts and Grudges

Every family has disagreements, but unresolved conflicts can fester for years. Avoiding tough conversations about old wounds or ongoing tension rarely leads to resolution. It’s healthier to address family conflicts openly, even if it feels uncomfortable at first. This approach can prevent small issues from snowballing into major rifts.

Set ground rules for respectful communication and let everyone have their say. Focus on listening rather than blaming. Sometimes, bringing in a neutral third party, like a counselor or mediator, can help keep the conversation productive. When you tackle these taboo topics as a group, you create space for forgiveness and understanding.

5. Career Choices and Life Goals

Families often have strong opinions about each member’s career and life path. Sometimes, parents expect children to follow in their footsteps or choose “safe” options. These expectations can make it hard to talk about true aspirations, especially if they don’t align with family traditions. However, discussing career choices and life goals openly can lead to greater happiness for everyone.

Encourage honest conversations about what each person wants from life. Celebrate achievements and discuss setbacks without judgment. Sharing dreams and ambitions can help families support each other and adjust expectations. These discussions can be significant for families with children about to graduate or adults considering a career change.

Building Trust Through Open Conversation

Addressing taboo topics with family members isn’t just about avoiding problems—it’s about building trust and understanding. When you discuss family finances, mental health, end-of-life wishes, and other sensitive subjects, you show your loved ones that you care about their well-being and future. These conversations can bring families closer, create shared goals, and reduce stress during difficult times.

It may take courage to be the first to bring up a tough subject, but the benefits far outweigh the discomfort. Make open discussion a regular part of your family dynamic. What taboo topics have you tackled in your own family? Share your experiences and tips in the comments below!

What to Read Next…

  • Why Even Wealthy Families Are Now Fighting Over Heirlooms
  • Why Do Adult Children Fight More Over Jewelry Than Homes?
  • 7 Ways a Family Member Can Accidentally Trigger Probate
  • 10 Things You Should Never Say When Writing a Will
  • 10 Things You Should Never Tell Your Children About Your Will
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Parenting & Family Tagged With: Career Advice, conflict resolution, end-of-life planning, family communication, family finances, mental health, taboo topics

The Financial Danger of a 100% Commission-Based Job

October 18, 2025 by Travis Campbell Leave a Comment

stocks
Image source: shutterstock.com

Thinking about a 100% commission-based job? Before you leap, it’s important to understand the risks. While these roles promise unlimited earning potential, the reality is far more complicated. Your income is tied directly to sales, not hours worked or effort put in. That unpredictability can be exciting, but it can also create real financial danger if you’re not prepared. Knowing what you’re getting into is the best way to protect your finances and your peace of mind.

1. Unpredictable Income Streams

The primary financial danger of a 100% commission-based job is the lack of a steady paycheck. Unlike salaried roles, your earnings fluctuate based on how much you sell—and sometimes, despite your best efforts, sales just don’t happen. This unpredictability makes budgeting a challenge and can throw off your long-term financial planning.

When your income varies month to month, it’s hard to know how much you’ll be able to save, spend, or invest. You might have a great month and feel flush with cash, only to have a dry spell that leaves you scrambling to cover the basics. For many, this rollercoaster can lead to stress, missed bills, or even debt.

2. No Guaranteed Base Salary

In a 100% commission-based job, there’s no base salary to fall back on. If you don’t make sales, you don’t make money. That means every paycheck is uncertain. This can be especially tough if you’re new to the field or if your industry is seasonal.

Without a financial safety net, you might feel pressured to accept unfavorable deals or push products just to survive. This can hurt your reputation in the long run and make it even harder to build a sustainable business.

3. Pressure to Sell at Any Cost

When your entire income depends on closing deals, the pressure to sell can become overwhelming. That pressure can lead to burnout or even ethical dilemmas. Some people may feel tempted to cut corners or push clients into decisions that aren’t right for them just to make a sale.

Not only does this make the job stressful, but it can also impact your long-term earning potential. Word travels fast, and if clients feel they’ve been misled, they won’t come back—or worse, they’ll warn others away.

4. Difficulties in Financial Planning and Saving

Financial planning is tough when you don’t know what you’ll earn next month. A 100% commission-based job makes it hard to set savings goals, qualify for loans, or plan for big expenses like a home or car. Lenders often want proof of stable income, and commission-based paychecks can make your finances look riskier than they are.

Without a consistent income, building an emergency fund becomes even more critical. But saving is harder when you’re never sure what you’ll bring home. This can leave you vulnerable in case of emergencies or unexpected expenses.

5. Lack of Employee Benefits

Most 100% commission-based jobs are considered self-employed or independent contractor roles. That means you’re usually on your own for health insurance, retirement savings, and other benefits. These perks can add up to thousands of dollars a year if you have to pay for them yourself.

Without employer contributions, you’ll need to set aside even more of your fluctuating income to cover these costs. If you’re not careful, you might end up underinsured or without any retirement savings at all.

6. Impact on Mental Health and Motivation

The stress of a 100% commission-based job can take a toll on your mental health. When you don’t know if you’ll make enough to pay the bills, anxiety can creep in. Motivation may wane during slow periods, making it even harder to break out of a slump.

Some people thrive in high-pressure, high-reward environments, but it’s not for everyone. If you’re not wired for constant uncertainty, this career path can leave you feeling drained and discouraged.

7. Inconsistent Work-Life Balance

Chasing commissions often means working odd hours, weekends, or even holidays. When your pay depends entirely on your hustle, it’s easy to let work take over your life. That can strain relationships and make it hard to ever fully relax.

Without boundaries, burnout becomes a real risk. Over time, you might find that the potential for high earnings isn’t worth the constant grind.

Weighing the Risks Before You Commit

A 100% commission-based job offers flexibility and the possibility of high earnings, but the financial danger is real. If you’re considering this path, take time to assess your risk tolerance, savings, and support system. Ask yourself if you can handle the uncertainty and whether you have a backup plan for lean months.

In the end, the best defense against the financial danger of a 100% commission-based job is preparation and a clear-eyed view of the risks.

Have you ever worked in a 100% commission-based job? What was your experience with the financial ups and downs? Share your thoughts in the comments below!

What to Read Next…

  • Are These 6 Trending Jobs Just A Rebranded Pyramid Scheme?
  • Why Some People Feel Rich But Can’t Afford A $400 Emergency
  • 7 Signs You Are Being Undervalued At Work And What To Do About It
  • 10 Signs You’re Living Above Your Means Without Realizing
  • Why ChatGPT May Be Generating Fake Financial Advice And Getting Away With It
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Career Advice Tagged With: Career Advice, commission-based jobs, income instability, job risks, Personal Finance, Planning

  • 1
  • 2
  • 3
  • 4
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework