• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Wealth Building

10 Investments That Could Make You a Fortune

February 24, 2025 by Latrice Perez Leave a Comment

Investment
Image Source: 123rf.com

In today’s rapidly evolving financial landscape, traditional investment avenues like stocks and bonds are no longer the only paths to wealth. Many individuals are exploring unconventional opportunities that offer significant returns. Let’s look into ten surprising investments that could potentially double your money.

1. Artificial Intelligence Startups

The AI sector is experiencing unprecedented growth, with applications spanning from healthcare to finance. Investing in early-stage AI companies can be lucrative, as these startups often pioneer groundbreaking technologies. However, it’s essential to conduct thorough research to identify ventures with robust business models and experienced teams. Engaging with industry experts and attending tech conferences can provide insights into promising opportunities. Remember, while the potential returns are high, so are the risks.

2. Renewable Energy Projects

As the world shifts towards sustainable energy, investments in renewable projects like wind farms and solar installations are gaining traction. Governments worldwide are offering incentives to promote green energy, enhancing the profitability of these ventures. Participating in community-funded renewable projects allows investors to support environmental initiatives while earning returns. It’s advisable to assess the project’s feasibility and the credibility of the managing entities before committing funds.

3. Vintage Wine Collections

Fine wine has historically appreciated in value, making it an attractive alternative investment. Rare vintages from renowned vineyards can yield substantial profits over time. Investors should consider factors like provenance, storage conditions, and market demand. Engaging with reputable wine merchants and utilizing specialized storage facilities can safeguard your investment. Patience is key, as wine investments typically require a long-term horizon.

4. Cryptocurrency Staking

Beyond traditional trading, cryptocurrency staking offers a way to earn passive income. By holding and “staking” certain digital currencies, investors can receive rewards over time. This process supports the blockchain network’s operations and, in return, provides holders with additional tokens. It’s crucial to understand the specific staking requirements and potential risks associated with each cryptocurrency. Diversifying your crypto portfolio can mitigate potential losses.

5. Farmland Investments
Farmland
Image Source: 123rf.com

Agricultural land has become a sought-after asset, especially as global food demand rises. Investing in farmland can provide steady income through leasing and potential appreciation. Consider regions with fertile soil, favorable climates, and access to water resources. Engaging with local agricultural experts can offer insights into crop selection and land management. This investment often requires a hands-on approach or partnership with experienced farmers.

6. Music Royalties

Purchasing rights to popular songs allows investors to earn royalties whenever the music is played. Platforms now enable individuals to buy shares in songs, diversifying their income streams. Analyzing streaming statistics and the artist’s popularity can guide investment decisions. It’s essential to understand the terms of royalty agreements and potential fluctuations in income. This niche market combines passion for music with financial gain.

7. Peer-to-Peer Lending

This platform enables individuals to lend money directly to borrowers, often at higher interest rates than traditional banks offer. While it can be profitable, it’s vital to assess the creditworthiness of borrowers. Diversifying loans across multiple borrowers can spread risk. Utilizing reputable P2P platforms with robust vetting processes enhances security. Be prepared for potential defaults and ensure you understand the platform’s fee structure.

8. Collectible Sneakers

The sneaker resale market has exploded, with limited-edition releases fetching high prices. Investors should stay informed about upcoming releases and market trends. Authenticity is paramount; purchasing from reputable sources and keeping the sneakers in pristine condition can enhance value. Engaging with sneaker communities can provide insights into desirable models. This investment requires a keen eye for trends and potential appreciation.

9. E-Sports Teams

The e-sports industry is booming, with revenues and audiences growing annually. Investing in e-sports teams or related enterprises can be lucrative. Understanding the gaming landscape and the popularity of specific games is crucial. Sponsorship deals, merchandise sales, and tournament winnings contribute to revenue streams. This sector combines entertainment with investment opportunities.

10. Urban Real Estate in Emerging Markets

Cities in developing countries are expanding rapidly, presenting opportunities in real estate. Investing in commercial or residential properties in these urban centers can yield high returns. It’s essential to research local property laws, economic stability, and demand trends. Partnering with local real estate professionals can navigate potential challenges. This investment often requires a long-term commitment and risk assessment.

Diversification Is Key

Exploring unconventional investments can diversify your portfolio and potentially lead to significant financial gains. However, thorough research and risk assessment are paramount before venturing into these areas. Only invest what you are willing to lose, but always play to win.

Have you tried out any of the investments we talked about? What has worked for you so far? Let’s talk about it in the comments.

Read More:

Here’s What Your Financial Advisor Won’t Tell You About Income Investing

Collections Worth Investing In: Making Hobbies And Interests Pay For Themselves

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.
Filed Under: Investing Tagged With: Alternative Assets, Emerging markets, Financial Growth, investments, Wealth Building

House Poor: 8 Real-Life Struggles of Overpaying For A House

February 14, 2025 by Latrice Perez Leave a Comment

House sitting on coins
Image Source: 123rf.com

Being “house poor” is a financial term that refers to a situation where a significant portion of your income—more than 30%, or in some extreme cases, 50% or more—is spent on housing costs. This can include rent or mortgage payments, property taxes, utilities, and home maintenance. While owning a home can feel like a dream come true, being house poor means you’re left with little financial flexibility, and everyday expenses can become a burden. If you find yourself in this position, here are eight challenges you’ll likely face and why it’s crucial to take action.

1. Limited Ability to Save for the Future

When the majority of your income is tied up in housing costs, there’s little room left for saving. Without savings, you’re not building an emergency fund, contributing to retirement accounts, or setting aside money for your future goals—like buying a car, funding your children’s education, or traveling. If a financial emergency arises, you’ll have no cushion to fall back on, which can lead to a cycle of borrowing or taking on debt.

2. Increased Financial Stress

Constantly worrying about how you’ll cover your housing expenses can lead to stress and anxiety. The weight of knowing that a huge chunk of your income goes toward one category—housing—can leave you feeling financially suffocated. You may struggle with day-to-day decisions, and even small financial setbacks can feel catastrophic when you don’t have room in your budget to absorb them.

3. Limited Flexibility in Your Budget

When over 50% of your income is dedicated to housing, your budget for everything else shrinks dramatically. You’ll likely have little room for other essential expenses such as healthcare, insurance, groceries, or transportation. This lack of flexibility means you may need to sacrifice or cut back on spending in other areas, making it harder to live comfortably or enjoy life’s little luxuries.

4. Difficulty Handling Unexpected Costs

Life is unpredictable, and unexpected costs will inevitably arise—whether it’s a medical emergency, a car repair, or an unexpected home repair. With such a high percentage of your income going to housing, you may struggle to pay for these costs without resorting to credit cards or loans, which can lead to even more debt. Being house poor means you have little margin for error when it comes to financial surprises.

5. Hindered Personal Growth and Opportunities

When you’re financially stretched, it can be difficult to pursue personal growth opportunities like further education, career advancement, or a new job. Many people in house poor situations find themselves stuck in their current job or career path because they need the income to cover their housing costs. Without the ability to invest in personal development or seize new opportunities, it can feel like you’re in a financial rut with little room to move forward.

6. Inability to Invest in Other Assets

Investments
Image Source: 123rf.com

Investing in assets like stocks, bonds, or real estate can help grow your wealth over time. However, when a large portion of your income is tied up in housing, you may not have enough money to invest in other areas. Without these additional investments, it’s harder to build wealth or create passive income streams that could provide more financial freedom and security in the future.

7. Potential for Financial Strain on Relationships

Money is a leading cause of stress in relationships, and when one partner is under financial strain due to being house poor, it can cause tension in the relationship. Whether it’s disagreement about finances, missed payments, or the inability to enjoy things together, the stress of living paycheck to paycheck can lead to arguments and create an emotional burden for both partners. Without the financial freedom to spend on experiences together, you might feel isolated or disconnected.

8. Limited Room for Enjoying Life’s Pleasures

One of the greatest challenges of being house poor is the constant feeling that you can’t enjoy life to the fullest. Whether it’s eating out, taking vacations, or indulging in small luxuries, your financial obligations to housing prevent you from experiencing those joys. Over time, the stress and resentment of not being able to enjoy life can negatively affect your mental and emotional well-being, leading to dissatisfaction.

Is There a Way Out?

Living in a house that consumes a significant portion of your income can feel like a trap. While homeownership is a worthwhile goal for many, becoming house poor can significantly hinder your ability to live comfortably and build long-term wealth. If you’re struggling with an extremely high mortgage payment, it might be time to consider adjusting your financial priorities. Whether it’s downsizing, refinancing, or finding ways to boost your income, taking proactive steps can relieve the financial strain and allow you to regain control of your finances.

Did you overpay for your home? How stressful has this experience been for you and have you found a way out? Tell us more in the comments below.

Read More:

How Much Income Do I Need For a 300k Mortgage in 2025?

15 Warning Signs You Should Refinance Your Mortgage

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.
Filed Under: Real Estate Tagged With: budgeting, financial freedom, Financial Security, house poor, Housing Costs, mortgage stress, Personal Finance, Planning, Wealth Building

Penniless At 50: 8 Things You Should Have Done By 30 to Be Rich Now!

February 12, 2025 by Latrice Perez Leave a Comment

50 and Penniless
Image Source: 123rf.com

It’s not uncommon to find yourself in a financial rut by the time you hit 50, especially if you’re just starting to consider your wealth-building strategies now. Whether you’re dealing with debt, limited savings, or missed opportunities, the reality can feel overwhelming. But the truth is, the earlier you start planning your financial future, the better off you’ll be.

If you’re feeling “penniless at 50,” you’re not alone, but it’s important to look back and understand what you could have done differently—starting from your 30s. Here are 8 key things you should have done by 30 to have built a strong financial foundation for your future—and how you can still make moves today.

1. Started Investing Early

By the time you reach your 50s, the key to wealth is often compound interest. The earlier you begin investing, the more time your money has to grow. If you had started investing in your 30s, even small amounts would have had the chance to grow exponentially by the time you hit 50. Whether it’s through stocks, bonds, or retirement accounts like 401(k)s or IRAs, putting your money to work early is one of the most important financial moves you can make.

If you’re starting late, don’t panic. Even though you’ve missed out on years of growth, it’s never too late to begin. Start investing now to give yourself the best shot at building a retirement fund for the future.

2. Built an Emergency Fund

One of the best things you could have done by 30 was to create an emergency fund. Life throws curveballs, and an emergency fund provides a financial cushion for when things go wrong, whether it’s a medical emergency, a car repair, or unexpected job loss. If you had started building that fund in your 30s, you would have less financial stress now, especially if you’ve been hit with unexpected events over the years.

It’s never too late to start. Begin small, and aim for at least three to six months’ worth of living expenses. This fund will give you financial freedom and security, no matter your age.

3. Saved for Retirement Religiously

Retirement may feel like a distant concern in your 30s, but the reality is that the sooner you start saving, the better. Contributing to a retirement account such as a 401(k) or an IRA while you’re in your 30s would have given you a huge advantage. The younger you are when you start saving, the more time your money has to grow, and the easier it will be to retire comfortably.

If you missed that opportunity, don’t despair—take action today. Start contributing to your retirement account, and if you’re able, catch up on contributions. Many retirement accounts allow for “catch-up” contributions after 50, so take advantage of these provisions to make up for lost time.

4. Developed Multiple Income Streams

Money on top of a keyboard
Image Source: 123rf.com

Relying on one income source can limit your wealth potential. By 30, you could have started developing multiple income streams to build your wealth. This could include side businesses, freelance work, or passive income sources like rental properties or dividends from investments. Having multiple income sources makes you less reliant on a single paycheck and can help grow your wealth much faster.

It’s not too late to develop multiple streams of income—whether it’s through a part-time business, an investment, or learning new skills to make more money at your job. Focus on income diversity and find ways to generate additional revenue in your 50s to build up your wealth.

5. Controlled Your Spending

By 30, you should have developed the discipline to control your spending. Living below your means and avoiding lifestyle inflation would have allowed you to save and invest more. Many people get stuck in the cycle of upgrading their lifestyle every time they get a raise, but this often leads to living paycheck to paycheck with little to show for it.

If you didn’t start saving and budgeting by 30, it’s time to get serious about your finances or be filled with even more regret. Track your spending, identify areas to cut back, and prioritize saving and investing. It’s not about depriving yourself but about making smarter choices for long-term financial freedom.

6. Avoided Bad Debt

Having a mortgage or a reasonable car loan is one thing, but high-interest credit card debt, payday loans, or other forms of bad debt can drain your finances. By 30, you should have started paying off high-interest debts quickly and avoided unnecessary loans. Good debt (like a mortgage) can help you build wealth, but bad debt holds you back from financial independence.

It’s not too late to tackle your debt. Pay off high-interest loans as quickly as possible, and work on improving your credit score. The less debt you carry, the more you can allocate toward savings and investments.

7. Created a Financial Plan

A solid financial plan helps you stay focused on your goals and achieve financial independence. By 30, you should have already set clear goals for your finances: saving for retirement, buying a home, paying off debt, or starting a business. A financial plan is essential for tracking your progress and making sure you’re staying on course.

Even if you’re behind, start developing a financial plan now. Identify your goals and map out a strategy to achieve them. Working with a financial planner or using budgeting tools can help you stay organized and motivated.

8. Learned About Taxes and Tax Strategies

Many people wait until they’re much older to learn about the impact taxes have on their income, investments, and savings. By 30, you should have started educating yourself on tax strategies that can help you minimize taxes and increase savings. Whether it’s through tax-advantaged accounts like a 401(k) or learning how to invest in a tax-efficient manner, understanding taxes is a key to building wealth.

If you missed out on this in your 30s, it’s not too late to start. Read up on tax strategies or consult with a tax professional to maximize your savings going forward.

It’s Never Too Late to Take Control

Being penniless at 50 may feel overwhelming, but it doesn’t mean it’s too late to take action. While you can’t go back and start building wealth at 30, you can certainly take steps today to improve your financial future. Start by reviewing the things you should have done by 30 and focus on building habits that will help you catch up and secure your financial independence. It’s never too late to make the necessary changes that will set you on the path to financial freedom.

Are you 50 or older and have no savings? What steps are you taking to ensure your financial future? Tell us more in the comments below.

Read More:

9 Tough Decisions You’ll Have to Make When Your Parents Can’t Afford to Retire

Cold Hard Facts: 12 Unexpected Complications of Electric Scooters

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.
Filed Under: Personal Finance Tagged With: budgeting, Debt Management, financial advice, financial freedom, investing, money management, Planning, Retirement, saving tips, Wealth Building

Here’s Why Your Children Are The Biggest Threat to Your Financial Future

February 12, 2025 by Latrice Perez Leave a Comment

Children with their hands raised
Image Source: 123rf.com

When we think about securing our financial future, we often focus on traditional concerns: savings, investments, retirement plans, and budgeting. But what if the real obstacle to your financial success isn’t rising healthcare costs, economic downturns, or unexpected job losses? What if the true threat to your financial stability is closer to home than you think—specifically, your children? While it’s natural to want to provide the best for your kids, the financial burden of raising children can have far-reaching implications on your wealth, savings, and future plans.

Although your children are your greatest joy, they could unintentionally become the biggest threat to your financial future, and what you can do to mitigate the impact.

1. The Never-Ending Cost of Raising Kids

It’s no secret that raising children is expensive. From diapers to college tuition, the costs seem to mount up year after year. According to recent estimates, the average cost of raising a child to the age of 18 in the U.S. is about $230,000—excluding college expenses. This staggering figure doesn’t account for inflation, unexpected medical costs, or other emergencies, all of which can make these figures even higher.

What makes this even more concerning is that many parents don’t realize how much they are spending until it’s too late. Parents often feel the need to keep up with the latest trends or provide the best experiences for their children, from expensive extracurricular activities to the latest tech gadgets. These seemingly small expenses add up quickly, often compromising the ability to save for retirement or invest in long-term financial goals.

2. Putting Your Kids First, Financially, Can Backfire

As parents, it’s natural to want to give our children the best—whether it’s top-tier education, opportunities for extracurricular activities, or financial support as they grow into adulthood. However, prioritizing your children’s financial needs over your own future can be disastrous.

Many parents dip into their retirement savings or forego contributions to their own investment accounts to pay for their kids’ needs. This short-term thinking can lead to long-term consequences. For instance, funding a child’s college education without considering how it will impact your retirement savings could leave you financially strained in your later years.

It’s important to remember that your financial future depends on you having enough resources to retire comfortably and live without financial worry. If you prioritize your children’s financial needs above your own, you might find yourself unable to support yourself in retirement or scrambling to make up for lost time when it’s too late.

3. The Hidden Costs of Financial Dependence in Adulthood

Young Adult
Image Source: 123rf.com

There’s a common misconception that once children reach adulthood, they’re financially independent. However, many young adults—especially in today’s challenging economic environment—find it difficult to secure well-paying jobs and are increasingly dependent on their parents for financial support. From living with parents into their 30s to needing help with student loans or credit card debt, the financial burden can last far longer than expected.

This financial dependence can drain your savings and delay your ability to build wealth. You may feel compelled to help your children with rent, car payments, or even funding their lifestyle. While helping your kids is admirable, it’s essential to recognize that your financial independence is just as important as theirs. The longer your children remain financially dependent on you, the longer it will take to recover your financial footing.

4. The Emotional Toll of Guilt-Induced Spending

Parents are often driven by guilt to overspend on their children. Whether it’s buying expensive gifts, covering last-minute expenses, or taking out loans for things like education or housing, the emotional pressure to provide for your kids can lead to unnecessary spending. This emotional toll can significantly undermine your ability to make sound financial decisions.

The desire to give your children everything they need can lead to decisions that are not in line with your long-term goals. If you’re constantly giving in to guilt-driven spending, it becomes harder to prioritize saving for your own future. This mindset can keep you locked in a cycle of financial instability, where you’re always playing catch-up instead of building wealth for yourself.

5. They Could Inadvertently Encourage Poor Financial Habits

Children learn financial habits from their parents, and while you may be teaching them how to save, budget, and plan, you could also be unintentionally teaching them bad financial habits. Overindulging your children with money, excessive spending, or not setting boundaries around money can create a sense of entitlement. This can lead to poor financial decision-making on their part, which could, in turn, require more financial support from you down the line.

The cycle of financial dependence can continue into adulthood if you don’t set the right example. By teaching your children the importance of financial independence, self-discipline, and budgeting, you can ensure that they are better equipped to make smart financial choices when they are on their own. Ultimately, healthy financial habits should be passed down to ensure they don’t create additional financial burdens for you in the future.

6. The Impact of Financial Worry on Your Mental Health

The financial burden of raising children can also take a significant toll on your mental health. The pressure of constantly worrying about how to provide for your children, pay for their education, and help them get ahead can lead to stress, anxiety, and burnout. In turn, this emotional strain can interfere with your decision-making abilities and lead to poor financial choices.

The best way to combat this is by creating a sustainable financial plan that includes saving for your own retirement while also supporting your children’s future in a balanced way. Having open conversations about money with your children, setting financial goals, and working together as a family can help reduce the burden and alleviate some of the emotional stress associated with raising financially dependent children.

Recognize The Financial Challenges

While raising children is one of the most rewarding experiences in life, it’s important to recognize the financial challenges that come with it. Children can be the biggest threat to your financial future if you’re not careful about where you allocate your resources. It’s essential to strike a balance between providing for your children and securing your own financial stability for the future.

By prioritizing your long-term financial goals, setting boundaries around financial support, and teaching your children the value of financial independence, you can ensure that you don’t sacrifice your own future for the sake of their immediate needs. After all, your children’s success is important—but your own financial health should never be neglected.

Have your children been an impediment to your financial future? What actions have you taken to ensure your financial well-being? Let’s talk about it in the comments below.

Read More:

13 Reasons Why Millennials Will Never Be Able To Pay For Their Kids To Go To College

5 Budgeting Tips for Newly Divorced Single Parents With Children

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.
Filed Under: kids and money Tagged With: financial burden, financial independence, future planning, managing family finances, parent financial support, Planning, raising children, Retirement, saving for the future, Wealth Building

Here Are 5 Books That Everyone Should Read to Improve Their Financial Literacy

October 16, 2024 by Vanessa Bermudez Leave a Comment

Here Are 5 Books That Everyone Should Read to Improve Their Financial Literacy
123rf

In today’s fast-paced world, having a solid understanding of financial literacy is essential. Whether you’re just starting out or looking to refine your skills, these five books offer invaluable insights to help you manage your money better. Let’s dive into the must-reads for anyone serious about improving their financial knowledge.

1. “Rich Dad Poor Dad” by Robert T. Kiyosaki

“Rich Dad Poor Dad” is a classic when it comes to financial literacy. In this book, Kiyosaki shares lessons learned from his two “dads”—one rich and one poor—on how they viewed money, investing, and education. The book emphasizes the importance of financial independence and investing in assets that generate passive income. Through relatable stories, Kiyosaki breaks down complex financial concepts, making them accessible to everyone. This book will challenge the way you think about money and is a great starting point for those new to personal finance.

2. “The Total Money Makeover” by Dave Ramsey

Dave Ramsey’s “The Total Money Makeover” is a straightforward guide to financial freedom, focusing on debt elimination and disciplined spending. Ramsey provides a step-by-step plan to help readers get out of debt, save for emergencies, and build wealth through smart budgeting. The book is full of real-life success stories, offering both motivation and practical advice. Ramsey’s approach is strict, but it’s highly effective for those struggling with debt or poor financial habits. If you’re serious about transforming your finances, this book is an essential read.

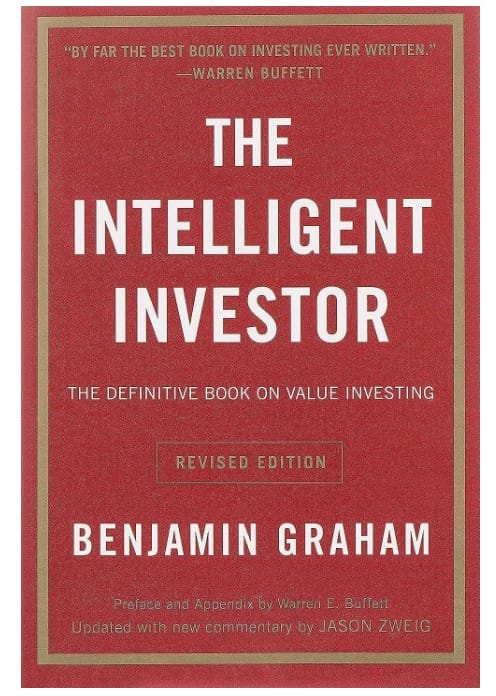
3. “The Intelligent Investor” by Benjamin Graham

The Intelligent Investor by Benjamin Graham
Amazon

For anyone interested in learning about investing, “The Intelligent Investor” by Benjamin Graham is a must-read. Known as one of the greatest investment advisors of all time, Graham’s book introduces the concept of value investing, which focuses on purchasing stocks that are undervalued by the market. The book is packed with timeless financial principles that help readers understand risk, reward, and long-term strategies for building wealth. Graham also emphasizes the importance of research and patience in investing, making this book a valuable resource for both beginners and seasoned investors. Warren Buffett himself cites it as one of his most influential reads.

4. “Your Money or Your Life” by Vicki Robin and Joe Dominguez

“Your Money or Your Life” takes a unique approach to financial literacy by focusing on the relationship between money and happiness. The authors guide readers through nine steps to transform their relationship with money, helping them track spending, reduce expenses, and ultimately achieve financial independence. This book teaches readers to see money as a tool for creating the life they want, rather than an end goal. Robin and Dominguez’s philosophy promotes mindful spending and sustainable living, making it a refreshing take on personal finance. It’s perfect for those looking to simplify their financial life and focus on what truly matters.

5. “I Will Teach You to Be Rich” by Ramit Sethi

“I Will Teach You to Be Rich” by Ramit Sethi
Amazon

Ramit Sethi’s “I Will Teach You to Be Rich” is a modern, no-nonsense guide to managing your money, with an emphasis on automating your finances and investing smartly. Sethi’s witty, conversational tone makes complex financial strategies easy to understand and follow. He covers everything from credit cards and savings accounts to investing and budgeting, offering practical advice for millennials and young professionals. The book is perfect for those looking to build wealth without feeling overwhelmed by financial jargon. Sethi’s approach is all about living a rich life, where money supports your goals and dreams.

Building Financial Literacy for a Secure Future

Improving your financial literacy is one of the most important investments you can make in yourself. These five books provide the foundational knowledge you need to take control of your finances, whether you’re aiming to get out of debt, build wealth, or simply become more confident in managing your money. By incorporating the lessons from these must-read books, you’ll be better equipped to make informed financial decisions and secure your financial future. Don’t wait—start building your financial literacy today!

Vanessa Bermudez
Vanessa Bermudez
Vanessa Bermudez is a content writer with over eight years of experience crafting compelling content across a diverse range of niches. Throughout her career, she has tackled an array of subjects, from technology and finance to entertainment and lifestyle. In her spare time, she enjoys spending time with her husband and two kids. She’s also a proud fur mom to four gentle giant dogs.

Filed Under: book review Tagged With: financial literacy, Investing Tips, money management, Personal Finance Books, Wealth Building

Need To Get Your Retirement In Order: Start By Reading These 5 Retirement Planning Books

August 27, 2024 by Vanessa Bermudez Leave a Comment

Need To Get Your Retirement In Order Start By Reading These 5 Retirement Planning Books
Canva

Planning for retirement can be overwhelming, but the right guidance can make all the difference. If you’re looking to get serious about your future, the best place to start is by diving into some highly recommended retirement planning books. These books offer expert advice, actionable tips, and peace of mind as you prepare for your golden years.

1. “The Total Money Makeover” by Dave Ramsey

If you’re looking to take control of your finances before retirement, Dave Ramsey’s “The Total Money Makeover” is a must-read. Ramsey’s straightforward approach to debt elimination, budgeting, and saving makes this book a staple for anyone serious about financial freedom. He breaks down complex concepts into easy-to-understand steps, helping you get your financial house in order. While not solely focused on retirement, the principles taught will lay a strong foundation for a worry-free retirement. Ramsey’s no-nonsense style is both motivating and practical, making it a perfect starting point.

2. “The Simple Path to Wealth” by JL Collins

For those seeking an easy-to-follow guide on building wealth, “The Simple Path to Wealth” by JL Collins is a game-changer. Collins offers a no-fuss approach to investing, focusing on low-cost index funds and long-term growth. His conversational tone makes complex financial topics accessible, even if you’re new to investing. The book is filled with practical advice on how to accumulate wealth steadily and avoid common financial pitfalls. Whether you’re nearing retirement or just starting out, Collins’ wisdom provides a clear roadmap to financial independence.

3. “How Much Money Do I Need to Retire?” by Todd R. Tresidder

“How Much Money Do I Need to Retire” by Todd R. Tresidder
Canva

One of the most daunting questions in retirement planning is how much you actually need to save. Todd R. Tresidder’s book, “How Much Money Do I Need to Retire?” tackles this question head-on. Tresidder offers a comprehensive approach to calculating your retirement needs, factoring in variables like lifestyle, inflation, and unexpected expenses. His method is flexible, allowing you to tailor your retirement plan to your unique circumstances. The book also delves into various strategies for generating income during retirement, making it a valuable resource for anyone aiming for financial security.

4. “Retire Inspired” by Chris Hogan

Chris Hogan’s “Retire Inspired” isn’t just a book about money; it’s a guide to envisioning and achieving the retirement of your dreams. Hogan encourages readers to take charge of their retirement planning with actionable steps and motivational insights. The book covers everything from creating a retirement budget to understanding different retirement accounts. Hogan’s engaging style and relatable stories make the content both informative and inspiring. Whether you’re years away from retirement or right around the corner, “Retire Inspired” will give you the tools and confidence to make your retirement vision a reality.

5. “The New Retirementality” by Mitch Anthony

Mitch Anthony’s “The New Retirementality” challenges traditional views of retirement and offers a fresh perspective on living a fulfilling life beyond your working years. Anthony explores the idea that retirement is not just an end but a new beginning filled with opportunities for growth, learning, and adventure. The book emphasizes the importance of aligning your financial plans with your personal values and goals. Anthony’s insights encourage readers to rethink retirement as a dynamic phase of life rather than a time to slow down. For those who want to approach retirement with a sense of purpose, this book is a must-read.

Your Retirement Starts with the Right Knowledge

Getting your retirement in order doesn’t have to be daunting—especially with the right resources. These five retirement planning books offer valuable insights, strategies, and motivation to help you plan a secure and fulfilling future. Whether you’re just beginning to think about retirement or refining your plans, these books provide the knowledge and inspiration needed to take control of your financial destiny. Start reading today and pave the way for a retirement that’s not just comfortable but extraordinary.

Vanessa Bermudez
Vanessa Bermudez
Vanessa Bermudez is a content writer with over eight years of experience crafting compelling content across a diverse range of niches. Throughout her career, she has tackled an array of subjects, from technology and finance to entertainment and lifestyle. In her spare time, she enjoys spending time with her husband and two kids. She’s also a proud fur mom to four gentle giant dogs.

Filed Under: Retirement Tagged With: financial freedom, Retirement Goals, Retirement Planning Books, retirement strategies, Wealth Building

  • « Previous Page
  • 1
  • …
  • 13
  • 14
  • 15

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • 10 Tactics for Building an Emergency Fund from Scratch by Vanessa Bermudez
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald

Copyright © 2026 · News Pro Theme on Genesis Framework