• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Personal Finance

The “Lifestyle Creep” That Ensures You’ll Never Get Ahead, No Matter Your Salary

October 31, 2025 by Travis Campbell Leave a Comment

lifestyle rich
Image source: shutterstock.com

People experience financial stagnation despite their salary growth and better job opportunities. The hidden pattern of lifestyle creep serves as the typical method that people use to discover their answer. This happens when your spending increases every time your income does. People often believe that receiving a higher income will fix their financial issues, but when expenses grow at the same rate as salary increases, it becomes impossible to make progress. The phenomenon of lifestyle creep produces more than just expensive cars and vacations, as it manifests through various everyday decisions. Understanding this habit pattern will help you establish actual financial stability. Your financial progress will stop because you fail to identify and manage lifestyle creep, regardless of your current income level.

1. Upgrading Your Home and Car Without a Second Thought

One of the most common signs of lifestyle creep is instantly upgrading your home or car after a raise or promotion. It feels natural: you’re making more, so you deserve a bigger apartment, a newer car, or a place in a trendier neighborhood. But these upgrades often come with higher rent, bigger car payments, and more expensive insurance. Suddenly, your extra income vanishes into monthly bills. Instead of building wealth, you’re stuck on a treadmill of higher expenses. If you want to avoid lifestyle creep, pause before making big purchases. Ask yourself if these upgrades truly improve your happiness or just add to your financial stress.

2. Dining Out and Entertainment: Small Splurges Add Up

When your income rises, it’s tempting to treat yourself more often. Maybe you grab takeout several nights a week or start meeting friends at pricier restaurants. You might also spend more on streaming services, concerts, or weekend getaways. These small splurges don’t feel like a big deal at first, but they add up quickly. Over time, your monthly spending on food and entertainment can balloon without you noticing. Lifestyle creep thrives on these subtle increases. To keep your budget in check, track how often you eat out or indulge in entertainment, and set a monthly limit that fits your financial goals.

3. Subscriptions and Automatic Upgrades You Forget About

It’s easy to sign up for new subscriptions when your paycheck grows. Perhaps you could add an extra fitness app, premium music streaming, or a subscription box for coffee or clothing. Many services offer “free trials” that quietly turn into monthly charges. These recurring expenses can slip under your radar, especially if they’re small. Over time, though, they quietly drain your bank account. Lifestyle creep often hides in these auto-renewing subscriptions. Take time every few months to review all your recurring charges. Cancel anything you don’t use or need. This simple habit helps you keep lifestyle creep in check and frees up money for savings or debt payoff.

4. Saying Yes to Every Social Invitation

As your income rises, your social life might expand, too. You may feel pressured to keep up with friends who have similar or higher salaries. This can mean more dinners out, group trips, or expensive events. It’s easy to justify these expenses in the name of fun or networking, but they can quickly eat into your budget. Lifestyle creep isn’t just about material things—it’s also about feeling like you need to match your peers’ spending habits. Remember, it’s okay to say no or suggest more affordable alternatives. Protecting your financial goals sometimes means skipping an event or organizing a potluck instead of a pricey night out.

5. Delaying Savings and Investments “Until Later”

One of the most damaging effects of lifestyle creep is putting off saving and investing for your future. When you spend every raise or bonus on upgrades and experiences, there’s nothing left to put toward your emergency fund, retirement, or other goals. It’s easy to think you’ll start saving “next year” or after the next promotion, but lifestyle creep makes it harder to change course. As your expenses increase, you will need to maintain your new lifestyle. To break the cycle, make saving automatic. Set up a portion of every paycheck to go directly into savings or investments before you spend a dime. This simple move helps you build real wealth, no matter your salary.

How to Beat Lifestyle Creep and Build Real Wealth

Recognizing lifestyle creep is the first step to taking control of your finances. You need to select particular targets that will receive your financial support during the following stage. Your budget should reflect your personal values and important life goals, rather than using your paycheck amount as a reference. You should increase your savings rate before using your salary boost to spend more money. You need to establish your fundamental financial targets by deciding which goals, retirement security, travel, or family support, hold the highest importance for you.

Reading about others who have faced similar challenges can be beneficial. Your ability to track your spending habits will enable you to change your behavior when your financial situation improves. You can achieve financial growth by controlling lifestyle creep because it enables you to save money and invest for the future while enjoying your most important possessions.

Do you understand how lifestyle creep affects your daily activities? What steps have you taken to improve your financial situation? Share your thoughts in the comments below!

What to Read Next…

  • 10 Signs You’re Living Above Your Means Without Realizing
  • How Many of These 8 Middle Class Habits Are Keeping You Poor
  • Are These 8 Money Saving Tricks Actually Keeping You Broke
  • 10 Ways You’re Wasting Money Just Trying to Keep Up Appearances
  • Are Budgeting Apps Designed to Push You into Debt
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.
Filed Under: Lifestyle Tagged With: budgeting, financial habits, Lifestyle creep, Personal Finance, saving money, Wealth Building

4 Essential Rules of Thumb for Buying Individual Stocks Safely

October 31, 2025 by Travis Campbell Leave a Comment

stocks
Image source: shutterstock.com

Stock market transactions, particularly through individual stock purchases, elicit both positive and negative emotional responses in inexperienced investors. Investing in individual companies through specific stock selection differs from investing in broad index funds or ETFs because it exposes your funds to direct business performance risks. You must establish specific rules to guide your decision-making process before you begin. The process of buying individual stocks safely becomes achievable through following specific rules, which help you reduce investment risks and boost your chances for enduring market success. These rules exist to create investment stability instead of producing quick financial gains. You need to understand the four fundamental principles that form the basis of your toolkit.

1. Never Invest Money You Can’t Afford to Lose

This rule of thumb for buying individual stocks safely is non-negotiable. Stock prices can swing wildly, and even the most promising company can face unexpected trouble. Before buying any stock, ask yourself: “If this investment went to zero, would my financial life be at risk?” If the answer is yes, hold off. Your emergency fund, rent, or essential bills should never depend on the fate of a single company’s stock.

One way to keep yourself safe is to limit your individual stock investments to a small percentage of your total portfolio. Many financial advisors recommend allocating no more than 10% of your assets to individual stocks, with the remainder in diversified funds. This keeps your exposure in check while still allowing you to participate in the potential upside of specific companies.

2. Do Your Homework—Really

It’s tempting to buy a stock because it’s in the news, a friend recommends it, or it seems like a “can’t-miss” opportunity on social media. But when it comes to rules of thumb for buying individual stocks safely, use a screener and do real research. Start by reading the company’s quarterly and annual reports. Look for earnings growth, stable cash flow, and a healthy balance sheet. Pay attention to the company’s debt level and whether it has a sustainable competitive advantage.

Don’t stop at the numbers. Research the company’s industry, major competitors, and any regulatory or market risks. Sites like Morningstar can help you dig deeper but always double-check information and look for a range of opinions. Understanding what you’re buying and why gives you a clear edge—and helps you avoid panic selling during inevitable downturns.

3. Diversify to Reduce Risk

Even if you follow every other rule of thumb for buying individual stocks safely, putting all your eggs in one basket is still risky. No single company, no matter how strong, is immune to bad news or industry shifts. That’s why diversification is key. By spreading your investments across several companies and sectors, you reduce the impact if one stock underperforms.

Diversification doesn’t mean buying dozens of random stocks. Instead, aim for a handful of companies in different industries that you understand well. For example, instead of owning three tech stocks, consider adding a healthcare company or a consumer goods brand to your portfolio. This approach helps smooth out the bumps and keeps your overall returns more stable.

If you’re not sure where to start, you can always supplement your individual stock picks with broad-based index funds. This keeps your portfolio balanced and gives you exposure to the overall market, while still letting you try your hand at picking winners.

4. Set Clear Entry and Exit Points

It’s easy to let emotions drive your decisions when buying and selling stocks. That’s why one of the best rules of thumb for buying individual stocks safely is to decide in advance when you’ll buy more, hold, or sell. Set a price target for selling if the stock reaches a certain high, and a stop-loss level if it drops below a point where you’re no longer comfortable holding it.

This discipline keeps you from chasing losses or getting swept up in hype. It also helps you avoid the trap of holding onto a losing stock in the hope it will bounce back or selling a winner too soon because you’re nervous. Write down your plan before you buy and review it regularly to see if your reasons for holding the stock still make sense.

Many online brokerages now offer tools that let you set automatic alerts or even execute trades when your target prices are hit. Utilizing these features can alleviate some of the stress associated with managing your investments and help you stay on track with your plan.

Building Confidence with Every Trade

The rules of thumb for buying individual stocks safely will protect you from typical investor mistakes, but they do not promise investment success. Investing always carries some level of risk, but you should make choices while understanding what you are getting into and safeguarding your money. You will develop skills to evaluate businesses and manage your feelings and investment portfolio adjustments over time as your financial targets evolve.

The path to investment success depends on learning and maintaining consistency, rather than pursuing quick profits. For additional practical guidance, consider seeking advice from an expert. Your skills and confidence will grow through disciplined practice of each trade, which requires patience.

What particular rules of thumb do you use when buying individual stocks for secure investment purposes? Share your thoughts or questions in the comments below!

What to Read Next…

  • Identifying Underpriced Stocks Using the Graham Formula
  • Why So Many Investors Are Losing Assets in Plain Sight
  • How Financial Planners Are Recommending Riskier Portfolios in 2025
  • 8 Subtle Illusions Used by Scammers in Investment Offers
  • 10 Ways Zero Fee Investing Platforms Make Money Off You
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.
Filed Under: Investing Tagged With: individual stocks, Investing Tips, Personal Finance, portfolio diversification, Risk management, stock investing

What Happens if You Die Without a Will? The Answer Is Scarier Than You Think

October 30, 2025 by Travis Campbell Leave a Comment

Will

Most people put off estate planning, assuming there’s plenty of time to handle it later. Your assets will encounter particular legal penalties after your death when you do not establish a will. Your bank account is the only account directly impacted by this situation. Your loved ones would encounter legal problems, family conflicts, and unexpected delays. The state takes control, but its choices do not align with what you would have chosen. The knowledge about death without a will enables you to safeguard your family from dealing with confusion and conflict. Your departure from this world without a plan will yield specific results.

1. The State Decides Who Gets What

When you die without a will—legally called dying “intestate”—your state’s laws determine who inherits your property. There’s no flexibility or consideration for personal relationships. The court follows a strict order: spouse, children, parents, siblings, and so on. If you have a partner but aren’t married, they may get nothing. Friends, stepchildren, or charities you care about? They’re left out entirely. The state’s plan is one-size-fits-all, and it probably doesn’t fit your life.

This is the core of what happens if you die without a will. It doesn’t matter what promises you made or what your family expects. The law is the law, and there’s no room for exceptions.

2. Your Children’s Guardianship Is Up in the Air

One of the most unsettling aspects of dying without a will is what happens to your minor children. If there’s no surviving parent with legal custody, the court will choose a guardian. Family members may petition for custody, but the judge decides who raises your kids. This process can be long and emotional, and it may spark family battles. Even worse, the person chosen may not be the one you’d pick.

If you want a say in your children’s future, a will is essential. Without it, you’re leaving this critical decision to strangers.

3. The Probate Process Gets More Complicated

Probate is the legal process of settling your estate. Without a will, probate is almost always more difficult and time-consuming. The court must appoint an administrator—often a family member, sometimes a public official—to handle your assets. This can lead to delays, additional paperwork, and higher legal fees. Your loved ones might wait months, or even years, for access to the money they need now.

This is a key part of what happens if you die without a will. The probate court has to do extra work to figure out your wishes, but often, it simply follows the law and moves on. Your family bears the burden of uncertainty and red tape.

4. Family Disputes Can Erupt

When there’s no will, family members may disagree about who should get what. Old resentments can surface. Siblings may clash over heirlooms, money, or even funeral arrangements. With no written instructions to follow, emotions—and tempers—run high. Sometimes, these disputes end up in court, draining the estate and damaging relationships for years.

Leaving a will isn’t just about money. It’s about preventing unnecessary conflict and providing clarity to those left behind.

5. Unintended Heirs May Inherit

State laws don’t account for complicated family dynamics. If you’re estranged from a relative, they may still inherit your assets. If you remarried but never updated your estate plans, your children from a previous marriage could be left out. In some cases, distant relatives you barely know could receive your property instead of people you truly care about.

Failing to make a will means you have no control over who benefits from your life’s work. The results can be surprising—and not in a good way.

6. Your Digital and Personal Assets Are in Limbo

In the digital age, your online accounts, photos, and digital assets often have both sentimental and financial value. Without a will, there’s no clear direction on who can access or manage these items. The same goes for personal possessions with emotional significance. Your family may have to guess your wishes or, worse, fight over them.

Having a will allows you to specify who receives what, reducing confusion and helping preserve your legacy.

How to Avoid the Pitfalls of Dying Without a Will

Creating a will is the most effective way to prevent the disorganization that occurs when someone passes away without one. It doesn’t have to be complicated or expensive. Even a basic will gives you control over your assets, guardianship for your children, and the ability to minimize family conflict. You can update your will as your life changes.

The state should not have the authority to decide matters that belong to you. The peace of mind you gain is worth the small investment of time.

Have you or someone you know experienced the consequences of passing away without a will? Share your experience or questions in the comments below—we’d love to hear your story.

What to Read Next…

  • Why Are So Many Boomers Dying Millionaires And Leaving No Will?
  • 7 Ways A Family Member Can Accidentally Trigger Probate
  • 10 Things You Should Never Say When Writing A Will
  • What Happens To Your Social Security If The Government Shuts Down Again
  • Why Even Wealthy Families Are Now Fighting Over Heirlooms
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.
Filed Under: Estate Planning Tagged With: Estate planning, family law, guardianship, Inheritance, Personal Finance, probate, wills

11 Things You Should Have in a “Grab-and-Go” Financial Binder for Emergencies

October 30, 2025 by Travis Campbell Leave a Comment

Binder
Image source: shutterstock.com

Emergencies usually provide no warning before they occur. A grab-and-go financial binder provides you with peace of mind while enabling you to take immediate action during emergencies such as natural disasters, hospitalizations, or evacuations. The binder holds vital financial papers that serve as security while keeping your money accessible during crises. During a crisis, avoid spending precious time searching for account numbers, insurance documents, and legal papers. Creating a complete financial binder at present will help you handle difficult financial situations better in the future. Let’s break down the 11 things you should include to ensure your financial emergency binder is ready to go.

1. Personal Identification Documents

Start with the basics. Include copies of driver’s licenses, passports, Social Security cards, birth certificates, and marriage certificates for everyone in your household. These documents prove your identity and are often needed to access services, file claims, or travel during emergencies. Store copies, not originals, to reduce the risk of loss.

2. Emergency Contact Information

List out phone numbers and addresses for family, close friends, doctors, and key professionals like your lawyer or accountant. Also include your employer’s contact details and those of your local emergency services. This ensures that, even if your phone dies or you lose access to digital records, you can still reach the people who matter most.

3. Medical Records and Health Insurance Details

Keep copies of your health insurance cards, a summary of each family member’s medical history, lists of medications, allergies, and immunization records for each family member. In an emergency, having this information readily available can speed medical care and help providers make informed decisions.

4. Financial Account Information

Your grab-and-go financial binder should have a section for all key bank accounts, credit cards, investment accounts, and retirement plans. List institution names, account numbers, and contact info for customer service. Do not include your online passwords but note where your password manager or secure login information is stored. This will help you or a trusted person manage your financial accounts if you’re unable to do it yourself.

5. Insurance Policies

Keep copies of all insurance policies, including home, auto, renters, life, and disability insurance. Include policy numbers, agent contact information, and a summary of coverage for each policy. If you need to file a claim after a disaster or accident, this information will be invaluable.

6. Estate Planning Documents

Include copies of your will, power of attorney, advance directives, and any trusts you’ve set up. These documents are essential if someone needs to make decisions on your behalf or settle your affairs. The grab-and-go financial binder should make it clear where the originals are stored and who is authorized to access them.

7. List of Recurring Bills and Obligations

Make a list of all regular bills—mortgage or rent, utilities, subscriptions, loan payments, and more. Note the due dates, amounts, and how each is paid (online, by mail, or auto-pay). This helps ensure nothing slips through the cracks if you’re away from home or unable to manage your finances for a time.

8. Property and Asset Documentation

Include copies of deeds, titles, and registration papers for your home, vehicles, and other valuable property. Add photos or a video inventory of your belongings for insurance purposes. If you have valuable collectibles or jewelry, document them here as well. This section of your financial emergency binder will help you prove ownership and file accurate claims if needed.

9. Tax Returns and Key Financial Statements

Store copies of your most recent federal and state tax returns, as well as important financial statements. If you need to apply for relief or loans or to prove income, these documents can be critical. You don’t need every year—usually the past two or three years are sufficient for your grab-and-go financial binder.

10. Important Legal Agreements

If you have prenuptial agreements, divorce decrees, custody papers, or business contracts, include copies in your binder. Legal documents can clarify your rights and obligations during stressful situations and help avoid confusion or disputes.

11. Digital Access and Password Guide

While you should never write down passwords in plain text, your financial emergency binder should have instructions for accessing your password manager or digital vault. Include master password hints or the location of a secure backup. This way, if you’re incapacitated, a trusted person can access your online accounts without compromising your security.

Making Your Financial Emergency Binder Work for You

A grab-and-go financial binder represents an excellent method to prepare for unexpected situations. You need to organize and verify all your required documents during this step. Review and update your binder at least once a year and after major life events, including marriage and divorce, and starting a new job.

Store your binder in a protected location that is both accessible and secure, such as a fireproof safe or a locked drawer. Tell a trusted friend or family member where it is. You should protect data by storing it in an encrypted cloud storage service that offers digital backup.

What financial documents do you store in your grab-and-go financial binder for emergencies? Have you located any important items we missed? Share your thoughts and tips in the comments below!

What to Read Next…

  • What Happens When a Medical Emergency Outpaces Your Emergency Fund
  • 5 Emergency Repairs That Could Force You Into Debt Overnight
  • Why Some People Feel Rich But Can’t Afford a $400 Emergency
  • 6 Monthly Bills You Should Cancel Immediately Even If You Can Afford Them
  • 8 Things You’re Doing That Make Criminals Think You’re an Easy Target
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.
Filed Under: Budgeting Tagged With: documents, emergency preparedness, Estate planning, Insurance, organization, Personal Finance, Planning

5 Genius Moves to Maximize Your 401k Match Aggressively

October 29, 2025 by Travis Campbell Leave a Comment

401k
Image source: shutterstock.com

Your financial future will benefit greatly from maximizing your 401k match potential. Employers make matching contributions through their benefits packages, yet most employees fail to take advantage of this opportunity. You should maximize your 401k match at full capacity because it represents free money that you would otherwise miss out on. The amount you will have available during retirement depends heavily on this factor. Your current minor adjustments will produce substantial future benefits because you should maximize all monetary benefits your employer provides.

Five effective methods exist to help you achieve the maximum 401k match potential, which will lead to better retirement savings than typical expectations.

1. Contribute Enough to Get the Full Match

It sounds simple, but the first step to maximize your 401k match aggressively is to contribute at least enough to receive your employer’s full match. Every company’s policy is different. Some match dollar-for-dollar up to a certain percentage, while others offer partial matches. Check your plan documents or talk to HR to find out exactly how your employer’s 401k match works.

If you’re only contributing 2% and your employer matches up to 5%, you’re missing out on free money. Adjust your payroll contributions so you always reach the threshold for the maximum match. Even if your finances are tight, prioritize getting this match before considering other investments. Remember, this is an immediate 100% return on your investment, something you rarely see elsewhere.

2. Front-Load Your Contributions

Want to maximize your 401k match aggressively right from the start of the year? Front-loading your contributions can help. Instead of spreading contributions evenly throughout the year, increase your contribution rate early on. This strategy helps your money start working for you sooner, taking advantage of compounding returns over a longer period.

However, be aware of your employer’s matching formula. Some companies match based on each paycheck, while others match based on your total annual contribution. If your employer only matches per paycheck, front-loading too much could mean missing out on some of the match. Double-check your policy to ensure you get the full employer contribution.

3. Avoid Taking Early Withdrawals or Loans

If you’re looking to maximize your 401k match aggressively, avoid dipping into your retirement savings before you reach retirement age. Early withdrawals and loans can reduce your balance, trigger taxes, and sometimes even result in penalties. Even if you repay a loan, you might miss out on employer matching contributions during the repayment period, especially if you pause or reduce your contributions.

It’s tempting to borrow from your 401k for emergencies or big expenses, but the long-term impact on your retirement savings can be significant. Instead, build an emergency fund outside your 401k to handle life’s surprises. This way, your retirement account keeps growing, and you continue to receive every possible matched dollar.

4. Increase Contributions When You Get a Raise

When your salary increases, it’s the perfect time to boost your 401k contributions and maximize your 401k match aggressively. Many people keep their contribution percentage the same after a raise, but even a small bump can make a big difference over time. If your employer matches up to a higher percentage, increasing your contribution means you’ll get more free money added to your account.

Set a reminder to revisit your 401k contribution rate whenever you get a raise or bonus. Even raising your contribution by 1% each year can add up. Some plans offer automatic escalation features that increase your savings rate annually—take advantage of them if available. This approach helps you stay on track with your retirement goals and ensures you never leave matching dollars behind.

5. Review and Rebalance Your Investments Regularly

Maximize your 401k match aggressively by making sure your investments are working as hard as your contributions. Many people set their asset allocation once and never revisit it. Over time, market fluctuations can leave your portfolio out of balance, potentially reducing your returns.

Check your 401k investments at least once a year. Rebalance to keep your risk and reward in line with your goals. This ongoing attention helps your matched contributions grow more efficiently. If you’re unsure how to rebalance, consider target-date funds or consult a financial advisor for guidance. The more you optimize your investments, the greater the long-term benefit from every matched dollar.

Building Wealth with Every Matched Dollar

You can reach the highest 401k match potential through aggressive methods, which do not require you to make drastic changes. The process involves performing regular small actions to obtain all available benefits from your workplace. Your retirement security will improve when you contribute enough to match the full amount, make your contributions at the right time, refrain from withdrawals, boost your contributions after salary increases, and maintain proper investment levels.

Don’t underestimate the power of your employer’s 401k match. Your nest egg will grow over time as these investments and their values accumulate. Make it a habit to review your strategy at least once a year and tweak it as needed. The more proactive you are, the more you’ll benefit in the long run. What method do you suggest for getting the highest possible 401k match benefit? Share your thoughts in the comments below!

What to Read Next…

  • Is Your Retirement Plan Outdated By A Decade Without You Knowing?
  • What Retirees Regret About Rolling Over Old 401ks Too Quickly
  • 6 Retirement Plan Provisions That Disqualify You From Aid
  • How Financial Planners Are Recommending Riskier Portfolios In 2025
  • 10 Employer Perks That Void Retirement Tax Breaks
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.
Filed Under: Retirement Tagged With: 401(k), employer match, investing, Personal Finance, Retirement, savings

The Pawn Shop Trap: Why It’s One of the Worst Ways to Get Cash

October 29, 2025 by Travis Campbell Leave a Comment

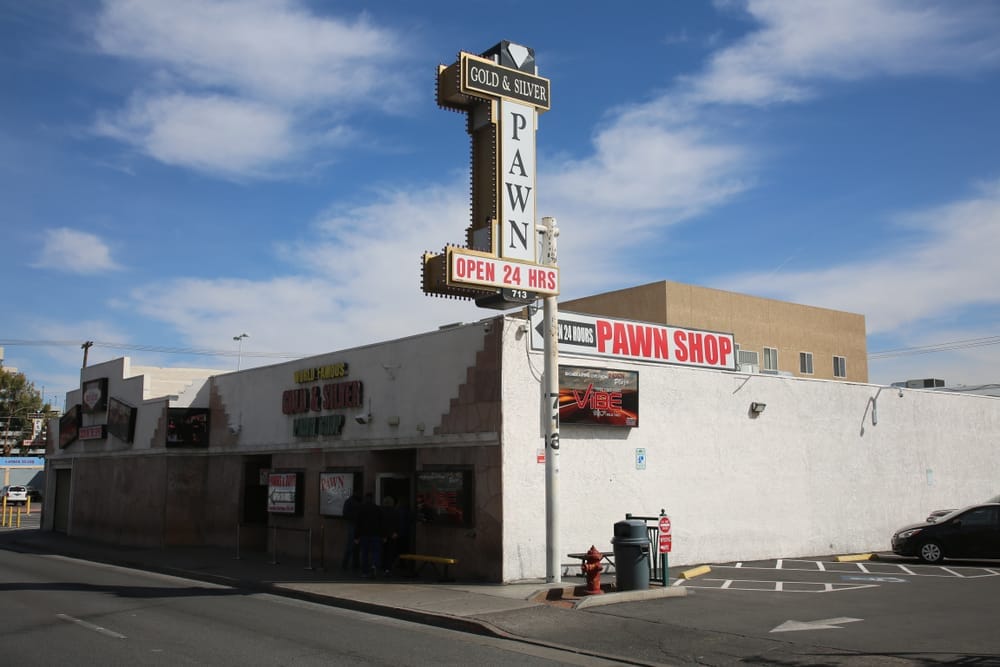
pawn shop
Image source: mikeledray / Shutterstock.com

People visit pawn shops because they require instant financial assistance to obtain cash right away. The service delivers cash instantly and does not perform credit checks. But is it really a good idea? Using a pawn shop for immediate financial needs will end up costing you more than what you initially borrow. Most people remain unaware of the actual process of pawn shop loans and their complete set of expenses. Before handing over your valuables, it’s important to know why the pawn shop trap is one of the worst ways to get cash and what you might be sacrificing in the process.

1. Extremely High Interest Rates and Fees

The primary reason the pawn shop trap is so dangerous is the steep cost of borrowing. Pawn shops typically charge interest rates far higher than banks or even payday lenders. It’s not unusual to see monthly interest rates between 10% and 25%, plus additional fees. Over a few months, these charges add up fast. If you borrow $100 and pay 20% interest per month, you’ll owe $140 after just two months—often more with fees. That’s a huge price to pay for a short-term loan.

Many borrowers don’t realize how quickly these costs can spiral. If you can’t repay on time, you could end up losing your item and still not have solved your cash problem. That’s why the pawn shop trap is such an expensive option for getting cash.

2. Risk of Losing Your Valuables

When you pawn something, you’re putting up a valuable item—like jewelry, electronics, or tools—as collateral. If you can’t repay the loan (plus interest and fees) by the deadline, the pawn shop keeps your property. For many people, these items have sentimental value or are hard to replace. The risk is very real: about 15% of pawned items are never reclaimed.

Even if you intend to get your item back, unexpected expenses or delays can make it impossible. You could end up losing a family heirloom or something essential just for a small amount of cash.

3. You Get Far Less Than Your Item Is Worth

Pawn shops make money by paying you as little as possible for your valuables. They typically offer only 25% to 60% of an item’s resale value. If you bring in a $500 watch, you might get just $125 to $300. The shop needs to cover its risks and make a profit, so you’ll never get full value.

Even if you’re confident you’ll repay the loan, you still walk out with a fraction of your item’s worth. If you end up defaulting, the shop resells your property at a hefty markup. This is yet another reason why the pawn shop trap is a poor way to access cash.

4. Short Repayment Windows

Pawn loans are meant to be short-term—often just 30 to 60 days. That doesn’t leave much time to get your finances back on track and repay what you owe. If you miss the deadline, your item is gone. Some shops offer extensions, but they’ll charge you even more in interest and fees. This adds pressure at a time when you’re already stressed and strapped for cash.

Many borrowers end up paying to extend their loans multiple times, paying far more than they ever borrowed in the first place. The short term of pawn shop loans is a key reason they can quickly become a financial trap.

5. No Credit Building or Financial Progress

Pawn shops don’t report your loan or repayment to credit bureaus. That means even if you repay on time, you’re not building credit or improving your financial situation long-term. If you need cash again in the future, you’ll be back where you started—without better options.

Other types of loans, like credit cards or personal loans, can at least help you build a positive credit history if managed well. With the pawn shop trap, you’re stuck in a cycle that doesn’t help you move forward financially.

Better Alternatives to Pawn Shops

Before you fall into the pawn shop trap, consider other ways to get cash. Selling items outright through online marketplaces like eBay or local listing sites can net you more money than pawning. You keep the full sale amount and avoid high fees. If you have a steady income, you may qualify for a small personal loan from a credit union or online lender—often at much lower rates than pawn shops charge.

Some communities offer nonprofit programs or payday alternative loans to help people in a pinch. Even asking friends or family for a small loan can be less costly and risky than a pawn shop. If you’re struggling with debt or ongoing financial problems, talking to a nonprofit credit counselor can help you find a sustainable solution. The key is to avoid the pawn shop trap so you don’t lose your valuables or end up paying far more than you borrowed.

Think Twice Before You Pawn

Pawn shops serve as a fundamental financial solution, providing immediate cash access to people who need it. The pawn shop trap is one of the most dangerous ways to obtain money because it involves significant costs, potential risks, and lasting consequences. You should explore alternatives rather than choosing the first option that comes to mind. You should handle pawning carefully because it protects your valuable possessions and your financial security.

Have you ever visited a pawn shop to get quick access to cash? What was your experience? Share your thoughts or questions below.

What to Read Next…

  • The Benefits Of Taking Personal Loans And Their Impact On Credit Scores
  • 5 Things That Instantly Decrease Your Credit Score By 50 Points
  • Are These 8 Money Saving Tricks Actually Keeping You Broke?
  • 7 Hidden Fees That Aren’t Labeled As Fees At All
  • 5 Invisible Service Charges Eating Into Your Bank Balance
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.
Filed Under: Debt Management Tagged With: alternatives, Debt, interest rates, loans, pawn shops, Personal Finance, quick cash

Can I Afford to Fire My Financial Person and Take All My Money Back?

October 29, 2025 by Travis Campbell Leave a Comment

financial person
Image source: shutterstock.com

Thinking about firing your financial advisor and taking all your money back is a big decision. You might doubt the costs of working with a financial advisor and their ability to provide helpful guidance, and whether you could achieve better results independently. You’re not alone—many people wonder if they’re getting enough value for what they pay. The decision to handle your financial matters independently extends past monetary value. The process helps you build confidence as you learn the necessary steps to complete the task.

You need to know if you have enough funds to dismiss your financial advisor while retrieving all your financial assets. You’re already on the right track. You need to assess all critical aspects before deciding to move. You can use this approach to select a decision that matches your personal objectives, daily routine, and mental serenity.

1. Know What You’re Paying For

Before you fire your financial person, take a close look at what you’re actually paying for. Are you paying a percentage of assets under management, a flat fee, or commissions? Pull out your statements or ask your advisor directly for a breakdown. Sometimes, the fees are buried in fine print or deducted from your returns, making them easy to miss.

Understanding the real cost is critical. If you’re paying 1% or more annually, ask yourself if you’re getting enough value in return. Some advisors offer comprehensive planning, tax help, and behavioral coaching. Others may just pick investments. If you’re mainly getting basic portfolio management, you might decide that handling things yourself is worth considering. The answer to “Can I afford to fire my financial person and take all my money back?” starts with knowing what you’re paying for and if it matches your needs.

2. Evaluate Your Investment Knowledge

Managing your own money isn’t rocket science, but it does take some time and effort. Do you know how to build a diversified portfolio? Are you comfortable choosing between stocks, bonds, mutual funds, or ETFs? How would you handle a market downturn?

If these questions make you nervous, that’s okay. There are plenty of resources to help you learn. Still, be honest about your willingness to learn and stay engaged. Some people thrive on DIY investing, while others find it stressful. Your answer to “Can I afford to fire my financial person and take all my money back?” depends on your investment comfort level.

3. Understand the Transfer Process

Taking all your money back isn’t as simple as just clicking a button. You’ll need to transfer your accounts from your advisor’s firm to a new brokerage or possibly cash out investments. There might be transfer fees, exit charges, or tax consequences.

Ask your current advisor for a list of potential fees and steps involved. Some firms charge exit fees or have restrictions on certain products. If you hold mutual funds or annuities, you may face surrender charges or redemption fees. Make sure you know the timeline, as some transfers can take several weeks. Planning ahead helps you avoid costly surprises and unnecessary stress.

4. Consider Tax Implications

Taxes can make a big difference when you move your money. Selling investments in a taxable account might trigger capital gains taxes. If you’re moving retirement accounts, like IRAs or 401(k)s, you’ll want to use a direct transfer or rollover to avoid penalties and taxes.

Before you fire your financial person, talk with a tax professional or use a calculator to estimate your potential tax bill. This step is often overlooked, but it’s crucial. Sometimes, leaving investments as they are until the timing is right can save you thousands. The answer to “Can I afford to fire my financial person and take all my money back?” may hinge on your tax situation.

5. Assess Your Time Commitment

Managing your own money takes time. Are you willing to review your portfolio regularly, rebalance, and stay up to date with financial news? Some people enjoy this and make it part of their routine. Others would rather spend their time elsewhere.

Think about your schedule and your interest level. If you’re already stretched thin, it might make sense to keep some professional help, even if you cut back on services. If you want more control and don’t mind spending a few hours a month, DIY could be a good fit.

What’s Your Next Move?

Asking “Can I afford to fire my financial person and take all my money back?” is a sign that you’re thinking critically about your financial future. There’s no one-size-fits-all answer. Taking control of operations provides certain individuals with both financial benefits and independence from external costs. People accept the expense of professional advice because they want to achieve peace of mind.

Take your time to evaluate all options by considering their advantages and disadvantages before making any decision. Basic account management should be handled through self-management, but you should use advisor services for complex planning requirements. Your selection needs to align with your predefined targets and your individual level of ease with the process. Have you fired your financial advisor or considered it? What elements determined your selection of the final option? Share your thoughts in the comments below!

What to Read Next…

  • 8 Signs Your Financial Advisor Is Not Acting In Your Best Interest
  • What If The Person Managing Your Finances Can’t Be Trusted?
  • 10 Financial Advisor Promises That Have Left Clients With No Safety Net
  • What Should You Do If Your Financial Advisor Stops Returning Your Calls?
  • 6 Reasons Your Financial Advisor May Not Be Acting In Your Best Interest
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.
Filed Under: Financial Advisor Tagged With: DIY investing, financial advisor, investment fees, Personal Finance, portfolio management, tax implications

8 Critical Questions You Must Ask Before Buying Long-Term Care Insurance

October 28, 2025 by Travis Campbell Leave a Comment

long term care
Image source: shutterstock.com

Planning for the future involves preparing for unexpected events, and long-term care insurance can help with that. This type of insurance provides financial protection for expenses that standard health insurance and Medicare do not cover, such as daily assistance and nursing home care. Given the annual increase in long-term care service costs, it’s important to make informed decisions about purchasing long-term care insurance to safeguard your financial stability. Different policies require careful evaluation, as overlooking key questions during this process can lead to costly mistakes. It’s essential to explore all options before deciding which choice is best for your family. Here are eight critical questions you should consider when evaluating long-term care insurance.

1. What Types of Care Does the Policy Cover?

Long-term care insurance policies can vary widely in the types of services they cover. Some may pay for in-home care, assisted living, adult day care, nursing home care, or respite care, while others might exclude certain options. Ask for a detailed list of covered services and settings. This helps you understand whether the policy aligns with your preferences and future needs. If you have a strong desire to stay at home as long as possible, make sure in-home care is included.

2. When Do Benefits Start?

This question addresses the “elimination period”—the waiting period before your insurance begins to pay for care. Typical elimination periods range from 30 to 90 days, but some policies may require even longer waits. During this time, you’ll have to pay for care out of pocket. Clarifying when benefits start can help you budget for any potential gaps and avoid unpleasant surprises.

3. How Much Does the Policy Pay Per Day or Per Month?

Long-term care insurance policies often set a daily or monthly benefit limit. If your care costs exceed this amount, you’re responsible for the difference. Ask about both the maximum amount the policy will pay and how it compares to the average cost of care in your area.

4. What Is the Benefit Period?

The benefit period is how long the policy will pay for your care. Some policies cover a set number of years (like two, three, or five), while others offer lifetime coverage. A longer benefit period usually means higher premiums. Think about your family’s health history and your own risk factors to decide which benefit period makes the most sense for you. Weigh the cost of premiums against the potential need for extended care.

5. Does the Policy Include Inflation Protection?

Care costs increase over time, so it’s important to know if your policy’s benefits will keep up. Inflation protection increases your daily or monthly benefit over the years, helping your coverage stay relevant. Some long-term care insurance policies offer automatic inflation adjustments, while others require you to opt in (usually for an extra cost). Skipping this feature to save on premiums may backfire if you need care many years from now, and your benefits fall short.

6. What Are the Policy’s Exclusions and Limitations?

No insurance policy covers everything. Long-term care insurance often excludes certain conditions, treatments, or situations. Common exclusions include care required due to substance abuse, mental disorders (other than dementia), or self-inflicted injuries. Pre-existing conditions may also be excluded for a period after you buy the policy. Read the fine print and ask for a plain-language list of exclusions. Knowing what isn’t covered is just as important as knowing what is.

7. How Stable Are the Premiums?

It’s easy to focus on the initial cost, but long-term care insurance premiums can rise over time. Some companies have raised rates on existing policyholders, sometimes by large amounts. Ask the insurer about their history of premium increases and whether your premiums are guaranteed or subject to change. Understanding the potential for future increases can help you decide if the policy will remain affordable as you age.

8. What Is the Financial Strength of the Insurance Company?

Long-term care insurance is a promise to pay benefits that you may not need for decades. That’s why it’s important to choose a company with a strong financial track record. Check ratings from agencies like AM Best, Moody’s, or Standard & Poor’s. A financially sound insurer is more likely to be there when you need them.

Making a Confident Decision About Long-Term Care Insurance

Buying long-term care insurance is a major financial decision. The essential questions you ask will help you assess different policies and stop future mistakes that could result in financial losses. The right policy needs to fulfill your requirements while staying within your budget and meeting your needs for upcoming medical expenses. Take your time gathering information and consult a fee-only financial advisor for advice before making any final decisions. Your additional work will create peace of mind for yourself and your family members who will exist in the future.

Have you faced any challenges or surprises while shopping for long-term care insurance? Share your experiences or questions in the comments below!

What to Read Next…

  • Why Your Long Term Care Policy Might Be Useless After Age 75
  • 5 Financial Habits That Quietly Void Long Term Care Policies
  • 7 Financial Assumptions That Collapse After One Health Emergency
  • 10 Financial Questions That Could Undo Your Entire Retirement Plan
  • 7 Retirement Perks That Come With Shocking Hidden Costs
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.
Filed Under: Insurance Tagged With: elder care, Insurance, long-term care insurance, Personal Finance, Planning, retirement planning

Accelerate Your Debt Repayment Using Our Powerful Snowball Method.

October 27, 2025 by Travis Campbell Leave a Comment

debt payoff
Image source: shutterstock.com

The need to pay multiple monthly bills makes debt responsibilities too heavy to handle. High interest rates combined with minimum payment requirements create a situation that prevents you from escaping continuous debt obligations. People who want to escape debt need to develop plans and learn how to control their spending. The debt snowball method serves as a solution for this situation. The system offers tools to help you build debt-repayment speed and stay motivated. Our guide provides the steps to use the snowball method for debt repayment so you can start making significant progress.

1. List All Your Debts

The first step in the debt snowball method is to get a clear picture of what you owe. Start by making a list of every outstanding debt. Include credit cards, personal loans, medical bills, car loans, and any other debts you have. For each, note the total balance, minimum monthly payment, and interest rate. This step might feel intimidating, but seeing everything in one place is crucial for building your repayment plan. Remember, you can’t tackle what you don’t track.

2. Organize Debts from Smallest to Largest

Now, arrange your debts from the smallest balance to the largest, regardless of interest rate. The debt snowball method focuses on quick wins. By knocking out the smallest debts first, you create a sense of accomplishment early on. This psychological boost can help keep you motivated to stick with your plan. Don’t worry about the interest rates for now—the focus is on building momentum.

3. Make Minimum Payments on Everything Except the Smallest Debt

To accelerate your debt repayment, you need to stay current on all your obligations to avoid late fees and credit damage. Continue making the minimum payments on each debt except for the one with the smallest balance. This ensures you’re not falling behind while you focus your energy on eliminating one debt at a time. The idea is to direct all your extra funds toward the smallest balance so you can pay it off as quickly as possible.

4. Throw Extra Money at Your Smallest Debt

Every extra dollar you can find goes toward the smallest debt. This could come from cutting expenses, taking on a side gig, or using your tax refund. The more you pay above the minimum, the faster you’ll see that balance disappear. Once the smallest debt is gone, you free up its payment amount to add to your next target. This is the core of the debt snowball method—it’s where your progress really starts to speed up.

5. Roll Payments Over as Debts Disappear

Once you’ve paid off your smallest debt, take the payment you were making on it and add it to the minimum payment of your next smallest debt. This creates a snowball effect: your payments grow larger with each debt you eliminate. As your snowball grows, you’ll pay off larger debts more quickly. This momentum makes it easier to stay motivated and continue accelerating your debt repayment.

6. Celebrate Milestones to Stay Motivated

It’s important to recognize your progress along the way. Every time you pay off a debt, take a moment to celebrate. This could be as simple as a small treat or sharing your success with a friend. These milestones reinforce that your hard work is paying off. Staying motivated is key, especially when working through larger balances.

7. Adjust and Refine Your Budget Regularly

Your financial situation may change over time. Review your budget each month to see if you can free up more money for your debt snowball. Maybe you’ve paid off a car, reduced utility bills, or picked up some extra work. Every little bit helps accelerate your debt repayment. Don’t hesitate to adjust your plan as needed to keep your momentum going.

8. Avoid Building New Debt

While you’re working through your debt snowball method, try to avoid taking on new debt. Using credit cards or loans for unnecessary expenses can slow your progress and undo your hard work. If you need tips on building better financial habits, check out these resources from the Consumer Financial Protection Bureau. Staying disciplined will help you reach your debt-free goal faster.

Your Path to Financial Freedom

The debt snowball method is a straightforward but effective way to speed up your debt repayment. You establish a debt management system that builds confidence through a single debt focus and rolling payments forward. Watching your debts disappear step by step creates a sense of inspiration and satisfaction. Stick with your plan, celebrate your progress, and stay committed to your goal. The debt snowball method helps people achieve unexpected financial progress through its successful debt elimination strategy.

What difficulties or achievements have you faced during your debt repayment acceleration process? Share your thoughts in the comments!

What to Read Next…

  • The Benefits Of Taking Personal Loans And Their Impact On Credit Scores
  • 5 Things That Instantly Decrease Your Credit Score By 50 Points
  • Are Budgeting Apps Designed To Push You Into Debt
  • 9 Surprising Penalties For Paying Off Loans Too Early
  • Are These 6 Helpful Budget Tips Actually Ruining Your Finances
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Debt Management Tagged With: budgeting, debt repayment, debt-free journey, motivation, Personal Finance, snowball method

Flight Attendants Are Revealing The Sneaky Ways Airlines Get You to Spend More Money

October 27, 2025 by Travis Campbell Leave a Comment

flight attended
Image source: shutterstock.com

Air travel appears to be a simple process which involves ticket purchase followed by seat selection before boarding the flight. But behind the scenes, airlines have a host of strategies to get you to spend more than you planned. Flight attendants serve as the first point of contact for these initiatives because they have started to reveal the hidden methods airlines use to increase their profits. Travelers who fly often and those who watch their expenses need to understand airline strategies for additional revenue to save their money. With ticket prices often appearing low at first glance, the real cost of flying often comes from these less obvious upsells. The following article explains how airlines use deceptive methods to increase your spending during flights so you can prevent unwanted expenses when traveling.

1. The Art of the In-Flight Sales Pitch

Flight attendants are trained to sell, and airlines equip them with scripts designed to tempt passengers. Mid-flight announcements about snacks, drinks, or duty-free items are carefully timed. The goal? To catch you when you’re bored, hungry, or just looking for a distraction. These offers may sound appealing, but in reality, the prices are often much higher than what you’d pay on the ground. The next time you hear a chipper voice promoting a “limited-time offer,” remember it’s all part of the plan to get you to spend more money while you’re a captive audience.

2. Strategic Placement of Food and Drink Menus

Ever notice how menus are tucked into seat pockets or handed out just as you start to feel hungry? That’s no accident. Airlines know that hunger and thirst are powerful motivators. Flight attendants reveal that displaying menus at eye level and announcing special combos are tactics to encourage purchases. The prices for these snacks and drinks are marked up significantly. By understanding this upselling strategy, you can pack your own snacks and avoid paying extra for convenience.

3. Limited-Time Offers and Scarcity Tactics

Airlines love to create a sense of urgency. Flight attendants may announce that there are “only a few” of a particular snack or drink left, even if the supply is adequate. This scarcity tactic pushes passengers to buy now rather than risk missing out. Airlines get you to spend more money by making you feel like you’ll lose out if you don’t act quickly. Staying aware of these psychological tricks can help you resist the pressure to splurge.

4. Upgrades and Seat Selection Fees

Gone are the days when you could pick your seat for free. Airlines now charge for everything from extra legroom to window seats. Flight attendants sometimes walk the aisle offering last-minute upgrades, making them sound like a great deal. In reality, these fees can add up fast. This is another way airlines get you to spend more money—by presenting optional extras as must-haves for comfort. If you’re not picky about where you sit, skipping these offers is a smart way to save.

5. Promoting Airline Credit Cards Mid-Flight

It’s not uncommon for flight attendants to make announcements about airline-branded credit cards. These pitches often include promises of free miles, priority boarding, or even a free checked bag. While some benefits can be worthwhile, the main aim is to get you to sign up and spend more money with the airline in the long run. Before biting on these offers, check if the perks truly outweigh the costs and if you’ll use the card enough to justify the annual fee.

6. Bundling Services for “Savings”

Bundling is a classic upselling technique. Airlines package things like checked bags, priority boarding, and in-flight meals, claiming you’ll save money by buying them together. While it might sound like a bargain, you could end up paying for extras you don’t need. Flight attendants sometimes reinforce these bundles during boarding or in announcements. To avoid falling for this tactic, consider what you actually need for your flight and purchase only those services individually.

7. Emotional Triggers and Personalization

Flight attendants are skilled at reading passengers and tailoring their pitches. If they notice you’re traveling with kids, they might suggest snack boxes or toys. Couples might be offered champagne or chocolates. Airlines get you to spend more money by making their offers feel personal and relevant. These small touches can be tempting, but they’re designed to open your wallet. Setting a budget before your flight can help you stick to it, no matter how personalized the pitch.

8. Making Payments Frictionless

Many airlines now accept tap-to-pay and mobile payments, making it effortless to buy something mid-flight. This frictionless payment process removes the mental barrier of handing over cash, increasing the likelihood that you’ll make impulse purchases. Flight attendants often have handheld devices ready, so transactions happen quickly. If you want to avoid overspending, decide in advance if you’ll make any in-flight purchases and stick to your plan.

Smart Ways to Outsmart Airline Upselling

The knowledge you gained from flight attendants helps you identify the sneaky tactics that lead you to spend additional money. The marketing strategies used during flights include flight sales pitches, strategic food placement, and emotional marketing techniques that operate from start to finish of the flight experience. Travelers who understand these fees can pick suitable options to protect their money during their trips.

You should bring your own food for the flight, check which extra items you require, and set aside money for costs. The less you fall for upselling tricks, the more you’ll save for your actual destination.

What sneaky airline upselling tricks have you noticed on your travels? Share your experiences and tips in the comments!

What to Read Next…

  • 7 Hidden Fees That Aren’t Labeled As Fees At All
  • Are Automatic Renewals Draining More Than You Realize?
  • 5 Budgeting Tools That Trick You Into Higher Spending
  • 7 Tactics Grocery Stores Use To Keep You From Thinking About Price
  • Are Financial Apps Sharing Your Spending Data More Than You Realize?
Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Travel Tagged With: air travel, airline fees, budget travel, flight attendants, Personal Finance, travel tips, upselling

  • « Previous Page
  • 1
  • …
  • 64
  • 65
  • 66
  • 67
  • 68
  • …
  • 186
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework