• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for banking

Big Banks Are Still Collecting Billions in Overdraft and NSF Fees

February 11, 2026 by Brandon Marcus Leave a Comment

Big Banks Are Still Collecting Billions in Overdraft and NSF Fees
Image source: shutterstock.com

We live in an era where you can deposit a check by waving your phone at it, but big banks are still raking in billions from overdraft and NSF (non-sufficient funds) fees. It feels like a relic from another time, yet it remains one of the most profitable corners of consumer banking. And while many financial institutions have trimmed or restructured these fees in recent years, the overall haul is still massive.

This isn’t just a quirky footnote in the world of personal finance—it’s a reminder of how the banking system continues to shape the everyday lives of millions of people.

The Fee Machine That Just Won’t Quit

Overdraft and NSF fees have long been a dependable revenue stream for major banks, and despite public pressure and regulatory scrutiny, they haven’t disappeared. In fact, some of the largest U.S. banks still generate billions from these charges every year. Even as some institutions have reduced the cost of overdraft fees or eliminated NSF fees altogether, the overall system still leans heavily on customers who slip into the red.

These fees often hit people who are already financially stretched, turning a small miscalculation into a costly setback. What makes this even more striking is that the technology exists to prevent many of these situations, yet the incentives to maintain the status quo remain strong.

Why These Fees Stick Around

If you’ve ever wondered why overdraft and NSF fees are still so common, the answer is surprisingly simple: they’re incredibly profitable. Banks argue that these fees help cover the cost of managing accounts and processing transactions, but the revenue they generate far exceeds those operational expenses.

Overdraft programs are structured in ways that maximize the likelihood of triggering a fee, such as processing larger transactions first or approving debit purchases that push accounts negative. While some banks have shifted toward more consumer-friendly practices, the industry as a whole still relies heavily on these charges. The persistence of these fees isn’t about necessity—it’s about financial incentive.

The People Who Pay the Most

One of the most troubling aspects of overdraft and NSF fees is how unevenly they’re distributed. A relatively small percentage of account holders end up paying the majority of these charges, often because they’re living paycheck to paycheck. When every dollar matters, timing becomes everything, and a single delayed deposit or unexpected bill can trigger a cascade of fees.

This creates a cycle that’s hard to escape, especially when multiple fees hit in rapid succession. For many households, these charges aren’t just an inconvenience—they’re a genuine financial burden that can derail budgets and deepen stress.

The Push for Change Is Growing

The good news is that momentum for change is building. Regulators have increasingly scrutinized overdraft practices, and several major banks have voluntarily reduced or eliminated certain fees. Some have introduced grace periods, low-balance alerts, or no-fee overdraft cushions to help customers avoid penalties.

These shifts show that the industry is capable of evolving, even if progress feels slow. Still, the overall fee revenue remains enormous, and many institutions continue to rely on these charges. For consumers, staying informed is essential, because the landscape is changing—but not fast enough to assume your bank has your back.

What Consumers Can Do Right Now

While the system may not transform overnight, consumers have more power than they realize. One of the most effective steps is simply comparing banks and switching to one that offers more consumer-friendly policies. Many online banks and credit unions have eliminated overdraft fees entirely or offer far more forgiving programs.

Setting up account alerts, keeping a small buffer in checking, or linking to a savings account can also help reduce the risk of fees. And if a fee does hit, it’s always worth asking your bank to reverse it—many will, especially if it’s a rare occurrence. Taking a proactive approach can save real money over time and reduce the stress of managing day-to-day finances.
Big Banks Are Still Collecting Billions in Overdraft and NSF Fees
Image source: shutterstock.com

What This Means for the Future of Banking

The continued reliance on overdraft and NSF fees raises important questions about the future of consumer banking. As technology advances and competition increases, the pressure on traditional banks to modernize their fee structures will only grow. Consumers are becoming more aware of their options, and institutions that cling to outdated practices risk losing customers to more transparent, flexible alternatives.

The shift won’t happen overnight, but the trend is clear: people want banking that works for them, not against them. Staying informed and choosing institutions that align with your financial values can help push the industry in a better direction.

A Smarter Way Forward for Your Money

At the end of the day, overdraft and NSF fees aren’t going away just yet, but that doesn’t mean consumers are powerless. Knowing how these fees work, why they persist, and what alternatives exist can help you make choices that protect your wallet and reduce unnecessary stress. The banking world is slowly evolving, and your decisions play a part in shaping that future. Staying alert, comparing options, and advocating for yourself can make a meaningful difference in how much you pay—and how much control you feel over your financial life.

What do you think? Should banks be doing more to reduce or eliminate these fees? How have they gotten in your financial way? Tell us all your thoughts in the comments below.

You May Also Like…

Why More Americans Are Being Charged Fees They Never Explicitly Agreed To

Bankrate Projects Credit Card Rates Will Only Drop to 19.1% by End of 2026

5 Outrageous Fees Hidden in Everyday Banking Services

Breaking Up Without Breaking the Bank: A Guide to Affordable Divorce

What the Stars on Your 2026 Bank Statement Really Means for Your Privacy

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Banking Tagged With: bank policies, banking, big banks, budgeting, Consumer Protection, financial literacy, money management, NSF fees, overdraft fees, Personal Finance, savings tips

The Federal Reserve Rate Cut That Did Nothing for Credit Card Holders

February 5, 2026 by Brandon Marcus Leave a Comment

The Federal Reserve Rate Cut That Did Nothing for Credit Card Holders
Image source: shutterstock.com

The Federal Reserve made headlines with its long‑awaited rate cut, and for a brief, shining moment, millions of credit card holders dared to hope. Maybe—just maybe—their sky‑high APRs would finally ease up. Perhaps carrying a balance wouldn’t feel like dragging a boulder uphill. And maybe this was the break everyone had been waiting for.

And then… nothing happened. Credit card interest rates barely blinked, balances didn’t get cheaper, and consumers were left wondering why the Fed’s big move felt like a firework that fizzled before it left the ground. If you’ve been staring at your statement wondering why your APR still looks like a bad joke, you’re not imagining it. There’s a very real reason the Fed’s rate cut didn’t help—and understanding it can save you money in ways the Fed never will.

Why Credit Card APRs Don’t Drop Just Because the Fed Says So

When the Federal Reserve cuts rates, it affects a lot of things—mortgages, auto loans, personal loans, and even savings account yields. But credit cards live in their own universe, one where interest rates are tied to the prime rate and to whatever margin your card issuer decides to tack on.

Yes, your APR is technically variable, but that doesn’t mean it moves in lockstep with the Fed. Even when the prime rate drops, issuers can keep their margins high, which means your APR barely budges. And because credit card rates are already at historic highs, many issuers simply choose not to pass along the full benefit of a rate cut. It’s not illegal, it’s not hidden—it’s just how the system works.

The Credit Card Industry Has Zero Incentive to Lower Your Rate

Credit card companies make money from interest, and right now, they’re making a lot of it. With average APRs sitting well above 20%, issuers have little motivation to reduce rates unless they absolutely have to. A Fed rate cut gives them the option to lower rates, but not the requirement. And because consumer demand for credit remains strong, issuers know they can maintain high APRs without losing customers.

Even when the prime rate shifts, the margin they add on top can stay exactly the same. This is why your APR might drop by a fraction of a percent—just enough to technically reflect the Fed’s move—but not enough to make any meaningful difference on your monthly bill. It’s a system designed to benefit lenders first and borrowers last.

The Federal Reserve Rate Cut That Did Nothing for Credit Card Holders
Image source: shutterstock.com

Variable APRs Move Slowly—And Sometimes Not at All

Many credit cards come with variable APRs, which means they’re supposed to adjust when benchmark rates change. But “adjust” doesn’t mean “drop dramatically.” In reality, variable APRs often move in tiny increments, and issuers can delay adjustments depending on their internal policies.

Some cards only update APRs quarterly, while others adjust monthly. And even when they do adjust, the change is usually small—think tenths of a percentage point, not whole numbers. For someone carrying a balance, that tiny shift barely makes a dent. So while the Fed’s rate cut may technically ripple through the system, it’s more like a gentle ripple in a bathtub than a wave strong enough to lower your debt burden.

Record‑High Consumer Debt Keeps APRs Elevated

Another reason credit card rates remain stubbornly high is the sheer amount of consumer debt in circulation. Americans are carrying record levels of credit card balances, and delinquency rates have been rising. When lenders see increased risk, they raise margins to protect themselves. Even if the Fed lowers rates, issuers may keep APRs high to offset the risk of borrowers falling behind.

This means your interest rate is influenced not just by economic policy, but by the behavior of millions of other cardholders. It’s a collective effect that keeps APRs elevated even when the broader financial environment becomes more favorable.

Why Your Minimum Payment Didn’t Shrink Either

Even if your APR technically dropped a little, your minimum payment probably didn’t. That’s because minimum payments are calculated using formulas that prioritize fees, interest, and a small percentage of your principal. A tiny APR reduction doesn’t change the math enough to lower your minimum.

And if your balance has grown due to everyday spending, inflation, or unexpected expenses, your minimum payment may actually increase despite the Fed’s rate cut. It’s a frustrating reality, but it’s also a reminder that relying on minimum payments is one of the most expensive ways to manage credit card debt.

What You Can Do When the Fed Won’t Save You

The good news is that you’re not powerless. Even if the Fed’s rate cut didn’t help, there are strategies that can. One of the most effective is calling your credit card issuer and asking for a lower APR. Many companies will reduce your rate if you have a strong payment history or if you mention that you’re considering transferring your balance elsewhere.

Speaking of balance transfers, 0% APR offers can be a game‑changer if you qualify and can pay off the balance before the promotional period ends. You can also explore debt‑consolidation loans, which often have lower rates than credit cards, especially after a Fed rate cut. And if you’re feeling overwhelmed, nonprofit credit counseling agencies can help you create a plan that reduces interest and simplifies payments.

Rate Cuts Don’t Fix Credit Card Debt—You Do

The Federal Reserve can influence a lot of things, but it can’t force credit card companies to lower your APR in a meaningful way. That power still lies with you. Whether it’s negotiating your rate, switching to a better card, consolidating your debt, or adjusting your spending habits, the most effective changes come from your own actions. The Fed may set the stage, but you’re the one who gets to rewrite the script. And the more you understand how credit card interest really works, the easier it becomes to take control of your financial story.

What’s the most surprising thing you’ve learned about credit card interest rates lately? Give us your thoughts in the comments.

You May Also Like…

Retail Store Credit Cards Now Charging 30% APR on Average

Why Credit Card APRs Only Dropped 0.35% Even After Three Fed Rate Cuts in 2025

7 Ways Credit Card Debt Builds Faster Than Expected

The Quiet Credit Score Rule Change That’s Raising Borrowing Costs for Older Americans

10 Reasons Your Credit Card Fraud Claim Was Denied—and What You Can Do About It

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: credit cards Tagged With: APR, banking, consumer debt, credit cards, credit credit card problems, Debt, Fed rate cut, federal reserve, financial literacy, interest rates, money tips, Personal Finance

The Bank Account Features That Can Freeze Your Money Without a Court Order

January 27, 2026 by Brandon Marcus Leave a Comment

The Bank Account Features That Can Freeze Your Money Without a Court Order
Image source: shutterstock.com

Imagine logging into your bank account one morning, excited to pay your rent or grab your morning coffee, only to find your funds totally frozen. And it’s not because of a mistake or a legal battle you forgot about, but because of a little-known banking tool that can lock your money without ever setting foot in a courtroom.

Banks can initiate it for a variety of reasons, and the result is the same: your money is temporarily untouchable. While this might feel like a nightmare, it’s actually a mechanism designed to prevent bigger financial headaches, but it’s also a reminder that your money isn’t always as free as you might think.

How Bank Account Freezes Work And Why Banks Use Them

A bank account freeze isn’t about your bank being mean or plotting against you. It’s a tool used to manage risk, comply with regulations, and ensure the institution isn’t facilitating fraud or illegal activity. When a freeze happens, the bank effectively locks the funds in your account so they can’t be withdrawn, transferred, or spent.

It’s important to understand that banks don’t make these decisions lightly; they’re often responding to federal and state regulations, their own compliance requirements, or alerts from financial monitoring systems.

Suspicious Activity Alerts That Can Trigger A Freeze

One of the most common reasons for a freeze is suspicious transactions and activity. Banks have sophisticated algorithms that monitor transactions for anything unusual: a sudden influx of cash, large withdrawals, or transactions in a different country can all trigger alarms. Even consistent small purchases in odd locations can raise red flags.

When these alerts pop up, the bank might freeze the account to prevent potential fraud or identity theft. While it may feel invasive, these measures protect both the customer and the bank. Banks must balance customer convenience with the responsibility to safeguard the system from illicit activity, which sometimes means freezing money until the situation is clarified.

Fraud Prevention And Security Holds

Banks also freeze accounts proactively for fraud prevention. When a bank suspects unauthorized access or potential criminal activity, it can impose a security hold. Sometimes these holds are temporary, lasting only a few hours or days, but they can feel dramatic because they disrupt access to your money unexpectedly.

Customers might be asked to verify their identity, confirm recent transactions, or provide additional documentation. While it may feel like a hassle, these security measures are essential for preventing larger financial disasters.

How To React When Your Account Is Frozen

So, what should you do? First, contact your bank immediately and ask why the freeze was placed. Be ready to provide any necessary documentation or explanations to resolve the issue. If it’s related to suspicious activity, be prepared to verify recent transactions.

Keeping calm and proactive is key. Also, documenting your communications with the bank and keeping records ensures that the process moves as smoothly as it can.

The Bank Account Features That Can Freeze Your Money Without a Court Order
Image source: shutterstock.com

Protecting Yourself From Unexpected Freezes

Preventing an account freeze is not always entirely under your control, but there are steps you can take to reduce the likelihood. Monitor your account regularly for unusual activity and report discrepancies immediately. Keep your contact information up to date with your bank so alerts reach you promptly, and stay on top of any tax obligations and debts that could trigger government intervention.

Understanding the triggers for freezes can make it less surprising if one happens. While you may never completely eliminate the risk, these practices create a buffer of preparedness that makes handling a freeze much less stressful when it occurs.

Understanding The Bigger Picture

Remember, your money isn’t vanishing into a void; it’s temporarily inaccessible to protect you, the bank, or the system as a whole.

Freezes highlight the importance of understanding your financial environment and staying informed about how banking systems work behind the scenes. They may be inconvenient, but they also reflect the complex dance between personal finance, regulatory compliance, and security measures that keep our money safer than most people realize.

Conclusion: Tell Us Your Experience With Account Freezes

These stories are more common than many think, and they often carry lessons about vigilance, communication, and financial awareness.

Your experiences can help others understand these mysterious banking moves and approach them with confidence instead of panic. Drop your thoughts and reflections in the comments section below and join the conversation about one of the most unusual tools in modern banking.

You May Also Like…

The Verizon $20 Trap: Why That “Outage Refund” Text Message Could Wipe Out Your Bank Account

What To Look For When Opening A Bank Account For Your Teen

Breaking Up Without Breaking the Bank: A Guide to Affordable Divorce

8 Suspicious Portfolio Shifts After Advisor Change

What Happens if You Use Tax Software After Fraudulent Activity?


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Banking Tagged With: bank, bank account freeze, bank accounts, bank customer service, bank info, bank policies, bank policy, banking, banking issues, Banks, court order, fraud prevention, government order, security holds, suspicious transactions, tax liens

8 Money Habits That Increase Anxiety Without Helping

January 23, 2026 by Brandon Marcus Leave a Comment

These Are 8 Money Habits That Increase Anxiety Without Helping
Image source: shutterstock.com

Some people think money anxiety is just about not having enough. The truth is, the way you handle money can be just as anxiety-inducing as an empty bank account. Imagine staring at your finances, trying to “stay on top of everything,” only to feel your chest tighten, palms sweat, and brain spiral into “what if?” mode.

It turns out, a lot of our financial stress isn’t caused by dollars and cents—it’s caused by habits that make us feel busy, responsible, or cautious, but do very little to actually improve our situation. Let’s break down eight of these surprisingly counterproductive behaviors.

Obsessively Checking Your Bank Account Multiple Times A Day

It seems harmless, even responsible, right? Checking your balance frequently might make you feel like you’re in control, but it can quickly turn into a vicious cycle. Each glance at your bank app can trigger anxiety spikes, especially if you see pending charges or bills you forgot about.

Research shows that repetitive checking can heighten stress and worsen decision-making because your brain becomes overloaded with micro-worries. Instead of clarity, you get tension, racing thoughts, and sometimes even impulsive spending out of frustration.

Your account balance is a snapshot, not a full story, and obsessing over it rarely helps you plan or save. Creating a schedule for reviewing finances—like once a week—can maintain awareness without turning your day into a mini panic fest.

Comparing Yourself To Others Constantly

Scrolling through social media or talking to friends about money can trigger the comparison trap. “They bought a new car, I’m still paying off last year’s credit card,” is a familiar thought pattern for many.

Comparison doesn’t motivate; it triggers anxiety and self-doubt. Financial situations are deeply personal, shaped by debt, income, savings, and life priorities. Comparing yourself to someone else’s highlight reel is like judging your marathon performance against someone who’s already halfway to the finish line.

It can make you feel inadequate, overworked, and stressed about things that don’t actually matter. Focusing on your own goals, however small, provides measurable progress and relief from constant mental pressure.

Ignoring Budgets Because They Feel Restrictive

Many people avoid creating budgets because they fear it will feel like jail for their money. Ironically, not budgeting can create more anxiety than following one. Without a clear plan, every purchase triggers a moment of guilt or panic.

You’re left guessing whether you can afford things, constantly second-guessing yourself, and carrying the mental load of financial uncertainty. A budget is not a cage—it’s a map.

By defining limits and priorities, you can make confident spending decisions without that nagging “did I overspend?” stress. Over time, seeing your money allocated intentionally can actually be liberating, reducing financial tension.

Making Impulse Purchases As Emotional Therapy

Shopping to feel better is a classic stress-relief trick, but it backfires financially and emotionally. Every time you buy a mood boost, your short-term pleasure is overshadowed by long-term worry.

Credit card balances rise, bills loom, and guilt accumulates faster than the receipts in your wallet. Emotional spending also teaches your brain that money equals comfort, making anxiety worse when you don’t spend.

The smarter approach? Identify your triggers—boredom, stress, loneliness—and find low-cost ways to satisfy them. A walk, a phone call, or even a quick meditation can calm anxiety without jeopardizing your bank account.

Hoarding Receipts And Financial Papers Without Organization

Some people keep stacks of receipts, invoices, and statements because they think it might help later. The truth is, disorganized piles just fuel stress.

When you need information, finding it feels like searching for treasure in a hurricane. Hoarding can also create a sense of looming doom, like something bad will happen if you throw anything away.

Organization doesn’t have to be extreme; a simple filing system, labeled folders, or even a digital scanning habit can cut anxiety dramatically. Knowing where everything is provides mental space, so your brain isn’t constantly running “what if” simulations about lost documents.

These Are 8 Money Habits That Increase Anxiety Without Helping
Image source: shutterstock.com

Overthinking Every Financial Decision

Spending hours deliberating over every minor purchase—$5 coffee or $6?—can be exhausting. Overanalyzing doesn’t guarantee better choices; it breeds indecision and anxiety.

While thoughtful planning is important for big-ticket items, micromanaging tiny transactions is overkill. Constant rumination also hijacks your attention, reducing your mental bandwidth for more meaningful financial planning.

Letting go of the need for perfection in small matters builds confidence and reduces stress. Trusting your judgment on everyday expenses frees mental energy for decisions that actually matter.

Avoiding Professional Advice Out Of Fear Or Pride

Many people think they can figure out finances alone, believing that asking for help is a weakness. Avoiding professional guidance can heighten anxiety, because unresolved questions linger and stress compounds.

Financial advisors, accountants, or even reputable educational resources can provide clarity, reduce errors, and give peace of mind. The trick isn’t blind reliance—it’s informed decision-making.

Getting help often reduces stress immediately, creating a foundation for smarter, calmer financial habits. Pride may feel good temporarily, but clarity feels better in the long term.

Obsessing Over News Headlines And Market Fluctuations

Watching the stock market or economic news obsessively might feel like staying informed, but it’s more likely to spike anxiety than improve your portfolio. Markets fluctuate constantly, and day-to-day news is rarely actionable for long-term financial health.

Consuming too much financial media can create a sense of impending doom, even when your personal finances are stable. Instead, consider limiting exposure to periodic reviews instead of continuous monitoring. Controlled, intentional information intake keeps your mind focused and reduces panic-driven decision-making.

Rethink, Relax, And Reset Your Money Habits

Money stress doesn’t come solely from lack of funds; it often comes from behaviors that keep your mind spinning. By identifying habits that raise anxiety without real benefits—like overchecking balances, comparing yourself to others, or overanalyzing every decision—you can take steps toward calmer, smarter financial management. Experiment with pacing, organization, and professional guidance to reclaim peace of mind.

Now it’s your turn: what money habits have you noticed increasing your stress, and which strategies have helped you breathe easier? Feel free to comment with your experiences, tips, or aha moments. Your insight could be exactly what someone else needs to feel less overwhelmed.

You May Also Like…

7 Common Money Habits That Increase Stress Instead of Reducing It

8 Financial Habits That Quietly Drain Your Checking Account

How To Regularly Save Money At The Grocery Store

8 Toxic Money Habits That Are Silently Poisoning Your Relationship

Why Does Money Anxiety Increase With Age Instead of Decrease

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Finance Tagged With: anxiety, bank account, banking, Budget, budget tips, budgeting, Budgeting Tips, comparison, finance, finances, financial anxiety, financial stress, impulse purchase, impulse spending, Money, money habits, money issues, news headline, overspending, overthinking, professional advice, saving money, Smart Spending, spending

Why January 20th Is the ‘Red Line’ for Your 2026 Financial Stability

January 18, 2026 by Brandon Marcus Leave a Comment

Why January 20th Is the 'Red Line' for Your 2026 Financial Stability
Image source: shutterstock.com

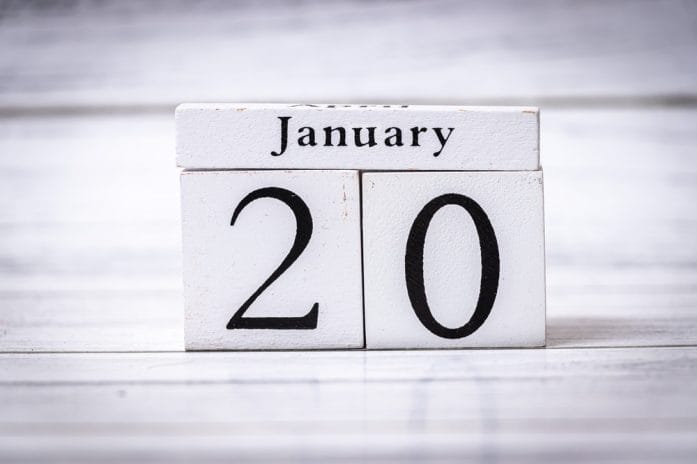
If your bank account could talk, it would probably be whispering warnings about January 20th. This isn’t some arbitrary date plucked from the void—it’s a critical turning point for financial decision-making that can either set you up for a smooth year or trap you in a web of preventable setbacks.

Think of it as a checkpoint where procrastination and poor planning can turn into real consequences faster than you can say “credit freeze.” The stakes are higher than most realize, and the clock is ticking. Understanding why this date matters and acting accordingly might just be the smartest move you make all year.

The End Of Post-Holiday Cushioning

By January 20th, most people have exhausted the financial buffer built during the holiday season. Credit card bills from gifts, travel, and festive splurges start landing in mailboxes and inboxes, and many don’t realize how quickly these balances can compound with interest. The post-holiday financial lull can disguise looming trouble, especially for those who used short-term loans or credit cards as temporary relief.

Being proactive before this date means assessing what’s really owed versus what’s manageable, setting a plan to avoid carrying high-interest balances, and resisting the temptation to “catch up” with more debt. If left unchecked, January 20th can feel like stepping off a cliff, except the ground is made of interest rates, fees, and late charges. Preparing now gives you breathing room, instead of a scramble to make ends meet in late January.

Tax Deadlines And The Early-Year Crunch

January 20th also falls at a critical point in the tax cycle. Many taxpayers begin seeing forms like W-2s, 1099s, and preliminary interest statements arrive right around this time. Missing the opportunity to organize documents, check deductions, or even estimate tax liabilities can create a domino effect of stress and financial strain. For self-employed individuals, freelancers, or those with variable income, this date signals the moment when financial projections for 2026 become urgent.

Why January 20th Is the 'Red Line' for Your 2026 Financial Stability
Image source: shutterstock.com

The earlier you review your tax situation, the better positioned you are to adjust withholding, make quarterly payments, or capitalize on deductions that can ease the burden later. Ignoring this timing doesn’t make the numbers go away—it only makes January 20th the day you realize you could have avoided an unnecessary headache.

Investment Decisions Need An Early-Year Lens

Financial advisors often stress the importance of early-year planning for investments, and January 20th serves as a key benchmark for decision-making. Markets react to policy announcements, interest rate changes, and corporate earnings projections, all of which can shift rapidly in the first few weeks of the year. By this date, patterns start emerging that inform your investment strategy for the months ahead. Delaying action until February or March could mean missed opportunities or entering positions when market conditions are less favorable. Whether it’s rebalancing a portfolio, adjusting retirement contributions, or reconsidering risk tolerance, January 20th is when the first real course corrections should happen to avoid costly missteps.

Personal Budgets Face Their First Real Test

The start of the year brings optimism, resolutions, and ambitious budgeting plans—but by January 20th, reality often hits. Bills, subscriptions, mortgage payments, and everyday expenses begin to accumulate, revealing whether your budget was aspirational or actually achievable. This is the moment to confront overspending, revisit discretionary categories, and make adjustments before habits become entrenched. Those who procrastinate might find themselves dipping into emergency savings or falling behind on bills, turning a minor inconvenience into a long-term financial challenge.

Approaching January 20th with a clear, realistic view of your cash flow can prevent small missteps from snowballing into full-blown crises.

Debt Management Must Take Priority

If debt management isn’t already a focus, January 20th is a wake-up call. Credit cards, personal loans, and other financial obligations can accumulate silently, with interest quietly chipping away at your available funds. Ignoring this date can result in missed minimum payments, higher interest accrual, and even damage to your credit score. A proactive approach includes reviewing all outstanding debts, prioritizing high-interest accounts, and considering strategies like consolidation or refinancing if necessary. By taking action before the red line of January 20th, you can transform a reactive, stressful financial situation into a structured, controlled plan that sets the stage for a more stable year.

Emergency Funds Should Be Evaluated Now

Finally, January 20th is the perfect checkpoint for your emergency fund. Unexpected expenses—a car repair, medical bill, or home maintenance—can derail financial stability if you’re unprepared. Assessing your savings, ensuring accessibility, and replenishing any shortfalls should be non-negotiable tasks before this date passes. An underfunded emergency cushion can turn minor inconveniences into significant disruptions. Planning for emergencies ahead of the curve isn’t just wise—it’s essential for maintaining momentum in your broader financial goals.

Take Action Before The Red Line

January 20th is more than a date—it’s a marker for proactive financial behavior. It signals the point where post-holiday recovery, tax considerations, budget testing, debt management, and investment strategy all intersect. Ignoring this date can magnify small missteps into larger financial problems. Meanwhile, acting beforehand sets you up for a smoother, more controlled year. Use it as a milestone to assess your overall financial health, make adjustments, and ensure your 2026 goals stay on track.

Have a personal experience or strategy that helped you navigate this crucial day? Leave your thoughts and stories in the comments below, because your insights might help someone else steer clear of pitfalls.

You May Also Like…

10 Financial Wake-Up Calls People Experience After Age 55

Income Stability: 6 Retirement Income Moves That Aren’t as Safe as They Seem

Savings Base: 6 Foundational Moves That Keep Retirement Plans Stable

Why Does Financial Anxiety Show Up Even When Bills Are Paid

8 Budget Fixes That Instantly Turn Finances Around

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Finance Tagged With: bank account, banking, Budget, budgeting, Debt, Debt Management, eliminating debt, end of year spending, finance, finances, Financial Stability, general finances, investing choices, investing decisions, investments, January, overspending, Pay Off Debt, personal budget, savings account, Smart Spending, spending, tax deadlines

What the Stars on Your 2026 Bank Statement Really Means for Your Privacy

January 16, 2026 by Brandon Marcus Leave a Comment

What the 'Star' on Your 2026 Bank Statement Really Means for Your Privacy
Image source: shutterstock.com

Your bank statement lands in your inbox, you skim past the usual charges, and then your eyes lock onto it: a small star sitting next to a transaction or account detail. It looks harmless, even decorative, but that tiny symbol is doing some serious behind-the-scenes work. In 2026, banks are quietly relying on symbols like this to balance convenience, security, and transparency in a world drowning in data.

That star is not there for flair. It is a signal, a shorthand, and in some cases a subtle shield between your personal information and prying eyes. Once you understand why it appears, you start seeing your bank statement very differently.

Why That Star Appears On Modern Bank Statements

In most cases, the “star” you see is an asterisk, a long-standing symbol used by banks to mask sensitive information. When an account number, card number, or reference ID is partially hidden, the star indicates that certain digits have been intentionally withheld. This practice reduces the risk of fraud if a statement is viewed by the wrong person or intercepted digitally.

By 2026, this masking has become more standardized as statements are increasingly accessed on phones, smartwatches, and shared household devices. The star acts as a visual cue that the missing information exists but is being protected. Importantly, it does not mean data is missing or lost, only that it is intentionally obscured. Banks continue to retain the full details securely on their internal systems.

What The Star Says About Data Minimization

The appearance of stars on statements reflects a broader privacy principle called data minimization. This concept means organizations should show only the information necessary for a specific purpose, and nothing more. On a bank statement, you usually need to recognize a transaction, not see every underlying identifier tied to it. By replacing excess digits or codes with stars, banks reduce the amount of personal data exposed at any given moment. This matters because financial statements are among the most commonly shared documents, whether for rentals, taxes, or expense reports. Fewer visible details mean fewer opportunities for misuse.

In 2026, regulators and auditors increasingly expect this approach as a baseline privacy practice. The star is a simple symbol representing a much larger shift toward restraint in data display.

Clearing Up Common Misunderstandings About The Star

One common misconception is that a star marks suspicious or monitored activity. In reality, asterisk symbols are usually neutral and routine. They do not indicate that your account is under investigation or that a transaction is risky. Another misunderstanding is that starred information has been deleted or anonymized permanently, which is not the case. The full data still exists within the bank’s secure records and can be accessed through authenticated channels if needed.

Some people also assume the star means a processing error, especially when it appears next to pending transactions. In fact, pending items may show stars simply because final reference numbers are not yet assigned. Understanding this prevents unnecessary panic and frantic calls to customer service. Most of the time, the star is just doing its quiet, protective job.

How The Star Fits Into Digital-First Banking In 2026

As banking becomes more digital, statements are no longer static documents. They are dynamic displays that adapt to screens, permissions, and contexts. In 2026, many banking apps automatically adjust how much information is visible based on how you access them. A star may appear in a notification preview, then disappear once you log in fully. This layered visibility helps prevent accidental exposure in public or shared spaces.

The star also supports accessibility features, ensuring sensitive numbers are not read aloud by default by screen readers. From a design standpoint, symbols like this reduce clutter while still communicating intent. They signal that information is protected without interrupting the user experience. In a world where speed and security must coexist, that balance is critical.

What You Can Do If You Want More Or Less Detail

If you ever feel confused or want to see full transaction details, most banks allow you to expand or reveal starred information after verifying your identity. This might involve biometric authentication, a passcode, or a secure message request. On the flip side, some banks let you increase masking for extra privacy, especially on downloaded or printed statements. It is worth exploring your account settings to understand these options. The presence of stars is not fixed; it is often customizable within certain limits. Knowing this gives you more control over how your financial information appears. Rather than being a mystery, the star can become a tool you actively manage.

What the 'Star' on Your 2026 Bank Statement Really Means for Your Privacy
Image source: shutterstock.com

A Small Symbol With A Big Privacy Story

That tiny star on your 2026 bank statement is doing more than filling space. It represents an evolving relationship between transparency and protection in modern finance. By understanding what it means and why it is there, you can read your statements with more confidence and less suspicion. Symbols like this reflect real efforts to respect privacy in everyday interactions.

If you have noticed stars appearing in unexpected places on your financial documents, or have experiences that changed how you view banking privacy, the comments section below is waiting for your perspective.

You May Also Like…

What Should I Do If My Spouse Refuses to Even Look at Our Bank Statements?

How Can Small Banking Errors Snowball Into Huge Losses

5 Outrageous Fees Hidden in Everyday Banking Services

What To Look For When Opening A Bank Account For Your Teen

6 Ways Big Tech’s Latest Privacy Policies Hurt People Over 45

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Banking Tagged With: bank, bank accounts, bank statement, banking, banking choices, Banks, data access, data privacy, major banks, paper statement, privacy

6 Major Banks Just Raised ‘Maintenance Fees’—Here is the List of Who to Ditch

January 16, 2026 by Brandon Marcus Leave a Comment

These 6 Major Banks Just Raised 'Maintenance Fees'
Image source: shutterstock.com

That quiet little line item on your bank statement just got louder. Monthly maintenance fees, once easy to dodge, are creeping higher or becoming harder to avoid at several major banks. Customers are opening their apps and realizing that simply keeping money in the bank is costing more than it used to.

If that makes your eyebrow twitch, you’re not alone. Let’s get into who’s charging, why it matters, and which banks might be pushing customers straight toward the exit.

1. Chase Bank

Chase remains one of the biggest names in American banking, and its size gives it plenty of confidence when adjusting fees. Recent account updates have made monthly maintenance charges feel heavier, especially for customers who don’t meet direct deposit or balance requirements. Many popular checking accounts now carry monthly fees that can reach the low double digits if you miss the waiver criteria. Those criteria themselves have become stricter over time, quietly turning “free checking” into a conditional promise.

Customers with fluctuating income or irregular deposits are often hit the hardest. Chase does offer strong digital tools, but for many people, those perks no longer offset the recurring cost. When you’re paying monthly just to park your paycheck, loyalty starts to wobble.

2. Bank Of America

Bank of America’s maintenance fees have long been a sore spot, and recent changes haven’t eased the tension. Some checking accounts now require higher balances or specific deposit thresholds to avoid monthly charges. Miss the mark, and a fee appears with impressive consistency. While the bank promotes its rewards tiers, not everyone qualifies, and many everyday customers remain outside those benefits. For students and seniors, exemptions exist, but they often expire or come with fine print. The frustration comes from how easy it is to fall out of compliance without realizing it. When a banking relationship feels like a monthly test, customers understandably start looking elsewhere.

3. Wells Fargo

Wells Fargo has worked hard to rebuild trust in recent years, yet its maintenance fees continue to irritate customers. Several checking accounts still carry monthly charges unless certain conditions are met. Those conditions can include minimum balances or qualifying deposits that don’t fit every household budget. The bank has adjusted some requirements, but many customers still report higher effective costs.

For people living paycheck to paycheck, one missed deposit cycle can trigger a fee. Wells Fargo’s physical branch network is extensive, but convenience only goes so far when fees eat into your balance. Many customers are questioning whether the relationship still makes financial sense.

These 6 Major Banks Just Raised 'Maintenance Fees'
Image source: shutterstock.com

4. Citibank

Citibank’s checking accounts have seen fee structures that feel increasingly unforgiving. Monthly maintenance fees can apply quickly if balances dip below required levels. Some accounts also impose penalties when activity thresholds aren’t met, compounding the frustration. Citi positions itself as a global bank with premium features, but those features don’t always matter to domestic customers. What does matter is watching money disappear for administrative reasons. Customers who don’t maintain steady balances often feel penalized rather than supported. As fee-free alternatives expand, Citi’s approach feels more old-school than necessary.

5. PNC Bank

PNC’s popular Virtual Wallet accounts have attracted attention for their budgeting tools, but fees are now a sticking point. Maintenance charges can apply if balance or deposit requirements aren’t satisfied. While the fee amount may seem modest at first glance, it adds up over a year. Many customers sign up expecting flexibility and transparency, only to find conditions that are easy to overlook.

PNC has adjusted account terms over time, which has left some longtime customers paying more than before. The tools are useful, but plenty of digital banks now offer similar features without monthly charges. That comparison is hard to ignore.

6. U.S. Bank

U.S. Bank rounds out the list with maintenance fees that have become harder to avoid. Several checking accounts require consistent deposits or minimum balances to stay fee-free. Customers who don’t meet those benchmarks can face monthly charges that feel out of step with modern banking trends.

While U.S. Bank offers solid customer service and a strong regional presence, fees remain a frequent complaint. Many customers say the requirements aren’t clearly communicated upfront. Over time, that erodes trust and satisfaction. When banking feels like a subscription you didn’t sign up for, frustration builds fast.

Is It Time To Rethink Your Bank?

Maintenance fees may seem small, but they quietly drain hundreds of dollars over time. With so many banks still charging for basic access to your own money, it’s fair to ask whether the relationship is still worth it. Plenty of newer and smaller institutions now offer genuinely fee-free checking with fewer hoops.

If you’ve been hit by a surprise charge or recently switched banks, your experience could help others navigate the same decision. Drop your thoughts or personal stories in the comments section below and keep the conversation going.

You May Also Like…

5 Outrageous Fees Hidden in Everyday Banking Services

How Can Small Banking Errors Snowball Into Huge Losses

5 Bank Fees That Are Secretly Draining Hundreds From Your Account Annually

8 Retirement Home Upgrades with Hidden Fees

The Credit Score Hack Financial Advisors Use That Banks Hope You Never Learn

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Banking Tagged With: bank, bank account, Bank of America, banking, banking fees, Chase Bank, checking account, Citibank, Hidden Fees, maintenance fees, major banks, PNC Bank, savings account, US Bank, Wells Fargo

Why Major Banks Are Quietly Lowering Credit Limits for Customers With ‘Holiday Debt

January 15, 2026 by Brandon Marcus Leave a Comment

Why Major Banks Are Quietly Lowering Credit Limits for Customers With 'Holiday Debt
Image Source: Shutterstock.com

The festive lights have dimmed, the last bits of wrapping paper are swept into the trash, and your bank statement lands like a snowball to the face. That’s right—holiday spending season has left millions juggling debt, and banks are taking notice. Suddenly, the credit limit that once felt like a safety net now seems more like a moving target. It’s not a coincidence. Behind the scenes, major financial institutions are quietly reviewing accounts and making adjustments, sometimes reducing credit limits without warning.

While this might feel like a punch to the gut, it’s part of a larger financial strategy that affects you, even if you’re diligent about payments. Understanding why this is happening—and how to respond—can mean the difference between a minor inconvenience and a financial headache.

How Holiday Spending Triggers Credit Limit Reductions

After the holidays, banks examine a mountain of data from countless transactions. If your account shows signs of heavy seasonal spending, it immediately flags potential risk. Think of it like a radar system: your spending patterns are tracked, analyzed, and weighed against your credit profile. The goal for banks isn’t to punish customers; it’s to protect themselves from potential losses.

High balances, late payments, and maxed-out cards all signal increased risk. In response, banks may lower your credit limit to reduce exposure. It’s a defensive move, but it can feel personal when you log in to see your available credit suddenly shrink. Customers who normally manage their accounts well can still be caught off guard if their holiday purchases were substantial.

Why Major Banks Are Quietly Lowering Credit Limits for Customers With 'Holiday Debt
Image Source: Shutterstock.com

The Psychology Behind The Banks’ Decisions

Financial institutions are not just number-crunching machines; they rely heavily on behavioral psychology. They know that consumers often overextend during festive seasons, thinking they can manage the repayment later. By lowering credit limits, banks are essentially nudging users to slow down before debt spirals. This approach also protects customers from accumulating interest that can snowball quickly. It’s a proactive tactic to curb risky borrowing behavior without making headlines.

Banks are betting that a reduced limit will encourage more responsible spending patterns. Surprisingly, this tactic can sometimes improve your credit score over time, even if it feels inconvenient in the moment.

Who Is Most Likely To Be Affected

Not every customer will see a drop in their credit limit, but certain profiles are more likely to feel the pinch. High-balance accounts, people with recent late payments, or those who carry revolving debt from holiday shopping are prime candidates. Even accounts in good standing aren’t immune if banks detect a sudden spike in spending. Newer cardholders are particularly vulnerable since banks haven’t built a long-term relationship with them.

Seasonal shopping habits are under scrutiny across the board, and no one is entirely exempt from the review process. Understanding whether you fall into these categories can help you anticipate potential changes before they hit your account.

How This Could Impact Your Credit Score

A lowered credit limit can have a ripple effect on your overall financial health. One immediate concern is credit utilization—the ratio of your debt to available credit. When a limit drops, your utilization can spike even if your balance hasn’t changed. This spike may slightly hurt your credit score, affecting your ability to secure loans or favorable interest rates. Some customers might find themselves unexpectedly close to maxing out their cards, which can increase stress and impact future borrowing.

Being aware of this connection allows you to plan smarter, such as paying down balances more aggressively or spacing out purchases. In essence, a temporary limit reduction can have longer-term implications if you don’t adjust your strategy.

Tips To Stay Ahead And Protect Your Credit

Being proactive is key when navigating post-holiday credit limit changes. First, monitor your accounts closely and track your credit utilization. Even small increases in spending can trigger alerts for banks. Paying down balances as quickly as possible signals responsible financial behavior. Consider calling your bank to discuss your options if you see a reduction—sometimes a conversation can prevent a negative impact. Avoid opening multiple new accounts immediately after the holidays, as it can look like financial desperation. Finally, plan your holiday spending for the future with a budget that anticipates repayment rather than relying on a high credit limit. Smart planning now reduces surprises later.

Why Banks Are Quietly Making These Moves

Banks rarely publicize limit reductions because transparency could prompt panic or backlash. If consumers knew limits were being lowered en masse, they might react unpredictably, such as suddenly trying to max out cards or transferring debt. Quiet adjustments allow institutions to manage risk while avoiding mass disruptions. This stealthy approach is rooted in careful data analysis and risk modeling, not malice. Banks are balancing customer behavior with regulatory expectations, ensuring they maintain profitability while minimizing defaults. While it can feel frustrating for individuals, it’s a calculated strategy that benefits the larger financial ecosystem.

It’s Time To Join The Conversation

Credit limit reductions may feel like an unwelcome holiday gift, but understanding the why and how can make them easier to handle.

Have you ever experienced a sudden drop in your credit limit after the holidays? How did you respond, and what strategies worked best to recover? Let us know your thoughts or stories in the comments below.

You May Also Like…

5 Warning Signs It’s Time To Change Banks

How Can Small Banking Errors Snowball Into Huge Losses

6 Data-Scraping Features in Online Banking

10 Warning Signs Your Banking App Was Compromised

Debt Alert: 6 Ways Holiday Spending Could Trigger a January Credit Score Crisis

Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Banking Tagged With: bank, bank credit, bank fees, bank info, bank policy changes, banking, banking choices, banking costs, banking decisions, credit, Debt, debt payoff, eliminating debt, holiday debt, holiday spending

Why Wealthy Families Are Moving Cash Out of Traditional Banks Before Jan 31st

January 14, 2026 by Brandon Marcus Leave a Comment

Why Wealthy Families Are Moving Cash Out of Traditional Banks Before Jan 31st
Image Source: Shutterstock.com

The financial world is buzzing with whispers, and not the boring kind that happens at a quiet dinner party. Imagine champagne bubbles of strategy popping in high-rise offices and sprawling estates, as wealthy families make moves that could change the way money flows in 2026. Suddenly, bank statements aren’t just numbers—they’re puzzles, and the puzzle solvers are plotting their moves before January 31st.

The stakes feel almost cinematic: hedge funds, tax incentives, and the looming presence of regulatory changes are all playing into a high-stakes game that affects fortunes, lifestyles, and yes, even the way you might think about your own checking account.

Changing Banking Habits Among The Wealthy

Over the past decade, there’s been a subtle but dramatic shift in how affluent families handle their liquid assets. Traditional banks, once the gold standard for safety and convenience, are now being scrutinized in a whole new way. With rising inflation, interest rate volatility, and new tax legislation, keeping large sums of money parked in conventional accounts is starting to look less like security and more like opportunity cost.

Wealth advisors are advising clients to diversify holdings, not just into investments like stocks and real estate, but into instruments that offer both protection and growth potential. The result? Families are moving cash into private banking solutions, alternative investment vehicles, and trusts designed to keep funds working harder than a savings account ever could. Timing is critical—January 31st isn’t just a date on the calendar; it’s a financial deadline that can influence tax outcomes and liquidity strategies.

Tax Planning Is Driving Urgency

One of the primary motivators behind these moves is tax strategy. The end of January often signals the close of certain fiscal opportunities for the previous year, especially for those who operate with complex estate plans or international assets. By transferring money out of traditional banks before this date, wealthy families can reduce exposure to specific taxes or take advantage of deductions and exemptions that vanish after the month ends. This isn’t about evading taxes—it’s about precision planning.

Wealthy families hire teams of tax attorneys and accountants who can choreograph financial maneuvers down to the exact day. In this context, the difference between moving cash on January 30th versus February 1st can amount to tens of thousands, sometimes even hundreds of thousands, of dollars in tax savings. The intensity of this timing creates a ripple effect, influencing financial behavior across sectors, from real estate to private equity.

Alternative Banking And Private Solutions Are Trending

Traditional banks offer convenience, but when money reaches the multi-million-dollar mark, families often crave more tailored solutions. Private banks, family offices, and alternative banking services provide options that standard accounts simply cannot. This can include higher-yield savings alternatives, structured products, or sophisticated hedging strategies designed to preserve wealth while generating returns. By moving funds before January 31st, families ensure they position themselves optimally for investment opportunities that only present themselves at the start of the calendar year.

These alternative solutions also offer enhanced privacy, more personalized advisory services, and sometimes exclusive investment opportunities that are simply inaccessible through conventional banking channels. In essence, it’s a move from mass-market convenience to boutique financial craftsmanship, and timing is everything.

Why Wealthy Families Are Moving Cash Out of Traditional Banks Before Jan 31st
Image Source: Shutterstock.com

The Role Of Economic Uncertainty

Economic uncertainty is another factor fueling this behavior. Interest rate changes, stock market fluctuations, and geopolitical tensions all play into how cash is managed at the highest levels. For families with substantial wealth, parking large sums in a traditional bank can feel like leaving money on a table in a casino where the odds are stacked against you. Moving money into more dynamic financial vehicles mitigates risk while opening doors to strategic opportunities. Advisors stress that proactive movement of funds is not reactive panic; it’s careful navigation. The period leading up to January 31st is critical because it aligns with financial reporting deadlines, investor cycles, and the release of new investment products, making timing not just strategic but essential. In a world where even a 1% difference in yield can represent millions, precision becomes almost an art form.

Estate Planning And Multi-Generational Strategy

For many wealthy families, moving cash isn’t just about the present—it’s about legacy. Estate planning often drives the redistribution of assets into trusts, family foundations, and intergenerational funds. By acting before January 31st, families can set up these structures in a way that maximizes both current tax benefits and long-term growth for heirs. It’s a delicate dance: ensure compliance with regulations, protect wealth from market volatility, and align with philanthropic goals. These actions often involve collaboration between legal teams, financial advisors, and investment managers, orchestrating a complex symphony of wealth preservation. This isn’t simply about money changing hands; it’s about shaping financial futures and ensuring that legacies endure across generations.

Technology And Data Are Changing The Game

Finally, technological tools have made these transitions smoother, faster, and more strategic than ever before. High-net-worth individuals now rely on sophisticated platforms to track global assets, automate transfers, and analyze tax implications in real time. Data analytics can simulate hundreds of scenarios, pinpointing the exact timing for optimal financial outcomes. This tech advantage magnifies the urgency of acting before January 31st, as algorithms crunch numbers that would take humans days to analyze manually. In this way, the movement of money is no longer just a practical necessity; it becomes a game of strategy where timing, intelligence, and foresight converge.

What’s Your Banking Take?

The January 31st deadline is more than a date—it’s a financial landmark that has families, advisors, and investors buzzing. Whether it’s about taxes, alternative banking, economic uncertainty, or legacy planning, the reasons wealthy families are moving cash out of traditional banks are varied, sophisticated, and fascinating.

If you’ve witnessed, been part of, or even just pondered the strategies behind such financial maneuvers, the floor is open. Drop your thoughts or stories in the comments below and let’s dive into the world where money, strategy, and timing intersect.

You May Also Like…

7 Unfavorable Truths About Marrying Into a Wealthy Family

5 Outrageous Fees Hidden in Everyday Banking Services

5 Warning Signs It’s Time To Change Banks

What Happens if Adult Children Control Your Online Banking Credentials

What Happens if Adult Children Control Your Online Banking Credentials


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: Wealth Building Tagged With: banking, banking costs, banking habits, banking policies, Banks, Family, family advice, family issues, family money, money issues, tax planning, traditional banks, Wealth, wealthy families

Payment Delay Alert: Why Your January Social Security Deposit May Not Hit Your Account Today

January 14, 2026 by Brandon Marcus 8 Comments

Here's Why Your January Social Security Deposit May Not Hit Your Account Today
Image Source: Shutterstock.com

The morning coffee is poured, the phone is unlocked, and there it is—the banking app—staring back with a balance that hasn’t budged. For millions of Social Security recipients, that moment can spark a mix of confusion, concern, and a dozen rapid-fire questions. January is supposed to feel like a clean slate, yet nothing rattles the calm quite like a missing deposit.

Before panic sets in or customer service numbers get dialed at lightning speed, it helps to understand what’s really going on behind the scenes. This isn’t a mystery novel twist or a financial cliffhanger—it’s a story with rules, timing quirks, and a few very human explanations.

How Social Security Payment Timing Really Works

Social Security payments don’t all land on the same day, and that alone explains a huge chunk of January confusion. The Social Security Administration uses a staggered schedule that depends on your birthday and the type of benefit you receive. Retirement and disability benefits typically arrive on a Wednesday, and which Wednesday depends on whether your birthday falls early, mid, or late in the month. Supplemental Security Income usually follows a different rhythm entirely, often arriving on the first of the month unless that date collides with a weekend or holiday.

January magnifies these differences because it opens with a federal holiday and a brand-new calendar. When expectations don’t match the actual schedule, it can feel like a delay even when everything is technically right on time.

January’s Calendar Quirks Can Shift Deposit Dates

January loves to play calendar tricks, and your Social Security payment sometimes feels the impact. New Year’s Day is a federal holiday, and banks close their doors, even if digital banking stays open. When a scheduled payment date lands on a weekend or holiday, the deposit doesn’t vanish—it simply moves. Sometimes it arrives earlier, sometimes the next business day, depending on the benefit type and banking processes.

That shift can make it seem like today was supposed to be the day, even when the official payment date quietly changed. Understanding that January’s layout isn’t business-as-usual can ease a lot of unnecessary worry.

Here's Why Your January Social Security Deposit May Not Hit Your Account Today
Image Source: Shutterstock.com

Banks And Processing Times Add Another Layer

Even when Social Security releases payments exactly as scheduled, banks still have a role to play. Financial institutions process deposits on their own timelines, and those timelines aren’t always identical. One bank might post funds the moment they’re received, while another may take several hours or even an extra business day. High-volume periods, such as the start of a new year, can slow things slightly as systems update and reconcile accounts. Online banking apps don’t always refresh instantly, which can add to the illusion of a missing payment. In many cases, patience of a single day is all it takes for the deposit to finally appear.

Cost-Of-Living Adjustments Can Cause Brief Confusion

January is also when cost-of-living adjustments take effect, and that change can add a layer of complexity. Updated benefit amounts require system-wide updates, recalculations, and verification checks. While these adjustments are designed to help recipients keep up with rising expenses, they can temporarily slow the flow of information between agencies and banks. Some people notice a different deposit amount and assume something went wrong, while others expect the increase and think a delay has occurred. The reality is that recalibration takes time, and January is when all of it happens at once. The payment is still coming, even if it arrives with a few extra steps behind the curtain.

When A Delay Is Normal And When It’s Not

Most January payment concerns fall squarely into the “normal” category, even if they don’t feel that way in the moment. A deposit that’s one business day late is rarely a sign of trouble, especially around holidays. However, a delay stretching beyond several days deserves attention. Incorrect banking information, a recently changed account, or a flagged issue can hold things up longer than expected. Keeping personal details up to date with Social Security is one of the simplest ways to avoid extended delays. Knowing the difference between a routine timing issue and a genuine problem helps you respond calmly and effectively.

Smart Steps To Take If Your Payment Hasn’t Arrived

The first and most powerful step is checking your official payment schedule to confirm the expected date. Next, take a look at your bank’s processing policies, especially around holidays and weekends. It’s also wise to monitor your account for pending deposits that may not be fully posted yet. If a few business days pass with no sign of your payment, reaching out to Social Security or your bank can provide clarity. Keeping notes of conversations and confirmation numbers can save time if follow-up is needed. Acting methodically beats reacting emotionally every time.

Stay Informed And Stay Calm

January payment delays can feel unsettling, but they’re often the result of timing, calendars, and behind-the-scenes processes rather than true problems. Understanding how Social Security schedules payments and how banks handle deposits puts the power back in your hands. If you’ve experienced a January delay before, or if today’s missing deposit sparked a few nerves, your perspective could help others feel less alone.

Drop your thoughts or personal experiences in the comments section below and join the conversation. Sometimes reassurance is just one story away.

You May Also Like…

Pension Shock: 9 Myths About Social Security That Could Derail Your Retirement

Could Your Social Security Plans Collapse If The Economy Shifts Again This Winter?

Did You Know Social Security Has a Hidden Bonus for Widowers?

11 Social Security Surprises That Hit You After Losing a Spouse

Is There Any Way to Get More Social Security Than You Qualify For?


Brandon Marcus
Brandon Marcus

Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.
Filed Under: social security Tagged With: America, bank account, bank processing, banking, Banks, elderly, government policy, January, Money, money issues, senior citizen, seniors, Social Security, social security changes, Social Security deposit, social security payment, United States

  • « Previous Page
  • 1
  • …
  • 4
  • 5
  • 6
  • 7
  • 8
  • …
  • 10
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework