• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for tax tips

6 Tax Breaks People Don’t Know They Can Claim

February 4, 2025 by Latrice Perez Leave a Comment

Tax Breaks
Image Source: 123rf.com

Navigating through the tax code can often feel like a maze, but there are plenty of tax breaks that most people overlook. While common deductions like mortgage interest or student loan interest are widely known, there are lesser-known credits and deductions that can potentially save you hundreds or even thousands of dollars. If you’ve been missing these breaks, now is the time to dig deeper into your tax situation. Here are six tax breaks that most people don’t know they can claim, which could help lighten your tax load this year.

1. The American Opportunity Tax Credit (AOTC)

The American Opportunity Tax Credit (AOTC) is often overlooked by many taxpayers, especially those who are paying for college education. This credit provides up to $2,500 per year for each eligible student. The AOTC is especially beneficial because it can be claimed for the first four years of post-secondary education and is partially refundable— meaning that if your tax liability is lower than the credit amount, you could receive the difference as a refund. To qualify, the student must be enrolled at least half-time in a degree or certificate program, and the credit applies to tuition, fees, and course materials. If you or a dependent are pursuing higher education, make sure to check if you can benefit from this credit.

2. State Sales Tax Deduction

When it comes to deductions, most people immediately think of state income tax. However, if you live in a state that doesn’t have an income tax, or if you had significant purchases throughout the year, you might be able to deduct state and local sales taxes instead. The IRS allows taxpayers to either deduct state income taxes or state sales taxes—whichever is higher. This can be especially helpful if you made large purchases, like a car or home improvement supplies, which would increase the sales tax you’ve paid. To take advantage of this, you can either use the IRS sales tax tables or keep a detailed record of your eligible purchases.

3. The Moving Expense Deduction (For Active Military)

While moving expenses are typically not deductible for most people, active-duty members of the Armed Forces can still claim them. This deduction applies when you move due to a military order, whether you’re relocating for a permanent change of station (PCS) or moving because of a combat zone assignment. Eligible moving expenses include the cost of moving your household goods, transportation, lodging, and storage while relocating. Although this deduction was suspended for most taxpayers after 2017, active military members can still benefit. If you or your spouse are in the military, check if this deduction applies to your recent relocation.
Teacher teaching a class
Image Source: 123rf.com

4. Tax Breaks for Educators

Teachers and educators have unique opportunities to claim tax breaks that many are unaware of. Teachers who spend their own money on classroom supplies can deduct up to $300 of out-of-pocket expenses, or up to $600 if both spouses are eligible educators. This deduction applies to supplies, equipment, and materials used in the classroom, even if they aren’t directly reimbursed by your school. This tax break was expanded in 2020 to include protective equipment related to COVID-19, such as masks, sanitizers, and other health-related items. If you’re an educator, make sure you’re taking advantage of this credit designed to ease the financial burden of teaching.

5. The Qualified Business Income (QBI) Deduction for Side Hustles

If you’re running a side business or a freelance operation, you may qualify for the Qualified Business Income (QBI) deduction, which allows you to deduct up to 20% of your qualified business income. While this deduction is well-known for small business owners, it’s often missed by freelancers and those with side gigs. The QBI deduction applies to pass-through businesses, such as sole proprietorships, partnerships, S corporations, and LLCs. To qualify, your business must generate income and meet certain limitations. Whether you’re a freelancer, an online seller, or a part-time consultant, don’t miss this opportunity to reduce your taxable income.

6. The Adoption Credit

Adopting a child is a life-changing event, and the tax code offers a credit to help ease some of the financial burden. The Adoption Credit can offer up to $$16,810 in tax relief for qualified adoption expenses. These expenses can include adoption fees, court costs, and legal fees. One of the most significant benefits of the Adoption Credit is that it’s non-refundable, meaning it can be used to offset your tax liability but not provide a refund if your taxes are already low. However, if you adopt a child with special needs, the credit can be claimed in full, regardless of actual adoption costs. If you’ve adopted a child recently, be sure to explore this credit and the related qualifying expenses.

Don’t Let These Tax Breaks Slip Through the Cracks

Tax breaks can make a significant difference in how much you owe or how much you get back, but too many taxpayers overlook these opportunities. By staying informed and understanding lesser-known tax breaks like the American Opportunity Tax Credit or moving expense deductions for military personnel, you could potentially save a significant amount of money this year. Don’t let these opportunities slip through the cracks—review your tax situation carefully and make sure you’re claiming all the deductions and credits you qualify for.

What are some other tax breaks that are often overlooked? Which ones have you benefited from? Share your tax knowledge in the comments below.

Read More:

How Are Property Taxes Determined Each Year?

Can These 8 Tax Planning Tips Make Filing Your Taxes Easier?

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.
Filed Under: tax tips Tagged With: adoption credit, education tax credit, freelance tax tips, lesser-known tax breaks, military tax breaks, moving expense deduction, Tax Deductions, tax savings

How Are Property Taxes Determined Each Year?

January 15, 2025 by Latrice Perez Leave a Comment

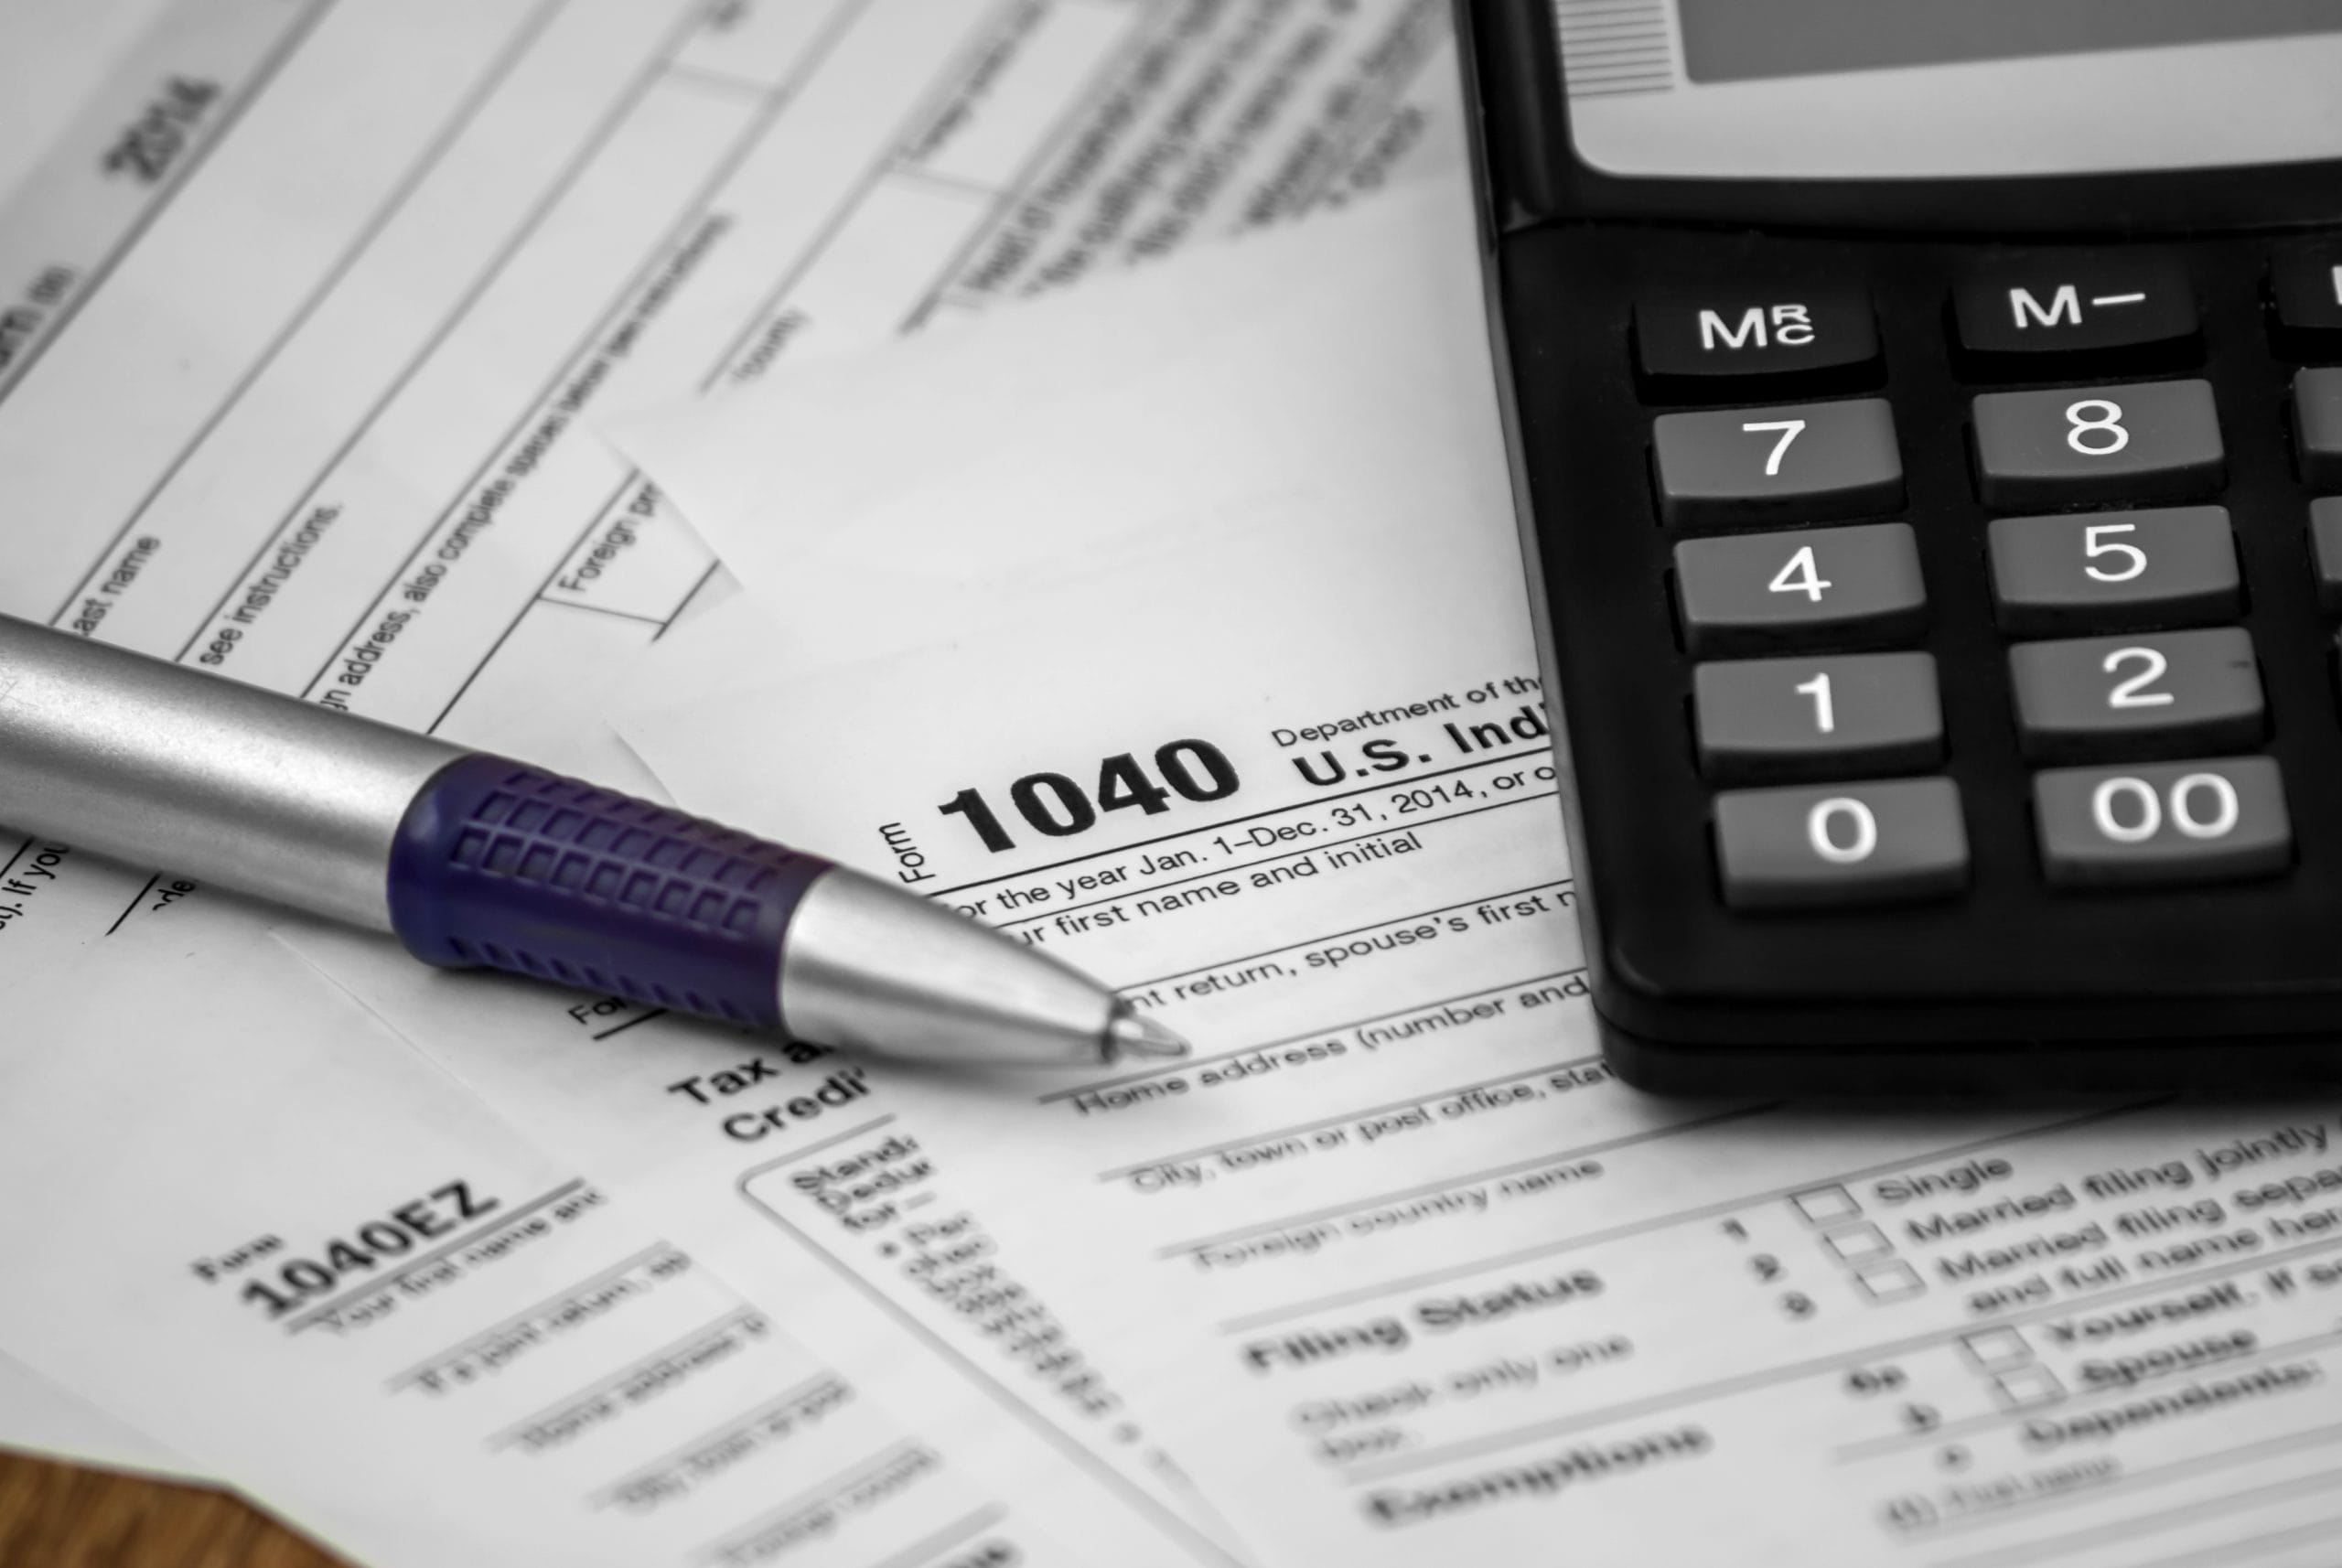
US tax form 1040 with pen and calculator
Image Source: 123rf.com 

Property taxes are a significant expense for homeowners, yet many people don’t fully understand how they are calculated. These taxes fund essential public services, such as schools, road maintenance, and emergency services, making them a vital part of local government budgets. Understanding how property taxes are determined can help you plan your finances better and even find opportunities for savings. Let’s break down the key factors that influence your annual property tax bill.

Assessing the Value of Your Property

The first step in determining property taxes is assessing the value of your home. Local tax assessors evaluate properties based on factors like market value, location, size, and condition. This assessment often involves comparing your property to similar homes in the area. Some jurisdictions reassess properties annually, while others do so every few years. It’s important to review your assessment and ensure it accurately reflects your home’s value, as this forms the basis for your tax bill.

Applying the Local Tax Rate

Once your property’s value is assessed, it is multiplied by the local tax rate, also known as the millage rate. This rate is set by local governments and varies depending on your location. The millage rate is typically expressed as a dollar amount per $1,000 of assessed property value. For example, if your home is valued at $200,000 and the local tax rate is $20 per $1,000, your property tax would be $4,000 annually. Local governments determine these rates based on budget needs for public services and infrastructure projects.

Factoring in Exemptions and Deductions

Many homeowners qualify for property tax exemptions or deductions that can lower their tax burden. Common exemptions include those for senior citizens, veterans, or primary residences under homestead exemptions. Some jurisdictions also offer relief for low-income households or properties used for agricultural purposes. These exemptions can significantly reduce the taxable value of your home, so it’s worth exploring the options available in your area. Be sure to apply for these exemptions, as they are not always automatically granted.

Adjusting for Market Trends

Mini house on stack of coins,Money and house, Real estate invest
Image Source: 123rf.com

Market trends can influence your property taxes, even if you haven’t made significant changes to your home. In a rising real estate market, property values tend to increase, leading to higher assessments and, consequently, higher taxes. Conversely, a declining market can result in lower taxes, although some areas have limits on how much taxes can decrease. Keeping an eye on local market trends can help you anticipate changes to your tax bill and prepare accordingly.

Challenging an Unfair Assessment

If you believe your property has been overvalued, you have the right to challenge the assessment. Start by reviewing the details of your assessment for errors or inaccuracies. You may need to gather evidence, such as recent appraisals or sales data for similar homes, to support your case. Most jurisdictions have an appeals process, allowing you to request a review or adjustment. Successfully challenging an assessment can lead to significant savings on your annual property taxes.

Stay Informed and Save

Property taxes are usually determined based on your home’s assessed value, local tax rates, and available exemptions. Understanding this process not only helps you plan your budget but also ensures you’re not overpaying. Take the time to review your assessment, apply for exemptions, and challenge unfair valuations when necessary. Being proactive can make a big difference in managing your property taxes. Share this article with friends and family to help them navigate the complexities of property taxes with confidence.

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.

Filed Under: tax tips Tagged With: homeowner tips, local tax rates, property tax exemptions, property taxes, real estate taxes, saving money on taxes, tax assessments

Are There Taxes That Have to Be Paid On Yearly Bonuses?

January 7, 2025 by Latrice Perez Leave a Comment

Image Source: 123rf.com

When it comes to financial rewards like yearly bonuses, understanding the tax implications is crucial for both employers and employees. Yearly bonuses are often a sign of appreciation and reward for hard work, but many may wonder about the “taxes on bonuses” and how they are handled by the IRS. This article provides a clear breakdown of the taxation process for bonuses and helps you navigate the specifics with ease.

 Understanding Levies on Extra Income

A yearly bonus, although a delightful addition to your earnings, is subject to federal withholding. The IRS treats all bonuses as supplemental income, which can be taxed at a higher rate than your regular salary. Specifically, if your bonus is under $1 million, it could be subject to a flat tax rate of 22%. This method simplifies the withholding process, ensuring that taxes on bonuses are appropriately managed.

State and Local Assessments on Supplementary Pay

Beyond federal taxes, bonuses may also be taxed at the state and, sometimes, local levels, depending on where you reside. Not all states tax income the same way, and some do not tax income at all. For instance, while states like California have a high-income tax rate that applies to bonuses, others like Florida do not impose state income taxes. It’s essential to understand the specific regulations in your state to accurately calculate the total taxes on bonuses.

Considerations for Larger Bonus Amounts

For substantial bonuses, specifically those exceeding $1 million, the IRS imposes a different set of rules. These larger sums are taxed at a 37% rate, reflecting the tax bracket for higher incomes. This ensures that higher earners meet their tax obligations proportionally. Understanding these rates is vital for those receiving larger bonuses and aids in financial planning and tax compliance.

Strategies to Reduce Tax Burden on Bonuses

While taxes on bonuses are inevitable, there are strategies you can employ to minimize the impact. For example, increasing your retirement contributions, such as to a 401(k), can reduce your taxable income. Another strategy might be to ask your employer to spread the bonus over several payments or defer it to a lower income tax year if possible. Consulting with a tax professional can provide personalized strategies based on your financial situation.

Key Takeaways on Bonus Taxation

Navigating the tax responsibilities on bonuses is crucial for maximizing your financial benefits while complying with tax laws. Understanding the federal, state, and potential local taxes will prepare you for the financial impact of your bonus. With strategic planning, you can potentially reduce the tax burden and optimize your earnings from such supplemental income.

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.
Filed Under: tax tips Tagged With: bonus tax rate, financial planning bonuses, reduce taxes on bonuses, supplemental income tax, taxes on bonuses

Do These 12 Things If You Can’t Pay Your Taxes On Time

April 3, 2024 by Tamila McDonald Leave a Comment

Can't Pay Taxes On Time

When tax season arrives and you find yourself unable to pay what you owe, it can be a source of significant stress. However, there are steps you can take to mitigate the situation and handle your tax obligations responsibly. Here’s a detailed guide on what to do if you can’t pay your taxes on time.

1. Don’t Ignore the Problem

Don't Ignore The Problem

Ignoring your tax bill won’t make it go away; it will only make things worse. The first step is to acknowledge the situation. Understand that the IRS deals with this frequently and offers several solutions to help taxpayers. The key is to act promptly to avoid additional penalties and interest that accrue over time.

2. File Your Tax Return on Time

File On Time


Even if you can’t pay, ensure you file your taxes or file for an extension. Failing to file can result in a failure-to-file penalty. Remember, this extension is only for filing your return, not an extension to pay your tax bill. By filing your taxes, you’re demonstrating a willingness to comply with tax laws, which can be beneficial in your communications with the IRS.

3. Contact the IRS

Contact IRS

Communicate with the IRS about your situation. They are often more accommodating when they see proactive efforts from taxpayers. In many cases, they can offer guidance or a solution you might not have considered. It’s also important to stay informed about any new IRS policies that may offer additional relief.

4. Explore Payment Plans

Explore Payment Options

The IRS offers various payment plans, including short-term extensions and longer installment agreements. These can be a viable option if you need more time to pay your tax bill. Research which plan suits your financial situation best and apply through the IRS website or by contacting them directly.

5. Consider a Short-term Loan or Credit Card Payment

credit card

While it may seem counterintuitive to take on debt, a short-term loan or credit card payment could have lower interest rates than the penalties and interest charged by the IRS. Compare the costs carefully and consider this option if it’s more economical in the long run.

6. Avoid Additional Penalties

Additional Penalties

Make every effort to minimize additional penalties. This includes filing on time, paying as much as you can by the due date, and staying in communication with the IRS. Penalties can accumulate quickly, making your situation more difficult.

7. Check Eligibility for Waiving Penalties

Check Eligibility

In some circumstances, the IRS may waive penalties for late payment if you can show reasonable cause for not paying on time. This does not typically apply to the interest charges on the taxes owed, but reducing penalties can still significantly decrease your total bill.

8. Seek Professional Help

Seek Professional Help

If you feel overwhelmed, it might be wise to consult a tax professional. They can offer guidance tailored to your situation and may know of options and programs that you are not aware of. Involving a professional can also ensure that all paperwork and communication with the IRS are handled correctly.

9. Don’t Overlook Tax Credits and Deductions

Taking Tax Credits and Deductions

Ensure you’ve taken advantage of all applicable tax credits and deductions. Sometimes, people miss out on these, which can reduce their tax liability. Look into any credits or deductions you may not have claimed, as this could significantly lower your tax bill.

10. Prioritize Your Tax Bill

Prioritize Your Tax Bill

If you have various debts, prioritize your tax bill. IRS debts can have more severe consequences than other types of debts, including the potential for wage garnishment. Evaluate your finances and consider paying off your tax debt first or seeking a balance that addresses all your obligations.

11. Consider Future Tax Adjustments

Consider Future Tax Adjustments

If this year was challenging, make adjustments for the next tax year. This might include increasing your withholdings or making estimated tax payments if you’re self-employed. Planning can help you avoid a similar situation in the future.

12. Stay Informed about Tax Law Changes

Tax Law Changes

Keeping abreast of changes in tax laws is crucial, as new legislation can significantly affect your tax liabilities and relief opportunities. Tax laws are frequently revised to reflect economic policies, address emerging issues, or provide relief in times of crisis, such as during economic downturns or public emergencies. These changes can introduce new deductions, credits, or even special programs offering additional relief to taxpayers.

Navigating Tax Challenges with Prudence

Tax Challenges

Facing tax challenges can be daunting, but taking these steps can help navigate through the process more smoothly. Remember, the worst action you can take is no action. By addressing the issue head-on, exploring available options, and seeking professional advice when necessary, you can manage your tax obligations in a way that minimizes stress and financial impact. Stay informed, stay proactive, and know that there are avenues available to help you through this challenging time.

Tamila McDonald
Tamila McDonald

Tamila McDonald is a U.S. Army veteran with 20 years of service, including five years as a military financial advisor. After retiring from the Army, she spent eight years as an AFCPE-certified personal financial advisor for wounded warriors and their families. Now she writes about personal finance and benefits programs for numerous financial websites.

Filed Under: Personal Finance, tax tips Tagged With: Check Eligibility for Waiving Penalties, credit card payment, Explore Payment Plans, Prioritize Your Tax Bill

What Tax Credits Can I Expect in 2023?

January 3, 2023 by Tamila McDonald Leave a Comment

Tax Credits

Now that 2023 is underway, many households are preparing for tax season. Keyboards ablaze with frantic efforts to figure out 2022 tax brackets and estimate tax refunds. As a result, it’s wise to learn about tax credits that may reduce your total financial obligation before you file. That way, you can prepare for how the adjustments impact the broader picture. While there are far more tax credits than an article can reasonably list, some are relatively widely used. Here’s a look at tax credits that a more significant number of tax filers are potentially eligible for, what they’re typically worth, and some initial information on qualifying.

What Tax Credits Can I Expect in 2023?

Child Tax Credit

The child tax credit is one of the most commonly claimed ones in the country. Generally, any household with a qualifying child as a dependent is potentially eligible. During the 2022 tax year – which is filed in 2023 – it’s potentially worth $2,000 per qualifying child. As a result, it’s potentially sizeable.

Earned Income Tax Credit

Another widely used tax credit is the earned income tax credit. Eligible taxpayers without children can receive a credit worth up to $500 when they file in 2023.

Child and Dependent Care Credit

While the child and dependent care credit is worth far less than it was in 2021 – when it sat at $8,000 – it’s still a decent amount. Qualifying households are eligible for up to $2,100 when they file their 2022 tax information in 2023.

Retirement Contributions Savings Credit

Individuals with adjusted gross incomes at or below $34,000 ($68,000 for married filing jointly) are potentially eligible for a tax credit related to their retirement savings. It’s worth up to 50 percent of the total contributions to a qualifying account, with the exact amount varying by income and the maximum value set at $1,000 (or $2,000).

American Opportunity Credit

During the first four years of college at a qualifying institution, students are potentially eligible for the American opportunity credit. This is worth up to $2,500 per student and is refundable up to 40 percent. However, it’s only available to individuals with incomes at or below $80,000 ($160,000 for married filing jointly).

Lifetime Learning Credit

The lifetime learning credit helps offset the cost of qualifying tuition or educational expenses for students at eligible institutions. Typically, that includes colleges, universities, and technical schools beyond high school. However, it’s only available to single taxpayers with income at or below $80,000 (or $160,000 for joint filers).

Premium Tax Credit

The premium tax credit helps offset the cost of purchasing health insurance through the Health Insurance Marketplace. Generally, it applies to lower or middle-income households, though the number of dependents and other factors do alter eligibility.

Clean Vehicles Tax Credit

Individuals who purchased a qualifying “clean vehicle” – typically an electric vehicle – are potentially eligible for a clean vehicles tax credit. The rules are complex, so not all EVs qualify. However, it’s worth exploring if you purchased an EV in 2022.

Federal Adoption Credit

Households that adopted a child in 2022 are potentially eligible for the federal adoption credit, which is worth up to $14,890 when you file your 2022 return in 2023. Income limits do apply, and it starts to phase out at $223,410. This credit is also non-refundable, so those who spend less on qualifying expenses can only receive up to the amount paid to cover eligible costs.

Credit for Other Dependents

The credit for other dependents allows households with dependents who aren’t eligible for a traditional child tax credit to potentially see some relief on their taxes. Generally, that includes individuals living in the household as dependents who are age 17 or older, and it’s worth $500 per qualifying dependent.

Determining Your Eligibility for Tax Credits

While the information above provides an overview of what it takes to qualify for many common tax credits, the rules are often far more complex than what’s outlined above. As a result, it’s wise to research any tax credits you might be able to use carefully, allowing you to ensure you qualify.

If you have doubts, consider working with a tax preparer this year, as they’re often well-equipped to help you determine if you’re eligible for a tax credit. You can also try tax preparation software, as many of those solutions have built-in guides or questionaries that can point you in the right direction.

Ultimately, being confident that you qualify is essential. Improperly claiming a tax credit comes with consequences, including fees, penalties, and potential criminal charges. As a result, it’s best to consult with an expert if you have any doubts about your eligibility.

Can you think of any other tax credits people may want to check out when filing their taxes in 2023? Have you run into issues with tax credits before and want to tell others about your experience? Share your thoughts in the comments below.

Read More:

  • 5 Places to File Your Taxes for Free
  • Minors Still Have to Pay Taxes
  • Annuities and Taxes: Here’s What You Need to Know


Tamila McDonald
Tamila McDonald

Tamila McDonald is a U.S. Army veteran with 20 years of service, including five years as a military financial advisor. After retiring from the Army, she spent eight years as an AFCPE-certified personal financial advisor for wounded warriors and their families. Now she writes about personal finance and benefits programs for numerous financial websites.

Filed Under: tax tips Tagged With: American Opportunity Credit, Child and Dependent Care Credit, Child Tax Credit, Clean Vehicles Tax Credit, Credit for Other Dependents, Earned Income Tax Credit, Federal Adoption Credit, Lifetime Learning Credit, Premium Tax Credit, Retirement Contributions Savings Credit, Tax Credits in 2023

Minors Still Have to Pay Taxes

July 18, 2022 by Tamila McDonald Leave a Comment

minors still have to pay taxes

Even if your children are young enough to be considered dependents, that doesn’t mean they won’t have to pay federal or state income taxes. Like adults, income earned by minors is considered taxable. If you are wondering whether your child needs to pay taxes and file a tax return, here’s what you need to know.

When Do Minors Have to Pay Taxes?

As with adults, minors have to pay taxes when their income exceeds the standard deduction or exemption. This is true regardless of whether they’re considered a dependent and can apply to both federal and state taxes.

Generally, there are two types of income that may result in minors needing to pay taxes. First, there’s earned income, which is typically money that comes from a job. With this, a child is only considered to have taxable income on a federal level if their earnings exceed the standard deduction, which is set at $12,950 for 2022. The threshold for owing state income taxes can vary, so you’ll need to check your state’s exemption amount to determine if they’ll need to pay.

Second, minors may have unearned income. Usually, this is money relating to investments or savings, such as interest or dividends. With this, the exemption is only $1,150 for 2022. Anything above that is potentially taxable.

Do Minors Get Taxes Taken Out of Their Paycheck?

If your child works for a traditional employer, taxes are often taken out of their paycheck. Most employers use the same process to ensure they meet legal requirements regarding withholding, so they treat all employees the same in that regard, no matter their age.

Like adults, minors complete Form W-4. On that, they can use the form to alter what’s withheld, allowing them to essentially have less removed than would be standard for their earnings. If a minor knows they won’t cross the standard deduction amount with their earnings, this could help them limit the amount that’s taken out of their paycheck. However, if they may exceed the threshold, that strategy could cause them to under withhold, which would leave them owing money when it was time to file.

Additionally, unless a child works for a company owned by their parents, FICA taxes – those covering Social Security and Medicare – are removed from their paycheck. There are no available exemptions to these taxes, aside from the aforementioned case of them working for a parent’s business.

Do Minors Have to File Taxes?

Technically, minors that earn less than the standard deduction and all of their income has already been reported to the IRS aren’t required to file their taxes, as they don’t owe any money to the government. However, that doesn’t mean they shouldn’t file, either through a parent’s return or on their own.

Many employers remove taxes from the paychecks of minors. If your child had taxes deducted, filing their taxes allows them to receive a refund. Without filing, that money isn’t returned, which makes submitting their tax information during the filing period essential.

For minors that earn more than the standard deduction, filing their state and federal taxes is essential. In that case, they do owe federal and state taxes. Even if their payroll deductions cover what’s owed, they need to file to formally settle the amount and either pay any additional amount owed or get a refund on the excess.

Additionally, minors that earn tips that aren’t reported to the IRS through their employer – something that’s more common with cash tips that go unrecorded by the company – they’ll need to file regardless of how much they’ve earned. That ensures that FICA taxes owed on the tip money are collected.

Finally, self-employed minors need to file their taxes if they make more than $400 in profit. Additionally, if the amount of tax owed is expected to exceed $1,000, then making quarterly tax payments is essential.

How a Minor Needs to File Taxes

There are technically two approaches a minor might have to use to file their federal taxes. First, if they make more than the standard deduction, they have to file their own return, regardless of age. Generally, minors with self-employment income should also file separately. Per the IRS, children who can’t handle the task on their own can receive assistance from a parent or guardian.

For earnings below that threshold, parents can report the income on their tax return instead. This ensures it’s properly tracked. Thus, any potential refund is capturable without the complexity of having a minor file a separate return. However, filing a separate return is an option here. This could serve as a great financial lesson that introduces your child to filing taxes, setting up for refunds, and otherwise understanding how taxes work.

If you have any questions regarding filing taxes for a minor child, speaking with a tax professional is a wise move. It allows you to get explicit guidance relating to your unique situation, which is beneficial.

Filing Requirements May Vary

Additionally, it’s important to note that state filing requirements for minor children can vary. While they often align with the federal thresholds, there can be some variances that alter the picture. As a result, you’ll want to research the rules in your area. This will help to determine if your child has to file separately or if they can be on a parent’s return. When in doubt, speak with a tax professional operating in your state for additional guidance.

Does it surprise you to learn that minors still have to pay taxes? Do you think making minors pay taxes is a smart move or that they should be exempt? Share your thoughts in the comments below.

Read More:

  • How to Reduce Business Taxes: A 2022 Guide
  • Annuities and Taxes: Here’s What You Need to Know
  • The Best Way to Do Your Taxes When Running Your Own Business


Tamila McDonald
Tamila McDonald

Tamila McDonald is a U.S. Army veteran with 20 years of service, including five years as a military financial advisor. After retiring from the Army, she spent eight years as an AFCPE-certified personal financial advisor for wounded warriors and their families. Now she writes about personal finance and benefits programs for numerous financial websites.

Filed Under: Tax Planning, tax tips Tagged With: file taxes, minors need to file taxes

5 Places to File Your Taxes For Free

February 7, 2022 by Tamila McDonald Leave a Comment

file your taxes for free

Filing your taxes is always cumbersome. You have to gather up paperwork, complete a number of forms, and make sure the calculations are correct. Usually, you also have to dive into deductions and credits, ensuring you find every legitimate opportunity for savings. Once you’re done, you typically have to pay a pretty penny to wrap it all up, which isn’t fun. But is paying to file a necessity? Not necessarily. If you qualify for certain programs, you may be able to handle the filing without spending a dime. Here’s a look at five places where you can file your taxes for free.

1. IRS Free File

If you’re looking for a straightforward option that lets you file your taxes for free, the IRS Free File program is an excellent option. You can complete your forms online and get clear guidance along the way. Plus, it’ll handle all of the calculations, so you don’t’ have to worry about the math.

Technically, this program is a partnership with many leading tax software providers. You can choose the service that best meets your needs, all without having to pay a traditional price tag.

Qualifying for the program is relatively straightforward. The biggest part is having an adjusted gross income (AGI) below $73,000. You’ll also have to answer some basic questions to show that you have a simple return and cover a few other must-haves. If you’re eligible, you can then choose a service provider from the list of options.

2. TCE or VITA

If you want in-person support, the Tax Counseling for the Elderly (TCE) or Volunteer Income Tax Assistance (VITA) programs may work well for qualifying individuals. The programs are sponsored by the IRS and help disadvantaged households get the support they need.

Qualifying for TCE usually involves being at least 60 years old. For VITA, the income limit is generally near $58,000. However, those with disabilities or limited English proficiency may qualify even if their income is higher, so it’s worth reaching out if either of those circumstances apply to you.

The preparers typically set up shop in widely accessible places, like public libraries, community centers, or local colleges and universities. You can find out exactly where you’ll need to go by using the IRS search tool.

Due to COVID-related restrictions, appointments may be necessary. Additionally, you might need to follow certain protocols – such as wearing a mask and not attending with guests – depending on where you live.

3. TurboTax

Another option that lets you file your taxes for free is the TurboTax Free Edition. As long as you have a simple return, you are potentially eligible for no-cost federal and state tax filings.

Along with using the online service to complete your own tax return, you have other choices. You can use a mostly DIY approach, reaching out to an expert only if you have a question. This approach is ideal if you are generally comfortable with using a classic fill-in-the-blank method to provide the needed information but might have questions about certain deductions, credits, forms, or fields.

However, you also have the option of having a tax professional take care of all of the work, all without owing a single cent when you’re done. This part of the program is only available until February 15, so act fast if you want to go in this direction.

Even if you don’t use a professional, everyone can get help for free if there is a technical issue. Additionally, if you’re having trouble accessing your account, you can reach out then, as well.

4. H&R Block

Like TurboTax, H&R Block has a Free Online program for simple returns that covers both federal and state tax filings. It’s simple and intuitive to use. Plus, you’ll get access to helpful information about potential deductions and credits, allowing you to reduce your tax obligation based on the options you’re eligible to use.

Do keep in mind that reaching out to a tax professional using this option isn’t necessarily free. However, there are a decent number of no-cost resources available, which may be enough if you aren’t wholly unfamiliar with tax filings. Additionally, you can get free help if you experience a technical issue, such as trouble accessing your account, so you aren’t entirely on your own as you work through the process.

5. TaxAct

TaxAct is another company with a free online filing option for federal returns. You’ll need to have a simple return to qualify, though you are eligible if you have education-related deductions, unemployment income, or a few other common – but not universal – tax situations you’ll need to navigate.

State filings do cost extra with TaxAct, so it may not be an ideal fit if you have to file in your state, too. Otherwise, you’ll get plenty of guidance through easy-to-use document libraries and similar resources to help you complete the forms and file electronically. However, assistance from a professional isn’t included for tax-related questions, only account issues like login trouble or similar technical difficulties.

Are you aware of any other places that let you file your taxes for free? Have you tried one of the free tax filing options above and want to let others know about your experience with that approach? Share your thoughts in the comments below.

Read More:

  • Pay Attention to These 8 Tax Pitfalls
  • Tax Tips for Tax Time
  • Annuities and Taxes: Here’s What You Need to Know


Tamila McDonald
Tamila McDonald

Tamila McDonald is a U.S. Army veteran with 20 years of service, including five years as a military financial advisor. After retiring from the Army, she spent eight years as an AFCPE-certified personal financial advisor for wounded warriors and their families. Now she writes about personal finance and benefits programs for numerous financial websites.

Filed Under: tax tips Tagged With: save money on taxes, tax planning, tax tips

Pay Attention to These 8 Tax Pitfalls

January 31, 2022 by Tamila McDonald Leave a Comment

tax pitfalls

Filing your taxes each year isn’t usually easy. For one, tax laws are incredibly complex. For another, there is a slew of credits and deductions out there, making it hard for most people to ensure that they’re tapping everything they’re eligible to use. Thankfully, by learning about tax pitfalls, it’s possible to handle your taxes correctly. Here are eight tax pitfalls that all filers need to pay attention to this year.

1. Not Researching Tax Breaks

As mentioned above, there are numerous credits and deductions available to tax filers. The thing is, if you don’t find the ones you can use on your own (or by using an appropriate tax service or professional), the IRS isn’t going to tell you that you missed one.

Generally, the IRS worries about you underpaying, not overpaying. If you miss a credit or deduction, that’ll essentially be on you.

If you’re worried that you’re overlooking an opportunity, then turn to a tax professional or use reputable tax software. With the former, they’ll have the expertise to ensure you check every potential option. With the latter, the software knows about every deduction and credit that’s out there and can help determine if you’re eligible with a few clicks.

2. Mixing Up the Deadlines

While it would be easier if all of the tax-related deadlines were the same, that isn’t how they’re set up. Certain things wrap up on December 31 of the tax year, while others extend into the new year. For example, mortgage interest and 401(k) contributions are calculated from January 1 through December 31 during the tax year.

However, you can make a qualifying contribution into an IRA until the tax filing deadline the year after. For instance, if you wanted to boost your tax deduction when you file your 2021 taxes in 2022, you could contribute to a qualifying IRA up until April 15, 2022, and apply that amount to your 2021 taxes. The same option is available for health savings accounts.

By knowing the various deadlines, you have the ability to maximize certain deductions within a given tax year. As a result, you may be able to reduce what you owe significantly.

3. Overlooking Non-Traditional Income

When you file your taxes, you need to include all of your income from every source. While this is simple with traditional jobs that provide W-2s, those aren’t the only kinds of earnings that you’ll need to report.

For instance, anything reported on a 1099 typically needs to be reported. This includes self-employment income from specific sources, as well as investment earnings, gambling winnings, sweepstakes prizes, lottery winnings, savings account interest, and more.

Additionally, you have to report income that doesn’t show on any forms. Usually, a 1099 is only required if the dollar amount in question crosses a specific line, such as $600. However, if you earned $200 doing online surveys, you still have to report that money, even if you don’t get a 1099. Otherwise, you may underreport and could face a penalty.

4. Making Math Mistakes

Even a small math error can have big consequences if it causes you to underpay. Plus, errors might increase your odds of getting audited, which isn’t any fun.

Usually, math issues are most likely for those doing their taxes by hand. With software systems – including those traditionally used by tax professionals – the calculations are built into the program, reducing the likelihood of a mistake. As a result, using a solution could be your best bet.

5. Incorrect Names or Social Security Numbers

While you might think that a small typo in a filer’s or dependent’s name or Social Security number isn’t a big deal, the IRS doesn’t agree. Missing or incorrect Social Security numbers will get noticed and trigger ramifications, the nature of which may vary depending on the rest of your situation.

The same goes for misspelled names. If the name doesn’t match what’s on file with Social Security, you could face filing difficulties.

6. Choosing the Wrong Filing Status (or Incorrectly Claiming Dependents)

When you file your taxes, you have to select a filing status. If you pick the wrong one, you could end up paying more than you should or less than you’re required. With the former, that means sending money to the IRS that you didn’t owe, which isn’t ideal. With the latter, you’ll face penalties when your mistake is caught.

Incorrectly claiming dependents comes with the same risks. You could end up over or underpaying, neither of which is good.

If you need more information about filing status and dependent options, the IRS has an online tool that can help. Plus, most tax software solutions and professionals can help you determine the right classification for your situation.

7. Not Filing for an Extension If You’re Struggling Last Minute

If you’re trying to wrap up your taxes and filing day is just a couple of days away, be realistic about whether you can pull it off. If your situation is too complex to finish on your own in that time, file for an extension immediately.

When you file for an extension, you’re letting the IRS know that you are having trouble getting everything handled before the deadline, keeping the agency in the loop. Usually, the IRS is reasonably forgiving if you file an extension and will typically grant you the needed time in this situation. Just remember that you need to pay what you owe by the filing deadline. Otherwise, you may face financial penalties.

8. Paying Too Much to File

Many people don’t realize that those with simple tax situations and who have household incomes below a specific threshold can usually file their taxes online for free. For example, if your adjusted gross income (AGI) is no more than $73,000, you can use the IRS Free File program, which includes online forms, automatic calculations, and e-file capabilities.

However, there are other free services available. Many of the major tax software providers have a free version for simple tax situations, such as those who only have W-2 income to report, are claiming the standard deduction, and are only using basic tax credits.

Before you pay for any service, see if a free filing option is available to you. That way, you can get the job done without spending any money unnecessarily.

Can you think of any other tax pitfalls people should watch out for when they file? Have you had to deal with any of the pitfalls above and want to tell others about your experience? Share your thoughts in the comments below.

Read More:

  • Tax Tips for Tax Time
  • Annuities and Taxes: Here’s What You Need to Know
  • The Best Way to Do Your Taxes When Running Your Own Business
Tamila McDonald
Tamila McDonald

Tamila McDonald is a U.S. Army veteran with 20 years of service, including five years as a military financial advisor. After retiring from the Army, she spent eight years as an AFCPE-certified personal financial advisor for wounded warriors and their families. Now she writes about personal finance and benefits programs for numerous financial websites.

Filed Under: tax tips Tagged With: tax audits, tax pitfalls, tax tips

Tax Tips for Tax Time

January 19, 2022 by Jacob Sensiba Leave a Comment

April is fast approaching and soon, everyone will have to visit their accountants and file their taxes. That said, we need to make sure we are filing taxes correctly. Keeping accurate and up-to-date records is important. Here are some tax tips and how to be well-prepared for tax time.

Contribute to retirement accounts

If you haven’t done so yet, or you’d like to contribute more, you have until tax filing day to do so. For a refresher, here are the contribution limits for some IRAs: IRA/Roth IRA – Max contribution is $6,000 ($7,000 if you’re over 50 or older).

If you have a SEP IRA and you get an extension, you have until October 17, 2022, to make your 2021 contribution.

This is more of a tip for the end of the year, but make sure you take your Required Minimum Distributions. For people that are either over 70 ½ or over 72, depending on when you turned those ages, you need to withdraw money from your IRA. If you don’t, you’ll pay a tax penalty of 50% of the amount you should have withdrawn. For example, if your required amount was $10,000. You’ll pay a $5,000 tax penalty if you didn’t take that distribution.

Make a last-minute estimated payment

If you didn’t pay enough or you didn’t make a payment to the IRS for 2021 taxes, you have until you file to make your payment.

According to the IRS rules, you must pay 100% of last year’s tax liability or 90% of this year’s or you will owe an underpayment penalty.

Get tax docs in order

Get all of your tax documents in order. For earnings for the year, you’ll need one to several forms, depending on what you do for a living and how your business is set up. W2s are pretty common. If you’re an independent contractor, you’ll need 1099. 

Itemize your deductions

Most people will take the standardized deduction, which is $12,550 for single filers and $25,100 for married couples filing jointly.

However, if you are self-employed or you have a lot of expenses that are tax-deductible, itemize your deductions. You could save a lot more money IF your total itemized deductions are larger than the standardized deduction.

Home office tax deduction

With the move to work from home still taking place, it might make sense to take advantage of the home office tax deduction. Here are some of the rules:

  • You must use the space exclusively for business
  • Expenses related to the space used for business are tax-deductible but need to be calculated according to the amount of square footage used for business
  • A lot of taxpayers stay away from this deduction, as they think it’s a red flag for an audit. If you’re legitimately using the space as you say and you aren’t fabricating numbers, then you have nothing to worry about

Last-minute tax tips for tax time

Triple-check your work if you prepared your own taxes and file on time. If you’re having someone prepare your taxes on your behalf, make your appointment ASAP because their calendars will fill up really fast.

Related reading:

Tax Tips for Small Business Owners

Are You Ready for Tax Time?

Why Financial Literacy is Important

Disclaimer:

**Securities offered through Securities America, Inc., Member FINRA/SIPC. Advisory services offered through Securities America Advisors, Inc. Securities America and its representatives do not provide tax or legal advice; therefore, it is important to coordinate with your tax or legal advisor regarding your specific situation. Please see the website for full disclosures: www.crgfinancialservices.com

Jacob Sensiba
Jacob Sensiba

Jacob Sensible is a financial advisor with decades of experience in the financial planning industry.  His journey into finance began out of necessity, stepping up to support his grandfather during a health crisis. This period not only grounded him in the essentials of stock analysis, investment strategies, and the critical roles of insurance and trusts in asset preservation but also instilled a comprehensive understanding of financial markets and wealth management.  Jacob can be reached at: jake.sensiba@mygfpartner.com.

mygfpartner.com/jacob-sensiba-wisconsin-financial-advisor/

Filed Under: money management, Personal Finance, Small business, Tax Planning, tax tips Tagged With: business tax, Income tax, Retirement, Tax, tax deductible, tax filing, tax planning, tax tips, taxes

How To Ask for Reimbursement of Travel Expenses

March 3, 2021 by Jacob Sensiba Leave a Comment

At this point in time, business travel is less common than it used to be. I have a hunch that it will never return to pre-pandemic levels, as employers found it easier and less expensive to accomplish this through Zoom. It’s still important to know the ins and outs. Today we will cover how to ask for reimbursement of travel expenses.

What are travel expenses?

Travel expenses occur when an employee travels for business purposes. A business trip can include conferences, business meetings, client meetings, training, job fairs, etc.  One thing about travel expenses, is you need to be sure you’re getting the best jet card program.  You want to get as many points or cash back rewards as possible.  

Travel expenses include lodging, food, rental car, tips for servers and bellhops, etc. Most organizations that require employees to travel on a regular basis have policies in place.

If an employee is traveling for an extended period of time or is at a particular location for an extended stay, the business may also include reimbursement to pay for your family to visit.

When entertaining a client or a business partner, there are limits on entertainment expense reimbursement, so make sure you check your company’s guidelines so you don’t breach that threshold.

How do employees pay for travel expenses?

Company credit cards, personal credit/debit cards, cash, or allowances given by the employer.

How to ask for reimbursement of travel expenses

If the corporate policies are unclear about the process, write a letter first. Before you go on a trip or take a client out for lunch, request the payment of the expense, or at least ask for some information about what is covered, what isn’t, and what the limits are. Establishing communication upfront is very important.

Per diem, aka travel allowance or an expense account, is recognized by the IRS. Per their guidelines, your expense report is due to your employer (usually HR) within 60 days. The report should include dates, location(s), and receipts.

If you have any allowances or advancements that haven’t been used or can’t be justified as a business expense, then you must return that to your employer. If you don’t return it, that money can be classified as taxable income.

Conclusion

As I said in the opening, I don’t believe business travel will return to pre-pandemic levels, but it’s important to know what travel expenses are and how to ask for reimbursement of travel expenses.

Review your company’s business travel policy for more information, and if your company doesn’t have one, speak to them about what’s covered, what’s not covered, and any limitations.

Related reading:

Why Financial Literacy Matters

Top Reasons you Need Car Insurance

**Securities offered through Securities America, Inc., Member FINRA/SIPC. Advisory services offered through Securities America Advisors, Inc. Securities America and its representatives do not provide tax or legal advice; therefore, it is important to coordinate with your tax or legal advisor regarding your specific situation. Please see the website for full disclosures: www.crgfinancialservices.com

Jacob Sensiba
Jacob Sensiba

Jacob Sensible is a financial advisor with decades of experience in the financial planning industry.  His journey into finance began out of necessity, stepping up to support his grandfather during a health crisis. This period not only grounded him in the essentials of stock analysis, investment strategies, and the critical roles of insurance and trusts in asset preservation but also instilled a comprehensive understanding of financial markets and wealth management.  Jacob can be reached at: jake.sensiba@mygfpartner.com.

mygfpartner.com/jacob-sensiba-wisconsin-financial-advisor/

Filed Under: Personal Finance, tax tips, Travel Tagged With: Business, taxes, travel, travel expenses, work travel

  • « Previous Page
  • 1
  • …
  • 16
  • 17
  • 18
  • 19
  • 20
  • 21
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework