• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for retirement planning

Is There Anyway to Temporarily Stop 401k Contributions in an Emergency Situation

April 10, 2025 by Travis Campbell Leave a Comment

coins in a jar
Image Source: unsplash.com

Yes, you can temporarily stop your 401(k) contributions during financial emergencies. 401(k) plans are voluntary retirement savings vehicles that allow you to adjust or pause contributions as needed. Most employers permit contribution changes at any time, though some may process changes only at specific intervals. The decision to pause contributions is entirely yours and protected under federal law. Stopping contributions doesn’t affect your existing account balance or investment growth potential. Your previously contributed funds remain invested according to your selections and continue to grow based on market performance. Remember that pausing contributions is different from withdrawing funds, which typically triggers taxes and penalties if done before retirement age. This flexibility gives you breathing room during financial hardships without abandoning your retirement security entirely.

Common Emergency Situations That Warrant Pausing Contributions

Financial emergencies come in various forms, and sometimes, pausing retirement contributions becomes necessary. Unexpected medical expenses can quickly deplete savings and create significant financial strain, making a temporary contribution pause reasonable. Job loss or reduced income may require redirecting every dollar toward essential living expenses. High-interest debt accumulation, particularly credit card debt with 18-25% rates, might justify temporarily redirecting retirement contributions toward debt reduction. Major home repairs that can’t be postponed, such as roof replacement or furnace failure, might necessitate additional cash flow. Family emergencies, including caring for ill relatives or unexpected childcare costs, can also strain finances. According to research, over half of American workers reduced or stopped retirement contributions during economic stress periods in recent years.

The Process of Temporarily Stopping Your 401(k) Contributions

Stopping your 401(k) contributions is typically straightforward and can be done through several methods. Contact your HR department or benefits administrator to request the appropriate form to change your contribution percentage. Many employers offer online portals where you can adjust your contribution rate to 0% without paperwork. Some companies allow changes via phone through their benefits hotline. When making the change, specify that you want to temporarily stop contributions rather than withdraw funds. Changes usually take effect within 1-2 pay periods, though timing varies by employer. Be sure to confirm the change by checking your next paycheck stub to ensure no deductions were taken. The IRS doesn’t impose penalties for stopping contributions, making this a penalty-free way to increase your take-home pay during emergencies.

Financial Implications of Pausing Your Retirement Savings

Temporarily stopping 401(k) contributions has several financial implications you should consider carefully. The most immediate impact is increased take-home pay, as pre-tax contributions that previously reduced your taxable income will now be included in your paycheck. However, you’ll lose valuable employer matching contributions during the pause period – essentially forfeiting “free money” toward your retirement. According to the IRS website, these matching funds are part of your total compensation package. The long-term effect of compounding growth on missed contributions can be substantial. For example, $5,000 in missed contributions could represent $15,000-$20,000 in retirement funds over 20 years, depending on investment returns. Your tax liability will increase without the pre-tax contributions, reducing your taxable income and potentially pushing you into a higher tax bracket.

Smart Alternatives to Completely Stopping Contributions

Before completely halting your 401(k) contributions, consider these alternative approaches that might better balance immediate needs with long-term goals. Reduce your contribution percentage rather than stopping entirely – even contributing 1-2% helps maintain the saving habit while increasing take-home pay. Contribute just enough to capture your employer’s full matching contribution, which provides an immediate 100% return on those dollars. Explore whether your plan allows for hardship withdrawals or loans instead of stopping contributions. Temporarily redirect contributions to an emergency fund, then resume retirement savings once the fund is established. Adjust your tax withholding to increase take-home pay without affecting retirement savings. Review your budget for other areas to cut before reducing retirement savings, such as subscription services or discretionary spending.

How to Restart Contributions After Your Emergency Passes

Once your financial emergency is resolved, promptly restarting your 401(k) contributions is crucial for your retirement security. Contact your HR department or log into your benefits portal to reinstate contributions, ideally setting a specific date for the restart. Consider implementing an automatic increase program that gradually raises your contribution percentage over time to rebuild momentum. Many plans offer this feature to help participants catch up. If possible, temporarily increase your contribution percentage above your pre-emergency level to compensate for lost time. The IRS contribution limits ($22,500 in 2023, plus a $7,500 catch-up for those over 50) provide room to accelerate savings. Review and potentially adjust your investment allocations when restarting to ensure they still align with your retirement timeline and risk tolerance.

Making the Right Choice for Your Financial Future

Temporarily stopping 401(k) contributions during genuine emergencies can provide needed financial relief but should be approached strategically. Weigh immediate needs against long-term retirement security and consider partial reductions before complete stops. Remember that employer matches represent immediate 100% returns on your contributions. Create a specific plan for restarting contributions once your situation improves.

Have you ever needed to pause retirement savings during a financial emergency? What strategies helped you get back on track? Share your experiences in the comments below.

Read More

Taxes and Penalties: 401k Withdrawals

Should I Tap My Retirement Funds for Medical Expenses?

Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Personal Finance Tagged With: 401k contributions, employer match, financial emergency, hardship withdrawal, retirement planning, retirement savings pause

8 Reasons Boomers Aren’t Leaving Their Homes To Their Kids

April 9, 2025 by Travis Campbell Leave a Comment

boomers eating popcorn
Image Source: pexels

The “Great Wealth Transfer” may not be so great after all. While economists have predicted up to $84 trillion in assets will transfer from baby boomers to younger generations over the next two decades, many boomers aren’t planning to leave their homes—often their most valuable asset—to their children. Here’s why this generational shift is happening.

1. Rising Healthcare Costs Are Depleting Retirement Savings

Healthcare expenses have skyrocketed, with medical care costs increasing by over 114% since 2000, significantly outpacing the 81% rise in overall prices. Many boomers spend their nest eggs on medical bills instead of preserving them for inheritance. Medicare doesn’t cover dental or vision care, and even small copays add up quickly when managing multiple health conditions. As Judi Koncak, an 83-year-old retiree, puts it, “I thought we’d spend our golden years sitting on a beach in Hawaii with Mai Tais, even if in wheelchairs.” Instead, her husband’s stroke, surgeries, and cancer treatments depleted their savings, leaving little for their children.

2. Longer Lifespans Mean Extended Retirement Funding Needs

Americans are living longer than ever before, requiring retirement savings to stretch further. According to health policy experts, 60% of healthcare costs come after age 65, and those over 85 use three times more healthcare services than people between 65 and 75. This longevity creates financial uncertainty, making many boomers reluctant to commit to leaving substantial assets behind. The fear of running out of money is a powerful motivator to hold onto assets rather than promising them to children who might be counting on an inheritance.

3. Long-Term Care Costs Can Quickly Deplete Home Equity

The average annual cost of nursing home care exceeds $108,000 for a private room—more than twice the typical annual income for people over 65. Home care isn’t much cheaper, averaging around $42,000 annually for just 30 hours of weekly care. As retirement expert Jason Fichtner notes, “If someone’s sitting on a $250,000 house, and it’s paid off, and they get into their 80s and they need long-term care, long-term care can cost $10,000 a month right now. That’s going to buy you 2, 2½ years of long-term care.”

4. Many Boomers Prioritize Their Own Financial Security

A Northwestern Mutual survey found that only 11% of boomers consider leaving an inheritance their top financial goal. After working hard for decades, many feel entitled to enjoy their assets rather than preserving them for the next generation. As financial planner Melissa Cox explains, “A lot of older people are saying ‘I’ve done my due.’ They had to work their tuchus off for what they have. I’ve heard people saying, ‘I don’t want your financial plan to be my death.'”

5. The “Me Generation” Philosophy Extends to Retirement

Baby boomers have been dubbed the “Me Generation” for a reason. A Charles Schwab survey of wealthy Americans revealed that 45% of boomers agreed with the statement: “I want to enjoy my money for myself while I’m still alive.” This contrasts sharply with millennials and Gen Xers, of whom only 15% and 11% respectively shared this sentiment. This generational attitude difference reflects deeper values about wealth and family responsibility.

6. Many Lack Proper Estate Planning

According to Northwestern Mutual, two-fifths of boomers have no will, and half don’t know how much money they’ll need for a comfortable retirement. Without proper estate planning, homes often end up in probate—a lengthy, expensive process that can diminish the value of the inheritance. This lack of planning means many homes may be sold to cover final expenses rather than transferred to children.

7. Reverse Mortgages and Home Equity Loans Reduce Transferable Value

Financial pressures have led many boomers to tap into their home equity through reverse mortgages or home equity loans. These financial products provide needed cash flow but reduce or eliminate the equity that might otherwise be passed to children. While only 9% of boomers in a Freddie Mac survey said they planned to use home equity to fund retirement, economic necessity often changes these plans as healthcare and living costs rise.

8. Some Boomers Use Their Homes as Bargaining Chips for Care

Some aging parents implicitly or explicitly use their homes as leverage to ensure their children provide care or attention in their final years. This transactional approach to inheritance creates uncertainty about whether the home will actually be transferred and under what conditions, leading to family tensions and complicated estate situations.

What This Means for Future Generations

The reality is that many in Gen X, Millennial, and Gen Z cohorts may need to adjust their expectations about receiving property inheritance. The anticipated wealth transfer may end up in the healthcare system rather than younger generations’ bank accounts. As Kathy Kiersted, a 64-year-old facing high healthcare costs, observes: “There’s no middle class, either you’re upper class or lower class. Children from high-net wealth families will come out of this generational wealth transfer with money, but that’s an upper-class thing, not afforded to every class anymore.”

Are You Prepared for Your Financial Future?

Have you had conversations with your parents about inheritance expectations, or are you a boomer making decisions about your estate? Share your thoughts and experiences in the comments below.

Read More

10 Smart Reasons Most Baby Boomers Are Aging in Place

12 Reasons Millennials Are Pushing Off Estate Planning

Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.

Filed Under: Estate Planning Tagged With: baby boomers, Estate planning, generational wealth, healthcare costs, Housing Market, Inheritance, Planning, retirement planning

8 Circumstances Where You Really Need Financial Advice and Where to Find It

April 7, 2025 by Travis Campbell Leave a Comment

money on table
Image Source: unsplash.com

Navigating your financial journey alone can sometimes feel like sailing through stormy waters without a compass. While many financial decisions can be handled independently, certain life events and financial complexities demand professional guidance. Recognizing when you need expert financial advice is crucial for protecting your wealth and securing your future. This article explores eight specific situations where seeking professional financial advice isn’t just helpful—it’s essential.

1. Major Life Transitions Require Financial Recalibration

Life transitions often trigger the need for comprehensive financial planning. Marriage, divorce, or the birth of a child fundamentally changes your financial responsibilities and goals. The death of a spouse can leave you navigating complex financial decisions while grieving. Career changes, especially those involving significant salary adjustments or relocation, necessitate a fresh look at your financial strategy. A financial advisor can help you adjust your financial plan during these transitions, ensuring your new life chapter starts on solid financial footing.

2. Inheritance Management Demands Strategic Planning

Receiving an inheritance often comes with emotional and financial complexities that require professional guidance. The sudden influx of assets may include investments, property, or retirement accounts that each carry different tax implications and management requirements. Poor inheritance management decisions can lead to unnecessary tax burdens or missed growth opportunities that diminish the inheritance’s value. A financial advisor can help you integrate inherited assets into your existing financial plan while respecting any wishes the benefactor may have had. Professional guidance ensures you honor the gift by managing it responsibly while maximizing its potential to support your financial goals.

3. Retirement Planning Becomes Increasingly Complex

Retirement planning involves more than simply saving money—it requires strategic decision-making about investment allocations, withdrawal rates, and timing. As retirement approaches, mistakes become costlier with less time to recover from market downturns or planning errors. Questions about Social Security optimization, pension options, and healthcare planning require specialized knowledge that most individuals don’t possess. A financial advisor can create a comprehensive retirement income strategy that addresses longevity risk, inflation, and market volatility. Professional guidance becomes particularly valuable when transitioning from the accumulation phase to the distribution phase of retirement planning.

4. Tax Optimization Requires Specialized Knowledge

Tax laws change frequently and contain numerous complexities that can significantly impact your financial situation. High-income earners, business owners, and those with diverse investment portfolios face particularly complicated tax scenarios. Strategic tax planning can legally reduce your tax burden through techniques like tax-loss harvesting, charitable giving strategies, and retirement account optimization. A financial advisor with tax expertise can coordinate with your accountant to implement tax-efficient investment strategies and withdrawal plans. Professional guidance ensures you’re not paying more in taxes than legally required while avoiding costly mistakes that could trigger IRS scrutiny.

5. Estate Planning Protects Your Legacy and Loved Ones

Estate planning goes beyond basic will creation to encompass comprehensive strategies for transferring wealth efficiently. Without proper planning, your assets may be distributed according to state laws rather than your wishes, potentially creating family conflicts. Estate taxes can significantly reduce the wealth transferred to your heirs without strategic planning techniques in place. A financial advisor can work with estate attorneys to create a cohesive plan that addresses wealth transfer, tax minimization, and charitable giving goals. Professional guidance ensures your estate plan remains updated as laws change and your family circumstances evolve over time.

6. Investment Management During Market Volatility

Market volatility tests even the most disciplined investors, often triggering emotional decisions that can damage long-term returns. Research consistently shows that individual investors underperform market indices largely due to behavioral biases and poor timing decisions. Complex investment vehicles like options, alternative investments, and tax-advantaged accounts require specialized knowledge to utilize effectively. A financial advisor provides an objective perspective during market turbulence, helping you stick to your long-term strategy rather than reacting to short-term fluctuations. Professional guidance becomes particularly valuable during major market corrections when emotional decision-making can lead to locking in losses.

7. Business Ownership Creates Unique Financial Challenges

Business owners face unique financial challenges that blur the line between personal and business finances. Succession planning, business valuation, and exit strategies require specialized expertise to execute effectively. Retirement planning becomes more complex for business owners who often have much of their net worth tied up in their business. A financial advisor with business expertise can help create strategies for business growth while ensuring personal financial security. Professional guidance can help business owners balance reinvesting in their business with diversifying their personal wealth to reduce concentration risk.

8. Special Needs Planning Requires Long-Term Vision

Families caring for individuals with special needs face unique financial planning challenges that extend far into the future. Government benefits for individuals with disabilities often have strict asset and income limitations that require careful financial structuring. Special needs trusts and ABLE accounts must be properly established and funded to provide for a loved one without jeopardizing their eligibility for benefits. A financial advisor with special needs expertise can coordinate with legal professionals to create a comprehensive care plan. Professional guidance ensures continuity of care and financial support even after parents or primary caregivers are no longer able to provide it.

Securing Your Financial Future: Taking the Next Step

Finding the right financial advisor requires understanding the different types of professionals and their compensation models. Fee-only fiduciary advisors offer conflict-free advice without commission incentives, while robo-advisors provide low-cost automated guidance for simpler situations. Professional designations like CFP® (Certified Financial Planner), CFA (Chartered Financial Analyst), or ChFC (Chartered Financial Consultant) indicate specialized training and ethical standards. Before committing, interview multiple advisors about their experience with situations similar to yours and their communication style. Remember that the best financial advice relationship is one built on trust, clear communication, and alignment with your specific needs and goals.

Have you faced any of these financial circumstances? What was your experience working with a financial advisor, or how did you handle the situation on your own? Share your insights in the comments below!

Read More

Help Me Help You: What Your Financial Advisor Wishes You’d Admit About Your Money Habits

Your Friend Makes More Money Than You—Now What? Dealing with Financial Jealousy

Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.
Filed Under: Finance Tagged With: Estate planning, financial advice, financial advisor, Investment management, Planning, retirement planning, tax planning, Wealth management

Retirees Are Firing Their Financial Advisors—Here’s the Surprising Reason Why

April 7, 2025 by Travis Campbell Leave a Comment

retirees looking at the ocean
Image Source: unsplash.com

In an unexpected trend sweeping across retirement communities nationwide, financial advisors are being shown the door by their long-term clients. This shift isn’t happening because of poor investment returns or high fees—though those factors certainly play a role. The surprising catalyst behind this exodus reveals a fundamental change in how today’s retirees view their financial futures and what they expect from professional guidance. Understanding this phenomenon could save your retirement strategy from costly missteps and help you determine whether your current financial relationship is truly serving your needs.

1. The Trust Gap Is Widening Between Advisors and Retirees

The relationship between financial advisors and their retired clients has historically been built on a foundation of trust and expertise. Many retirees are discovering their advisors have been operating under outdated models that prioritize product sales over genuine financial planning. According to a recent survey by Vanguard, nearly 60% of retirees who switched advisors cited “lack of transparency” as their primary motivation. Technology has empowered retirees to verify information independently, making it easier to spot discrepancies between what they’re told and what research reveals. The generational shift toward self-education means today’s retirees are more financially literate than previous generations, enabling them to ask tougher questions. This knowledge gap closure has exposed situations where some advisors simply cannot justify their recommendations when pressed for evidence-based reasoning.

2. One-Size-Fits-All Retirement Strategies No Longer Satisfy

Modern retirees are rejecting cookie-cutter financial plans that fail to address their unique circumstances and goals. The traditional “4% withdrawal rule” and other standardized approaches are increasingly viewed as outdated oversimplifications that don’t account for longer lifespans and changing economic conditions. Personalization has become non-negotiable, with retirees expecting strategies tailored to their specific health situations, family dynamics, and lifestyle aspirations. Many advisors still rely heavily on age-based asset allocation formulas rather than developing truly customized approaches based on individual risk tolerance and objectives. Retirees are increasingly seeking advisors who demonstrate genuine curiosity about their lives and develop financial strategies that reflect their personal values, not just mathematical formulas.

3. Fee Structures Are Finally Coming Under Scrutiny

The veil has been lifted on the true cost of financial advice, prompting many retirees to question the value they receive relative to fees paid. Traditional percentage-based advisory fees that seemed reasonable during wealth accumulation phases can represent significant dollar amounts when applied to retirement portfolios. According to a study by NerdWallet, the average American pays between $502,407 and $936,390 in investment fees over their lifetime. Retirees are increasingly gravitating toward fee-only fiduciaries who eliminate conflicts of interest inherent in commission-based models. The rise of low-cost robo-advisors and digital platforms has established new benchmarks for what basic investment management should cost. This fee awareness has forced many retirees to ask the uncomfortable question: “What exactly am I paying for, and is it worth it?”

4. Communication Styles Are Creating Generational Disconnects

Today’s retirees expect advisors to communicate in ways that respect their intelligence and technological competence. Many advisors still rely on intimidating jargon and technical terminology that creates unnecessary barriers to understanding. Retirees report frustration with advisors who speak condescendingly or assume limited financial knowledge based solely on age. The frequency of communication has become another pain point, with many retirees expecting more regular updates than quarterly meetings or annual reviews. Digital natives entering retirement expect advisors to leverage technology for more efficient communication while still maintaining the personal touch that builds relationship trust.

5. Retirement Goals Have Evolved Beyond Simple Wealth Preservation

The definition of retirement success has fundamentally changed, leaving some advisors struggling to adapt their approaches. Modern retirees increasingly prioritize experiences over assets, seeking financial strategies that enable active lifestyles rather than merely preserving wealth. Environmental and social impact considerations have become important factors in investment decisions for many retirees, who want portfolios aligned with their values. Healthspan—not just lifespan—has emerged as a critical planning factor, with retirees seeking advisors who understand the financial implications of longevity and wellness. Many advisors remain fixated on traditional metrics like portfolio size rather than the more meaningful measure of how finances support quality of life. Retirees are seeking professionals who understand that money is merely a tool for living rather than an end goal in itself.

Finding True Financial Partnerships in Retirement

The exodus from traditional advisory relationships doesn’t mean retirees are abandoning professional guidance altogether—they’re simply becoming more discerning consumers. The most successful retirement planning relationships now resemble partnerships rather than the paternalistic models of the past. Advisors who thrive in this new landscape demonstrate genuine empathy, technological competence, and a willingness to collaborate rather than dictate. Transparency has become the cornerstone of trust, with successful advisors proactively disclosing all fees, potential conflicts of interest, and the reasoning behind recommendations. The future belongs to advisors who position themselves as retirement lifestyle designers rather than merely investment managers.

Have you noticed changes in your relationship with your financial advisor as you’ve approached or entered retirement? What qualities would make you reconsider your current financial guidance arrangement?

Read More

Best Free Financial Advice

In Defense of Financial Advisor Fees

Travis Campbell
Travis Campbell

Travis Campbell is a digital marketer/developer with over 10 years of experience and a writer for over 6 years. He holds a degree in E-commerce and likes to share life advice he’s learned over the years. Travis loves spending time on the golf course or at the gym when he’s not working.
Filed Under: Finance Tagged With: fee transparency, fiduciary responsibility, financial advisors, modern retirement, retirement income, retirement planning

Before You Die Broke: The Financial Decisions You’ll Wish You Made Sooner

April 1, 2025 by Latrice Perez Leave a Comment

Portrait elderly couple whose blind wife sleeps on the lawn with her husband posing for a photo together. Their hearts are bright because they have a loving and caring husband always by their side.
Image Source: 123rf.com

As life winds down, many people reflect on the choices they made—or didn’t make—along the way. For those who struggle financially in their later years, certain missed opportunities often stand out as glaring regrets. These overlooked decisions have the power to transform lives, yet they’re frequently ignored until it’s too late. Let’s explore the key financial moves that people wish they had made earlier and how you can avoid the same mistakes.

1. Taking Financial Risks When You Were Young

Many regret being overly cautious with their money during their youth. Whether it was hesitating to invest in stocks, start a business, or pursue lucrative career opportunities, fear of failure often leads to stagnant growth. At the end of life, people often wish they had embraced risk while they still had the time to recover from setbacks and capitalize on potential success.

2. Saving for Retirement Earlier

Procrastination in retirement planning is a universal regret. Waiting until your 40s or 50s to save means missing out on decades of compound interest—a loss that’s hard to make up for later. People frequently look back and wish they had started saving earlier, even modest amounts in their 20s, realizing that every dollar could have multiplied exponentially over time.

3. Prioritizing Experiences Over Material Possessions

Many people regret spending money on fleeting luxuries rather than investing in meaningful experiences. Big-ticket items like fancy cars or designer clothes lose their allure, but memories of trips, hobbies, and time spent with loved ones remain. At the end of life, those who focused on material possessions often feel they missed out on the true richness of living.

4. Talking About Money Earlier in Relationships

Money is a difficult topic for couples, but avoiding these conversations can lead to poor financial decisions and missed opportunities for growth. Many people wish they had been more open about budgeting, saving, and future plans with their partner sooner. Transparency not only strengthens relationships but also ensures financial goals align over time.

5. Learning Financial Literacy While You Still Had Time

Some of the most painful regrets come from realizing how little you understood about managing money. Those who struggle financially in later years often wish they had educated themselves earlier—whether it was understanding investments, managing debt, or spotting financial scams. Financial literacy empowers smarter choices and protects against pitfalls.

6. Investing in Health to Avoid Financial Strain

Neglecting health-related spending is a common regret for those facing medical bills later in life. Skipping regular checkups, ignoring preventive care, or avoiding fitness investments can lead to costly issues that drain savings. Many look back and wish they had prioritized health earlier to avoid financial and physical stress in their later years.

7. Helping Others Strategically

business woman and a businessman hold money
Image Source: 123rf.com

Generosity is important, but unchecked giving can leave you financially vulnerable. Many regret helping family or friends without setting boundaries, particularly when loans or gifts weren’t repaid. On the flip side, some wish they had been more purposeful with their giving, supporting causes they believed in while maintaining financial security.

8. Diversifying Income Streams

Relying solely on a paycheck is a regret that often surfaces later in life. People wish they had pursued side hustles, created passive income, or taken advantage of entrepreneurial opportunities. Those who diversified their income early are better prepared for economic downturns and unexpected expenses, avoiding the financial stress faced by those who didn’t.

9. Estate Planning Before It Was Too Late

Failing to create a will or trust is a regret that often leads to conflict among loved ones. Those who neglect estate planning may inadvertently leave their family in disarray, facing legal battles or confusion about finances. Early planning ensures peace of mind and secures a lasting legacy.

10. Spending Less Time Stressing About Money

For many, the final years of life bring clarity that money isn’t everything. People often wish they had spent less time worrying about financial pressures and more time appreciating the relationships and experiences they did have. While financial security is important, it’s not worth sacrificing the joys of living.

A Legacy Worth Leaving

Financial regrets can weigh heavily, but the good news is that it’s never too late to start making smarter choices. Reflecting on the regrets of others can inspire you to take proactive steps toward stability, freedom, and fulfillment. Before it’s too late, start building a life and legacy that you’ll be proud of—not one defined by financial struggles.

Which financial decision do you think is the most important to make earlier in life? What money move do you wish you’d made sooner? Share your thoughts and experiences in the comments below.

Read More:

7 Eye-Opening Talks Every Mother and Adult Daughter Must Have Before It’s Too Late

9 Embarrassing Money Problems No One Talks About (But Everyone Has)


Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.

Filed Under: Personal Finance Tagged With: Estate planning, financial literacy, financial regrets, money moves, retirement planning, saving money, Wealth Building

The FIRE Movement’s Unspoken Challenges: Is Early Retirement for Everyone?

March 31, 2025 by Latrice Perez Leave a Comment

Group of people holding the TIME TO RETIRE written speech bubble
Image Source: 123rf.com

The Financial Independence, Retire Early (FIRE) movement has garnered significant attention for its promise of escaping the traditional workforce decades ahead of schedule. By emphasizing extreme savings and disciplined investing, adherents aim to achieve financial freedom and enjoy life on their own terms. However, beneath the allure of early retirement lie several challenges that are often overlooked. It’s crucial to examine these unspoken hurdles to determine if the FIRE lifestyle aligns with one’s personal and financial circumstances.​

1. Sustaining Extreme Frugality

Achieving FIRE typically requires maintaining a high savings rate, often necessitating a lifestyle of stringent frugality. While cutting expenses can accelerate financial independence, sustaining such a minimalist lifestyle over the long term can be mentally and emotionally taxing. Some individuals find that even after accumulating substantial savings, they struggle to transition away from frugality, potentially hindering their ability to enjoy the wealth they’ve amassed. ​

2. Emotional and Social Implications

Early retirement can lead to unexpected emotional and social challenges. Without the structure and social interactions provided by a traditional job, some early retirees experience feelings of isolation, boredom, or a loss of purpose. Building and maintaining a fulfilling post-retirement life requires proactive engagement in social activities and personal interests.

3. Healthcare Access and Costs

Retiring before the age of 65 means losing employer-sponsored health insurance and facing the complexities of securing private coverage. Navigating the healthcare marketplace can be daunting, and the associated costs can significantly impact one’s retirement budget. Ensuring continuous and affordable healthcare coverage is a critical consideration for prospective early retirees. ​

4. Market Volatility and Economic Uncertainty

The success of the FIRE strategy heavily relies on the performance of investments. Economic downturns, market volatility, and unforeseen financial crises can jeopardize the sustainability of an early retirement plan. Without the cushion of employment income, early retirees may find themselves vulnerable during prolonged market slumps.

5. Reentering the Workforce

Should financial circumstances change or the desire to return to work arise, reentering the workforce after an extended hiatus can be challenging. Gaps in employment may make it difficult to find positions comparable in responsibility and compensation to those held prior to retirement. Maintaining relevant skills and professional networks is advisable for those considering early retirement. ​

6. Impact on Social Security Benefits

Social Security Cards for identification and retirment USA
Image Source: 123rf.com

Retiring early can affect the amount of Social Security benefits one is eligible to receive. Benefits are calculated based on the highest 35 years of earnings; fewer working years can result in reduced monthly payments during traditional retirement years. Understanding these implications is essential for comprehensive retirement planning. ​

7. Potential for Regret and Unfulfilled Expectations

Some individuals who achieve early retirement find that the reality doesn’t match their expectations. Feelings of purposelessness or regret can emerge, leading some to return to work or seek new ventures to fill the void left by their careers. It’s important to have a clear vision for post-retirement life beyond just the financial aspects. ​

Not A One-Size-Fits-All Solution

While the FIRE movement offers an appealing alternative to traditional career trajectories, it’s not a one-size-fits-all solution. The challenges associated with early retirement—ranging from sustaining frugality to navigating emotional and financial uncertainties—underscore the importance of thorough planning and self-reflection. Prospective early retirees should carefully assess whether the FIRE lifestyle aligns with their personal goals, values, and circumstances before embarking on this unconventional path.​

What are your thoughts on the challenges of early retirement? Have you considered or pursued the FIRE lifestyle? Share your experiences and insights in the comments below.

Read More:

7 Ways Retirement Can Be Cheaper Than You Can Imagine

Need To Get Your Retirement In Order: Start By Reading These 5 Retirement Planning Books

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.

Filed Under: Retirement Tagged With: early retirement challenges, financial independence, FIRE movement, Personal Finance, retirement planning

8 Reasons Your Kids Don’t Want To Be Your Retirement Plan

March 22, 2025 by Latrice Perez Leave a Comment

Offended senior woman sitting on sofa in apartment. Her son and daughter-in-law quarreling with her.
Image Source: 123rf.com

It’s natural to hope your kids will be there for you in old age. After all, you raised them, supported them, and maybe even sacrificed your own dreams so they could chase theirs. But here’s the reality many parents avoid: most adult children don’t want—or plan—to become their parents’ retirement plan. Not because they don’t love you, but because the world they’re growing up in looks very different from the one you knew. If you’re banking on your kids to carry the financial or caregiving burden of your retirement, it may be time for a rethink.

They’re Already Struggling to Stay Afloat

Millennials and Gen Z are facing a financial landscape that’s far more brutal than previous generations. Between student loan debt, housing costs, and stagnant wages, many of your adult children are just trying to keep their heads above water. The idea of adding a parent’s financial needs into the mix feels overwhelming—if not impossible. It’s not that they don’t care; it’s that they’re barely managing their own bills. Relying on them adds pressure to an already strained system.

They Grew Up Watching You Struggle

If your kids saw you burn out working multiple jobs or fight to make ends meet, they may associate money with stress and instability. For some, that’s motivation to do better. For others, it sparks fear about repeating the same cycle. Asking them to shoulder your retirement may trigger resentment or anxiety, especially if they’re just finding their financial footing. Many want to break generational patterns, not repeat them.

They Want Boundaries You Didn’t Have

Today’s young adults are redefining what family obligations look like. They’re prioritizing mental health, balance, and boundaries—things many older generations were never taught to value. That includes setting limits with parents. Just because you were willing to care for aging family members doesn’t mean your kids feel the same obligation. They may love you deeply and still say no to becoming your caregiver, especially if it compromises their own lives.

They Feel Trapped by Cultural Expectations

Retirement Plan
Image Source: 123rf.com

In some families, there’s an unspoken rule: kids take care of their parents, no questions asked. But not everyone wants—or is equipped—to follow that path. Immigrant families, in particular, may carry traditions that assume adult children will provide financial and emotional support in return for being raised. Yet younger generations are starting to push back, feeling the weight of those expectations as a burden, not an honor. That internal conflict can strain relationships and foster guilt, especially when children feel forced into roles they didn’t choose.

They’re Watching You Spend Freely Now

If you’re living large in your 50s and 60s—taking vacations, upgrading your home, or driving luxury cars—your kids are noticing. And they may be quietly questioning how you plan to support yourself later. It’s hard for them to reconcile generous spending now with an expectation of help later. The message it sends? “You’ll be responsible for me later while I enjoy myself now.” That dynamic can create resentment or even distance over time.

They Want to Break the Cycle of Financial Codependence

Some families pass financial dependence down like a bad habit. Parents rely on their parents, and then their kids feel forced to step up in return. But many younger adults are saying, “No more.” They want financial independence—not just for themselves, but for their future children. That means making tough choices about how much they give and when. It’s not about being selfish—it’s about breaking unhealthy generational cycles of financial codependence.

They’re Already Planning for Their Own Retirement

Surprisingly, many younger adults are already thinking about their own long-term futures. They’re contributing to retirement accounts, building emergency savings, and trying to avoid debt. Why? Because they’ve seen firsthand what happens when retirement isn’t planned. Being asked to delay their own financial goals to care for a parent’s lack of preparation feels unfair. They’re not rejecting you—they’re protecting themselves.

They Want a Relationship—Not a Responsibility

At the heart of it all, your kids want to love you, not manage you. They want dinners, laughter, shared memories—not caregiver schedules and unpaid bills. When the relationship becomes transactional, it can chip away at emotional closeness. Adult children don’t want to feel like a financial plan—they want to feel like your family. The more independence you can maintain, the more authentic your connection will likely stay.

They May Want to Support You

Your kids may absolutely want to support you emotionally, physically, and even financially—but only if it comes from love, not obligation. They’re not being selfish—they’re setting boundaries in a world that demands more from them than ever before. The best gift you can give them is preparing for your future without making them responsible for it. Do it for their peace of mind—and your relationship.

Have you had this conversation with your children? How did it go—or what’s holding you back? Share your thoughts in the comments below.

Read More:

Here’s How to Tell Which One of Your Children Will Stay by Your Side Until the End

13 Things Young People Won’t Stop Doing That Elderly People Don’t Understand

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.

Filed Under: Retirement Tagged With: adult children, caregiving stress, elder care, family boundaries, financial independence, generational money issues, parenting and aging, retirement planning

Retire in Style: The 12 Most Gorgeous (and Pricey) Places to Settle Down

March 19, 2025 by Latrice Perez Leave a Comment

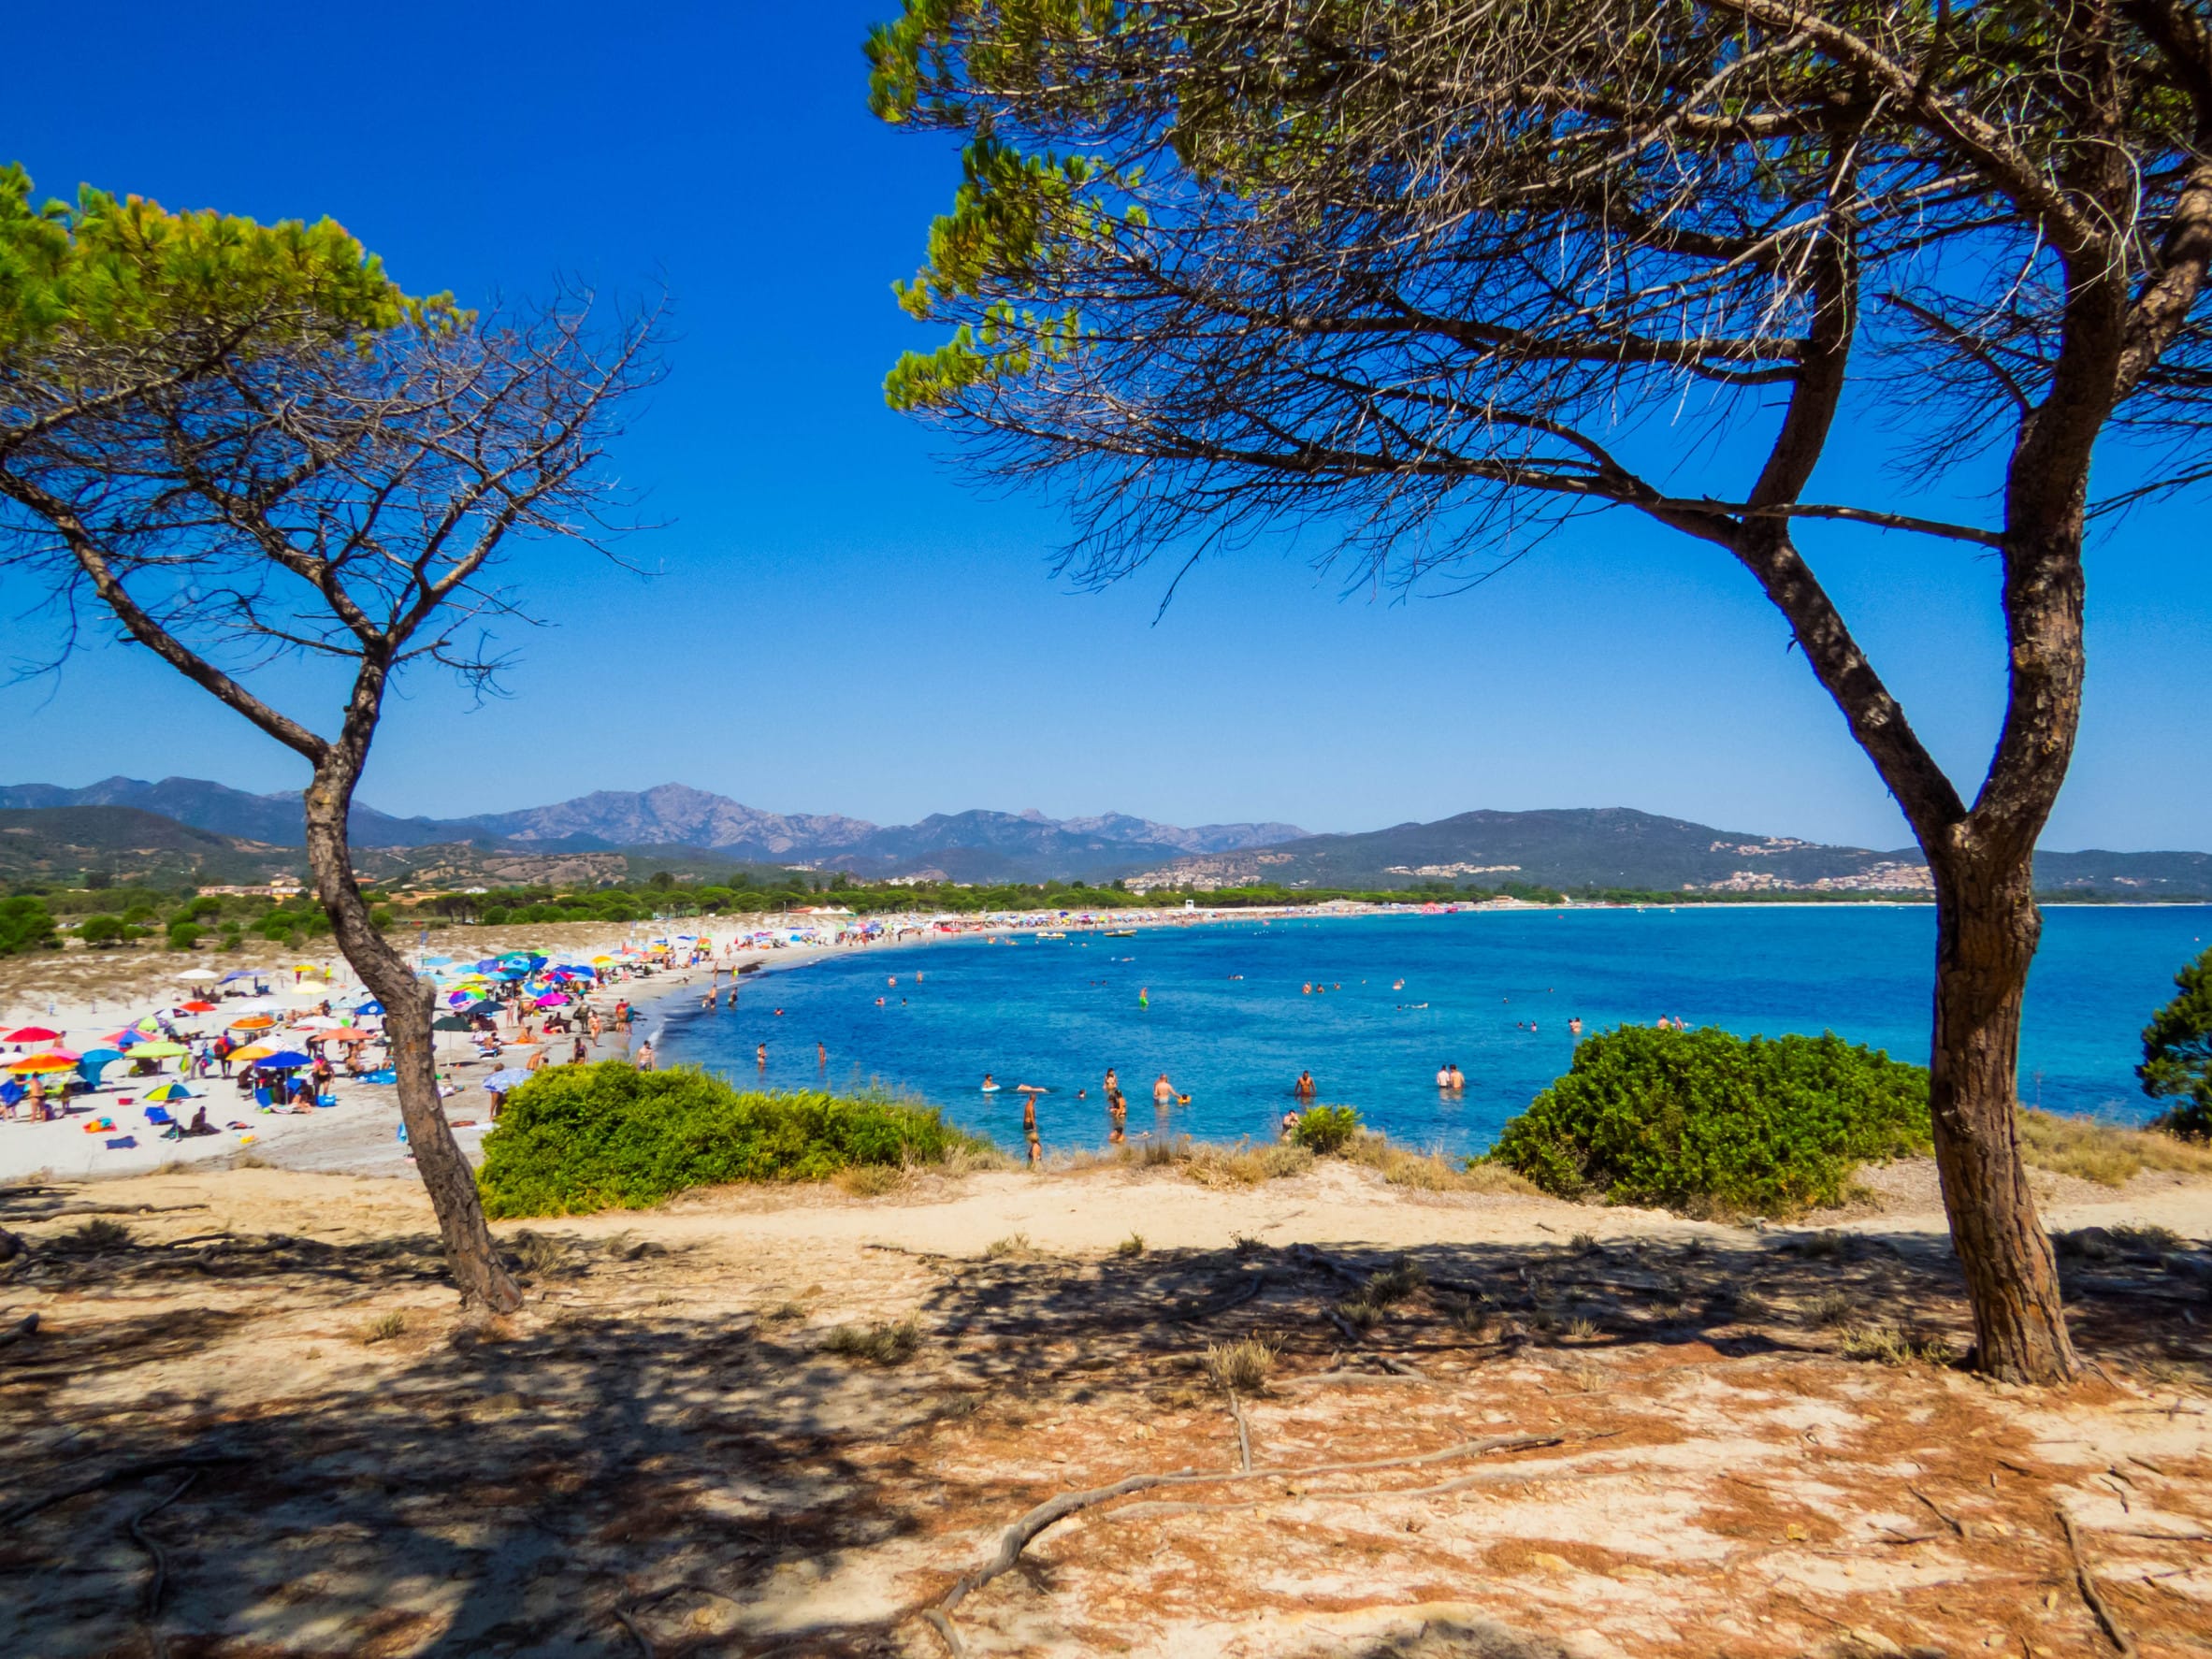
Sardinia
Image Source: 123rf.com

Retirement is a time to savor the fruits of your labor, and for many, this means settling in a place that offers both beauty and luxury. While numerous destinations worldwide cater to retirees seeking an upscale lifestyle, some stand out for their breathtaking landscapes and high living costs. Here are twelve of the most stunning yet expensive places to consider for your retirement:​

1. Rancho Palos Verdes, California, USA

Perched on the bluffs of the Palos Verdes Peninsula, Rancho Palos Verdes offers panoramic views of the Pacific Ocean. This serene city is known for its affluent neighborhoods, golf courses, and the iconic Point Vicente Lighthouse. The cost of living here is notably high, with annual homeowner expenses averaging around $149,970. Mortgage payments alone can reach $126,036 yearly, reflecting the area’s premium real estate market. Additionally, residents face average annual grocery costs of $5,277 and healthcare expenses of $6,801. ​

2. Porto Cervo, Sardinia, Italy

Nestled along the Costa Smeralda, Porto Cervo is a luxurious seaside resort renowned for its pristine beaches and crystal-clear waters. Developed in the 1960s by Prince Karim Aga Khan, it has become a playground for the elite, attracting celebrities and billionaires alike. The area boasts a well-equipped marina, upscale boutiques, and exquisite dining options. Real estate here is among the most expensive in Europe, with property prices reaching up to €300,000 per square meter in exclusive areas like Romazzino Bay.

3. Sotogrande, Andalusia, Spain

As one of the largest privately owned residential developments in Andalusia, Sotogrande offers a blend of luxury and natural beauty. Spanning 25 square kilometers, it provides contrasting views of the sea, hills, cork forests, and green fairways. Residents enjoy access to world-class golf courses, polo fields, and a bustling marina. The community is known for its high property values, attracting affluent individuals from across Europe. The architectural styles vary from traditional Andalusian to modern designs, adding to its unique charm.

4. Jackson Hole, Wyoming

Nestled amidst the Teton Mountains, Jackson Hole serves as a retreat for America’s ultra-wealthy. The region is one of the wealthiest in the U.S., with the top 1% earning an average of $16 million. Renowned celebrities like Kanye West, the Kardashians, and Harrison Ford own property there. Real estate is scarce due to limited private land, making properties highly valuable and competitive. The luxurious allure, Western nostalgia, and breathtaking landscape make Jackson Hole a coveted enclave for affluent Americans.

5. Hilo, Hawaii

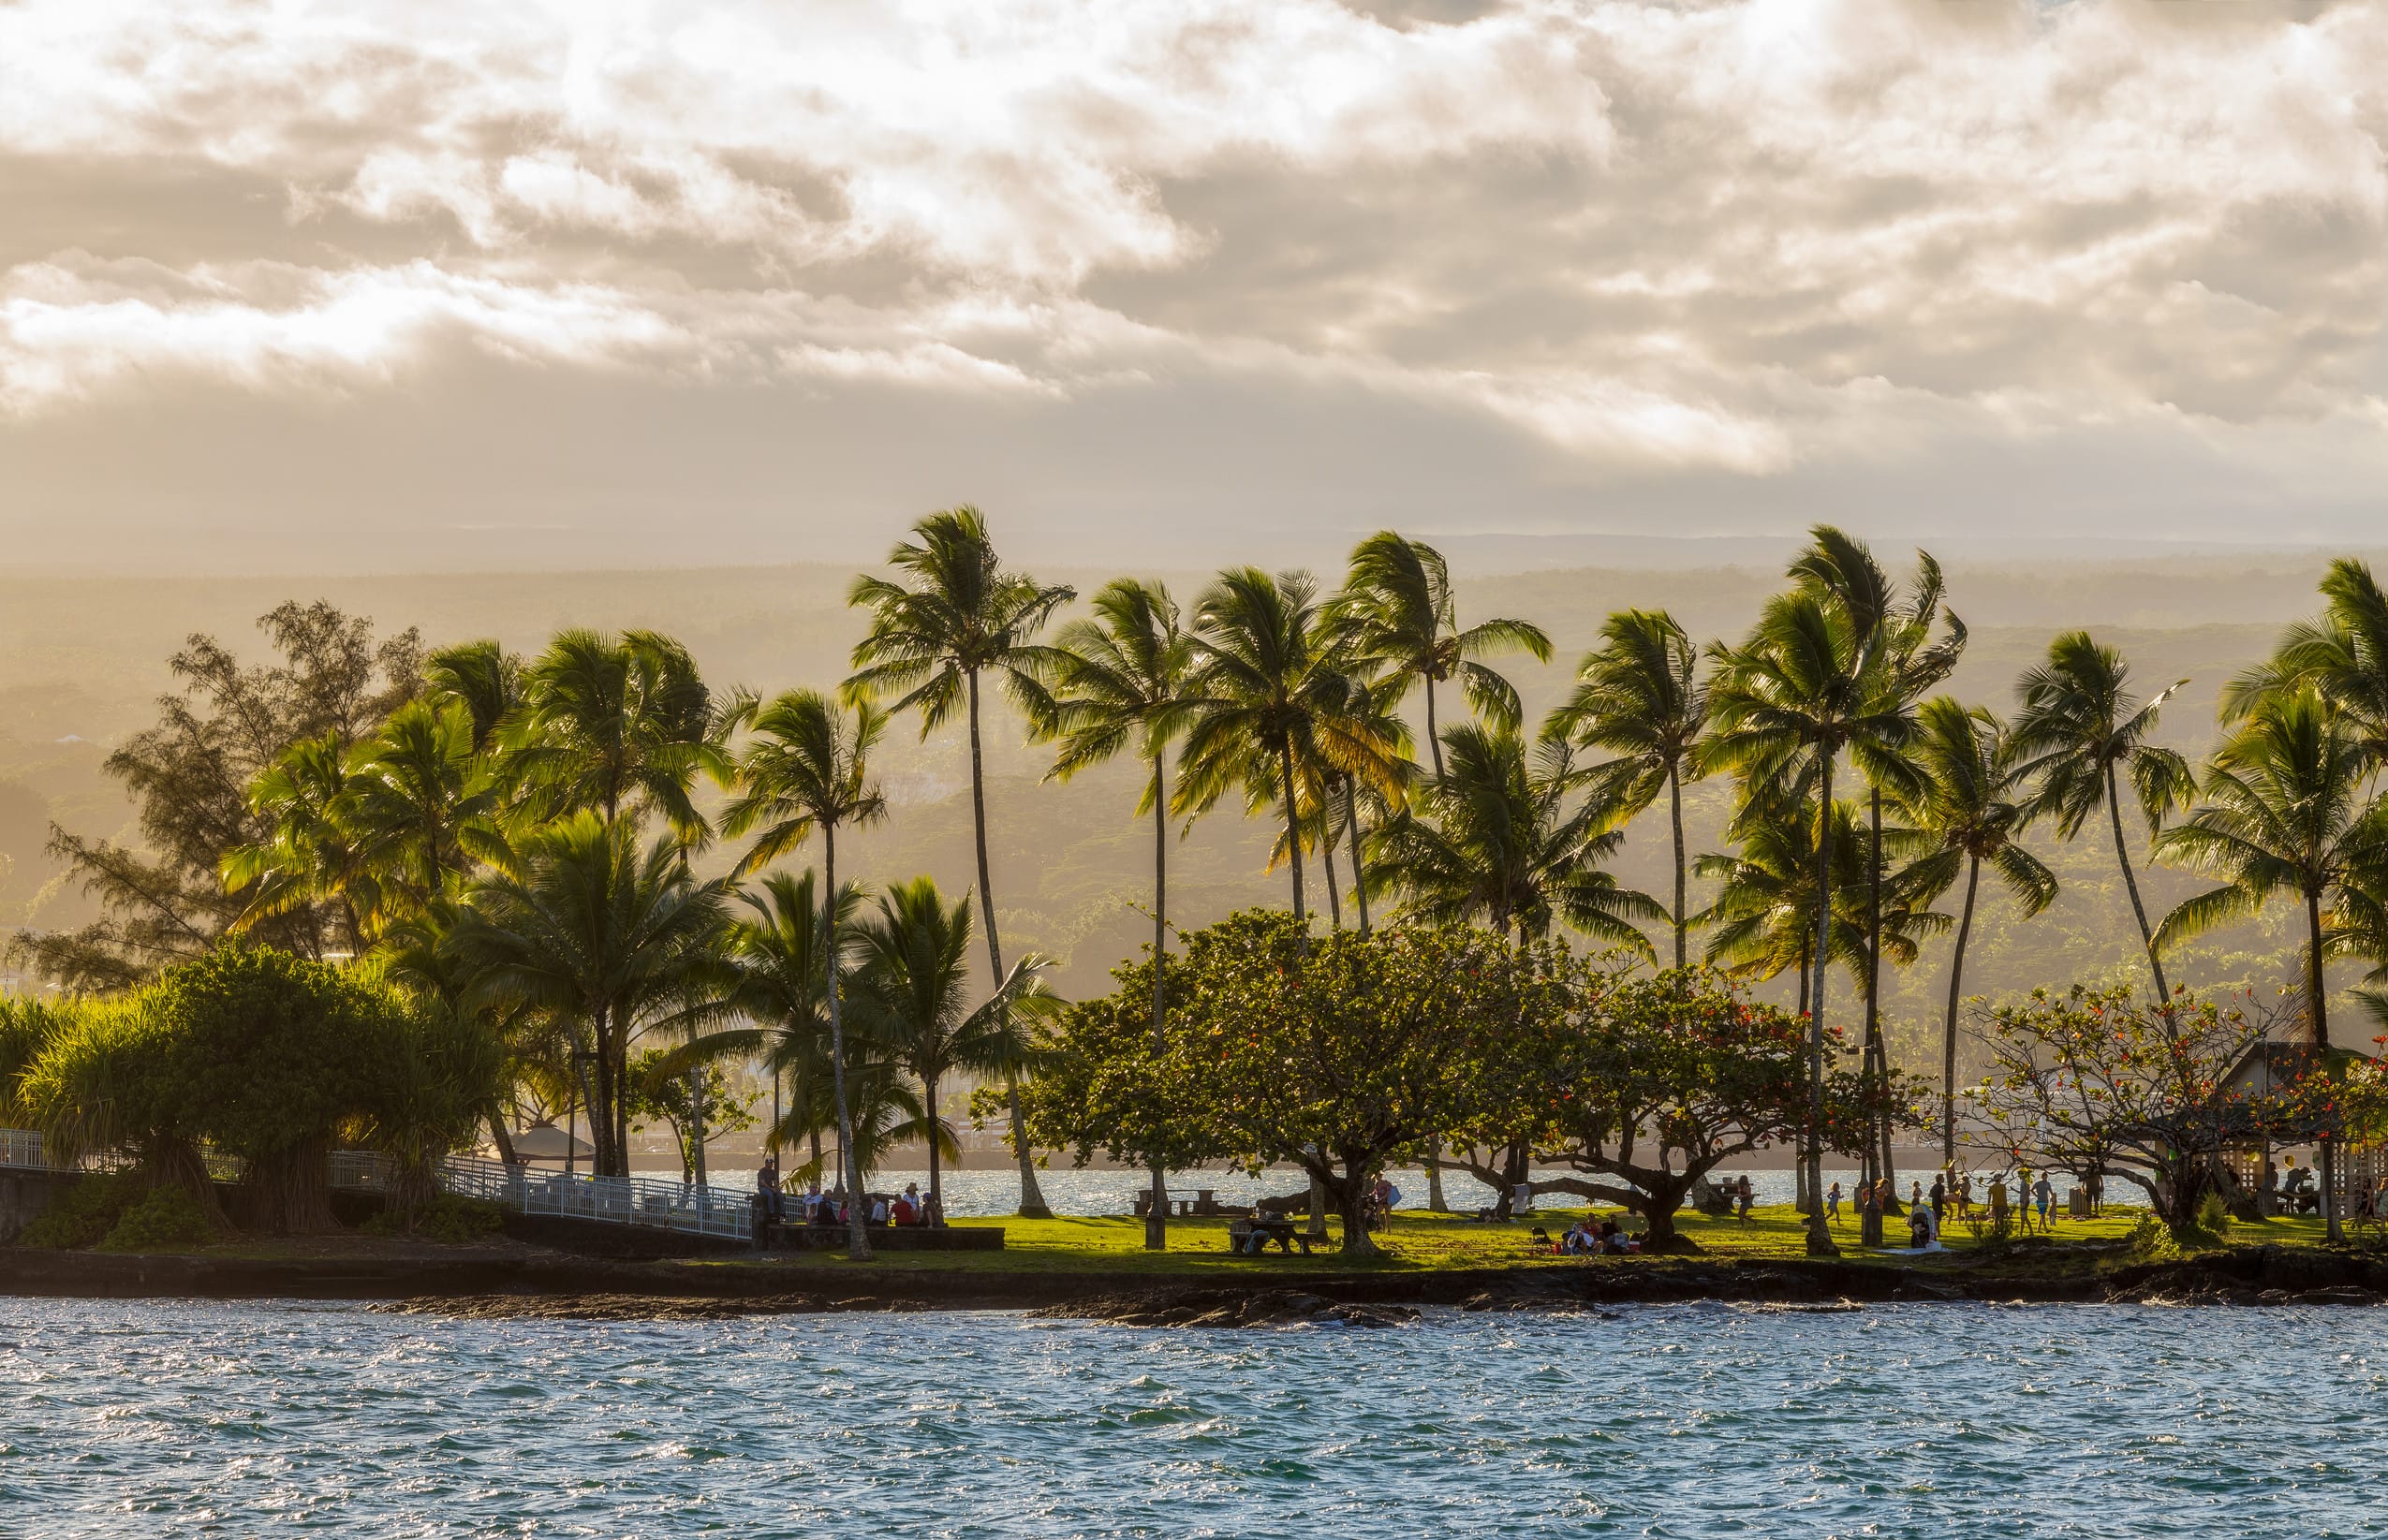
Beautiful Liliuokalani Park and Gardens in Hilo, Hawaii, on a rainy sunset
Image Source: 123rf.com

Located on the lush eastern side of the Big Island, Hilo is celebrated for its tropical rainforests, waterfalls, and vibrant cultural scene. However, the cost of living is notably high, with expenses approximately 36.4% above the national average. The median home value in Hilo is around $339,800, reflecting its desirability and the premium placed on island living. Despite the costs, many are drawn to Hilo’s unique blend of natural beauty and rich Hawaiian heritage. ​

6. Aventura, Florida

Situated in Miami-Dade County, Aventura is known for its upscale amenities, including high-end shopping centers and luxury condominiums. The cost of living is significantly higher than the national average, making it one of the more expensive places to retire in the U.S. The city’s strategic location between Miami and Fort Lauderdale adds to its appeal, offering residents easy access to urban conveniences while maintaining a suburban feel. ​

7. Palm Beach Gardens, Florida

Palm Beach Gardens offers a blend of natural beauty and luxury living, with numerous golf courses, upscale shopping, and dining options. The area has a high cost of living, reflecting its status as a desirable retirement destination. Its proximity to the Atlantic Ocean provides residents with beautiful beaches and recreational opportunities, enhancing its appeal to retirees seeking an active lifestyle. ​

8. Boca Raton, Florida, USA

Boca Raton is famed for its Mediterranean Revival architecture, parks, and beaches. The city offers a high standard of living, which comes with a correspondingly high cost, making it a popular yet pricey retirement spot. Its cultural attractions, including museums and theaters, along with top-notch medical facilities, make it particularly appealing to retirees seeking both luxury and convenience. ​

9. Palm City, Florida, USA

Palm City provides a quiet, community-focused environment with easy access to waterways and golf courses. The cost of living is higher than average, reflecting its appeal to retirees seeking a serene yet upscale lifestyle. Its location along Florida’s Treasure Coast offers residents opportunities for boating and fishing, adding to its charm for those seeking a leisurely retirement. ​

10. Bonita Springs, Florida, USA

Known for its Gulf Coast beaches and parks, Bonita Springs offers a relaxed lifestyle with luxury amenities. The area has a higher cost of living, making it a more expensive retirement destination. Its vibrant arts scene, coupled with numerous dining and shopping options, provides a well-rounded environment for retirees seeking both relaxation and engagement. ​

11. Estero, Florida, USA

Estero is an appealing retirement destination for those who love both nature and luxury. Surrounded by beautiful preserves, the area offers retirees a mix of outdoor adventures and high-end living. With its proximity to Naples and Fort Myers, Estero provides access to excellent healthcare, shopping, and entertainment. The cost of living is notably higher than the national average, with property prices steadily increasing due to the area’s desirability. For retirees who want a peaceful, upscale environment without sacrificing modern conveniences, Estero is a prime choice.

12. Naples, Florida, USA

Naples is frequently ranked as one of the best places to retire in the United States, and for good reason. Located on the Gulf Coast, it boasts stunning white-sand beaches, a warm climate, and world-class golf courses. The city is also home to some of the finest dining and shopping in Florida, with a strong cultural scene that includes art galleries, theaters, and music venues. However, luxury comes at a price, with Naples being one of the most expensive retirement destinations in the country. The high cost of real estate and overall living expenses make it an exclusive location for retirees with a significant financial cushion.

Time to Enjoy Life

Retirement is a time to enjoy the lifestyle you’ve worked hard for, and these twelve destinations offer some of the most breathtaking and luxurious environments to settle down. However, beauty and comfort often come with a steep price tag, requiring careful financial planning before making the move. Whether you prefer the serene beaches of Hawaii, the rolling hills of Rancho Palos Verdes, or the cultural vibrancy of Boca Raton, these locations cater to retirees who want to enjoy their golden years in style.

Would you choose one of these luxury retirement destinations, or do you prefer an affordable yet comfortable location? Share your thoughts in the comments below.

Read More:

Need To Get Your Retirement In Order: Start By Reading These 5 Retirement Planning Books

What to Do After You Fire Your Financial Advisor in Retirement


Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.

Filed Under: Retirement Tagged With: Beautiful Places to Retire, Cost of Living in Retirement, Expensive Retirement Locations, High-Cost Living, Luxury Living, Luxury Retirement, Retirement Destinations, Retirement Lifestyle, retirement planning, Upscale Retirement Communities

Help Me Help You: What Your Financial Advisor Wishes You’d Admit About Your Money Habits

March 18, 2025 by Latrice Perez Leave a Comment

businessman and crying client discussing contract during meeting in office
Image Source: 123rf.com

Financial advisors spend their days helping people build wealth, reduce debt, and plan for the future. But no matter how much experience they have, many clients make the same mistakes over and over again. The truth is, money management is not just about numbers—it is about mindset, habits, and behaviors that either push you toward financial freedom or keep you stuck in the same cycle.

There are certain financial realities that many people refuse to accept, and financial advisors see them all the time. If you want to improve your financial situation, the first step is being honest about your own habits. Here are the things your financial advisor wishes you would admit to yourself.

You Are Probably Spending More Than You Think

Most people believe they have a good handle on their spending, but when they actually track every dollar, they are often shocked at how much they are wasting. Small purchases like daily coffee, impulse buys, and last-minute takeout meals add up quickly. Even larger expenses, like car payments or streaming services, often go overlooked because they feel necessary.

Financial advisors know that many clients struggle to acknowledge how much they are really spending. The best way to fix this problem is to track expenses for at least a month. Seeing the numbers in black and white makes it easier to identify where money is slipping away and where adjustments need to be made.

A Budget Will Not Fix Bad Spending Habits

Many people think that simply having a budget will solve their financial issues. While budgeting is an essential tool, it does not work unless spending habits change. Financial advisors often see clients who set up a perfect budget but fail to stick to it because they continue spending on non-essentials.

A budget should not just exist on paper—it should reflect real-life spending. If impulse shopping or eating out is a weakness, simply writing down a lower number in that category will not change behavior. The real work comes in adjusting habits and making conscious spending decisions.

Making More Money Will Not Solve Everything

Many people believe that if they just earned more, all their financial problems would disappear. While an increase in income can help, it does not automatically fix bad money habits. Financial advisors often see clients who make six figures but still struggle with debt because they continue increasing their spending as their earnings grow.

Without good financial discipline, more income simply means more spending. The key to long-term financial success is learning how to manage what you have before focusing on earning more. If financial problems exist at a lower income level, they will likely continue at a higher one.

Debt Will Not Disappear on Its Own

Ignoring debt will not make it go away. Many people put off making extra payments on their loans and credit cards, assuming they will deal with it later. Financial advisors know that the longer debt lingers, the worse it gets due to interest and fees.

Even small extra payments can make a big difference over time. Waiting for the perfect moment to start paying off debt often means it never happens. A plan to tackle debt, even if it starts with small amounts, is better than avoiding it altogether.

Investing Is Not Just for the Rich

Business Man Working
Image Source: 123rf.com

Many people believe they need to be wealthy before they can start investing. This misconception keeps them from building wealth over time. Financial advisors know that the earlier someone starts investing, the easier it is to grow their money.

Even small contributions to retirement accounts or brokerage accounts can make a difference in the long run. Waiting until there is extra money to invest often means missing out on years of compound interest. Starting with what is affordable now, even if it is a small amount, is better than waiting for the perfect moment.

Emergency Funds Are Non-Negotiable

Too many people assume they can rely on credit cards or loans if they ever face a financial emergency. Financial advisors often see clients struggling because they never built up an emergency fund, leaving them vulnerable to unexpected expenses like medical bills, car repairs, or job loss.

Having at least three to six months’ worth of expenses saved can prevent financial disaster. Even starting with a small emergency fund is better than having nothing at all. Without a financial cushion, even minor setbacks can turn into long-term financial struggles.

Your Credit Score Matters More Than You Think

Some people dismiss their credit score as unimportant, but financial advisors know that a low score can cost thousands of dollars over a lifetime. Credit scores do matter. A poor credit score can lead to higher interest rates on loans, more expensive insurance premiums, and even difficulties renting an apartment or buying a home.

Building and maintaining a good credit score is not just about borrowing money—it affects many aspects of financial life. Paying bills on time, keeping credit utilization low, and avoiding unnecessary debt can all help maintain a strong credit profile.

Retirement Will Come Sooner Than You Expect

Many people delay saving for retirement because it feels far away. But financial advisors know that waiting too long makes it much harder to build enough savings. The earlier someone starts, the less they need to contribute each month to reach their goals.

Relying on social security or expecting to work forever is not a solid retirement plan. Even small contributions to a retirement account can grow significantly over time. The best time to start saving for retirement was yesterday—the second-best time is today.

You Must Be Honest About Your Money Habits

Financial advisors can offer the best strategies and tools, but none of it matters if people are not honest about their money habits. Acknowledging where mistakes are being made is the only way to fix them.

Taking control of finances means making better choices, being willing to change, and accepting responsibility for financial decisions. Small improvements over time lead to big results, but only for those willing to admit where they need to improve.

Have you ever had a financial habit you had to change? What made you realize it was time to do things differently? Share your thoughts in the comments below.

Read More:

How to Spot a Bad Financial Advisor—And Fire Them Before It’s Too Late

Is Your Financial Advisor Scamming You? 10 Tricks to Watch Out For

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.

Filed Under: Financial Advisor Tagged With: Budgeting Tips, building wealth, Credit Score Tips, Debt Management, financial advice, financial habits, investing for beginners, money management, Personal Finance, retirement planning

7 Cunning Ways Nursing Homes Can Drain Your Life Savings

March 6, 2025 by Latrice Perez Leave a Comment

Nursing Home
Image Source: 123rf.com

Nursing homes provide essential care for elderly individuals, but the costs can quickly deplete a lifetime of savings. While many expect to pay for basic care, few realize just how easily hidden fees, legal loopholes, and deceptive billing practices can drain their finances. Without careful planning, families can find themselves facing financial ruin. Here are seven cunning ways nursing homes can strip away your life savings and what you can do to protect yourself.

1. Excessive Private Pay Requirements Before Medicaid Eligibility

Many people assume that Medicaid will immediately cover nursing home costs, but facilities often require residents to exhaust their private funds before allowing Medicaid to step in. This can force families to deplete savings, sell assets, or even take out loans before government assistance kicks in.

Some nursing homes manipulate this system by delaying Medicaid applications or giving incorrect information about eligibility. They may also push residents into paying privately for as long as possible to maximize their profits. Understanding Medicaid eligibility rules and applying as early as possible can help protect your finances.

2. Sky-High Daily Fees for Basic Services

Nursing homes often charge daily rates that far exceed the actual cost of care. While families expect to pay for food, lodging, and medical services, they are often surprised by the inflated costs. Some facilities charge hundreds of dollars per day, even when a resident receives minimal care.

These costs quickly add up, wiping out life savings within months. The best way to combat this is by thoroughly reviewing the nursing home’s fee structure before admission. Comparing multiple facilities and negotiating rates can prevent overpaying.

3. Extra Fees for “Additional” Services

Basic care may be covered under the standard daily rate, but nursing homes frequently add fees for extra services. These hidden costs can include assistance with dressing, grooming, transportation, and even routine medical monitoring.

Some facilities itemize services that should be included in standard care, creating an illusion of affordability while quietly increasing monthly expenses. Families should request a detailed breakdown of all potential fees and clarify what is included in the base rate before signing any contracts.

4. Forcing Residents to Sign Over Assets

Sign Over Assets
Image Source: 123rf.com

Many nursing homes use legal contracts that require residents to sign over assets as a condition of admission. This can include bank accounts, real estate, and life insurance policies. Families may not realize the full extent of what they are agreeing to, especially if the paperwork is complex.

Some contracts also contain clauses that make it difficult to move a loved one to another facility without financial penalties. Consulting an elder law attorney before signing any documents can prevent families from unknowingly giving up their financial security.

5. Medicaid Estate Recovery After Death

Even if Medicaid covers nursing home costs, the government may seek repayment through estate recovery after the resident’s death. This means that assets such as homes, savings, and other valuables could be seized to reimburse Medicaid expenses.

Many families are caught off guard when they realize that a home they intended to pass down to their children is now subject to government claims. Proper estate planning, such as irrevocable trusts or asset transfers done years in advance, can help shield assets from Medicaid recovery.

6. Charging for Unused or Unneeded Services

Nursing homes may include charges for services that residents don’t need or use. This can range from therapies that were never requested to overpriced prescription drugs that could be obtained at a lower cost elsewhere.

In some cases, residents are charged for meals even when they are unable to eat or for activities they are physically incapable of participating in. Families should carefully review monthly billing statements and question any suspicious charges. Requesting an itemized bill and disputing unnecessary fees can help prevent overpayments.

7. Pushing Expensive Private Rooms and Unnecessary Upgrades

Many nursing homes prioritize profit over patient care and use sales tactics to push residents into more expensive accommodations. They may claim that only private rooms are available or pressure families into purchasing costly add-ons like special dietary plans or additional recreational activities.

In reality, many of these upgrades are unnecessary and serve only to increase revenue for the facility. Families should insist on seeing all available room options and resist pressure to accept high-priced extras that don’t genuinely benefit the resident.

Families Must Be Proactive

The costs of long-term care can quickly drain life savings, especially when nursing homes use deceptive billing practices, hidden fees, and asset seizures to maximize profits. Families must be proactive in reviewing contracts, questioning charges, and planning ahead for Medicaid eligibility. Consulting with an elder law attorney and understanding the fine print before committing to a facility can help protect hard-earned assets from being wiped out.

Have you or a loved one faced unexpected financial burdens due to nursing home costs? Were you able to resolve the financial burdens? Share your experiences in the comments.

Read More:

7 Types of Nursing Homes You Should Never Leave Your Parents In

3 Factors That Change How Much You Pay for Long Term Care Insurance

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.

As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy, the nuances of life, and the importance of inner peace.

Filed Under: Personal Finance Tagged With: assisted living, elder care, estate recovery, financial protection, healthcare fraud, Hidden Fees, Long-term care, Medicaid planning, nursing home costs, retirement planning

  • « Previous Page
  • 1
  • …
  • 53
  • 54
  • 55
  • 56
  • 57
  • 58
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • 10 Tactics for Building an Emergency Fund from Scratch by Vanessa Bermudez
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald

Copyright © 2026 · News Pro Theme on Genesis Framework