• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Personal Finance

Understanding Your Credit Report: What It Is, Factors, And How To Improve Your Score

February 12, 2024 by Susan Paige Leave a Comment

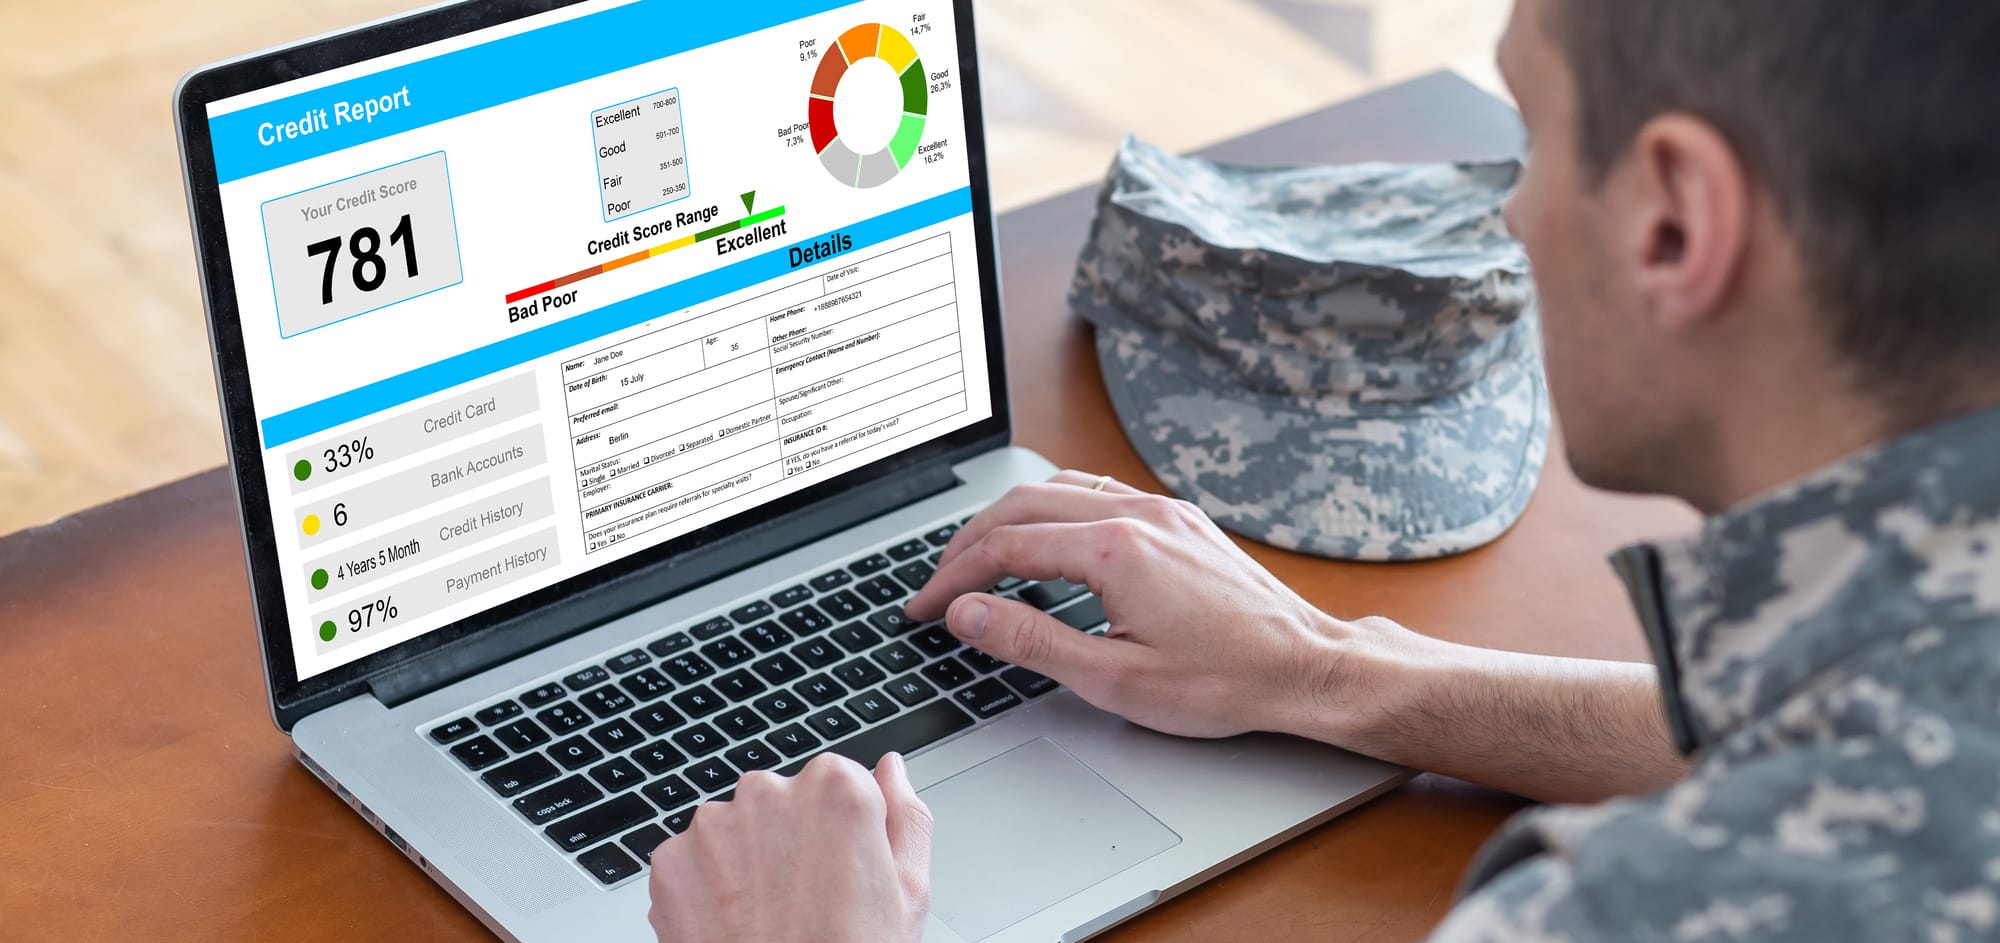
report credit score banking borrowing application risk form document loan business market policy deployment data check workplace concept – stock image. High quality photo

Your credit report is one of the most important documents that lenders, creditors, landlords, utility companies, and even potential employers evaluate to determine your creditworthiness and reliability. However, many people lack a comprehensive understanding of what a credit report contains and how it significantly influences their financial choices and opportunities.

The good news is that you have more control than you realize over this influential report and your all-important credit score. By gaining insight into the contents of your credit report, regularly monitoring it, understanding the key factors that affect it, and adopting good credit practices over time, you can enhance your score and credit standing. Continue reading to discover more.

What Is A Credit Report?

Before exploring online credit solutions from service providers like softpullsolutions.com, it’s crucial to understand what a credit report is. Think of it as your financial report card, showing how well you’ve handled money and debts in the past, so banks and other companies can decide if they want to do business with you.

Prepared by credit reporting agencies, it documents various aspects of your financial behavior, showcasing your reliability and risk as a borrower. This detailed record includes information ranging from credit accounts and loans to payment histories and more, essentially outlining your financial standing and practices.

Components Of A Credit Report

Here’s a deeper dive into the sections of a credit report:

  • Personal Information: This segment captures essential identifiers, including your name, Social Security number, addresses, and sometimes your employment history. It serves to verify your identity for anyone reviewing the report.
  • Credit Accounts: Detailed information on current and historical credit accounts, such as mortgages, credit cards, and auto loans, is listed here. This includes the type of account, the date it was opened, the credit limit or loan amount, the account balance, and your payment history, including any late payments.
  • Credit Inquiries: Your report distinguishes between ‘soft’ inquiries, which don’t affect your credit score and occur when your credit is checked as part of a background check, and ‘hard’ inquiries, which can impact your score and happen when you apply for new credit. Only hard inquiries appear on your report for two years.
  • Public Records And Collections: This part of the report covers more serious financial issues, such as bankruptcies, foreclosures, legal judgments, and accounts turned over to collection agencies. These entries can drastically reduce your credit score and indicate major financial missteps.
Importance Of Regular Monitoring

Frequently reviewing your credit report is crucial for several reasons. First, it allows you to verify the accuracy of the information presented. Mistakes, unfortunately, are not uncommon and can negatively impact your credit score. By monitoring your report, you can identify and dispute any inaccuracies with the credit bureaus.

Second, checking your report can alert you to potential identity theft. Unfamiliar accounts or credit inquiries could indicate that someone else uses your personal information to open accounts in your name. Early detection is critical to minimizing the damage from identity theft.

Lastly, understanding the contents of your credit report can help you make informed decisions about managing your credit. By recognizing the factors that contribute to your credit score, you can take steps to improve it, like paying down balances or correcting inaccurate information.

In essence, your credit report is a vital tool in your financial toolkit. By familiarizing yourself with its contents and how it influences your credit score, you’re better equipped to navigate the complexities of credit and work towards financial stability.


Key Factors Influencing Your Credit Score

Your credit score is a three-digit number that lenders use to decide how risky it is to lend you money. It influences the interest rates you’ll get and whether you’re approved for loans or credit cards. Here are the key factors that affect your credit score, offering you the clarity needed to enhance your financial standing:

  • Payment History

How timely you pay your bills is the most important part of your credit score. It’s like a record of how often you pay on time, showing if you’re a reliable borrower. This factor examines whether you’ve paid past credit accounts on time. It encompasses payments on credit cards, mortgages, loans, and any other debt reported to credit bureaus.

A history of punctual payments indicates reliability, boosting your score, while late payments, defaults, and bankruptcies can significantly harm it. The key takeaway? Maintaining a flawless payment record is paramount.

  • Credit Utilization Ratio

Credit utilization ratio — the percentage of your available credit that you’re using — is a vital score influencer. High utilization can signal potential over-reliance on credit, suggesting financial instability.

Conversely, low utilization demonstrates responsible credit management. Experts recommend keeping your utilization below 30% of your total credit limit across all accounts to foster a positive impact on your credit score.

  • Length Of Credit History

How long you’ve had credit goes into your score, too. It’s like a track record showing how long you’ve been using credit responsibly. It includes how long your accounts have been open and the age of your oldest account.

A lengthy credit history can be beneficial, as it offers a more extensive track record of your financial habits. However, even those with shorter histories can score well if they manage their credit wisely across different accounts.

  • Types Of Credit In Use

Using different kinds of credit wisely, like credit cards, car loans, and home loans, shows you can handle money responsibly. This mix can help boost your score. This variety offers lenders the ability to take on different credit responsibilities. However, it’s crucial to avoid opening new credit accounts without a solid financial reason.

Unnecessary credit applications can lead to hard inquiries that might temporarily lower your score. More importantly, accumulating too much new credit in a short time can be perceived as risky by lenders, potentially having a negative impact on your financial health. Aim for a balanced credit mix that reflects responsible usage and management without overextending yourself.

  • New Credit

Opening several new credit accounts quickly can be perceived as risky behavior, potentially lowering your score. Each time you apply for credit, a hard inquiry is made, which can slightly decrease your score. While these dips are usually temporary, multiple inquiries can accumulate, leading to a more substantial impact. The strategy here is to apply for new credit sparingly and only as needed to avoid unintended consequences on your score.

By focusing on these factors and actively optimizing each, you’re not just improving a number—you’re building a foundation for financial stability and access to better opportunities. Whether you’re aiming for a loan with favorable terms or seeking to secure lower interest rates, understanding and positively influencing these key components can lead you towards achieving your financial goals.


Strategies To Boost Your Credit Score

Improving your credit score isn’t an overnight process, but with patience and discipline, you can make significant strides. Here are actionable steps to enhance your score, leading to better loan terms and more financial opportunities:

  • Review Your Credit Report Regularly

Errors can creep into your report and drag down your score. Regular checks allow you to spot and dispute inaccuracies promptly, ensuring your report accurately reflects your financial behavior. Each year, you have the right to obtain a complimentary free credit report from each of the three primary credit reporting agencies. Utilize this chance to ensure your data is current and correct.

  • Strategically Manage Old Accounts

While keeping old credit accounts open can boost your score by extending your credit history and lowering credit utilization, evaluate each for potential downsides like annual fees or security risks. If the benefits outweigh the risks and there are no high fees, keep them open but use them sparingly to avoid unnecessary costs and maintain account activity. Close accounts judiciously to minimize negative impacts on your credit score.

  • Pay Bills On Time

Consistency in bill payments can’t be overstressed. Late payments can significantly hurt your score, so make punctuality a priority. Setting up reminders or automatic payments can help you stay on track, ensuring you never miss a due date. This simple habit can have a profound impact on your credit score over time.

  • Reduce Debt

Lowering your credit utilization ratio is a direct way to boost your score. Aim to pay down balances, starting with high-interest accounts. Lower debt levels signal control and responsibility to lenders. Not only does reducing debt improve your credit score, but it also lessens financial stress by lowering interest payments.

  • Limit New Credit Applications

Each application can cause a small, temporary dip in your score. Apply only for the credit you need, and do so sparingly to avoid unnecessary hits to your credit. This strategy prevents those dips from adding up and reflects a thoughtful approach to managing new credit, demonstrating to lenders that you are a low-risk borrower.

Adopting these strategies can significantly influence your credit score, paving the way for financial stability and success. As you implement these tips, remember that consistency is key. Over time, these practices will improve your credit score and enhance your overall financial well-being.

Conclusion

Your credit report and score play pivotal roles in your financial journey. By understanding what influences your credit, and actively working to improve it, you set the stage for a healthier financial future. Remember, building and sustaining good credit is a long-term endeavor. With persistence, your efforts will lead to significant benefits.
Filed Under: Personal Finance

How to Craft a Spending Plan That Works For You

February 12, 2024 by Susan Paige Leave a Comment

Personal budgets seem restrictive or intimidating. But having a plan for your money simply means deciding in advance how to allocate your income. Budgeting gives you control over your finances so you can save for goals, reduce debt, and prepare for both expected and unexpected expenses. Here are the key steps to create a realistic spending plan tailored to your needs and priorities:

Take Stock of Your Current Finances

Before making a budget, take time to understand your full financial picture. Tally up all sources of income you receive each month after taxes and deductions. Be sure to include irregular income like bonuses or freelance work.

Next, list your fixed and variable expenses. Fixed costs stay the same every month like rent, car payments, or insurance premiums. Variable expenses fluctuate, like utility bills, groceries, dining out, or entertainment. Analyze 3-6 months of bank and credit card statements to determine your average spending in each category.

Some helpful calculators:

  • Monthly income total
  • Average monthly expenses breakdown
  • Percentage of income spent per category

Unsure where to start analyzing past expenses or estimating averages? Check out guides from Joy Wallet with budgeting advice tailored to all stages of personal financing.

Set SMART Financial Goals

With your current finances in mind, define specific financial goals to work towards. Setting Specific, Measurable, Attainable, Relevant, and Time-based (SMART) goals gives your budget focus and purpose.

Shorter-term goals might include:

  • Paying off a credit card balance
  • Saving an emergency fund
  • Funding a vacation

Longer horizons could incorporate:

  • Saving for a down payment
  • Paying off student loan debt
  • Retirement savings

Be sure to prioritize goals by urgency. Factor in timelines and minimum monthly savings required to achieve each one.

Calculate Essential Expenses

Start your spending plan framework with essential needs that allow you to live safely and comfortably. Budget enough to cover:

  • Housing: rent/mortgage, property taxes, homeowners insurance, etc.
  • Utilities: electricity, water, gas, phone, internet, etc.
  • Food: groceries and essential household items
  • Insurance: health, life, car, disability coverage
  • Transportation: gas, standard car maintenance, public transport
  • Minimum debt payments

As a rule of thumb, limit essential expenses to 50-60% of your net monthly income. If these unchangeable costs exceed that threshold, look at ways to reduce any flexible necessities.

Define Your Personal Lifestyle Costs

Next, tally up all the extras that fund the lifestyle you currently enjoy. These include:

  • Dining out
  • Entertainment, recreation events
  • Hobbies
  • Memberships, subscriptions
  • Personal care appointments
  • Shopping, personal items
  • Travel, vacations
  • Donations, gifts

Be ruthlessly honest about where you allocate discretionary spending each month. If you regularly carry credit card debt, these extras likely make up too large a percentage of income. Define which ones add the most value and happiness to craft spending aligned with priorities.

Connect Expenses to Income

With essentials and lifestyle costs defined, compare expenses to after-tax monthly income. Use an online budget template or spreadsheet to calculate if you operate at a surplus or deficit each month.

If expenses exceed income, you’ll need to make adjustments by lowering spending or earning more. Don’t resort to incurring debt except for true necessities.

With a surplus budget, allocate extra funds to accelerate debt repayments or savings goals through additional principal payments, contributions, or lump sum deposits. Automate transfers whenever possible to remove the temptation of spending surplus cash.
Build Your Personalized Budget

Now, transform expense categories into monthly spending targets aligned with your income and resources. Be sure to incorporate:

  • Fixed vs. variable costs: Set limits for fluctuating expenses based on averages and known annual costs. Buffer at least 10% more for unpredictables.
  • Debt repayments: Pay at least the minimums; increase allotments if aiming to pay off debts quickly.
  • Savings contributions: Pay yourself first via automated deposits toward short and long-term goals.
  • Discretionary spending: Indulgences stay within pre-defined limits aligned with resources and goals.
  • Periodic annual expenses: Divide predictable annual costs like Amazon Prime, vehicle registration fees, or holiday gifts across all 12 months.

Build in a $100-500 monthly cushion for unanticipated expenses or income fluctuations. Small cuts across categories often yield this extra breathing room without huge lifestyle sacrifices.

Make Your Budget Ultra-Customizable

Create a budget organization that matches your unique situation and priorities. For example:

  • If eliminating credit card debt ASAP is most important, have separate tracked categories for each card, ordered by interest rate.
  • If saving for a house, break down homebuying goals with sub-targets by down payment, closing costs, moving fees, and new furniture/appliances.
  • If supporting elderly parents, have a distinct category for caregiving-related costs that might spike and fluctuate month-to-month.

Name all categories in a way that keeps the budget aligned with big-picture objectives. It builds ongoing engagement and accountability.

Take Budgeting As Your Ally, Not Enemy

Budgeting is not a restrictive barrier but an intentional safeguard toward dreams and possibilities. When aligned with personal priorities and flexible enough to allow reasonable pleasures, spending plans grant freedom from haphazard money chaos.

Give yourself permission to begin where you are financially, then build steadily toward greater control. Perfection or precision matters far less than mindfully directing dollars in service of flourishing. Small progress compounds over the years into amazing feats that seem impossible today. Why not start crafting your unique money path one manageable month at a time?


Filed Under: Personal Finance

10 Financial Advisors’ Tips That Don’t Hold Up in Today’s Economy

February 12, 2024 by Tamila McDonald Leave a Comment

In an ever-evolving financial landscape, the wisdom that once guided investors and savers alike may no longer hold the same weight. As we navigate through unprecedented economic conditions marked by rapid technological advancements, shifting market dynamics, and unexpected global events, some traditional advice from financial advisors seems increasingly out of touch. Here, we explore ten financial advisor tips that might not stand up to the rigors of today’s economy.

1. Sticking Strictly to the Traditional 60/40 Investment Portfolio

The age-old investment strategy of allocating 60% of one’s portfolio to stocks and 40% to bonds is being challenged by today’s low-interest-rate environment. While this diversification tactic was once considered a safe bet for steady growth and income, the diminishing returns on bonds and increased market volatility have called its effectiveness into question. Investors are now exploring alternative assets, such as real estate, commodities, and even cryptocurrencies, to find the right balance between risk and reward.

2. Homeownership as the Ultimate Financial Goal

For decades, owning a home was synonymous with financial success and stability. However, the modern economy, characterized by job mobility, skyrocketing real estate prices, and the gig economy, has made homeownership an unattainable dream for many. The flexibility of renting, coupled with the high costs associated with property maintenance and taxes, makes it an increasingly viable option, challenging the notion that buying a home is always the best investment.

3. The Assurance of a College Degree

cgsgc

While higher education has traditionally been touted as a surefire path to a lucrative career, the rising cost of college tuition and the burden of student loans are prompting a reevaluation. With the emergence of alternative education paths, such as online courses, boot camps, and apprenticeships, many are questioning the return on investment of a traditional four-year degree, especially in fields where practical skills often outweigh academic credentials.

4. Saving 10% of Your Income for Retirement

The conventional wisdom of setting aside 10% of one’s income for retirement may not suffice in today’s economic climate. Longer life expectancies, increasing healthcare costs, and the uncertain future of Social Security demand a more aggressive savings strategy. Financial experts now recommend saving at least 15% to 20% of your income to ensure a comfortable retirement, taking into account the potential for inflation and unforeseen expenses.

5. Counting on Social Security

Relying on Social Security as a significant component of one’s retirement plan is becoming increasingly risky. With the program facing potential funding shortfalls, future benefits may be reduced, leaving those who haven’t saved enough on their own in a precarious position. It’s more important than ever to diversify retirement savings across various vehicles, such as 401(k)s, IRAs, and personal savings, to build a more secure financial future.

6. The Infallibility of the Emergency Fund Rule of Thumb

The standard advice of having three to six months’ worth of living expenses saved in an emergency fund might not be adequate for today’s economic uncertainties. Given the volatility of the job market and the potential for unexpected costs, a more robust safety net of up to twelve months’ worth of expenses is advisable for those in less stable employment situations or with higher financial obligations.

7. Avoiding All Debt

While excessive debt is undoubtedly harmful, the blanket advice to avoid all debt doesn’t take into account the nuanced role it can play in financial health. Strategic borrowing, such as low-interest loans for education, a home, or to start a business, can be an investment in one’s future. It’s the high-interest, non-productive debt from credit cards and consumer loans that should be handled with caution.

8. The Necessity of a Large Down Payment on a Home

The traditional advice to make a 20% down payment on a home to avoid private mortgage insurance (PMI) and secure better loan terms is not always feasible or advisable in today’s market. With home prices soaring, saving a 20% down payment can be prohibitive, delaying homeownership for many. Financing options that allow for smaller down payments can open the door to homeownership sooner, allowing buyers to start building equity and benefit from potential property appreciation.

9. Keeping a Fixed Asset Allocation

The idea of setting and forgetting an asset allocation does not hold up in the face of rapid economic changes and personal life transitions. Regular rebalancing and adjusting one’s investment strategy in response to market fluctuations and personal circumstances, such as age and risk tolerance, are crucial for optimizing investment returns and managing risk.

10. Delaying Investing Until You Have Significant Savings

Waiting to invest until you have a substantial amount of money saved is a missed opportunity, especially in today’s digital age where investment platforms allow you to start with minimal amounts. The power of compounding interest means that even seemingly tiny but regular investments made early can grow substantially over time, making it essential to begin investing as early as possible, regardless of the amount.

Ultimately

Ultimately, while traditional financial advice has its roots in historical success, the rapid changes in today’s economy necessitate a more flexible, informed approach to personal finance. By questioning outdated wisdom and adapting to current realities, individuals can navigate the complexities of modern financial planning with greater confidence and success.

Can you think of any other financial advisors’ tips that don’t hold up in today’s economy? Do you disagree with an item on this list and want to tell others why? Share your thoughts in the comments below.

Read More:

  • 10 ‘Bargain’ Online Shopping Sites That Could Drain Your Wallet
  • From Wealth to Want: 8 Luxury Spending Habits That Could Lead to Financial Ruin
Tamila McDonald
Tamila McDonald

Tamila McDonald is a U.S. Army veteran with 20 years of service, including five years as a military financial advisor. After retiring from the Army, she spent eight years as an AFCPE-certified personal financial advisor for wounded warriors and their families. Now she writes about personal finance and benefits programs for numerous financial websites.

Filed Under: Personal Finance Tagged With: 10 Financial Advisors' Tips That Don't Hold Up in Today's Economy, Sticking Strictly to the Traditional 60/40 Investment Portfolio

FinTech and Sustainable Finance: A Market Research Exploration

February 12, 2024 by Susan Paige Leave a Comment

In recent years, the convergence of financial technology (FinTech) and sustainable finance has emerged as a powerful and disruptive force in the financial sector. As worries about environmental, social, and governance (ESG) issues become more prominent, FinTech is playing a critical role in redefining how organisations approach sustainability. 

Green Financing Platforms for Businesses

B2B FinTech is at the forefront of facilitating green financing for businesses committed to sustainable practices. Market research reveals the emergence of platforms that connect businesses with environmentally conscious investors and lenders. These platforms streamline the process of securing financing for green initiatives, such as renewable energy projects or sustainable supply chain enhancements, fostering a more eco-friendly corporate landscape.

Blockchain for Transparent and Ethical Supply Chains

Supply chain transparency is a critical component of sustainable finance, and B2B FinTech is leveraging blockchain technology to revolutionise it. Businesses are increasingly adopting blockchain to trace the origins of their products, ensuring ethical sourcing and production. This transparency not only meets consumer demands for responsible practices but also aligns with the sustainable finance goals of many businesses.

B2B FinTech Partnerships for Sustainable Procurement

Collaborations between B2B FinTech firms and sustainable procurement platforms are becoming instrumental in promoting responsible business practices. B2B market research in FinTech can help businesses that are seeking FinTech solutions that integrate seamlessly with sustainable procurement processes, providing a holistic approach to responsible sourcing and financial management.

Challenges and Opportunities in B2B FinTech for Sustainable Finance

While the marriage of B2B FinTech and sustainable finance presents significant opportunities, it also comes with its set of challenges. There are key areas that businesses and FinTech providers need to address for sustained growth and impact.

1. Integration Challenges in Legacy Systems

One prominent challenge highlighted by market research is the integration of sustainable finance solutions into existing legacy systems. Many businesses operate on traditional financial platforms that may not readily accommodate the advanced features of B2B FinTech for sustainability. Addressing these integration challenges will be crucial for widespread adoption.

2. Data Security and Privacy Concerns

As B2B FinTech relies heavily on data analytics, ensuring the security and privacy of sensitive business information is paramount. businesses are cautious about the ethical use of data in sustainable finance initiatives. B2B FinTech providers must prioritise robust data security measures to build trust among their corporate clientele.

3. Regulatory Compliance

Achieving compliance with evolving regulations while maintaining the agility needed for innovation requires a delicate balance. Businesses and FinTech providers should collaborate closely to stay abreast of regulatory changes and ensure adherence.

The Road Ahead for B2B FinTech and Sustainable Finance

B2B FinTech has the potential to drive innovation in the creation of sustainable financial products tailored to the unique needs of businesses. Market research anticipates the development of specialised financial instruments that align with ESG criteria, providing businesses with a diverse array of sustainable financing options.

The utilisation of smart contracts on blockchain platforms holds promise for ensuring ESG compliance in B2B transactions. Market research suggests that the automation and transparency afforded by smart contracts can streamline processes related to sustainable finance, reducing the risk of non-compliance and enhancing the overall sustainability of business operations.

B2B FinTech can revolutionise working capital management by incorporating sustainable finance principles. Market research indicates that businesses are seeking solutions that optimise working capital while aligning with sustainability goals. B2B FinTech platforms can offer tools that provide insights into the environmental and social impact of working capital decisions.

Conclusion

In conclusion, the synergy between B2B FinTech and sustainable finance represents a transformative force in the corporate world. Market research plays a crucial role in understanding the dynamics of this evolving landscape, providing insights that guide businesses and FinTech providers toward effective strategies for sustainable financial growth. 

As businesses increasingly prioritise sustainability in their operations, B2B FinTech is poised to be a key enabler, driving positive change and fostering a more socially and environmentally conscious business ecosystem.

Filed Under: Personal Finance

Top Reasons You Don’t Need a Fortune to Start Investing

February 8, 2024 by Susan Paige Leave a Comment

One of the main excuses that people use for not investing (or postponing their investments) is the idea that they somehow just don’t have enough money. 

Sure, we’re not suggesting that you skimp off your utility bill or your pension fund in order to start investing, but the idea that those $100 extras that you managed to save somehow aren’t enough is just ridiculous.

In this post, we’ll try to prove to you that the lack of substantial capital isn’t really a reason why you’re not investing. This is just your false assumption, one that’s hurting your financial goals in the long run.

So, here are some top reasons why you don’t really need a fortune to start investing and why you need to do this as soon as possible.

Explore the concept of micro-investing

There are some assets, like stocks, bonds, ETFs, and mutual funds, which allow you to invest small amounts regularly with little to no commission fees. 

In other words, you don’t actually have to buy a whole coin or a full share. You can buy fractions of stocks, which is great for people who are interested in buying but have limited means to do so. 

This doesn’t restrict you in any major way. You can still diversify your investments (by micro-investing into multiple venues).

Even passive income sources can be inexpensive. Sure, you don’t have enough money to buy a rental apartment, but what about a stock that pays dividends? What about intellectual property that will yield royalties? 

It’s like with your retirement fund: the sooner you start, the sooner you retire, even if you invest a minuscule amount in your 20s. The same goes for investing and your financial goals. 

ICOs, presales, and new coins

At one point, BTC was $1 or $12 or $30, and if you bought it, then you could have made tens of thousands after 2017. Will this process repeat itself? Almost certainly, but not with BTC. 

Now, we’re not suggesting that BTC will never rise again. All that we’re implying is that, from this point on, BTC will not grow by thousands of percent. Even if you buy at $20k and sell at $60k, you’ve tripled your money. However, you’re not buying at $12 and selling at $21k. 

The only way to do so is to discover a promising new coin and adopt it early (before its price explodes). Some of the cheapest cryptos to buy have the potential to provide a massive return to those who adopt them early on.

Another thing to watch out for is ICOs and presales. These are the absolute earliest instances during which you’ll be allowed to buy crypto. This is when they’ll be sold in massive quantities and at a bargain price. According to Techopedia, investing $100 in Bitcoin today would yield just 0.003 of 1 BTC. The same $100 investment in the Bitcoin Minetrix presale would yield over 7575 tokens. Ultimately, there is little motivation for owning a tiny fraction of one crypto token. This is why cheap cryptocurrencies remain a popular alternative for casual investors.

Ultimately, buying crypto in 2024 is as easy as it gets. The exchanges are simple and user-friendly; most of the time, all you need is a smartphone and access to the internet. Also, unlike before, there are tons of guides and tutorials out there. 

Set up automatic investing

As we’ve already explained, the main problem with investing is a psychological barrier that you have to overcome. Sure, you’ve managed to save just $50 this month, so it doesn’t make sense to invest it. After all, what kind of difference will these $50 make? Sure, you can’t get yourself anything meaningful for this money, but you’ll invest more next month when you make more, right?

It’s like going to the gym. Skipping one day is not a big deal, but the real problem is that you’re making a dangerous precedent that you won’t be able to overcome as easily as you think. A day will turn into a month until you quit completely. In the same way, your one missed payment will turn into a few, which will make you develop delusions that, no matter how much you invest, it never makes a difference.

By setting up automatic investing, you’ll completely override this part. This way, the money will be automatically deducted from your account and invested into the asset of your choice. You can even put robo-advisors on the task and eliminate the need to pick your investments autonomously. 

In other words, in 2024, all you need to do is make a choice to invest. Everything else can be automated so that it feels less burdensome (even though the financial burden remains the same).

Gatekeeping is no longer as significant as before

In the past, in order to get access to all the information you needed, you actually had to know someone with a lot of experience and hope that they’ll teach you. It was either that or dedicating a portion of your life to working as a broker (or a broker’s assistant) in order to get the knowledge you need. You could also start with a lot of money and test out various strategies until you figure out what worked.

Today, there are so many learning materials available (most of which are not even behind a paywall) for you to explore. This means that knowledge is no longer as big of an obstacle.

Not only that, but you’re not even at a disadvantage compared to much larger traders and companies when it comes to analytics and projections. AI-assisted analytical tools and robo-traders are available to anyone, and they’re not even that expensive. In other words, you can make money even if you can’t afford a broker with a degree in finance from an Ivy League university.

All in all, modern investment and analytical tools act as equalizers. 

You have more assets than you think

Depending on what your financial objectives are, it might be possible for you to diversify your portfolio even without spending any money. How come? 

Well, there are a lot of valuable items in your own home that are hiding in plain sight. 

Chances are that you have some vintage coins, first-edition books, antique jewelry, vinyl records, and even old electronics lying around. While you could, technically, sell them and use this cash to buy more assets, why not keep them as a natural way to diversify your portfolio?

The way this helps you is really simple – by having them, you already have a diverse portfolio without having to spend your already strained budget on alternative investments. Just make sure to start treating them as alternative investments and valuable assets. This means that you should put them someplace safe, secure them, and ensure that they are in a mint condition. Sometimes, even restoration might be in place; just try your hardest not to damage them in the process.

Excuses and procrastination will keep you away from success

While an argument can be made that there are many valid reasons why people are not investing (living paycheck to paycheck, being in debt, or not being interested enough), having too little capital is not one of them. There’s a massive difference between having a bit of capital and having no capital. The difference between these two terms can make or break your financial goals, if you do it right. 


Filed Under: Personal Finance

Pensions In The UK: What To Consider

February 8, 2024 by Susan Paige Leave a Comment

When it comes to personal finance management, you should never overlook the importance of pension planning. While it might be difficult to think about the future when the cost of living is so high, it is vital that you contribute to a pension so that you can lead the kind of lifestyle you wish in retirement. It is never too late to start, but the earlier that you start planning and saving, the better. This post will look at a few of the key considerations with pension planning in the UK so that you can start building towards an enjoyable retirement. 

State Pension Eligibility

First, you want to check your State Pension eligibility. This is the pension provided to you by the government – the current amount is £203.85 per week. You need at least ten years of National Insurance contributions to qualify and the current age you can take the pension is 66, but it is thought that this could rise as high as 71 in the future. You can learn more about your eligibility online. 

Private Pension & Auto Enrollment

If you are employed, a workplace pension scheme should also be available. You should be auto-enrolled in this, so it is important to check and review your contributions. Employers are required to match contributions, and there are tax benefits, so this is an excellent way to build your finances for retirement. 

Personal Pension

If you are self-employed or not eligible for a workplace pension, you can set up your own personal pension. There are numerous types available, but a SIPP (self-invested personal pension) is a good option as the government tops up contributions. You also have greater flexibility with the ability to choose your own investment and invest as and when you please. 

Contributions

You also need to work out how much you can contribute to your pension. Obviously, you want to contribute enough to fund your desired lifestyle once you finish working and take advantage of matched contributions. Still, you also need to make sure that you have enough money to fund a comfortable lifestyle now. The earlier that you start contributing, the better, as you can benefit from compound interest over many years. 

Strategy

You also need to develop an investment strategy based on your goals and financial situation. This can be complex, which is why it is worth speaking with a financial adviser. A financial adviser will be able to develop a pension plan to help you achieve your goals, factoring in your current situation and future goals. You can use platforms like financialadvisers.co.uk to compare FCA-approved advisors. It is then a case of finding one you feel comfortable with and who has expertise in pension planning. 

Pension planning is something that everybody needs to consider, and the earlier that you start this, the better. The above are a few of the key considerations that will help you gain control of your pension planning and start building towards an enjoyable retirement. 

Filed Under: Personal Finance

9 Ways Teachers Can Increase Their Financial Positioning

February 8, 2024 by Susan Paige Leave a Comment

Teaching is one of the most rewarding professions out there. What can be better than being a role model for children, making a positive impact on their lives and seeing them learn and develop in front of your eyes?

According to Seek, the average full-time teacher in Australia makes around $85k a year. Not bad, considering they also get around 15 weeks of holiday every year. However, make no mistake, teachers earn every cent through their hard work, patience and dedication.

Moreover, given the high cost of living, and the fact that many of them must also provide for their own families, a teacher’s wage might not give them the security they need.

Subsequently, many teachers are looking for ways to increase their financial positioning, which is why we have written this post to help them earn more coin. Here are nine strategies to help them do just that.

Factors that determine a teacher’s pay

Like many other industries, a teacher’s salary is dependent on a range of variants. So, before outlining the strategies, it is worth quickly going over what factors determine a teacher’s level of pay.

By understanding some of the more common influences, you will be able to take steps to increase your wage.

Qualifications

Before becoming a teacher, you are required to earn a Bachelor of Education degree as a minimum requirement. However, if you are a teacher who has also achieved academic success beyond that level – for instance, by attaining a Masters Degree -, you will most likely earn a higher wage than colleagues who do not have this formal qualification.

Experience

They say experience counts. Well, it certainly does for teachers in terms of their wage. Essentially, the more years you have worked as an educator, the higher your salary will be.

For example, teachers who have worked for over 10 years can expect to receive a bigger pay packet than a first-year colleague who has just graduated from uni.

Generally speaking, teachers earn incremental pay rises year-on-year to reflect their overall experience. If they have been in their current role for a prolonged length of time, they might also receive a ‘loyalty’ bonus from their employer as well.

Specific role

The salary a teacher receives is not consistent among the education system as a whole. So, if you are a high school teacher, you are more likely to receive a higher wage than a junior school teacher.

At the same time, if you have a niche skill or qualification, for example, as a fluent Indonesian speaker or in teaching special education students, you will usually earn more too.


School Type

The type of school you teach at will play a part in how much you earn. Typically, educators at private schools get paid more than those at state schools. This is because they charge higher tuition fees which enables them to allocate more funds towards the salary of their teachers.

Location

Lastly, where your school is based will also go some way to determining your wage. Schools that are located within major cities will generally pay their staff more than those situated in rural areas.

In addition, some states in Australia such as New South Wales and Victoria, might pay more than others like Tasmania or Western Australia, particularly in the more affluent or better funded areas.

That said, it is worth pointing out that the cost of living in their places might be higher, which offsets the increased wage.

How to make more money as a teacher

Now that you are aware of some of the factors that contribute to your wage, let’s look at how you can increase it.

Here are 9 proactive steps you can take to boost your financial positioning as a teacher. 

  • Get a higher paying job

The first way is kind of obvious. Just get a new job. Or rather a higher paying one. Depending on your personal circumstances this could be easier said than done. However, you should try to be open to the opportunities out there.

Throughout Australia there are plenty of schools you could be working at, so consider relocating to a place where teachers get paid more. At the same time, explore possibilities in a different type of school to the one you currently work in.

A good tip is to look for schools that are just opening up. They may be willing to pay more to attract good quality educators that will help them get their name established as an excellent institute of learning.

  • Look for ways to earn more in your current school

Within your current school, the chances are there might be several opportunities to supplement your income through additional work they might have available.

For instance, teachers can potentially earn more cash by taking on extracurricular activities outside of regular school hours. These may include coaching sports teams, helping out at musical or drama performances or chaperoning children to specific events. Alternatively, there might be leadership responsibilities you can assume to which you can get paid extra for.

This is probably the easiest way for you to strengthen your financial position because it is simply a matter of increasing your current remit.

3. Focus on professional development

Learning should be a lifelong endeavour, even for teachers. So, it is worth focusing on your professional development to add extra strings to your bow.

There are various aspects of teaching you can develop new skills in, or brush up on, that might help you command a higher salary. Mastering digital technologies or dynamic learning are two areas you can concentrate on. However, it might be worth talking to the principal to get an honest opinion of how you can improve as a teacher or in what areas your school can use expertise.

The good thing about professional development these days is that it is no longer essential to be done face-to-face. Instead, there are plenty of resources you can tap into, including live streamed webinars, zoom workshops, virtual events, digital seminars and online summits. These can be completed at any time, from the comfort of your home or school, without the need for travel.

4. Study for formal qualifications

As mentioned earlier, teachers who have qualifications beyond the mandatory Bachelor of Education tend to earn more money than those who don’t. Therefore, it might be a good idea for you to enrol in a relevant Master’s programme. 

You might consider UTS Online to study a Masters of Education Online if you want to continue working at the same time.

Doing this will help you to increase the theoretical side of your core competencies further. It should also ensure you receive a higher wage when moving to a new role.

5. Become a tutor

As a teacher you have an excellent ability to impart knowledge to your classroom. But some children struggle more than others. For this reason, you can use your talents to earn extra money as a tutor.

Whether you do this on a one-on-one basis or as part of a group is up to you. However, it would be a good way to increase your earning capacity. Moreover, if you offered a tutoring service via an online platform like Zoom, you could take your tutoring sideline to children all round Australia, or even the world.

It is worth bearing in mind that parents are more likely to hire someone as a tutor to their child if they are well-qualified. Therefore, this can become quite a lucrative venture for you if you manage to generate a substantial number of clients.

6. Substitute during breaks for out-of-state schools

In Australia, teachers get a lot of holiday time – often as many as 15 weeks. But while some take the opportunity to disappear off on a well-deserved getaway, if you want to earn some extra money, you may want to proffer your services as a supply teacher.

Schools often have different term times depending on if they are public or private schools and what state they are based. So, there could be an opportunity to fill in at one of them for a week or two, while yours is on a break.

As a substitute teacher you won’t have as demanding a set of responsibilities to manage and you will be able to earn additional income. However, just be mindful of the potential to burn out if you choose to work during your break.

7. Sell your class materials and lesson plans

Teachers are always looking for inspiration when it comes to class materials and lesson plans. Therefore, to make extra money, you might want to sell the ones you have previously developed online.

This is a potentially lucrative area the majority of teachers are yet to tap into. However, if your work is of an excellent standard and relevant to the current curriculum, you can make a decent amount of cash by offering them for a price online.

You can do this either through your own website or via established sites like Amazon KDP, Etsy or TeachersPayTeachers.

8. Help develop the curriculum

If you enjoy lesson planning and are good at it, you might have a natural flair for developing the school curriculum too. Therefore, it is worth asking the management of your school if they can contract you to do so.

This will likely incorporate various subjects and grade levels and could result in a lot of extra work. However, it will help you earn more money within your current position and will give you something impressive to put on your resume.

9. Become a school administrator

If you have been a teacher for a while and are ready for a change of responsibility as well as a higher wage, then it might be time to become a school administrator.

This role encompasses principals, vice principals, school leaders and operations managers, and although much of the work is done outside of the classroom, you still get to work with students in an educational setting.

A school administrator gets paid a lot more than a teacher, particularly if you work your way up to a district level. While this type of job will involve more work, it will also go a long way towards putting educators in a better financial position, if they want to be richer.

Filed Under: Personal Finance

Why Adding Cleaning Services Into Your Monthly Budget Is Essential

February 7, 2024 by Erin H. Leave a Comment

When you have to consider your monthly finances, you look more at bills and not as much at the services you may need for your home to be deep cleaned regularly. While you maintain your regular cleaning duties, some things you may not be getting to should be cleaned regularly. You can budget your finances to include cleaning services in your monthly routine, having a professional ensure your home or rental property has been spotless.

Reduce Pests

One of the biggest concerns that comes with not having your property cleaned regularly is the presence of pests. If you are missing something or do not clean the remains of pests from your home, you can get an infestation that could take a lot to get rid of. According to Penn State, an adult female Indian meal moth can leave around 100 to 300 eggs on food and surfaces around the home. If they aren’t cleaned before the eggs hatch, you will have an investigation beginning and an unsanitary home to cook and live in.

Reduce Germ Exposure

We know that germs linger out in public, so when we come to our homes, we want them to be as clean and safe as possible. Your hands spread 80% of illness-causing germs. Your hands also regularly touch walls, surfaces, door handles, and other surfaces where you can pick up germs and spread them to everyone in the space. With a cleaning service, they will clean the areas that are easy to overlook in your weekly cleanings so that these germs are not growing and leaving the potential to make you sick.

Appliances Are Often Forgotten

One of the true benefits of hiring someone for cleaning services is the benefit of them cleaning appliances. They are often forgotten or just looked over because they can be a real chore to do on your own. This makes it worth the money spent on professional cleaning services. According to the Stove Dr, you need an annual stove cleaning when you burn more than 75 bags of fuel each season. Other appliances like your dishwasher, washing machine, and microwave should also have regular cleanings.

Get Back Family Time

When you add cleaning services to your finances, you are paying for grueling tasks that can take a lot of time. When you hire a professional team to come in and do them for you, you are getting back valuable time with your family that you would have otherwise spent on the task yourself. Making these memories is invaluable, and having someone come in and do it correctly while you enjoy your day is worth the money.

Save Sleep And Peace Of Mind

Some of these tasks can even cut into your sleep and your peace doing them correctly. It will take longer if you are not a professional cleaner or do some of these tasks regularly. You could even find yourself doing it incorrectly and spending more money correcting the issue. When you outsource this task, you spend your finances on mental peace and solid sleep. It is worth not having that stress and knowing that the task has been completed correctly.

Make The Investment

While it may sound better for finances on paper to tackle some of these tasks on your own, it is worth having professional cleaning services come in and tackle the large projects. These professionals have the skills and tools they need to complete the task and also ensure that. it is done correctly. Not every task needs to be a DIY project and should be handled by those who are familiar. Choose to see this addition to your finances as an investment in your family, your happiness, and your peace of mind.

Filed Under: Personal Finance

Common Challenges and Solutions in Bank Reconciliation for Businesses

February 6, 2024 by Susan Paige Leave a Comment

In today’s fast-paced corporate world, maintaining accurate financial records is paramount for any business. A crucial aspect often overlooked by businesses is the bank reconciliation process, which plays a vital role in financial integrity. Reconciliation errors can lead to severe financial discrepancies, affecting business decisions and credibility. Understanding the potential challenges and solutions in bank reconciliation can shield a company from financial mishaps. Keep reading to dive into the common hurdles and how businesses can efficiently navigate them.

Understanding the Importance of Accurate Bank Reconciliations

Accurate bank reconciliations are the cornerstone of reliable financial reporting. By ensuring that the bank’s records match a company’s internal financial data, businesses can affirm the integrity of their financial statements. This comparison is not only a safeguard against fraud but also an indispensable tool in highlighting any inconsistencies that can distort a company’s financial health.

Inaccuracies in the reconciliation process can result in misleading information about cash flow and capital, which are critical factors in decision-making. Companies that diligently reconcile their accounts can better manage their cash, avoid overdraft charges, and identify unauthorized transactions quickly.

The task of reconciling bank statements with internal records can sometimes be daunting. However, the advent of digital solutions has made it easier to address discrepancies. By consistently following best practices in reconciliation, companies can significantly reduce financial risks.

Common Pitfalls in Bank Reconciliation and How to Avoid Them

Among the most frequent pitfalls in bank reconciliation are data entry issues caused by human error. These may seem trivial, but they can have a compounding effect on financial reports. Diligence and attention to detail are critical in preventing these mistakes from occurring.

Additionally, businesses often face problems due to timing differences, such as outstanding checks or deposits in transit. Maintaining a thorough record of pending transactions and regularly updating cash flow statements can help alleviate these issues.

Another common obstacle is the problem of lost records or unaccounted-for charges. To prevent such scenarios, firms should enforce a policy of regular documentation and review of all expenditures and receipts, along with prompt recording of each transaction.

Businesses must also contend with bank errors. Though infrequent, they can and do happen. Regular reconciliations enable companies to detect and address these errors swiftly, thereby maintaining accurate financial records.

Leveraging Technology to Streamline Bank Reconciliation Processes

Technology has revolutionized bank reconciliation by enabling automation and real-time data syncing. Advanced software can now match transactions almost instantaneously, saving businesses countless hours of manual work. Investing in such tools can reduce the likelihood of human error and boost efficiency.

Cloud-based reconciliation platforms are now the norm, offering the convenience of remote access and collaboration. These systems ensure that the financial team can work on reconciliations without being confined to the office, which is an asset in today’s increasingly mobile workforce.

Furthermore, modern reconciliation software often comes with analytical tools that provide insights into financial health. Understanding how to leverage these can empower a business to manage its cash flow more effectively, detect potential fraud, and make data-informed financial decisions.

Integration of the reconciliation software with other financial systems within the company creates a seamless flow of data. It ensures that every transaction reflects across all platforms, providing a coherent and accurate financial picture for stakeholders.

Implementing Internal Controls to Improve Reconciliation Accuracy

Companies should implement robust internal controls to improve accuracy in bank reconciliations. These include establishing clear protocols for recording transactions and conducting reconciliations. Checks and balances should be in place to ensure that no single individual has unfettered control over the financial reporting process.

Cross-verification by different departments or team members can significantly enhance the accuracy of reconciliations. It’s a method that fosters accountability and serves as a deterrent against potential financial misreporting or misappropriation.

Employee training is another cornerstone of robust internal controls. Ensuring that staff are knowledgeable about reconciliation procedures and the company’s accounting software prevents errors and enhances efficiency.

Altogether, meticulous bank reconciliation is indispensable for safeguarding a business’s financial integrity. While challenges are a given, implementing best practices and leveraging modern technology can streamline the task, turning potential obstacles into opportunities for improving financial management.

Filed Under: Personal Finance

20 Valuable Items In Your Home Hiding in Plain Sight

February 6, 2024 by Tamila McDonald Leave a Comment


House

Your home may be a treasure trove of items with hidden value. Often overlooked, these everyday objects can be of significant worth, either as collectibles or for their historical importance. Check out these 20 such household items, revealing their potential hidden value and how to identify them.

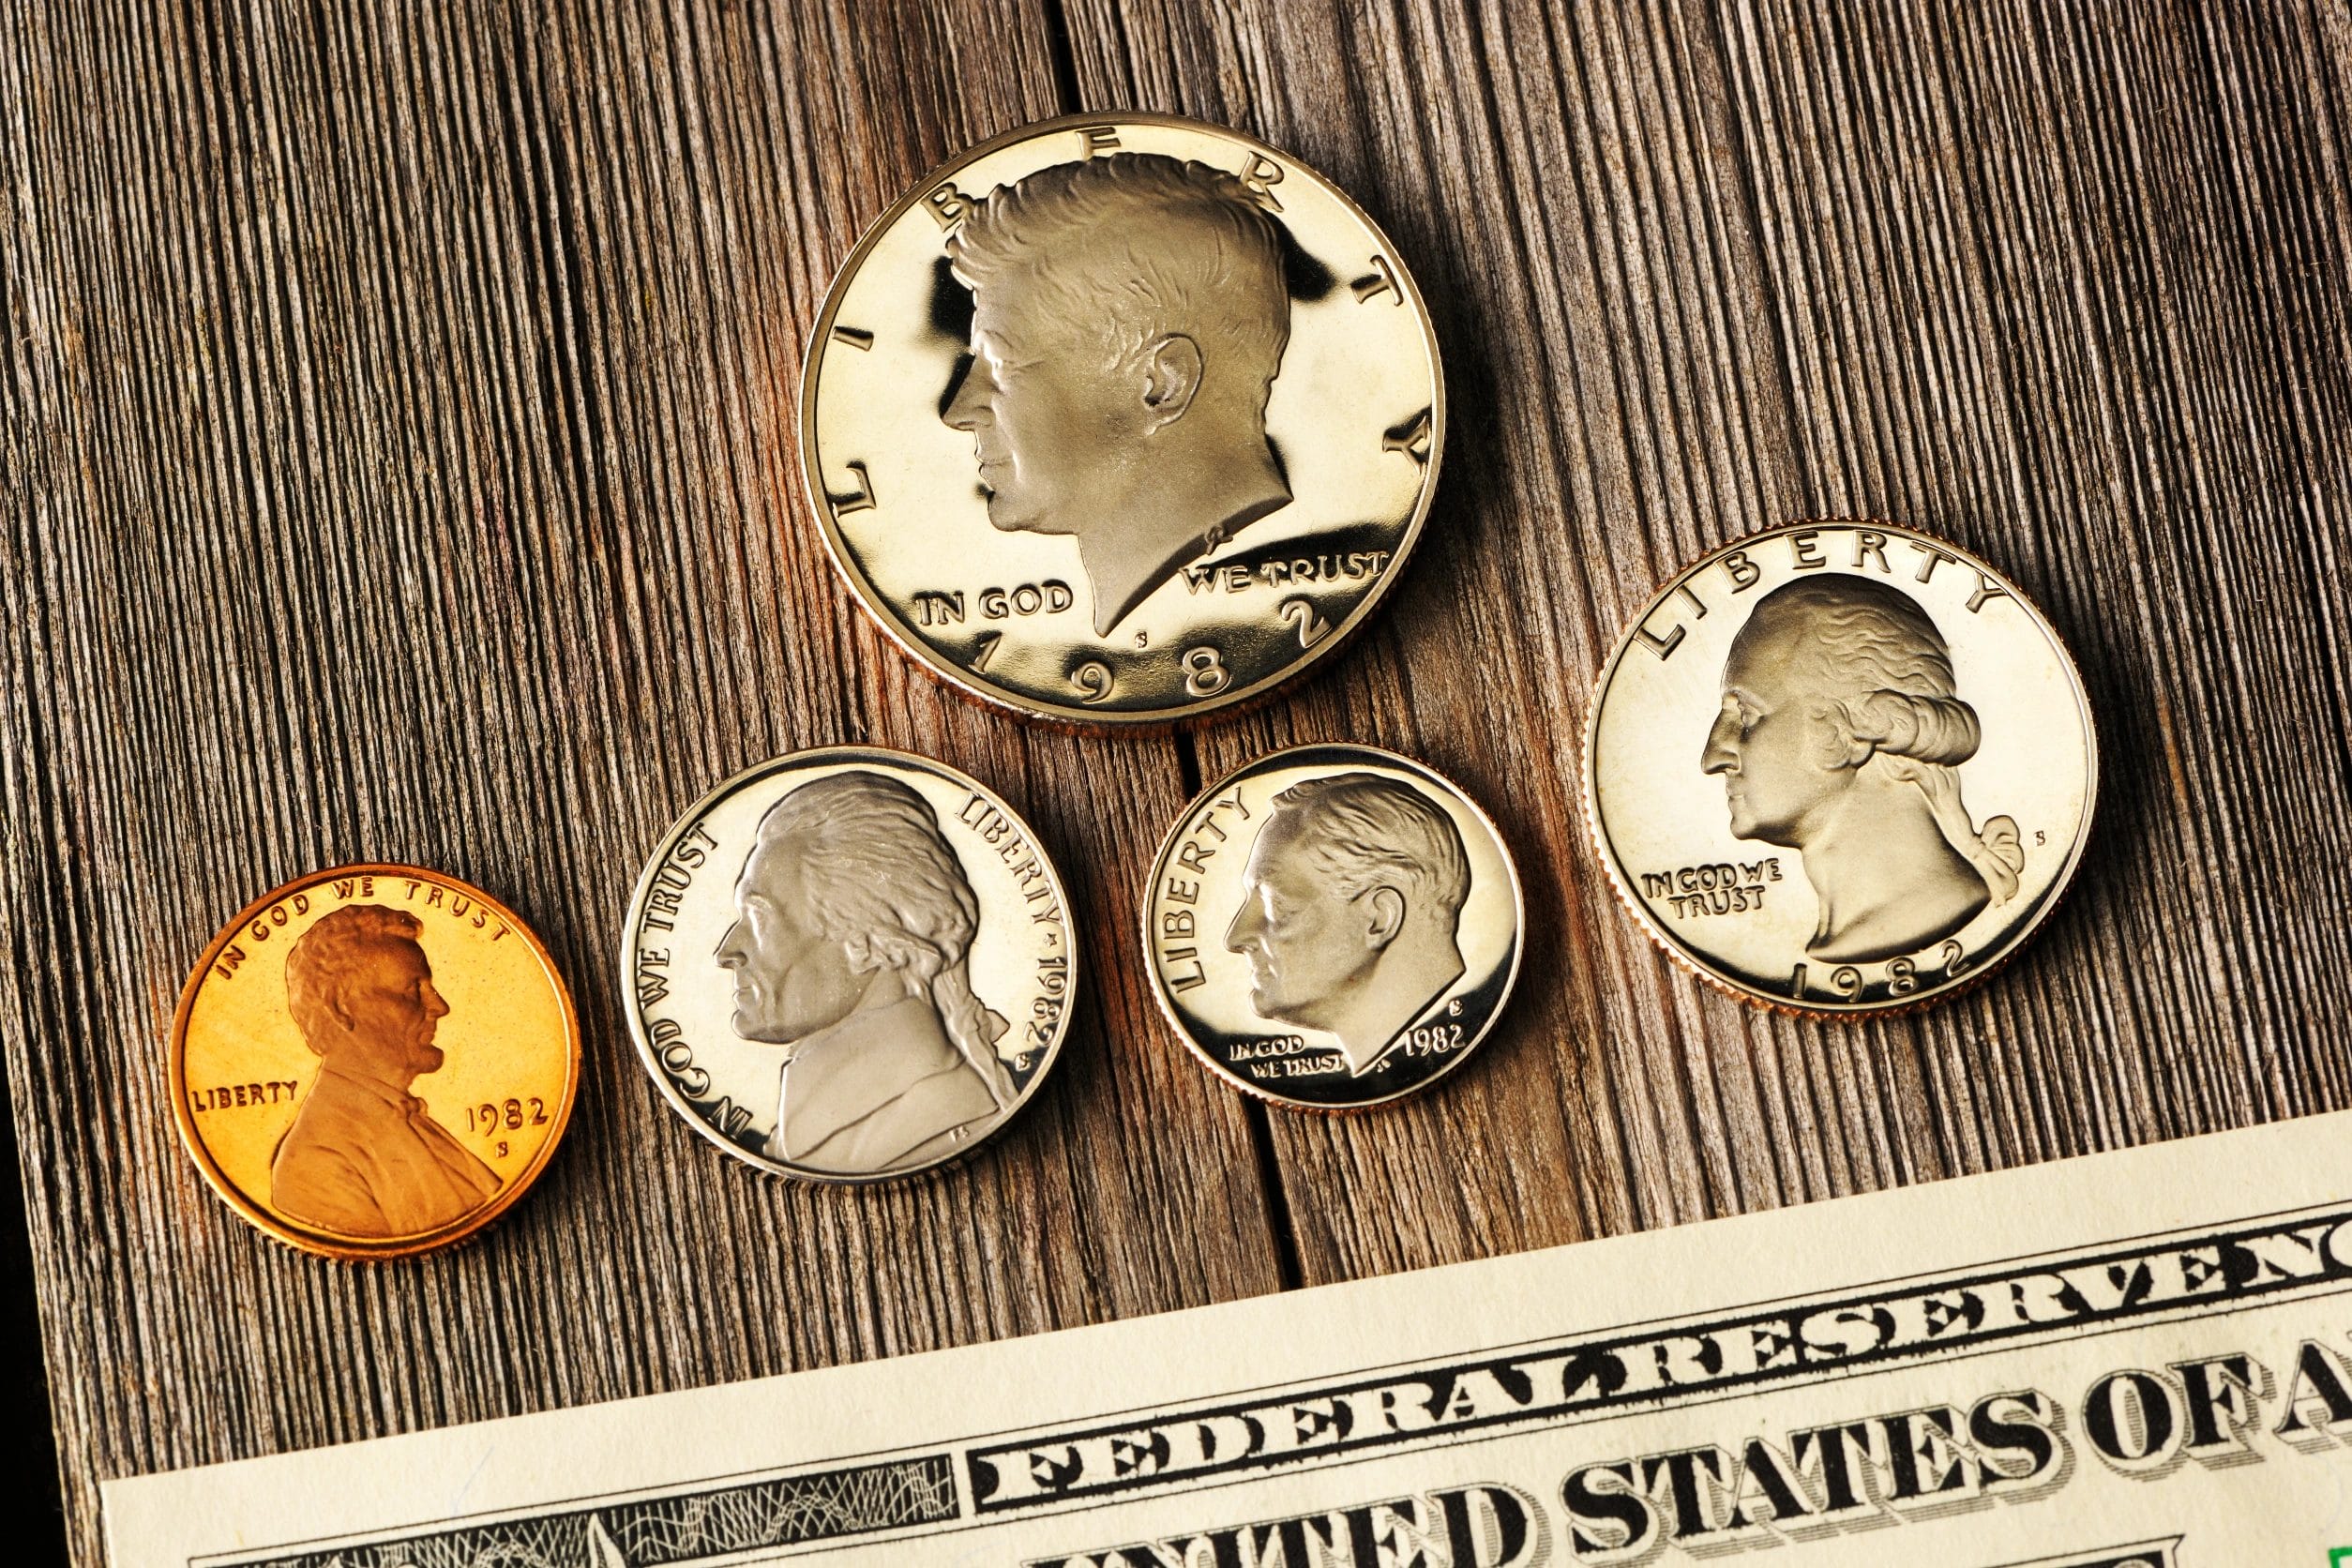
1. Vintage Coins and Currency

vintage coins and currency

Old coins and currency tucked in drawers or old jars could be miniature goldmines. Collectors often seek rare editions, mint errors, or pieces with historical significance. Beyond their face value, these items can tell a story of the past, making them even more valuable to collectors. Examine your old change; there might be a rare piece waiting to be discovered.

2. First Edition Books

first edition books

First editions, especially those signed by the author, can be worth a fortune. These treasures often sit unnoticed on bookshelves, gathering dust. First editions from iconic authors or books that have had a significant cultural impact are particularly valuable. To identify a first edition, look for specific publishers’ markings and print numbers.

3. Antique Jewelry

Antique Jewelry

Inherited jewelry, often deemed out of style, can hold surprising value. Vintage pieces, particularly from recognized brands or specific historical periods, often fetch high prices. Their craftsmanship, rarity, and sometimes the stories behind them add to their allure and value. Check for maker’s marks or hallmarks to identify their origins.

4. Vintage Toys and Games

vintage toys


Old toys and games from your childhood could be worth more than sentimental value. Pristine conditions and original packaging significantly increase their worth. Brands like LEGO, Barbie, and classic video games from the 80s and 90s are in high demand among collectors. Even everyday toys can be valuable if they are rare or discontinued.

5. Vinyl Records

vinyl records

Certain old vinyl records are highly collectible, especially limited editions or original pressings. Albums by iconic artists or rare recordings can fetch substantial sums. The revival of vinyl records as a preferred music format has only increased their value. Check for records that were limited runs or special editions.

6. Old Magazines and Newspapers

newspapers

Particular old magazines and newspapers, especially those marking significant historical events, can be collectible. The value lies in their condition and rarity. Collectors often seek unique editions or those in excellent shape. They serve as a window into history and are cherished by enthusiasts.

7. Vintage Electronics

electronics

Retro electronics like old video game consoles, turntables, and early computers can be surprisingly valuable. Their nostalgic appeal makes them popular among collectors, especially when they’re in working condition. Original accessories and packaging can significantly enhance their value. Look for iconic models that were either a technological breakthrough or a cultural phenomenon.

8. Stamps

rare stamps

Stamp collections can be hidden gems. Rare stamps, error prints, and older, well-preserved collections are in high demand. Their value can be determined by rarity, condition, and historical significance. Stamps from certain eras or countries, or those featuring errors, are particularly sought after by philatelists.

9. Antique Furniture

Antique Furniture

Vintage furniture, especially pieces from notable periods or makers, can be highly valuable. Original condition and historical significance greatly add to their worth. Look for unique craftsmanship or signature elements that indicate a piece’s age and origin. The furniture’s provenance can also significantly increase its value.

10. Artwork

artwork

Original artwork, even from lesser-known artists, can be valuable. The value lies not just in the name but in the art’s uniqueness and the story it tells. Check for signatures and research the artist’s history to gauge its worth. Sometimes, the frame itself can be an antique and of considerable value.

11. Designer Clothing and Accessories

designer clothes

Designer clothing and accessories, particularly from iconic brands, retain value. Vintage or slightly used high-end brands like Chanel, Louis Vuitton, or Hermes are particularly sought after. The craftsmanship and brand heritage play a significant role in their valuation. Limited edition pieces or those from significant fashion eras are especially valuable.

12. Vintage Cameras and Photography Equipment

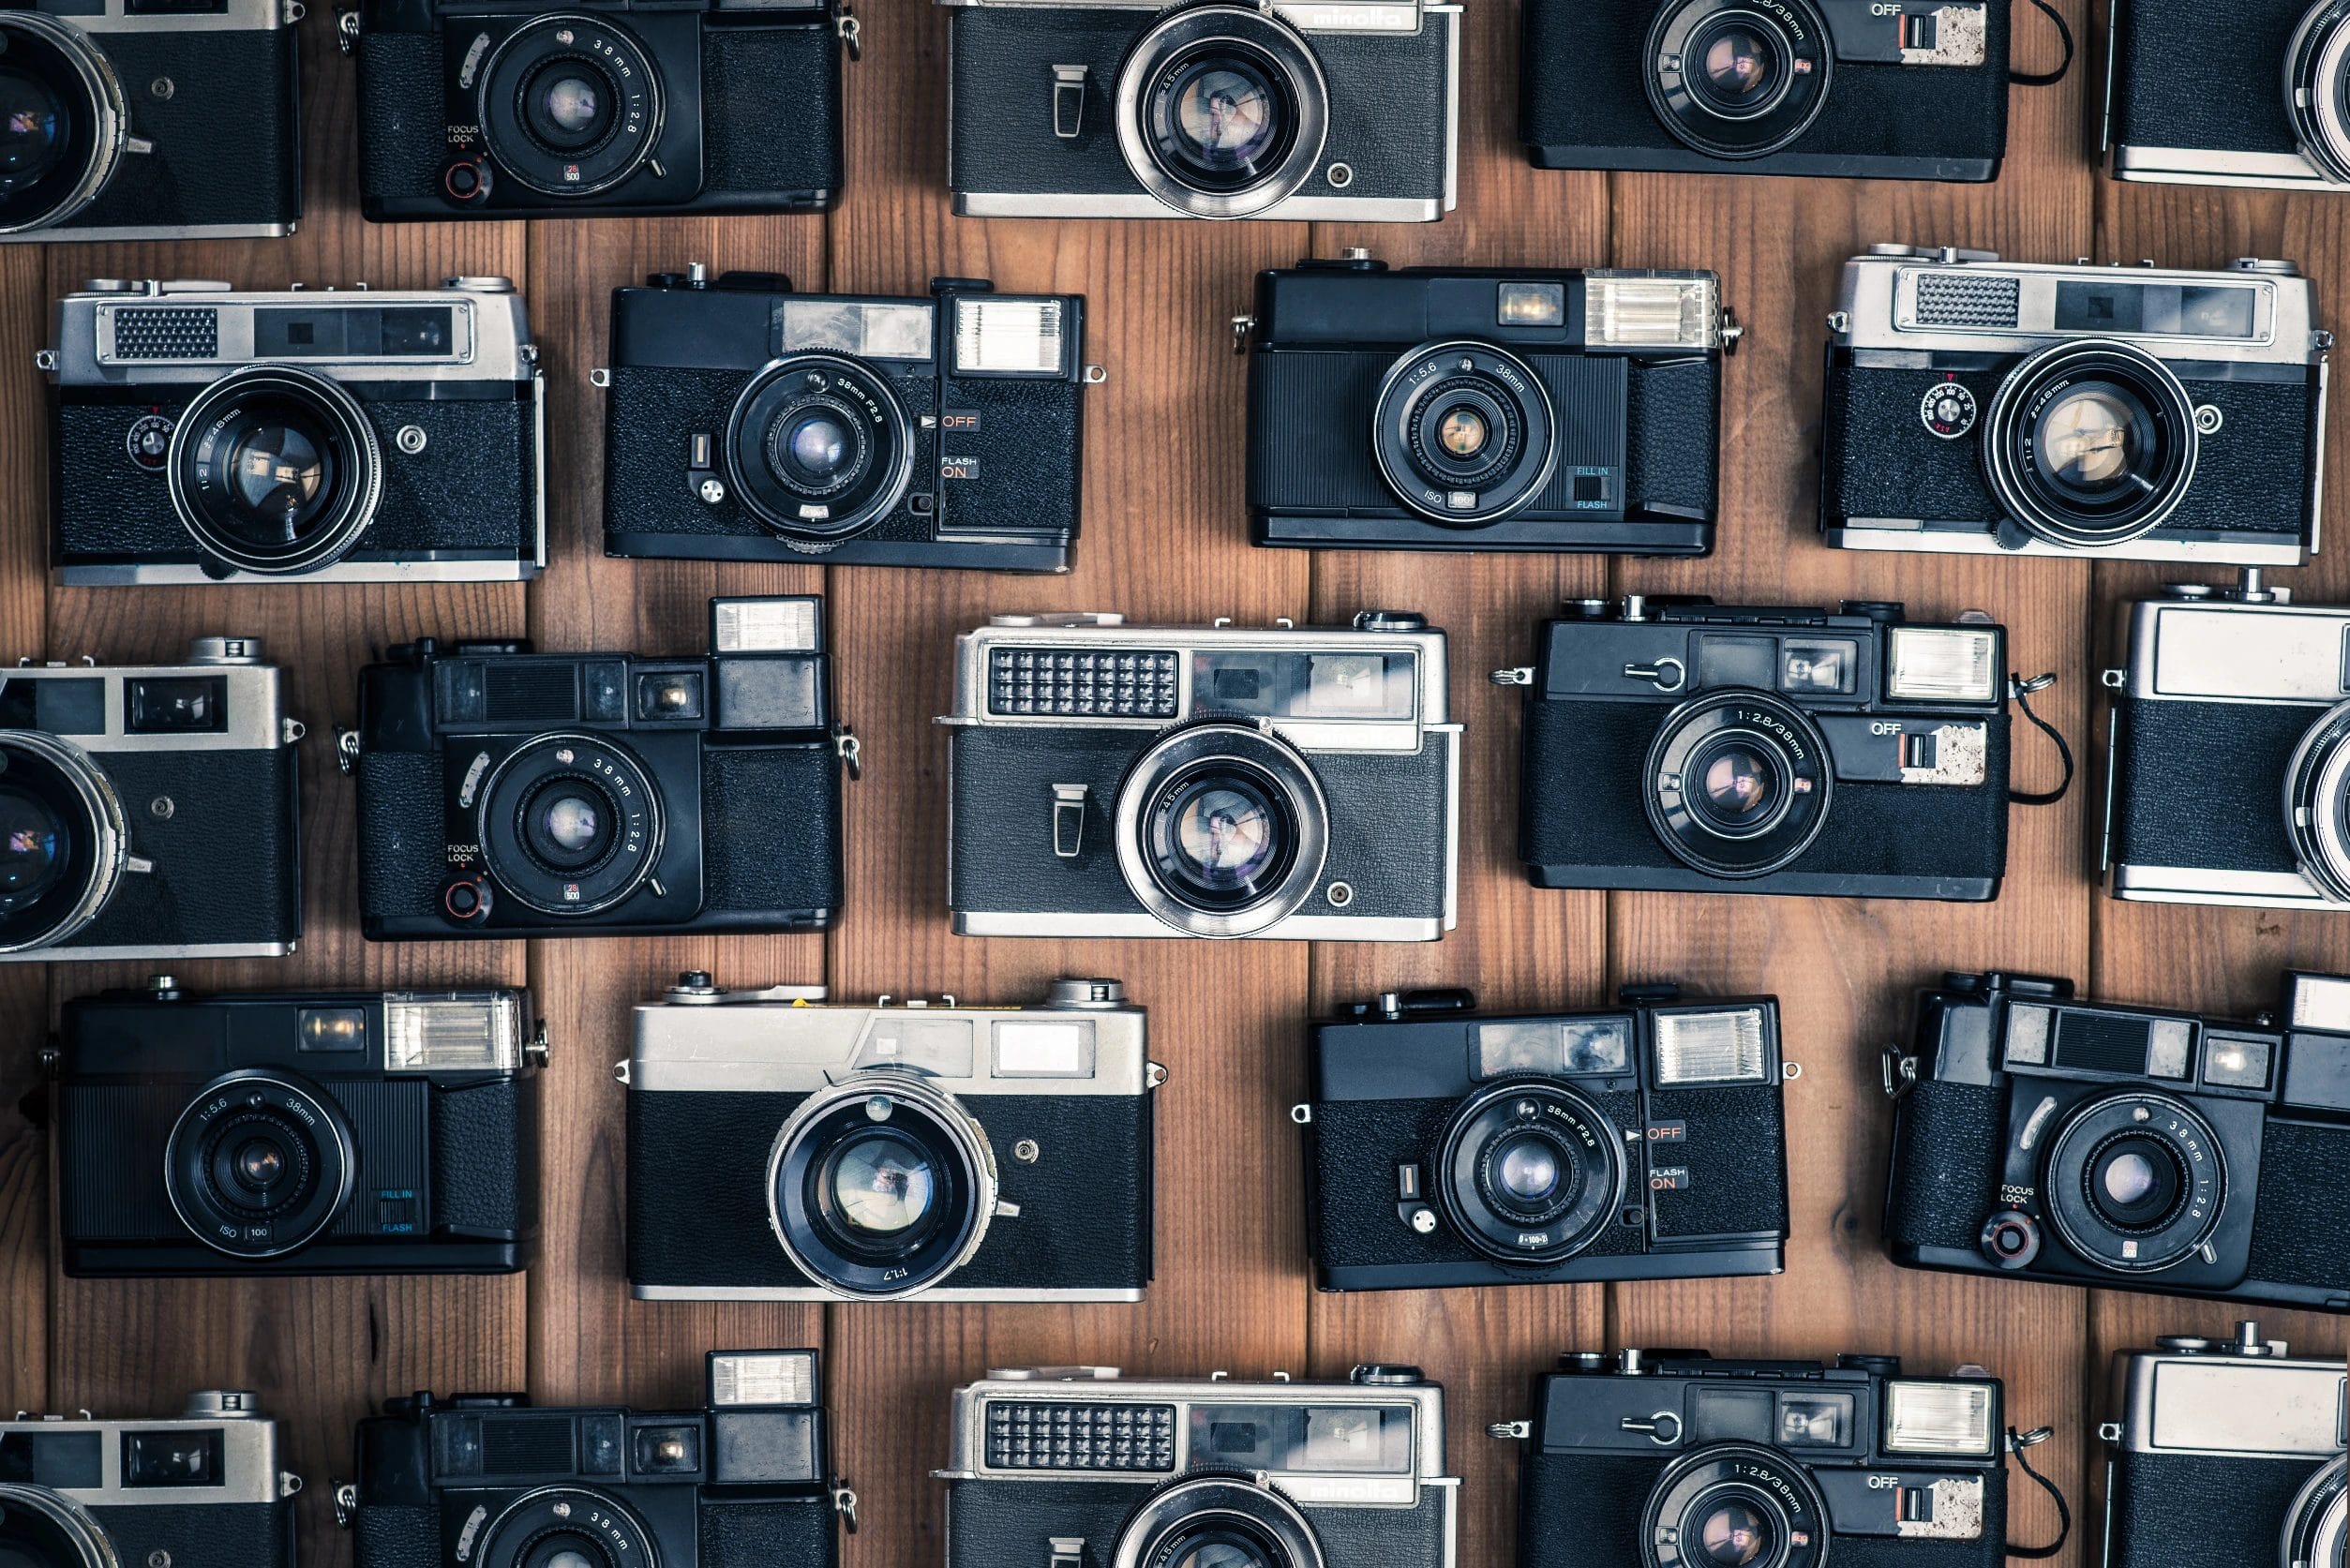
vintage cameras

Old cameras and photography equipment have a market among collectors and enthusiasts. Classic models from brands like Leica or Nikon, especially those in good condition, are highly prized. The historical significance of the camera model and its contribution to photography can add to its value.

13. Handmade Quilts and Textiles

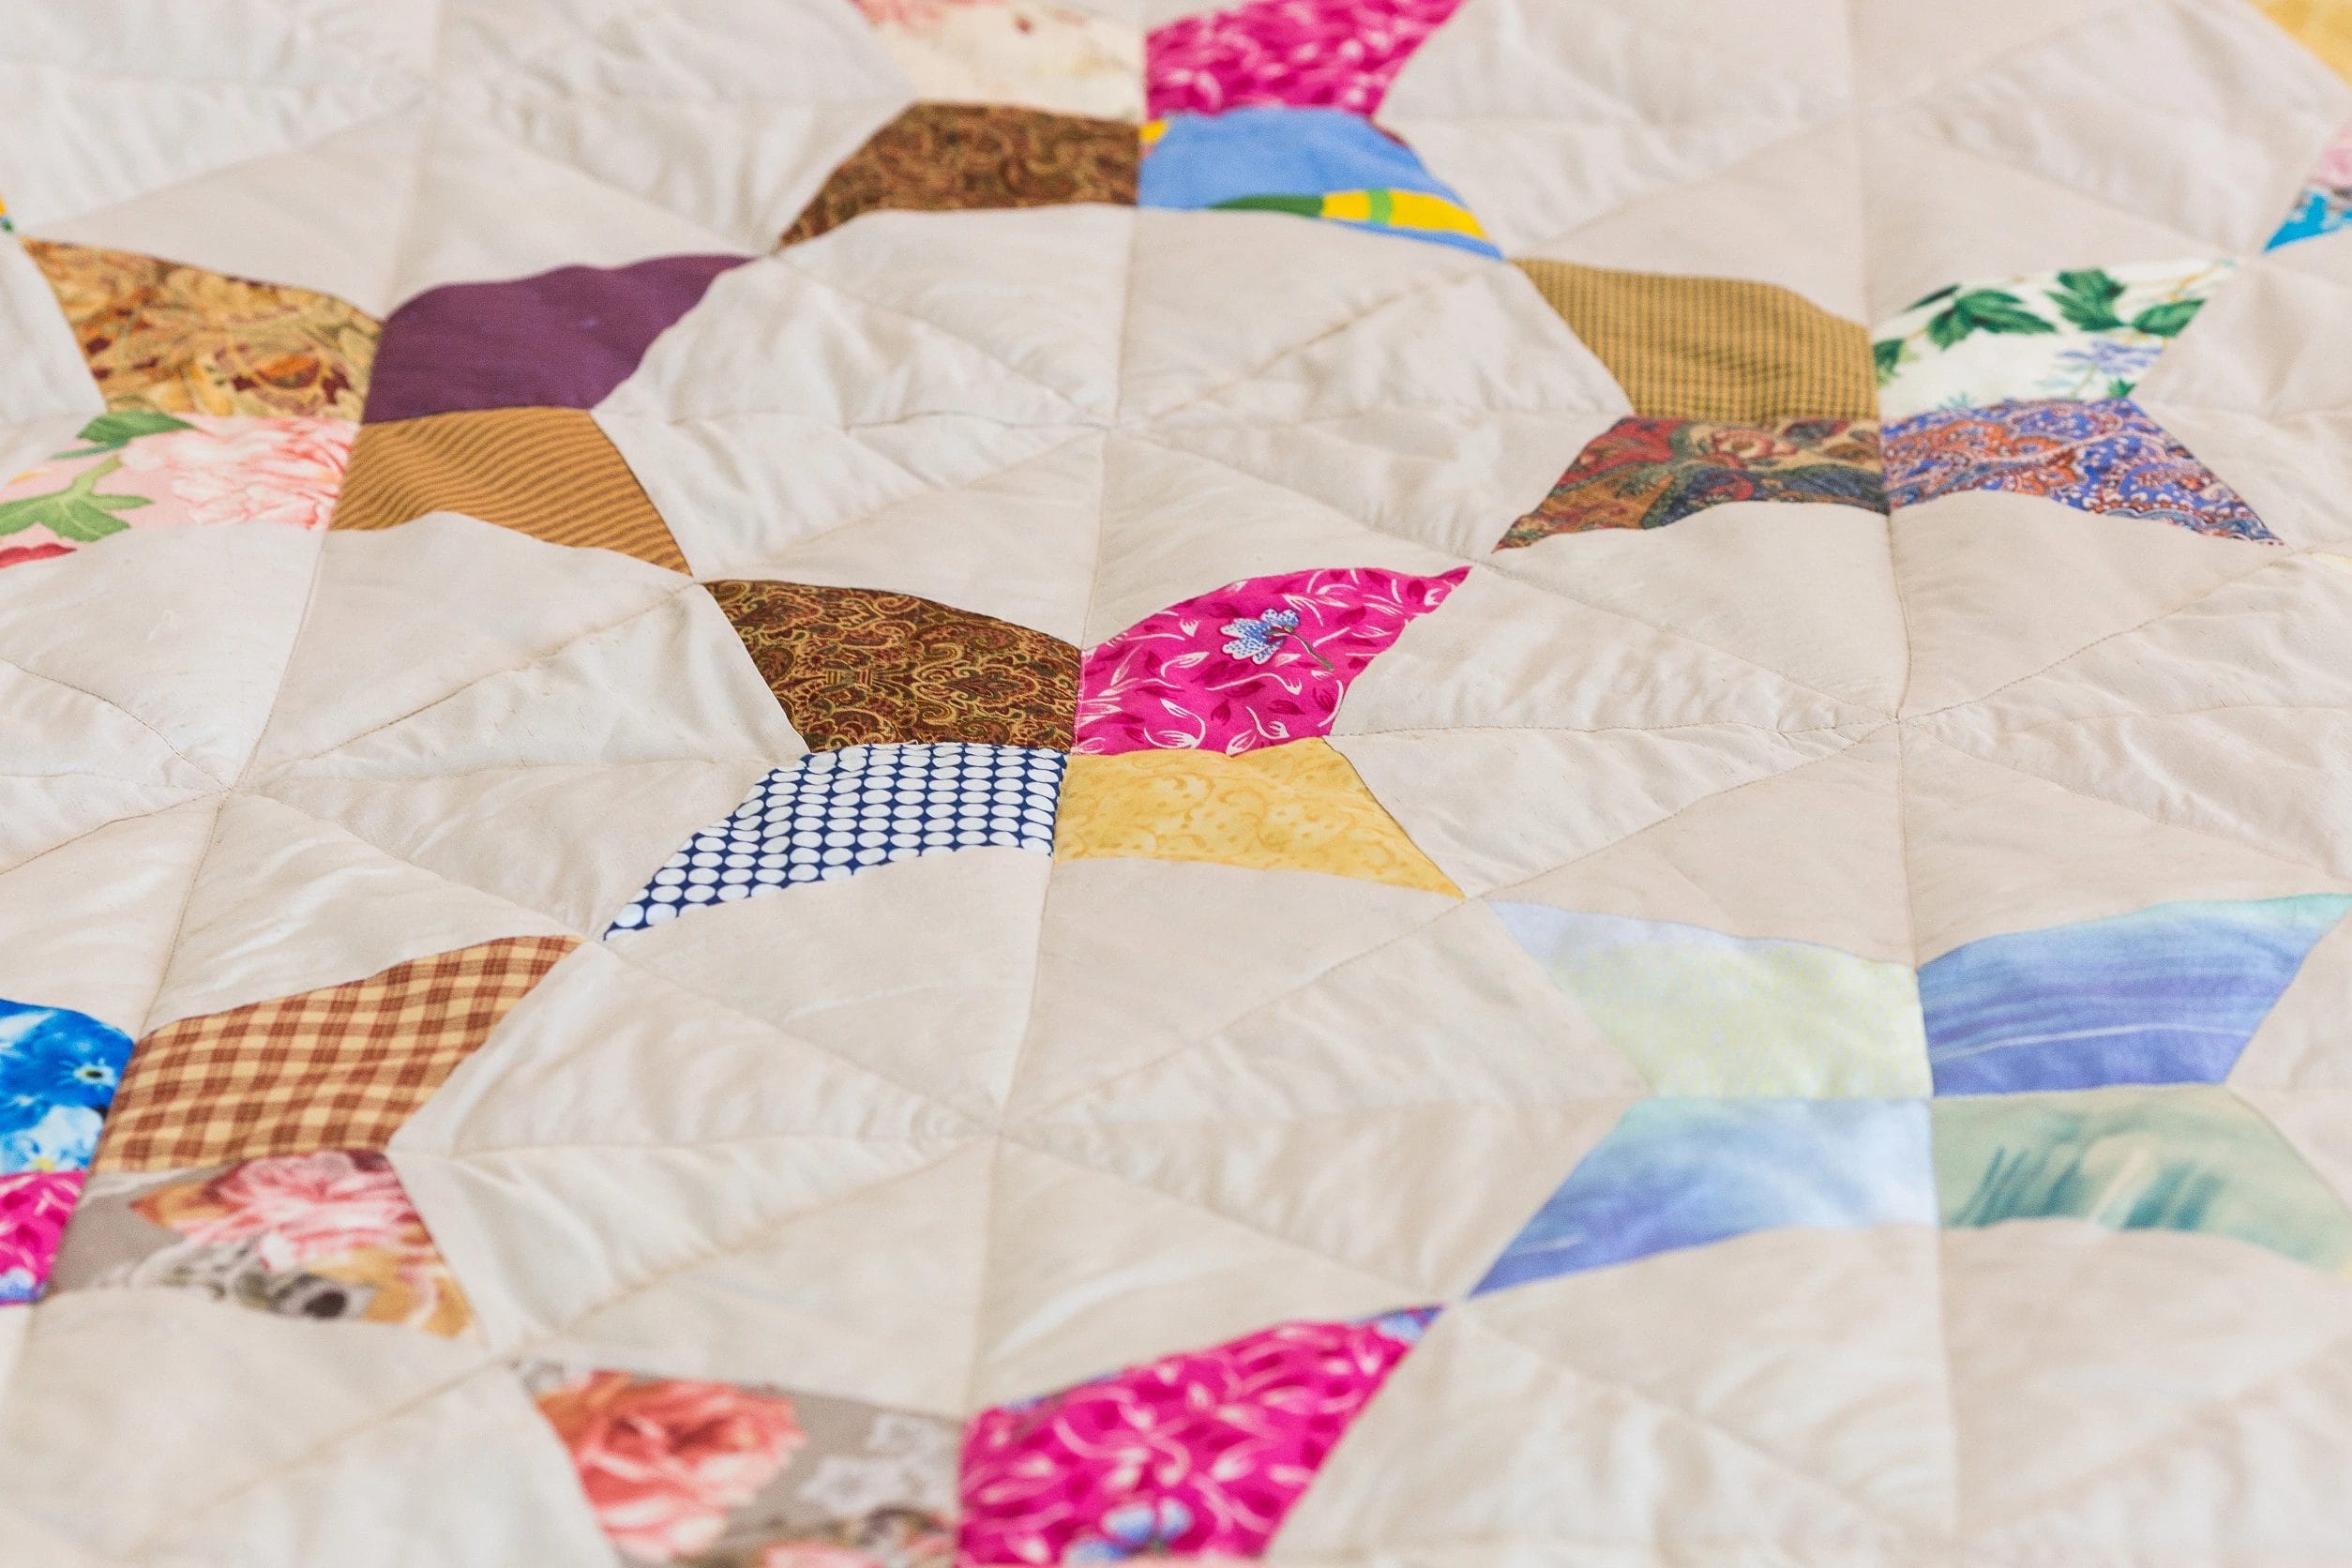
handmade quilts

Handmade quilts and textiles, particularly antique or with a unique history, can be of considerable value. The craftsmanship, materials used, and the story behind the piece add to its worth. These items are often undervalued but can fetch high prices, especially if they are from a known artisan or a historically significant period.

14. Sports Memorabilia

sports memorabilia

Sports memorabilia, including signed equipment or vintage items, hold both sentimental and monetary value. The item’s connection to a famous athlete or a significant sports event can greatly increase its worth. Authentication plays a crucial role in valuing these items, so it’s essential to have proper documentation.

15. Collectible Pottery and Porcelain

porcelain

Pottery and porcelain from well-known makers or unique pieces are highly collectible. Their value is determined by the maker’s mark, age, and the item’s condition. Collectible pieces often come from specific periods or have distinctive designs that set them apart. Even everyday items can be valuable if they are rare or have historical significance.

16. Silverware and Flatware

silverware

Silverware sets, particularly those made of real silver, can be quite valuable. The value is not just in the material but also in the craftsmanship and design. Even individual pieces or incomplete sets can be of worth, based on their weight and craftsmanship. Look for hallmarks that indicate the silver quality.

17. Wine and Spirits

wines

Certain bottles of wine and spirits increase in value with age. Collectible bottles include limited edition releases, vintage years, and unique blends. The storage conditions and provenance of the bottle also play a significant role in its valuation.

18. Antique Glass and Crystal

Antique Glass and Crystal

Glassware and crystal, particularly from notable manufacturers or with unique designs, can be of considerable value. Items in excellent condition and with distinctive features like etchings or unique colors are highly sought after. The rarity and history of the piece add to its allure.

19. Old Maps and Globes

old maps

Vintage maps and globes are collectible items, especially rare or hand-drawn ones. Their historical significance and the story they tell make them valuable. Look for maps and globes that are in good condition and have unique features or were made by well-known cartographers.

20. Classic Car Models and Parts

classic cars

Classic car models, even small die-cast ones, can be valuable, particularly if they are rare or in mint condition. Additionally, old car parts, especially from vintage or classic cars, are in demand. Their value lies in their rarity, condition, and the vehicle model they belong to.

Exciting and Lucrative Adventure

lucrative

Discovering hidden treasures in your home can be an exciting and potentially lucrative endeavor. Whether it’s a piece of history, a work of art, or a nostalgic item, these household objects can offer more than meets the eye.

If you’ve found some valuable household items in your home, we’d like to hear about it in the comments.

Tamila McDonald
Tamila McDonald

Tamila McDonald is a U.S. Army veteran with 20 years of service, including five years as a military financial advisor. After retiring from the Army, she spent eight years as an AFCPE-certified personal financial advisor for wounded warriors and their families. Now she writes about personal finance and benefits programs for numerous financial websites.

Filed Under: Personal Finance Tagged With: hiding in plain sight, House, vintage coins

  • « Previous Page
  • 1
  • …
  • 66
  • 67
  • 68
  • 69
  • 70
  • …
  • 95
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework